
- Market Size (2026)
- USD 6272.2 Mn
- Forecast (2036)
- USD 12807.4 Mn
- CAGR (2026 to 2036)
- 7.4%
How big is Mobile Fuel Delivery Market in 2026?
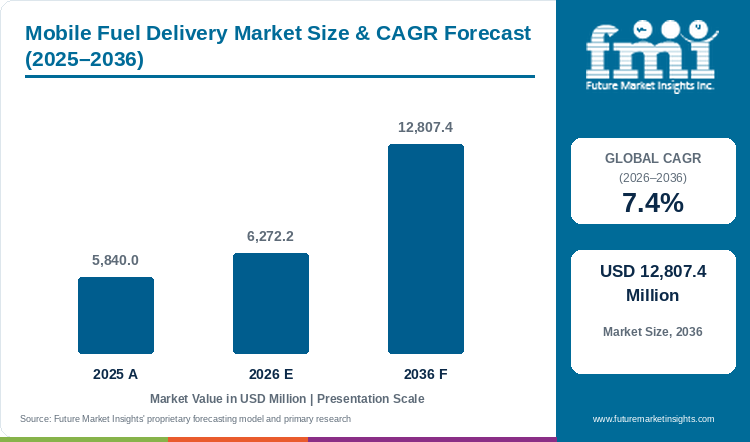
The mobile fuel delivery market is estimated at USD 5.8 billion in 2025 and is projected to reach USD 6.3 billion in 2026. The market is likely to grow at a 7.4% CAGR to USD 12.8 billion by 2036.
Sales of mobile fuel delivery are highest in North America, as trucking and construction fleets move refuelling from the forecourt to the yard overnight. Demand for mobile fuel delivery, an estimated USD 5.8 billion in 2025, is forecast to rise to USD 6.3 billion in 2026. FMI estimates a 7.4% CAGR, which brings the market to USD 12.8 billion by 2036. NextNRG credited wider fuel volumes and service areas in mobile fueling for a 40.9% sales gain to USD 27.7 million in the June 2026 quarter.[1] The same release noted that new microgrid sites often belong to fleet operators the company already fuels, so operators are turning adjacent opportunities into growth with existing fleet customers.
Truck-heavy Germany is projected to grow at a 7.5% CAGR through 2036, ahead of the United Kingdom on 7.1%. Destatis reported that the German truck toll mileage index rose 2% in August 2026 against August 2025.[2] More truck kilometres on German motorways burn more diesel in depots and logistics yards, which keeps fleet operators adding scheduled tanker visits. Sales in the United Kingdom lean more on construction sites, and slower site activity keeps the country below the 7.4% global rate.
Key Market Trends & Insights
- Diesel is projected at 62% of fuel-type sales in 2026, about five times gasoline at an estimated 12%.
- Truck refuelling is likely to be 70% of equipment sales in 2026. NextNRG ran 144 active delivery vehicles across seven states after entering Oklahoma, the company said in May 2025.[3]
- Fleet, construction and logistics buyers keep commercial accounts close to 71% of 2026 end-use sales (estimated), with farms near 17%.
Regional Highlights
- Generator users switching to delivered diesel give India an expected 8.9% CAGR through 2036, the quickest in the table.
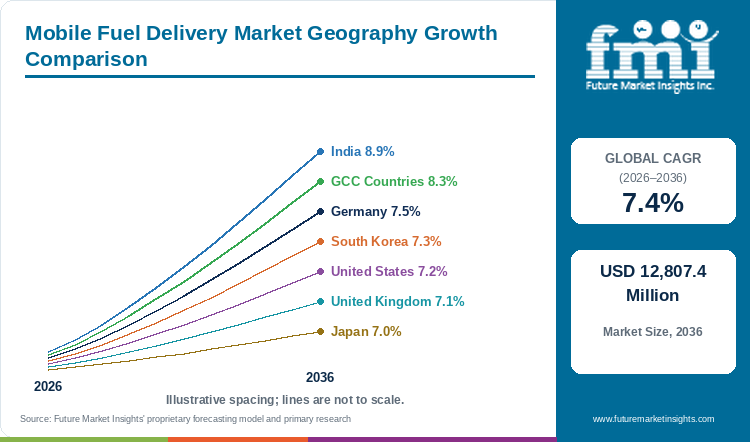
- The GCC Countries come next at 8.3%, and Germany is the third market ahead of the 7.4% global CAGR, at 7.5%. South Korea, the United States and the United Kingdom fall within 0.3 points below that rate, at 7.3%, 7.2% and 7.1%, and Japan is lowest at 7%.
- Japan counted 381 municipalities with three or fewer fuel stations at the end of fiscal 2024, nine more than a year earlier, the Agency for Natural Resources and Energy reported.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Mobile Fuel Delivery Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5,840.0 million |
| Estimated Market Size in 2026 | USD 6,272.2 million |
| Projected Market Size by 2036 | USD 12,807.4 million |
| CAGR, 2026 to 2036 | 7.4% |
| Added Revenue, 2026 to 2036 | USD 6,535.2 million |
| Market Expansion Multiple | 2.0x |
Fleet fueling contracts usually start with a pilot depot and then add states and vehicles. NextNRG entered Oklahoma as the company's seventh operating state in early 2025 under a long-term agreement with a large in-house fleet operator.[3] Service-area growth carries most new volume, and Gross profit at NextNRG increased 24.6% to USD 1.96 million in Q2 2026, on sales up 40.9%.[1] Gross profit rising more slowly than sales points to thinner margins on each added route. Fleet software sets the schedule for each tanker visit, and more fleets will order fuel through the same telematics screens used for routing as the fleet management market grows at a forecast 16.9% CAGR through 2036. The decade is projected to bring USD 6,535.2 million of incremental sales, in FMI's estimate, leaving the 2036 market at 2.0x the 2026 size. Electric vans and trucks are the main long-term risk, since every fleet vehicle moved to batteries drops out of the diesel delivery round.
Diesel Fleets, Generators and Rural Supply Gaps
Diesel fleets in the United States will stay in service longer after California stepped back from forced truck electrification. CARB agreed in May 2025 to propose repealing the High-Priority Fleet and Drayage Fleet requirements and not to enforce them in the meantime, CCJ reported.[5] High-Priority fleets include operators running 50 or more trucks, and these large yards keep buying diesel delivered on site. Generator refuelling is a second source of volume, and Data center applications drove most of a 29% rise in Caterpillar Power Generation sales, to USD 3,098 million for April to June 2026.[6] Rented generator sets need the same service, which ties sales to growth of the power rental market. In FMI's estimate, backup generators at data centers and construction sites will add scheduled diesel drops outside the truck yard.
Rural Japan had 381 municipalities with three or fewer fuel stations at the end of fiscal 2024, including 11 with none, and mobile refuelling equipment has been allowed in rural areas since March 2021 under municipal plans.[4] The government set aside JPY 530 million in the fiscal 2026 budget for new regional fuel supply systems.[4] Station closures push farms, care homes and small businesses toward delivered fuel, which keeps orders for delivered diesel and kerosene coming in rural Japan.
Table 2: Fleet, Generator and Station Indicators for the Mobile Fuel Delivery Market (values, dates and growth), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| NextNRG sales, Q2 2026 | USD 27.7 million; up 40.9% | Fleet fueling volumes and service areas are widening. | [1] |
| Repos Energy MoU with DPIIT, March 2026 | Fuel-tech ecosystem agreement signed | Doorstep delivery gains official backing in India. | [7] |
| Rural Gyeongbuk fuel stations, 2026 | About 1,100; down from about 1,400 | Station closures widen the delivery need in Korea. | [8] |
| NextNRG active delivery vehicles, Q1 2025 | 144 vehicles; seven states | Operators expand state by state. | [3] |
| Caterpillar Power Generation sales, Q2 2026 | USD 3,098 million; up 29% | More generators need on-site diesel. | [6] |
| Japan municipalities with three or fewer stations, FY2024 | 381; up 9 | Station closures widen the delivery need. | [4] |
| German truck toll mileage index, August 2026 | Up 2% on August 2025 | More truck kilometres raise diesel use. | [2] |
Analyst Perspective
“The best returns in mobile fuel delivery over the next decade will come from generator and construction sites, because data center builders and site contractors cannot let a diesel tank run dry. Caterpillar's generator sales rose 29% in one quarter on data center work, and every one of those units needs scheduled refuelling. I would advise fuelers to sign multi-site generator contracts now, before electric vans thin out the light-vehicle round.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the mobile fuel delivery market segmented?
The market is segmented into fuel type, equipment, end use, and region. Diesel is likely to hold 62% of fuel-type sales in 2026, and trucks are expected to account for 70% of equipment sales.
By fuel type: diesel, diesel exhaust fluid, red diesel, gasoline, and bulk fuel.
By equipment: truck, generators, construction equipment, landscaping equipment, reefers, and bulk tanks.
By end use: residential, commercial, and agriculture.
By region: North America and Latin America, Western Europe and Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does diesel lead mobile fuel delivery sales by fuel type?
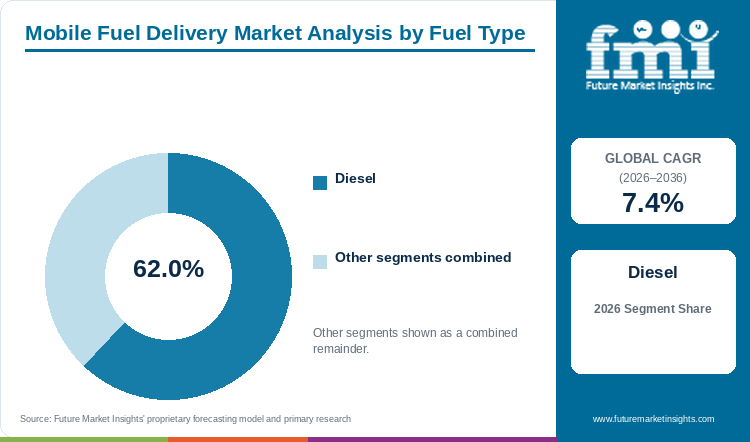
Diesel is expected to lead fuel-type sales with 62% share in 2026, ahead of gasoline at an estimated 12%.
Table 3: Fuel Type Share for the Mobile Fuel Delivery Market (percentage share), 2026
| Fuel Type | Estimated Share (2026) |
|---|---|
| Diesel | 62% |
| Gasoline | 12% |
| Diesel Exhaust Fluid | 11.5% |
| Red Diesel | 8% |
| Bulk Fuel | 6.5% |
| Total | 100.0% |
Table 4: Fuel Type Leadership and Market Growth for the Mobile Fuel Delivery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.4% |
| Leading Segment | Diesel |
Diesel is expected to account for 62% of 2026 fuel sales. Heavy trucks, generators and site machines burn diesel in volume, and one tanker stop can fill a whole yard overnight. Gasoline, an estimated 12%, goes mainly into light vans and passenger cars, which take smaller loads per stop and refuel easily at stations. Diesel exhaust fluid, about 11.5%, travels on the same truck as diesel, so DEF sales follow the diesel round. Red diesel, near 8%, is limited to off-road and farm uses allowed under fuel tax rules, which narrows the buyer list. Bulk fuel, about 6.5%, covers large tank fills for industrial sites that order less often. Some fleets also order treated winter diesel, which links delivered volumes to growth of the fuel additives market. Fleet managers pick one supplier for diesel and DEF together, which keeps diesel ahead of every other fuel.
- Fleet trucks, standby generators and earthmoving machines take most diesel drops.
- Existing delivery services in rural Gyeongbuk set minimum order quantities and face limits on delivering gasoline to passenger cars, Gyeongbuk Maeil reported on 2 September 2026.[8]
Why do trucks lead mobile fuel delivery sales by equipment?
Truck refuelling is projected to lead equipment sales with 70% share in 2026, with generators at an estimated 10.5%.
Table 5: Equipment Share for the Mobile Fuel Delivery Market (percentage share), 2026
| Equipment | Estimated Share (2026) |
|---|---|
| Truck | 70% |
| Generators | 10.5% |
| Construction Equipment | 8.5% |
| Reefers | 5% |
| Bulk Tanks | 3.5% |
| Landscaping Equipment | 2.5% |
| Total | 100.0% |
Trucks lead the equipment split, projected at 70% of 2026 sales. A parked fleet of tractors and box trucks gives a tanker dozens of fills in one yard visit, which cuts delivery cost per gallon. Generators, about 10.5% (estimated), need fuel at fixed sites such as data centers and hospitals, though each site holds fewer tanks than a truck yard. Construction equipment, near 8.5%, moves between job sites, so fuelers have to find the machines before each fill. Reefers, an estimated 5%, run diesel cooling units on refrigerated boxes parked at docks, and growth of the reefer container market adds cold boxes that burn diesel at the port gate. Bulk tanks, about 3.5%, and landscaping equipment, near 2.5%, buy in small or irregular volumes. Fuelers chasing volume will sign truck yards first and add generators on the same route.
- Tractor units, box trucks, delivery vans and refuse trucks make up the truck group.
- Construction Industries sales at Caterpillar rose 35% to USD 8,346 million in Q2 2026, with North America up 50%.[6]
Why do commercial customers lead mobile fuel delivery sales by end use?
Commercial customers are estimated to lead end-use sales with about 71% share in 2026.
Table 6: End Use Share for the Mobile Fuel Delivery Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Commercial | 71% |
| Agriculture | 17% |
| Residential | 12% |
| Total | 100.0% |
Commercial accounts lead the end-use split, estimated near 71% of 2026 sales. Logistics, construction and utility fleets sign recurring contracts that fix delivery nights and volumes, and the fueler can plan routes weeks ahead. Agriculture, about 17%, buys diesel for tractors and harvesters in peak seasons and leaves delivery trucks idle in winter months. Residential buyers, near 12%, order single fills for a car or home tank, and each stop carries a small load for the same truck time. Commercial buyers will stay ahead because one signed fleet replaces dozens of household orders.
- Logistics fleets, construction contractors, utilities and data center operators form the commercial group.
- From 14 August 2025, Parkin customers in Dubai could order CAFU fuel delivery to parked cars through an SMS or WhatsApp link.[9]
What are the drivers, restraints, and opportunities in the mobile fuel delivery market?
Fleets that park overnight in one yard are moving refuelling off the forecourt to save driver hours. Thin fuel margins and the shift to electric vans hold growth back, and rural station closures open delivery routes in places with no nearby pump.
- Driver: Fleet managers lose paid driver time on every station visit, so overnight yard fueling becomes a cost saving that grows with fleet size.
- Restraint: Margins per gallon are thin and fuel prices swing, and each van or truck converted to battery power leaves the delivery round for good.
- Opportunity: Towns and rural areas losing fuel stations need delivered fuel for farms, homes and small firms, which opens routes no forecourt serves.
Yard Fueling Saves Fleet Driver Hours
Overnight yard fueling turns refuelling from a driver task into a supplier service, and fleet buyers judge the switch on driver hours saved. NextNRG reported first-quarter 2025 gallons delivered of 4.7 million, up 183%, after integrating the Yoshi Mobility fuel division and completing the Shell Oil mobile fleet acquisition.[3] CARB agreed in May 2025 to propose repealing the High-Priority Fleet rule, which keeps large diesel fleets in place for longer.[5] Large diesel fleets that stay on the road through the 2030s will keep signing yard fueling contracts.
Thin Margins and Fleet Electrification Limit Growth
Low gross margins leave mobile fuelers little room to absorb price swings or idle trucks. For the June 2026 quarter, NextNRG gross profit grew 24.6% to USD 1.96 million against a 40.9% rise in sales to USD 27.7 million, and cash was USD 883,696 at the end of June.[1] Operators without scale will struggle to fund new tankers, and fleets moving vans to batteries will shrink the light-vehicle round.
Station Closures Open Rural Delivery Routes
Fuel station closures are creating delivery routes in rural areas that pumps no longer serve. Eleven Japanese municipalities had no fuel station and 97 had only one at the end of fiscal 2024.[4] Dubai shows the urban version of the same model, with CAFU fueling parked cars at Parkin sites since August 2025.[9] Growth of the last mile delivery market puts more vans on city streets that need depot fueling. A fueler serving rural tanks and city car parks on the same platform widens the customer base beyond truck yards.
Which country CAGRs are profiled in the mobile fuel delivery market?
Table 7: Country CAGR Comparison for the Mobile Fuel Delivery Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 8.9% |
| GCC Countries | 8.3% |
| Germany | 7.5% |
| South Korea | 7.3% |
| United States | 7.2% |
| United Kingdom | 7.1% |
| Japan | 7% |
How do country-level CAGRs compare in the mobile fuel delivery market?
German truck kilometres on tolled roads rose 2% in August 2026 against a year earlier, Destatis reported.[2] FMI estimates three countries ahead of the 7.4% global CAGR. India and the GCC Countries, at 8.9% and 8.3%, add new city fleets and app users, and Germany, at 7.5%, adds truck activity on a dense motorway network. The other four sit in a 0.3-point band below the global rate, from South Korea at 7.3% down to Japan at 7%, with American growth at 7.2% and British growth at 7.1% between them. North America leads adoption, so growth in the United States runs close to the global rate.
- Diesel users in India are moving to metered delivery from licensed bowsers.
- Drivers in Dubai can order fuel to a parked car at Parkin sites.
- German logistics yards are refuelling more trucks as toll kilometres rise.
- Courier and logistics fleets in South Korea are the main contract buyers.
- California's move to repeal the High-Priority Fleet rule keeps diesel trucks in large US fleets.
- Falling construction output in the United Kingdom slows site fueling orders.
- Rural Japan relies on delivered fuel as fuel stations close.
Full report country CAGRs cover: Fleet-heavy markets in India and GCC Countries carry the fastest rates in this list, and Germany is a little above the 7.4% global CAGR. South Korea, the United States and the United Kingdom run just below, Japan is lowest, and Latin America and Eastern Europe are given as regional tables.
Country-wise Analysis
India Mobile Fuel Delivery Market Outlook (2026 to 2036)
Construction sites, telecom towers and housing societies in India run diesel generators, and demand for delivered diesel there is predicted to rise at an 8.9% CAGR from 2026 to 2036, the top profiled rate. Repos Energy, a Pune-based platform for on-demand and trackable last-mile fuel delivery, signed a memorandum of understanding with DPIIT on 27 March 2026 to support startups in energy distribution and logistics.[7] Government backing gives doorstep operators easier access to housing societies and tower companies, and delivered fuel will replace jerry-can trips to the pump as licensed bowser operators reach more cities.
Key takeaway: Generator-heavy buyers make India the fastest market in the table.
GCC Countries Mobile Fuel Delivery Market Outlook (2026 to 2036)
CAFU began fueling cars at Parkin facilities in Dubai on 14 August 2025, with orders placed through an SMS or WhatsApp link.[9] An 8.3% CAGR is forecast for the GCC Countries through 2036, 0.9 points over the market rate of 7.4%. Parkin expects AED 5 to 7 million in annual revenue from the partnership.[9] Car park partnerships give app fuelers fixed pickup points, which will cut the cost of each consumer fill.
Key takeaway: Car park tie-ups give the GCC Countries a consumer route that most profiled countries lack.
Germany Mobile Fuel Delivery Market Outlook (2026 to 2036)
The truck toll mileage index rose 0.6% from July to August 2026 and 2% on August 2025.[2] In the FMI outlook, Germany is projected at a 7.5% CAGR from 2026 to 2036, the only profiled European country above the global rate. Rising truck kilometres raise diesel use in depots, and logistics operators will move more of that refuelling to scheduled tanker visits.
Key takeaway: Truck activity on tolled motorways places Germany 0.1 points over the global CAGR.
South Korea Mobile Fuel Delivery Market Outlook (2026 to 2036)
Delivered fuel in South Korea is likely to grow at a 7.3% CAGR to 2036, just under the global rate. Gyeongbuk province has lost about 300 fuel stations in roughly 15 years, down to about 1,100, and Gyeongbuk Maeil reported in September 2026 that farm towns are looking to mobile delivery fueling as the replacement.[8] Minimum order sizes and limits on gasoline delivery to cars still hold existing services back, and short distances between city stations keep light-vehicle drivers at the pump. Courier and construction fleets will sign most new contracts, with rural farm deliveries adding volume.
Key takeaway: Courier and construction fleet yards set the outlook for South Korea.
United States Mobile Fuel Delivery Market Outlook (2026 to 2036)
American fleets are expected to keep sales growing at a 7.2% CAGR through 2036, per FMI's country model, 0.2 points short of the 7.4% rate for the market as a whole. Second-quarter 2026 sales at NextNRG rose 40.9% to USD 27.7 million on wider fuel volumes and service areas.[1] CARB's May 2025 move to repeal the High-Priority Fleet rule keeps diesel trucks in California fleets for longer.[5] A large existing base of fleet contracts keeps the United States near the global rate, and new states such as Oklahoma add volume.
Key takeaway: New states and longer-lived diesel fleets carry growth in the United States.
United Kingdom Mobile Fuel Delivery Market Outlook (2026 to 2036)
Site fueling in the United Kingdom is anticipated to rise by a CAGR of 7.1% through 2036. Construction output in Great Britain fell 0.2% in August 2026, the fourth monthly fall in a row, and new work fell 1.4% in the three months to August.[10] Fewer new sites mean fewer generators and machines waiting for fuel, which keeps growth in the United Kingdom below the global rate.
Key takeaway: Weak site activity keeps the United Kingdom second lowest among the seven.
Japan Mobile Fuel Delivery Market Outlook (2026 to 2036)
Japan comes last in the country ranking at a 7% CAGR through 2036 in FMI's base case. The Agency for Natural Resources and Energy counted 381 municipalities with three or fewer fuel stations at the end of fiscal 2024.[4] Rural delivery will grow as stations close, though an ageing population and fewer vehicles cap overall fuel use.
Key takeaway: Station closures open rural routes in Japan, and a shrinking vehicle base keeps the CAGR lowest.
Who are the notable companies in the mobile fuel delivery market?
NextNRG (EzFill), Booster, Filld, Fuel Logic, Shipley Energy, CAFU and Fuelster are the profiled companies.
Fleet buyers award mobile fueling contracts on coverage, truck count and price per gallon. NextNRG (EzFill) ran 144 active delivery vehicles in early 2025 and added the Shell Oil mobile fleet and the Yoshi Mobility fuel division.[3] The company reported USD 27.7 million of sales for the June 2026 quarter and is building microgrids for fleet operators already on the fueling list.[1] The supply-side forces shaping market growth are truck count, driver numbers and margin per gallon, and NextNRG reported an average fuel margin of USD 0.71 per gallon in the first quarter of 2025.[3] CAFU fuels cars at Dubai car parks through a long-term Parkin partnership.[9] Booster, Filld, Fuel Logic, Shipley Energy and Fuelster complete the profiled group in FMI's company review.
- US on-demand fleet fuelers: NextNRG (EzFill), Booster and Filld.
- Regional fuel distributors: Fuel Logic and Shipley Energy.
- App-based international operators: CAFU and Fuelster.
Competitive Benchmarking: Mobile Fuel Delivery Market
Table 8: Competitive Benchmarking for the Mobile Fuel Delivery Market (qualitative documentation ratings), 2026
| Company | Fleet Coverage | Fuel Range | Digital Ordering | Recency |
|---|---|---|---|---|
| NextNRG (EzFill) | High | High | High | High |
| Booster | Medium | High | High | Low |
| CAFU | Medium | Medium | High | High |
| Shipley Energy | Medium | High | Low | Low |
| Fuel Logic | Low | Medium | Medium | Low |
Scores here reflect the amount of dated filing and release detail available, and none is a market share.
Key Developments in the Mobile Fuel Delivery Market
- On 15 October 2026, the Office for National Statistics reported a 0.2% fall in construction output in Great Britain for August.[10]
- On 9 September 2026, Destatis reported a 2% rise in German truck toll kilometres for August against a year earlier.[2]
- On 2 September 2026, Gyeongbuk Maeil reported fuel station closures across rural Gyeongbuk and the case for mobile delivery fueling.[8]
- NextNRG announced on 13 August 2026 a 40.9% sales gain for the June quarter, to USD 27.7 million.[1]
- On 4 August 2026, Caterpillar reported Power Generation sales up 29%, mainly in data center applications.[6]
- On 3 June 2026, Japan's Agency for Natural Resources and Energy presented plans for areas with few fuel stations.[4]
- On 27 March 2026, Repos Energy signed a memorandum of understanding with DPIIT to build a fuel-tech ecosystem in India.[7]
- On 13 August 2025, Parkin and CAFU announced on-demand fuel delivery at Parkin car parks in Dubai.[9]
- On 21 May 2025, NextNRG reported first-quarter gallons of 4.7 million after the Shell Oil mobile fleet acquisition.[3]
- In May 2025, CARB agreed to propose repealing the Advanced Clean Fleets High-Priority and Drayage requirements.[5]
Key Players in the Mobile Fuel Delivery Market
US On-Demand Fleet Fuelers
- NextNRG (EzFill)
- Booster
- Filld
Regional Fuel Distributors
- Fuel Logic
- Shipley Energy
App-Based International Operators
- CAFU
- Fuelster
Mobile Fuel Delivery Market - Report Scope
Table 9: Report Scope for the Mobile Fuel Delivery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Fuel type; equipment; end use; region |
| Quantitative units | USD million |
| Market definition | On-site delivery of diesel, diesel exhaust fluid, red diesel, gasoline and bulk fuel by tanker truck to fleets, generators, construction and landscaping equipment, reefers, bulk tanks and private vehicles. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | NextNRG (EzFill), Booster, Filld, Fuel Logic, Shipley Energy, CAFU, Fuelster |
| Forecast period | 2026 to 2036 |
Mobile Fuel Delivery Market - Research Methodology
Table 10: Research Methodology for the Mobile Fuel Delivery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Fueler filings, equipment maker results, statistics office releases, regulator guidance and trade press from May 2025 onward. |
| Desk Research | Desk research covers fleet rules, generator use, truck mileage, construction output and station closures. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 5,840.0 million and the 7.4% CAGR from 2026 to 2036. |
| Data Validation | Sales, gallons, rule dates and station counts were matched to the filing or agency that issued them. |
Mobile Fuel Delivery Market by Segments
Mobile Fuel Delivery Market segmented by Fuel Type:
- Diesel
- Diesel Exhaust Fluid
- Red Diesel
- Gasoline
- Bulk Fuel
Mobile Fuel Delivery Market segmented by Equipment:
- Truck
- Generators
- Construction Equipment
- Landscaping Equipment
- Reefers
- Bulk Tanks
Mobile Fuel Delivery Market segmented by End Use:
- Residential
- Commercial
- Agriculture
Mobile Fuel Delivery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] NextNRG, Inc. (2026, August 13). NextNRG Reports Second Quarter 2026 Financial Results. Exhibit 99.1 to Form 8-K. https://www.sec.gov/Archives/edgar/data/0001817004/000149315226037830/ex99-1.htm
- [2] Statistisches Bundesamt (Destatis). (2026, September 9). Lkw-Maut-Fahrleistungsindex im August 2026, +0,6 % zum Vormonat. Press release No. 319. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/09/PD26_319_421.html
- [3] NextNRG, Inc. (2025, May 21). NextNRG Reports Q1 2025 Revenues up 147% Year-over-Year. Exhibit 99.1 to Form 8-K. https://www.sec.gov/Archives/edgar/data/1817004/000164117225011911/ex99-1.htm
- [4] Agency for Natural Resources and Energy. (2026, June 3). (Measures for areas with few service stations). https://www.chisou.go.jp/sousei/about/chiisanakyoten/meeting/pdf/r08-0603_2-8_keisanshou.pdf
- [5] CCJ. (2025, May 7). CARB agrees to officially repeal Advanced Clean Fleets. https://www.ccjdigital.com/alternative-power/article/15745098/carb-to-formally-repeal-advanced-clean-fleets-rule
- [6] Caterpillar Inc. (2026, August 4). Caterpillar Reports Second-Quarter 2026 Results. Exhibit 99.1 to Form 8-K. https://www.sec.gov/Archives/edgar/data/0000018230/000001823026000040/ex991toformcat2q2026earnin.htm
- [7] The Week. (2026, March 27). Fuel-tech firm Repos Energy inks MoU with DPIIT to help develop fuel tech ecosystem. https://www.theweek.in/news/biz-tech/2026/03/27/repos-energy-dpiit-fuel-tech-mou.amp.html
- [8] Gyeongbuk Maeil. (2026, September 2). (A one-hour round trip to refuel, rural Gyeongbuk and Pohang face disappearing fuel stations). https://www.kbmaeil.com/article/20260901500862
- [9] Government of Dubai Media Office. (2025, August 13). Parkin and CAFU Launch Region's First On-Demand Fuel and Car Wash Service. https://www.mediaoffice.ae/en/news/2025/august/13-08/parkin-and-cafu-launch-region-1st
- [10] Office for National Statistics. (2026, October 15). Construction output in Great Britain, August 2026. https://www.ons.gov.uk/businessindustryandtrade/constructionindustry/bulletins/constructionoutputingreatbritain/august2026
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the mobile fuel delivery market during 2026?
- What market size is projected by 2036?
- Which fuel type holds notable share?
- Which equipment holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Fuel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Fuel Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Fuel Type, 2026 to 2036
- Diesel
- Diesel Exhaust Fluid
- Red Diesel
- Gasoline
- Bulk Fuel
- Y-o-Y Growth Trend Analysis By Fuel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Type, 2026 to 2036
- Global Market Analysis and Forecast, By Equipment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Equipment, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Equipment, 2026 to 2036
- Truck
- Generators
- Construction Equipment
- Landscaping Equipment
- Reefers
- Bulk Tanks
- Y-o-Y Growth Trend Analysis By Equipment, 2021 to 2025
- Absolute $ Opportunity Analysis By Equipment, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Residential
- Commercial
- Agriculture
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Fuel Type
- By Equipment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Type
- By Equipment
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Type
- By Equipment
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Fuel Type
- By Equipment
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- NextNRG (EzFill)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Booster
- CAFU
- Shipley Energy
- Fuel Logic
- Filld
- Fuelster
- NextNRG (EzFill)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Fuel Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Equipment, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Fuel Type
- Figure 6: Global Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Equipment
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Fuel Type
- Figure 26: North America Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Equipment
- Figure 29: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End Use
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Fuel Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Equipment
- Figure 39: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End Use
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Fuel Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Equipment
- Figure 49: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End Use
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Fuel Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Equipment
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Fuel Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Equipment
- Figure 69: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End Use
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Fuel Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Equipment
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Fuel Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Equipment, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Equipment, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Equipment
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the mobile fuel delivery market expected in 2026?
In 2026, demand for mobile fuel delivery is projected to reach USD 6.3 billion in 2026, against USD 5.8 billion in 2025. FMI expects USD 12.8 billion by 2036.
What CAGR is projected for the mobile fuel delivery market through 2036?
Growth is forecast at a 7.4% CAGR between 2026 and 2036. Overnight yard fueling for diesel truck fleets is the main driver.
Which fuel type holds a notable market share in 2026?
Diesel will hold 62% share in 2026. Gasoline is a distant second at an estimated 12%.
Which equipment holds a notable market share in 2026?
Trucks are likely to lead with 70% share in 2026. Generators follow near 10.5% (estimated).
Which country has a notable expansion outlook through 2036?
Among the profiled countries, India leads on an 8.9% CAGR from 2026 to 2036, as per FMI. Japan is the lowest at 7%.
Who are the key companies in the mobile fuel delivery market?
NextNRG (EzFill), Booster, Filld, Fuel Logic, Shipley Energy, CAFU and Fuelster are the key companies. NextNRG (EzFill) absorbed the Shell Oil mobile fleet and the Yoshi Mobility fuel division in 2025.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
