
- Market Size (2026)
- USD 9.5 Bn
- Forecast (2036)
- USD 41.9 Bn
- CAGR (2026 to 2036)
- 16.0%
How big is Open Source Intelligence Market in 2026?
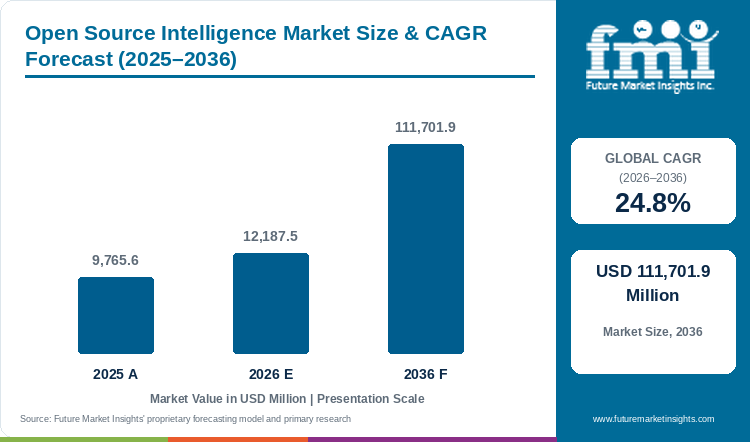
Assessed at USD 8.2 billion in 2025 and progressing to USD 9.5 billion in 2026, the open source intelligence market valuation is on course to reach USD 41.9 billion by 2036, supported by a forecast-period CAGR of 16.0%.
Table 1: Market Size and Forecast for the Open Source Intelligence Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 8.2 billion |
| Estimated Market Size in 2026 | USD 9.5 billion |
| Projected Market Size by 2036 | USD 41.9 billion |
| CAGR, 2026 to 2036 | 16.0% |
| Added Revenue, 2026 to 2036 | USD 32.4 billion |
The global open source intelligence market was valued at USD 8.2 billion in 2025 and is estimated to reach USD 9.5 billion in 2026. The market is projected to reach USD 41.9 billion by 2036, expanding at a compound annual growth rate (CAGR) of 16.0% between 2026 and 2036. Public Social and Web commands a 48.0% portion of 2026 spending as military commands and corporate security teams triage public messaging channels before threats strike internal networks. FMI demand analysis indicates that buyer procurement is shifting from manual browser toolkits to automated multi-language ingestion seats, since human analysts can no longer clear splintered dark-web feeds within statutory incident windows. That pre-incident collection cadence separates the industry from digital forensics investigation tools expanding at an 11.4% CAGR, where purchasing follows post-breach device seizure rather than continuous external reconnaissance. Suppliers are expanding integrated workflow platforms to convert this demand, with Palantir scaling its Artificial Intelligence Platform across defense and commercial accounts in 2026 and Janes combining validated military databases with Seerist geopolitical risk feeds in September 2026. Intelligence directors renew platform subscriptions on verified source provenance and automated cross-lingual entity resolution that cut analyst triage time through 2036.
Key Market Trends & Insights
- By source type: Public Social and Web holds an estimated 48.0% share in 2026 as real-time monitoring of surface forums and public messaging groups provides the earliest warning of coordinated cyber and physical threats.
- By solution type: OSINT Analytics Platforms represent 44.0% in 2026 since automated graph databases resolve aliases, corporate registries, and network infrastructure into unified investigation views.
- By end-user sector: National Security Agencies account for 56.0% in 2026 owing to multi-year unclassified intelligence modernization programs across allied military commands.
- By deployment mode: Cloud-Native OSINT Suites secure 62.0% in 2026 through elastic petabyte-scale web indexing and continuous crawler updates without on-premises server maintenance.
- By analytical technique: Multilingual Text Mining commands 41.0% in 2026 driven by automated translation and entity extraction across more than 100 languages.
Regional Highlights
- Top national expansion: Australia leads national growth projections at a 17.3% CAGR through 2036 under Project REDSPICE intelligence investments and Indo-Pacific threat monitoring.
- Broader country progression: The United Kingdom tracks at a 16.6% CAGR ahead of Canada at 16.5% and the United States at 16.2%, while France advances at a 14.4% CAGR.
Market Size & Forecast
Security operations centers and national intelligence cells confront a fragmented external threat environment where state-sponsored proxies and ransomware syndicates coordinate across encrypted messaging boards and ephemeral dark-web leak sites. When investigators rely on manual keyword searches across disconnected repositories, language barriers and alias rotation delay threat attribution until after network intrusion occurs. In April 2026, Europol reported in its Internet Organised Crime Threat Assessment that cybercriminals and state-aligned hacking coalitions are rapidly migrating across splintered dark-web marketplaces and end-to-end encrypted surface channels to evade law enforcement takedowns. Government and enterprise buyers are therefore expanding multi-year commitments for automated open-source intelligence platforms that correlate surface and dark-web telemetry in real time.
Vulnerability Exploitation & Triage Telemetry
Table 2: Open Threat Telemetry and Ingestion Indicators for the Open Source Intelligence Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 8.2 | 9.5 | 41.9 |
| Disclosed N-day vulnerabilities exploited in the wild (annual count) | 127 | 216 | 680 to 740 |
| High-risk CVE weaponization events tracked across open feeds | 28 | 112 | 420 to 490 |
| Automated multilingual feed ingestion share (%) | 54.0% to 58.0% | 61.0% to 65.0% | 84.0% to 88.0% |
Operational note: Vulnerability weaponization and automated ingestion ranges reflect documented N-day exploitation counts and enterprise open-source feed automation rates.
Rapid weaponization of newly disclosed software vulnerabilities forces enterprise vulnerability management teams to monitor public code repositories, researcher blogs, and criminal forums simultaneously. Data published by the Google Threat Intelligence Group in September 2026 shows that 141 distinct vulnerabilities were disclosed and exploited in the wild between January and August 2026, surpassing the 127 exploited across all of 2025 as high-risk CVE exploitation more than doubled from 28 to 75. That compressed window between public disclosure and active exploitation compels security directors to purchase automated open-source ingestion engines that flag proof-of-concept exploit code hours before standard signature feeds update.
Analyst Seat Deployment & Triage Economics
Table 3: Analyst Seat Deployment and Triage Indicators for the Open Source Intelligence Market (thousands and operational percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Enterprise and government OSINT analyst seats (thousand) | 310.0 | 355.0 | 1,120.0 |
| Annual software spend per intelligence cell (USD thousand) | 26.5 to 31.0 | 28.0 to 33.5 | 42.0 to 49.0 |
| Average analyst triage window per incident (minutes) | 90.0 | 45.0 | 12.0 |
| Cloud-native subscription deployment share (%) | 59.0% to 61.0% | 62.0% to 64.0% | 76.0% to 80.0% |
Table 4: Institutional and Solution Spending Indicators for the Open Source Intelligence Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 9.5 billion | 2026 global industry valuation baseline |
| AI threat-triage utilization growth | 605% increase | FBI 18-month threat triage telemetry benchmark |
| National security and defense share, 2026 | 56.0% | Unclassified IC OSINT Strategy procurement allocation |
| OSINT analytics platform revenue, 2026 | USD 4.2 billion | 44.0% solution category allocation |
Law enforcement and corporate risk departments measure open-source platform return on investment by how many minutes an analyst saves when verifying an external threat actor or supply-chain disruption. In April 2026, the Federal Bureau of Investigation reported that its Internet Crime Complaint Center received nearly 3,000 daily complaints and logged 22,364 artificial-intelligence-related fraud filings costing Americans nearly USD 893 million through fake social profiles and voice clones. Automated first-pass translation and source credibility scoring allow lean security teams to handle surging alert volumes without proportional headcount expansion.
Analyst Perspective
"Defense commands and enterprise security officers no longer buy open source intelligence tools merely to scrape web pages; they buy verified source provenance and compressed decision time across dozens of languages. Platform vendors that combine court-admissible evidence capture with domain-tuned entity graphs will secure multi-year seat renewals as synthetic media floods the open web."
- Sudip Saha, Principal Consultant, Future Market Insights.
How is the open source intelligence market segmented?
The open source intelligence market is segmented by source type, solution type, end-user sector, deployment mode, and analytical technique. In 2026, Public Social and Web is projected at 48.0%, OSINT Analytics Platforms at 44.0%, National Security Agencies at 56.0%, Cloud-Native OSINT Suites at 62.0%, and Multilingual Text Mining at 41.0%.
By source type: Public Social and Web, Commercial Satellite GEOINT, Broadcasts and Dark Web, and Academic and Patent Records.
By solution type: OSINT Analytics Platforms, Data Visualization Engines, Managed Threat Intelligence, and Automated Web Scrapers.
By end-user sector: National Security Agencies, Police Cybercrime Units, Corporate Brand Protection, Financial Fraud Teams, and Incident Response Providers.
By deployment mode: Cloud-Native OSINT Suites, On-Premises Air-Gapped Systems, Sovereign Hybrid Clouds, and Field Investigation Kits.
By analytical technique: Multilingual Text Mining, Entity Graph Mapping, Geospatial Image Correlation, and Deepfake Media Verification.
Why does Public Social and Web lead the source type category?
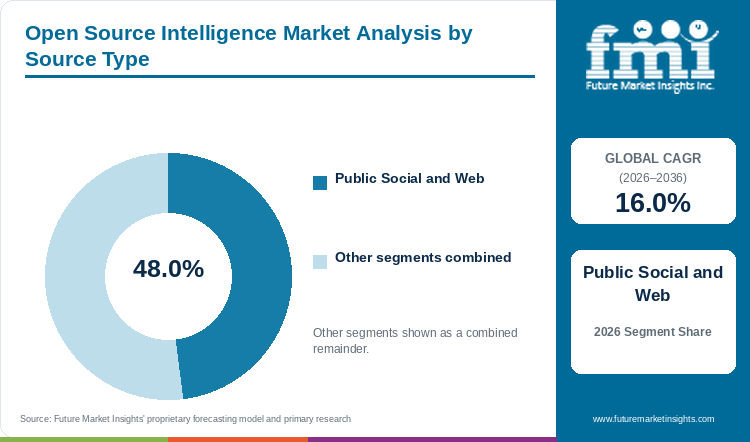
Public Social and Web holds an estimated 48.0% of source type demand in 2026, anchored by continuous surface-web, messaging-channel, and forum ingestion across defense and corporate security teams.
Table 5: Source Type Share for the Open Source Intelligence Market (percentage share), 2026
| Source Type | Share (2026) |
|---|---|
| Public Social and Web | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining source type categories account for the balance of 2026 global open source intelligence demand.
Table 6: Source Type Leadership and Market Growth for the Open Source Intelligence Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 16.0% |
| Leading Segment | Public Social and Web |
Public Social and Web forms the foundational data layer for modern investigations since threat actors, activist groups, and corporate insiders continuously broadcast operational intent across public social networks and open forums. Security teams integrating cyber threat intelligence platforms prioritize social and web collection given that it requires zero sensor hardware deployment while exposing leaked credentials and infrastructure misconfigurations in real time. Platform rate-limiting and anti-scraping captchas remain the primary operational hurdle, prompting buyers to favor vendors with compliant commercial firehose agreements.
- Within the source type category, Public Social and Web is projected to account for a leading 48.0% share in 2026, supported by continuous demand for early warning across corporate risk and law enforcement units.
- Operational findings published by ShadowDragon in December 2025 confirm that open-source social and web correlation matured into a mandatory enterprise risk discipline by late 2025, enabling investigators to map alias networks in 30 to 90 minutes.
What sustains OSINT Analytics Platforms leadership in the solution type segment?
OSINT Analytics Platforms represent 44.0% of the solution type category in 2026, supported by automated entity resolution and link-graph visualization.
OSINT Analytics Platforms capture the largest share of buyer budgets since raw open-web collection is useless without an analytical ontology that resolves millions of disparate text, image, and network records into actionable intelligence graphs. Organizations pairing open-source feeds with proactive threat hunting services rely on integrated software suites to score source reliability and automate alert routing into security operations centers. Active commercial adoption reflects this platform shift, as Palantir Technologies reported in November 2026 that third-quarter 2026 U.S. government revenue grew 96% year over year while U.S. commercial revenue surged 148% on ontology and AI platform adoption. High implementation complexity and analyst training curves still challenge mid-sized buyers during initial rollouts.
- In 2026, OSINT Analytics Platforms are anticipated to capture 44.0% of the solution type segment as enterprises consolidate standalone scraping scripts into unified investigation workbenches.
- Over the forecast period through 2036, software platform vendors that embed autonomous agentic triage and pre-built connectors for corporate identity directories are expected to outpace standalone ingestion tool providers.
How do National Security Agencies lead the end-user sector category?
National Security Agencies account for 56.0% of end-user sector demand in 2026, driven by unclassified open-source mission integration.
National Security Agencies anchor global purchasing given that military intelligence directorates treat publicly available information as the primary foundation intelligence discipline rather than a secondary supplement to classified sensors. Defense commands deploying zero trust security architectures use unclassified open-source platforms to share real-time order-of-battle, maritime AIS tracking, and geopolitical warning indicators with coalition partners without lengthy declassification delays. Strict cross-domain security accreditation and air-gap transfer rules nevertheless lengthen procurement cycles for new commercial vendors entering defense tenders.
- By end-user sector, National Security Agencies are estimated to represent 56.0% of total demand in 2026, driven by sustained defense budget allocations for unclassified multi-source intelligence fusion.
- Defense industry discussions documented by Janes at the July 2026 DoDIIS conference confirm that military commands now prioritize machine-speed OSINT validation and trusted data provenance to compress battlespace decision cycles.
Why do Cloud-Native OSINT Suites lead the deployment mode category?
Cloud-Native OSINT Suites secure 62.0% of deployment mode share in 2026, supported by elastic petabyte-scale web indexing and zero-maintenance updates.
Cloud-Native OSINT Suites dominate buyer selection given that indexing billions of daily web pages, paste-site dumps, and dark-web onion forums requires elastic compute and distributed proxy rotation that on-premises server rooms cannot economically sustain. Corporate security directors running identity threat detection software prefer cloud-delivered intelligence subscriptions since vendor-managed crawlers continuously adapt to changing website schemas and Tor mirror addresses. In February 2026, Recorded Future's Insikt Group documented in its 2026 State of Security report that threat actors splintered into smaller and faster operations across fragmented domains in 2025, making continuous cloud-scale telemetry essential for defender warning time. Data sovereignty rules in defense ministries remain the main restraint on public cloud adoption.
- Cloud-Native OSINT Suites are projected to secure 62.0% of deployment mode share in 2026, supported by rapid subscription onboarding and shared global threat telemetry.
- While multi-tenant cloud platforms retain majority volume through 2036, hybrid sovereign cloud deployments are forecast to gain incremental share among European and Middle Eastern defense agencies.
What gives Multilingual Text Mining the leading position in analytical technique?
Multilingual Text Mining commands 41.0% of analytical technique share in 2026, anchored by cross-lingual translation and sentiment extraction.
Multilingual Text Mining leads the analytical technique hierarchy since over four-fifths of open-source intelligence arrives as unstructured text spanning foreign news broadcasts, regulatory dockets, and colloquial forum chatter. Financial compliance and threat teams evaluating artificial intelligence security platforms depend on domain-tuned NLP pipelines to extract named entities, ownership links, and threat intent without hallucinating false positives. Regional slang, code-mixed dialects, and adversarial prompt manipulation remain persistent technical hurdles requiring hybrid symbolic and neural language models.
- With a projected 41.0% share of the analytical technique category in 2026, Multilingual Text Mining remains the core analytical engine for cross-lingual intelligence extraction.
- Technical analysis released by Expert.ai in September 2026 demonstrates why regulated banking and intelligence teams adopt Composite AI combining deterministic domain rules with language models to ensure explainable, audit-ready text extraction.
What are the drivers, restraints, and opportunities in the open source intelligence market?
In the open source intelligence market, splintered dark-web threat channels and unclassified defense mandates are projected to drive adoption whereas social platform API restrictions restrain uncalibrated scraping and domain-tuned language models create new demand avenues.
- Driver: Splintered dark-web extortion channels and mandatory unclassified defense intelligence modernization compel government and corporate security teams to automate multi-source open-web collection.
- Restraint: Aggressive social media API paywalls, anti-bot rate limits, and surging AI-generated synthetic disinformation increase verification friction and false-positive triage costs.
- Opportunity: Instruction-tuned cybersecurity language models and integrated geospatial-to-cyber correlation workflows create new high-margin subscription avenues across supply-chain risk and financial crime compliance.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Geopolitical hybrid warfare and supply-chain cyber dependencies are compelling both public agencies and private enterprises to expand continuous open-source threat monitoring outside their network perimeters. When state-affiliated hacking groups and hacktivist coalitions coordinate DDoS and ransomware campaigns across public Telegram channels and regional forums, internal firewall logs provide zero advance warning. Automated open-source feeds paired with security orchestration and automation playbooks allow defenders to block malicious infrastructure and patch targeted vulnerabilities before attacks strike. In September 2026, the European Union Agency for Cybersecurity confirmed in its ENISA Threat Landscape 2026 report that expanding digital supply-chain dependencies and convergent cybercrime-espionage tactics require continuous external threat vigilance across European sectors. That operational imperative is driving sustained multi-year seat expansion across defense, energy, and financial buyers.
Risk Assessment of the Open Source Intelligence Market: Operational and Formulation Friction
Restrictive platform API policies and the rapid proliferation of synthetic AI-generated text, deepfake imagery, and bot-amplified narratives represent the primary operational barriers restraining uncalibrated open-source intelligence adoption. As major social media networks lock down public application programming interfaces or charge prohibitive enterprise data licensing fees, automated web scrapers face frequent schema breaks and legal compliance reviews. Simultaneously, adversaries flood public forums with synthetic personas that contaminate unverified ingestion pipelines. In January 2026, researchers at Maltego Technologies documented in their Future of OSINT study that restricted platform access and synthetic media have complicated source attribution and verification for investigative analysts. Buyers consequently withhold budget from raw scraping tools until vendors prove cryptographic source capture and provenance scoring.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Software vendors are capturing premium contract value by pairing domain-tuned cybersecurity language models with multi-layered geospatial intelligence analytics solutions that verify physical and digital events simultaneously. General-purpose foundation models frequently misclassify technical MITRE ATT&CK techniques, vulnerability severity scores, and corporate subsidiary structures unless they are fine-tuned on curated security corpora. In October 2026, computer scientists publishing on arXiv demonstrated that targeted gradient and quality instruction-tuning frameworks enable 7-billion and 8-billion parameter models to match full-dataset threat attribution and vulnerability correlation accuracy at a fraction of the compute cost. Deployment of these compact domain-tuned models into air-gapped and sovereign cloud OSINT workbenches creates lucrative expansion avenues across defense, central banking, and semiconductor supply-chain security teams.
Open Source Intelligence Market by Country (2026 to 2036)
FMI country modeling indicates that Australia leads open source intelligence expansion at a 17.3% CAGR through 2036, while France advances at a 14.4% CAGR. Commercial adoption across Five Eyes intelligence agencies, European industrial exporters, and East Asian technology hubs hinges on national cyber defense legislation and sovereign cloud accreditation.
Table 7: Country CAGR and Primary Growth Levers for the Open Source Intelligence Market (CAGR percentage and operational drivers), 2026 to 2036
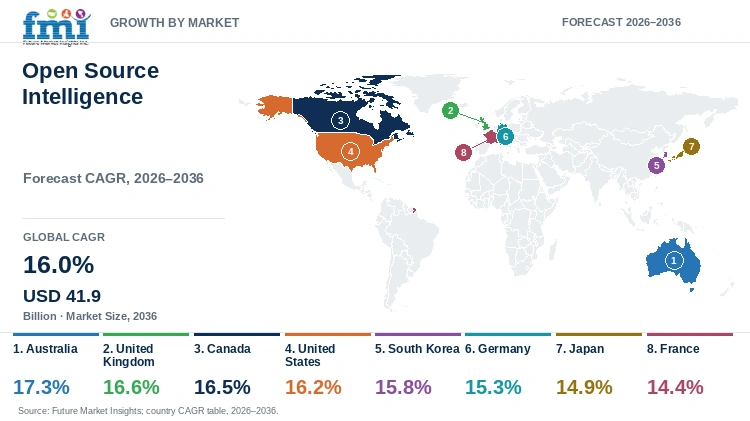
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 17.3% | Project REDSPICE intelligence expansion and 4,400+ annual entity threat notifications |
| United Kingdom | 16.6% | NCSC automated cyber defense workflows and Five Eyes open-source fusion |
| Canada | 16.5% | Federal critical infrastructure protection against agentic AI reconnaissance |
| United States | 16.2% | ODNI IC OSINT Strategy unclassified procurement and Fortune 500 threat cells |
| South Korea | 15.8% | Semiconductor supply-chain counter-espionage and dark-web leak monitoring |
| Germany | 15.3% | BSI explainable AI security validation and industrial export risk screening |
| Japan | 14.9% | Active Cyber Defense legislation and IPA geopolitical threat monitoring |
| France | 14.4% | Sovereign defense intelligence clouds and European strategic autonomy programs |
Source: Future Market Insights analysis
Australia Open Source Intelligence Market Outlook (2026 to 2036)
Demand for open source intelligence in Australia is projected to expand at a leading 17.3% CAGR between 2026 and 2036 as federal defense, telecom, and critical minerals operators scale Indo-Pacific threat reconnaissance. Domestic commercial demand is driven by the Australian Government's multi-year Project REDSPICE intelligence buildout and mandatory critical infrastructure risk monitoring across energy and port operators. In October 2026, the Australian Signals Directorate reported in its Annual Cyber Threat Report 2025 to 2026 that its Australian Cyber Security Centre responded to more than 1,500 incidents and issued over 4,400 proactive malicious-activity notifications to entities for nearly an 80% annual increase. Local security teams consequently invest heavily in automated multilingual Indo-Pacific forum and dark-web ingestion platforms.
Key takeaway: In Australia, Project REDSPICE intelligence expansion and proactive critical infrastructure threat notifications are projected to drive leading adoption of multilingual OSINT platforms.
United Kingdom Open Source Intelligence Market Outlook (2026 to 2036)
Procurement of open source intelligence platforms in the United Kingdom is estimated to advance at a 16.6% CAGR from 2026 to 2036 across defense intelligence units, police Regional Organised Crime Units, and London financial institutions. British agencies combine national security open-source fusion with commercial financial fraud and sanctions-evasion tracking. In November 2026, the UK National Cyber Security Centre noted in its 2026 Annual Review that operational cyber defense is shifting toward AI-assisted evidence correlation and continuous contextual threat intelligence across public and private partners. Strict UK evidentiary chain-of-custody standards further drive police and corporate investigators toward verified link-analysis and browser-capture software.
Key takeaway: In the United Kingdom, AI-assisted national cyber defense correlation and City of London financial sanctions screening are estimated to sustain rapid OSINT software growth.
Canada Open Source Intelligence Market Outlook (2026 to 2036)
In Canada, open source intelligence adoption is forecast to grow at a 16.5% CAGR over the 2026 to 2036 period as federal ministries and banking groups counter state-backed reconnaissance and Arctic geopolitical risks. Canadian procurement diverges from standard commercial averages through bilingual English-French NLP requirements and close Five Eyes threat-sharing integration under the National Cyber Security Strategy. In October 2026, the Canadian Centre for Cyber Security warned in a national cyber threat bulletin that state and criminal adversaries are deploying agentic artificial intelligence to automate open-source target reconnaissance and social engineering against Canadian organizations. That escalating automated threat pressure compels Canadian security directors to deploy defensive OSINT platforms that audit external digital footprints continuously.
Key takeaway: In Canada, federal counter-reconnaissance directives and Five Eyes intelligence sharing are forecast to accelerate enterprise and government OSINT seat deployments.
United States Open Source Intelligence Market Outlook (2026 to 2036)
Commercial and federal open source intelligence demand in the United States is anticipated to progress at a 16.2% CAGR through 2036 across the 18 Intelligence Community agencies, combatant commands, and Fortune 500 global security operations centers. What sets the United States apart from all other national markets is the scale of unclassified commercial-first procurement mandated under the ODNI IC OSINT Strategy coupled with massive private-sector dark-web ransomware monitoring. In August 2026, the Cybersecurity and Infrastructure Security Agency issued Advisory AA26-222A detailing how double-extortion ransomware affiliates recruit on dark-web forums and operate Tor-based leak portals targeting American healthcare and manufacturing entities. Federal FedRAMP High authorization requirements and strict privacy compliance govern vendor selection across domestic agencies.
Key takeaway: In the United States, unclassified Intelligence Community procurement and enterprise dark-web extortion monitoring are anticipated to anchor the largest national OSINT customer base.
South Korea Open Source Intelligence Market Outlook (2026 to 2036)
South Korea's open source intelligence sector is projected to register a 15.8% CAGR between 2026 and 2036, driven by defense command modernization and semiconductor intellectual-property protection. South Korean conglomerates and defense agencies prioritize deep-web technical leak detection and North Korean state-actor attribution across Asian-language forums. In September 2026, the U.S. National Institute of Standards and Technology CAISI published a technical evaluation of frontier Asian language model cyber capabilities, confirming how rapidly automated code and reconnaissance models are evolving across the region. Korean security buyers consequently specify OSINT platforms with high-accuracy Hangul, Mandarin, and Russian natural language processing.
Key takeaway: In South Korea, semiconductor trade-secret protection and sovereign cyber threat attribution are projected to sustain strong demand for Asian-language OSINT analytics.
Germany Open Source Intelligence Market Outlook (2026 to 2036)
Open source intelligence adoption in Germany is slated to expand at a 15.3% CAGR across the 2026 to 2036 window as federal security authorities, automotive OEMs, and machinery exporters strengthen supply-chain due diligence and NIS2 compliance. German buyer behavior differs from Anglo-American patterns due to strict Bundesdatenschutzgesetz privacy rules and a strong preference for explainable, on-premises or sovereign-cloud graph investigation workbenches. In November 2025, the German Federal Office for Information Security documented in its State of IT Security in Germany report how foreign Doppelganger disinformation operations deployed fake media domains and social bots across more than 100 tracked campaigns targeting German public discourse. Domestic investigators and industrial risk teams therefore favor Munich-based Maltego and certified European NLP vendors that provide transparent, auditable link provenance.
Key takeaway: In Germany, strict NIS2 supply-chain compliance and BSI explainable-AI standards are slated to favor auditable graph analysis and sovereign OSINT platforms.
Japan Open Source Intelligence Market Outlook (2026 to 2036)
Demand for open source intelligence solutions in Japan is predicted to rise at a 14.9% CAGR from 2026 to 2036, supported by national Active Cyber Defense reforms and financial sector anti-phishing programs. Japan commercial expansion is shaped by historic constitutional constraints limited proactive government cyber reconnaissance until recent legislative updates expanded public-private threat telemetry sharing. In September 2026, the Information-technology Promotion Agency Japan detailed in its Information Security White Paper 2026 how Japan is operationalizing public-private threat telemetry sharing and critical infrastructure cybersecurity councils under national active cyber defense reforms. Japanese ministries and trading houses are now partnering with domestic integrators and international defense primes to deploy automated Japanese-script and multilingual open-source warning platforms.
Key takeaway: In Japan, national Active Cyber Defense reforms and economic security screening are predicted to accelerate institutional adoption of automated OSINT warning systems.
France Open Source Intelligence Market Outlook (2026 to 2036)
France's open source intelligence market is expected to progress at a 14.4% CAGR between 2026 and 2036 across Ministry of Armed Forces directorates, aerospace exporters, and regulated banking groups. What differentiates French procurement from global cloud-first norms is the country's SecNumCloud sovereign hosting doctrine and strong domestic defense-electronics industrial base led by Thales and specialized European cyber startups. In April 2026, Thales reported in its 2026 Data Threat Report analysis that 61% of organizations now cite artificial intelligence as their top data security risk while nearly 60% experienced deepfake-driven attacks and 48% reported reputational damage from AI-generated misinformation. French defense and enterprise buyers consequently prioritize sovereign-hosted OSINT platforms equipped with synthetic-media verification and Francophone geopolitical risk analytics.
Key takeaway: In France, SecNumCloud data-sovereignty mandates and deepfake counter-disinformation initiatives are expected to anchor demand for sovereign OSINT platforms.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the open source intelligence market?
Palantir Technologies Inc., Recorded Future Inc., BAE Systems, Thales Group, Maltego Technologies GmbH, Janes Group UK Limited, Expert.ai SpA, Babel Street, Dataminr Inc., and ShadowDragon are the notable companies in the open source intelligence market.
Competitive positioning in the open source intelligence industry separates enterprise ontology and defense prime integrators, dedicated cyber threat intelligence clouds, and specialized link-analysis and multilingual NLP providers. Palantir Technologies, BAE Systems, and Thales Group deliver mission-critical intelligence fusion and sovereign command platforms for defense agencies. Recorded Future, Dataminr, and Janes operate continuous global threat and military intelligence clouds. Meanwhile, Maltego Technologies and Expert.ai join Babel Street and ShadowDragon in supplying link-graph and cross-lingual investigation toolkits.
- Defense Ontology and Sovereign Fusion Primes: Palantir Technologies Inc., BAE Systems, and Thales Group engineer large-scale multi-INT fusion and battlespace open-source correlation systems for military and cabinet agencies.
- Real-Time Threat and Military Intelligence Clouds: Recorded Future Inc., Dataminr Inc., and Janes Group UK Limited operate continuous global ingestion networks combining dark-web telemetry and verified defense order-of-battle databases.
- Link-Graph and Investigation Specialists: Maltego Technologies GmbH and Expert.ai SpA join Babel Street and ShadowDragon in providing investigator link-mapping workbenches and social-breach correlation tools.
Competitive Benchmarking: Open Source Intelligence Market
Table 8: Competitive Benchmarking for the Open Source Intelligence Market (qualitative capability ratings), 2026
| Company | Multilingual Ingestion Scale | Entity Graph & Link Depth | Defense & Enterprise Fit | Geographic Reach |
|---|---|---|---|---|
| Palantir Technologies Inc. | High | High | High | Global defense and commercial ontology footprint; USD 2.31B Q3 2026 revenue |
| Recorded Future Inc. | High | High | High | Global intelligence cloud integrated with Mastercard financial fraud network |
| BAE Systems | High | High | High | UK, Europe, Middle East, and Asia-Pacific national security and space OSINT |
| Thales Group | High | Medium | High | European and global defense electronics, sovereign cloud, and cyber threat labs |
| Maltego Technologies GmbH | Medium | High | High | Global link-analysis workstation standard with Hunchly evidence capture |
| Janes Group UK Limited | Medium | High | High | Global defense order-of-battle and military equipment open-source verification |
| Expert.ai SpA | High | Medium | High | European and North American composite NLP for banking and national security |
| Babel Street | High | Medium | High | U.S. federal and international cross-lingual persistent search and identity risk |
| Dataminr Inc. | High | Medium | High | Global real-time event detection and agentic AI risk alerting across 100+ languages |
| ShadowDragon | High | High | Medium | North American and European law enforcement social-link and breach investigation |
Evaluation basis: Multilingual Ingestion Scale evaluates documented real-time collection across 100+ languages and dark-web forums, while Entity Graph and Link Depth rates automated alias resolution and visual link mapping. Defense and Enterprise Fit measures accredited deployment across defense networks (such as FedRAMP High, DoDIIS, or SecNumCloud) and Fortune 500 security operations centers.
Key Developments in the Open Source Intelligence Market
- Janes Group UK Limited and Seerist partnered on September 29, 2026 to integrate Janes validated military equipment and order-of-battle intelligence with Seerist real-time geopolitical risk signals inside a single analytical workflow.
- Dataminr Inc. and Crisis24 launched an integrated real-time intelligence and agentic AI solution inside the Crisis24 Horizon platform at Global Security Exchange on September 14, 2026 to automate enterprise threat triage.
- BAE Systems Digital Intelligence signed a Memorandum of Understanding with NEC Corporation on June 15, 2026 to co-develop active cyber defense and open-source threat intelligence capabilities for government and critical infrastructure clients.
Key Players in the Open Source Intelligence Market
Defense Ontology and Sovereign Fusion Primes
- Palantir Technologies Inc.
- BAE Systems
- Thales Group
- Janes Group UK Limited
Real-Time Threat and Multilingual Intelligence Clouds
- Recorded Future Inc.
- Dataminr Inc.
- Babel Street
- Expert.ai SpA
Link-Graph and Investigator Workstation Specialists
- Maltego Technologies GmbH
- ShadowDragon
Open Source Intelligence Market - Report Scope
Table 9: Report Scope for the Open Source Intelligence Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Source Type; Solution Type; End-User Sector; Deployment Mode; Analytical Technique |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial vendor revenue from open source intelligence (OSINT) software platforms, automated web and dark-web ingestion tools, link-analysis and entity-resolution engines, commercial geospatial/imagery correlation modules, and managed open-source threat intelligence subscriptions derived from publicly available information. Category Scope Note: Excludes classified signals intelligence (SIGINT) hardware, internal-only security information and event management (SIEM) log storage, and physical background-check courier services. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, United Kingdom, Canada, United States, South Korea, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Palantir Technologies Inc., Recorded Future Inc., BAE Systems, Thales Group, Maltego Technologies GmbH, Janes Group UK Limited, Expert.ai SpA, Babel Street, Dataminr Inc., ShadowDragon |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Open Source Intelligence Market - Research Methodology
Table 10: Research Methodology for the Open Source Intelligence Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with defense intelligence collection managers, law enforcement cybercrime investigators, enterprise SOC threat-hunting directors, and OSINT platform engineers to validate seat pricing and ingestion throughput. |
| Secondary Research | Analysis of U.S. ODNI IC OSINT Strategy dockets, Europol IOCTA and ENISA Threat Landscape reports, FBI and CISA advisories, national cyber agency publications, and corporate financial disclosures. |
| Market Sizing and Forecasting | Top-down cybersecurity and defense intelligence baselines reconciled against bottom-up active analyst seat deployments (355,000 seats in 2026) and annual platform subscription expenditure from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight defense intelligence modernization budgets, mandatory NIS2 and critical infrastructure incident reporting laws, and enterprise supply-chain risk screening across eight countries. |
| Operational Benchmark Traceability | Vulnerability exploitation and triage metrics in Tables 2, 3, and 4 trace to Google Threat Intelligence Group CVE logs, FBI threat-triage telemetry, and ODNI procurement disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate publicly available information collection, correlation, and ontology software while excluding classified sensor hardware and general IT firewall appliances. |
Open Source Intelligence Market by Segments
Open Source Intelligence Market segmented by Source Type:
- Public Social and Web
- Commercial Satellite GEOINT
- Broadcasts and Dark Web
- Academic and Patent Records
Open Source Intelligence Market segmented by Solution Type:
- OSINT Analytics Platforms
- Data Visualization Engines
- Managed Threat Intelligence
- Automated Web Scrapers
Open Source Intelligence Market segmented by End-User Sector:
- National Security Agencies
- Police Cybercrime Units
- Corporate Brand Protection
- Financial Fraud Teams
- Incident Response Providers
Open Source Intelligence Market segmented by Deployment Mode:
- Cloud-Native OSINT Suites
- On-Premises Air-Gapped Systems
- Sovereign Hybrid Clouds
- Field Investigation Kits
Open Source Intelligence Market segmented by Analytical Technique:
- Multilingual Text Mining
- Entity Graph Mapping
- Geospatial Image Correlation
- Deepfake Media Verification
Open Source Intelligence Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Australian Signals Directorate. (2026, October 26). Annual Cyber Threat Report 2025-26. Australian Cyber Security Centre.
- BAE Systems plc. (2026, June 15). BAE Systems Digital Intelligence and NEC Sign MoU to Strengthen Active Cyber Defence. BAE Systems Newsroom.
- Canadian Centre for Cyber Security. (2026, October 27). Cyber Threat Bulletin: Agentic Artificial Intelligence Is Accelerating Cyber Attacks. Communications Security Establishment Canada.
- Cybersecurity and Infrastructure Security Agency. (2026, August 10). StopRansomware: Gunra Ransomware (Advisory AA26-222A). U.S. Department of Homeland Security.
- Dataminr Inc. (2026, September 14). Dataminr and Crisis24 Deliver Real-Time Intelligence and Agentic AI Solution in Crisis24 Horizon. Dataminr Press Room.
- European Union Agency for Cybersecurity. (2026, September 22). ENISA Threat Landscape 2026. ENISA Publications.
- Europol European Cybercrime Centre. (2026, April 28). New 2026 IOCTA Highlights Sophisticated Tactics and Emerging Challenges in the Digital Landscape. European Union Agency for Law Enforcement Cooperation.
- Expert.ai SpA. (2026, September 15). Composite AI: The Foundation for Mission-Critical AI in Banking. Expert.ai Technical Insights.
- Federal Bureau of Investigation. (2026, April 6). Cryptocurrency and AI Scams Bilk Americans of Billions. U.S. Department of Justice FBI Press Releases.
- Federal Office for Information Security. (2025, November 11). The State of IT Security in Germany 2025: Doppelganger Disinformation Campaign. Bundesamt fur Sicherheit in der Informationstechnik.
- Google Threat Intelligence Group. (2026, September 30). Vulnerability Discovery and Exploitation Trends in the AI Era. Google Cloud Security.
- Han Y. and Huang Z. (2026, October 15). Towards Efficient Threat Intelligence Instruction Tuning via Quality-Aware and Optimal Transport-Guided Data Selection. Cornell University arXiv.
- Information-technology Promotion Agency Japan. (2026, September 24). Information Security White Paper 2026: Public-Private Cybersecurity Coordination and Threat Analysis. Information-technology Promotion Agency Japan.
- Janes Group UK Limited. (2026, July 22). DoDIIS 2026: The Race for Decision Advantage. Janes Defence Intelligence.
- Janes Group UK Limited. (2026, September 29). Seerist and Janes Bring Real-Time Global Risk Signals and Validated Military Intelligence into One Workflow. Janes Corporate Updates.
- Maltego Technologies GmbH. (2025, May 19). Maltego Welcomes Hunchly to Expand OSINT Capabilities. Maltego Newsroom.
- Maltego Technologies GmbH. (2026, January 8). The Future of OSINT. Maltego Research.
- National Institute of Standards and Technology. (2026, September 17). CAISI Assessment of Z.ai GLM-5.3 Cyber Capabilities. U.S. Department of Commerce.
- Office of the Director of National Intelligence. (2025, January 24). The IC OSINT Strategy 2024-2026. U.S. Intelligence Community.
- Palantir Technologies Inc. (2026, November 2). Palantir Reports Q3 2026 U.S. Comm Revenue Growth of 148% Y/Y and Revenue Growth of 96% Y/Y. Palantir Investor Relations.
- Recorded Future Insikt Group. (2026, February 12). Fragmentation Defined 2025 Threat Landscape: What It Means for 2026. Recorded Future Inc.
- ShadowDragon. (2025, December 23). OSINT Year in Review 2025: How Open Source Intelligence Became Core to Enterprise Risk. ShadowDragon Research.
- Thales Group. (2026, April 14). 2026 Data Threat Report: AI Emerges as Insider Threat. Thales Cloud Protection and Licensing.
- UK National Cyber Security Centre. (2026, November 3). NCSC Annual Review 2026: The Changing Nature of Operational Cyber Defence. Government Communications Headquarters.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the open source intelligence market in 2026 and what is forecast for 2036?
- Which dark-web fragmentation and defense modernization pressures support demand for open source intelligence?
- Why does Public Social and Web lead the source type category?
- Why do OSINT Analytics Platforms lead the solution type category globally?
- How do growth rates differ across Australia, the United Kingdom, and the United States?
- Which leading companies supply defense ontology platforms versus specialized link-analysis tools today?
- What limits automated web scraping or causes false-positive triage friction in the open source intelligence market?
- What should security directors evaluate before upgrading from manual browser tools to enterprise OSINT platforms?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Type, 2026 to 2036
- Public Social and Web
- Commercial Satellite GEOINT
- Broadcasts and Dark Web
- Academic and Patent Records
- Y-o-Y Growth Trend Analysis By Source Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Type, 2026 to 2036
- Global Market Analysis and Forecast, By Solution Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Solution Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Solution Type, 2026 to 2036
- OSINT Analytics Platforms
- Data Visualization Engines
- Managed Threat Intelligence
- Automated Web Scrapers
- Y-o-Y Growth Trend Analysis By Solution Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Solution Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-User Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-User Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-User Sector, 2026 to 2036
- National Security Agencies
- Police Cybercrime Units
- Corporate Brand Protection
- Financial Fraud Teams
- Incident Response Providers
- Y-o-Y Growth Trend Analysis By End-User Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment Mode, 2026 to 2036
- Cloud-Native OSINT Suites
- On-Premises Air-Gapped Systems
- Sovereign Hybrid Clouds
- Field Investigation Kits
- Y-o-Y Growth Trend Analysis By Deployment Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Analytical Technique, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Analytical Technique, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Analytical Technique, 2026 to 2036
- Multilingual Text Mining
- Entity Graph Mapping
- Geospatial Image Correlation
- Deepfake Media Verification
- Y-o-Y Growth Trend Analysis By Analytical Technique, 2021 to 2025
- Absolute $ Opportunity Analysis By Analytical Technique, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source Type
- By Solution Type
- By End-User Sector
- By Deployment Mode
- By Analytical Technique
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Palantir Technologies Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Recorded Future Inc.
- BAE Systems
- Thales Group
- Maltego Technologies GmbH
- Janes Group UK Limited
- Expert.ai SpA
- Babel Street
- Dataminr Inc.
- ShadowDragon
- Palantir Technologies Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Source Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Solution Type, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-User Sector, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Analytical Technique, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Source Type
- Figure 6: Global Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Solution Type
- Figure 9: Global Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-User Sector
- Figure 12: Global Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Deployment Mode
- Figure 15: Global Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Analytical Technique
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source Type
- Figure 32: North America Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Solution Type
- Figure 35: North America Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-User Sector
- Figure 38: North America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Deployment Mode
- Figure 41: North America Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Analytical Technique
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Source Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Solution Type
- Figure 51: Latin America Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-User Sector
- Figure 54: Latin America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Deployment Mode
- Figure 57: Latin America Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Analytical Technique
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Source Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Solution Type
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-User Sector
- Figure 70: Western Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Deployment Mode
- Figure 73: Western Europe Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Analytical Technique
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Source Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Solution Type
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-User Sector
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Deployment Mode
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Analytical Technique
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Source Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Solution Type
- Figure 99: East Asia Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-User Sector
- Figure 102: East Asia Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Deployment Mode
- Figure 105: East Asia Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Analytical Technique
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Source Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Solution Type
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-User Sector
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Deployment Mode
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Analytical Technique
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Source Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Source Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Source Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Solution Type, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Solution Type, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Solution Type
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-User Sector, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-User Sector, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-User Sector
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Deployment Mode
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Analytical Technique, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Analytical Technique, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Analytical Technique
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the open source intelligence market in 2026, and what is forecast for 2036?
Global open source intelligence revenue stood at USD 8.2 billion during 2025. Annual spending reaches USD 9.5 billion for 2026 and climbs to USD 41.9 billion by 2036 (16.0% CAGR).
What is the CAGR for the open source intelligence market from 2026 to 2036?
The open source intelligence sector is projected to expand at a 16.0% CAGR over the 2026 to 2036 window, adding USD 32.4 billion in cumulative new revenue across software platforms and intelligence subscriptions.
Which source type segment leads the open source intelligence market?
Public Social and Web holds an estimated 48.0% of source type demand in 2026 since real-time monitoring of surface forums and messaging channels provides the earliest warning of cyber and physical risks.
Which solution type segment leads the open source intelligence market?
OSINT Analytics Platforms represent 44.0% of the solution type category in 2026 as automated ontology and link-analysis workbenches replace fragmented manual collection scripts.
Which country has a notable growth outlook during the assessment period?
Australia leads national expansion projections at a 17.3% CAGR through 2036, driven by Project REDSPICE cyber intelligence investments and Indo-Pacific critical infrastructure monitoring.
Who are the key players in the market?
Palantir Technologies Inc., Recorded Future Inc., and BAE Systems lead defense and enterprise supply with Thales Group and Janes Group UK Limited. Maltego Technologies GmbH, Expert.ai SpA, and Babel Street also hold prominent positions with Dataminr Inc. and ShadowDragon.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
