

- Market Size (2026)
- USD 12.4 Bn
- Forecast (2036)
- USD 22.3 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is Oral Clinical Nutritional Supplement Market in 2026?
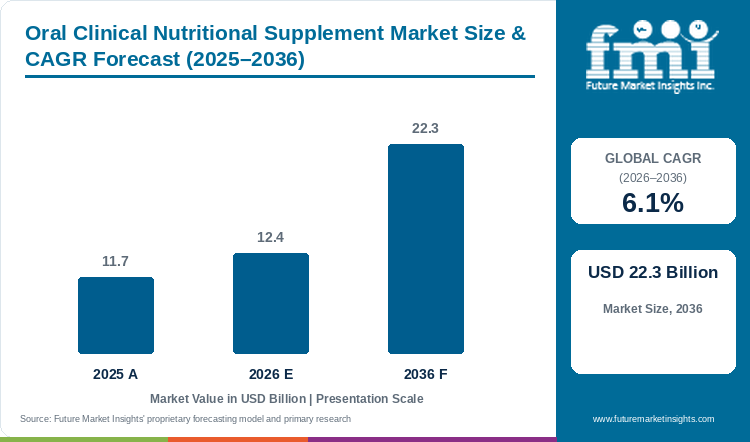
Sales in the oral clinical nutritional supplement market are projected to grow at 6.1% CAGR, with the market size rising from USD 11.7 billion in 2025 to USD 12.4 billion in 2026 and reaching USD 22.3 billion by 2036.
Clinical nutritional intervention is shifting from acute inpatient crisis management toward proactive, home-based recovery regimens, as hospitals compress length of stay to curb readmission liabilities. Malnourished or convalescing patients transitioning from intensive clinical supervision to homecare frequently experience rapid caloric deficits, positioning ready-to-consume oral supplements between routine meals and invasive tube feeding. According to Future Market Insights analysis, global oral clinical nutritional supplement market value reached USD 11.7 billion in 2025 and rises to USD 12.4 billion in 2026. The market is projected to reach USD 22.3 billion by 2036, expanding at a 6.1% CAGR over the assessment period and delivering USD 9.9 billion in added revenue. In July 2025, Abbott Laboratories reported over 6% organic sales growth in adult nutrition, driven by sustained inpatient and outpatient demand across Ensure and Glucerna product lines [1]. Standard formula commands the leading position with 67.9% share in 2026, as clinicians initiate broad macronutrient support before disease-specific restrictions are established. This supports the hypothesis that clinical nutrition demand remains tied to outpatient continuity; however, fragmented payer reimbursement and taste fatigue continue to limit uninterrupted long-term adherence.
Key Market Trends & Insights
- By product type: Standard formula is projected at 67.9% in 2026 because it can be started across routine recovery cases before a disease-specific restriction becomes clear.
- By indication: General well-being is estimated at 22.7% in 2026 as poor intake is commonly noticed before the purchase is attached with one defined disease.
- By form: Liquid is expected to hold 49.0% in 2026 since measured, ready-to-use servings reduce preparation work, though transport and packaging cost can support powder in price-sensitive use.
- By end user: Geriatric users are forecast at 44.9% in 2026 as reduced appetite and longer recovery bring repeat nutrition need into the same age group.
- By flavour: Flavoured products lead because taste fatigue appears quickly during daily use, making rotation and familiar profiles important for continuation.
Regional Highlights
- Fastest-growing evaluated country: Japan, at 7.8% CAGR from 2026 to 2036.
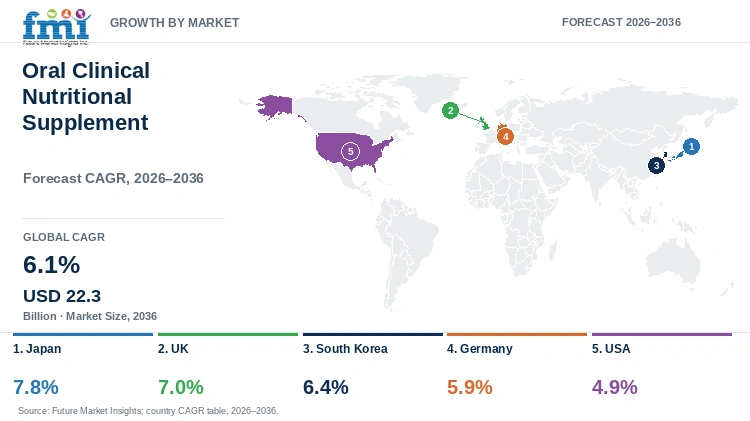
- By country: The UK at 7.0% and South Korea at 6.4% follow, while Germany records 5.9% and the USA stands at 4.9% through 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for the Oral Clinical Nutritional Supplement Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11,700 million |
| Estimated Market Size in 2026 | USD 12,400 million |
| Projected Market Size by 2036 | USD 22,300 million |
| CAGR, 2026 to 2036 | 6.1% |
| Added Revenue, 2026 to 2036 | USD 9,900 million |
Commercial conditions differ across the profiled countries owing to distinct clinical reimbursement frameworks and community care structures. Standardized screening protocols in acute facilities increasingly document nutritional deficits before hospital discharge. In September 2025, the Centers for Medicare & Medicaid Services recorded a 5.15% malnutrition diagnosis rate during clinical quality screening trials, demonstrating how structured assessments formalize nutritional intervention within discharge planning [2]. Once nutritional therapy is written into post-acute discharge plans, outpatient adherence improves, supporting recurring pharmacy dispenses and direct home shipments. Conversely, where statutory insurance ceases upon discharge, patient attrition escalates due to out-of-pocket costs.
Patient-Use and Serving-Requirement Sizing
Table 2: Patient-Use and Serving-Requirement Sizing for the Oral Clinical Nutritional Supplement Market (USD million and scenario indicators), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 11,700 | 12,400 | 22,300 |
| Estimated annual users (million) | 78 to 91 | 82 to 96 | 128 to 151 |
| Average servings per user per year | 52 to 68 | 54 to 70 | 60 to 82 |
| Implied annual spend per user (USD) | 129 to 150 | 129 to 151 | 148 to 174 |
Per Capita and Care-Channel Sizing
Oral supplements are gaining use where a patient is able to swallow but an ordinary meal is not giving enough intake. This middle position is important because it can delay the movement towards enteral nutrition and gives the patient a format that can be taken without clinical equipment. Ready-to-drink products reduce preparation work, but convenience supports repeat sales only when taste and serving size remain manageable. This is bringing oral products closer to wider clinical nutrition pathways across hospitals, pharmacies and home care.
Table 3: Per Capita Spending Indicators for the Oral Clinical Nutritional Supplement Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 1.42 | 1.49 | 2.49 |
| Spend per 1,000 people (USD) | 1,421.63 | 1,493.98 | 2,491.62 |
| Annual spend per active user (USD) | 129 to 150 | 129 to 151 | 148 to 174 |
Table 4: Care-Channel Revenue Indicators for the Oral Clinical Nutritional Supplement Market (USD million and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 12,400 million | Report value |
| Geriatric revenue, 2026 | USD 5,567.6 million | 44.9% share |
| Liquid-form revenue, 2026 | USD 6,076.0 million | 49.0% share |
| Standard-formula revenue, 2026 | USD 8,419.6 million | 67.9% share |
Analyst Perspective
“Oral nutrition earns repeat revenue when nutrient density remains tolerable across daily use. Suppliers must align taste, clinical positioning, and reimbursement continuity across hospital and home settings.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Oral Clinical Nutritional Supplement Market segmented?
The oral clinical nutritional supplement market is segmented by product type, indication, form, end user, and flavour. In 2026, standard formula is projected at 67.9%, general well-being at 22.7%, liquid at 49.0%, and geriatric at 44.9%.
By product type: Standard formula is projected at 67.9% in 2026 because it can be started across routine recovery cases before a disease-specific restriction becomes clear.
By indication: General well-being is estimated at 22.7% in 2026 as poor intake is commonly noticed before the purchase is attached with one defined disease.
By form: Liquid is expected to hold 49.0% in 2026 since measured, ready-to-use servings reduce preparation work, though transport and packaging cost can support powder in price-sensitive use.
By end user: Geriatric users are forecast at 44.9% in 2026 as reduced appetite and longer recovery bring repeat nutrition need into the same age group.
By flavour: Flavoured products lead because taste fatigue appears quickly during daily use, making rotation and familiar profiles important for continuation.
What makes Standard Formula central to the Product Type category?
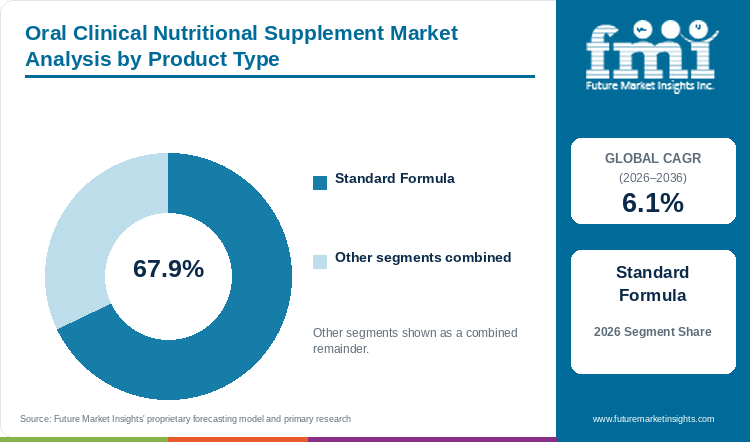
Standard formula is projected to capture 67.9% of product type revenue in 2026, supported by balanced macronutrient composition and universal clinical applicability.
Table 5: Product Type Share for the Oral Clinical Nutritional Supplement Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Standard Formula | 67.9% |
| Other Segments Combined | 32.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Oral Clinical Nutritional Supplement Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.1% |
| Leading Segment | Standard Formula |
Standard formula is expected to retain 67.9% share in 2026 because nutritional risk generally appears before a narrow disease requirement is confirmed. Hospitals can begin support with one complete formula and later shift the patient if renal, diabetic or oncology needs become clearer. Standard formulas also sit close to enteral formula decisions when oral intake starts falling. The large share is therefore attached to wider usability, although specialized formulas take revenue where clinical restrictions become mandatory.
- Standard formula maintains clinical leadership as acute care dietitians rely on complete nutritional profiles before diagnosing specific metabolic restrictions.
- In May 2026, Japan's Consumer Affairs Agency updated regulatory standards for complete nutritional foods within its Foods for Patients clinical framework [3].
Why does General Well-being account for a notable share of Indication demand?
General well-being is estimated to represent 22.7% of indication demand in 2026, reflecting early nutritional decline and broad outpatient convalescence requirements.
General well-being is estimated to account for 22.7% in 2026 because poor intake often begins as weakness, appetite loss or incomplete meals and not as one clearly labelled disease. This drives early outpatient prescribing of medical nutrition and broader clinical nutrition formulas. The segment can gain when recovery support is recommended early; however, it may also face loose clinical positioning, because a general-purpose purchase is easier for households to postpone when price becomes a concern.
- General well-being addresses early involuntary weight loss and fatigue before patients qualify for specialized oncology or renal medical nutrition.
- In June 2026, the Australian Institute of Health and Welfare documented that 89% of seniors aged 75 and older failed to achieve basic daily nutritional intake benchmarks [4].
How does Liquid meet changing application needs within the Form category?
Liquid products are forecast to command 49.0% of form revenue in 2026, driven by ready-to-drink convenience and standardized single-serve dosing.
Liquid is projected to hold 49.0% share in 2026 as the format removes mixing errors and gives the same nutrient quantity in each serving. This becomes useful for older users, caregivers and patients taking a number of medicines, where an added preparation step can reduce compliance. Ready-to-drink convenience maintains leadership across commercial medical food channels, whereas powder formats remain competitive where price per serving decides out-of-pocket purchasing.
- Ready-to-drink liquid formulations eliminate measurement errors and water contamination risks for vulnerable outpatients managing multiple oral medications.
- In July 2025, Kate Farms introduced its plant-based High Protein Nutrition Shake, delivering 25 grams of protein for adult clinical recovery [5].
What supports Geriatric leadership in the End User category?
Geriatric users are anticipated to generate 44.9% of end-user expenditure in 2026, owing to age-related frailty, sarcopenia risks, and prolonged convalescence periods.
Geriatric users are forecast to represent 44.9% of demand in 2026 because ageing brings several intake problems together. Reduced appetite, medicine burden, chewing difficulty and slower recovery make a normal meal insufficient, stimulating steady demand for targeted protein supplements. Still, the share can face pressure where caregivers change frequently or monthly out-of-pocket spending is difficult to maintain.
- Geriatric demographics concentrate recurring supplement intake, as chronic illness and reduced appetite prevent adequate nutritional replenishment from standard meals.
- In June 2025, the CDC National Center for Health Statistics recorded chronic multi-morbidity among 66.9% of noninstitutionalized seniors aged 85 and older [6].
Why are buyers selecting Flavoured Products within the Flavour mix?
Flavoured products are set to dominate the flavour category in 2026, reinforced by sensory rotation that prevents taste fatigue during extended clinical feeding.
Flavoured products are taking the lead because clinical suitability does not automatically result in daily consumption. A product may meet nutrient requirements, but the same sweetness or aftertaste taken every day can cause patient fatigue. Formulation work is increasingly borrowing from sports nutrition formats where high protein and acceptable mouthfeel must coexist alongside comprehensive vitamin and mineral supplement fortification.
- Sensory diversification across vanilla, chocolate, and fruit profiles improves long-term patient compliance during multi-week oral rehabilitation regimens.
- In September 2025, Tate & Lyle launched its Sensation formulation toolkit in Asia Pacific, optimizing mouthfeel and masking metallic aftertastes in high-protein medical liquids [8].
What are the drivers, restraints, and opportunities in the Oral Clinical Nutritional Supplement Market?
In the oral clinical nutritional supplement market, standardized clinical malnutrition screening drives early intervention demand, strict reimbursement documentation and sensory fatigue restrain adherence, and compact nutrient-dense formulations create substantial commercial value through 2036.
- Driver: Earlier identification of nutritional risk expands oral support before escalation to tube or parenteral feeding.
- Restraint: Classification and reimbursement rules can delay access when documentation is required before paid supply begins.
- Opportunity: Better taste and lower serving burden can improve continuation across several weeks or months.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Hospitals are identifying nutritional risk earlier as quality programs connect screening with discharge planning. Future Market Insights data suggests that documented malnutrition turns hidden need into a defined care decision. In September 2025, a CMS quality demonstration recorded a 5.15% malnutrition diagnosis rate among screened admissions, proving how routine assessment elevates clinical nutritional intervention [2]. Suppliers that support assessment records, serving instructions, and community fulfillment secure repeat supply across post-acute care transitions.
Risk Assessment of the Oral Clinical Nutritional Supplement Market: Regulatory and Formulation Friction
Access weakens when classification and payment rules require more documentation than an ordinary food purchase. In October 2025, the Ministry of Health of Italy updated its national guidelines for foods for special medical purposes (FSMP), requiring clinical efficacy dossiers before products qualify for regional pharmacy reimbursement [7]. Manufacturers must keep intended use, evidence and labelling aligned, which can slow entry into professional channels. High protein loading can also intensify aftertaste and dense liquids can become difficult over repeated daily servings, elevating patient discontinuation rates.
Commercial Opportunity Analysis: Sensory Differentiation and Compact Formats
Concentrating daily macronutrients into reduced fluid volumes solves early mealtime fatigue among frail patients. Formulating dense liquids below 125 milliliters without increasing osmolality or throat stickiness requires sophisticated hydrocolloid stabilization. In October 2025, Danone Nutricia introduced savory plant-based Fortimel formulations in Spain, widening sensory choice beyond conventional sweet shakes and improving patient adherence [16]. Expanding compact medical nutrition options across oral clinical nutrition supplements and specialized institutional lines captures premium pricing across acute and community healthcare networks.
Oral Clinical Nutritional Supplement Market by Country (2026 to 2036)
As per Future Market Insights, Japan represents the fastest-growing oral clinical nutritional supplement market among the five evaluated countries at a 7.8% CAGR from 2026 to 2036, while the USA records the slowest expansion at 4.9%. Across these countries, commercial performance depends on age structure, clinical classification, reimbursement continuity, and dependable community supply.
Table 7: Country CAGR and Primary Growth Levers for the Oral Clinical Nutritional Supplement Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 7.8% | Foods for Patients framework and advanced population ageing |
| UK | 7.0% | Established dietetic pathways and community-care continuation |
| South Korea | 6.4% | Rapid ageing and customized nutrition policy |
| Germany | 5.9% | Older population and structured pharmacy or home-care channels |
| USA | 4.9% | Large ageing base and broad hospital plus retail access |
Source: Future Market Insights analysis
Japan Oral Clinical Nutritional Supplement Market Outlook (2026 to 2036)
Japan is expected to record the fastest evaluated CAGR at 7.8%, and its difference from the global market is the depth of ageing rather than only population size. The Statistics Bureau estimated 36.24 million people aged 65 years and above on September 15, 2026, equal to 29.6% of the population [9]. This creates a regular need for compact products where appetite is low and care continues for longer periods. The Foods for Patients framework improves clinical confidence, but exact category and labelling requirements slow product revisions. Demand rises faster where suppliers bring locally familiar flavor systems and smaller servings.
Key takeaway: In Japan, special-diet permissions and an advanced age profile favor compact products with exact category fit.
UK Oral Clinical Nutritional Supplement Market Outlook (2026 to 2036)
The UK is forecast to grow at 7.0%, but the main opening is not inside the hospital alone. A large part of repeat demand depends on whether dietetic advice, community prescribing and delivery continue after discharge. The Care Quality Commission reported that 68% of new social-care requests in England came from older people during 2023/24 [10]. This raises the number of care transitions where nutrition can be lost between services. A supplier with formulary acceptance and dependable community stock can hold users for longer.
Key takeaway: In UK, community-care continuity and dietetic pathways make reliable post-discharge supply a central purchasing requirement.
South Korea Oral Clinical Nutritional Supplement Market Outlook (2026 to 2036)
South Korea is projected at 6.4% CAGR and its opportunity is being formed by rapid ageing alongside a consumer market which responds strongly to convenient nutrition. Statistics Korea reported that adults aged 65 years and above represented 20.3% of the population in 2025 [11]. This moves oral nutrition closer to household purchase, especially when products use familiar cereal, nut or mild savory profiles. However, medical positioning and ordinary healthy-ageing products overlap, making price comparison direct.
Key takeaway: In South Korea, rapid ageing supports demand while price sensitivity rewards compact formats and locally familiar flavor systems.
Germany Oral Clinical Nutritional Supplement Market Outlook (2026 to 2036)
Germany is projected to grow at 5.9% CAGR as outpatient homecare networks expand. In May 2026, the Federal Statistical Office of Germany (Destatis) reported that the domestic population aged 65 and older reached 18.7 million, intensifying institutional and homecare nursing requirements [12]. Competition is divided by the ability to keep a patient supplied across structured pharmacy and outpatient care channels. Suppliers that integrate with regional sickness fund formularies defend market share against generic private-label alternatives.
Key takeaway: In Germany, structured reimbursement scrutiny favors clearly indicated products with dependable pharmacy and home-care availability.
USA Oral Clinical Nutritional Supplement Market Outlook (2026 to 2036)
The USA records a 4.9% CAGR, where a vast geriatric demographic provides steady commercial volume. The U.S. Census Bureau reported 61.2 million people aged 65 years and above in 2024, up 3.1% from 2023 [13]. Hospital brands, retail pharmacies, and direct-to-consumer delivery networks ensure high visibility and self-purchase. However, uneven insurance reimbursement after hospital discharge shifts costs to household budgets, constraining extended compliance.
Key takeaway: In USA, a large ageing population supports scale while uneven coverage makes price and channel reach decisive.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Oral Clinical Nutritional Supplement Market?
Abbott Laboratories, Danone S.A., Nestlé Health Science, Fresenius Kabi, Kate Farms, Medtrition, Inc., Ajinomoto Co., Inc., and Meiji Co., Ltd. are the significant market players in this market.
Future Market Insights analysis indicates that competition centers on finished oral and medical nutrition businesses serving hospitals, community care, retail, and home-use channels. Global companies maintain broad clinical portfolios across diverse therapeutic areas. Specialized firms compete through plant-based, protein-dense, or condition-oriented specialized nutrition formats. Buyers compare documented nutrient profiles, format tolerance, channel continuity, and geographic availability.
- Global Finished Oral Nutrition Manufacturers: Abbott Laboratories, Danone S.A., Nestlé Health Science, and Fresenius Kabi.
- Specialized Oral and Medical Nutrition Companies: Kate Farms, Medtrition, Inc., Ajinomoto Co., Inc., and Meiji Co., Ltd.
Competitive Benchmarking: Oral Clinical Nutritional Supplement Market
Table 8: Competitive Benchmarking for the Oral Clinical Nutritional Supplement Market (qualitative capability ratings), 2026
| Company | Finished ONS Portfolio | Specialized Coverage | Care-Setting Breadth | Geographic Reach |
|---|---|---|---|---|
| Abbott Laboratories | High | High | High | High |
| Danone S.A. | High | High | High | High |
| Nestlé Health Science | High | High | High | High |
| Fresenius Kabi | High | High | High | High |
| Kate Farms | High | High | High | Medium |
| Medtrition, Inc. | Medium | Medium | High | Medium |
| Ajinomoto Co., Inc. | Medium | High | Medium | Medium |
| Meiji Co., Ltd. | High | Medium | Medium | Medium |
Scoring basis: High finished-portfolio breadth requires several documented oral nutrition lines. High specialized coverage requires multiple condition-oriented or age-specific groups. Care-setting breadth reflects documented hospital, community, retail, or home use. Geographic reach records commercial presence rather than corporate size.
Key Developments in the Oral Clinical Nutritional Supplement Market
- In May 2026, Abbott Laboratories launched Ensure Strength Pro in India with 31 nutrients and 30 grams of protein per 100 grams for adult healthy-ageing support [14].
- In March 2026, Nestlé Health Science launched Compleat Paediatric Oral Blends in seven European markets for children requiring specialized medical nutrition away from home [15].
- In October 2025, Danone through Nutricia launched savory Fortimel PlantBased Protein options in Spain for disease-related malnutrition requiring oral support [16].
Key Players in the Oral Clinical Nutritional Supplement Market
Global Finished Oral Nutrition Manufacturers
- Abbott Laboratories
- Danone S.A.
- Nestlé Health Science
- Fresenius Kabi
Specialized Oral and Medical Nutrition Companies
- Kate Farms
- Medtrition, Inc.
- Ajinomoto Co., Inc.
- Meiji Co., Ltd.
Oral Clinical Nutritional Supplement Market - Report Scope
Table 9: Report Scope for the Oral Clinical Nutritional Supplement Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Indication; Form; End User; Flavour |
| Quantitative Units | USD Million |
| Market Definition | Includes revenue from oral nutritional supplements sold as standard or specialized formulas. Excludes tube-only feeding, parenteral nutrition, standalone ingredients, and conventional dietary supplements outside the clinical scope. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Germany, Japan, South Korea, and additional countries in the full report |
| Key Companies Covered | Abbott Laboratories; Danone S.A.; Nestlé Health Science; Fresenius Kabi; Kate Farms; Medtrition, Inc.; Ajinomoto Co., Inc.; Meiji Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Oral Clinical Nutritional Supplement Market - Research Methodology
Table 10: Research Methodology for the Oral Clinical Nutritional Supplement Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews are conducted with manufacturers, suppliers, distributors, healthcare professionals, industry experts, and key opinion leaders across the value chain to validate demand dynamics and purchasing decisions. |
| Secondary Research | Secondary research includes company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other public sources. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 use top-down and bottom-up approaches to assess product demand, price points, channel activity, and adoption trends. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, relevant clinical drivers, the regulatory environment, and historical trend analysis to improve accuracy without double counting adjacent categories. |
Oral Clinical Nutritional Supplement Market by Segments
Oral Clinical Nutritional Supplement Market segmented by Product Type:
- Standard Formula
- Specialized Formula
Oral Clinical Nutritional Supplement Market segmented by Indication:
- General Well-being
- Diabetes
- Renal Disorders
- Oncology Nutrition
- Neurology Nutrition
- Respiratory Disorders
- Hepatic Disorders
- Others
Oral Clinical Nutritional Supplement Market segmented by Form:
- Liquid
- Powder
- Semi-solid
Oral Clinical Nutritional Supplement Market segmented by End User:
- Geriatric
- Adult
- Pediatric
Oral Clinical Nutritional Supplement Market segmented by Flavour:
- Flavoured
- Chocolate
- Regular
- Vanilla
- Strawberry
- Mixed Berries
- Orange
- Others
Oral Clinical Nutritional Supplement Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Abbott Laboratories. (2025, July 17). Second-quarter 2025 financial results and adult nutrition performance. Abbott Investor News.
- [2] Centers for Medicare & Medicaid Services. (2025, September). Malnutrition Care Score information session. CMS Quality Programs.
- [3] Consumer Affairs Agency, Government of Japan. (2026). Foods with health claims and foods for special dietary uses. Consumer Affairs Agency Publications.
- [4] Australian Institute of Health and Welfare. (2026, June). Nutrition across the life stages for older Australians. Australian Government Publishing.
- [5] Kate Farms. (2025, July 8). High Protein Nutrition Shake launch announcement. Kate Farms Newsroom.
- [6] National Center for Health Statistics. (2025, June). Hypertension prevalence among adults aged 85 years and older. CDC National Health Statistics Reports.
- [7] Ministry of Health, Italy. (2025, October). Foods for special medical purposes guidance update. Government of Italy Official Gazette.
- [8] Tate & Lyle. (2025, September). Sensation formulation tool launch in Asia-Pacific. Corporate News.
- [9] Statistics Bureau of Japan. (2026, September 20). Statistical Topics No. 149: Population aged 65 years and above. Ministry of Internal Affairs and Communications.
- [10] Care Quality Commission. (2025, October). State of Care 2024/25: Adult social care services in England. UK Government Publications.
- [11] Statistics Korea. (2025, September). 2025 statistics on older persons. Government of the Republic of Korea.
- [12] Federal Statistical Office of Germany (Destatis). (2026, May). Population aged 65 years and older in Germany. Statistisches Bundesamt.
- [13] U.S. Census Bureau. (2025, June). Older population estimates in the United States. United States Department of Commerce.
- [14] Abbott India. (2026, May 13). Abbott launches Ensure Strength Pro in India to support healthy ageing. Abbott Corporate Press Releases.
- [15] Nestlé Health Science. (2026, March 30). Nestlé introduces an innovative complete nutritional solution for children with special medical nutrition needs. Nestlé Global Newsroom.
- [16] Danone Nutricia. (2025, October 1). Nutricia's new savory plant-based medical nutrition proven to improve patient adherence. Nutricia Medical Press.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the oral clinical nutritional supplement market in 2026 and what is forecast for 2036?
- Which nutrition-screening and care-continuity pressures support demand?
- Why does standard formula lead the product type category?
- Why does liquid lead the form category globally?
- How do growth rates differ across Japan, the UK, South Korea, Germany, and the USA?
- Which companies supply finished oral and specialized medical nutrition products?
- What limits access, continuation, or supplier switching in this market?
- What should buyers evaluate before purchasing an oral clinical nutritional supplement?
Frequently Asked Questions
How big is the oral clinical nutritional supplement market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global market will reach USD 12.4 billion in 2026 and USD 22.3 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 6.1% CAGR over the assessment period, supported by ageing populations and earlier nutrition screening.
Which product type leads the market?
Standard formula is projected to hold 67.9% share in 2026 due to broad routine clinical use and complete macronutrient balance.
Which form leads the market?
Liquid products are estimated to account for 49.0% share in 2026 owing to controlled single-serve administration and low preparation burden.
Which country has the fastest evaluated growth outlook?
Japan is projected to register a 7.8% CAGR from 2026 to 2036, supported by an advanced geriatric cohort and structured special-diet frameworks.
Who are the key players?
Notable companies include Abbott Laboratories, Danone S.A., Nestlé Health Science, Fresenius Kabi, Kate Farms, Medtrition, Ajinomoto, and Meiji.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Standard Formula
- Specialized Formula
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Indication, 2026 to 2036
- General Well-being
- Diabetes
- Renal Disorders
- Oncology Nutrition
- Neurology Nutrition
- Respiratory Disorders
- Hepatic Disorders
- Others
- Y-o-Y Growth Trend Analysis By Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Liquid
- Powder
- Semi-solid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Geriatric
- Adult
- Pediatric
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Flavour, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavour, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavour, 2026 to 2036
- Flavoured
- Chocolate
- Regular
- Vanilla
- Strawberry
- Mixed Berries
- Orange
- Others
- Y-o-Y Growth Trend Analysis By Flavour, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavour, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Indication
- By Form
- By End User
- By Flavour
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Abbott Laboratories
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- Nestlé Health Science
- Fresenius Kabi
- Kate Farms
- Medtrition, Inc.
- Ajinomoto Co., Inc.
- Meiji Co., Ltd.
- Abbott Laboratories
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


