

- Market Size (2026)
- USD 676.1 Bn
- Forecast (2036)
- USD 972.3 Bn
- CAGR (2026 to 2036)
- 3.7%
How big is Oral Solid Dosage Pharmaceutical Formulation Market in 2026?
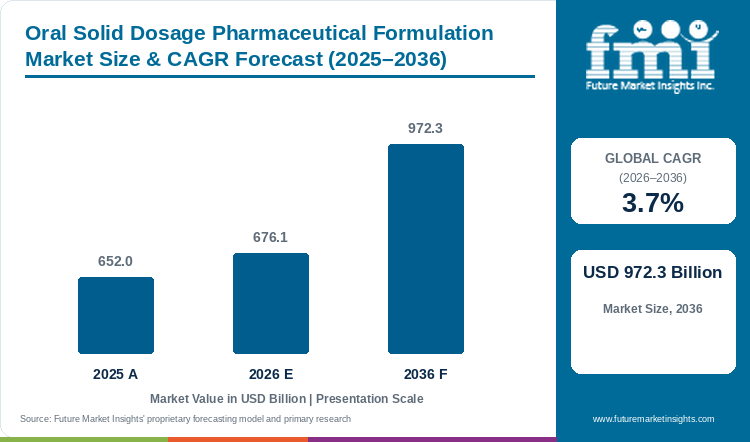
Assessed at USD 652.0 billion in 2025 and progressing to USD 676.1 billion in 2026, the oral solid dosage pharmaceutical formulation market valuation is on course to reach USD 972.3 billion by 2036, supported by a forecast-period CAGR of 3.7%.
The global oral solid dosage pharmaceutical formulation market was valued at USD 652.0 billion in 2025 and is estimated to reach USD 676.1 billion in 2026, with market size projected to reach USD 972.3 billion by 2036 at a CAGR of 3.7%. According to FMI, this 3.7% expansion is steadier than the faster-growing high-potent oral solid contract manufacturing niche as price competition in commodity generics moderates overall industry valuation. Compressed film-coated and uncoated tablets capture 57.1% of dosage form value in 2026 as health systems favor room-temperature tablets over costly cold-chain injectables. The demand for oral tablet conversion is supported by a May 2026 meta-analysis of 24,859 patients in touchREVIEWS in Endocrinology showing oral semaglutide tablets reduced HbA1c by 1.19% at 12 months [1]. However, humidity-induced drug recrystallization restrains shelf stability, so long-term demand favors formulators with validated moisture-barrier packaging.
Key Market Trends & Insights
- By dosage form: By dosage form, compressed film-coated and uncoated tablets is projected to capture 57.1% in 2026, driven by rotary compression throughput and fixed-dose combinations.
- By release mechanism: Within release mechanism, immediate-release conventional OSD is estimated to command 61.9% in 2026, supported by rapid gastrointestinal dissolution across acute and chronic dosing.
- By solubility enhancement tech: Based on solubility enhancement tech, direct compression and wet granulation is expected to hold 53.9% in 2026, underpinned by compendial validation and low excipient overhead.
- By therapeutic area: By therapeutic area, cardiovascular, metabolic and oral GLP-1/SGLT2 is forecast to generate 29.7% in 2026, propelled by oral incretin mimetics and SGLT2 prescribing.
- By manufacturing model: Within manufacturing model, in-house innovator and generic pharma plants is anticipated to account for 64.7% in 2026, reinforced by captive continuous tableting lines.
- By primary packaging: By primary packaging, thermoformed PVC/PVDC and cold-form Alu-Alu blisters is projected to secure 58.3% in 2026, enabled by unit-dose moisture barrier protection.
Regional Highlights
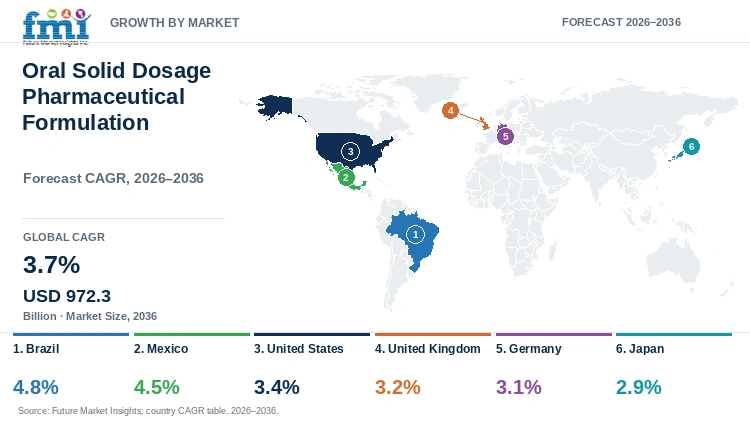
- Latin American expansion: Brazil paces national growth at a 4.8% CAGR through 2036 while Mexico follows at 4.5% on expanding ANVISA and COFEPRIS generic bioequivalence approvals.
- Developed market progression: United States demand advances at a 3.4% CAGR ahead of the United Kingdom at 3.2% and Germany at 3.1%, while Japan records a 2.9% annual rate.
Market Size & Forecast
Table 1: Market Size and Forecast for the Oral Solid Dosage Pharmaceutical Formulation Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 652.0 billion |
| Estimated Market Size in 2026 | USD 676.1 billion |
| Projected Market Size by 2036 | USD 972.3 billion |
| CAGR, 2026 to 2036 | 3.7% |
| Added Value, 2026 to 2036 | USD 296.2 billion |
The growth in oral solid tablet demand is also reflected in regional procurement, with Brazil expanding at a 4.8% CAGR on public pharmacy volume while Germany grows at 3.1%. According to a February 2025 IQ Consortium paper in The AAPS Journal, inline spectroscopic blend testing cuts batch quarantine delays [2], helping plants scale tablet and capsule packaging output for national tenders.
Unit-Dose Production and Batch-Volume Sizing
Table 2: Unit-Dose Production and Batch-Volume Sizing for the Oral Solid Dosage Pharmaceutical Formulation Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 652.0 | 676.1 | 972.3 |
| Annual commercial OSD units dispensed (trillion) | 1.85 to 2.05 | 1.90 to 2.12 | 2.55 to 2.85 |
| Active GMP OSD manufacturing lines globally | 14,200 to 15,600 | 14,500 to 16,000 | 17,800 to 19,500 |
| Average manufacturer valuation per dose (USD) | 0.32 to 0.35 | 0.32 to 0.36 | 0.34 to 0.38 |
Operational note: Unit-dose production ranges reflect global prescription and hospital-dispensed tablets and capsules and softgels and multiparticulate sachets across GMP facilities.
Stronger pressure to shorten batch release times is prompting pharmaceutical plants to replace slow destructive tablet dissolution checks with automated spectroscopic testing. For instance, a July 2026 study in the Journal of Controlled Release validated a five-year model predicting tablet disintegration with R-squared accuracy above 0.92 [3], which accelerates pharmaceutical unit-dose packaging shipments.
Per Capita & Manufacturing Plant Sizing
Table 3: Per Capita and Manufacturing Facility Allocation Indicators for the Oral Solid Dosage Pharmaceutical Formulation Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per capita (USD) | 79.5 | 81.5 | 108.0 |
| Annual valuation per GMP OSD plant (USD million) | 145.0 to 170.0 | 150.0 to 176.0 | 195.0 to 230.0 |
| In-house plant production share (%) | 64.0% to 65.5% | 64.2% to 65.2% | 60.5% to 62.5% |
Table 4: Manufacturing Plant & Packaging Allocation Indicators for the Oral Solid Dosage Pharmaceutical Formulation Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 676.1 billion | 2026 global market valuation baseline |
| GMP OSD formulation plants globally | 4,100 | Global FDA, EMA, PMDA & WHO GMP site registry |
| Market value per GMP site | USD 164.9 million | Annualized finished OSD formulation output |
| In-house innovator & generic allocation, 2026 | USD 437.4 billion | 64.7% manufacturing model segment allocation |
Wider development of poorly water-soluble drug candidates requires specialized polymer and lipid carriers to achieve reliable bloodstream absorption after oral dosing. Manufacturers are therefore adopting softgel capsule formulations and plant-based hydroxypropyl methylcellulose shells to protect moisture-sensitive compounds and improve patient swallowing comfort.
Analyst Perspective
"High-volume generic direct compression anchors baseline tablet volume while value growth shifts toward hot-melt extruded dispersions and oral peptides. Manufacturers integrating continuous tableting with cold-form Alu-Alu blister lines will defend operating margins through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the oral solid dosage pharmaceutical formulation market segmented?
The oral solid dosage pharmaceutical formulation market is segmented by six primary commercial axes and region: dosage form, release mechanism, solubility enhancement tech, therapeutic area, manufacturing model, and primary packaging. In 2026, compressed film-coated and uncoated tablets is projected at 57.1%, immediate-release conventional OSD at 61.9%, direct compression and wet granulation at 53.9%, cardiovascular, metabolic and oral GLP-1/SGLT2 at 29.7%, in-house innovator and generic pharma plants at 64.7%, and thermoformed PVC/PVDC and cold-form Alu-Alu blisters at 58.3%.
By dosage form: compressed film-coated & uncoated tablets, hard gelatin & HPMC vegetarian capsules, softgel liquid-filled capsules, orally disintegrating, chewable & effervescent tablets, and multiparticulate pellets, granules & sachets.
By release mechanism: immediate-release conventional OSD, controlled-, sustained- & osmotic-release, and delayed-release enteric-coated.
By solubility enhancement tech: direct compression & wet granulation, hot-melt extrusion & spray-dried amorphous solid dispersion, and lipid self-emulsifying & nano-milled.
By therapeutic area: cardiovascular, metabolic & oral GLP-1/SGLT2, central nervous system & pain, oncology small-molecule kinase inhibitors, and anti-infectives, GI & respiratory.
By manufacturing model: in-house innovator & generic pharma plants and contract development & manufacturing organizations.
By primary packaging: thermoformed PVC/PVDC & cold-form Alu-Alu blisters and HDPE desiccant-canister pill bottles.
Why do compressed tablets account for a notable share of dosage form demand?
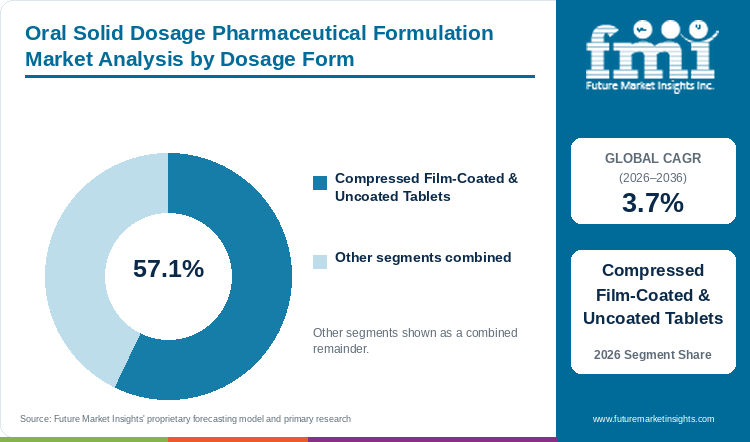
Based on dosage form, compressed film-coated and uncoated tablets is projected to account for 57.1% in 2026, driven by rotary press throughput.
Table 5: Dosage Form Share for the Oral Solid Dosage Pharmaceutical Formulation Market (percentage share), 2026
| Dosage Form | Share (2026) |
|---|---|
| Compressed Film-Coated & Uncoated Tablets | 57.1% |
| Other Segments Combined | 42.9%* |
| Total | 100.0% |
*Note: Remaining dosage form categories sum to 100.0% of 2026 oral solid dosage pharmaceutical formulation market value.
Table 6: Dosage Form Leadership and Market Growth for the Oral Solid Dosage Pharmaceutical Formulation Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.7% |
| Leading Segment | Compressed Film-Coated & Uncoated Tablets |
In the FMI report, compressed tablets remain the foundational pharmaceutical dosage form as double-sided rotary presses produce over 500,000 tablets per hour with tight weight uniformity. Aqueous film coatings using pharmaceutical coating excipients mask bitter active ingredients and enable bilayer fixed-dose combinations.
- By dosage form, compressed film-coated and uncoated tablets is estimated to hold 57.1% in 2026, supported by high mechanical durability and economical rotary compression.
- In addition to tablets, a May 2026 study in Marine Drugs showed that ternary HPMC hard capsules achieved disintegration within 15 minutes across four gastrointestinal pH media and over 85% drug release within 30 minutes [4].
What supports immediate-release formulations as a preferred choice in release mechanism?
By release mechanism, immediate-release conventional OSD is estimated to hold 61.9% in 2026, owing to rapid systemic absorption.
Immediate-release tablets and capsules lead prescription volume as antihypertensives and oral anti-infectives and analgesics require predictable dissolution within 30 to 45 minutes. Sponsors deploy oral controlled-release drug delivery matrices when narrow therapeutic index drugs require zero-order 24-hour plasma profiles.
- In 2026, immediate-release conventional OSD is expected to lead release mechanism with 61.9% share, underpinned by straightforward bioequivalence validation and superdisintegrant performance.
- In March 2026, a multicenter Phase 2/3 randomized trial of 261 adults published in PLOS One showed that single-dose rimegepant 75 mg orally disintegrating tablets achieved 59.4% headache pain relief at 2 hours and 79.5% global impression improvement at 24 hours [5].
How is direct compression gaining use across applications in solubility enhancement?
Direct compression and wet granulation is projected to hold 53.9% share in 2026, underpinned by compendial excipient infrastructure.
High-shear wet granulation and direct compression remain the primary industrial processing routes as free-flowing spray-dried lactose and microcrystalline cellulose grades run reliably on standard presses. Formulators incorporate direct-compression tableting excipients and co-processed binders to compress poorly compactable active substances without thermal stress.
- By solubility enhancement tech, direct compression and wet granulation is forecast to represent 53.9% in 2026, reinforced by minimal solvent recovery overhead.
- For BCS Class II molecules requiring amorphous stabilization, a January 2026 study in the International Journal of Pharmaceutics proved that acid-base supersolubilization with Kollidon VA64 enabled low-temperature hot-melt extrusion at 80 degrees Celsius and raised indomethacin aqueous solubility to over 240 mg/mL [6].
Why are buyers selecting cardiometabolic regimens for products within therapeutic area?
Cardiovascular, metabolic and oral GLP-1/SGLT2 is likely to capture 29.7% share in 2026, propelled by oral incretin prescribing.
Chronic cardiometabolic management generates the largest share of oral solid formulation value as hundreds of millions of patients take daily statins and SGLT2 inhibitors and oral GLP-1 receptor agonists. Permeation enhancers such as salcaprozate sodium allow peptide therapeutics to cross gastric membranes in tablet form.
- Within therapeutic area, cardiovascular, metabolic and oral GLP-1/SGLT2 is anticipated to maintain the leading position with 29.7% share in 2026, linked to first-line cardiometabolic guideline status.
- In July 2025, Merck & Co., Inc. reported positive Phase 3 CORALreef clinical trial results for oral macrocyclic peptide PCSK9 inhibitor enlicitide decanoate while narrowing full-year corporate guidance to USD 64.3 to 65.3 billion [7].
Which market conditions keep in-house pharma plants relevant within manufacturing model?
In-house innovator and generic pharma plants is set to lead the manufacturing model with 64.7% share in 2026, supported by captive lines.
Multinational originator and generic pharmaceutical companies retain captive oral solid manufacturing for flagship blockbusters and high-volume generic portfolios to protect supply security. At the same time, innovator sponsors outsource specialized spray-dried dispersion and high-containment oncology runs to contract development and manufacturing organizations.
- The manufacturing model category is forecast to be led by in-house innovator and generic pharma plants at 64.7% share in 2026, enabled by automated multi-shift rotary compression.
- In February 2026, Pfizer Inc. reported full-year 2025 corporate receipts of USD 62.6 billion and 17% growth in its contract manufacturing unit Pfizer CentreOne to USD 1,338 million [8].
How do thermoformed and cold-form blisters meet changing needs in primary packaging?
Calendarized blister cards lead European, Asian, and hospital unit-dose dispensing by shielding hygroscopic tablets from humidity and microbial cross-contamination. Formulation engineers specify high-barrier blister packaging films and thermoformed blister packs and pharmaceutical plastic pill bottles to preserve shelf life across tropical ICH Zone IVb climates.
- In 2026, thermoformed PVC/PVDC and cold-form Alu-Alu blisters is expected to lead primary packaging with 58.3% share, attributable to moisture-induced recrystallization prevention.
- A June 2026 sensitivity analysis of 20,129 outpatient antibacterial dispensing records in Japan published in the Journal of Pharmaceutical Health Care and Sciences showed that triple-drug Helicobacter pylori combination blister packs accounted for a median 1.13% of monthly oral records [9].
What are the drivers, restraints, and opportunities in the oral solid dosage pharmaceutical formulation market?
In the oral solid dosage pharmaceutical formulation market, the key driver is oral peptide and kinase tablet adoption, the key restraint is amorphous dispersion recrystallization, and the key opportunity is PBBM-guided continuous manufacturing.
- Driver: Oral GLP-1 and PCSK9 peptide tablets and small-molecule oncology kinase inhibitors expand high-margin oral solid production.
- Restraint: Amorphous solid dispersion recrystallization under elevated humidity and steep multi-competitor generic price erosion compress unit margins.
- Opportunity: Physiologically based biopharmaceutics modeling and continuous hot-melt extrusion with injection molding shorten bioequivalence development timelines.
Growth Analysis and Demand Catalysts
Stronger patient preference for convenient daily pills over clinic injections is a primary factor driving demand for oral solid dosage formulations across chronic diseases. Manufacturers are reformulating multi-dose drugs into once-daily extended-release tablets to improve patient compliance and expand prescription volume. For instance, in January 2026, Teva Pharmaceutical Industries reported that 2025 corporate receipts grew 4% to USD 17.3 billion as strong adoption of once-daily Austedo XR tablets lifted franchise demand by 34% to USD 2.26 billion across 254 million U.S. generic prescriptions [10]. FMI research indicates that switching patients to once-daily tablets reduces side effects and extends brand life. Similarly, AstraZeneca reported 16 positive Phase 3 trials in February 2026 while expanding its oral oncology tablet pipeline [11].
Risk Assessment and Operational Restraints
Moisture sensitivity and drug crystallization during storage in warm climates act as major restraining factors that can hamper the growth of oral solid dosage formulations. According to a March 2025 stability study in the International Journal of Pharmaceutics, spray-dried amorphous dispersions crystallize faster under high humidity than hot-melt extruded tablets because of their larger surface area [12]. In addition to this, a July 2025 evaluation in Pharmaceutics found that standard gelatin capsules soften at 25 degrees Celsius and 75% relative humidity while plant-based HPMC shells keep their strength [13]. These stability issues force drugmakers to use costly cold-form aluminum blisters or desiccant bottles, which raises unit packaging costs and squeezes profit margins on generic tablets.
Commercial Opportunity and Format Differentiation
Wider use of computer dissolution modeling and continuous melt extrusion is creating lucrative opportunities for manufacturers to speed up generic and modified-release tablet approvals. For instance, in December 2025, researchers in Pharmaceuticals combined experimental design with computer dissolution modeling across HPMC tablet matrices to prove virtual bioequivalence for extended-release donepezil tablets [14]. Computer-guided dissolution testing helps generic drugmakers secure regulatory waivers and avoid costly human trials. Besides this, new continuous manufacturing methods are improving tablet strength and dissolution speed. According to a July 2025 study in the International Journal of Pharmaceutics, continuous hot-melt extrusion and molding produced break-resistant amorphous tablets with 5.01% porosity and over 90% drug release within one hour [15].
Oral Solid Dosage Pharmaceutical Formulation Market by Country (2026 to 2036)
As per FMI, national oral solid expansion diverges between rapid public generic tablet procurement across Latin America and continuous tableting modernization in North America and Western Europe and East Asia. Regulatory bioequivalence pathways, statutory generic tender velocity, and domestic CDMO containment capacity govern country growth rates through 2036.
Table 7: Country CAGR and Primary Growth Levers for the Oral Solid Dosage Pharmaceutical Formulation Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 4.8% | ANVISA generic bioequivalence expansion and public Farmacia Popular oral chronic therapy volume |
| Mexico | 4.5% | COFEPRIS generic bioequivalence approvals and nearshoring of North American OSD tableting |
| United States | 3.4% | Oral GLP-1 and oncology kinase tablet launches and 505(b)(2) modified-release filings |
| United Kingdom | 3.2% | High-throughput ASD screening and MHRA continuous manufacturing regulatory pathways |
| Germany | 3.1% | Co-processed excipient engineering and high-volume statutory health insurance generic tenders |
| Japan | 2.9% | Geriatric orally disintegrating tablet adoption and targeted enteric-coated capsule prescribing |
Source: Future Market Insights analysis
Brazil Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Federal Farmacia Popular chronic-disease dispensing programs and ANVISA generic bioequivalence rules are driving high-volume tablet demand across Brazilian pharmaceutical plants and public clinics. Local generic drugmakers are expanding tableting capacity to supply affordable daily pills for hypertension and diabetes across public health pharmacies. In December 2025, Brazilian and international pharmaceutical researchers showed in Pharmaceuticals that combining Design of Experiments with PBBM dissolution simulation streamlines extended-release tablet bioequivalence under ANVISA and FDA standards [14]. By 2036, Brazil is projected to grow at 4.8% CAGR, driven by public chronic-disease tablet procurement. Tropical ICH Zone IVb heat and humidity degrade moisture-sensitive amorphous dispersions during distribution, so domestic manufacturers in Sao Paulo and Goias invest in cold-form Alu-Alu blister lines and HPMC capsule encapsulation.
Key takeaway: In Brazil, expanding public chronic-disease tablet dispensing and PBBM-guided generic bioequivalence development propel a 4.8% CAGR through 2036.
Mexico Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Fast-track COFEPRIS generic bioequivalence approvals and high national diabetes and hypertension prevalence are driving oral solid tablet demand across Mexico City, Jalisco, and Estado de Mexico. For instance, a May 2026 crossover bioequivalence trial in healthy Mexican adults published in Pharmaceuticals confirmed that generic empagliflozin 25 mg immediate-release tablets matched reference blood absorption at 98.30% for peak concentration and 101.72% for total exposure [16]. Mexico's oral solid dosage pharmaceutical formulation outlook is anticipated to advance at 4.5% CAGR over the assessment period, underpinned by generic cardiometabolic tablet launches. Public sector consolidated tender price caps squeeze generic tablet margins, prompting Mexican CDMOs to add high-speed rotary compression and export packaging suites.
Key takeaway: In Mexico, generic SGLT2 and cardiometabolic bioequivalence approvals and regional tableting investment drive a 4.5% CAGR through 2036.
United States Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Rapid generic price erosion after patent expiry contrasts with premium pricing for novel oral oncology kinase inhibitors and oral metabolic peptides across the United States. A September 2025 longitudinal observational study of 530 active substances in BMJ Public Health found that an average of 4.0 generic competitors entered within three years of U.S. patent expiry, pushing generic volume share to 90% once five generics launched [17]. Oral solid dosage pharmaceutical formulation demand in the United States is forecast to rise at 3.4% CAGR over the forecast period, supported by oncology and oral peptide launches. In October 2026, Novartis reported that oral oncology demand lifted Kisqali receipts by 37% to USD 1,821 million and Scemblix by 67% [18].
Key takeaway: In the United States, rapid generic volume conversion after patent expiry and high-value oral metabolic and oncology launches sustain a 3.4% CAGR.
United Kingdom Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Centralized NHS generic tablet procurement and pharmaceutical research investments in solubility enhancement are shaping oral solid formulation demand across the United Kingdom. For instance, in August 2026, a joint research team from University College London and AstraZeneca Macclesfield published a high-speed screening and hot-melt extrusion method in the International Journal of Pharmaceutics that rapidly identified stable nifedipine amorphous solid dispersions [19]. Adoption of oral solid dosage pharmaceutical formulations in the United Kingdom is estimated to expand at 3.2% CAGR through 2036, reinforced by ICH Q13 continuous tableting adoption. NHS Drug Tariff reimbursement clawbacks pressure generic tablet profitability, compelling UK contract manufacturers to specialize in high-potency OEB 4/5 oncology encapsulation.
Key takeaway: In the United Kingdom, automated high-throughput amorphous dispersion screening and continuous tableting adoption drive a 3.2% CAGR through 2036.
Germany Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Germany leads Western Europe's primary pharmaceutical tableting and excipient engineering hub under dense statutory health insurance generic tender competition. Across 406 active substances analyzed in BMJ Public Health in September 2025, Germany averaged 7.6 generic competitors within three years of loss of exclusivity [17]. The Germany oral solid dosage pharmaceutical formulation sector is projected to record 3.1% CAGR during the assessment period, owing to co-processed excipient and minitablet innovation. In June 2026, researchers at Heinrich Heine University Duesseldorf and Bayer AG reported in the International Journal of Pharmaceutics that aqueous fluid-bed layering onto co-processed excipients enabled direct compression of orodispersible minitablets at up to 66% drug loading [20].
Key takeaway: In Germany, statutory health insurance generic tender scale and advanced pediatric and geriatric minitablet engineering support a 3.1% CAGR.
Japan Oral Solid Dosage Pharmaceutical Formulation Market Outlook (2026 to 2036)
Super-aging patient demographics in Japan create distinct clinical demand for orally disintegrating tablets, fine granules, and site-specific enteric-coated capsules that ease geriatric swallowing. A January 2025 Japanese health insurance big-data analysis of 7,364 Crohn's disease patients in Biological and Pharmaceutical Bulletin documented that 14.2% (1,049 patients) received budesonide enteric-coated capsules for targeted ileocecal release [21]. In Japan, oral solid dosage pharmaceutical formulation demand is predicted to advance at 2.9% CAGR through 2036, enabled by geriatric ODT and multiparticulate prescribing. Annual National Health Insurance drug price cuts squeeze profit margins on older generic tablets, which prompts Japanese contract manufacturers to automate high-speed visual inspection and moisture-proof blister packaging lines across domestic plants.
Key takeaway: In Japan, geriatric preference for orally disintegrating tablets and targeted enteric-coated capsules underpins a 2.9% annual growth rate.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the oral solid dosage pharmaceutical formulation market?
Pfizer Inc., Novartis AG, AstraZeneca PLC, Merck & Co., Inc., and Teva Pharmaceutical Industries Ltd. are the notable companies in the oral solid dosage pharmaceutical formulation market.
As per the analysis from FMI, the oral solid dosage pharmaceutical formulation market is moderately fragmented across commodity immediate-release generics while concentrating among multinational innovators for amorphous dispersions and oral peptides. Major manufacturers compete through captive continuous direct compression suites, OEB 4/5 containment capacity, and third-party contract manufacturing services.
- Innovator Small-Molecule and Oral Oncology Leaders: Pfizer Inc., Novartis AG, and AstraZeneca PLC operate global continuous compression and high-containment OEB 4/5 plants producing targeted oncology kinase and cardiovascular tablets.
- Cardiometabolic and Oral Peptide Innovators: Merck & Co., Inc. advances complex oral macrocyclic peptide tablets and fixed-dose cardiometabolic combinations across global primary-care formularies.
- Hybrid Generic and Extended-Release Specialists: Teva Pharmaceutical Industries Ltd. combines the world's largest generic oral solid footprint with proprietary once-daily extended-release osmotic and matrix tablets.
Competitive Benchmarking Oral Solid Dosage Pharmaceutical Formulation Market
Table 8: Competitive Benchmarking for the Oral Solid Dosage Pharmaceutical Formulation Market (qualitative capability ratings), 2026
| Company | Tablet & Capsule Breadth | Modified-Release & ASD Depth | In-House / CDMO Scale | Geographic Reach |
|---|---|---|---|---|
| Pfizer Inc. | High | High | High | High |
| Novartis AG | High | High | High | High |
| AstraZeneca PLC | High | High | High | High |
| Merck & Co., Inc. | High | High | High | High |
| Teva Pharmaceutical Industries Ltd. | High | High | High | High |
Evaluation basis: Capability tiers evaluate commercialized oral solid dosage breadth across tablets and capsules and amorphous solid dispersion capabilities and continuous tableting capacity.
Key Developments in the Oral Solid Dosage Pharmaceutical Formulation Market
- In October 2026, Novartis AG announced that nine-month 2026 net receipts reached USD 42.0 billion, propelled by oral solid oncology blockbusters Kisqali (+37% cc in Q3 to USD 1,821 million) and Scemblix (+67% cc in Q3 to USD 593 million) [18].
- In February 2026, AstraZeneca PLC delivered 16 positive Phase 3 clinical trials and 16 blockbuster medicines in its full-year report while partnering on high-throughput hot-melt extrusion screening for poorly soluble APIs [19] [11].
- In February 2026, Pfizer Inc. reported that its contract manufacturing arm Pfizer CentreOne expanded receipts by 17% in 2025 to USD 1,338 million while full-year corporate receipts reached USD 62.6 billion [8].
- In January 2026, Teva Pharmaceutical Industries Ltd. reported that 2025 corporate receipts rose 4% to USD 17.3 billion as once-daily extended-release oral tablet Austedo XR drove Austedo franchise growth of 34% to USD 2.26 billion [10].
Key Players in the Oral Solid Dosage Pharmaceutical Formulation Market
Global Innovator Oral Solid & CDMO Platforms
- Pfizer Inc.
- Novartis AG
- AstraZeneca PLC
Oral Peptide & Cardiometabolic Formulation Leaders
- Merck & Co., Inc.
High-Volume Generic & Extended-Release Matrix Specialists
- Teva Pharmaceutical Industries Ltd.
Oral Solid Dosage Pharmaceutical Formulation Market Report Scope
Table 9: Report Scope for the Oral Solid Dosage Pharmaceutical Formulation Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Dosage Form, Release Mechanism, Solubility Enhancement Tech, Therapeutic Area, Manufacturing Model, Primary Packaging |
| Quantitative Units | USD Billion |
| Market Definition | Includes finished prescription and hospital-dispensed oral solid pharmaceutical dosage forms comprising compressed film-coated and uncoated tablets, hard gelatin and HPMC capsules, softgels, orally disintegrating and chewable tablets, and multiparticulate pellets, granules, and sachets. Category Scope Note Excludes parenteral vials and prefilled syringes, topical creams, inhaled aerosols, and unmedicated food confectionery. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Germany, Japan, and additional national markets in the full report |
| Key Companies Covered | Pfizer Inc., Novartis AG, AstraZeneca PLC, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. Segment shares and forecast estimates are FMI proprietary analytical estimates. |
Oral Solid Dosage Pharmaceutical Formulation Market Research Methodology
Table 10: Research Methodology for the Oral Solid Dosage Pharmaceutical Formulation Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, healthcare professionals, industry experts, and key opinion leaders across the value chain to validate market trends, compression and dissolution protocols, demand dynamics, and purchasing decisions. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements reviewed for relevance and consistency with the defined market scope. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess tablet and capsule volume demand, price points, and CDMO outsourcing trends. |
| Data Validation | Data is validated against macro-economic indicators, chronic disease prevalence, compendial regulatory standards, and historical trend analysis to ensure accuracy without double counting bulk API trade. |
Oral Solid Dosage Pharmaceutical Formulation Market by Segments
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Dosage Form:
- Compressed Film-Coated & Uncoated Tablets
- Hard Gelatin & HPMC Vegetarian Capsules
- Softgel Liquid-Filled Capsules
- Orally Disintegrating, Chewable & Effervescent Tablets
- Multiparticulate Pellets, Granules & Sachets
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Release Mechanism:
- Immediate-Release Conventional OSD
- Controlled-, Sustained- & Osmotic-Release
- Delayed-Release Enteric-Coated
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Solubility Enhancement Tech:
- Direct Compression & Wet Granulation
- Hot-Melt Extrusion & Spray-Dried Amorphous Solid Dispersion
- Lipid Self-Emulsifying & Nano-Milled
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Therapeutic Area:
- Cardiovascular, Metabolic & Oral GLP-1/SGLT2
- Central Nervous System & Pain
- Oncology Small-Molecule Kinase Inhibitors
- Anti-Infectives, GI & Respiratory
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Manufacturing Model:
- In-House Innovator & Generic Pharma Plants
- Contract Development & Manufacturing Organizations
Oral Solid Dosage Pharmaceutical Formulation Market segmented by Primary Packaging:
- Thermoformed PVC/PVDC & Cold-Form Alu-Alu Blisters
- HDPE Desiccant-Canister Pill Bottles
Oral Solid Dosage Pharmaceutical Formulation Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Jena, S., Jindal, R., Dutta, D., Kamrul-Hasan, A. B. M., & Mahajan, K. (2026, May 14). Efficacy and Safety of Oral Semaglutide in the Management of Diabetes and Obesity: A Comprehensive Meta-analysis of Real-world Evidence. touchREVIEWS in Endocrinology, 22(1), 16-28 (PubMed PMID 42272996).
- [2] Bautista, M., Caille, S., Corredor, C., Anantharaman, S., Bradbury, J., Chen, B., et al. (2025, February 26). Blend Uniformity and Content Uniformity in Oral Solid Dosage Manufacturing: an IQ Consortium Industry Position Paper. The AAPS Journal, 27(2), 49 (PubMed PMID 40011408).
- [3] Leung, C. K., Bawuah, P., Spiesshofer, N., Kottlan, A., Baumberg, J. J., & Zeitler, J. A. (2026, July 24). Simple hybrid predictive model for point-of-care pharmaceutical tablet disintegration. Journal of Controlled Release, 398, 115190 (PubMed PMID 42498232).
- [4] Dong, Y., Ye, S., Hong, X., Shi, Y., Liu, Y., Zhang, X., Ye, J., & Xiao, M. (2026, May 2). Development of HPMC-Based Hard Capsules with Rapid Disintegration Across Simulated Gastrointestinal pH Conditions: Formulation Design, Process Optimization, and Disintegration Mechanism of the HPMC/GG/ι-C Ternary System. Marine Drugs, 24(5), 162 (PubMed PMID 42188297).
- [5] Franjic, D., Fountaine, R. J., Nalpas, C., Goswami, B., & Fullerton, T. (2026, March 4). Efficacy and safety of rimegepant 75 mg orally disintegrating tablet for the acute treatment of chronic rhinosinusitis in adults: Results from a multicenter, randomized, placebo-controlled, phase 2/3 trial. PLOS One, 21(3), e0342907.
- [6] Raje, V., Lu, I., Keir, R. S., & Serajuddin, A. T. M. (2026, January 5). Development of indomethacin amorphous solid dispersion by applying acid-base supersolubilization (ABS) principle to enhance solubility and enable low-temperature hot melt extrusion. International Journal of Pharmaceutics, 687, 126405 (PubMed PMID 41260348).
- [7] Merck & Co., Inc. (2025, July 29). Merck & Co., Inc., Rahway, N.J., USA Announces Second-Quarter 2025 Financial Results. Merck Newsroom.
- [8] Pfizer Inc. (2026, February 3). Pfizer Reports Solid Full-Year 2025 Results And Reaffirms 2026 Guidance. Pfizer Investor Relations.
- [9] Kishino, Y., Fukuda, Y., Kiyokawa, S., & Hiroi, K. (2026, June 12). Influence of Helicobacter pylori eradication blister-pack handling on outpatient AWaRe access share: a Japanese community pharmacy-based sensitivity analysis. Journal of Pharmaceutical Health Care and Sciences (PubMed PMID 42286771).
- [10] Teva Pharmaceutical Industries Ltd. (2026, January 28). Teva Innovative Portfolio and Consistent Execution of Pivot to Growth Strategy Deliver Third Consecutive Year of Growth; Pipeline Positioned to Unlock Significant Value Potential. Teva Investor Relations.
- [11] AstraZeneca PLC. (2026, February 10). Full Year and Q4 2025 results. AstraZeneca Media Centre.
- [12] Martynek, D., Ridvan, L., Sivén, M., & Šoóš, M. (2025, March 15). Stability and recrystallization of amorphous solid dispersions prepared by hot-melt extrusion and spray drying. International Journal of Pharmaceutics, 672, 125331 (PubMed PMID 39933609).
- [13] Magramane, S., Kállai-Szabó, N., Farkas, D., Süvegh, K., Zelkó, R., & Antal, I. (2025, July 3). Comparative Evaluation of Gelatin and HPMC Inhalation Capsule Shells Exposed to Simulated Humidity Conditions. Pharmaceutics, 17(7), 877 (PubMed PMID 40733086).
- [14] Martins, F. S., Borges, L. L., Kollipara, S., Sivadasu, P., & do Couto, R. O. (2025, December 16). DoE- and PBBM-Driven Formulation Development of an Extended-Release Donepezil Tablet. Pharmaceuticals (Basel), 18(12), 1894 (PubMed PMID 41471383).
- [15] Wood, C. C., Patel, K. G., Weber, V. L., Osakwe, A. R., Manovacia Moreno, N. P., Broich, M. L., et al. (2025, July 25). Development of impact resistant immediate release amorphous solid dispersion via hot-melt extrusion and injection molding. International Journal of Pharmaceutics, 680, 125746 (PubMed PMID 40449639).
- [16] de la Cruz Cruz, P., Martínez Muñoz, A., Guido Ávila, E. G., Hernández Piña, O. E., & Pérez Urizar, J. T. (2026, May 28). Bioequivalence of Two Empagliflozin 25 mg Immediate-Release Tablet Formulations Under Fasting Conditions in Healthy Mexican Subjects. Pharmaceuticals (Basel), 19(6), 842 (PubMed PMID 42356460).
- [17] Hediger, S., Locher, L., & Vokinger, K. N. (2025, September 17). Generic competition and price developments in the USA, Germany and Switzerland (2007-2023): a longitudinal observational study. BMJ Public Health, 3(2), e002535 (PubMed PMID 41001243).
- [18] Novartis AG. (2026, October 27). Novartis delivered sales growth and core margin expansion in Q3; raised FY core operating income guidance. Novartis Media Releases.
- [19] Tsolaki, E., Howard, A., Jiang, Y., Lu, X., Wang, L., Abouselo, A., et al. (2026, August 4). High-throughput eutectic screening and hot-melt extrusion enable rapid development of nifedipine amorphous solid dispersions. International Journal of Pharmaceutics, 127282 (PubMed PMID 42551721).
- [20] Badawi, S., Fischer, B., Lillotte, T., Esser, E., Nueboldt, C., & Breitkreutz, J. (2026, June 22). Preparation of orodispersible minitablets containing a poorly compactable drug substance by aqueous fluid bed layering onto coprocessed excipients. International Journal of Pharmaceutics, 701, 127120 (PubMed PMID 42331116).
- [21] Yagisawa, K., Kubota, A., Imai, S., Nashimoto, S., Sato, Y., Kashiwagi, H., et al. (2025, January 1). Actual Use of Budesonide Enteric-Coated Capsules for Crohn's Disease in Japan: Analysis of Health Insurance Big Data. Biological and Pharmaceutical Bulletin, 48(1), 33-38 (PubMed PMID 39864854).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the oral solid dosage pharmaceutical formulation market in 2026?
- Which formulation technologies support demand for oral solid dosage forms through 2036?
- Why do compressed tablets lead the dosage form category in 2026?
- Why does immediate-release conventional OSD lead the release mechanism category globally?
- How do growth rates differ across Brazil, Mexico, and the USA?
- Which notable companies supply innovative and generic oral solid formulations today?
Frequently Asked Questions
How big is the oral solid dosage pharmaceutical formulation market in 2026, and what is forecast for 2036?
As noted by FMI, global oral solid dosage pharmaceutical formulation market value is estimated to reach USD 676.1 billion in 2026 from USD 652.0 billion in 2025 and is projected to total USD 972.3 billion by 2036.
What is the CAGR for the oral solid dosage pharmaceutical formulation market from 2026 to 2036?
An FMI analyst notes that the market is forecast to expand at a 3.7% compound annual growth rate between 2026 and 2036, adding USD 296.2 billion in valuation.
Which dosage form segment leads the oral solid dosage pharmaceutical formulation market?
Compressed film-coated and uncoated tablets is projected to capture 57.1% of dosage form demand in 2026, driven by high-speed rotary compression efficiency and fixed-dose combination versatility.
Which release mechanism segment leads the oral solid dosage pharmaceutical formulation market?
Immediate-release conventional OSD is estimated to secure 61.9% of the release mechanism category in 2026 as acute and standard chronic medications rely on rapid gastrointestinal dissolution.
Which country has a notable growth outlook during the assessment period?
Brazil is projected to record a 4.8% CAGR through 2036 followed by Mexico at 4.5%, supported by ANVISA generic bioequivalence approvals and public pharmacy tablet dispensing.
Who are the notable companies in the market?
Pfizer Inc., Novartis AG, AstraZeneca PLC, Merck & Co., Inc., and Teva Pharmaceutical Industries Ltd. are the notable companies operating in the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Dosage Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Dosage Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Dosage Form, 2026 to 2036
- Compressed Film-Coated & Uncoated Tablets
- Hard Gelatin & HPMC Vegetarian Capsules
- Softgel Liquid-Filled Capsules
- Orally Disintegrating, Chewable & Effervescent Tablets
- Multiparticulate Pellets, Granules & Sachets
- Y-o-Y Growth Trend Analysis By Dosage Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Dosage Form, 2026 to 2036
- Global Market Analysis and Forecast, By Release Mechanism, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Release Mechanism, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Release Mechanism, 2026 to 2036
- Immediate-Release Conventional OSD
- Controlled-, Sustained- & Osmotic-Release
- Delayed-Release Enteric-Coated
- Y-o-Y Growth Trend Analysis By Release Mechanism, 2021 to 2025
- Absolute $ Opportunity Analysis By Release Mechanism, 2026 to 2036
- Global Market Analysis and Forecast, By Solubility Enhancement Tech, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Solubility Enhancement Tech, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Solubility Enhancement Tech, 2026 to 2036
- Direct Compression & Wet Granulation
- Hot-Melt Extrusion & Spray-Dried Amorphous Solid Dispersion
- Lipid Self-Emulsifying & Nano-Milled
- Y-o-Y Growth Trend Analysis By Solubility Enhancement Tech, 2021 to 2025
- Absolute $ Opportunity Analysis By Solubility Enhancement Tech, 2026 to 2036
- Global Market Analysis and Forecast, By Therapeutic Area, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapeutic Area, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapeutic Area, 2026 to 2036
- Cardiovascular, Metabolic & Oral GLP-1/SGLT2
- Central Nervous System & Pain
- Oncology Small-Molecule Kinase Inhibitors
- Anti-Infectives, GI & Respiratory
- Y-o-Y Growth Trend Analysis By Therapeutic Area, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapeutic Area, 2026 to 2036
- Global Market Analysis and Forecast, By Manufacturing Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Manufacturing Model, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Manufacturing Model, 2026 to 2036
- In-House Innovator & Generic Pharma Plants
- Contract Development & Manufacturing Organizations
- Y-o-Y Growth Trend Analysis By Manufacturing Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Manufacturing Model, 2026 to 2036
- Global Market Analysis and Forecast, By Primary Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Primary Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Primary Packaging, 2026 to 2036
- Thermoformed PVC/PVDC & Cold-Form Alu-Alu Blisters
- HDPE Desiccant-Canister Pill Bottles
- Y-o-Y Growth Trend Analysis By Primary Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Primary Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Dosage Form
- By Release Mechanism
- By Solubility Enhancement Tech
- By Therapeutic Area
- By Manufacturing Model
- By Primary Packaging
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pfizer Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Novartis AG
- AstraZeneca PLC
- Merck & Co., Inc.
- Teva Pharmaceutical Industries Ltd.
- Pfizer Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


