
- Market Size (2026)
- USD 25.7 Bn
- Forecast (2036)
- USD 38.0 Bn
- CAGR (2026 to 2036)
- 4.0%
How big is Over-the-Counter Pain Medication Market in 2026?
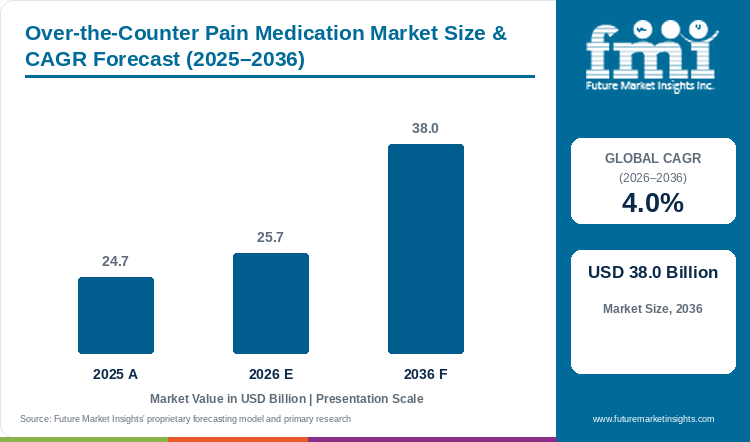
The over-the-counter pain medication market demonstrated steady progress from USD 24.7 billion in 2025 to USD 25.7 billion in 2026, building toward a targeted valuation of USD 38.0 billion by 2036 at a CAGR of 4.0%.
Per FMI estimates, the over-the-counter pain medication industry valuation rose from USD 24.7 billion for 2025 to USD 25.7 billion during 2026 and is forecast to reach USD 38.0 billion in 2036 on a 4.0% CAGR, with non-steroidal anti-inflammatory drugs commanding 45.3% of 2026 active drug class demand. This 4.0% expansion outpaces the 2.8% CAGR of standalone fixed-dose combination analgesics since consumers buy both fast-acting oral liquid-gels and targeted topical gels. Consumer demand for longer-lasting non-opioid pain relief is driving pharmacy adoption of new formulas. For instance, in July 2026 Kenvue received US FDA approval for Tylenol with Naproxen after a March 2026 survey of 6,240 pain sufferers showed 75% wanted stronger twelve-hour relief than single-ingredient pills offer [1]. Even so, stomach irritation from frequent NSAID use and cheap store brands limit price hikes, so growth depends on trade-up to gentle topical gels and dual-action caplets.
Key Market Trends & Insights
- By active drug class: Non-steroidal anti-inflammatory drugs (ibuprofen and naproxen or diclofenac) are projected to capture 45.3% in 2026, driven by cyclooxygenase inhibition.
- By route of administration: Oral tablets and liquid-gels or effervescent powders are estimated to command 82.5% in 2026, supported by rapid plasma absorption.
- By pain indication: Headache and migraine or tension pain is expected to concentrate 35.9% in 2026 due to frequent episodic work-day headaches.
- By distribution channel: Retail pharmacies and drugstores are forecast to generate 53.1% in 2026, reinforced by pharmacist triage and pack consultations.
- By patient demographic: Adult population aged 18 to 64 years is anticipated to account for 57.6% in 2026, while private commercial health insurance and out-of-pocket represents 55.4% and prescription and clinician-supervised holds 54.5%.
Regional Highlights
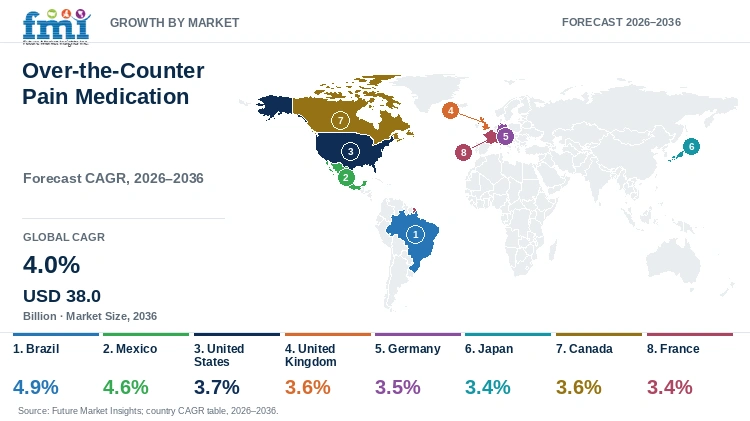
- Top national expansion: Brazil tops national self-care growth at a 4.9% CAGR until 2036 on rapid pharmacy chain expansion and solubilized liquid-gel adoption.
- Broader country progression: Mexico logs a 4.6% CAGR to 2036 while the United States posts 3.7% and the United Kingdom records 3.6% with Germany at 3.5% and Japan at 3.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Over-the-Counter Pain Medication Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 24.7 billion |
| Estimated Market Size in 2026 | USD 25.7 billion |
| Projected Market Size by 2036 | USD 38.0 billion |
| CAGR, 2026 to 2036 | 4.0% |
| Added Market Value, 2026 to 2036 | USD 12.3 billion |
Outpatient dental clinics and day-surgery centers are recommending over-the-counter dual-action pills and topical gels so recovering patients can avoid prescription opioids. For instance, in September 2026, Phase 3 trials presented by Kenvue at PAINWeek showed fixed-dose acetaminophen and naproxen sodium cut 48-hour opioid rescue use by nearly 40% versus placebo [2]. Pharmacies now pair dual-action caplets with localized topical pain relief formulations for post-surgical home care.
Consumer-Pool and Dose-Volume Sizing
Table 2: Consumer-Pool and Dose-Volume Sizing for the Over-the-Counter Pain Medication Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 24.7 | 25.7 | 38.0 |
| Self-treating analgesic users globally (billion) | 2.8 to 3.1 | 2.9 to 3.2 | 3.6 to 4.0 |
| Retail packs dispensed annually (billion) | 4.1 to 4.5 | 4.3 to 4.7 | 5.8 to 6.4 |
| Average retail pack value (USD) | 5.5 to 6.0 | 5.5 to 6.0 | 5.9 to 6.6 |
Operational note: Consumer-pool ranges apply global adult and pediatric self-medication incidence figures to standard 200 mg to 650 mg oral unit doses and topical application courses.
Higher retail demand for fast-dissolving ibuprofen liquid-gels and sustained-release tablets requires consumer health brands to lock in steady bulk active ingredient supply. Global tableting plants sign multi-year purchasing agreements for bulk ibuprofen active pharmaceutical ingredients to protect retail pack margins against raw material price swings.
Per Capita & Retail Pharmacy Outlet Sizing
Table 3: Per Capita and Household Allocation Indicators for the Over-the-Counter Pain Medication Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 3,012.2 | 3,096.4 | 4,222.2 |
| Annual household OTC pain allocation (USD) | 11.0 to 14.5 | 11.5 to 15.2 | 16.0 to 21.5 |
| Oral dosage form share of volume (%) | 82.2% to 82.8% | 82.3% to 82.7% | 80.5% to 81.5% |
Table 4: Retail Pharmacy & Outlet Allocation Indicators for the Over-the-Counter Pain Medication Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 25.7 billion | 2026 global market value baseline |
| Retail pharmacies & drugstores | 1.4 million outlets | Global licensed community pharmacy and drugstore registry |
| Average value per pharmacy outlet | USD 18,357 | Annualized OTC analgesic category value per outlet |
| Retail pharmacy channel value, 2026 | USD 13.6 billion | 53.1% distribution channel segment allocation |
High consumer preference for easy-to-swallow caplets and rapid-dissolve fever powders is pushing contract manufacturers to upgrade tablet coating and granulation lines. Formulators purchase direct-compressible paracetamol and acetaminophen bulk actives to produce smooth-coated adult caplets and taste-masked children's suspensions.
Analyst Perspective
"Retail pharmacy category managers and self-treating consumers are trading up from single-ingredient generic tablets to fixed-dose acetaminophen-NSAID combinations and 2% diclofenac emulgels. Consumer health brands that pair twelve-hour sustained relief claims with lower gastrointestinal risk profiles will capture premium shelf space through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the over-the-counter pain medication market segmented?
The over-the-counter pain medication market is segmented by seven primary commercial axes (active drug class, route of administration, pain indication, distribution channel, patient demographic, reimbursement pathway, and regulatory classification) and region. In 2026, non-steroidal anti-inflammatory drugs are projected at 45.3%, oral tablets and liquid-gels at 82.5%, headache and migraine pain at 35.9%, retail pharmacies at 53.1%, and adults aged 18 to 64 at 57.6%.
By active drug class: non-steroidal anti-inflammatory drugs (ibuprofen, naproxen, aspirin, and diclofenac), acetaminophen and paracetamol analgesics, topical local anesthetics (lidocaine, menthol, and capsaicin), and combination analgesic plus caffeine or antihistamine formulas.
By route of administration: oral tablets, liquid-gels, caplets, and effervescent powders, and topical emulgels, transdermal hydrogel patches, and roll-ons.
By pain indication: headache, migraine, and tension pain, musculoskeletal, backache, and osteoarthritis joint pain, and dental, menstrual dysmenorrhea, and cold or flu fever.
By distribution channel: retail pharmacies and drugstores, supermarkets, convenience, and mass merchandisers, and online pharmacies and quick-commerce.
By patient demographic & pathway: adult population 18 to 64 years, geriatric population 65 years and older, and pediatric and adolescent patients, plus private commercial health insurance and out-of-pocket (55.4%) and prescription and clinician-supervised (54.5%).
Why do non-steroidal anti-inflammatory drugs lead active drug class demand?
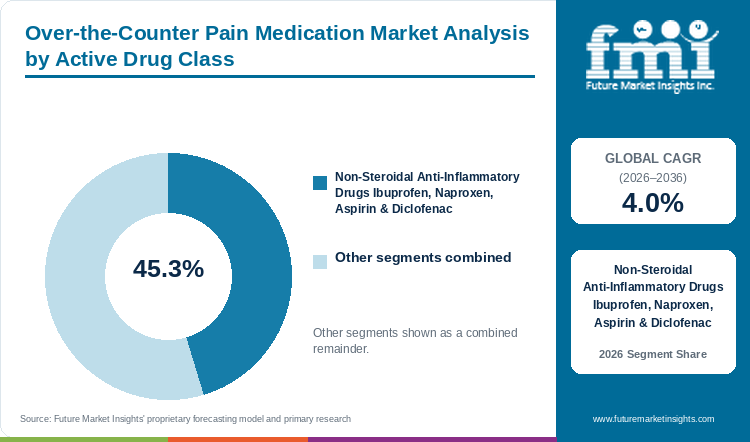
Based on active drug class, non-steroidal anti-inflammatory drugs are projected to account for 45.3% in 2026, driven by anti-inflammatory potency.
Table 5: Active Drug Class Share for the Over-the-Counter Pain Medication Market (percentage share), 2026
| Active Drug Class | Share (2026) |
|---|---|
| Non-Steroidal Anti-Inflammatory Drugs Ibuprofen, Naproxen, Aspirin & Diclofenac | 45.3% |
| Other Active Drug Classes Combined | 54.7%* |
| Total | 100.0% |
*Note: Remaining active drug class categories sum to 100.0% of 2026 market value.
Table 6: Active Drug Class Leadership and Market Growth for the Over-the-Counter Pain Medication Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.0% |
| Leading Segment | Non-Steroidal Anti-Inflammatory Drugs Ibuprofen, Naproxen, Aspirin & Diclofenac |
Household buyers choose ibuprofen, naproxen, and diclofenac over plain fever reducers because these medicines relieve both everyday pain and joint or muscle swelling. Retail drugstores stock high-margin NSAID liquid-gels beside finished acetaminophen dosage forms to cover both inflammatory joint aches and simple headaches.
- Non-steroidal anti-inflammatory drugs are set to lead the active drug class category with 45.3% share in 2026, reinforced by dual analgesic and anti-swelling action.
- Per a May 2025 network meta-analysis of 31 randomized trials covering 68,539 knee osteoarthritis patients in PLoS One, naproxen improved physical joint function at MD minus 0.43 and diclofenac reduced stiffness at MD minus 0.40 [3].
What supports oral tablets and liquid-gels as the preferred administration route?
By route of administration, oral tablets and liquid-gels are estimated to hold 82.5% in 2026, supported by rapid systemic absorption.
Consumers prefer oral tablets and solubilized liquid-gels or effervescent packets for everyday headaches, dental pain, and menstrual cramps because single-dose blister packs are affordable and easy to carry. Buyers also combine oral pills with cooling menthol muscle relaxing creams for sore muscles after work or exercise.
- Oral tablets and liquid-gels or effervescent powders are projected to hold 82.5% share in 2026, enabled by low unit-dose cost and portable blister packs.
- For instance, pharmacokinetic trials published in February 2026 showed that 400 mg bilayer ibuprofen tablets kept blood drug levels above 6.8 ug/mL for eight full hours while staying within the 1,200 mg daily OTC limit [4].
How is headache and migraine pain driving analgesic indication demand?
In 2026, headache, migraine, and tension pain is expected to lead pain indication with 35.9% share, owing to episodic attacks.
Frequent work-day tension headaches and sudden migraine attacks generate the highest repeat purchase volume across retail drugstores, supermarkets, and convenience stores. While oral caffeine-added pills lead acute headache sales, older adults with chronic joint pain also buy transdermal non-opioid pain patches for overnight relief.
- Headache and migraine pain will top pain indication demand with 35.9% share in 2026, linked to thirty-minute workplace relief.
- An October 2025 UK health-economic study in Cost Effectiveness and Resource Allocation across 230.3 million primary-care visits showed that a 5% rise in OTC ibuprofen self-care for migraine and menstrual pain saved 409,243 NHS doctor visits and 882,875 work hours annually [5].
Why are buyers selecting retail pharmacies and drugstores for self-care?
By distribution channel, retail pharmacies and drugstores are forecast to represent 53.1% in 2026, reinforced by pharmacist dosing triage.
Shoppers rely on chain drugstores and neighborhood pharmacies for pain medication purchases because pharmacists offer free advice on safe dosing and blood-pressure drug interactions. Pharmacy chains also expand their own lower-priced store brands to keep budget-conscious families shopping in their aisles.
- In distribution channel, retail pharmacies and drugstores are anticipated to hold the leading spot at 53.1% share in 2026 due to behind-the-counter pharmacist guidance.
- For instance, Perrigo Company plc reported in February 2026 that fiscal 2025 net sales reached USD 4.25 billion, including USD 2.59 billion in Americas self-care as US store-brand pain products gained 120 basis points of fourth-quarter volume share [6].
Which market conditions keep working-age adults leading patient demographic demand?
Adult population aged 18 to 64 years is likely to capture 57.6% share in 2026, linked to occupational pain.
Working-age adults between 18 and 64 years buy the highest volume of non-prescription pain relievers to manage workplace backaches, headaches, and sports sprains or monthly menstrual cramps. By payment and regulatory category, private insurance and out-of-pocket cash purchases hold 55.4% share while clinician-supervised behind-the-counter packs account for 54.5%.
- Within the patient demographic category, adult population aged 18 to 64 years is likely to secure 57.6% share in 2026, influenced by recurring backache and dysmenorrhea.
- Per an August 2025 clinical study of 247 outpatient rehabilitation patients in Scientific Reports, use of 400 mg over-the-counter ibuprofen within eight hours of physical therapy raised sensory pain thresholds during exercise [7].
What are the drivers, restraints, and opportunities in the over-the-counter pain medication market?
In the over-the-counter pain medication market, the key driver is fixed-dose combination approvals, the key restraint is oral NSAID gastric toxicity, and the key opportunity is 2% topical diclofenac gels.
- Driver: Regulatory approvals of fixed-dose acetaminophen-NSAID combinations and twelve-hour topical diclofenac gels expand non-opioid self-care options.
- Restraint: Patient-reported gastrointestinal ulceration and renal side effects from chronic oral NSAID intake prompt clinical warnings and dose duration caps.
- Opportunity: Permeation-enhanced topical NSAID emulgels and lidocaine creams deliver localized joint and neuropathic relief without systemic gastric exposure.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Higher healthcare costs and long wait times for doctor appointments are driving consumers and health systems to rely on non-prescription analgesics for everyday pain management. FMI research indicates that tax-free health savings accounts in the United States and pharmacy self-care programs in Europe encourage families to stock menstrual dysmenorrhea pain therapies and children's fever liquids at home. For instance, in October 2025, a review of 15 clinical studies in the Italian Journal of Pediatrics found that pediatric ibuprofen share rose from 31.2% to 36.7% while OTC pediatric ibuprofen pack purchases jumped 61% [8]. Stronger shopper preference for fast-acting liquid-gels and twelve-hour dual-action caplets continues to lift retail category sales.
Risk Assessment of the Over-the-Counter Pain Medication Market: Operational and Formulation Friction
Stomach ulcer risks, blood-pressure concerns, and liver dosing limits from taking too many oral pain pills are the main factors restraining long-term tablet consumption. Adults managing chronic back pain or knee arthritis often take oral NSAIDs more days per month than label directions recommend, which raises gastrointestinal side-effect rates. Per a November 2025 randomized trial of 425 US adult regular OTC NSAID users averaging 20.14 dose-days per month in PLoS One, a short patient education video cut high-risk NSAID overuse by 32.8% to 36.5% within four weeks [9]. Strict stomach-bleeding and liver warning labels on retail boxes therefore push frequent headache sufferers toward non-oral options like acute migraine nasal spray delivery when pills cause nausea.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Stronger demand among older adults for joint pain relief that does not upset the stomach opens major commercial opportunities for high-strength topical NSAID gels and patches. Topical diclofenac gels and lidocaine creams deliver pain-relieving ingredients directly through the skin into sore knees, hands, and shoulders while supporting orthopedic fracture and joint care recovery. For instance, in March 2025, a meta-analysis of 12 randomized trials in BMC Musculoskeletal Disorders showed that topical diclofenac patches provided strong one-to-two-week knee osteoarthritis pain relief at SMD minus 0.64 while diclofenac gels sustained eight-to-twelve-week joint function [10]. No-mess roll-on applicators and twice-daily 2% diclofenac gels allow brands to charge premium retail prices.
Over-the-Counter Pain Medication Market by Country (2026 to 2036)
In the FMI report, Brazil tops over-the-counter pain medication expansion with a 4.9% CAGR until 2036, while Japan registers a 3.4% CAGR over the decade. National sales momentum across Western Hemisphere and European drugstore chains as well as Asian pharmacies tracks Rx-to-OTC switch approvals and store-brand shelf share.
Table 7: Country CAGR and Primary Growth Levers for the Over-the-Counter Pain Medication Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 4.9% | Consumer trade-up to solubilized ibuprofen softgels and rapid pharmacy chain expansion |
| Mexico | 4.6% | Strong demand for Actron ibuprofen liquid-gels and quick-commerce pharmacy delivery |
| United States | 3.7% | FDA approval of Tylenol with Naproxen and FSA/HSA-eligible self-care spending |
| United Kingdom | 3.6% | NHS self-care minor-ailment triage and Panadol Dual Action and Voltaren 2% Gel growth |
| Germany | 3.5% | Apotheke-exclusive dispensing and pharmacist counseling toward topical diclofenac gels |
| Japan | 3.4% | Geriatric adoption of transdermal NSAID hydrogel patches and Self-Medication Tax Deduction |
| Canada | 3.6% | Pharmacist minor-ailment prescribing and rehabilitative 5% topical lidocaine cream uptake |
| France | 3.4% | Behind-the-counter ANSM pharmacist counseling and Doliprane paracetamol franchise scale |
Source: Future Market Insights analysis
Brazil Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
Stronger consumer trade-up from basic paracetamol and dipyrone tablets to fast-dissolving ibuprofen softgel capsules and topical diclofenac gels is driving retail sales across Brazil. Per a June 2026 quality and dissolution study in ACS Omega testing Brazilian ibuprofen soft gelatin capsules, the liquid-filled capsules released 81.96% to 105.1% of their active ibuprofen within 60 minutes [11]. Brazil's self-care analgesic sector will advance at a 4.9% CAGR until 2036, reinforced by ANVISA RDC 98 self-care rules and rapid retail drugstore chain expansion across major southern and southeastern Brazilian urban centers. Although imported raw material costs pressure local tablet margins, domestic softgel plants sustain high-volume supply for national pharmacy chains.
Key takeaway: In Brazil, consumer trade-up to solubilized ibuprofen softgels and national drugstore expansion will sustain a top 4.9% CAGR.
Mexico Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
Broader modern pharmacy chains, supermarket drug counters, and mobile delivery apps are boosting household purchases of branded pain relievers across Mexico. Whereas North American shoppers buy large club-store bottles, Mexican consumers prefer affordable small blister packs of naproxen and ibuprofen or caffeine-added headache tablets. For instance, Bayer AG reported in August 2026 that first-half Consumer Health sales rose 3.5% and second-quarter Pain and Cardio sales grew 3.4% on strong Latin American demand for Actron ibuprofen capsules [12]. Analgesic demand across Mexico is forecast to rise at a 4.6% CAGR through 2036, supported by urban job growth, though low-priced domestic generics keep price competition tight on basic tablets.
Key takeaway: In Mexico, strong Latin American demand for branded ibuprofen caplets like Actron and pharmacy delivery apps will support a 4.6% CAGR.
United States Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
High household self-medication rates and new FDA approvals for dual-action non-opioid pain relievers are supporting steady retail demand across American pharmacies. Per an April 2026 national survey of over 14,000 US adults published in Public Health, 43.6% of American adults reported taking acetaminophen in the past month between October and December 2025 [13]. Self-care analgesic adoption in the United States is slated to climb at a 3.7% CAGR until 2036, driven by the July 2026 FDA approval of Kenvue Tylenol with Naproxen and broad HSA-eligible retail spending. High store-brand share at Walmart, CVS, and Walgreens limits price increases on plain tablets while rewarding patented dual-action and topical launches.
Key takeaway: In the United States, FDA clearance of fixed-dose Tylenol with Naproxen and broad HSA-eligible self-care spending are anticipated to support a 3.7% CAGR.
United Kingdom Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
National Health Service self-care campaigns encouraging adult patients to visit neighborhood community pharmacies for minor aches, migraines, and period pain are driving steady retail demand across the United Kingdom. For instance, Weybridge-headquartered Haleon plc reported in July 2026 that Pain Relief generated 24% of first-half group revenue and grew 2.1% organically on strong pharmacy sales of Voltaren 2% Gel and Panadol Dual Action [14]. The British non-prescription analgesic category is projected to log a 3.6% CAGR during the ten-year horizon, enabled by community pharmacist consultations and premium topical gel adoption. Statutory 16-tablet supermarket pack limits prevent bulk buying at checkout aisles while generating steady repeat visits to high-street pharmacies.
Key takeaway: In the United Kingdom, NHS self-care triage pathways and strong pharmacy demand for Panadol Dual Action and Voltaren 2% Gel are estimated to drive a 3.6% CAGR.
Germany Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
Pharmacy-only dispensing laws in Germany protect non-prescription analgesic retail prices from supermarket discounting while giving pharmacists a direct role in product selection. Per a September 2026 European meta-analysis of eight randomized trials covering 1,325 pediatric patients in the European Journal of Pediatrics, ibuprofen and acetaminophen delivered comparable acute pain relief with a pooled SMD of minus 0.28 favoring ibuprofen in inflammatory pain [15]. In Germany, non-prescription pain medication demand is expected to climb at a 3.5% CAGR through 2036, linked to Apotheke pharmacist counseling and licensed online pharmacy delivery. Four-day self-treatment label limits on oral NSAIDs lead German pharmacists to recommend topical diclofenac gels for longer-term joint pain.
Key takeaway: In Germany, pharmacy-exclusive Apotheke dispensing and strong pharmacist counseling toward topical diclofenac emulgels are forecast to sustain a 3.5% CAGR.
Japan Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
High demand among older adults for soothing transdermal NSAID patches and pharmacist-dispensed loxoprofen tablets shapes the non-prescription pain market in Japan. For instance, a July 2026 clinical study of 72 Japanese patients in In Vivo showed that switching from oral NSAIDs to transdermal diclofenac patches cut mean pain scores from 3.8 to 2.4 within eight days and improved pain in 64% of patients [16]. Japanese self-care demand is projected to post a 3.4% CAGR across the forecast window due to geriatric joint care needs and Self-Medication Tax Deduction tax credits for households. Strong consumer loyalty to low-irritation adhesive tapes supports premium retail margins across Tokyo and Osaka drugstore chains.
Key takeaway: In Japan, high geriatric preference for transdermal NSAID patches and Self-Medication Tax Deduction tax credits are projected to anchor a 3.4% CAGR.
Canada Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
Stronger outpatient physical therapy demand for numbing lidocaine creams and open-shelf retail pharmacy access for fast-acting oral ibuprofen and naproxen caplets support steady sales across Canada. Per an October 2025 rehabilitation study in Cureus, over-the-counter 5% lidocaine cream numbed localized upper-limb pain nerves within 60 minutes across 18 participants [17]. Canadian non-prescription analgesic demand is projected to rise at a 3.6% CAGR by 2036, influenced by provincial minor-ailment pharmacist consultation programs across Ontario and British Columbia. Grocery and pharmacy private-label store brands still capture nearly half of plain tablet volume, so multinational consumer health brands focus on solubilized liquid-gels and dual-action caplets or targeted topical creams.
Key takeaway: In Canada, broader minor-ailment pharmacist consultation programs and rehabilitation adoption of 5% topical lidocaine creams are slated to support a 3.6% CAGR.
France Over-the-Counter Pain Medication Market Outlook (2026 to 2036)
Mandatory behind-the-counter retail pharmacist dispensing rules for all oral paracetamol, ibuprofen, and aspirin packs shape everyday consumer buying behavior across France. For instance, in July 2026, Paris-headquartered Sanofi S.A. reported 15.7% constant-exchange-rate first-half sales growth and second-quarter Opella consumer-health transition revenues supporting its flagship Doliprane paracetamol line across French pharmacies [18]. Across 2026 to 2036, French non-prescription pain demand is anticipated to progress at a 3.4% CAGR, associated with pharmacist-guided self-care consultations at neighborhood officine counters. Because ANSM rules ban open-shelf self-selection of oral pain pills to prevent overdose, French adult consumers rely on pharmacist-dispensed Doliprane 1,000 mg powder sachets and effervescent tablets or topical diclofenac gels.
Key takeaway: In France, behind-the-counter ANSM pharmacist counseling rules and entrenched household loyalty to Doliprane paracetamol formats are likely to sustain a 3.4% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the over-the-counter pain medication market?
Haleon plc, Kenvue Inc., Bayer AG, Reckitt Benckiser Group plc, Sanofi S.A., Perrigo Company plc, Taisho Pharmaceutical Holdings Co., Ltd., and Dr. Reddy's Laboratories Ltd. are the notable companies in the over-the-counter pain medication market.
FMI analysis indicates that the over-the-counter pain medication sector is moderately concentrated across global heritage brands and competitive across retail store-brand equivalents. Pure-play consumer health leaders invest in Rx-to-OTC switch trials and twelve-hour topical or dual-action line extensions, whereas private-label specialists supply bioequivalent tablet and liquid-gel store brands to pharmacy and mass-merchandiser chains.
- Pure-Play Consumer Health Leaders: Haleon plc and Kenvue Inc. with Opella (Sanofi S.A.) market flagship franchises led by Panadol and Voltaren along with Tylenol and Doliprane.
- European & Asian Analgesic Innovators: Bayer AG and Reckitt Benckiser Group plc with Taisho Pharmaceutical Holdings Co., Ltd. commercialize Aleve and Aspirin along with Actron and Nurofen.
- Store-Brand & Specialty Self-Care Platforms: Perrigo Company plc and Dr. Reddy's Laboratories Ltd. supply private-label retail store brands and branded topical or migraine self-care products.
Competitive Benchmarking: Over-the-Counter Pain Medication Market
Table 8: Competitive Benchmarking for the Over-the-Counter Pain Medication Market (qualitative capability ratings), 2026
| Company | Oral NSAID & Paracetamol Breadth | Topical & Dual-Action Innovation | Pharmacy & Retail Shelf Access | Geographic Reach |
|---|---|---|---|---|
| Haleon plc | High | High | High | High |
| Kenvue Inc. | High | High | High | High |
| Bayer AG | High | Medium | High | High |
| Reckitt Benckiser Group plc | High | High | High | High |
| Sanofi S.A. (Opella) | High | Medium | High | High |
| Perrigo Company plc | High | Medium | High | Medium |
| Taisho Pharmaceutical Holdings Co., Ltd. | Medium | High | High | Medium |
| Dr. Reddy's Laboratories Ltd. | Medium | Medium | Medium | Medium |
Scoring basis: Benchmark ratings assess product range across oral NSAIDs and acetaminophen as well as fixed-dose combinations and topical emulgels. Retail distribution and geographic ratings reflect verified drugstore shelf presence and e-commerce fulfillment across major regions.
Key Developments in the Over-the-Counter Pain Medication Market
- In October 2026, Reckitt Benckiser Group plc reported 2.2% like-for-like third-quarter Self Care net revenue growth and committed USD 0.6 billion toward US healthcare manufacturing expansion [19].
- In August 2026, Yanagihara and Imai reported in the Journal of Orthopaedic Science that diclofenac etalhyaluronate delivered cartilage-protective lower OARSI joint degeneration scores at 12 weeks in knee osteoarthritis models [20].
- In February 2026, Green et al. reported in JAMA Network Open across 21,000 US adults that 46.0% used an OTC medication in the past seven days led by acetaminophen (29.4%) and ibuprofen (22.3%) [21].
Key Players in the Over-the-Counter Pain Medication Market
Global Pure-Play Consumer Health Leaders
- Haleon plc
- Kenvue Inc.
- Sanofi S.A. (Opella)
Multinational NSAID and Asian Self-Care Innovators
- Bayer AG
- Reckitt Benckiser Group plc
- Taisho Pharmaceutical Holdings Co., Ltd.
Private-Label Store-Brand and Specialty OTC Platforms
- Perrigo Company plc
- Dr. Reddy's Laboratories Ltd.
Over-the-Counter Pain Medication Market Report Scope
Table 9: Report Scope for the Over-the-Counter Pain Medication Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Active Drug Class, Route of Administration, Pain Indication, Distribution Channel, Patient Demographic, Reimbursement and Payment Pathway, Regulatory Classification |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer value from non-prescription and pharmacist-supervised oral NSAIDs, acetaminophen/paracetamol, fixed-dose dual-mechanism combinations, topical NSAID emulgels and patches, and cutaneous lidocaine or menthol pain products. Category Scope Note: Excludes Schedule II/III prescription opioids, injectable hospital anesthetics, and standalone nutritional joint glucosamine supplements. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Germany, Japan, Canada, France, and additional countries in the full report |
| Key Companies Covered | Haleon plc, Kenvue Inc., Bayer AG, Reckitt Benckiser Group plc, Sanofi S.A., Perrigo Company plc, Taisho Pharmaceutical Holdings Co., Ltd., Dr. Reddy's Laboratories Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Over-the-Counter Pain Medication Market Research Methodology
Table 10: Research Methodology for the Over-the-Counter Pain Medication Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with retail pharmacy category managers, community pharmacists, outpatient pain clinicians, and OTC formulation directors to validate brand-versus-private-label shelf dynamics. |
| Secondary Research | Analysis of consumer health divisional filings, US FDA NDA/monograph approvals, European Medicines Agency and ANSM self-care advisories, and peer-reviewed PubMed analgesic trials. |
| Market Sizing and Forecasting | Top-down consumer health Pain Relief segment disclosures reconciled against bottom-up retail scanner pack volumes and average unit prices from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight adult and geriatric demographics, OTC monograph switch approvals, and pharmacy versus mass-merchandiser channel rules across major markets. |
| Operational Benchmark Traceability | Consumer-pool and pharmacy outlet indicators in Tables 2, 3, and 4 trace to Kenvue Phase 3 post-surgical cohorts, UK NHS self-care economic models, and national acetaminophen panels. |
| Data Triangulation and Validation | Category value estimates are cross-checked against Haleon, Kenvue, Bayer, Reckitt, Sanofi, and Perrigo segment reports without double counting bulk active pharmaceutical ingredients. |
Over-the-Counter Pain Medication Market by Segments
Over-the-Counter Pain Medication Market segmented by Active Drug Class:
- Non-Steroidal Anti-Inflammatory Drugs Ibuprofen, Naproxen, Aspirin & Diclofenac
- Acetaminophen / Paracetamol Analgesics
- Topical Local Anesthetics Lidocaine, Menthol & Capsaicin
- Combination Analgesic + Caffeine/Antihistamine Formulas
Over-the-Counter Pain Medication Market segmented by Route of Administration:
- Oral Tablets, Liquid-Gels, Caplets & Effervescent Powders
- Topical Emulgels, Transdermal Hydrogel Patches & Roll-Ons
- Oral Pediatric Suspensions & Melt-in-Mouth Granules
Over-the-Counter Pain Medication Market segmented by Pain Indication:
- Headache, Migraine & Tension Pain
- Musculoskeletal, Backache & Osteoarthritis Joint Pain
- Dental, Menstrual Dysmenorrhea & Cold/Flu Fever
Over-the-Counter Pain Medication Market segmented by Distribution Channel:
- Retail Pharmacies & Drugstores
- Supermarkets, Convenience & Mass Merchandisers
- Online Pharmacies & Quick-Commerce
- Hospital Outpatient & Clinic Pharmacies
Over-the-Counter Pain Medication Market segmented by Patient Demographic, Payment & Classification:
- Adult Population 18 to 64 Years
- Geriatric Population 65 Years and Older
- Pediatric and Adolescent Patients
- Private Commercial Health Insurance and Out-of-Pocket / Public Healthcare Systems
- Prescription and Clinician-Supervised / Over-the-Counter and Consumer Self-Care
Over-the-Counter Pain Medication Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Kenvue Inc. (2026, July 24). FDA approves Tylenol with Naproxen, the first and only over-the-counter fixed-dose combination of acetaminophen and naproxen sodium. Kenvue Inc.
- [2] Kenvue Inc. (2026, September 8). New clinical evidence presented at PAINWeek 2026 demonstrates the powerful, long-lasting relief of TYLENOL with Naproxen in post-surgical pain studies. Kenvue Inc.
- [3] JiaoYi, P., YongQi, S., KeChun, G., XingYu, L., ZeZhong, L., Jin Shuai, D., et al. (2025, May 7). Assessing the efficacy and safety of different nonsteroidal anti-inflammatory drugs in the treatment of osteoarthritis: A systematic review and network meta-analysis based on RCT trials. PLoS One, 20(5), e0320379 (PubMed PMID 40333622).
- [4] Smrčka, D., Ramesh, S., Dumicic, A., & Beránek, J. (2026, February 18). Optimizing ibuprofen dosing: insights from in vivo and virtual pharmacokinetic trials. European Journal of Pharmaceutical Sciences, 220, 107474 (PubMed PMID 41720357).
- [5] Afonso, D., Dymond, A., Eastwood, I., Green, W., Laughey, W., Aluko, P., et al. (2025, October 15). A health economics assessment of self-care with over-the-counter ibuprofen in dysmenorrhoea, migraine and acute rhinosinusitis in the United Kingdom. Cost Effectiveness and Resource Allocation, 23(1), 56 (PubMed PMID 41094660).
- [6] Perrigo Company plc. (2026, February 26). Perrigo Reports Fourth Quarter and Fiscal Year 2025 Financial Results From Continuing Operations. Perrigo Company plc.
- [7] Witkoś, J., Hartman-Petrycka, M., & Błażejewski, G. (2025, August 13). The effect of over-the-counter analgesics on changes to the sensory sensitivity of patients treated with transcutaneous electrical nerve stimulation. Scientific Reports, 15(1), 29638 (PubMed PMID 40804438).
- [8] Vassallo, F., Martinelli, M., Varcamonti, L., & Buono, P. (2025, October 28). Adverse reactions to acetaminophen and ibuprofen in pediatric patients: a narrative review. Italian Journal of Pediatrics, 51(1), 295 (PubMed PMID 41152986).
- [9] Vinson, M. G., Tegge, A. N., Tokala, M. R., Spivey, C. R., Tenzer, M. M., Stein, J. S., et al. (2025, November 10). A brief, theory-driven patient education video reduces high-risk over-the-counter nonsteroidal anti-inflammatory drug (NSAID) use. PLoS One, 20(11), e0323582 (PubMed PMID 41212921).
- [10] Chen, Z.-R., Chen, B.-K., Li, P., & Feng, K. (2025, March 10). Efficacy and safety of different topical diclofenac formulations for the treatment of knee osteoarthritis: a meta-analysis of short-term and long-term treatment comparisons. BMC Musculoskeletal Disorders, 26(1), 230 (PubMed PMID 40065343).
- [11] Souza E Souza, L. B., Ferreira Nunes, A. C., Simões, I. F., de Souza, T. L., & Santos Júnior, A. F. (2026, June 23). Development of a Sustainable Analytical Method Using High-Performance Liquid Chromatography (HPLC) and Dissolution Studies for Quality Control of Ibuprofen Soft Gelatin Capsules from Brazil. ACS Omega, 11(26), 38487-38496 (PubMed PMID 42428874).
- [12] Bayer AG. (2026, August 4). Consumer Health - Bayer Half-Year Financial Report Q2 2026. Bayer AG.
- [13] Sandlin, E. W. (2026, April 29). Partisan differences in acetaminophen use after revised federal guidance in the United States. Public Health, 256, 106313 (PubMed PMID 42060971).
- [14] Haleon plc. (2026, July 30). 2026 Half year results Statement: Six months ended 30 June 2026. Haleon plc.
- [15] Marseglia, G. L., Marchisio, P. G., Milani, G. P., Miraglia Del Giudice, M., Schiavetti, I., & Ciprandi, G. (2026, September 7). Ibuprofen versus acetaminophen for acute mild-to-moderate pain management in pediatric populations: a systematic review and meta-analysis of their efficacy. European Journal of Pediatrics, 185(9), 723 (PubMed PMID 42704487).
- [16] Iikura, Y., Yokokawa, T., Harashima, W., Kawakami, K., Mae, Y., Ishiguro, T., et al. (2026, July 1). Efficacy of Switching from Prior Nonsteroidal Anti-inflammatory Drugs to Transdermal Diclofenac in Cancer Pain Management. In Vivo, 40(4), 2196-2203 (PubMed PMID 42379803).
- [17] Baker, K., Salinas, D., Lozano Bonilla, M., Hensley, J., Butler, H., Lozano Garcia, M., et al. (2025, October 17). Evaluation of Over-the-Counter Cutaneous Lidocaine Cream for Temporary Deafferentation in Upper Limb Rehabilitation: A Cross-Sectional Study. Cureus, 17(10), e94797 (PubMed PMID 41250702).
- [18] Sanofi S.A. (2026, July 30). Q2 2026: double-digit sales growth and strong business EPS growth; 2026 guidance upgraded. Sanofi S.A.
- [19] Reckitt Benckiser Group plc. (2026, October 27). Q3 Results 2026: Powerbrands driving continued growth. Reckitt Benckiser Group plc.
- [20] Yanagihara, Y., & Imai, Y. (2026, August 27). Diclofenac etalhyaluronate provides cartilage-protective effects in a mouse model of knee osteoarthritis. Journal of Orthopaedic Science, S0949-2658(26)00238-1 (PubMed PMID 42660697).
- [21] Green, J. L., Dailey-Govoni, T., Kalidindi, S. D., & Vosburg, S. K. (2026, February 2). Prevalence of Over-the-Counter and Prescription Medication Use in the US. JAMA Network Open, 9(2), e2559479 (PubMed PMID 41697701).
- [22] Haleon plc. (2026, March 15). Our Brands: Pain Relief Portfolio (Panadol, Voltaren, Advil, Fenbid, and Excedrin). Haleon plc.
- [23] Perrigo Company plc. (2026, April 10). Pain and Sleep-Aids: Private Label Self-Care Portfolio. Perrigo Company plc.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the over-the-counter pain medication market in 2026?
- Which non-opioid clinical pressures support demand for non-prescription pain medications?
- Why do non-steroidal anti-inflammatory drugs lead active drug class demand?
- Why do oral tablets and liquid-gels lead by administration route?
- How do growth rates differ across Brazil, Mexico, and the USA?
- Which notable consumer healthcare companies supply oral and topical analgesics today?
- What limits prolonged oral NSAID dosing across self-treating adult consumers?
- What should pharmacy category buyers evaluate when selecting OTC analgesic assortments?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Active Drug Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Active Drug Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Active Drug Class, 2026 to 2036
- Non-Steroidal Anti-Inflammatory Drugs Ibuprofen, Naproxen, Aspirin & Diclofenac
- Acetaminophen / Paracetamol Analgesics
- Topical Local Anesthetics Lidocaine, Menthol & Capsaicin
- Combination Analgesic + Caffeine/Antihistamine Formulas
- Y-o-Y Growth Trend Analysis By Active Drug Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Active Drug Class, 2026 to 2036
- Global Market Analysis and Forecast, By Route of Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route of Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route of Administration, 2026 to 2036
- Oral Tablets, Liquid-Gels, Caplets & Effervescent Powders
- Topical Emulgels, Transdermal Hydrogel Patches & Roll-Ons
- Oral Pediatric Suspensions & Melt-in-Mouth Granules
- Y-o-Y Growth Trend Analysis By Route of Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route of Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Pain Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pain Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pain Indication, 2026 to 2036
- Headache, Migraine & Tension Pain
- Musculoskeletal, Backache & Osteoarthritis Joint Pain
- Dental, Menstrual Dysmenorrhea & Cold/Flu Fever
- Y-o-Y Growth Trend Analysis By Pain Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Pain Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail Pharmacies & Drugstores
- Supermarkets, Convenience & Mass Merchandisers
- Online Pharmacies & Quick-Commerce
- Hospital Outpatient & Clinic Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Patient Demographic, Payment & Classification, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Patient Demographic, Payment & Classification, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Patient Demographic, Payment & Classification, 2026 to 2036
- Adult Population 18 to 64 Years
- Geriatric Population 65 Years and Older
- Pediatric and Adolescent Patients
- Private Commercial Health Insurance and Out-of-Pocket / Public Healthcare Systems
- Prescription and Clinician-Supervised / Over-the-Counter and Consumer Self-Care
- Y-o-Y Growth Trend Analysis By Patient Demographic, Payment & Classification, 2021 to 2025
- Absolute $ Opportunity Analysis By Patient Demographic, Payment & Classification, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Active Drug Class
- By Route of Administration
- By Pain Indication
- By Distribution Channel
- By Patient Demographic, Payment & Classification
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Haleon plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kenvue Inc.
- Bayer AG
- Reckitt Benckiser Group plc
- Sanofi S.A. (Opella)
- Perrigo Company plc
- Taisho Pharmaceutical Holdings Co., Ltd.
- Dr. Reddy's Laboratories Ltd.
- Haleon plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Active Drug Class, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Pain Indication, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Patient Demographic, Payment & Classification, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Active Drug Class
- Figure 6: Global Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Route of Administration
- Figure 9: Global Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Pain Indication
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Active Drug Class
- Figure 32: North America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Route of Administration
- Figure 35: North America Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Pain Indication
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Active Drug Class
- Figure 48: Latin America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Route of Administration
- Figure 51: Latin America Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Pain Indication
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Active Drug Class
- Figure 64: Western Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Route of Administration
- Figure 67: Western Europe Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Pain Indication
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Active Drug Class
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Route of Administration
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Pain Indication
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Active Drug Class
- Figure 96: East Asia Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Route of Administration
- Figure 99: East Asia Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Pain Indication
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Active Drug Class
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Route of Administration
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Pain Indication
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Active Drug Class, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Active Drug Class, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Active Drug Class
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Route of Administration
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Pain Indication, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Pain Indication, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Pain Indication
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Patient Demographic, Payment & Classification, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Patient Demographic, Payment & Classification, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Patient Demographic, Payment & Classification
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the over-the-counter pain medication market in 2026, and what is forecast for 2036?
As per FMI, global over-the-counter pain medication market value will reach USD 25.7 billion during 2026 from a 2025 baseline of USD 24.7 billion before hitting USD 38.0 billion in 2036.
What is the CAGR for the over-the-counter pain medication market from 2026 to 2036?
Analysts at Future Market Insights forecast a 4.0% compound growth rate from 2026 to 2036, which adds an estimated USD 12.3 billion in incremental market size across pharmacy and online channels.
Which active drug class segment leads the over-the-counter pain medication market?
Non-steroidal anti-inflammatory drugs (ibuprofen and naproxen or diclofenac) are projected to capture 45.3% of active drug class demand in 2026 by targeting both prostaglandin pain pathways and peripheral inflammation.
Which route of administration segment leads the over-the-counter pain medication market?
Oral tablets and liquid-gels or effervescent powders are estimated to secure 82.5% of the route of administration category in 2026 through fast systemic bioavailability and low unit-dose cost.
Which country has a notable growth outlook during the assessment period?
Brazil tops national growth forecasts with a 4.9% CAGR until 2036 on consumer shifts toward solubilized ibuprofen softgels and expanding national drugstore chains.
Who are the key players in the market?
Haleon plc and Kenvue Inc. with Bayer AG and Reckitt Benckiser Group plc lead commercial supply across retail drugstores and supermarkets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
