
- Market Size (2026)
- USD 2.9 Bn
- Forecast (2036)
- USD 7.3 Bn
- CAGR (2026 to 2036)
- 9.8%
How big is Plant-Based Ice Cream Market in 2026?
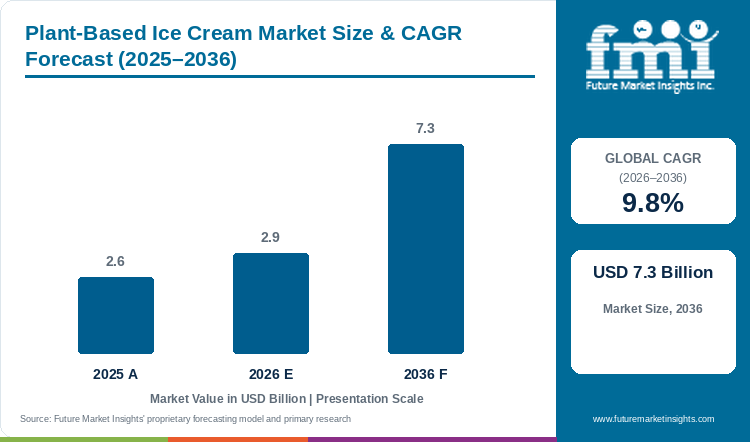
Sales in the plant-based ice cream market are projected to grow at 9.8% CAGR, with market valuation rising from USD 2.6 billion in 2025 to USD 2.9 billion in 2026 and reaching USD 7.3 billion by 2036.
According to Future Market Insights analysis, the global plant-based ice cream market stands at USD 2.6 billion in 2025 and rises to USD 2.9 billion in 2026. Industry valuation is projected to reach USD 7.3 billion by 2036, expanding at a 9.8% CAGR and generating USD 4.4 billion in added revenue. Demand expansion is no longer moving only through dairy avoidance, as food manufacturers reformulate frozen desserts to match conventional creaminess and eliminate off-flavors. In 2025, the Good Food Institute placed total U.S. plant-based retail sales at USD 7.9 billion, indicating established shopper familiarity with plant-based alternatives [1]. Blended plant bases lead the market with a 56.8% share in 2026, because combining fats from coconut and proteins from oat or cashew prevents icy crystallization during distribution. Growth across evaluated economies ranges from 5.0% in Germany to 8.5% in India, though cold-chain temperature fluctuations and price premiums over dairy continue to challenge household replenishment.
Key Market Trends & Insights
- By form: Blends are projected to account for 56.8% in 2026, supported by improved creaminess and reduced aftertaste.
- By product type: Cups and tubs are estimated to hold 41.9% in 2026, owing to shareable formats and household freezer stocking.
- By flavor: Nut flavors are expected to lead with 33.4% share in 2026, driven by premium taste cues and confectionery familiarity.
- By source: Coconut milk is forecast to represent 38.6% in 2026, underpinned by natural fat content and stable scoopability.
- By sales channel: Hypermarkets and supermarkets are likely to capture 46.2% in 2026, linked to freezer visibility and routine replenishment across commercial dairy-free frozen desserts categories.
Regional Highlights
- Fastest-growing country: India is projected to record a CAGR of 8.5% from 2026 to 2036.
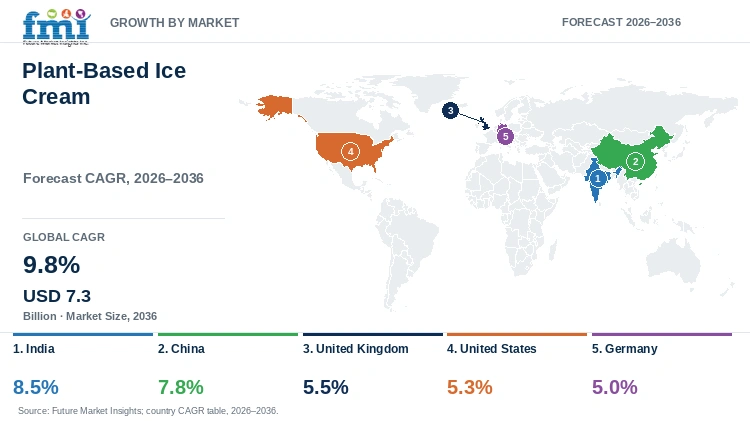
- By country: China follows at 7.8%, the United Kingdom at 5.5%, and the United States at 5.3%, while Germany records 5.0% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Plant-Based Ice Cream Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.6 billion |
| Estimated Market Size in 2026 | USD 2.9 billion |
| Projected Market Size by 2036 | USD 7.3 billion |
| CAGR, 2026 to 2036 | 9.8% |
| Added Revenue, 2026 to 2036 | USD 4.4 billion |
Household Freezer and Retail Throughput Sizing
Table 2: Demand and Channel Sizing Indicators for the Plant-Based Ice Cream Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.6 | 2.9 | 7.3 |
| Implied value per 1,000 people (USD) | 315.9 | 349.4 | 815.6 |
| Organized retail revenue (USD billion) | 1.2 | 1.3 | 3.4 |
| Cups and tubs revenue (USD billion) | 1.1 | 1.2 | 3.1 |
Per Capita and Segment Revenue Sizing
Plant-based ice cream is expanding beyond specialty health food outlets because modern formulations integrate into conventional dessert occasions. Blended recipes assist manufacturers in stabilizing fat emulsions, while growing non dairy ice cream selections secure prominent space in standard supermarket freezers. Commercial opportunity extends across flexitarian households, but sustained sales depend on whether products maintain texture through logistics and offer competitive shelf pricing.
Table 3: Per Capita Spending Indicators (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.32 | 0.35 | 0.82 |
| Spend per 1,000 people (USD) | 315.9 | 349.4 | 815.6 |
Table 4: Leading Segment Revenue Indicators, 2026
| Metric | Value | Basis |
|---|---|---|
| Blends revenue | USD 1.6 billion | 56.8% share |
| Cups and tubs revenue | USD 1.2 billion | 41.9% share |
| Nut flavors revenue | USD 1.0 billion | 33.4% share |
| Coconut milk revenue | USD 1.1 billion | 38.6% share |
| Hypermarkets and supermarkets revenue | USD 1.3 billion | 46.2% share |
Analyst Perspective
“Plant-based ice cream scales effectively when texture and price reach parity with established frozen desserts. Blended bases and dependable freezer placement will shape repeat household purchasing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Plant-Based Ice Cream Market segmented?
The plant-based ice cream market is segmented by form, product type, flavor, source, and sales channel. In 2026, blends lead at 56.8%, cups and tubs at 41.9%, nut flavors at 33.4%, coconut milk at 38.6%, and hypermarkets and supermarkets at 46.2%.
- By form: Singles and blends.
- By product type: Bars, cones, cups / tubs, and others.
- By flavor: Fruits, nuts, herbs, and beans.
- By source: Soy milk, coconut milk, almond milk, cashew milk, and others.
- By sales channel: Direct sales and indirect sales, including hypermarkets / supermarkets, franchise outlets, online, and others.
Why do Blends lead the form category?
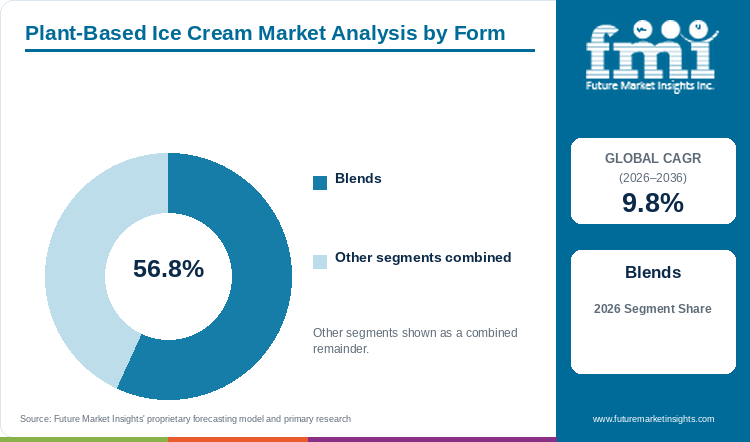
Blends represent 56.8% of form demand in 2026, balancing creamy mouthfeel with controlled melt performance.
Table 5: Form Share for the Plant-Based Ice Cream Market (percentage share), 2026
| Form | Share (2026) |
|---|---|
| Blends | 56.8% |
| Other Segments Combined | 43.2%* |
| Total | 100.0% |
*Calculated as the balance after deducting the leading segment share from 100.0%.
Table 6: Form Leadership and Market Growth for the Plant-Based Ice Cream Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.8% |
| Leading Segment | Blends |
Blends command 56.8% of form demand because relying on a single plant source frequently leaves technical defects in finished ice cream. Pure coconut creates necessary fat solid content but imparts strong tropical flavor notes, whereas oat, soy, or cashew bases yield neutral profiles but lack melting resistance. Processors overcome these limitations by blending complementary bases alongside fortified plant-based milk proteins. This formulation approach ensures stable overrun and smooth mouthfeel, enabling products to withstand commercial freezer display cases.
- Blended plant bases are projected to account for 56.8% of form revenue in 2026, supported by improved emulsification and reduced aftertaste.
- Food formulators combine coconut fat with oat and cashew proteins to stabilize air cells during commercial freezing cycles.
What keeps Cups and Tubs ahead by product type?
Cups and tubs hold 41.9% of product type demand in 2026, supported by shared household dessert occasions.
Cups and tubs account for 41.9% of product type demand because multi-serve containers serve primary family dining and planned dessert occasions. Rigid paperboard tubs provide ample volume for complex confectionery swirls, fruit ribbons, and baked inclusions that justify premium retail price positioning. Supermarket procurement teams favor tub inventory because it generates predictable weekly volume across standard frozen desserts fixtures. However, higher retail carton pricing can cause purchase hesitation during initial consumer trials.
- Cups and tubs are estimated to represent 41.9% of product type sales in 2026, driven by family dessert consumption and multi-serve value.
- Commercial tub formats facilitate layered confectionery swirls and nut inclusions that enhance premium visual appeal.
Why do Nut Flavors define the largest flavor segment?
Nut flavors account for 33.4% of flavor demand in 2026, combining familiar confectionery cues with dairy-free indulgence.
Nut flavors capture 33.4% of total flavor demand as roasted pistachio, hazelnut, pecan, and almond profiles provide rich confectionery cues that mask underlying plant proteins. The natural lipid profile of nut pastes complements non-dairy fat systems, yielding dense textures reminiscent of traditional gelato. In addition, nut profiles blend seamlessly with cocoa and caramel notes in vegan confectionery offerings. Higher raw ingredient costs and allergen labeling regulations remain primary commercial friction points for mass-market adoption.
- Nut flavors are projected to capture 33.4% of flavor sales in 2026, reflecting consumer preference for pistachio, hazelnut, and almond profiles.
- Pairing roasted nut pastes with dairy alternatives masks vegetal notes while delivering authentic dessert richness.
How does Coconut Milk maintain source leadership?
Coconut milk captures 38.6% of source demand in 2026, underpinned by natural fat and stable scoopability.
Coconut milk leads the source category with 38.6% share because its high saturated fat content mimics the crystallization behavior of dairy butterfat. Saturated medium-chain triglycerides provide structural body, allowing manufacturers to achieve smooth scoopability without excessive hydrocolloids. Sourcing coconut milk products remains standard practice, though formulators increasingly incorporate neutral almond milk streams when addressing consumers who dislike residual coconut flavor notes.
- Coconut milk is forecast to contribute 38.6% of source revenue in 2026, owing to high medium-chain triglyceride content that mimics dairy fat.
- Natural saturated fat structures in coconut cream provide structural firmness and delay melting during ambient serving.
What gives Hypermarkets and Supermarkets leadership in sales channels?
Hypermarkets and supermarkets represent 46.2% of sales in 2026, driven by freezer visibility and routine household replenishment.
Hypermarkets and supermarkets generate 46.2% of category turnover because ice cream purchasing is closely integrated with weekly grocery replenishment. Mainstream supermarkets provide the cold-storage infrastructure and multi-deck freezer displays necessary to sustain product integrity across commercial packaged food aisles. Placing plant-based pints adjacent to conventional dairy ice cream accelerates flexitarian trial, although grocery buyers monitor sales velocity per foot closely before renewing seasonal freezer space agreements.
- Hypermarkets and supermarkets are set to command 46.2% of sales channel revenue in 2026, reinforced by organized cold storage and promotional reach.
- Strategic placement in main frozen dessert aisles rather than isolated vegan sections significantly increases impulse purchasing.
What are the drivers, restraints, and opportunities in the Plant-Based Ice Cream Market?
Wider dairy-free acceptance lifts household trial, while price and texture gaps limit repeat purchases, and formulation improvements create premium value.
- Driver: Greater acceptance of dairy-free and lactose-free desserts expands the addressable household base.
- Restraint: Price premiums and sensory inconsistency weaken repeat purchasing against established dairy ice cream.
- Opportunity: Blended bases and clean-label stabilizer systems can improve creaminess without diluting indulgence cues.
Growth Analysis and Future Potential: Mainstream Dessert Adoption
Plant-based ice cream is transitioning from specialist dietary niches into routine household dessert carts. The USD 7.9 billion retail baseline for U.S. plant-based foods in 2025 demonstrates broad consumer willingness to integrate alternative products into regular meal patterns. However, dessert categories face rigorous sensory scrutiny because consumers treat ice cream as an indulgence rather than a functional staple. FMI data suggests that cups and tubs successfully secure repeat orders when mouthfeel replicates dairy custard without waxy mouth-coating. Maintaining cold-chain continuity from regional distribution centers to retail displays remains essential to avoid ice crystal formation.
Risk Assessment of the Plant-Based Ice Cream Market: Formulation and Cost Friction
Temperature cycling during transit represents the primary operational hazard for non-dairy frozen desserts. Without dairy milk solids, plant emulsions undergo rapid phase separation when exposed to ambient temperature spikes, causing syneresis and gritty texture. Commercial formulators incorporate specialized food stabilizer systems to stabilize water migration. However, adding functional hydrocolloids conflicts with consumer demand for short ingredient statements, while volatile commodity costs for nuts and coconut fats increase finished product prices relative to subsidized dairy inputs.
Commercial Opportunity Analysis: Blended Bases and Premium Formats
Engineering multi-source plant matrices presents a high-margin commercial runway for frozen dessert manufacturers. Blending coconut cream with enzymatic oat pastes or fermented cashew purees enables processors to balance viscosity, freeze point depression, and melting rates without artificial gums. Sourcing certified clean label ingredients enables brands to position pints at premium price tiers. In addition, introducing portion-controlled handheld novelty bars and premium pints creates lucrative brand trial opportunities across convenience and quick-commerce retail channels.
Plant-Based Ice Cream Market by Country (2026 to 2036)
As noted by FMI, India is projected to expand at the highest rate among evaluated markets, recording an 8.5% CAGR from 2026 to 2036, while Germany records 5.0%. Across covered regional markets, commercial success depends on cold-chain infrastructure, localized flavor profiles, and pricing strategies that align with household dessert budgets.
Table 7: Country CAGR and Primary Growth Levers for the Plant-Based Ice Cream Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 8.5% | Modern retail growth and localized dairy-free flavors |
| China | 7.8% | Urban premiumization and digital grocery access |
| United Kingdom | 5.5% | Mainstream vegan assortments and retailer private labels |
| United States | 5.3% | Mature alternative dairy distribution and premium innovation |
| Germany | 5.0% | Established plant-based consumption and clean-label demand |
Source: Future Market Insights analysis
India Plant-Based Ice Cream Market Outlook (2026 to 2036)
India is projected to record an 8.5% CAGR through 2036, leading all evaluated markets as quick-commerce platforms and modern retail chains expand rapid refrigerated delivery across Tier-1 metropolitan centers. Tropical climatic conditions sustain year-round frozen dessert demand, while regional formulations featuring mango, pistachio, and saffron integrate seamlessly with traditional dessert expectations. However, cold-chain fragmentation outside major cities and stark price differences against traditional dairy ice cream restrict mass distribution. Processors overcome these barriers by introducing single-serve cups and leveraging regional coconut supply chains to maintain competitive unit pricing.
Key takeaway: In India, quick-commerce delivery expansion and localized flavor adaptation drive rapid urban market penetration.
China Plant-Based Ice Cream Market Outlook (2026 to 2036)
China is forecast to expand at a 7.8% CAGR through 2036, supported by high adult lactose sensitivity and strong consumer interest in novel culinary experiences. Urban consumers in Shanghai, Beijing, and Guangzhou embrace plant-based pints as premium lifestyle items rather than medical dietary substitutes. E-commerce platforms and temperature-controlled cold delivery networks allow specialized brands to scale without expensive traditional supermarket slotting agreements. Growth will remain contingent on deploying light, neutral-tasting plant bases that align with regional palate preferences for lower sweetness and delicate tea or floral infusions.
Key takeaway: In China, digital grocery fulfillment and premium novelty positioning create substantial growth runway in Tier-1 cities.
United Kingdom Plant-Based Ice Cream Market Outlook (2026 to 2036)
The United Kingdom is expected to rise at a 5.5% CAGR through 2036, reflecting an established market where plant-based foods form a permanent component of supermarket retail assortments. In 2025, the National Diet and Nutrition Survey highlighted shifting domestic consumer dietary preferences toward reduced dairy consumption [3]. Consequently, major supermarket chains allocate dedicated freezer shelf space to plant-based private label and branded tubs. Price competition from store brands exerts margin pressure on independent manufacturers, forcing premium brands to differentiate through certified organic credentials, traceable single-origin nuts, and sustainable paperboard packaging.
Key takeaway: In the UK, high supermarket private label penetration makes texture parity and cost discipline essential for commercial survival.
United States Plant-Based Ice Cream Market Outlook (2026 to 2036)
The United States is projected to register a 5.3% CAGR over the assessment period, representing a mature alternative dairy environment where growth requires capturing mainstream flexitarian dessert occasions. Widespread distribution across national retail banners ensures strong consumer awareness, but brand crowdedness and substantial distributor slotting fees limit retail expansion for smaller entrants. Commercial success favors established dessert manufacturers that leverage multi-serve tub promotions and innovative handheld novelties, proving consistent weekly inventory turnover to preserve vital supermarket freezer facings.
Key takeaway: In the USA, brand consolidation and high freezer slotting expenses require suppliers to drive steady inventory velocity.
Germany Plant-Based Ice Cream Market Outlook (2026 to 2036)
Germany is anticipated to expand at a 5.0% CAGR through 2036, anchored by deep ethical vegan demographics and strong environmental consumer awareness. In May 2025, the Federal Statistical Office (Destatis) reported sustained domestic manufacturing volumes across plant-based food and dairy alternatives [4]. German shoppers scrutinize ingredient declarations rigorously, rejecting formulations reliant on artificial emulsifiers, synthetic flavor enhancers, or excessive saturated fats. Brand success in discount retail chains requires clean-label oat and lupin formulation architectures delivered at accessible price points.
Key takeaway: In Germany, strict clean-label scrutiny and hard discount retail dominance mandate transparent ingredient decks and cost discipline.
Full report country coverage includes North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Plant-Based Ice Cream Market?
Unilever, Nestle, Danone, General Mills, Oatly AB, Froneri International, Eclipse Foods, and Tofutti Brands are notable companies operating in this market.
In the FMI report, competition across the plant-based ice cream landscape combines global frozen dessert conglomerates, specialized alternative-dairy corporations, and agile food-tech startups. Global corporations leverage extensive cold-chain logistics networks, established retail partnerships, and recognizable dessert branding. Meanwhile, specialized producers differentiate through proprietary fat-protein blending technologies, organic certifications, and allergen-free processing protocols.
- Global frozen-dessert platforms: The Magnum Ice Cream Company, Nestle, Froneri International, and General Mills.
- Dairy-alternative platforms: Danone and Oatly AB.
- Specialist plant-based brands: Eclipse Foods and Tofutti Brands.
Competitive Benchmarking: Plant-Based Ice Cream Market
Table 8: Competitive Benchmarking for the Plant-Based Ice Cream Market, 2026
| Company | Plant-Based Breadth | Flavor Innovation | Retail Access | Geographic Reach |
|---|---|---|---|---|
| The Magnum Ice Cream Company | High | High | High | High |
| Nestle | High | High | High | High |
| Danone | High | High | High | High |
| General Mills | Medium | High | High | Medium |
| Oatly AB | Medium | High | High | Medium |
| Froneri International | Medium | High | High | Medium |
| Eclipse Foods | Medium | Medium | Medium | Low |
| Tofutti Brands | Medium | Medium | Medium | Low |
Key Developments in the Plant-Based Ice Cream Market
- In December 2025, Oatly announced a partnership with Carvel to introduce oatmilk-based non-dairy frozen desserts, including strawberry soft serve, cookies and cream, and chocolate peanut butter varieties, across approximately 300 Carvel locations in 18 states across the United States.
Key Players in the Plant-Based Ice Cream Market
Global Frozen-Dessert Platforms
- Unilever
- Nestle
- Froneri International
- General Mills
Dairy-Alternative Platforms
- Danone
- Oatly AB
Specialist Plant-Based Brands
- Eclipse Foods
- Tofutti Brands
Plant-Based Ice Cream Market - Report Scope
Table 9: Report Scope for the Plant-Based Ice Cream Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; Product Type; Flavor; Source; Sales Channel; Region |
| Quantitative units | USD Billion |
| Market definition | Supplier revenue from dairy-free frozen desserts formulated primarily with plant-derived bases. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries with published CAGR | India; China; United Kingdom; United States; Germany |
| Key companies covered | Unilever; Nestle; Danone; General Mills; Oatly AB; Froneri International; Eclipse Foods; Tofutti Brands |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Plant-Based Ice Cream Market - Research Methodology
Table 10: Research Methodology for the Plant-Based Ice Cream Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with manufacturers, ingredient suppliers, distributors, retailers, foodservice buyers, and industry experts validate demand dynamics and purchasing decisions. |
| Secondary Research | Company reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public sources are assessed. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess revenue, segment mix, price points, and adoption from 2026 to 2036. |
| Data Triangulation and Validation | Results are checked against macro-economic indicators, consumer demand signals, regulatory conditions, and historical trends to limit double counting. |
Plant-Based Ice Cream Market by Segments
Plant-Based Ice Cream Market segmented by Form:
- Singles
- Blends
Plant-Based Ice Cream Market segmented by Product Type:
- Bars
- Cones
- Cups / Tubs
- Others
Plant-Based Ice Cream Market segmented by Flavor:
- Fruits
- Nuts
- Herbs
- Beans
Plant-Based Ice Cream Market segmented by Source:
- Soy Milk
- Coconut Milk
- Almond Milk
- Cashew Milk
- Others
Plant-Based Ice Cream Market segmented by Sales Channel:
- Direct Sales
- Indirect Sales
- Hypermarkets / Supermarkets
- Franchise Outlets
- Online
- Others
Plant-Based Ice Cream Market by Region
- North America: United States, Canada, Mexico
- Latin America: Brazil, Chile, Rest of Latin America
- Western Europe: Germany, UK, Italy, Spain, France, Nordics, BENELUX
- Eastern Europe: Poland, Hungary, Balkans and Baltics, Rest of Eastern Europe
- East Asia: China, Japan, South Korea
- South Asia and Pacific: India, ASEAN, Australia and New Zealand
- Middle East and Africa: GCC Countries, South Africa, Turkiye, Israel, Rest of MEA
Research Sources and Bibliography
- [1] The Good Food Institute. (2026). Plant-based retail market overview: U.S. retail sales data for 2025.
- [2] The Good Food Institute Europe. (2026, June 9). European plant-based retail sales data for 2025.
- [3] Office for Health Improvement and Disparities. (2025, June 11). National Diet and Nutrition Survey 2019 to 2023.
- [4] Federal Statistical Office (Destatis). (2025, May 7). Production of meat and dairy alternatives in Germany: 2024 statistical review.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the plant-based ice cream market in 2026 and what is forecast for 2036?
- Which formulation and retail pressures support demand?
- Why do blended plant bases lead the form category?
- Why do cups and tubs lead product type demand?
- How do published country growth rates differ?
- Which companies maintain visible plant-based frozen-dessert portfolios?
- What limits repeat purchase and retailer acceptance?
- What should buyers evaluate before selecting a supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Singles
- Blends
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Bars
- Cones
- Cups / Tubs
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor, 2026 to 2036
- Fruits
- Nuts
- Herbs
- Beans
- Y-o-Y Growth Trend Analysis By Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Soy Milk
- Coconut Milk
- Almond Milk
- Cashew Milk
- Others
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct Sales
- Indirect Sales
- Hypermarkets / Supermarkets
- Franchise Outlets
- Online
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordics
- BENELUX
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Hungary
- Balkans and Baltics
- Rest of Eastern Europe
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- Rest of MEA
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Product Type
- By Flavor
- By Source
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Unilever
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle
- Danone
- General Mills
- Oatly AB
- Froneri International
- Eclipse Foods
- Tofutti Brands
- Unilever
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Flavor, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form
- Figure 6: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Type
- Figure 9: Global Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Flavor
- Figure 12: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Source
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Form
- Figure 32: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Product Type
- Figure 35: North America Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Flavor
- Figure 38: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Source
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Form
- Figure 48: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Product Type
- Figure 51: Latin America Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Flavor
- Figure 54: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Source
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Form
- Figure 64: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Product Type
- Figure 67: Western Europe Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Flavor
- Figure 70: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Source
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Form
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Flavor
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Source
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Form
- Figure 96: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Product Type
- Figure 99: East Asia Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Flavor
- Figure 102: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Source
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Flavor
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Flavor
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the plant-based ice cream market in 2026, and what is forecast for 2036?
Future Market Insights estimates the market will reach USD 2.9 billion in 2026. The market is projected to expand further and reach USD 7.3 billion by 2036.
What is the CAGR forecast for the plant-based ice cream market from 2026 to 2036?
As per FMI, the plant-based ice cream market is projected to grow at a 9.8% CAGR from 2026 to 2036. Growth is supported by formulation advances in blended plant bases and wider distribution across supermarket freezers.
Which form segment leads the plant-based ice cream market in 2026?
Blended plant bases lead the form category with a 56.8% market share in 2026. The segment benefits from combining complementary fats and proteins to replicate traditional custard creaminess.
Which source segment holds the largest share of market demand?
Coconut milk captures the leading position with a 38.6% share of source demand in 2026. Saturated plant lipids in coconut cream provide structural firmness and stable overrun.
Which country has the fastest growth outlook during the assessment period?
India is projected to expand at an 8.5% CAGR between 2026 and 2036. High growth is driven by expanding modern retail, quick-commerce cold-chain expansion, and urban flexitarian trial.
Who are the prominent companies active in the plant-based ice cream market?
Notable market participants include Unilever, Nestle, Danone, General Mills, Oatly AB, Froneri International, Eclipse Foods, and Tofutti Brands. Manufacturers focus on flavor innovation, cold-chain stability, and grocery distribution expansion.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
