
- Market Size (2026)
- USD 103.5 Bn
- Forecast (2036)
- USD 165.4 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Pouch Market in 2026?
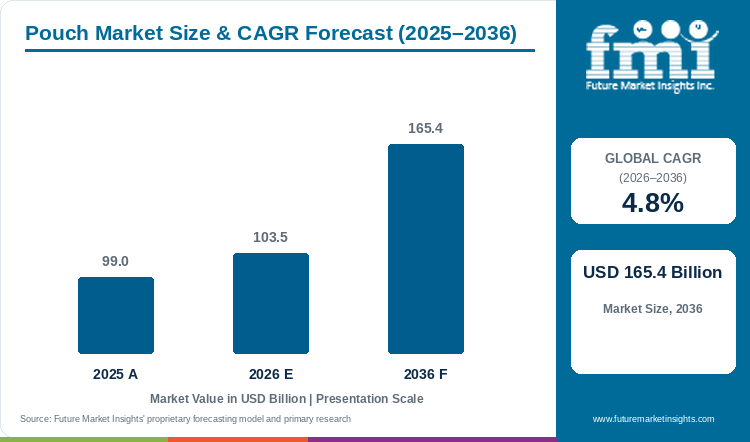
The pouch market establishes its foundation at USD 99.0 billion in 2025, advances to USD 103.5 billion in 2026, and is forecast to scale to USD 165.4 billion by 2036 at a CAGR of 4.8%.
Industry valuation across the global pouch market rose from USD 99.0 billion in 2025 to an estimated USD 103.5 billion in 2026, while ten-year projections point to USD 165.4 billion by 2036 at a 4.8% CAGR. Food, pet care, and household cleaning brands are shifting filling lines from rigid bottles and metal cans into flexible pouches because lightweight film laminates lower unit packaging costs and cut outbound truck freight weight. In September 2026, packaging researchers publishing in Foods analyzed 57 grocery food categories and showed that shifting away from flexible plastic packaging significantly increases consumer food prices per pound [1]. Recent FMI assessment indicates that stand-Up Pouches with Bottom Gusset account for 35.5% of 2026 volume as retailers favor upright packs, while overall web and bag converting grows in parallel with pre-made pouch packaging demand at a 6.4% CAGR. Suppliers are launching commercial dispensing pouches to capture foodservice demand, and in September 2026 Sealed Air Corporation introduced its CRYOVAC ZeroPrep condiment pouch delivering up to 97% product yield without squeeze bottles [2]. However, strict extended producer responsibility fees on non-recyclable aluminum laminates restrain multi-material pouch growth and force converters to qualify mono-polyolefin films.
Key Market Trends & Insights
- By pouch structure: Stand-Up Pouches with Bottom Gusset hold an estimated 35.5% share in 2026 because W-fold and K-seal bottom gussets expand to stand upright on retail shelves.
- By barrier material: Multi-Layer Polyolefin Plastic Laminate represents 47.6% in 2026 as oriented polyethylene and polypropylene films with EVOH tie layers pass store-drop and curbside recycling audits.
- By closure system: Press-to-Close Resealable Zipper accounts for 51.3% in 2026 because multi-serve dry foods, grated cheese, and pet treats require hermetic reclosure between household uses.
- By end-use sector: Food and Beverage Processing secures 46.7% in 2026 owing to high-speed form-fill-seal adoption across coffee and sauces, baby food, frozen produce and dry snacks.
- By distribution channel: Direct Converter-to-Brand Contracts command 63.4% in 2026 through multi-year rotogravure and flexo rollstock and pre-made pouch supply agreements.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at a 5.9% CAGR through 2036 under expanding beverage, sauce, and export food pouch filling capacity.
- Broader country progression: Poland tracks at a 5.4% CAGR ahead of the United States at 4.9% and Canada at 4.8%, whereas Germany records a 4.6% CAGR and Italy advances at a 4.1% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Pouch Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 99.0 billion |
| Estimated Market Size in 2026 | USD 103.5 billion |
| Projected Market Size by 2036 | USD 165.4 billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Valuation, 2026 to 2036 | USD 61.9 billion |
Higher extended producer responsibility fees on mixed-plastic and aluminum laminates are driving food and beverage brands to adopt recyclable paper-based and mono-polyolefin stand-up pouches. Brand owners want flexible bags that protect dry coffee, snacks, and powdered foods against humidity without paying municipal waste penalties for unrecyclable multi-layer plastics. In May 2026, packaging engineers reporting in Polymers demonstrated that a hybrid paper and co-extruded polyethylene-EVOH stand-up pouch cut oxygen transmission from 35.38 to 0.56 cubic centimeters per square meter per day while reducing plastic weight by 37% [3]. Consequently, grocery brands sourcing stand-up paper pouches steadily select barrier-coated paper and mono-material webs that run on existing filling machines.
Converted Pouch Volume and Film Web Tonnage Sizing
Table 2: Converted Pouch Volume and Film Web Sizing for the Pouch Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 99.0 | 103.5 | 165.4 |
| Global finished pouch volume (billion units) | 1,120.0 to 1,210.0 | 1,170.0 to 1,265.0 | 1,810.0 to 1,960.0 |
| Converted flexible barrier film & paper input (million metric tons) | 18.4 to 20.1 | 19.2 to 21.0 | 29.5 to 32.4 |
| Mean realized converter price per 1,000 pouches (USD) | 81.5 to 88.4 | 82.0 to 89.0 | 84.5 to 91.5 |
Operational note: Unit volume and tonnage ranges cover 3-gram single-serve sachets, 12-gram stand-up food pouches, and 38-gram 2-liter spouted home-care refill bags across rollstock and pre-made converting lines.
Regulatory mandates requiring recycled plastic content and full recyclability in food packaging are pushing flexible converters to replace polyester-polyethylene laminates with all-polyolefin pouch structures. When a pouch combines a polyester outer print film with a polyethylene inner sealant, mechanical recyclers cannot melt the two plastics together cleanly. In February 2026, researchers at Nofima in Norway publishing in the Journal of Food Science outlined how mono-material polyolefin packaging designs help food brands meet EU targets requiring 10% to 30% recycled content by 2030 [4]. Converters producing mono-material barrier pouches therefore pair oriented polyethylene print webs with low-temperature polyethylene sealants so the entire bag recycles in a single stream.
Per Capita & Filling Line Allocation
Table 3: Per Capita and Filling Line Allocation Indicators for the Pouch Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 12,073.2 | 12,469.9 | 18,377.8 |
| Annual pouch laminate procurement per filling line (USD thousand) | 610.0 to 680.0 | 635.0 to 710.0 | 940.0 to 1,050.0 |
| Recycle-ready mono-material and bio-based pouch share (%) | 36.0% to 40.0% | 39.0% to 43.0% | 64.0% to 69.0% |
Table 4: Filling Plant & Channel Indicators for the Pouch Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 103.5 billion | 2026 global valuation baseline |
| Active commercial HFFS, VFFS & pre-made pouch lines global | 154,000 lines | Food, beverage, pet food, personal care & home-care fillers |
| Mean pouch material allocation per filling line | USD 672,077.9 | Annualized printed rollstock and pre-made pouch allocation |
| Direct Converter-to-Brand Contracts value, 2026 | USD 65.6 billion | 63.4% distribution channel allocation |
Wider household and retail collection of flexible plastic bags requires new polymer additives that allow recycled pouch films to retain tear strength and clarity when reprocessed. Without chemical compatibilizers, trace polyester or barrier resin in post-consumer pouch bales causes brittle weak spots in blown recycled film. In February 2026, chemists at Cornell University reporting in the JACS showed that adding 0.5% to 1.0% C-H functionalized polyolefin compatibilizers restored stretch and toughness in recycled plastic blends [5]. Film extruders supplying recyclable polyethylene pouches use these compatibilizer advances to incorporate higher post-consumer recycled resin into commercial retail pouches.
Analyst Perspective
"Brand owners do not switch from rigid bottles or cans to flexible pouches simply to save resin weight because they switch when a pouch runs at 150 packs per minute without seal leakers and passes retailer recyclability scorecards. Converters that pair high-barrier mono-material polyolefin or paper laminates with pre-applied spouts and zippers will capture multi-year national brand contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the pouch market segmented?
The pouch market is segmented by pouch structure, barrier material, closure system, end-use sector, and distribution channel. In 2026, Stand-Up Pouches with Bottom Gusset is projected at 35.5%, Multi-Layer Polyolefin Plastic Laminate at 47.6%, Press-to-Close Resealable Zipper at 51.3%, Food and Beverage Processing at 46.7%, and Direct Converter-to-Brand Contracts at 63.4%.
By pouch structure: Stand-Up Pouches with Bottom Gusset, Flat Three-Side Seal Pouches, Spouted Pouches for Liquids and Retort Thermal Processing Pouches.
By barrier material: Multi-Layer Polyolefin Plastic Laminate, Aluminum Foil High-Barrier Laminate, and Bio-Based Compostable Polymer.
By closure system: Press-to-Close Resealable Zipper, Tamper-Evident Pouring Spout, and Tear Notch Heat-Sealed.
By end-use sector: Food and Beverage Processing, Pet Care and Animal Food, Personal Care and Liquid Soap and Household Chemical Cleaners.
By distribution channel: Direct Converter-to-Brand Contracts, Contract Co-Packing and Filling Networks, and Wholesale Stock Pouch Distributors.
Why do Stand-Up Pouches with Bottom Gusset lead the pouch structure category?
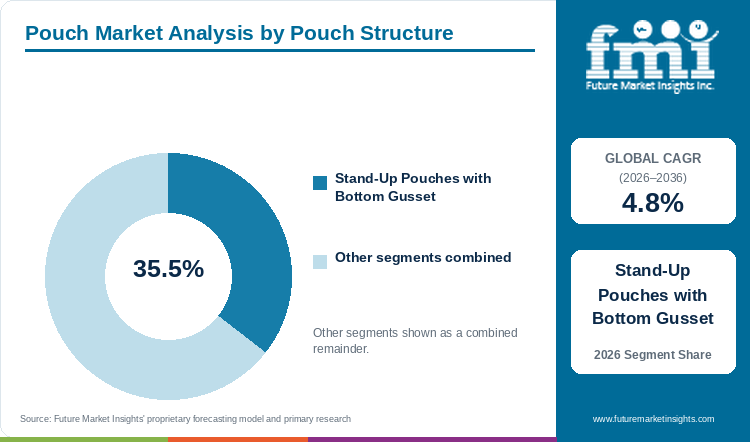
Stand-Up Pouches with Bottom Gusset hold an estimated 35.5% of pouch structure demand in 2026, anchored by upright retail shelf presence and 75% inbound freight reduction versus rigid jars.
Table 5: Pouch Structure Share for the Pouch Market (percentage share), 2026
| Pouch Structure | Share (2026) |
|---|---|
| Stand-Up Pouches with Bottom Gusset | 35.5% |
| Other Segments Combined | 64.5%* |
| Total | 100.0% |
*Note: Remaining pouch structure categories (Flat Three-Side Seal Pouches at 26.8%, Spouted Pouches for Liquids at 21.4%, and Retort Thermal Processing Pouches at 16.3%) account for the balance of 2026 global pouch demand.
Table 6: Pouch Structure Leadership and Market Growth for the Pouch Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Stand-Up Pouches with Bottom Gusset |
Retailer preference for upright front-panel branding and warehouse freight savings keeps Stand-Up Pouches with Bottom Gusset at the top of the pouch structure category. When filled on horizontal or vertical form-fill-seal lines, the bottom gusset flattens into a stable base that stands unsupported on grocery shelves, whereas unfilled pouch reels take up 85% less warehouse space than rigid plastic tubs. Flat Three-Side Seal Pouches hold 26.8% of 2026 demand for single-serve condiments and medical wipes, Spouted Pouches for Liquids capture 21.4% for baby food and soap refills, and Retort Thermal Processing Pouches represent 16.3%. Home-care and beverage brands ordering spouted liquid pouches combine bottom gussets with corner spouts for easy household pouring.
- Stand-Up Pouches with Bottom Gusset hold 35.5% of pouch structure value in 2026 because upright front-panel billboards maximize retail shelf impact per linear foot.
- In July 2025, Amcor plc and Mediacor launched a 2-liter AmPrima mono-PE spouted stand-up refill pouch for Nana liquid laundry and cleaning products that cuts carbon footprint compared to rigid bottles [6].
What sustains Multi-Layer Polyolefin Plastic Laminate leadership in barrier material?
Multi-Layer Polyolefin Plastic Laminate represents 47.6% of the barrier material category in 2026, supported by mono-PE and mono-PP recyclability compliance.
Supermarket recyclability scorecards and lower extended producer responsibility fees explain why Multi-Layer Polyolefin Plastic Laminate leads the barrier material segment. By laminating biaxially oriented polyethylene or polypropylene outer films to thin EVOH barrier layers and polyethylene sealants, converters keep polyolefin content above 95% so the pouch passes RecyClass and store-drop recycling audits. Aluminum Foil High-Barrier Laminate accounts for 33.2% of 2026 demand in retort ready meals and instant coffee requiring total light and oxygen block, while Bio-Based Compostable Polymer holds 19.2%. Food packers comparing foil pouch packaging against polyolefin laminates steadily switch dry and chilled SKUs into recyclable polyolefin structures.
- Multi-Layer Polyolefin Plastic Laminate represents 47.6% of the barrier material segment in 2026 as European and United States and Canada retailers enforce mono-material recyclability grades.
- In November 2025, food engineers at Ege University reporting in Foods measured accelerated shelf-life stability across PET/Al-foil/LDPE (800.32 days), AlOx-coated PET/LDPE (577.92 days) and metallized BOPP pouches [7].
How does Press-to-Close Resealable Zipper lead the closure system category?
Press-to-Close Resealable Zipper accounts for 51.3% of closure system demand in 2026, driven by household portion control and multi-serve freshness retention.
Consumer demand for portion control and multi-week product freshness without transferring food into kitchen canisters drives the leadership of Press-to-Close Resealable Zipper closures. Extruded polyethylene flange and slider zippers add less than one cent per bag while allowing shoppers to reclose shredded cheese, roasted nuts, dry pet food and protein powders repeatedly. Tamper-Evident Pouring Spout closures account for 27.4% of 2026 demand in liquid refills and fruit purees, while Tear Notch Heat-Sealed bags hold 21.3% for single-serve packs. Converters manufacturing stand-up zipper pouches ultrasonically seal zipper ends into the side gussets to prevent air leaks.
- Press-to-Close Resealable Zipper accounts for 51.3% of closure system demand in 2026 because inline flange-zipper insertion adds less than USD 0.008 per pouch while preventing household food staling.
- In August 2026, Amcor plc won two Institute of Packaging Professionals AmeriStar Awards for its AmPrima recycle-ready refill pouch and its reclosable healthcare pouch [8].
Why does Food and Beverage Processing lead the end-use sector category?
Food and Beverage Processing secures 46.7% of end-use sector value in 2026, supported by high-speed form-fill-seal packaging across dry groceries, frozen foods, and liquid beverages.
High daily consumption of packaged groceries and fast-growing adoption of single-serve wet pet food pouches make Food and Beverage Processing the largest end-use sector. Coffee roasters, sauce makers, dairy processors and frozen food packers rely on flexible pouches to lock in aroma and moisture while shipping more units per pallet to supermarket distribution centers. Pet Care and Animal Food accounts for 22.5% of 2026 demand, Personal Care and Liquid Soap holds 17.2%, and Household Chemical Cleaners represent 13.6%. Pet nutrition brands adopting retortable mono-material pouches replace steel cans with polypropylene retort bags that cook faster in factory autoclaves.
- Food and Beverage Processing secures 46.7% of end-use sector demand in 2026 because flexible pouches extend ambient and chilled shelf life while cutting grocery transport weight.
- In October 2026, Amcor plc published a survey of 2,457 European wet pet food buyers showing that convenient single-serve portioning and recyclability strongly influence pouch purchasing [9].
What gives Direct Converter-to-Brand Contracts the lead in distribution channel?
Direct Converter-to-Brand Contracts command 63.4% of distribution channel share in 2026, anchored by custom 10-color rotogravure printing and food-contact migration compliance.
Brand requirements for custom high-barrier film formulations, multi-color rotogravure printing, and food-contact safety guarantees keep Direct Converter-to-Brand Contracts as the leading distribution channel. National food and home-care companies sign multi-year rollstock and pre-made pouch contracts directly with major converters to lock in resin pass-through pricing and multi-plant backup supply. Contract Co-Packing and Filling Networks hold 24.8% of 2026 demand by bundling pouch sourcing with retort or liquid filling, while Wholesale Stock Pouch Distributors represent 11.8% for smaller coffee and snack brands. Direct converter partnerships also speed up filling-line qualification when switching to mono-material films.
- Direct Converter-to-Brand Contracts command 63.4% of distribution channel value in 2026 because national brands require audited food-safety certification and guaranteed coefficient-of-friction tolerances on high-speed fillers.
- In September 2026, Mondi Group plc highlighted its mono-material re/cycle FlexiBag and FunctionalBarrier Paper pouch range for brand qualification at PACK EXPO International 2026 [10].
What are the drivers, restraints, and opportunities in the pouch market?
In the pouch market, rigid-to-flexible freight and resin savings alongside household refill convenience are projected to drive adoption whereas multi-layer recycling sorting challenges and solvent-retention curing times restrain uncalibrated laminates and high-barrier paper and active biopolymer pouches unlock circular food packaging.
- Driver: Switching from rigid glass jars, metal cans, and plastic bottles to stand-up and spouted pouches cuts package weight by 75% and lowers freight costs.
- Restraint: Multi-layer aluminum and mixed-plastic pouches face rising extended producer responsibility waste fees and complex recycling separation hurdles.
- Opportunity: High-barrier paper pouches and active antimicrobial bio-films open plastic-tax exemptions and extend fresh food shelf life.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Retailer shelf-space economics and corporate targets to cut plastic bottle weight are driving consumer brands to shift liquid soaps, detergents, sauces and pet foods into flexible pouches. A 1.5-liter spouted refill pouch uses roughly 75% to 80% less plastic resin than a rigid high-density polyethylene pump bottle and ships flat in roll form before filling, taking nine out of ten empty-container delivery trucks off the road. Brands purchasing animal feed pouches and home-care refills steadily specify mono-polyethylene structures that qualify for curbside and store-drop recycling. In September 2026, Huhtamaki Oyj detailed how its mono-material flexible packaging structures with over 90% single-polymer content increase recycling yield purity under EU circularity rules [11].
Risk Assessment of the Pouch Market: Recycling Separation and Delamination Friction
Difficulty separating bonded aluminum foil, polyester, and polyethylene layers in municipal sorting plants remains the primary restraint limiting conventional multi-layer pouch growth. When unrecyclable trilaminate pouches enter paper hydropulpers or mechanical plastic recyclers, the mixed layers cause high fiber reject losses and trigger punitive eco-modulated waste fees across Europe. In August 2025, chemical engineers at Aalto University in Finland reporting in Waste Management showed that plastic-coated and multilayer packaging required hydraulic pressure pretreatment and perforation to cut hydropulping time by up to 67% [12]. Food brands evaluating compostable pouches and multi-layer laminates must therefore verify municipal sorting compatibility before launching hybrid packs.
Commercial Opportunity Analysis: High-Barrier Paper Pouches and Active Biopolymer Films
Substitution of plastic and foil films with heat-sealable barrier papers and active bio-based coatings gives pouch converters a major commercial opportunity across dry foods and perishable produce. Paper pouches coated with water-based oxygen and moisture barriers allow coffee, spice, and dry snack brands to avoid plastic packaging taxes while running on standard vertical and horizontal form-fill-seal lines. In November 2025, researchers at the Chinese Academy of Agricultural Sciences publishing in Food Chemistry showed that an active chitosan packaging film loaded with green-tea polyphenols extended fresh fruit storage life to 12 days [13]. Converters that combine active freshness coatings with recyclable paper or mono-polyolefin webs can win premium grocery contracts across North America and Europe.
Pouch Market by Country (2026 to 2036)
Geographic demand forecasts identify Mexico as the fastest-expanding pouch market at a 5.9% CAGR between 2026 and 2036, followed by Poland at 5.4%, the United States at 4.9% and Italy at 4.1%. Country trajectories depend on domestic form-fill-seal food capacity, wet pet food retort lines, and mono-material tax incentives.
Table 7: Country CAGR and Primary Growth Levers for the Pouch Market (CAGR percentage and operational drivers), 2026 to 2036
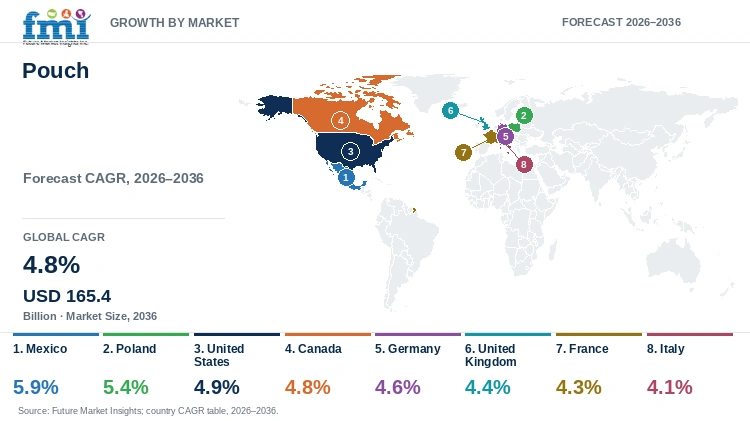
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 5.9% | High-volume sauce, dairy, beverage, and export snack form-fill-seal pouch converting |
| Poland | 5.4% | Central European wet pet food retort pouches and private-label grocery exports |
| United States | 4.9% | Automated VFFS foodservice condiment pouches and mono-PE store-drop recyclable bags |
| Canada | 4.8% | Front-of-package labeling redesigns and USD 125B food processor pouch conversions |
| Germany | 4.6% | PPWR recyclability grading driving mono-material polyolefin and barrier paper pouches |
| United Kingdom | 4.4% | 85% pet treat penetration and UK Plastic Packaging Tax PCR film adoption |
| France | 4.3% | AGEC single-use plastic reduction pushing liquid soap refills and paper-barrier pouches |
| Italy | 4.1% | Paper-barrier aseptic and flexible dairy, coffee, and culinary sauce exports |
Source: Future Market Insights analysis
Mexico Pouch Market Outlook (2026 to 2036)
Flexible pouch consumption in Mexico is forecast to climb at a leading 5.9% CAGR over the 2026 to 2036 period while food, beverage, and home-care manufacturers expand stand-up and spouted filling lines for domestic grocery and export trade. Salsa, refried bean, dairy and liquid detergent brands in Mexico choose gusseted retort and spouted bags because lightweight flexible laminates lower per-unit retail prices across neighborhood stores and reduce cross-border trucking weight. In August 2025, Mondi Group plc scaled up production of its FunctionalBarrier Paper Ultimate ultra-high barrier paper web engineered to run on standard horizontal and vertical form-fill-seal machines [14]. Film converters in Monterrey and Guadalajara continue adding solventless laminators and ultrasonic spout welders.
Key takeaway: In Mexico, culinary sauce and detergent refill bag adoption with cross-border food exports are forecast to drive a 5.9% CAGR.
Poland Pouch Market Outlook (2026 to 2036)
Flexible pouch volume in Poland is slated to advance at a 5.4% CAGR between 2026 and 2036 because international pet nutrition, dry grocery, and confectionery companies use Poland as their central European pouch co-packing and converting base. High-speed autoclave retort lines in Poland fill single-serve wet cat and dog food pouches for supermarket chains across the European Union, while domestic polymer institutes develop recyclable barrier laminates. In July 2025, chemical engineers at the Silesian University of Technology in Gliwice reporting in Foods fabricated multilayer biodegradable chitosan and electrospun polycaprolactone packaging films with 57.1 megapascal tensile strength [15]. Flexible converters in Poland actively transition retort accounts from aluminum foil to mono-polypropylene structures.
Key takeaway: In Poland, European wet pet food retort co-packing and mono-polypropylene barrier film upgrades are projected to sustain a 5.4% CAGR.
United States Pouch Market Outlook (2026 to 2036)
Valuation of the pouch market across the United States is slated to post a 4.9% CAGR from 2026 through 2036 as snack, pet food, and quick-service restaurant brands swap rigid plastic tubs and squeeze bottles for resealable and spouted bags. After its 2025 combination with Berry Global Group Inc., Amcor plc integrated its polyethylene film extrusion and injection-molded closure plants across the United States to deliver recycle-ready stand-up pouches at national scale. In its third-quarter fiscal 2026 Form 10-Q filed with the U.S. Securities and Exchange Commission for the period ended March 31, 2026, Amcor plc reported combined flexible and rigid packaging operations [16]. Grocery fillers across the United States specify store-drop recyclable mono-PE zipper bags.
Key takeaway: In the United States, restaurant condiment dispensing pouches and store-drop recyclable mono-PE grocery bags are anticipated to support a 4.9% CAGR.
Canada Pouch Market Outlook (2026 to 2036)
Demand for flexible pouches in Canada should climb at a 4.8% CAGR during the ten-year forecast because federal front-of-pack nutrition symbol rules effective January 2026 and provincial extended producer responsibility tariffs require complete film artwork and laminate updates. Shredded cheese, frozen berry, dry snack and pet treat brands in Ontario and Quebec are replacing mixed-polymer films with mono-polyethylene stand-up pouches accepted in municipal blue-box recycling programs. Insights from the July 2026 USDA Foreign Agricultural Service Exporter Guide for Canada confirm that the country remained the top foreign buyer of U.S. consumer-ready foods across consolidated supermarket chains [17]. Converters in Canada formulate metallocene polyethylene sealants that resist brittle cracking during sub-zero winter freight.
Key takeaway: In Canada, provincial blue-box recycling fee modulation and 2026 nutrition-symbol film redesigns are estimated to maintain a 4.8% CAGR.
Germany Pouch Market Outlook (2026 to 2036)
Pouch industry valuation in Germany is slated to register a 4.6% CAGR from 2026 through 2036 while discount grocers and private-label tenders enforce statutory design-for-recycling grades under national packaging waste law in Germany. Roast coffee packers, dry culinary mix blenders, and liquid detergent makers in Germany are phasing out aluminum-foil trilaminates in favor of mono-material polypropylene pouches and extrusion-coated barrier papers that sort cleanly in dual-system recovery plants. Documentation in the July 2026 USDA Foreign Agricultural Service Exporter Guide for Germany notes that grocery retailers in Germany enforce strict sustainability and packaging compliance requirements across all consumer-ready food suppliers [18]. Flexible converters in Germany lead Europe in qualifying laser-perforated tear strips and mono-PP spouted refill bags.
Key takeaway: In Germany, discounter private-label recyclability thresholds and aluminum-free barrier pouch conversions are slated to drive a 4.6% CAGR.
United Kingdom Pouch Market Outlook (2026 to 2036)
Sales of flexible pouches in the United Kingdom are expected to expand at a 4.4% CAGR through 2036 because the UK Plastic Packaging Tax and supermarket packaging charters reward lightweight refill bags and certified post-consumer recycled resin content. Wet pet food, baby puree and cooking sauce brands across the United Kingdom use single-serve retort and spouted pouches, while preserve and beverage packers adopt third-party audited recycled polyolefin films. In August 2026, Amcor plc teamed with preserve producer Wilkin & Sons in the United Kingdom to roll out RecyClass-certified 30% post-consumer recycled polyethylene films ahead of Plastic Packaging Tax adjustments [19]. Supermarkets across the United Kingdom also expand front-of-store flexible film return bins.
Key takeaway: In the United Kingdom, Plastic Packaging Tax incentives and high pet-food and home-care refill pouch usage are expected to support a 4.4% CAGR.
France Pouch Market Outlook (2026 to 2036)
Flexible pouch demand in France is predicted to advance at a 4.3% CAGR across the ten-year horizon while national single-use plastic reduction decrees push dermocosmetics, liquid soap, and fruit compote brands into spouted eco-refills and paper-barrier bags. Pharmacies and hypermarkets in France merchandise 250-milliliter to 1-liter spouted refill pouches that cut rigid bottle plastic weight by 75% and pair with in-store bulk dispensing fixtures. Guidance in the July 2026 USDA Foreign Agricultural Service Exporter Guide for France details mandatory national environmental labeling and packaging reduction rules governing retail food and consumer goods [20]. Converters in France invest in mono-polyethylene spout sealing and dispersion-coated paper pouch laminating lines.
Key takeaway: In France, pharmacy dermocosmetic and liquid soap eco-refill pouches under national plastic reduction laws are predicted to sustain a 4.3% CAGR.
Italy Pouch Market Outlook (2026 to 2036)
Flexible pouch valuation in Italy will progress at a 4.1% CAGR across the ten-year forecast and supported by export-focused espresso coffee, tomato sauce, mozzarella and UHT dairy processors adopting aluminum-free barrier laminates. Across Italy's fragmented base of 55,000 food processors, specialty food exporters require oxygen transmission rates below 1.0 cubic centimeter per square meter per day to protect aroma without paying composite foil waste penalties. In April 2026, Tetra Pak International SA and dairy processor Sterilgarda Alimenti in Italy introduced a 1-liter aseptic package utilizing a paper-based barrier that replaces aluminum foil while preserving ambient shelf life [21]. Rotogravure converters in Italy pair high-definition printing with solventless mono-polyolefin laminations for global export brands.
Key takeaway: In Italy, export coffee, dairy and tomato sauce processors adopting foil-free barrier laminates are projected to maintain a 4.1% CAGR.
Full report country CAGRs cover: North America and Latin America and Western Europe and Eastern Europe, East Asia, South Asia and Pacific and Middle East and Africa.
Who are the notable companies in the pouch market?
Tetra Pak International SA, Smurfit Westrock plc, Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Mondi Group plc, Sonoco Products Company, International Paper Company, Huhtamaki Oyj, and Constantia Flexibles Group GmbH are the notable companies in the pouch market.
Competitive positioning in the pouch industry separates global flexible film and pouch converters, paper-barrier and bag-in-box liquid packaging specialists, and fiber-to-flexible hybrid packaging groups. Amcor plc and Berry Global Group Inc. and Huhtamaki Oyj and Sealed Air Corporation and Constantia Flexibles Group GmbH extrude and print and laminate high-barrier polyolefin, foil and retort pouches across global food, pet care and healthcare plants. Mondi Group plc and Sonoco Products Company supply both mono-material polymer pouches and functional barrier paper bags while Tetra Pak International SA, Smurfit Westrock plc and International Paper Company participate across aseptic paper-barrier packs, Bag-in-Box flexible bladders and fiber-based pouch alternatives.
- Global Flexible Film and High-Barrier Pouch Converters: Amcor plc and Berry Global Group Inc. and Huhtamaki Oyj and Constantia Flexibles Group GmbH manufacture stand-up, retort, spouted and mono-material polyolefin pouches across multi-continent converting networks.
- Foodservice VFFS and Hybrid Paper Leaders: Sealed Air Corporation and Mondi Group plc with Sonoco Products Company and Tetra Pak International SA supply automated vertical form-fill-seal liquid pouches, high-barrier paper stand-up pouches, and aseptic barrier packs.
- Bag-in-Box Liquid Bladders and Fiber-Packaging Groups: Smurfit Westrock plc and International Paper Company produce flexible Bag-in-Box inner pouches with dispensing taps and renewable kraft paper substrates for flexible mailers and bags.
Competitive Benchmarking: Pouch Market
Table 8: Competitive Benchmarking for the Pouch Market (qualitative capability ratings), 2026
| Company | High-Barrier Pouch Converting | Filling-Line & Spout Integration | Mono-Material Recyclability Fit | Geographic Reach |
|---|---|---|---|---|
| Amcor plc | High | High | High | 400+ locations in 40+ countries; USD 23B sales post-Berry Global combination |
| Berry Global Group Inc. | High | High | High | Combined with Amcor plc in April 2025; global PE film, spout, and closure scale |
| Sealed Air Corporation | High | High | High | Global CRYOVAC and Liquibox network; launched ZeroPrep VFFS pouch in September 2026 |
| Mondi Group plc | High | Medium | High | European and North American re/cycle FlexiBag and FunctionalBarrier Paper |
| Huhtamaki Oyj | High | Medium | High | Global blueloop mono-material PE and PP pouches across Europe, India, and Asia |
| Sonoco Products Company | High | Medium | High | North American and global flexible stand-up pouches and peelable lidding films |
| Constantia Flexibles Group GmbH | High | Medium | High | European and global Ecolutions mono-polyolefin and foil retort pouches |
| Tetra Pak International SA | Medium | High | High | Global high-speed aseptic and paper-barrier liquid packaging lines |
| Smurfit Westrock plc | Medium | High | High | Global Vitop Bag-in-Box flexible liquid pouches and paper-based packaging |
| International Paper Company | Unscored | Medium | High | Global renewable kraft paper and fiber substrates for mailers and bags |
Evaluation basis: High-Barrier Pouch Converting evaluates documented first-party production of multi-layer polyolefin, foil or barrier-paper stand-up and retort pouches, whereas Filling-Line & Spout Integration rates proprietary VFFS/HFFS equipment and spout/fitment manufacturing. Mono-Material Recyclability Fit measures commercialized >90% mono-PE, mono-PP, or repulpable paper pouch structures.
Key Developments in the Pouch Market
- Amcor plc reported on February 10, 2026 that its 2025 combination with Berry Global Group Inc. created a global polyethylene shrink, flexible pouch film, and injection-molded closure portfolio across consumer and healthcare packaging [22].
- Amcor plc announced on September 9, 2026 that it will display its award-winning AmPrima recycle-ready refill pouch and Amcor HealthCare reclosable pouch across machinery partner lines at PACK EXPO International 2026 [23].
- Smurfit Westrock plc published a multi-country European consumer recycling study on September 3, 2026 confirming high household separation of flexible Bag-in-Box inner pouches from outer corrugated cases for recycling [24].
Key Players in the Pouch Market
Global Flexible Film and High-Barrier Pouch Converters
- Amcor plc
- Berry Global Group Inc.
- Huhtamaki Oyj
- Constantia Flexibles Group GmbH
Foodservice VFFS and Hybrid Paper Leaders
- Sealed Air Corporation
- Mondi Group plc
- Sonoco Products Company
- Tetra Pak International SA
Bag-in-Box Liquid Bladders and Fiber-Packaging Groups
- Smurfit Westrock plc
- International Paper Company
Pouch Market - Report Scope
Table 9: Report Scope for the Pouch Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Pouch Structure, Barrier Material, Closure System, End-Use Sector, Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial converter valuation from pre-made flexible pouches and printed form-fill-seal pouch rollstock across stand-up bottom-gusset (Doypack), flat three-side and four-side seal, spouted liquid, and retort thermal-processing pouches made from polyolefin laminates, aluminum foil laminates, barrier paper, and bio-based polymers. Category Scope Note: Excludes heavy-duty industrial woven sacks, open-mouth grocery shopping bags, and rigid thermoformed tubs. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | Mexico, Poland, United States, Canada, Germany, United Kingdom, France, Italy, and additional countries in the full report |
| Key Companies Covered | Tetra Pak International SA, Smurfit Westrock plc, Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Mondi Group plc, Sonoco Products Company, International Paper Company, Huhtamaki Oyj, Constantia Flexibles Group GmbH |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Pouch Market - Research Methodology
Table 10: Research Methodology for the Pouch Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with flexible packaging extrusion and lamination directors, CPG food and pet-care packaging procurement heads, spout and zipper tooling engineers, and co-packing plant managers to validate unit pricing and mono-material conversion rates. |
| Secondary Research | Analysis of Regulation (EU) 2025/40 packaging recyclability rules, USDA FAS national food and retail reports, SEC Form 10-Q/10-K filings, and peer-reviewed barrier laminate and seal-strength studies. |
| Market Sizing and Forecasting | Top-down Global Industrial and Consumer Packaging baseline (where pouches represent 6.5% share) reconciled against bottom-up finished pouch shipments (1.17T to 1.26T units in 2026) and converter realizations per 1,000 units from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight installed HFFS/VFFS filling lines, wet pet food and convenience food output, EPR plastic tax rates, and household refill adoption across eight countries. |
| Operational Benchmark Traceability | Unit volume and filling-line allocation indicators in Tables 2, 3, and 4 trace to ASTM F88 seal-strength and D3985 oxygen-permeability assays, SEC segment disclosures, and USDA FAS national food processing registries. |
| Data Triangulation and Validation | Valuation estimates isolate flexible consumer and institutional pouches and attributable FFS pouch rollstock while excluding rigid plastic bottles, metal cans, bulk IBC liners, and pallet stretch wrap. |
Pouch Market by Segments
Pouch Market segmented by Pouch Structure:
- Stand-Up Pouches with Bottom Gusset
- Flat Three-Side Seal Pouches
- Spouted Pouches for Liquids
- Retort Thermal Processing Pouches
Pouch Market segmented by Barrier Material:
- Multi-Layer Polyolefin Plastic Laminate
- Aluminum Foil High-Barrier Laminate
- Bio-Based Compostable Polymer
Pouch Market segmented by Closure System:
- Press-to-Close Resealable Zipper
- Tamper-Evident Pouring Spout
- Tear Notch Heat-Sealed
Pouch Market segmented by End-Use Sector:
- Food and Beverage Processing
- Pet Care and Animal Food
- Personal Care and Liquid Soap
- Household Chemical Cleaners
Pouch Market segmented by Distribution Channel:
- Direct Converter-to-Brand Contracts
- Contract Co-Packing and Filling Networks
- Wholesale Stock Pouch Distributors
Pouch Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Mahmoudi, M. & Davis, L. (2026, September 9). The Hidden Costs of Shifting Away from Flexible Packaging on Food Prices and Household Access. Foods, 15(18), 3188 (PubMed PMID 42793974).
- [2] Sealed Air Corporation. (2026, September 22). CRYOVAC Brand Food Packaging Introduces ZeroPrep for Food Service Condiment Dispensing. Sealed Air Media Center.
- [3] Bernal-Carrillo, J. G. & Garduno, I. E. (2026, May 13). Comparative Assessment of Hybrid Paper-Based Flexible Food Packaging Solutions for the Circular Economy. Polymers, 18(10), 1197 (PMC13210668).
- [4] Sharmin, N. & Pettersen, M. K. (2026, February 1). An Overview of Polyolefin Recycling in Food Packaging and EU Design for Recycling Regulations. Journal of Food Science, 91(2), e70856 (PubMed PMID 41607276).
- [5] Zhang, M. & Coates, G. W. (2026, February 4). C-H Insertion Functionalization of Polyolefins for Versatile Polyolefin-Polyester Compatibilization. Journal of the American Chemical Society, 148(4), 4599 (PubMed PMID 41581025).
- [6] Amcor plc. (2025, July 11). Amcor and Mediacor launch a 2-liter spouted refill pouch for Nana household cleaning products. Amcor Media News.
- [7] Turksever, C. & Esmer, O. K. (2025, November 7). Sustainable Alternatives in Multilayer Packaging and Storage Stability of Pudding Powder. Foods, 14(22), 3806 (PubMed PMID 41299964).
- [8] Amcor plc. (2026, August 14). Amcor Garners Two 2026 AmeriStar Awards for AmPrima Recycle-Ready Refill Pouch and HealthCare Reclosable Pouch. Amcor Media News.
- [9] Amcor plc. (2026, October 20). Amcor European Research on Wet Pet Food Packaging Preferences Across 2,457 Buyers. Amcor Media News.
- [10] Mondi Group plc. (2026, September 24). Mondi sustainable flexible and paper packaging innovations at PACK EXPO International 2026. Mondi Group Newsroom.
- [11] Huhtamaki Oyj. (2026, September 10). Flexible packaging mono-material strategy and blueloop recyclable structures. Huhtamaki Flexible Packaging News.
- [12] Kauppi E. & Paltakari J. (2025, August 1). Pretreatment methods for plastic-coated cartons in hydropulping recovery. Waste Management, 204, 114905 (PubMed PMID 40408804).
- [13] Zhang, J. & Tan, Z. (2025, November 30). An active packaging film prepared from aqueous two-phase Pickering emulsion and chitosan for fruit preservation. Food Chemistry, 493(Pt 4), 146033 (PubMed PMID 40865446).
- [14] Mondi Group plc. (2025, August 14). Mondi ramps up FunctionalBarrier Paper Ultimate to meet demand for high-barrier paper-based packaging. Mondi Group Newsroom.
- [15] Jakubska, J. & Dudek, G. (2025, July 14). Innovative Multilayer Biodegradable Films of Chitosan and PCL Fibers for Food Packaging. Foods, 14(14), 2470 (PubMed PMID 40724291).
- [16] Amcor plc. (2026, May 1). Quarterly Report on Form 10-Q for the Period Ended March 31, 2026. U.S. Securities and Exchange Commission EDGAR.
- [17] USDA Foreign Agricultural Service. (2026, July 31). Canada Exporter Guide Annual Report CA2026-0019. U.S. Department of Agriculture GAIN.
- [18] Foreign Agricultural Service. (2026, July 1). Germany Exporter Guide Annual Report on Consumer-Ready Food Retail and Packaging Compliance. U.S. Department of Agriculture GAIN.
- [19] Amcor plc. (2026, August 25). Amcor and Tiptree Adopt RecyClass-Certified 30% PCR Films Ahead of UK Plastic Packaging Tax Changes. Amcor Media News.
- [20] USDA Foreign Agricultural Service. (2026, July 9). France Exporter Guide Annual Report FR2026-0006. U.S. Department of Agriculture GAIN.
- [21] Tetra Pak International SA. (2026, April 22). Tetra Pak and Sterilgarda Alimenti Launch Industry-First 1-Litre Package With Paper-Based Barrier. Tetra Pak News Archive.
- [22] Amcor plc. (2026, February 10). Amcor 2025 combination with Berry Global provides industry polyethylene and flexible packaging portfolio. Amcor Media News.
- [23] Amcor plc. (2026, September 9). Amcor to display recycle-ready pouch and healthcare packaging innovations at PACK EXPO International 2026. Amcor Media News.
- [24] Smurfit Westrock plc. (2026, September 3). New European study finds consumers are actively separating Bag-in-Box flexible packaging for recycling. Smurfit Westrock Newsroom.
- [25] Wu, R. & Yang, X. (2026, April 29). Nanoengineered All-Cellulose Bilayer Barrier Papers for High-Performance and Recyclable Food Packaging. Chem & Bio Engineering, 3(6), 619 (PMC13312226).
- [26] Huhtamaki Oyj. (2026, March 25). Healthcare Innovation Days 2026 on PPWR and high-barrier flexible packaging technology. Huhtamaki Flexible Packaging News.
- [27] Huhtamaki Oyj. (2026, January 12). Huhtamaki Flexible Packaging Solutions Recognised at the WorldStar Awards 2026. Huhtamaki Flexible Packaging News.
- [28] Tetra Pak International SA. (2026, February 10). Tetra Pak extends paper-based barrier packaging to high-speed packaging lines in Asia with Maeil Dairies. Tetra Pak News Archive.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the pouch market in 2026 and what is forecast for 2036?
- Which rigid-to-flexible freight savings and mono-material recyclability rules support demand for pouches?
- Why do Stand-Up Pouches with Bottom Gusset lead the pouch structure category?
- Why does Multi-Layer Polyolefin Plastic Laminate lead the barrier material category globally?
- How do growth rates differ across Mexico and Poland and the United States, Canada, Germany and Italy?
- Which leading companies supply mono-material polyolefin pouches versus high-barrier paper and Bag-in-Box systems?
- What multi-layer delamination and recycling separation hurdles restrain conventional foil laminates?
- What should food and pet-care brands evaluate before transitioning from aluminum-foil trilaminates to mono-polyolefin pouches?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Pouch Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pouch Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pouch Structure, 2026 to 2036
- Stand-Up Pouches with Bottom Gusset
- Flat Three-Side Seal Pouches
- Spouted Pouches for Liquids
- Retort Thermal Processing Pouches
- Y-o-Y Growth Trend Analysis By Pouch Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Pouch Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Material, 2026 to 2036
- Multi-Layer Polyolefin Plastic Laminate
- Aluminum Foil High-Barrier Laminate
- Bio-Based Compostable Polymer
- Y-o-Y Growth Trend Analysis By Barrier Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Material, 2026 to 2036
- Global Market Analysis and Forecast, By Closure System, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Closure System, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Closure System, 2026 to 2036
- Press-to-Close Resealable Zipper
- Tamper-Evident Pouring Spout
- Tear Notch Heat-Sealed
- Y-o-Y Growth Trend Analysis By Closure System, 2021 to 2025
- Absolute $ Opportunity Analysis By Closure System, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food and Beverage Processing
- Pet Care and Animal Food
- Personal Care and Liquid Soap
- Household Chemical Cleaners
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct Converter-to-Brand Contracts
- Contract Co-Packing and Filling Networks
- Wholesale Stock Pouch Distributors
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Pouch Structure
- By Barrier Material
- By Closure System
- By End-Use Sector
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global Group Inc.
- Sealed Air Corporation
- Mondi Group plc
- Huhtamaki Oyj
- Sonoco Products Company
- Constantia Flexibles Group GmbH
- Tetra Pak International SA
- Smurfit Westrock plc
- International Paper Company
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Pouch Structure, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Barrier Material, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Closure System, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Pouch Structure
- Figure 6: Global Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Barrier Material
- Figure 9: Global Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Closure System
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Sector
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Pouch Structure
- Figure 32: North America Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Barrier Material
- Figure 35: North America Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Closure System
- Figure 38: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-Use Sector
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Pouch Structure
- Figure 48: Latin America Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Barrier Material
- Figure 51: Latin America Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Closure System
- Figure 54: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Pouch Structure
- Figure 64: Western Europe Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Barrier Material
- Figure 67: Western Europe Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Closure System
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Pouch Structure
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Barrier Material
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Closure System
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Pouch Structure
- Figure 96: East Asia Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Barrier Material
- Figure 99: East Asia Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Closure System
- Figure 102: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Pouch Structure
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Barrier Material
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Closure System
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Pouch Structure, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Pouch Structure, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Pouch Structure
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Barrier Material, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Barrier Material, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Barrier Material
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Closure System, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Closure System, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Closure System
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the pouch market in 2026, and what is forecast for 2036?
Pouch industry valuation totaled USD 99.0 billion in 2025 and stands at USD 103.5 billion in 2026. Global market value is on course to achieve USD 165.4 billion by 2036 as food, pet care, and liquid soap brands shift from rigid bottles to stand-up and spouted bags.
What is the CAGR for the pouch market from 2026 to 2036?
Pouch demand progresses at a 4.8% CAGR across the 2026 to 2036 horizon, yielding USD 61.9 billion in added market valuation across pre-made bags and form-fill-seal rollstock.
Which pouch structure segment leads the pouch market?
Stand-Up Pouches with Bottom Gusset hold 35.5% of pouch structure demand in 2026 because self-standing base gussets provide upright retail shelf visibility while reducing inbound empty-pack freight volume by more than 75%.
Which barrier material segment leads the pouch market?
Multi-Layer Polyolefin Plastic Laminate accounts for 47.6% of the barrier material category in 2026 as oriented polyethylene and polypropylene structures with EVOH barrier layers satisfy 2030 recyclability rules.
Which country has a notable growth outlook during the assessment period?
Mexico paces national growth at a 5.9% CAGR to 2036 on the strength of culinary sauce, dairy, beverage and export food pouch filling lines.
Who are the key players in the market?
Major pouch suppliers include Amcor plc and Berry Global Group Inc. along with Sealed Air Corporation and Mondi Group plc. Sonoco Products Company and Huhtamaki Oyj also hold key positions beside Constantia Flexibles Group GmbH, Tetra Pak International SA, Smurfit Westrock plc and International Paper Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
