

- Market Size (2026)
- USD 74.5 Bn
- Forecast (2036)
- USD 123.6 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is the printed circuit boards market in 2026?
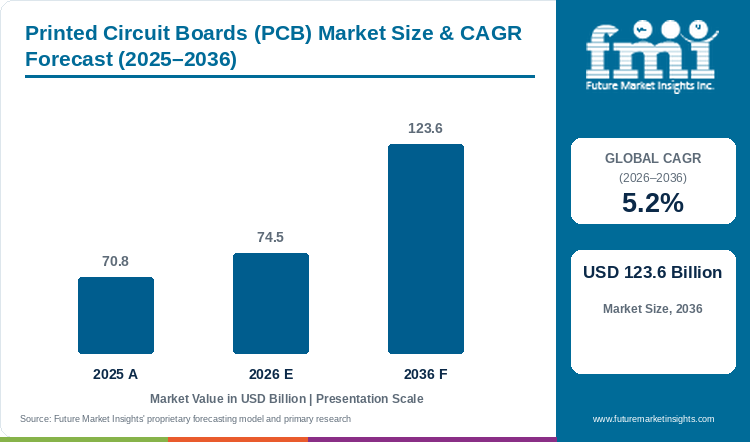
The Printed Circuit Boards (PCB) Market is projected to expand at a CAGR of 5.2% between 2026 and 2036. Market value rises from USD 70.8 billion in 2025 to USD 74.48 billion in 2026 and USD 123.61 billion by 2036. [1]
The printed circuit boards (PCB) market was valued at USD 70.8 billion in 2025. It is estimated at USD 74.48 billion in 2026 and forecast to reach USD 123.61 billion by 2036. Multilayer boards are the leading board-type category. Buyers select a board construction through the routing, electrical and mechanical requirements of the equipment, then work with manufacturers to establish a production-ready design. The printed circuit boards market is forecast to expand at 5.2% CAGR from 2026 to 2036. [1] Boards provide the physical interconnect structure within electronic products, with different constructions serving different circuit and packaging needs. The commercial comparison includes the layers, materials, interconnections and manufacturing process. A useful supplier offer connects those requirements with a design that can be produced at the quality and volume the customer needs. Recent investment spans board and package interconnects. TTM opened an Ultra-HDI PCB facility in Syracuse in June 2026. Ibiden announced additional high-performance IC substrate investment in February 2026, while AT&S inaugurated its Leoben substrate facility and competence center in June 2025. The facilities address different constructions, so buyers compare their manufacturing capabilities with the design they need to source. [2, 3, 4]
Key Market Trends & Insights
- Multilayer boards lead the board-type category. [1]
- The substrate taxonomy includes standard multilayer, HDI, IC substrates, rigid 1-2 sided, rigid-flex and other constructions. [1]
- Computer, communications, consumer, industrial, automotive and aerospace applications have different board requirements. [1]
- Stackup planning and fabrication capability connect the board design with production. [7]
Regional Highlights
- South Korea leads the profiled forecasts at 4.9% CAGR, followed by the United States at 4.8% through 2036. [1]
- Japan has a 4.7% CAGR outlook, with the European Union at 4.6% and the United Kingdom at 4.5%. [1]
- Supplier capabilities span advanced boards, flexible circuits and IC substrates, with construction requirements guiding procurement. [2, 3, 4, 10]
Market Size & Forecast
Table 1: Market Size and Forecast for the Printed Circuit Boards (PCB) Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 70.8 billion |
| Estimated Market Size in 2026 | USD 74.48 billion |
| Projected Market Size by 2036 | USD 123.61 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 49.1 billion |
| Market Expansion Multiple | 1.7x |
The market is forecast to expand at 5.2% CAGR over 2026 to 2036. [1] Boards provide the physical interconnect structure within electronic products, with different constructions serving different circuit and packaging needs. The commercial comparison includes the layers, materials, interconnections and manufacturing process. A useful supplier offer connects those requirements with a design that can be produced at the quality and volume the customer needs.
Printed Circuit Boards (PCB) Market Industry and Operating Indicators
Published product, supplier and service developments describe the operating choices within this market.
Table 2: Industry Indicators for the Printed Circuit Boards (PCB) Market, 2025 to 2026
| Indicator | Data Point | Why It Matters | Source |
|---|---|---|---|
| Ultra-HDI manufacturing facility | On June 22, 2026, TTM celebrated the opening of its Ultra-HDI PCB manufacturing facility in Syracuse, New York, supporting advanced interconnect production. | Adds a documented U.S. manufacturing setting for advanced board interconnects. | [2] |
| IC substrate investment | On February 3, 2026, Ibiden announced a capital-investment plan for high-performance IC package substrates, including additional capacity at its existing Gama plant. | Expands packaging-interconnect capacity through a named investment plan. | [3] |
| Substrate production and competence center | On June 3, 2025, AT&S inaugurated its Leoben competence center and IC substrate production facility in Austria. | Combines production with development capability for IC substrates. | [4] |
Analyst Perspective
The board design and the manufacturing process need to meet early in product development. A routing choice or layer arrangement can change the materials, interconnect process and cost of production. Buyers can improve the supplier comparison by defining the electrical and mechanical requirements before choosing a construction. The manufacturer’s value then includes helping turn the design into a repeatable production process.
- Sudip Saha, Principal Analyst at Future Market Insights
How is the printed circuit boards market segmented?
Type comprises Multi-Layer, Double-Sided and Single-Sided boards. Substrate Type covers Standard Multilayer, HDI, IC Substrate, Rigid 1-2 Sided, Rigid Flex and Others. End Use identifies seven application groups. [1]
By Type: Multi-Layer, Double-Sided, Single-Sided.
By Substrate Type: Standard Multilayer, High-Density Interconnect (HDI), IC Substrate, Rigid 1-2 Sided, Rigid Flex, Others.
By End Use: Computer & Peripherals, Communications, Consumer Electronics, Industrial Electronics, Automotive, Aerospace & Defence, Others.
By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Type describes the board’s conductive-layer arrangement, while the substrate taxonomy covers different interconnect constructions and packaging roles. End use identifies the equipment or application served. An IC substrate connects a semiconductor package with the wider electronic system, while a rigid-flex board combines different mechanical sections within a circuit. These distinctions help buyers identify the available technologies before specifying the actual product. [1, 5, 6]
Why do multilayer boards lead the type category?
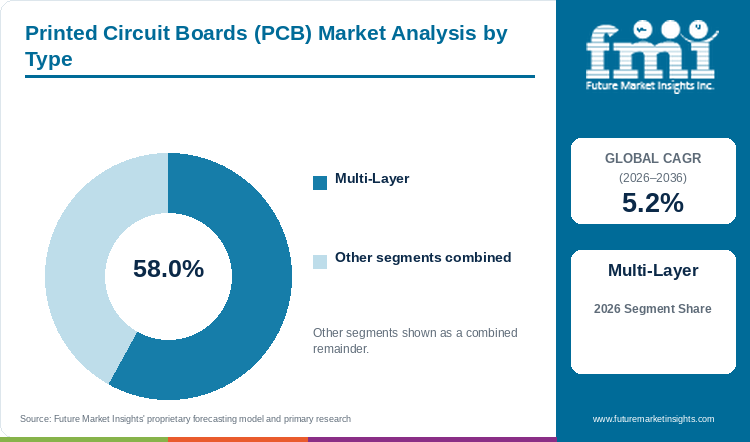
Multilayer boards lead the board-type outlook. Additional routing layers must fit the materials, stackup and fabrication process selected for the electronic design. [1, 7]
Table 3: Type Focus and Market Growth for the Printed Circuit Boards (PCB) Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Multi-layer |
Multilayer boards provide more routing layers within a defined board area. PCB design software establishes the circuit layout, while stackup planning addresses materials, thickness and connections between layers. Eurocircuits’ buildup editor combines manufacturing capabilities with price guidance. Buyers need to agree a construction that fits both the design and the selected fabrication process. [7]
- Multilayer boards are the leading Type category. [1]
- Stackup planning connects routing requirements with manufacturing options. [7]
What supports high-density interconnect demand?
High-density interconnect supports dense connections in compact designs. Supplier assessment connects the required construction with manufacturing and qualification capabilities. [2, 8] [1]
HDI serves designs requiring dense interconnections in a compact area. Zhen Ding documents its HDI portfolio, while TTM’s new Syracuse facility provides a current example of Ultra-HDI manufacturing investment. A buyer can compare these capabilities through the design’s actual interconnect requirements and the process needed to build them. The supplier review should examine the proposed construction and the information needed to qualify it for the customer’s product. [2, 8]
- High-Density Interconnect is a separate Substrate Type category. [1]
- Manufacturing capability should be matched to the required interconnect structure. [2, 8]
What makes IC substrates a distinct opportunity?
Semiconductor packaging uses IC substrates to connect the chip package with the board. A June 2026 Unimicron-group filing describes that connection and its substrate business. Ibiden’s February 2026 investment plan focuses on high-performance substrates, particularly for servers; Samsung Electro-Mechanics lists FCBGA substrates in its AI-server offer. Buyers specify the package layout and interconnections before selecting a substrate configuration. [3, 5, 9]
- IC Substrate is included within Substrate Type. [1]
- Package and system requirements determine the substrate configuration needed. [3, 5, 9]
How do flexible and rigid-flex circuits affect design choices?
Flexible printed circuit boards address the product’s physical arrangement as well as its electrical connections. TTM supplies rigid-flex and HDI combinations, while Mektec specializes in flexible circuits. Procurement includes the installation geometry, materials and fabrication information needed to produce the chosen construction consistently. [6, 10]
- Rigid Flex is included within the substrate taxonomy. [1]
- Flexible-circuit capability is documented within current supplier portfolios. [6, 10]
What changes across end-use applications?
Consumer electronics, industrial systems and aerospace equipment place different demands on size, electrical performance, mechanical arrangement and production volume. TTM’s industrial capabilities include RF, microwave and connectivity work; Isola supplies laminate and prepreg materials for high-speed and microwave designs. Those requirements guide the board construction, materials and manufacturing process. [11, 12]
- The taxonomy covers Computer & Peripherals, Communications, Consumer Electronics, Industrial Electronics, Automotive, Aerospace & Defence and Others. [1]
- Materials and construction should be selected for the intended application. [11, 12]
What are the drivers, restraints and opportunities?
Electronic-product requirements support demand; design and manufacturing constraints limit available constructions; closer design review and advanced interconnect capabilities create opportunities.
- Driver: Electronic products require interconnections suited to their packaging and performance needs.
- Restraint: The proposed construction must fit an available manufacturing process and material supply.
- Opportunity: Suppliers can connect advanced board capabilities with earlier design review and clearer production information.
Driver. Compact systems and high-performance packages create specific interconnect requirements. Current portfolios include HDI boards, rigid-flex circuits and IC substrates serving different product needs. The commercial opportunity is to identify which construction the customer requires and establish how it can be delivered. A manufacturer can support the buying decision through clear capability information rather than treating every advanced board as interchangeable. [5, 6, 8]
Restraint. A detailed board design may require materials, via structures or tolerances that change its manufacturing options. Eurocircuits’ technical tools connect design choices with its available capabilities and price guidance. Materials also have their own processing requirements, as illustrated by Isola’s laminate documentation. Buyers can reduce uncertainty by discussing these constraints while the design is still being prepared. [7, 12]
Opportunity. Manufacturers can add value through a design review that makes the proposed board easier to produce and qualify. TTM documents flex and rigid-flex support, while Eurocircuits provides digital manufacturing checks. The Global Electronics Association maintains IPC standards for the industry. These resources provide different forms of support for agreeing the construction and acceptance requirements before production begins. [6, 13, 14]
Which country and regional growth outlooks are profiled?
The outlook covers 2026 to 2036 and distinguishes the European Union as a regional market group. [1]
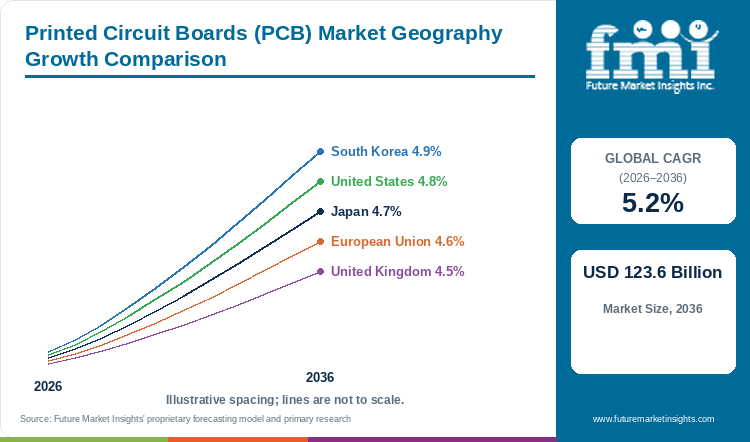
| Country or Regional Market | CAGR Outlook 2026 to 2036 |
|---|---|
| South Korea | 4.9% |
| United States | 4.8% |
| Japan | 4.7% |
| European Union | 4.6% |
| United Kingdom | 4.5% |
How do the profiled markets compare?
South Korea, the United States and Japan have the fastest profiled country forecasts. The European Union and United Kingdom have separate outlooks. Supplier developments include Korean package substrates, US Ultra-HDI capacity, Japanese high-performance substrate investment and European fabrication or development capabilities. Procurement depends on the construction required and the process available to produce it. [1, 2, 3, 4, 9, 15]
In South Korea and Japan, current substrate portfolios and investment connect with semiconductor packaging. In the United States, new Ultra-HDI capacity provides a domestic advanced-board manufacturing example. In the European Union and United Kingdom, local fabrication and design support provide different routes into board procurement.
Country and Regional Analysis
South Korea
South Korea has a 4.9% CAGR outlook through 2036. [1] Samsung Electro-Mechanics lists FCBGA package substrates in its AI-server portfolio. These connect device packaging with the board, making package layout, interconnections and manufacturing requirements part of the supplier comparison. Customers also need qualification information and a process for managing production changes. [9]
The commercial review can examine the supplier’s ability to support the required construction over the product lifecycle. A substrate design may need to fit a particular package layout and manufacturing process. The customer should establish the qualification information and the arrangements for production changes. Those details make the offer easier to compare with a supplier serving a different package or board configuration.
United States
The United States has a 4.8% CAGR outlook over 2026 to 2036. [1] In June 2026, TTM opened its Syracuse Ultra-HDI manufacturing facility to support defense electronics and advanced interconnect needs. Buyers sourcing such boards need a design, material selection and acceptance requirements that fit the facility’s capabilities, with a route from engineering review to qualified production. [2]
A buyer sourcing advanced boards can examine how the design will move from review to qualified production. The proposed material and interconnect choices need to match the selected facility’s capabilities. Clear design information and acceptance requirements help establish that match. Suppliers can also explain the support available when the customer needs to revise the board or change its production schedule.
Japan
Japan has a 4.7% CAGR outlook through 2036. [1] Ibiden announced additional investment for high-performance IC package substrates in February 2026, with the first phase centered on its existing Gama plant. Nippon Mektron’s group also documents flexible-circuit products through Mektec. These are different interconnect businesses, giving buyers examples of packaging and flexible-board capabilities within the Japanese supplier ecosystem. [3, 10]
The procurement comparison should start with the device or equipment design being served. Package substrates and flexible circuits solve different connection and mechanical requirements. Buyers can establish the intended construction and the information needed from the supplier before comparing capacity claims. A useful offer also describes how the design will be qualified and how the manufacturer will manage changes during production.
European Union
The European Union has a 4.6% CAGR outlook over 2026 to 2036. [1] AT&S inaugurated its Leoben competence center and IC substrate plant in Austria on June 3, 2025. Eurocircuits also documents European manufacturing and digital design-verification services. These sources illustrate separate routes into interconnect procurement: advanced substrate development and production, and fabrication support for customer board designs. [4, 13]
A regional supplier comparison can consider both technical fit and the work required to prepare the design. Buyers need a construction that the selected manufacturer can build, with materials and acceptance criteria defined before the order is finalized. Design tools and engineering support can help make those choices explicit. The commercial value depends on their fit with the customer’s actual product and production needs.
United Kingdom
The United Kingdom has a 4.5% CAGR outlook through 2036. [1] Merlin PCB Group offers UK high-technology manufacturing, HDI microvia and impedance-control capabilities, with technical support from design to production. Buyers compare the proposed construction with the available materials and fabrication processes, including support for prototypes and repeat orders. [15]
The working relationship can be particularly useful when a board needs several design iterations. Clear manufacturing feedback helps the customer understand which choices affect the available process and cost. The buyer should also establish the information required for qualification and repeat production. Those arrangements connect the prototype work with the later procurement plan instead of treating them as unrelated orders.
Who are the notable companies?
Zhen Ding, Nippon Mektron, TTM Technologies, Unimicron, Samsung Electro-Mechanics, Ibiden, Shennan Circuits, Tripod Technology and AT&S are notable interconnect participants.
Providers serve different board and packaging requirements. Zhen Ding documents HDI, Nippon Mektron’s Mektec group specializes in flexible circuits, and TTM provides rigid-flex and advanced PCB capabilities. Unimicron and Ibiden include IC substrates, while AT&S combines substrate production with development capability. The buyer can compare this range through the actual construction needed and the engineering or manufacturing support available. [2, 3, 4, 5, 6, 8, 10]
- Advanced boards and interconnects: Zhen Ding, TTM, Unimicron, Shennan Circuits and Tripod.
- Flexible circuits: Nippon Mektron and related Mektec operations.
- Package substrates: Ibiden, Samsung Electro-Mechanics, Unimicron and AT&S.
Competitive Benchmarking: Printed Circuit Boards Market
| Provider | Documented Capability | Technology Focus | Application Context | Buyer Relevance |
|---|---|---|---|---|
| Zhen Ding | HDI portfolio | Dense interconnections | Compact electronic layouts | Board construction choice |
| Nippon Mektron / Mektec | Flexible printed circuits | Flexible interconnects | Mechanical packaging needs | Circuit configuration |
| TTM Technologies | Ultra-HDI and rigid-flex | Advanced PCB manufacturing | Defense and other electronics | Qualified production capability |
| Unimicron | PCB and IC substrate portfolio | Board and package interconnects | Chip-to-board connections | Several construction options |
| Ibiden | High-performance IC substrates | Package interconnections | Server-related packaging | Substrate capacity and design |
| Samsung Electro-Mechanics | FCBGA substrates | Semiconductor packaging | AI-server product offer | Package requirements |
| AT&S | IC substrate production and R&D | Advanced substrates | High-performance microchips | Development and production support |
| Merlin PCB Group | HDI and flex services | Local board fabrication | UK customer designs | Engineering and manufacturing access |
Key Developments in the Printed Circuit Boards Market
- On June 22, 2026, TTM celebrated the opening of its Ultra-HDI PCB manufacturing facility in Syracuse, New York, supporting advanced interconnect production. [2]
- On February 3, 2026, Ibiden announced a capital-investment plan for high-performance IC package substrates, including additional capacity at its existing Gama plant. [3]
- On June 3, 2025, AT&S inaugurated its Leoben competence center and IC substrate production facility in Austria. [4]
Key Players in the Printed Circuit Boards Market
- Zhen Ding Technology Holding Ltd.
- Nippon Mektron, Ltd.
- TTM Technologies
- Unimicron Technology Corp.
- Samsung Electro-Mechanics
- Ibiden Co., Ltd.
- Shennan Circuits Co., Ltd.
- Tripod Technology Corporation
- AT&S
- Merlin PCB Group
Printed Circuit Boards Market - Report Scope
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Type; Substrate Type; End Use; Region |
| Quantitative Units | Revenue in USD billion |
| Market Definition | Commercial printed circuit boards and covered interconnect substrates, including multilayer, double-sided and single-sided constructions; HDI, rigid-flex and IC package substrates; and other defined board formats. Coverage concerns the board or substrate product rather than the full value of electronic assemblies, semiconductor devices or finished equipment. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Markets Profiled | South Korea; United States; Japan; European Union; United Kingdom |
| Providers Profiled | Zhen Ding; Nippon Mektron; TTM; Unimicron; Samsung Electro-Mechanics; Ibiden; Shennan Circuits; Tripod; AT&S; Merlin |
| 2025 Market Value | USD 70.8 billion |
| 2026 Market Estimate | USD 74.48 billion |
| 2036 Forecast Value | USD 123.61 billion |
| CAGR | 5.2% |
| Forecast Period | 2026 to 2036 |
Printed Circuit Boards Market - Research Methodology
| Research Area | Coverage |
|---|---|
| Market Coverage | PCB and covered substrate products across type, construction and end-use categories. |
| Industry Evidence | Manufacturer capabilities, materials documentation and dated capacity announcements. |
| Market Analysis | Country and regional production examples, product portfolios and design-support resources. |
| Competitive Analysis | Construction, application fit, manufacturing process, qualification and engineering support. |
Market Segmentation
By Type
- Multi-Layer
- Double-Sided
- Single-Sided
By Substrate Type
- Standard Multilayer
- High-Density Interconnect (HDI)
- IC Substrate
- Rigid 1-2 Sided
- Rigid Flex
- Others
By End Use
- Computer & Peripherals
- Communications
- Consumer Electronics
- Industrial Electronics
- Automotive
- Aerospace & Defence
- Others
By Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] Future Market Insights. Printed Circuit Boards Market.
- [2] TTM Technologies (2026, June 22). Syracuse Ultra-HDI facility opening.
- [3] Ibiden (2026, February 3). High-performance IC substrate investment.
- [4] AT&S (2025, June 3). Leoben substrate plant opening.
- Unimicron Technology (Suzhou) (2026, June 8). Application Proof: Business and IC Substrate Definitions.
- TTM Technologies. Flex and Rigid-flex Manufacturing Capabilities.
- [7] Eurocircuits. Board buildup and stackup planning.
- Zhen Ding Technology. HDI Product Portfolio.
- [9] Samsung Electro-Mechanics. AI-server Product Applications and FCBGA Substrates.
- Mektec International. Flexible Printed Circuits and Nippon Mektron Group Locations.
- TTM Technologies. Industrial and Instrumentation Capabilities.
- Isola. I-Tera MT40 Laminate and Prepreg Materials.
- Eurocircuits. Design Verification and European Manufacturing.
- Global Electronics Association. IPC Standards.
- [15] Merlin PCB Group. UK Manufacturing and Technical Services.
This Report Answers
- What is the PCB market forecast through 2036?
- Which board and substrate constructions are covered?
- How do HDI, rigid-flex and IC substrates differ?
- Which country and regional growth outlooks are profiled?
- What advanced manufacturing investments were announced?
- How does design preparation affect the supplier comparison?
Frequently Asked Questions
How big is the printed circuit boards market in 2026?
The market is estimated at USD 74.48 billion in 2026, following USD 70.8 billion in 2025. [1]
What is the forecast for 2036?
The market is forecast to reach USD 123.61 billion by 2036 at 5.2% CAGR. [1]
Which board type leads?
Multilayer boards are the leading Type category.
Which substrate categories are covered?
Standard Multilayer, HDI, IC Substrate, Rigid 1–2 Sided, Rigid Flex and Others.
Which profiled country grows fastest?
South Korea leads at 4.9% CAGR, followed by the United States at 4.8%. [1]
How is the European Union represented?
The European Union is a regional market group with a 4.6% growth outlook. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Multi-Layer
- Double-Sided
- Single-Sided
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Substrate Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Substrate Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Substrate Type, 2026 to 2036
- Standard Multilayer
- High-Density Interconnect (HDI)
- IC Substrate
- Rigid 1-2 Sided
- Rigid Flex
- Others
- Y-o-Y Growth Trend Analysis By Substrate Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Substrate Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Computer & Peripherals
- Communications
- Consumer Electronics
- Industrial Electronics
- Automotive
- Aerospace & Defence
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Rest of Latin America
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Western Europe
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Rest of Eastern Europe
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- By Type
- By Substrate Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Substrate Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Substrate Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Substrate Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Zhen Ding
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nippon Mektron / Mektec
- TTM Technologies
- Unimicron
- Ibiden
- Samsung Electro-Mechanics
- AT&S
- Merlin PCB Group
- Zhen Ding Technology Holding Ltd.
- Nippon Mektron, Ltd.
- Unimicron Technology Corp.
- Ibiden Co., Ltd.
- Shennan Circuits Co., Ltd.
- Tripod Technology Corporation
- Zhen Ding
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


