
- Market Size (2026)
- USD 15.8 Bn
- Forecast (2036)
- USD 37.4 Bn
- CAGR (2026 to 2036)
- 9.0%
How big is Prostate Cancer Market in 2026?
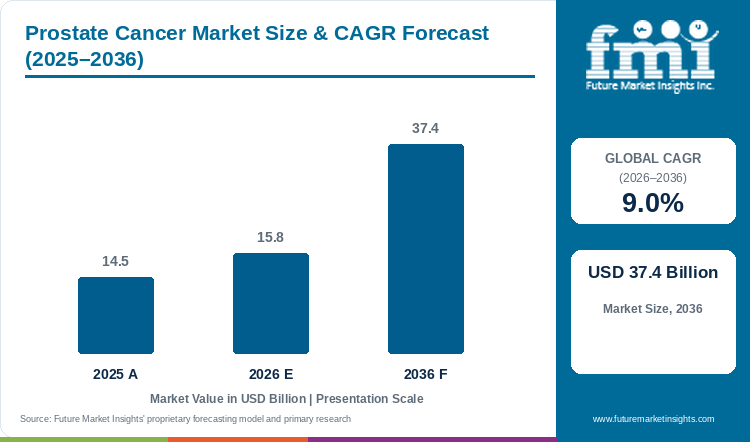
The prostate cancer market establishes its foundation at USD 14.5 billion in 2025, advances to USD 15.8 billion in 2026, and is forecast to scale to USD 37.4 billion by 2036 at a CAGR of 9.0%.
The global prostate cancer market was valued at USD 14.5 billion in 2025 and is estimated to reach USD 15.8 billion in 2026. The market is projected to reach USD 37.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 9.0% between 2026 and 2036. Hormone therapy anti-androgens and GnRH agonists are projected to command a 52.0% share of 2026 demand, given that oral androgen receptor pathway blockers remain the backbone of systemic treatment across recurrent and metastatic lines. Analysts at FMI find that industry revenue is expanding through treatment-intensity uplift per patient, as urologists and oncologists move oral androgen receptor doublets and radioligand infusions into pre-chemotherapy settings that double therapy duration [1]. That first-line combination migration lifts systemic prostate oncology growth well above diagnostic and therapeutic radiopharmaceuticals at a 6.5% CAGR, where hospital demand remains constrained by isotope half-life logistics. Manufacturers are actively capturing earlier-line prescribers, as Bayer secured U.S. FDA approval in June 2025 for Nubeqa plus androgen deprivation therapy across metastatic castration-sensitive prostate cancer [2]. Hospital oncology formularies through 2036 will allocate spending toward biomarker-selected combinations and pre-taxane radioligand regimens that delay visceral progression.
Key Market Trends & Insights
- By therapy class: Hormone Therapy Anti-Androgens and GnRH Agonists hold an estimated 52.0% share in 2026 as enzalutamide, darolutamide, and apalutamide anchor multi-year first-line doublets.
- By disease staging: Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC represents 48.0% in 2026 driven by earlier biochemical recurrence detection via PSMA-PET imaging.
- By distribution channel: Hospital Pharmacies secure 68.0% in 2026 owing to inpatient and hospital-outpatient administration of taxane infusions, radioligands, and oncology specialty drugs.
- By route of administration: Oral Systemic Formulations account for 56.0% in 2026 supported by daily at-home tablet regimens across androgen receptor, PARP, and AKT inhibitors.
- By biomarker profile: Androgen Receptor Pathway Driven Unselected Cohorts command 62.0% in 2026 while PSMA-positive, BRCA-mutated, and PTEN-deficient cohorts post the fastest growth.
Regional Highlights
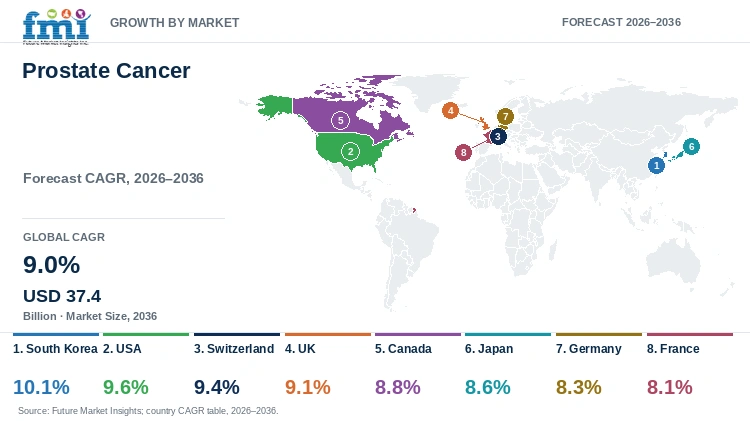
- Top national expansion: South Korea leads national growth projections at a 10.1% CAGR through 2036 under rapid demographic aging and tertiary hospital adoption of robotic and radioligand care.
- Broader country progression: The USA tracks at a 9.6% CAGR ahead of Switzerland at 9.4% and the UK at 9.1%, while Canada advances at 8.8% and Japan records 8.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Prostate Cancer Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 14.5 billion |
| Estimated Market Size in 2026 | USD 15.8 billion |
| Projected Market Size by 2036 | USD 37.4 billion |
| CAGR, 2026 to 2036 | 9.0% |
| Added Revenue, 2026 to 2036 | USD 21.6 billion |
Multidisciplinary uro-oncology teams are intensifying systemic therapy earlier in the disease course by pairing luteinizing hormone-releasing hormone agonists with next-generation androgen receptor pathway inhibitors and molecularly targeted agents. Clinical integration of oral poly ADP-ribose polymerase inhibitors in homologous recombination repair-mutated patients is extending progression-free survival and increasing cumulative drug expenditure per treated patient.
Global Diagnosed Incidence and Treated Cohort Sizing
Table 2: Global Diagnosed Incidence and Treated Patient Sizing for the Prostate Cancer Market (USD billion and patient ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 14.5 | 15.8 | 37.4 |
| Annual global new prostate cancer cases, IARC (million) | 1.50 | 1.54 | 1.95 |
| Active systemic therapy patient pool (thousand men) | 920.0 to 980.0 | 965.0 to 1,030.0 | 1,520.0 to 1,650.0 |
| Pre-taxane & post-taxane radioligand infusions (thousand doses) | 85.0 to 105.0 | 125.0 to 150.0 | 480.0 to 560.0 |
Operational note: Treated patient ranges reflect multi-year systemic therapy prevalence across biochemical recurrence and nmCRPC as well as mHSPC and pre/post-taxane mCRPC lines.
Data from the World Health Organization International Agency for Research on Cancer in September 2026 confirms that prostate cancer accounts for approximately 1.5 million new diagnoses and 397,000 deaths globally each year, making it the second most frequent malignancy in men [3]. As nuclear medicine centers deploy PSMA-targeted theranostic radioligands to detect micrometastatic lesions earlier, a larger proportion of recurrent patients transition onto high-value systemic regimens.
Per Patient Regimen Expenditure & Biomarker Testing Benchmarks
Table 3: Annualized Regimen Expenditure and Biomarker Testing Indicators for the Prostate Cancer Market (USD thousand and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| 5-year survival, localized vs distant stage, SEER (%) | 99.0% vs 37.0% | 99.0% vs 38.0% | 99.5% vs 48.0% |
| Annual net regimen spend per ARPI/PARP patient (USD thousand) | 42.0 to 68.0 | 44.0 to 72.0 | 55.0 to 88.0 |
| Complete 6-cycle Lu-177 radioligand course spend (USD thousand) | 145.0 to 185.0 | 150.0 to 190.0 | 165.0 to 210.0 |
| Biomarker-tested (PSMA/BRCA/HRR/PTEN) mHSPC/mCRPC share (%) | 48.0% to 54.0% | 55.0% to 62.0% | 82.0% to 88.0% |
Table 4: Clinical Stage Survival & Channel Allocation Indicators for the Prostate Cancer Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 15.8 billion | 2026 global net systemic prostate oncology baseline |
| Global annual prostate cancer incidence | 1.5 million cases | WHO / IARC Prostate Cancer Awareness Month 2026 report |
| Canadian 2026 diagnosed incidence | 29,300 males | Public Health Agency of Canada (October 2026 report) |
| Hospital Pharmacies channel revenue, 2026 | USD 10.7 billion | 68.0% distribution channel allocation |
National Cancer Institute SEER program statistics reviewed in May 2025 demonstrate that 5-year relative survival reaches 99% for localized and regional prostate cancer but drops to 37% for distant metastatic disease [4]. This steep survival gap drives oncology payers to fund castration-resistant oncology regimens and early biochemical-recurrence hormone doublets that prevent distant bone and visceral metastases.
Analyst Perspective
"Uro-oncology prescribing is undergoing a structural front-loading shift where androgen receptor pathway inhibitors, radioligands, and PARP or AKT combinations move from late-stage salvage into biochemical recurrence and de novo hormone-sensitive disease. Pharmaceutical manufacturers that pair oral endocrine backbones with companion PSMA-PET, BRCA, and PTEN diagnostics will capture the longest treatment durations through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the prostate cancer market segmented?
The prostate cancer market is segmented by therapy class, disease staging, distribution channel, route of administration, and biomarker profile. In 2026, Hormone Therapy Anti-Androgens and GnRH Agonists are projected at 52.0%, Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC at 48.0%, Hospital Pharmacies at 68.0%, Oral Systemic Formulations at 56.0%, and Androgen Receptor Pathway Driven Unselected Cohorts at 62.0%.
By therapy class: Hormone Therapy Anti-Androgens and GnRH Agonists and Chemotherapy Docetaxel and Cabazitaxel lead selection. Additional classes include Targeted PARP Inhibitors Olaparib and Rucaparib, Immunotherapy Sipuleucel-T, and Radioligand Therapy Lutetium Lu-177 Vipivotide Tetraxetan.
By disease staging: Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC and Metastatic Castration-Resistant Prostate Cancer mCRPC account for core demand, followed by Metastatic Hormone-Sensitive Prostate Cancer mHSPC and Localized Early-Stage Prostate Cancer.
By distribution channel: Hospital Pharmacies, Specialty Oncology Clinics, and Retail Pharmacies.
By route of administration: Oral Systemic Formulations, Parenteral Subcutaneous and Intramuscular Depot Injections, and Intravenous Infusions and Radiopharmaceutical Injections.
By biomarker profile: Androgen Receptor Pathway Driven Unselected Cohorts and PSMA-Positive Radioligand-Selected Patients lead volume, followed by BRCA1/2 and HRR Gene-Mutated Cohorts and PTEN-Deficient and MSI-High Subgroups.
Why do Hormone Therapy Anti-Androgens and GnRH Agonists lead the therapy class category?
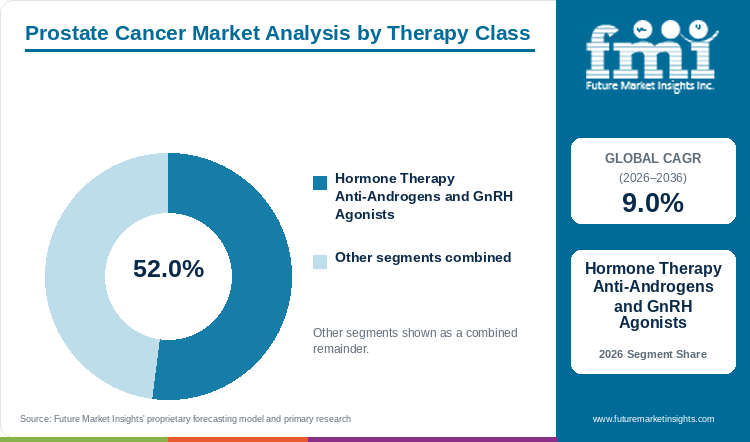
Hormone Therapy Anti-Androgens and GnRH Agonists hold an estimated 52.0% of therapy class demand in 2026, anchored by multi-year enzalutamide, darolutamide, and apalutamide regimens.
Table 5: Therapy Class Share for the Prostate Cancer Market (percentage share), 2026
| Therapy Class | Share (2026) |
|---|---|
| Hormone Therapy Anti-Androgens and GnRH Agonists | 52.0% |
| Other Segments Combined | 48.0%* |
| Total | 100.0% |
*Note: Remaining therapy class categories account for the balance of 2026 global prostate cancer demand.
Table 6: Therapy Class Leadership and Market Growth for the Prostate Cancer Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.0% |
| Leading Segment | Hormone Therapy Anti-Androgens and GnRH Agonists |
Endocrine anti-androgens and GnRH agonists capture over half of global revenue because second-generation androgen receptor pathway inhibitors such as enzalutamide, darolutamide, and apalutamide are maintained continuously for two to five years per patient. Wider clinical adoption of hormone-sensitive androgen deprivation therapies in combination with oral ARPIs has replaced androgen deprivation monotherapy as the global standard of care. Generic abiraterone price erosion and upcoming patent expirations for first-wave oral anti-androgens nevertheless pressure mature brand pricing in North America and Europe.
- By therapy class, Hormone Therapy Anti-Androgens and GnRH Agonists are projected to account for 52.0% of category demand in 2026 given multi-year treatment duration across nmCRPC and mHSPC.
- In October 2025, Pfizer and Astellas announced final EMBARK overall survival results showing that Xtandi plus leuprolide reduced the risk of death by 40% versus leuprolide alone in non-metastatic hormone-sensitive biochemical recurrence [5].
What sustains Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC leadership in the disease staging segment?
Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC represents an estimated 48.0% of the disease staging category in 2026 due to early PSMA-PET recurrence detection and 3-year to 4-year oral ARPI treatment duration.
Non-metastatic castration-resistant and high-risk biochemically recurrent stages represent the largest revenue pool because patients remain asymptomatic and stay on daily oral anti-androgen therapy for 36 to 45 months before radiographic progression. After the November 2023 FDA clearance of enzalutamide for non-metastatic castration-sensitive prostate cancer with high-risk biochemical recurrence based on the 1,068-patient EMBARK trial, community urologists initiate oral ARPIs years earlier than in prior decades [6]. Clinicians managing advanced endocrine oncology therapeutics must still balance multi-year hormone suppression against cumulative cardiovascular fatigue and bone-density loss.
- Within the disease staging category, Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC is anticipated to capture a leading 48.0% share in 2026 owing to prolonged 3-year to 4-year per-patient therapy durations.
- Metastatic hormone-sensitive and pre-taxane mCRPC stages are forecast to record rapid growth through 2036 as triplet regimens, BRCA combinations, and pre-chemotherapy Lu-177 radioligands expand per-patient treatment value.
How do Hospital Pharmacies lead the distribution channel category?
Hospital Pharmacies secure an estimated 68.0% of distribution channel demand in 2026 through hospital control over radiopharmaceutical infusions, taxane chemotherapy, and specialty oncology formularies.
Hospital pharmacies control two-thirds of global distribution because intravenous taxane chemotherapy and Lu-177 vipivotide tetraxetan radioligand infusions as well as hospital-dispensed oral oncology regimens are managed through accredited hospital oncology centers. Tertiary hospital nuclear medicine departments also coordinate oncology biomarker translation assays and PSMA-PET scans required before authorizing targeted radioligand or PARP therapies. Radiation safety licensing, lead-shielded infusion bays, and radiopharmaceutical waste storage requirements nevertheless limit radioligand dispensing to specialized hospital centers.
- Hospital Pharmacies are estimated to secure 68.0% of distribution channel demand in 2026 given hospital control over radiopharmaceutical infusions, parenteral depots, and oncology clinic formularies.
- In February 2026, Novartis presented real-world data from 506 mCRPC patients at ASCO GU showing that administering Pluvicto before chemotherapy more than doubled median progression-free survival to 13.8 months versus 6.4 months post-taxane [7].
Why do Oral Systemic Formulations lead the route of administration category?
Oral Systemic Formulations account for an estimated 56.0% of route of administration value in 2026 supported by daily at-home oral anti-androgen, PARP, and AKT inhibitor regimens.
Oral systemic formulations generate the majority of revenue because androgen receptor pathway inhibitors and PARP or AKT inhibitors as well as oral GnRH antagonists such as relugolix are taken daily at home without requiring hospital infusion chairs. On December 12, 2025, Johnson & Johnson received U.S. FDA clearance for its dual-action oral tablet Akeega combining niraparib and abiraterone acetate for BRCA2-mutated metastatic castration-sensitive disease, cutting radiographic progression risk by 54% in AMPLITUDE [8]. High specialty pharmacy copayments and polypharmacy drug-drug interactions in elderly men on cardiovascular medications remain practical adherence hurdles for oral regimens.
- Oral Systemic Formulations are forecast to account for 56.0% of route of administration demand in 2026 supported by daily oral ARPI, PARP, and AKT inhibitor combinations.
- Intravenous radiopharmaceutical injections are projected to post the fastest route growth through 2036 as pre-taxane Lu-177 vipivotide tetraxetan and investigational alpha-emitting Ac-225 radioligands scale across nuclear medicine clinics.
What gives Androgen Receptor Pathway Driven Unselected Cohorts the leading position in biomarker profile?
Androgen Receptor Pathway Driven Unselected Cohorts command an estimated 62.0% of biomarker profile demand in 2026 as first-line ARPI + ADT doublets treat the broad hormone-sensitive population.
Androgen receptor pathway driven unselected cohorts account for the largest patient share because over 85% of newly diagnosed recurrent and hormone-sensitive prostate tumors depend on androgen signaling and respond to ARPI + ADT therapy without requiring a rare genomic mutation. Broad unselected efficacy allows urologists and medical oncologists to prescribe darolutamide, enzalutamide, or apalutamide immediately upon staging confirmation. However, acquired androgen receptor splice variants and lineage plasticity eventually drive castration resistance, requiring subsequent biomarker-guided switching.
- Androgen Receptor Pathway Driven Unselected Cohorts are expected to command 62.0% of biomarker profile demand in 2026 as first-line ARPI doublets treat the broad hormone-sensitive population.
- On June 18, 2026, AstraZeneca received U.S. FDA approval for its AKT inhibitor Truqap plus abiraterone and ADT in PTEN-deficient de novo metastatic hormone-sensitive prostate cancer based on the Phase III CAPItello-281 trial [9].
What are the drivers, restraints, and opportunities in the prostate cancer market?
In the prostate cancer market, front-line ARPI combination migration and pre-taxane Pluvicto expansion drive growth, nuclear medicine chair bottlenecks and generic abiraterone erosion restrain value, and BRCA, PTEN, and alpha-radioligand precision therapies create major opportunities.
- Driver: Front-line migration of oral androgen receptor pathway inhibitors into high-risk localized and biochemical-recurrence settings and pre-taxane Pluvicto expansion multiply per-patient treatment duration.
- Restraint: Radioligand nuclear medicine infrastructure bottlenecks, generic abiraterone price erosion, and hematologic or cardiovascular toxicities from multi-drug combinations restrain market value.
- Opportunity: Scaling precision biomarker regimens for BRCA-mutated, PTEN-deficient, and PSMA-positive subgroups with next-generation alpha radioligands opens high-margin oncology revenue.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Perioperative and first-line clinical trial breakthroughs are moving potent systemic therapies into curable high-risk localized prostate cancer and de novo biomarker-selected metastatic disease. Routine deployment of molecular companion diagnostic assays enables oncology teams to identify BRCA1/2, HRR, and PTEN alterations at initial biopsy rather than waiting for castration resistance. In February 2026, Johnson & Johnson announced positive Phase 3 PROTEUS results showing that perioperative Erleada plus ADT before and after radical prostatectomy reduced metastasis or death risk by 47% and recurrence by 62% in high-risk localized prostate cancer [10]. Earlier systemic ARPI therapy in surgical localized cohorts opens a large new patient pool previously treated with surgery or radiation alone.
Risk Assessment of the Prostate Cancer Market: Operational and Formulation Friction
Six-cycle lutetium-177 radioligand regimens across broader pre-chemotherapy mCRPC populations strain hospital nuclear medicine chair capacity, radiation safety staffing, and public health reimbursement budgets. Even as hospitals adopt genomic liquid biopsy diagnostics and PSMA-PET imaging, multi-week referral delays between community urologists and accredited theranostic centers can cause clinical deterioration before infusion start. In November 2026, a multicenter Canadian real-world study in Current Oncology reported that while publicly reimbursed Lu-177-PSMA-617 achieved a 38% PSA50 response rate, multidisciplinary referral coordination and patient performance status drop-off remained key implementation hurdles [11]. Decentralized outpatient radiopharmacy networks and streamlined public reimbursement pathways are essential to resolve these referral bottlenecks.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Combination of gallium-68 and fluorine-18 PSMA-PET diagnostic kits with pre-taxane radioligand and targeted alpha therapies creates a high-growth theranostic revenue flywheel for oncology suppliers. In parallel with immuno-oncology assay kits and genomic panels, PSMA-PET imaging directly quantifies receptor expression to select responders for lutetium-177 and actinium-225 therapeutics. In June 2025, Telix Pharmaceuticals received U.S. FDA label expansion for its Illuccix gallium-68 gozetotide PSMA-PET kit to select patients for pre-taxane radioligand therapy, opening an estimated 20,000-plus additional annual U.S. scans [12]. Companion theranostic imaging paired with earlier-line radioligands and oral precision combinations will drive premium value expansion through 2036.
Prostate Cancer Market by Country (2026 to 2036)
FMI country modeling indicates that South Korea leads prostate cancer market expansion at a 10.1% CAGR through 2036 ahead of the USA at 9.6% and Switzerland at 9.4%. The UK follows at 9.1% and Canada tracks at 8.8%, while Japan at 8.6% and Germany at 8.3% outpace France at 8.1%.
Table 7: Country CAGR and Primary Growth Levers for the Prostate Cancer Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 10.1% | Rapid male demographic aging and NHIS reimbursement for oral ARPIs and radioligands |
| USA | 9.6% | FDA approvals of pre-taxane Pluvicto, Nubeqa mCSPC, Akeega BRCA2 mCSPC, and Truqap PTEN mHSPC |
| Switzerland | 9.4% | Universal Spezialitatenliste coverage and pioneering Basel/Zurich PSMA theranostic centers |
| UK | 9.1% | NICE NG131 combination pathways and May 2026 MHRA approval of Akeega in BRCA mCSPC |
| Canada | 8.8% | 29,300 annual cases and provincial public reimbursement of Lu-177-PSMA-617 and ARPIs |
| Japan | 8.6% | Super-aging male incidence and Phase 3 TLX591-Px (Illuccix) theranostic registration trial |
| Germany | 8.3% | DKG-certified prostate centers, nuclear medicine capacity, and EMA Truqap PTEN assessment |
| France | 8.1% | 100% ALD oncology coverage, INCa BRCA genomic network, and Acces Precoce radioligand access |
Source: Future Market Insights analysis
South Korea Prostate Cancer Market Outlook (2026 to 2036)
South Korean expenditure on prostate cancer therapeutics is projected to expand at a leading 10.1% CAGR from 2026 to 2036, driven by rapid demographic aging and National Health Insurance Service reimbursement for second-generation oral anti-androgens and radioligands. South Korean tertiary medical centers in Seoul rapidly centralize robotic prostatectomy, PSMA-PET staging, and early ARPI doublet initiation under national cancer control programs. A 2025 global statistics review in CA: A Cancer Journal for Clinicians reported that East Asian nations including South Korea are experiencing among the fastest age-standardized increases in prostate cancer incidence due to longevity and Westernized diets [13]. Health Insurance Review and Assessment Service risk-sharing price negotiations still govern the reimbursement timeline for newly launched PARP and radioligand combinations.
Key takeaway: In South Korea, rapid population aging and centralized tertiary hospital adoption of oral ARPIs and PSMA radioligands are projected to drive leading 10.1% growth.
USA Prostate Cancer Market Outlook (2026 to 2036)
The USA prostate cancer market is forecast to grow at a 9.6% CAGR between 2026 and 2036 as FDA approvals for pre-taxane Pluvicto and Nubeqa in mCSPC as well as Akeega and Truqap expand first-line combination spending. American uro-oncology groups operate large integrated community dispensing networks and academic nuclear medicine centers that rapidly adopt NCCN Category 1 combination regimens. Data from the Centers for Disease Control and Prevention United States Cancer Statistics report updated in June 2025 confirms that prostate cancer remains the leading male malignancy in the United States with over 300,000 annual diagnoses [14]. Medicare Part D out-of-pocket redesign and Inflation Reduction Act price negotiations will shape net realized pricing across oral specialty oncology drugs.
Key takeaway: In the USA, rapid FDA approvals across pre-taxane radioligands and biomarker-selected mHSPC combinations are anticipated to anchor high-value market expansion.
Switzerland Prostate Cancer Market Outlook (2026 to 2036)
Sales of prostate cancer therapeutics in Switzerland are anticipated to advance at a 9.4% CAGR through 2036, supported by mandatory basic health insurance coverage on the federal Spezialitatenliste and nuclear medicine infrastructure in Basel and Zurich. As the domestic home of Novartis and Roche, Swiss university hospitals pioneer early clinical access to lutetium-177 and actinium-225 PSMA radioligands and genomic companion testing. In April 2026, a Swiss national cancer registry study in Swiss Medical Weekly documented long-term improvements in Swiss prostate cancer survival driven by opportunistic PSA screening and multidisciplinary systemic therapy [15]. Triennial Federal Office of Public Health international reference-price reviews periodically trim list prices for mature hormone therapies.
Key takeaway: In Switzerland, early Swissmedic authorization of radiopharmaceuticals and universal Spezialitatenliste oncology coverage are expected to sustain 9.4% annual growth.
UK Prostate Cancer Market Outlook (2026 to 2036)
Prostate cancer market expenditure in the UK is estimated to progress at a 9.1% CAGR from 2026 to 2036 as NHS England expands commissioning for darolutamide and apalutamide as well as BRCA-targeted combinations across hormone-sensitive disease. British oncology prescribing is anchored by National Institute for Health and Care Excellence clinical pathways and Cancer Drugs Fund managed access agreements that standardize systemic doublet and triplet uptake across NHS trusts. In April 2025, NICE updated Guideline NG131 on prostate cancer diagnosis and management while the UK MHRA approved Akeega in May 2026 for BRCA-mutated mCSPC patients [16]. Strict NICE cost-per-QALY thresholds and NHS nuclear medicine camera capacity constraints continue to pace public radioligand rollout.
Key takeaway: In the UK, NICE NG131 combination pathways and MHRA approval of precision BRCA regimens are estimated to support 9.1% annual growth.
Canada Prostate Cancer Market Outlook (2026 to 2036)
The Canadian prostate cancer market is projected to expand at an 8.8% CAGR between 2026 and 2036 following provincial public oncology formulary funding for Lu-177-PSMA-617 radioligand therapy, ARPI doublets, and PARP inhibitor combinations. Canadian cancer agencies coordinate systemic drug access through pan-Canadian Pharmaceutical Alliance price negotiations and provincial systemic therapy programs in Ontario and Quebec as well as British Columbia and Alberta. On October 30, 2026, the Public Health Agency of Canada reported that an estimated 29,300 Canadian men are diagnosed with prostate cancer in 2026 (representing over 20% of male cancers) with a 91% five-year survival rate [17]. Inter-provincial disparities in PET-CT scanner density and provincial formulary listing delays remain operational hurdles for rural oncology patients.
Key takeaway: In Canada, 29,300 annual diagnoses and expanding provincial public reimbursement for PSMA radioligands and oral ARPIs are forecast to drive 8.8% growth.
Japan Prostate Cancer Market Outlook (2026 to 2036)
Revenue from prostate cancer therapeutics in Japan is forecast to grow at an 8.6% CAGR through 2036 as super-aging demographics make prostate cancer the top male malignancy by incidence and PMDA approvals introduce PSMA theranostics and AKT inhibitors. Japanese urology departments historically maintained patients on long-term combined androgen blockade and are now rapidly upgrading to darolutamide, enzalutamide, and olaparib regimens under National Health Insurance. On January 29, 2026, Telix Pharmaceuticals dosed the first patient in its registration Phase 3 study of TLX591-Px (Illuccix gallium-68 PSMA-PET imaging) in Japanese prostate cancer patients to support national theranostic adoption [18]. Biennial NHI drug price revisions and stringent domestic radiation-control hospital regulations moderate net revenue growth in Japan.
Key takeaway: In Japan, super-aging male incidence and Phase 3 registration of PSMA theranostic imaging and systemic combinations are slated to sustain 8.6% growth.
Germany Prostate Cancer Market Outlook (2026 to 2036)
The German prostate cancer market is expected to record an 8.3% CAGR from 2026 to 2036, supported by Europe's largest network of Deutsche Krebsgesellschaft-certified prostate cancer centers and established statutory GKV reimbursement for Lu-177 radioligands and oral ARPIs. German university nuclear medicine departments in Essen, Munich, and Heidelberg lead Europe in PSMA radioligand administration and molecular tumor board profiling. In July 2026, the European Medicines Agency advanced its variation assessment for AstraZeneca's AKT inhibitor Truqap in PTEN-deficient metastatic hormone-sensitive prostate cancer, expanding precision combination options for German clinicians [19]. Strict G-BA added-benefit assessments and AMNOG statutory rebates restrain net unit price inflation across mature hormone classes.
Key takeaway: In Germany, extensive nuclear medicine theranostic capacity and statutory GKV coverage of precision mHSPC combinations are predicted to support 8.3% growth.
France Prostate Cancer Market Outlook (2026 to 2036)
France is projected to achieve an 8.1% CAGR in the prostate cancer market between 2026 and 2036, supported by 100% Assurance Maladie Affection de Longue Duree coverage and early access to novel radioligands and PARP combinations under the national Accès Précoce program. French oncology centers coordinate genomic BRCA1/2 testing through the National Cancer Institute INCa molecular genetics network to guide first-line combination prescribing. The World Health Organization global cancer burden report notes that Western European health systems face mounting demand for multidisciplinary oncology services as aging male cohorts live longer with chronic metastatic disease [20]. Mandatory CEPS price clawbacks and generic abiraterone and cabazitaxel substitution in public hospitals temper overall value growth in France.
Key takeaway: In France, full ALD long-term illness reimbursement and Accès Précoce early authorization for radioligands and PARP combinations are expected to sustain 8.1% growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the prostate cancer market?
Astellas Pharma Inc., Pfizer Inc., Johnson & Johnson, Novartis AG, AstraZeneca plc, Sanofi SA, Bayer AG, Merck & Co. Inc., Orion Corporation, and Telix Pharmaceuticals Limited represent the notable companies in the prostate cancer market.
Competitive positioning in the prostate cancer industry separates global androgen receptor pathway leaders, radioligand and precision PARP/AKT oncology innovators, and specialized theranostic and chemotherapy suppliers.
- Androgen Receptor Pathway Leaders: Astellas Pharma Inc. and Pfizer Inc. with Johnson & Johnson, Bayer AG, and Orion Corporation anchor global systemic revenue through Xtandi and Erleada plus Nubeqa across recurrent and hormone-sensitive stages.
- Radioligand & Precision PARP/AKT Innovators: Novartis AG, AstraZeneca plc, and Merck & Co. Inc. lead biomarker-selected therapy through pre-taxane Pluvicto, Lynparza, and Truqap plus Keytruda and ODM-208 programs.
- Chemotherapy & Theranostic Imaging Specialists: Sanofi SA and Telix Pharmaceuticals Limited supply Jevtana (cabazitaxel) cytotoxic chemotherapy and Illuccix or Gozellix gallium-68 PSMA-PET companion imaging with investigational TLX591/TLX592 targeted alpha radioligands.
Competitive Benchmarking: Prostate Cancer Market
Table 8: Competitive Benchmarking for the Prostate Cancer Market (qualitative capability ratings), 2026
| Company | Hormone-Sensitive & Early-Stage Portfolio | Biomarker & Radioligand Innovation | Global Oncology Hospital Reach | Geographic Reach |
|---|---|---|---|---|
| Astellas Pharma Inc. | High | Medium | High | Global Xtandi (enzalutamide) leader across nmHSPC (EMBARK), nmCRPC, mHSPC, and mCRPC |
| Pfizer Inc. | High | High | High | Global Xtandi co-commercialization, Talzenna (talazoparib) mCRPC doublet, and Orgovyx partner |
| Johnson & Johnson | High | High | High | Erleada (apalutamide) in mHSPC/nmCRPC/PROTEUS and FDA/MHRA-approved Akeega in BRCA mCSPC |
| Novartis AG | Medium | High | High | Global radioligand leader; Pluvicto FDA-approved in pre-taxane mCRPC (PSMAfore) and PSMAddition |
| AstraZeneca plc | High | High | High | Lynparza (olaparib) in BRCA mCRPC and FDA-approved Truqap (capivasertib) in PTEN mHSPC |
| Sanofi SA | Low | Low | High | Global oncology reach; Jevtana (cabazitaxel) post-docetaxel chemotherapy standard of care |
| Bayer AG | High | High | High | Nubeqa (darolutamide) FDA-approved in mCSPC/nmCRPC and Xofigo (radium-223) bone radiopharmaceutical |
| Merck & Co. Inc. | Medium | High | High | Keytruda (MSI-H) and Phase III CYP11A1 inhibitor opevesostat (ODM-208) with Orion |
| Orion Corporation | High | High | Medium | Originator of darolutamide (Nubeqa) with Bayer and opevesostat (ODM-208) with Merck |
| Telix Pharmaceuticals Limited | Medium | High | Medium | Illuccix/Gozellix PSMA-PET kits (FDA pre-taxane RLT selection) and Phase 3 TLX591/TLX592 |
Evaluation basis: Hormone-Sensitive & Early-Stage Portfolio evaluates approved indications across localized and biochemical-recurrence as well as nmCRPC and mHSPC settings, whereas Biomarker & Radioligand Innovation rates PSMA-targeted radioligands and PARP or AKT inhibitors. Global Oncology Hospital Reach measures commercial formulary penetration and nuclear medicine supply-chain infrastructure across North America, Europe, and Asia Pacific.
Key Developments in the Prostate Cancer Market
- Bayer AG presented Phase III ARASTEP data at ESMO 2026 on October 24, 2026 showing that Nubeqa (darolutamide) plus ADT and radiation reduced metastasis or death risk by 58% in high-risk prostate cancer [21].
- Johnson & Johnson received UK MHRA approval on May 14, 2026 for Akeega (niraparib plus abiraterone acetate) in BRCA-mutated metastatic castration-sensitive prostate cancer following December 2025 U.S. FDA approval [22].
- Telix Pharmaceuticals Limited presented Phase 3 ProstACT Global lutetium-177 TLX591 and alpha-therapy TLX592 prostate theranostic programs at EANM 2026 on October 18, 2026 in addition to pre-taxane Illuccix selection [23].
Key Players in the Prostate Cancer Market
Androgen Receptor Pathway Leaders
- Astellas Pharma Inc.
- Pfizer Inc.
- Johnson & Johnson
- Bayer AG
Orion Corporation
- Radioligand & Precision PARP/AKT Innovators
- Novartis AG
- AstraZeneca plc
- Merck & Co. Inc.
Chemotherapy & Theranostic Specialists
- Sanofi SA
- Telix Pharmaceuticals Limited
Prostate Cancer Market - Report Scope
Table 9: Report Scope for the Prostate Cancer Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Therapy Class; Disease Staging; Distribution Channel; Route of Administration; Biomarker Profile |
| Quantitative Units | USD Billion |
| Market Definition | Includes net hospital and specialty pharmacy sales of hormone therapies, radioligands, PARP/AKT inhibitors, immunotherapies, and chemotherapies for prostate cancer |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, USA, Switzerland, UK, Canada, Japan, Germany, France, and additional regional markets |
| Key Companies Covered | Astellas Pharma Inc., Pfizer Inc., Johnson & Johnson, Novartis AG, AstraZeneca plc, Sanofi SA, Bayer AG, Merck & Co. Inc., Orion Corporation, Telix Pharmaceuticals Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with stage-stratified patient-regimen modeling |
Prostate Cancer Market - Research Methodology
Table 10: Research Methodology for the Prostate Cancer Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with uro-oncologists, medical oncologists, hospital nuclear medicine directors, and oncology pharmacy buyers |
| Secondary Research | Analysis of FDA/EMA/MHRA/PMDA drug approvals, NCI SEER and WHO/IARC registries, ESMO/ASCO GU trial readouts, and corporate filings |
| Market Sizing and Forecasting | Stage-stratified active patient cohorts (biochemical recurrence, nmCRPC, mHSPC, mCRPC) multiplied by regimen duration and net annual therapy cost |
| Country Forecasting Model | Country projections weight age-standardized male incidence, national HTA reimbursement of ARPI/PARP/RLT combinations, and PSMA-PET scanner density |
| Operational Benchmark Traceability | Incidence counts, 5-year survival rates, radioligand infusion volumes, and biomarker testing rates in Tables 2, 3, and 4 validate revenue projections |
| Data Triangulation and Validation | Revenue estimates isolate systemic pharmaceutical and radiopharmaceutical prostate cancer therapies and exclude surgical hardware and external-beam radiation |
Prostate Cancer Market by Segments
Prostate Cancer Market segmented by Therapy Class:
- Hormone Therapy Anti-Androgens and GnRH Agonists
- Chemotherapy Docetaxel and Cabazitaxel
- Targeted PARP Inhibitors Olaparib and Rucaparib
- Immunotherapy Sipuleucel-T and Checkpoint Inhibitors
Prostate Cancer Market segmented by Disease Staging:
- Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC
- Metastatic Castration-Resistant Prostate Cancer mCRPC
- Metastatic Hormone-Sensitive Prostate Cancer mHSPC
- Localized Early-Stage Prostate Cancer
Prostate Cancer Market segmented by Distribution Channel:
- Hospital Pharmacies
- Specialty Oncology Clinics
- Retail Pharmacies
- Accredited Nuclear Medicine & Radiopharmacy Centers
- Specialty Mail-Order Oncology Pharmacies
Prostate Cancer Market segmented by Route of Administration:
- Oral Systemic Formulations
- Parenteral Subcutaneous and Intramuscular Depot Injections
- Intravenous Infusions
- Targeted Radiopharmaceutical Intravenous Injections
Prostate Cancer Market segmented by Biomarker Profile:
- Androgen Receptor Pathway Driven Unselected Cohorts
- PSMA-Positive Radioligand-Selected Patients
- BRCA1/2 and HRR Gene-Mutated Cohorts
- PTEN-Deficient and MSI-High Subgroups
Prostate Cancer Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration (FDA) (2025, March 28). FDA Expands Pluvicto's Metastatic Castration-Resistant Prostate Cancer Indication to Pre-Taxane Setting. U.S. Food and Drug Administration Oncology Center of Excellence.
- [2] Bayer AG (2025, June 3). U.S. FDA Approves NUBEQA (darolutamide) in Combination with Androgen Deprivation Therapy for Metastatic Castration-Sensitive Prostate Cancer. Bayer U.S. Media Relations.
- [3] International Agency for Research on Cancer (IARC / WHO) (2026, September 1). Prostate Cancer Awareness Month 2026: Global Incidence and Mortality Burden. World Health Organization IARC.
- [4] National Cancer Institute (NCI SEER) (2025, May 15). Cancer Stat Facts: Prostate Cancer Incidence, Stage Distribution, and 5-Year Relative Survival. National Institutes of Health SEER Program.
- [5] Pfizer Inc. & Astellas Pharma Inc. (2025, October 19). XTANDI Plus Leuprolide Reduced Risk of Death by 40% Versus Leuprolide Alone in Men with Non-Metastatic Hormone-Sensitive Prostate Cancer (EMBARK OS Analysis). Pfizer Inc. Media Relations.
- [6] U.S. Food and Drug Administration (FDA) (2023, November 16). FDA Approves Enzalutamide for Non-Metastatic Castration-Sensitive Prostate Cancer with Biochemical Recurrence. U.S. Food and Drug Administration.
- [7] Novartis AG (2026, February 24). New Real-World Data Reinforce Earlier Use of Pluvicto Before Chemotherapy in Metastatic Castration-Resistant Prostate Cancer. Novartis Media Releases.
- [8] Johnson & Johnson (2025, December 12). U.S. FDA Approves AKEEGA (niraparib and abiraterone acetate) as the First Precision Therapy for BRCA2-Mutated Metastatic Castration-Sensitive Prostate Cancer. Johnson & Johnson Media Center.
- [9] AstraZeneca plc (2026, June 18). Truqap (capivasertib) Approved in the US for PTEN-Deficient Metastatic Hormone-Sensitive Prostate Cancer Based on CAPItello-281. AstraZeneca Media Centre.
- [10] Johnson & Johnson (2026, February 26). Johnson & Johnson Phase 3 PROTEUS Study Shows ERLEADA (apalutamide) Before and After Surgery Significantly Reduces Risk of Metastasis or Death in High-Risk Localized Prostate Cancer. Johnson & Johnson Media Center.
- [11] Di Maria, S., et al. (2026, November 1). Implementation and Real-World Outcomes of [177Lu]Lu-PSMA-617 Radioligand Therapy Following Public Reimbursement in Canada. Current Oncology (MDPI 33(11):666).
- [12] Telix Pharmaceuticals Limited (2025, June 23). Illuccix Approved in U.S. for Patient Selection for Pre-Taxane Radioligand Therapy in Prostate Cancer. Telix Pharmaceuticals Investor Relations.
- [13] Siegel, R. L., Kratzer, T. B., Giaquinto, A. N., Sung, H., & Jemal, A. (2025, January 16). Prostate Cancer Statistics, 2025: Global and East Asian Incidence and Mortality Trends. CA: A Cancer Journal for Clinicians (PMC12593258).
- [14] Centers for Disease Control and Prevention (CDC) (2025, June 10). United States Cancer Statistics: Prostate Cancer Incidence and Mortality Data. U.S. Department of Health and Human Services CDC.
- [15] Chiolero, A., et al. (2026, April 21). Prostate Cancer Incidence, Mortality, and Survival in Switzerland: National Registry Analysis. Swiss Medical Weekly / PMC13100841.
- [16] National Institute for Health and Care Excellence (NICE) (2025, April 10). Prostate Cancer: Diagnosis and Management (NICE Guideline NG131). NICE United Kingdom.
- [17] Public Health Agency of Canada (2026, October 30). Prostate Cancer in Canada: 2026 Incidence, Mortality, and 5-Year Survival Statistics. Government of Canada (Canada.ca).
- [18] Telix Pharmaceuticals Limited (2026, January 29). First Patient Dosed in Pivotal Phase 3 Study of TLX591-Px (Illuccix) for Prostate Cancer Imaging in Japanese Patients. Telix Pharmaceuticals Newsroom.
- [19] European Medicines Agency (EMA) (2026, July 15). Truqap (capivasertib) Variation Assessment Report for PTEN-Deficient Prostate Cancer in the European Union. European Medicines Agency CHMP.
- [20] World Health Organization (WHO) (2024, February 1). Global Cancer Burden Growing, Amidst Mounting Need for Oncology Services Across Europe and Worldwide. World Health Organization.
- [21] Bayer AG (2026, October 24). ESMO 2026: NUBEQA (darolutamide) Plus ADT and Radiation Therapy Reduces Risk of Metastasis or Death by 58% in High-Risk Prostate Cancer. Bayer U.S. Newsroom.
- [22] Johnson & Johnson (2026, May 14). UK MHRA Approves AKEEGA (niraparib and abiraterone acetate) for BRCA-Mutated Metastatic Castration-Sensitive Prostate Cancer. Johnson & Johnson Innovative Medicine UK.
- [23] Telix Pharmaceuticals Limited (2026, October 18). Telix Highlights Pivotal Trials in Prostate, Brain and Renal Cancers and Next-Generation Theranostics at EANM 2026. Telix Pharmaceuticals Newsroom.
- [24] Orion Corporation (2026, August 12). Clinical Pharmaceutical Development Pipeline: Darolutamide (Nubeqa) Global Prostate Cancer Programs and ODM-208. Orion Pharma Research & Development.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations across all primary and secondary sources.
This Report Answers
- How large is the prostate cancer market in 2026 and what is forecast for 2036?
- Which front-line ARPI combination and pre-taxane radioligand approvals support demand for prostate cancer therapeutics?
- Why do Hormone Therapy Anti-Androgens and GnRH Agonists lead the therapy class category?
- Why does Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC lead the disease staging category globally?
- How do growth rates differ across South Korea and the USA compared with Switzerland and the UK?
- Which leading companies supply oral androgen receptor inhibitors versus PSMA radioligands and PARP/AKT precision regimens today?
- What limits radioligand infusion scaling or causes combination toxicity in the prostate cancer market?
- What should oncology hospital formularies evaluate when sequencing pre-taxane Pluvicto, BRCA PARP doublets, and PTEN AKT regimens?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Therapy Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapy Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapy Class, 2026 to 2036
- Hormone Therapy Anti-Androgens and GnRH Agonists
- Chemotherapy Docetaxel and Cabazitaxel
- Targeted PARP Inhibitors Olaparib and Rucaparib
- Immunotherapy Sipuleucel-T and Checkpoint Inhibitors
- Y-o-Y Growth Trend Analysis By Therapy Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapy Class, 2026 to 2036
- Global Market Analysis and Forecast, By Disease Staging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Disease Staging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Disease Staging, 2026 to 2036
- Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC
- Metastatic Castration-Resistant Prostate Cancer mCRPC
- Metastatic Hormone-Sensitive Prostate Cancer mHSPC
- Localized Early-Stage Prostate Cancer
- Y-o-Y Growth Trend Analysis By Disease Staging, 2021 to 2025
- Absolute $ Opportunity Analysis By Disease Staging, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hospital Pharmacies
- Specialty Oncology Clinics
- Retail Pharmacies
- Accredited Nuclear Medicine & Radiopharmacy Centers
- Specialty Mail-Order Oncology Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Route of Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route of Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route of Administration, 2026 to 2036
- Oral Systemic Formulations
- Parenteral Subcutaneous and Intramuscular Depot Injections
- Intravenous Infusions
- Targeted Radiopharmaceutical Intravenous Injections
- Y-o-Y Growth Trend Analysis By Route of Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route of Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Biomarker Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Biomarker Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Biomarker Profile, 2026 to 2036
- Androgen Receptor Pathway Driven Unselected Cohorts
- PSMA-Positive Radioligand-Selected Patients
- BRCA1/2 and HRR Gene-Mutated Cohorts
- PTEN-Deficient and MSI-High Subgroups
- Y-o-Y Growth Trend Analysis By Biomarker Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Biomarker Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- By Country
- Market Attractiveness Analysis
- By Country
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Therapy Class
- By Disease Staging
- By Distribution Channel
- By Route of Administration
- By Biomarker Profile
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Astellas Pharma Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pfizer Inc.
- Johnson & Johnson
- Novartis AG
- AstraZeneca plc
- Sanofi SA
- Bayer AG
- Merck & Co. Inc.
- Orion Corporation
- Telix Pharmaceuticals Limited
- Radioligand & Precision PARP/AKT Innovators
- Astellas Pharma Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Therapy Class, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Disease Staging, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Biomarker Profile, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Therapy Class
- Figure 6: Global Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Disease Staging
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Route of Administration
- Figure 15: Global Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Biomarker Profile
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Therapy Class
- Figure 32: North America Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Disease Staging
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Route of Administration
- Figure 41: North America Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Biomarker Profile
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Therapy Class
- Figure 48: Latin America Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Disease Staging
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Route of Administration
- Figure 57: Latin America Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Biomarker Profile
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Therapy Class
- Figure 64: Western Europe Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Disease Staging
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Route of Administration
- Figure 73: Western Europe Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Biomarker Profile
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Therapy Class
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Disease Staging
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Route of Administration
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Biomarker Profile
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Therapy Class
- Figure 96: East Asia Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Disease Staging
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Route of Administration
- Figure 105: East Asia Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Biomarker Profile
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Therapy Class
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Disease Staging
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Route of Administration
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Biomarker Profile
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Therapy Class, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Therapy Class, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Therapy Class
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Disease Staging, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Disease Staging, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Disease Staging
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Route of Administration
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Biomarker Profile, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Biomarker Profile, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Biomarker Profile
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the prostate cancer market in 2026, and what is forecast for 2036?
FMI estimates that global prostate cancer valuation stood at USD 14.5 billion in 2025 and reached USD 15.8 billion in 2026. Total sector revenue is on track to hit USD 37.4 billion by 2036 as oral ARPI doublets, biomarker combinations, and pre-taxane radioligands expand.
What is the CAGR for the prostate cancer market from 2026 to 2036?
The prostate cancer sector is projected to expand at a 9.0% CAGR over the 2026 to 2036 window, adding USD 21.6 billion across hospital pharmacies and specialty oncology channels.
Which therapy class segment leads the prostate cancer market?
Hormone Therapy Anti-Androgens and GnRH Agonists hold an estimated 52.0% of therapy class demand in 2026 since enzalutamide, darolutamide, and apalutamide are prescribed continuously for multi-year durations.
Which disease staging segment leads the prostate cancer market?
Non-Metastatic Castration-Resistant Prostate Cancer nmCRPC represents an estimated 48.0% of the disease staging category in 2026 owing to earlier PSMA-PET biochemical recurrence detection and 3-year to 4-year oral therapy duration.
Which country has a notable growth outlook during the assessment period?
South Korea leads national expansion projections at a 10.1% CAGR through 2036, driven by rapid male demographic aging and NHIS reimbursement for oral ARPIs and radioligands.
Who are the key players in the market?
Astellas Pharma Inc. and Pfizer Inc. supply global demand with Johnson & Johnson, Novartis AG, and AstraZeneca plc. Additional active participants include Sanofi SA and Bayer AG, while Merck & Co. Inc., Orion Corporation, and Telix Pharmaceuticals Limited also compete.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
