

- Market Size (2026)
- USD 197.8 Mn
- Forecast (2036)
- USD 494.8 Mn
- CAGR (2026 to 2036)
- 9.6%
How big is Savory Oral Nutrition Supplement Market in 2026?
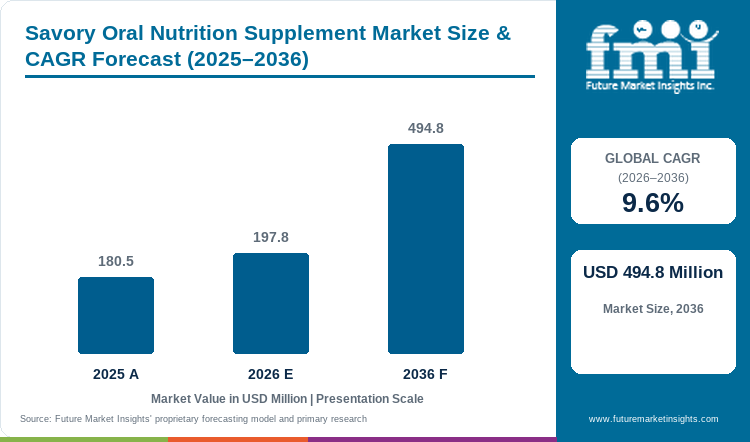
USD 197.8 million in 2026 and USD 494.8 million by 2036, expanding at 9.6% CAGR.
Sales of savory oral nutrition supplements are estimated to rise at 9.6% CAGR through 2036, increasing valuation from USD 180.5 million in 2025 to USD 197.8 million in 2026, and reaching USD 494.8 million by 2036. Long interventions make flavor choice commercially relevant because prescribed nutrition must remain acceptable during repeated use. In October 2025 Nutricia reported that one in five patients stopped medical nutrition early and its savory study recorded 95% adherence after four weeks.
National prescribing rules determine how adherence needs become recurring purchase in different countries during care. UK demand is projected at 9.1% CAGR and Germany at 8.7% over the same period. G-BA began its first national online evaluation survey for balanced diets in July 2025, keeping clinical evidence and economic review near reimbursement decisions. UK suppliers instead work through a monthly Drug Tariff plus local formularies before products become routine prescriptions.
Key Takeaways
- Demand rises when repeated ONS use makes a different taste direction necessary for continued nutritional support.
- Based on product type, fortified savory soups are projected to account for 41.3% in 2026, supported by meal familiarity.
- In 2026, sweet fatigue is expected to lead rationale with 46.7% share, driven by sweet repetition.
- By product form, ready-to-heat liquids are forecast to represent 43.7% in 2026, attributable to limited preparation.
- Prescription rules and local formularies can delay routine purchase after clinicians identify a need for oral nutrition.
- Some of the key players in this market include Danone Nutricia, Nestlé Health Science, AYMES, Meiji Co., Ltd., Nualtra, Fresenius Kabi, Medtrition, and Abbott.
Analyst Perspective
“Clinical teams use savory products to maintain continuity when repeated supplementation makes sweet options difficult. Buyers favor formats that protect intake without adding preparation work during routine clinical use.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the savory oral nutrition supplement market segmented?
Savory Oral Nutrition Supplement Market is segmented by Product Type, Rationale, Product Form, End User, Sales Channel, and Region.
The savory oral nutrition supplement market is segmented by product type, rationale, product form, end user, sales channel, and region. Product type covers soups, sip feeds, broths, custards, and mousses while rationale covers sweet fatigue, treatment-related taste changes, and meal-pattern fit. Product form distinguishes liquids, powders, and semi-solids while end users and sales channels separate care settings from pharmacy, online, and institutional routes.
What makes fortified savory soups central to the product type category?
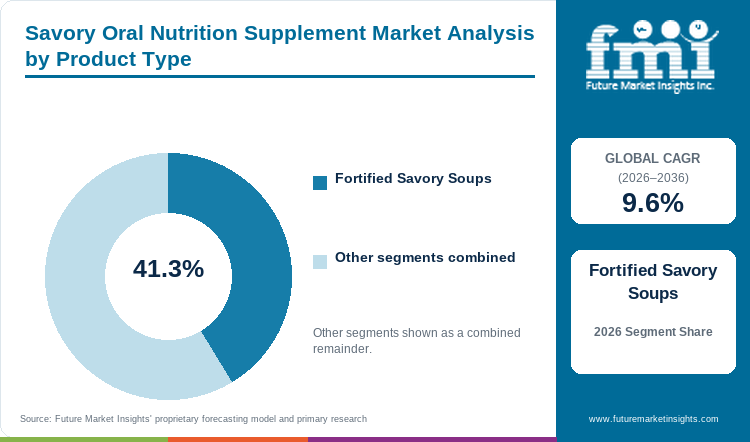
Fortified savory soups place clinical nutrition inside a meal format with familiar temperature and taste cues. Meiji’s Soup Taste Series provides 200 kcal in a 125 ml cup with corn-soup and onion-soup flavors for meals. That configuration narrows the gap between prescribed nutrition and ordinary food without increasing serving volume. Buyers comparing an oral clinical nutrition supplement with another sweet drink can use the meal cue to support longer routines. Hospitals and care facilities can fit one cup into scheduled meal service with limited preparation during routine daily nutrition support.
- By product type, fortified savory soups are estimated to hold 41.3% in 2026, owing to familiar meal placement.
- Meiji’s Soup Taste Series pairs two savory flavors with compact nutrition intended for ordinary meal occasions.
How does sweet fatigue shape demand within the rationale category?
Sweet fatigue becomes more relevant as supplementation lasts longer and the same flavor direction repeats daily. BAPEN advises clinicians to offer a range of ONS flavors to avoid taste fatigue and notes that intolerance can stop supplementation. The guidance makes sensory variety a clinical-use issue with direct implications for continued intake. Savory formats give dietitians another taste direction without changing the nutrition goal for patients who still need oral support. Within the medical food context, continued use depends on matching flavor choice with the prescribed regimen and consistent daily consumption.
- Sweet fatigue is set to lead the rationale category with 46.7% share in 2026, driven by repeated sweetness.
- Dietitians can change taste direction without changing the nutrition objective when savory alternatives meet clinical requirements.
Why do ready-to-heat liquids hold the product form position?
Ready-to-heat liquids reduce preparation variation while retaining the sensory value of a warm savory serving. Nestlé Health Science’s Resource Soup range provides nutritionally complete soup-format medical nutrition in ready-to-use portions. Staff can control portion size and temperature without mixing powder at the bedside or in a care-home kitchen. Semi-solid products remain useful where texture needs change during routine clinical nutrition support programs. The adjacent clinical nutrition cream category shows why texture alternatives matter, yet measured liquids provide a simpler route to consistent dosing and repeat service during routine clinical care in hospitals.
- The product form category is forecast to be led by ready-to-heat liquids at 43.7% share in 2026, supported by measured portions.
- Care teams can warm one measured portion without the mixing steps required by powdered regimens.
What operating condition supports long-term care demand?
Long-term care concentrates repeated nutrition support where staff can observe intake and respond to product refusal. Mersey Care’s ONS support service reviews care-home residents using oral nutritional supplements and works with local prescribers on continuation. The service shows why supervision matters after an initial recommendation because care teams can adjust serving routines before poor acceptance becomes persistent underconsumption. A therapeutic food delivery approach fits the same operating need because staff time and portion control influence consumption. Savory rotation is useful where facilities already schedule supplements beside meals during repeated daily support.
- Long-term care is likely to capture 46.9% share in 2026, attributable to monitored repeat use in care settings.
- Care-home reviews let staff adjust serving routines before poor acceptance becomes a persistent intake problem.
How does hospital pharmacy influence the sales channel category?
Hospital pharmacy influences demand when ONS moves from dietetic recommendation into a product clinicians can prescribe and services can stock. The October 2025 NHS Drug Tariff provides a national reference for listed ONS products and reimbursement terms in England and Wales. That framework gives pharmacy teams a defined route for availability but does not remove local formulary decisions. Clinical nutrition products still need policy fit and dependable supply for reliable repeat dispensing. Savory variants add value only after those access conditions are met within routine hospital and community prescribing pathways.
- Hospital pharmacy is set to lead the sales channel category with 46.3% share in 2026, supported by prescribing and formulary controls.
- National listing supports prescribers while local pharmacy and formulary decisions still determine routine product availability.
What are the drivers, restraints and opportunities in the Savory Oral Nutrition Supplement Market?
Taste fatigue increases demand for savory choices, prescription rules can delay access, and meal-compatible formats give suppliers a route for product extension.
- Driver: Longer ONS use increases the value of flavor alternatives when repeated sweet profiles reduce continued intake.
- Restraint: Prescribing and coverage rules can separate documented nutrition need from a reimbursable route for oral supplements.
- Opportunity: Meal-compatible serving formats can widen clinical use without changing the core nutrition objective for patients requiring repeated support.
Flavor variety changes the adherence decision
Longer nutrition interventions make flavor fatigue a purchasing issue because prescribed products fail when patients stop consuming them. Nutricia reported at ESPEN in September 2025 that one in three cancer patients had treatment interruption related to weight loss. Oncology nutrition presents a specific use case because treatment can alter appetite and taste while intake must remain adequate. Savory choices give dietitians another sensory direction without changing the clinical target during treatment. Manufacturers can preserve nutrition density while giving patients a different eating experience during repeated support. That option becomes commercially useful where adherence determines whether a prescription becomes repeat consumption.
Coverage rules separate clinical need from paid access
Prescription rules can delay adoption after a clinician identifies nutritional need for oral support. NHS Shropshire and Telford’s July 2025 ONS guide requires food-first care and reserves products for defined treatment goals or specialist dietetic use. Clinicians must document why routine food measures are insufficient before prescribed products become appropriate. The adjacent enteral nutrition category follows a different coverage logic where tube administration can attract device-based benefits. Savory differentiation cannot remove a prescribing gate that controls funded access to oral nutrition products. Suppliers need an accepted clinical indication and channel for repeat orders after dietetic review under local prescribing rules.
Meal-compatible formats can widen use without changing the clinical objective
Meal-compatible formats give suppliers an expansion route because serving occasions can change without changing the nutrition objective. NHS Frimley’s January 2025 adult ONS formulary lists AYMES ActaSolve Savoury as a soup-style powder mixed with hot water or milk. The listing provides a prescribing route for savory medical nutrition and ties the format to dietitian-led selection. Suppliers can build warm products that fit existing formularies without adding a separate service routine. Ready-to-heat liquids can reduce preparation further where limited staffing makes mixing time operationally important. Revenue expands where savory formats are clinically acceptable and simple enough for routine stocking during care.
Which country CAGRs are profiled in the Savory Oral Nutrition Supplement Market?
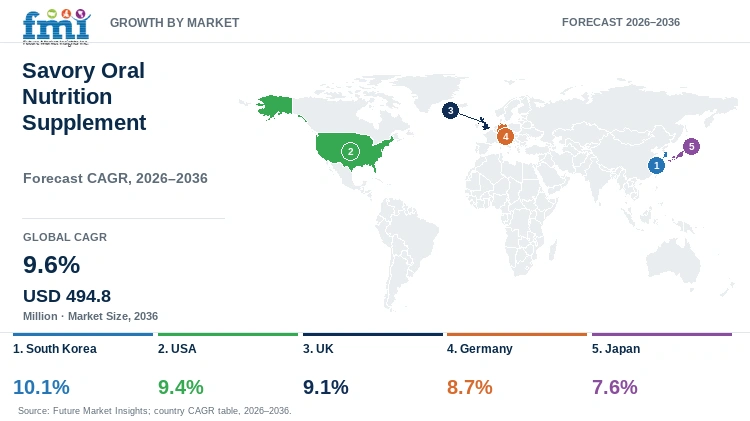
| Country | CAGR |
|---|---|
| South Korea | 10.1% |
| USA | 9.4% |
| UK | 9.1% |
| Germany | 8.7% |
| Japan | 7.6% |
How do country-level CAGRs compare in the Savory Oral Nutrition Supplement Market?
The five country forecasts form a narrow 2.5-point band from South Korea at 10.1% CAGR to Japan at 7.6%. USA and UK occupy the middle of the range while Germany stays close to both. The spacing reflects different access conditions and does not measure present market size alone.
- South Korea requires food-standard compliance and local formulation work before specialized nutrition reaches routine channels.
- USA demand follows payer boundaries separating oral supplementation from Medicare’s device-based enteral nutrition benefit.
- UK suppliers use national Drug Tariff listing plus local formularies that determine routine stocking decisions.
- Germany keeps balanced-diet products close to clinical evidence and economic review within statutory insurance rules.
- Japan combines older-adult nutrition needs with meal-culture expectations that influence serving acceptance and portion choice.
Comparable CAGRs produce different commercial conditions because each country converts clinical need into access differently. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- USA hospitals and long-term care facilities use oral nutrition under rules separating supplements from Medicare’s tube-feeding benefit. By 2036, the USA is projected to grow at 9.4% CAGR, supported by institutional oral nutrition outside Medicare’s device-based benefit. CMS stated in 2025 HCPCS determinations that Medicare does not pay oral nutrition under the DMEPOS benefit. That national rule makes institutional contracts and other payer routes important for oral ONS. Clinical teams still need products that fit nutrition plans and patient tolerance during repeated use. The specialized nutrition route strengthens where savory options fit those plans without relying on device coverage.
- UK dietitians prescribe ONS within a national tariff system while local formularies determine which products become routine choices. The UK's savory oral nutrition supplement outlook is anticipated to advance at 9.1% CAGR over the assessment period, supported by Drug Tariff access and local formulary review. NHSBSA added Fortisip PlantBased 2kcal to Part XV of the August 2025 Drug Tariff for listed indications. That national listing gives oral nutrition a recognized prescription route before local value review. Care teams may compare savory ONS with calorie supplements after discharge, yet routine use still depends on indication fit and local stocking decisions.
- Germany ties balanced diets for enteral nutrition to prescribing rules covering oral drinking nutrition and tube-fed products. Savory oral nutrition supplement demand in Germany is forecast to rise at 8.7% CAGR over the forecast period, driven by prescribed balanced-diet routes under statutory health insurance. G-BA approved the first national evaluation concept for this benefit area in June 2025 and requested evidence on current care plus new products. The process keeps scientific support and economic appropriateness close to reimbursement policy for clinical nutrition products. Savory products need recognized indications and documentation supporting routine prescribing before taste differentiation becomes commercially useful.
- Japan combines a large older-adult population with meal patterns that favor compact nutrition resembling ordinary food. Adoption of savory oral nutrition supplements in Japan is estimated to expand at 7.6% CAGR through 2036, supported by older-adult nutrition needs and compact meal-compatible formats. Japan’s Ministry of Health reported in December 2025 that 19.5% of adults aged 65 or older met the national low-nutrition threshold in the 2024 survey. That national condition supports repeated oral nutrition where appetite or meal intake becomes insufficient. Suppliers need modest portions and familiar savory cues because clinical adequacy alone does not secure daily acceptance.
- South Korea regulates patient nutrition formula foods as a national class for medically directed nutrition. The South Korean savory oral nutrition supplement sector is projected to record 10.1% CAGR during the assessment period, shaped by product standards. MFDS published national guidance for patient nutrition formula foods in April 2026 to support nutrition management. The guidance gives clinicians and suppliers a national reference for selecting specialized nutrition products. Savory ONS suppliers still need local classification records before adapting broth or soup flavors for Korean clinical channels. Technical review remains part of market entry for specialized nutrition products in South Korea.
Who are the notable companies in the Savory Oral Nutrition Supplement Market?
Danone Nutricia, Nestlé Health Science, AYMES, Meiji Co., Ltd., Nualtra, Fresenius Kabi, Medtrition, and Abbott are notable companies serving this market.
Direct savory ONS companies compete with broader nutrition platforms where product fit controls institutional supply.
- Danone Nutricia, Meiji Co., Ltd., and AYMES sell savory oral nutrition products for medically supervised use.
- Nestlé Health Science, Fresenius Kabi, and Nualtra supply broader oral medical nutrition portfolios through clinical channels.
- Medtrition and Abbott add institutional oral nutrition experience through adjacent specialized nutrition routes serving clinical teams.
Competitive Benchmarking: Savory Oral Nutrition Supplement Market
| Company | Savory ONS Range | Clinical Channel | Serving Flexibility | Geographic Reach |
|---|---|---|---|---|
| Danone Nutricia | High | High | High | Europe and international markets |
| Nestlé Health Science | High | High | High | Global |
| AYMES | High | High | High | UK and Ireland |
| Meiji Co., Ltd. | High | Medium | Medium | Japan |
| Nualtra | Low | High | High | UK and Ireland |
| Fresenius Kabi | Low | High | High | Europe and international markets |
| Medtrition | Low | High | Medium | North America and selected international markets |
| Abbott | Medium | High | High | Global |
High savory-format evidence requires a dedicated line or two savory choices while Medium requires one documented route and Low indicates none. High clinical-channel evidence requires multiple settings while Medium requires one documented route and Low indicates less direct evidence. High serving flexibility requires two oral formats while Medium requires one documented adaptation and Low indicates narrower evidence.
Key Developments in the Savory Oral Nutrition Supplement Market
- In March 2026, Nestlé Health Science launched Compleat Paediatric Oral Blends in seven European markets.
- In November 2025, Abbott launched advanced Ensure Diabetes Care through Indian pharmacy and e-commerce channels.
- In March 2025, Meiji Co., Ltd. launched onion-soup flavor and renewed corn-soup flavor nationwide in Japan.
Key Players in the Savory Oral Nutrition Supplement Market
Direct Savory Oral Nutrition Suppliers
- Danone Nutricia
- AYMES
- Meiji Co., Ltd.
Global Medical Nutrition Platforms
- Nestlé Health Science
- Fresenius Kabi
- Abbott
Clinical ONS and Institutional Nutrition Companies
- Nualtra
- Medtrition
Savory Oral Nutrition Supplement Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, rationale, product form, end user, sales channel, and region. |
| Quantitative Units | USD million. |
| Market Definition | Commercial savory oral nutritional supplements intended for oral use in clinically managed or medically supervised nutrition support. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, UK, Germany, Japan, South Korea, and 20+ countries included in the full report. |
| Key Companies Profiled | Danone Nutricia, Nestlé Health Science, AYMES, Meiji Co., Ltd., Nualtra, Fresenius Kabi, Medtrition, Abbott. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Savory Oral Nutrition Supplement Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Savory Oral Nutrition Supplement Market by Segments
Savory Oral Nutrition Supplement Market segmented by Product Type:
- Fortified Savory Soups
- Savory Sip Feeds
- Umami Broth Drinks
- Savory Custards & Mousses
- Others
Savory Oral Nutrition Supplement Market segmented by Rationale:
- Sweet Fatigue (Long-Term ONS Users)
- Taste Changes (Oncology - Ageing)
- Meal-Pattern Fit
- Others
Savory Oral Nutrition Supplement Market segmented by Product Form:
- Ready-to-Heat Liquids
- Powdered Mixes
- Semi-Solids
- Others
Savory Oral Nutrition Supplement Market segmented by End User:
- Long-Term Care
- Homecare
- Hospitals
- Others
Savory Oral Nutrition Supplement Market segmented by Sales Channel:
- Hospital Pharmacy
- Retail Pharmacy
- Online
- Institutional Tender
- Others
Savory Oral Nutrition Supplement Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Nutricia. (2025, October 1). Nutricia’s new savory plant-based medical nutrition proven to improve patient adherence.
- Gemeinsamer Bundesausschuss. (2025, July 1). Bilanzierte Diäten zur enteralen Ernährung: Onlinebefragung bei Herstellern und Fachgesellschaften startet.
- Meiji Co., Ltd. (n.d.). 明治メイバランスMiniカップスープテイスト. Retrieved September 16, 2026.
- British Association for Parenteral and Enteral Nutrition. (n.d.). Oral Nutritional Supplements (ONS). Retrieved September 16, 2026.
- Nestlé Health Science. (n.d.). Resource Soup. Retrieved September 16, 2026.
- Mersey Care NHS Foundation Trust. (n.d.). Nutrition Review and Support Service. Retrieved September 16, 2026.
- NHS Business Services Authority. (2025, October). Drug Tariff October 2025.
- Nutricia. (2025, September 14). 1 in 3 patients impacted: Nutricia calls for action on cancer-related malnutrition at ESPEN.
- NHS Shropshire, Telford and Wrekin Medicines Optimisation Team. (2025, July). ONS Prescribing Guidelines: Quick Reference Guide.
- NHS Frimley. (2025, January). Oral Nutritional Supplement (ONS) Formulary for Adults.
- Centers for Medicare & Medicaid Services. (2025). Healthcare Common Procedure Coding System Level II final coding, benefit category and payment determinations: First biannual 2025 coding cycle.
- NHS Business Services Authority. (2025, August). Drug Tariff August 2025.
- Gemeinsamer Bundesausschuss. (2025, June 19). Bilanzierte Diäten zur enteralen Ernährung: Erstes Evaluationskonzept steht fest - Onlinebefragung startet im Juli 2025.
- Ministry of Health, Labour and Welfare, Japan. (2025, December 2). 令和6年「国民健康・栄養調査」の結果.
- Ministry of Food and Drug Safety, Republic of Korea. (2026, April 29). [보도참고] 식약처, 환자용 영양조제식품 정보집 발간...환자 영양관리 지원.
- Nestlé Health Science. (2026, March 30). Nestlé introduces an innovative complete nutritional solution for children with special medical nutrition needs.
- Ajinomoto Co., Inc. (2025, May 19). Nualtra launches Altrini Compact Fibre for kids.
- Meiji Co., Ltd. (2025, March 11). カラダに大切な栄養素がまとめて摂れる!「食事の一品」としておすすめ!「明治メイバランスMiniカップ」に「スープテイストシリーズ」が新登場!
- Danone. (2025, May 12). Danone and Kate Farms to join forces to serve people with health needs across both medical and everyday nutrition.
- AYMES. (2026, July 30). Introducing AYMES rebrand journey.
- Nestlé. (2026, March 23). 2025 operating segments and information by products restated.
- Meiji Co., Ltd. (2026, September 7). 少量で高エネルギーが摂れるゼリー飲料シリーズから新味登場!「明治メイバランスソフトJelly りんごヨーグルト味/ミックスフルーツヨーグルト味」.
- Danone. (2025, July 1). Danone completes the acquisition of Kate Farms, enhancing its USA specialized nutrition offerings.
- Nestlé. (2026, February). Creating Shared Value at Nestlé - 2025.
- Nualtra. (2025, July 11). ARFID (Avoidant Restrictive Food Intake Disorder) webinar 8th July 2025.
- Fresenius Kabi. (2025, December 23). 2025 Year in review.
- Medtrition, Inc. (2025, March 25). Medtrition, Inc. launches the ProSource Cup portfolio.
- Abbott. (2025, November 13). Abbott launches new and advanced Ensure Diabetes Care, a clinically proven formula to help manage blood sugar.
- Nualtra. (n.d.). About us. Retrieved September 16, 2026.
- Abbott Nutrition. (n.d.). Ensure Plus Therapeutic Nutrition. Retrieved September 16, 2026.
- Nestlé Health Science. (2025, November 3). Nestlé Health Science to collaborate with universities in the USA and Australia to further the science of nutrition.
- Abbott. (2026, May 13). Abbott launches Ensure Strength Pro in India to support healthy ageing.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the savory oral nutrition supplement market by 2036?
- Which patient-use condition is increasing demand for savory oral nutrition?
- Why do fortified savory soups hold 41.3% of product-type demand?
- How does sweet fatigue change selection during longer ONS use?
- Why do ready-to-heat liquids hold 43.7% of product-form demand?
- How do the five included country growth rates differ commercially?
- Which companies sell savory ONS or adjacent clinical nutrition products?
- Which prescribing conditions can delay routine savory ONS purchasing decisions?
Frequently Asked Questions
How big is the Savory Oral Nutrition Supplement Market in 2026?
The savory oral nutrition supplement market reaches USD 197.8 million in 2026 and USD 494.8 million by 2036. Savory flavor alternatives can protect continued intake during longer nutrition support that makes sweetness repetitive.
What is the CAGR of the Savory Oral Nutrition Supplement Market?
The savory oral nutrition supplement market is projected to grow at 9.6% CAGR from 2026 to 2036. Growth depends on sensory variety fitting clinical eligibility and serving requirements for repeated use.
Which product type accounts for 41.3% of demand in 2026?
In 2026, fortified savory soups are expected to lead product type with 41.3% share, supported by meal-like serving. Their meal-like format gives clinical teams another option for patients who tire of repeated sweet drinks.
How do South Korea and USA compare on included CAGRs through 2036?
By 2036, South Korea is projected to grow at 10.1% CAGR, supported by national specialized-nutrition standards. USA is projected at 9.4% CAGR under payer rules governing oral nutrition access.
Which companies are active in the Savory Oral Nutrition Supplement Market?
Active companies include Danone Nutricia, Nestlé Health Science, AYMES, Meiji Co., Ltd., Nualtra, Fresenius Kabi, Medtrition, and Abbott. Their roles span direct savory products and clinical nutrition platforms serving institutional care channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Fortified Savory Soups
- Savory Sip Feeds
- Umami Broth Drinks
- Savory Custards & Mousses
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Rationale, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Rationale, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Rationale, 2026 to 2036
- Sweet Fatigue (Long-Term ONS Users)
- Taste Changes (Oncology - Ageing)
- Meal-Pattern Fit
- Others
- Y-o-Y Growth Trend Analysis By Rationale, 2021 to 2025
- Absolute $ Opportunity Analysis By Rationale, 2026 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Form, 2026 to 2036
- Ready-to-Heat Liquids
- Powdered Mixes
- Semi-Solids
- Others
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- Long-Term Care
- Homecare
- Hospitals
- Others
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Hospital Pharmacy
- Retail Pharmacy
- Online
- Institutional Tender
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Rationale
- By Product Form
- By End User
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone Nutricia
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestlé Health Science
- AYMES
- Meiji Co., Ltd.
- Nualtra
- Fresenius Kabi
- Medtrition
- Abbott
- Danone Nutricia
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


