

- Market Size (2026)
- USD 1020.9 Mn
- Forecast (2036)
- USD 1845.2 Mn
- CAGR (2026 to 2036)
- 6.1%
How big is Sea Bream Market in 2026?
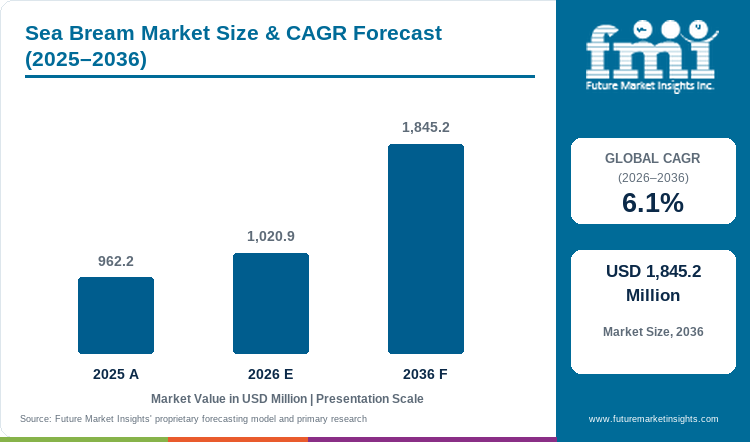
USD 1,020.9 million in 2026 and USD 1,845.2 million by 2036, expanding at 6.1% CAGR.
Sales of sea bream are estimated to rise at 6.1% CAGR through 2036, increasing valuation from USD 962.2 million in 2025 to USD 1,020.9 million in 2026, and reaching USD 1,845.2 million by 2036. Farmed Mediterranean output is offering importers harvest windows that reduce exposure to seasonal wild-catch availability. Eurostat reported in April 2026 that gilthead seabream represented 10.0% of EU aquaculture volume and 13.5% of value in 2024. Consistent size and cold-chain specifications let buyers convert that production base into scheduled orders.
Germany is projected to grow at 8.0% CAGR through 2036 compared with 6.0% CAGR for the USA. German demand depends on imported whole fresh supply while US distributors operate inside a seafood import system. NOAA Fisheries reported in March 2026 that imports supplied about 80% of seafood Americans consumed in 2023. Sea bream suppliers compete on delivered consistency and species positioning instead of relying on import access alone.
Key Takeaways
- Farmed Mediterranean supply is supporting consistent purchasing because hatcheries and marine grow-out sites can schedule harvests for regular retail and foodservice programs.
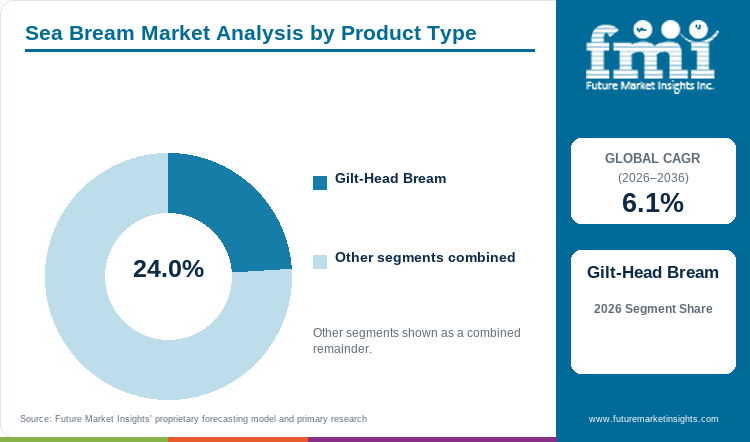
- By product type, gilt-head bream is projected to account for 24.0% of revenue in 2026, supported by mature Mediterranean production and trade channels.
- By form, processed sea bream is estimated to hold 39.0% of revenue in 2026, driven by cuts and packs that reduce downstream preparation work.
- The nature category is forecast to be led by conventional sea bream at 72.0% in 2026, influenced by broader supply and lower certification overhead.
- Biological risk and delivered-price gaps can delay supplier switching even when the underlying category demand remains stable for familiar species and formats.
- Some of the key players in this market include Cooke Hellas, Cooke España, Cromaris, CUPIBAR (Lubimar), Mariculture Systems, Özsu Balık Üretim A.Ş., Defne Aquaculture, and Gloria Maris Côte d’Opale.
Analyst Perspective
"Sea bream suppliers win repeat programs by holding harvest timing and product specification together at a defensible delivered cost. Buyers compare biological reliability with preparation labor because either weakness can disrupt a regular retail or foodservice listing."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the sea bream market segmented?
The sea bream market is segmented by Product Type, Form, Nature, and Region. Forecast period from 2026 to 2036.
The sea bream market is segmented by product type, form, nature, and region for the 2026 to 2036 assessment period. Product type covers gilt-head bream, black bream, white bream, red bream (red porgy), others, and pandora bream. Form includes processed, frozen, fresh, and canned products. Nature distinguishes conventional and organic supply.
What supports gilt-head bream within the product type category?
Gilt-head bream is purchased within a mature Mediterranean farming system that gives distributors familiar size grades and regular harvest windows. Marine farms depend on specialized aquafeed programs that align growth targets with water temperature and production schedules. EUMOFA documents Germany as an import-dependent destination for whole fresh gilthead seabream within the European trade system. That import structure favors farms that can maintain stable specifications during repeated shipments to wholesale and retail buyers.
- By product type, gilt-head bream is projected to account for 24.0% in 2026, supported by mature production depth and cross-border familiarity among Mediterranean seafood buyers. Commercial fish feed availability supports scheduled grow-out programs by aligning feed conversion with harvest timing.
- Germany provides a practical demand test because whole fresh gilthead seabream reaches the market mainly through imports instead of a large domestic farming base.
Why does processed sea bream hold the leading form position?
Processed sea bream moves gutting and filleting work upstream before the fish reaches a retail counter or commercial kitchen. That shift makes fish processing capacity part of supplier qualification because buyers can specify portion size and pack format before delivery. Retailers and foodservice kitchens reduce preparation variation when the approved cut arrives with the same handling requirements on each scheduled order.
- By form, processed sea bream is estimated to hold 39.0% in 2026, attributable to buyer demand for repeatable cuts and packaging that reduce preparation variability. Matching processing equipment capacity to harvest volumes can shorten handling time during scheduled production runs.
- Cooke España reported in June 2026 that its School Trips program included open-sea farm visits and packing-plant visits in Águilas. The program documents the production route from marine farming to final preparation for seafood channels.
How does conventional supply shape the nature category?
Conventional production uses the existing farm base without the additional chain-of-custody conditions attached to certified organic supply. The European Commission reports that organic aquaculture represented 9% of total EU aquaculture production in 2021. Organic sea bream can serve differentiated programs but certification narrows eligible production and documentation routes. Conventional supply therefore provides the broader sourcing pool for standard retail and foodservice specifications.
- The nature category is forecast to be led by conventional sea bream at 72.0% share in 2026, shaped by wider eligible output and fewer segregated handling requirements. Buyers requiring end-to-end traceability use certified seafood packaging to preserve records from packing through chilled distribution and final receipt.
- Organic supply has a defined role in programs that can absorb certification controls and maintain identity from farming through packing and distribution records.
What are the drivers, restraints and opportunities in the Sea Bream Market?
Farmed supply supports repeat ordering, biological and cost pressure can delay switching, and genetics or processing can improve production economics and buyer fit.
- Driver: Mediterranean aquaculture capacity gives importers predictable harvest windows for repeat retail and foodservice programs.
- Restraint: Disease exposure and permitting friction can raise delivered cost enough to make technically acceptable supply commercially difficult to qualify.
- Opportunity: Selective breeding and farm monitoring can lower biological variability while value-added handling reduces preparation work before purchase.
Commercial sea bream supply depends on controlled Mediterranean grow-out that turns juvenile stocking into scheduled harvest windows for importers and foodservice accounts. FAO’s 2025 review reported 940,000 tonnes of marine and brackish aquaculture production in the Mediterranean and Black Sea during 2023. Gilthead seabream represented 34% of that regional output and supplied a commercial volume base for buyers. That farm base lets distributors plan chilled and frozen seafood programs for intended size grades instead of variable wild-catch availability. Hatchery continuity gives processors a firmer volume plan before they commit labor and packaging capacity. Farms that protect survival and harvest timing make repeat orders easier to maintain within normal cold-chain replenishment cycles.
Biological and regulatory friction can interrupt a sea bream crop before a distributor changes an approved specification. FAO identifies heat stress and disease as persistent aquaculture risks for Mediterranean marine finfish producers. The same regional work also notes complex legal frameworks that can delay investment and farm expansion. Feed economics add another exposure because fishmeal and fish oil prices influence production cost before harvest. Farms cannot pass every cost change into a retail or foodservice program without risking a lost listing. Operators therefore need health controls and feeding plans that keep survival and growth within planned ranges. A technically acceptable fish can still fail commercially if delivered price exceeds the buyer’s approved margin.
Genetic selection and higher-throughput handling reduce separate sources of biological variation and preparation labor. Benchmark Genetics reported in July 2026 that the AVRAMAR gilthead seabream program achieved 76% cumulative genetic improvement in harvest weight over 20 years. The result gives Mediterranean farms a measured breeding basis for planning more consistent harvest weights. Processing investment addresses a different cost by moving gutting or portioning before the product reaches a kitchen or retail counter. Seafood packaging systems protect the approved cut and pack specification during chilled distribution to commercial buyers. Better farm performance produces repeatable yield that processors can convert into the same cut and pack on scheduled orders.
Which country CAGRs are profiled in the Sea Bream Market?
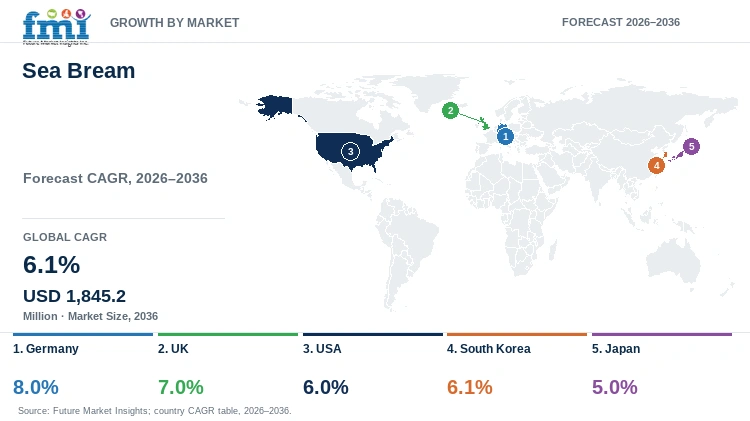
| Country | CAGR |
|---|---|
| Germany | 8.0% |
| UK | 7.0% |
| USA | 6.0% |
| South Korea | 6.1% |
| Japan | 5.0% |
How do country-level CAGRs compare in the Sea Bream Market?
Germany and the UK form the upper band while South Korea is projected at 6.1% and the USA at 6.0%. Japan carries 5.0%, and these rates compare forecast speed instead of current revenue.
- Germany depends on imported whole fresh gilthead seabream, making delivered price central to assortment decisions.
- UK import distribution favors suppliers that maintain chilled logistics for dependable retail and foodservice availability.
- US distributors handle high imported-seafood volumes, so sea bream must earn listings through stable presentation.
- South Korea combines domestic marine-fish farming with temperature and disease exposure that can disrupt harvest conditions.
- Japan’s mature red seabream production shifts competition toward differentiated formats that offer convenience beyond basic category availability.
Comparable CAGRs produce different entry conditions because national supply structures convert demand into orders differently. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Germany has little domestic gilthead seabream production and depends on imported whole fresh product for mainstream availability. Sea bream demand in Germany is forecast to rise at 8.0% CAGR over the forecast period, influenced by Mediterranean farms that maintain competitive landed prices. EUMOFA documented this import dependence and a material cost gap between local land-based production and Turkish supply. German distributors therefore compare delivered price with supply continuity before approving wider retail or foodservice assortment. Other seafood supply categories compete for chilled counter space and force distributors to budget logistics capacity carefully.
- UK seafood wholesalers operate inside a large net-import system that already handles substantial international volume. The UK sea bream sector is projected to record 7.0% CAGR during the assessment period, supported by chilled distribution that carries Mediterranean species into retail and foodservice channels. The Marine Management Organisation reported 633 thousand tonnes of fish and fish preparations imported during 2024. Inconsistent deliveries can quickly remove unfamiliar species from approved listings and weaken repeat orders for chilled programs. Protective seafood packaging systems must match practical case sizes and route lengths without raising handling losses.
- Sea bream sales in the USA are forecast to expand at 6.0% CAGR by 2036, supported by an imported-seafood system that already handles substantial international volume. NOAA Fisheries reported 19.1 pounds of seafood consumption per person in 2023 and estimated that imports supplied about 80% of consumption. Foreign suppliers still compete for shelf and menu space against species with wider consumer recognition. Sea bream must compete on stable naming and size while preserving freshness and preparation convenience. Stable naming and size specifications can widen placement during repeat shipments without sacrificing freshness or preparation convenience.
- South Korean marine-fish farmers operate in a market that combines local species familiarity with temperature-related biological risk. Adoption of sea bream in South Korea is estimated to expand at 6.1% CAGR through 2036, linked to domestic aquaculture experience and mature fish distribution. Statistics Korea reported 81,911 tonnes of fish-culture production in 2024 with output up 2.6% from 2023 partly because of higher black sea bream shipments. Farms still need heat and disease controls that protect survival during warmer summer production periods. Feed programs using fish oil must remain secondary to documented growth and health performance in each production cycle.
- Japanese buyers compare imported sea bream with a mature domestic red seabream industry that sets demanding standards for freshness and controlled sizing. Sea bream sales in Japan are forecast to expand at 5.0% CAGR by 2036, shaped by established domestic farming and national aquaculture policy. The Fisheries Agency reported 70 thousand tonnes of red seabream production in 2023 and a 110 thousand-tonne production target for 2030. Imported supply must differentiate on format and seasonality while meeting channel-specific specifications instead of basic category availability. Processors that remove preparation labor can address convenience-focused channels without displacing the local production knowledge already embedded in buyer decisions.
Who are the notable companies in the Sea Bream Market?
Cooke Hellas, Cooke España, Cromaris, CUPIBAR (Lubimar), Mariculture Systems, Özsu Balık Üretim A.Ş., Defne Aquaculture, Gloria Maris Côte d’Opale are active within the defined sea bream supply boundary.
Competition separates integrated Mediterranean producers from certified specialty farms and offshore production developers serving distinct models. Entry requires current sea bream evidence plus control of farming risk and downstream handling. Corporate identity matters because Cooke Hellas now represents the former AVRAMAR Greece operations in company references.
- Cooke Hellas and Cooke España operate integrated Mediterranean aquaculture routes that include hatchery or farming assets and downstream handling capabilities.
- Cromaris and CUPIBAR (Lubimar) compete with certified production systems that support traceability and differentiated farm-origin claims for European buyers.
- Mariculture Systems and Özsu Balık Üretim A.Ş. represent offshore development and export-oriented farming models. Defne Aquaculture and Gloria Maris Côte d’Opale add monitored cage operations and certified French production.
Competitive Benchmarking: Sea Bream Market
| Company | Sea Bream Farming Integration | Processing or Packing Capability | Certification or Technical Development | Geographic Reach |
|---|---|---|---|---|
| Cooke Hellas | High | High | High | Greece with export markets |
| Cooke España | High | High | High | Spain with national and international channels |
| Cromaris | High | High | High | Croatia with European export markets |
| CUPIBAR (Lubimar) | Medium | Medium | High | Spain with sales in more than 15 countries |
| Mariculture Systems | Low | Low | High | Portugal project with planned European access |
| Özsu Balık Üretim A.Ş. | High | High | Medium | Türkiye with United Kingdom trading subsidiary |
| Defne Aquaculture | Medium | Low | High | Türkiye offshore farms |
| Gloria Maris Côte d’Opale | Medium | Low | High | France and regional European channels |
Scoring basis: High farming integration requires current evidence of multiple controlled production stages or a large integrated farm platform. Medium reflects a narrower documented farming model while Low identifies a development-stage production role with limited operating depth. High processing or packing capability requires integrated value-added handling while Medium reflects limited documented handling and Low identifies a farm-centered model. High technical evidence requires a current certification or validated technology program while Medium and Low reflect progressively narrower documented technical depth.
Key Developments in the Sea Bream Market
- In September 2026, Cooke Hellas officially launched its new corporate identity for the former Greek operations of AVRAMAR while retaining integrated Mediterranean aquaculture operations under the Cooke name.
- In July 2026, Cooke España reported results from its three-year GENVI program that consolidated genomic-selection tools for sea bream and sea bass under commercial farming conditions.
- In July 2026, Mariculture Systems announced that Portuguese authorities had issued an Aquaculture Activity Title for its CORALIS offshore facility planned for gilthead sea bream and seabass.
Key Players in the Sea Bream Market
Integrated Mediterranean production
- Cooke Hellas
- Cooke España
- Cromaris
- Özsu Balık Üretim A.Ş.
Certified and differentiated farming
- CUPIBAR (Lubimar)
- Gloria Maris Côte d’Opale
Offshore and monitored production models
- Mariculture Systems
- Defne Aquaculture
Sea Bream Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, form, nature, and region. |
| Quantitative Units | USD million. |
| Market Definition | Commercial sea bream sold within the listed species, form, and nature categories. Downstream restaurant meal value, feed, equipment, juveniles, and substitute fish are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Germany, UK, USA, South Korea, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | Cooke Hellas, Cooke España, Cromaris, CUPIBAR (Lubimar), Mariculture Systems, Özsu Balık Üretim A.Ş., Defne Aquaculture, Gloria Maris Côte d’Opale. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Sea Bream Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Sea Bream Market by Segments
Sea Bream Market segmented by Product Type:
- Gilt-Head Bream
- Black Bream
- White Bream
- Red Bream (Red Porgy)
- Others
- Pandora Bream
Sea Bream Market segmented by Form:
- Processed
- Frozen
- Fresh
- Canned
Sea Bream Market segmented by Nature:
- Conventional
- Organic
Sea Bream Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Eurostat. (2026, April 23). EU aquaculture: 1 million tonnes produced in 2024.
- NOAA Fisheries. (2026, March 3). Fisheries of the United States.
- European Market Observatory for Fisheries and Aquaculture Products. (2022). Fresh gilthead seabream in the EU.
- Cooke España. (2026, June 18). Los School Trips 2026 acercan la acuicultura a estudiantes y profesionales en Águilas.
- European Commission, EU Aquaculture. (n.d.). How much does organic aquaculture production represent in the EU?.
- Food and Agriculture Organization of the United Nations, General Fisheries Commission for the Mediterranean. (2025). The State of Mediterranean and Black Sea Fisheries 2025: Highlights.
- Benchmark Genetics. (2026, July 2). 76% genetic gain over 20 years in AVRAMAR’s seabream programme.
- Marine Management Organisation. (2025, December 2). Fishing industry 2024 statistics published.
- Statistics Korea. (2025, March 21). Preliminary Results of the Survey on the Status of Fish Culture in 2024.
- Fisheries Agency of Japan. (2025, June). FY2024 White Paper on Fisheries.
- Cooke Hellas. (2026, September 11). Welcome to Cooke Hellas [LinkedIn post].
- Cooke España. (2026, July 30). GENVI conecta la innovación científica con la acuicultura: desde los reproductores seleccionados hasta la granja marina.
- European Commission, EU Blue Economy Observatory. (2026, July 7). Portugal achieves major milestone with permit for offshore aquaculture facility.
- Cooke Seafood. (2026, March 19). Cooke Enters Into Preliminary Agreement to Acquire the Debt of Avramar Greece.
- Cooke España. (2026, March 2). Aquicultura Balear, innovación para impulsar el crecimiento sostenible de COOKE España.
- Maison EQ. (2026, March 9). New partnership between Maison EQ. and Cromaris d.d. [LinkedIn post].
- Aquaculture Stewardship Council. (2026, March 30). World’s First Farm Achieves Certification to the New ASC Farm Standard.
- Mariculture Systems Ltd. (2026, March 26). Mariculture Systems Portugal partners with Zalmhuys Group for offshore aquaculture [LinkedIn post].
- Özsu Balık Üretim A.Ş., Public Disclosure Platform. (2026, January 6). Non-current Financial Asset Acquisition: Ozsu Fish UK.
- Akuamaks. (2026, March 28). Advanced Monitoring Systems Commissioned at DEFNE AQUACULTURE.
- Aquaculture Stewardship Council. (2026, August 25). Gloria Maris Côte d’Opale becomes the first French seabass and seabream farm to achieve ASC Certification.
- BioMar. (2026, September 8). BioMar completes its ASC certification pipeline with BioMar Greece.
- AquaWind. (2026, May 7). Canary Islands prove viability of offshore wind and aquaculture for Europe: AquaWind final event in Las Palmas.
- Cooke Hellas. (2026, September 17). New outward-looking prospects for Greek aquaculture [LinkedIn post].
- AVRAMAR. (2026, March 31). ASC Feed Certification for Our 3 Feed Plants! [LinkedIn post].
- AquaWind. (2026, February 2). AquaWind Successfully Completes Sea Bream Juvenile Stocking and Advances Offshore Validation Phase.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How does Mediterranean aquaculture capacity translate into repeat sea bream purchasing for importers and foodservice operators?
- Which product type and form hold the leading 2026 shares in the sea bream market?
- How does conventional production differ from organic supply within the nature category?
- Which biological and permitting conditions can interrupt farm output before buyers change approved specifications?
- Why do Germany and the UK show faster forecast growth than Japan in the sea bream market?
- How do import dependence and domestic farming change the commercial route in Germany, the USA, South Korea, and Japan?
- Which current companies show direct sea bream farming, certification, technology, or offshore-development activity?
- Which 2026 company actions are changing genetics, hatchery capability, ownership, monitoring, or offshore capacity?
Frequently Asked Questions
How big is the sea bream market in 2026?
The sea bream market is expected to be valued at USD 1,020.9 million in 2026 and reach USD 1,845.2 million by 2036. Farmed production supports the forecast by giving distributors repeatable harvest windows and more consistent commercial specifications.
What is the CAGR of the sea bream market from 2026 to 2036?
The sea bream market is projected to grow at 6.1% CAGR between 2026 and 2036. Farmed supply supports the forecast by preserving repeat harvest windows for buyers that require controlled delivered price and size specifications.
Which product type leads the sea bream market?
The gilt-head bream segment is expected to hold 24.0% of product type revenue in 2026, supported by mature Mediterranean farming and import channels. Buyers recognize the species and can source repeatable size grades from a comparatively mature production base.
Which form leads the sea bream market?
The processed segment is expected to hold 39.0% of form revenue in 2026, attributable to cuts and packs that remove downstream preparation work. Retailers and foodservice kitchens can specify portions and handling requirements before product reaches the final service point.
Which nature segment leads the sea bream market?
The conventional segment is forecast to represent 72.0% of nature demand in 2026, influenced by broader eligible supply and fewer certification controls. Organic programs remain relevant for buyers able to support segregation and documented chain-of-custody requirements during repeated shipments.
Which companies are active in the sea bream market?
Key companies operating in the sea bream market include Cooke Hellas, Cooke España, Cromaris, CUPIBAR (Lubimar), Mariculture Systems, Özsu Balık Üretim A.Ş., Defne Aquaculture, and Gloria Maris Côte d’Opale. Their roles span integrated farming and certified production alongside offshore development and instrumented cage operations serving commercial buyers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Gilt-Head Bream
- Black Bream
- White Bream
- Red Bream (Red Porgy)
- Others
- Pandora Bream
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Processed
- Frozen
- Fresh
- Canned
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By Form
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Nature
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Nature
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cooke Hellas
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cooke España
- Cromaris
- CUPIBAR (Lubimar)
- Mariculture Systems
- Özsu Balık Üretim A.Ş.
- Defne Aquaculture
- Gloria Maris Côte d’Opale
- Cooke Hellas
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


