
- Market Size (2026)
- USD 3448.8 Mn
- Forecast (2036)
- USD 5617.7 Mn
- CAGR (2026 to 2036)
- 5.0%
How big is the Seed Polymer Market in 2026?
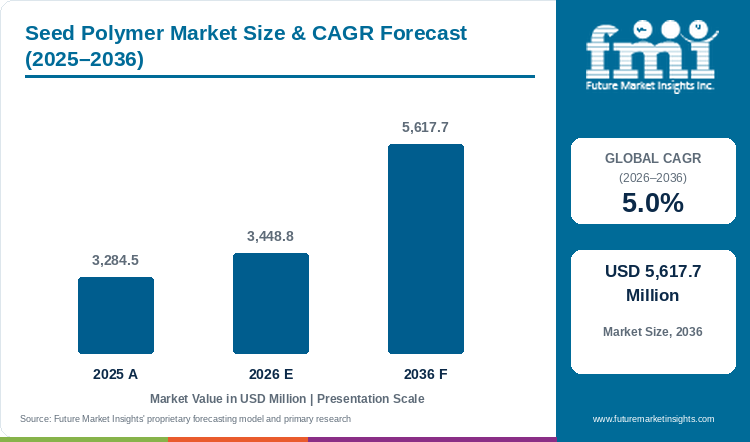
The Seed Polymer Market is projected to reach USD 5,617.7 million by 2036, growing at a 5.0% CAGR from 2026 to 2036.
FMI estimates the market at USD 3,448.8 million in 2026, after it was valued at USD 3,284.5 million in 2025. Demand rises with treated seed volumes and with the shift to coatings that stay outside the EU microplastics restriction. Non-degradable synthetic coating polymers fall under the restriction when 1% or more of the seeds in a batch measure under 5 mm. Biodegradable polymers and polymers that dissolve at 2 g/L or more fall outside it.
Seed polymer demand depends on how much seed farmers buy instead of save. Biotech varieties cover 92% of United States corn acres and herbicide resistant varieties 95% of soybean acres. Brazil records commercial seed use of 67% for soybean and 85% for cotton, against under 20% for beans. Soybean seed use runs below 40% in Rio Grande do Sul but above 80% in Mato Grosso. Industrial treatment accounts for 36.3% of soybean seed volume sold by surveyed Brazilian seed producers. Trait adoption in the United States is near complete, so growth there rests on price and mix.
Key Market Trends & Insights
- Regulation (EU) 2023/2055 on synthetic polymer microparticles has applied since 17 October 2023. In-scope seed coated with plant protection products can be sold until 17 October 2031. Other in-scope coated seed can be sold until 17 October 2028. Suppliers are therefore launching binders that show biodegradation, the product class tracked in the microplastic-free seed treatment polymer market.
- Biodegradable binders are reaching the market. In April 2026 Covestro published its Amulix S F6320 RED corn film coating. The company states that its ingredients biodegrade by 60.0% or more within 60 days under the OECD 301F test. Michelman said its biodegradable candidates are being refined and prepared for wider validation. Seed companies will compare these products on dust control, flow and cost against current synthetic grades.
- Seed enhancement suppliers are adding capacity near their customers. Incotec, a Croda brand, opened renewed laboratories in Holambra, Brazil in August 2026. It also completed an upgrade of its Tianjin facility in China.
Regional Highlights
- In Europe, regulation is setting the product roadmap. A large export seed base, led by France, sells into a market that restricts non-degradable coating polymers. Seed companies need compliant coatings before the 2028 and 2031 dates.
- In South America, area growth sustains demand. CONAB's first survey for 2026/27 puts Brazilian soybean area at 49.3 million hectares, up 1.4%. Planting at that scale supports steady purchases of treatment and flowability polymers for oilseeds.
Seed Polymer Market Size and Forecast
Table 1: Seed Polymer Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 3,284.5 million |
| Estimated market size in 2026 | USD 3,448.8 million |
| Projected market size by 2036 | USD 5,617.7 million |
| CAGR from 2026 to 2036 | 5.0% |
Source: Future Market Insights analysis of the seed polymer market, 2026.
Analyst Perspective
“Seed companies buy polymers against specifications for flow, dust, adhesion and compatibility with the active ingredient. They requalify each product when the formula changes. Suppliers with a biodegradable binder that passes European tests can win share from synthetic grades as deadlines near. Price and performance parity with current products will decide how fast buyers switch. Suppliers must establish whether their seed-coating polymers fall within the EU microplastics restriction. They must then meet the applicable exclusion, compliance and transition requirements.”
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the Seed Polymer Market segmented?
- By coating type: Film coating, Pelleting, Encrusting, Gels and priming.
- By polymer origin: Synthetic polymers, Bio-based and biodegradable polymers.
- By crop type: Cereals and grains, Oilseeds, Vegetables and fruits, Pulses, Flowers and ornamentals.
- By region: North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa.
Why does Film coating lead by Coating Type in the Seed Polymer Market in 2026?
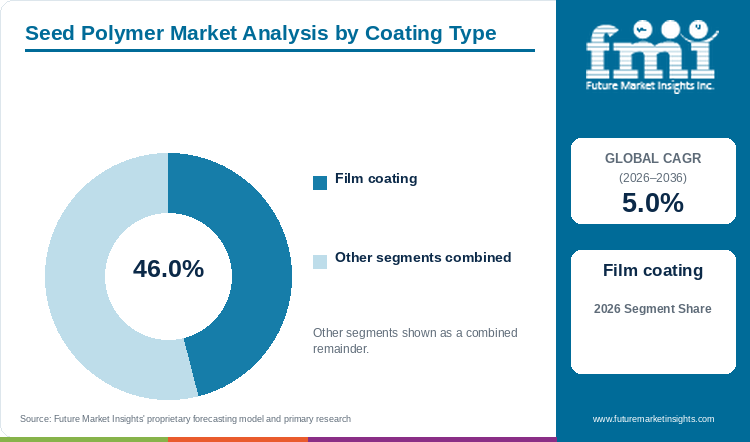
Film coating holds 46.0% of the Seed Polymer Market by coating type in 2026.
A film coat adds little weight, holds treatments on the seed and improves flow through the planter. It suits large field crops. BASF launched Flo Rite Pro 02 in November 2023 as a plantability polymer for corn that improves seed flow and spacing. Its seed coating range sits alongside colour coats and binders used by commercial treaters in the wider seed coating material market. The Amulix range offers biodegradable film coatings and binders that can be predominantly formulated with bio-based ingredients. Pelleting, encrusting, gels and priming hold the remaining 54.0%. Pelleting is used for small or irregular seed such as sugar beet and vegetables. Germains describes itself as a seed technology supplier to sugar beet, vegetable and flower seed producers. It introduced one of the first sugar beet seed pellet technologies. These coatings use more material per seed and cost more, so they stay concentrated in higher-value crops.
Table 2: Coating Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Film coating | 46.0% |
| All Other Segments Combined Share | 54.0% |
Source: Future Market Insights analysis of the seed polymer market, 2026.
Why do Synthetic polymers lead by Polymer Origin in the Seed Polymer Market in 2026?
Synthetic polymers hold 78.0% of the Seed Polymer Market by polymer origin in 2026.
Established synthetic grades have long track records for adhesion, dust control and compatibility with fungicides and insecticides. Seed companies therefore keep them in approved recipes. BASF describes its Flo Rite products as compatible with major fungicides, insecticides and nematicides. Switching a polymer means testing each treatment recipe again, so the change happens slowly. Each product is counted once in this split. A polymer that is bio-based, biodegradable or both counts in the second group, and all other polymers count as synthetic. Bio-based and biodegradable polymers, tracked in the biodegradable polymers market, hold the remaining 22.0%. The EU restriction exempts biodegradable polymers, so seed companies can use them after the 2028 and 2031 dates.
Table 3: Polymer Origin, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Synthetic polymers | 78.0% |
| All Other Segments Combined Share | 22.0% |
Source: Future Market Insights analysis of the seed polymer market, 2026.
Why do Cereals and grains lead by Crop Type in the Seed Polymer Market in 2026?
Cereals and grains hold 34.0% of the Seed Polymer Market by crop type in 2026.
Corn covers 95.3 million acres in the United States in 2026. Film coating helps treated seed flow through high-speed planters. Large acreage and standardised treatment recipes favour repeat orders of the same polymer. Oilseeds, vegetables and fruits, pulses and flowers hold the remaining 66.0%. Oilseeds are backed by 85.4 million acres of United States soybean and 49.3 million hectares in Brazil. Vegetable and flower seed use fewer hectares but more polymer per seed because of pelleting. Their value share is therefore higher than their area share.
Table 4: Crop Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Cereals and grains | 34.0% |
| All Other Segments Combined Share | 66.0% |
Source: Future Market Insights analysis of the seed polymer market, 2026.
What are the key drivers, restraints and opportunities?
Driver
Treated seed demand in large field crops. Large planted areas keep treated and coated seed in demand. CONAB projects Brazilian grain output for 2026/27 at 367.1 million tonnes, up 1.4%, on 2.3% more planted area. Each hectare planted with treated seed needs binders and flow polymers, so area growth lifts polymer demand.
Reformulation to meet European rules. In-scope seed with non-degradable synthetic coatings can be sold only until 17 October 2028. The date is 17 October 2031 when the coating holds plant protection products. Seed companies with such coatings must requalify recipes with biodegradable or exempt binders before those dates.
Restraint
Regulatory uncertainty over treated seed. Defra refused emergency authorisation of a thiamethoxam seed treatment for sugar beet in England for 2025, the first refusal in five years. In the United States, EPA exempts treated seed from pesticide registration. In September 2026 environmental groups asked the Ninth Circuit to revive their challenge to that exemption. States such as Minnesota and Vermont are moving ahead on their own.
Qualification cost of new polymers. Seed companies must retest each recipe when a polymer changes. That takes a season or more and slows switching from approved synthetic grades. Biodegradable candidates such as those from Michelman still need testing before broader validation.
Opportunity
Biodegradable binders. Biodegradable polymers fall outside the EU restriction, so seed companies can use them after the 2028 and 2031 dates. Covestro states that its Amulix S F6320 RED ingredients qualify for exemption from the regulation. Suppliers that qualify early gain time with seed companies that must requalify their recipes.
Seed exports from India. Exports rose 34.5% to 123.82 thousand tonnes in fiscal 2025 to 2026. FMI expects higher export volumes to widen demand for coated seed within the seed treatment materials market. Polymer suppliers with local technical service can capture that demand.
Seed Polymer Market by Country (2026 to 2036)
Table 5: Seed Polymer Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
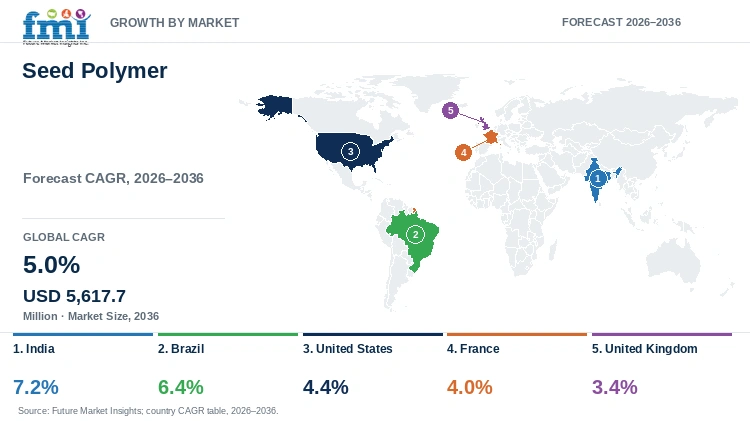
| India | 7.2% |
| Brazil | 6.4% |
| United States | 4.4% |
| France | 4.0% |
| United Kingdom | 3.4% |
Source: Future Market Insights analysis of the seed polymer market, 2026.
India
India starts from a small base of treated and coated seed. Public seed infrastructure and export growth support expansion. The projected CAGR of 7.2% for 2026 to 2036 is the highest among the profiled countries.
India is a net seed exporter by weight and by value. Exports reached 123.82 thousand tonnes in fiscal 2025 to 2026, up 34.5% from the year before. Imports of 31.84 thousand tonnes were worth INR 17.6 billion, against INR 30.2 billion for exports. A tonne of imported seed is therefore worth more than twice a tonne of exported seed. Polymer cost is a small share of high-priced seed, so coating is easier to price in.
Production and testing rest on 229 Seed Hubs, 384 breeder seed production centres and 178 notified laboratories. A traceability portal covers certification, inventory and distribution, which supports quality assurance. Import and export approvals run through digital platforms since the EXIM Committee was disbanded in October 2024. The government promotes seed exports through the OECD Seed Schemes, the ISTA framework and NABL accreditation of seed testing laboratories. It also funds seed processing, storage and testing facilities. Exporters must meet buyers' specifications for flow and germination. FMI expects polymer suppliers with documented test results to qualify more easily with those exporters. Supply is shared between 17 State Seed Corporations and private firms.
Brazil
Brazil combines large area with high treatment use. CONAB's first survey for 2026/27 puts soybean area at 49.3 million hectares, up 1.4%, and output at 181.6 million tonnes. Area growth is modest. Industrial seed treatment is already common on soybean and corn, so the CAGR is held to 6.4% from 2026 to 2036.
Hybrid species such as corn reach commercial seed use near 90%, so growth there depends on treatment. Outside corn, industrial treatment stands near 40% of demand because treated seed stores poorly. Among industrially treated soybean seed, 93.5% receives insecticide and 92.0% fungicide. Polymer binders hold those actives on the seed, so treatment growth carries polymer volume with it. Soybean industrial treatment was worth BRL 1.19 billion in 2021 and is projected above BRL 1.76 billion for 2025/26. That is about 48% above the 2021 value. Seed volume adds little, rising 1.9% from 48.3 million bags in 2025/26 to 49.2 million in 2026/27. Value growth therefore comes from treatment.
Industry estimates cited in the yearbook show pirate seed on 11% of Brazilian soybean area. Uncertified seed, saved or pirated, is valued at BRL 9 billion for 2025/26. Moving that volume into certified channels would widen the base for factory treatment. CONAB projects corn area across its three crops at 23.7 million hectares for 2026/27, up 4.9%. That adds seed that needs film coating and flow polymers, which supports the 6.4% CAGR.
United States
Mature acreage and unsettled federal rules on treated seed hold United States growth to a 4.4% CAGR from 2026 to 2036.
Corn area fell 3% to 95.3 million acres while soybean area rose 5% to 85.4 million acres. The two crops together cover 180.7 million acres. The corn decline and the soybean gain largely offset each other, so volume growth is limited and value growth rests on formulation. A plantability polymer for corn seed, launched in November 2023, shows where suppliers seek price gains.
EPA received extensive comments on an October 2023 notice for treated seed. EPA exempts treated seed from pesticide registration. In September 2026 environmental groups asked the Ninth Circuit to revive their challenge to that exemption. New Jersey's neonicotinoid ban does not cover seed, and it awaits the federal decision. New York signed its Birds and Bees Protection Act on December 22, 2023. From January 1, 2029 it bars sale or use of neonicotinoid-treated corn, soybean and wheat seed without a waiver. Waivers last two years and require integrated pest management certification and a pest risk assessment. The law targets the insecticide, so FMI expects film-coat demand to shift to other actives, not disappear. Seed companies selling nationally therefore face state rules that differ from the federal exemption.
France
France is Europe's main seed exporter. Its seed sector reached turnover of EUR 3.9 billion in 2024-2025, with 57.0% exported to 160 countries. Coatings on seed sold into the Union fall under the EU microplastics restriction when they meet its scope criteria. Seed multiplication area is stable, which holds growth to a 4.0% CAGR from 2026 to 2036.
The European Union accounts for 68% of French seed and plant exports, led by Germany and Spain. The restriction therefore reaches the buyers of most French export seed as the 2028 and 2031 dates pass. SEMAE reports work on alternatives to microplastics in film coatings for flax and hemp. French seed companies spend about 11% of turnover on research.
Exports rose 10% in value in 2024 to 2025, and the provisional trade surplus was EUR 1.26 billion. Seed multiplication area reached 380,411 hectares in 2025, up 1% on 2024. French beet growers also work without neonicotinoids and have no effective control for the SBR disease. A five-year EUR 7.5 million project is testing resistant varieties, rotations and other options. FMI expects beet pelleting demand to depend on area and alternative actives, not neonicotinoid loads. Pellet suppliers to French beet growers therefore need recipes that carry other actives or none. Coating suppliers to French seed houses also need biodegradation data that export buyers in the Union can check.
United Kingdom
The United Kingdom has the slowest forecast growth among the profiled countries. Defra refused emergency use of a neonicotinoid seed treatment on sugar beet for 2025. That leaves fewer approved treatments and reduces the polymer needed for sugar beet pelleting. A small arable base and a shrinking beet crop support a 3.4% CAGR from 2026 to 2036.
Sugar beet area fell 8.6% to 94 thousand hectares in 2025, and production fell 7.1% to 7.3 million tonnes. Value fell 22% to GBP 286 million, driven by lower volume and a 16% lower price. Lower grower returns weigh on planting decisions, and virus yellows can cut yields by up to 80%. NFU Sugar says the crop now carries much higher risk after the 2025 refusal. Defra described the decision as the first refusal in five years.
Cereal area rose 1.6% to 3,013 thousand hectares in 2025, with wheat up 9.1% and barley down 9.5%. Wheat gained while barley lost, so the cereal base is broadly flat and offers no volume lift. Gene-edited resistant varieties may need up to eight years to reach fields. Growers therefore have no resistant variety for most of the forecast period. Sugar beet seed suppliers in the United Kingdom depend on approved treatments, so pellet volume stays tied to a shrinking crop.
Who are the notable companies in the Seed Polymer Market?
Notable companies in the Seed Polymer Market include Covestro, Croda, Michelman, Germains and BASF.
Documented biodegradation separates seed polymer suppliers as the EU restriction nears its 2028 and 2031 dates. Covestro AG states that Amulix S F6320 RED ingredients biodegrade by 60.0% or more within 60 days under OECD 301F. Michelman, Inc. reports biodegradable candidates in refinement ahead of wider validation. BASF SE launched the Flo Rite Pro 02 plantability polymer for corn seed in November 2023. Each polymer change needs new tests on the recipe, so suppliers with documented test results shorten approval time.
Seed enhancement specialists add services on top of the polymer, so reach and laboratory capacity separate them. Incotec, part of Croda International Plc, opened renewed laboratories in Holambra, Brazil in August 2026. It also completed an upgrade of its Tianjin facility in China. The site brings Asia-Pacific research, production and sales teams into one location. Germains Seed Technology focuses on sugar beet, vegetable and flower seed and describes one of the first sugar beet seed pellet technologies. Pelleting is used for small or irregular seed, so these specialists depend on higher-value crops. In the United Kingdom, Defra's refusal of a neonicotinoid seed treatment on sugar beet reduces the polymer needed for pelleting.
Large crop science and seed groups decide which polymers enter approved recipes. Bayer AG reported Crop Science sales of EUR 21.6 billion in 2025. They rose 1.1% on a currency and portfolio adjusted basis, with corn seed and traits as the main growth driver. Limagrain's Hazera started an environmentally focused seed treatment programme in March 2025. Area growth lifts polymer demand, as CONAB projects Brazilian grain area up 2.3% for 2026/27. Groups that build their own low-impact recipes set the specifications that polymer suppliers must meet.
Key Developments in the Seed Polymer Market
- In 2026, Incotec (a Croda International Plc brand) completed the upgrade of its Tianjin facility in China. The site consolidates China and Asia-Pacific research, production, sales and marketing teams in one location, strengthening the company’s ability to serve corn, soya, sunflower and cotton seed customers across the region [24].
- In April 2026, Covestro AG published product information for Amulix S F6320 RED, a biodegradable film coating for corn seed. The company states its ingredients biodegrade by 60.0% or more within 60 days under the OECD 301F test, qualifying them for exemption from the EU microplastics restriction [21].
- In March 2025, Hazera announced a new seed treatment programme focused on environmental performance. The programme introduces microplastic-free film coating and novel biological plant protection solutions, available across Hazera’s distribution network spanning more than 130 countries [26].
Key Players in the Seed Polymer Market
- BASF SE
- Croda International Plc
- Covestro AG
- Michelman, Inc.
- Germains Seed Technology
- Bayer AG
- Limagrain (Hazera)
Seed Polymer Market Report Scope
Table 6: Seed Polymer Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Polymer-based binders, film coats, gels and pelleting materials applied to seed to carry treatments, improve flow and protect germination, valued at manufacturer selling prices. Seed treatment active ingredients, colourants sold without polymer and seed itself are excluded. |
| Coating Type | Film coating; Pelleting; Encrusting; Gels and priming |
| Polymer Origin | Synthetic polymers (fossil-based and non-degradable); Bio-based and biodegradable polymers (bio-based, biodegradable or both). Each product is assigned to one group |
| Crop Type | Cereals and grains; Oilseeds; Vegetables and fruits; Pulses; Flowers and ornamentals |
| Regions and profiled countries | North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa. Profiled countries: India, Brazil, United States, France, United Kingdom |
| Companies covered | BASF SE; Croda International Plc; Covestro AG; Michelman, Inc.; Germains Seed Technology; Bayer AG; Limagrain (Hazera) |
| Quantitative Units | USD million |
Seed Polymer Market by Segments
Seed Polymer Market segmented by Coating Type:
- Film coating
- Pelleting
- Encrusting
- Gels and priming
Seed Polymer Market segmented by Polymer Origin:
- Synthetic polymers
- Bio-based and biodegradable polymers
Seed Polymer Market segmented by Crop Type:
- Cereals and grains
- Oilseeds
- Vegetables and fruits
- Pulses
- Flowers and ornamentals
Seed Polymer Market by Region
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- India
- Brazil
- United States
- France
- United Kingdom
Research Sources and Bibliography
- [1] European Commission, Access2Markets. (2023, October 17). Restriction of microplastics in the EU. https://trade.ec.europa.eu/access-to-markets/ko-kr/news/restriction-microplastics-eu-17-october-2023
- [2] Covestro. Biodegradable seed coatings (Amulix binders). https://solutions.covestro.com/en/highlights/articles/theme/applications/biodegradable-seed-coatings
- [3] Zhang, G., Michelman. (2026, January). Michelman's Sustainable Shift: From Synthetic Seed Coatings to Biodegradable Innovation. Seed World, January 2026, p. 25. https://seedworld.com/cdn/flipbooks/US/flipbook_january2026/inc/html/27.html
- [4] AgroPages. Hazera environmentally focused seed treatment programme (Limagrain). https://news.agropages.com/News/print-53301.htm
- [5] SEMAE. (2026, February 18). La filiere francaise des semences et plants au service de la terre. https://www.semae.fr/uploads/semae-fr_publication_20260218_D1922_la-filiere-francaise-des-semences-et-plants-au-service-de-la-terre.pdf
- [6] Oklahoma Farm Report. (2023, November 28). BASF introduces Flo Rite Pro 02 plantability polymer. https://www.oklahomafarmreport.com/2023/11/28/basf-introduces-flo-rite-pro-02-plantability-polymer/
- [7] BASF Agricultural Solutions. Seed coatings. https://agriculture.basf.com/global/en/business-areas/crop-protection-and-seeds/seed-treatment/seed-coatings.html
- [8] Wageningen University & Research. Germains seed technology. https://www.wur.nl/en/article/Germains-seed-technology.htm
- [9] Indian Chemical News. Bayer hits 2025 targets but warns turnaround still incomplete. https://www.indianchemicalnews.com/general/bayer-hits-2025-targets-but-warns-turnaround-still-incomplete-29577
- [10] UK Government (Defra). Pesticide emergency authorisation denied for 2025 to protect bees. https://www.gov.uk/government/news/pesticide-emergency-authorisation-denied-for-2025-to-protect-bees
- [11] AAPCO. (2026, June). Region 2 June Pre-SFIREG report. https://aapco.org/wp-content/uploads/2026/06/Region-2-June-Pre-SFIREG-report.pdf
- [12] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, June 30). Corn planted acreage down 3% from 2025, soybean acreage up 5% from last year. https://www.nass.usda.gov/Newsroom/2026/06-30-2026.php
- [13] ABRASEM, Associacao Brasileira de Sementes e Mudas. (2025, September). Anuario ABRASEM 2025. https://www.abrasem.com.br/wp-content/uploads/2025/09/Anuario-Abrasem-2025-com-capa_compactado.pdf
- [14] Franca-Neto, J. B. et al., Embrapa Soja. (2025). Adocao do tratamento de sementes de soja na industria. https://www.embrapa.br/en/busca-de-publicacoes/-/publicacao/1179179/adocao-do-tratamento-de-sementes-de-soja-na-industria
- [15] Press Information Bureau, Government of India. (2026, July 21). Initiatives to Strengthen Seed Sector. https://www.pib.gov.in/PressReleasePage.aspx?PRID=2287250
- [16] SEMAE. (2025, December 11). Malgre les defis, la filiere francaise des semences et plants affiche sa resilience et consolide son leadership mondial en 2025. https://www.semae.fr/communique/malgre-les-defis-la-filiere-francaise-des-semences-et-plants-affiche-sa-resilience-et-consolide-son-leadership-mondial-en-2025/
- [17] Department for Environment, Food and Rural Affairs. (2026). Agriculture in the United Kingdom 2025, Chapter 7: Crops. https://www.gov.uk/government/statistics/agriculture-in-the-united-kingdom-2025/chapter-7-crops
- [18] NFU Sugar. (2026, February 25). NFU26 Sugar: resilience in a post-neonicotinoid world. https://www.nfuonline.com/news/nfu26-sugar-resilience-in-a-post-neonicotinoid-world/
- [19] Cornell Integrated Pest Management. (2026). About the Birds and Bees Protection Act. https://cals.cornell.edu/integrated-pest-management/research-initiatives/current-projects/about-birds-and-bees-protection-act
- [20] European Commission. (2025). REACH restriction of synthetic polymer microparticles (Entry 78 of Annex XVII REACH, as introduced by Commission Regulation (EU) 2023/2055): Explanatory Guide, Version 1. https://webgate.ec.europa.eu/circabc-ewpp/d/d/workspace/SpacesStore/e094e675-7785-4b92-b030-a91a6bbdae7d/download
- [21] Covestro. (2026, April 29). Biodegradable, high performance corn film coating (Amulix S F6320 RED). https://solutions.covestro.com/en/highlights/articles/stories/2026/amulix-biodegradable-corn-film-coating
- [22] Agencia Gov, via Companhia Nacional de Abastecimento (Conab). (2026, October 15). Conab estima safra de graos 2026/27 acima de 367 milhoes de toneladas. https://agenciagov.ebc.com.br/noticias/202610/primeiro-levantamento-da-safra-de-graos-2026-27-estima-producao-acima-de-367-milhoes-de-toneladas
- [23] HortiDaily. (2026, September 10). Incotec opens new and updated lab facilities in Brazil. https://www.hortidaily.com/article/9871393/incotec-opens-new-and-updated-lab-facilities-in-brazil/
- [24] Incotec. (2026). Incotec strengthens seed enhancement in China. https://www.incotec.com/en-gb/news-and-media/news-and-opinion/seed-enhancement-china-tianjin-facility-upgrade
- [25] Capital Press. (2026, September 29). 9th Circuit hears arguments over neonicotinoid-coated seeds. https://capitalpress.com/2026/09/29/9th-circuit-hears-arguments-over-neonicotinoid-coated-seeds/
- [26] Hazera. (2025, March 13). Hazera Leads the Way in Sustainable Seed Treatment. https://hazera.com/hazera-leads-the-way-in-sustainable-seed-treatment/
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Coating Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Coating Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Coating Type, 2026 to 2036
- Film coating
- Pelleting
- Encrusting
- Gels and priming
- Y-o-Y Growth Trend Analysis By Coating Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating Type, 2026 to 2036
- Global Market Analysis and Forecast, By Polymer Origin, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Polymer Origin, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Polymer Origin, 2026 to 2036
- Synthetic polymers
- Bio-based and biodegradable polymers
- Y-o-Y Growth Trend Analysis By Polymer Origin, 2021 to 2025
- Absolute $ Opportunity Analysis By Polymer Origin, 2026 to 2036
- Global Market Analysis and Forecast, By Crop Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Crop Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Crop Type, 2026 to 2036
- Cereals and grains
- Oilseeds
- Vegetables and fruits
- Pulses
- Flowers and ornamentals
- Y-o-Y Growth Trend Analysis By Crop Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Crop Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- South Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Oceania Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Middle East Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Brazil
- United States
- France
- United Kingdom
- By Coating Type
- By Polymer Origin
- By Crop Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating Type
- By Polymer Origin
- By Crop Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Type
- By Polymer Origin
- By Crop Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Type
- By Polymer Origin
- By Crop Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Type
- By Polymer Origin
- By Crop Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Type
- By Polymer Origin
- By Crop Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating Type
- By Polymer Origin
- By Crop Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Coating Type
- By Polymer Origin
- By Crop Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BASF SE
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Croda International Plc
- Covestro AG
- Michelman, Inc.
- Germains Seed Technology
- Bayer AG
- Limagrain (Hazera)
- BASF SE
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 13: Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Europe Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 15: Europe Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 16: Europe Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 19: East Asia Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 20: East Asia Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 21: South Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: South Asia Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 23: South Asia Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 24: South Asia Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 25: Oceania Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Oceania Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 27: Oceania Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 28: Oceania Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 29: Middle East Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 31: Middle East Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 32: Middle East Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
- Table 33: Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 34: Africa Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 35: Africa Market Value (USD Million) Forecast by Polymer Origin, 2021 to 2036
- Table 36: Africa Market Value (USD Million) Forecast by Crop Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Coating Type
- Figure 6: Global Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Polymer Origin
- Figure 9: Global Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Crop Type
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: South Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Oceania Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 24: North America Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 25: North America Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 26: North America Market Attractiveness Analysis by Coating Type
- Figure 27: North America Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 28: North America Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 29: North America Market Attractiveness Analysis by Polymer Origin
- Figure 30: North America Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 31: North America Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 32: North America Market Attractiveness Analysis by Crop Type
- Figure 33: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Latin America Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 35: Latin America Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 36: Latin America Market Attractiveness Analysis by Coating Type
- Figure 37: Latin America Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 38: Latin America Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 39: Latin America Market Attractiveness Analysis by Polymer Origin
- Figure 40: Latin America Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 41: Latin America Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 42: Latin America Market Attractiveness Analysis by Crop Type
- Figure 43: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 44: Europe Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 45: Europe Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 46: Europe Market Attractiveness Analysis by Coating Type
- Figure 47: Europe Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 48: Europe Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 49: Europe Market Attractiveness Analysis by Polymer Origin
- Figure 50: Europe Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 51: Europe Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 52: Europe Market Attractiveness Analysis by Crop Type
- Figure 53: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 54: East Asia Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 55: East Asia Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 56: East Asia Market Attractiveness Analysis by Coating Type
- Figure 57: East Asia Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 58: East Asia Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 59: East Asia Market Attractiveness Analysis by Polymer Origin
- Figure 60: East Asia Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 61: East Asia Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 62: East Asia Market Attractiveness Analysis by Crop Type
- Figure 63: South Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 64: South Asia Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 65: South Asia Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 66: South Asia Market Attractiveness Analysis by Coating Type
- Figure 67: South Asia Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 68: South Asia Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 69: South Asia Market Attractiveness Analysis by Polymer Origin
- Figure 70: South Asia Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 71: South Asia Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 72: South Asia Market Attractiveness Analysis by Crop Type
- Figure 73: Oceania Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: Oceania Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 75: Oceania Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 76: Oceania Market Attractiveness Analysis by Coating Type
- Figure 77: Oceania Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 78: Oceania Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 79: Oceania Market Attractiveness Analysis by Polymer Origin
- Figure 80: Oceania Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 81: Oceania Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 82: Oceania Market Attractiveness Analysis by Crop Type
- Figure 83: Middle East Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 84: Middle East Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 85: Middle East Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 86: Middle East Market Attractiveness Analysis by Coating Type
- Figure 87: Middle East Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 88: Middle East Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 89: Middle East Market Attractiveness Analysis by Polymer Origin
- Figure 90: Middle East Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 91: Middle East Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 92: Middle East Market Attractiveness Analysis by Crop Type
- Figure 93: Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 94: Africa Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 95: Africa Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 96: Africa Market Attractiveness Analysis by Coating Type
- Figure 97: Africa Market Value Share and BPS Analysis by Polymer Origin, 2026 and 2036
- Figure 98: Africa Market Y-o-Y Growth Comparison by Polymer Origin, 2026-2036
- Figure 99: Africa Market Attractiveness Analysis by Polymer Origin
- Figure 100: Africa Market Value Share and BPS Analysis by Crop Type, 2026 and 2036
- Figure 101: Africa Market Y-o-Y Growth Comparison by Crop Type, 2026-2036
- Figure 102: Africa Market Attractiveness Analysis by Crop Type
- Figure 103: Global Market - Tier Structure Analysis
- Figure 104: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Seed Polymer Market in 2026?
FMI estimates the market at USD 3,448.8 million in 2026, up from USD 3,284.5 million in 2025. It is forecast to reach USD 5,617.7 million by 2036 at a 5.0% CAGR.
Which coating type leads the Seed Polymer Market in 2026?
Film coating leads by coating type with 46.0% in 2026. Pelleting, encrusting, gels and priming together hold 54.0%.
Which polymer origin and crop type lead?
Synthetic polymers hold 78.0% by polymer origin and cereals and grains hold 34.0% by crop type in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
India has the highest forecast CAGR among the profiled countries at 7.2% during 2026 to 2036, followed by Brazil at 6.4%.
How does European regulation affect seed polymer suppliers?
Regulation (EU) 2023/2055 restricts intentionally added synthetic polymer microparticles and has applied since 17 October 2023 [1]. In-scope seed coated with plant protection products can be sold until 17 October 2031 [20]. Other in-scope coated seed can be sold until 17 October 2028 [20]. Biodegradable polymers fall outside the restriction [20].
Which companies are covered in the Seed Polymer Market?
BASF, Croda, Covestro, Michelman, Germains Seed Technology, Bayer and Limagrain are covered.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
