

- Market Size (2026)
- USD 19.5 Bn
- Forecast (2036)
- USD 29.7 Bn
- CAGR (2026 to 2036)
- 4.3%
How big is the Shea Butter Market in 2026?
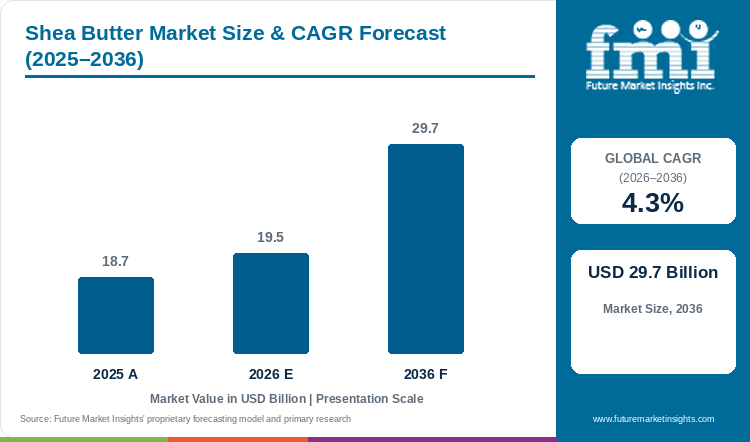
The shea butter market is forecast to register a CAGR of 4.3% through 2036. Revenue increases from USD 18.7 billion in 2025 to USD 19.5 billion in 2026 before reaching USD 29.7 billion by 2036.
Replacing petrochemical petrolatum and high-cost cocoa butter in dermal emulsions and chocolate coatings requires a botanical lipid with elevated unsaponifiable triterpenes and sharp stearic-oleic melting behavior. Global shea butter revenue progresses from USD 18.7 billion in 2025 to USD 19.5 billion in 2026 and reaches a projected USD 29.7 billion by 2036 at a 4.3% CAGR, creating USD 10.2 billion in incremental opportunity, as per FMI. In May 2025, the Global Shea Alliance reported in its annual industry review that West African origin crushing and refined export volumes exceeded 350,000 metric tons as international cosmetic and confectionery buyers expanded direct parklands sourcing [1]. Formulators incorporate shea fractions into whipped body butters while chocolate refiners substitute shea stearin for natural cocoa butter, placing cosmetic-grade butter at 46.0% of grade demand in 2026.
Key Market Trends & Insights
- By grade: Cosmetic-grade butter led the market with a share of 46.0% in 2026, driven by its five-to-nine percent unsaponifiable fraction containing cinnamic acid esters and phytosterols that repair dry skin barriers.
- By application sector: Cosmetics and personal care accounted for 61.0% of revenue in 2026, as dermo-cosmetic laboratories and textured haircare brands replace mineral oils with plant lipids.
- By source nature: Conventional source represented 72.0% of demand in 2026, underpinned by large-scale industrial kernel collection for solvent-free stearin and olein fractionation.
Regional Highlights
- Fastest-growing evaluated country: France (5.2% CAGR, 2026 to 2036).
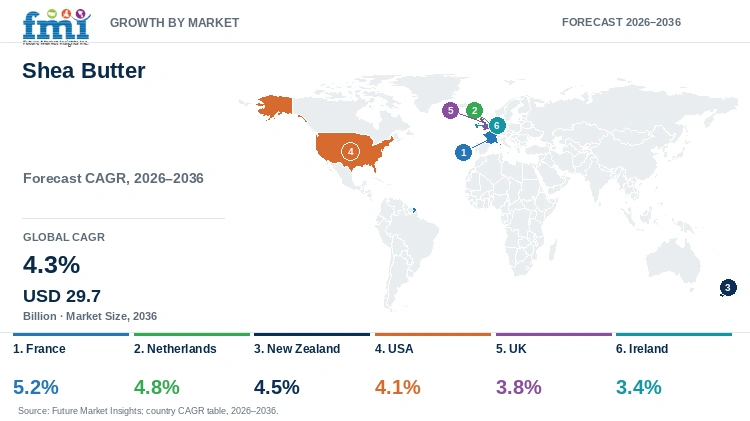
- By country: The Netherlands (4.8%), New Zealand (4.5%), and the USA (4.1%) follow, while the UK (3.8%) and Ireland (3.4%) record steady expansion across evaluated markets.
Market Size & Forecast
Table 1: Market Size and Forecast for the Shea Butter Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 18.7 billion |
| Estimated Market Size in 2026 | USD 19.5 billion |
| Projected Market Size by 2036 | USD 29.7 billion |
| CAGR, 2026 to 2036 | 4.3% |
| Added Revenue, 2026 to 2036 | USD 10.2 billion |
Phased raw shea nut export bans across Ghana, Burkina Faso, and Mali are forcing European and North American lipid refiners to procure origin-pressed crude butter rather than uncrushed kernels. In June 2026, Cosmetics Europe reported on its Our industry portal that European cosmetics and personal care retail sales reached EUR 110 billion in 2025 (led by Germany at EUR 18.0 billion, the United Kingdom at EUR 14.7 billion, and France at EUR 14.5 billion), with skincare accounting for EUR 32.3 billion and haircare EUR 20.3 billion alongside EUR 29.8 billion in exports [2]. Meanwhile, Dutch specialty fat terminals in Rotterdam and the Zaanstreek corridor fractionate imported crude butter into confectionery stearin and cosmetic olein. Oleochemical suppliers are qualifying cold-pressed botanical emollients and enzymatic stearin fractions that meet European deforestation-free and polycyclic aromatic hydrocarbon purity thresholds.
Kernel Extraction Yield and Stearin Fractionation Economics
Table 2: Kernel Crushing, Butter Extraction, and Stearin Fractionation Indicators for the Shea Butter Market (USD billion, thousand metric tons, and extraction percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 18.7 | 19.5 | 29.7 |
| Harvested dry shea kernel trade & crushing volume (thousand metric tons) | 820 to 890 | 850 to 920 | 1,180 to 1,290 |
| Mechanical expeller crude butter yield from dry kernels (%) | 42.0% to 46.0% | 42.5% to 46.5% | 44.0% to 48.0% |
| High-melting stearin yield from crude shea butter (%) | 45.0% to 50.0% | 46.0% to 51.0% | 48.0% to 54.0% |
Operational note: Extraction yields reflect industrial mechanical screw-press expellers operating in Ghana, Côte d'Ivoire, Nigeria, and European port refineries. Stearin fractionation yields reflect solvent-free crystallization and enzymatic separation into cocoa butter equivalent (CBE) stearin and cosmetic liquid olein.
Per Capita & Cosmetic Formulation Sizing
Botanical lipid conditioning has become a baseline requirement in prestige skincare, textured hair masks, and palm-free chocolate coatings as brands phase out synthetic hydrocarbons. Formulating barrier repair creams requires a fat matrix that stays solid in the jar at room temperature yet melts rapidly between 32 and 38 degrees Celsius upon skin contact. Fractionated shea stearin additionally provides the exact symmetrical triglyceride crystallization needed to prevent chocolate bloom in warm climates, so multinational personal care houses and confectionery refiners compete directly for West African parkland harvests.
Table 3: Per Capita and Formulation Spending Indicators for the Shea Butter Market (USD and population in billions), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Global spend per capita (USD) | 2.27 | 2.35 | 3.32 |
| Spend per 1,000 people (USD) | 2,272.2 | 2,349.4 | 3,318.4 |
| Average inclusion rate in dermal body butters (% by weight) | 8.0% to 20.0% | 8.5% to 22.0% | 10.0% to 25.0% |
Table 4: Segment Revenue Exposure and Industry Benchmarks for the Shea Butter Market (USD billion, percentages, and EUR billion), mixed reporting years from 2025 to 2026
| Metric | Value | Operational Basis |
|---|---|---|
| Market size, 2026 | USD 19.5 billion | FMI report estimate |
| Cosmetic-grade butter revenue, 2026 | USD 9.0 billion | 46.0% share of grade category |
| Cosmetics and personal care revenue, 2026 | USD 11.9 billion | 61.0% share of application sector |
| European cosmetics & personal care retail pool (2025) | EUR 110.0 billion | Cosmetics Europe 2026 industry report |
Analyst Perspective
"Elevated cocoa butter prices and clean-label skincare formulas give refined shea stearin and unrefined cosmetic butter strong commercial momentum. West African raw nut export restrictions still compel processors to invest in origin crushing mills and cooperative traceability."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the shea butter market segmented?
The shea butter market is segmented by grade, application sector, source nature, and region. In 2026, cosmetic-grade butter is projected to account for 46.0% of grade revenue, cosmetics and personal care 61.0% of application sector demand, and conventional source 72.0% of source nature sales.
By grade: Cosmetic-grade butter, food-grade and confectionery butter, and pharmaceutical-grade butter.
By application sector: Cosmetics and personal care, confectionery and bakery fats, and pharmaceutical formulations.
By source nature: Conventional source and certified organic and fair trade.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why Does Cosmetic-Grade Butter Lead the Shea Butter Market by Grade?
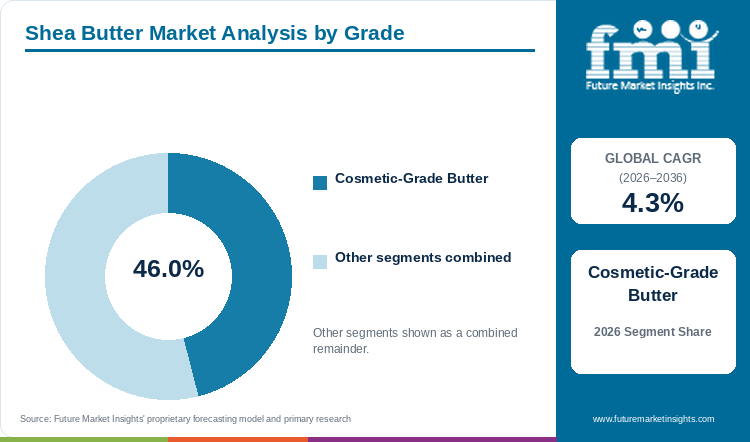
By grade, cosmetic-grade butter is estimated to hold 46.0% in 2026, driven by high unsaponifiable triterpene lipid content.
Table 5: Grade Share for the Shea Butter Market (percentage share), 2026
| Grade | Share (2026) |
|---|---|
| Cosmetic-Grade Butter | 46.0% |
| Other Segments Combined | 54.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Grade Leadership and Market Growth for the Shea Butter Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.3% |
| Leading Segment | Cosmetic-Grade Butter |
Cosmetic-grade butter commands the largest grade share because cold-pressed and clay-bleached cosmetic grades preserve five to nine percent bioactive unsaponifiable matter, far exceeding the under-one-percent unsaponifiable fraction found in avocado, soy, or almond oils. Because unrefined and gently deodorized cosmetic grades retain triterpene cinnamates, lupeol, and phytosterols, formulators use them as bioactive barrier lipids in body creams, lip balms, and hair masks. Industrial bleaching, neutralization, and dry fractionation standardize that variable wild-harvest triglyceride profile while lowering free fatty acid levels below 0.15% and eliminating smoky latex odors so formulators can run high-speed chocolate tempering and cosmetic emulsification lines without batch rejection.
- Cosmetic-grade butter is estimated to hold 46.0% of grade revenue in 2026, supported by high bioactive unsaponifiable lipid concentrations and superior dermal barrier occlusion.
- In February 2025, a multi-locus genome-wide association study across 122 Vitellaria paradoxa trees by Attikora et al. published in BMC Genomics demonstrated that raw kernel fat content varies from 36% to 58% (mean 50%) with stearic acid averaging 38.76% and oleic acid averaging 51.26% alongside a -0.98 inverse correlation [3].
What Places Cosmetics and Personal Care Ahead Within the Application Sector Category?
Within application sector, cosmetics and personal care is projected to command 61.0% share in 2026, reflecting skin-melting emollient performance.
Cosmetics and personal care represents the primary demand center because shea triglycerides melt cleanly between 32 and 38 degrees Celsius upon contact with human skin, delivering non-greasy occlusion that synthetic mineral oils cannot match. Formulators across Europe and North America incorporate five to twenty percent shea butter into body lotions, hand creams, sunscreens, and textured hair conditioners.
- Cosmetics and personal care is projected to capture 61.0% of application sector demand in 2026, underpinned by widespread petrolatum replacement across skincare and textured haircare lines.
- In June 2026, Cosmetics Europe's European Consumer Perception Study (conducted with IFOP across more than 8,000 citizens) found that 72% of consumers rated daily skincare and body care products as essential to quality of life and skin health [4].
How Does Conventional Source Maintain the Largest Share by Source Nature?
Conventional source is anticipated to account for 72.0% of source nature demand in 2026, underpinned by industrial stearin fractionation.
Conventional source origin accounts for the majority of commercial turnover because industrial oilseed crushers and confectionery fat refiners require tens of thousands of metric tons of wild-gathered kernels across Ghana, Nigeria, Côte d'Ivoire, and Burkina Faso to keep continuous expeller presses running. While wild shea trees grow naturally without synthetic pesticides, certifying millions of dispersed smallholder trees under formal organic audit protocols adds substantial inspection overhead. Industrial refiners convert conventional crude butter into cocoa butter equivalents and emollient esters in personal care for mass-market lotions and soaps. Rising luxury beauty demand for audited women's cooperative provenance is still lifting the certified organic and fair-trade segment at a faster 5.1% CAGR through 2036.
- Conventional source is anticipated to account for 72.0% of source nature revenue in 2026 on the strength of high-volume kernel aggregation for confectionery stearin and mass-market personal care refining.
- In April 2025, the International Cocoa Organization noted that multi-year cocoa bean supply deficits accelerated confectionery processor contracting for conventional shea stearin under EU 5% vegetable-fat chocolate allowances [5].
What are the drivers, restraints, and opportunities in the shea butter market?
In the shea butter market, petrochemical emollient replacement and cocoa butter substitution will continue to support demand, Sahel harvest variability and raw kernel export bans will constrain supply, and solvent-free enzymatic stearin fractionation is expected to expand margins through 2036.
- Driver: Clean-label replacement of synthetic petrolatum in skincare alongside elevated cocoa butter prices in chocolate manufacturing continues to expand demand for refined shea fractions.
- Restraint: Wild parkland rainfall fluctuations, bushfire flower damage, and West African government export bans on raw uncrushed shea kernels tighten raw material logistics for overseas refiners.
- Opportunity: Solvent-free enzymatic fractionation, origin solar kernel curing, and liquid shea olein esters for waterless cosmetics unlock premium B2B ingredient margins.
Growth Analysis and Future Potential: Petrochemical Emollient Replacement and Cocoa Butter Equivalents
Demand for shea butter is reinforced by two parallel industrial shifts: beauty brands replacing fossil-derived mineral oils with biodegradable plant lipids, and chocolate makers substituting shea stearin for expensive cocoa butter. Under European Union and Codex Alimentarius chocolate standards, formulators can incorporate up to five percent vegetable fat cocoa butter equivalents (CBEs), where shea stearin provides the critical 1,3-distearoyl-2-oleoyl-glycerol (SOS) triglyceride structure that raises heat resistance and snap. In March 2026, the Global Shea Alliance convened over 500 industry delegates in Tamale, Ghana, launching its SHEA 2026 roadmap to expand origin processing and parkland restoration [6]. Beauty chemists also blend shea triterpenes with specialty cosmetic ingredients to substantiate barrier-repair claims before retail launch.
Risk Assessment of the Shea Butter Market: Wild Harvest Volatility and West African Raw Export Bans
Unlike oil palm or soybean crops grown on irrigated plantations, Vitellaria paradoxa trees grow wild across the semi-arid Sudano-Sahelian belt and require fifteen to twenty years to reach bearing maturity. Seasonal Harmattan wind shifts, erratic rainfall, and parkland clearing for charcoal directly reduce annual nut yields. Compounding agricultural risk, Ghana's Directorate of Presidential Initiatives in Agriculture and Agribusiness announced on July 9, 2025 a phased ban on raw shea nut exports by 2026 alongside the rehabilitation of the Buipe Shea Processing Factory (designed to process up to 180,000 metric tonnes annually under 24-hour operation and support over 10,000 indirect jobs) [7]. European and Asian refiners lacking local West African expeller mills face acute feedstock bottlenecks and higher working-capital requirements.
Commercial Opportunity Analysis: Green Enzymatic Stearin Fractionation and Bio-Based Cosmetic Esters
Specialty lipid refiners are capturing higher margins by replacing hexane-based solvent fractionation with dry mechanical crystallization and enzymatic interesterification, yielding clean-label stearin and liquid shea olein without chemical solvent residues. While solid stearin goes into heat-stable chocolate coatings and firm lip balms, the co-produced liquid shea olein fraction is increasingly esterified into lightweight, fast-spreading dermal emollients for facial serums and sunscreens. In June 2025, biophysical and analytical chemistry assays by Asher, Angara, and Salaudeen published in the Ptolemy Journal of Chemistry demonstrated that topical shea butter (43.2% oleic acid, 24.5% stearic acid, and 8.4% linoleic acid) reduced trans-epithelial water loss by 37.8% (from 8.2 to 5.1 g/m²/h) and increased skin hydration by 58.0% within 24 hours while raising skin impedance by 33% [8]. Pairing these green fractions with functional cosmetic ingredients allows suppliers to win eco-certified contracts across luxury skincare and confectionery accounts.
Which country CAGRs are profiled in the shea butter market?
Dermo-cosmetic formulation density in France and bulk vegetable-oil fractionation in the Netherlands anchor European demand, whereas multicultural haircare and clean-beauty bars shape consumption across North America and Oceania. France leads the six evaluated countries at a 5.2% CAGR from 2026 to 2036, followed by the Netherlands at 4.8% and New Zealand at 4.5%, while Ireland expands at a 3.4% CAGR over the assessment period, according to FMI. Statutory chocolate vegetable-fat limits, EU cosmetic safety dossiers, and direct West African cooperative contracts determine national growth trajectories.
Table 7: Country CAGR and Primary Growth Levers for the Shea Butter Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 5.2% | Prestige dermo-cosmetic formulation, pharmacy balm lines, and direct West African women's cooperative contracts |
| Netherlands | 4.8% | Rotterdam and Zaanstreek lipid refining hub and specialty CBE stearin re-exports |
| New Zealand | 4.5% | Waterless eco-beauty bars and botanical blending with indigenous manuka extracts |
| USA | 4.1% | Textured haircare curl formulations, mass body care lotions, and MoCRA safety compliance |
| UK | 3.8% | Soil Association COSMOS organic beauty retail and EU-aligned 5% chocolate vegetable fat use |
| Ireland | 3.4% | Pharmaceutical atopic dermatitis barrier ointments and cold-climate dermal repair creams |
Source: Future Market Insights analysis
France Shea Butter Market Outlook (2026 to 2036)
Prestige dermo-cosmetic laboratories across Paris, Lyon, and Provence formulate high-inclusion (10% to 25%) shea barrier balms for global pharmacy export rather than relying on domestic mass-grocery soap volume. Demand in France is projected to advance at a 5.2% CAGR from 2026 to 2036, supported by steroid-sparing atopic skincare lines and textured hair conditioners. In February 2026, the Fédération des Entreprises de la Beauté (FEBEA) reported that French cosmetic exports totaled EUR 22.4 billion in 2025 with a EUR 17 billion trade surplus, led by EUR 11 billion in skincare and makeup alongside a 5.5% rise in haircare exports to EUR 1.5 billion [9]. While U.S. tariffs slowed trans-Atlantic beauty shipments, French houses secure intra-EU growth through direct Burkinabè women's cooperative contracts.
Key takeaway: In France, EUR 22.4 billion cosmetic export scale and pharmacy dermo-cosmetic formulation density drive direct multi-year purchasing from West African women's cooperatives.
Netherlands Shea Butter Market Outlook (2026 to 2036)
Deep-water tank terminals at the Port of Rotterdam and specialty fat fractionation towers along the Zaanstreek corridor position the Netherlands as Europe's B2B refining gateway rather than a purely domestic retail market. In March 2026, the Netherlands Oils and Fats Industry Association (MVO) highlighted in its 2025 trade review that Dutch refineries expanded sustainable tropical butter processing and cocoa butter equivalent stearin re-exports across European food and cosmetic supply chains [10]. The Netherlands shea butter sector is projected to record a 4.8% CAGR during the 2026 to 2036 assessment period, backed by solvent-free stearin crystallization for chocolate compounders. Yet commercial uptake faces friction from West African raw nut export bans, compelling Dutch refiners to import origin-pressed crude butter.
Key takeaway: In the Netherlands, Rotterdam and Zaanstreek fractionation refineries pivot from raw kernel crushing to importing West African crude butter for European CBE stearin and olein distribution.
New Zealand Shea Butter Market Outlook (2026 to 2036)
Export-focused clean-beauty laboratories in Auckland and Wellington utilize imported organic shea butter as a plastic-free structural base for anhydrous shampoo bars and native manuka-honey skin balms shipped across Asia-Pacific retail corridors. Sales of shea butter in New Zealand are forecast to expand at a 4.5% CAGR through 2036, underpinned by high-margin natural skincare exports and zero-water solid cosmetic formats. According to 2026 United Nations COMTRADE and Stats NZ trade records, New Zealand's exports of essential oils, perfumes, cosmetics, and toiletries reached USD 117.87 million (NZD 163.4 million) during 2025 as demand in the United States and Australia climbed [11]. However, long maritime transit times from West Africa elevate peroxide oxidation risks, prompting local formulators to procure nitrogen-flushed, tocopherol-stabilized butter drums.
Key takeaway: In New Zealand, USD 117.87 million clean-beauty export production and anhydrous solid bar formulations drive demand for antioxidant-stabilized organic shea butter.
USA Shea Butter Market Outlook (2026 to 2036)
Multicultural textured-haircare aisles and dermatologist-endorsed body lotions anchor United States shea demand, as brands reformulate daily moisturizers away from synthetic silicones and perfluoroalkyl substances. The shea butter market in the USA is anticipated to grow at a 4.1% CAGR between 2026 and 2036, aided by curl-conditioning masks and FDA GRAS-notified (GRN No. 850) confectionery compound coatings. In August 2026, the U.S. Food and Drug Administration updated its Modernization of Cosmetics Regulation Act (MoCRA) implementation guidance, noting Americans use 6 to 12 cosmetic products daily, following its December 2025 report on PFAS in cosmetics and mandatory biennial facility registration [12]. FDA 21 CFR Part 163 rules nonetheless prohibit vegetable-fat CBEs in pure chocolate, keeping U.S. growth concentrated in personal care.
Key takeaway: In the USA, MoCRA safety substantiation across daily skincare and textured haircare routines drives cosmetic shea volume while 21 CFR Part 163 limits food use to compound coatings.
UK Shea Butter Market Outlook (2026 to 2036)
Unlike the United States, United Kingdom food law permits up to 5% vegetable fat cocoa butter equivalents in milk chocolate while British high-street pharmacies simultaneously anchor Europe's second-largest national personal care market. Between 2026 and 2036, the UK market is expected to progress at a 3.8% CAGR, reflecting dual demand for confectionery shea stearin and fair-trade body butters. According to Soil Association Certification's Beauty and Wellbeing market data, UK certified organic beauty sales grew 8% in 2025 across 3,833 certified businesses, with 84% of surveyed consumers prioritizing COSMOS certification criteria [13]. The central commercial obstacle involves post-Brexit UK REACH registration costs and separate cosmetic notification filings, prompting British soap and chocolate makers to source pre-registered grades through domestic distributors.
Key takeaway: In the UK, 8% annual organic beauty sales growth and the statutory 5% chocolate vegetable-fat allowance sustain demand for COSMOS-certified butter and CBE stearin.
Ireland Shea Butter Market Outlook (2026 to 2036)
Damp Atlantic winter weather and widespread consumer sensitivity to degraded cosmetic preservatives have created a specialized Irish pharmacy market for ultra-refined, low-peroxide shea barrier ointments. In Ireland, shea butter adoption is predicted to register a 3.4% CAGR over the forecast period, supported by community pharmacist referrals for pediatric eczema and chronic xerosis emollients. In December 2025, Ireland's Health Products Regulatory Authority (HPRA) published national survey findings across 1,000 adults showing that 49% use four or more cosmetic products daily, while 35% reported skin irritation or rashes and 60% used products past their open-jar shelf life [14]. Smaller domestic production runs and strict European Pharmacopoeia oxidation thresholds nonetheless raise landed drum costs, leading Irish laboratories to pool purchasing of antioxidant-stabilized grades.
Key takeaway: In Ireland, HPRA shelf-life safety findings and a 35% adult cosmetic irritation rate bolster pharmacy demand for oxidation-resistant, medical-grade shea barrier creams.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the shea butter market?
Bunge Loders Croklaan, Cargill Incorporated, AAK AB, Olvea Group, Wilmar International, Ghana Nuts Company, Sophim S.A., and Clariant AG are the notable companies profiled in this market.
Ownership of local West African expeller crushing mills, direct women's collector networks, and solvent-free stearin fractionation towers separates tier-one lipid processors from spot-market importers. Global agribusiness and specialty fat leaders AAK AB, Bunge Loders Croklaan, Cargill Incorporated, and Wilmar International combine Sahelian parkland collection programs with high-capacity fractionation plants in Europe and Ghana. Origin processing specialists Ghana Nuts Company and Olvea Group supply expeller-pressed crude and organic deodorized butter directly from West African facilities. Downstream cosmetic ingredient formulators Clariant AG and Sophim S.A. engineer standardized unsaponifiable triterpene concentrates, liquid shea esters, and COSMOS-certified phytosqualane-shea blends for prestige skincare brands.
- Multinational Specialty Fat and CBE Fractionation Leaders: AAK AB, Bunge Loders Croklaan, Cargill Incorporated, and Wilmar International combine West African parkland collection programs with industrial stearin and cosmetic lipid refining.
- West African Origin Crushing and Fair-Trade Lipid Specialists: Ghana Nuts Company and Olvea Group operate local mechanical expeller mills, solar kernel-drying centers, and organic deodorization units.
- Bioactive Cosmetic Emollient and Specialty Ingredient Formulators: Clariant AG and Sophim S.A. engineer standardized unsaponifiable triterpene fractions and biodegradable shea esters for prestige skincare.
Competitive Benchmarking: Shea Butter Market
Table 8: Competitive Benchmarking for the Shea Butter Market (qualitative capability ratings), 2026
| Company | West African Origin Sourcing & Crushing | Stearin & Cosmetic Fractionation Tech | Fair-Trade / Organic Traceability | Geographic Reach |
|---|---|---|---|---|
| Bunge Loders Croklaan | High | High | High | High |
| Cargill Incorporated | High | High | High | High |
| AAK AB | High | High | High | High |
| Olvea Group | High | Medium | High | Medium |
| Wilmar International | High | High | Medium | High |
| Ghana Nuts Company | High | Medium | Medium | Medium |
| Sophim S.A. | Medium | High | High | Medium |
| Clariant AG | Medium | High | High | High |
Scoring basis: Evaluations reflect documented West African women's collector networks and local expeller mills, solvent-free stearin and liquid ester fractionation capacity, and Fairtrade or COSMOS certification coverage. Ratings summarize verified supply-chain capabilities rather than commercial market share.
Key Developments in the Shea Butter Market
- In March 2026, Cargill Incorporated strengthened its global specialty fats portfolio and expanded processing capacity for shea-based cocoa butter equivalents and personal care emollients [15].
- In May 2026, Ghana Nuts Company commissioned an upgraded biomass-powered mechanical expeller pressing and physical refining line at its Techiman agro-industrial complex in Ghana to boost domestic value-added butter exports [16].
- In February 2026, Sophim S.A. introduced a COSMOS-certified deodorized organic shea butter and olive-squalane co-emollient system engineered for fast-absorbing facial serums at its Peyruis facility in France [17].
- In January 2026, Clariant AG expanded its Plantasens bio-based emollient portfolio with a lightweight liquid shea ester complex designed to replace volatile cyclic silicones in sunscreens and color cosmetics [18].
- In October 2025, Olvea Group inaugurated expanded solar-assisted kernel drying and eco-designed storage warehouses in Burkina Faso to eliminate wood-smoke polycyclic aromatic hydrocarbon contamination and lower curing carbon intensity [19].
- In January 2026, AAK AB presented new liquid shea butter solutions and oil-phase crystallization protocols to prevent grainy stearic blooming in cosmetic emulsions while scaling its Kolo Nafaso direct women's sourcing program [20].
- In September 2026, Bunge Loders Croklaan advanced regulatory and commercial deployment of its Coberine shea-based cocoa butter equivalents and FDA GRAS-notified (GRN No. 850) shea olein food fat replacements [21].
Key Players in the Shea Butter Market
Multinational Specialty Lipid and CBE Fractionation Platforms
- Bunge Loders Croklaan
- Cargill Incorporated
- AAK AB
- Wilmar International
West African Origin Crushing and Sustainable Vegetable Oil Producers
- Olvea Group
- Ghana Nuts Company
Specialty Cosmetic Emollient and Bioactive Lipid Formulators
- Clariant AG
- Sophim S.A.
Shea Butter Market - Report Scope
Table 9: Report Scope for the Shea Butter Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Grade; Application Sector; Source Nature; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes B2B and wholesale revenue from unrefined crude, refined/deodorized, and fractionated (stearin, olein, and bioactive unsaponifiable) shea butter derived from Vitellaria paradoxa kernels for cosmetic, confectionery/food, and pharmaceutical applications. Excludes raw uncrushed shea nut farmgate trade and retail markups on finished consumer cosmetics or chocolate bars. Category Scope Note: Market valuation reflects the commercial B2B crude expeller-pressed shea butter, refined/deodorized shea butter, and fractionated shea stearin/olein ingredient supply tier sold to food, confectionery, and personal care manufacturers, rather than gross downstream retail prices of finished chocolate bars or cosmetic creams. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | France, Netherlands, New Zealand, USA, UK, Ireland, and additional countries in the full report |
| Key Companies Covered | Bunge Loders Croklaan, Cargill Incorporated, AAK AB, Olvea Group, Wilmar International, Ghana Nuts Company, Sophim S.A., Clariant AG |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
As noted by FMI, the report covers commercial crude, refined, and fractionated shea butter ingredients and excludes uncrushed raw nut trade and downstream finished consumer goods revenue.
Shea Butter Market - Research Methodology
Table 10: Research Methodology for the Shea Butter Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with West African crushing mill directors, Global Shea Alliance cooperative coordinators, European specialty lipid chemists, chocolate CBE formulators, and dermo-cosmetic procurement managers across Europe, West Africa, North America, and Oceania. |
| Secondary Research | Secondary research evaluated Global Shea Alliance trade assessments, Cosmetics Europe and FEBEA industry reports, UNCTAD West African export bulletins, AOCS lipid chemistry publications, and corporate sustainability disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 reconciled West African dry kernel crushing volumes and expeller extraction yields against FOB/CIF crude butter, refined cosmetic grade, and fractionated CBE stearin pricing. |
| Data Triangulation and Validation | Estimates were cross-checked against port customs import registries in Rotterdam, Marseille, and Newark alongside cosmetic and confectionery inclusion rates to eliminate double counting between crude kernel crushers and downstream fractionators. |
Shea Butter Market by Segments
Shea Butter Market segmented by Grade:
- Cosmetic-Grade Butter
- Food-Grade / Confectionery Butter
- Pharmaceutical-Grade Butter
Shea Butter Market segmented by Application Sector:
- Cosmetics and Personal Care
- Confectionery & Bakery Fats
- Pharmaceutical Formulations
Shea Butter Market segmented by Source Nature:
- Conventional Source
- Certified Organic & Fair Trade
Shea Butter Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- France
- Netherlands
- United Kingdom
- Ireland
- Germany
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- China
- South Asia and Pacific
- New Zealand
- Australia
- India
- ASEAN
- Middle East and Africa
- Ghana
- Burkina Faso
- Côte d'Ivoire
- Nigeria
- South Africa
- GCC Countries
Research Sources and Bibliography
- [1] Global Shea Alliance. (2025, May). Annual reports for 2025: 2025 annual report, May - 2025. Global Shea Alliance.
- [2] Cosmetics Europe. (2026, June). Our industry: Economic value of the cosmetics and personal care industry. Cosmetics Europe.
- [3] Attikora, A. J. P., Kouassi, K. A., Yao, S. D. M., Dago, D. N., Silué, S., De Clerck, C., Diarrassouba, N., Alabi, T., Achigan-Dako, E. G., Fauconnier, M.-L., Danthine, S., & Lassois, L. (2025, February 19). Genome-wide association study of fat content and fatty acid composition of shea tree (Vitellaria paradoxa C.F. Gaertn subsp. paradoxa). BMC Genomics, 26(1), 164. https://doi.org/10.1186/s12864-025-11344-z
- [4] Cosmetics Europe & IFOP. (2026, June). European Consumer Perception Study 2026: Essentiality of personal care and skincare formulations across Europe. Cosmetics Europe.
- [5] International Cocoa Organization. (2025, April 24). Cocoa market deficit dynamics and industrial substitution of shea-derived cocoa butter equivalents in confectionery coatings. ICCO Quarterly Bulletin of Cocoa Statistics, 51(2), 18–31.
- [6] Global Shea Alliance. (2026, March 17). Global Shea Alliance Launches SHEA 2026: Beyond Trade Conference in Tamale, Signaling New Momentum for Origin Value Addition. GSA Official Press Releases.
- [7] Presidential Initiatives in Agriculture and Agribusiness (PIAA), Office of the President, Republic of Ghana. (2025, July 9). Govt to ban raw shea nut exports by 2026. Presidential Initiatives in Agriculture and Agribusiness.
- [8] Asher, A. S., Angara, A. A., & Salaudeen, A. O. (2025, June 30). Investigation of the in vitro effects of shea butter on skin barrier function and hydration using analytical chemistry methodologies. Ptolemy Journal of Chemistry, 5(1), 1–7. https://doi.org/10.30538/psrp-ojc2025.0022
- [9] Fédération des Entreprises de la Beauté (FEBEA). (2026, February 6). Coup de frein sur les exportations de cosmétiques français en 2025 : le secteur demeure deuxième contributeur à la balance commerciale malgré un repli sur le marché américain. FEBEA. https://www.febea.fr/presse/coup-frein-exportations-cosmetiques-francais-2025-le-secteur-demeure-deuxieme-contributeur-a
- [10] MVO – The Netherlands Oils and Fats Industry. (2026, March). The Netherlands oils and fats industry: Handel in 2025. MVO. https://mvo.nl/en
- [11] United Nations COMTRADE & Stats NZ. (2026, April). New Zealand exports of essential oils, perfumes, cosmetics, toiletries (HS Category 33, 2025 annual series). United Nations Statistics Division.
- [12] U.S. Food and Drug Administration. (2026, August 10). Modernization of Cosmetics Regulation Act of 2022 (MoCRA). U.S. Department of Health and Human Services. https://www.fda.gov/cosmetics/cosmetics-laws-regulations/modernization-cosmetics-regulation-act-2022-mocra
- [13] Soil Association Certification. (2026, August). Beauty and wellbeing certification (Organic Market Report 2025). Soil Association. https://www.soilassociation.org/for-business/soil-association-certification/organic-certification/beauty-and-wellbeing/
- [14] Health Products Regulatory Authority (HPRA). (2025, December 3). Six in ten Irish adults use cosmetics beyond their expiry or recommended shelf life. Health Products Regulatory Authority. https://www.hpra.ie/news-events/news/article/six-in-ten-irish-adults-use-cosmetics-beyond-their-expiry-or-recommended-shelf-life
- [15] Cargill, Incorporated. (2026, March 31). Cargill strengthens global specialty fats portfolio and expands high-performance shea processing capabilities. Cargill Corporate Newsroom.
- [16] Ghana Nuts Company Limited. (2026, May 14). Ghana Nuts commissions expanded biomass-powered shea expeller pressing and physical refining line in Techiman. Corporate Expansion Announcements.
- [17] Sophim S.A. (2026, February 10). Sophim introduces COSMOS-certified deodorized organic shea and olive-squalane co-emollient system in Peyruis, France. Sophim Corporate Releases.
- [18] Clariant AG. (2026, January 20). Clariant Personal & Home Care expands Plantasens bio-based liquid shea ester range for silicone-free sunscreens and skincare. Clariant Media Releases, Muttenz, Switzerland.
- [19] Olvea Group. (2025, October 16). Olvea Burkina inaugurates solar-assisted shea kernel drying and low-PAH curing centers in West Africa. Olvea Corporate Sustainability News.
- [20] AAK AB. (2026, January 5). Innovate with Shea: Liquid shea butter solutions and oil-phase strategies to prevent grainy cosmetic formulations. AAK Personal Care Technical Releases, Malmö, Sweden.
- [21] U.S. Food and Drug Administration. (2026, September). Agency response letter GRAS Notice No. GRN 000850. U.S. Department of Health and Human Services.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the shea butter market in 2026 and what is forecast for 2036?
- Which clean-label emollient and cocoa butter substitution pressures support demand for shea butter?
- Why does cosmetic-grade butter lead the grade category in 2026?
- What places cosmetics and personal care ahead within the application sector category?
- How do growth rates differ across France, the Netherlands, New Zealand, and the USA through 2036?
- Which leading companies operate West African crushing mills and specialty stearin refineries today?
- What Sahel harvest fluctuations and raw kernel export bans limit supply in the shea butter market?
- What should cosmetic and confectionery buyers evaluate before qualifying a shea butter supplier?
Frequently Asked Questions
How big is the shea butter market expected to be in 2026, and what is forecast for 2036?
The global shea butter market is estimated to reach USD 19.5 billion in 2026, rising from USD 18.7 billion in 2025. The market is projected to expand further and reach USD 29.7 billion by 2036, supported by petrochemical emollient replacement and cocoa butter equivalent demand.
What CAGR is forecast for the shea butter market from 2026 to 2036?
As per FMI, the shea butter market is projected to grow at a 4.3% CAGR from 2026 to 2036. Growth is supported by rising inclusion of unrefined and deodorized shea lipids in dermo-cosmetics alongside solvent-free stearin fractionation for chocolate coatings.
Which grade segment holds a notable shea butter demand share in 2026?
Cosmetic-grade butter is projected to hold 46.0% of grade demand in 2026. The segment benefits from its high five-to-nine percent unsaponifiable triterpene ester fraction that repairs skin barriers and reduces moisture loss.
Which application sector holds the leading share in 2026?
Cosmetics and personal care is estimated to account for 61.0% of application sector revenue in 2026. Demand is underpinned by body butters, facial barrier creams, lip balms, and textured haircare conditioning masks.
Which country has a notable shea butter expansion outlook during the forecast period?
FMI finds that France is projected to expand at a 5.2% CAGR during the 2026 to 2036 assessment period. Growth is supported by prestige dermo-cosmetic R&D laboratories and direct fair-trade sourcing contracts with West African women's cooperatives.
Which companies are active in the shea butter market during 2026?
Notable companies include Bunge Loders Croklaan, Cargill Incorporated, AAK AB, Olvea Group, Wilmar International, Ghana Nuts Company, Sophim S.A., and Clariant AG. These companies are focusing on West African origin mechanical crushing, solvent-free enzymatic stearin fractionation, low-PAH solar kernel drying, and COSMOS-certified liquid shea esters.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade, 2026 to 2036
- Cosmetic-Grade Butter
- Food-Grade / Confectionery Butter
- Pharmaceutical-Grade Butter
- Y-o-Y Growth Trend Analysis By Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Application Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Sector, 2026 to 2036
- Cosmetics and Personal Care
- Confectionery & Bakery Fats
- Pharmaceutical Formulations
- Y-o-Y Growth Trend Analysis By Application Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Source Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Nature, 2026 to 2036
- Conventional Source
- Certified Organic & Fair Trade
- Y-o-Y Growth Trend Analysis By Source Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- Netherlands
- United Kingdom
- Ireland
- Germany
- Italy
- Spain
- Benelux
- Nordics
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- New Zealand
- Australia
- India
- ASEAN
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Ghana
- Burkina Faso
- Côte d'Ivoire
- Nigeria
- South Africa
- GCC Countries
- By Grade
- By Application Sector
- By Source Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application Sector
- By Source Nature
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- Ireland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application Sector
- By Source Nature
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Grade
- By Application Sector
- By Source Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bunge Loders Croklaan
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill Incorporated
- AAK AB
- Olvea Group
- Wilmar International
- Ghana Nuts Company
- Sophim S.A.
- Clariant AG
- Bunge Loders Croklaan
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


