
- Market Size (2026)
- USD 4.8 Bn
- Forecast (2036)
- USD 8.8 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Nut Butters Market in 2026?
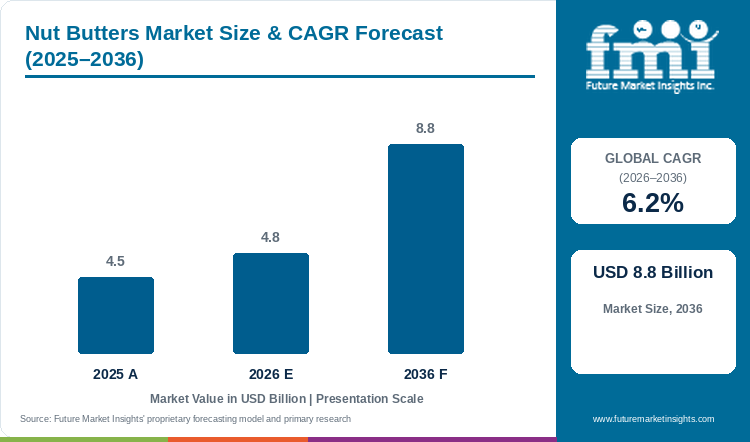
Sales in the nut butters market are projected to grow at 6.2% CAGR, with the market size rising from USD 4.5 Billion in 2025 to USD 4.8 Billion in 2026 and reaching USD 8.8 Billion by 2036.
According to Future Market Insights analysis, the global nut butters market stands at USD 4.5 Billion in 2025 and rises to USD 4.8 Billion in 2026. Industry valuation reaches USD 8.8 Billion by 2036. The sector expands at a 6.2% CAGR and yields USD 4.0 Billion in added revenue over the 2026 to 2036 period. Routine household grocery purchases drive baseline volume. Families incorporate plant protein spreads into morning routines and post-exercise smoothies.
In January 2025, USDA Economic Research Service data confirmed that per capita tree nuts availability rose by 4.8% [1]. This agricultural supply provides stable raw ingredient volume for milling operations. Slices, shreds & blocks format accounts for 46.3% of texture demand in 2026. Evaluated country growth spans 5.0% in Germany to 7.6% in Italy. Raw nut harvest volatility and shelf stability requirements continue to challenge processing margins.
Key Market Trends & Insights
- Based on product form / texture, slices, shreds & blocks is projected to account for 46.3% in 2026, driven by convenient portion control in commercial baking and culinary preparation.
- By source base, traditional dairy milk is estimated to hold 54.9% in 2026, owing to established dairy-blended spread traditions and rich mouthfeel preferences.
- In 2026, supermarkets & hypermarkets is expected to lead distribution channel with 56.9% share, supported by prominent center-store placement and bulk promotional multipacks.
- By flavor / variant, plain & unsweetened is forecast to represent 46.1% in 2026, underpinned by health-conscious consumer demand for single-ingredient spreads without added cane sugar.
Regional Highlights
- Fastest-growing evaluated country: Italy, at 7.6% CAGR from 2026 to 2036.
- By country: Denmark at 6.9%, Canada at 6.4%, the USA at 6.0%, and Australia at 5.5% follow, while Germany records the lowest evaluated CAGR at 5.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Nut Butters Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.5 Billion |
| Estimated Market Size in 2026 | USD 4.8 Billion |
| Projected Market Size by 2036 | USD 8.8 Billion |
| CAGR, 2026 to 2036 | 6.2% |
| Added Revenue, 2026 to 2036 | USD 4.0 Billion |
Country commercial conditions differ as retail grocery channels manage shelf space allocation. In February 2025, UN Food and Agriculture Organization commodity data documented rising international trade in edible nuts [2]. Food brands are expanding peanut butter and almond butter blends to satisfy growing consumer interest in healthy spreads.
Milling Throughput and Oil Separation Dynamics
Table 2: Milling Throughput and Oil Separation Indicators for the Nut Butters Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 4.5 | 4.8 | 8.8 |
| Commercial nut butter production volume (million metric tons) | 1.15 to 1.30 | 1.22 to 1.38 | 1.85 to 2.15 |
| Stone-ground milling line yield rate (percent) | 94.5 to 97.2 | 95.0 to 97.5 | 96.5 to 98.4 |
| Annual natural stabilizer cost savings per plant (USD) | 14,000 to 22,000 | 15,000 to 24,000 | 22,000 to 35,000 |
Retail Velocity and Packaging Innovation Sizing
High-velocity spreads depend on oxygen-barrier containers that preserve fresh roasted aromas without chemical preservatives. Category buyers evaluate suppliers based on seal integrity, natural oil separation resistance, and squeeze-pack convenience.
Table 3: Retail Velocity and Packaging Indicators for the Nut Butters Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Retail store grocery distribution doors (million outlets) | 1.65 | 1.72 | 2.25 |
| Average annual category spend per retail door (USD) | 2,720 | 2,790 | 3,910 |
| Single-serve squeeze pouch unit packaging cost (USD) | 0.12 to 0.22 | 0.13 to 0.24 | 0.18 to 0.30 |
| Glass jar container cost per unit (USD) | 0.28 to 0.45 | 0.30 to 0.48 | 0.42 to 0.65 |
Table 4: End-Use Sector Procurement Indicators for the Nut Butters Market (USD Billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 4.8 Billion | Report value |
| Supermarkets & hypermarkets retail sales, 2026 | USD 2.73 Billion | 56.9% share |
| Traditional dairy milk base procurement spend, 2026 | USD 2.64 Billion | 54.9% share |
| Slices, shreds & blocks format revenue, 2026 | USD 2.22 Billion | 46.3% share |
Analyst Perspective
"Spread manufacturers cannot rely on added sugars to mask bitter nut skins. Brands are investing in cryogenic fine-grinding and natural emulsifiers to maintain smooth texture across room-temperature shelf displays."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Nut Butters Market segmented?
The nut butters market is segmented by product form / texture, source base, distribution channel, and flavor / variant. In 2026, slices, shreds & blocks is projected at 46.3%, traditional dairy milk at 54.9%, supermarkets at 56.9%, and plain variants at 46.1%.
By product form / texture: slices, shreds & blocks, drinkable liquid & shakes, set tubs & cups, and spreads & dips.
By source base: traditional dairy milk, plant-based alternative (oat/almond/soy), and lactose-free & specialized.
By distribution channel: supermarkets & hypermarkets, specialty natural food stores, and food service & quick service bakeries.
By flavor / variant: plain & unsweetened, fruit-flavored & indulgent, and savory & herbed.
Why do slices, shreds & blocks lead the product form / texture category?
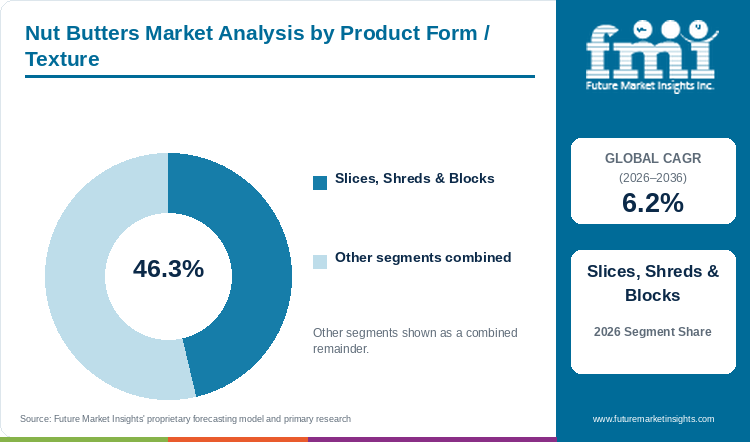
Slices, shreds & blocks is expected to hold 46.3% of product form revenue in 2026, supported by versatile commercial culinary and foodservice utility.
Table 5: Product Form / Texture Share for the Nut Butters Market (percentage share), 2026
| Product Form / Texture | Share (2026) |
|---|---|
| Slices, Shreds & Blocks | 46.3% |
| Other Segments Combined | 53.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form / Texture Leadership and Market Growth for the Nut Butters Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.2% |
| Leading Segment | Slices, Shreds & Blocks |
According to Future Market Insights, solid and semi-solid formats lead industrial food service and bakery demand. Commercial kitchens use portioned blocks and shreds for melting into sauces and baking fillings. The format avoids messy scooping and delivers uniform melt characteristics in commercial ovens. Food processors incorporate these blocks into bakery mixes and snack bars. Manufacturers optimize tempering chambers to prevent bloom and maintain consistent firmness.
- Slices, shreds & blocks is likely to capture 46.3% share in 2026, attributable to streamlined culinary handling and exact portion control in food processing.
- In March 2025, Hormel Foods Corporation introduced culinary nut butter blocks designed for commercial bakery glaze formulations [3].
What drives traditional dairy milk to the forefront of the source base segment?
Traditional dairy milk is estimated to represent 54.9% of source base demand in 2026, reflecting established consumer preference for rich creamy dairy fat.
Dairy-blended nut spreads deliver rich mouthfeel and familiar flavor profiles that appeal to broad family demographics. Blending nut paste with dairy solids provides balanced emulsion stability and prevents oil separation during ambient pantry storage. Dairy fats complement clean label ingredients without requiring hydrogenated vegetable oils. Sourcing teams partner with dairy cooperatives to secure high-butterfat cream supplies.
- Traditional dairy milk base is set to lead source base with 54.9% share in 2026, influenced by mainstream breakfast spread traditions and superior emulsification.
- In May 2025, General Mills, Inc. expanded its dairy-infused cashew spread line across North American grocery channels [4].
How do supermarkets & hypermarkets maintain 56.9% share in distribution channels?
Supermarkets & hypermarkets is projected to capture 56.9% of distribution channel revenue in 2026, driven by center-store shelf visibility and promotional multipacks.
Supermarkets remain the dominant purchasing channel for everyday household staples. Shoppers expect to find extensive brand selections spanning creamy, crunchy, and organic variants within the breakfast spread aisle. Large retail chains offer promotional discounts and multi-pack pricing that encourage pantry stockpiling. Brands also market dairy free spreads alongside traditional spreads to capture health-minded flexitarians.
- Supermarkets & hypermarkets is projected to hold 56.9% share in 2026, reinforced by wide brand variety and convenient one-stop grocery shopping trips.
- In August 2025, The Kraft Heinz Company secured expanded center-aisle endcap merchandising displays across major supermarket chains [5].
What supports plain & unsweetened leadership in the flavor category?
Plain & unsweetened is anticipated to contribute 46.1% of flavor revenue in 2026, owing to clean ingredient preferences among fitness-focused shoppers.
Clean formulations containing only roasted nuts and salt appeal strongly to consumers monitoring daily sugar consumption. Fitness enthusiasts incorporate unsweetened nut butter into better for you snacks and morning oatmeal bowls. Eliminating cane sugar also provides culinary versatility for savory dressings, satay sauces, and low-carb keto baking. Processors use gentle roasting protocols to enhance natural nut sweetness without artificial additives.
- Plain & unsweetened variants are set to command 46.1% share in 2026, supported by keto diet adoption and minimalist ingredient deck preferences.
- In October 2025, Campbell Soup Company expanded its Pacific Foods organic unsweetened roasted peanut butter distribution [6].
What are the drivers, restraints, and opportunities in the Nut Butters Market?
Plant protein snacking trends accelerate retail spread sales, while raw nut price volatility strains processing margins and single-serve squeeze packs unlock on-the-go revenue.
- Driver: Consumer interest in wholesome plant protein and healthy fats sustains recurring breakfast and snacking spread consumption.
- Restraint: Climatic drought and crop disease in key almond and peanut growing regions trigger raw ingredient wholesale cost spikes.
- Opportunity: Developing portable single-serve squeeze pouches and nutrient-dense seed blends captures active commuter and school lunchbox demand.
Growth Analysis and Future Potential: Plant Protein Snacking and Breakfast Routine Catalysts
Consumers increasingly replace sugary breakfast jams with nutrient-dense nut and seed spreads. High levels of monounsaturated fats, dietary fiber, and plant protein make nut butter an essential pantry staple for health-minded households. Future Market Insights research indicates that millennial parents prioritize nutrient-dense morning meals for their families. In July 2025, consumer survey data revealed that 69.4% of households purchased nut butter at least once a month [7]. Manufacturers expand crunchy, creamy, and artisan hazelnut paste portfolio variants to satisfy diverse textural preferences.
Risk Assessment and Operational Hurdles: Agricultural Commodity Swings and Allergen Management
Wholesale price volatility in raw tree nuts and peanuts presents persistent margin challenges for spread manufacturers. Drought conditions in California almond orchards and unseasonal rains across peanut growing belts disrupt seasonal crop yields. In September 2025, agricultural commodity reports confirmed that raw almond spot prices fluctuated by 16.5% over a six-month period [8]. In addition to commodity swings, strict food allergen segregation protocols require dedicated processing lines, increasing factory capital costs.
Commercial Opportunity Analysis: On-the-Go Pouch Formats and Seed-Nut Hybrids
Packaging innovation and allergen-conscious ingredient blending represent major commercial growth avenues for spread manufacturers. Single-serve squeeze pouches with re-closable caps allow outdoor athletes and school children to consume protein without utensils. Formulators combine spread bases with cashew milk to create versatile dipping formats that complement healthy australia fruit snacks. Manufacturers also blend peanuts with chia seeds, flaxseed, and pumpkin seeds to enhance omega-3 nutrient profiles. Introducing fortified nut spreads for athletes creates premium retail price tiers across specialty health channels.
Nut Butters Market by Country (2026 to 2036)
Future Market Insights analysis indicates that Italy represents the fastest-growing nut butters market among the six evaluated countries at a 7.6% CAGR from 2026 to 2036. Germany records the slowest expansion at 5.0% CAGR over the forecast period. Across all six covered economies, brand performance depends on sourcing high-grade nuts and preventing natural oil separation on grocery store shelves.
Table 7: Country CAGR and Primary Growth Levers for the Nut Butters Market (CAGR percentage and operational drivers), 2026 to 2036
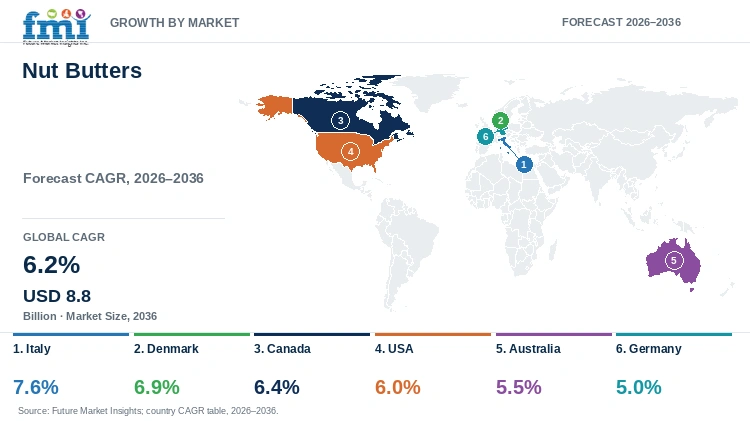
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 7.6% | Artisan hazelnut spread heritage and premium organic almond butter adoption in northern culinary centers |
| Denmark | 6.9% | Nordic clean-label nutrition trends and organic rye bread spread consumption across Copenhagen |
| Canada | 6.4% | High household peanut butter penetration and expanding natural specialty nut butter retail assortment |
| USA | 6.0% | Core breakfast staple demand, fitness lifestyle snacking, and premium single-serve squeeze pouch growth |
| Australia | 5.5% | Domestic macadamia and almond crop utilization paired with outdoor active snacking culture |
| Germany | 5.0% | Whole-grain bread spread traditions and organic bio-market retail expansion across major metropolitan cities |
Source: Future Market Insights analysis
USA Nut Butters Market Outlook (2026 to 2036)
By 2036, the USA is projected to grow at 6.0% CAGR, driven by deep consumer familiarity with peanut butter and expanding specialty almond spread offerings. In January 2026, the National Peanut Board confirmed that retail spread sales exceeded USD 2.65 Billion in 2025 [9]. Parents view nut butter as an economical, protein-rich staple for school lunches and afternoon snacks. However, widespread peanut allergy concerns in public schools restrict lunchbox usage in educational settings. Manufacturers resolve this barrier by producing dedicated sunflower seed and almond spreads on allergen-free processing lines.
Key takeaway: In the USA, ingrained breakfast traditions and portable squeeze-pack innovation sustain reliable category revenue growth.
Italy Nut Butters Market Outlook (2026 to 2036)
Italy's nut butters outlook is anticipated to advance at 7.6% CAGR over the assessment period, owing to artisan hazelnut traditions and surging interest in single-origin almond butter. In March 2025, the Italian National Institute of Statistics reported a 6.8% increase in organic packaged spread sales across northern grocery banners [10]. Italian consumers appreciate smooth stone-ground textures paired with rustic breads and pastries. However, deeply entrenched chocolate-hazelnut spread loyalties slow consumer adoption of unsweetened peanut variants. Brands overcome this hesitation by highlighting Sicilian almonds and Piedmont hazelnuts on premium artisan jar labels.
Key takeaway: In Italy, rich culinary confectionery heritage and rising organic health awareness accelerate premium almond and hazelnut spread adoption.
Denmark Nut Butters Market Outlook (2026 to 2036)
Nut butters demand in Denmark is forecast to rise at 6.9% CAGR over the forecast period, supported by clean-label organic diets and open-faced sandwich traditions. In April 2025, Statistics Denmark confirmed that organic food retail sales grew by 5.6%, with nut spreads gaining traction as dairy butter alternatives [11]. Danish shoppers favor minimalist ingredients with zero added palm oil. However, high retail import tariffs on non-European nut crops elevate shelf prices in discount grocery supermarkets. Distributors address this barrier by importing bulk Mediterranean nuts for local Danish packaging under certified eco-labels.
Key takeaway: In Denmark, strong organic grocery commitments and plant-forward sandwich culture propel healthy nut spread sales.
Canada Nut Butters Market Outlook (2026 to 2036)
Adoption of nut butters in Canada is estimated to expand at 6.4% CAGR through 2036, underpinned by high per capita spread consumption and multicultural flavor experimentation. In May 2025, Statistics Canada reported that packaged breakfast spread retail revenues reached USD 420.0 Million across major grocery chains [12]. Canadian consumers actively buy crunchy and smooth peanut spreads for winter baking and breakfast toast. However, cold winter distribution routes cause oil separation and spread hardening in ambient transport trailers. Brands solve this logistical issue by introducing optimized natural stabilizer blends that maintain spreadability in cold climates.
Key takeaway: In Canada, reliable breakfast spread routines and cold-tolerant emulsion formulations support resilient category sales.
Australia Nut Butters Market Outlook (2026 to 2036)
The Australia nut butters sector is projected to record 5.5% CAGR during the assessment period, reinforced by domestic macadamia nut processing and fitness lifestyle nutrition. In June 2025, the Australian Bureau of Statistics reported that health food and specialty spread sales rose steadily across East Coast supermarkets [13]. Active consumers add almond and macadamia pastes to protein shakes and acai bowls. However, intense supermarket private-label price competition compresses gross margins for independent artisan brands. Spread makers differentiate by highlighting 100% Australian-grown nuts and recyclable glass packaging on retail shelves.
Key takeaway: In Australia, strong domestic tree nut agriculture and active outdoor lifestyle nutrition stimulate steady specialty spread demand.
Germany Nut Butters Market Outlook (2026 to 2036)
In Germany, nut butters demand is predicted to advance at 5.0% CAGR through 2036, enabled by organic reformulations and whole-grain sourdough breakfast traditions. In July 2025, Federal Statistical Office data confirmed that bio-supermarket spread revenues increased as consumers sought plant-based dairy substitutes [14]. German buyers prioritize rigorous quality seals and fair-trade certifications. However, conservative consumer taste preferences for traditional fruit jams and dairy butter slow the rate of pantry conversion. Manufacturers counter this friction by offering mild-roast cashew spreads that deliver familiar creamy textures.
Key takeaway: In Germany, established organic food preferences and artisan sourdough bread habits sustain steady nut butter growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the nut butters market?
Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, and Mondelez International, Inc. are the significant market players in this market.
Future Market Insights analysis indicates that the nut butter competitive landscape comprises multinational consumer food corporations and dedicated organic spread manufacturers. Leading packaged food conglomerates leverage vast distribution networks to secure prime supermarket shelf space and launch line extensions. Specialized organic brands focus on single-origin nuts, zero palm oil, and artisanal stone-milling techniques. Procurement teams evaluate suppliers based on nut roasting quality, foreign matter detection, and certified allergen segregation.
- Global Consumer Packaged Food Leaders: Hormel Foods Corporation, The Kraft Heinz Company, and General Mills, Inc. manage top-tier national peanut and specialty spread brands.
- Diversified Nutrition & Confectionery Conglomerates: Nestle S.A., Danone S.A., Campbell Soup Company, and Mondelez International, Inc. incorporate nut butter formulations into snack bars and plant-based dairy lines.
- Breakfast Cereal & Bakery Specialists: WK Kellogg Co and Tyson Foods, Inc. utilize nut butter pastes as functional ingredients in commercial breakfast snacks and protein bars.
Competitive Benchmarking: Nut Butters Market
Table 8: Competitive Benchmarking for the Nut Butters Market (qualitative capability ratings), 2026
| Company | Brand Portfolio Breadth | Organic & Clean Label Depth | Single-Serve Packaging Innovation | Global Market Reach |
|---|---|---|---|---|
| Hormel Foods Corporation | High | Medium | High | High |
| The Kraft Heinz Company | High | Medium | High | High |
| General Mills, Inc. | High | High | Medium | High |
| Campbell Soup Company | Medium | High | Medium | High |
| Nestle S.A. | High | High | High | High |
| Danone S.A. | Medium | High | High | High |
| Mondelez International, Inc. | High | Medium | High | High |
| WK Kellogg Co | Medium | Medium | High | High |
| Tyson Foods, Inc. | Medium | Low | Medium | High |
Scoring basis: Brand portfolio breadth is High when offering peanut, almond, cashew, and mixed seed spreads across creamy and crunchy textures. Organic & clean label depth is High when the brand line features certified USDA Organic, Non-GMO Project Verified, and palm-oil-free variants. Single-serve packaging innovation is High when providing on-the-go squeeze packs and portion-control cups. Global market reach is High for multi-continent retail grocery distribution. Low reflects limited product differentiation.
Key Developments in the Nut Butters Market
- In February 2026, Hormel Foods Corporation launched SKIPPY protein squeeze pouches featuring five grams of plant protein per serving [15].
- In November 2025, The Kraft Heinz Company unveiled an organic roasted almond butter line with zero added sugar and sea salt seasoning [16].
- In July 2025, General Mills, Inc. expanded its Annie's organic certified peanut butter distribution across natural food grocers in North America [17].
Key Players in the Nut Butters Market
Global Consumer Packaged Food Leaders
- Hormel Foods Corporation
- The Kraft Heinz Company
- General Mills, Inc.
Diversified Nutrition & Confectionery Conglomerates
- Nestle S.A.
- Danone S.A.
- Campbell Soup Company
- Mondelez International, Inc.
Breakfast Cereal & Bakery Specialists
- WK Kellogg Co
- Tyson Foods, Inc.
Nut Butters Market - Report Scope
Table 9: Report Scope for the Nut Butters Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form / Texture; Source Base; Distribution Channel; Flavor / Variant |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and retail brand revenue from commercial nut and seed spreads including peanut, almond, cashew, hazelnut, and walnut butters. Excludes whole raw nuts and confectionery pralines. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Italy, Denmark, Canada, USA, Australia, Germany, and additional countries in the full report |
| Key Companies Covered | Hormel Foods Corporation, The Kraft Heinz Company, General Mills, Inc., Campbell Soup Company, Nestle S.A., Danone S.A., Mondelez International, Inc., WK Kellogg Co, Tyson Foods, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Nut Butters Market - Research Methodology
Table 10: Research Methodology for the Nut Butters Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews engaged commercial nut roasters, food scientists, supermarket category managers, and retail distributors to validate consumer velocity and milling costs. |
| Desk Research | Secondary research included tree nut agricultural production data, commodity price indexes, retail scanner data, trade association reports, and company annual reports. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were calculated using retail store sales volume and grocery household penetration rates. |
| Data Validation | Estimates were cross-verified against wholesale nut shipment volumes, retail shelf audits, and import-export records without double counting bulk raw agricultural commodities. |
Nut Butters Market by Segments
Nut Butters Market segmented by Product Form / Texture:
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
Nut Butters Market segmented by Source Base:
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
Nut Butters Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
Nut Butters Market segmented by Flavor / Variant:
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
Nut Butters Market by Region
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Argentina
- Western Europe
- Germany
- United Kingdom
- Italy
- France
- Denmark
- Spain
- Eastern Europe
- Poland
- Czech Republic
- Hungary
- Romania
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Australia and New Zealand
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
- Turkey
Research Sources and Bibliography
- [1] U.S. Department of Agriculture (USDA) Economic Research Service. (2025, January 23). Fruit and Tree Nuts Outlook: 2024 Crop Production and Consumption Benchmarks. USDA Publications. https://www.ers.usda.gov
- [2] Food and Agriculture Organization (FAO). (2025, February 18). World Food and Agriculture Statistical Pocketbook: Edible Tree Nuts and Oilseeds Trade. United Nations. https://www.fao.org
- [3] Hormel Foods Corporation. (2025, March 14). Commercial introduction of culinary nut butter blocks for industrial food service baking. Hormel Corporate News.
- [4] General Mills, Inc. (2025, May 22). Launch of clean-label dairy-blended cashew butter spreads across retail grocery banners. General Mills Press Room.
- [5] The Kraft Heinz Company. (2025, August 19). National merchandising expansion for Planters natural nut spreads in major supermarket chains. Kraft Heinz Investor Releases.
- [6] Campbell Soup Company. (2025, October 15). Expansion of Pacific Foods organic unsweetened peanut butter line. Campbell News Center.
- [7] National Peanut Board. (2025, July 10). Consumer Trends in Plant Protein and Nut Spread Consumption: 2025 Annual Survey. National Peanut Board Research.
- [8] Almond Board of California. (2025, September 24). 2024-2025 Almond Crop Shipment and Price Volatility Report. Almond Industry Publications.
- [9] National Peanut Board. (2026, January 16). U.S. Peanut Butter Retail Sales and Consumer Pantry Penetration Annual Report. NPB Industry Data.
- [10] Italian National Institute of Statistics (ISTAT). (2025, March 28). Retail Sales and Packaged Organic Foods Index in Italy, 2025 Edition. ISTAT Rome. https://www.istat.it
- [11] Statistics Denmark. (2025, April 24). Organic Food Consumption and Retail Turnover in Denmark: 2024 Full-Year Review. Government of Denmark. https://www.dst.dk
- [12] Statistics Canada. (2025, May 29). Monthly Survey of Retail Trade: Breakfast Food and Spreads Category Performance. Government of Canada.
- [13] Australian Bureau of Statistics (ABS). (2025, June 26). Retail Trade Australia: Packaged Food and Health Nutrition Category Trends. Commonwealth of Australia.
- [14] Federal Statistical Office of Germany (Destatis). (2025, July 18). Retail Turnover in Organic Food and Grocery Stores: 2025 Economic Digest. Destatis Wiesbaden.
- [15] Hormel Foods Corporation. (2026, February 11). Commercial rollout of SKIPPY protein squeeze packs for active lifestyles. Hormel Media Center.
- [16] The Kraft Heinz Company. (2025, November 18). Expansion of natural almond butter line with clean ingredient deck. Kraft Heinz Newsroom.
- [17] General Mills, Inc. (2025, July 30). Expansion of Annie's organic certified peanut butter distribution in natural food stores. General Mills Corporate.
- [18] Nestle S.A. (2026, January 20). Introduction of fortified nut and seed butter spreads with micro-encapsulated vitamins. Nestle Research & Development.
- [19] Danone S.A. (2025, September 15). Expansion of plant-based almond protein spreads across European health grocers. Danone Corporate News.
- [20] Mondelez International, Inc. (2025, December 10). Rollout of cocoa-blended almond spread with reduced saturated fat. Mondelez Press Room.
- [21] WK Kellogg Co. (2026, March 05). Deployment of roasted peanut butter fillings in high-fiber morning breakfast pastries. WK Kellogg Corporate.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the nut butters market in 2026 and what is forecast for 2036?
- Which consumer snacking habits support steady demand for natural nut spreads?
- Why do slices, shreds & blocks lead the product form / texture category?
- Why does traditional dairy milk lead the source base category globally?
- How do spread growth rates differ across Italy, Denmark, Canada, the USA, Australia, and Germany?
- Which leading food companies supply branded nut butters and culinary ingredients today?
- What agricultural price risks constrain profitability in the nut butters market?
- What should grocery buyers evaluate before selecting a nut butter supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form / Texture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form / Texture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form / Texture, 2026 to 2036
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
- Y-o-Y Growth Trend Analysis By Product Form / Texture, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form / Texture, 2026 to 2036
- Global Market Analysis and Forecast, By Source Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Base, 2026 to 2036
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
- Y-o-Y Growth Trend Analysis By Source Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Base, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor / Variant, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor / Variant, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor / Variant, 2026 to 2036
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
- Y-o-Y Growth Trend Analysis By Flavor / Variant, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor / Variant, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Argentina
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- France
- Denmark
- Spain
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Hungary
- Romania
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia and New Zealand
- ASEAN
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkey
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Denmark
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Hormel Foods Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Kraft Heinz Company
- General Mills, Inc.
- Campbell Soup Company
- Nestle S.A.
- Danone S.A.
- Mondelez International, Inc.
- WK Kellogg Co
- Tyson Foods, Inc.
- Hormel Foods Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Form / Texture, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Source Base, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Flavor / Variant, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Form / Texture
- Figure 6: Global Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Source Base
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Flavor / Variant
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Form / Texture
- Figure 29: North America Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source Base
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Flavor / Variant
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Form / Texture
- Figure 42: Latin America Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Source Base
- Figure 45: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Flavor / Variant
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Form / Texture
- Figure 55: Western Europe Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Source Base
- Figure 58: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Flavor / Variant
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Form / Texture
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Source Base
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Flavor / Variant
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Form / Texture
- Figure 81: East Asia Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Source Base
- Figure 84: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Flavor / Variant
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Form / Texture
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Source Base
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Flavor / Variant
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Form / Texture, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form / Texture, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Form / Texture
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Source Base, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Source Base, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Source Base
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Flavor / Variant, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor / Variant, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Flavor / Variant
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Nut Butters Market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global nut butters market will reach USD 4.8 Billion in 2026. The market is projected to reach USD 8.8 Billion by 2036, driven by rising plant protein snacking and natural clean-label food demand.
What is the CAGR for the Nut Butters Market from 2026 to 2036?
According to Future Market Insights, the market is projected to expand at a 6.2% CAGR over the assessment period. Growth is supported by daily breakfast routines and fitness-driven consumer adoption.
Which product form / texture segment leads the nut butters market?
As per FMI, slices, shreds & blocks will hold a 46.3% share in 2026. The segment benefits from commercial foodservice handling convenience, exact portion control, and bakery baking applications.
Which source base segment leads the Nut Butters Market?
Food industry research indicates that traditional dairy milk blends will account for a 54.9% share in 2026. Demand is underpinned by familiar creamy dairy fat mouthfeel and superior emulsion stability during room-temperature storage.
Which country has a notable growth outlook during the assessment period?
FMI finds that Italy is projected to register a 7.6% CAGR from 2026 to 2036. High market growth is supported by rich artisan confectionery traditions, hazelnut heritage, and organic grocery adoption.
Who are the key players in the market?
Key participants include Hormel Foods Corporation, The Kraft Heinz Company, General Mills, Inc., Campbell Soup Company, Nestle S.A., Danone S.A., Mondelez International, Inc., WK Kellogg Co, and Tyson Foods, Inc. Leading market participants focus on clean-label formulations, on-the-go squeeze pouches, and organic nut sourcing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
