

- Market Size (2026)
- USD 49.6 Bn
- Forecast (2036)
- USD 199.3 Bn
- CAGR (2026 to 2036)
- 15.0%
How big is Nutraceutical Gummies Market in 2026?
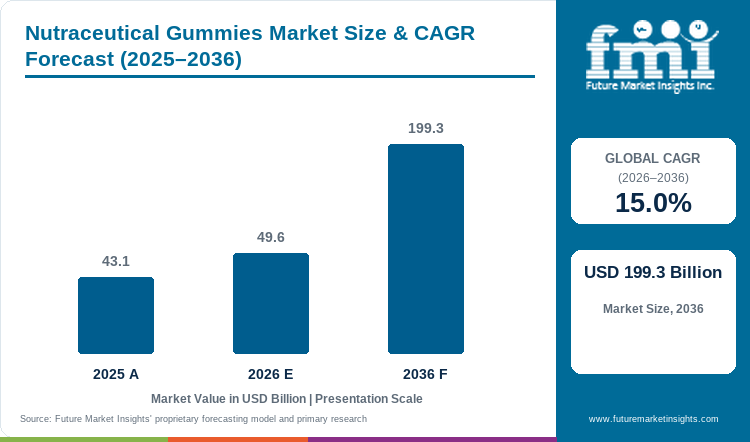
USD 49.6 Billion in 2026 and USD 199.3 Billion by 2036 at a 15.0% CAGR.
Sales of nutraceutical gummies are estimated to grow at 15.0% from USD 49.6 Billion in 2026 to USD 199.3 Billion by 2036. The market was valued at USD 43.1 Billion in 2025. Supplement use already forms part of everyday health routines in several major markets. The US National Center for Health Statistics reported in May 2026 that 60.2% of adults and 35.7% of youth had used a dietary supplement during the surveyed period.
Gummies compete for consumers who already buy tablets, capsules and powders, rather than relying solely on first-time supplement users. This connects demand with the wider gummy supplements market and dietary supplement market. The commercial advantage comes from easier daily use, but manufacturers still need controlled nutrient levels and a claims position that works in the destination country.
Key Takeaways of Nutraceutical Gummies Market
- Established supplement-taking habits support demand for chewable daily nutrition formats.
- In 2026, Vitamin & Minerals leads the Nutritional Class segment with a 31.0% share, while Immunity & Strength accounts for 26.0% of Functionality demand.
- Adult accounts for 61.0% of the Age category in 2026, while Drugstores lead the Distribution Channel with a 28.0% share.
- Stability, dose consistency, and country-specific supplement rules remain important barriers to faster product launches.
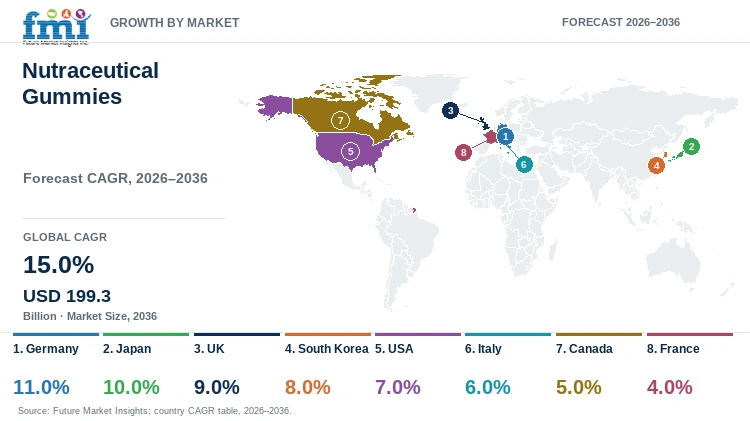
- Germany records the highest profiled CAGR at 11.0%, followed by Japan at 10.0%, reflecting different growth conditions across the two markets.
- Notable participants include Piping Rock Health Products, H&H Group, Amway, Bayer AG, Haleon, Nestlé, Unilever, Otsuka Holdings, Swanson, and Herbaland Naturals.
Analyst Perspective
“The best gummy platform makes daily supplementation easier without lowering the quality standard applied to conventional formats. Taste helps secure trial, but accurate formulation, shelf-life stability and a clear functional proposition are what support repeat purchasing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Nutraceutical Gummies Market segmented?
The Nutraceutical Gummies Market is segmented by Nutritional Class, Functionality, Age, Distribution Channel and Region.
Nutritional Class comprises Vitamin & Minerals, Prebiotics & Probiotics, Polyunsaturated & Fatty Acids, Antioxidants, Vitamin C, Calcium & Vitamin D, Dietary Fiber, B Complex, Iron and Others. Functionality includes Immunity & Strength, Digestive Health, Bone & Muscles Health, Cardiovascular Health and Others. Age comprises Adult, Pediatric and Geriatric. Distribution Channel comprises Drugstores, Retail Pharmacies, Hospital Pharmacies, Supermarkets and Online Stores.
Why does Vitamin & Minerals lead demand within the Nutritional Class category?
Vitamin and mineral gummies translate familiar supplement ingredients into a chewable format, allowing manufacturers to address daily multivitamin use as well as more focused requirements such as vitamin C, vitamin D, iron or B vitamins. The category also overlaps naturally with the vitamin gummies market. Formulation becomes more demanding when a product combines several nutrients or uses actives that are sensitive to heat, moisture or oxidation.
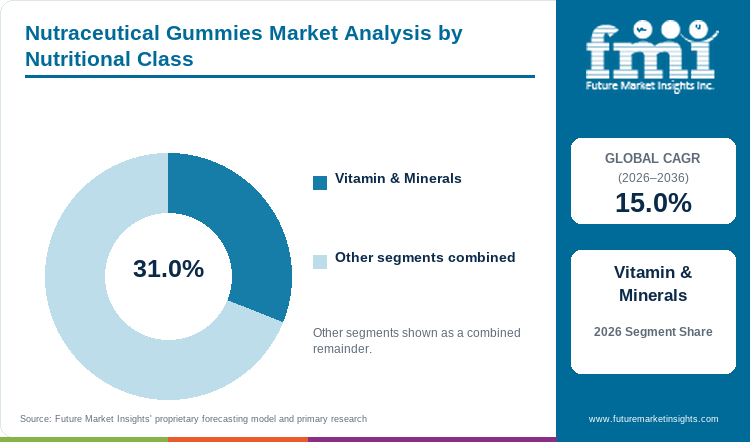
- Vitamin & Minerals accounts for 31.0% of Nutritional Class demand in 2026.
- Bayer launched One A Day Kids Multi with Iron in July 2025, a gummy multivitamin delivering 12 mg of iron per serving, as part of a new Kids line that also includes a standard multivitamin gummy and a probiotic gummy variant.
Why does Immunity & Strength lead demand within the Functionality category?
Immunity & Strength gives consumers an easily understood reason for taking a daily gummy. Familiar nutrients such as vitamin C, vitamin D and zinc allow manufacturers to communicate the proposition without relying on an unfamiliar ingredient story. Products can also combine immune positioning with broader everyday nutrition, as seen across the vitamin supplement market.
- Immunity & Strength holds 26.0% of the Functionality category in 2026.
- Current gummy portfolios from major brands combine immune-support nutrients with multivitamin, digestive and daily-wellness propositions.
Why does Adult lead demand within the Age category?
Adults provide the broadest set of gummy purchasing occasions. Products span multivitamins, beauty, digestive health, sleep, stress, prenatal nutrition and healthy-aging requirements. NCHS reported in May 2026 that US supplement use increased with age among adults, creating a large established audience that manufacturers can address with life-stage formulations.
- Adult accounts for 61.0% of Age demand in 2026.
- Adult-oriented propositions range from general multivitamins to targeted wellness products, supporting broader portfolio depth than a single pediatric need state.
Why do Drugstores lead demand within the Distribution Channel category?
Drugstores combine everyday accessibility with a retail environment already associated with vitamins and wellness products. Consumers can compare gummy products against tablets, capsules and other supplement formats in the same location, while recognized brands benefit from established health-category traffic. Online channels widen assortment, but physical drugstores retain value where buyers want immediate purchase and straightforward label comparison.
- Drugstores account for 28.0% of Distribution Channel demand in 2026.
- Bayer's One A Day portfolio refresh began appearing through Walgreens, CVS, Walmart, Target and Amazon in September 2025, illustrating the coordinated role of drug, mass and online distribution.
What are the drivers, restraints and opportunities in the Nutraceutical Gummies Market?
Established supplement routines support gummy adoption, formulation and compliance requirements restrain execution, and improved manufacturing platforms create room for more sophisticated products.
- Driver: Consumers already accustomed to supplements can shift daily routines toward chewable formats.
- Restraint: Stability and dose accuracy become more difficult to control as formulations incorporate sensitive or high-load actives.
- Opportunity: Advances in delivery technology and dedicated manufacturing infrastructure open the door to a wider range of functional gummy products.
A large existing supplement population reduces the need to educate consumers about supplementation itself. Manufacturers instead compete for format preference. Gummies can offer easier consumption and differentiated flavor while delivering familiar nutrients. This also creates opportunities alongside the multivitamin gummies market, particularly for brands targeting daily-use consumers.
Technical execution remains a constraint. A gummy is a food-like matrix carrying ingredients that may respond differently to heat and moisture. Manufacturers must manage potency through processing and storage while maintaining an acceptable texture. The problem becomes more difficult when several active ingredients are combined or when the formulation also targets lower sugar.
Manufacturing investment creates a route to address these limits. Pharmavite opened its New Albany, Ohio, facility in 2025 specifically for gummy supplements. The site includes a Gummies Innovation Center of Excellence and manufactures Nature Made gummies, linking formulation development with dedicated production capacity.
Which country CAGRs are profiled in the Nutraceutical Gummies Market?
| Country | CAGR |
|---|---|
| Germany | 11.0% |
| Japan | 10.0% |
| UK | 9.0% |
| South Korea | 8.0% |
| USA | 7.0% |
| Italy | 6.0% |
| Canada | 5.0% |
| France | 4.0% |
How do country-level CAGRs compare in the Nutraceutical Gummies Market?
Germany and Japan form the highest-growth group at 11.0% and 10.0%, respectively. The UK, South Korea and USA range from 7.0% to 9.0%, while Italy, Canada and France form the lower-growth group at 4.0% to 6.0%. Germany's forecast is 7.0 percentage points above France over 2026 to 2036.
- Germany: Germany leads the profiled countries at 11.0% CAGR. Nutrient dose remains a commercial consideration because German authorities continue to evaluate upper intake levels for vitamins and minerals used in supplements. BfR updated its proposed maximum level for iodine in supplements in 2025, reinforcing the importance of designing gummy formulas around measured daily intake rather than flavor or convenience alone.
- Japan: Japan is forecast at 10.0% CAGR. Functional positioning requires careful evidence management. The Consumer Affairs Agency states that businesses using the Foods with Function Claims system submit safety and functionality information before launch and remain responsible for the claim. Updated guidance and system changes continued during 2025 and 2026.
- UK: The UK market is projected to grow at 9.0% CAGR. Food Standards Agency guidance published in June 2026 explicitly identifies gummies as a food-supplement format. Brands can therefore use the format across daily nutrition propositions, while ingredient choice, recommended intake and product communication still operate within food-supplement requirements.
- South Korea: South Korea is forecast at 8.0% CAGR. MFDS amended its Health Functional Food Code in March 2025, including changes to specifications, intake levels and precautions for several functional ingredients and nutrients. Manufacturers need enough formulation flexibility to respond when ingredient conditions change.
- USA: The USA is projected at 7.0% CAGR. The market benefits from a large existing supplement-taking population. NCHS reported supplement use among 60.2% of adults and 35.7% of youth, giving gummy brands a substantial base of consumers already accustomed to daily nutritional products.
- Italy: Italy is forecast at 6.0% CAGR. Ministry of Health information updated in March 2025 requires electronic notification for individual food supplements before market entry. Manufacturers therefore need label preparation and formula documentation ready before broader channel rollout.
- Canada: Canada is projected at 5.0% CAGR. Health Canada's revised natural-health-product GMP guide was published in September 2025 and became effective in March 2026. It covers manufacturing, packaging, labeling, importing, testing and other quality activities, raising the importance of documented quality systems for both brand owners and contract manufacturers.
- France: France is forecast at 4.0% CAGR. DGCCRF reported in November 2025 that one-third of 270 supplement establishments checked in its review had anomalies. Testing of children's supplements also identified repeated differences between declared and measured nutrient levels, making composition control particularly important for family and pediatric gummies.
Country-wise Analysis
- Germany is projected to record an 11.0% CAGR from 2026 to 2036, the highest among the profiled countries. Growth is supported by an established supplement market in which gummies can extend familiar vitamin and mineral routines into a more convenient dosage form. Formulation discipline remains important because German authorities continue to assess appropriate nutrient levels in food supplements. In December 2025, the Federal Institute for Risk Assessment updated its recommendations for iodine, proposing a maximum of 100 micrograms per recommended daily intake for supplements intended for people aged 15 years and above, with a higher level for pregnant and breastfeeding women. This type of guidance directly affects multivitamin development because a gummy has to balance taste, serving size and nutrient loading without creating an impractical number of pieces per daily dose. Manufacturers serving Germany can therefore compete through better formulation efficiency and clearer dose architecture. Products designed for drugstores and pharmacies also benefit when the nutritional proposition can be understood quickly from the label without relying on aggressive health claims.
- Japan is forecast to expand at a 10.0% CAGR from 2026 to 2036. Functional gummies have an attractive route to market because the format can combine convenience with specific digestive, sleep, beauty or daily-wellness propositions, but the regulatory environment places substantial responsibility on the business making the claim. Japan's Consumer Affairs Agency operates the Foods with Function Claims notification system and maintains a public database containing submitted product information and scientific support. The system was further strengthened following changes to the functional-food framework, with manufacturing and labeling requirements becoming more demanding and GMP-related transition measures running through August 2026. For gummy suppliers, this makes documentation part of product development rather than an activity that begins after the formulation is complete. Ingredient quantities, serving sizes, stability and claim wording need to remain aligned. Companies that can adapt gummy matrices around locally acceptable functional ingredients while keeping the daily serving convenient are better placed to serve Japan's market. The commercial advantage comes from combining easy consumption with a formulation that can support the exact positioning used on the finished product.
- The UK nutraceutical gummies market is projected to grow at a 9.0% CAGR between 2026 and 2036. The market benefits from broad consumer familiarity with supplements and multiple routes to purchase through pharmacies, supermarkets, specialist retailers and e-commerce. Updated UK government guidance published in June 2026 explicitly identifies gummies among the dose forms used for food supplements, alongside capsules, powders and pills. This gives the format a clear place within the established supplement framework rather than treating it as conventional confectionery. The commercial opportunity is strongest where gummy convenience is combined with an easily understood nutritional purpose such as vitamin D, multivitamins, children's nutrition or targeted wellness. Product development still needs to account for recommended intake, permitted ingredients and compliant communication. Higher active loads can also create texture and serving-size challenges, especially when manufacturers try to reduce sugar or combine several nutrients in a single gummy. Brands that simplify the daily regimen without overcrowding the formulation can compete effectively across both physical retail and online channels while keeping the proposition recognizably nutritional rather than confectionery-led.
- South Korea is forecast to expand at an 8.0% CAGR from 2026 to 2036. Demand for functional nutrition gives gummies room to develop as a convenient alternative to traditional tablets and capsules, but manufacturers need sufficient formulation flexibility to respond to changes in the country's Health Functional Food Code. In March 2025, the Ministry of Food and Drug Safety amended standards and specifications following safety and functionality reassessments covering several functional ingredients and nutrients. The changes included revised specifications, daily intake levels and precautions for certain ingredients. This matters commercially because a gummy formulation often combines several active components within a fixed serving size. A regulatory change to one ingredient can therefore affect dose design, flavor, texture and label information across the complete product. Suppliers able to reformulate quickly have an advantage when brands refresh existing products or build new function-led lines. Digestive health, immunity and everyday nutrition remain practical propositions, but manufacturers need to treat regulatory monitoring as part of portfolio management. Faster growth will favor companies that can preserve palatability while adjusting ingredient loads without disrupting the consumer's daily serving routine.
- The USA is projected to grow at a 7.0% CAGR from 2026 to 2036 and offers one of the deepest established consumer bases for nutraceutical gummies. National Center for Health Statistics data released in May 2026 show that 60.2% of US adults and 35.7% of youth used a dietary supplement during the surveyed period. Among adults, supplement use increased with age, while 38.7% used two or more supplements. This creates several commercial openings for gummies because brands can target consumers who already understand daily supplementation rather than build the behavior from the beginning. Adult multivitamins, women's health, beauty, sleep, digestive wellness and healthy-aging products can all be positioned around distinct routines. Pediatric gummies provide another route, particularly where taste and ease of consumption reduce resistance to conventional formats. The challenge is avoiding formulation overload as brands combine more nutrients and functions. Larger ingredient loads can increase the number of gummies required per serving or affect taste and texture. Suppliers that offer stable formulations with simple daily dosing can therefore compete on convenience without sacrificing the nutritional proposition.
- Italy is forecast to record a 6.0% CAGR from 2026 to 2036. Gummies can benefit from the country's established food-supplement channel because the format allows familiar vitamin, mineral and functional ingredients to be presented in a portable and consumer-friendly form. Market access, however, requires preparation before distribution begins. Italy's Ministry of Health updated its supplement notification information in March 2025 and states that each food supplement subject to notification must be submitted electronically before it is placed on the market. The Ministry assesses conformity with applicable requirements and can request changes, including amendments to the label. This makes formulation and label development closely connected. A brand planning several gummy variants cannot assume that one notification or one label approach covers the entire portfolio. Different nutrient levels, functional ingredients or serving instructions can create separate requirements. Manufacturers that finalize composition and claims early can reduce rework before pharmacy, parapharmacy or online expansion. The opportunity is therefore strongest for suppliers that combine formulation flexibility with disciplined launch preparation, especially for multivitamin, beauty, digestive and adult wellness propositions.
- Canada is projected to expand at a 5.0% CAGR from 2026 to 2036. Nutraceutical gummies operate within the country's natural health product framework, which places substantial weight on manufacturing quality as well as the finished consumer proposition. Health Canada published version 4.0 of its Good Manufacturing Practices guide for natural health products in September 2025, with the guidance taking effect on March 4, 2026. It applies across manufacturing, packaging, labeling, importing, distributing, storage and testing activities. The guide also addresses specifications, quality assurance, stability, records, samples and recall processes. These requirements are particularly relevant to gummies because moisture, temperature and formulation interactions can affect texture and active-ingredient stability over shelf life. Brands using contract manufacturers therefore need more than an attractive prototype. They need a production system capable of maintaining medicinal ingredient quantity, potency and physical characteristics through the declared stability period. Suppliers with strong formulation controls and scalable gummy manufacturing can use this environment to differentiate themselves, particularly when serving multivitamin, women's health, children's and targeted functional products.
- France is forecast to grow at a 4.0% CAGR from 2026 to 2036. The comparatively lower profiled growth rate still sits within an active supplement market where gummies have gained visibility, particularly among younger consumers. In November 2025, France's DGCCRF described gummies as a format that had become especially popular with younger buyers while reporting persistent compliance problems across the wider food-supplement sector. Its review of 2023 controls found anomalies at roughly one-third of 270 establishments examined, including problems involving therapeutic claims, unsupported claims and product composition. For nutraceutical gummy manufacturers, this increases the commercial importance of analytical control and conservative product communication. The format's confectionery-like appearance can support trial, but it also places greater responsibility on brands to communicate dosage and nutritional purpose clearly, especially for products aimed at children or families. Manufacturers that maintain measured nutrient content through shelf life and avoid exaggerated health positioning are better placed to retain pharmacy and retail confidence. In France, quality consistency can therefore become a stronger competitive advantage than adding another flavor or visual novelty to the assortment.
Who are the notable companies in the Nutraceutical Gummies Market?
Piping Rock Health Products, H&H Group, Amway, Bayer AG, Haleon, Nestlé, Unilever, Otsuka Holdings Co., Ltd., Swanson and Herbaland Naturals Inc. are notable companies profiled in this market.
Competition spans large consumer-health platforms, specialist supplement brands and dedicated gummy manufacturers. Piping Rock Health Products became the owner of VitaFusion and L'il Critters after completing the acquisition from Church & Dwight at the end of December 2025. The transaction also included associated manufacturing and distribution facilities.
Bayer competes through One A Day, Haleon through Centrum, Nestlé Health Science through Nature's Bounty, Unilever through OLLY, and Otsuka through Pharmavite and Nature Made. H&H operates Swisse and Little Swisse products, while Amway and Swanson maintain direct supplement portfolios. Herbaland has a different position as a specialist gummy manufacturer serving other brands as well as its own business.
- Scaled consumer-health and multivitamin platforms: Piping Rock Health Products; Bayer AG; Haleon; Nestlé; Unilever; Otsuka Holdings Co., Ltd.
- Specialist and direct-selling nutrition portfolios: H&H Group; Amway; Swanson.
- Dedicated gummy manufacturing: Herbaland Naturals Inc.
Competitive Benchmarking: Nutraceutical Gummies Market
Scoring basis: Gummy Portfolio Breadth is High where current offerings span several gummy categories and Medium where coverage is narrower. Life-Stage & Functional Coverage is High where gummies serve multiple ages or wellness needs and Medium where the offer is more focused. Gummy Manufacturing / Formulation Control is High where dedicated gummy manufacturing or R&D capability is documented. Unscored remains a table state where comparable manufacturing evidence is not assigned.
| Company | Gummy Portfolio Breadth | Life-Stage & Functional Coverage | Geographic Reach |
|---|---|---|---|
| Piping Rock Health Products | High | High | USA gummy portfolio through VitaFusion and L'il Critters |
| H&H Group | Medium | Medium | Australia, New Zealand and wider Swisse markets |
| Amway | Medium | Medium | Global direct-selling network |
| Bayer AG | High | High | Major US retail channels with broader global Consumer Health reach |
| Haleon | High | High | Centrum platform across international markets |
| Nestlé | High | High | Global Nestlé Health Science channels with Nature's Bounty gummy products |
| Unilever | High | High | OLLY gummy portfolio with broad US consumer reach |
| Otsuka Holdings Co., Ltd. | High | High | USA manufacturing through Pharmavite with selected international Nature Made markets |
| Swanson | High | High | US direct-to-consumer and online distribution |
| Herbaland Naturals Inc. | High | High | Canadian manufacturing with exports to more than 40 countries |
Current product pages show broad gummy assortments across VitaFusion, Centrum, Nature's Bounty, OLLY and Swanson, while Herbaland documents dedicated contract manufacturing and international supply.
Key Developments in the Nutraceutical Gummies Market
- In July 2026, Bayer AG reformulated One A Day Women's Multi Gummy to deliver 1,000 mcg of biotin per serving alongside vitamins A, C and E and zinc, strengthening its life-stage and beauty-oriented positioning within the gummy portfolio.
- In December 2025, Piping Rock Health Products completed the acquisition of VitaFusion, L'il Critters and their associated manufacturing and distribution facilities from Church & Dwight.
- In May 2025, Otsuka subsidiary Pharmavite opened a dedicated gummy supplement manufacturing facility in New Albany, Ohio. The site celebrated its grand opening on May 8, 2025 and includes a Gummies Innovation Center of Excellence.
Key Players in the Nutraceutical Gummies Market
Scaled consumer-health and multivitamin platforms
- Piping Rock Health Products
- Bayer AG
- Haleon
- Nestlé
- Unilever
- Otsuka Holdings Co., Ltd.
Specialist and direct-selling nutrition portfolios
- H&H Group
- Amway
- Swanson
Dedicated gummy manufacturing
- Herbaland Naturals Inc.
Nutraceutical Gummies Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Nutritional Class; Functionality; Age; Distribution Channel; Region |
| Quantitative Units | Revenue in USD Billion and CAGR in %. |
| Market Definition | Revenue from nutraceutical products sold in gummy form across the defined nutritional classes, functionalities, age groups and distribution channels. Conventional confectionery, medicinal gummies regulated as drugs, adjacent tablet, capsule, powder and liquid formats, standalone ingredient revenue and products where the gummy is not separately priced are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany; Japan; UK; South Korea; USA; Italy; Canada; France |
| Key Companies Profiled | Piping Rock Health Products; H&H Group; Amway; Bayer AG; Haleon; Nestlé; Unilever; Otsuka Holdings Co., Ltd.; Swanson; Herbaland Naturals Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Nutraceutical Gummies Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from gummy manufacturers, supplement brands, retailers, pharmacies, distributors, contract manufacturers, procurement teams and subject-matter experts. Interviews examined formulation requirements, purchasing behavior, quality expectations, channel conditions and commercial barriers. |
| Desk Research | Desk research covered government publications, supplement regulations, company filings, current product portfolios, manufacturing information and official corporate announcements. |
| Market Sizing and Forecasting | The market model combined the baseline value with segment structure, pricing, consumer adoption, product mix, distribution conditions, company participation and country-level demand trends. |
| Data Validation | Estimates were assessed against independent market indicators, company activity, current product availability, regulatory developments and primary-research findings. |
Nutraceutical Gummies Market by Segments
Nutraceutical Gummies Market segmented by Nutritional Class:
- Vitamin & Minerals
- Prebiotics & Probiotics
- Polyunsaturated & Fatty Acids
- Antioxidants
- Vitamin C
- Calcium & Vitamin D
- Dietary Fiber
- B Complex
- Iron
- Others
Nutraceutical Gummies Market segmented by Functionality:
- Immunity & Strength
- Digestive Health
- Bone & Muscles Health
- Cardiovascular Health
- Others
Nutraceutical Gummies Market segmented by Age:
- Adult
- Pediatric
- Geriatric
Nutraceutical Gummies Market segmented by Distribution Channel:
- Drugstores
- Retail Pharmacies
- Hospital Pharmacies
- Supermarkets
- Online Stores
Nutraceutical Gummies Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- USA National Center for Health Statistics (2026, May). Dietary Supplement Use: United States, August 2021-August 2023.
- German Federal Institute for Risk Assessment (2025). Update 2025: Maximum Levels Proposed for Iodine in Foods, Including Food Supplements.
- Consumer Affairs Agency, Japan (2026). Foods with Health Claims and Foods with Function Claims.
- Food Standards Agency, UK (2026, June 25). Food Supplements Guidance.
- Ministry of Food and Drug Safety, South Korea (2025, March 5). Health Functional Food Code, Notice No. 2025-11.
- Ministry of Health, Italy (2025, March 26). New Notification of a Food Supplement.
- Health Canada (2025, September 4). Good Manufacturing Practices Guide for Natural Health Products, GUI-0158.
- DGCCRF, France (2025, November). Food Supplements: Anomalies Still Too Numerous.
- Bayer AG (2025, July 23). One A Day Launches First of Its Kind Multivitamin Gummy with Iron to Help Fill Nutrient Gaps in Kids.
- Bayer AG (2025, October). One A Day Unveils New Brand Identity and Platform.
- Otsuka Pharmaceutical Co., Ltd. (2025, May 9). Pharmavite Opens Dedicated Gummy Supplement Facility in Ohio.
- Church & Dwight Co., Inc. (2026, January). Completion of VitaFusion and L'il Critters Sale to Piping Rock.
- H&H Group (2026, March). 2025 Annual Results.
- H&H Group (2025). Interim Results 2025.
- Herbaland Naturals Inc. (current). Contract Manufacturing.
- VitaFusion (current). Gummy Vitamin Portfolio.
- Centrum (current). MultiGummies Portfolio.
- Nature's Bounty (current). Gummy Vitamin Supplements.
- OLLY (2026). Gummy Supplement Portfolio.
- Swanson (current). Gummy Vitamins and Supplements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Nutraceutical Gummies Market in 2026 and what value is forecast for 2036?
- Which consumer routines and formulation requirements support nutraceutical gummy demand?
- Why does Vitamin & Minerals lead Nutritional Class?
- Why does Immunity & Strength lead Functionality?
- Why does Adult lead the Age category and Drugstores lead Distribution Channel?
- How do growth rates differ across the profiled countries?
- Which companies compete through branded gummies or manufacturing capability?
- What should buyers assess before listing or manufacturing a nutraceutical gummy?
Frequently Asked Questions
How big is the Nutraceutical Gummies Market in 2026 and what is forecast for 2036?
The Nutraceutical Gummies Market is valued at USD 49.6 Billion in 2026 and is forecast to reach USD 199.3 Billion by 2036. The market was valued at USD 43.1 Billion in 2025.
What is the Nutraceutical Gummies Market CAGR from 2026 to 2036?
The market is projected to expand at 15.0% CAGR from 2026 to 2036.
Which Nutritional Class leads the market?
Vitamin & Minerals leads Nutritional Class with 31.0% share in 2026.
Which Functionality leads the market?
Immunity & Strength leads Functionality with 26.0% share in 2026.
Which Age and Distribution Channel segments lead in 2026?
Adult leads the Age category with 61.0%, while Drugstores leads Distribution Channel with 28.0%.
Which profiled countries have the highest growth rates?
Germany has the highest profiled CAGR at 11.0%, followed by Japan at 10.0% and the UK at 9.0%.
Which companies are active in the Nutraceutical Gummies Market?
Piping Rock Health Products, H&H Group, Amway, Bayer AG, Haleon, Nestlé, Unilever, Otsuka Holdings, Swanson and Herbaland Naturals are among the notable participants.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nutritional Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nutritional Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nutritional Class, 2026 to 2036
- Vitamin & Minerals
- Prebiotics & Probiotics
- Polyunsaturated & Fatty Acids
- Antioxidants
- Vitamin C
- Calcium & Vitamin D
- Dietary Fiber
- B Complex
- Iron
- Others
- Y-o-Y Growth Trend Analysis By Nutritional Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Nutritional Class, 2026 to 2036
- Global Market Analysis and Forecast, By Functionality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Functionality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Functionality, 2026 to 2036
- Immunity & Strength
- Digestive Health
- Bone & Muscles Health
- Cardiovascular Health
- Others
- Y-o-Y Growth Trend Analysis By Functionality, 2021 to 2025
- Absolute $ Opportunity Analysis By Functionality, 2026 to 2036
- Global Market Analysis and Forecast, By Age, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Age, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Age, 2026 to 2036
- Adult
- Pediatric
- Geriatric
- Y-o-Y Growth Trend Analysis By Age, 2021 to 2025
- Absolute $ Opportunity Analysis By Age, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Drugstores
- Retail Pharmacies
- Hospital Pharmacies
- Supermarkets
- Online Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nutritional Class
- By Functionality
- By Age
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Piping Rock Health Products
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- H&H Group
- Amway
- Bayer AG
- Haleon
- Nestlé
- Unilever
- Otsuka Holdings Co., Ltd.
- Swanson
- Herbaland Naturals Inc.
- Piping Rock Health Products
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


