

- Market Size (2026)
- USD 7.8 Bn
- Forecast (2036)
- USD 13.2 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Jellies and Gummies Market in 2026?
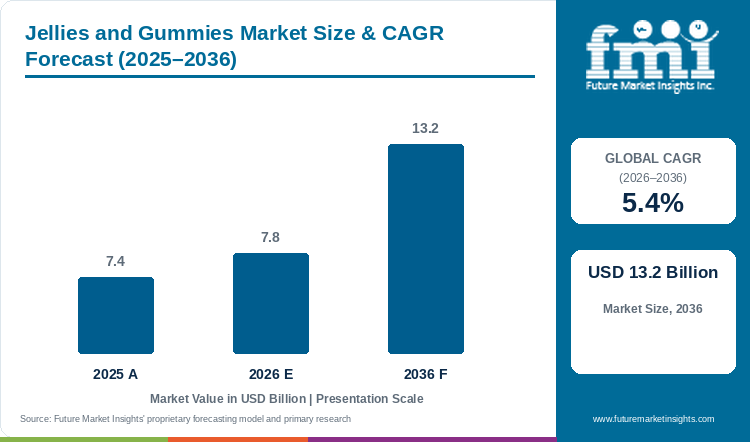
Global jellies and gummies market size is projected to rise from USD 7.4 billion in 2025 to USD 7.8 billion in 2026, advancing at an anticipated 5.4% CAGR to reach USD 13.2 billion by 2036.
Global jellies and gummies market size stands at USD 7.4 billion for 2025 and reaches an estimated USD 7.8 billion during 2026, while a 5.4% projected CAGR carries 2036 valuation to USD 13.2 billion and generates USD 5.4 billion in ten-year expansion. In March 2026, the National Confectioners Association reported that total United States confectionery retail value reached USD 55 billion in 2025 as shoppers turned to dual-textured and sour non-chocolate chewy treats across seasonal and everyday occasions [1]. Enabled by reversible collagen hydrogel elasticity and crystal-clear moulding fidelity, Gelatin-Based Chewy Gummies represent a projected 83.7% of 2026 hydrocolloid gelling agent valuation across starch-mogul lines using food-grade gelatin hydrocolloids. Nevertheless, pork- and bovine-free dietary rules and sugar-sanding stickiness in humid tropical supply chains continue to challenge conventional confectionery recipes.
Key Market Trends & Insights
- By hydrocolloid gelling agent: Elastic 220-to-260-Bloom recovery and body-temperature melting put Gelatin-Based Chewy Gummies at a projected 83.7% share of 2026 gelling-agent valuation.
- By flavor profile: Malic and citric acid sanding that attracts Gen-Z and millennial snackers fuels an estimated 58.9% flavor-profile share for Sour & Tangy Fruit Gummies during 2026.
- By packaging format: Multi-occasion portion control and vertical pegboard visibility give Resealable Stand-Up Peg Bags an expected 60.7% share of 2026 packaging valuation.
- By sugar & functional profile: Shelf-stable 0.75-to-0.82 water activity and glass-transition clarity back a forecast 63.3% share for Conventional Sugar & Glucose Syrup in 2026.
- By distribution channel: Seasonal Halloween and Easter aisle displays together with family multipacks support an anticipated 40.9% channel share for Supermarkets & Hypermarkets in 2026.
Regional Highlights
- Latin American and East Asian expansion: Modern convenience and cash-and-carry confectionery distribution propel Brazilian demand at a 6.4% projected annual clip to 2036 ahead of Mexican (6.1%) and South Korean (5.8%) retail channels.
- North American and Western European progression: Sour-cluster and vegan-pectin sharing-bag launches sustain mature confectionery expansion in the USA (5.1% expected yearly rate) and across German (4.7%) and British (4.5%) grocery banners.
Market Size & Forecast
Table 1: Market Size and Forecast for the Jellies and Gummies Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 7.4 billion |
| Estimated Market Size in 2026 | USD 7.8 billion |
| Projected Market Size by 2036 | USD 13.2 billion |
| CAGR, 2026 to 2036 | 5.4% |
| Added Market Value, 2026 to 2036 | USD 5.4 billion |
Confectionery R&D teams are engineering hybrid gelatin-pectin hydrocolloid networks that preserve firm bite cohesion while carrying natural fruit pigments and botanical extracts. In July 2026, food engineers at Universidad del Bío-Bío published a simplex-centroid formulation study in Gels demonstrating that combining 6% gelatin with 1% low-methoxyl pectin and 7.5% grape extract lowered water activity to 0.925-0.954 and optimized chewiness and cohesiveness [2]. Attributed to these hydrocolloid advances, major candy makers are scaling aerated foam-bottom gummies and liquid-filled chewy bites within the broader global gummy confectionery sector. Consequently, retail buyers are allocating more checkout and center-store peg space to multi-textured gummy bags.
Starch-Mogul Depositing Throughput and Hydrocolloid Sizing
Table 2: Starch-Mogul Depositing Throughput and Hydrocolloid Sizing for the Jellies and Gummies Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 7.4 | 7.8 | 13.2 |
| Commercial jellies & gummies output (million metric tons) | 1.6 to 1.8 | 1.7 to 1.9 | 2.7 to 3.0 |
| Starch-mogul & starchless depositing lines (active units) | 920 to 1,020 | 960 to 1,065 | 1,410 to 1,560 |
| Average realized valuation per kilogram (USD) | 4.2 to 4.6 | 4.3 to 4.7 | 4.6 to 5.1 |
Operational note: Production tonnage and depositing line ranges reconcile NCA non-chocolate confectionery benchmarks and European BDSI sugar confectionery output against standard 2,000-to-3,500-kilogram-per-hour starch-mogul line capacities.
High-speed starch-mogul lines stamp moulding trays filled with conditioned cornstarch at 25 to 35 trays per minute before multi-manifold pistons deposit 78-to-80-Brix cooked slurry. In addition to this, confectionery plants are installing starchless silicone-mould depositors to manufacture pectin-based sugar confectionery without cross-contaminating vegan or vitamin-fortified batches.
Per Capita & Confectionery Line Sizing
Table 3: Per Capita and Line Valuation Indicators for the Jellies and Gummies Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 902.4 | 939.8 | 1,466.7 |
| Annual market valuation per mogul/depositing line (USD million) | 7.2 to 8.1 | 7.4 to 8.3 | 8.5 to 9.6 |
| Dual-texture & sour-sanded SKU share in retail bags (%) | 54.0% to 58.0% | 56.0% to 60.0% | 64.0% to 68.0% |
Table 4: Retail & Packaging Valuation Indicators for the Jellies and Gummies Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 7.8 billion | 2026 global jellies and gummies valuation baseline |
| Gelatin-based chewy gummies valuation, 2026 | USD 6.5 billion | 83.7% hydrocolloid gelling agent allocation |
| Resealable stand-up peg bags valuation, 2026 | USD 4.7 billion | 60.7% packaging format segment allocation |
| Supermarkets & hypermarkets valuation, 2026 | USD 3.2 billion | 40.9% distribution channel segment allocation |
After 24 to 48 hours of curing in temperature-controlled drying rooms, moulded gummies pass through rotary polishing drums coated with carnauba wax or sour acid crystals. To protect polished pieces from moisture pickup, packaging lines feed weighed portions directly into automated pouch loading machines that seal high-barrier stand-up bags.
Analyst Perspective
"Non-chocolate confectionery growth is increasingly anchored by multi-sensory sour, crunchy-coated, and aerated foam gummies packed in resealable stand-up peg bags. Manufacturers that pair high-speed starch-mogul efficiency with heat-stable pectin and allulose options will capture both mainstream supermarket and Halal or vegan retail tiers."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the jellies and gummies market segmented?
The jellies and gummies market is segmented by hydrocolloid gelling agent, flavor profile, packaging format, sugar and functional profile, distribution channel, and region. In 2026, Gelatin-Based Chewy Gummies is projected at 83.7%, Sour & Tangy Fruit Gummies at 58.9%, Resealable Stand-Up Peg Bags at 60.7%, Conventional Sugar & Glucose Syrup at 63.3%, and Supermarkets & Hypermarkets at 40.9%.
By hydrocolloid gelling agent: Gelatin-Based Chewy Gummies, and Pectin, Starch & Agar Vegan Jellies.
By flavor profile: Sour & Tangy Fruit Gummies, Sweet Classic Berry & Citrus, and Botanical & Cola Flavors.
By packaging format: Resealable Stand-Up Peg Bags, Single-Serve Impulse Pouches, and Bulk Tubs.
By sugar & functional profile: Conventional Sugar & Glucose Syrup, Reduced-Sugar, Allulose & High-Fiber, and Vitamin- & Botanical-Fortified Confectionery.
By distribution channel: Supermarkets & Hypermarkets, Convenience Stores & Gas Forecourts, and Cinema, Travel Retail & E-Commerce.
Why do Gelatin-Based Chewy Gummies lead the hydrocolloid gelling agent category?
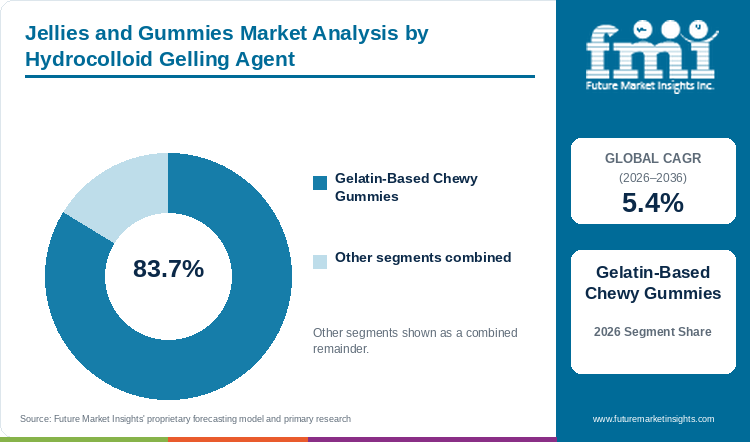
Gelatin-Based Chewy Gummies are projected to capture 83.7% of gelling agent market value in 2026, driven by elastic chew.
Table 5: Hydrocolloid Gelling Agent Share for the Jellies and Gummies Market (percentage share), 2026
| Hydrocolloid Gelling Agent | Share (2026) |
|---|---|
| Gelatin-Based Chewy Gummies | 83.7% |
| Other Segments Combined | 16.3%* |
| Total | 100.0% |
*Note: Combined share of remaining hydrocolloid gelling agent categories totaling 100.0% of 2026 market valuation.
Table 6: Hydrocolloid Gelling Agent Leadership and Market Growth for the Jellies and Gummies Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Leading Segment | Gelatin-Based Chewy Gummies |
Porcine and bovine Type A and Type B gelatins form thermo-reversible triple-helix networks that melt at 35 to 37 degrees Celsius, giving classic gummy bears their signature bounce and burst of fruit flavor in the mouth. At the same time, vegan pectin and agar jellies are expanding rapidly among plant-based and Halal shoppers who prefer clean-bite vegan confectionery formulations. High-speed confectioners also blend gelatin with whipped egg or milk proteins to deposit two-layer foam gummies.
- Unmatched tensile springiness and whipped-foam aeration allow Gelatin-Based Chewy Gummies to hold a projected 83.7% of 2026 hydrocolloid gelling agent valuation.
- In July 2026, a comprehensive review published in Foods examined hydrocolloid matrix engineering across gelatin and pectin gummy formulations to balance chewiness and shelf stability [3].
Why do Sour & Tangy Fruit Gummies define the largest flavor profile segment?
Sour & Tangy Fruit Gummies are estimated to secure 58.9% of flavor profile valuation in 2026, fueled by acid-sanded coatings.
Fruit-flavored gummy pieces coated with encapsulated malic and citric acid crystals create an immediate tart-then-sweet sensory contrast that drives high repeat purchase among teenagers and young adults. While Sweet Classic Berry & Citrus and Botanical & Cola Flavors remain staple family assortments, sour worms and crunchy-shelled gummy clusters lead incremental velocity in convenience and grocery aisles that also carry high-methoxyl citrus pectin jellies. Confectioners use fat-encapsulated acidulants so sour sanding does not draw moisture out of the gummy core.
- Strong Gen-Z preference for multi-layered tart and spicy-fruit profiles gives Sour & Tangy Fruit Gummies an estimated 58.9% share of 2026 flavor-profile market value.
- In October 2025, the National Confectioners Association reported in its Getting to Know Candy Consumers study that sour and textural gummy momentum will push United States non-chocolate candy retail value to USD 27.8 billion come 2030 [4].
What keeps Resealable Stand-Up Peg Bags ahead by packaging format?
Resealable Stand-Up Peg Bags are expected to command 60.7% of packaging format valuation in 2026, supported by zipper freshness.
Gusseted bottom pouches fitted with press-to-close zipper tracks and euro-slot hang holes allow retailers to display 140-gram to 280-gram sharing bags either upright on shelves or suspended on vertical pegboards. Because re-closing the bag blocks ambient humidity between snacking sessions, Resealable Stand-Up Peg Bags prevent pectin and gelatin pieces from hardening or sticking together when compared with open tear-top pouches. Candy brands increasingly source recyclable mono-material films from stand-up zipper pouch converters while using Single-Serve Impulse Pouches and Bulk Tubs for checkout counters and club stores.
- Resealable Stand-Up Peg Bags are expected to hold 60.7% of packaging format market value in 2026 due to multi-serve household sharing and moisture-barrier protection.
- In 2026, the National Confectioners Association's State of Treating report highlighted how resealable sharing bags and portion-guidance packs fit multi-occasion household treating routines [5].
Why does Conventional Sugar & Glucose Syrup lead the sugar and functional profile category?
Conventional Sugar & Glucose Syrup is forecast to generate 63.3% of profile valuation in 2026, backed by sucrose-syrup clarity.
Granulated sucrose cooked with 42-DE or 63-DE corn glucose syrup creates an amorphous sugar glass matrix that inhibits sucrose recrystallization and locks water activity between 0.75 and 0.82 without artificial preservatives. Simultaneously, reduced-sugar allulose and vitamin-fortified confectionery lines are expanding as shoppers adopt rare-sugar allulose sweeteners and sugar-free gummy formulations. Mainstream holiday and movie-theater treating nonetheless remains anchored by classic sucrose-and-glucose recipes.
- Low sweetener cost and glossy translucent appearance give Conventional Sugar & Glucose Syrup 63.3% of forecast 2026 sugar and functional profile valuation.
- In 2026, food scientists indexed in PubMed Central (PMC12701288) demonstrated that incorporating polyphenol-rich peanut-skin bioactive extracts into gelatin and pectin gummy matrices preserves gloss and elasticity while adding dietary antioxidants [6].
What gives Supermarkets & Hypermarkets the leading position in distribution channel?
Supermarkets & Hypermarkets are anticipated to account for 40.9% of channel valuation in 2026, enabled by seasonal promotional aisles.
Large-format grocery chains and hypermarkets anchor global volume because they combine year-round center-store pegboard bays with massive promotional endcaps across Halloween and Easter seasons. Shoppers buying weekly groceries routinely add multipack gummy pouches and family sharing bags to their carts while also browsing nutraceutical gummy supplements in adjacent wellness aisles. Meanwhile, convenience stores and gas forecourts together with travel retail and e-commerce channels capture high-margin road-trip and movie-night impulse purchases.
- Supermarkets & Hypermarkets are anticipated to capture 40.9% of distribution channel market value in 2026 because multi-bag promotions and holiday displays drive high basket penetration.
- In February 2026, Mondelēz International reported full-year 2025 net revenues of USD 38.54 billion in its SEC Form 10-K filing, supported by strong supermarket and convenience distribution of Sour Patch Kids and Maynards Bassetts gummies [7].
What are the drivers, restraints, and opportunities in the jellies and gummies market?
Across the jellies and gummies market, dual-textured sour and crunchy-cluster formats are projected to expand category valuation whereas gelatin hide costs and sugar taxation restrain margins and vegan pectin-allulose gummies create growth opportunities.
- Driver: Rapid consumer adoption of multi-textured sour and crunchy-coated gummy clusters across social-media-driven snacking occasions boosts per-kilogram realizations.
- Restraint: Front-of-pack high-sugar warning labels in Latin America and Europe together with volatile porcine and bovine gelatin hide prices pressure manufacturing margins.
- Opportunity: Heat-resistant pectin vegan jellies sweetened with allulose and soluble prebiotic fibers unlock Halal and better-for-you snacking channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Confectionery shoppers increasingly favor chewy gummies that combine contrasting textures such as crunchy mini-candy shells over tangy gummy centers or aerated marshmallow foam bonded to fruit jelly. Unlike flat single-flavor jellies, 3D-moulded peelable fruit gummies and crunchy clusters command 25% to 40% higher retail prices per ounce and drive viral trial across convenience and grocery channels together with functional gummy supplement formats. In February 2026, Ferrara Candy Company announced strong fiscal 2025 performance led by NERDS Gummy Clusters and SweeTARTS gummy innovations across North American retail banners [8]. Confectionery manufacturers are therefore investing in multi-head co-depositors and automated panning lines.
Risk Assessment of the Jellies and Gummies Market: Operational and Formulation Friction
Sugar confectionery producers confront rising raw material and energy costs as well as mandatory front-of-pack nutritional warning octagons in Mexico and Brazil and HFSS promotional restrictions in the United Kingdom. Furthermore, traditional porcine gelatin gummies cannot be sold in Halal or Kosher markets and tend to soften or sweat when warehouse temperatures exceed 32 degrees Celsius. In January 2026, the Association of the German Confectionery Industry (BDSI) highlighted ongoing cost pressures from sugar and gelatin inputs as well as energy and packaging tariffs across German candy exporters [9]. Manufacturers serving price-sensitive grocery tiers must therefore optimize bag weights and starch-drying energy consumption.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Buffered citrus pectin and rare-sugar allulose allow brands to replace animal gelatin and high-fructose corn syrup while capturing vegan and Halal shoppers simultaneously. Because citrus pectin gels set at higher temperatures (75 to 85 degrees Celsius) and resist melting in warm delivery vans, pectin jellies hold their shape across tropical Latin American and Asian convenience stores. In 2026, Katjes Fassin GmbH + Co. KG expanded its 100% animal-gelatin-free vegan fruit gummy range across European and United States grocery shelves without palm oil or high-fructose corn syrup [10]. Confectioners that pair plant-based hydrocolloids with natural spirulina and black carrot colors can win clean-label supermarket endcaps.
Jellies and Gummies Market by Country (2026 to 2036)
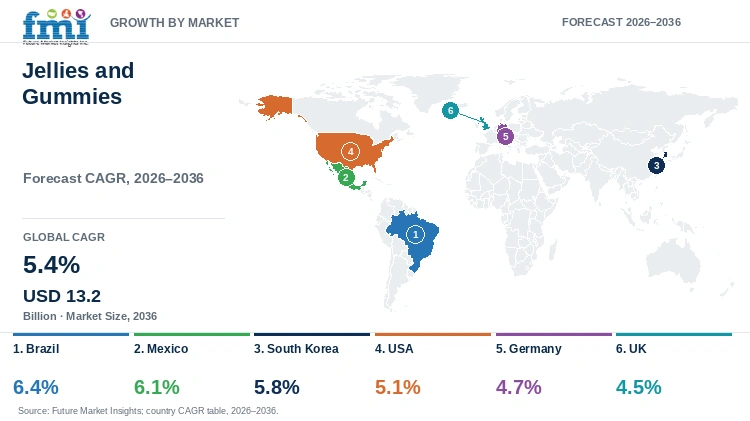
Country-level confectionery modeling shows Brazil (6.4% yearly rate) and Mexico (6.1%) outpacing South Korea (5.8%) over 2026 to 2036, while high-tonnage grocery channels in the USA (5.1%) and Germany (4.7%) as well as the UK (4.5%) sustain steady gains. Tropical heat-stable pectin and sour-sanded formats in Latin America together with peelable 3D fruit gummies in East Asia and high-capacity starch-mogul manufacturing in North America and Europe drive country performance.
Table 7: Country CAGR and Primary Growth Levers for the Jellies and Gummies Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 6.4% | Domestic starch-mogul plant expansion and tropical sour-belt and fruit-jelly distribution across atacarejo stores |
| Mexico | 6.1% | Chili-lime and tamarind-spiced sour gummies and single-serve impulse bags across convenience chains |
| South Korea | 5.8% | Peelable 3D fruit-juice gummies, allulose low-sugar jellies, and convenience-store beauty/functional treats |
| USA | 5.1% | Crunchy gummy clusters, sour peg bags, and new domestic starch-mogul manufacturing capacity |
| Germany | 4.7% | Domestic fruit-gummy heritage, animal-gelatin-free vegan pectin lines, and discounter sharing bags |
| UK | 4.5% | HFSS-compliant reduced-sugar fruit jellies, vegan sour gummies, and supermarket multipack pouches |
Source: Future Market Insights analysis
USA Jellies and Gummies Market Outlook (2026 to 2036)
The United States anchors global jellies and gummies demand through year-round convenience-store pegboard velocity and massive Halloween and Easter road-trip promotional cycles. In June 2026, a National Confectioners Association consumer survey reported by NACS revealed that 83% of American road-trippers purchase candy for travel, with gummies and chewy non-chocolate treats ranking among top car snacks [11]. Domestic starch-mogul capacity additions by HARIBO of America and Ferrara Candy Company together with Albanese Confectionery Group lift United States jellies and gummies market value by a projected 5.1% per annum through 2036. Multi-textured crunchy clusters and resealable stand-up pouches continue to outpace flat traditional candies.
Key takeaway: In the USA, frequent road-trip and holiday treating occasions paired with domestic starch-mogul plant builds sustain a projected 5.1% yearly market value gain.
Germany Jellies and Gummies Market Outlook (2026 to 2036)
As the birthplace of the modern gelatin gummy bear, Germany boasts Europe's highest per capita fruit-gum consumption and serves as the primary engineering hub for starch-mogul and vegan pectin confectionery. In October 2026, German confectionery industry coverage tracked HARIBO Holding GmbH & Co. KG's network optimization across its Grafschaft and Bonn production sites while domestic brands scaled vegetarian pectin lines [12]. Consumer demand for both classic Goldbears and 100% plant-based Katjes fruit gums carries German jellies and gummies market size upward by an expected 4.7% per annum through 2036. Strong private-label discounter competition requires branded suppliers to launch limited-edition sour and foam-backed shapes.
Key takeaway: In Germany, deep domestic fruit-gum loyalty and rapid supermarket adoption of vegetarian pectin gummies are expected to support steady 4.7% yearly expansion.
UK Jellies and Gummies Market Outlook (2026 to 2036)
Regulatory restrictions on high-fat and high-sugar (HFSS) checkout placements in England have accelerated British confectioners' transition toward 30%-reduced-sugar and vegan pectin gummies that qualify for prominent aisle ends. In 2026, HARIBO UK operated its Pontefract and Castleford Yorkshire manufacturing facilities to supply Tangfastics and Starmix portion-controlled mini-bags across British grocery and convenience retailers [13]. Household preference for price-marked sharing bags and nostalgic wine gums expands British jellies and gummies valuation at a forecast 4.5% yearly pace through 2036. Brands using natural fruit and vegetable concentrates and Halal-certified bovine or pectin gels capture growing urban multicultural demand.
Key takeaway: In the UK, HFSS-compliant reduced-sugar reformulation and domestic Yorkshire manufacturing of sour and sharing-bag gummies are forecast to anchor 4.5% annual growth.
Brazil Jellies and Gummies Market Outlook (2026 to 2036)
Cash-and-carry atacarejo supermarket openings and domestic starch-mogul lines in São Paulo and interior states put Brazil atop all six analyzed confectionery nations. In April 2026, Ferrara Candy Company highlighted its growing sugar confectionery footprint across the United States and Brazil following its integration of Brazilian gummy and chewy candy operations [14]. Youth demand for sour tubes and fruit-juice bears carries Brazilian jellies and gummies valuation along an anticipated 6.4% yearly expansion curve through 2036. Because tropical heat can soften pure gelatin, Brazilian plants formulate higher-bloom gelatin and pectin-blend coatings.
Key takeaway: In Brazil, expanding atacarejo wholesale-supermarket distribution and local manufacturing of tropical fruit and sour gummies are anticipated to drive a leading 6.4% CAGR.
Mexico Jellies and Gummies Market Outlook (2026 to 2036)
Mexico's vibrant street and convenience-store snacking culture favors bold sweet-and-heat flavor profiles that pair mango and watermelon gummies with chili powder and tangy lime sanding. In July 2026, Mondelēz International reported second-quarter 2026 financial results noting 4.1% net revenue expansion supported by Latin American and North American confectionery brands after integrating Ricolino's Mexican gummy and candy distribution network [15]. Distribution across OXXO convenience stores and traditional mom-and-pop tiendas lifts Mexican jellies and gummies market size by a predicted 6.1% each year through 2036. Confectioners also use allulose and polydextrose to reformulate lines around front-of-pack excess-sugar octagons.
Key takeaway: In Mexico, high-velocity convenience and traditional trade distribution of chili-lime and tropical sour gummies is predicted to sustain 6.1% annual market growth.
South Korea Jellies and Gummies Market Outlook (2026 to 2036)
South Korea's convenience-store chains and health-and-beauty retailers have turned 3D peelable fruit jellies and low-calorie allulose gummies into a daily adult and youth snacking habit. In May 2026, the National Confectioners Association's Sweets & Snacks Expo Most Innovative New Product Awards highlighted global consumer demand for 3D peelable fruit gummies and dual-textured chewy confections popularized across Asian and Western convenience channels [16]. Domestic and European brands launching zero-sugar allulose and maltitol-free chewy formats carry South Korean jellies and gummies market value along a slated 5.8% yearly expansion to 2036. High digital commerce penetration also accelerates viral K-snack gummy exports.
Key takeaway: In South Korea, viral 3D peelable fruit jellies and allulose-sweetened low-sugar gummies across urban convenience stores are slated to drive 5.8% annual growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the jellies and gummies market?
HARIBO Holding GmbH & Co. KG, Albanese Confectionery Group, Inc., Ferrara Candy Company, Mondelēz International, Inc., Perfetti Van Melle Group B.V., Katjes Fassin GmbH + Co. KG, Cloetta AB, and PIM Brands, Inc. are the notable companies in the jellies and gummies market.
FMI analysis indicates that competitive leadership in the jellies and gummies sector is anchored by high-speed starch-mogul manufacturing scale and proprietary multi-textured co-depositing across supermarket pegboards. German pioneer HARIBO Holding GmbH & Co. KG and U.S. specialist Albanese Confectionery Group Inc. focus on high-clarity gelatin fruit gummies and sour worms. Diversified confectionery majors including Ferrara Candy Company and Mondelēz International Inc. together with Perfetti Van Melle Group B.V. scale crunchy gummy clusters and Sour Patch Kids, while Katjes Fassin GmbH + Co. KG and Cloetta AB along with PIM Brands Inc. lead vegan pectin and real-fruit snack formats.
- Global Starch-Mogul Gummy Specialists: HARIBO Holding GmbH & Co. KG and Albanese Confectionery Group, Inc. operate dedicated high-output gelatin and sour-sanded gummy factories across Europe and the United States.
- Multi-Category Sour & Clustered Confectionery Majors: Ferrara Candy Company and Mondelēz International Inc. together with Perfetti Van Melle Group B.V. market global megabrands such as NERDS Gummy Clusters and Sour Patch Kids.
- Vegan Pectin & Real-Fruit Jelly Innovators: Katjes Fassin GmbH + Co. KG and Cloetta AB along with PIM Brands Inc. specialize in animal-gelatin-free vegan gummies and fruit-puree chewy snacks.
Competitive Benchmarking: Jellies and Gummies Market
Table 8: Competitive Benchmarking for the Jellies and Gummies Market (qualitative capability ratings), 2026
| Company | Starch-Mogul & Co-Deposit Scale | Sour, Vegan & Cluster Innovation | Supermarket & C-Store Peg Access | Geographic Reach |
|---|---|---|---|---|
| HARIBO Holding GmbH & Co. KG | High | High | High | High |
| Albanese Confectionery Group, Inc. | High | High | High | Medium |
| Ferrara Candy Company | High | High | High | High |
| Mondelēz International, Inc. | High | High | High | High |
| Perfetti Van Melle Group B.V. | High | High | High | High |
| Katjes Fassin GmbH + Co. KG | Medium | High | High | Medium |
| Cloetta AB | Medium | Medium | High | Medium |
| PIM Brands, Inc. | High | Medium | High | Medium |
Evaluation basis: Capability tiers evaluate starch-mogul and starchless depositing tonnage as well as multi-textured sour/cluster R&D and resealable peg-bag velocity across supermarkets and convenience stores in 40+ countries.
Key Developments in the Jellies and Gummies Market
- HARIBO of America, Inc. introduced Balla Bites and Balla Bites Sour poppable dual-textured gummies in August 2026 while expanding its Pleasant Prairie, Wisconsin manufacturing campus [17].
- Ferrara Candy Company selected Orangeburg County, South Carolina in April 2026 for a new sugar confectionery manufacturing and distribution facility following record FY2025 NERDS Gummy Clusters demand [14].
- Perfetti Van Melle Group B.V. reported 2025 net revenue exceeding EUR 4.0 billion across its 31 global manufacturing sites and expanded Fruittella and Mentos chewy confectionery lines in 2026 [18].
Key Players in the Jellies and Gummies Market
Global Starch-Mogul Gummy Specialists
- HARIBO Holding GmbH & Co. KG
- Albanese Confectionery Group, Inc.
Multi-Category Sour & Clustered Confectionery Majors
- Ferrara Candy Company
- Mondelēz International, Inc.
- Perfetti Van Melle Group B.V.
Vegan Pectin & Real-Fruit Jelly Innovators
- Katjes Fassin GmbH + Co. KG
- Cloetta AB
- PIM Brands, Inc.
Jellies and Gummies Market - Report Scope
Table 9: Report Scope for the Jellies and Gummies Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Hydrocolloid Gelling Agent; Flavor Profile; Packaging Format; Sugar & Functional Profile; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and brand market value from hydrocolloid-gelled chewy confectionery jellies and gummies (gelatin, pectin, starch, agar, and carrageenan) across sweet, sour-sanded, foam-backed, liquid-filled, crunchy-clustered, reduced-sugar, and vitamin-fortified confectionery lines. Category Scope Note: Excludes hard-boiled candies, compressed tablet mints, elastomer chewing gum bases, chocolate-bar confectionery, and prescription pharmaceutical drugs. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Germany, UK, Brazil, Mexico, South Korea, and additional countries in the full report |
| Key Companies Covered | HARIBO Holding GmbH & Co. KG, Albanese Confectionery Group, Inc., Ferrara Candy Company, Mondelēz International, Inc., Perfetti Van Melle Group B.V., Katjes Fassin GmbH + Co. KG, Cloetta AB, PIM Brands, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Jellies and Gummies Market - Research Methodology
Table 10: Research Methodology for the Jellies and Gummies Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with starch-mogul plant engineering directors, hydrocolloid confectionery R&D scientists, supermarket non-chocolate category buyers, and convenience-store wholesale distributors across North America, Europe, Latin America, and East Asia. |
| Secondary Research | Analysis of National Confectioners Association (NCA) State of Treating reports, German BDSI sugar confectionery statistics, SEC Form 10-K filings from Mondelēz International, corporate disclosures from HARIBO, Ferrara, Albanese, and Perfetti Van Melle, and peer-reviewed hydrocolloid studies in Gels and Foods. |
| Market Sizing and Forecasting | Top-down non-chocolate confectionery retail and manufacturer valuation models reconciled against bottom-up starch-mogul and starchless depositing line tonnage from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight per capita sugar confectionery intake and modern convenience store expansion together with seasonal holiday treating demand and sugar-labeling reformulation across six national markets. |
| Operational Benchmark Traceability | Starch-mogul depositing throughput and retail peg-bag valuation indicators in Tables 2, 3, and 4 trace to NCA confectionery benchmarks, BDSI production registries, and corporate plant capacity disclosures. |
| Data Triangulation and Validation | Demand estimates are cross-checked against food-grade gelatin and confectionery pectin consumption and retail scanner market value without double counting hard-boiled sweets or chewing gum. |
Jellies and Gummies Market by Segments
Jellies and Gummies Market segmented by Hydrocolloid Gelling Agent:
- Gelatin-Based Chewy Gummies
- Pectin, Starch & Agar Vegan Jellies
Jellies and Gummies Market segmented by Flavor Profile:
- Sour & Tangy Fruit Gummies
- Sweet Classic Berry & Citrus
- Botanical & Cola Flavors
Jellies and Gummies Market segmented by Packaging Format:
- Resealable Stand-Up Peg Bags
- Single-Serve Impulse Pouches
- Bulk Tubs
Jellies and Gummies Market segmented by Sugar & Functional Profile:
- Conventional Sugar & Glucose Syrup
- Reduced-Sugar, Allulose & High-Fiber
- Vitamin- & Botanical-Fortified Confectionery
Jellies and Gummies Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Forecourts
- Cinema, Travel Retail & E-Commerce
Jellies and Gummies Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- South Korea
- China
- Japan
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] National Confectioners Association (NCA). (2026, March 09). Confectionery Sales Climb to $55 Billion in 2025 - NCA. National Confectioners Association.
- [2] Pena-Portillo, G.-C., Bastias-Montes, J.-M., Garcia-Flores, V.-A., & Acuna-Nelson, S.-M. (2026, July 27). Development and Characterization of Functional Gummies Enriched with Pais Grape Extract for Presbyphagia. Gels, 12(8), 674 (MDPI).
- [3] Bianchi, F., et al. (2026, July 25). Unconventional Ingredients in Gummy Reformulation: A Review of Nutritional, Functional, and Technological Implications. Foods, 15(15), 2615 (MDPI).
- [4] National Confectioners Association (NCA). (2025, October 09). Candy Sales to Hit $27.8 Billion by 2030 - NCA. National Confectioners Association.
- [5] National Confectioners Association (NCA). (2026, March 15). State of Treating 2026 - NCA. National Confectioners Association.
- [6] de Oliveira, V. S., et al. (2026, January 10). Peanut skin bioactive extract on pectin and gelatin candies: is it a potential dietary antioxidant delivery system for human health?. PubMed Central (PMC12701288).
- [7] Mondelēz International, Inc. (2026, February 03). Form 10-K Annual Report for the Fiscal Year Ended December 31, 2025 (mdlz-20251231). U.S. Securities and Exchange Commission (EDGAR).
- [8] Ferrara Candy Company. (2026, February 23). Ferrara Candy Company Announces FY 2025 Performance. Ferrara Candy Company Newsroom.
- [9] Bundesverband der Deutschen Suesswarenindustrie e.V. (BDSI). (2026, January 29). Arbeitsplaetze in der Suesswarenindustrie in Gefahr: German Confectionery Industry Review. BDSI Journal.
- [10] Katjes Fassin GmbH + Co. KG. (2026, April 16). All Katjes Gummies - Katjes USA. Katjes USA.
- [11] National Association of Convenience Stores (NACS). (2026, June 02). NCA: 83% of Roadtrippers Bring Candy. NACS Magazine.
- [12] HARIBO Holding GmbH & Co. KG. (2026, October 05). Milestones throughout HARIBO's unique success story. HARIBO GmbH & Co. KG.
- [13] HARIBO Dunhills (Pontefract) PLC. (2026, August 12). HARIBO UK: The number 1 in fruit gummies worldwide. HARIBO UK.
- [14] Ferrara Candy Company. (2026, April 22). Ferrara Candy Company Selects Orangeburg County for New Manufacturing Site. Ferrara Candy Company Media.
- [15] Mondelēz International, Inc. (2026, July 28). Mondelēz International Reports Q2 2026 Results. Mondelēz International Investor Relations.
- [16] National Confectioners Association (NCA). (2026, May 18). Sweets & Snacks Expo Announces 2026 Most Innovative New Product Awards Winners. Sweets & Snacks Expo / NCA.
- [17] HARIBO of America, Inc. (2026, August 19). News & Stories - Haribo: HARIBO Introduces Balla Bites & Balla Bites Sour. HARIBO of America Newsroom.
- [18] Perfetti Van Melle Group B.V. (2026, March 20). Who we are | At a glance - Perfetti Van Melle. Perfetti Van Melle Group B.V.
- [19] Albanese Confectionery Group, Inc. (2026, May 14). 12 Flavor Gummi Bears | Albanese Confectionery. Albanese Confectionery Group, Inc.
- [20] Bundesverband der Deutschen Suesswarenindustrie e.V. (BDSI). (2026, February 18). Suesswarenindustrie in Zahlen: Production and Export Statistics. BDSI Statistical Portal.
- [21] PIM Brands, Inc. (2026, May 18). Welch's Fusions Invites Fans to Taste the Ultimate Remix with Two New Varieties. PIM Brands Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the jellies and gummies market in 2026 and what is forecast for 2036?
- Which sour, dual-textured, and functional treating shifts support demand for jellies and gummies?
- Why do Gelatin-Based Chewy Gummies lead the hydrocolloid gelling agent category?
- Why do Sour & Tangy Fruit Gummies lead the flavor profile category globally?
- How do growth rates differ across Brazil, Mexico, and South Korea compared with the USA and Europe?
- Which leading confectionery manufacturers supply jellies and gummies today?
- What limits shelf stability or supplier switching in the jellies and gummies market?
- What should retail category managers evaluate before listing jellies and gummies?
Frequently Asked Questions
How big is the jellies and gummies market in 2026, and what is forecast for 2036?
As per FMI, the global jellies and gummies market size is estimated to reach USD 7.8 billion in 2026 from USD 7.4 billion in 2025 and is forecast to hit an industry valuation of USD 13.2 billion by 2036 as shoppers purchase sour-sanded and dual-textured gummies in resealable peg bags.
What is the CAGR for the jellies and gummies market from 2026 to 2036?
Over the 2026 to 2036 decade, the category is anticipated to expand at a 5.4% annual rate, lifting yearly confectionery valuation by USD 5.4 billion as starch-mogul and pectin lines scale.
Which hydrocolloid gelling agent segment leads the jellies and gummies market?
Gelatin-Based Chewy Gummies are projected to capture 83.7% of hydrocolloid gelling agent market value in 2026 driven by thermo-reversible triple-helix elasticity and clean flavor release.
Which flavor profile segment leads the jellies and gummies market?
Sour & Tangy Fruit Gummies are estimated to command 58.9% of the flavor profile category in 2026 fueled by citric and malic acid sanding across youth and young-adult snacking occasions.
Which country has a notable growth outlook during the assessment period?
Brazil is projected to lead national growth at a 6.4% CAGR through 2036, supported by domestic starch-mogul capacity expansion and cash-and-carry retail distribution.
Who are the key players in the market?
HARIBO Holding GmbH & Co. KG, Albanese Confectionery Group, Inc., Ferrara Candy Company, Mondelēz International, Inc., Perfetti Van Melle Group B.V., Katjes Fassin GmbH + Co. KG, Cloetta AB, and PIM Brands, Inc. anchor global commercial supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Hydrocolloid Gelling Agent, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Hydrocolloid Gelling Agent, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Hydrocolloid Gelling Agent, 2026 to 2036
- Gelatin-Based Chewy Gummies
- Pectin, Starch & Agar Vegan Jellies
- Y-o-Y Growth Trend Analysis By Hydrocolloid Gelling Agent, 2021 to 2025
- Absolute $ Opportunity Analysis By Hydrocolloid Gelling Agent, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor Profile, 2026 to 2036
- Sour & Tangy Fruit Gummies
- Sweet Classic Berry & Citrus
- Botanical & Cola Flavors
- Y-o-Y Growth Trend Analysis By Flavor Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Resealable Stand-Up Peg Bags
- Single-Serve Impulse Pouches
- Bulk Tubs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sugar & Functional Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sugar & Functional Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sugar & Functional Profile, 2026 to 2036
- Conventional Sugar & Glucose Syrup
- Reduced-Sugar, Allulose & High-Fiber
- Vitamin- & Botanical-Fortified Confectionery
- Y-o-Y Growth Trend Analysis By Sugar & Functional Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Sugar & Functional Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Forecourts
- Cinema, Travel Retail & E-Commerce
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- China
- Japan
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Hydrocolloid Gelling Agent
- By Flavor Profile
- By Packaging Format
- By Sugar & Functional Profile
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- HARIBO Holding GmbH & Co. KG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Albanese Confectionery Group, Inc.
- Ferrara Candy Company
- Mondelēz International, Inc.
- Perfetti Van Melle Group B.V.
- Katjes Fassin GmbH + Co. KG
- Cloetta AB
- PIM Brands, Inc.
- HARIBO Holding GmbH & Co. KG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


