

- Market Size (2026)
- USD 336.1 Mn
- Forecast (2036)
- USD 781.2 Mn
- CAGR (2026 to 2036)
- 8.8%
How big is Spanakopita Market in 2026?
The market was valued at USD 308.9 Million in 2025 and is expected to reach USD 336.1 Million in 2026, with growth at an 8.8% CAGR from 2026 to 2036 taking its value to USD 781.2 Million by 2036.
Prepared spanakopita saves the work of making a filling and assembling thin filo sheets, while leaving the manufacturer responsible for preserving the contrast between moist spinach and crisp pastry through storage and final baking. Too much filling moisture can soften the layers even when a frozen product looks intact, so the cooking instructions need to work in the customer’s equipment. Grocery households need a reliable domestic-oven result, whereas foodservice kitchens need portions they can prepare in batches and replenish during service. Mini triangles suit appetizer trays, while larger pieces need a clear role as a light meal or side dish. Frozen supply separates production from the final bake and allows outlets to finish smaller quantities with less preparation labor. Imported products also require suitable labeling and temperature control before reaching grocery or hospitality buyers. Greek or Mediterranean identity may introduce the product, while a workable delivered price, dependable filling balance and intact filo give customers a reason to order it again. [5]
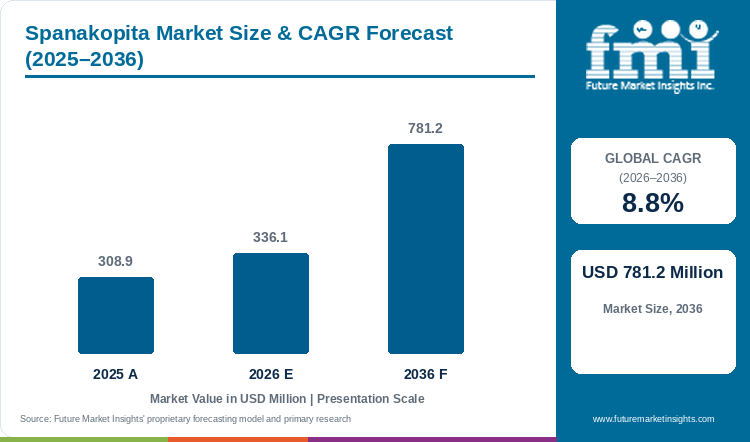
Key Market Trends & Insights
- Classic / original holds 38.0% of product type in 2026, with spinach, feta and herbs in thin filo providing a recognizable recipe for comparing suppliers.
- Conventional holds 54.0% of claim / nature in 2026, while organic and clean-label alternatives require more specific ingredient choices and supplier documentation.
- Frozen holds 30.0% of format in 2026, allowing distributors to hold filo pies for a planned bake cycle rather than needing each delivery to sell out immediately.
- Multipack holds 37.0% of packaging format in 2026, supporting portion-by-portion preparation from the freezer with cooking guidance retained on the carton.
Regional Highlights
- UAE has the highest profiled CAGR at 10.0% during 2026–2036.
- The next two profiled growth rates are Saudi Arabia at 9.7% and South Korea at 9.3% over the same period.
Market Size & Forecast
| Metric | Value |
|---|---|
| 2025 market value | USD 308.9 Million |
| 2026 market estimate | USD 336.1 Million |
| 2036 market forecast | USD 781.2 Million |
| Forecast CAGR, 2026–2036 | 8.8% |
The market covers finished spanakopita products in the stated portions and distribution formats. Plain filo dough, unrelated savory pastries and additional revenue from complete meals containing spanakopita are outside the scope.
Among bakery products, spanakopita requires particular care to keep spinach moisture from softening the surrounding filo layers.
Bakery buying and handling
| Documented operating context | Source |
|---|---|
| FSANZ reviewed the first year of mandatory plain-English allergen labelling in March 2025. | [1] |
| Australian authorities reminded food importers about plain-English allergen labelling in October 2025. | [2] |
| USDA’s February 2025 analysis separates spending on food at home from food away from home. | [3] |
| AMF and Puratos announced a joint pilot bakery in June 2025 for commercial baking development. | [4] |
Analyst Perspective
Buyers need spanakopita portions that preserve a balanced spinach-and-cheese filling within clearly defined filo layers after the final bake. A supplier can make that offer practical through manageable case quantities and instructions suited to the customer’s oven, storage space and intended service period.
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the spanakopita market segmented?
Product Type covers Classic / original, Whole grain & seeded, Flavored & filled, Mini & snacking formats and Premium / artisan. Claim / Nature covers Conventional, Clean label, Organic, Gluten-free and High-protein / fortified. Format covers Frozen, Fresh, Ambient packaged, Chilled and Par-baked / thaw-and-serve. Packaging Format covers Multipack, Single-serve, Family / loaf pack and Bulk foodservice. Sales Channel covers Supermarkets & hypermarkets, Artisan & specialty bakeries, Convenience & forecourt, Online & DTC and Foodservice distributors.
The ready-to-eat food setting provides both appetizer and meal occasions, which call for different spanakopita portion sizes and service instructions.
Why does Classic / original lead product type demand?
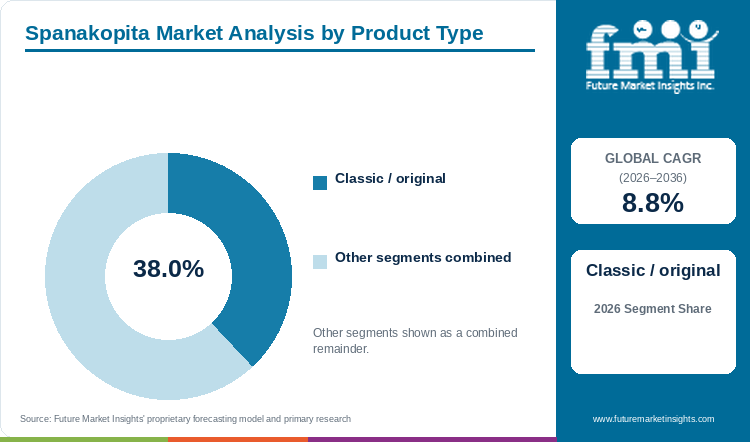
Classic / original: 38.0% of product type in 2026.
The classic spinach-and-cheese recipe gives customers a recognizable expectation of spanakopita, helping importers explain its Greek identity and retailers place it among vegetarian savory foods. The manufacturer has to control spinach moisture before assembly so the filo retains distinct layers after baking, with a consistent pastry-to-filling ratio preserving the result between purchases. Miniatures can change the serving size while retaining that familiar recipe. Specialized versions still need to justify their price through the finished portion and its preparation performance, alongside any appeal associated with origin.
- The Classic / original segment accounts for 38.0% of product type in 2026.
- Controlling spinach moisture before assembly helps preserve the layered pastry that distinguishes spanakopita from other filled snacks.
Why does Conventional lead claim / nature demand?
Conventional: 54.0% of claim / nature in 2026.
Conventional spanakopita allows established dairy ingredients and pastry fats to be adjusted for the expected flavor, moisture balance and texture. Organic recipes need additional sourcing records, while gluten-free filo requires a different dough structure and handling controls and fortified versions must retain flakiness alongside their nutritional claims. Buyers can make a useful comparison after baking, when uneven filling or softened layers become apparent, with relevant allergens clearly declared across the range.
- The Conventional segment accounts for 54.0% of claim / nature in 2026.
- A conventional recipe can retain familiar feta flavor while allowing manufacturers to adjust the filling’s salt and moisture balance.
What are the drivers, restraints, and opportunities in the spanakopita market?
Filo convenience supports appetizer and meal use
Prepared spanakopita removes filo assembly from a kitchen’s service schedule. Staff can bake a portioned product instead of preparing spinach filling and handling thin pastry sheets for each batch. Supermarkets can offer a recognizable Greek savory item without a full in-store production process. The useful saving depends on the product working in the available oven and with the staff on duty. Clear baking guidance and a realistic holding period let outlets add variety without introducing a complicated preparation routine. That makes the format more practical than a recipe concept alone.
Filling moisture and fragile layers complicate distribution
Filo can tear in handling or absorb moisture from spinach during storage and preparation, reducing the number of portions suitable for display even when packs arrive intact. Case protection and freezing need to preserve the layers, followed by baking trials showing that filling and pastry finish together. Accurate information for relevant wheat, dairy and egg ingredients belongs in the same specification, allowing safety and finished-product quality to be reviewed together.
Portioned formats support controlled service
Small triangles let caterers replenish buffet trays in controlled quantities while larger pies can serve household meals. Each size needs separate baking instructions because a different thickness changes the result. Suppliers can make trials easier with manageable case quantities and clear temperature requirements. Grocery buyers need to understand how much can be prepared from an opened pack. Hospitality operators need to know how long finished portions remain suitable for service. A useful range extension answers those questions rather than treating a change in portion size as packaging alone.
A frozen baked goods distribution system can protect production planning while allowing hospitality customers to bake nearer to the intended service time.
Which country and market CAGRs are profiled for spanakopita?
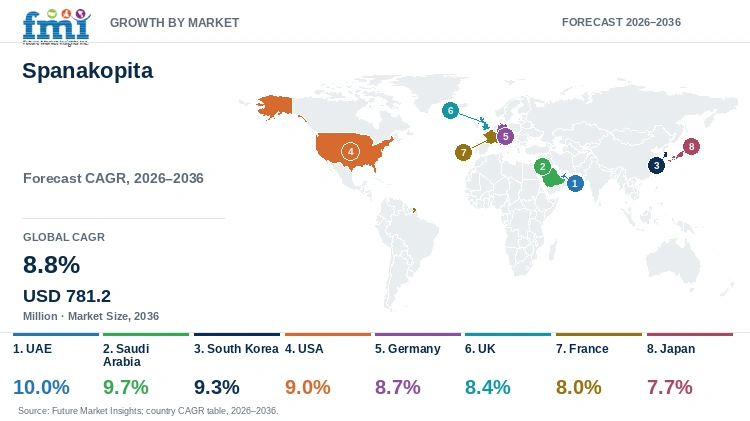
| Country | CAGR |
|---|---|
| UAE | 10.0% |
| Saudi Arabia | 9.7% |
| South Korea | 9.3% |
| USA | 9.0% |
| Germany | 8.7% |
| UK | 8.4% |
| France | 8.0% |
| Japan | 7.7% |
Country-wise Analysis
UAE
- UAE hotels and specialty grocers provide possible outlets for imported Greek filo pies. The UAE has a 10.0% CAGR from 2026 to 2036, the highest profiled rate. Import registration and label assessment precede the storage and delivery arrangements. Temperature-controlled transport needs to preserve the layers rather than merely keep the pack frozen. Trials should use the buyer’s oven or reheating equipment and include the delivered price per usable serving. This shows whether the pastry remains commercially practical after the full import journey.
Saudi Arabia
- Saudi catering buyers can use small spanakopita portions to replenish buffets without preparing whole trays at once. Saudi Arabia has a 9.7% forecast CAGR over 2026 to 2036. The product needs to remain identifiable and intact after holding. Distributors also have to align the declared cheese ingredients with labeling and storage requirements. Modern grocery and Mediterranean restaurant accounts may need different pack sizes, with complete technical information and reliable temperature-controlled delivery allowing suppliers to serve both without unnecessarily changing the underlying recipe.
South Korea
- Small frozen trial packs can introduce spanakopita through South Korean online food retail. South Korea’s CAGR is 9.3% from 2026 to 2036. The order must survive insulated delivery with its filo undamaged and carry clear Korean-language information. Price after delivery matters to a first-time customer unfamiliar with the product. Trials should therefore evaluate the baked serving as well as the unopened frozen pack. Stable storage is only part of the requirement when the consumer still has to produce crisp pastry around a moist filling.
USA
- American buyers already have retail and appetizer examples from Kontos and Athens Foods to compare. The USA spanakopita CAGR is 9.0% for 2026 to 2036. A side dish and a shared appetizer call for different portion sizes and case arrangements. Foodservice trials need to show that rapid preparation leaves the filo intact, while grocery packs require handling and allergen information that customers can use during home preparation. Manufacturers should assess moisture after the stated cooking method because the contrast between filling and layers is a major reason to choose spanakopita over another frozen savory product.
Germany
- German wholesalers can compare spanakopita with other frozen savory pastries on serving price and stock turnover. Germany is associated with an 8.7% CAGR from 2026 to 2036. Greek identity may introduce the product but does not resolve those purchasing questions. Ingredient information and oven directions need to be clear enough for both retail and foodservice users. Protecting the layers through distribution preserves the feature that makes the product distinctive. Buyers then have a more useful comparison based on acceptable portions per case rather than the appearance of a frozen sample.
UK
- British hospitality kitchens can add spanakopita as a vegetarian option when it fits their existing ovens and service routine. The UK is forecast at an 8.4% CAGR during 2026–2036. Consistent portions help staff plan how much to bake, while holding tests establish whether the crispness of the first serving remains acceptable later in service. Retail counters also need accurate consumer information and scheduled deliveries that limit unsold stock. A straightforward preparation process gives the product a practical place in a mixed menu.
France
- French specialty outlets may emphasize the spinach-and-cheese recipe while mainstream bakery buyers need a clear serving occasion for customers. France is forecast to grow at an 8.0% CAGR from 2026 to 2036. Both need recognizable filo layers after baking. French-language information and an appropriate case size make the product easier to assess. Smaller portions allow controlled service while larger trays need guidance on cutting and holding. The supplier should preserve those finished qualities through storage rather than rely on an authenticity claim to secure repeat orders.
Japan
- An unfamiliar Greek product name may need an explanation of the filling and expected texture for Japanese shoppers. Japan closes the profiled range with a 7.7% CAGR between 2026 and 2036. Small protected portions can make the first purchase easier through specialty importers or frozen groceries. Clear oven or air-fryer directions should match the actual product size. Import formalities remain necessary before supply begins. Once listed the product needs consistent preparation and intact pastry so that customers can confidently repeat the same serving at home.
Who are the notable companies in the spanakopita market?
Paliria; Kontos Foods; Krinos Foods; Athens Foods; The Fillo Factory
Spanakopita producers compete through the balance of spinach and cheese as well as the condition of the filo. A broader Mediterranean range may help introduce a supplier but the buyer still needs to test the specific portion and its preparation requirements.
Competitive Benchmarking: Spanakopita Market
| Participant | Commercial focus | Buyer qualification priority |
|---|---|---|
| Paliria | Greek prepared foods | Spinach-to-cheese balance and portion consistency |
| Kontos Foods | Filo-based savory foods | Pastry integrity and bake instructions |
| Krinos Foods | Mediterranean foods | Regional distributor availability |
| Athens Foods | Filo pastries and appetizers | Layer integrity and frozen handling |
| The Fillo Factory | Filled filo products | Cooking yield and pack protection |
Key Developments in the Spanakopita Market
- FSANZ reviewed the first year of mandatory plain-English allergen labelling in March 2025. [1]
- Australian authorities reminded food importers about plain-English allergen labelling in October 2025. [2]
Key Players in the Spanakopita Market
- Paliria
- Kontos Foods
- Krinos Foods
- Athens Foods
- The Fillo Factory
Spanakopita Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Claim / Nature; Format; Packaging Format; Sales Channel; Region |
| Quantitative unit | USD Million |
| Market definition | The market covers finished spanakopita products in the stated portions and distribution formats. Plain filo dough, unrelated savory pastries and additional revenue from complete meals containing spanakopita are outside the scope. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries / markets profiled | UAE; Saudi Arabia; South Korea; USA; Germany; UK; France; Japan |
| Key companies profiled | Paliria; Kontos Foods; Krinos Foods; Athens Foods; The Fillo Factory |
| Base year / forecast period | 2026 / 2026–2036 |
| Estimate coverage | 2025 and 2026 market estimates; 2036 forecast; segment shares and country / market CAGRs. |
Spanakopita Market - Research Methodology
| Method | Application |
|---|---|
| Market definition | The analysis follows the stated product or service boundary and distinguishes direct category revenue from adjacent activities. |
| Secondary research | Official technical, regulatory, research and company publications provide the documented operating context and recent developments cited in this report. |
| Forecast and segmentation | Market estimates, segment shares and geographic forecasts are presented as analytical estimates within the stated commercial scope. |
| Competitive assessment | Participants are compared by their relevant products or services, commercial role and buyer qualification requirements. |
| Interpretation | The assessment considers purchasing conditions and the scope of the documented product, service or performance claim. |
Spanakopita Market by Segments
Product Type
- Classic / original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
Claim / Nature
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
Format
- Frozen
- Fresh
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
Packaging Format
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
Sales Channel
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Spanakopita Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Food Standards Australia New Zealand. (2025, March 5). Plain English Allergen Labelling: One year of clearer, safer food labels.
- [2] Australian Government, Department of Agriculture, Fisheries and Forestry. (2025, October 14). Reminder for importers about plain English allergen labelling.
- [3] U.S. Department of Agriculture, Economic Research Service. (2025, February 24). Food spending in the United States.
- [4] AMF Bakery Systems. (2025, June 9). AMF and Puratos launch joint pilot bakery facility to accelerate commercial baking innovation.
- [5] Future Market Insights. (2026). Spanakopita Market: Global industry analysis and opportunity assessment, 2026–2036.
This Report Answers
- How large is the spanakopita market in 2026?
- What value and CAGR are forecast through 2036?
- Which product type segment leads in 2026?
- Which claim / nature segment has the largest share?
- Which profiled country or market has the fastest forecast growth?
- Which participants are covered in the competitive assessment?
Frequently Asked Questions
How large is the spanakopita market in 2026?
The market was valued at USD 308.9 Million in 2025 and is expected to reach USD 336.1 Million in 2026.
What value and CAGR are forecast through 2036?
The market is projected to reach USD 781.2 Million by 2036, with an 8.8% CAGR during 2026–2036.
Which product type segment leads in 2026?
The Classic / original segment accounts for 38.0% of product type in 2026.
Which claim / nature segment has the largest share?
The Conventional segment accounts for 54.0% of claim / nature in 2026.
Which profiled country or market has the fastest forecast growth?
UAE has the highest profiled CAGR at 10.0% during 2026–2036.
Which participants are covered in the competitive assessment?
The assessment covers Paliria, Kontos Foods, Krinos Foods, Athens Foods and The Fillo Factory.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic / original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Frozen
- Fresh
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Paliria
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kontos Foods
- Krinos Foods
- Athens Foods
- The Fillo Factory
- Paliria
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


