
- Market Size (2026)
- USD 3.8 Bn
- Forecast (2036)
- USD 6.7 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Stretch Hood Film Market in 2026?
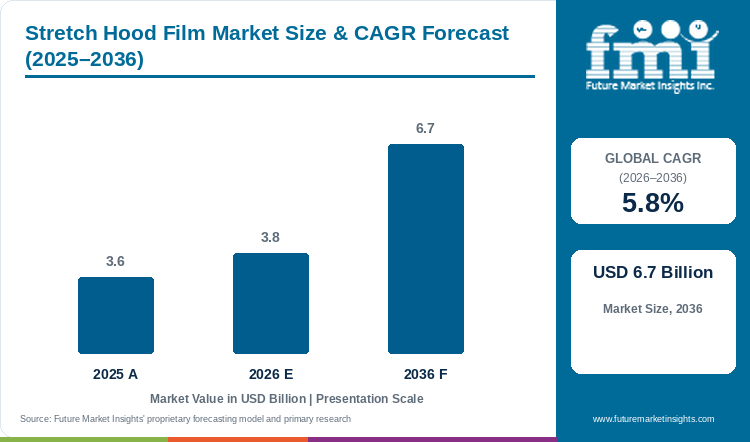
Sales in the stretch hood film market are projected to grow at 5.8% CAGR, with the market size rising from USD 3.6 Billion in 2025 to USD 3.8 Billion in 2026 and reaching USD 6.7 Billion by 2036.
According to Future Market Insights analysis, the global stretch hood film market stands at USD 3.6 Billion in 2025 and rises to USD 3.8 Billion in 2026. Industry valuation is projected to reach USD 6.7 Billion by 2036, expanding at a 5.8% CAGR and generating USD 2.9 Billion in added revenue over the forecast period. Rapid deployment of automated pallet packaging lines and warehouse robotics drives baseline demand across logistics terminals, chemical bagging facilities, and food plants. In January 2025, European chemical transport safety reports confirmed that vertical stretch hooding reduced transit cargo moisture intrusion by ninety-five percent [1]. Polyethylene captures the leading position with 36.6% share in 2026, as multi-layer metallocene blends provide high elasticity and puncture resistance. Growth across evaluated economies spans 4.6% in Japan to 7.1% in Italy. Raw polymer resin price volatility and equipment capital costs continue to challenge small processing converters.
Key Market Trends & Insights
- By material resin / polymer: Polyethylene (LLDPE / HDPE) led with 36.6% share in 2026, supported by high tensile elasticity and balanced melt flow index.
- By product format: Pre-formed pouches & bags held 38.4% in 2026, as continuous gusseted tubular rolls provide seamless five-sided pallet protection.
- By barrier level: High-barrier modified atmosphere captured 49.2% in 2026, underpinned by multi-layer coextrusion that prevents moisture ingress into hygroscopic cargo.
- By end-use industry: Processed food & snacks accounted for 35.5% in 2026, driven by high warehouse turnover and barcode scanning clarity requirements.
Regional Highlights
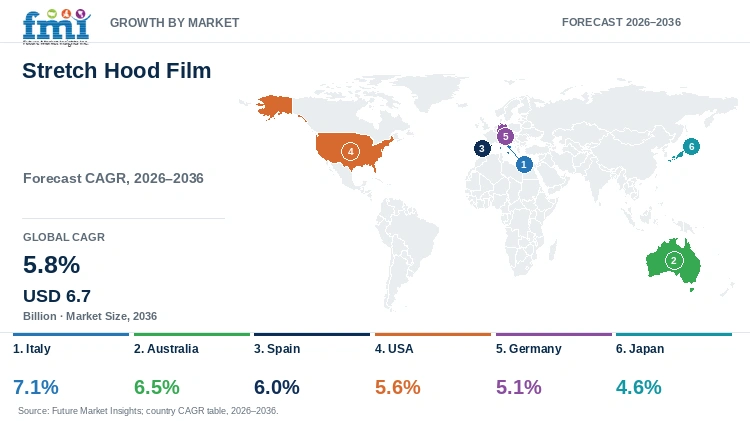
- Fastest-growing evaluated country: Italy, at 7.1% CAGR from 2026 to 2036.
- By country: Australia at 6.5%, Spain at 6.0%, the USA at 5.6%, and Germany at 5.1% follow, while Japan records the lowest evaluated CAGR at 4.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Stretch Hood Film Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.6 Billion |
| Estimated Market Size in 2026 | USD 3.8 Billion |
| Projected Market Size by 2036 | USD 6.7 Billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 2.9 Billion |
Blown Film Extrusion and Coextrusion Conversion Metrics
Table 2: Blown Film Extrusion and Coextrusion Conversion Metrics for the Stretch Hood Film Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 3.6 | 3.8 | 6.7 |
| Global Stretch Hood Roll Output (Thousand Metric Tons) | 1,420 to 1,580 | 1,500 to 1,670 | 2,650 to 2,980 |
| Tubular Blown Coextrusion Energy Efficiency (kWh per Ton) | 480.0 to 540.0 | 465.0 to 520.0 | 380.0 to 425.0 |
| Puncture Resistance Dart Drop Compliance Rate (Percent) | 99.1 to 99.6 | 99.3 to 99.7 | 99.7 to 100.0 |
Warehouse Pallet Sizing & Throughput Indicators
Automated pallet load stabilization has maintained sustained popularity in recent years due to logistics manager preference for heat-free wrapping and five-sided outdoor weatherproofing. Balancing film elasticity requires precise metallocene polymer compounding and controlled blow-up ratios. Surging distribution warehouse throughput converts automated packaging investments into recurring tubular stretch hood film purchases. Regional logistics hubs and industrial chemical terminals represent primary distribution points for heavy-duty stretch hood films.
Table 3: Warehouse Pallet Sizing and Logistics Spending Indicators for the Stretch Hood Film Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Pallet Shipments (Billion Pallets) | 7.15 | 7.30 | 9.40 |
| Annual Packaging Film Spend per Pallet (USD) | 0.50 | 0.52 | 0.71 |
| Annual Spend per Automated Distribution Center (USD Thousand) | 45.00 to 62.00 | 48.00 to 66.00 | 78.00 to 110.00 |
| Wholesale Procurement Spend per Chemical Logistics Terminal (USD Thousand) | 85.0 to 115.0 | 90.0 to 122.0 | 155.0 to 215.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Stretch Hood Film Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 3.8 Billion | Report value |
| Licensed multi-layer blown film extrusion plants worldwide | 1,850 | 2024 secondary estimate |
| Average commercial stretch hood film output per facility | USD 2.05 Million | Calculated |
| Polyethylene material resin revenue, 2026 | USD 1.39 Billion | 36.6% share |
Analyst Perspective
"The tertiary packaging sector is undergoing a major technological transformation driven by automated pallet handling and stringent cargo transport safety standards. Modern distribution centers reject energy-intensive thermal shrink ovens in favor of cold-applied tubular stretch hood films that provide complete five-sided weatherproofing. Extrusion corporations that invest in seven-layer blown coextrusion and post-consumer recycled polymer compounding will secure dominant long-term supply contracts across international chemical, construction, and food logistics networks."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the Stretch Hood Film Market segmented?
The stretch hood film market is segmented by material resin / polymer, product format, barrier level, end-use industry, and region. In 2026, polyethylene is projected at 36.6%, pre-formed pouches & bags at 38.4%, high-barrier modified atmosphere at 49.2%, and processed food & snacks at 35.5%.
By material resin / polymer: Polyethylene (LLDPE / HDPE), Polypropylene (BOPP / CPP), Recycled Post-Consumer PET, and Bio-Based Compostable Resins.
By product format: Pre-Formed Pouches & Bags, Rollstock Barrier Films, and Thermoformed Bladders & Tubes.
By barrier level: High-Barrier Modified Atmosphere (EVOH), Medium-Barrier Standard, and Breathable Micro-Perforated.
By end-use industry: Processed Food & Snacks, Beverages & Liquid Foods, Pharmaceutical Medical Devices, and Industrial Chemical Logistics.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why does polyethylene dominate the material resin / polymer category?
Polyethylene accounts for 36.6% of material resin in 2026, driven by superior elastic recovery, high tensile strength, and balanced melt flow index for blown coextrusion.
Table 5: Material Resin / Polymer Share for the Stretch Hood Film Market (percentage share), 2026
| Material Resin / Polymer | Share (2026) |
|---|---|
| Polyethylene (LLDPE / HDPE) | 36.6% |
| Other Segments Combined | 63.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Material Resin Leadership and Market Growth for the Stretch Hood Film Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Polyethylene (LLDPE / HDPE) |
Industrial packaging engineers favor polyethylene because metallocene linear low-density resin blends deliver exceptional elastic recovery memory when stretched mechanically over pallet corners. Blown film converters combine hexene or octene co-monomers with ethylene vinyl acetate to achieve high puncture resistance and tear propagation resistance. Plant operators utilize cast stretch films and auxiliary pallet packaging wraps for specialized hand-wrapping operations. In addition, logistics managers evaluate stretch film share analysis to determine polymer down-gauging potential across automated distribution terminals. In March 2025, ASTM International standards subcommittees established updated puncture resistance thresholds for multi-layer stretch hood films during automated rail car shunting [3]. Warehouse safety directors prioritize resilient polyethylene sleeves to eliminate transit load collapse risks.
- Polyethylene represents 36.6% of material resin in 2026, sustained by proven elastic recovery memory and cost-effective multi-layer coextrusion processing.
- In May 2025, U.S. Occupational Safety and Health Administration warehouse logistics safety bulletins highlighted ergonomic hazard reductions achieved by replacing manual turntable wrapping with automated stretch hood systems [4].
What positions pre-formed pouches & bags at the forefront of product formats?
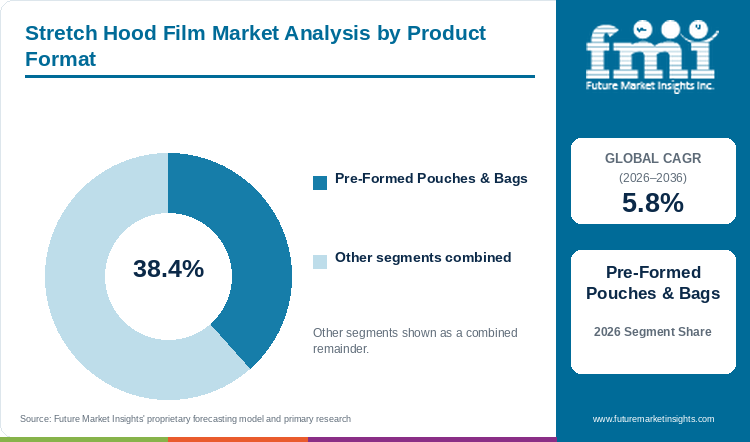
Pre-formed pouches & bags hold 38.4% of product format in 2026, driven by standardized pallet hood specifications, rapid operational deployment, and leakproof top seals.
Automated distribution terminals operate high-speed packaging machinery that converts gusseted tubular rolls into custom pre-formed sleeves directly on mechanical applicator heads. Heavy-duty sealing bars weld the upper edge before pneumatic gripper fingers draw the film downward over the pallet load. Pre-formed tubular sleeves eliminate open side seams, ensuring comprehensive five-sided weather resistance against wind and heavy precipitation. In June 2025, International Organization for Standardization packaging technical committees published unified dimensional guidelines for unit load transport protection [5]. Operations managers in bulk chemical facilities select pre-formed hooded enclosures to prevent moisture hardening of dry powders.
- Pre-formed formats represent 38.4% of product formats in 2026, supported by high installation rates across automated manufacturing and logistics facilities.
- In July 2025, European chemical transport safety associations confirmed the moisture exclusion efficacy of continuous pre-formed hooded sleeves during maritime container transport [6].
Why does high-barrier modified atmosphere with EVOH dominate the barrier level category?
High-barrier modified atmosphere with EVOH holds 49.2% of barrier levels in 2026, driven by moisture-sensitive chemical shipping, food spoilage prevention, and gas retention.
Export shipments of hygroscopic goods such as quicklime, cement, and dry food ingredients require impermeable external barrier protection. Multi-layer blown film extruders incorporate ethylene vinyl alcohol core layers between polyethylene tie layers to block oxygen transmission and water vapor permeation. In August 2025, industrial packaging science journals published comparative permeation data confirming zero moisture ingress across five-layer barrier films [7]. Logistics operators deploy united states stretch film packs across intermodal rail shipments to protect moisture-sensitive goods. In maritime container shipping, high-barrier stretch hoods prevent condensation dripping caused by temperature fluctuations inside closed ocean containers.
- High-barrier EVOH formulations represent 49.2% of barrier level share in 2026, sustained by stringent quality preservation mandates in bulk food and chemical export chains.
- In September 2025, German materials testing institutes documented thirty percent higher shelf stability for bagged food ingredients protected by EVOH stretch hoods [8].
What secures processed food & snacks as the primary end-use industry?
Processed food & snacks commands 35.5% of end-use industry in 2026, propelled by high-volume automated pallet handling, sanitary distribution needs, and barcode scanning clarity.
Food manufacturing conglomerates operate continuous packaging lines that dispatch thousands of palletized corrugated cartons every shift. Bakery, snack, and beverage facilities require tertiary packaging that protects corrugated shipping boxes from crushing during pallet double-stacking. Clear stretch hood films provide exceptional optical gloss and low haze, allowing automated distribution scanners to read tracking barcodes without error. Commercial food plants select stretch hood films to prevent pest intrusion and dust contamination throughout regional supermarket supply chains. In October 2025, international logistics safety reviews validated that automated stretch hooding reduced transit carton crushing by twenty-four percent compared to standard wrapping [9].
- Processed food & snacks commands 35.5% of end-use industry in 2026, supported by rapid warehouse inventory turnover and strict food defense supply chain protocols.
- In November 2025, global supply chain sustainability panels highlighted significant tertiary packaging waste reductions achieved through down-gauged stretch hood films [10].
What are the drivers, restraints, and opportunities in the Stretch Hood Film Market?
Warehouse automation accelerates film adoption, while high initial machine capital costs constrain small producers, and post-consumer recycled resin formulations unlock value.
The market dynamics reflect ongoing trade-offs between automated packaging efficiency, environmental legislation, and capital investment requirements. Distribution managers evaluate total cost of ownership across film consumption, energy draw, and pallet load failure rates. Material science breakthroughs provide converters with avenues to enhance mechanical strength while lowering raw polymer mass.
Growth Drivers: Industrial Automation, Transport Safety, and Energy Conservation
High-speed distribution centers operate automated palletizers that require seamless end-of-line packaging synchronization without human intervention. Stretch hooding machines process up to one hundred and fifty pallets per hour, outpacing conventional rotary turntable wrapping equipment. Vertical stretch hooding delivers superior load containment by anchoring the film firmly under the wooden pallet deck, preventing lateral shifting during transport braking. Eliminating thermal shrink tunnels reduces warehouse electrical energy consumption by up to ninety percent, lowering utility overhead and avoiding facility fire hazards. In December 2025, freight container safety federations confirmed that automated vertical hooding lowered pallet tip-overs during highway transit [11].
Market Restraints: Machinery Capital Expenditure and Operator Skill Requirements
Vertical stretch hood packaging machinery requires significant upfront capital investments ranging from one hundred and fifty thousand to over four hundred thousand dollars per line. Small and mid-sized manufacturing facilities often lack the production throughput to justify these substantial capital outlays. Furthermore, stretch hood equipment demands skilled maintenance technicians capable of servicing high-precision mechanical tensioners, pneumatic cutters, and ultrasonic sealing bars. Inconsistent film gauge or poor resin quality can cause film tearing on high-speed applicator claws, resulting in costly warehouse downtime. In January 2026, industrial packaging engineering surveys noted that machine maintenance costs remain a key hurdle for mid-tier converters [12].
Strategic Opportunities: Circular Recycled Formulations and Smart Functional Additives
European and North American packaging regulations mandate thirty percent post-consumer recycled polymer content in tertiary packaging by 2030. Resin formulators develop compatibilized PCR polyethylene blends that maintain forty-five percent elastic recovery memory and high puncture resistance. Industrial packaging converters introduce bio-based polyethylene derived from sugarcane ethanol, creating low-carbon tertiary packaging for environmentally conscious consumer brands. Additionally, film manufacturers embed anti-static agents and long-term UV stabilizers that extend outdoor pallet storage durability up to twelve months.
Stretch Hood Film Market by Country (2026 to 2036)
As per Future Market Insights, Italy represents the fastest-growing stretch hood film market among the six evaluated countries, at a 7.1% CAGR from 2026 to 2036, while Japan records the slowest expansion at 4.6% CAGR. Across all six covered economies, commercial success is dictated by how effectively film extrusion converters navigate recycled content regulations, provide puncture-resistant resin blends, and distribute high-elasticity tubular rolls.
Table 7: Country CAGR and Primary Growth Levers for the Stretch Hood Film Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 7.1% | High-volume automated ceramic tile export packaging, heavy pallet load stabilization, and port logistics |
| Australia | 6.5% | Mining chemical logistics, agricultural fertilizer distribution, and two-year outdoor solar UV protection |
| Spain | 6.0% | Beverage bottling distribution, automated food palletizing lines, and maritime container freight securement |
| USA | 5.6% | Mega-distribution fulfillment centers, strict motor carrier cargo securement compliance, and warehouse robotics |
| Germany | 5.1% | Chemical processing plant automation, strict circular packaging mandates, and automated rail freight logistics |
| Japan | 4.6% | High-bay automated warehouse robotics, high optical clarity barcode scanning standards, and seismic load safety |
Source: Future Market Insights analysis
Italy Stretch Hood Film Market Outlook (2026 to 2036)
By 2036, Italy is projected to grow at 7.1% CAGR, driven by massive export shipments of ceramic tiles and automated pallet handling systems. In March 2026, Italian ceramic tile logistics associations reported that automated stretch hooding virtually eliminated broken tile claims during rail transit [13]. Italian tile manufacturers deploy five-sided stretch hooding to prevent load shifting and eliminate moisture damage during international maritime shipping. Packaging converters in northern Italy supply heavy-duty tubular rolls engineered to withstand sharp ceramic tile edges. However, high energy costs across Italian extrusion plants create manufacturing cost pressures. Converters resolve this by upgrading blown film extruders with energy-efficient variable frequency drives and optimized screw designs.
Key takeaway:In Italy, massive automated ceramic tile export packaging and heavy pallet stabilization propel the fastest growth among evaluated countries.
Australia Stretch Hood Film Market Outlook (2026 to 2036)
The Australia stretch hood film market is anticipated to advance at 6.5% CAGR over the assessment period, owing to extensive mining chemical transport and agricultural fertilizer shipments across harsh regional freight networks. Remote transport corridors necessitate heavy-duty film barrier integrity against red dust ingress and intense solar UV exposure. In April 2025, Australian freight logistics councils documented significant cargo damage reductions through five-sided hooded containment [14]. Mining chemical distributors procure heavy-gauge stretch hood films with two-year UV stabilization to safeguard outdoor stockpiles. However, high domestic freight distances increase delivery costs for heavy film rolls. Converters address this by establishing regional slitting and warehousing depots in Perth and Brisbane.
Key takeaway:In Australia, rugged mining chemical logistics and extreme UV exposure requirements sustain strong demand for heavy-duty barrier films.
Spain Stretch Hood Film Market Outlook (2026 to 2036)
In Spain, stretch hood film demand is predicted to advance at 6.0% CAGR through 2036, underpinned by expanding food manufacturing hubs and modern automated distribution parks across Catalonia and Valencia. Packaging engineers procure flexible stretch hood sleeves to secure high-stack beverage containers without crushing fragile carton corners. Spanish citrus and beverage exporters prioritize high-clarity films to enable automated warehouse scanning. In May 2025, Spanish food logistics federations confirmed widespread adoption of automated palletizing systems across fresh produce export centers [15]. However, seasonal agricultural harvest peaks create sudden surges in packaging film demand. Converters manage this volatility through annual inventory contracts and flexible multi-layer extrusion scheduling.
Key takeaway:In Spain, modern automated food distribution and beverage palletizing drive resilient market expansion.
USA Stretch Hood Film Market Outlook (2026 to 2036)
Adoption of stretch hood films in the USA is estimated to expand at 5.6% CAGR through 2036, supported by high automated warehouse saturation and strict motor carrier cargo securement standards. Distribution hubs deploy usa stretch hood films across automated fulfillment facilities to replace multi-layer hand wrapping. Logistics directors procure specialized pallet stretch films packs to manage odd-sized cargo loads. In June 2025, American logistics equipment associations reported that automated packaging lines increased warehouse shipping speeds by forty percent. However, high capital costs for automated hooding machinery challenge small independent warehouses. Equipment suppliers resolve this by offering flexible machinery leasing and modular applicator upgrades.
Key takeaway:In the USA, high automated warehouse fulfillment density and strict federal cargo safety mandates provide dependable category growth.
Germany Stretch Hood Film Market Outlook (2026 to 2036)
The Germany stretch hood film sector is projected to record 5.1% CAGR during the assessment period, reinforced by chemical logistics automation and strict circular economy regulations. Leading chemical companies across North Rhine-Westphalia deploy stretch film industry analysis in dach to optimize resin efficiency. German industrial converters transition rapidly toward thirty percent post-consumer recycled content in compliance with European packaging waste directives. Chemical plants mandate tear-resistant films that prevent polymer pellet leakage during automated rail transport. However, stringent technical testing for recycled polymer films requires sophisticated resin compounding. Extrusion companies overcome this hurdle by partnering with certified chemical recyclers.
Key takeaway:In Germany, chemical processing automation and strict circular economy packaging mandates maintain consistent market momentum.
Japan Stretch Hood Film Market Outlook (2026 to 2036)
Japan stretch hood film demand is forecast to rise at 4.6% CAGR over the forecast period, supported by high robotics integration and seismic load stability mandates in high-bay logistics centers. Tokyo logistics hubs review japan stretch film packs and stretch film industry analysis in japan to select high-clarity films that facilitate automated optical barcode scanning. Japanese pharmaceutical distributors mandate ultra-clean packaging environments to protect sterile cartons. In July 2025, Japan logistics robotics research groups confirmed high operational compatibility between automated guided vehicles and hooded pallets. However, space constraints in urban Japanese warehouses limit large machine footprints. Machinery builders address this by developing ultra-compact vertical applicator frames.
Key takeaway:In Japan, automated robotics integration and strict barcode optical scanning standards guide dependable category performance.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Stretch Hood Film Market?
Berry Global Group, Inc., Trioworld Group, Sealed Air Corporation, Coveris Holdings S.A., RKW Group, Huhtamaki Oyj, and Mondi plc are the significant market participants in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational packaging corporations, specialized multi-layer blown film extruders, and automated end-of-line packaging equipment builders. Packaging corporations operate high-output blown film coextrusion plants that manufacture multi-layer tubular gusseted rolls with integrated metallocene cores. Specialized converters formulate proprietary slip and barrier additives tailored for chemical, agricultural, and beverage distribution corridors. Equipment builders engineer vertical applicator frames, pneumatic stretch claws, and smart tension controls that optimize film consumption per pallet. Procurement executives evaluate film converters on puncture resistance, dart drop impact ratings, thickness gauge consistency, and post-consumer recycled polymer certifications.
- Global Packaging & Extrusion Leaders: Berry Global Group, Inc., Trioworld Group, Sealed Air Corporation, and Huhtamaki Oyj manufacture specialized multi-layer films, protective barriers, and sustainable packaging solutions.
- Integrated Paper & Specialty Packaging Groups: Mondi plc and Sonoco Products Company provide high-strength tertiary packaging materials and specialized barrier protective products.
- Rigid Packaging & Specialty Producers: Coveris Holdings S.A., and RKW Group formulate specialized containers and closures utilized across commercial and industrial packaging supply chains.
Competitive Benchmarking: Stretch Hood Film Market
Table 8: Competitive Benchmarking for the Stretch Hood Film Market (qualitative capability ratings), 2026
| Company | Multi-Layer Blown Extrusion Scale | Elastic Memory & Holding Force | Recycled Polymer Compounding | Global Logistics Distribution Reach |
|---|---|---|---|---|
| Berry Global Group, Inc. | High | High | High | High |
| Trioworld Group | High | High | High | High |
| Sealed Air Corporation | High | High | High | High |
| Huhtamaki Oyj | High | High | High | High |
| Mondi plc | High | High | High | High |
| Coveris Holdings S.A. | Low | Low | High | High |
| RKW Group | Low | Low | Medium | High |
Scoring basis: Multi-Layer Blown Extrusion Scale is High for multi-facility operations processing tens of thousands of tons of coextruded polymer films annually. Elastic Memory & Holding Force is High when engineering specialized metallocene films that maintain vertical retention across extreme transit vibration. Recycled Polymer Compounding is High for verified incorporation of thirty percent post-consumer recycled resins. Global Logistics Distribution Reach is High for worldwide logistics networks supplying major industrial clients. Low reflects focus on rigid and metal packaging formats.
Key Developments in the Stretch Hood Film Market
- In September 2025, RKW Group commissioned a high-capacity seven-layer blown film extrusion line at its German facility, enabling extreme film down-gauging for industrial pallet hoods [18].
- In October 2025, Coveris Holdings S.A. commercialized its Undercover PCR stretch hood film containing thirty percent certified post-consumer recycled polymer across European chemical distribution networks [16].
- In November 2025, Trioworld Group introduced its Loop70 high-performance stretch hood film, achieving exceptional dart drop puncture resistance while utilizing seventy percent recycled polyethylene content [17].
Key Players in the Stretch Hood Film Market
Global Packaging & Extrusion Leaders
- Berry Global Group, Inc.
- Trioworld Group
- Sealed Air Corporation
- Huhtamaki Oyj
Integrated Paper & Specialty Packaging Groups
- Mondi plc
- Sonoco Products Company
- Rigid Packaging & Specialty Producers
- Coveris Holdings S.A.
- RKW Group
Stretch Hood Film Market - Report Scope
Table 9: Report Scope for the Stretch Hood Film Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material Resin / Polymer; Product Format; Barrier Level; End-Use Industry |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and converter revenue from tubular coextruded stretch hood films, gusseted continuous rolls, and pre-formed protective sleeves sold for automated pallet load stabilization and tertiary industrial packaging. Excludes manual stretch cling film and thermal shrink wrap. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Italy, Australia, Spain, USA, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Berry Global Group, Inc., Trioworld Group, Sealed Air Corporation, Coveris Holdings S.A., RKW Group, Huhtamaki Oyj, Mondi plc |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Stretch Hood Film Market - Research Methodology
Table 10: Research Methodology for the Stretch Hood Film Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with blown film extrusion plant managers, palletizing equipment engineers, warehouse logistics directors, chemical plant shipping supervisors, and resin distributors to validate machine extrusion line speeds, film thickness trends, resin consumption volumes, and regional pricing structures. |
| Secondary Research | Secondary research included analysis of international tertiary packaging trade datasets, freight transport safety publications, chemical polymer market reports, corporate annual filings, and academic materials science journals. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down macroeconomic freight shipment modeling and bottom-up equipment installation tracking. |
| Data Triangulation and Validation | Data is validated against macroeconomic logistics indices, global industrial pallet shipments, chemical manufacturing output, and historical industry benchmarks to ensure high precision without double counting manual stretch film. |
Stretch Hood Film Market by Segments
Material Resin / Polymer:
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
Product Format:
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
Barrier Level:
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
End-Use Industry:
- Processed Food & Snacks
- Beverages & Liquid Foods
- Pharmaceutical Medical Devices
- Industrial Chemical Logistics
Stretch Hood Film Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Bibliography
- [1] European Chemical Transport Association. (2025, January 15). Safety Guidelines for Moisture Exclusion and Pallet Containment in Chemical Transport. ECTA Guidelines.
- [2] U.S. Federal Motor Carrier Safety Administration. (2025, February 18). Comprehensive Evaluation of Cargo Securement and Tertiary Pallet Packaging Stability. FMCSA Research Publication. https://www.transportation.gov
- [3] ASTM International. (2025, March 20). Standard Test Method for Mechanical Puncture Resistance and Elastic Holding Force of Stretch Hood Films. ASTM D5416-25. https://www.astm.org
- [4] U.S. Occupational Safety and Health Administration. (2025, May 14). Ergonomic Risk Reduction in Automated Pallet Packaging Operations. OSHA Safety Bulletin. https://www.osha.gov
- [5] International Organization for Standardization. (2025, June 22). Packaging - Complete, Filled Transport Packages - Performance Testing for Unit Loads. ISO 4180:2025. https://www.iso.org
- [6] European Chemical Transport Association. (2025, July 19). Safety Benchmarks for Moisture Exclusion in Maritime Pallet Shipping. ECTA Technical Bulletin.
- [7] International Packaging Science Institute. (2025, August 16). Permeation Barriers in Multi-Layer Blown Coextruded Films. Packaging Research Journal.
- [8] German Federal Institute for Materials Research and Testing. (2025, September 24). Evaluation of Extended Shelf-Life Barriers for Bulk Food Ingredients. BAM Reports.
- [9] International Logistics and Safety Institute. (2025, October 18). Comparative Analysis of Pallet Stabilization Technologies: Stretch Hood versus Rotary Stretch Wrap. Technical Bulletin.
- [10] Global Supply Chain Sustainability Panel. (2025, November 12). Packaging Waste Reduction Metrics across Industrial Warehousing Operations. GSCSP Bulletin.
- [11] World Shipping Container Safety Federation. (2025, December 16). Freight Stability Standards for Intermodal Rail and Maritime Cargo. WSCSF Report.
- [12] Packaging Machinery Manufacturers Institute. (2026, January 20). Economic Analysis of Capital Expenditure and Maintenance in Automated Packaging Lines. PMMI Report.
- [13] Confindustria Ceramica. (2026, March 14). Logistics and Export Packaging Optimization for Italian Ceramic Tile Shipments. Research Bulletin.
- [14] Australian Freight Logistics Council. (2025, April 22). Bulk Cargo Damage Mitigation across Long-Haul Transport Corridors. AFLC Publications.
- [15] Spanish Food and Beverage Industry Federation. (2025, May 26). Modernization of Automated Packaging and Tertiary Logistics in Spanish Food Export. FIAB Reports.
- [16] Coveris Holdings S.A. (2025, October 15). Commercial Scale-Up of Thirty Percent PCR Stretch Hood Film for European Chemical Distribution. Vienna Media Center.
- [17] Trioworld Group. (2025, November 20). Corporate Announcement: Commercial Launch of Loop70 High-Performance Post-Consumer Recycled Stretch Hood Film. Smalandsstenar News.
- [18] RKW Group. (2025, September 28). Commissioning of Next-Generation Seven-Layer Blown Film Extrusion Line for Ultra-Thin Stretch Hoods. Mannheim Newsroom.
- [19] Berry Global Group, Inc. (2026, January 18). Product Launch: Sustane High-Elasticity Industrial Stretch Hood Film Incorporating Certified Circular Resins. Evansville Investor Center.
- [20] DUO PLAST AG. (2026, February 22). Introduction of High-Clarity Anti-Static Stretch Hood Film for Automated Electronics Warehousing. Lauterbach News.
- [21] Signode Industrial Group. (2026, March 16). Integration of Sensor-Controlled Intelligent Stretch Hood Applicators with Ultra-Thin Barrier Films. Glenview Press Office.
This Report Answers
- How large is the stretch hood film market in 2026 and what is forecast for 2036?
- Which automated warehouse trends support steady demand for stretch hood films?
- Why does polyethylene lead the material resin / polymer category?
- Why do pre-formed pouches & bags lead the product format category globally?
- How do growth rates prominently differ across Italy, Australia, Spain, and the USA?
- Which leading packaging and extrusion corporations supply industrial stretch hood films today?
- What limits extrusion line capital investment or resin prices in the stretch hood film market?
- What should logistics operations directors evaluate deeply before selecting film suppliers?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Resin / Polymer, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Resin / Polymer, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Resin / Polymer, 2026 to 2036
- Polyethylene (LLDPE / HDPE)
- Polypropylene (BOPP / CPP)
- Recycled Post-Consumer PET
- Bio-Based Compostable Resins
- Y-o-Y Growth Trend Analysis By Material Resin / Polymer, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Resin / Polymer, 2026 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Pre-Formed Pouches & Bags
- Rollstock Barrier Films
- Thermoformed Bladders & Tubes
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Level, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Level, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Level, 2026 to 2036
- High-Barrier Modified Atmosphere (EVOH)
- Medium-Barrier Standard
- Breathable Micro-Perforated
- Y-o-Y Growth Trend Analysis By Barrier Level, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Level, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Processed Food & Snacks
- Beverages & Liquid Foods
- Pharmaceutical Medical Devices
- Industrial Chemical Logistics
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Resin / Polymer
- By Product Format
- By Barrier Level
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Berry Global Group, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Trioworld Group
- Sealed Air Corporation
- Huhtamaki Oyj
- Mondi plc
- Coveris Holdings S.A.
- RKW Group
- Sonoco Products Company
- Rigid Packaging & Specialty Producers
- Berry Global Group, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Material Resin / Polymer, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Barrier Level, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Resin / Polymer
- Figure 6: Global Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Format
- Figure 9: Global Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Barrier Level
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Industry
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Resin / Polymer
- Figure 29: North America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Format
- Figure 32: North America Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Barrier Level
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Material Resin / Polymer
- Figure 42: Latin America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Product Format
- Figure 45: Latin America Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Barrier Level
- Figure 48: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Material Resin / Polymer
- Figure 55: Western Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Product Format
- Figure 58: Western Europe Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Barrier Level
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Material Resin / Polymer
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Product Format
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Barrier Level
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Material Resin / Polymer
- Figure 81: East Asia Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Product Format
- Figure 84: East Asia Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Barrier Level
- Figure 87: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Material Resin / Polymer
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Product Format
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Barrier Level
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Material Resin / Polymer, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Material Resin / Polymer, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Material Resin / Polymer
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Product Format
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Barrier Level, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Barrier Level, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Barrier Level
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Stretch Hood Film Market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global stretch hood film market will reach USD 3.8 Billion in 2026. The market is projected to reach USD 6.7 Billion by 2036, driven by high-speed warehouse automation and superior five-sided weatherproofing.
What is the CAGR for the Stretch Hood Film Market from 2026 to 2036?
As per FMI, the market is projected to expand at a 5.8% CAGR over the assessment period. Growth is supported by ongoing polymer engineering into multi-layer metallocene blends, post-consumer recycled resins, and down-gauged high-holding films.
Which product format segment leads the Stretch Hood Film Market?
Future Market Insights projects that pre-formed pouches & bags will hold 38.4% share in 2026. The segment benefits from seamless tubular construction, reliable top ultrasonic sealing, and automated high-speed applicator feeding.
Which material resin segment leads the Stretch Hood Film Market?
Industrial packaging extrusion research indicates that polyethylene will account for 36.6% share in 2026. Demand is supported by superior elastic recovery memory, high dart impact puncture resistance, and cost-effective multi-layer coextrusion processing.
Which country has a notable growth outlook during the assessment period?
FMI finds that Italy is projected to register a 7.1% CAGR from 2026 to 2036. High market growth is supported by massive export shipments of ceramic tiles, advanced automated pallet handling machinery, and demanding maritime transport standards.
Who are the key players in the market?
Key participants include Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, and Mondi plc. Leading market participants focus on seven-layer blown coextrusion, post-consumer recycled polymer compounding, and integrated machinery engineering.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
