

- Market Size (2026)
- USD 1.5 Bn
- Forecast (2036)
- USD 3.0 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Stuffed Dates Market in 2026?
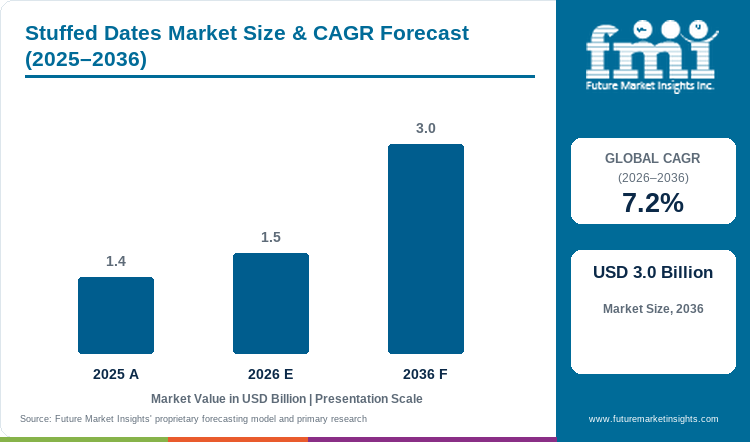
USD 1.5 Billion in 2026 and USD 3.0 Billion by 2036 at a 7.2% CAGR.
Sales of stuffed dates are estimated at USD 1.5 Billion in 2026 and are forecast to reach USD 3.0 Billion by 2036 at a 7.2% CAGR. The market was valued at USD 1.4 Billion in 2025. The category starts with a deep agricultural base but earns its premium after pitting, filling and presentation. Saudi Arabia produced 1.9 million tons of dates in 2024, while 2024 exports of fresh or dried dates from Saudi Arabia were valued at about USD 452.2 Million. Stuffed dates capture only a small part of that raw volume, yet each kilogram can carry far more value once premium varieties, nuts, chocolate or fruit fillings and gift packaging are added.
Demand sits between everyday snacking and formal gifting. A simple almond-filled date can compete with nuts and dried fruit, placing part of the category near the healthy snacks market. A decorated assortment in a rigid box is purchased for a different reason: hospitality, Ramadan and Eid gifting, weddings or corporate appreciation. The same product therefore moves through both repeat snack channels and high-value seasonal channels. Suppliers have to manage date texture, filling stability and allergen controls while keeping the presentation consistent enough to justify a premium price.
Key Takeaways
- The market is estimated at USD 1.5 Billion in 2026 and is forecast to reach USD 3.0 Billion by 2036 at a 7.2% CAGR. The 2025 base is USD 1.4 Billion.
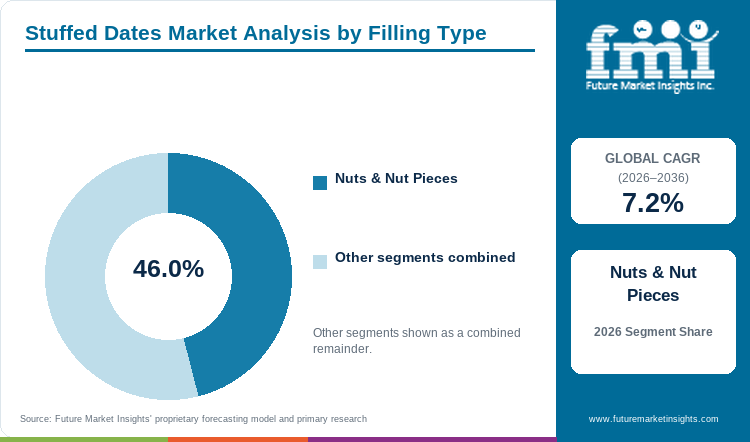
- Nuts & Nut Pieces account for 46.0% of Filling Type demand in 2026 because whole almonds, pistachios and other nuts create a clear texture contrast without requiring a complex cream-filling system.
- Medjool holds 34.0% of Date Variety demand in 2026 because its larger fruit size provides more room for fillings and supports premium presentation in export and gifting channels.
- Uncoated products represent 58.0% of Coating demand in 2026, keeping the date visible and reducing temperature sensitivity compared with fully chocolate-coated formats.
- Gift Boxes account for 43.0% of Pack Format demand, while Specialty Retail & Boutiques hold 32.0% of Sales Channel demand because assortment curation and presentation are part of the purchase decision.
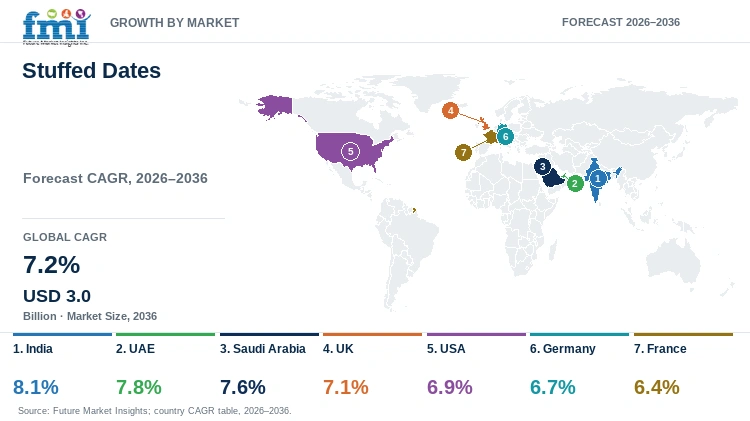
- Country CAGRs range from 8.1% in India to 6.4% in France from 2026 to 2036. Growth is shaped by raw-date access, gifting culture, imported-date availability and the depth of premium retail channels.
Analyst Perspective
Fruit size and texture determine how a date can be filled without tearing or losing its shape. Nuts, pastes and coatings then introduce different allergen, moisture and temperature requirements. Gift orders add short packing deadlines and presentation standards. Everyday snack packs can spread demand beyond festive periods, but they must remain economical alongside the more elaborate assortments.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Stuffed Dates Market segmented?
The Stuffed Dates Market is segmented by Filling Type, Date Variety, Coating, Pack Format, Sales Channel, and Region.
Filling Type includes Nuts & Nut Pieces, Nut Pastes & Pralines, Chocolate & Confectionery Fillings, Fruit/Peel/Mukhwas, and Sesame & Other Fillings. Date Variety covers Medjool, Khalas/Kholas, Khudri/Khodri, Fard/Fardh, and Other Varieties such as Sagai, Sukkari, Ajwa and Safawi. Coating includes Uncoated, Fully Chocolate-Coated, Partially Coated/Drizzled, and Dusted or Glazed. Pack Format covers Gift Boxes, Retail Pouches & Trays, Jars/Tubs, and Individually Wrapped Bulk Packs. Sales Channel includes Specialty Retail & Boutiques, Supermarkets & Hypermarkets, Online/DTC, Travel Retail & Duty Free, and Direct Corporate & HORECA. Regional coverage spans North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and Middle East & Africa.
Why do Nuts & Nut Pieces lead the Filling Type category?
Whole nuts solve the core formulation problem with relatively little processing. An almond, pistachio, walnut, cashew or pecan gives an immediate crunch against the soft date and can be inserted without a pumpable filling. Al Foah lists almond, hazelnut and walnut stuffed dates, while The Date Room pairs Khalas and Fard dates with pistachio, almond, cashew, macadamia and pecan. Kingdom Dates UAE carries nut-filled products across Medjool and Sagai varieties. Nut pastes and pralines create richer flavor systems, but they add consistency control, cleaning requirements and more sensitivity to temperature during filling.
- Nuts & Nut Pieces hold 46.0% of Filling Type demand in 2026 because the filling is visually clear, provides texture contrast and works across premium gifting and everyday packs.
- Creams, chocolate centers and fruit fillings widen the assortment, but suppliers need tighter control over viscosity, migration and shelf stability than with a whole nut.
Why does Medjool lead the Date Variety category?
Medjool has a practical advantage for stuffing: the fruit is typically large enough to create a visible cavity after the pit is removed. That gives producers room for whole nuts, nut pastes or chocolate while preserving an attractive shape. Tamr Boutique builds its stuffed-date range around Medjool, and Falcon Dates sells Medjool products with full nuts, flaked nuts, peels, crunches and mukhwas. Bateel also uses premium date varieties across gourmet filled assortments. Khalas, Khudri, Fard and Sagai remain important, especially in Gulf portfolios, because their flavor and texture profiles can suit specific fillings or price points.
- Medjool accounts for 34.0% of Date Variety demand in 2026 because its size supports generous filling loads and a premium visual cue in boxed assortments.
- Regional producers still rely heavily on Khalas/Kholas, Khudri/Khodri, Fard/Fardh and Sagai, so suppliers that can grade several varieties have more flexibility across price tiers.
Why do Uncoated products lead the Coating category?
An uncoated stuffed date keeps the fruit visible, lowers the risk of coating bloom or melting and makes the nut or filling easier to recognize. That matters in markets where dates are bought as fruit first and confectionery second. Chocolate-coated and partially coated products create a stronger indulgence cue and connect stuffed dates with the chocolate confectionery market. Bayara sells dates filled with almonds and coated in milk, dark or assorted chocolate, showing how a single SKU can sit across both categories. Coating can raise value per piece, but it also increases temperature-control and packaging requirements during storage and distribution.
- Uncoated products hold 58.0% of Coating demand in 2026 because they preserve the identity of the date and are easier to handle across warm-climate and ambient distribution.
- Chocolate-coated products create stronger confectionery positioning and gifting appeal, but the supplier has to manage coating quality, heat exposure and additional allergen declarations.
Why do Gift Boxes lead the Pack Format category?
Stuffed dates are frequently bought as a present rather than as a simple pantry refill, so packaging becomes part of the product. The Date Room offers stuffed-date versions across multiple gift collections and Tamr Boutique sells corporate boxes that can be customized with company branding. Bateel packages gourmet filled dates in presentation sets, while Falaj Dates sells 15-piece and 30-piece stuffed-date boxes. This purchasing logic links the category with the wider gift boxes market. Retail pouches remain important for repeat snacking, but a box creates room for assortment, portion separation and a higher-value gifting occasion.
- Gift Boxes account for 43.0% of Pack Format demand in 2026 because packaging communicates occasion, assortment and premium positioning before the product is tasted.
- Pouches and trays support everyday purchase, while individually wrapped bulk formats are useful for offices, hotels and travel settings where portion control matters.
Why do Specialty Retail & Boutiques lead the Sales Channel category?
A stuffed-date buyer often wants to compare varieties, fillings, box sizes and presentation rather than choose only on price. Specialty stores and boutiques can support tasting, customization and gift selection in a way that a standard grocery shelf cannot. The Date Room operates a boutique in Abu Dhabi, Tamr Boutique combines gifting and direct delivery in the UAE, and Amal Al Khair operates more than 11 branches in Saudi Arabia. Online channels are expanding selection beyond the store, but premium date brands still use physical retail to make texture, freshness and packaging visible before purchase.
- Specialty Retail & Boutiques hold 32.0% of Sales Channel demand in 2026 because service, curation and immediate gifting presentation influence conversion.
- Online/DTC gains relevance when brands can ship temperature-stable products reliably and let buyers configure flavors or branded boxes before delivery.
What are the drivers, restraints and opportunities in the Stuffed Dates Market?
Value-added date processing expands the revenue pool, seasonal concentration limits utilization, and everyday snack formats create a route beyond gifting.
- Driver: Large date-producing and trading systems give processors access to fruit that can be graded, pitted and converted into higher-value stuffed products.
- Restraint: Demand can concentrate around Ramadan, Eid and gifting periods, while nut allergens, filling stability and chocolate heat sensitivity add operating complexity.
- Opportunity: Smaller snack packs, corporate customization and new fillings can move stuffed dates into more frequent purchase occasions without abandoning the premium gift business.
The raw-material base is large enough for processors to separate fruit by grade and end use. Saudi Arabia produced 1.9 million tons of dates in 2024, and Saudi exports reached SAR 1.7 billion in the same year. The National Center for Palms & Dates reported exports to 133 countries. Stuffing requires fruit with suitable size, texture and grade. It is to divert suitable fruit into a format where the filling, brand and pack create more value per kilogram. Saudi industrial listings already distinguish prepared and stuffed dates, dates with nuts and gift dates as separate product categories, showing that value-added processing has become a formal manufacturing activity rather than a household-only preparation.
Seasonality can still make the business difficult to plan. Premium boxes sell heavily around Ramadan, Eid, weddings and corporate calendars, creating short periods when labor, packing capacity and inventory have to move quickly. Fillings also change the risk profile. Nuts require allergen segregation, soft pastes can migrate into the fruit, and chocolate coatings can suffer in hot distribution. These constraints separate stuffed dates from simpler fruit snacks market where the product structure may be more uniform. A brand that expands into many flavors without controlling moisture and storage can create more complexity than revenue.
One expansion route is to make the product less occasion-dependent. The Date Room offers build-your-own assortments and 500 g mixed boxes, while Tamr Boutique also positions stuffed dates as daily bites. Falcon Dates has extended fillings into mukhwas, linking a date snack with an Indian after-meal flavor system. Another route is adjacent date processing such as spreads, paste or syrup, which sits outside this market but can use the same sourcing base; the commercial adjacency is visible in the date syrup market. Producers that can route different grades into different finished products can reduce dependence on a single premium format.
Which country CAGRs are profiled in the Stuffed Dates Market?
| Country | CAGR |
|---|---|
| India | 8.1% |
| UAE | 7.8% |
| Saudi Arabia | 7.6% |
| UK | 7.1% |
| USA | 6.9% |
| Germany | 6.7% |
| France | 6.4% |
How do country-level CAGRs compare in the Stuffed Dates Market?
Growth across the profiled countries ranges from 8.1% CAGR in India to 6.4% in France from 2026 to 2036. India combines a very large imported-date flow with a growing premium gifting and online-snacking channel. The UAE and Saudi Arabia benefit from direct access to date production, established gifting culture and a supplier base already selling stuffed products. The UK, USA, Germany and France have sizeable imported-date markets, but the category competes more directly with chocolate, dried fruit and nut snacks. In those countries, conversion depends on retail education and repeated purchase outside religious or ethnic occasions.
- India leads the profiled range at 8.1% CAGR. Established date imports provide raw material for stuffed formats sold through festive gifting, weddings and premium snack channels.
- UAE at 7.8% and Saudi Arabia at 7.6% combine cultural familiarity with a dense supplier ecosystem, giving brands more routes through boutiques, corporate gifting, travel retail and modern grocery.
- UK at 7.1% and USA at 6.9% have imported-date bases near USD 100 Million each in 2024, creating enough raw-product familiarity for premium filled formats to build specialized shelf space.
- Germany at 6.7% and France at 6.4% benefit from established North African and Mediterranean date supply, though premium stuffed formats still have to justify a price step-up over plain dates.
Country-wise Analysis
- India: Demand for Stuffed Dates is forecast to expand at 8.1% CAGR from 2026 to 2036. World Bank WITS data show that India imported USD 286.2 Million of fresh or dried dates in 2024, equal to 526.6 million kg. The UAE supplied USD 124.4 Million of that value, followed by Iraq and Iran. The size of the raw-date channel gives Indian processors and importers a broad base from which to build nut-filled and festive gift assortments. Falcon Dates already sells stuffed Safawi, Khidri and Medjool products in India, including a 2025 Mukhwas-stuffed range that adapts the format to local after-meal and gifting traditions.
- UAE: Demand is forecast to rise at 7.8% CAGR from 2026 to 2036. Al Foah states that it handles more than 220,000 tons of dates annually, exports to more than 40 countries and manages more than 200 SKUs. The same market supports boutique specialists such as The Date Room and Tamr Boutique alongside Kingdom Dates UAE, Bayara and Falaj Dates. This depth makes the UAE a test market for assortment, corporate branding and travel-oriented packs. Supplier competition therefore centers on design and freshness as much as on access to dates.
- Saudi Arabia: Demand is forecast to expand at 7.6% CAGR from 2026 to 2036. GASTAT reported 1.9 million tons of date production in 2024 from more than 37.6 million palm trees. The National Center for Palms & Dates reported SAR 1.7 billion of exports to 133 countries in 2024, while 2025 exports rose to SAR 1.9 billion. Saudi industrial directories separately classify prepared and stuffed dates, dates with nuts and wedding/gift dates. Grading, filling and branded presentation can increase the value of suitable fruit sold domestically or exported.
- UK: Demand is forecast to increase at 7.1% CAGR from 2026 to 2036. The UK imported USD 98.0 Million of dates in 2024, totaling 28.2 million kg. Supply came from Israel, Tunisia, Jordan, the UAE, Palestinian territories and Saudi Arabia among other sources. That diversified import base supports broad date availability, while premium stuffed products can target Ramadan gifting, specialty food retail and year-round natural-snack buyers. The challenge is keeping the proposition distinct from both plain dates and boxed chocolate.
- USA: Demand is forecast to expand at 6.9% CAGR from 2026 to 2036. The United States imported USD 98.8 Million of dates in 2024, equal to 33.9 million kg, with Mexico, Tunisia and Algeria among the main suppliers. USDA also maintains specific import inspection rules for dates intended for human consumption, which reinforces the importance of clear product handling and processing status. Stuffed-date brands can target specialty retail, online gifting and natural-food channels, but they need allergen declarations and stable shelf performance for nut and chocolate variants.
- Germany: Demand is forecast to grow at 6.7% CAGR from 2026 to 2036. Germany imported USD 95.6 Million of dates in 2024, totaling 32.4 million kg. Tunisia supplied nearly half of the import value, with Israel and Iran also significant. This existing date distribution network lowers the raw-product access barrier for importers. Stuffed dates can move through ethnic and specialty retail, then extend into mainstream premium snacking if brands communicate filling quality and portion value without relying only on seasonal demand.
- France: Demand is forecast to rise at 6.4% CAGR from 2026 to 2036. France imported USD 124.1 Million of dates in 2024, equal to 54.1 million kg. Tunisia and Algeria together supplied a large majority of that value, creating strong North African sourcing links. The domestic opportunity is less about introducing dates and more about increasing value per purchase through nuts, confectionery fillings and gifting packs. Brands that fit French premium-food merchandising can use the existing date habit as a base rather than building category awareness from zero.
Who are the notable companies in the Stuffed Dates Market?
Bateel; Al Foah; Nadiya Luxury Arabian Dates; Bayara; The Date Room; Tamr Boutique; Falaj Dates; Kingdom Dates UAE; Falcon Dates; Amal Al Khair Dates
The competitive set combines scaled date processors with boutique gift specialists and regional snack brands. Al Foah brings a large UAE sourcing and export platform. Bateel positions gourmet filled dates within luxury gifting. Nadiya, The Date Room, Tamr Boutique and Falaj Dates compete through assortment and presentation in the UAE. Bayara connects stuffed dates with mainstream packaged confectionery. Kingdom Dates UAE operates a broad filled-date catalog with retail and export inquiry channels. Falcon Dates adapts the format for India through several date varieties and locally familiar fillings. Amal Al Khair combines Saudi manufacturing with more than 11 domestic showrooms and Gulf distribution.
- Scaled processors compete on grading, food safety, export capability and the ability to route several date varieties into value-added SKUs.
- Boutique brands compete on flavor design, box customization and short-run gifting programs for corporate or event buyers.
- Packaged snack brands compete on price points, supermarket readiness and repeatable shelf life rather than bespoke presentation alone.
Competitive Benchmarking: Stuffed Dates Market
| Company | Filling & Flavor Breadth | Gifting & Customization | Retail / DTC Reach | Geographic Reach |
|---|---|---|---|---|
| Bateel | High | High | High | GCC, Europe, North America and other international markets |
| Al Foah | High | High | High | UAE platform exporting to 40+ countries |
| Nadiya Luxury Arabian Dates | High | High | High | UAE with retail, corporate and HORECA channels |
| Bayara | Medium | Medium | High | UAE and regional packaged-food channels |
| The Date Room | High | High | High | UAE, boutique and direct delivery |
| Tamr Boutique | High | High | High | UAE with corporate and direct-to-consumer focus |
| Falaj Dates | Medium | High | High | UAE with bulk/corporate delivery |
| Kingdom Dates UAE | High | Medium | High | UAE retail plus export inquiries |
| Falcon Dates | High | Medium | High | India with online and trade channels |
| Amal Al Khair Dates | Medium | Medium | High | Saudi Arabia, Gulf distributors and export business |
Scoring basis: Filling & Flavor Breadth measures documented variety across nuts, pastes, fruit, confectionery or other fillings. Gifting & Customization measures dedicated gift formats, corporate branding or configurable assortments. Retail / DTC Reach measures direct selling, store presence or packaged retail availability. High indicates broad documented capability against the criterion. Medium indicates narrower but active coverage.
Key Developments in the Stuffed Dates Market
- In April 2026, The Date Room promoted its Build Your Own Date Gift Box, allowing customers to select up to seven stuffed-date flavors in a half-kilogram box. The offer turns customization into a standard online purchase rather than a special-order service and gives the brand a way to capture both gifting and self-purchase demand.
- In March 2026, Agthia’s FY2025 presentation highlighted value-added date innovation across its snacking platform, including a new Date Crown pack format and Medjool coated and filled dates within the broader portfolio. The update shows continued investment in packaging and filled-date formats as a route to higher-value date consumption.
- In May 2025, Falcon Dates introduced Mukhwas Stuffed Safawi Dates, combining Safawi or Khidri dates with fennel, sesame, coconut and herb-style mukhwas. The launch translated the stuffed-date format into an Indian after-meal and festive-gifting flavor system rather than relying only on nuts or chocolate.
Key Players in the Stuffed Dates Market
Scaled Date Processing and Export Platforms
- Al Foah
- Bateel
- Amal Al Khair Dates
- Bayara
Premium Gift and Boutique Specialists
- Nadiya Luxury Arabian Dates
- The Date Room
- Tamr Boutique
- Falaj Dates
Regional Filled-Date and Snack Specialists
- Kingdom Dates UAE
- Falcon Dates
Stuffed Dates Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Filling Type; Date Variety; Coating; Pack Format; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from packaged dates that are pitted and filled with nuts, nut pastes, confectionery, fruit, peel, mukhwas, sesame or other edible fillings. Products may be uncoated, partially coated or fully coated after stuffing. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries Covered | India; UAE; Saudi Arabia; UK; USA; Germany; France; and more than twenty-five additional countries in the full report |
| Key Companies Profiled | Bateel; Al Foah; Nadiya Luxury Arabian Dates; Bayara; The Date Room; Tamr Boutique; Falaj Dates; Kingdom Dates UAE; Falcon Dates; Amal Al Khair Dates |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid bottom-up and top-down sizing that reconciles date trade and production, product pricing, value-added conversion, pack mix and channel economics within the defined stuffed-date boundary. |
Stuffed Dates Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | Commercial assumptions are tested against the purchase criteria visible across producers, specialty retailers, packaged-food sellers, corporate-gifting offers and distribution channels. The assessment focuses on date grade, filling choice, pack architecture, shelf life, gifting demand and channel fit. |
| Desk Research | The evidence base uses government agricultural statistics, World Bank trade data, U.S. import rules, Saudi industrial classifications, current producer catalogs and dated company releases relevant to value-added date products. |
| Market Sizing and Forecasting | Sizing triangulates raw-date availability with the share suitable for premium filling, observed pack economics and channel mix across producing and importing countries. Forecast assumptions reflect value-added processing, premium retail penetration, gifting demand, online customization and the move toward more frequent snack occasions. |
| Data Validation | Country, segment and supplier views are cross-checked against the market boundary. Plain dates, date paste, date syrup, maamoul, date bars and products without an internal edible filling are kept outside stuffed-date revenue. |
Stuffed Dates Market by Segments
Stuffed Dates Market segmented by Filling Type:
- Nuts & Nut Pieces
- Nut Pastes & Pralines
- Chocolate & Confectionery Fillings
- Fruit / Peel / Mukhwas
- Sesame & Other Fillings
Stuffed Dates Market segmented by Date Variety:
- Medjool
- Khalas / Kholas
- Khudri / Khodri
- Fard / Fardh
- Other Varieties (Sagai, Sukkari, Ajwa, Safawi and others)
Stuffed Dates Market segmented by Coating:
- Uncoated
- Fully Chocolate-Coated
- Partially Coated / Drizzled
- Dusted or Glazed
Stuffed Dates Market segmented by Pack Format:
- Gift Boxes
- Retail Pouches & Trays
- Jars / Tubs
- Individually Wrapped Bulk Packs
Stuffed Dates Market segmented by Sales Channel:
- Specialty Retail & Boutiques
- Supermarkets & Hypermarkets
- Online / DTC
- Travel Retail & Duty Free
- Direct Corporate & HORECA
Stuffed Dates Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia & Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East & Africa
- GCC Countries
- Saudi Arabia
- United Arab Emirates
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- General Authority for Statistics, Saudi Arabia. Agricultural Statistics Publication 2024. Released November 30, 2025.
- National Center for Palms & Dates, Saudi Arabia. Saudi Dates Expand Global Presence, Export Value Tops SAR 1.7 Billion. June 15, 2025.
- Saudi Press Agency. Saudi date exports reached SAR 1.938 billion in 2025. April 25, 2026.
- World Bank World Integrated Trade Solution, based on UN Comtrade. Dates, fresh or dried, global exports for 2024.
- World Bank World Integrated Trade Solution. India imports of Dates, fresh or dried, 2024.
- World Bank World Integrated Trade Solution. United Kingdom imports of Dates, fresh or dried, 2024.
- World Bank World Integrated Trade Solution. United States imports of Dates, fresh or dried, 2024.
- World Bank World Integrated Trade Solution. Germany imports of Dates, fresh or dried, 2024.
- World Bank World Integrated Trade Solution. France imports of Dates, fresh or dried, 2024.
- U.S. Department of Agriculture, Agricultural Marketing Service. Importing Dates, Section 8e requirements.
- Saudi B2B e-Marketplace / industry.com.sa. Factory product classifications covering prepared and stuffed dates, dates with nuts and gift dates.
- Al Foah. Current company and product pages covering annual date handling, export reach, SKUs and stuffed-date products.
- Agthia Group. FY2025 Earnings Call Presentation, March 2026, and Al Foah engagement materials, November 2025.
- Bateel. Current gourmet filled-date and gift-set product pages.
- The Date Room. Stuffed Dates collection and Build Your Own Box, accessed 2026.
- Tamr Boutique. Stuffed Dates: Flavors, Ingredients and Gifting in the UAE. May 10, 2026.
- Falcon Dates. Why Mukhwas Stuffed Dates Are the Next Big Thing in Healthy Snacking. May 8, 2025.
- Bayara. Current Coated & Stuffed Dates range and 2025 confectionery catalog.
- Kingdom Dates UAE. Current Stuffed Dates collection and export inquiry information.
- Amal Al Khair Dates / J. Baghlaf Group. Current company profile and branch information.
This Report Answers
- What is the Stuffed Dates Market size in 2026 and what value is forecast for 2036?
- Why do Nuts & Nut Pieces account for 46.0% of Filling Type demand in 2026?
- Why does Medjool hold the leading position within Date Variety?
- How do coatings and gift-box formats change handling requirements and value per kilogram?
- How do growth rates differ across India, UAE, Saudi Arabia, UK, USA, Germany and France?
- Which suppliers compete through scaled processing versus boutique customization?
- What limits year-round utilization in a category with strong Ramadan, Eid and gifting demand?
- What should retail, corporate-gifting and distribution buyers evaluate before qualifying a stuffed-date supplier?
Frequently Asked Questions
What is driving growth in the Stuffed Dates Market?
Growth comes from the conversion of widely traded dates into higher-value products through filling, assortment and presentation. Nut-filled products work for everyday snacking, while decorated boxes serve Ramadan, Eid, weddings and corporate gifting. Online configuration and smaller packs create additional purchase occasions outside the traditional festive calendar.
Who are the key players in the Stuffed Dates Market?
Key companies include Bateel, Al Foah, Nadiya Luxury Arabian Dates, Bayara, The Date Room, Tamr Boutique, Falaj Dates, Kingdom Dates UAE, Falcon Dates and Amal Al Khair Dates. They compete from different positions, ranging from scaled date processing and export to boutique customization and region-specific fillings.
What notable restraint affects the Stuffed Dates Market?
Seasonal concentration can leave packing capacity underused outside major gifting periods. The product also becomes more complex as fillings are added: nuts introduce allergen controls, soft centers create migration risk and chocolate coatings increase sensitivity to heat during storage and delivery.
Why should executives track the Stuffed Dates Market?
The market shows how date producers can raise value without moving far from the core fruit. It also reveals whether premium date consumption is becoming less seasonal. Growth in snack packs, configurable assortments and corporate programs would indicate a broader revenue base than bulk or plain-date sales alone.
What business problem does the Stuffed Dates Market address?
Stuffing gives processors a way to differentiate date varieties that might otherwise compete mainly on grade, origin and price. For buyers, the finished product combines a ready-to-eat fruit base with a defined filling and presentation format, reducing the need to assemble a separate confectionery or gift assortment.
What should buyers evaluate before sourcing stuffed dates?
Buyers should compare date variety and grade, filling consistency, allergen controls, coating stability, pack barrier, declared shelf life and the supplier’s ability to deliver the same piece count and presentation across batches. Corporate buyers should also check customization lead time, minimum order quantities and temperature exposure during delivery.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Filling Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Filling Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Filling Type, 2026 to 2036
- Nuts & Nut Pieces
- Nut Pastes & Pralines
- Chocolate & Confectionery Fillings
- Fruit / Peel / Mukhwas
- Sesame & Other Fillings
- Y-o-Y Growth Trend Analysis By Filling Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Filling Type, 2026 to 2036
- Global Market Analysis and Forecast, By Date Variety, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Date Variety, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Date Variety, 2026 to 2036
- Medjool
- Khalas / Kholas
- Khudri / Khodri
- Fard / Fardh
- Other Varieties (Sagai, Sukkari, Ajwa, Safawi and others)
- Y-o-Y Growth Trend Analysis By Date Variety, 2021 to 2025
- Absolute $ Opportunity Analysis By Date Variety, 2026 to 2036
- Global Market Analysis and Forecast, By Coating, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coating, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coating, 2026 to 2036
- Uncoated
- Fully Chocolate-Coated
- Partially Coated / Drizzled
- Dusted or Glazed
- Y-o-Y Growth Trend Analysis By Coating, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating, 2026 to 2036
- Global Market Analysis and Forecast, By Pack Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pack Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pack Format, 2026 to 2036
- Gift Boxes
- Retail Pouches & Trays
- Jars / Tubs
- Individually Wrapped Bulk Packs
- Y-o-Y Growth Trend Analysis By Pack Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Pack Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Specialty Retail & Boutiques
- Supermarkets & Hypermarkets
- Online / DTC
- Travel Retail & Duty Free
- Direct Corporate & HORECA
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- Saudi Arabia
- United Arab Emirates
- South Africa
- Türkiye
- Israel
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Filling Type
- By Date Variety
- By Coating
- By Pack Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bateel
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Al Foah
- Nadiya Luxury Arabian Dates
- Bayara
- The Date Room
- Tamr Boutique
- Falaj Dates
- Kingdom Dates UAE
- Falcon Dates
- Amal Al Khair Dates
- Bateel
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


