

- Market Size (2026)
- USD 545.0 Mn
- Forecast (2036)
- USD 1032.7 Mn
- CAGR (2026 to 2036)
- 6.6%
How big is Vegan Makeup Market in 2026?
USD 545.0 Million in 2026 and USD 1,032.7 Million by 2036 at a 6.6% CAGR.
The Vegan Makeup Market is valued at USD 545.0 Million in 2026 and is forecast to reach USD 1,032.7 Million by 2036 at a 6.6% CAGR. The Vegan Makeup Market was valued at USD 511.3 Million in 2025. Buyers assess shade match and wear alongside proof that a formula contains no animal-derived ingredients. The Vegan Society reported more than 35,000 Vegan Trademark registrations across cosmetics and toiletries in April 2025. This count covers the wider beauty category. [2]
In the United States, MoCRA requires covered cosmetic facilities to register and responsible persons to list products and ingredients. EU markets apply common cosmetic-claims criteria and an animal-testing marketing ban. Gulf markets use national conformity or notification systems for product entry. [3] [4] [5] [12] [16]
Suppliers need ingredient-origin records and safety documentation before entering these channels. Animal-free positioning also extends across other beauty categories in the wider vegan cosmetics market.
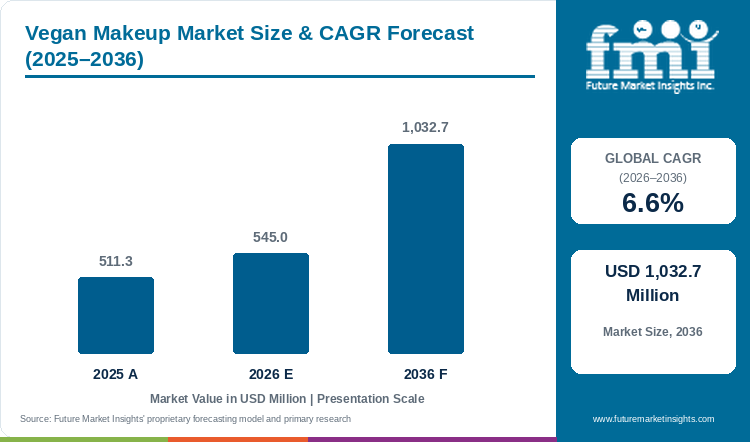
Vegan Makeup Market Size & CAGR Forecast (2025-2036)
| Year | Basis | Market value (USD million) |
|---|---|---|
| 2025 | Actual | 511.3 |
| 2026 | Estimate | 545.0 |
| 2036 | Forecast | 1,032.7 |
| CAGR, 2026 to 2036 | 6.6% | |
Source: Future Market Insights proprietary forecasting model and primary research.
Key Takeaways
- Consumers and retailers increasingly look for clear support for animal-free ingredients and testing claims.
- Core / classic lines hold 35.0% of the market in 2026 as everyday face, eye and lip products support repeat purchase across price tiers.
- Conventional holds 50.0% of the Nature axis in 2026. Mainstream formulas and merchandising remain important within vegan makeup.
- Cream & balm holds 26.0% of the Format axis in 2026. These textures support blending and skin comfort in multi-use lip and complexion products.
- Claim documentation can slow product launches. Brands must support vegan and cruelty-free wording while meeting safety, labeling and registration requirements.
- Profiled companies are Kao Corporation, Procter & Gamble, Estee Lauder Companies, e.l.f. Beauty, L'Oreal, Beiersdorf, Coty, Amorepacific, Unilever, and Shiseido.
Analyst Perspective
“Revenue realization depends less on ethical interest than on whether brands can document vegan claims while matching conventional expectations for shade choice and wear. Price and retail availability remain decisive.”
- Rahul Pandita, Principal Consultant, Future Market Insights
How is the vegan makeup market segmented?
The market is segmented by Product Type, Nature, Format, Price Positioning, and Sales Channel.
Product Type covers Core / classic lines, Targeted treatment lines, Sensitive & gentle lines, Premium & clinical lines, and Kits & sets. Nature covers Conventional, Vegan & cruelty-free, Natural & organic, Dermocosmetic / clinical, and Fragrance-free & sensitive. Format covers Cream & balm, Liquid & serum, Stick & solid, Spray & mist, Sheet & patch, and Powder. Price Positioning covers Mass, Masstige, Premium, and Professional. Sales Channel covers E-commerce & DTC, Specialty beauty retail, Pharmacies & drugstores, Supermarkets & hypermarkets, and Salons & spas.
What makes Core / classic lines central to the Product Type category?
Core / classic lines cover familiar everyday makeup that consumers replace regularly.
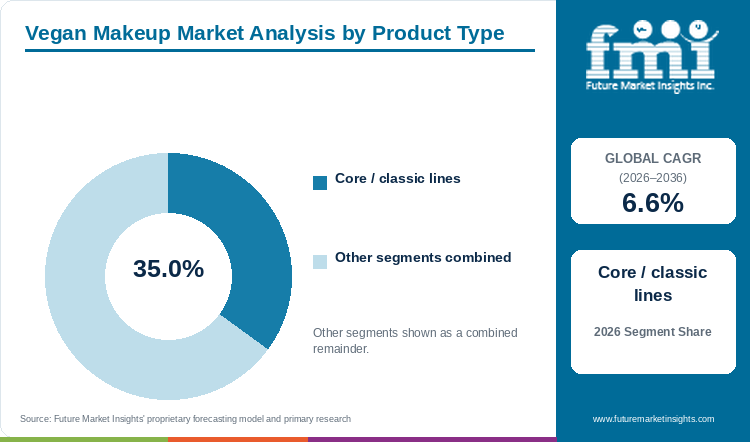
| Product type | Share (2026) |
|---|---|
| Core / classic lines | 35.0% |
| Other segments combined | 65.0%* |
| Total | 100.0% |
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.6% |
| Leading segment | Core / classic lines |
- Core / classic lines account for 35.0% of 2026 revenue as routine makeup use supports a broad customer base and regular replenishment.
- Core / classic lines cover the makeup consumers use and replace regularly. Familiar application makes it easier to introduce vegan formulas into existing routines. A broad choice of shades and finishes also gives retailers a clear reason to stock these products. Everyday face and lip products share this repeat-purchase role with the wider colour cosmetics market.
- In August 2024, Estée Lauder Companies launched Smashbox in Amazon Premium Beauty. The announcement identified Photo Finish primer as vegan and cruelty-free, giving an established core product a wider digital audience. [6]
Why does Conventional lead the Nature category?
Mainstream formulations can meet vegan requirements while retaining familiar performance and pricing.
Conventional describes mainstream formulas and merchandising within this vegan makeup taxonomy. Buyers still expect color payoff and wear at a suitable price. Suppliers can meet those expectations with synthetic or plant-derived functional ingredients while excluding animal-derived inputs. Natural & organic and dermocosmetic positioning introduce additional formulation requirements. Ingredient-origin preferences are also central to the adjacent natural cosmetics market.
- Conventional represents 50.0% of the Nature axis in 2026. Mainstream performance and price expectations remain the main purchase benchmarks within vegan makeup.
What are the drivers, restraints and opportunities in the vegan makeup market?
Demand for verifiable animal-free formulas supports growth. Claim documentation and compliance across markets raise launch costs, while ingredient innovation helps suppliers retain familiar makeup performance.
- Driver: Independent vegan and cruelty-free verification helps shoppers assess unfamiliar ingredients and testing claims.
- Restraint: Brands need to support ingredient and testing claims while meeting safety and labeling rules in each market.
- Opportunity: Plant-derived or synthetic substitutes can replace animal inputs while preserving color intensity, feel and wear.
The Vegan Society reported that 81% of surveyed UK and US respondents looked for vegan certification on cosmetics and toiletries when buying vegan products. Its late-2023 Attest survey covered 3,000 primarily non-meat-eating adults across the US, UK and Australia. The findings concern cosmetics and toiletries broadly. [1] Certification can simplify ingredient checks before a shopper compares shades and prices. Testing claims serve a separate purpose in the cruelty-free cosmetics market: they address animal testing rather than establishing whether a formula contains animal-derived ingredients. [2] EU common criteria require adequate support for cosmetic claims. In the USA, MoCRA requires covered facilities to register and responsible persons to list products and ingredients, subject to exemptions. Keeping these records current adds work to product review across markets. [4] [3] Ingredient substitution offers a practical route to more vegan makeup formulas. A Unilever investor presentation highlighted Hourglass Red 0 as a vegan alternative to insect-derived carmine, with color vibrancy and intensity retained. [11] Red pigments are important in lip and cheek products. Replacing animal-derived colorants or other functional inputs while preserving wear can broaden vegan ranges. The commercial opportunity also depends on keeping prices and shades aligned with buyer expectations.
Which country CAGRs are profiled in the vegan makeup market?
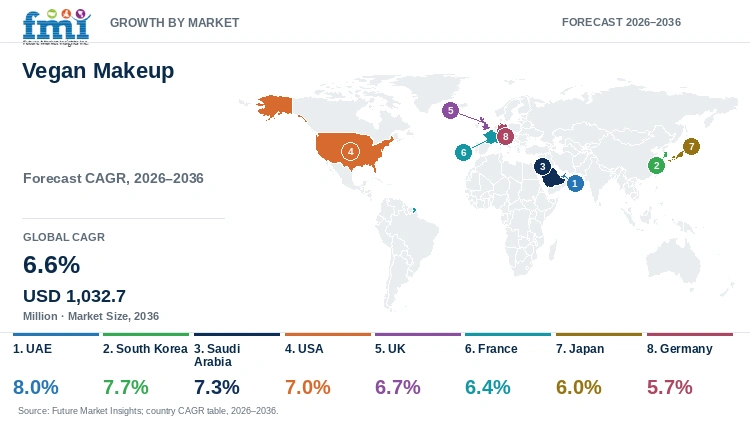
| Country | CAGR |
|---|---|
| UAE | 8.0% |
| South Korea | 7.7% |
| Saudi Arabia | 7.3% |
| USA | 7.0% |
| UK | 6.7% |
| France | 6.4% |
| Japan | 6.0% |
| Germany | 5.7% |
- UAE: At 8.0% CAGR from 2026 to 2036, the UAE has the fastest growth among the countries profiled. Imported eye and facial makeup falls within Ministry of Industry and Advanced Technology conformity requirements. Dubai Municipality also operates Montaji registration for consumer products. Vegan makeup brands therefore need the technical file and local registration work ready before distribution begins. [12] [13]
- South Korea: Vegan makeup has a visible place in the mainstream beauty market. Amorepacific launched vegan-certified HERA Blush in July 2024 through online and department-store channels. [15] The Cosmetics Act restricts cosmetics tested on animals and products made with animal-tested raw materials, subject to statutory exceptions. [14] South Korea is forecast to grow at a 7.7% CAGR through 2036. Shade quality and texture remain important to winning repeat purchases.
- Saudi Arabia: L’Oréal identified online sales as an important growth driver in Saudi Arabia in its 2024 results. [17] Cosmetic products require Saudi Food and Drug Authority notification before marketing. [16] At a 7.3% CAGR from 2026 to 2036, the forecast points to room for expansion when local notification and Arabic-language product information are in place.
- USA: MoCRA requires covered manufacturers and processors to register facilities. Responsible persons must list marketed products and ingredients with FDA, subject to exemptions. [3] The USA is forecast to grow at a 7.0% CAGR from 2026 to 2036. e.l.f. and Smashbox show how vegan makeup products can reach buyers through large digital and retail channels. [18] [6]
- UK: Products launched in Great Britain need both ordinary cosmetics documentation and support for vegan claims. Government guidance requires a UK-established Responsible Person and applicable notification before market placement. [19] The UK is forecast to grow at a 6.7% CAGR through 2036. Clear claim wording is part of routine launch preparation.
- France: Cosmetic claims face close scrutiny. In November 2023 the DGCCRF reported anomalies at 40% of operators checked for “free-from” claims. [10] Its 2025 clarification stated that wording such as “without ingredients or substances of animal origin” can be equivalent to vegan when properly supported. [20] France is forecast to grow at a 6.4% CAGR from 2026 to 2036. Clear raw-material records help brands substantiate these claims.
- Japan: Texture and finish shape makeup competition. Kao opened the first global KATE flagship in Shibuya in July 2024, while Shiseido promoted its serum-first foundation concept that year. [22] [23] Vegan formulas enter the same competitive setting and remain subject to Japanese cosmetic standards. [21] Japan is forecast to grow at a 6.0% CAGR from 2026 to 2036. Color and sensory performance remain important alongside ingredient origin.
- Germany: At a 5.7% CAGR from 2026 to 2036, Germany has the lowest forecast growth rate among the countries profiled. The Federal Institute for Risk Assessment explains that cosmetics do not require EU pre-market authorisation. Safety responsibilities and notification requirements still apply. Vegan makeup suppliers also need ingredient-origin records to support their claims. [24]
Who are the notable companies in the vegan makeup market?
Kao Corporation, Procter & Gamble, Estee Lauder Companies, e.l.f. Beauty, L'Oreal, Beiersdorf, Coty, Amorepacific, Unilever, and Shiseido are the notable companies profiled in this market.
e.l.f. Cosmetics and Hourglass under Unilever have brand-wide vegan policies. Hourglass says it has been fully vegan since 2020. [18] [26] Coty relaunched Kylie Cosmetics with vegan formulas. [7] Smashbox and Chantecaille offer vegan makeup assortments under Estee Lauder Companies and Beiersdorf respectively. [32] [27]
NYX, HERA and NARS identify specific vegan makeup formulas. [29] [15] [28] Kao participates in makeup through KATE. Vegan makeup participation is not specified for Kao or Procter & Gamble in the cited company information. [22] [31]
- Brand-wide vegan propositions: e.l.f. Beauty, Coty through Kylie Cosmetics, and Unilever through Hourglass.
- Vegan assortments or individual products: Estee Lauder Companies, L’Oreal, Beiersdorf, Amorepacific and Shiseido.
- Other profiled beauty companies: Kao Corporation and Procter & Gamble.
Competitive Benchmarking: Vegan Makeup Market
| Company | Vegan Formula Breadth | Claim Support | Makeup Channels | Geographic Reach |
|---|---|---|---|---|
| Kao Corporation | Vegan range not specified | Vegan makeup claim not specified | KATE flagship retail [22] | KATE makeup activity in Japan and Asia |
| Procter & Gamble | Vegan range not specified | Vegan makeup claim not specified | Vegan makeup channel not specified [31] | Global beauty operations |
| Estee Lauder Companies | Smashbox vegan assortment [32] | Product and assortment claims | Prestige retail and Amazon [6] | International prestige makeup through Smashbox |
| e.l.f. Beauty | Brand-wide vegan positioning [18] | Brand vegan policy | Retail and DTC [35] [36] | United States plus expanding European and international retail and DTC |
| L'Oreal | Selected NYX vegan formulas [29] | Product-level claims | Mass beauty retail | Europe, North America, Asia and emerging beauty markets |
| Beiersdorf | Chantecaille vegan collection [27] | Collection and product claims | Prestige beauty channels | Chantecaille prestige channels and vegan makeup collection |
| Coty | Kylie Cosmetics vegan formulas [7] | Brand and formula claims | Selected retail and DTC | United States, Europe, UK, Australia and global DTC through Kylie Cosmetics |
| Amorepacific | HERA vegan blush [15] | Product vegan certification | Online and department stores | South Korea and selected international beauty markets |
| Unilever | Hourglass vegan brand [26] | Brand vegan policy | Prestige beauty channels | International Hourglass prestige beauty channels |
| Shiseido | NARS vegan foundation [28] | Product-level claim | Prestige beauty channels | NARS prestige channels |
Vegan claims apply to the brands, collections or products identified in the table. Parent-company ownership does not establish a vegan claim for every product.
Key Developments in the Vegan Makeup Market
- In May 2025, e.l.f. Beauty expanded e.l.f. Cosmetics into KRUIDVAT and TREKPLEISTER stores in the Netherlands and Belgium. The company described the brand as offering clean and vegan products. The expansion added more opportunities for in-store trial alongside its digital channels and accessible pricing. [35]
- In August 2024, Estee Lauder Companies launched Smashbox in the U.S. Amazon Premium Beauty store. The announcement described the brand as cruelty free and identified Photo Finish primer as vegan and cruelty-free. The launch made its prestige makeup assortment available to more marketplace shoppers. [6]
- In July 2024, Amorepacific launched HERA Blush in South Korea. It described the product as vegan certified with a 95% natural-origin index. Online platforms and department-store counters carried the launch, placing the certified formula in established premium beauty channels. [15]
Key Players in the Vegan Makeup Market
Brand-level vegan platforms
- e.l.f. Beauty
- Coty
- Unilever
Vegan assortments or individual products
- Estee Lauder Companies
- L'Oreal
- Beiersdorf
- Amorepacific
- Shiseido
Other profiled beauty companies
- Kao Corporation
- Procter & Gamble
Vegan Makeup Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Nature; Format; Price Positioning; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Revenue includes vegan makeup products sold within the stated segmentation universe, including face, eye, lip, cheek, complexion, primer, setting, and kit products where the makeup offer is marketed as vegan or animal-ingredient-free. Revenue excludes adjacent skincare, haircare, fragrance, standalone tools, salon-service revenue, and products marketed only as cruelty-free when vegan formulation is not established. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Country Forecast Profiles | USA; Germany; France; UK; Saudi Arabia; UAE; Japan; South Korea |
| Key Companies Profiled | Kao Corporation; Procter & Gamble; Estee Lauder Companies; e.l.f. Beauty; L'Oreal; Beiersdorf; Coty; Amorepacific; Unilever; Shiseido |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Vegan Makeup Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI's primary research framework examines purchasing criteria and claim documentation with manufacturers, distributors, buyers and subject-matter experts. It also covers channel requirements and product-approval workflows. For vegan makeup, the focus is on product performance and ingredient-origin records alongside market access. |
| Desk Research | Desk research draws on regulatory publications, industry sources and company filings alongside official product information and announcements. Sources are assessed against the market definition, geography and period. Vegan formulation claims are distinguished from cruelty-free testing claims. |
| Market Sizing and Forecasting | Sizing combines baseline market values with the segment structure, pricing indicators and country conditions. Estimates are compared with demand patterns and company information before segment and country forecasts are reconciled. |
| Data Validation | Revenue is checked against the vegan makeup definition. Adjacent skincare and fragrance are excluded, as are standalone tools and salon services. Cruelty-free products qualify only when animal-free formulation is also established. |
Vegan Makeup Market by Segments
Vegan Makeup Market segmented by Product Type:
- Core / classic lines
- Targeted treatment lines
- Sensitive & gentle lines
- Premium & clinical lines
- Kits & sets
Vegan Makeup Market segmented by Nature:
- Conventional
- Vegan & cruelty-free
- Natural & organic
- Dermocosmetic / clinical
- Fragrance-free & sensitive
Vegan Makeup Market segmented by Format:
- Cream & balm
- Liquid & serum
- Stick & solid
- Spray & mist
- Sheet & patch
- Powder
Vegan Makeup Market segmented by Price Positioning:
- Mass
- Masstige
- Premium
- Professional
Vegan Makeup Market segmented by Sales Channel:
- E-commerce & DTC
- Specialty beauty retail
- Pharmacies & drugstores
- Supermarkets & hypermarkets
- Salons & spas
Vegan Makeup Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] The Vegan Society (14 March 2024). The impact of vegan certification on consumer trust and behaviour
- [2] The Vegan Society (4 April 2025). Cruelty-Free vs Vegan: Why the Vegan Trademark is the gold standard in beauty
- [3] FDA (9 September 2026). Registration & Listing of Cosmetic Product Facilities and Products
- [4] European Commission (10 July 2013). Commission Regulation 655/2013
- [5] European Commission (n.d.). Ban on animal testing
- [6] Estée Lauder Companies (8 August 2024). Smashbox Debuts in the U.S. Amazon Premium Beauty Store
- [7] Coty (1 July 2021). Coty Announces the Relaunch of Kylie Cosmetics With New and Improved Clean and Vegan Formulas
- e.l.f. Cosmetics (n.d.). Putty Blush
- e.l.f. Beauty (11 August 2025). e.l.f. Cosmetics Launches Legal-themed e.l.f.ino & schmarnes
- [10] DGCCRF (17 November 2023). Allégations sur les produits cosmétiques : tout n’est pas permis !
- [11] Unilever (23 June 2021). Innovation at Unilever: Deep Dive Webcast
- [12] UAE MoIAT (n.d.). Service Card for Cosmetics Products
- [13] Dubai Municipality (n.d.). Register Consumer Products (Montaji)
- [14] Korean National Law Information Center (2026). Cosmetics Act, Article 15-2
- [15] Amorepacific (8 July 2024). HERA Blush launch
- [16] Saudi Food and Drug Authority (n.d.). List of Notification of Marketing for Cosmetic Products
- [17] L’Oréal (6 February 2025). 2024 Annual Results
- [18] e.l.f. Beauty (n.d.). e.l.f. Cosmetics
- [19] UK Government (29 June 2026). Regulation 1223/2009 and the Cosmetic Products Enforcement Regulations 2013: Great Britain
- [20] DGCCRF (1 October 2025). Allégations sans dans les produits cosmétiques
- [21] MHLW Japan (n.d.). Standards for Cosmetics
- [22] Kao (18 July 2024). KATE unveils first global flagship store
- [23] Shiseido (10 May 2024). Serum First Technology
- [24] German BfR (7 March 2024). Cosmetic products: All ingredients must be tested
- IKW (2026). Economy, Annual Report 2025/2026
- [26] Hourglass (n.d.). The Hourglass Story
- [27] Chantecaille (n.d.). Vegan Makeup
- [28] NARS (n.d.). Light Reflecting Advanced Skincare Foundation
- [29] NYX (n.d.). Buttermelt High-Pigment Blush
- [30] Beiersdorf (2 February 2022). Beiersdorf successfully completes acquisition of Chantecaille
- [31] Procter & Gamble (2026). P&G Focused Portfolio
- [32] Smashbox (n.d.). Vegan & Cruelty-Free Makeup
- Unilever (2023). How robots help design our beauty products
- L’Oréal (n.d.). Consumer Products Division: NYX
- [35] e.l.f. Beauty (15 May 2025). e.l.f. Beauty Expands Presence in The Netherlands and Belgium with Entry into KRUIDVAT and TREKPLEISTER Drugstores
- [36] e.l.f. Beauty (9 October 2024). Discover e.l.f.ecto! e.l.f. Cosmetics Launches in Sephora Mexico
- [37] L'Oréal (28 March 2025). 2024 Annual Report - Consumer Products Division
This Report Answers
- How large is the Vegan Makeup Market in 2026 and what is forecast for 2036?
- Which industry pressures are supporting demand for vegan makeup?
- Why do Core / classic lines hold the leading Product Type position?
- Why does Conventional hold the leading Nature position within the market taxonomy?
- How do profiled country growth rates differ from 2026 to 2036?
- Which profiled companies supply or participate in relevant vegan makeup and adjacent makeup categories?
- What limits adoption or switching toward vegan makeup formulas?
- What should buyers evaluate before purchasing vegan makeup products?
Frequently Asked Questions
How big is the Vegan Makeup Market in 2026, and what is forecast for 2036?
The market is valued at USD 545.0 Million in 2026 and is forecast to reach USD 1,032.7 Million by 2036. Broader availability across mass and prestige retail supports the forecast, alongside digital sales.
What is the CAGR of the Vegan Makeup Market from 2026 to 2036?
The market is forecast to expand at a 6.6% CAGR from 2026 to 2036. Growth depends on suppliers matching mainstream makeup performance while making vegan claims easier to verify.
Which Product Type segment leads the Vegan Makeup Market?
Core / classic lines lead Product Type with a 35.0% share in 2026. Everyday complexion and lip or eye products support trial and regular replacement.
Which Nature segment leads the Vegan Makeup Market?
Conventional leads the Nature axis with a 50.0% share in 2026. This category covers mainstream formulations and merchandising within vegan makeup.
Which profiled countries have the highest growth rates in the Vegan Makeup Market?
The UAE has the highest profiled CAGR at 8.0%, followed by South Korea at 7.7% from 2026 to 2036. These are growth rates; they do not indicate the countries’ absolute market sizes.
Which companies are active in the Vegan Makeup Market?
The report profiles Kao Corporation, Procter & Gamble, Estee Lauder Companies, e.l.f. Beauty, L'Oreal, Beiersdorf, Coty, Amorepacific, Unilever and Shiseido. Participation ranges from brand-wide vegan makeup to individual vegan products and broader beauty operations. Vegan makeup participation is not specified for Kao or Procter & Gamble in the cited company information.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Core / classic lines
- Targeted treatment lines
- Sensitive & gentle lines
- Premium & clinical lines
- Kits & sets
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Vegan & cruelty-free
- Natural & organic
- Dermocosmetic / clinical
- Fragrance-free & sensitive
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Cream & balm
- Liquid & serum
- Stick & solid
- Spray & mist
- Sheet & patch
- Powder
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Price Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Price Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Price Positioning, 2026 to 2036
- Mass
- Masstige
- Premium
- Professional
- Y-o-Y Growth Trend Analysis By Price Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- E-commerce & DTC
- Specialty beauty retail
- Pharmacies & drugstores
- Supermarkets & hypermarkets
- Salons & spas
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By Format
- By Price Positioning
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kao Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Procter & Gamble
- Estee Lauder Companies
- e.l.f. Beauty
- L'Oreal
- Beiersdorf
- Coty
- Amorepacific
- Unilever
- Shiseido
- Kao Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


