
- Market Size (2026)
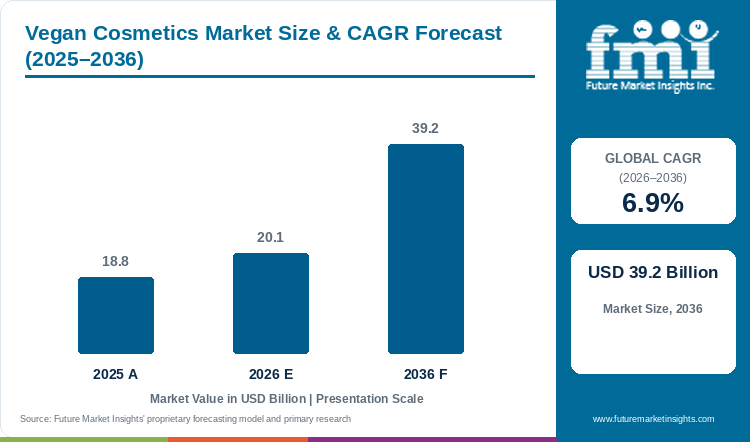
- USD 20.1 Bn
- Forecast (2036)
- USD 39.2 Bn
- CAGR (2026 to 2036)
- 6.9%
How big is the Vegan Cosmetics Market in 2026?
Purchases of beauty products without animal-derived ingredients should carry the Vegan Cosmetics Market to USD 39.2 billion by 2036. FMI estimates the market at USD 20.1 billion in 2026 and forecasts a 6.9% CAGR across 2026 to 2036. The market was valued at USD 18.8 billion in 2025. Plant-based formulations hold 41.0% by ingredient in 2026. Skincare accounts for 36.0% by product, and E-commerce Platforms represent 29.5% by distribution channel in FMI's 2026 assessment.
Certification volumes show how many brands compete for this buyer. The Vegan Society counts more than 70,000 registered products from over 2,500 companies [1]. Some 30,000 of them are cosmetics and toiletries. Regulators are also removing animal tests from safety rules. The European Commission presented a roadmap on 1 June 2026 to phase out animal testing in chemical safety assessments [3]. The UK Government intends to stop regulatory skin and eye irritation tests on animals by the end of 2026 [4].
Ingredient cost is the main restraint. Lush reported cocoa butter prices rose over 400.0% in its 2025 financial year and added GBP 3.1 million to costs [25]. Brands replacing animal inputs with plant butters carry that price risk. e.l.f. Beauty provides a qualified example of scale [20]. Its net sales reached USD 1,636.5 million in its year to March 2026 and rose 25.0%. One company's growth does not prove that every vegan brand is gaining share.
Key Market Trends & Insights
- Brand participation is widening fast. The Vegan Society reports that over 82.0% of its product registrations arrived in the last five years, and more than 50.0% now come from companies outside the UK [1]. Retail buyers can therefore choose from many certified lines in each category, which raises the bar for shelf placement.
- Safety rules are moving away from animal tests. The US Food and Drug Administration states that animal testing is not a requirement for marketing a cosmetic product [8]. China's regulator says priority will be given to reducing or waiving animal testing requirements for perming products, non-oxidative hair dyes and products with new ingredients [5]. Cruelty-free status is becoming easier to hold across markets, so vegan ingredient claims become the point of difference.
- Online channels are growing faster than store-based beauty retail. US nonstore retailers sold USD 124.3 billion in September 2026, up 8.2% on a year earlier. Health and personal care stores fell 1.2% [10]. cosnova grew e-commerce by about 20.0% in 2025, and Lush grew digital sales by 13.0% in its year to June 2025 [27][25].
Regional Highlights
- In Europe, prestige vegan brands are entering mainstream chains across many countries at once. rhode became available at Sephora online and in most of its stores in 19 European countries from 30 September 2026 [22]. The European Commission's June 2026 roadmap covers 15 areas of legislation with 22 actions to speed up non-animal methods [3].
- In East Asia, Korean exports and Chinese retail demand are both rising. Korean cosmetics exports reached USD 11.4 billion in 2025, up 11.8%. Basic skincare made up 74.7% of the total [13]. Chinese retail sales of cosmetics rose 6.1% in January to September 2026, against 1.1% for all retail goods [6].
Vegan Cosmetics Market Size and Forecast
Table 1: Vegan Cosmetics Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 18.8 billion |
| Estimated market size in 2026 | USD 20.1 billion |
| Projected market size by 2036 | USD 39.2 billion |
| CAGR from 2026 to 2036 | 6.9% |
Analyst Perspective
“Shoppers read the ingredient list and the certification mark before they read the brand story, and they expect a vegan product to cost no more than the conventional item next to it. Brands differentiate through third-party certification, stable formulas and distribution in the chains where their buyers already shop. The qualification risk arises in the supply chain. One animal-derived input or one supplier that tests on animals can cost a brand its mark and its shelf space.”
- Rahul Pandita, Principal Consultant, FMI
How is the Vegan Cosmetics Market segmented?
- By product: Skincare, Haircare, Makeup, Fragrances, Bath and Body, and Other Products. Makeup lines overlap with the wider colour cosmetics market that FMI tracks separately.
- By ingredient: Plant-based, Synthetic, Mineral-based, and Other Ingredient Approaches.
- By distribution channel: E-commerce Platforms, Company Websites, Specialty Stores, Supermarkets and Hypermarkets, Department Stores, and Pharmacies.
- By end user: Women, Men, and Unisex.
- By price tier: Mass and Premium.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Plant-based lead by Ingredient in the Vegan Cosmetics Market in 2026?
Plant-based formulations hold 41.0% of the Vegan Cosmetics Market by ingredient in 2026.
Shoppers who avoid animal inputs usually look for botanical replacements first. Plant butters, oils and extracts replace beeswax, lanolin and animal squalene. They also give the pack a visible origin story that a lab-made substitute cannot match. Well People, an e.l.f. Beauty brand, describes its clean and vegan cosmetics as powered by plants since 2008 [41]. Its mineral sunscreen serum combines an antioxidant oil complex and aloe leaf juice with zinc oxide [41]. Lush makes fresh handmade products in six countries and began selling 19 essential oils in October 2026 [25][40].
Botanical sourcing carries the segment's main cost risk. Lush reported that poor West African harvests pushed cocoa butter prices up by over 400.0% and added GBP 3.1 million to its costs in one year [25]. Certification adds a second check on every farm-derived input. The Body Shop checked over 4,000 raw materials to have 100.0% of its formulas certified by The Vegan Society [26]. Brands that document each botanical input can hold the mark through supplier changes.
Synthetic, Mineral-based and Other Ingredient Approaches together hold the remaining 59.0% by ingredient. Synthetic and mineral inputs also pass the exclusion test and give batch consistency at mass price points. cosnova sells its 100.0% vegan essence and Catrice brands in over 90 countries [28]. Buyers who want botanical positioning overlap with the natural cosmetics market.
Table 2: Ingredient, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Plant-based | 41.0% |
| All Other Segments Combined Share | 59.0% |
Source: Future Market Insights analysis of the vegan cosmetics market, 2026.
Why does Skincare lead by Product in the Vegan Cosmetics Market in 2026?
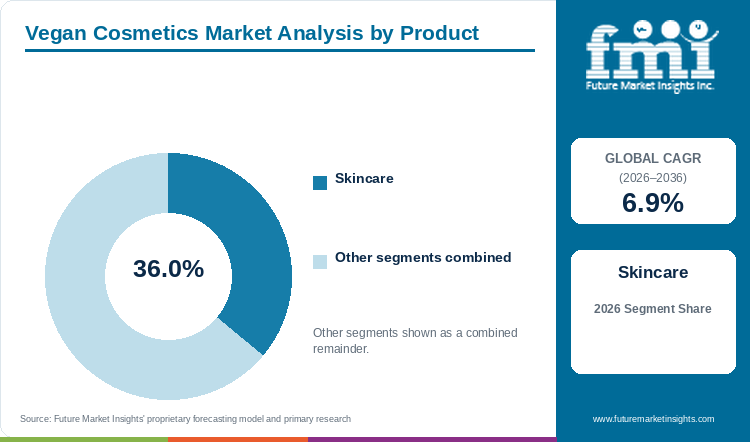
Skincare accounts for 36.0% of the Vegan Cosmetics Market by product in 2026.
Skincare is the category in which ingredient lists are read most closely. Shoppers compare actives and exclusions before they buy a serum or moisturiser. That habit favours brands that print a vegan mark on the pack. The category is also where growth is concentrated. German skin and face care sales rose 11.1% to EUR 4.0 billion in 2025. Among IKW's beauty care categories, only the residual group of other products grew faster, at 14.1% [17].
Export data point the same way. Basic skincare made up 74.7% of South Korea's USD 11.4 billion cosmetics exports in 2025 and 57.5% of its domestic output [13]. Skincare brands also travel well online because the products are light and the claims are easy to compare. Amorepacific reported that its COSRX skincare brand grew revenue by more than 30.0% in Europe, the Middle East and Africa in the third quarter of 2026 [30].
Haircare, Makeup, Fragrances, Bath and Body and Other Products together hold the remaining 64.0% by product. Brands are extending into these categories from a skincare or makeup base. e.l.f. launched six haircare products in June 2026 and added fragrance and body care under e.l.f. POP in October 2026 [38][39]. Lush began selling 19 essential oils online and in its Spa stores and Perfume Libraries from 8 October 2026, with a core range of eight in all UK shops [40].
Table 3: Product, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Skincare | 36.0% |
| All Other Segments Combined Share | 64.0% |
Source: Future Market Insights analysis of the vegan cosmetics market, 2026.
Why do E-commerce Platforms lead by Distribution Channel in the Vegan Cosmetics Market in 2026?
E-commerce Platforms account for 29.5% by distribution channel in FMI's 2026 assessment of the Vegan Cosmetics Market.
Marketplaces let a shopper filter for vegan products and read full ingredient lists before paying. Filtering by claim is harder on a crowded store shelf. Large groups now sell a high share online. L'Oréal reported that e-commerce accounted for above 30.0% of its EUR 44.1 billion sales in 2025 [24]. e.l.f. Beauty earned 24.0% of net sales through e-commerce in its 2026 fiscal year, and Amazon alone accounted for 11.0% [19].
National statistics show the same shift. Online sales made up 28.8% of retail sales in Great Britain in September 2026 [12]. US e-commerce reached 17.1% of total retail sales in the second quarter of 2026, up 12.2% on a year earlier [9]. South Korean online shopping reached KRW 25.0 trillion in September 2026 [14]. Amorepacific said revenue through TikTok Shop UK rose by more than 200.0% in the third quarter of 2026 [30].
Company Websites, Specialty Stores, Supermarkets and Hypermarkets, Department Stores and Pharmacies together hold the remaining 70.5%. Specialty chains remain the route into premium buyers. rhode reached Sephora stores across 19 European countries in September 2026, and e.l.f. Cosmetics entered Brazil through Sephora in the same month [22][23]. Store shelves still decide trial for first-time buyers.
Table 4: Distribution Channel, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| E-commerce Platforms | 29.5% |
| All Other Segments Combined Share | 70.5% |
Source: Future Market Insights analysis of the vegan cosmetics market, 2026.
What are the key drivers restraints and opportunities?
Vegan cosmetics sell when a shopper can verify the claim at the shelf or on the screen. The same verification creates cost and supply work for every brand that wants the mark.
Driver
Demand for products without animal-derived ingredients is pulling large and small brands into the category. The Vegan Society holds 30,000 cosmetics and toiletries registrations among more than 70,000 certified products [1]. e.l.f. Beauty states that all of its brands are vegan [19]. Its net sales rose 36.0% to USD 479.4 million between April and June 2026 [21]. cosnova describes its essence and Catrice brands as 100.0% vegan and sells in over 90 countries on EUR 991.0 million of 2025 turnover [28][27]. Each new entrant adds shelf space and advertising weight behind the claim.
Restraint
Ingredient sourcing, certification and price limit how fast brands can convert their ranges. Lush absorbed a GBP 3.1 million rise in cocoa butter costs in one year [25]. The Leaping Bunny programme requires companies to recommit every year and to remain open to independent audits [35]. Every raw material has to be checked. For The Body Shop, that check covered more than 4,000 inputs [26]. e.l.f. reports that most of its China-made products have carried a 25.0% US tariff since May 2019 [19]. These costs arise before a product earns a single extra sale.
Opportunity
Mainstream retail entry and clear ingredient verification can lift revenue per brand. rhode moved from three markets into Sephora across 19 more European countries on 30 September 2026 [22]. Regulators are making ingredient data easier to verify. MoCRA requires each marketed cosmetic and its ingredients to be listed with the FDA and updated yearly [8]. China planned electronic labelling pilots from February 2026 [5]. Brands with cruelty-free credentials can also sell into the cruelty-free cosmetics market that FMI covers separately.
How do animal testing rules and cosmetics regulations affect vegan cosmetics purchasing?
Animal testing bans set the entry conditions for the category. The EU has prohibited animal testing of finished cosmetics since 11 September 2004 and of ingredients since 11 March 2009, with a full marketing ban from 11 March 2013 [2]. These bans were set by the cosmetics directive, and Regulation (EC) 1223/2009 has carried the same provisions since 11 July 2013 [2]. The European Commission added a roadmap on 1 June 2026 with three pillars and 22 actions to phase out animal testing in chemical safety assessments [3]. The UK plans to stop regulatory testing on animals for skin and eye irritation and skin sensitisation by the end of 2026 [4].
Other markets are catching up. India notified a ban on animal testing of cosmetics in May 2014 and requires every imported cosmetic to be registered under Rule 12(1) of the Cosmetics Rules, 2020 [7]. China's regulator counted 2.29 million filed ordinary cosmetics at the end of October 2025 and plans to give priority to waiving animal tests for several product groups [5]. In the US, MoCRA requires facility registration every two years and serious adverse event reports within 15 business days [8]. Buyers can therefore expect vegan products to clear safety rules in several markets without animal data.
What limits reliable vegan ingredient supply and product quality?
Raw material supply sets the first limit. Lush reported that poor West African harvests pushed cocoa butter prices up by over 400.0% during its 2025 financial year [25]. Plant butters, waxes and oils that replace animal inputs come from farm cycles. A vegan formula can therefore lose its margin in one season. Synthetic substitutes avoid that swing but need documented sources to pass certification.
Quality also depends on the supplier chain behind each ingredient. The Leaping Bunny standard asks companies to remove animal testing at every stage of product development and to recommit each year [35]. A single uncertified supplier can break the claim for a finished product. Most e.l.f. products are made in China, so one country's trade rules shape the landed cost of a large share of mass vegan supply [19]. Brands that hold tested, documented formulas can switch suppliers without losing their mark.
Where can vegan cosmetics suppliers win additional business?
Suppliers win by following their buyers into new channels and categories. e.l.f. Beauty raised its net sales outlook for the year to March 2027 to USD 1,938.0 million to USD 1,968.0 million after a 36.0% first-quarter rise [21]. Amorepacific's AESTURA entered Boots in the UK and Matas in the Nordic region during the September 2026 quarter [30]. Nykaa served over 60 million customers online and ran 324 beauty stores across 105 cities in India at 30 June 2026 [33]. Category extensions add a second purchase from the same shopper, which links makeup brands with the organic cosmetics market. Each channel needs its own ingredient disclosure so that the vegan claim survives the move.
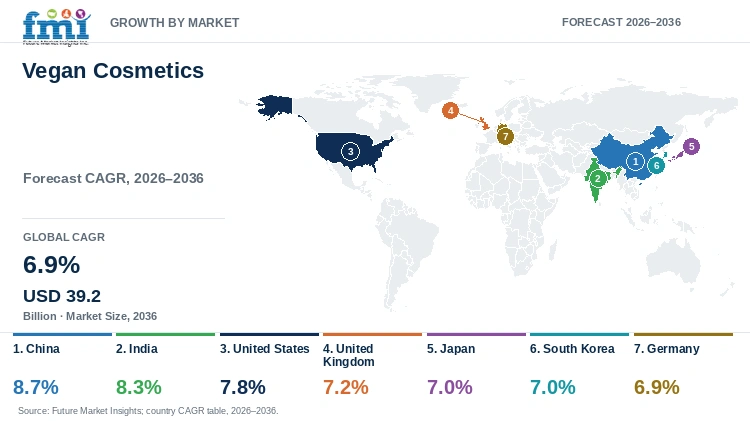
Vegan Cosmetics Market by Country (2026 to 2036)
Table 5: Vegan Cosmetics Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
| China | 8.7% |
| India | 8.3% |
| United States | 7.8% |
| United Kingdom | 7.2% |
| Japan | 7.0% |
| South Korea | 7.0% |
| Germany | 6.9% |
Source: Future Market Insights analysis of the vegan cosmetics market, 2026.
China
Cosmetics are outgrowing most other goods in Chinese shops. The National Bureau of Statistics recorded cosmetics retail sales of CNY 349.1 billion in January to September 2026, up 6.1% [6]. Total retail sales of consumer goods rose only 1.1% over the same period. Online retail sales of goods reached CNY 9,506.0 billion and grew 3.8% [6]. Shoppers are spending on skincare and makeup while they hold back on larger purchases.
Regulation is opening the door to imported vegan lines. The National Medical Products Administration counted over 20,000 registrants and filing entities and 2.29 million filed ordinary cosmetics at the end of October 2025 [5]. Its reform plan will shorten review periods for registration changes to 60 working days for high-risk changes and 45 for low-risk ones. It also plans to give priority to reducing or waiving animal testing requirements and to exempt eligible new overseas products from submitting overseas marketing authorisation documents [5]. Brands that refuse animal tests can expect fewer test demands when they plan a China entry.
Imported supply still competes with local brands on price. Korean cosmetics exports to China were USD 2.0 billion in 2025, below the USD 2.5 billion shipped in 2024 [13][36]. That decline shows that imported skincare is not guaranteed a rising share. Sustained cosmetics demand and a lower compliance burden place China at the top of the profiled group at an 8.7% CAGR over 2026 to 2036. Growth will favour brands that file products early and price against domestic skincare lines. Amorepacific expanded AESTURA's distribution network in China during July to September 2026 as one response [30].
India
Specialist retail is building the distribution that vegan brands need in India. Nykaa reported consolidated gross merchandise value of INR 55.9 billion for April to June 2026, up 34.0% [33]. Its beauty vertical alone produced INR 41.1 billion of that total. The company ran 324 beauty stores across 105 cities and served more than 60 million customers through its online platforms [33]. Its Superstore reached more than 1,200 cities. That network carries branded cosmetics far beyond the metro markets.
The rules favour imported vegan lines. The Central Drugs Standard Control Organisation lists a 2014 notification banning animal testing of cosmetics and requires registration of every imported cosmetic under Rule 12(1) of the Cosmetics Rules, 2020 [7]. Rule 36 bars claims that mislead the user, so a vegan label must be supported by the formula [7]. International brands are responding. Lush opened a shop in New Delhi and plans sites in Mumbai and Bengaluru [25]. cosnova listed India among its 2025 market entries, and Amorepacific grew its India revenue by more than 60.0% in the three months to September 2026 [27][30].
Rapid retail expansion and a rising base of first-time branded buyers support an 8.3% CAGR for India across 2026 to 2036. The main constraint is price. Imported products carry registration costs that domestic brands avoid. Nykaa's own House of Nykaa brands grew net sales value by 36.0% in the June 2026 quarter, which shows that local labels can compete for the same shelf [33]. Vegan positioning will need local manufacturing to reach mass price points in Indian cities.
United States
Mass retail is the engine of vegan cosmetics sales in the United States. e.l.f. Beauty earned 79.0% of its net sales in the US in the year to March 2026 [19]. Target accounted for 18.0% of net sales and Walmart for 13.0%. Amazon represented 11.0% and Sephora 10.0% [19]. Every e.l.f. brand is vegan and double-certified as cruelty-free by Leaping Bunny and PETA [19]. Net sales rose 36.0% to USD 479.4 million in the quarter to June 2026, and the company raised its full-year outlook to 18.0% to 20.0% growth [21].
Regulation and trade policy set the cost base. MoCRA requires facility registration and product listing with ingredients, and the FDA states that animal testing is not a requirement for marketing a cosmetic [8]. Most e.l.f. products are made in China and have carried a 25.0% US tariff since May 2019 [19]. On 20 February 2026 the Supreme Court held that IEEPA, the International Emergency Economic Powers Act, gives the President no power to impose tariffs [11]. e.l.f. then booked tariff refunds that lifted its gross margin to 83.0% in the June 2026 quarter [21].
Online demand keeps shifting the channel mix. Nonstore retailers sold USD 124.3 billion in September 2026, up 8.2% [10]. Health and personal care stores fell 1.2% to USD 39.5 billion. Mass distribution and steady online growth support a 7.8% CAGR for the US market during 2026 to 2036. Further tariff changes can move landed costs within a single season, so brands that make goods in more than one country will protect their prices. Waldencast completed the sale of Obagi Medical in July 2026 to concentrate on Milk Makeup [32]. That vegan colour cosmetics brand sells through Sephora, Ulta Beauty and Amazon.
United Kingdom
The United Kingdom is home to two owned-store vegan beauty chains and the body that certifies many of their rivals. Lush operated 869 permanent shops worldwide at 30 June 2025 and reported group turnover of GBP 736.2 million, up 9.4% [25]. Its profit before tax was GBP 0.2 million, after a loss of GBP 36.7 million a year earlier. The Body Shop has 100.0% of its product formulas certified by The Vegan Society [26]. The Vegan Trademark itself is run from the UK, although over 50.0% of registered products now come from companies based elsewhere [1].
Online sales already account for a high share of British retail. The Office for National Statistics reported online sales at 28.8% of retail sales in September 2026 [12]. Sales volumes stood 0.8% above their level twelve months before. Korean skincare brands are using that channel. Amorepacific reported that revenue through TikTok Shop UK rose by more than 200.0% in the three months to September 2026 [30]. Its AESTURA brand also entered Boots.
The policy direction supports the category. On 11 November 2025 the UK Government published a strategy backed by GBP 75.0 million [4]. It commits to ending animal-based regulatory tests for skin and eye irritation and sensitisation by the end of 2026. Established chains, a strong online channel and clear rules support a 7.2% CAGR for the United Kingdom through 2026 to 2036. Weak store traffic remains the risk. Lush grew retail store sales by 7.0% but digital by 13.0% over the twelve months to June 2025 [25]. Shop estates must therefore carry more online fulfilment to stay profitable.
Japan
Imports are supplying a growing share of the cosmetics sold in Japan. METI reported that cosmetics imports reached about JPY 400.0 billion in 2023 [15]. The largest increases came from South Korea, France and China. Domestic shipments were about JPY 1.3 trillion in 2023 and remained below pre-pandemic levels. South Korea shipped USD 1.1 billion of cosmetics to Japan in 2025, its third-largest market [13]. METI notes that South Korea's cosmetics export growth since 2010 has been nearly double Japan's [15].
Korean groups confirm the pull. Amorepacific said that AESTURA and COSRX each grew by more than 100.0% in Japan in the July to September 2026 period [30]. HERA grew by more than 90.0%. Domestic majors are slower. Shiseido reported first-half 2026 sales of JPY 499.0 billion, up 6.0% [34]. Its Japan sales were broadly in line with the previous year. Inbound purchases by tourists were still falling in the mid-teens, although the rate of decline narrowed [34].
Visitor numbers add a second drag. The Japan National Tourism Organization counted 27.6 million arrivals in January to August 2026, down 2.7% [16]. August alone was down 9.6%. METI notes that the growth once driven by inbound tourist demand disappeared after the pandemic [15]. Import-led growth against a flat domestic base gives Japan a 7.0% CAGR for 2026 to 2036. METI counts roughly 3,000 companies in the sector [15]. The top 10 firms hold about 50.0% of the prestige market. Small Japanese brands with vegan formulas can therefore find room in a market where the leaders are few and large.
South Korea
South Korea earns more from cosmetics abroad than any country except France. The Ministry of Food and Drug Safety reported exports of USD 11.4 billion in 2025, up 11.8% [13]. The trade surplus reached USD 10.1 billion. The United States was the top destination at USD 2.2 billion, followed by China at USD 2.0 billion and Japan at USD 1.1 billion. Export destinations rose by 30 to 202 countries. Domestic production reached a record KRW 17.9 trillion, up 2.3% [13]. Basic skincare made up 57.5% of output.
The home market is growing through online channels and derma brands. Korean online shopping transactions reached KRW 25.0 trillion in September 2026, up 4.1% [14]. Mobile shopping accounted for KRW 19.1 trillion. Amorepacific lifted domestic sales by 11.0% to KRW 620.5 billion in the September 2026 quarter [30]. Its domestic operating profit rose 42.0%. The company grew group revenue 8.9% to KRW 1.2 trillion in the quarter.
Korean shoppers already buy skincare in high volumes, so the home market grows more slowly than exports. Export strength and a mature home base therefore combine in a 7.0% CAGR for South Korea between 2026 and 2036. Vegan claims compete within a crowded skincare shelf. Cosmetics Day is now a statutory anniversary, and the ministry held its second ceremony on 7 September 2026 with a new government commendation for the sector [37]. Brands that export vegan skincare to Europe and the US will carry the higher growth, while the home market rewards reformulated derma lines.
Germany
Germany is the home base of a vegan colour cosmetics group that sells in over 90 countries. cosnova lifted turnover to EUR 991.0 million in 2025, up 4.0% [27]. Its e-commerce sales grew by about 20.0%. The company describes its brands as 100.0% vegan and cruelty-free according to EU law [28]. In January 2026 it acquired Niche Beauty Lab, a Spanish skincare specialist [29]. The group sells the Transparent Lab, Theramid and Acnemy brands. That deal gives a makeup-led group a direct route into skincare.
The domestic market grew faster in 2025 than the wider economy. IKW estimated beauty care sales at EUR 18.0 billion in 2025, up 6.3% [17]. Skin and face care rose 11.1% to EUR 4.0 billion, while decorative cosmetics rose 1.5% to EUR 2.2 billion. Vegan brands that depend on makeup therefore face a slower category than those with skincare ranges.
Consumer spending has weakened in 2026. Destatis reported a 2.3% real drop in retail turnover in September 2026 against the same month of 2025 [18]. Internet and mail-order retail rose 4.4% in real terms. Shoppers are buying beauty online and cutting other purchases. A mature market and soft store demand leave Germany with the lowest forecast of the seven countries at a 6.9% CAGR through 2026 to 2036. The EU roadmap presented on 1 June 2026 is meant to speed up non-animal methods for ingredient safety assessments [3]. German brands with export reach can grow faster than the home market by selling vegan makeup through the same marketplaces that serve their domestic buyers.
Who are the notable companies in the Vegan Cosmetics Market?
e.l.f. Beauty, Lush, cosnova and The Body Shop show the main commercial positions in vegan cosmetics. e.l.f. Beauty sells mass-priced vegan makeup and skincare through large retailers and Amazon, with 24.0% of net sales from e-commerce in fiscal 2026 [19]. Its brands include e.l.f. Cosmetics, e.l.f. SKIN, rhode, Naturium and Well People [19]. Lush makes fresh handmade products in six countries and sells through 869 shops in 50 countries [25]. The Body Shop (now owned by Auréa Group following its acquisition in September 2024): 100% of product formulas are certified by The Vegan Society. The brand exited the United States in March 2024 and operates a significantly reduced store network following restructuring across multiple markets[26]. cosnova runs the essence and Catrice mass brands from Germany and describes them as 100.0% vegan [28].
Prestige vegan brands are owned by larger groups or operate as standalone listed companies. Milk Makeup is now the sole brand of Waldencast after the sale of Obagi Medical to Bridgepoint for up to USD 460.0 million in July 2026 [32]. Unilever named Hourglass among the leaders of its prestige skincare growth for July to September 2026 [31]. Amorepacific owns a portfolio that includes COSRX and AESTURA. Both grew strongly in the US, Europe and Japan in the same quarter [30].
Retailers also shape the category. Nykaa runs 324 beauty stores and an online platform with more than 60 million customers in India [33]. Sephora carries rhode in 19 European countries and e.l.f. Cosmetics in Brazil [22][23]. Buyers should compare certification, price tier and channel reach when they assess each supplier. Pacifica, Biossance, Tarte, KVD Beauty and Cover FX are also tracked in this market. Their results are not publicly disclosed in the same detail.
Key Developments in the Vegan Cosmetics Market
- On 29 January 2026, cosnova announced that Spanish skincare specialist Niche Beauty Lab had joined the group with effect from 14 January 2026 [29].
- On 30 July 2026, Waldencast completed the sale of Obagi Medical to Bridgepoint for up to USD 460.0 million. Milk Makeup is now its remaining brand [32].
- On 30 September 2026, e.l.f. Beauty's rhode brand went on sale at Sephora online and in most of its stores across 19 European countries [22]. The brand already sold in Canada, the UK and the US.
Key Players in the Vegan Cosmetics Market
- e.l.f. Beauty, Inc.
- Lush Cosmetics Limited
- The Body Shop
- cosnova GmbH (essence, Catrice)
- Waldencast plc (Milk Makeup)
- Amorepacific Corporation
- L'Oréal S.A.
- Unilever PLC (Hourglass)
- Pacifica Beauty
- Biossance
- Tarte Cosmetics
- KVD Beauty
- Cover FX
Vegan Cosmetics Market Report Scope
Table 6: Vegan Cosmetics Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Finished beauty and personal care products formulated without animal-derived ingredients. Cruelty-free products that contain animal-derived ingredients are excluded. |
| Product | Skincare; Haircare; Makeup; Fragrances; Bath and Body; Other Products |
| Ingredient | Plant-based; Synthetic; Mineral-based; Other Ingredient Approaches |
| Distribution Channel | E-commerce Platforms; Company Websites; Specialty Stores; Supermarkets and Hypermarkets; Department Stores; Pharmacies |
| End User | Women; Men; Unisex |
| Price Tier | Mass; Premium |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | China, India, United States, United Kingdom, Japan, South Korea, Germany |
| Companies covered | e.l.f. Beauty, Inc.; Lush Cosmetics Limited; The Body Shop; cosnova GmbH; Waldencast plc (Milk Makeup); Amorepacific Corporation; L'Oréal S.A.; Unilever PLC (Hourglass); Pacifica Beauty; Biossance; Tarte Cosmetics; KVD Beauty; Cover FX |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the vegan cosmetics market, 2026.
Vegan Cosmetics Market Research Methodology
The vegan cosmetics assessment draws on certification body statistics, regulator publications, national retail and trade statistics and company disclosures [1][5][6][13]. FMI measures annual retail sales value of finished vegan skincare, haircare, makeup, fragrance and bath and body products. Segment values are classified by product, ingredient and distribution channel. Country forecasts reflect local retail demand, regulatory conditions, import flows and channel structure over the same 2026 to 2036 period. Certification counts, export values and company revenues are reviewed as separate measures.
Vegan Cosmetics Market by Segments
Vegan Cosmetics Market segmented by Product:
- Skincare
- Haircare
- Makeup
- Fragrances
- Bath and Body
- Other Products
Vegan Cosmetics Market segmented by Ingredient:
- Plant-based
- Synthetic
- Mineral-based
- Other Ingredient Approaches
Vegan Cosmetics Market segmented by Distribution Channel:
- E-commerce Platforms
- Company Websites
- Specialty Stores
- Supermarkets and Hypermarkets
- Department Stores
- Pharmacies
Vegan Cosmetics Market segmented by End User:
- Women
- Men
- Unisex
Vegan Cosmetics Market segmented by Price Tier:
- Mass
- Premium
Vegan Cosmetics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] The Vegan Society. (2026). Vegan Trademark statistics, accessed 3 November 2026.
- [2] European Commission. (2026). Ban on animal testing: Cosmetics, accessed 3 November 2026. https://single-market-economy.ec.europa.eu/sectors/cosmetics/ban-animal-testing_en
- [3] European Commission, Representation in Luxembourg. (2026, June 1). Commission accelerates transition away from animal testing in chemical safety assessments. https://luxembourg.representation.ec.europa.eu/actualites-et-evenements/actualites/commission-accelerates-transition-away-animal-testing-chemical-safety-assessments-2026-06-01_fr
- [4] UK Government, Department for Science, Innovation and Technology. (2025, November 11). Animal testing to be phased out faster as UK unveils roadmap for alternative methods. https://www.gov.uk/government/news/animal-testing-to-be-phased-out-faster-as-uk-unveils-roadmap-for-alternative-methods
- [5] National Medical Products Administration, China. (2025, December 22). Policy Interpretation of the NMPA's Opinions on Deepening the Reform of Cosmetics Regulation and Promoting High-Quality Industry Development. https://english.nmpa.gov.cn/2025-12/22/c_1156416.htm
- [6] National Bureau of Statistics of China. (2026, October 20). Total Retail Sales of Consumer Goods from January to September 2026. https://www.stats.gov.cn/english/PressRelease/202610/t20261020_1965662.html
- [7] Central Drugs Standard Control Organisation, Government of India. (2026). Cosmetics: Regulatory framework and notifications, accessed 3 November 2026. https://cdsco.gov.in/opencms/opencms/en/Cosmetics/cosmetics/
- [8] U.S. Food and Drug Administration. (2026, October 29). Modernization of Cosmetics Regulation Act of 2022 (MoCRA). https://www.fda.gov/cosmetics/cosmetics-laws-regulations/modernization-cosmetics-regulation-act-2022-mocra
- [9] U.S. Census Bureau. (2026, August 18). Quarterly Retail E-Commerce Sales, 2nd Quarter 2026 (CB26-133).
- [10] U.S. Census Bureau. (2026, October 15). Advance Monthly Sales for Retail and Food Services, September 2026 (CB26-165). https://www.census.gov/retail/marts/www/marts_current.pdf
- [11] Supreme Court of the United States. (2026, February 20). Learning Resources, Inc. v. Trump, No. 24-1287. https://www.supremecourt.gov/opinions/25pdf/24-1287_4gcj.pdf
- [12] Office for National Statistics. (2026, October 23). Retail sales, Great Britain: September 2026.
- [13] Korea.net, Ministry of Culture, Sports and Tourism. (2026, May 26). Cosmetics surplus breaks USD 10B, exports ranked 2nd worldwide (Ministry of Food and Drug Safety analysis). https://www.korea.net/NewsFocus/Business/view?articleId=292940
- [14] Ministry of Data and Statistics, Republic of Korea. (2026, November 2). Online Shopping in September 2026. https://mods.go.kr/board.es?act=view&bid=11722&list_no=447782&mainXml=Y&mid=a20101000000
- [15] Ministry of Economy, Trade and Industry, Japan. (2025, December 8). The cosmetics manufacturing industry: current situation (化粧品製造業をめぐる状況). https://www.meti.go.jp/shingikai/mono_info_service/cosmetic_industry/pdf/001_04_00.pdf
- [16] Japan National Tourism Organization. (2026, September 16). Visitor arrivals to Japan, August 2026. https://www.jnto.go.jp/statistics/data/_files/20260916_1615-4.pdf
- [17] Industrieverband Körperpflege- und Waschmittel (IKW). (2025, December 3). Marktzahlen 2025: Schönheits- und Haushaltspflege in Deutschland.
- [18] Statistisches Bundesamt (Destatis). (2026, November 2). Press release No. 383: Retail turnover, September 2026. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/11/PD26_383_45212.html
- [19] e.l.f. Beauty, Inc. (2026). Form 10-K for the fiscal year ended March 31, 2026. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001600033/000160003326000020/elf-20260331.htm
- [20] e.l.f. Beauty, Inc. (2026, May 20). e.l.f. Beauty Announces Fourth Quarter Fiscal 2026 Results. https://www.elfbeauty.com/articles/e-l-f-beauty-announces-fourth-quarter-fiscal-2026-results
- [21] e.l.f. Beauty, Inc. (2026, August 5). Form 8-K, Exhibit 99.1: First Quarter Fiscal 2027 Results. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001600033/000160003326000036/q12027er-991.htm
- [22] e.l.f. Beauty, Inc. (2026, August 31). rhode Announces Official Launch Date for Its Retail Expansion in Europe with Sephora. https://investor.elfbeauty.com/stock-and-financial/press-releases/landing-news/2026/08-31-2026-140024924
- [23] e.l.f. Beauty, Inc. (2026, September 15). Olá! e.l.f. Cosmetics Launches in Brazil Exclusively with Sephora. https://investor.elfbeauty.com/stock-and-financial/press-releases/landing-news/2026/09-15-2026-133028040
- [24] L'Oréal. (2026, April 15). Annual Report 2025: Financial performance. https://www.loreal-finance.com/en/annual-report-2025/financial-performance/
- [25] Lush Cosmetics Limited. (2026, March 25). Lush Audited Accounts: Year ending June 2025. https://weare.lush.com/lush-life/lush-audited-accounts-year-ending-june-2025/
- [26] The Body Shop International Limited. (2026). Vegan beauty: 100% of our product formulas certified by The Vegan Society, accessed 3 November 2026. https://global.thebodyshop.com/en-hk/about-us/brand-values/vegetarian-and-vegan/a/a00014
- [27] cosnova GmbH. (2026, February 5). Annual Results 2025: cosnova continues to grow. https://www.cosnova.com/en/news/annual-results-2025
- [28] cosnova GmbH. (2026). Company overview and brands, accessed 3 November 2026. https://www.cosnova.com/en/
- [29] cosnova GmbH. (2026, January 29). Next growth step for cosnova: Niche Beauty Lab joins the cosnova group. https://www.cosnova.com/en/news/niche-beauty-lab-joins-the-cosnova-group
- [30] Amorepacific Group. (2026, October 29). Amorepacific Group Announces Q3 2026 Business Performance. https://www.apgroup.com/int/en/news/2026-10-29-1.html
- [31] Unilever PLC. (2026, October 28). Continued strong performance in the third quarter: Q3 2026 Trading Statement. https://www.unilever.com/news/press-and-media/press-releases/2026/continued-strong-performance-in-the-third-quarter/
- [32] Waldencast plc. (2026, July 30). Waldencast Announces Completion of the Sale of Obagi Medical to Bridgepoint. https://ir.waldencast.com/node/9021/pdf
- [33] FSN E-Commerce Ventures Limited (Nykaa). (2026, August 4). Press release: Financial results for the quarter ended June 30, 2026. https://www.nykaa.com/media/wysiwyg/uiTools/2026-8/NykaaPressRelease.pdf
- [34] Shiseido Company, Limited. (2026, August 5). 2026 Q2 Financial Results Briefing. https://corp.shiseido.com/en/ir/pdf/ir20260805_300.pdf
- [35] Leaping Bunny Program. (2026). The Leaping Bunny Program: Corporate Standard of Compassion for Animals, accessed 3 November 2026. https://www.leapingbunny.org/
- [36] Korea.net, Ministry of Culture, Sports and Tourism. (2025, May 28). Cosmetics exports in 2024 rank 3rd worldwide with USD 10.2B. https://www.korea.net/NewsFocus/Business/view?articleId=272319
- [37] Ministry of Food and Drug Safety, Republic of Korea. (2026, September 9). The Confidence of K-Beauty, In Full Bloom: 2026 Cosmetics Day Ceremony. https://www.mfds.go.kr/eng/brd/m_61/view.do?seq=192
- [38] e.l.f. Beauty, Inc. (2026, June 15). Look Who's e.l.f.ing Hair: e.l.f. Enters the Haircare Chat in New Category Extension. https://investor.elfbeauty.com/stock-and-financial/press-releases/landing-news/2026/06-15-2026-210025445
- [39] e.l.f. Beauty, Inc. (2026, October 5). e.l.f. Expands Into Fragrance and Body Care Categories with Launch of e.l.f. POP. https://investor.elfbeauty.com/stock-and-financial/press-releases/landing-news/2026/10-05-2026-050119864
- [40] Lush Cosmetics Limited. (2026, October 7). Discover Lush's first-ever essential oils collection. https://weare.lush.com/press-releases/discover-lushs-first-ever-essential-oils-collection/
- [41] e.l.f. Beauty, Inc. (2026, April 15). Well People Celebrates Being Plant-Powered, Partnering with Arbor Day Foundation. https://investor.elfbeauty.com/stock-and-financial/press-releases/landing-news/2026/04-15-2026-140130495
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Skincare
- Haircare
- Makeup
- Fragrances
- Bath and Body
- Other Products
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Ingredient, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient, 2026 to 2036
- Plant-based
- Synthetic
- Mineral-based
- Other Ingredient Approaches
- Y-o-Y Growth Trend Analysis By Ingredient, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- E-commerce Platforms
- Company Websites
- Specialty Stores
- Supermarkets and Hypermarkets
- Department Stores
- Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Women
- Men
- Unisex
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier, 2026 to 2036
- Mass
- Premium
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Ingredient
- By Distribution Channel
- By End User
- By Price Tier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- e.l.f. Beauty, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Lush Cosmetics Limited
- cosnova GmbH
- Waldencast plc
- Amorepacific Corporation
- The Body Shop
- cosnova GmbH (essence, Catrice)
- Waldencast plc (Milk Makeup)
- L'Oréal S.A.
- Unilever PLC (Hourglass)
- Pacifica Beauty
- Biossance
- Tarte Cosmetics
- KVD Beauty
- Cover FX
- e.l.f. Beauty, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Ingredient, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Ingredient
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End User
- Figure 15: Global Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Price Tier
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product
- Figure 32: North America Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Ingredient
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End User
- Figure 41: North America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Price Tier
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product
- Figure 48: Latin America Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Ingredient
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End User
- Figure 57: Latin America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Price Tier
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product
- Figure 64: Western Europe Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Ingredient
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End User
- Figure 73: Western Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Price Tier
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Ingredient
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End User
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Price Tier
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product
- Figure 96: East Asia Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Ingredient
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End User
- Figure 105: East Asia Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Price Tier
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Ingredient
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Price Tier
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Ingredient, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Ingredient, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Ingredient
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Price Tier
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Vegan Cosmetics Market in 2026?
FMI estimates the market at USD 20.1 billion in 2026, up from USD 18.8 billion in 2025. It is forecast to reach USD 39.2 billion by 2036 at a 6.9% CAGR.
Which ingredient type leads the Vegan Cosmetics Market in 2026?
Plant-based formulations lead by ingredient with 41.0% in 2026. Synthetic, mineral-based and other ingredient approaches together hold 59.0%.
Which product and distribution channel lead in 2026?
Skincare holds 36.0% by product. E-commerce Platforms hold 29.5% by distribution channel in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
China has the highest forecast CAGR at 8.7% during 2026 to 2036, followed by India at 8.3%. Japan and South Korea tie at 7.0%. These are FMI forecasts and are not rates reported by the cited public bodies.
How do animal testing rules affect vegan cosmetics?
Bans on animal testing remove one barrier to entry but do not define a vegan product. The EU marketing ban on animal-tested cosmetics has applied in full since 11 March 2013 [2]. The FDA states that animal testing is not a requirement for marketing a cosmetic product in the US [8].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
