

- Market Size (2026)
- USD 650.0 Mn
- Forecast (2036)
- USD 2993.5 Mn
- CAGR (2026 to 2036)
- 16.5%
How big is Vegan Egg Market in 2026?
The vegan egg market is forecast to register a CAGR of 16.5% through 2036. Market valuation rises from USD 557.9 million in 2025 to USD 650.0 million in 2026 before reaching USD 2,993.5 million by 2036.
Recurring outbreaks of highly pathogenic avian influenza across commercial laying-hen flocks have exposed institutional cafeterias, industrial bakeries, and retail grocers to sudden shell-egg shortages and sharp wholesale price spikes. Formulated vegan eggs address that supply vulnerability by combining extracted legume globulins or precision-fermented albumins with plant lipids, gellan gum, and natural carotenoids to replicate thermal coagulation, cake batter aeration, and mayonnaise emulsification without poultry inputs. According to Future Market Insights, global vegan egg valuation advances from USD 557.9 million in 2025 to USD 650.0 million in 2026 and is projected to reach USD 2,993.5 million by 2036, expanding at a 16.5% CAGR and generating USD 2,343.5 million in incremental revenue. Pourable liquid egg replacers capture 49.0% of product format sales in 2026 because chilled 12-ounce retail bottles and foodservice bag-in-box bladders substitute 1:1 on breakfast griddles. In February 2025, the U.S. Department of Agriculture committed up to USD 1.0 billion to combat avian influenza and stabilize domestic egg supply, reinforcing foodservice diversification into contract-priced botanical egg liquids [1].
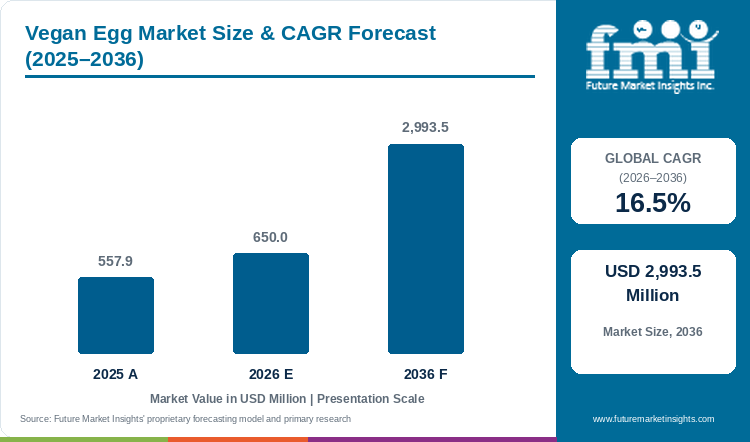
Key Market Trends & Insights
- By product format: Pourable liquid egg replacers led with 49.0% share in 2026, supported by high-speed aseptic bottling and direct griddle compatibility across quick-service breakfast chains and retail dairy cases.
- By protein source: Mung bean & lupin globulin isolates accounted for 55.4% share in 2026, as extracted 8S vicilin proteins form cohesive, springy thermal gels without off-flavor sulfur notes.
- By end-use channel: Retail grocery & supermarket channels held 40.0% share in 2026, propelled by flexitarian households purchasing zero-cholesterol liquid bottles and pre-cooked breakfast bites alongside conventional shell eggs.
Regional Highlights
- Fastest-growing evaluated country: Australia, at 20.1% CAGR from 2026 to 2036.
- By country: Sweden at 18.3%, France at 16.9%, the United States at 15.9%, and the United Kingdom at 14.3% follow, while Germany records a 13.4% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vegan Egg Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 557.9 million |
| Estimated Market Size in 2026 | USD 650.0 million |
| Projected Market Size by 2036 | USD 2,993.5 million |
| CAGR, 2026 to 2036 | 16.5% |
| Added Revenue, 2026 to 2036 | USD 2,343.5 million |
Federal front-of-pack naming rules in the United States and novel-food protein dossiers in the European Union and the United Kingdom shape how manufacturers label and market botanical egg alternatives across retail and foodservice channels. In January 2025, the U.S. Food and Drug Administration issued its Draft Guidance for Industry on the labeling of plant-based alternatives to animal-derived foods, instructing brands to declare the specific botanical protein source prominently on principal display panels [2]. Clear source disclosure helps procurement teams distinguish mung-bean and lupin scrambles from starch-heavy commercial bakery egg replacers that lack thermal curd formation. Consequently, ingredient processors that supply allergen-transparent, soy-free legume isolates are winning multi-year co-manufacturing contracts with multinational bakery and coffeehouse operators.
Pulse Protein Fractionation and Precision Fermentation Capacity Indicators
Table 2: Protein Isolate Throughput and Commercial Output Indicators for the Vegan Egg Market (USD million, thousand metric tons, and degrees Celsius), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 557.9 | 650.0 | 2,993.5 |
| Refined pulse & recombinant protein consumed (thousand MT) | 68.5 to 74.0 | 79.5 to 86.0 | 365.0 to 398.0 |
| Aseptic pourable liquid & patty output (million kg) | 142.0 to 156.0 | 165.0 to 182.0 | 740.0 to 815.0 |
| Target thermal gelation window (degrees Celsius) | 78.0 to 84.0 | 76.0 to 82.0 | 72.0 to 78.0 |
Protein mass balance note: Baseline 2025 isolate tonnage and gelation parameters are derived from Good Food Institute alternative protein production registries, UK Food Standards Agency novel-food dossier RP32 specifications, and commercial processor filings at 12% to 16% protein solids in liquid blends; 2026 and 2036 figures reflect FMI econometric scenario projections.
Wholesale Cost Parity & Foodservice Steam-Table Benchmarks
Institutional foodservice directors evaluate plant-based egg liquids on whether cooked curds resist syneresis (water weeping) and green-gray iron sulfide discoloration during 60-to-90-minute steam-table holding. Blending transglutaminase-crosslinked legume globulins into pasteurized liquid egg cartons stabilizes moisture retention under heat lamps while narrowing the wholesale per-pound price gap against conventional cage-free liquid eggs.
Table 3: Wholesale Pricing and Functional Performance Indicators for the Vegan Egg Market (USD per kilogram, days, and minutes), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Average wholesale pourable vegan egg price (USD/kg) | 6.10 to 7.45 | 5.85 to 7.10 | 4.10 to 5.20 |
| Precision-fermented recombinant ovalbumin powder (USD/kg) | 28.0 to 38.0 | 25.0 to 34.0 | 14.5 to 20.0 |
| Unopened refrigerated aseptic carton shelf life (days) | 75 to 90 | 85 to 105 | 110 to 140 |
| Steam-table curd moisture retention stability (minutes) | 60 to 80 | 70 to 90 | 95 to 120 |
Table 4: Segment Revenue Allocation and Operational Benchmarks for the Vegan Egg Market (USD million and percentages), 2026
| Metric | Value | Operational Context |
|---|---|---|
| Market size, 2026 | USD 650.0 million | Global 100% plant-based and precision-fermented egg substitutes |
| Pourable liquid egg replacers revenue, 2026 | USD 318.5 million | 49.0% product format share |
| Mung bean & lupin globulin isolates revenue, 2026 | USD 360.1 million | 55.4% protein source share |
| Retail grocery & supermarket revenue, 2026 | USD 260.0 million | 40.0% end-use channel share |
Analyst Perspective
"Avian influenza supply shocks are pushing quick-service chains and industrial bakeries toward contract-priced mung bean liquids and recombinant ovalbumin powders. Wet-fractionation isolate costs and clean-label hydrocolloid scrutiny still constrain price parity with commodity shell eggs."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the vegan egg market segmented?
The vegan egg market is segmented by product format, protein source, end-use channel, and region. In 2026, pourable liquid egg replacers are projected at 49.0%, mung bean & lupin globulin isolates at 55.4%, and retail grocery & supermarket channels at 40.0%.
By product format: Pourable Liquid Egg Replacers, Pre-Cooked Folded Patties, Egg Bites & Whole Boiled Formats, and Functional Dry Baking & Egg White Powders.
By protein source: Mung Bean & Lupin Globulin Isolates, Chickpea, Yellow Pea & Soy Protein Blends, and Precision-Fermented Recombinant Ovalbumin.
By end-use channel: Retail Grocery & Supermarket Channels, Foodservice, QSR & Institutional Dining, and Industrial Bakery & Mayonnaise/Sauce Manufacturing.
Why Do Pourable Liquid Egg Replacers Lead the Vegan Egg Market by Product Format?
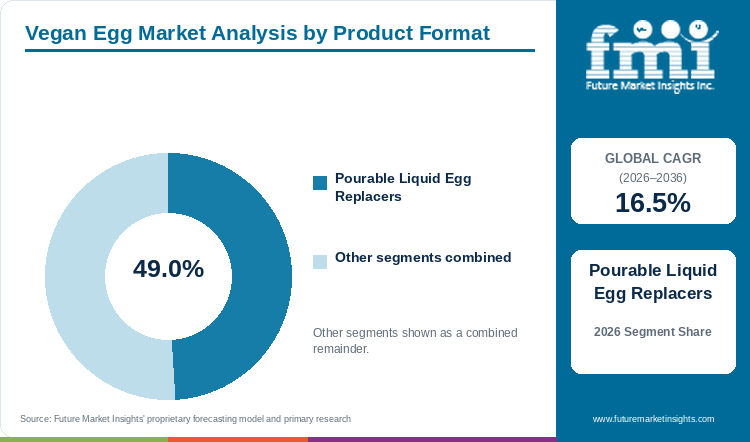
Pourable liquid egg replacers are expected to hold 49.0% of product format revenue in 2026, supported by griddle versatility.
Table 5: Product Format Share for the Vegan Egg Market (percentage share), 2026
| Product Format | Share (2026) |
|---|---|
| Pourable Liquid Egg Replacers | 49.0% |
| Other Segments Combined | 51.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Format Leadership and Market Growth for the Vegan Egg Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 16.5% |
| Leading Segment | Pourable Liquid Egg Replacers |
Supermarket dairy buyers and commercial breakfast cooks favor pourable liquid egg replacers because homogenized oil-in-water protein emulsions ladle directly onto hot griddles, crepe pans, and quiche molds without pre-hydration or high-shear mixing. When packaged in aseptic multi-layer polyethylene terephthalate bottles or 20-pound bag-in-box foodservice liners, pourable formulated plant-based eggs deliver 75 to 90 days of unopened chilled shelf life while eliminating shell-cracking labor and raw *Salmonella* cross-contamination hazards. While pre-cooked frozen plant-based egg bites and folded sandwich patties capture 31.8% share across coffeehouse drive-thrus, pourable liquids remain the primary household and restaurant workhorse.
- Pourable liquid egg replacers account for 49.0% of product format revenue in 2026, supported by 1:1 culinary substitution in scrambles, omelets, and French toast batters.
- In August 2025, Eat Just, Inc. and Vegan Food Group launched JUST Egg pourable plant-based liquid cartons in the United Kingdom backed by an GBP 11.5 million automated European production line investment [3].
What Makes Mung Bean & Lupin Globulin Isolates Central to the Protein Source Category?
Mung bean & lupin globulin isolates are estimated to represent 55.4% of the protein source category in 2026, reflecting thermal curd formation.
Replicating the elastic coagulated network of cooked avian ovalbumin requires botanical storage proteins that unfold and cross-link through hydrophobic and disulfide bonds just below 85 degrees Celsius. Mung bean & lupin globulin isolates anchor raw material procurement because 8S mung bean vicilin and sweet lupin conglutin fractions form firm, opaque golden curds without the gritty mouthfeel or grassy hexanal off-notes typical of unrefined pea flour. Furthermore, pairing sweet lupin protein isolates with soluble chickpea protein concentrates allows formulators to market soy-free and gluten-free breakfast scrambles that pass school and airline allergen restrictions.
- Mung bean & lupin globulin isolates represent 55.4% of protein source demand in 2026, reflecting clean flavor profiles and rapid thermal gelation on commercial griddles.
- In September 2025, a peer-reviewed food science review in Critical Reviews in Food Science and Nutrition validated the emulsification and thermal gelling performance of EFSA-approved mung bean protein isolates across egg-free formulations [4].
Why Do Retail Grocery & Supermarket Channels Anchor the End-Use Channel Category?
Retail grocery & supermarket channels are projected to capture 40.0% of end-use channel demand in 2026, driven by dairy-case merchandising.
Positioning chilled plant-based egg bottles and hard-boiled vegan egg packs directly inside the conventional supermarket egg set has transformed category visibility among mainstream flexitarian shoppers. Retail grocery & supermarket channels generate the largest revenue share because households managing pediatric egg allergies, elevated serum LDL cholesterol, or shell-egg price spikes purchase pourable cartons during weekly grocery trips. Meanwhile, industrial bakeries and sauce processors accounting for 23.5% of demand increasingly procure dehydrated ovalbumin powders and glaze and egg wash substitutes to stabilize brioche crumb structure and mayonnaise viscosity.
- Retail grocery & supermarket channels hold 40.0% of end-use channel revenue in 2026, driven by adjacent merchandising in chilled dairy cases and club-store multipacks.
- In March 2026, The EVERY Company partnered with Healthier Comforts to bring EVERY animal-free precision-fermented egg white protein to retail home kitchens for the first time [5].
What are the drivers, restraints, and opportunities in the vegan egg market?
Avian influenza shell-egg volatility and novel-food regulatory approvals accelerate vegan egg procurement, whereas wet-fractionation isolate costs and hydrocolloid scrutiny create friction, and precision-fermented ovalbumin unlocks industrial bakery replacement.
- Driver: Recurrent avian influenza flock depopulations and regulatory clearances for mung bean and recombinant egg proteins are pushing foodservice and bakery buyers into multi-year plant egg contracts.
- Restraint: Wet-isoelectric pulse protein isolation expenses and consumer scrutiny of methylcellulose and phosphate emulsifiers keep retail unit prices above off-peak conventional shell eggs.
- Opportunity: Scaling precision-fermented recombinant ovalbumin and whole-food hard-boiled plant eggs opens high-margin commercial patisserie, salad-bar, and grab-and-go convenience channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Harmonized safety clearances for novel legume isolates combined with commercial bakery demand for pathogen-free egg replacers are converting trial placements into permanent menu items. On July 30, 2025, the UK Food Standards Agency and Food Standards Scotland published their positive safety assessment of mung bean protein (RP32) as a novel food for commercial food applications [6]. Regulatory validation across Europe and North America enables multinational quick-service chains and institutional caterers to standardize on functional egg replacement ingredients that eliminate cold-storage *Salmonella* testing and insulate breakfast menus from seasonal poultry culling.
Risk Assessment of the Vegan Egg Market: Operational and Supply Friction
High capital intensity in wet-milling pulse protein fractionation and rheological trade-offs in clean-label hydrocolloid systems constrain margin expansion for emerging brands. In March 2026, the Good Food Institute's technical review of plant-based and fermentation-enabled egg substitutes highlighted that extracting high-purity 8S mung bean globulins and scaling food-grade bioreactor fermentation still incur higher per-kilogram unit costs than commodity shell eggs during disease-free poultry cycles [7]. In addition, removing methylcellulose to satisfy clean-label grocery standards often reduces hot-curd elasticity, requiring formulators to balance native starch blends with enzymatic transglutaminase cross-linking.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Pairing precision-fermented recombinant egg white proteins with agricultural bioprocessing infrastructure unlocks drop-in replacement for high-foam bakery applications such as macarons, angel food cakes, and meringues. In July 2026, The EVERY Company partnered with Archer Daniels Midland (ADM) at ADM's Clinton, Iowa bioprocessing complex and expanded its Huvepharma fermentation capacity fourfold to scale OvoPro animal-free egg white protein [8]. By blending precision fermentation food proteins with plant-based lipid yolks, ingredient suppliers can offer industrial bakeries and ready-meal manufacturers zero-cholesterol powders that whip to stiff peaks and survive retort pasteurization.
Vegan Egg Market by Country (2026 to 2036)
National growth trajectories between 2026 and 2036 reflect domestic pulse-fractionation infrastructure, municipal public-catering carbon mandates, and retail supermarket private-label depth. Australia leads the six evaluated countries at a 20.1% CAGR, followed by Sweden at 18.3%, France at 16.9%, and the United States at 15.9% (reaching USD 235.0 million in 2026). The United Kingdom advances at 14.3%, while Germany records a 13.4% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the Vegan Egg Market (CAGR percentage and operational drivers), 2026 to 2036
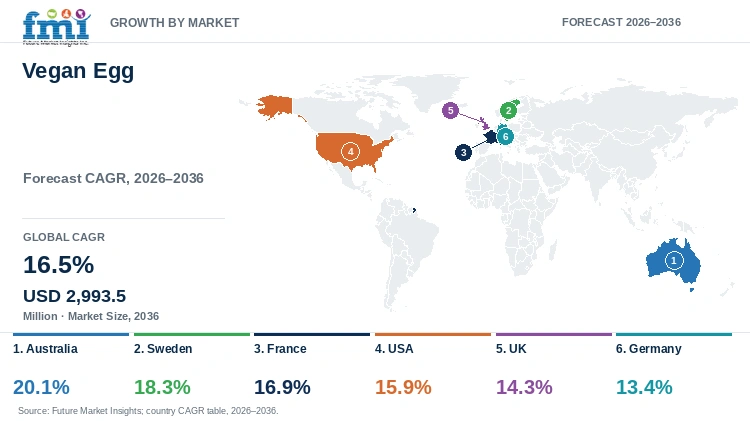
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 20.1% | Urban Melbourne and Sydney cafe brunch adoption and domestic sweet lupin/faba bean isolate extraction |
| Sweden | 18.3% | Municipal school and public catering climate targets and Nordic yellow-pea protein processing |
| France | 16.9% | Artisan patisserie and brioche egg-wash reformulation backed by INRAE legume breeding programs |
| USA | 15.9% | Avian influenza shell-egg volatility and 20,000-store supermarket dairy-case distribution (USD 235.0M in 2026) |
| UK | 14.3% | FSA mung bean novel-food clearance, Veganuary retail habits, and localized European liquid bottling |
| Germany | 13.4% | Discount supermarket private-label vegan egg lines and federal Protein Crop Strategy funding |
Source: Future Market Insights analysis
Australia Vegan Egg Market Outlook (2026 to 2036)
Independent specialty coffeehouses and brunch venues across Melbourne, Sydney, and Brisbane anchor commercial demand in Australia, where chefs pair folded botanical scrambles and egg-free hollandaise with sourdough breakfast plates. In February 2026, Australia's national science agency CSIRO updated its National Protein Roadmap and Kick-Start faba bean and sweet lupin extraction programs, targeting AUD 13 billion in domestic plant-based protein value transformation [9]. Sales of vegan eggs in Australia are forecast to expand at a world-leading 20.1% CAGR through 2036 as local formulators replace imported soy with Western Australian lupin isolates. However, refrigerated road-freight tariffs across dispersed state capitals elevate chilled carton distribution costs, prompting manufacturers to co-pack shelf-stable bakery premixes alongside chilled foodservice bags.
Key takeaway: In Australia, metropolitan cafe brunch menus and domestic CSIRO-backed lupin and faba bean fractionation propel the fastest national expansion globally.
Sweden Vegan Egg Market Outlook (2026 to 2036)
Public-sector institutional catering across Swedish municipalities, universities, and hospital kitchens drives baseline volume by enforcing strict per-meal carbon-equivalent budgets that penalize conventional animal proteins. In November 2025, the Swedish Food Agency (Livsmedelsverket) implemented its updated national dietary guidelines grounded in the Nordic Nutrition Recommendations, encouraging higher legume and plant-protein intake across public meal programs [10]. By 2036, Sweden is projected to grow at an 18.3% CAGR as retail chains ICA and Coop stock multiple pourable scramble and dry baking replacer SKUs. Yet commercial uptake faces friction from short northern growing seasons for warm-climate mung beans, steering Swedish food-tech formulators toward domestic yellow-pea globulin and oat-lipid emulsion blends.
Key takeaway: In Sweden, Livsmedelsverket public-catering nutrition guidelines and domestic yellow-pea protein extraction sustain rapid institutional and grocery adoption.
France Vegan Egg Market Outlook (2026 to 2036)
Industrial viennoiserie bakeries, mayonnaise processors, and Parisian patisseries define the French market, where technical buyers prioritize fine crumb aeration, golden crust glaze, and emulsion stability over simple breakfast scrambles. In September 2025, France's National Research Institute for Agriculture, Food and Environment (INRAE) launched a 34-partner European legume breeding and plant-protein functionality initiative under the France 2030 TRANSFORM program [11]. The French vegan egg sector is projected to record a 16.9% CAGR from 2026 to 2036 as boulangeries qualify pulse-and-ovalbumin hybrids for brioche, quiche, and choux pastry. Nonetheless, strict French culinary standards regarding additive-free ingredient lists penalize methylcellulose-stabilized liquids, favoring clean-label faba bean, chickpea, and flaxseed mucilage formulations.
Key takeaway: In France, commercial patisserie and mayonnaise reformulation backed by INRAE legume research drives demand for clean-label emulsifying and glazing replacers.
USA Vegan Egg Market Outlook (2026 to 2036)
Valued at USD 235.0 million in 2026 as the largest national market, the United States combines 20,000-store supermarket dairy-case placement with breakfast sandwich integration across coffeehouse chains. In June 2025, the U.S. Department of Agriculture reported that over 130 commercial poultry facilities underwent biosecurity audits under its USD 1.0 billion strategy to contain highly pathogenic avian influenza and shell-egg price swings [12]. Demand across the USA vegan egg sector is expected to increase at a 15.9% CAGR through 2036 as foodservice buyers lock in fixed-price annual contracts for pourable mung bean liquids. The central commercial obstacle involves episodic price drops in conventional caged shell eggs when flocks recover, requiring brands to compete on zero-cholesterol nutrition and 90-day chilled shelf life.
Key takeaway: In the USA, avian influenza supply hedging across national coffeehouse chains and mainstream grocery dairy cases anchors global revenue leadership.
UK Vegan Egg Market Outlook (2026 to 2036)
High-street bakery chains, chilled supermarket meal deals, and annual January Veganuary retail campaigns give the United Kingdom Europe's highest per-capita trial rate for ready-to-eat plant breakfast wraps and quiches. In December 2025, the Department for Environment, Food & Rural Affairs (DEFRA) published the United Kingdom Food Security Digest 2025, tracking national dietary protein diversification alongside notifiable avian disease pressures on domestic laying flocks [13]. In the UK, demand for vegan eggs is predicted to advance at a 14.3% CAGR through 2036 following local automated bottling investments by Vegan Food Group and Eat Just. Nevertheless, intense retail price competition among Tesco, Sainsbury's, and Asda private-label tiers compresses branded supplier gross margins.
Key takeaway: In the UK, FSA novel-food clearance for mung bean protein and domestic co-manufacturing capacity accelerate high-street foodservice and supermarket rollout.
Germany Vegan Egg Market Outlook (2026 to 2036)
Discount grocery leaders Aldi, Lidl, and Rewe shape German volume by merchandising affordable private-label vegan egg powders and chilled scramble bottles directly alongside conventional organic shell eggs. In December 2025, the German Federal Ministry of Food and Agriculture (BMLEH) expanded its national Protein Crop Strategy to boost domestic sweet lupin, faba bean, and pea cultivation for food processing [14]. Germany's vegan egg outlook is anticipated to advance at a 13.4% CAGR over the assessment period as flexitarian households substitute plant scrambles into weekend breakfasts. While German shoppers lead Europe in total plant-based volume, strict Oeko-Test consumer magazine audits against synthetic gums and phosphate salts compel brands to reformulate with short, recognizable legume ingredient decks.
Key takeaway: In Germany, discount supermarket private-label penetration and federal Protein Crop Strategy support for domestic lupin and faba beans drive mainstream volume.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the vegan egg market?
Eat Just, Inc., The EVERY Company, Float Foods Pte. Ltd., Crafty Counter (WunderEggs), Zero Egg, Simply Eggless, Inc., EVO Foods, Nabati Foods Global Inc., and Spero Foods are the notable companies active in this market.
Competitive positioning in the vegan egg market divides between wet-fractionated legume liquid pioneers, precision-fermentation recombinant protein brewers, and whole-egg structural format specialists. Eat Just, Inc. commands leading retail and foodservice volume across North America and Europe with its mung-bean-based JUST Egg pourable carton and folded toaster patty lines. The EVERY Company (formerly Clara Foods) operates at the biotechnology frontier by fermenting bio-identical recombinant ovalbumin with industrial partners ADM and Huvepharma for commercial bakeries. Challenger brands including Crafty Counter, Float Foods, Zero Egg, Simply Eggless, EVO Foods, Nabati Foods, and Spero Foods target hard-boiled salad eggs, sunny-side-up foodservice pucks, lupin liquids, and clean-label bakery replacers.
- Pourable Liquid & Foodservice Scale Leaders: Eat Just, Inc. and Simply Eggless, Inc. operate high-throughput mung bean and lupin protein extraction and aseptic bottling networks serving grocery dairy cases and quick-service chains.
- Precision Fermentation & Bakery Protein Innovators: The EVERY Company and Zero Egg supply recombinant avian ovalbumin and multi-legume functional powders engineered for industrial brioche, meringues, and sauces.
- Whole-Boiled & Regional Culinary Specialists: Crafty Counter, Float Foods Pte. Ltd., EVO Foods, Nabati Foods Global Inc., and Spero Foods produce whole hard-boiled vegan eggs, poached yolks, and allergen-free seed scrambles.
Competitive Benchmarking: Vegan Egg Market
Table 8: Competitive Benchmarking for the Vegan Egg Market (qualitative capability ratings), 2026
| Company | Protein Isolation & Fermentation IP | Format Portfolio Breadth | Thermal Curd & Foaming Fidelity | Geographic Reach |
|---|---|---|---|---|
| Eat Just, Inc. | High | High | High | High |
| The EVERY Company | High | Medium | High | High |
| Zero Egg | Medium | High | High | Medium |
| Crafty Counter (WunderEggs) | Medium | Medium | High | Medium |
| Simply Eggless, Inc. | Medium | Medium | High | Medium |
| Float Foods Pte. Ltd. | High | High | Medium | Medium |
| EVO Foods | Medium | Medium | Medium | Medium |
| Nabati Foods Global Inc. | Medium | Medium | Medium | Medium |
| Spero Foods | Medium | Medium | Medium | Medium |
Ratings in Table 8 evaluate four operational dimensions: Protein Isolation & Fermentation IP rates a producer High when it owns patented mung bean 8S globulin extraction or recombinant yeast ovalbumin expression strains. Format Portfolio Breadth compares suppliers spanning pourable cartons, folded patties, and baking powders against single-format brands. Thermal Curd & Foaming Fidelity measures steam-table holding and stiff-peak whipping across vegan protein powders, and Geographic Reach separates multi-continental distribution from single-country retail.
Key Developments in the Vegan Egg Market
- In June 2026, The EVERY Company and Huvepharma announced a fourfold production capacity expansion for precision-fermented animal-free egg white protein to serve industrial bakery and foodservice accounts [15].
- In April 2025, Eat Just, Inc. signed an exclusive European manufacturing and distribution partnership with Vegan Food Group to produce JUST Egg mung bean liquids across the United Kingdom and European Union [16].
- In June 2026, Crafty Counter expanded its WunderEggs plant-based hard-boiled egg portfolio by launching High Protein Egg & Cheese Buns and 12-to-20-tray foodservice packs across North America [17].
Key Players in the Vegan Egg Market
Global Pourable Liquid and Precision Fermentation Leaders
- Eat Just, Inc.
- The EVERY Company
Commercial Foodservice and Functional Bakery Replacer Specialists
- Zero Egg
- Simply Eggless, Inc.
- Float Foods Pte. Ltd.
Whole-Boiled, Lupin, and Seed-Based Clean-Label Innovators
- Crafty Counter (WunderEggs)
- EVO Foods
- Nabati Foods Global Inc.
- Spero Foods
Vegan Egg Market - Report Scope
Table 9: Report Scope for the Vegan Egg Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Format; Protein Source; End-Use Channel; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial revenue from 100% plant-based and precision-fermented egg substitutes (pourable liquid scrambles, pre-cooked folded patties and egg bites, whole hard-boiled and poached simulations, and functional dry baking/albumen powders) sold across retail, foodservice, and industrial food manufacturing. Category Scope Note: Market valuation (USD 650.0 million in 2026; USD 2,993.5 million by 2036 at 16.5% CAGR; 2025 base year USD 557.9 million) captures dedicated culinary vegan egg products and precision-fermented ovalbumin replacers; broader unformulated commodity starch/hydrocolloid binders and conventional avian liquid egg products are excluded from scope. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Sweden, France, United States, United Kingdom, Germany, Canada, Japan, South Korea, Singapore, India, and additional countries in the full report |
| Key Companies Covered | Eat Just, Inc., The EVERY Company, Float Foods Pte. Ltd., Crafty Counter, Zero Egg, Simply Eggless, Inc., EVO Foods, Nabati Foods Global Inc., Spero Foods |
| Forecast Period | 2026 to 2036 (Base Year: 2025) |
| Approach | Primary and secondary research with top-down and bottom-up econometric market triangulation. |
Vegan Egg Market - Research Methodology
Table 10: Research Methodology for the Vegan Egg Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with pulse protein fractionation engineers, precision fermentation bioprocess directors, quick-service restaurant culinary heads, industrial bakery formulators, and supermarket dairy-case category buyers. |
| Secondary Research | Secondary research reviewed USDA APHIS and ERS avian influenza and egg price releases, U.S. FDA plant-based labeling draft guidance, UK FSA novel food safety dossier RP32, Good Food Institute technical reports, CSIRO and INRAE legume publications, and company filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 triangulated aseptic bottling and patty line capacities, pulse globulin isolate tonnage, and precision-fermented ovalbumin bioreactor output against retail scanner and foodservice distributor volumes. |
| Data Triangulation and Validation | Estimates were cross-checked against wholesale conventional liquid egg spot prices, retail dairy-case velocity per store, and commercial bakery egg-wash/albumin substitution rates. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's alternative protein econometric model, calibrating evaluated national growth rates against the 16.5% global baseline through verified HPAI poultry supply disruptions, municipal public-catering carbon rules, novel-food clearances, and domestic lupin/pea fractionation capacity. |
| Operational Benchmark Traceability | Operational benchmarks (refined pulse and recombinant protein tonnage, aseptic liquid and patty output, thermal gelation temperature windows, wholesale pricing, and steam-table holding duration) represent modeled estimates synthesized from GFI, UK FSA RP32, USDA, and manufacturer technical disclosures. |
Vegan Egg Market by Segments
Vegan Egg Market segmented by Product Format:
- Pourable Liquid Egg Replacers
- Pre-Cooked Folded Patties, Egg Bites & Whole Boiled Formats
- Functional Dry Baking & Egg White Powders
Vegan Egg Market segmented by Protein Source:
- Mung Bean & Lupin Globulin Isolates
- Chickpea, Yellow Pea & Soy Protein Blends
- Precision-Fermented Recombinant Ovalbumin
Vegan Egg Market segmented by End-Use Channel:
- Retail Grocery & Supermarket Channels
- Foodservice, QSR & Institutional Dining
- Industrial Bakery & Mayonnaise/Sauce Manufacturing
Vegan Egg Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Argentina
- Western Europe
- Sweden
- France
- United Kingdom
- Germany
- Netherlands
- Italy
- Eastern Europe
- Poland
- Czechia
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- Australia
- New Zealand
- Singapore
- India
- Middle East and Africa
- Israel
- United Arab Emirates
- South Africa
Research Sources and Bibliography
- [1] U.S. Department of Agriculture. (2025, February 26). USDA Invests Up To $1 Billion to Combat Avian Flu and Reduce Egg Prices. U.S. Department of Agriculture.
- [2] U.S. Food and Drug Administration. (2025, January 6). Draft Guidance for Industry: Labeling of Plant-Based Alternatives to Animal-Derived Foods. U.S. Department of Health and Human Services.
- [3] Vegconomist / Vegan Food Group & Eat Just, Inc. (2025, August 7). Just Egg Launches in UK Backed by VFG's GBP 11.5M Investment in Production. Vegconomist.
- [4] Verma, D., et al. (2025, September 29). A comprehensive overview of three novel plant proteins approved by EFSA: alfalfa protein concentrate, rapeseed and mung bean protein isolates. Critical Reviews in Food Science and Nutrition, 66(11), 2215-2231.
- [5] The EVERY Company. (2026, March 11). Healthier Comforts Brings EVERY's Animal-Free Egg White Protein to Home Kitchens. The EVERY Company Press Releases.
- [6] Food Standards Agency & Food Standards Scotland. (2025, July 30). Safety Assessment of Mung Bean Protein as a Novel Food for Use in Food (RP32). GOV.UK Science and Research.
- [7] The Good Food Institute. (2026, March 18). Innovations in egg substitutes: Plant-based and fermentation-enabled innovations for egg substitutes. The Good Food Institute.
- [8] Food Ingredients First / ADM & The EVERY Company. (2026, July 15). ADM partners with The Every Company for precision-fermented egg white protein scale-up in Iowa. CNS Media B.V..
- [9] Commonwealth Scientific and Industrial Research Organisation (CSIRO). (2026, February 25). Australia's protein roadmap and Australian Plant Proteins optimised faba bean and lupin extraction. CSIRO Futures.
- [10] Livsmedelsverket (Swedish Food Agency). (2025, November 10). Nordic Nutrition Recommendations and updated national dietary guidelines for plant-based proteins and legumes. Livsmedelsverket Uppsala.
- [11] Institut National de Recherche pour l'Agriculture, l'Alimentation et l'Environnement (INRAE). (2025, September 9). European legume breeding is taken to next level for competitive seed market and sustainable protein production. INRAE Paris.
- [12] U.S. Department of Agriculture. (2025, June 26). Secretary Rollins Provides Update on Bird Flu Strategy, Egg Prices Continue to Fall. U.S. Department of Agriculture Press Releases.
- [13] Department for Environment, Food & Rural Affairs. (2025, December 11). United Kingdom Food Security Digest 2025. GOV.UK.
- [14] Federal Ministry of Food and Agriculture (BMLEH). (2025, December 16). The BMLEH's Protein Crop Strategy and Implementing the Food and Nutrition Strategy in Germany. BMLEH Berlin.
- [15] The EVERY Company. (2026, June 15). EVERY and Huvepharma Announce 4x Production Capacity Expansion. The EVERY Company Press Releases.
- [16] AgFunderNews / Eat Just, Inc. (2025, April 15). Eat Just strikes deal with VFG to take plant-based JUST Egg to Europe. AgFunderNews.
- [17] Crafty Counter. (2026, June 30). WunderEggs Plant-Based and Vegan Hard-Boiled Eggs (Food Service 12 or 20 Trays) & High Protein Egg & Cheese Buns. Crafty Counter WunderEggs.
- [18] The EVERY Company. (2025, November 4). The EVERY Company closed $55 million in Series D to scale precision-fermented egg proteins for retail and industrial bakeries. The EVERY Company Resources.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vegan egg market in 2026 and what is forecast for 2036?
- How do recurring avian influenza outbreaks and novel-food clearances shape demand for vegan eggs?
- Why do Pourable Liquid Egg Replacers lead the product format category?
- Why do Mung Bean & Lupin Globulin Isolates lead the protein source category globally?
- How do growth rates differ across Australia, Sweden, France, the United States, the United Kingdom, and Germany?
- Which leading companies manufacture plant-based scrambles, hard-boiled vegan eggs, and precision-fermented ovalbumin?
- What pulse fractionation cost and hydrocolloid factors limit adoption in the vegan egg market?
- What should foodservice and industrial bakery buyers evaluate before qualifying vegan egg suppliers?
Frequently Asked Questions
How big is the vegan egg market in 2026, and what is forecast for 2036?
The global vegan egg market will reach USD 650.0 million in 2026. Valuation is projected to expand further and reach USD 2,993.5 million by 2036 as foodservice chains and grocers hedge against shell-egg volatility.
What CAGR is forecast for the Vegan Egg Market through 2036?
As per FMI, the vegan egg market is projected to grow at a 16.5% CAGR from 2026 to 2036. Expansion is supported by avian influenza supply hedging, zero-cholesterol dietary shifts, and precision-fermented ovalbumin scaling.
Which product format holds a notable vegan egg demand share in 2026?
Pourable Liquid Egg Replacers are projected to hold 49.0% of product format demand in 2026. The segment benefits from 1:1 griddle substitution and 75-to-90-day unopened chilled shelf stability.
Which protein source segment holds a notable vegan egg share in 2026?
Mung Bean & Lupin Globulin Isolates will hold 55.4% of protein source demand in 2026. Demand is supported by 8S vicilin thermal gelation at 78 to 84 degrees Celsius and soy-free allergen positioning.
Which country has a notable vegan egg expansion outlook during the forecast period?
FMI finds that Australia is projected to expand at a 20.1% CAGR during the 2026 to 2036 assessment period. Growth is supported by metropolitan cafe brunch adoption and domestic CSIRO-backed lupin and faba bean protein extraction.
Which companies are active in the Vegan Egg Market during 2026?
Notable companies include Eat Just, Inc., The EVERY Company, Float Foods Pte. Ltd., Crafty Counter, Zero Egg, Simply Eggless, Inc., EVO Foods, Nabati Foods Global Inc., and Spero Foods. These producers focus on mung bean and lupin liquid scrambles, precision-fermented ovalbumin, and whole hard-boiled vegan eggs.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Format, 2026 to 2036
- Pourable Liquid Egg Replacers
- Pre-Cooked Folded Patties, Egg Bites & Whole Boiled Formats
- Functional Dry Baking & Egg White Powders
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Protein Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Protein Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Protein Source, 2026 to 2036
- Mung Bean & Lupin Globulin Isolates
- Chickpea, Yellow Pea & Soy Protein Blends
- Precision-Fermented Recombinant Ovalbumin
- Y-o-Y Growth Trend Analysis By Protein Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Protein Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Channel, 2026 to 2036
- Retail Grocery & Supermarket Channels
- Foodservice, QSR & Institutional Dining
- Industrial Bakery & Mayonnaise/Sauce Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Argentina
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Sweden
- France
- United Kingdom
- Germany
- Netherlands
- Italy
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czechia
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- Singapore
- India
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Israel
- United Arab Emirates
- South Africa
- By Product Format
- By Protein Source
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Protein Source
- By End-Use Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Protein Source
- By End-Use Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Format
- By Protein Source
- By End-Use Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Eat Just, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The EVERY Company
- Zero Egg
- Crafty Counter (WunderEggs)
- Simply Eggless, Inc.
- Float Foods Pte. Ltd.
- EVO Foods
- Nabati Foods Global Inc.
- Spero Foods
- Eat Just, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


