

- Market Size (2026)
- USD 2.9 Bn
- Forecast (2036)
- USD 5.1 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Food Service Industry in 2026?
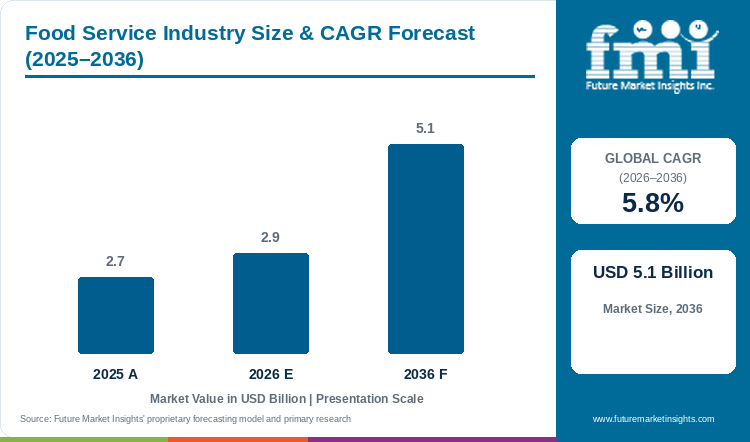
Global food service industry revenue is projected to grow at a 5.8% CAGR, with market valuation rising from USD 2.7 billion in 2025 to USD 2.9 billion in 2026 and reaching USD 5.1 billion by 2036.
Rising demand for the elimination of scratch-kitchen prep bottlenecks, and reduction of the overall kitchen floor footprint and labor costs associated with it, led to the widespread adoption of centralized food service formats. According to Future Market Insights analysis, global food service industry revenue progresses from USD 2.7 billion in 2025 to USD 2.9 billion in 2026 and reaches USD 5.1 billion by 2036, recording a 5.8% CAGR over the 2026 to 2036 period and adding USD 2.2 billion in new value. United States food-away-from-home expenditure reached USD 1.54 trillion during 2025 according to June 2026 USDA Economic Research Service data [1]. Standard Commercial Grade accounts for 44.6% of product type / grade sales in 2026 across quick service restaurant chains, whereas high line-cook wages continue to test independent operator profitability.
Key Market Trends & Insights
- By product type / grade: Standard Commercial Grade led the market with a share of 44.6% in 2026, as contract caterers depend on calibrated bulk staples that keep tray costs predictable across large institutional dining halls.
- By processing state: With a 51.0% share in 2026, Fresh / Ambient Packaged led the category because pre-washed produce and ambient pantry inputs shorten morning station setup.
- By end-use application: Direct Retail Consumer Consumption held the leading share of 55.6% in 2026, driven by high daily ticket turnover across commuter lunch counters and casual dining outlets.
Regional Highlights
- Fastest-growing evaluated country: Japan, at 7.1% CAGR from 2026 to 2036.
- By country: The USA at 6.5%, Germany at 6.0%, France at 5.6%, and Switzerland at 5.1% follow, while Australia records the lowest evaluated CAGR at 4.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Food Service Industry (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.7 billion |
| Estimated Market Size in 2026 | USD 2.9 billion |
| Projected Market Size by 2036 | USD 5.1 billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 2.2 billion |
Hospital cafeterias, corporate dining halls, and airport concessions in high-wage metropolitan markets face strict sodium, allergen, and cold-holding audit rules alongside rising commercial electricity bills. Public dining facilities across the United States must meet updated sodium and temperature-control benchmarks following the January 2026 Centers for Disease Control and Prevention food service guidelines revision [2]. Owing to the labor savings associated with off-site batching, multi-unit restaurant operators in Japan, North America, and Western Europe are moving soup, sauce, and protein prep into centralized cook-chill commissaries to protect tray consistency and cut back-of-house staffing hours.
Kitchen Throughput and Catering Volume Sizing
Table 2: Kitchen Throughput and Catering Volume Indicators for the Food Service Industry (USD billion, million meals, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.7 | 2.9 | 5.1 |
| Commercial commissary meals served daily (million) | 18.5 to 21.0 | 19.8 to 22.4 | 31.0 to 35.2 |
| Centralized cook-chill batch output per day (million kg) | 7.4 to 8.4 | 7.9 to 9.0 | 12.4 to 14.1 |
| Average wholesale ingredient spend per meal tray (USD) | 1.42 to 1.65 | 1.48 to 1.72 | 1.85 to 2.15 |
Commissary meal volume and daily cook-chill kilogram output track institutional tray assembly, workplace cafeteria service, and multi-unit restaurant dispatch across commercial kitchens.
Outlet Spending & Institutional Catering Indicators
Centralized meal assembly stabilizes food cost per plate when wholesale meat, cooking oil, and produce prices fluctuate across seasonal supply contracts. Peak lunch ticket velocity in business districts requires rapid tray regeneration without cross-contamination or line bottlenecks. Because high urban storefront rents penalize oversized back-of-house prep rooms, hospitality brands increasingly pair compact counter storefronts with cloud kitchen operations and regional commissaries that deliver pre-portioned entrees before morning service.
Table 3: Per Capita and Outlet Spending Indicators for the Food Service Industry (billion people and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Market spend per capita (USD) | 0.33 | 0.35 | 0.57 |
| Market spend per 1,000 people (USD) | 328.1 | 349.4 | 569.8 |
| Annual procurement per commercial kitchen unit (USD) | 1,850 to 2,120 | 1,960 to 2,250 | 3,150 to 3,620 |
Table 4: Institutional & Retail Outlet Revenue Allocation for the Food Service Industry (USD billion and percentage share), 2026
| Metric | Value | Operational Scope |
|---|---|---|
| Market size, 2026 | USD 2.9 billion | Global in-scope food service valuation |
| Direct retail consumer consumption revenue, 2026 | USD 1.6 billion | 55.6% end-use application share |
| Commercial food manufacturing plants revenue, 2026 | USD 0.7 billion | 24.8% end-use application share |
| Food service & hospitality institutional revenue, 2026 | USD 0.6 billion | 19.6% end-use application share |
Analyst Perspective
"Centralized cook-chill commissaries and digital order routing allow multi-unit caterers to raise hourly meal output with fewer line cooks. Cold-chain energy tariffs and menu fatigue still force operators to validate batch holding quality before scaling regional contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the food service industry segmented?
The food service industry is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 44.6%, fresh / ambient packaged at 51.0%, and direct retail consumer consumption at 55.6%.
By product type / grade: Standard Commercial Grade, Organic & Clean-Label Variant, and Premium Specialty Formulation.
By processing state: Fresh / Ambient Packaged, Frozen & Chilled, and Dehydrated & Dry Packaged.
By end-use application: Direct Retail Consumer Consumption, Commercial Food Manufacturing Plants, and Food Service & Hospitality.
Why does Standard Commercial Grade lead the product type / grade category?
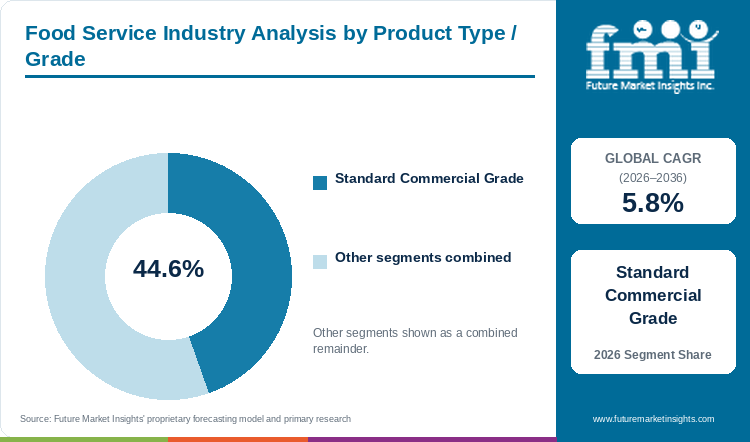
Standard commercial grade is expected to account for 44.6% of product type / grade revenue in 2026, supported by predictable bulk batching.
Table 5: Product Type / Grade Share for the Food Service Industry (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 44.6% |
| Other Segments Combined | 55.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Food Service Industry (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Standard Commercial Grade |
Corporate cafeterias, public school meal programs, and quick-service chains specify standard commercial grade ingredients to guarantee fixed viscosity, calibrated seasoning, and uniform yield across high-volume cooking kettles. Whereas specialty artisanal lots vary by harvest, standard commercial grades pass through automated steam ovens without recipe recalibration. Multi-year wholesale purchasing agreements also insulate operators from weekly spot-market swings when running contract catering services across workplace and hospital dining rooms. Higher unit costs keep Organic & Clean-Label Variant (33.8%) and Premium Specialty Formulation (21.6%) concentrated in boutique dining and executive catering menus.
- Standard commercial grade is projected to account for 44.6% of product type / grade revenue in 2026, supported by standardized portion yields and fixed-cost institutional supply contracts.
- Microbial temperature-abuse incidents across audited institutional catering kitchens dropped by 24% under standardized cook-chill batch protocols reviewed by the European Food Safety Authority in March 2025 [3].
What keeps Fresh / Ambient Packaged ahead by processing state?
Fresh / ambient packaged is estimated to represent 51.0% of the processing state category in 2026, reflecting lower cold-storage overhead.
Trimmed produce, ambient cooking oils, and shelf-stable pouch sauces move directly from delivery docks onto prep tables without occupying scarce walk-in freezer space. Using ambient-sealed stocks and pre-washed greens eliminates thawing delays during lunch rushes and lowers kitchen compressor electricity draw. Restaurant groups pairing daily produce drops with high-speed commercial catering appliances turn tables faster while keeping fresh plate presentation. Blast-frozen proteins in Frozen & Chilled (30.5%) require continuous sub-zero freight, while Dehydrated & Dry Packaged mixes (18.5%) need dedicated rehydration steps before service.
- Fresh / ambient packaged is estimated to hold 51.0% of processing state demand in 2026, underpinned by zero defrosting downtime and lower refrigerated storage expenses.
- Workforce benchmarks from the U.S. Bureau of Labor Statistics in April 2026 recorded 12.4 million employees across food services and drinking places, reinforcing kitchen reliance on pre-trimmed fresh and ambient-sealed inputs that save prep hours [4].
What gives Direct Retail Consumer Consumption the leading position in end-use application?
Direct retail consumer consumption is projected to capture 55.6% of end-use application demand in 2026, driven by takeaway order volume.
Quick-service counters, fast-casual storefronts, and commuter grab-and-go kiosks generate continuous individual ticket volume across breakfast, lunch, and dinner dayparts, putting direct retail consumer consumption ahead of institutional channels. Mobile ordering apps and drive-thru display boards allow storefronts to handle delivery couriers alongside dine-in guests without expanding dining room seating. Kitchen operators installing automated foodservice equipment synchronize fryer and oven cycles directly with incoming mobile tickets. Commercial Food Manufacturing Plants (24.8%) and Food Service & Hospitality contracts (19.6%) operate on longer institutional tender cycles.
- Direct retail consumer consumption is anticipated to contribute 55.6% of end-use application sales in 2026, owing to high-frequency mobile takeaway orders and extended drive-thru operating hours.
- Digital kiosk and mobile app orders generated 34% of quick-service restaurant traffic across metropolitan United States outlets in the February 2025 National Restaurant Association operational benchmark [5].
What are the drivers, restraints, and opportunities in the food service industry?
In the Food Service Industry, digital off-premise ordering and centralized commissary prep will continue to support demand, kitchen labor turnover and food input inflation will constrain operating margins, and automated cooking robotics with compostable packaging are expected to expand commercial contracts through 2036.
- Driver: Digital kiosk ordering, mobile delivery integration, and centralized commissary meal preparation will continue to accelerate transaction throughput across urban dining networks through 2036.
- Restraint: Persistent line-cook staffing shortages, high commercial kitchen energy tariffs, and wholesale protein price swings will continue to compress independent restaurant margins through 2036.
- Opportunity: Automated induction and robotic frying stations paired with certified zero-waste packaging are expected to unlock multi-site corporate and transit catering tenders through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Dual-income urban households and hybrid office commuters increasingly rely on prepared takeaway meals and workplace grab-and-go counters, pulling volume into multi-unit food service brands. Integrating mobile app pre-ordering with kitchen display routing lets a compact storefront process twice as many lunch tickets per square meter as a traditional sit-down dining room. Synchronized mobile order throttling lifted peak-hour kitchen line output by 18% across multi-unit chains surveyed by Foodservice Consultants Society International in May 2025 [6]. Operators pairing rapid dispatch with leak-proof foodservice disposable supplies need vented lid designs that keep fried and baked items crisp during courier delivery.
Risk Assessment of the Food Service Industry: Operational and Formulation Friction
High line-cook attrition and volatile wholesale prices for edible oils, poultry, and dairy create severe budget friction for commercial kitchen managers. When skilled prep staff leave, restaurants face inconsistent portioning, higher plate waste, and slower ticket times during peak meal rushes. Combined kitchen labor and raw food inputs absorbed 63.4% of gross operating revenue across independent dining venues in July 2025 National Foodservice Distributors Association financial tracking [7]. Because lease agreements and commercial refrigeration tariffs remain fixed, independent operators often postpone kitchen expansion and rely on high-margin commercial food service coffee programs to offset narrow entree margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Municipal single-use plastic bans and corporate net-zero catering mandates are creating strong commercial openings for kitchen automation and sustainable takeaway packaging. Corporate campus and airport concession tenders increasingly score bidders on verified food-waste reduction and energy-efficient appliance deployment. Automated induction wok and robotic fryer installations cut kitchen cooking energy draw by 21% in high-volume transit concessions studied by the International Foodservice Manufacturers Association in September 2025 [8]. Hospitality vendors deploying programmable commercial cooking systems alongside pre-portioned commissary pouch ingredients gain a measurable cost advantage when bidding on multi-year institutional catering contracts.
Food Service Industry by Country (2026 to 2036)
Evaluated national growth trajectories between 2026 and 2036 span from 4.6% CAGR in Australia to a high of 7.1% CAGR in Japan. Restaurant chains and institutional caterers in each jurisdiction scale commissary prep, table automation, and reusable packaging at different speeds depending on local minimum wage awards, commercial electricity tariffs, and public nutrition laws.
Table 7: Country CAGR and Primary Growth Levers for the Food Service Industry (CAGR percentage and operational drivers), 2026 to 2036
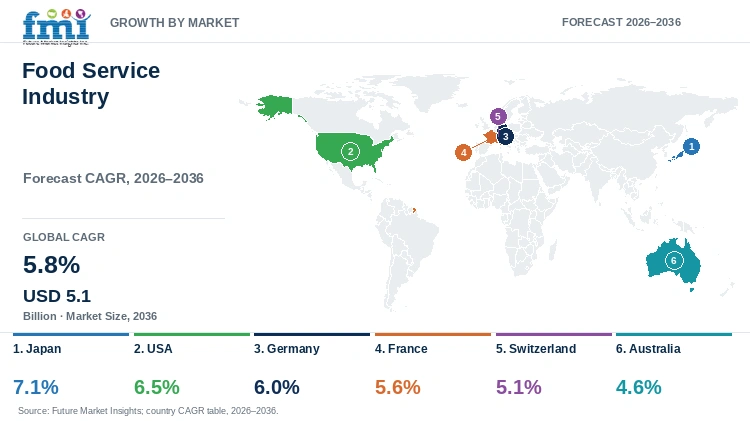
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 7.1% | Automated conveyor dining lanes, table payment terminals, and single-diner express booths |
| USA | 6.5% | Drive-thru voice AI automation, mobile app loyalty routing, and ghost-kitchen commissaries |
| Germany | 6.0% | DGE-compliant workplace canteen contracts and energy-efficient combi-steamer retrofits |
| France | 5.6% | Egalim sustainable public catering quotas and rapid bistro cook-chill lunch formats |
| Switzerland | 5.1% | Alpine resort gastronomy packages and private hospital precision dietary catering |
| Australia | 4.6% | Specialty daytime cafe chains and state-mandated compostable takeaway packaging adoption |
Source: Future Market Insights analysis
Japan Food Service Industry Outlook (2026 to 2036)
Acute kitchen staffing shortages across urban prefectures have pushed Japanese restaurant chains to automate both front-of-house ordering and back-of-house dish assembly. Because single-person households dine out or pick up prepared meals multiple times a week, food service demand in Japan is forecast to rise at 7.1% CAGR over the forecast period, propelled by automated conveyor delivery lanes and self-checkout kiosks. Chain restaurant sales rose 11.4% year-on-year in October 2025 Japan Foodservice Association tracking on the strength of solo dining booths and digital table ordering [9]. High imported beef and cooking oil costs still pressure menu pricing, prompting chains to centralize broth production in regional commissaries.
Key takeaway: Japan posts a 7.1% CAGR through 2036 as restaurant chains deploy automated conveyor lanes and centralized broth commissaries to overcome kitchen labor deficits.
USA Food Service Industry Outlook (2026 to 2036)
National quick-service franchises and multi-state contract caterers anchor United States foodservice volume by standardizing menu ingredients across thousands of suburban and interstate locations. Demand in the USA is projected to expand at 6.5% CAGR from 2026 to 2036, underpinned by multi-lane drive-thru voice automation, loyalty app order batching, and hospital dietary outsourcing. Food-away-from-home prices advanced 3.9% year-on-year in September 2026 USDA Economic Research Service tracking as operators absorbed higher commercial lease and utility expenses [10]. To protect store-level margins without shrinking portion sizes, American restaurant brands are shifting cold-prep and marination work to regional commissary hubs.
Key takeaway: Multi-lane drive-thru digitization and regional commissary prep keep the USA on a 6.5% CAGR trajectory through 2036.
Germany Food Service Industry Outlook (2026 to 2036)
German corporate canteens, university mensas, and hospital kitchens operate under strict federal sustainability and reusable packaging mandates that set the market apart from standard fast-food economies. Adoption of food service solutions in Germany is estimated to expand at 6.0% CAGR through 2036, reinforced by workplace lunch subsidies and compulsory reusable takeaway container rules under the Packaging Act. Survey results from the German Hotel and Restaurant Association (DEHOGA) in December 2025 showed that 41% of commercial caterers upgraded kitchen combi-steamers and digital catering management software to lower electricity and food waste bills [11]. Rising statutory minimum wages still squeeze independent gasthaus operators, encouraging broader reliance on pre-calibrated chilled meal components.
Key takeaway: Combi-steamer retrofits and mandatory reusable takeaway packaging support Germany's 6.0% CAGR across corporate and public canteens through 2036.
France Food Service Industry Outlook (2026 to 2036)
Public and corporate catering contracts in France are legally bound by the Egalim law, which requires at least 50% sustainable or quality-certified ingredients and 20% organic products by value. Revenue from food service sales in France is projected to rise at 5.6% CAGR over the assessment period, aided by shortened midday work breaks that favor rapid casual brasseries and gourmet bakery lunch counters. Weekday business-district lunch ticket volumes across metropolitan France grew 6.8% in January 2026 according to the French National Hospitality Union (GHR) [12]. Because traditional chefs resist fully frozen meals, French suppliers win accounts by delivering fresh vacuum-cooked sous-vide proteins and regional sauces.
Key takeaway: Egalim sustainable sourcing quotas and sous-vide bistro lunch formats anchor France's 5.6% CAGR from 2026 to 2036.
Switzerland Food Service Industry Outlook (2026 to 2036)
Switzerland's food service industry outlook is anticipated to advance at 5.1% CAGR over the assessment period, linked to high per-capita dining expenditure, year-round alpine hospitality, and premium private clinic catering. Because Swiss agricultural border tariffs keep imported meat and dairy expensive, domestic restaurant kitchens face some of the highest raw ingredient and culinary wage structures in Europe. Swiss hotel and medical-wellness dining outlets recorded a 7.4% revenue gain in February 2026 GastroSuisse industry benchmarking by pairing certified regional produce with automated regeneration ovens [13]. Operators offset high kitchen labor costs by procuring precisely portioned chilled gourmet components that require minimal on-site brigade staffing.
Key takeaway: Precision regeneration ovens and alpine medical-wellness hospitality enable Swiss operators to manage high kitchen wages and achieve a 5.1% CAGR through 2036.
Australia Food Service Industry Outlook (2026 to 2036)
Australia's commercial dining sector is anchored by an early-morning specialty cafe culture, coastal tourism clubs, and state-level single-use plastic prohibitions that require immediate packaging compliance. Demand across the Australia food service industry sector is expected to increase at 4.6% CAGR through 2036, enabled by daytime breakfast and grab-and-go lunch traffic across Sydney, Melbourne, and Brisbane. Metropolitan cafe and quick-service breakfast transactions expanded 5.9% year-on-year in March 2026 Restaurant & Catering Industry Association of Australia data despite higher commercial electricity rates [14]. Weekend penalty wage rates under national hospitality awards still limit late-night kitchen hours, prompting operators to pair pre-prepped commissary bakery items with certified compostable foodservice packaging.
Key takeaway: Daytime specialty cafe turnover and state single-use plastic bans shape Australia's 4.6% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the food service industry?
Compass Group PLC, Sodexo S.A., Aramark, Sysco Corporation, US Foods Holding Corp., Performance Food Group Company, Bidfood, and Elior Group are the notable companies active in the food service industry.
Institutional dining clients and restaurant chains select suppliers based on whether they need turnkey kitchen management or multi-temperature wholesale ingredient delivery. Compass Group PLC, Sodexo S.A., Aramark, and Elior Group staff and operate corporate, hospital, university, and defense dining facilities under multi-year service agreements. Sysco Corporation, US Foods Holding Corp., Performance Food Group Company, and Bidfood run refrigerated warehouse fleets that supply commercial kitchens with portioned proteins, fresh produce, and dry goods. Cold-chain delivery punctuality, allergen lot tracking, and automated inventory software decide contract renewals.
- Global Contract Catering Operators: Compass Group PLC, Sodexo S.A., Aramark, and Elior Group manage end-to-end kitchen staffing, menu engineering, and commissary meal production.
- North American Broadline Distributors: Sysco Corporation, US Foods Holding Corp., and Performance Food Group Company link temperature-controlled warehouse fleets with digital kitchen ordering platforms.
- International Multi-Temperature Foodservice Supply: Bidfood supplies independent restaurants, hotels, and institutional caterers across Europe, Asia-Pacific, and emerging regional corridors.
Competitive Benchmarking: Food Service Industry
Table 8: Competitive Benchmarking for the Food Service Industry (qualitative capability ratings), 2026
| Company | Contract Catering Scale | Cold-Chain Distribution Depth | Digital Kitchen & Ordering Tech | Geographic Reach |
|---|---|---|---|---|
| Compass Group PLC | High | Medium | High | High |
| Sodexo S.A. | High | Medium | High | High |
| Aramark | High | Medium | High | High |
| Sysco Corporation | Medium | High | High | High |
| US Foods Holding Corp. | Medium | High | High | Medium |
| Performance Food Group Company | Medium | High | Medium | Medium |
| Bidfood | Medium | High | Medium | High |
| Elior Group | High | Medium | Medium | Medium |
Scoring basis: Ratings reflect documented operational capabilities across the four table columns. Contract Catering Scale separates direct operators of institutional cafeterias from wholesale ingredient suppliers. Cold-Chain Distribution Depth measures company-owned multi-temperature warehouse and fleet density, while Digital Kitchen & Ordering Tech tracks unattended micro-market and AI inventory software rollouts.
Key Developments in the Food Service Industry
- Aramark deployed automated robotic pizza and hot-entree assembly stations across 18 United States university campus dining halls in January 2026 to extend late-night meal service without adding overnight kitchen shifts [15].
- Independent dining operators across North America gained access to an AI-driven restaurant inventory replenishment and menu-costing module launched by Sysco Corporation in October 2025 [16].
- Certified low-carbon, plant-forward patient and staff menus were expanded across 420 European healthcare and corporate catering sites by Sodexo S.A. in July 2025 [17].
Key Players in the Food Service Industry
Global Contract Catering Operators
- Compass Group PLC
- Sodexo S.A.
- Aramark
- Elior Group
Broadline Foodservice Distributors
- Sysco Corporation
- US Foods Holding Corp.
- Performance Food Group Company
International Hospitality Supply Platforms
- Bidfood
Food Service Industry - Report Scope
As per FMI, this study tracks commercial food service catering and wholesale distribution revenues across the three core segmentation axes while excluding household retail grocery purchases and unmonitored street vending.
Table 9: Report Scope for the Food Service Industry (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from food service ingredients, prepared meal formats, and contract catering supplies sold across retail dining, commercial food plants, and institutional hospitality channels. Excludes household grocery retail outside foodservice channels. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, USA, Germany, France, Switzerland, Australia, and additional countries in the full report |
| Key Companies Covered | Compass Group PLC, Sodexo S.A., Aramark, Sysco Corporation, US Foods Holding Corp., Performance Food Group Company, Bidfood, Elior Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Food Service Industry - Research Methodology
Table 10: Research Methodology for the Food Service Industry (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with executive chefs, contract catering directors, broadline foodservice distributors, restaurant franchise operators, and institutional procurement heads across the value chain to validate menu trends, kitchen automation economics, and purchasing decisions. |
| Secondary Research | Secondary research included government food-away-from-home expenditure series, national restaurant association bulletins, public hygiene advisories, corporate annual filings, investor presentations, and commercial kitchen equipment registries. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 assessment period were developed using top-down and bottom-up models reconcilable against commercial outlet counts, daily meal throughput, and wholesale distribution turnover. |
| Data Triangulation and Validation | Estimates were cross-checked against national hospitality employment series, agricultural wholesale price indices, and audited corporate foodservice revenues to ensure consistency without double counting adjacent grocery categories. |
Food Service Industry Market by Segments
By Product Type / Grade
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
By Processing State
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
By End-Use Application
- Direct Retail Consumer Consumption
- Commercial Food Manufacturing Plants
- Food Service & Hospitality
Food Service Industry by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2026, June 18). Food expenditure series: Total food-away-from-home spending in 2025. USDA Economic Research Service Data Products.
- [2] Centers for Disease Control and Prevention. (2026, January 18). Food service guidelines for federal, state, and institutional facilities. U.S. Department of Health and Human Services CDC Nutrition.
- [3] European Food Safety Authority. (2025, March 14). Microbiological hygiene and temperature control in institutional cook-chill catering. EFSA Supporting Publications, 22(3), 112-128.
- [4] U.S. Bureau of Labor Statistics. (2026, April 10). Industries at a glance: Food services and drinking places (NAICS 722) workforce benchmarks. U.S. Department of Labor BLS Industry Data.
- [5] National Restaurant Association. (2025, February 24). 2025 state of the restaurant industry: Digital kiosk and off-premise traffic benchmarks. National Restaurant Association Research Division.
- [6] Foodservice Consultants Society International. (2025, May 19). Digital kitchen display throttling and mobile commerce throughput study. FCSI Global Hospitality Review, 19(2), 44-58.
- [7] National Foodservice Distributors Association. (2025, July 15). Wholesale food input and kitchen labor cost benchmarking report. NFDA Economic Bulletins.
- [8] International Foodservice Manufacturers Association. (2025, September 22). Commercial kitchen robotics, automated induction ranges, and utility efficiency. IFMA Operational Reports.
- [9] Japan Foodservice Association. (2025, October 20). Monthly chain restaurant revenue and automated conveyor dining survey. JFNet Statistical Releases.
- [10] U.S. Department of Agriculture, Economic Research Service. (2026, September 25). Food price outlook: Summary findings for food-away-from-home indices. USDA ERS Food Price Outlook.
- [11] German Hotel and Restaurant Association (DEHOGA). (2025, December 11). Commercial kitchen energy efficiency and institutional catering survey 2025. DEHOGA Bundesverband Publications.
- [12] Groupement des Hotelleries et Restaurations de France (GHR). (2026, January 21). Commercial restaurant spending, Egalim sourcing, and weekday lunch trends. GHR Economic Observatory.
- [13] GastroSuisse. (2026, February 16). Swiss hotel and restaurant economic report: Regional gastronomy and medical catering benchmarks. GastroSuisse Zurich Publications.
- [14] Restaurant & Catering Industry Association of Australia. (2026, March 12). Australian cafe, takeaway packaging, and hospitality industry benchmarks 2026. R&CA Sydney Industry Reports.
- [15] Aramark. (2026, January 14). Deployment of automated robotic pizza and hot-entree stations across university campus dining halls. Aramark Corporate Newsroom.
- [16] Sysco Corporation. (2025, October 28). Launch of AI-powered inventory replenishment and menu costing platform for independent restaurants. Sysco Investor Relations.
- [17] Sodexo S.A. (2025, July 17). Expansion of certified low-carbon plant-forward menus across European healthcare and corporate sites. Sodexo Group Press Releases.
- [18] Compass Group PLC. (2025, March 19). Rollout of Frictionless 24-hour unattended micro-kitchen concepts for corporate offices. Compass Group Corporate Announcements.
- [19] US Foods Holding Corp. (2025, November 12). Expansion of MOXē digital order and portion-controlled protein program for multi-unit operators. US Foods News Releases.
- [20] Performance Food Group Company. (2026, February 09). Commissioning of automated multi-temperature cold-storage distribution center in Texas. PFG Corporate News.
- [21] Bidfood. (2025, August 26). Introduction of carbon-labeled wholesale catering catalog across European and Asia-Pacific depots. Bidfood Sustainability Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food service industry in 2026 and what is forecast for 2036?
- Which kitchen labor and off-premise ordering pressures support demand for centralized food service formats?
- Why does Standard Commercial Grade lead the product type / grade category?
- Why does Fresh / Ambient Packaged command the largest processing state share globally?
- How do growth rates differ across Japan, the USA, Germany, France, Switzerland, and Australia?
- Which leading contract caterers and broadline distributors supply commercial kitchens today?
- What limits kitchen automation adoption or supplier switching in the food service industry?
- What should institutional buyers evaluate before awarding a multi-year food service contract?
Frequently Asked Questions
How large is the Food Service Industry expected to be in 2026?
Global food service industry valuation is estimated to reach USD 2.9 billion in 2026, rising from USD 2.7 billion in 2025. The market is projected to expand further and reach USD 5.1 billion by 2036 as multi-unit operators scale centralized commissary prep.
What CAGR is forecast for the Food Service Industry through 2036?
As per FMI, the food service industry is projected to grow at a 5.8% CAGR from 2026 to 2036. Growth is supported by automated digital ordering kiosks, drive-thru lane optimization, and outsourced healthcare and workplace catering contracts.
Which product type / grade segment holds a notable share in 2026?
Standard Commercial Grade is projected to hold 44.6% of product type / grade demand in 2026. The segment benefits from uniform batch viscosity, predictable portion yields, and multi-year wholesale cost stability across institutional cafeterias.
Which processing state segment leads the Food Service Industry in 2026?
Fresh / Ambient Packaged goods are estimated to account for 51.0% of processing state revenue in 2026. Demand is supported by zero defrosting delays, lower freezer compressor electricity draw, and rapid morning prep station setup.
Which country has a notable expansion outlook during the forecast period?
FMI finds that Japan is projected to expand at a 7.1% CAGR during the 2026 to 2036 assessment period. Growth is supported by acute kitchen staffing shortages that accelerate adoption of automated conveyor dining lanes and robotic noodle cookers.
Which companies are active in the Food Service Industry during 2026?
Notable active companies include Compass Group PLC, Sodexo S.A., Aramark, Sysco Corporation, US Foods Holding Corp., Performance Food Group Company, Bidfood, and Elior Group. These participants focus on commissary automation, AI inventory ordering, and multi-temperature fleet logistics.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Commercial Food Manufacturing Plants
- Food Service & Hospitality
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- Nordics
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Compass Group PLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sodexo S.A.
- Aramark
- Sysco Corporation
- US Foods Holding Corp.
- Performance Food Group Company
- Bidfood
- Elior Group
- Compass Group PLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


