
- Market Size (2026)
- USD 13.5 Bn
- Forecast (2036)
- USD 21.8 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Vegan Chocolate Market in 2026?
The vegan chocolate market is forecast to register a CAGR of 4.9% through 2036. Revenue increases from USD 12.9 billion in 2025 to USD 13.5 billion in 2026 before reaching USD 21.8 billion by 2036.
Eliminating bovine milk powder from confectionery lines requires chocolatiers to re-engineer fat crystallization and particle milling so plant-based bars snap and melt like traditional dairy recipes. Dark vegan chocolate captures 45.0% of 2026 product type demand alongside culinary baking chocolate across commercial kitchens, with FMI data suggesting that global revenue expands from USD 12.9 billion in 2025 to USD 13.5 billion in 2026 and reaches USD 21.8 billion by 2036 at a 4.9% CAGR (USD 8.3 billion in added revenue). International Cocoa Organization statistics published in February 2026 documented tight global cocoa bean stocks following the 2024/25 supply deficit, keeping raw cocoa liquor and butter costs elevated for confectionery processors [1].
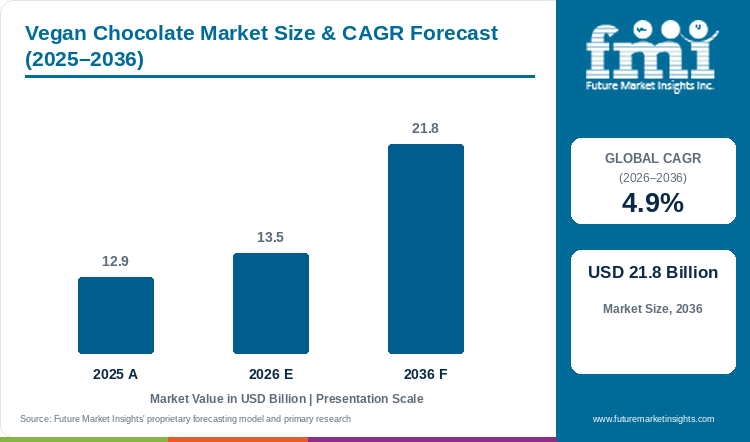
Key Market Trends & Insights
- By product type: Dark vegan chocolate held the leading share of 45.0% in 2026, supported by naturally dairy-free high-cacao recipes that need no milk fat substitution.
- By sweetener formulation: With a 58.0% share in 2026, cane sugar led the category, reflecting predictable sucrose crystal tempering and clean caramel notes during conching.
- By distribution channel: Supermarkets and hypermarkets represented 43.0% of demand in 2026, driven by dedicated free-from grocery aisles and private-label plant-based tablet launches.
Regional Highlights
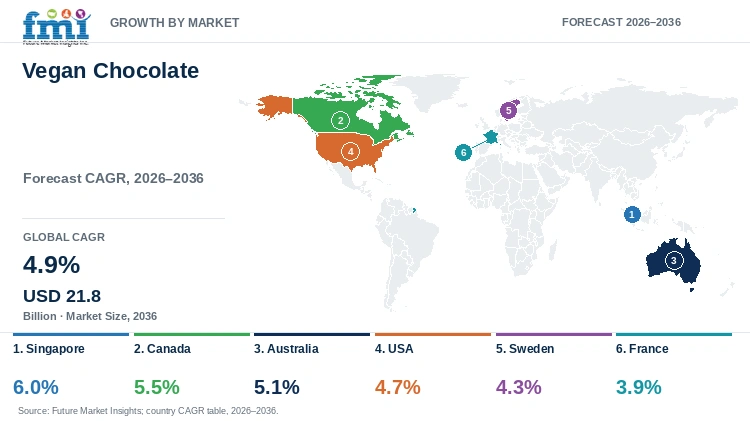
- Fastest-growing evaluated country: Singapore, at 6.0% CAGR from 2026 to 2036.
- By country: Canada at 5.5%, Australia at 5.1%, the USA at 4.7%, and Sweden at 4.3% follow, while France records the lowest evaluated CAGR at 3.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vegan Chocolate Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 12.9 billion |
| Estimated Market Size in 2026 | USD 13.5 billion |
| Projected Market Size by 2036 | USD 21.8 billion |
| CAGR, 2026 to 2036 | 4.9% |
| Added Revenue, 2026 to 2036 | USD 8.3 billion |
Strict undeclared milk-allergen recall enforcement in North America and year-round tropical humidity across Southeast Asian grocery distribution force chocolatiers to adapt both factory sanitation and cold-chain packaging. Shared moulding lines that run conventional milk chocolate during the week risk trace casein carry-over unless processors install segregated dairy-free conching tanks and dedicated pipelines. Updated food allergen labeling guidance issued by the U.S. Food and Drug Administration in March 2025 emphasized that undeclared milk remains a primary trigger for confectionery recalls [2]. Manufacturers are therefore pairing hydrolyzed oat flour and emulsified plant milk inside dedicated allergen-validated rooms to win grocery private-label contracts.
Cocoa Processing and Confectionery Output Sizing
Table 2: Cocoa Grindings and Dairy-Free Output Sizing for the Vegan Chocolate Market (USD billion and thousand metric tons), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 12.9 | 13.5 | 21.8 |
| Finished vegan chocolate volume (thousand metric tons) | 890.0 to 940.0 | 925.0 to 975.0 | 1,420.0 to 1,510.0 |
| Cocoa liquor & butter utilized (thousand metric tons) | 510.0 to 545.0 | 530.0 to 565.0 | 810.0 to 865.0 |
| Average retail realization per kilogram (USD) | 13.7 to 14.5 | 13.8 to 14.6 | 14.4 to 15.3 |
Grindings scope note: Volume estimates cover finished molded tablets, filled truffles, baking chips, and industrial dairy-free couverture blocks across retail and commercial pastry channels.
Per Capita & Retail Confectionery Spend Sizing
Five-roll refining below 20 microns allows plant-based chocolatiers to mill gluten-free oat, toasted almond, and rice powders down to a particle size that melts smoothly on the palate without gritty fiber residue. Supermarkets now merchandise dairy-free bars and boxed vegan confectionery assortments inside mainstream confectionery aisles rather than isolating them in small health-food corners. Repeat purchases from lactose-intolerant households and seasonal holiday gifting boxes sustain high retail shelf turnover.
Table 3: Per Capita and Household Spending Indicators for the Vegan Chocolate Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 1.57 | 1.63 | 2.44 |
| Spend per 1,000 people (USD) | 1,567.4 | 1,626.5 | 2,435.8 |
| Annual spend per regular dairy-free household (USD) | 42.0 to 54.0 | 44.0 to 56.0 | 62.0 to 78.0 |
Table 4: Segment & Channel Revenue Allocation for the Vegan Chocolate Market (USD billion and percentages), mixed reporting years from 2025 to 2036
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 13.5 billion | Report value |
| Dark vegan chocolate revenue, 2026 | USD 6.1 billion | 45.0% share |
| Cane sugar formulation revenue, 2026 | USD 7.8 billion | 58.0% share |
| Supermarkets & hypermarkets revenue, 2026 | USD 5.8 billion | 43.0% share |
Analyst Perspective
"Enzymatically treated oat powders and segregated refining rooms allow confectionery brands to win mainstream supermarket free-from space. Elevated West African cocoa butter prices and strict below-5-ppm milk allergen swabbing still compress smaller chocolatier margins."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the vegan chocolate market segmented?
The vegan chocolate market is segmented by product type, sweetener formulation, distribution channel, and region. In 2026, dark vegan chocolate is projected at 45.0% of product type, cane sugar at 58.0% of sweetener formulation, and supermarkets and hypermarkets at 43.0% of distribution channel.
By product type: Dark vegan chocolate, milk-style oat / almond chocolate, and white vegan chocolate.
By sweetener formulation: Cane sugar, coconut sugar and date powder, and stevia and monk fruit blend.
By distribution channel: Supermarkets and hypermarkets, specialty organic retailers, and online direct-to-consumer.
Why does Dark Vegan Chocolate lead the product type category?
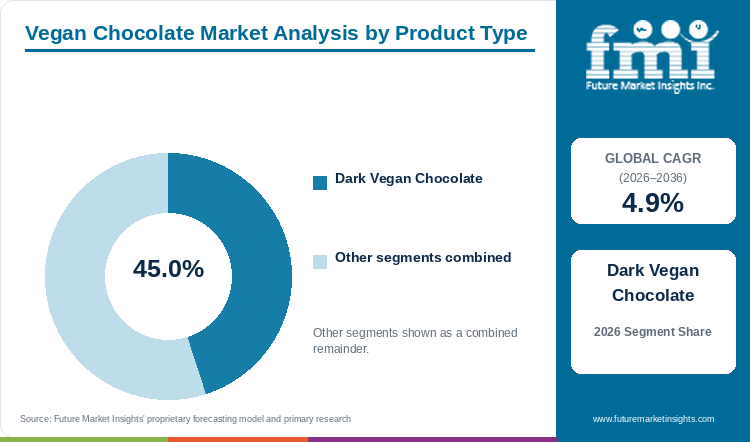
Dark vegan chocolate is set to lead product type with 45.0% share in 2026, reinforced by naturally dairy-free cacao recipes.
Table 5: Product Type Share for the Vegan Chocolate Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Dark Vegan Chocolate | 45.0% |
| Other Segments Combined | 55.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Vegan Chocolate Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.9% |
| Leading Segment | Dark Vegan Chocolate |
High-cacao dark formulations between 60% and 85% cocoa solids generate nearly half of global vegan chocolate turnover because cocoa mass, cocoa butter, and sugar require no dairy fat replacers to temper into a glossy bar. Proper polymorph V beta-crystal tempering gives dark tablets a clean snap and strong resistance to warm shelf temperatures. An FMI analyst notes that industrial pastry kitchens purchase dark chocolate couverture blocks in ten-kilogram slabs to enrobe vegan croissants, ganaches, and ice cream bars. Trace milk protein on shared factory scrapers can still trigger precautionary allergen warnings unless processors run dedicated dark moulding lines.
- Dark vegan chocolate is set to lead product type with 45.0% share in 2026, reinforced by clean-label cocoa formulations and natural flavanol appeal.
- Technical guidance published by the European Cocoa Association in March 2025 established updated dairy allergen segregation and EUDR geolocation rules for European cocoa processors [3].
What makes Cane Sugar central to the sweetener formulation category?
Cane sugar is expected to command 58.0% of sweetener formulation revenue in 2026, enabled by reliable conching viscosity control.
Crystalline cane sugar remains the primary sweetener in vegan chocolate because sucrose crystals fracture cleanly inside five-roll refiners and release bound moisture evenly during dry conching. Specifying organic, non-bone-char-filtered cane sugar lets chocolatiers pass strict Vegan Action and Vegan Society audits at a lower ingredient cost than date powder or monk fruit blends. Sucrose also delivers the snap and caramel flavor profile expected across mainstream commercial chocolate products without the cooling sensation of erythritol. Coconut and date sugars contain higher hygroscopic invert syrups that thicken plastic viscosity during mixing, requiring extra cocoa butter or sunflower lecithin to flow through depositing pistons.
- Cane sugar is expected to command 58.0% of sweetener formulation revenue in 2026, enabled by predictable crystal tempering and bone-char-free vegan refining.
- The U.S. Department of Agriculture Economic Research Service Sugar and Sweeteners Outlook in September 2026 tracked tighter 2026/27 domestic cane and beet sugar supply balances impacting confectionery contract pricing [4].
What keeps Supermarkets & Hypermarkets ahead by distribution channel?
Supermarkets and hypermarkets are projected to hold 43.0% of distribution channel sales in 2026, backed by mainstream free-from aisle expansion.
Weekly grocery trips drive the largest share of vegan chocolate sales through supermarkets and hypermarkets as households pick up dairy-free tablets, peanut-butter cups, and baking chips alongside standard pantry items. Category managers increasingly group certified plant-based bars next to plant-based spreads and allergen-safe school snacks to lift multi-item checkout value. Major European and North American supermarket chains have also launched own-label oat-milk chocolate slabs priced within 15.0% of conventional dairy bars. Emerging bean-to-bar brands still have to fund promotional end-caps and hit strict weekly scan-rate targets to retain national grocery distribution.
- Supermarkets and hypermarkets are projected to hold 43.0% of distribution channel sales in 2026, backed by private-label vegan range launches and multi-bar promotional pricing.
- Retail tracking from the Plant Based Foods Association in May 2025 showed that mainstream grocery chains generated over 68.0% of plant-based confectionery and snack sales in the United States [5].
What are the drivers, restraints, and opportunities in the vegan chocolate market?
Lactose intolerance and allergen-free retail mandates drive recurring demand, whereas high West African cocoa bean costs and oat-powder rheology friction restrain margins, and single-origin traceable bars create premium value.
- Driver: Rising lactose intolerance awareness and mainstream grocery free-from aisle expansion pull oat-milk and dark vegan chocolate into weekly household purchases through 2036.
- Restraint: Elevated raw cocoa liquor and cocoa butter prices alongside plant-milk conching viscosity challenges compress margins for chocolatiers through 2036.
- Opportunity: Deforestation-free single-origin cacao traceability and micro-milled creamy plant couvertures unlock premium gifting and bakery supply contracts through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Lactose sensitivity, pediatric milk allergies, and flexitarian eating habits have turned dairy-free chocolate from a specialty health-store product into an everyday grocery staple. Shoppers who previously avoided bitter 85% dark bars are buying creamy milk-style tablets formulated with enzymatically hydrolyzed oat flour and roasted hazelnut paste. Confectionery groups are consequently reformulating classic molded chocolate confectionery into certified vegan sharing bags and seasonal hollow figures. In June 2025, the Specialty Food Association State of the Specialty Food Industry report ranked dairy-free and plant-based chocolate tablets among the fastest-expanding specialty confectionery lines [6].
Risk Assessment of the Vegan Chocolate Market: Operational and Formulation Friction
Structural harvest deficits and swollen-shoot virus infections across Côte d'Ivoire and Ghana have kept raw cocoa bean and pressed cocoa butter prices at historic highs, compressing margins for chocolate makers worldwide. Because vegan milk-style recipes cannot use inexpensive dairy whey or skim milk powder as a filler, formulators must add higher percentages of costly cocoa butter to coat porous oat and rice flour particles during conching. World Cocoa Foundation supply assessments in July 2025 noted that West African farmgate and export bean prices remained more than double 2022 baselines [7]. Smaller artisan chocolatiers face acute working-capital strain when financing forward cocoa butter inventories.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pairing polygon-mapped single-origin cacao with allergen-segregated oat and almond milk refining opens high-margin seasonal gifting and commercial bakery accounts. European Union Deforestation Regulation (EUDR) compliance and Fairtrade living-income audits require chocolate brands to prove farm-level geolocation across premium chocolate tablets. Fairtrade International expanded digital supply-chain verification tags across West African and Latin American cocoa cooperatives in September 2025 to verify deforestation-free plots and farmer income premiums [8]. According to Future Market Insights analysis, chocolatiers that print QR-verified farm origin data on compostable carton wrappers command premium shelf prices in department stores and travel retail.
Vegan Chocolate Market by Country (2026 to 2036)
High lactose sensitivity and specialty cafe gifting place Singapore at the front of the six profiled countries with a 6.0% CAGR through 2036, as noted by FMI, ahead of Canada (5.5%), Australia (5.1%), the United States (4.7%), Sweden (4.3%), and France (3.9%). Cold-chain protection against tropical fat bloom, school-safe allergen rules, and single-origin dark tablet traditions determine how brands formulate and package bars in each market.
Table 7: Country CAGR and Primary Growth Levers for the Vegan Chocolate Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Singapore | 6.0% | High lactose intolerance prevalence and premium specialty cafe gifting |
| Canada | 5.5% | CFIA allergen-free school snack demand and grocery private-label bars |
| Australia | 5.1% | Artisanal bakery couverture adoption and ethical plant-based retail |
| USA | 4.7% | Mainstream supermarket free-from aisles and direct-to-consumer bundles |
| Sweden | 4.3% | Fika coffee-break culture and Nordic organic fair-trade retail co-ops |
| France | 3.9% | High-cacao bean-to-bar ateliers and vegan patisserie couverture |
Source: Future Market Insights analysis
Singapore Vegan Chocolate Market Outlook (2026 to 2036)
High adult lactose malabsorption across Southeast Asian demographics paired with Changi Airport travel retail and Orchard Road boutique gifting propels Singapore at a 6.0% CAGR from 2026 to 2036. Premium supermarkets and specialty coffee chains stock imported European oat-milk truffles and single-origin dark tablets for corporate hampers. In May 2026, the Singapore Food Agency published its Singapore Food Statistics 2025 report highlighting import source diversification across high-value processed food and confectionery supply chains [9]. Year-round equatorial humidity above 80.0% rapidly triggers white fat bloom on untempered bars, so Singaporean importers rely on chilled micro-fulfillment hubs and hermetically sealed foil flow-wraps.
Key takeaway: Chilled micro-fulfillment logistics and duty-free luxury gifting make Singapore the fastest-growing vegan chocolate market profiled.
Canada Vegan Chocolate Market Outlook (2026 to 2036)
School-safe allergen policies and national grocery private-label ranges across Ontario, Quebec, and British Columbia support a 5.5% CAGR in Canada between 2026 and 2036. Parents and institutional buyers look for chocolate chips and snack bars produced in dedicated peanut-free and dairy-free facilities that meet strict Canadian Food Inspection Agency swabbing rules. Food and Consumer Products of Canada industry reviews in November 2025 recorded an 11.0% annual rise in retail sales of certified plant-based and allergen-free chocolate items [10]. Sub-zero winter highway freight across the prairies can crack tempered chocolate slabs, requiring heated insulated trailers for national grocery distribution.
Key takeaway: CFIA school-safe allergen compliance and supermarket private-label baking chips anchor Canadian vegan chocolate demand.
Australia Vegan Chocolate Market Outlook (2026 to 2036)
Melbourne and Sydney's third-wave coffee culture, where oat-milk flat whites are standard menu items, fuels a projected 5.1% CAGR for the Australian vegan chocolate sector through 2036. Independent patisseries, gelato makers, and major grocery chains purchase Rainforest Alliance certified dark and caramelized-oat chocolate blocks in high volume. Australian Industry Group confectionery benchmarking in January 2026 showed a 12.0% increase in dairy-free couverture orders among independent bakeries and cafes [11]. Summer highway temperatures exceeding 40 degrees Celsius across interstate trucking routes force Australian distributors to use phase-change gel packs and temperature-logged reefers.
Key takeaway: Oat-milk cafe pairing habits and bakery couverture orders drive Australian growth despite high summer refrigerated freight costs.
USA Vegan Chocolate Market Outlook (2026 to 2036)
Natural food co-ops, conventional supermarket free-from end-caps, and multi-bar online subscriptions drive a projected 4.7% CAGR across the United States vegan chocolate market from 2026 to 2036. American households actively buy paleo-friendly coconut-sugar dark tablets, oat-milk peanut butter cups, and allergen-free baking drops that exclude dairy, soy lecithin, and refined corn syrup. In December 2025, the National Confectioners Association reported that premium dark and plant-based chocolate lines generated over USD 420.0 million in tracked U.S. retail food channel sales [12]. High grocery slotting fees still push emerging chocolatiers to launch in natural channel chains and direct-to-consumer bundles before scaling into mass retail.
Key takeaway: Over USD 420.0 million in tracked U.S. retail sales rests on coconut-sugar dark bars and allergen-free baking chips.
Sweden Vegan Chocolate Market Outlook (2026 to 2036)
Daily fika coffee breaks and deep consumer familiarity with domestic enzymatic oat processing underpin a 4.3% CAGR for the Swedish vegan chocolate market through 2036. Shoppers in Stockholm, Gothenburg, and Malmö treat oat-powder milk chocolate tablets and Fairtrade pralines as mainstream confectionery rather than niche diet foods. Swedish Food Federation retail surveys in February 2026 documented an 8.0% rise in sales of KRAV-organic and Fairtrade-certified plant-based confectionery across Nordic grocery cooperatives [13]. Strict Nordic producer-responsibility fees on foil-plastic laminates are pushing Swedish chocolate makers into recyclable mono-paper wrappers.
Key takeaway: Domestic oat-processing expertise and KRAV-organic grocery standards keep Sweden at the forefront of Nordic plant-based confectionery.
France Vegan Chocolate Market Outlook (2026 to 2036)
Bean-to-bar dark chocolate connoisseurship and Parisian haute patisserie standards shape the French market, which is forecast to expand at a 3.9% CAGR between 2026 and 2036. French shoppers traditionally prefer 70% to 85% single-origin dark tablets that naturally contain no dairy, while artisanal pastry chefs are replacing heavy cream in truffles with stone-ground almond and Piedmont hazelnut praline emulsions. In March 2026, the Syndicat du Chocolat reported that dark tablets above 70% cacao represented over one-third of French retail tablet sales alongside rising vegan ganache launches [14]. Because French decrees strictly forbid vegetable fat substitutes under standard chocolate naming, producers rely on 100% pure cocoa butter and fine nut pastes.
Key takeaway: High-cacao single-origin dark tablets and nut-praline patisserie ganaches define French vegan chocolate formulation.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the vegan chocolate market?
Lindt & Sprüngli, Barry Callebaut, Mondelēz International, Mars Incorporated, Nestlé S.A., Ritter Sport, Plamil Foods, and Hu Kitchen are the notable companies in the vegan chocolate market.
West African and Latin American cocoa bean origination, five-roll refining scale, and dedicated allergen-free moulding rooms determine which confectionery suppliers win national supermarket and industrial bakery accounts. Barry Callebaut supplies dairy-free Plant Craft couvertures and cocoa butter to commercial bakeries worldwide, while Lindt & Sprüngli, Mondelēz International, Mars Incorporated, and Nestlé S.A. market branded oat-milk and dark tablets across grocery chains. Ritter Sport, Plamil Foods, and Hu Kitchen focus on segregated milk-free factories, roasted nut pastes, and coconut-sugar low-calorie chocolate bars for natural and free-from retail channels.
- Global Confectionery & Industrial Cocoa Leaders: Barry Callebaut, Lindt & Sprüngli, Mondelēz International, Mars Incorporated, and Nestlé S.A. operate global cacao grinding, dairy-free couverture, and mass-retail bar lines.
- European Certified Vegan Tablet Specialists: Ritter Sport and Plamil Foods run dedicated dairy-free conching and moulding lines for European grocery and health-store channels.
- Clean-Label & Paleo Confectionery Pioneers: Hu Kitchen formulates organic dark and plant-based chocolate bars sweetened with unrefined coconut sugar for natural and omnichannel retail.
Competitive Benchmarking: Vegan Chocolate Market
Table 8: Competitive Benchmarking for the Vegan Chocolate Market (qualitative capability ratings), 2026
| Company | Dairy-Free Portfolio Breadth | Allergen-Segregated Manufacturing | Retail / B2B Channel Access | Geographic Reach |
|---|---|---|---|---|
| Lindt & Sprüngli | High | High | High | High |
| Barry Callebaut | High | High | High | High |
| Mondelēz International | Medium | Medium | High | High |
| Mars Incorporated | Medium | Medium | High | High |
| Nestlé S.A. | Medium | High | High | High |
| Ritter Sport | High | High | High | High |
| Plamil Foods | High | High | Medium | Medium |
| Hu Kitchen | High | High | High | Medium |
Scoring basis: Qualitative ratings benchmark verified confectionery capabilities across four operational criteria. Dairy-Free Portfolio Breadth is scored High where a manufacturer offers dark, oat/almond milk-style, white, and baking formats, and Medium where limited to dark tablets or selected bars. Allergen-Segregated Manufacturing is High when dedicated 100% milk-free factories or validated segregated refining lines eliminate cross-contact warnings. Retail / B2B Channel Access distinguishes suppliers with nationwide grocery end-caps or global bakery distribution (High) from specialty-channel brands (Medium), while Geographic Reach compares worldwide export footprints against single-region sales concentration.
Key Developments in the Vegan Chocolate Market
- Ritter Sport expanded its dedicated plant-based chocolate square production capacity in Germany during January 2026 to supply roasted peanut and salted caramel vegan bars across European supermarkets [15].
- Mondelēz International introduced Fairtrade-certified vegan dark and almond-paste chocolate gift assortments in October 2025 across European and travel retail channels [16].
- During June 2025, Barry Callebaut expanded its dairy-free Plant Craft oat chocolate couverture and micro-milled choco-base production in North America and Europe for commercial bakeries [17].
Key Players in the Vegan Chocolate Market
Global Confectionery & Industrial Cocoa Leaders
- Lindt & Sprüngli
- Barry Callebaut
- Mondelēz International
- Mars Incorporated
- Nestlé S.A.
European Certified Vegan Tablet Specialists
- Ritter Sport
- Plamil Foods
Clean-Label & Paleo Confectionery Pioneers
- Hu Kitchen
Vegan Chocolate Market - Report Scope
Table 9: Report Scope for the Vegan Chocolate Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Sweetener Formulation; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from certified vegan and dairy-free dark, plant-milk (oat, almond, rice, coconut, hazelnut), and white chocolate bars, pralines, baking drops, and B2B vegan chocolate couvertures sold within the listed segmentation. Excludes conventional dairy milk chocolate and raw unroasted cocoa beans. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Singapore, Canada, Australia, USA, Sweden, France, and additional countries in the full report |
| Key Companies Covered | Lindt & Sprüngli, Barry Callebaut, Mondelēz International, Mars Incorporated, Nestlé S.A., Ritter Sport, Plamil Foods, Hu Kitchen |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Vegan Chocolate Market - Research Methodology
Table 10: Research Methodology for the Vegan Chocolate Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with industrial cocoa processors, master chocolatiers, allergen quality-assurance managers, supermarket free-from category buyers, and plant-based food scientists to validate recipe reformulation, cocoa butter pricing impacts, and retail velocity. |
| Secondary Research | Secondary research included corporate annual reports, International Cocoa Organization (ICCO) statistical bulletins, U.S. FDA allergen labeling guidance, USDA sugar and sweeteners reports, European Cocoa Association sustainability releases, and retail scanner datasets. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models tracking dairy-free chocolate tonnage, retail price per kilogram across dark and plant-milk tiers, and B2B couverture demand. |
| Data Triangulation and Validation | Estimates were cross-checked against dedicated dairy-free refining capacity, cocoa liquor grindings, certified vegan SKU counts in major grocers, and company confectionery segment disclosures to prevent double counting conventional dark chocolate without vegan positioning. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's plant-based confectionery econometric model, calibrating evaluated national growth rates against the 4.9% global baseline through verified dairy-free chocolate bar retail placements, oat and coconut milk conching technology adoption, and ethical vegan consumer purchasing. |
| Operational Benchmark Traceability | Operational benchmarks (finished vegan chocolate volume, cocoa butter substitution ratios, and micro-particle refining yields) represent modeled estimates synthesized from ICCO cocoa bulletins, FDA food allergen guidance, USDA sweetener outlooks, and commercial chocolaterie disclosures. |
Vegan Chocolate Market by Segments
Vegan Chocolate Market segmented by Product Type:
- Dark Vegan Chocolate
- Milk-Style Oat / Almond Chocolate
- White Vegan Chocolate
Vegan Chocolate Market segmented by Sweetener Formulation:
- Cane Sugar
- Coconut Sugar & Date Powder
- Stevia & Monk Fruit Blend
Vegan Chocolate Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Organic Retailers
- Online Direct-to-Consumer
Vegan Chocolate Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Sweden
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Singapore
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Cocoa Organization. (2026, February 27). February 2026 quarterly bulletin of cocoa statistics and global bean stock assessments. ICCO Statistical Publications.
- [2] U.S. Food and Drug Administration. (2025, March 26). Frequently asked questions on food allergen labeling guidance for industry and undeclared milk controls in confectionery. FDA Center for Food Safety and Applied Nutrition.
- [3] European Cocoa Association. (2025, March 19). Technical guidance on dairy allergen segregation and EUDR deforestation traceability in cocoa processing. ECA Regulatory Technical Bulletins.
- [4] U.S. Department of Agriculture Economic Research Service. (2026, September 18). Sugar and sweeteners outlook: Domestic cane and beet sugar supply and confectionery demand. USDA ERS Market Outlook Reports.
- [5] Plant Based Foods Association. (2025, May 14). U.S. retail sales benchmark for plant-based confectionery and supermarket free-from aisles. PBFA Retail Market Insights.
- [6] Specialty Food Association. (2025, June 17). State of the specialty food industry: Dairy-free and plant-based chocolate subcategory performance. SFA Annual Research Reports.
- [7] World Cocoa Foundation. (2025, July 22). West African cocoa supply deficit, swollen-shoot disease management, and farmgate price review. WCF Global Market Updates.
- [8] Fairtrade International. (2025, September 16). Digital supply-chain traceability and living-income reference price verification in cocoa cooperatives. Fairtrade Cocoa Standards Publications.
- [9] Singapore Food Agency. (2026, May 08). Singapore food statistics 2025: Import diversification and food safety standards across processed food supply chains. SFA Official Publications.
- [10] Food and Consumer Products of Canada. (2025, November 18). Canadian grocery retail performance of allergen-free and plant-based confectionery products. FCPC Sector Economic Reviews.
- [11] Australian Industry Group Confectionery Sector. (2026, January 15). Artisanal bakery and specialty cafe adoption of plant-based chocolate couverture in Australia. Ai Group Confectionery Benchmarks.
- [12] National Confectioners Association. (2025, December 11). State of treating: Premium dark and plant-based chocolate retail channel sales in the United States. NCA Industry Economic Reports.
- [13] Swedish Food Federation. (2026, February 19). Nordic consumption trends for KRAV-organic and oat-based confectionery products. Livsmedelsföretagen Market Surveys.
- [14] Syndicat du Chocolat. (2026, March 12). French retail sales of high-cacao dark tablets and plant-based patisserie ganaches. Chiffres Clés du Chocolat en France.
- [15] Alfred Ritter GmbH & Co. KG. (2026, January 21). Expansion of dedicated vegan chocolate square production capacity in Waldenbuch, Germany. Ritter Sport Corporate Newsroom.
- [16] Mondelēz International, Inc. (2025, October 23). Introduction of Fairtrade-certified vegan dark and almond-paste seasonal chocolate assortments. Mondelēz Global Press Releases.
- [17] Barry Callebaut AG. (2025, June 19). Expansion of dairy-free Plant Craft oat couverture and choco-base refining lines in North America and Europe. Barry Callebaut Corporate Announcements.
- [18] Chocoladefabriken Lindt & Sprüngli AG. (2025, March 28). Investment in segregated oat-milk chocolate refining and moulding lines in Europe for HELLO Vegan bars. Lindt & Sprüngli Operational Updates.
- [19] Mars, Incorporated. (2025, August 14). Expansion of certified vegan oat-milk chocolate bar and truffle formats across UK and European grocery channels. Mars Wrigley Product News.
- [20] Plamil Foods Ltd. (2025, November 06). Commissioning of solar-powered allergen-free white and milk-style vegan chocolate moulding lines in Kent, UK. Plamil Foods Corporate Releases.
- [21] Nestlé S.A. (2026, February 10). Rollout of Rainforest Alliance certified plant-based chocolate tablets and bakery inclusions in Europe and Latin America. Nestlé Confectionery Announcements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vegan chocolate market in 2026 and what is forecast for 2036?
- Which allergen-free and dietary shifts support demand for vegan chocolate?
- Why does Dark Vegan Chocolate lead the product type category?
- Why does Cane Sugar hold the largest share by sweetener formulation?
- How do growth rates differ across Singapore, Canada, Australia, and the USA?
- Which leading companies manufacture vegan chocolate bars and couvertures today?
- What limits adoption or margin expansion in the vegan chocolate market?
- What should grocery and bakery buyers evaluate before qualifying a vegan chocolate supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Dark Vegan Chocolate
- Milk-Style Oat / Almond Chocolate
- White Vegan Chocolate
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sweetener Formulation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sweetener Formulation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sweetener Formulation, 2026 to 2036
- Cane Sugar
- Coconut Sugar & Date Powder
- Stevia & Monk Fruit Blend
- Y-o-Y Growth Trend Analysis By Sweetener Formulation, 2021 to 2025
- Absolute $ Opportunity Analysis By Sweetener Formulation, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Organic Retailers
- Online Direct-to-Consumer
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Sweden
- Benelux
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Australia and New Zealand
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Singapore
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Sweetener Formulation
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lindt & Sprüngli
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Barry Callebaut
- Mondelēz International
- Mars Incorporated
- Nestlé S.A.
- Ritter Sport
- Plamil Foods
- Hu Kitchen
- Lindt & Sprüngli
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Sweetener Formulation, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Sweetener Formulation
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Sweetener Formulation
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Sweetener Formulation
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Sweetener Formulation
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Sweetener Formulation
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Sweetener Formulation
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Sweetener Formulation
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Sweetener Formulation, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Sweetener Formulation, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Sweetener Formulation
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Vegan Chocolate Market expected to be in 2026?
Global vegan chocolate sales are estimated to reach USD 13.5 billion in 2026, rising from USD 12.9 billion in 2025. The market is projected to expand further and reach USD 21.8 billion by 2036.
What CAGR is forecast for the Vegan Chocolate Market through 2036?
As per FMI, the vegan chocolate market is projected to grow at a 4.9% CAGR from 2026 to 2036. Growth is supported by rising lactose intolerance awareness, dedicated allergen-free conching lines, and mainstream supermarket free-from aisles.
Which product type holds a notable vegan chocolate demand share in 2026?
Dark vegan chocolate is projected to hold 45.0% of product type demand in 2026. The segment benefits from naturally dairy-free high-cacao formulations, crisp cocoa butter tempering, and clean ingredient labels.
Which sweetener formulation holds a notable vegan chocolate share in 2026?
Cane sugar is estimated to account for 58.0% of sweetener formulation demand in 2026. Demand is supported by predictable sucrose crystallization, smooth conching viscosity, and bone-char-free vegan refining.
Which country has a notable vegan chocolate expansion outlook during the forecast period?
FMI finds that Singapore is projected to expand at a 6.0% CAGR during the 2026 to 2036 assessment period. Growth is supported by high adult lactose sensitivity, specialty cafe culture, and premium dairy-free confectionery gifting.
Which companies are active in the Vegan Chocolate Market during 2026?
Notable companies active in the market include Lindt & Sprüngli, Barry Callebaut, Mondelēz International, Mars Incorporated, Nestlé S.A., Ritter Sport, Plamil Foods, and Hu Kitchen. These manufacturers focus on micro-milled oat and almond milk formulations, allergen-segregated factories, and deforestation-free cocoa sourcing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
