

- Market Size (2026)
- USD 5.7 Bn
- Forecast (2036)
- USD 11.4 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Vegan Protein Powder Market in 2026?
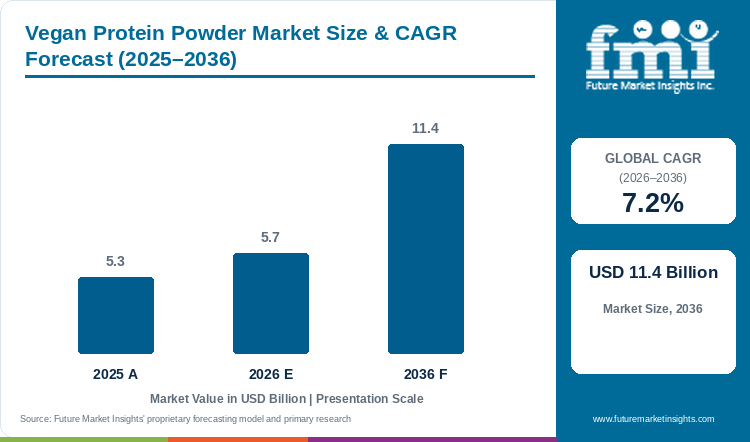
Worldwide vegan protein powder industry valuation stood at USD 5.3 billion during 2025 and is estimated at USD 5.7 billion in 2026 market size, before reaching USD 11.4 billion in overall market valuation come 2036 on a 7.2% CAGR.
As per FMI, worldwide vegan protein powder valuation is expected to expand beyond USD 5.3 billion during 2025 toward USD 5.7 billion in 2026 market size and attain USD 11.4 billion come 2036, recording a 7.2% CAGR that yields USD 5.7 billion of incremental yearly market value. This ten-year expansion is happening because shoppers who experience dairy bloating or follow plant-forward diets now expect dairy-free shakes to mix smoothly in cold water and support post-workout muscle recovery. A Bayesian meta-analysis of 12 human clinical studies published in the Journal of the Academy of Nutrition and Dietetics in April 2026 showed that younger adults under 65 years achieved similar muscle protein synthesis responses from plant and animal proteins whilst older adults aged 65 to 85 still saw a modest advantage from animal sources [1]. To deliver all nine essential amino acids in every scoop, supplement makers rely on Pea & Brown Rice Complementary Blends for 57.9% of plant protein source valuation in 2026 while also sourcing yellow pea protein isolates for everyday recovery tubs.
Key Market Trends & Insights
- By plant protein source: Pea & Brown Rice Complementary Blends are expected to hold 57.9% of source valuation in 2026 because pairing pea and rice proteins balances limiting sulfur amino acids.
- By flavor profile: Chocolate & Vanilla Bean varieties are projected to account for 59.7% of flavor market size in 2026 as natural cocoa and Madagascar vanilla mask grassy pulse off-notes.
- By sales channel: D2C E-Commerce & Subscription Platforms are estimated to generate 61.3% of channel market value during 2026 through automated 30-day refill bundles and online nutrition quizzes.
- By functional fortification: Probiotic, Digestive Enzyme & Greens Fortified recipes are forecast to claim 62.9% of fortification valuation in 2026 by combining bromelain and Bacillus coagulans with organic greens.
- By packaging format: Recyclable HDPE & PCR Plastic Tubs are slated to capture 64.7% of packaging market size in 2026 owing to moisture-tight screw lids that protect dry powders.
Regional Highlights
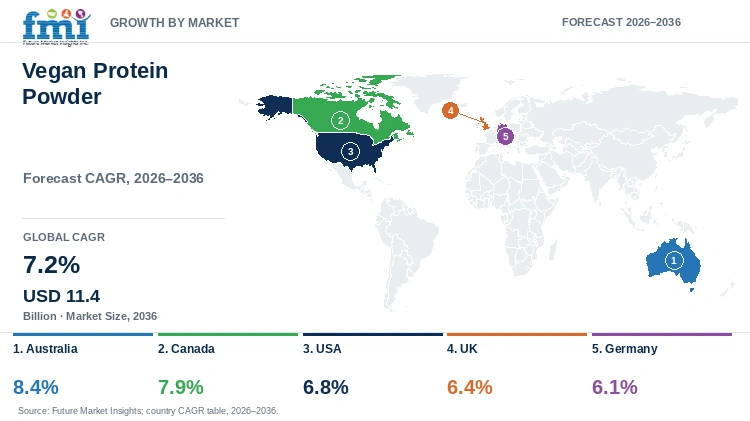
- Commonwealth expansion leaders: Australia is forecast to top analyzed country markets with an 8.4% annual growth rate until 2036, while Canada is projected to record a 7.9% yearly pace on domestic pulse fractionation.
- North American and European progression: Market value across the USA is expected to rise by 6.8% annually compared with 6.4% in the UK and 6.1% across Germany.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vegan Protein Powder Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Value | USD 5.3 billion |
| Estimated Market Size in 2026 | USD 5.7 billion |
| Projected Industry Valuation by 2036 | USD 11.4 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Annual Market Value, 2026 to 2036 | USD 5.7 billion |
Clinical comparisons between single-crop and blended plant proteins and stricter heavy-metal purity checks in North America and Europe are pushing brands toward multi-source pulse isolates. A July 2025 Queen's University Belfast meta-analysis of 30 randomized controlled trials in Nutrition Reviews found zero pooled muscle-mass difference between soy and milk protein across 17 trials and no strength gap across 14 trials, while single-source rice and oat or potato proteins trailed animal protein across 5 trials [2]. To close those single-crop amino acid gaps without using soy allergens, supplement brands blend extruded plant-based protein concentrates from yellow peas and fava beans with cold-pressed hemp seeds. Co-packers that verify low lead and cadmium levels under Clean Label Project and USP standards win repeat retail and D2C contracts.
Pulse Fractionation and Dry-Blend Canister Sizing
Table 2: Pulse Fractionation and Dry-Blend Canister Sizing for the Vegan Protein Powder Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.3 | 5.7 | 11.4 |
| Finished vegan powder retail volume (thousand tonnes) | 215.0 to 232.0 | 230.0 to 248.0 | 435.0 to 470.0 |
| Packaged canisters and pouches shipped (million units) | 240.0 to 260.0 | 258.0 to 278.0 | 490.0 to 530.0 |
| Average retail realization (USD per 900g canister) | 32.5 to 36.0 | 33.0 to 37.0 | 36.5 to 41.0 |
Operational note: Finished volume and unit ranges reflect 750-gram to 1,000-gram multi-serving retail tubs and gusseted pouches standardized to 20 to 30 grams of plant protein per serving.
Wet-extracted 85% pulse protein isolates prevent the thick, chalky settling inside shaker cups that used to happen with coarse dry-milled bean flours. Contract dry-blenders keep particle sizes between 80 and 120 mesh while comparing cold-water mixing speed against defatted soy protein isolates for ready-to-mix shakes.
Per Capita & Co-Packing Facility Sizing
Table 3: Per Capita and Subscriber Valuation Indicators for the Vegan Protein Powder Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 646.3 | 686.7 | 1,266.7 |
| Annual subscription value per active D2C user (USD) | 265.0 to 310.0 | 275.0 to 320.0 | 340.0 to 395.0 |
| Certified organic & non-GMO valuation share (%) | 54.0% to 58.0% | 56.0% to 60.0% | 64.0% to 68.0% |
Table 4: Dry-Blending Facility & Channel Valuation Indicators for the Vegan Protein Powder Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 5.7 billion | 2026 global market valuation baseline |
| Certified allergen-free dry-blending plants worldwide | 680 facilities | Global nutraceutical co-packing registry |
| Average annual vegan powder output value per plant | USD 8.4 million | Annualized contract blending valuation |
| D2C e-commerce & subscription market value, 2026 | USD 3.5 billion | 61.3% sales channel allocation |
Dairy-free and gluten-free powder filling lines require positive-pressure rooms and verified allergen swab tests between production runs. Brand owners pair yellow pea isolates with sprouted organic rice proteins grown in low-arsenic fields so their canisters meet family and maternal clean-label standards.
Analyst Perspective
"De-flavored pea and fava isolates are eliminating the chalky mouthfeel that historically restricted repeat vegan powder purchases. Brands that pair complete amino acid blends with transparent heavy-metal testing will dominate subscription and mass-retail shelves."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the vegan protein powder market segmented?
The vegan protein powder market is segmented by plant protein source, flavor profile, sales channel, functional fortification, packaging format, and region. In 2026, Pea & Brown Rice Complementary Blends is projected at 57.9%, Chocolate & Vanilla Bean at 59.7%, D2C E-Commerce & Subscription Platforms at 61.3%, Probiotic, Digestive Enzyme & Greens Fortified at 62.9%, and Recyclable HDPE & PCR Plastic Tubs at 64.7%.
By plant protein source: Pea & Brown Rice Complementary Blends, Soy Protein Isolate, and Hemp, Pumpkin Seed & Fava Bean.
By flavor profile: Chocolate & Vanilla Bean, Unflavored Culinary Grade, and Berry & Matcha.
By sales channel: D2C E-Commerce & Subscription Platforms, Specialty Vitamin & Health Food Stores, and Supermarkets & Pharmacies.
By functional fortification: Probiotic, Digestive Enzyme & Greens Fortified, Pure Single-/Dual-Source Protein Only, and BCAA, Creatine & Adaptogen Performance Blends.
By packaging format: Recyclable HDPE & PCR Plastic Tubs, Multi-Layer Gusseted Stand-Up Pouches, and Single-Serve Travel Stick Packs.
Why do Pea & Brown Rice Complementary Blends lead plant protein sources?
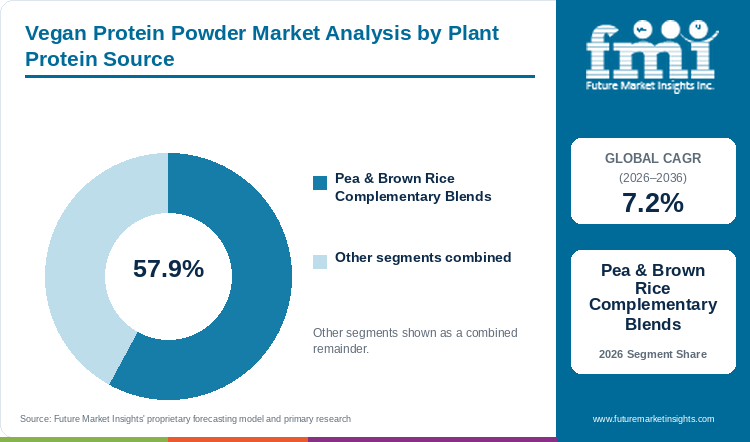
Pea & Brown Rice Complementary Blends are expected to hold 57.9% of source valuation in 2026, sustained by amino acid complementarity.
Table 5: Plant Protein Source Share for the Vegan Protein Powder Market (percentage share), 2026
| Plant Protein Source | Share (2026) |
|---|---|
| Pea & Brown Rice Complementary Blends | 57.9% |
| Other Segments Combined | 42.1%* |
| Total | 100.0% |
*Note: Combined share of remaining plant protein source categories totaling 100.0% of 2026 market valuation.
Table 6: Plant Protein Source Leadership and Market Growth for the Vegan Protein Powder Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Pea & Brown Rice Complementary Blends |
Yellow pea isolate supplies plenty of lysine and arginine but falls short on methionine and cysteine, whereas brown rice protein has the opposite amino acid balance. Because of this, a 70-to-30 blend of pea and rice proteins with cold-pressed hemp protein powders achieves a full 1.00 digestibility score while avoiding soy and dairy allergen warnings.
- Pea & Brown Rice Complementary Blends are expected to capture 57.9% of plant protein source market value in 2026 by matching dairy leucine and methionine levels without soy allergens.
- Roquette Freres launched NUTRALYS Pea 850F in February 2026, a clean-tasting pea protein isolate built to remove raw bean flavor at the ingredient stage without masking agents for ready-to-mix shakes [3].
What keeps Chocolate & Vanilla Bean ahead by flavor profile?
Chocolate & Vanilla Bean flavors are projected to account for 59.7% of flavor demand in 2026, enabled by off-note masking.
Natural fats inside dry peas and seeds oxidize slightly during milling, which creates grassy aromas that can put off everyday buyers. Dutch-processed cocoa and natural Madagascar vanilla extracts cover those earthy notes across debittered fava bean protein isolates and pea blends while giving households familiar base flavors that mix well with oat milk or fruit smoothies.
- Chocolate & Vanilla Bean profiles are projected to secure 59.7% of flavor market value in 2026 because classic dessert flavors fit daily smoothies without taste fatigue.
- Orgain, LLC expanded distribution of its USDA-certified organic 30g Plant-Based Protein Powder in Vanilla and Chocolate tubs across 2025 and 2026, delivering 9 grams of essential amino acids and 4 grams of prebiotic agave inulin fiber per scoop [4].
How do D2C E-Commerce & Subscription Platforms lead sales channels?
D2C E-Commerce & Subscription Platforms are estimated to concentrate 61.3% of channel market size in 2026, centered on automated refill bundles.
Direct brand websites and online subscription programs let buyers read batch heavy-metal test reports and amino acid tables before signing up for monthly tub deliveries. Online storefronts also let new brands test neutral chickpea protein concentrates and limited-edition flavors without paying supermarket shelf slotting fees.
- D2C E-Commerce & Subscription Platforms are estimated to generate 61.3% of channel market size in 2026 as 15% to 20% auto-ship discounts lock in repeat monthly orders.
- THG Nutrition launched its Myprotein sports and plant nutrition range directly into U.S. Walmart supercenters in August 2025 to complement its global D2C platform, reaching toward 40,000 retail doors worldwide [5].
Why does Probiotic, Digestive Enzyme & Greens Fortified lead fortification?
Probiotic, Digestive Enzyme & Greens Fortified formulas are forecast to claim 62.9% of fortification valuation in 2026, guided by gut-comfort protocols.
Leftover complex sugars in legume proteins can cause stomach gas if consumed without digestive enzyme support. For this reason, brands combine plant protein powders with alpha-galactosidase and bromelain plus Bacillus coagulans probiotics and organic greens so buyers get complete protein and gut comfort with daily greens in one morning scoop.
- Probiotic, Digestive Enzyme & Greens Fortified blends are forecast to command 62.9% of fortification market value in 2026 by speeding up protein digestion and reducing post-shake bloating.
- Vega (Vega US) rolled out its redesigned 2025 performance and everyday plant-based protein line featuring NSF Certified for Sport and Informed Choice credentials with greens-and-probiotic all-in-one blends [6].
What gives Recyclable HDPE & PCR Plastic Tubs the packaging lead?
Recyclable HDPE & PCR Plastic Tubs are slated to capture 64.7% of packaging demand in 2026, shaped by moisture-barrier rigidity.
Wide-mouth high-density polyethylene tubs molded with post-consumer recycled resin protect dry protein and probiotic powders from humidity and parcel crushing. Unlike flexible pouches where fine powder often clogs the zipper track and stops it from sealing, rigid HDPE2 canisters give easy scoop access and go straight into household recycling bins.
- Recyclable HDPE & PCR Plastic Tubs are anticipated to hold 64.7% of packaging format market size in 2026 by pairing foil moisture seals with curbside recyclability.
- Huel Limited expanded its vegan Complete Protein and Black Edition powder containers across North American and European fulfillment hubs in 2025 and 2026, supplying 20 to 40 grams of pea-rice-fava protein with 27 essential vitamins and minerals [7].
What are the drivers, restraints, and opportunities in the vegan protein powder market?
Dairy-allergen avoidance and domestic pulse-fractionation investments are forecast to lift vegan protein powder market value through 2036, whereas heavy-metal testing scrutiny restrains low-grade botanical sourcing and creatine-fortified recovery blends open athletic opportunities.
- Driver: New pulse-isolation plants and consumer demand for lactose-free, allergen-friendly daily nutrition support multi-source vegan powder adoption.
- Restraint: Natural soil lead and cadmium uptake in crops and federal plant-based naming guidelines raise batch testing and label compliance costs.
- Opportunity: Clean-tasting pea and fava isolates fortified with vegan creatine monohydrate and prebiotic fibers attract strength-training and GLP-1 buyers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
New investments in solvent-free dry and wet bean fractionation are bringing down ingredient costs whilst giving non-dairy protein powders a much cleaner taste and smoother texture. Because of this, supplement makers now blend yellow pea and fava bean concentrates with roasted pumpkin seed protein flours so households get complete daily protein without paying high dairy whey prices. In September 2025, Protein Industries Canada announced a CAD 32.5 million co-investment project with Phytokana Ingredients and Maia Farms to commercialize solvent-free fava bean protein concentrates and build a 30,000-metric-tonne annual fractionation plant in Alberta [8]. This added regional processing capacity gives North American powder brands a reliable domestic isolate supply.
Risk Assessment of the Vegan Protein Powder Market: Operational and Formulation Friction
Trace soil metals in organic cocoa and brown rice and federal front-of-pack naming expectations remain the main operational hurdles for plant protein brands. Because deep-rooting crops draw natural cadmium and lead from agricultural soil, brands that use unrefined rice or hemp flours risk crossing California Proposition 65 warning limits. In addition to this, formulators adding proteolytic digestive enzyme supplements must keep their front-label wording aligned with federal transparency guidelines. Federal regulators at the U.S. Food and Drug Administration issued non-binding draft industry guidance (Docket FDA-2022-D-1102) in January 2025 recommending that plant-based alternatives clearly state the specific botanical source in the statement of identity [9]. Routine ICP-MS heavy-metal screening on every batch and label updates add to unit packaging costs.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Supplement brands can earn higher retail margins across gym and medical weight-loss channels when they pair smooth pea and fava isolates with 3 to 5 grams of vegan creatine monohydrate and prebiotic fiber. Patients using GLP-1 weight-management medications need compact, high-protein shakes that protect lean muscle mass while working well with fortified meal replacement products. Economists at the U.S. Department of Agriculture Economic Research Service published the April 2026 Vegetables and Pulses Outlook (VGS-378) detailing North American dry pea and lentil plus chickpea supply and trade balances that feed pulse protein mills [10]. Brands that certify NSF for Sport purity across North American pulse blends win university and pro athletic supply contracts.
Vegan Protein Powder Market by Country (2026 to 2036)
Future Market Insights forecasts Australia to lead national vegan protein powder markets with an 8.4% annual CAGR up to 2036, whereas Germany is slated to progress at 6.1% per year. Growth differences between Oceania and North America compared with Western Europe depend on domestic pea and lupin harvests and pharmacy or D2C subscription adoption.
Table 7: Country CAGR and Primary Growth Levers for the Vegan Protein Powder Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 8.4% | High adult recreational sport participation and domestic lupin, fava, and pea isolate blending |
| Canada | 7.9% | Prairie yellow-pea and fava-bean fractionation scale and CFIA pedigreed pulse seed quality |
| USA | 6.8% | High D2C subscription penetration, big-box retail expansion, and GLP-1 companion protein demand |
| UK | 6.4% | Domestic field-bean crop expansion and pharmacy and supermarket vegan wellness merchandising |
| Germany | 6.1% | Strict organic and non-GMO drugstore private-label standards and EFSA novel-food compliance |
Source: Future Market Insights analysis
Australia Vegan Protein Powder Market Outlook (2026 to 2036)
Australia stands out across Asia-Pacific because local supplement blenders combine Western Australian sweet lupin and Victorian fava bean isolates with Golden European pea proteins for pharmacy and gym shelves. In April 2026, the Australian Sports Commission released its January to December 2025 AusPlay national survey data tables covering roughly 40,000 respondents and confirming strong adult participation in gym training and outdoor fitness [11]. Retail and online market value for vegan protein powders in Australia is forecast to climb by 8.4% annually over 2026 to 2036 as flexitarian households buy dairy-free recovery shakes. Strict Therapeutic Goods Administration rules separating listed sports supplements from general foods still require careful label claim verification.
Key takeaway: In Australia, widespread recreational sport participation and domestic lupin-and-pea isolate blending are forecast to drive 8.4% annual market value expansion.
Canada Vegan Protein Powder Market Outlook (2026 to 2036)
Large yellow pea and fava bean harvests in Saskatchewan and Alberta plus Manitoba give Canada an integrated local supply chain for wet-extracted and dry-milled plant protein isolates. On June 30, 2026, Statistics Canada reported in its June 2026 Field Crop Survey of 25,000 farms that Canadian growers seeded 6.0 million acres of soybeans (up 3.1%) and 3.0 million acres of dry peas and 3.9 million acres of lentils [12]. Canadian market size for vegan protein powders is projected to climb 7.9% yearly between 2026 and 2036 as domestic co-packers blend low-carbon pulse powders for North American retailers. However, farmer shifts toward canola acreage still tighten spot yellow-pea feedstock pricing.
Key takeaway: In Canada, Prairie pulse-fractionation infrastructure and 3.0 million acres of dry-pea cultivation are projected to anchor a 7.9% annual valuation expansion.
USA Vegan Protein Powder Market Outlook (2026 to 2036)
Broad distribution across subscription e-commerce and warehouse clubs plus supermarkets makes the United States the largest national market for vegan protein canisters. In April 2026, a U.S. Centers for Disease Control and Prevention National Center for Health Statistics data brief (No. 555) reported that 47.2% of U.S. adults met federal aerobic physical activity guidelines in 2024 [13]. United States vegan protein powder industry valuation is expected to advance 6.8% annually across the ten-year horizon to 2036 as gym-goers and GLP-1 patients buy organic pea-and-rice shakes with added prebiotic fiber. Even so, shopper scrutiny over California Proposition 65 heavy-metal notices still forces U.S. brands to audit cocoa and brown-rice suppliers.
Key takeaway: In the USA, mass-retail shelf expansion and third-party heavy-metal-verified organic blends are expected to support a 6.8% yearly valuation growth pace.
UK Vegan Protein Powder Market Outlook (2026 to 2036)
High-street health chains and supermarket meal-replacement aisles with domestic bean breeding programs shape demand for vegan protein powders across the United Kingdom. In September 2026, official UK DEFRA crop statistics in Chapter 7 of Agriculture in the United Kingdom 2025 reported that British field-bean output rose 4.7% to 482 thousand tonnes across 141 thousand hectares whilst dry harvested field peas added 96 thousand tonnes for food use [14]. British retail and online market value for vegan protein powders is estimated to grow 6.4% annually until 2036 across pharmacy and grocery chains. Variable spring rainfall affecting UK bean protein levels still requires local blenders to import French and Canadian pea isolates.
Key takeaway: In the UK, rising domestic field-bean harvests and high-street pharmacy distribution are estimated to sustain a 6.4% annual valuation pace through 2036.
Germany Vegan Protein Powder Market Outlook (2026 to 2036)
Germany's dense network of Drogerie drugstores and local sports clubs creates steady demand for certified non-GMO, clean-label plant protein powders across central Europe. In November 2025, the German Olympic Sports Confederation (DOSB) reported a record 29.3 million memberships across roughly 86,000 sports clubs nationwide [15]. As club athletes and eco-conscious shoppers trade dairy shakes for pea and fava blends, vegan protein powder industry valuation in Germany is slated to progress at 6.1% annually over the forecast period to 2036 across drugstore and e-commerce channels. Strict European Union Novel Food approval rules for new fermented and sprouted botanical proteins still lengthen launch timelines for specialty German supplement brands.
Key takeaway: In Germany, record sports-club participation across 29.3 million members and drugstore clean-label standards are slated to guide 6.1% annual market growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the vegan protein powder market?
Orgain, LLC, Vega, Garden of Life LLC, Sunwarrior LLC, Huel Limited, THG plc, NOW Health Group, Inc., and Nuzest are the notable companies in the vegan protein powder market.
FMI evaluation shows that competition across vegan protein powders spans organic probiotic-fortified lifestyle brands and D2C complete-nutrition platforms plus sprouted clean-label specialists. Organic lifestyle brands hold club-store and pharmacy shelf space through USDA Organic and NSF for Sport certifications. Meanwhile, digital-native platforms scale monthly subscription bundles and rapid flavor launches across North America and Europe plus Asia-Pacific.
- Organic & Microbiome-Fortified Brand Leaders: Orgain, LLC and Garden of Life LLC with Vega lead mass-retail and pharmacy plus natural grocery shelves with probiotic-fortified pea-and-rice tubs.
- Global D2C & Omnichannel Sports Platforms: Huel Limited and THG plc (Myprotein) run high-volume subscription storefronts and international retail partnerships.
- Sprouted & Single-Source Clean-Label Specialists: Sunwarrior LLC and NOW Health Group, Inc. with Nuzest formulate sprouted multi-source and European golden-pea isolate powders for allergen-sensitive buyers.
Competitive Benchmarking: Vegan Protein Powder Market
Table 8: Competitive Benchmarking for the Vegan Protein Powder Market (qualitative capability ratings), 2026
| Company | Multi-Source Blend Breadth | Probiotic & Enzyme Fortification | D2C & Retail Omnichannel Reach | Geographic Reach |
|---|---|---|---|---|
| Orgain, LLC | High | High | High | High |
| Vega | High | High | High | Medium |
| Garden of Life LLC | High | High | High | High |
| Sunwarrior LLC | High | Medium | Medium | Medium |
| Huel Limited | High | High | High | High |
| THG plc | High | Medium | High | High |
| NOW Health Group, Inc. | High | Medium | High | High |
| Nuzest | Medium | High | Medium | High |
Scoring basis: Capability scores assess botanical protein diversity across pea and rice plus hemp and fava isolates paired with USDA Organic and NSF Certified for Sport verification. Distribution and regional scores reflect recurring subscription fulfillment and pharmacy and supermarket shelf presence.
Key Developments in the Vegan Protein Powder Market
- THG plc (Myprotein) reformulated and rebranded its flagship Impact Vegan Protein into Impact Plant Protein across 2025 and 2026, combining a 95% pea and fava bean isolate blend that delivers 22 to 24 grams of complete plant protein per 30-gram scoop across 450g and 900g plus 2.7kg packs [16].
- NOW Health Group, Inc. expanded its NOW Sports non-GMO Pea Protein Organic and Unflavored powder lines during 2025 and 2026, providing 15 to 24 grams of bioavailable yellow-pea isolate and over 4,200 milligrams of branched-chain amino acids per serving [17].
- Garden of Life LLC scaled its quadruple-certified Raw Organic Protein and SPORT Organic Plant-Based Protein powder lines across U.S. and international retail channels in 2025 and 2026, combining sprouted organic grains and legumes with 3 billion CFU of probiotics and 13 digestive enzymes [18].
Key Players in the Vegan Protein Powder Market
Organic & Microbiome-Fortified Brand Leaders
- Orgain, LLC
- Garden of Life LLC
- Vega
Global D2C & Omnichannel Sports Platforms
- Huel Limited
- THG plc
Sprouted & Single-Source Clean-Label Specialists
- Sunwarrior LLC
- NOW Health Group, Inc.
- Nuzest
Vegan Protein Powder Market - Report Scope
Table 9: Report Scope for the Vegan Protein Powder Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Plant Protein Source; Flavor Profile; Sales Channel; Functional Fortification; Packaging Format; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial market value of dry ready-to-mix vegan and plant-based protein supplement powders formulated from pea, brown rice, soy, hemp, pumpkin seed, fava bean, and chia proteins packaged in tubs, pouches, and single-serve sticks. Category Scope Note: Excludes dairy whey and casein powders, bovine or marine collagen powders, ready-to-drink liquid bottles, and extruded protein bars. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Canada, USA, UK, Germany, and additional countries in the full report |
| Key Companies Covered | Orgain, LLC, Vega, Garden of Life LLC, Sunwarrior LLC, Huel Limited, THG plc, NOW Health Group, Inc., Nuzest |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Vegan Protein Powder Market - Research Methodology
Table 10: Research Methodology for the Vegan Protein Powder Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with nutraceutical dry-blending directors, pulse-isolate flavor chemists, D2C subscription category managers, and sports dietitians to validate amino acid blending ratios and canister pricing. |
| Secondary Research | Analysis of corporate filings, Statistics Canada and UK DEFRA pulse crop surveys, USDA ERS Vegetables and Pulses Outlook (VGS-378), Protein Industries Canada fractionation disclosures, U.S. FDA and EFSA regulatory guidances, and PubMed randomized controlled trials. |
| Market Sizing and Forecasting | Top-down consumer sports and lifestyle supplement valuation models reconciled against bottom-up co-packing canister output and D2C subscriber cohorts from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight domestic pulse-fractionation capacity, adult sports participation rates, organic certification adoption, and D2C subscription penetration across five national markets. |
| Operational Benchmark Traceability | Canister volume, subscriber valuation, and co-packing plant indicators in Tables 2, 3, and 4 trace to Statistics Canada and UK DEFRA pulse registries, USDA ERS pulse balances, CDC NCHS activity surveys, and brand disclosures. |
| Data Triangulation and Validation | Market value estimates are cross-checked against food-grade pea, rice, and fava isolate tonnages and retail scanner valuation without double counting upstream bulk agricultural grain trade. |
Vegan Protein Powder Market by Segments
Vegan Protein Powder Market segmented by Plant Protein Source:
- Pea & Brown Rice Complementary Blends
- Soy Protein Isolate
- Hemp, Pumpkin Seed & Fava Bean
Vegan Protein Powder Market segmented by Flavor Profile:
- Chocolate & Vanilla Bean
- Unflavored Culinary Grade
- Berry & Matcha
Vegan Protein Powder Market segmented by Sales Channel:
- D2C E-Commerce & Subscription Platforms
- Specialty Vitamin & Health Food Stores
- Supermarkets & Pharmacies
Vegan Protein Powder Market segmented by Functional Fortification:
- Probiotic, Digestive Enzyme & Greens Fortified
- Pure Single-/Dual-Source Protein Only
- BCAA, Creatine & Adaptogen Performance Blends
Vegan Protein Powder Market segmented by Packaging Format:
- Recyclable HDPE & PCR Plastic Tubs
- Multi-Layer Gusseted Stand-Up Pouches
- Single-Serve Travel Stick Packs
Vegan Protein Powder Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Mendes, B. R., Correia, J. M., Dos Santos, I. R., Schoenfeld, B. J., Swinton, P. A., & de Mendonca, G. V. (2026, April 27). Effects of Plant- vs Animal-Based Proteins on Muscle Protein Synthesis: A Systematic Review With Meta-Analysis. Journal of the Academy of Nutrition and Dietetics, 126(9), 156365 (PubMed PMID 42055214).
- [2] Reid-McCann, R. J., Brennan, S. F., Ward, N. A., Logan, D., McKinley, M. C., & McEvoy, C. T. (2025, July 1). Effect of Plant Versus Animal Protein on Muscle Mass, Strength, Physical Performance, and Sarcopenia: A Systematic Review and Meta-analysis of Randomized Controlled Trials. Nutrition Reviews, 83(7), e1581-e1603 (PubMed PMID 39813010).
- [3] Roquette Freres. (2026, February 23). Launch of Breakthrough Clean-Tasting Pea Protein Isolate. Roquette Press Releases.
- [4] Orgain, LLC. (2026, January 15). 30g Plant Based Protein Powder - Vanilla | Orgain. Orgain Official Product Specifications.
- [5] THG plc. (2025, July 29). Myprotein Launches in Walmart in Major US Retail Push - THG. THG Press Room.
- [6] Vega (Vega US). (2025, January 10). Perform Better in 2025 with the All New Vega. Vega Plant-Based Nutrition Blog.
- [7] Huel Limited. (2026, February 12). Complete Protein Powder - Huel. Huel Official Nutritional Documentation.
- [8] Protein Industries Canada. (2025, September 10). Canadian start-up Phytokana developing new fava-based ingredients | Protein Industries Canada. Protein Industries Canada News Releases.
- [9] U.S. Food and Drug Administration. (2025, January 6). Draft Guidance for Industry: Labeling of Plant-Based Alternatives to Animal-Derived Foods. U.S. Department of Health and Human Services, FDA (Docket FDA-2022-D-1102).
- [10] Davis, W. V., Weber, C., & Wakefield, H. (2026, April 30). Vegetables and Pulses Outlook: April 2026. U.S. Department of Agriculture, Economic Research Service (Report VGS-378).
- [11] Australian Sports Commission. (2026, April 30). Data Tables | Clearinghouse | ASC - Australian Sports Commission. Australian Government Sports Commission (AusPlay January - December 2025).
- [12] Statistics Canada. (2026, June 30). The Daily — Principal field crop areas, June 2026. Government of Canada Statistics Canada.
- [13] Elgaddal, N., & Kramarow, E. A. (2026, April 7). Aerobic Physical Activity Among Adults Age 18 and Older: United States, 2024. National Center for Health Statistics (NCHS Data Brief No. 555).
- [14] Department for Environment, Food & Rural Affairs (DEFRA). (2026, September 3). Chapter 7: Crops - GOV.UK. GOV.UK Agriculture in the United Kingdom 2025.
- [15] Deutscher Olympischer Sportbund (DOSB). (2025, November 11). Naechster Mitgliederrekord im deutschen Sport. Deutscher Olympischer Sportbund.
- [16] THG plc (Myprotein). (2026, January 15). Impact Plant Protein | Myprotein UK. THG Nutrition Limited Official Product Documentation.
- [17] NOW Health Group, Inc. (2026, June 18). Pea Protein, Organic Powder - NOW Foods. NOW Sports Nutrition Catalog.
- [18] Garden of Life LLC. (2026, January 20). SPORT Organic Plant-Based Protein Powder - Vanilla - Garden of Life. Garden of Life Official Product Documentation.
- [19] Sunwarrior LLC. (2025, October 21). Warrior Blend Organic Protein - Chocolate - Sunwarrior. Sunwarrior Plant-Based Proteins and Supplements.
- [20] Canadian Food Inspection Agency (CFIA). (2026, April 1). Specific work instructions (SWI 142.1.2-3): Pulse seed crop inspection procedures - inspection.canada.ca. Government of Canada CFIA.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vegan protein powder market in 2026 and what is forecast for 2036?
- Which amino acid complementarity and gut-comfort pressures support vegan powder demand?
- Why do Pea & Brown Rice Complementary Blends lead the plant protein source category?
- Why does Chocolate & Vanilla Bean lead the flavor profile category globally?
- How do growth rates differ across Australia, Canada, the USA, the UK, and Germany?
- Which leading companies formulate and market vegan protein powders today?
- What limits adoption or brand switching in the vegan protein powder market?
- What should retail buyers evaluate before qualifying a vegan protein powder brand?
Frequently Asked Questions
How big is the vegan protein powder market in 2026, and what is forecast for 2036?
As per FMI, worldwide vegan protein powder industry valuation is estimated at USD 5.7 billion in 2026, up from USD 5.3 billion in 2025. Overall market size is projected to reach USD 11.4 billion by 2036 as de-flavored pulse isolates enter mass retail.
What is the CAGR for the vegan protein powder market from 2026 to 2036?
Worldwide vegan protein powder market value is projected by FMI to expand at a 7.2% CAGR from 2026 through 2036, adding USD 5.7 billion in annual industry valuation across subscription and brick-and-mortar retail channels.
Which plant protein source segment leads the vegan protein powder market?
Pea & Brown Rice Complementary Blends are expected to hold 57.9% of plant protein source market size in 2026 because combining legume lysine with cereal methionine achieves a complete 1.00 DIAAS profile.
Which functional fortification segment leads the vegan protein powder market?
Probiotic, Digestive Enzyme & Greens Fortified formulas are forecast to claim 62.9% of fortification market value in 2026 by pairing proteolytic enzymes with spore-forming probiotics to prevent bloating.
Which country has a notable growth outlook during the assessment period?
Australia is forecast to lead national market expansion at an 8.4% CAGR through 2036, supported by high adult sport participation and domestic pulse-and-lupin isolate blending.
Who are the key players in the market?
Orgain, LLC, Vega, Garden of Life LLC, Sunwarrior LLC, Huel Limited, THG plc, NOW Health Group, Inc., and Nuzest anchor commercial supply across D2C subscriptions and retail grocers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Plant Protein Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Plant Protein Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Plant Protein Source, 2026 to 2036
- Pea & Brown Rice Complementary Blends
- Soy Protein Isolate
- Hemp, Pumpkin Seed & Fava Bean
- Y-o-Y Growth Trend Analysis By Plant Protein Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Plant Protein Source, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor Profile, 2026 to 2036
- Chocolate & Vanilla Bean
- Unflavored Culinary Grade
- Berry & Matcha
- Y-o-Y Growth Trend Analysis By Flavor Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- D2C E-Commerce & Subscription Platforms
- Specialty Vitamin & Health Food Stores
- Supermarkets & Pharmacies
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Functional Fortification, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Functional Fortification, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Functional Fortification, 2026 to 2036
- Probiotic, Digestive Enzyme & Greens Fortified
- Pure Single-/Dual-Source Protein Only
- BCAA, Creatine & Adaptogen Performance Blends
- Y-o-Y Growth Trend Analysis By Functional Fortification, 2021 to 2025
- Absolute $ Opportunity Analysis By Functional Fortification, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Recyclable HDPE & PCR Plastic Tubs
- Multi-Layer Gusseted Stand-Up Pouches
- Single-Serve Travel Stick Packs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Plant Protein Source
- By Flavor Profile
- By Sales Channel
- By Functional Fortification
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Orgain, LLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Vega
- Garden of Life LLC
- Sunwarrior LLC
- Huel Limited
- THG plc
- NOW Health Group, Inc.
- Nuzest
- Orgain, LLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


