
- Market Size (2026)
- USD 5.7 Bn
- Forecast (2036)
- USD 14.9 Bn
- CAGR (2026 to 2036)
- 10.1%
How big is Vegan Dog Food Market in 2026?
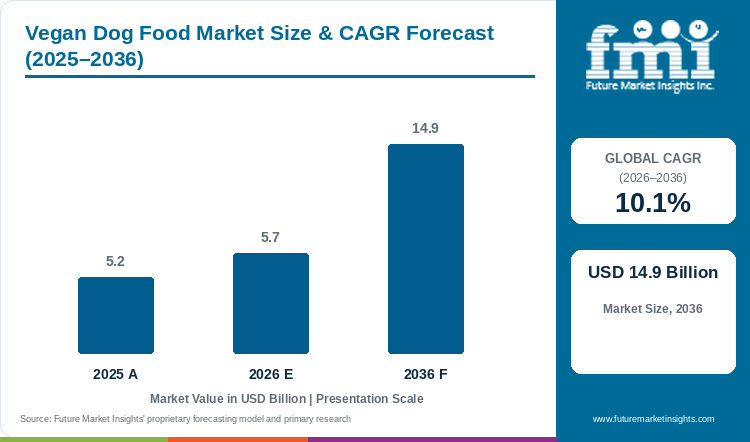
Sales in the vegan dog food market are projected to grow at 10.1% CAGR, with the market size rising from USD 5.2 billion in 2025 to USD 5.7 billion in 2026 and reaching USD 14.9 billion by 2036.
Increasing demand for the elimination of beef and poultry antigens from adult canine rations, along with the need to resolve chronic skin pruritus without lifelong steroid therapy, has led to the widespread adoption of complete vegan dog food. An April 2025 production study by the Pet Food Institute and the Institute for Feed Education and Research showed that U.S. pet food plants process more than 600 agricultural ingredients across 9.8 million tons of annual output, with corn and field peas leading plant inputs [1]. Vegan dog food turnover moves from USD 5.2 billion during 2025 to a 2026 valuation of USD 5.7 billion, with Future Market Insights projecting USD 14.9 billion by 2036 at a 10.1% CAGR as USD 9.2 billion in new value enters the sector. Dry extruded kibble captures 51.0% of product form demand in 2026, though synthetic taurine premix prices still restrain mass-grocery margins.
Key Market Trends & Insights
- By product form: Dry extruded kibble captures 51.0% of 2026 category sales because low-moisture pellets resist spoilage and scrape tartar from canine premolars.
- By dietary nature: Conventional vegan formulation represents 68.0% of 2026 volume as extruders pair defatted soy flour with yellow field-pea concentrates.
- By distribution channel: Specialty pet retail stores generate 44.0% of 2026 turnover through in-person nutrition consultations during elimination trials.
Regional Highlights
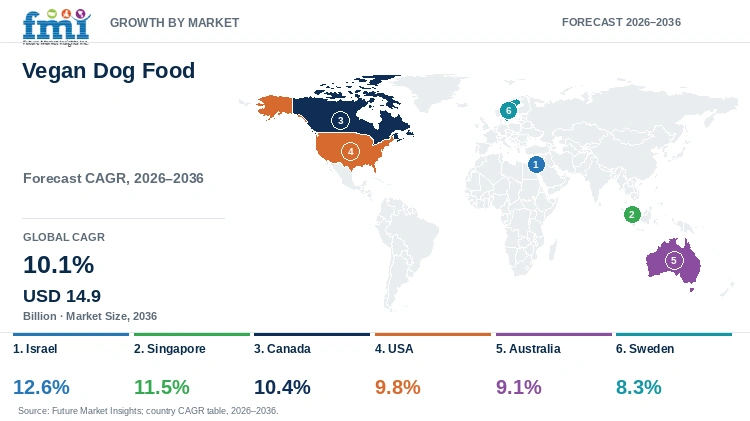
- Israel paces the six evaluated national markets with a 12.6% compound annual growth rate through 2036 on strong urban veterinary allergy referrals.
- Singapore (11.5%) and Canada (10.4%) rank next ahead of the USA (9.8%) and Australia (9.1%), whereas Sweden posts an 8.3% trajectory.
Market Size & Forecast
Table 1: Market Size and Forecast for the Vegan Dog Food Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.2 billion |
| Estimated Market Size in 2026 | USD 5.7 billion |
| Projected Market Size by 2036 | USD 14.9 billion |
| CAGR, 2026 to 2036 | 10.1% |
| Added Revenue, 2026 to 2036 | USD 9.2 billion |
United States and European feed regulators require amino acid bioavailability proofs before a meat-free ration can carry a complete maintenance claim on retail bags. Ingredient standards maintained by the Association of American Feed Control Officials in 2025 mandate that every plant protein and synthetic amino acid establish its utility through Generally Recognized as Safe or AAFCO-defined feed pathways [2]. Owing to the advantages associated with twin-screw cooking extruders, pet nutrition plants combine yellow pea isolates with brewer's yeast to manufacture digestible plant-based pet food rations. Vacuum coating chambers then infuse algal omega-3 oils and savory vegetable digests into warm kibble pores so allergic dogs maintain lean muscle mass.
Canine Allergy-Pool and Diet-Requirement Sizing
Table 2: Canine Allergy-Pool and Diet-Requirement Sizing for the Vegan Dog Food Market (USD billion and millions), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.2 | 5.7 | 14.9 |
| Household dogs on allergy or meat-free diets (million) | 14.5 to 16.2 | 15.8 to 17.6 | 34.0 to 38.5 |
| Annual plant-based ration volume (million metric tons) | 1.8 to 2.1 | 2.0 to 2.3 | 4.8 to 5.4 |
| Average annual spend per enrolled dog (USD) | 320 to 358 | 324 to 360 | 387 to 438 |
Baseline figures above pair household canine populations managed for cutaneous adverse food reactions with annual dry and wet ration intake across specialty and online channels.
Per-Dog Household & Specialty Retail Sizing
Replacing rendered beef tallow and poultry meal in commercial dog food requires balancing legume starch gelatinization with bio-fermented micronutrients so adult dogs absorb complete protein without loose stools. Once a veterinarian confirms that a plant ration resolves a dog's paw licking and ear inflammation, households rarely rotate back to conventional meat kibble. That clinical stickiness generates recurring monthly auto-ship orders across organic pet food boutiques and digital subscription clubs.
Table 3: Household Canine Spending Indicators for the Vegan Dog Food Market (USD and millions), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global household dog population (million) | 515.0 | 524.0 | 612.0 |
| Vegan dog food spend per household dog (USD) | 10.10 | 10.88 | 24.35 |
| Spend per 1,000 household dogs (USD) | 10,097 | 10,878 | 24,346 |
| Monthly ration outlay per active vegan dog (USD) | 26.60 to 29.80 | 27.00 to 30.00 | 32.25 to 36.50 |
Table 4: Retail & Veterinary Channel Indicators for the Vegan Dog Food Market (USD billion and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 5.7 billion | Report value |
| Specialty pet retail channel revenue, 2026 | USD 2.5 billion | 44.0% share |
| Online e-commerce channel revenue, 2026 | USD 1.9 billion | 33.2% share |
| Dry extruded kibble revenue, 2026 | USD 2.9 billion | 51.0% share |
Analyst Perspective
"Twin-screw extrusion paired with bio-fermented taurine and algal DHA allows plant-based dog foods to match meat digestibility in clinical maintenance diets. Elevated premix costs and strict palatability testing still require formulators to optimize enzymatic yeast coatings before mass grocery rollout."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the vegan dog food market segmented?
The vegan dog food market is segmented by product form, dietary nature, distribution channel, and region. In 2026, dry extruded kibble is projected at 51.0%, conventional vegan formulation at 68.0%, and specialty pet retail stores at 44.0%.
By product form: Dry extruded kibble, wet canned food & pouches, and freeze-dried & baked treats.
By dietary nature: Conventional vegan formulation, and organic, grain-free & clean-label.
By distribution channel: Specialty pet retail stores, online e-commerce platforms, and supermarkets & mass merchandisers.
Why does Dry Extruded Kibble lead the product form category?
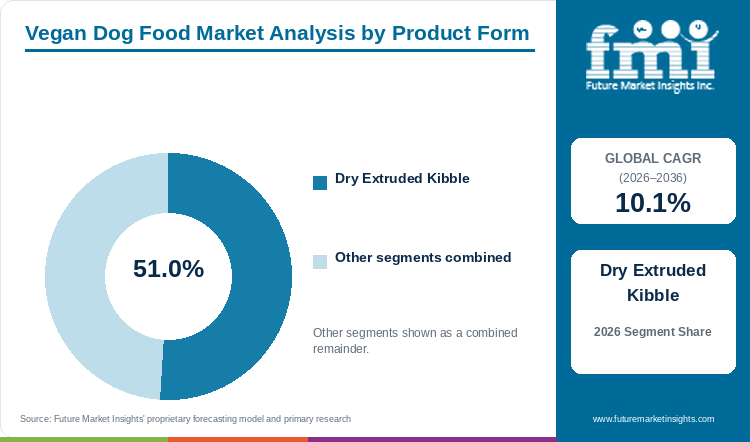
Dry extruded kibble is expected to account for 51.0% of product form revenue in 2026, supported by extended shelf stability.
Table 5: Product Form Share for the Vegan Dog Food Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Dry Extruded Kibble | 51.0% |
| Other Segments Combined | 49.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form Leadership and Market Growth for the Vegan Dog Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.1% |
| Leading Segment | Dry Extruded Kibble |
Multi-dog households and veterinary boarding kennels rely on dry extruded kibble for daily feeding because low-moisture pellets resist microbial spoilage in opened 10-kilogram bags and cut per-meal feeding expense below canned rations. High-shear barrel cooking gelatinizes chickpea and pea starches into crisp kibbles that scrape dental plaque from canine premolars during chewing, complementing dog dental chews in daily oral care. Wet canned food and pouches account for 32.4% of product form demand in 2026 for senior or hydration-sensitive dogs, while freeze-dried and baked treats hold 16.6% share.
- Dry extruded kibble is projected to claim 51.0% of product form revenue in 2026, supported by economical bulk bag storage and automated bowl portioning.
- For instance, V-dog expanded its North American dry kibble portfolio in 2025 with its Kind Kibble plant-based adult maintenance recipe incorporating pea protein and flaxseed [3].
What makes Conventional Vegan Formulation central to the dietary nature category?
Conventional vegan formulation is estimated to represent 68.0% of dietary nature demand in 2026, reflecting accessible plant protein ingredient pricing.
Combining non-organic defatted soy flour and yellow field peas with corn gluten meal enables pet food extruders to hit 24% to 28% crude protein targets without paying steep farmgate premiums for certified organic pulses. As per FMI, conventional vegan formulation holds 68.0% of dietary nature demand in 2026, whereas certified organic and grain-free recipes account for 32.0% share. Because complementary legume and cereal amino acids balance lysine and sulfur amino acids economically, extrusion plants can price conventional meat-free kibble competitively against mid-tier lamb formulas while expanding high-protein dog food options for active breeds.
- Conventional vegan formulation is estimated to hold 68.0% of dietary nature demand in 2026, underpinned by steady agricultural supply of field peas and brewer's yeast.
- In September 2025, the British Small Animal Veterinary Association released its updated BSAVA Guide to Nutrition in Small Animal Practice outlining clinical evaluation criteria for dogs fed commercial maintenance diets [4].
What supports Specialty Pet Retail Stores leadership within distribution channel?
Specialty pet retail stores are projected to capture 44.0% of distribution channel sales in 2026, driven by staff allergy consultations.
Switching an allergic dog onto a non-animal ration requires careful ingredient label screening and a gradual 16-day bowl transition to avoid osmotic digestive upset. Independent pet boutiques and dedicated specialty chains generate 44.0% of distribution channel revenue in 2026 because store nutrition specialists walk pet parents through amino acid adequacy profiles and sample packs in person. Furthermore, specialty retailers display hypoallergenic kibble beside savory dog food toppers that coax selective eaters to finish their bowls, while online e-commerce platforms hold 33.2% share and supermarkets represent 22.8%.
- Specialty pet retail stores capture 44.0% of 2026 channel turnover through staff-guided allergy diet consultations and neighborhood store loyalty programs.
- In October 2026, UK veterinary-founded brand Omni expanded its 30%-protein Adult Dry Food kibble formulated with potato and pea proteins alongside 1,500 mg/kg taurine and microalgae across British specialty channels [5].
What are the drivers, restraints, and opportunities in the vegan dog food market?
Veterinary elimination of beef and chicken allergens propels recurring plant kibble demand, whereas synthetic taurine and methionine premix costs restrain mass-market pricing, and precision yeast fermentation creates high-palatability formulation opportunities.
- Driver: Rising clinical diagnosis of canine cutaneous adverse food reactions to beef and poultry proteins shifts long-term maintenance feeding toward plant-based rations.
- Restraint: Mandatory supplementation with synthetic taurine and L-carnitine precursors increases formulation costs and requires extended feeding validation trials.
- Opportunity: Precision biomass fermentation of nutritional yeast and microalgae proteins unlocks meat-like umami palatability and complete amino acid digestibility.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Canine cutaneous adverse food reactions to beef and poultry proteins represent one of the most frequent causes of recurring veterinary dermatology visits for pruritus and otitis externa. Controlled feeding trials published in Animals in November 2025 at the University of Veterinary Medicine Hannover demonstrated that plant press-cake canine diets achieved apparent total tract protein digestibility of 85.11% for pumpkin press cake and 84.23% for sunflower press cake, while noting that 12.0% of surveyed UK dog owners feed vegan diets [6]. When meat-free rations resolve skin lesions without lifelong corticosteroid prescriptions, owners keep their dogs on those formulas permanently. In addition to this, pet nutrition brands are fortifying natural pet food kibble with algal DHA and linseed lipids to repair damaged epidermal barriers.
Risk Assessment of the Vegan Dog Food Market: Operational and Formulation Friction
Unlike humans, domestic dogs have limited hepatic enzyme capacity to synthesize taurine and L-carnitine when fed unfortified plant proteins that are naturally low in methionine and cystine. Updated Version 2025 Nutritional Guidelines for Complete and Complementary Pet Food for Cats and Dogs from the European Pet Food Industry Federation (FEDIAF) reinforce peer-reviewed nutrient thresholds under biochemical and bacteriological control [7]. Because high-pressure extruder barrels degrade heat-sensitive vitamins and sulfur amino acids, processors must dose 15% to 25% premix overages. Those synthetic amino acid and arachidonic-precursor additions raise per-ton batch costs and widen the retail price gap against conventional dog food and snacks in supermarket aisles.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Raw pea and faba-bean concentrates carry bitter saponin and grassy hexanal notes that frequently cause bowl refusal among dogs accustomed to rendered poultry fat coatings. A July 2025 peer-reviewed study in Foods on alternative pet-food proteins documented that sheared pea-and-faba-bean meat analogues achieve 72.8% dry-matter crude protein digestibility, while microalgae (Chlorella vulgaris and Arthrospira platensis) blended at 0.5% to 4.0% supply bioavailable omega-3 fatty acids [8]. Combining single-cell yeast extracts with spray-dried microalgae eliminates grassy legume off-notes without slaughterhouse inputs. Suppliers that coat dry kibble or formulate moisture-rich wet pet food chunks with yeast and algal concentrates can win veterinary therapeutic shelf space through 2036.
Vegan Dog Food Market by Country (2026 to 2036)
Evaluated ten-year compound annual growth rates for plant-based canine diets run from 12.6% in Israel and 11.5% across Singapore to 8.3% in Sweden. Where urban apartment density and household vegetarian alignment are high, veterinary clinics and specialty retailers rapidly adopt meat-free maintenance kibble; in colder agricultural economies such as Canada and Sweden, formulators must also engineer higher lipid density and local pulse sourcing to offset winter caloric needs and import freight.
Table 7: Country CAGR and Primary Growth Levers for the Vegan Dog Food Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Israel | 12.6% | High urban vegan household share and veterinary skin-allergy prescriptions |
| Singapore | 11.5% | High-rise apartment dog ownership and low-odor hypoallergenic indoor diets |
| Canada | 10.4% | Domestic pulse fractionation supply and veterinary dermatology adoption |
| USA | 9.8% | Automated direct-to-consumer kibble subscriptions and specialty pet superstores |
| Australia | 9.1% | Quarantine biosecurity rules favoring domestic lupin and field-pea kibble |
| Sweden | 8.3% | Carbon-labeled pet food retail and cold-climate botanical fat fortification |
Source: Future Market Insights analysis
Israel Vegan Dog Food Market Outlook (2026 to 2036)
Tel Aviv and central Israel pair high urban household vegan alignment with hot Mediterranean summers that intensify canine atopic and food-allergy pruritus. Veterinary Services (SHVAT) animal feed supervision records from the Israel Ministry of Agriculture and Food Security in June 2026 documented a 19.0% annual rise in approved plant-based companion animal feed import permits across commercial ports [9]. Israeli plant-based dog food turnover is set to advance at a 12.6% ten-year CAGR as neighborhood veterinary clinics and urban pet boutiques stock imported meat-free kibble. While spring Passover retail rules restrict leavened grain ingredients in mainstream supermarkets—a religious dietary status distinct from clinical veterinary allergen control—port storage fees also push distributors toward grain-free pea formulas.
Key takeaway: In Israel, high urban vegan household density and grain-free Passover retail compliance propel plant-based canine ration adoption by 12.6% annually to 2036.
Singapore Vegan Dog Food Market Outlook (2026 to 2036)
High-density HDB public housing and private condominiums across Singapore shape companion dog nutrition around compact bag storage and low indoor stool odor. During the 2026-to-2036 window, Singapore vegan dog food turnover is set to expand at an 11.5% CAGR as same-day delivery apps bundle hypoallergenic kibble with natural dog treats for indoor toy and medium breeds. Updated pet food import conditions enforced by the Animal and Veterinary Service under the National Parks Board in July 2026 streamlined customs clearance for heat-treated non-animal feeds, supporting a 16.0% rise in vegetarian skin-elimination diets across private veterinary clinics [10]. Yet commercial uptake faces friction from 80% tropical humidity that oxidizes unsealed fats, forcing importers to specify nitrogen-flushed 2-kilogram foil pouches.
Key takeaway: In Singapore, high-rise apartment odor control and streamlined AVS heat-treated feed import rules anchor an 11.5% CAGR through 2036.
Canada Vegan Dog Food Market Outlook (2026 to 2036)
Direct rail access to Saskatchewan and Alberta dry-pea and lentil fractionation mills allows Canadian pet food extruders to procure high-purity plant protein isolates without ocean freight or cross-border tariff markups. Canadian Veterinary Medical Association clinical allergy guidance in December 2025 noted that 13.0% of canine chronic enteropathy and cutaneous food-allergy cases in domestic practices are managed with plant-protein maintenance rations [11]. However, sub-zero winter temperatures across prairie and northern provinces elevate caloric demand for active outdoor dogs, compelling Canadian formulators to enrich legume kibble with cold-pressed canola and camelina oils. The Canadian vegan dog food sector is projected to record 10.4% CAGR from 2026 to 2036 as specialty pet chains expand across Ontario and British Columbia.
Key takeaway: In Canada, proximity to prairie pulse fractionation mills and high-calorie winter lipid fortification support a 10.4% CAGR outlook.
USA Vegan Dog Food Market Outlook (2026 to 2036)
Subscription auto-ship platforms and veterinary tele-triage networks give the United States a distinct commercialization engine across the world's largest companion dog population. American Pet Products Association benchmarks from March 2026 confirmed that U.S. pet outlays reached USD 158.0 billion in 2025 across 71 million dog-owning homes (53% of households) and approach USD 165.0 billion for 2026 [12]. Domestic vegan dog food sales will compound at 9.8% annually through 2036, aided by FDA Center for Veterinary Medicine GRAS oversight for yeast and plant protein feed ingredients [13]. Nonetheless, raw-meat feeding advocacy and high supermarket slotting fees slow mass-grocery placement, concentrating volume in digital subscriptions and pet superstores.
Key takeaway: In the USA, direct-to-consumer subscription scale across 71 million dog-owning households underpins a 9.8% CAGR through 2036.
Australia Vegan Dog Food Market Outlook (2026 to 2036)
Strict federal quarantine borders isolate Australian companion animal retail from routine foreign kibble shipments and favor domestic grain-and-legume extrusion mills. Australian demand for plant-based canine diets is predicted to progress at a 9.1% CAGR through 2036 alongside locally baked commercial pet treats in urban eco-pet boutiques. Biosecurity Import Conditions (BICON) updated by the Australian Department of Agriculture, Fisheries and Forestry in July 2026 require verified thermal-processing certificates and border inspections for imported pet foods, encouraging an 11.0% annual shift toward domestically extruded Western Australian sweet-lupin and field-pea diets [14]. The central commercial obstacle involves extreme summer heat across long interstate road-train corridors, requiring local processors to stabilize algal and canola fat coatings with natural mixed tocopherols.
Key takeaway: In Australia, federal BICON quarantine barriers and domestic sweet-lupin extrusion underpin a 9.1% annual growth trajectory to 2036.
Sweden Vegan Dog Food Market Outlook (2026 to 2036)
Nordic grocery cooperatives and specialty pet chains in Stockholm and Gothenburg print per-kilogram carbon dioxide equivalents directly on shelf price tags, steering sustainability-minded dog owners away from beef-heavy feeds. Nevertheless, Sweden's mandatory 25% value-added tax on pet food and prolonged sub-arctic winter darkness restrain premium bag pricing and require fortification with lichen-derived vitamin D3 and algal DHA. Feed registration statistics from the Swedish Board of Agriculture (Jordbruksverket) in April 2026 recorded a 9.0% annual increase in approved plant-based and oat-pea companion maintenance rations [15]. Sweden's vegan dog food sector is anticipated to register an 8.3% CAGR over the decade as domestic extruders upcycle regional oats and cold-pressed rapeseed cake into complete adult kibble.
Key takeaway: In Sweden, shelf-edge carbon labeling and Nordic winter vitamin D3 fortification guide an 8.3% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the vegan dog food market?
V-dog, Wild Earth, Halo Pets, Benevo, Ami Pet Food, Biopet, Yarrah Organic Pet Food, and Omnipet are the significant market players in this market.
Supplier qualification in the vegan dog food market centers on whether a manufacturer can maintain strict animal-protein line segregation during extrusion while proving post-cooking taurine and methionine retention across 18-month shelf lives. Dedicated 100% meat-free brands including V-dog and Benevo alongside Ami Pet Food and Omnipet contract with allergen-segregated extrusion mills and build recurring revenue through direct-to-consumer subscriptions and veterinary dermatology referrals. Wild Earth and Halo Pets differentiate by blending precision-fermented yeast proteins and prebiotic fibers to raise apparent protein digestibility. Meanwhile, Yarrah Organic Pet Food and Biopet utilize certified European organic supply chains and domestic Australian sweet-lupin milling to serve regional specialty retailers.
- Dedicated Plant-Based Canine Pioneers: V-dog and Benevo alongside Ami Pet Food and Omnipet formulate 100% meat-free dry kibble and allergy-safe dental chews.
- Fermentation and Natural Nutrition Platforms: Wild Earth and Halo Pets combine precision-fermented yeast proteins with digestible whole-plant formulations.
- Certified Organic and Regional Specialists: Yarrah Organic Pet Food and Biopet supply certified organic and domestic pulse-based vegetarian dog foods across European and Australian retail channels.
Competitive Benchmarking: Vegan Dog Food Market
Table 8: Competitive Benchmarking for the Vegan Dog Food Market (qualitative capability ratings), 2026
| Company | Plant-Based Format Breadth | Amino Acid & Clinical Fortification | Specialty Retail & DTC Access | Geographic Reach |
|---|---|---|---|---|
| V-dog | High | High | High | Medium |
| Wild Earth | Medium | High | High | Medium |
| Halo Pets | High | High | High | High |
| Benevo | High | High | Medium | High |
| Ami Pet Food | High | High | Medium | High |
| Biopet | Medium | Medium | Medium | Medium |
| Yarrah Organic Pet Food | High | Medium | High | High |
| Omnipet | Medium | High | High | Medium |
Scoring basis: Format Breadth reflects whether a brand's catalog spans dry extruded kibble and wet retort cans alongside dental treats (High) or focuses primarily on dry rations (Medium). Amino Acid & Clinical Fortification evaluates documented taurine and algal DHA dosing alongside veterinary feeding trials. Specialty Retail & DTC Access measures active subscription auto-ship platforms paired with independent pet boutique placement, while Geographic Reach tracks export clearance across North America and Europe alongside Asia-Pacific.
Key Developments in the Vegan Dog Food Market
- In January 2026, Ami Pet Food expanded European specialty pet retail distribution of its Ami Dog 100% plant-based dry and wet canned canine maintenance line [16].
- In October 2025, Benevo expanded UK and European specialty distribution of its Benevo Dog Organic and Benevo Duo 100% plant-based companion recipes [17].
- In March 2025, Wild Earth scaled North American retail and e-commerce placement of its High Protein Performance Formula Veggie Supreme plant-based dry dog food [18].
Key Players in the Vegan Dog Food Market
Dedicated Plant-Based Canine Nutrition Pioneers
- V-dog
- Benevo
- Ami Pet Food
- Omnipet
Fermentation-Driven and Holistic Pet Nutrition Platforms
- Wild Earth
- Halo Pets
Certified Organic and Regional Pulse-Based Specialists
- Yarrah Organic Pet Food
- Biopet
Vegan Dog Food Market - Report Scope
Table 9: Report Scope for the Vegan Dog Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Dietary Nature; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from complete and complementary 100% plant-based, vegetarian, and precision-fermented non-animal dog foods and treats. Excludes meat-based, poultry-based, fish-based, and insect-protein canine diets. Category Scope Note: Market valuation reflects finished commercial plant-based canine maintenance rations and functional treats sold across retail and veterinary channels rather than gross all-species pet industry expenditure (USD 158.0 billion in U.S. spend) or upstream bulk raw pulse commodity sales. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Israel, Singapore, Canada, USA, Australia, Sweden, and additional countries in the full report |
| Key Companies Covered | V-dog, Wild Earth, Halo Pets, Benevo, Ami Pet Food, Biopet, Yarrah Organic Pet Food, Omnipet |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Vegan Dog Food Market - Research Methodology
Table 10: Research Methodology for the Vegan Dog Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with pet food extrusion engineers, veterinary nutritionists, companion animal dermatologists, specialty pet retail buyers, and ingredient formulators across the value chain to validate amino acid fortification protocols, palatability benchmarks, and channel purchasing dynamics. |
| Secondary Research | Secondary research included regulatory feed guidelines (AAFCO, FEDIAF, FDA CVM), national veterinary association surveys, agricultural pulse processing statistics, corporate product disclosures, and peer-reviewed companion animal nutrition journals. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up approaches reconciling household canine allergy prevalence, annual ration consumption volumes, and retail channel pricing. |
| Data Triangulation and Validation | Estimates were validated against national pet ownership registries, specialty pet store scanner data, and commercial ingredient production volumes to ensure accuracy without double counting conventional meat-based pet foods. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's companion animal nutrition econometric model, calibrating evaluated national growth rates against the 10.1% global baseline through verified veterinary food-allergy elimination diet adoption, urban household plant-based alignment, and specialty pet retail channel penetration. |
| Operational Benchmark Traceability | Operational benchmarks (enrolled canine allergy and meat-free diet cohorts, annual plant-based ration tonnage, and average annual spend per enrolled dog) represent modeled estimates synthesized from AAFCO nutrient profiles, FEDIAF production registries, PFI/IFEEDER ingredient audits, and commercial extruder disclosures. |
Vegan Dog Food Market by Segments
Vegan Dog Food Market segmented by Product Form:
- Dry Extruded Kibble
- Wet Canned Food & Pouches
- Freeze-Dried & Baked Treats
Vegan Dog Food Market segmented by Dietary Nature:
- Conventional Vegan Formulation
- Organic, Grain-Free & Clean-Label
Vegan Dog Food Market segmented by Distribution Channel:
- Specialty Pet Retail Stores
- Online E-Commerce Platforms
- Supermarkets & Mass Merchandisers
Vegan Dog Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Sweden
- Italy
- Spain
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Singapore
- Australia and New Zealand
- Middle East and Africa
- Israel
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Pet Food Institute & Institute for Feed Education and Research. (2025, April 7). Feeding pets, fueling the economy: 600+ ingredients drive $51.7B pet food sales, according to new IFEEDER report. Pet Food Institute.
- [2] Association of American Feed Control Officials. (2025). Ingredient standards: Understanding pet food. AAFCO.
- [3] V-dog. (2025). Kind Kibble: 100% plant-based complete and balanced adult dog food nutritional profile. V-dog.
- [4] British Small Animal Veterinary Association. (2025, September 4). BSAVA guide to nutrition in small animal practice – available now. BSAVA.
- [5] Omni Pet Limited. (2026, October 15). Best dry dog food | Allergy-friendly food for adult dogs | Omni. Omni Pet Limited.
- [6] Godglück, A., Hankel, J., Wilke, V., Ullrich, C., & Visscher, C. (2025, November 13). Investigation of the digestibility, fecal characteristics, and palatability of oil mill by-products as a plant-based protein source in canine diets. Animals, 15(22), 3279.
- [7] European Pet Food Industry Federation. (2025). Nutritional guidelines for complete and complementary pet food for cats and dogs. FEDIAF.
- [8] Klinmalai, P., Kamonpatana, P., Thongpech, A., Sodsai, J., Promhuad, K., Srisa, A., Laorenza, Y., Kovitvadhi, A., Areerat, S., Seubsai, A., Sablani, S. S., & Harnkarnsujarit, N. (2025, July 28). Comprehensive review of alternative proteins in pet food: Research publications, patents, and product trends in plant, aquatic, insect, and cell-based sources. Foods, 14(15), 2640.
- [9] Ministry of Agriculture and Food Security. (2026, June 3). Procedure for the import of dogs and cats into Israel and Veterinary Services (SHVAT) animal feed import supervision. Government of Israel (Gov.il).
- [10] Animal and Veterinary Service, National Parks Board. (2026, July 14). Importing pet food: Commercial importers and exporters of animal feed. Government of Singapore.
- [11] Canadian Veterinary Medical Association. (2025, December 9). Canine and feline allergies: Dietary management and clinical nutrition resources. CVMA.
- [12] American Pet Products Association. (2026, March 26). U.S. pet industry reaches $158 billion in 2025, poised for continued growth in 2026. APPA.
- [13] U.S. Food and Drug Administration. (2025). Pet food: Animal foods & feeds regulatory oversight. U.S. Department of Health and Human Services.
- [14] Department of Agriculture, Fisheries and Forestry. (2026, July 13). Importing animal feed: Biosecurity import conditions (BICON) for pet food, pet food ingredients, and supplements for companion animals. Australian Government DAFF.
- [15] Swedish Board of Agriculture (Jordbruksverket). (2026, April 22). Feed and animal products: Regulations for companion animals and pet food trade. Jordbruksverket.
- [16] Ami Pet Food S.r.l. (2026, January 20). Ami Dog: 100% plant-based complete dry and wet canine nutrition portfolio. Ami Planet.
- [17] Benevo. (2025, October 15). Benevo: Vegan pet food for dogs & cats | 100% plant-based recipes. Benevo.
- [18] Wild Earth. (2025, March 25). Wild Earth pet food: Vegan nutrition for healthy dogs & cats (High Protein Performance Formula Veggie Supreme). Wild Earth.
- [19] Halo Pets. (2025, July 22). Halo Holistic plant-based dry and wet dog food recipes with prebiotic fiber. Halo Pets.
- [20] Yarrah Organic Pet Food B.V. (2025, November 28). Organic vegetarian and vegan dog food product range and sustainability standards. Yarrah Organic Pet Food.
- [21] Biopet Australia. (2026, February 4). Biopet Vegan Dog Food: Australian pulse and sweet-lupin extruded adult dog nutrition. Biopet.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the vegan dog food market in 2026 and what is forecast for 2036?
- Which clinical allergy and amino acid fortification factors shape demand for vegan dog food?
- Why does dry extruded kibble lead the product form category?
- Why does conventional vegan formulation lead the dietary nature category globally?
- How do growth rates differ across Israel and Singapore alongside Canada and the USA?
- Which leading companies supply plant-based kibble, wet rations, and fermented yeast diets today?
- What limits adoption or retail margin expansion in the vegan dog food market?
- What should veterinary and retail buyers evaluate before qualifying a vegan dog food supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Dry Extruded Kibble
- Wet Canned Food & Pouches
- Freeze-Dried & Baked Treats
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Dietary Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Dietary Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Dietary Nature, 2026 to 2036
- Conventional Vegan Formulation
- Organic, Grain-Free & Clean-Label
- Y-o-Y Growth Trend Analysis By Dietary Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Dietary Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Pet Retail Stores
- Online E-Commerce Platforms
- Supermarkets & Mass Merchandisers
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Sweden
- Italy
- Spain
- Benelux
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Australia and New Zealand
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Israel
- GCC Countries
- South Africa
- By Product Form
- By Dietary Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Israel
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Singapore
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Dietary Nature
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Dietary Nature
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- V-dog
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Wild Earth
- Halo Pets
- Benevo
- Ami Pet Food
- Biopet
- Yarrah Organic Pet Food
- Omnipet
- V-dog
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Form
- Figure 6: Global Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Dietary Nature
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Form
- Figure 26: North America Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Dietary Nature
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Form
- Figure 36: Latin America Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Dietary Nature
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Form
- Figure 46: Western Europe Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Dietary Nature
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Form
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Dietary Nature
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Form
- Figure 66: East Asia Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Dietary Nature
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Form
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Dietary Nature
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Form
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Dietary Nature
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the vegan dog food market in 2026, and what is forecast for 2036?
The global vegan dog food market is projected to reach USD 5.7 billion in 2026 and expand further to USD 14.9 billion by 2036, supported by veterinary elimination diets for meat-allergic dogs.
What is the CAGR for the vegan dog food market from 2026 to 2036?
As per FMI, the vegan dog food market is projected to grow at a 10.1% CAGR from 2026 to 2036. Growth is supported by twin-screw extrusion advances and precision-fermented yeast palatability coatings.
Which product form segment holds a notable vegan dog food demand share in 2026?
Dry extruded kibble is projected to hold 51.0% of product form demand in 2026. The segment benefits from ambient shelf stability, economical per-meal portioning, and mechanical tartar removal.
Which dietary nature segment holds a notable vegan dog food share in 2026?
Conventional vegan formulation accounts for 68.0% of dietary nature demand in 2026. Demand is supported by accessible soy and yellow pea protein pricing across mainstream extrusion lines.
Which country has a notable vegan dog food expansion outlook during the forecast period?
FMI finds that Israel is projected to expand at a 12.6% CAGR during the 2026 to 2036 assessment period. Growth is supported by high urban vegan household adoption and veterinary dermatology prescriptions.
Which companies are active in the vegan dog food market during 2026?
Notable companies include V-dog, Wild Earth, Halo Pets, Benevo, Ami Pet Food, Biopet, Yarrah Organic Pet Food, and Omnipet. These manufacturers focus on amino acid fortification, fermented yeast proteins, and allergy-safe extrusion.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
