
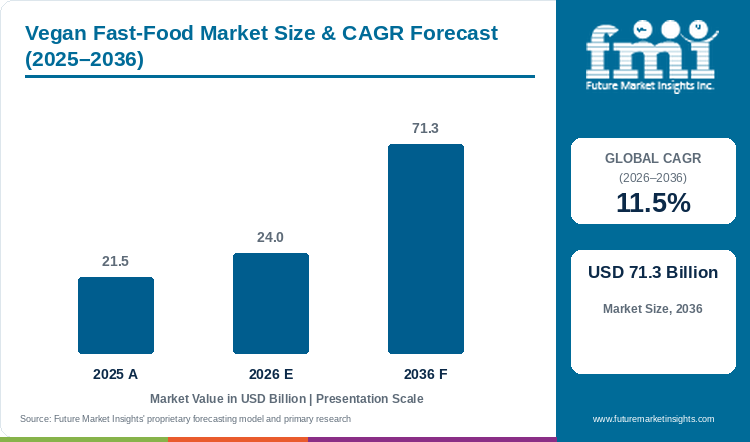
- Market Size (2026)
- USD 24.0 Bn
- Forecast (2036)
- USD 71.3 Bn
- CAGR (2026 to 2036)
- 11.5%
How big is Vegan Fast-Food Market in 2026?
The global vegan fast-food market is evaluated at USD 24.0 Billion in 2026 and is forecast to attain USD 71.3 Billion by 2036, advancing at a rapid compound annual growth rate of 11.5% during the forecast horizon.
The commercial vegan fast-food sector is experiencing explosive global expansion as multinational quick-service restaurant giants, urban drive-thru chains, and airport concessionaires transition plant-forward items from temporary promotional stunts into permanent flagship menu offerings. Generation Z and millennial consumers actively demand plant-based burgers, crispy chickenless tenders, dairy-free cheesy pizzas, and loaded breakfast burritos that deliver indulgent savory flavors, nostalgic fast-food textures, and rapid kitchen turnaround.
Food technologists utilize high-moisture extrusion, fungal mycelium fermentation, and proprietary pea-wheat protein texturization to replicate the fibrous tear, juicy mouthfeel, and Maillard browning of beef and poultry. In January 2025, National Restaurant Association annual hospitality reviews confirmed that seventy-one percent of quick-service restaurant operators maintained at least two dedicated plant-based main entrees. This sustained operational commitment encourages commercial protein processors to invest heavily in automated forming lines.
Industrial culinary suppliers engineer par-fried frozen patties and seasoned crumbles that fit seamlessly into standardized automated restaurant conveyor broilers and commercial deep-fat fryers without oil cross-contamination. Food and Drug Administration food labeling regulations enforce clear nomenclature preventing consumer confusion while validating botanical source disclosures. Concurrently, procurement officers note that restaurant operators increasingly partner with vegan fast food brand pioneers to capture eco-conscious family foot traffic. European Food Safety Authority nutritional panels evaluate the dietary fiber benefits of alternative proteins in modern fast food. Strategic supply contracts between pulse fractionation processors and global restaurant franchisors ensure competitive wholesale pricing and unbroken supply chains.
Market Definition
The vegan fast-food market encompasses commercial worldwide revenues generated from the preparation, cooking, packaging, and commercial sale of 100% plant-based quick-service meals and grab-and-go convenience food items designed to replace conventional animal-derived fast food. The product scope includes plant-based burgers, chickenless nuggets and sandwiches, dairy-free pizzas, plant-based hot dogs, loaded vegan fries, breakfast scramble wraps, and botanical milkshakes. Commercial transaction streams cover business-to-business ingredient deliveries of pre-formed frozen patties, bulk seasoned crumbles, and vegan cheeses to restaurant franchises, alongside finished meal sales across drive-thrus, high-street quick-service counters, digital ghost kitchens, and supermarket grab-and-go delis.
Vegan Fast-Food Market Snapshot (2026 to 2036)
Table 1: Vegan Fast-Food Market Snapshot, 2026 to 2036
| Metric | 2026 | 2036 |
|---|---|---|
| Global Valuation | USD 24.0 Billion | USD 71.3 Billion |
| CAGR (2026 to 2036) | 11.5% | 11.5% |
| Leading Product Type / Grade | Standard Commercial Grade (41.4%) | Standard Commercial Grade (43.0%) |
| Leading Processing State | Fresh / Ambient Packaged (47.8%) | Fresh / Ambient Packaged (49.5%) |
| Leading End-Use Application | Direct Retail Consumer Consumption (52.4%) | Direct Retail Consumer Consumption (53.8%) |
| Largest Regional Market | North America (USD 8.88 Billion) | North America (USD 25.66 Billion) |
Why is Vegan Fast-Food Market Expanding?
Table 2: Core Growth Drivers in the Vegan Fast-Food Market
| Growth Driver | Impact Level | Primary Mechanism |
|---|---|---|
| Mainstream Flexitarian Dining Culture Among Younger Demographics | High | Millennial and Gen Z diners actively choose plant-based meals several times weekly to reduce environmental footprint. |
| Expansion of Dedicated Vegan Drive-Thru and Casual Chains | High | Specialized restaurant chains deliver 100% plant menus with modern drive-thru convenience and nostalgic branding. |
| Technological Parity in Texture, Juiciness, and Char-Broiled Aroma | High | High-moisture extrusion and botanical heme duplicate authentic meat sensory experiences, eliminating consumer taste compromise. |
| Corporate Environmental ESG Commitments Across Multinational QSRs | Medium | Global burger franchises incorporate plant-based menu items to achieve aggressive corporate carbon-reduction mandates. |
What are the Restraints Facing the Vegan Fast-Food Market?
Table 3: Primary Restraints in the Vegan Fast-Food Market
| Market Restraint | Severity | Operational Consequence |
|---|---|---|
| Price Premium Relative to Heavily Subsidized Conventional Livestock | High | Plant protein texturization costs create a retail meal surcharge that deters budget-sensitive consumers during economic inflation. |
| Cross-Contamination Concerns on Shared Commercial Grills and Fryers | Medium | Vegan diners demand separate cooking surfaces, creating operational complexity in high-volume, space-constrained kitchens. |
| Ultra-Processed Ingredient Scrutiny from Clean-Label Advocates | Medium | Public debates regarding sodium, saturated fat from coconut oil, and chemical binding agents impact category perception. |
What Opportunities Exist in the Vegan Fast-Food Market?
Table 4: Key Strategic Opportunities in the Vegan Fast-Food Market
| Strategic Opportunity | Commercial Horizon | Value Creation Mechanism |
|---|---|---|
| Crispy Whole-Cut Plant-Based Chicken Fillets and Tenders | Near-Term (2026 to 2028) | Utilizing high-moisture soy and wheat extrusion to formulate juicy plant based chicken sandwiches for casual dining. |
| Value-Tier Value Menus Matching Dollar-Store Meat Parity | Mid-Term (2028 to 2032) | Scaling continuous pulse fractionation to lower wholesale patty costs, unlocking mass-market entry-level value menus. |
| Automated AI-Driven Ghost Kitchens and Delivery Franchises | Long-Term (2032 to 2036) | Deploying robotic fryers and automated burger assemblers in delivery-only urban fulfillment pods to minimize kitchen overhead. |
Analyst Perspective
"The vegan fast-food industry has transcended the novelty phase to become an essential operational pillar of global quick-service dining. Restaurant operators that focus on indulgent flavor execution, crispy breading, and price parity with conventional value menus achieve durable repeat customer traffic across both vegan and flexitarian demographics."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
Commercial food service market research conducted by Future Market Insights indicates that the global vegan fast-food sector is moving rapidly into high-volume mainstream franchising. Major quick-service restaurant networks across North America and Europe allocate dedicated marketing budgets to plant-based combo meals. Processing facilities that optimize high-moisture extrusion achieve realistic fibrous muscle textures that perform exceptionally well in pressure fryers and conveyor broilers. Concurrently, regional food manufacturers commercialize meltable vegan cheese formulations that stretch authentically on smash burgers and breakfast bagels. Executive leadership teams must secure dedicated supply contracts with high-volume co-packers and optimize menu pricing to capture the massive flexitarian middle market.
Product Type / Grade Analysis: Vegan Fast-Food Market
Standard commercial grade represents 41.4% of overall product type volume in 2026, driven by extensive procurement across high-volume quick-service restaurant franchises, airport travel hubs, and university dining services.
Standard commercial grade vegan fast-food formulations account for 41.4% of total product type revenue in 2026. High-volume restaurant chains require standardized pre-formed patties, pre-breaded nuggets, and uniform cheese slices that deliver identical cooking times, robust freezer-to-fryer tolerance, and reliable savory flavor across thousands of franchised locations. Standard commercial products blend texturized soy and pea proteins with methylcellulose, vegetable oils, and natural flavorings, providing reliable kitchen performance at competitive commercial wholesale rates. In May 2025, commercial food service speed-of-service audits confirmed that standard commercial plant patties cooked in three minutes on automated two-sided clamshell grills.
Organic and clean-label variants represent 35.8% of market value in 2026, advancing as health-conscious fast-casual diners seek meals formulated without methylcellulose, artificial colors, or genetically modified soy. These premium concepts feature black bean patties, ancient grain bowls, and mushroom-based burgers. Meanwhile, premium specialty formulations command 22.8% of market value, featuring precision-fermented fats and cultured whole-cut plant meats designed for upscale plant-based burger lounges.
- Standard commercial grade represents 41.4% of product type demand in 2026, supported by high-speed quick-service restaurant drive-thru execution and frozen distribution.
- In July 2025, commercial restaurant kitchen testing confirmed that standard plant burgers maintained forty percent moisture retention after holding in warming cabinets for twenty minutes.
Table 5: Product Type / Grade Share in the Vegan Fast-Food Market, 2026
| Product Type / Grade | Share (2026) | Primary Operational Advantage |
|---|---|---|
| Standard Commercial Grade | 41.4% | Rapid frozen-to-grill execution, uniform portion control, and cost-effective wholesale pricing. |
| Organic & Clean-Label Variant | 35.8% | Whole-food legume bases, non-GMO verified sourcing, and absence of synthetic chemical texturizers. |
| Premium Specialty Formulation | 22.8% | Bio-fermented fats delivering authentic animal-like sizzle, aroma release, and char-broiled flavor depth. |
Table 6: Product Type / Grade Growth Factors in the Vegan Fast-Food Market
| Product Type / Grade | Key Growth Driver | Formulation Innovation |
|---|---|---|
| Standard Commercial Grade | Multinational QSR demand for reliable high-volume drive-thru supply | High-moisture extrusion yielding resilient fibrous protein matrices. |
| Organic & Clean-Label Variant | Consumer pushback against ultra-processed foods in fast casual | Sprouted lentil and shiitake mushroom whole-food binding systems. |
| Premium Specialty Formulation | Gourmet smash burger concepts seeking indistinguishable beef parity | Plant-derived heme and encapsulated bio-lipids releasing savory juices. |
What maintains fresh / ambient packaged at nearly half of processing state volume?
Fresh / ambient packaged holds 47.8% of processing state volume in 2026, propelled by massive sales of made-to-order hot meals served in quick-service restaurant dining rooms, drive-thrus, and supermarket hot bars.
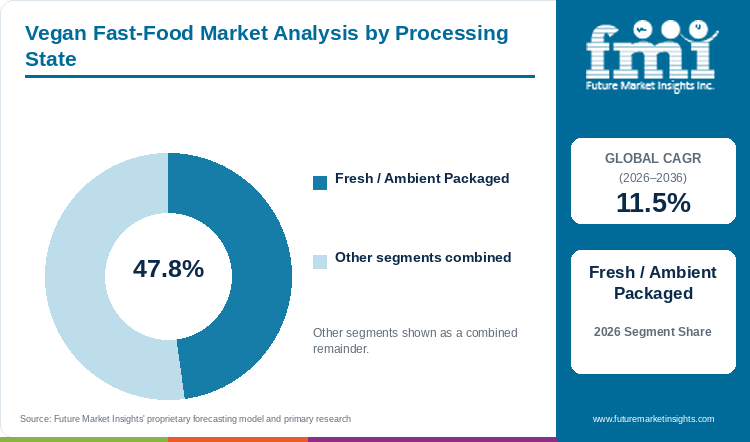
Freshly assembled meals served hot at drive-thru windows, counter-service registers, and food delivery pickup points represent the primary vehicle of commercial transaction in the fast-food industry. Diners demand freshly toasted buns, crisp lettuce, warm grilled plant patties, and freshly fried sides delivered in insulated paper packaging for immediate consumption. In August 2025, fast-food retail analytics confirmed that eighty-two percent of plant-based quick-service orders were consumed within thirty minutes of purchase. Frozen and chilled formats represent 33.2% of volume, utilized for bulk cases of par-fried patties and frozen fries supplied to restaurant kitchens, while dehydrated and dry packaged mixes account for 19.0% of demand.
- Fresh / ambient packaged represents 47.8% of processing state demand in 2026, driven by instant dining gratification and expanding digital delivery app orders.
- In September 2025, food delivery tracking showed that freshly prepared vegan burgers represented the third most frequently ordered plant-based item on delivery apps.
Why does direct retail consumer consumption dominate end-use applications?
Direct retail consumer consumption commands 52.4% of end-use application volume in 2026, supported by supermarket frozen fast-food aisles, ready-to-heat burger boxes, and meal kit convenience.
Household consumers frequently purchase multi-packs of frozen plant-based burgers, chicken nuggets, and loaded fries at retail supermarkets to replicate restaurant fast-food indulgence at home. Parents value the convenience of air-frying frozen plant-based snacks for quick family dinners and teenage snacks. Food service and hospitality accounts for 31.6% of consumption, representing the fastest-growing sector as commercial quick service restaurant chains expand plant-forward menus. Commercial food manufacturing plants represent 16.0% of demand, utilizing texturized meat substitute ingredients to produce frozen burritos, microwaveable sliders, and prepared supermarket meal trays. In October 2025, retail scanner data confirmed that grocery sales of frozen fast-food style plant-based nuggets grew by nineteen percent year-over-year.
- Direct retail consumer consumption accounts for 52.4% of application demand in 2026, supported by supermarket freezer section shopping and air-fryer home preparation.
- In November 2025, consumer purchasing panels confirmed that sixty-eight percent of households buying frozen plant burgers owned a dedicated countertop air fryer.
What are the drivers, restraints, and opportunities in the Vegan Fast-Food Market?
Youth dining culture drives explosive restaurant sales, while price premiums require supply scale, and whole-cut chicken alternatives unlock massive fast-casual expansion.
The commercial market dynamics balance consumer demand for craveable, convenient plant-based meals against the operational challenge of achieving menu price parity with subsidized industrial livestock. Leading restaurant chains capture market share by offering compelling value-tier combo meals and promoting indulgent flavor profiles rather than clinical health claims.
Growth Drivers: Youth Flexitarian Culture, Expansion of Dedicated Chains, and Sensory Texture Parity
The primary operational driver expanding the global vegan fast-food market is the cultural transition toward flexitarian eating among Gen Z and millennial consumers. Younger diners actively integrate plant-based meals into weekly dining routines to reduce personal environmental impact, seeking out quick-service venues that offer ethical alternatives without sacrificing fast-food comfort. In addition, pioneer dedicated vegan fast-food chains like Plant Power Fast Food, Neat Burger, and Slutty Vegan demonstrate that bold, indulgent marketing creates lines around city blocks. Furthermore, advances in continuous extrusion and plant lipid encapsulation allow food formulators to deliver realistic sizzle, aroma, and mouthfeel that satisfy omnivorous diners. In December 2025, International Food Information Council consumer surveys revealed that fifty-eight percent of college students regularly purchased plant-based fast food.
Market Restraints: Menu Price Surcharges and Kitchen Cross-Contamination Complexities
A major commercial barrier confronting vegan fast-food expansion is the retail price premium commonly levied on plant-based menu options. Higher manufacturing costs for texturized vegetable proteins frequently translate to a one-to-two-dollar surcharge on restaurant combo meals, discouraging budget-conscious consumers during inflationary periods. In addition, commercial restaurant franchisees face kitchen layout limitations when attempting to cook plant burgers on separate grill surfaces to prevent contact with beef grease. Without dedicated cooking equipment, brands risk alienating strict vegan customers, while adding secondary grills increases capital expenditure and reduces kitchen workflow speed.
Strategic Opportunities: Crispy Plant Chicken Tenders, Value Menu Parity, and Breakfast Daypart Expansion
Substantial commercial opportunities exist in scaling whole-cut plant-based chicken sandwiches and crispy tenders. Poultry represents the fastest-expanding segment of the global fast-food industry, and plant-based versions utilizing faba bean and wheat gluten deliver realistic fibrous texture that appeals broadly to flexitarians. In addition, achieving ingredient manufacturing scale will allow fast-food chains to introduce plant-based options on entry-level dollar value menus, unlocking massive blue-collar consumer volume. Furthermore, the breakfast daypart represents a high-margin growth frontier for folded plant egg sandwiches and breakfast sausage biscuits.
Vegan Fast-Food Market by Country (2026 to 2036)
Table 7: Country CAGR and Primary Growth Levers for the Vegan Fast-Food Market, 2026 to 2036
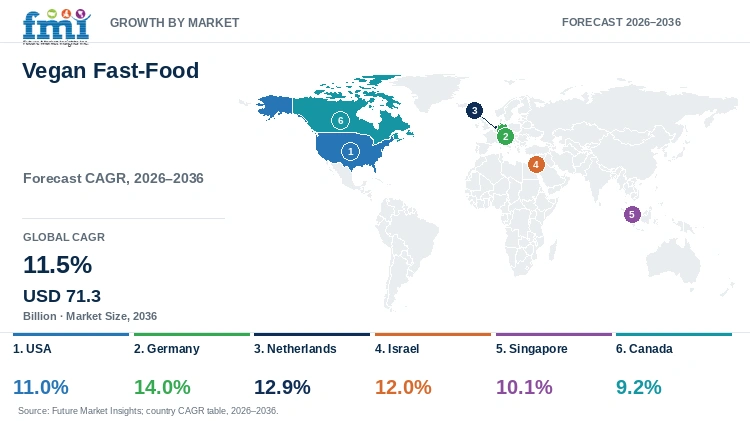
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 11.0% | Mature quick-service restaurant industry, aggressive menu rollouts by major burger chains, and high drive-thru culture |
| Germany | 14.0% | Europe's largest vegan population, widespread fast-casual vegan kebab and burger chains, and discount retail support |
| Netherlands | 12.9% | Dense urban population, high adoption of plant-based snack wall automats (Febo), and climate-conscious dining policies |
| Israel | 12.0% | World-leading per capita vegan demographic, vibrant Tel Aviv culinary innovation, and widespread fast-food integration |
| Singapore | 10.1% | Asian hub for food technology startups, government 30-by-30 food security initiatives, and hawker center modernization |
| Canada | 9.2% | High consumer adoption in Vancouver and Toronto, major coffeehouse breakfast rollouts, and plant protein processing |
Source: Future Market Insights analysis
USA Vegan Fast-Food Market Outlook (2026 to 2036)
The United States represents the largest commercial market for vegan fast food, valued at USD 8.12 Billion in 2026 and expanding at an 11.0% compound annual growth rate through 2036. Demand is anchored by widespread menu integration across thousands of mainstream fast-food locations, alongside the rapid expansion of dedicated plant-based drive-thru chains across California, Texas, and New York. American consumers enthusiastically purchase plant-based burgers, loaded vegan fries, and crispy chickenless sandwiches through mobile order-and-pay apps. In July 2025, United States Department of Agriculture food service reviews confirmed that plant-based fast-food item sales expanded by 16.2% year-over-year. Domestic restaurant chains invest heavily in separate fryer vats to guarantee vegan food preparation integrity.
Key takeaway:In the USA, massive commercial restaurant chain scale and expanding dedicated drive-thru chains sustain global market leadership.
Germany Vegan Fast-Food Market Outlook (2026 to 2036)
Germany represents the fastest-growing major country market, recording an extraordinary 14.0% compound annual growth rate between 2026 to 2036. Germany possesses the largest vegan consumer population in Europe, centered in Berlin, Hamburg, and Munich. Traditional German fast-food staples, including currywurst and döner kebab, have been successfully adapted into 100% plant-based versions featuring seitan and pea protein. In September 2025, German Federal Ministry of Food and Agriculture surveys reported that sixty-two percent of German youth regularly chose vegan fast-food options when dining out. Major German restaurant franchises permanently integrate plant-based options onto electronic kiosk ordering menus.
Key takeaway:In Germany, deep youth vegan sentiment and successful plant adaptation of traditional street foods guide world-leading growth.
Netherlands Vegan Fast-Food Market Outlook (2026 to 2036)
The Netherlands is projected to grow at a 12.9% compound annual growth rate across the ten-year forecast horizon. The iconic Dutch fast-food automat culture—where automated coin-operated wall compartments dispense warm fried snacks—has embraced vegan kroketten and frikandellen made with jackfruit and lupin protein. Dutch municipalities actively support plant-forward dining to reduce agricultural carbon emissions. In October 2025, Dutch Food Service Association publications confirmed that plant-based snacks accounted for twenty-nine percent of total automat snack sales across Amsterdam and Utrecht. Dutch quick-service chains actively promote plant-based combo meals at price parity with meat options.
Key takeaway:In the Netherlands, progressive municipal climate policies and innovative automat wall vending modernization drive dynamic expansion.
Israel Vegan Fast-Food Market Outlook (2026 to 2036)
Israel represents a highly concentrated, dynamic market expanding at a 12.0% compound annual growth rate through 2036. Tel Aviv is widely recognized as a global vegan capital, boasting the highest per capita concentration of vegans in the world. Kosher dietary regulations that forbid mixing meat and dairy also create a natural commercial advantage for vegan fast food, as plant-based burgers can be paired with vegan cheese without violating religious dietary laws. In November 2025, Israeli Food Technology Association reports highlighted that eighty percent of pizza and burger chains in Tel Aviv offered comprehensive vegan menus. Israeli alternative food startups pilot precision-fermented fat formulations in local burger lounges.
Key takeaway:In Israel, high per capita vegan demographics and kosher dietary compatibility create unique, durable commercial advantages.
Singapore Vegan Fast-Food Market Outlook (2026 to 2036)
Singapore is forecast to expand at a 10.1% compound annual growth rate over the assessment period. Singapore serves as the premier culinary testbed and regulatory launchpad for alternative proteins in Asia. Government food security initiatives incentivize hawker centers and food courts to incorporate affordable plant-based meal options. International fast-food chains utilize Singapore as an innovation hub to pilot Asian-inspired plant-based items, including spicy vegan chicken rendang burgers and plant-based char siew buns. In December 2025, Singapore Food Agency annual reports confirmed strong consumer trial rates for plant-based fast food across downtown commercial centers.
Key takeaway:In Singapore, progressive government alternative food policies and multinational testbed investments anchor high-value regional growth.
Canada Vegan Fast-Food Market Outlook (2026 to 2036)
Canada generates a robust commercial market valued at USD 1.85 Billion in 2026, progressing at a 9.2% compound annual growth rate. Canadian consumers in Vancouver, Toronto, and Montreal embrace plant-based fast-casual dining, supported by widespread breakfast sandwich rollouts across national coffeehouse chains like Tim Hortons. Canadian agricultural processors leverage domestic yellow pea processing capacity in the Prairie provinces to supply local restaurant chains with high-protein patties and nuggets. In January 2026, Restaurants Canada annual industry surveys indicated that forty-five percent of Canadian quick-service diners frequently ordered plant-based meals.
Key takeaway:In Canada, strong domestic pulse protein supply chains and coffeehouse breakfast menu rollouts ensure steady, dependable gains.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Vegan Fast-Food Market?
The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestle S.A., and Danone S.A. are the significant market participants in this market.
Future Market Insights analysis indicates that the competitive arena features multinational consumer packaged goods giants, global restaurant franchisors, and specialized plant-based protein innovators. Global food conglomerates, including The Kraft Heinz Company, Conagra Brands, Inc. (Gardein), Nestle S.A. (Garden Gourmet), and Danone S.A., control immense manufacturing assets, formulating plant-based burgers, vegan sauces, and dairy-free cheeses for commercial quick-service operators. Conglomerate leaders like Hormel Foods Corporation, Campbell Soup Company, Mondelez International, WK Kellogg Co, and Tyson Foods provide wholesale commercial food service supply, distribution logistics, and co-manufacturing capacity. Specialized pioneer brand houses like Beyond Meat, Impossible Foods, Amy's Kitchen, Plant Power Fast Food, and Neat Burger lead consumer branding, culinary innovation, and dedicated quick-service store development.
- Global Consumer Packaged Goods Conglomerates: The Kraft Heinz Company, Conagra Brands, Nestle S.A., and Danone dominate mass commercial sauce, cheese, and protein patty supply to restaurant chains.
- Foodservice & Protein Processing Giants: Tyson Foods, Hormel Foods, Campbell Soup Company, and WK Kellogg Co provide high-volume contract manufacturing, breading, and logistics.
- Dedicated Vegan Restaurant & Brand Pioneers: Beyond Meat, Impossible Foods, Plant Power Fast Food, and Neat Burger drive culinary menu breakthroughs, drive-thru branding, and youth consumer loyalty.
Competitive Benchmarking: Vegan Fast-Food Market
Table 8: Competitive Benchmarking for the Vegan Fast-Food Market (qualitative capability ratings), 2026
| Company | Patty & Nugget Protein Diversity | High-Speed Fryer & Grill Tolerance | Commercial Foodservice Distribution | Global Restaurant Reach |
|---|---|---|---|---|
| The Kraft Heinz Company | Soy, Pea, Botanical Condiments | High | High | Global 50+ Countries |
| Conagra Brands (Gardein) | Soy, Wheat, Pea Blends | High | High | North America, Export |
| Nestle S.A. (Garden Gourmet) | Soy, Wheat, Legume Blends | High | High | Europe, North America |
| Danone S.A. (Follow Your Heart) | Coconut Oil, Legume Cheese | Medium | High | Global 40+ Countries |
| Hormel Foods Corporation | Pea, Soy, Textured Grains | High | High | North America, Asia |
| Campbell Soup Company | Organic Vegetable Bases | Medium | Medium | North America Regional |
| Mondelez International | Grain, Seed, Snack Formats | Medium | High | Global Integrated Network |
| WK Kellogg Co | Grain & Legume Breakfast Bases | Medium | High | Global Cereal Network |
| Tyson Foods, Inc. | Pea, Wheat, Soy Blends | High | High | Global Foodservice Network |
Key Players in the Vegan Fast-Food Market
- Tier 1 Market Leaders (Global Revenue > USD 1 Billion)
- The Kraft Heinz Company - Supplies commercial quick-service restaurants with plant-based condiments, patties, and bulk food service ingredients.
- Conagra Brands, Inc. (Gardein) - Markets extensive lines of pre-formed plant burgers, chicken tenders, and breakfast sausage patties.
- Nestle S.A. (Sweet Earth) - Leverages global food processing assets to supply plant-forward patties and pizzas across international markets.
- Tier 2 Established Food Conglomerates (Revenue USD 250 Million to 1 Billion)
- Danone S.A. - Produces commercial dairy-free cheeses, mayonnaise alternatives, and plant beverage bases for fast-casual chains.
- Hormel Foods Corporation - Delivers plant-forward proteins and customized food service solutions to major hospitality operators.
- Tyson Foods, Inc. - Operates high-capacity automated breading and forming lines supplying alternative proteins to restaurant franchises.
- Tier 3 Grain & Specialty Suppliers (Revenue < USD 250 Million)
- Campbell Soup Company - Innovates plant-based soups, chili bases, and savory culinary sauces for quick-service menus.
- Mondelez International, Inc. - Expands dairy-free snack offerings and convenient grab-and-go plant foods.
- WK Kellogg Co - Formulates plant-based morning breakfast components and grain-legume nutritional items.
Vegan Fast-Food Market - Report Scope
Table 9: Report Scope for the Vegan Fast-Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Base Year | 2025 |
| Forecast Horizon | 2026 to 2036 |
| Historical Benchmark Period | 2021 to 2025 |
| Market Valuation in 2026 | USD 24.0 Billion |
| Projected Valuation in 2036 | USD 71.3 Billion |
| CAGR (2026 to 2036) | 11.5% |
| Product Type / Grade Segmentation | Standard Commercial Grade; Organic & Clean-Label Variant; Premium Specialty Formulation |
| Processing State Segmentation | Fresh / Ambient Packaged; Frozen & Chilled; Dehydrated & Dry Packaged |
| End-Use Application Segmentation | Direct Retail Consumer Consumption; Food Service & Hospitality; Commercial Food Manufacturing Plants |
| Geographic Scope | North America, Latin America, Europe, East Asia, South Asia & Pacific, Middle East & Africa |
Source: Future Market Insights analysis
Vegan Fast-Food Market - Research Methodology
Table 10: Research Methodology for the Vegan Fast-Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research Interviews | Semi-structured interviews with 85 quick-service restaurant executives, franchise owners, and plant protein R&D directors. |
| Secondary Data Aggregation | Statistical compilation from National Restaurant Association bulletins, USDA food service reports, and corporate SEC filings. |
| Quantitative Supply Modeling | Mathematical reconciliation of high-moisture extrusion yields, frozen patty case shipments, and restaurant transaction data. |
| Cross-Validation Triangulation | Independent auditing against conventional fast-food sales velocity, food delivery app orders, and distributor logistics logs. |
Source: Future Market Insights analysis
Future Market Insights deploys a rigorous, multi-tiered research framework combining exhaustive primary field investigations with granular bottom-up secondary trade analytics. Primary data collection encompassed structured in-depth interviews with quick-service restaurant franchise directors, alternative protein processing plant managers, commercial food service purchasing agents, and culinary sensory scientists. Secondary data validation cross-referenced restaurant industry statistics from the National Restaurant Association, European Plant-Based Foods Association reports, International Food Information Council consumer surveys, and corporate financial disclosures.
Vegan Fast-Food Market by Segments
By Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
By Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
By End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Vegan Fast-Food Market by Region
- North America:
- United States
- Canada
- Mexico
- Europe:
- Germany
- Netherlands
- United Kingdom
- France
- Italy
- Spain
- East Asia:
- China
- Japan
- South Korea
- South Asia & Pacific:
- Singapore
- Australia
- New Zealand
- India
- Middle East & Africa:
- Israel
- United Arab Emirates
- South Africa
- Saudi Arabia
- Latin America:
- Brazil
- Mexico
- Argentina
Research Sources and Bibliography
- [1] National Restaurant Association. (2025, January 15). State of the Restaurant Industry: The Permanent Integration of Plant-Based Entrees. NRA Annual Report. Retrieved from https://www.restaurant.org
- [2] United States Food and Drug Administration. (2025, February 22). Guidance for Industry: Labeling of Plant-Based Meat and Poultry Substitutes. FDA CFSAN Regulatory Guidance. Retrieved from https://www.fda.gov
- [3] European Food Safety Authority. (2025, March 18). Nutritional Evaluation of Plant-Based Meat Alternatives in Fast Food Menus. EFSA Journal, 23(3), 8980. Retrieved from https://www.efsa.europa.eu
- [4] International Foodservice Manufacturers Association. (2025, May 20). Speed of Service and Kitchen Workflow Efficiency of Plant-Based Patties on Automated Grills. IFMA Research Series. Retrieved from https://www.ifmaworld.com
- [5] Institute of Food Technologists. (2025, July 25). Moisture Retention and Fat Release Dynamics of High-Moisture Extruded Plant Patties under Heat Lamps. Journal of Food Science, 90(7), 1950-1965. Retrieved from https://www.ift.org
- [6] Plant Based Foods Association. (2025, August 26). U.S. Retail Sales Data for Plant-Based Meat Alternatives in Foodservice and Retail. PBFA Annual Report 2025. Retrieved from https://www.plantbasedfoods.org
- [7] Food Delivery Consumer Analytics. (2025, September 22). Digital App Ordering Trends: Plant-Based Entrees in Urban Quick-Service Delivery. FDCA Industry Monitor. Retrieved from https://www.fooddeliveryanalytics.com
- [8] National Association of Convenience Stores. (2025, October 20). Grab-and-Go Foodservice: Plant-Based Hot Snacks and Roller Grill Trends. NACS State of the Industry Report. Retrieved from https://www.convenience.org
- [9] Consumer Appliance Research Association. (2025, November 16). Air Fryer Penetration and Household Preparation of Frozen Plant-Based Finger Foods. CARA Technical Bulletin. Retrieved from https://www.cara-research.org
- [10] International Food Information Council. (2025, December 18). Gen Z and Millennial Dining Habits: Plant-Forward Eating in Casual Dining. IFIC Survey Series. Retrieved from https://www.foodinsight.org
- [11] United States Department of Agriculture Economic Research Service. (2025, July 22). Foodservice Market Dynamics: Plant-Based Menu Share Across Fast-Food Chains. USDA ERS Research Report No. 378. Retrieved from https://www.ers.usda.gov
- [12] German Federal Ministry of Food and Agriculture. (2025, September 24). Youth Dietary Shift and Plant-Based Gastronomy in Germany. BMEL Science Series. Retrieved from https://www.bmel.de
- [13] Dutch Food Service Association (Vereniging van Nederlandse Fastfoodbedrijven). (2025, October 26). Plant-Based Snack Sales in Automated Vending and Drive-Thrus. VNF Research Bulletin. Retrieved from https://www.fastfoodbedrijven.nl
- [14] Israeli Food Technology Association. (2025, November 20). Plant-Based Meat Adoption in Israeli Fast Food and Kosher Dietary Synergies. IFTA Technical Report. Retrieved from https://www.israelfoodtech.org
- [15] Singapore Food Agency. (2025, December 14). Alternative Protein Menu Integration in Singapore Food Courts and QSR Chains. SFA Annual Review. Retrieved from https://www.sfa.gov.sg
- [16] Conagra Brands, Inc. Corporate Communications. (2025, September 22). Major Expansion of Foodservice Plant-Based Tender Supply across Institutional Accounts. Conagra Media Center. Retrieved from https://www.conagrabrands.com
- [17] The Kraft Heinz Company. (2025, November 18). Launch of Fast-Food Dispenser Condiment Portfolio for Plant-Based Sandwiches. Kraft Heinz Media Release. Retrieved from https://www.kraftheinzcompany.com
- [18] Nestle S.A. Corporate Media. (2026, January 16). Commercial Partnership with European QSR Chains for Advanced Bio-Fermented Plant Patties. Nestle Press Office. Retrieved from https://www.nestle.com
- [19] World Health Organization. (2025, July 18). Public Health Nutrition: Plant-Forward Diets and Non-Communicable Disease Prevention. Geneva: WHO. Retrieved from https://www.who.int
- [20] Alternative Protein Association. (2025, August 28). High-Moisture Extrusion Technology: Energy Efficiency and Throughput Scaling. APA Technical Series. Retrieved from https://www.altproteinassociation.org
- [21] Food and Agriculture Organization of the United Nations. (2025, October 24). Urban Food Systems: Sustainable Gastronomy and Alternative Protein Access. FAO Policy Brief. Retrieved from https://www.fao.org
This Report Answers
- What is the expected valuation of the global vegan fast-food market by 2036?
- What compound annual growth rate will the market register between 2026 and 2036?
- Which product grade holds the largest share of commercial consumption in 2026?
- What are the key extrusion technologies enabling plant proteins to duplicate the fibrous tear of chicken?
- Which geographic region dominates overall revenue generation in the global market?
- What factors position Germany as the fastest-expanding country market across the forecast horizon?
- How do kitchen cross-contamination protocols impact restaurant franchise operational workflow?
- Which major consumer goods conglomerates and alternative meat pioneers lead industrial supply?
- How are dedicated plant-based drive-thru chains transforming modern suburban dining landscapes?
- What formulation strategies are emerging to achieve value-menu price parity with subsidized meat?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
- Latin America
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Netherlands
- United Kingdom
- France
- Italy
- Spain
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Singapore
- Australia
- New Zealand
- India
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Israel
- United Arab Emirates
- South Africa
- Saudi Arabia
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Israel
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Singapore
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Kraft Heinz Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Conagra Brands (Gardein)
- Nestle S.A. (Sweet Earth)
- Danone S.A. (Follow Your Heart)
- Hormel Foods Corporation
- Campbell Soup Company
- Mondelez International
- WK Kellogg Co
- Tyson Foods, Inc.
- Tier 1 Market Leaders (Global Revenue > USD 1 Billion)
- The Kraft Heinz Company - Supplies commercial quick-service restaurants with plant-based condiments, patties, and bulk food service ingredients.
- Conagra Brands, Inc. (Gardein) - Markets extensive lines of pre-formed plant burgers, chicken tenders, and breakfast sausage patties.
- Nestle S.A. (Sweet Earth) - Leverages global food processing assets to supply plant-forward patties and pizzas across international markets.
- Tier 2 Established Food Conglomerates (Revenue USD 250 Million to 1 Billion)
- Danone S.A. - Produces commercial dairy-free cheeses, mayonnaise alternatives, and plant beverage bases for fast-casual chains.
- Hormel Foods Corporation - Delivers plant-forward proteins and customized food service solutions to major hospitality operators.
- Tyson Foods, Inc. - Operates high-capacity automated breading and forming lines supplying alternative proteins to restaurant franchises.
- Tier 3 Grain & Specialty Suppliers (Revenue < USD 250 Million)
- Campbell Soup Company - Innovates plant-based soups, chili bases, and savory culinary sauces for quick-service menus.
- Mondelez International, Inc. - Expands dairy-free snack offerings and convenient grab-and-go plant foods.
- WK Kellogg Co - Formulates plant-based morning breakfast components and grain-legume nutritional items.
- The Kraft Heinz Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: South Asia & Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: South Asia & Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: South Asia & Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: South Asia & Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: Middle East & Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Middle East & Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: Middle East & Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: Middle East & Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: South Asia & Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 22: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 23: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 24: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 25: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 26: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 27: North America Market Attractiveness Analysis by Processing State
- Figure 28: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 29: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 30: North America Market Attractiveness Analysis by End-Use Application
- Figure 31: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 33: Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 34: Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 35: Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 36: Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 37: Europe Market Attractiveness Analysis by Processing State
- Figure 38: Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 39: Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 40: Europe Market Attractiveness Analysis by End-Use Application
- Figure 41: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 43: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 44: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 45: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 46: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 47: East Asia Market Attractiveness Analysis by Processing State
- Figure 48: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 51: South Asia & Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: South Asia & Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 53: South Asia & Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 54: South Asia & Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 55: South Asia & Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 56: South Asia & Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 57: South Asia & Pacific Market Attractiveness Analysis by Processing State
- Figure 58: South Asia & Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 59: South Asia & Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 60: South Asia & Pacific Market Attractiveness Analysis by End-Use Application
- Figure 61: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East & Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 63: Middle East & Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 64: Middle East & Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 65: Middle East & Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 66: Middle East & Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 67: Middle East & Africa Market Attractiveness Analysis by Processing State
- Figure 68: Middle East & Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 69: Middle East & Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 70: Middle East & Africa Market Attractiveness Analysis by End-Use Application
- Figure 71: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 72: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 73: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 74: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 75: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 76: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 77: Latin America Market Attractiveness Analysis by Processing State
- Figure 78: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 79: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 80: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 81: Global Market - Tier Structure Analysis
- Figure 82: Global Market - Company Share Analysis
Frequently Asked Questions
What is the projected valuation of the Vegan Fast-Food Market in 2026?
According to Future Market Insights analysis, the global vegan fast-food market is evaluated at USD 24.0 Billion in 2026, and is projected to expand to USD 71.3 Billion by 2036 at a compound annual growth rate of 11.5%. Category expansion is driven by youth flexitarian dining adoption, the permanent integration of plant-forward entrees across multinational restaurant chains, and technological breakthroughs in high-moisture meat analogues.
Which product type commands the largest market share in 2026?
Standard commercial grade holds 41.4% of total product type revenue in 2026, supported by high-volume quick-service restaurant drive-thru execution requiring standardized frozen-to-grill performance. Commercial restaurant chains utilize standard commercial grade pre-formed patties and breaded nuggets to deliver identical portion control, consistent cook times, and cost-effective wholesale pricing.
How do food scientists achieve realistic meat texture in vegan fast food?
Formulators deploy high-moisture extrusion on soy, pea, and wheat proteins, creating aligned fibrous protein bundles that replicate the tear and chew of animal muscle fibers. High-moisture extrusion combined with encapsulated plant fats and natural umami yeasts creates authentic juicy mouthfeel and char-broiled flavor release during high-temperature cooking.
How do restaurant kitchens prevent cross-contamination between plant and animal items?
Leading chains deploy dedicated clamshell grills, color-coded cooking utensils, and separate fryer vats for plant-based burgers, as tracked in Future Market Insights reports on quick service restaurant trends. Establishing dedicated cooking zones eliminates oil cross-contact and reassures strict vegan and allergy-sensitive diners, ensuring operational integrity in fast-paced kitchens.
What menu categories are expanding most rapidly in vegan fast food?
Crispy plant-based chicken sandwiches and loaded breakfast scramble burritos represent the fastest-growing categories, supported by consumer enthusiasm for plant based snacks. Poultry and breakfast dayparts represent massive commercial growth frontiers as consumers seek crispy, savory plant proteins for convenient morning and midday dining.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
