
- Market Size (2026)
- USD 7.2 Bn
- Forecast (2036)
- USD 17.0 Bn
- CAGR (2026 to 2036)
- 9.0%
How big is Wood Plastic Composite Market in 2026?
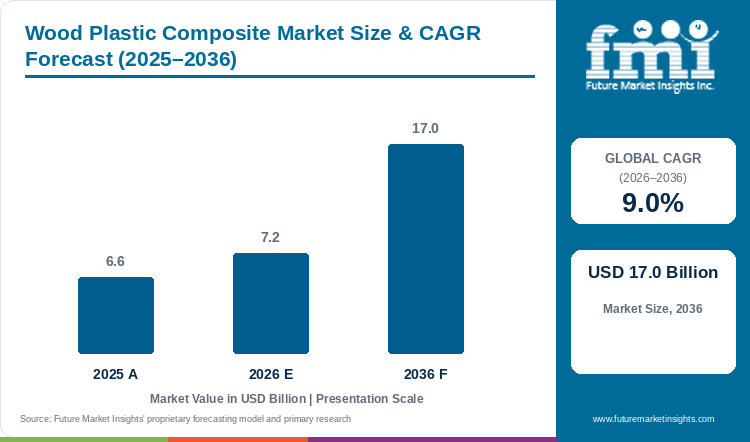
The wood plastic composite market demonstrated steady progress from USD 6.6 billion in 2025 to USD 7.2 billion in 2026, building toward a targeted valuation of USD 17.0 billion by 2036 at a CAGR of 9.0%.
The global wood plastic composite market was valued at USD 6.6 billion in 2025 and is estimated to reach USD 7.2 billion in 2026. The market is projected to reach USD 17.0 billion by 2036, expanding at a compound annual growth rate (CAGR) of 9.0% between 2026 and 2036. Polyethylene high-density wood composites are anticipated to capture an estimated 58.0% share of 2026 polymer matrix demand, since encapsulated recycled polyethylene and wood-fiber formulations resist rot and termites without annual chemical staining. Buyer adoption tracking at FMI shows that demand for wood plastic composites is driven by residential deck replacement cycles and contractor labor economics, as scalloped capped composite boards install faster and outlast pressure-treated softwood lumber by two decades.
The growth in wood plastic composite adoption is also supported by favorable material price stability, with Statistics Canada reporting in July 2026 that the wood and plastics composite construction division recorded a 0.3% residential price decline in the second quarter of 2026 while structural steel framing rose 1.8%. That exterior lumber-substitution cycle separates the category from the biaxially oriented polypropylene market at a 5.0% CAGR, given that packaging film demand tracks retail grocery volume while composite decking sales follow homeowner outdoor-living conversions. Building-product leaders are consolidating exterior cladding and decking distribution to capture contractor remodeling spend, evidenced when James Hardie closed its acquisition of AZEK and the TimberTech composite decking brand in July 2025. Pro-channel lumberyards and residential builders commit to composite decking brands that back 25-to-50-year fade-and-stain warranties with local distributor inventory through 2036.
Key Market Trends & Insights
- By polymer matrix base: Polyethylene High-Density (HDPE) Wood Composites hold an estimated 58.0% share in 2026 since post-consumer HDPE film compounds smoothly with wood flour.
- By processing technology: Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) represents 72.0% in 2026 owing to continuous linear profile output and polymer shell encapsulation.
- By end-use application: Outdoor Decking Boards account for 54.0% in 2026 given that aging pressure-treated residential decks and hospitality boardwalks require rot-proof replacement.
- By profile structure: Capped Co-Extruded Solid and Grooved Profiles secure 63.0% in 2026 through hidden-fastener groove compatibility and four-sided moisture encapsulation.
- By distribution channel: Pro Contractor Lumberyards and Specialty Dealers command 56.0% in 2026 supported by job-site boom-truck delivery and contractor loyalty programs.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at a 9.9% CAGR through 2036 under coastal resort boardwalk construction and automotive interior trim molding.
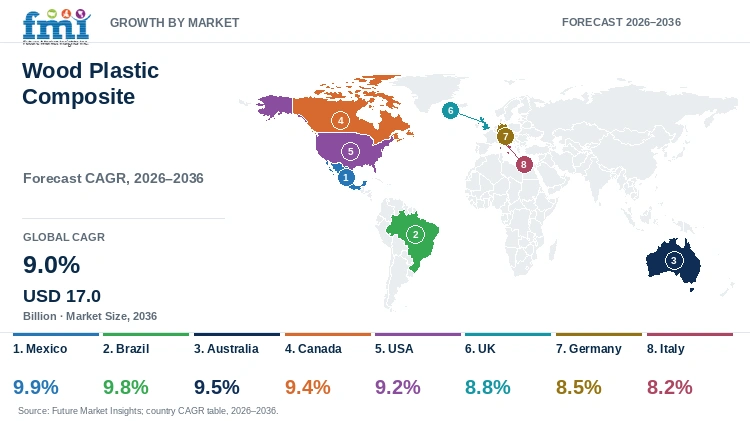
- Broader country progression: Brazil tracks at a 9.8% CAGR ahead of Australia at 9.5% and Canada at 9.4%. The USA advances at 9.2% and the UK at 8.8%, while Germany records 8.5% and Italy 8.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Wood Plastic Composite Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 6.6 billion |
| Estimated Market Size in 2026 | USD 7.2 billion |
| Projected Market Size by 2036 | USD 17.0 billion |
| CAGR, 2026 to 2036 | 9.0% |
| Added Revenue, 2026 to 2036 | USD 9.8 billion |
Residential remodeling contractors and commercial property developers actively specify wood plastic composite decking and cladding even when new single-family housing starts fluctuate. While higher mortgage rates temper greenfield subdivision builds, homeowners staying in existing houses redirect capital toward outdoor living kitchens and composite interior floorings that raise property resale value. Official construction spending statistics released by the U.S. Census Bureau on November 2, 2026 reported total United States construction activity running at a seasonally adjusted pace of USD 2,186.1 billion in September 2026. Within this construction base, exterior repair-and-remodel contractors favor scalloped entry-tier composite boards priced within 1.5 to 2.0 times pressure-treated southern yellow pine.
Wood Flour and Recycled Thermoplastic Feedstock Sizing
Table 2: Feedstock Tonnage and Extrusion Sizing for the Wood Plastic Composite Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 6.6 | 7.2 | 17.0 |
| Global WPC profile & molded output (million metric tons) | 4.7 to 5.1 | 5.1 to 5.6 | 11.2 to 12.4 |
| Reclaimed wood flour & natural fiber utilized (million metric tons) | 2.5 to 2.8 | 2.7 to 3.0 | 6.0 to 6.7 |
| Recycled thermoplastic resin consumed (million metric tons) | 1.9 to 2.2 | 2.1 to 2.4 | 4.8 to 5.4 |
Operational note: Composite extrusion mass balances apply a standard 50% to 60% oven-dry hardwood or softwood flour loading blended with 35% to 45% thermoplastic resin and 3% to 5% maleic-anhydride compatibilizers, UV stabilizers, and mineral pigments.
Compounders manufacturing wood plastic composites convert sawmill planer shavings and storm-damaged timber into high-value structural profiles, insulating board margins from virgin lumber price spikes. Material valorization research published by the USDA Forest Service in August 2025 demonstrated that downed timber fibers from hurricane-damaged forests reinforce thermoplastic polymer matrices effectively after drying and mesh screening. Extruders procuring high-density polyethylene resins and reclaimed grocery stretch film pair these domestic wood fibers with compatibilizers to achieve up to 95% total recycled content.
Residential Deck Conversion & Contractor Line Indicators
Table 3: Deck Replacement and Extrusion Line Indicators for the Wood Plastic Composite Market (operational metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Composite share of North American decking linear footage (%) | 25.0% to 26.5% | 26.5% to 28.0% | 38.0% to 42.0% |
| Average residential composite deck installation size (sq. ft.) | 320 to 380 | 330 to 390 | 360 to 420 |
| Co-extruded capped board share of WPC decking (%) | 78.0% to 82.0% | 80.0% to 84.0% | 90.0% to 94.0% |
| Average factory realization per metric ton of WPC (USD) | 1,310 to 1,420 | 1,330 to 1,450 | 1,410 to 1,560 |
Table 4: Material Formulation & Channel Allocation Indicators for the Wood Plastic Composite Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 7.2 billion | 2026 global wood plastic composite revenue baseline |
| US total construction spending annual rate, Sept 2026 | USD 2,186.1 billion | U.S. Census Bureau November 2026 construction release |
| Canadian wood, plastics & composites Q2 2026 price change | -0.3% residential index | Statistics Canada July 2026 Building Construction Price Index |
| Polyethylene (HDPE) Wood Composites revenue, 2026 | USD 4.18 billion | 58.0% polymer matrix base allocation across extruders |
Precise calibration of the ratio of thermoplastic polymer to lignocellulosic filler governs both flexural stiffness and water-absorption resistance in outdoor structural profiles. Experimental polymer engineering studies published by the American Chemical Society in ACS Omega in February 2025 verified that a 60% high-density polyethylene to 40% reinforcement composition achieves optimal compressive strength and controlled density between 780 and 987 kilograms per cubic meter. Manufacturers supplying architectural deck railings and fascia boards maintain this exact resin-to-fiber balance so fasteners hold tightly without edge splitting.
Analyst Perspective
"The wood plastic composite industry is winning share from pressure-treated lumber on two fronts simultaneously: entry-level scalloped boards that match wood installation budgets, and premium heat-mitigating capped boards that stay cool under direct summer sun. Manufacturers that control captive post-consumer polyethylene recycling paired with two-step pro-dealer distribution will capture industry profit pools through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Wood Plastic Composite Market segmented?
The wood plastic composite market is segmented by polymer matrix base, processing technology, end-use application, profile structure, and distribution channel. In 2026, Polyethylene High-Density (HDPE) Wood Composites are projected at 58.0%, Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) at 72.0%, Outdoor Decking Boards at 54.0%, Capped Co-Extruded Solid and Grooved Profiles at 63.0%, and Pro Contractor Lumberyards and Specialty Dealers at 56.0%.
By polymer matrix base: Polyethylene High-Density (HDPE) Wood Composites and Polypropylene (PP) Wood Plastic Composites. The segment also covers Polyvinyl Chloride (PVC) Cellular and Rigid Composites and Polylactic Acid (PLA) Bio-Composites.
By processing technology: Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) and Injection Molding (Structural Precision Shapes). Additional processes include Compression Molding and Thermoforming and Additive 3D Extrusion.
By end-use application: Outdoor Decking Boards and Railing and Privacy Screens. The category also includes Wall Cladding and Architectural Louvers, Automotive Interior Door Panels and Trunk Liners, and Molded Pallets and Marine Docks.
By profile structure: Capped Co-Extruded Solid and Grooved Profiles and Hollow-Core Structural Cellular Profiles. The breakdown also covers Uncapped Mono-Extruded Composite Profiles and Acoustic and Fire-Retardant Profiles.
By distribution channel: Pro Contractor Lumberyards and Specialty Dealers and Home Improvement Big-Box Retail Centers. The segment also includes Direct Commercial and Municipal Specification and Automotive OEM Tier-1 Supply.
Why do Polyethylene High-Density (HDPE) Wood Composites lead the polymer matrix base category?
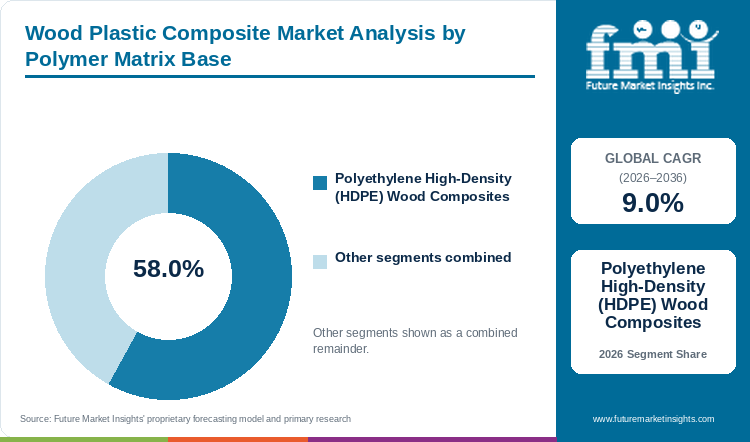
Polyethylene High-Density (HDPE) Wood Composites hold an estimated 58.0% of polymer matrix base demand in 2026, anchored by low processing temperatures and recycled polyethylene film integration.
Table 5: Polymer Matrix Base Share for the Wood Plastic Composite Market (percentage share), 2026
| Polymer Matrix Base | Share (2026) |
|---|---|
| Polyethylene High-Density (HDPE) Wood Composites | 58.0% |
| Other Segments Combined | 42.0%* |
| Total | 100.0% |
*Note: Remaining polymer matrix base categories account for the balance of 2026 global wood plastic composite demand.
Table 6: Polymer Matrix Base Leadership and Market Growth for the Wood Plastic Composite Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.0% |
| Leading Segment | Polyethylene High-Density (HDPE) Wood Composites |
High-density polyethylene wood composites anchor polymer matrix demand since high-density and linear low-density polyethylene melt at 130 to 170 degrees Celsius, well below the 200 degrees Celsius thermal degradation threshold where wood hemicellulose chars and releases volatile organic acids. While automotive molders specify homo-polymer polypropylene resins for higher heat-deflection cabin trim, exterior decking extruders rely on reclaimed polyethylene film and rigid milk-jug flake to keep raw material costs low. Corporate financial disclosures from Trex Company in February 2026 confirmed that strong homeowner demand for polyethylene-based composite decking and railing supported full-year 2025 net sales and a positive 2026 growth outlook despite a flat broader remodeling market.
- Within the polymer matrix base segment, Polyethylene High-Density Wood Composites are projected to account for a 58.0% share in 2026 through low processing temperatures.
- Polyvinyl chloride cellular composites and polypropylene automotive grades are anticipated to record steady gains where Class A flame-spread ratings are required.
What sustains Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) leadership in the processing technology segment?
Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) represents 72.0% of the processing technology category in 2026, supported by continuous linear output and weather-resistant polymer capping.
Profile Extrusion using counter-rotating or co-rotating twin-screw extruders paired with crosshead co-extrusion dies leads processing technology since continuous linear extrusion forms 12-to-20-foot decking, cladding, and fencing boards in a single automated pass. The outer co-extruded protective polymer cap shields the inner wood-filled core from ultraviolet lignin bleaching and moisture swelling, outperforming older uncapped extruded thermoplastic profiles. Regulation of melt-pressure surges and die swell across variable wood-flour moisture levels remains the primary technical challenge on high-output extrusion lines.
- In 2026, Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) is anticipated to capture 72.0% of processing technology demand across capped deck and siding boards.
- Polymer rheology studies published in Polymers in June 2026 demonstrated that on-line capillary rheometry and twin-screw shear calibration prevent surface tearing during extrusion.
How do Outdoor Decking Boards (Commercial and Residential) lead the end-use application category?
Outdoor Decking Boards (Commercial and Residential) account for 54.0% of end-use application volume in 2026, driven by residential pressure-treated wood deck replacement and hospitality boardwalks.
Outdoor Decking Boards for residential backyards and commercial hospitality boardwalks represent the largest application since horizontal walking surfaces suffer the harshest rainwater pooling and ultraviolet exposure on a building exterior. While architects routinely specify composite louvers and ventilated rainscreen cladding for vertical facades, deck boards consume the highest linear footage and weight per installation. Product launches from leading manufacturers reinforce how decking anchors full-backyard specification, evidenced when Trex debuted its integrated composite decking and Seclusions and Horizons privacy fencing portfolio at the International Builders' Show in February 2026.
- By end-use application, Outdoor Decking Boards are estimated to reach 54.0% of category share in 2026 as homeowners replace rotting pressure-treated pine decks.
- Coordinated composite railing, privacy fencing, and architectural wall cladding are projected to grow faster than baseline decking through 2036 as contractors bundle exterior packages.
Why do Capped Co-Extruded Solid and Grooved Profiles lead the profile structure category?
Capped Co-Extruded Solid and Grooved Profiles secure 63.0% of profile structure value in 2026, supported by hidden-fastener clip grooves and four-sided stain and fade protection.
Capped Co-Extruded Solid and Grooved Profiles dominate profile structure demand since solid square-edge boards replicate the rigid underfoot feel of traditional timber on stair treads and picture-frame borders, while grooved-edge boards accept hidden clip fasteners that cut contractor installation time by 30%. Hollow-core cellular profiles weigh less for European balcony tiles but can trap condensation if end-caps are omitted. Formulation of heat-reflective cap layers to reduce surface temperatures under direct summer sunlight has become the primary product differentiator across solid and grooved profiles.
- Strong contractor preference for hidden-fastener grooved boards places Capped Co-Extruded Solid and Grooved Profiles on course to hold a 63.0% share in 2026.
- Materials research in Industrial & Engineering Chemistry Research verified that embedding titanium dioxide nanoparticles into trilayer wood-plastic composite plates lowers outdoor surface temperatures by 10 degrees Celsius.
What gives Pro Contractor Lumberyards and Specialty Dealers the leading position in distribution channel?
Pro Contractor Lumberyards and Specialty Dealers command 56.0% of distribution channel share in 2026, anchored by job-site delivery logistics and professional deck-builder loyalty programs.
Pro Contractor Lumberyards and Specialty Dealers command the largest distribution share because professional deck builders rely on two-step wholesale distributors and specialty pro yards for job-site boom-truck delivery, custom 16-to-20-foot board lengths, and coordinated railing hardware kits. Commercial product rollouts target both pro dealers and retail home centers, illustrated when Trex expanded its value-driven Enhance scalloped decking line in January 2026 with Pebble Beach and Golden Hour colors engineered with sun-mitigating cap technology to convert wood buyers across dealer and home-center shelves.
- Pro Contractor Lumberyards and Specialty Dealers are predicted to secure 56.0% of distribution channel sales in 2026 through professional deck-builder credit terms.
- Big-box home improvement centers and direct municipal boardwalk specifications are forecast to expand steadily as scalloped composite boards narrow the retail price gap.
What are the drivers, restraints, and opportunities in the wood plastic composite market?
In the wood plastic composite market, ongoing replacement of rotting pressure-treated softwood decks and low maintenance costs are projected to drive adoption, while higher upfront board pricing restrains budget builds and heat-mitigating cap chemistry and automotive interior panels open new growth avenues.
- Driver: Ongoing replacement of decaying chromated-copper-arsenate and alkaline-copper-quaternary treated softwood decks with zero-maintenance capped composites drives recurring residential and commercial demand.
- Restraint: Upfront material costs running 1.5 to 3.0 times pressure-treated lumber combined with thermal expansion and interfacial moisture sensitivity at high wood loadings restrain budget-constrained builds.
- Opportunity: Solar-reflective cool-deck cap chemistry, Class A fire-rated wildfire-zone profiles, and lightweight bio-composite automotive interior panels open high-margin growth avenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Multi-decade residential deck replacement cycles and green-building material credits across North America, Europe, and Oceania are converting wood-lumber buyers into wood plastic composite customers. Over 50 million residential decks in North America alone are constructed from pressure-treated softwood lumber that warps and requires replacement every 10 to 15 years, paired with growing commercial specification of low-emission vinyl construction compounds and recycled-content composites. Official state economic development records from the Arkansas Economic Development Commission documented Trex Company's construction of a USD 400 million specialty composite decking and recycled polyethylene manufacturing campus in Little Rock to serve central and southern United States lumber conversion demand. This regional extrusion capacity expansion shortens freight lead times and supports multi-year dealer stocking agreements.
Risk Assessment of the Wood Plastic Composite Market: Operational and Formulation Friction
Hydrophilic wood-flour hydroxyl groups and hydrophobic thermoplastic chains exhibit natural interfacial incompatibility, creating moisture-swelling and flexural creep risks if coupling agents are under-dosed or wood content exceeds 60%. Furthermore, in high-rise commercial facades where strict non-combustible codes apply, specifiers often substitute exterior aluminium cladding or fiber-cement panels unless composite profiles carry verified flame-retardant additives. Technical materials research published in MDPI in December 2024 confirmed that increasing wood content above 50% to 60% in wood-plastic composites elevates melt viscosity and water uptake unless maleic-anhydride-grafted polyolefins or pyrolysis modifiers encapsulate the fibers. Compounders must balance wood-flour loading against coupling-agent costs to preserve 25-year structural warranties.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Expansion of wood and natural-fiber thermoplastic composites into lightweight automotive door panels, trunk load floors, and acoustic parcel shelves creates a high-volume industrial growth channel paired with solar-reflective outdoor living boards. Automotive original equipment manufacturers replacing glass-fiber-reinforced plastics in molded cabin trim components achieve 15% to 25% component weight reductions and lower cabin noise while meeting European Union end-of-life vehicle circularity targets. Open-access materials characterization published on Zenodo in November 2025 demonstrated that hybrid natural-fiber and wood-reinforced polymer composites deliver high flexural modulus and thermal stability for lightweight automotive interior structures and sustainable packaging. Compounders offering pelletized injection-molding and compression-molding WPC granulates are winning multi-year automotive platform contracts.
Wood Plastic Composite Market by Country (2026 to 2036)
FMI country modeling indicates that Mexico leads wood plastic composite expansion at a 9.9% CAGR through 2036 ahead of Brazil at 9.8% and Australia at 9.5%. Canada follows at 9.4% and the USA at 9.2%, while the UK records 8.8% and Italy 8.2%.
Table 7: Country CAGR and Primary Growth Levers for the Wood Plastic Composite Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 9.9% | Coastal resort boardwalk construction and automotive interior door-panel molding |
| Brazil | 9.8% | IBAMA native tropical hardwood restrictions and termite-proof residential decking |
| Australia | 9.5% | Native hardwood logging bans and bushfire-rated suburban alfresco deck builds |
| Canada | 9.4% | Freeze-thaw resistant residential deck conversion and stable material price index |
| USA | 9.2% | 50M+ aging residential wood deck replacement base and Little Rock plant ramp-up |
| UK | 8.8% | Damp maritime rot resistance and 30-to-40-year municipal and caravan-park decking |
| Germany | 8.5% | PEFC-certified PVC-free biocomposite terraces and EV cabin interior lightweighting |
| Italy | 8.2% | Mediterranean Lido beach boardwalks and architectural sun-shading louver facades |
Source: Future Market Insights analysis
Mexico Wood Plastic Composite Market Outlook (2026 to 2036)
Demand for wood plastic composites in Mexico is projected to expand at a leading 9.9% CAGR between 2026 and 2036 across Caribbean and Pacific resort hospitality developments and northern automotive manufacturing clusters. What distinguishes Mexico from purely residential North American markets is its dual demand engine combining hurricane- and salt-resistant resort boardwalks in Quintana Roo and Baja California with injection-molded automotive interior door panels in Nuevo Leon and Coahuila. Experimental composite research published in Frontiers in Bioengineering and Biotechnology demonstrated that chlorinated polyethylene and calcium-zinc stabilizers significantly enhance the impact and flexural strength of polyvinyl chloride and thermoplastic wood-plastic composites. Mexican extruders and tier-one auto molders are scaling local compounding of pine sawdust and recycled polyolefins.
Key takeaway: In Mexico, coastal resort boardwalk construction and automotive interior door-panel molding are projected to drive leading wood plastic composite demand.
Brazil Wood Plastic Composite Market Outlook (2026 to 2036)
Brazil's wood plastic composite sector is anticipated to advance at a 9.8% CAGR from 2026 to 2036 as residential condominium developers, coastal municipalities, and logistics pallet users substitute composite profiles for native tropical hardwoods. Compared with temperate northern markets, Brazil's high humidity and intense ultraviolet radiation combine with subterranean termite pressure to degrade untreated wood rapidly, while strict IBAMA forest-traceability enforcement restricts native Ipé and Cumaru harvesting. Natural weathering studies published in Forests in November 2024 documented how ultraviolet stabilizers and co-extruded polymer caps protect wood-plastic composite flexural properties and color stability under intense solar and moisture exposure. Brazilian extruders in Santa Catarina and Paraná combine plantation pine and eucalyptus flour with post-consumer polyethylene to supply domestic builders.
Key takeaway: In Brazil, tropical hardwood conservation rules and high-humidity termite resistance are anticipated to accelerate adoption of capped pine-and-eucalyptus WPC decking and cladding.
Australia Wood Plastic Composite Market Outlook (2026 to 2036)
Commercial wood plastic composite sales in Australia are forecast to progress at a 9.5% CAGR through 2036 across suburban outdoor-alfresco decks, coastal marinas, and bushfire-resilient residential facades. What sets Australia apart from European markets is the combination of native hardwood logging bans in Victoria and Western Australia, severe bushfire building codes (BAL ratings), and cross-border consolidation by Australian building-products leaders. Strategic earnings reports from Sydney- and Dublin-listed James Hardie Industries plc examine portfolio expansion into composite decking and exterior architectural cladding for Australasian and North American residential projects. Australian builders routinely specify BAL-rated mineral-and-wood composite boards for outdoor living renovations.
Key takeaway: In Australia, native hardwood harvesting restrictions and bushfire-rated outdoor alfresco living builds are forecast to sustain strong composite decking and cladding growth.
Canada Wood Plastic Composite Market Outlook (2026 to 2036)
Canadian wood plastic composite demand is expected to climb at a 9.4% CAGR between 2026 and 2036 across Ontario, British Columbia, and Quebec residential renovation corridors. In contrast to southern climates where ultraviolet heat dominates, Canadian homeowners and municipal park engineers specify capped composite decking to eliminate freeze-thaw cracking and annual waterproofing labor required by pressure-treated spruce-pine-fir lumber. Official manufacturing survey instruments updated by Statistics Canada in May 2026 track industrial consumption of virgin and post-consumer recycled plastic resins and wood inputs across Canadian polymer product manufacturers. Canadian lumberyard cooperatives are expanding pre-season stocking of scalloped and solid grooveless composite boards for short summer building windows.
Key takeaway: In Canada, severe freeze-thaw durability requirements and stable composite construction material pricing are expected to drive steady conversion from treated spruce-pine-fir lumber.
USA Wood Plastic Composite Market Outlook (2026 to 2036)
United States wood plastic composite revenue is estimated to grow at a 9.2% CAGR through 2036, anchored by the world's largest installed base of residential wood decks and pro-contractor remodeling networks. What distinguishes the USA from other global regions is its vertically integrated domestic manufacturing scale, where leading brands process hundreds of millions of pounds of reclaimed grocery bags and hardwood sawdust into co-extruded boards. Corporate construction disclosures from Trex Company detail the steel topping-out and phased commissioning of its Little Rock, Arkansas manufacturing campus, adding central United States decking and railing extrusion capacity to complement its Virginia and Nevada plants. American pro dealers and home centers continue shifting shelf space toward entry-tier and heat-mitigating composite lines.
Key takeaway: Multi-plant domestic extrusion capacity in Virginia, Nevada, and Arkansas and pro-dealer remodeling programs are estimated to anchor United States market volume.
UK Wood Plastic Composite Market Outlook (2026 to 2036)
Procurement of wood plastic composites in the UK is slated to expand at an 8.8% CAGR over the 2026 to 2036 forecast period across residential garden decking, holiday-park caravan verandas, and municipal community refurbishments. Compared with dry continental climates, Britain's damp maritime weather causes rapid algae sliming and fungal rot on softwood timber decks, prompting local councils and homeowners to specify slip-resistant grooved composite boards. Local government refurbishment briefs published by South Woodham Ferrers Town Council in 2026 illustrate how British community and municipal facilities specify 30-to-40-year low-maintenance composite decking and cladding systems to eliminate recurring timber replacement costs. British builders' merchants are expanding composite fencing and cladding ranges to complement garden decking.
Key takeaway: In the UK, damp maritime rot resistance and 30-to-40-year municipal and holiday-park lifecycle specifications are slated to support steady composite decking and fencing adoption.
Germany Wood Plastic Composite Market Outlook (2026 to 2036)
In Europe, biocomposite building materials advance through circular fiber integration and multi-pass extrusion recycling, as materials research published in Polymers in June 2026 demonstrated that closed-loop reprocessing maintains mechanical stability and structural stiffness across PVC-based wood-plastic composite profiles.
Key takeaway: In Germany, PEFC-certified PVC-free biocomposite terrace specifications and automotive interior lightweighting are predicted to sustain balanced industrial and construction growth.
Italy Wood Plastic Composite Market Outlook (2026 to 2036)
Sales of wood plastic composites in Italy are likely to increase at an 8.2% CAGR through 2036, driven by Adriatic and Tyrrhenian beach-club boardwalks and architectural sun-shading louvers under national building-renovation energy incentives. Compared with northern European markets with abundant domestic softwood sawlogs, Italian extruders rely heavily on recycled wood flour from furniture manufacturing districts in Friuli-Venezia Giulia and Lombardy blended with post-consumer polyolefins. Forestry supply planning documents from Natural Resources Wales and European timber agencies confirm tightening long-term softwood sawlog availability through 2026 and beyond, reinforcing the cost advantage of sawmill-residue wood composites. Italian architects actively specify co-extruded wood-plastic brise-soleil louvers for Mediterranean commercial facades.
Key takeaway: In Italy, coastal hospitality Lido boardwalks and furniture-district recycled wood-flour compounding are likely to anchor steady composite decking and louver demand.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Wood Plastic Composite Market?
Trex Company, Inc., James Hardie Industries plc (TimberTech / AZEK Exteriors), Fiberon (Fortune Brands Innovations), DuraLife Decking (Barrette Outdoor Living), UPM-Kymmene Oyj (UPM ProFi), TAMKO Building Products LLC, MoistureShield (Oldcastle APG), NewTechWood Corporation, Beologic NV, and Eva-Last International are the notable companies in the wood plastic composite market.
Competitive positioning in the wood plastic composite industry separates tier-one North American exterior living leaders, diversified fencing and decking manufacturers, and European biocomposite specialists. Trex Company and TimberTech parent The AZEK Company join Fiberon and MoistureShield in operating large-scale twin-screw co-extrusion plants paired with national pro-lumberyard and home-center distribution. DuraLife Decking, NewTechWood, and TAMKO Building Products supply capped residential decking and cladding systems. UPM-Kymmene, Eva-Last, and Beologic focus on European PEFC-certified biocomposites and bamboo-polymer architectural profiles.
- Tier-1 Exterior Living & Capped Decking Leaders: Trex Company and The AZEK Company (TimberTech) join Fiberon and MoistureShield to manufacture co-extruded HDPE and cellular PVC decking and railing systems.
- Diversified Building Products & Cladding Extruders: DuraLife Decking, TAMKO Building Products, and NewTechWood Corporation produce polypropylene and HDPE capped decking and architectural siding.
- European Biocomposite & Bamboo-Polymer Specialists: UPM-Kymmene (UPM ProFi), Beologic NV, and Eva-Last International supply PEFC-certified biocomposite decking and custom WPC compounds.
Competitive Benchmarking: Wood Plastic Composite Market
Table 8: Competitive Benchmarking for the Wood Plastic Composite Market (qualitative capability ratings), 2026
| Company | Co-Extrusion & Cap Tech | Recycled Feedstock Scale | Pro-Dealer & Retail Reach | Geographic Reach |
|---|---|---|---|---|
| Trex Company, Inc. | High | High | High | Global leader; Virginia, Nevada, and new Little Rock, Arkansas plants |
| James Hardie Industries plc (TimberTech / AZEK Exteriors) | High | High | High | Combined with James Hardie in July 2025 across North America and global markets |
| Fiberon (Fortune Brands Innovations) | High | High | High | North Carolina and Idaho extrusion plants serving North America and exports |
| DuraLife Decking (Barrette Outdoor Living) | Medium | Medium | High | North American polypropylene and HDPE composite decking and fencing network |
| UPM-Kymmene Oyj (UPM ProFi) | High | High | Medium | Germany, Finland, and European PEFC-certified biocomposite terrace network |
| TAMKO Building Products LLC | High | Medium | High | United States Envision compression-molded and co-extruded decking network |
| MoistureShield (Oldcastle APG) | High | High | High | North American solid-core sub-waterline and cool-deck composite network |
| NewTechWood Corporation | High | High | Medium | USA, Europe, Asia-Pacific, and Latin America UltraShield capped decking and siding |
| Beologic NV | Medium | High | Medium | Belgium and European custom wood-plastic and bio-polymer extrusion compounds |
| Eva-Last International | High | High | Medium | Global bamboo-plastic co-extruded decking and architectural louver supply |
Key Developments in the Wood Plastic Composite Market
- In May 2026, Trex Company, Inc. reported first quarter 2026 net sales of USD 343 million, up 1.0% over the prior year period. Results reflected a favorable mix of higher-margin premium decking boards and operational efficiencies, with the Little Rock, Arkansas manufacturing campus build-out nearing completion and capital expenditures expected to decline significantly as the facility shifts from construction to operational status [25].
- In July 2025, James Hardie Industries plc completed its acquisition of The AZEK Company, adding the TimberTech composite decking and railing brand to its exterior building products portfolio. The transaction was valued at an implied USD 8.4 billion, including the repayment of AZEK’s outstanding debt, and established James Hardie as a provider across both fiber cement siding and composite outdoor living products [26].
Key Players in the Wood Plastic Composite Market
Tier-1 Exterior Living & Capped Decking Leaders
- Trex Company, Inc.
- James Hardie Industries plc (TimberTech / AZEK Exteriors)
- Fiberon (Fortune Brands Innovations)
- MoistureShield (Oldcastle APG)
Diversified Building Products, Fencing & Cladding Extruders
- DuraLife Decking (Barrette Outdoor Living)
- TAMKO Building Products LLC
- NewTechWood Corporation
- UPM-Kymmene Oyj (UPM ProFi)
European Biocomposite, Granulate & Bamboo-Polymer Specialists
- Beologic NV
- Eva-Last International
Wood Plastic Composite Market - Report Scope
Table 9: Report Scope for the Wood Plastic Composite Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Polymer Matrix Base; Processing Technology; End-Use Application; Profile Structure; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from wood plastic composite (WPC) profiles, boards, molded automotive and industrial components, and compounded WPC granulates containing wood flour or plant-derived lignocellulosic fibers encapsulated in thermoplastic resins (HDPE, LDPE, PP, PVC, or PLA). Category Scope Note: Excludes pure unfilled polyvinyl chloride (PVC) cellular decking containing zero wood or natural fiber, cementitious fiberboard siding, and thermoset resin-impregnated engineered wood (such as LVL, glulam, or OSB). |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, Brazil, Australia, Canada, USA, UK, Germany, Italy, and additional countries in the full report |
| Key Companies Covered | Trex Company, Inc., James Hardie Industries plc (TimberTech / AZEK Exteriors), Fiberon (Fortune Brands Innovations), DuraLife Decking (Barrette Outdoor Living), UPM-Kymmene Oyj (UPM ProFi), TAMKO Building Products LLC, MoistureShield (Oldcastle APG), NewTechWood Corporation, Beologic NV, Eva-Last International |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down construction and bottom-up extrusion tonnage triangulation. |
Wood Plastic Composite Market - Research Methodology
Table 10: Research Methodology for the Wood Plastic Composite Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with pro-lumberyard category buyers, twin-screw WPC extrusion plant directors, waste-polyethylene reclamation managers, and automotive interior trim engineers to validate resin-to-wood ratios and board realizations. |
| Secondary Research | Analysis of U.S. Census Bureau Construction Spending reports, Statistics Canada Building Construction Price Indexes, USDA Forest Service wood-fiber valorization studies, ACS and MDPI polymer rheology research, and corporate SEC 10-K filings. |
| Market Sizing and Forecasting | Top-down exterior building-product and automotive interior baselines reconciled against bottom-up extruded and molded WPC tonnage (5.1M to 5.6M MT in 2026) and factory gate realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight residential repair-and-remodel expenditure, tropical hardwood logging bans, freeze-thaw or coastal moisture severity, and domestic automotive production across eight countries. |
| Operational Benchmark Traceability | Feedstock mass balances, price index shifts, and construction spending metrics in Tables 2, 3, and 4 trace to Statistics Canada Q2 2026 indexes, U.S. Census Bureau September 2026 releases, and ACS Omega formulation benchmarks. |
| Data Triangulation and Validation | Revenue estimates isolate wood- and natural-fiber-reinforced thermoplastic composites while strictly excluding 100% synthetic unfilled PVC boards, fiber-cement siding, and pressure-treated solid wood lumber. |
Wood Plastic Composite Market by Segments
Wood Plastic Composite Market segmented by Polymer Matrix Base:
- Polyethylene High-Density (HDPE) Wood Composites
- Polypropylene (PP) Wood Plastic Composites
- Polyvinyl Chloride (PVC) Cellular and Rigid Composites
- Polylactic Acid (PLA) and Bio-Polymer Wood Composites
Wood Plastic Composite Market segmented by Processing Technology:
- Profile Extrusion (Twin-Screw Co-Extruded Protective Cap)
- Injection Molding (Structural Precision Shapes)
- Compression Molding and Thermoforming
- Additive 3D Extrusion and Pultrusion
Wood Plastic Composite Market segmented by End-Use Application:
- Outdoor Decking Boards (Commercial and Residential)
- Railing, Balusters, and Privacy Fencing Screens
- Wall Cladding, Siding, and Architectural Louvers
- Automotive Interior Door Panels, Trunk Liners, and Shelves
- Molded Pallets and Marine Docks Boardwalks
Wood Plastic Composite Market segmented by Profile Structure:
- Capped Co-Extruded Solid and Grooved Profiles
- Hollow-Core Structural Cellular Profiles
- Uncapped Mono-Extruded Composite Profiles
- Acoustic and Fire-Retardant Engineered Profiles
Wood Plastic Composite Market segmented by Distribution Channel:
- Pro Contractor Lumberyards and Specialty Dealers
- Home Improvement Big-Box Retail Centers
- Direct Commercial, Marine, and Municipal Specification
- Automotive OEM and Industrial Tier-1 Supply
Wood Plastic Composite Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Statistics Canada. (2026, July 24). Building Construction Price Indexes, Second Quarter 2026: Wood, Plastics, and Composites Division. Government of Canada The Daily.
- [2] James Hardie Industries plc. (2025, July 1). James Hardie Completes Acquisition of AZEK to Become a Leading Exterior and Outdoor Living Solutions Provider. James Hardie Corporate Releases.
- [3] U.S. Census Bureau. (2026, November 2). Monthly Construction Spending Report, September 2026. United States Department of Commerce Release CB26-184.
- [4] USDA Forest Service. (2025, August 14). Valorization of Downed Timber into Wood Fibers for Thermoplastic Wood Polymer Composites. U.S. Department of Agriculture Treesearch Report 80837.
- [5] American Chemical Society. (2025, February 14). Eco-Friendly and Cost-Effective High-Density Polyethylene-Based Wood-Plastic Composites. ACS Omega, 10(7), 6437.
- [6] Trex Company, Inc. (2026, February 24). Trex Company Reports Fourth Quarter and Full Year 2025 Results and 2026 Revenue Guidance. Trex Investor Relations Releases.
- [7] MDPI Polymers Editorial Office. (2026, June 4). Advances in Wood and Wood Polymer Composites: Twin-Screw Extrusion Rheology and Interfacial Bonding. Polymers, 18(11), 1403.
- [8] Trex Company, Inc. (2026, February 17). Trex Showcases the Future of Outdoor Living and Composite Fencing at IBS 2026. Trex Company Press Room.
- [9] American Chemical Society. (2024, December 24). Triple Thermal Management Wood-Plastic Composite Plate with Solar Reflectance and Radiative Cooling. Industrial & Engineering Chemistry Research, 64(1), 453.
- [10] Trex Company, Inc. (2026, January 20). Trex Expands Its Value-Driven Enhance Decking Line with Two New Heat-Mitigating Colors. Trex Company Investor Releases.
- [11] Arkansas Economic Development Commission (AEDC). (2024, August 22). Trex Celebrates Steel Topping Out at New USD 400 Million Composite Decking Facility in Little Rock. State of Arkansas Official Newsroom.
- [12] MDPI Forestry & Materials Group. (2024, December 10). Challenges for Wood-Plastic Composites: Increasing Wood Fiber Content and Moisture Resistance. International Wood Products Journal / MDPI, 31(1), 1.
- [13] CERN OpenAIRE / Zenodo. (2025, November 14). Development and Characterization of Natural Fiber and Wood Hybrid Polymer Composites for Automotive Interiors. Zenodo Open Science Repository Record 17607710.
- [14] Frontiers in Bioengineering and Biotechnology. (2024, November 18). Enhanced Mechanical Properties of Polyvinyl Chloride and Thermoplastic Wood-Plastic Composites. Frontiers Media SA, 9, 829821.
- [15] MDPI Forests Research Group. (2024, November 27). Changes in Wood Plastic Composite Properties After Natural Tropical and Subtropical Weathering. Forests, 15(12), 2102.
- [16] James Hardie Industries plc. (2026, August 18). James Hardie Reports First Quarter FY27 Results and Siding and Outdoor Living Portfolio Outlook. James Hardie Investor Relations.
- [17] Statistics Canada. (2026, May 20). Annex to the 2025 Annual Survey of Manufacturing Industries: Virgin and Recycled Resin Inputs. Government of Canada Statistical Programs.
- [18] Trex Company, Inc. (2024, August 22). Trex Celebrates Steel Topping Out at New Little Rock Composite Decking and Railing Manufacturing Campus. Trex Official Corporate Releases.
- [19] South Woodham Ferrers Town Council. (2026, January 15). Municipal Decking and Cladding Refurbishment Project Brief: 30-to-40-Year Composite Lifespan Specifications. UK Local Government Infrastructure Dossiers.
- [20] Mikušová, L., & Kvietková, M. (2026, June 16). Influence of Reprocessing on the Properties of PVC-Based Wood-Plastic Composites. Polymers (Basel).
- [21] Natural Resources Wales. (2025, April 19). Timber Sales and Marketing Plan 2021-2026: Softwood Sawlog and Wood Fiber Supply Forecasts. UK Government / Welsh Government Forestry Dossiers.
- [22] Trex Company, Inc. (2026, May 7). Trex Company Reports Solid First Quarter 2026 Results Driven by Pro-Channel and Home Center Demand. Trex Investor Relations News Releases.
- [23] James Hardie Industries plc. (2025, March 24). James Hardie and The AZEK Company to Combine Creating a Leading Building Products Growth Platform. James Hardie Official M&A Releases.
- [24] Trex Company, Inc. (2025, February 24). Form 10-K Annual Report for the Fiscal Year Ended December 31, 2024. U.S. Securities and Exchange Commission EDGAR.
- [25] Trex Company, Inc. (2026). Trex Company Reports Solid First Quarter 2026 Results. Business Wire. https://www.businesswire.com/news/home/20260507430582/en/
- [26] James Hardie Industries plc. (2025). James Hardie Completes Acquisition of AZEK — Form 6-K. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/1159152/000119312525154175/d68606dex991.htm
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the wood plastic composite market in 2026 and what is forecast for 2036?
- Which residential deck replacement cycles and lumber cost trends support demand for wood plastic composites?
- Why do Polyethylene High-Density (HDPE) Wood Composites lead the polymer matrix base category?
- Why does Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) lead the processing technology category globally?
- How do national growth rates compare across Mexico and Brazil as well as Australia and Canada through 2036?
- Which leading companies manufacture capped residential decking versus European biocomposites and automotive granulates today?
- What limits wood-flour loading ratios or causes moisture swelling in the wood plastic composite market?
- What should building-material distributors and contractors evaluate when specifying capped composite decking and cladding?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Polymer Matrix Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Polymer Matrix Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Polymer Matrix Base, 2026 to 2036
- Polyethylene High-Density (HDPE) Wood Composites
- Polypropylene (PP) Wood Plastic Composites
- Polyvinyl Chloride (PVC) Cellular and Rigid Composites
- Polylactic Acid (PLA) and Bio-Polymer Wood Composites
- Y-o-Y Growth Trend Analysis By Polymer Matrix Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Polymer Matrix Base, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Technology, 2026 to 2036
- Profile Extrusion (Twin-Screw Co-Extruded Protective Cap)
- Injection Molding (Structural Precision Shapes)
- Compression Molding and Thermoforming
- Additive 3D Extrusion and Pultrusion
- Y-o-Y Growth Trend Analysis By Processing Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Technology, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Outdoor Decking Boards (Commercial and Residential)
- Railing, Balusters, and Privacy Fencing Screens
- Wall Cladding, Siding, and Architectural Louvers
- Automotive Interior Door Panels, Trunk Liners, and Shelves
- Molded Pallets and Marine Docks Boardwalks
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Profile Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Profile Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Profile Structure, 2026 to 2036
- Capped Co-Extruded Solid and Grooved Profiles
- Hollow-Core Structural Cellular Profiles
- Uncapped Mono-Extruded Composite Profiles
- Acoustic and Fire-Retardant Engineered Profiles
- Y-o-Y Growth Trend Analysis By Profile Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Profile Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Pro Contractor Lumberyards and Specialty Dealers
- Home Improvement Big-Box Retail Centers
- Direct Commercial, Marine, and Municipal Specification
- Automotive OEM and Industrial Tier-1 Supply
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Polymer Matrix Base
- By Processing Technology
- By End-Use Application
- By Profile Structure
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Trex Company, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- James Hardie Industries plc (TimberTech / AZEK Exteriors)
- Fiberon (Fortune Brands Innovations)
- DuraLife Decking (Barrette Outdoor Living)
- UPM-Kymmene Oyj (UPM ProFi)
- TAMKO Building Products LLC
- MoistureShield (Oldcastle APG)
- NewTechWood Corporation
- Beologic NV
- Eva-Last International
- James Hardie Industries plc (TimberTech / AZEK Exteriors)
- Trex Company, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Polymer Matrix Base, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Processing Technology, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Profile Structure, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Polymer Matrix Base
- Figure 6: Global Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing Technology
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Profile Structure
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Polymer Matrix Base
- Figure 32: North America Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Processing Technology
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Application
- Figure 38: North America Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Profile Structure
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Polymer Matrix Base
- Figure 48: Latin America Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Processing Technology
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Profile Structure
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Polymer Matrix Base
- Figure 64: Western Europe Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Processing Technology
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Profile Structure
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Polymer Matrix Base
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Processing Technology
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Profile Structure
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Polymer Matrix Base
- Figure 96: East Asia Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Processing Technology
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Profile Structure
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Polymer Matrix Base
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Processing Technology
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Profile Structure
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Polymer Matrix Base, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Polymer Matrix Base, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Polymer Matrix Base
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Processing Technology, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Processing Technology, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Processing Technology
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Profile Structure, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Profile Structure, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Profile Structure
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Wood Plastic Composite Market in 2026, and what is forecast for 2036?
FMI estimates that global wood plastic composite demand stood at USD 6.6 billion in 2025 and reached USD 7.2 billion in 2026, rising to USD 17.0 billion by 2036.
What is the CAGR for the Wood Plastic Composite Market from 2026 to 2036?
The wood plastic composite sector is projected to expand at a 9.0% CAGR over the 2026 to 2036 forecast period, adding USD 9.8 billion across exterior building products and automotive interior components.
Which polymer matrix base segment leads the Wood Plastic Composite Market?
Polyethylene High-Density (HDPE) Wood Composites are anticipated to hold 58.0% of polymer matrix base demand in 2026 since reclaimed polyethylene film and rigid flake compound smoothly with wood flour at low processing temperatures.
Which processing technology segment leads the Wood Plastic Composite Market?
Profile Extrusion (Twin-Screw Co-Extruded Protective Cap) is projected to represent 72.0% of the processing technology category in 2026 owing to continuous linear board output and UV-resistant polymer shell encapsulation.
Which country has a notable growth outlook during the assessment period?
Mexico leads national expansion projections at a 9.9% CAGR through 2036, driven by coastal resort boardwalk construction and automotive interior trim molding.
Who are the key players in the market?
Trex Company and The AZEK Company (TimberTech) lead supply with Fiberon, DuraLife Decking, and UPM-Kymmene. TAMKO Building Products and MoistureShield also hold major positions with NewTechWood, Beologic, and Eva-Last.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
