

- Market Size (2026)
- USD 450.0 Mn
- Forecast (2036)
- USD 1045.9 Mn
- CAGR (2026 to 2036)
- 8.8%
How big is Wooden Cutlery Market in 2026?
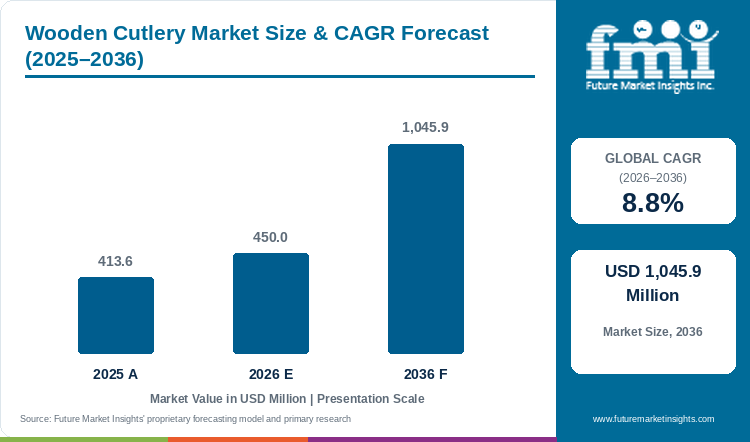
Demand for wooden cutlery is projected to rise at 8.8% CAGR through 2036. Sector valuation increases from USD 413.6 million in 2025 to USD 450.0 million in 2026 and is predicted to reach USD 1,045.9 million by 2036.
Quick-service restaurant chains, airline caterers, and hospital cafeterias are replacing single-use polystyrene and polypropylene utensils with rotary-stamped wooden cutlery to comply with statutory plastic prohibitions. According to Future Market Insights, the global wooden cutlery market rises from USD 413.6 million in 2025 to USD 450.0 million in 2026 and is projected to reach USD 1,045.9 million by 2036, expanding at an 8.8% CAGR and generating USD 595.9 million in added revenue between 2026 and 2036. Wooden Spoons lead the product type category with a 47.2% share in 2026, reflecting year-round takeaway volume across hot soups, grain bowls, and frozen dairy desserts where thin paper utensils collapse. In December 2025, the Food and Agriculture Organization of the United Nations (FAO) reported that global industrial roundwood removals rose 2.0% to 1.96 billion cubic metres while wood-based panel output grew 5.0% to 393 million cubic metres, stabilizing veneer log supply for cutlery die-cutters [1]. However, issues such as dry wood-grain tongue sensation and tine splitting in dense proteins still push converters to invest in hot-calendered wax polishing.
Key Market Trends & Insights
- By product type: Wooden Spoons led with 47.2% share in 2026, attributed to deep-bowl thermo-molding needed for liquid soups, curries, and ice cream.
- By wood species: FSC-Certified Birchwood accounted for 54.8% in 2026, supported by fine closed grain, pale splinter-free surfaces, and neutral flavor.
- By end user: Food Service Outlets held 42.9% in 2026, reinforced by quick-service delivery meal kits and fast-casual takeaway orders.
- By sales channel: Direct B2B Foodservice Contracts represented 38.6% in 2026, driven by custom-embossed utensil sleeves procured directly by restaurant groups.
Regional Highlights
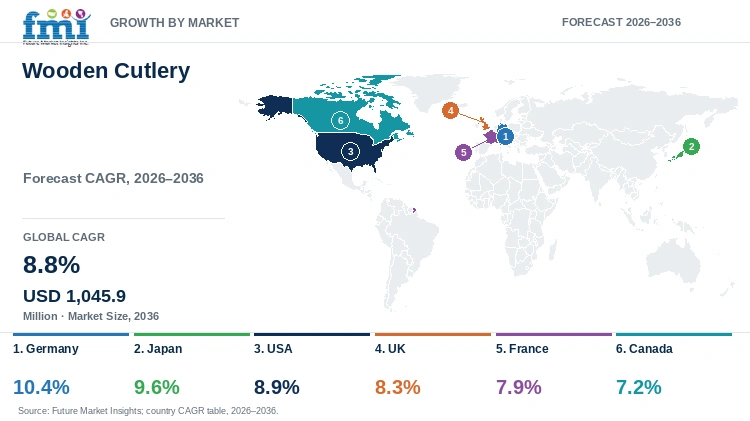
- Fastest-growing evaluated country: Germany, at 10.4% CAGR from 2026 to 2036.
- By country: Japan at 9.6%, USA at 8.9%, UK at 8.3%, and France at 7.9% follow, while Canada records a 7.2% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Wooden Cutlery Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 413.6 million |
| Estimated Market Size in 2026 | USD 450.0 million |
| Projected Market Size by 2036 | USD 1,045.9 million |
| CAGR, 2026 to 2036 | 8.8% |
| Added Revenue, 2026 to 2036 | USD 595.9 million |
Procurement timelines differ between regional markets depending on how strictly national environmental agencies police takeaway utensil bans and forestry chain-of-custody certificates. In August 2026, the European Commission's Directorate-General for Environment confirmed the entry into application of the Packaging and Packaging Waste Regulation (EU) 2025/40 alongside strict limits on PFAS in food-contact tableware and wraps [2]. Because unmodified birch and bamboo utensils contain zero synthetic polymer coatings and qualify as natural fibers under the EU Single-Use Plastics Directive, European and British restaurant chains specify wooden cutlery over bio-plastic CPLA forks that remain banned in EU takeaway service. Meanwhile, North American and Japanese buyers procuring disposable cutlery formats weigh FSC chain-of-custody verification and smooth carnauba-burnished edges against lower-cost molded fiber and polypropylene options.
Foodservice Utensil Volume and Timber Conversion Sizing
Table 2: Utensil Production Volume and Veneer Conversion Indicators for the Wooden Cutlery Market (USD million, billion units, and cubic metres), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 413.6 | 450.0 | 1,045.9 |
| Commercial wooden utensils shipped (billion pieces) | 24.3 to 26.8 | 26.5 to 29.0 | 58.1 to 63.4 |
| Rotary-peeled birch & bamboo veneer consumed (thousand m3) | 145 to 160 | 158 to 174 | 345 to 378 |
| Average B2B wholesale price per 1,000 utensils (USD) | 15.40 to 17.00 | 15.50 to 17.10 | 16.50 to 18.00 |
Operational note: Piece volume estimates apply standard 160-millimeter (2.5-gram to 2.8-gram) die-cut birch and bamboo utensils packed in bulk 1,000-count catering cartons and paper-wrapped 3-in-1 takeaway meal kits.
Veneer Stamping Yield & Surface Burnishing Economics
Manufacturing food-safe wooden cutlery at industrial scale requires steaming debarked birch bolts, rotary-peeling 1.6-millimeter veneer sheets, die-cutting utensil blanks, and hot-pressing curved spoon bowls in heated steel molds. Unpolished die-cut blanks leave microscopic wood fibers raised on the rim, which swell upon contact with hot broth and create an unpleasant dry sensation on the diner's tongue. Consequently, mills supplying biodegradable disposable tableware tumble stamped utensils in rotating beechwood-chip drums for four to six hours and apply micro-thin food-grade beeswax or carnauba glazes. Furthermore, automated optical vision cameras inspect every fork tine for grain knots or micro-splinters before high-speed paper-sleeve wrapping.
Table 3: Mill Stamping Speed and Finishing Cost Indicators for the Wooden Cutlery Market (physical units and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Rotary die-cutting press output (strokes per minute) | 220 to 260 | 240 to 280 | 320 to 380 |
| Hot-press spoon bowl cycle time (seconds per batch) | 18 to 24 | 16 to 22 | 11 to 15 |
| Wax-burnished smooth-finish premium over raw birch (%) | 14% to 18% | 13% to 17% | 10% to 13% |
| FSC / PEFC certified log share of commercial output (%) | 68.0% | 71.5% | 86.0% |
Table 4: Foodservice & Channel Revenue Indicators for the Wooden Cutlery Market (USD million and percentages), 2026 baseline
| Metric | Value | Reference Basis |
|---|---|---|
| Global wooden cutlery market, 2026 | USD 450.0 million | 2026 baseline |
| Wooden spoons segment revenue, 2026 | USD 212.4 million | 47.2% segment share |
| FSC-certified birchwood revenue, 2026 | USD 246.6 million | 54.8% segment share |
| Food service outlets end-use revenue, 2026 | USD 193.1 million | 42.9% segment share |
Analyst Perspective
"Quick-service restaurant buyers specify FSC-certified birch and bamboo utensils because unmodified natural wood clears European and Canadian single-use plastic bans without synthetic polymer caveats. Mills must still invest in hot-pressed carnauba burnishing to match plastic mouthfeel in hot soups."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the wooden cutlery market segmented?
The wooden cutlery market is segmented by product type, wood species, end user, and sales channel. In 2026, Wooden Spoons are projected at 47.2%, FSC-Certified Birchwood at 54.8%, Food Service Outlets at 42.9%, and Direct B2B Foodservice Contracts at 38.6%.
By product type: Wooden Spoons, Wooden Forks, Wooden Knives, and Sporks, Tasters & Specialty Utensils.
By wood species: FSC-Certified Birchwood, Moso & Fast-Growth Bamboo, Poplar & Maple Veneer, and Other Certified Hardwoods.
By end user: Food Service Outlets (QSRs, Cafes & Restaurants), Institutional Catering (Airlines, Hospitals & Schools), and Household & Retail Events.
By sales channel: Direct B2B Foodservice Contracts, Foodservice Distributors & Wholesalers, and E-Retail & Supermarket Channels.
Why Do Wooden Spoons Lead the Wooden Cutlery Market by Product Type?
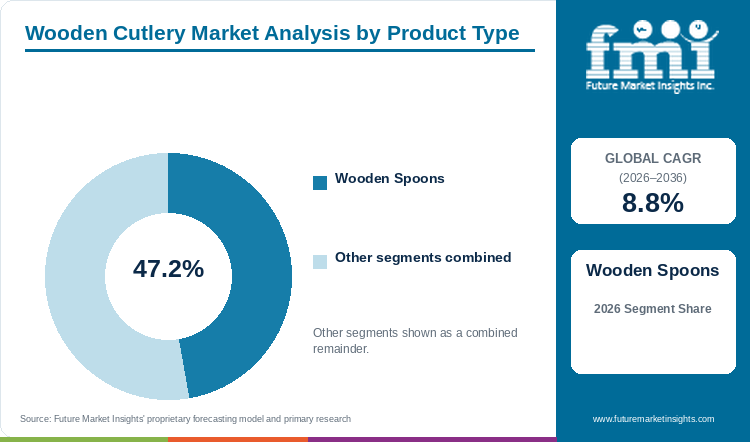
Wooden Spoons are set to lead product type with 47.2% share in 2026, underpinned by takeaway soup and dessert volume.
Table 5: Product Type Share for the Wooden Cutlery Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Wooden Spoons | 47.2% |
| Other Segments Combined | 52.8%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Wooden Cutlery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.8% |
| Leading Segment | Wooden Spoons |
Spoons generate nearly half of global wooden utensil turnover because liquid soups, ramen bowls, oatmeal cups, yogurt parfaits, and ice cream tubs cannot be eaten by hand or with flat paper sticks. When foodservice chains test laminated paper spoons in 80-degree Celsius broth, moisture wicks into the seam and flattens the bowl within minutes, whereas thermo-pressed 1.8-millimeter birch spoons retain structural camber throughout the meal. Besides this, dairy processors pack millions of miniature wooden tasting spoons directly inside single-serve ice cream lids alongside paper drinking cups and dessert tubs.
- Wooden Spoons represent 47.2% of product type revenue in 2026 because hot liquid entrees and chilled dairy cups require rigid, moisture-tolerant bowl geometry.
- In June 2025, the Compost Manufacturing Alliance registered Eco Gecko Creation LLC's 100% natural birch wooden spoons and forks as field-validated compostable foodservice substrates [3].
What Makes FSC-Certified Birchwood Central to the Wood Species Category?
By wood species, FSC-Certified Birchwood is estimated to hold 54.8% in 2026, backed by splinter-free rotary veneer peeling.
Silver birch and white birch (Betula pendula and Betula platyphylla) dominate industrial cutlery stamping because straight, knot-free logs peel cleanly into uniform 1.6-millimeter sheets on high-speed rotary lathes without tearing fibers. Unlike resinous softwoods such as pine that impart turpentine off-flavors into warm food, or coarse-pored oak that splinters along fork tines, birchwood exhibits tight, odorless pores and pale ivory aesthetics. Meanwhile, fast-growing Moso bamboo tableware products capture premium airline and casual-dining accounts where higher flexural tensile strength justifies a 15% to 25% unit price premium over birch.
- FSC-Certified Birchwood accounts for 54.8% of wood species revenue in 2026, facilitated by high rotary-peeling yields, neutral taste, and low splinter rates.
- In November 2025, the Forest Stewardship Council (FSC) adopted Motion 30 at its General Assembly to tighten chain-of-custody verification and prevent timber fraud across certified wood supply chains [4].
Why Do Food Service Outlets Anchor the End User Category?
Food Service Outlets are projected to capture 42.9% of end user demand in 2026, propelled by takeaway plastic prohibitions.
Quick-service restaurants, coffeehouse chains, and online meal-delivery kitchens represent the largest recurring buyer pool because every off-premise salad box, noodle bowl, and breakfast platter requires hygienically wrapped single-use utensils. Under European Union, British, Canadian, and Australian statutory bans on disposable polystyrene and oxo-degradable cutlery, restaurant operators cannot legally distribute plastic forks or spoons with delivery bags. Consequently, multi-unit restaurant chains bundle individually paper-sleeved wooden forks, knives, and napkins alongside compostable foodservice packaging to simplify counter assembly and pass municipal health and environmental inspections.
- Food Service Outlets hold 42.9% of end user demand in 2026, driven by high-frequency QSR meal delivery and statutory bans on plastic takeaway utensils.
- In October 2025, Duni Group reported in its Q3 Interim Report that its BioPak division acquired Australia-based ByGreen to strengthen sustainable single-use foodservice cutlery and tableware supply [5].
What Supports Direct B2B Foodservice Contracts Leadership within Sales Channel?
In 2026, Direct B2B Foodservice Contracts are expected to lead sales channel with 38.6% share, driven by custom-branded meal kits.
National quick-service chains, airline catering hubs, and stadium concessionaires procure wooden cutlery through direct multi-year manufacturer contracts to lock in container-load pricing and custom handle hot-stamping. Direct contracting allows restaurant procurement teams to audit FSC chain-of-custody certificates, verify European Regulation (EC) No 1935/2004 food-contact compliance, and co-pack wooden utensils with bagasse tableware products in unified shipping containers. Smaller independent cafes and regional caterers rely instead on cash-and-carry wholesalers and e-retail portals that offer lower minimum order quantities.
- Direct B2B Foodservice Contracts account for 38.6% of sales channel revenue in 2026, owing to volume price locks, custom logo embossing, and direct forestry audit traceability.
- In April 2026, Duni Group published its 2025 Annual and Sustainability Report detailing expanded direct foodservice contracting across the Duni, BioPak, and Paper+Design tableware brands [6].
What are the drivers, restraints, and opportunities in the wooden cutlery market?
Statutory single-use plastic cutlery prohibitions drive foodservice conversion, whereas EUDR timber traceability audits and rough unpolished mouthfeel constrain margins, and plant-polymer surface coatings unlock premium dining accounts.
- Driver: Nationwide single-use plastic cutlery bans across the European Union, the UK, Canada, and Asia Pacific force quick-service restaurants and airlines to procure natural birch and bamboo utensils.
- Restraint: Stringent EU Deforestation Regulation (EUDR) geolocation audits on imported birch logs and 2.0x to 2.5x unit cost premiums over legacy polypropylene utensils pressure foodservice operating margins.
- Opportunity: Applying thin plant-protein, carnauba wax, and PLA-free natural glazes eliminates dry wood mouthfeel while automated multi-item cutlery-and-napkin wrapping lines boost institutional catering sales.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Statutory prohibitions on single-use plastic forks, knives, and spoons have permanently eliminated petrochemical utensils from legal takeaway service in dozens of jurisdictions. Crucially, the European Union's Single-Use Plastics Directive (Directive (EU) 2019/904) bans chemically modified polymers including bio-based PLA and CPLA in single-use cutlery, leaving unmodified natural wood, bamboo, and molded fiber pulp as the only compliant disposable utensil materials. In June 2025, Duni Group acquired a majority stake in Finnish packaging distributor LinePack Oy to expand fiber and wooden takeaway tableware supply across Northern European QSR chains [7]. Airline and rail caterers simultaneously adopt lightweight wooden cutlery packs to cut cabin waste weight.
Risk Assessment of the Wooden Cutlery Market: Operational and Supply Friction
Raw material geopolitics and forestry traceability compliance create significant supply friction for wooden cutlery converters. Following trade sanctions on Russian and Belarusian birch timber, Chinese and European rotary-veneer mills faced tighter competition for Scandinavian, Baltic, and North East Asian birch logs. Furthermore, compliance with the EU Deforestation Regulation (EUDR) requires importers to provide exact polygon geolocation coordinates for every harvested forest plot. In June 2025, the United Nations Economic Commission for Europe (UNECE) documented in its Forest Tracks 2024/2025 market review that European and North American wood-product supply chains face structural log cost pressures and stricter sustainability documentation [8]. When competing against reusable commercial dining cutlery in dine-in restaurants required by EU PPWR reuse rules from 2028, disposable wooden utensils are increasingly confined to takeaway, delivery, and travel channels.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Cutlery manufacturers that solve the chalky, dry mouthfeel of raw stamped wood through natural surface engineering are capturing premium fast-casual, airline, and hotel room-service accounts. By hot-calendering stamped birch spoons in heated steel dies and applying microscopic carnauba wax, beeswax, or plant-protein glazes, producers achieve a glass-smooth rim that resists hot-soup warping for over 45 minutes without violating EU plastic-free definitions. In 2025, Bambu LLC partnered with professional culinary chefs to launch an ergonomically contoured, fine-burnished bamboo cutlery collection tailored for hospitality and epicurean catering [9]. Co-packaging smooth-finish wooden utensils with bio-based cutlery and molded fiber bowls allows distributors to sell complete zero-plastic meal kits.
Wooden Cutlery Market by Country (2026 to 2036)
As per FMI, Germany represents the fastest-growing wooden cutlery market among the six profiled countries at a 10.4% CAGR from 2026 to 2036, followed by Japan at 9.6%, the USA at 8.9%, and the UK at 8.3%, while Canada expands at a 7.2% CAGR. Country growth differentials reflect how national laws treat bio-plastic CPLA utensils, whether municipal taxes penalize single-use takeaway packaging, and how QSR delivery chains source FSC-certified timber.
Table 7: Country CAGR and Primary Growth Levers for the Wooden Cutlery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 10.4% | Strict SUPD enforcement against CPLA utensils, ZSVR packaging registry, and large F&B sector |
| Japan | 9.6% | Plastic Resource Circulation Act mandatory charges/reductions on konbini plastic spoons and forks |
| USA | 8.9% | State plastic utensil-on-request and compostable laws (WA, CA, NY) plus fast-casual delivery growth |
| UK | 8.3% | Defra England single-use plastic cutlery ban enforcement and PackUK foodservice EPR compliance |
| France | 7.9% | AGEC Law takeaway utensil rules balanced against mandatory reusable tableware for dine-in QSRs |
| Canada | 7.2% | Federal Single-use Plastics Prohibition Regulations on plastic cutlery and domestic birch supply |
Source: Future Market Insights analysis
Germany Wooden Cutlery Market Outlook (2026 to 2036)
Classifying chemically modified bio-plastics such as polylactic acid (CPLA) as prohibited single-use plastics under Germany's Single-Use Plastics Ban Ordinance eliminates polymer cutlery competition across Europe's largest foodservice market. In January 2026, Germany's Federal Environment Agency (Umweltbundesamt) reported that 5.5 million tonnes of household packaging waste were collected through dual recovery systems out of 19.0 million tonnes of total national packaging waste [10]. Heightened federal and municipal scrutiny on takeaway litter forces bakery chains, supermarket salad bars, and rail caterers to standardize on unmodified FSC-certified birch utensils, propelling the Germany wooden cutlery market at a 10.4% CAGR from 2026 to 2036. While municipal packaging taxes in cities such as Tübingen levy EUR 0.20 on wooden cutlery, national takeaway volume expands.
Key takeaway: In Germany, strict statutory bans on both fossil and CPLA bio-plastic utensils make FSC-certified birchwood cutlery the default standard across bakery and QSR takeaway channels.
Japan Wooden Cutlery Market Outlook (2026 to 2036)
Across Japan's 56,000 convenience stores (konbini), high daily turnover of chilled bento boxes, parfaits, and soups creates massive point-of-sale demand for wrapped disposable spoons and forks. In February 2026, Japan's Ministry of the Environment published the Seventh G20 Report on Actions against Marine Plastic Litter, documenting enforcement of the Plastic Resource Circulation Act across retailers and foodservice operators distributing 5.0 tonnes or more of single-use plastic cutlery annually [11]. To avoid consumer plastic charges and meet reduction targets, konbini chains switch to precision-stamped birch and bamboo utensils, so demand for wooden cutlery in Japan is projected to advance at a 9.6% CAGR through 2036. Yet commercial uptake faces friction from strict consumer expectations for smooth rims, requiring hot-calendered carnauba burnishing.
Key takeaway: In Japan, mandatory reduction rules for operators exceeding 5.0 tonnes of plastic utensils drive convenience-store conversion to smooth-burnished wooden bento spoons and forks.
USA Wooden Cutlery Market Outlook (2026 to 2036)
Because federal U.S. law imposes no nationwide ban on plastic utensils, American wooden cutlery demand relies on state plastic-on-request statutes in California, Washington, and New York alongside fast-casual brand positioning. In October 2025, the United States Environmental Protection Agency (US EPA) reported that containers and packaging waste totaled 82.22 million tons, including 11.53 million tons of wood packaging and 14.53 million tons of plastic packaging where 10.09 million tons entered landfills [12]. Salad, poke, and airline buyers replacing landfilled polystyrene forks with PFAS-free meal kits build on that shift, and the USA's wooden cutlery market is forecast to expand at an 8.9% CAGR between 2026 and 2036. However, competition from polypropylene utensils in unregulated states focuses growth on custom-sleeved QSR kits.
Key takeaway: In the USA, coastal state foodware laws and fast-casual chain commitments to PFAS-free compostable meal kits sustain steady bamboo and birch utensil adoption.
UK Wooden Cutlery Market Outlook (2026 to 2036)
Comprehensive enforcement of England, Scotland, and Wales prohibitions on single-use plastic and compostable-plastic cutlery removes low-cost polystyrene forks from fish-and-chip shops, street-food markets, and QSR chains nationwide. In September 2026, the Department for Environment, Food and Rural Affairs (Defra) reported in UK statistics on waste that wood packaging waste reached 1.24 million tonnes (43.7% recycled) within 11.06 million tonnes of total UK packaging arisings [13]. As PackUK Extended Producer Responsibility fees penalize hard-to-recycle foodservice plastics, British catering wholesalers import container-loads of rotary-peeled birch forks and dessert spoons, and commercial sales across the UK are set to register an 8.3% CAGR over the 2026 to 2036 period. Nonetheless, wholesale margin compression among catering distributors favors suppliers offering automated multi-item paper-wrapped meal kits.
Key takeaway: In the UK, Defra's nationwide ban on plastic and bio-plastic takeaway utensils locks in high-volume QSR and catering wholesaler demand for birchwood forks and spoons.
France Wooden Cutlery Market Outlook (2026 to 2036)
To enforce circular dining under the Anti-Waste for a Circular Economy (AGEC) Law, French regulators mandate washable crockery and metal flatware for dine-in meals at restaurants seating 20 or more patrons while banning plastic utensils in takeaway bags. In October 2025, Eurostat reported that European Union packaging waste reached 79.7 million tonnes (177.8 kilograms per inhabitant) with wood representing 15.8%, while France's plastic packaging recycling rate stood at 25.7% [14]. Strict French enforcement against unrecycled plastic foodware channels off-premise restaurant, patisserie, and salad-bar volume into natural wood; consequently, revenue in the France wooden cutlery market progresses at an estimated 7.9% CAGR through 2036. The central commercial obstacle involves dine-in volume shifting to reusable tableware, focusing suppliers on delivery and rail catering.
Key takeaway: In France, while dine-in restaurants must use washable flatware, strict AGEC takeaway plastic bans and low 25.7% plastic recycling rates anchor off-premise wooden cutlery demand.
Canada Wooden Cutlery Market Outlook (2026 to 2036)
Unlike jurisdictions that only restrict conventional polystyrene, Canada's federal Single-use Plastics Prohibition Regulations (SOR/2022-138) ban the manufacture, import, and sale of both conventional and non-conventional plastic cutlery across all provinces. In March 2026, Environment and Climate Change Canada (ECCC) reaffirmed in its regulatory overview that federal single-use plastic prohibitions target over 1.5 billion plastic utensils annually alongside 5.0 million tonnes of discarded national plastic waste [15]. National coffee chains, hospital cafeterias, and quick-service restaurants rely on birch and bamboo utensils to maintain legal takeaway operations; over the 2026 to 2036 forecast window, Canada posts a 7.2% CAGR in wooden cutlery turnover. Nevertheless, reliance on Asian stamping mills despite vast Canadian birch forests exposes distributors to trans-Pacific freight rates, encouraging domestic veneer-stamping investment.
Key takeaway: In Canada, federal SOR/2022-138 prohibitions eliminating 1.5 billion plastic utensils annually guarantee recurring QSR and institutional demand for birch and bamboo cutlery.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the wooden cutlery market?
Huhtamaki Oyj, Duni Group (BioPak), Vegware Ltd. (Novolex), Bambu LLC, Greenwood (Dalian) Industrial Co., Ltd., PacknWood (First Pack), Eco-gecko Products Inc., and PAPSTAR GmbH are the notable companies in this market.
FMI analysis indicates that competition in the wooden cutlery sector links vertically integrated Asian birch and bamboo rotary-veneer stamping mills with global foodservice packaging distributors and eco-tableware brands. High-capacity Chinese and Eastern European timber converters control debarking, rotary peeling, hot-press bowl molding, and automated paper-sleeve wrapping, while Western foodservice brands manage FSC chain-of-custody audits, EUDR geolocation compliance, and bundled delivery alongside molded fiber containers and paper cups.
- Global Foodservice Packaging Platforms: Huhtamaki Oyj, Duni Group (BioPak), and Vegware Ltd. (Novolex) supply FSC-certified wooden cutlery bundled with compostable cups, bowls, and takeaway boxes to multinational QSR chains.
- High-Volume Timber & Bamboo Stamping Manufacturers: Greenwood (Dalian) Industrial Co., Ltd. and Bambu LLC operate large-scale rotary veneer peeling, die-cutting, and carnauba/plant-oil burnishing mills.
- Specialty Hospitality & European Tableware Brands: PacknWood (First Pack), Eco-gecko Products Inc., and PAPSTAR GmbH distribute ergonomic, custom-embossed, and coated wooden utensils to caterers, airlines, and retailers.
Competitive Benchmarking: Wooden Cutlery Market
Table 8: Competitive Benchmarking for the Wooden Cutlery Market (qualitative capability ratings), 2026
| Company | Utensil & Kit Format Breadth | Surface Burnishing & Coating Tech | FSC / EUDR Traceability | Geographic Reach |
|---|---|---|---|---|
| Huhtamaki Oyj | High | High | High | High |
| Duni Group (BioPak) | High | High | High | High |
| Vegware Ltd. (Novolex) | High | Medium | High | High |
| Greenwood (Dalian) Industrial | High | High | High | High |
| Bambu LLC | Medium | High | High | Medium |
| PacknWood (First Pack) | High | Medium | High | Medium |
| Eco-gecko Products Inc. | Medium | High | Medium | Medium |
| PAPSTAR GmbH | High | Medium | High | Medium |
Scoring basis: Utensil & Kit Format Breadth is High when a supplier offers spoons, forks, knives, sporks, ice-cream tasters, and multi-item paper-wrapped meal kits, and Medium when focused on select utensil SKUs. Surface Burnishing & Coating Tech evaluates hot-calendered mold smoothness, carnauba/beeswax polishing, and moisture-resistant coatings. FSC / EUDR Traceability reflects documented 100% FSC or PEFC chain-of-custody certification and plot-level timber legality verification across global trade corridors.
Key Developments in the Wooden Cutlery Market
- In April 2026, Huhtamäki Oyj published its Q1 2026 Interim Report highlighting resilient comparable foodservice packaging demand and expanded fiber and wooden tableware programs across Europe and North America [16].
- In July 2025, Huhtamäki Oyj and Bunzl UK & Ireland partnered with Xampla to supply plant-based coated food boxes paired with plastic-free takeaway tableware across UK catering operators [17].
- In April 2026, Dalian GreenWood Industrial Co., Ltd. detailed expanded 6-billion-piece annual birch wooden spoon and cutlery stamping capacity across its Northern China production bases [18].
Key Players in the Wooden Cutlery Market
Global Foodservice Packaging Platforms
- Huhtamaki Oyj
- Duni Group (BioPak)
- Vegware Ltd. (Novolex)
High-Volume Timber & Bamboo Stamping Manufacturers
- Greenwood (Dalian) Industrial Co., Ltd.
- Bambu LLC
Specialty Hospitality & European Tableware Brands
- PacknWood (First Pack)
- Eco-gecko Products Inc.
- PAPSTAR GmbH
Wooden Cutlery Market - Report Scope
Table 9: Report Scope for the Wooden Cutlery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Wood Species; End User; Sales Channel; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes global commercial revenue from single-use and semi-reusable wooden and bamboo spoons, forks, knives, sporks, and pre-wrapped cutlery kits. Category Scope Note: Market valuation is reconciled in USD Million to reflect commercial B2B foodservice and retail sales of rotary-stamped wooden and bamboo utensils, excluding metal flatware, conventional plastic cutlery, and non-utensil paperboard containers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany, Japan, USA, UK, France, Canada, and additional countries in the full report |
| Key Companies Covered | Huhtamaki Oyj, Duni Group (BioPak), Vegware Ltd. (Novolex), Greenwood (Dalian) Industrial Co., Ltd., Bambu LLC, PacknWood (First Pack), Eco-gecko Products Inc., PAPSTAR GmbH |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Approach | Primary and secondary research with veneer conversion and foodservice outlet triangulation. |
Wooden Cutlery Market - Research Methodology
Table 10: Research Methodology for the Wooden Cutlery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with birch and bamboo rotary-veneer mills, die-cutting equipment engineers, QSR packaging procurement managers, airline catering buyers, and FSC chain-of-custody auditors. |
| Secondary Research | Secondary research covered FAO Global Forest Products statistical yearbooks, UNECE timber market reviews, EU PPWR and SUPD regulatory guidelines, Environment and Climate Change Canada registries, and company reports. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 reconciled bottom-up rotary stamping mill output (in billion pieces and cubic metres of birch/bamboo veneer) with top-down QSR and institutional takeaway meal volumes. |
| Data Triangulation and Validation | Estimates were cross-checked against national single-use plastic cutlery ban enforcement dates, wholesale carton price tiers (per 1,000 pieces), and FSC-certified birch log allocations. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's foodservice fiber and timber tableware econometric model, calibrating evaluated national growth rates against the 8.8% global baseline through verified plastic and CPLA utensil prohibitions, takeaway meal delivery penetration, and municipal packaging tax exemptions. |
| Operational Benchmark Traceability | Operational benchmarks (commercial wooden utensils shipped, rotary-peeled birch and bamboo veneer volume, and die-cutting press output per minute) represent modeled estimates synthesized from FAO forestry statistics, FSC certification registries, and commercial cutlery mill engineering disclosures. |
Wooden Cutlery Market by Segments
Wooden Cutlery Market segmented by Product Type:
- Wooden Spoons
- Wooden Forks
- Wooden Knives
- Sporks, Tasters & Specialty Utensils
Wooden Cutlery Market segmented by Wood Species:
- FSC-Certified Birchwood
- Moso & Fast-Growth Bamboo
- Poplar & Maple Veneer
- Other Certified Hardwoods
Wooden Cutlery Market segmented by End User:
- Food Service Outlets (QSRs, Cafes & Restaurants)
- Institutional Catering (Airlines, Hospitals & Schools)
- Household & Retail Events
Wooden Cutlery Market segmented by Sales Channel:
- Direct B2B Foodservice Contracts
- Foodservice Distributors & Wholesalers
- E-Retail & Supermarket Channels
Wooden Cutlery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations (FAO). (2025, December 24). Global forest products trade and production show signs of recovery in 2024. FAO Newsroom.
- [2] European Commission, Directorate-General for Environment. (2026, August 11). New EU rules on packaging enter into application. European Union Environment Portal.
- [3] Compost Manufacturing Alliance & Eco Gecko Creation LLC. (2025, June 10). Eco Gecko Creation LLC Birch Cutlery. Compost Manufacturing Alliance.
- [4] Forest Stewardship Council (FSC). (2025, November 27). FSC General Assembly 2025: Uniting for the future of forests. Forest Stewardship Council.
- [5] Duni Group. (2025, October 24). Interim Report January 1 – September 30, 2025. Duni Group Investor Relations.
- [6] Duni Group. (2026, April 23). Duni Group's 2025 Annual and Sustainability Report is now available online. Duni Group Investor Relations.
- [7] Duni Group. (2025, June 03). Duni Group Acquires Majority Stake in LinePack Oy. Duni Group Press Releases.
- [8] United Nations Economic Commission for Europe (UNECE). (2025, June 12). Forest Tracks: Country-level Market Insights 2024/2025. UNECE Committee on Forests and the Forest Industry.
- [9] Bambu LLC. (2025, August 20). Bamboo Kitchen & Tableware - FSC-Certified & Non-Toxic. Bambu Home.
- [10] Umweltbundesamt (German Federal Environment Agency). (2026, January 27). Facts against myths: Packaging waste recycling in Germany is working. Umweltbundesamt Press Information.
- [11] Ministry of the Environment, Japan. (2026, February 13). Publication of the "G20 Report on Actions against Marine Plastic Litter: Seventh Information Sharing Based on the G20 Implementation Framework". Ministry of the Environment, Japan.
- [12] United States Environmental Protection Agency (US EPA). (2025, October 23). Containers and Packaging: Product-Specific Data. US EPA.
- [13] Department for Environment, Food & Rural Affairs (Defra). (2026, September 23). UK statistics on waste. GOV.UK.
- [14] Eurostat, European Commission. (2025, October 22). Plastic packaging waste in the EU: 35.3 kg per person. Eurostat News.
- [15] Environment and Climate Change Canada (ECCC). (2026, March 02). Single-use Plastics Prohibition Regulations: Overview. Government of Canada.
- [16] Huhtamäki Oyj. (2026, April 29). Huhtamaki publishes Q1 2026 Interim Report on April 29, 2026. Huhtamaki Stock Exchange Releases.
- [17] Packaging Europe & Huhtamäki Oyj. (2025, July 30). Bunzl UK & Ireland and Huhtamaki provide food boxes with plant-based coating. Packaging Europe.
- [18] Dalian GreenWood Industrial Co., Ltd. (2026, April 29). 2026 Corporate Decision-Making Guide: Best Birch Wooden Spoon Supplier in Northern China - Dalian GreenWood Industrial Co., Ltd. Greenwood Corporate Publications.
- [19] PacknWood (First Pack). (2025, April 18). Eco-Friendly Utensils | Disposable | Wood & Bamboo Cutlery. PacknWood.
- [20] PAPSTAR GmbH. (2025, December 09). Papstar Wooden cutlery set. PAPSTAR.
- [21] WebstaurantStore & Eco-gecko Products Inc. (2024, December 19). Eco-gecko No PFAS Added Disposable Wooden Taster Spoon. WebstaurantStore.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the wooden cutlery market in 2026 and what is forecast for 2036?
- Which statutory single-use plastic bans support demand for wooden cutlery products?
- Why do Wooden Spoons lead the product type category?
- Why does FSC-Certified Birchwood lead the wood species category globally?
- How do growth rates differ across Germany, Japan, the USA, the UK, France, and Canada?
- Which leading companies supply wooden and bamboo cutlery products today?
- What EUDR timber traceability and surface-finish hurdles limit adoption in the wooden cutlery market?
- What should QSR and airline buyers evaluate before signing multi-year wooden cutlery contracts?
Frequently Asked Questions
How big is the wooden cutlery market in 2026, and what is forecast for 2036?
The global wooden cutlery market is estimated to reach USD 450.0 million in 2026. Revenue is projected to expand further and reach USD 1,045.9 million by 2036, driven by global prohibitions on single-use plastic and bio-plastic takeaway utensils.
What CAGR is forecast for the Wooden Cutlery Market through 2036?
As per FMI, the wooden cutlery market is projected to grow at an 8.8% CAGR from 2026 to 2036. Expansion is supported by QSR meal-delivery volume, airline weight-reduction goals, and hot-calendered wax surface finishing.
Which product type holds the leading wooden cutlery demand share in 2026?
Wooden Spoons are projected to hold 47.2% of product type demand in 2026. The segment benefits from deep-bowl structural rigidity required for hot soups, curries, rice bowls, and frozen dairy desserts.
Which wood species segment leads the wooden cutlery market in 2026?
FSC-Certified Birchwood is estimated to hold 54.8% of wood species demand in 2026. Demand is supported by high rotary-veneer peeling yields, tight splinter-free grain, and neutral flavor in hot foods.
Which country has the fastest wooden cutlery expansion outlook during the forecast period?
FMI finds that Germany is projected to expand at a 10.4% CAGR during the 2026 to 2036 assessment period. Growth is supported by strict enforcement of the Single-Use Plastics Ban Ordinance against both fossil and CPLA utensils.
Which companies are active in the Wooden Cutlery Market during 2026?
Notable market participants include Huhtamaki Oyj, Duni Group (BioPak), Vegware Ltd. (Novolex), Greenwood (Dalian) Industrial Co., Ltd., Bambu LLC, PacknWood (First Pack), Eco-gecko Products Inc., and PAPSTAR GmbH. These suppliers focus on carnauba-wax burnishing, automated paper-sleeve wrapping, and EUDR plot-level timber traceability.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Wooden Spoons
- Wooden Forks
- Wooden Knives
- Sporks, Tasters & Specialty Utensils
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Wood Species, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Wood Species, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Wood Species, 2026 to 2036
- FSC-Certified Birchwood
- Moso & Fast-Growth Bamboo
- Poplar & Maple Veneer
- Other Certified Hardwoods
- Y-o-Y Growth Trend Analysis By Wood Species, 2021 to 2025
- Absolute $ Opportunity Analysis By Wood Species, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- Food Service Outlets (QSRs, Cafes & Restaurants)
- Institutional Catering (Airlines, Hospitals & Schools)
- Household & Retail Events
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct B2B Foodservice Contracts
- Foodservice Distributors & Wholesalers
- E-Retail & Supermarket Channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Wood Species
- By End User
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Huhtamaki Oyj
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Duni Group (BioPak)
- Vegware Ltd. (Novolex)
- Greenwood (Dalian) Industrial
- Bambu LLC
- PacknWood (First Pack)
- Eco-gecko Products Inc.
- PAPSTAR GmbH
- Greenwood (Dalian) Industrial Co., Ltd.
- Huhtamaki Oyj
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


