
- Market Size (2026)
- USD 10.4 Bn
- Forecast (2036)
- USD 17.5 Bn
- CAGR (2026 to 2036)
- 5.3%
How big is Hot Melt Adhesives Market in 2026?
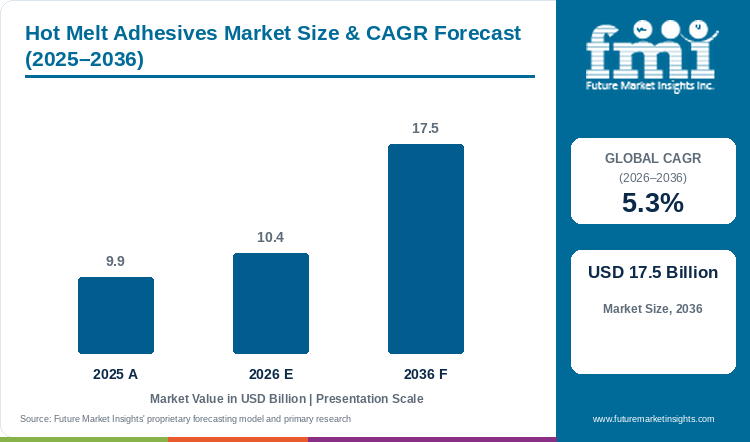
The hot melt adhesives market is estimated at USD 9.9 billion in 2025 and is forecast to reach USD 10.4 billion in 2026. Sales will grow at a 5.3% CAGR and are projected to reach USD 17.5 billion by 2036.
Sales of hot melt adhesives are highest in packaging, as carton sealing and case erecting lines apply glue on every box that leaves a plant. Estimated at USD 9.9 billion in 2025, hot melt adhesive sales are forecast to reach USD 10.4 billion in 2026 and USD 17.5 billion by 2036, a 5.3% CAGR over ten years. The dominant trend to 2036 will be fast pass-through of resin and oil costs into adhesive prices. Arkema reported a sharp increase in raw material costs after the Middle East conflict began and said the company answered with quick price adjustments during April to June 2026.[1] Raw material swings are the risks behind the headline growth rate, because packaging buyers on annual contracts now receive mid-year price notices. FMI analysts recommend that adhesive makers offer low-density, low-temperature grades to packaging customers, since each gram saved per case cuts the buyer's cost even after a price rise.
Key Market Trends & Insights
- Ethylene vinyl acetate is expected to hold 36% of base polymer sales in 2026 on standard packaging melters, and polyolefins about 27.5% on faster case lines.
- Carton, tray and label lines are likely to use 42% of hot melt adhesives in 2026, more than twice the estimated 18.6% for disposable hygiene products. Henkel grew Packaging and Consumer Goods 4.7% organically over January to June 2026.[2]
- Demand for non-reactive hot melts is projected to make up 62.4% of technology sales in 2026, and pressure sensitive and reactive systems split the remainder at 23.1% and 14.5%.
Regional Highlights
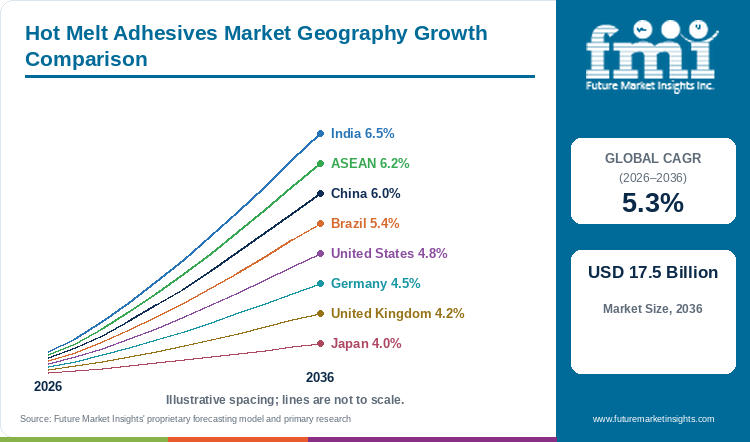
- New food, diaper and carton lines give India the quickest growth in FMI's country model, at 6.5% against 5.3% for the whole market.
- ASEAN and China follow India above the global figure, at 6.2% and 6%, and Brazil clears the global figure by only 0.1 points. The four mature markets fall between 4.8% for the United States and 4% for Japan, last in the country ranking.
- Asia-Pacific sales at Henkel grew 10.3% organically in the six months to June 2026, and Europe fell 1.5%.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Hot Melt Adhesives Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.9 billion |
| Estimated Market Size in 2026 | USD 10.4 billion |
| Projected Market Size by 2036 | USD 17.5 billion |
| CAGR, 2026 to 2036 | 5.3% |
| Added Revenue, 2026 to 2036 | USD 7.1 billion |
| Market Expansion Multiple | 1.7x |
Hot melt orders follow the run rates of packaging, hygiene and furniture lines, and adhesive makers reprice within one or two quarters of a resin move. After 7.4% organic growth in the June quarter, Henkel set a higher 2026 organic sales range of 2% to 4% for Adhesive Technologies, and the company said customer forward-buying tied to geopolitical uncertainty supported Consumer Goods.[2] Sales at Sika came to CHF 5,589.8 million for H1 2026, 4% more in local currencies.[3] Food cartons and trays carry a large part of the glue volume, and the food packaging market is forecast to expand at the same 5.3% CAGR as hot melts. Under FMI's forecast, hot melt adhesive sales are projected to gain USD 7.1 billion between 2026 and 2036, a rise of close to 70% on the 2026 figure. Forward-buying is the near-term risk, since stock built in the first half can thin orders later in 2026.
Raw Material Costs, Price Pass-Through and Line Speeds
Oil and resin inputs rose sharply in 2026. Naphthenic oil from Process Oils and Ergon cost 45 cents per gallon more from 13 March 2026, and some lubricant and oil makers put through increases of 9% to 16%.[4] H.B. Fuller said in September 2026 that pricing actions are offsetting higher raw material costs, and the company built strategic inventory because of ongoing disruption in the Middle East.[5] Adhesive Solutions was among the main drivers as Arkema grew April to June 2026 EBITDA by 7.4%, to EUR 391 million.[1] Styrenic hot melts use process oil as a plasticiser, so formulators will shift some grades toward polyolefin bases with less oil.
Assembly lines decide volume outside packaging. In the August 2026 fiscal quarter, Engineering Adhesives at H.B. Fuller grew 0.7% organically, and Hygiene, Health and Consumable Adhesives grew 6.4%.[5] Jowat do Brasil prepared polyolefin edgebanding hot melts and a PUR grade for profile wrapping to show furniture makers at ForMóbile 2026 in São Paulo.[6] Assembly lines running faster will order more reactive and fast-setting grades, and slower car plants will cut orders for interior trim adhesives.
Table 2: Raw Material, Supplier and Output Indicators for the Hot Melt Adhesives Market (prices, growth and output), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Henkel Adhesive Technologies organic growth, Q2 2026 | Up 7.4% | Price and volume both rose. | [2] |
| Arkema EBITDA, Q2 2026 | EUR 391 million; up 7.4% | Adhesive Solutions drove earnings. | [1] |
| Sika sales, H1 2026 | CHF 5,589.8 million; up 4% in local currencies | Construction and industry adhesives grow. | [3] |
| Naphthenic process oil price, March 2026 | Up 45 cents per gallon | Plasticiser costs rise for styrenic grades. | [4] |
| H.B. Fuller net revenue, Q3 FY2026 | USD 938 million; up 5.2% | Hygiene and consumable adhesives grow fastest. | [5] |
| China parcel volume, 2025 | 198.95 billion parcels; up 13.6% | Each parcel carton is sealed with glue. | [7] |
Analyst Perspective
“The packaging buyer has become the toughest customer in hot melts, because a cent per case adds up across billions of boxes. Suppliers that cut coat weight and application temperature are gaining those contracts in 2026, and I expect lightweight polyolefin grades to take EVA volume on high-speed lines through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the hot melt adhesives market segmented?
The market is segmented into base polymer, end use industry, technology, and region. Ethylene vinyl acetate is expected to lead base polymer sales with 36% share in 2026, and packaging solutions lead end use with 42%.
By base polymer: ethylene vinyl acetate, polyolefins, polyamides, polyurethanes, styrene block copolymers, and others.
By end use industry: packaging solutions, disposable hygiene products, furniture and woodwork, automotive and transportation, footwear and textile, electronics, publishing and bookbinding, and others.
By technology: reactive hot melt, non-reactive hot melt, and pressure sensitive.
By region: packaging, hygiene and assembly plants in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does ethylene vinyl acetate lead hot melt adhesives sales by base polymer?
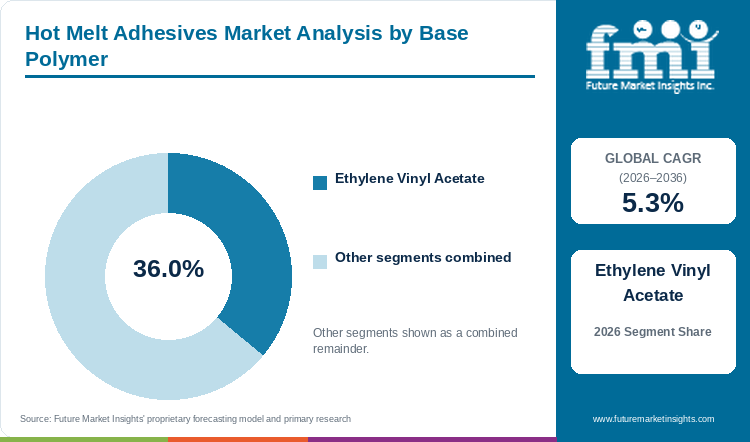
Ethylene vinyl acetate is expected to lead base polymer sales with 36% share in 2026, ahead of polyolefins at about 27.5% and styrene block copolymers at roughly 15.8%.
Table 3: Base Polymer Share for the Hot Melt Adhesives Market (percentage share), 2026
| Base Polymer | Estimated Share (2026) |
|---|---|
| Ethylene Vinyl Acetate | 36% |
| Polyolefins | 27.5% |
| Styrene Block Copolymers | 15.8% |
| Polyurethanes | 10.9% |
| Others | 5.2% |
| Polyamides | 4.6% |
| Total | 100.0% |
Table 4: Base Polymer Leadership and Market Growth for the Hot Melt Adhesives Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.3% |
| Leading Segment | Ethylene Vinyl Acetate |
Ethylene vinyl acetate is expected to lead with 36% share in 2026, because EVA grades bond corrugated board quickly, cost little and run on every standard melter. Polyolefins, an estimated 27.5%, hold heat better and run at lower coat weights, so high-speed case lines are moving to them. Styrene block copolymers, near 15.8%, give the tack needed for diaper and label constructions but need process oil, whose price rose by 45 cents per gallon at Process Oils and Ergon in March 2026.[4] Polyurethanes, about 10.9%, cure into structural bonds for furniture, textiles and electronics. Polyamides, near 4.6%, serve high-heat bonding, and other bases take 5.2%. A carton plant choosing between EVA and polyolefin will stay with EVA until line speed or heat resistance forces the switch.
- General purpose and packaging grade EVA formulas account for most of the EVA volume.
- A sharp increase in raw material costs followed the start of the Middle East conflict, Arkema said in the July 2026 results release.[1]
Why do packaging solutions lead hot melt adhesives sales by end use industry?
Packaging solutions are likely to hold 42% of end use sales in 2026, with disposable hygiene products at about 18.6% and furniture and woodwork at roughly 11.2%.
Table 5: End Use Industry Share for the Hot Melt Adhesives Market (percentage share), 2026
| End Use Industry | Estimated Share (2026) |
|---|---|
| Packaging Solutions | 42% |
| Disposable Hygiene Products | 18.6% |
| Furniture and Woodwork | 11.2% |
| Automotive and Transportation | 7.4% |
| Footwear and Textile | 6.1% |
| Others | 5.6% |
| Electronics | 4.8% |
| Publishing and Bookbinding | 4.3% |
| Total | 100.0% |
Every carton leaving a food, drink or e-commerce warehouse is sealed with hot melt, so glue volume follows parcel and grocery volume and packaging solutions will lead end use with 42% share in 2026. Strong Packaging growth came with a 9.1% organic rise in Henkel Consumer Goods over the three months to June 2026.[2] Disposable hygiene products, an estimated 18.6%, use elastic and construction glues in diapers and wipes, and the wet wipes market is likely to rise at a 7.4% CAGR, two points faster than hot melts. Furniture and woodwork, near 11.2%, use edge banding glue, and growth in the contract furniture market is expected at a 6.1% CAGR. Automotive, about 7.4%, footwear and textile, 6.1%, electronics, 4.8%, and bookbinding, 4.3%, are smaller lines, and other uses take 5.6%. Box makers buy glue by the truckload, which keeps packaging far ahead of every assembly use.
- Packaging use centres on case and carton sealing, tray forming and labelling.
- Henkel said customer forward-buying tied to geopolitical uncertainty supported Consumer Goods sales in Q2 2026.[2]
Why do non-reactive systems lead hot melt adhesives sales by technology?
Non-reactive hot melts are estimated at 62.4% of technology sales in 2026, against about 23.1% for pressure sensitive and 14.5% for reactive systems.
Table 6: Technology Share for the Hot Melt Adhesives Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Non-Reactive Hot Melt | 62.4% |
| Pressure Sensitive | 23.1% |
| Reactive Hot Melt | 14.5% |
| Total | 100.0% |
EVA and polyolefin glues set on cooling and need no curing time on a packaging line, so non-reactive hot melts are projected to account for 62.4% of technology sales in 2026. Pressure sensitive systems, near 23.1%, stay tacky for labels, tapes and hygiene backsheets. Reactive hot melts, about 14.5%, cure with moisture into bonds that survive heat and solvents, and Electronics within the Henkel Mobility and Electronics unit grew at a double-digit pace in the opening half of 2026.[2] The 14.5% reactive share matches the polyurethane share plus some reactive polyolefin grades. Plant engineers will keep non-reactive glue on every line that needs speed and choose reactive grades for heat-exposed parts.
- Non-reactive volume comes mostly from thermoplastic EVA and polyolefin systems and fast-setting grades.
- Reactive PUR hot melts wrap PVC foils, decor papers and veneers onto furniture profiles, Jowat do Brasil said in June 2026.[6]
What are the drivers, restraints, and opportunities in the hot melt adhesives market?
Packaged goods, parcels and hygiene products need glue on every unit, which keeps volume rising with consumption. Resin and oil price spikes squeeze converters, and lower-weight and recyclable grades open new contracts.
- Driver: Every carton, diaper and labelled bottle carries hot melt, so adhesive volume grows in step with packaged consumption and parcel shipments.
- Restraint: Resin and oil inputs move with crude and supply shocks, which forces mid-contract price rises that packaging buyers resist.
- Opportunity: Brands seeking recyclable packs and lower glue use per pack reward suppliers with low coat weight and wash-off grades.
Packaged Consumption Keeps Glue Volume Rising
Popularity of packaged food and e-commerce delivery keeps carton lines running. Henkel raised the 2026 organic growth outlook for Adhesive Technologies to 2% to 4%.[2] Sika expects to keep outperforming the construction and industrial markets in 2026.[3] Each extra parcel and grocery pack adds a few grams of hot melt to supplier volume.
Raw Material Spikes Squeeze Converters
Producers of hot melt adhesives face input costs that can jump within weeks, and FMI analysts expect resin and oil swings to recur through 2036. Naphthenic process oil prices rose by 25 to 45 cents per gallon in March 2026.[4] Arkema answered input cost inflation with quick selling price increases over April to June 2026.[1] Packaging converters on fixed-price contracts will absorb part of each rise until contracts reset.
Lightweight and Recyclable Grades Open New Contracts
Buyer preference is moving to glues that use less material and come off in recycling. The EU Packaging and Packaging Waste Regulation generally applies from 12 August 2026 and sets recyclability performance grades from 2030.[8] Recyclable packs are spreading, with the sustainable packaging market expected to expand at a 5.8% CAGR across the forecast period. Suppliers with wash-off and low-weight grades will gain specification with brand owners.
Which country CAGRs are profiled in the hot melt adhesives market?
Table 7: Country CAGR Comparison for the Hot Melt Adhesives Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 6.5% |
| ASEAN | 6.2% |
| China | 6% |
| Brazil | 5.4% |
| United States | 4.8% |
| Germany | 4.5% |
| United Kingdom | 4.2% |
| Japan | 4% |
How do country-level CAGRs compare in the hot melt adhesives market?
Organic growth of 14.9% in the IMEA region, which covers India, the Middle East and Africa, came through for Henkel in the half to June 2026.[2] Packaged food and hygiene products reaching new households put four markets over the 5.3% global CAGR in the FMI country split, led by India at 6.5% and ASEAN at 6.2%. China grows at 6%, and Brazil, at 5.4%, sits just over the line. Mature lines in the United States and Germany mostly replace glue, at 4.8% and 4.5%, and the United Kingdom and Japan close the table near 4%.
- Indian food and hygiene brands are adding carton and diaper lines.
- Contract packers in ASEAN serve export food and consumer goods.
- E-commerce parcels in China carry hot melt on every carton.
- Demand in Brazil follows food and beverage packaging.
- American converters face slow manufacturing growth.
- German packers are adapting cartons to EU packaging rules from August 2026.
- British packaging lines replace glue on mature equipment.
- Japanese demand comes from ageing populations buying adult hygiene products.
Full report country CAGRs cover: Packaging and hygiene production in India, ASEAN and China gives the three fastest rates, with Brazil just above the 5.3% global CAGR. The United States and Germany are below that rate, the United Kingdom and Japan are lowest, and Eastern Europe and Middle East and Africa are summarised at regional level.
Country-wise Analysis
India Hot Melt Adhesives Market Outlook (2026 to 2036)
Demand for hot melt adhesives in India is projected to rise at a 6.5% CAGR as packaged goods reach smaller cities. Henkel's IMEA region, which includes India, achieved 14.9% organic growth in H1 2026.[2] Packaged food, diapers and e-commerce cartons are reaching smaller cities, and each new line needs a melter and a glue supply contract.
Key takeaway: Packaged goods reaching new households make India the fastest profiled country.
ASEAN Hot Melt Adhesives Market Outlook (2026 to 2036)
Contract packing for export brands gives ASEAN a forecast 6.2% CAGR. Henkel grew 10.3% organically in Asia-Pacific over the half.[2] Contract packers in Vietnam, Thailand and Indonesia seal export cartons for food and consumer brands.
Key takeaway: Export packing lines carry growth across ASEAN.
China Hot Melt Adhesives Market Outlook (2026 to 2036)
China handled 198.95 billion parcels in 2025, up 13.6%, and passed 100 billion parcels by 30 June 2026, the State Post Bureau reported.[7] Per FMI's country model, parcel cartons and domestic hygiene brands are expected to carry China at a 6% CAGR. Local adhesive makers compete hard on price for carton glue.
Key takeaway: Parcel and hygiene volume carries China, and local suppliers hold price low.
Brazil Hot Melt Adhesives Market Outlook (2026 to 2036)
Food, beverage and personal care brands in Brazil are adding carton and label lines for domestic consumers, which supports a 5.4% CAGR, only a fraction above the global figure. Furniture makers form a second buyer group, and Jowat do Brasil planned a stand at ForMóbile 2026, held in São Paulo from 30 June to 3 July, to present edgebanding and wrapping hot melts.[6]
Key takeaway: Food and beverage packing sets the outlook in Brazil.
United States Hot Melt Adhesives Market Outlook (2026 to 2036)
Minnesota-based H.B. Fuller grew net sales 5.2% to USD 938 million in the quarter to August 2026, with 4.4% organic growth.[5] FMI places the United States at a 4.8% CAGR, half a point under the global figure. North American organic growth at Henkel was 2.4% in the first six months of 2026.[2] American converters will buy more polyolefin grades to cut coat weight on high-speed lines.
Key takeaway: Slow factory growth and a shift to lighter grades shape the United States.
Germany Hot Melt Adhesives Market Outlook (2026 to 2036)
German food and consumer goods packers face EU packaging rules that apply from 12 August 2026.[8] Those rules and weak European demand point to a projected 4.5% CAGR for Germany. Henkel's European business shrank 1.5% organically over January to June 2026.[2] Packers redesigning cartons for recyclability will test lower-weight and wash-off glues on existing lines.
Key takeaway: Weak European demand and new packaging rules keep Germany below the global rate.
United Kingdom Hot Melt Adhesives Market Outlook (2026 to 2036)
British food and drink packers run mature carton lines, and the United Kingdom is forecast at a 4.2% CAGR. PackUK set illustrative Year 2 base fees for 2026 to 2027 at GBP 210 per tonne for paper and board and GBP 455 per tonne for plastic under packaging extended producer responsibility.[9] Adhesive volume grows with replacement melters and new e-commerce fulfilment centres.
Key takeaway: Replacement lines and fulfilment centres carry the British outlook.
Japan Hot Melt Adhesives Market Outlook (2026 to 2036)
Japanese hygiene makers are shifting diaper lines from baby sizes to adult incontinence products, and each adult product carries more construction and elastic glue. Baby diaper volume falls with the birth rate. Fewer births leave Japan last in the country ranking, with a projected 4% CAGR.
Key takeaway: Adult hygiene growth only partly offsets fewer births in Japan.
Who are the notable companies in the hot melt adhesives market?
H.B. Fuller, Henkel, 3M, Arkema, Avery Dennison, Sika, Jowat, Beardow Adams, Dow and Heartland Adhesives are the profiled companies.
The ten companies FMI profiles include global adhesive groups, diversified materials companies and specialist hot melt makers. Adhesive Technologies at Henkel sold EUR 5,534 million of products in the half to June 2026.[2] Arkema earned EUR 391 million of EBITDA in Q2 2026.[1] Sika, with CHF 5,589.8 million of sales in the half, is the largest construction-focused member.[3] H.B. Fuller, 3M, Avery Dennison, Dow, Jowat, Beardow Adams and Heartland Adhesives complete the group.
- Global adhesive leaders: Henkel, H.B. Fuller, Arkema and Sika.
- Diversified materials groups: 3M, Dow and Avery Dennison.
- Specialist hot melt makers: Jowat, Beardow Adams and Heartland Adhesives.
Competitive Benchmarking: Hot Melt Adhesives Market
Table 8: Competitive Benchmarking for the Hot Melt Adhesives Market (qualitative documentation ratings), 2026
| Company | Packaging Range | Hygiene Range | Regional Plants | Recency |
|---|---|---|---|---|
| Henkel | High | High | High | High |
| H.B. Fuller | High | High | High | High |
| Arkema | Medium | High | High | High |
| Sika | Low | Low | High | Medium |
| Jowat | Medium | Low | Medium | High |
How many recent company filings and releases support a rating sets each score, and none of the scores ranks share.
Key Developments in the Hot Melt Adhesives Market
- On 23 September 2026, H.B. Fuller announced fiscal third-quarter net sales of USD 938 million, 5.2% higher.[5]
- On 6 August 2026, Henkel moved the Adhesive Technologies organic growth outlook for 2026 up to a range of 2% to 4%.[2]
- On 30 July 2026, Arkema announced a 7.4% EBITDA gain for the quarter, to EUR 391 million.[1]
- In July 2026, Sika published half-year sales of CHF 5,589.8 million.[3]
- On 4 July 2026, the State Post Bureau of China reported that parcel volume passed 100 billion for 2026.[7]
- On 11 June 2026, Jowat do Brasil previewed polyolefin and PUR hot melts for ForMóbile 2026.[6]
- On 6 April 2026, the European Circular Economy Stakeholder Platform confirmed that the EU packaging regulation applies from 12 August 2026.[8]
- In March 2026, Process Oils, Ergon and Calumet raised naphthenic oil prices.[4]
- On 16 December 2025, PackUK published illustrative Year 2 waste disposal fees for packaging producers.[9]
Key Players in the Hot Melt Adhesives Market
Global Adhesive Leaders
- Henkel
- H.B. Fuller
- Arkema
- Sika
Diversified Materials Groups
- 3M
- Dow
- Avery Dennison
Specialist Hot Melt Makers
- Jowat
- Beardow Adams
- Heartland Adhesives
Hot Melt Adhesives Market - Report Scope
Table 9: Report Scope for the Hot Melt Adhesives Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Base polymer; end use industry; technology; region |
| Quantitative units | USD billion |
| Market definition | Thermoplastic and reactive adhesives applied molten, including EVA, polyolefin, polyamide, polyurethane and styrenic block copolymer grades, for packaging, hygiene, woodwork, automotive, textile, electronics and bookbinding. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | H.B. Fuller, Henkel, 3M, Arkema, Avery Dennison, Sika, Jowat, Beardow Adams, Dow, Heartland Adhesives |
| Forecast period | 2026 to 2036 |
Hot Melt Adhesives Market - Research Methodology
Table 10: Research Methodology for the Hot Melt Adhesives Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Adhesive maker results, raw material price reports, packaging regulator notices, postal authority releases and trade press from May 2025 onward. |
| Desk Research | Desk research covers raw material prices, supplier results, packaging and hygiene trends and industrial output. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 10.4 billion and the 5.3% CAGR for 2026 to 2036. |
| Data Validation | Prices, growth rates and output figures were matched to the company, agency or trade publication that reported them. |
Hot Melt Adhesives Market by Segments
Hot Melt Adhesives Market segmented by Base Polymer:
- Ethylene Vinyl Acetate
- Polyolefins
- Polyamides
- Polyurethanes
- Styrene Block Copolymers
- Others
Hot Melt Adhesives Market segmented by End Use Industry:
- Packaging Solutions
- Disposable Hygiene Products
- Furniture and Woodwork
- Automotive and Transportation
- Footwear and Textile
- Electronics
- Publishing and Bookbinding
- Others
Hot Melt Adhesives Market segmented by Technology:
- Reactive Hot Melt
- Non-Reactive Hot Melt
- Pressure Sensitive
Hot Melt Adhesives Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Arkema. (2026, July 30). Second-quarter 2026 results. https://www.arkema.com/global/en/media/newslist/news/global/investorrelations/2026/20260730--second-quarter-2026-results/
- [2] Henkel AG & Co. KGaA. (2026, August 6). News release: Henkel first half-year 2026. https://www.henkel.com/resource/blob/2217816/f75cb43c06c2102319810e23bb21e784/data/henkel-news-release-h1-2026-eng.pdf
- [3] Sika AG. (2026). Half-Year Report 2026. https://www.sika.com/en/half-year-report/half-year-report-2026.html
- [4] Lubes'N'Greases. (2026, March 25). Weekly Americas Base Oil Price Report. https://www.lubesngreases.com/bor-americas/weekly-americas-base-oil-price-report-65/
- [5] H.B. Fuller Company. (2026, September 23). Exhibit 99.1: H.B. Fuller Reports Third Quarter 2026 Results (Form 8-K). https://www.sec.gov/Archives/edgar/data/0000039368/000143774926031113/ex_1019044.htm
- [6] Wood & Panel. (2026, June 11). Jowat do Brasil targets furniture and wood producers with advanced adhesive systems at ForMóbile 2026. https://www.woodandpanel.us/news/article/jowat-do-brasil-targets-furniture-and-wood-producers-with-advanced-adhesive-systems-at-formobile-2026/
- [7] China Daily. (2026, July 4). China sets a new record in express delivery. https://govt.chinadaily.com.cn/s/202607/04/WS6a4cabae498e36855033dadb/china-sets-a-new-record-in-express-delivery.html
- [8] European Circular Economy Stakeholder Platform. (2026, April 6). The EU Packaging and Packaging Waste Regulation: when will it come into effect and what does it cover? https://circulareconomy.europa.eu/platform/en/news-and-events/all-news/eu-packaging-and-packaging-waste-regulation-when-will-it-come-effect-and-what-does-it-cover
- [9] PackUK and Department for Environment, Food & Rural Affairs. (2025, December 16). Year 2 illustrative waste disposal fees: extended producer responsibility for packaging. https://www.gov.uk/government/publications/year-2-illustrative-waste-disposal-fees-extended-producer-responsibility-for-packaging/year-2-illustrative-waste-disposal-fees-extended-producer-responsibility-for-packaging
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the hot melt adhesives market during 2026?
- What market size is projected by 2036?
- Which base polymer holds notable share?
- Which end use industry holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Base Polymer, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Base Polymer, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Base Polymer, 2026 to 2036
- Ethylene Vinyl Acetate
- Polyolefins
- Polyamides
- Polyurethanes
- Styrene Block Copolymers
- Others
- Y-o-Y Growth Trend Analysis By Base Polymer, 2021 to 2025
- Absolute $ Opportunity Analysis By Base Polymer, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use Industry, 2026 to 2036
- Packaging Solutions
- Disposable Hygiene Products
- Furniture and Woodwork
- Automotive and Transportation
- Footwear and Textile
- Electronics
- Publishing and Bookbinding
- Others
- Y-o-Y Growth Trend Analysis By End Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Reactive Hot Melt
- Non-Reactive Hot Melt
- Pressure Sensitive
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Base Polymer
- By End Use Industry
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Base Polymer
- By End Use Industry
- By Technology
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Base Polymer
- By End Use Industry
- By Technology
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Base Polymer
- By End Use Industry
- By Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Henkel
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- H.B. Fuller
- Arkema
- Sika
- Jowat
- 3M
- Dow
- Avery Dennison
- Beardow Adams
- Heartland Adhesives
- Henkel
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Base Polymer, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by End Use Industry, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Technology, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Base Polymer
- Figure 6: Global Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use Industry
- Figure 9: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Technology
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Base Polymer
- Figure 26: North America Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by End Use Industry
- Figure 29: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Technology
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Base Polymer
- Figure 36: Latin America Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by End Use Industry
- Figure 39: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Technology
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Base Polymer
- Figure 46: Western Europe Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by End Use Industry
- Figure 49: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Technology
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Base Polymer
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by End Use Industry
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Base Polymer
- Figure 66: East Asia Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by End Use Industry
- Figure 69: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Technology
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Base Polymer
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by End Use Industry
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Base Polymer, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Base Polymer, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Base Polymer
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by End Use Industry, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by End Use Industry, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by End Use Industry
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Technology
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the hot melt adhesives market expected in 2026?
Hot melt adhesive sales are estimated at USD 10.4 billion in 2026 by FMI, against USD 9.9 billion in 2025. Sales are projected to reach USD 17.5 billion by 2036.
What CAGR is projected for the hot melt adhesives market through 2036?
Sales are expected to grow at a 5.3% CAGR from 2026 to 2036. Cartons, diapers and labels that need glue on every unit carry that growth.
Which base polymer holds a notable market share in 2026?
Base polymer sales are led by ethylene vinyl acetate, expected at 36% share in 2026. Polyolefins follow at an estimated 27.5%.
Which end use industry holds a notable market share in 2026?
Packaging solutions are likely to hold 42% share in 2026. Disposable hygiene products follow at an estimated 18.6%.
Which country has a notable expansion outlook through 2036?
Fastest of the eight profiled countries in the FMI outlook, India is projected to grow at a 6.5% CAGR. ASEAN follows at 6.2%.
Who are the key companies in the hot melt adhesives market?
Global adhesive leaders include Henkel, H.B. Fuller, Arkema and Sika. 3M, Dow, Avery Dennison, Jowat, Beardow Adams and Heartland Adhesives complete the profiled group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
