

- Market Size (2026)
- USD 512.4 Mn
- Forecast (2036)
- USD 1341.1 Mn
- CAGR (2026 to 2036)
- 10.1%
How big is AI Workload Carbon-Aware Placement Software Market in 2026?
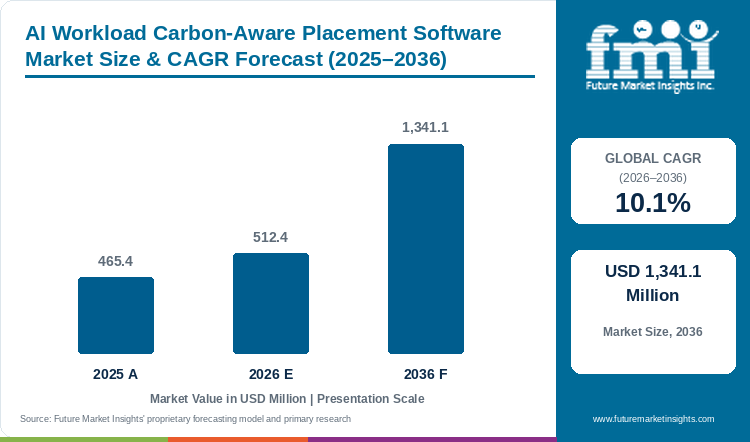
The market was valued at USD 465.4 Million in 2025 and is expected to reach USD 512.4 Million in 2026, with growth at a 10.1% CAGR from 2026 to 2036 taking its value to USD 1,341.1 Million by 2036.
Carbon-aware placement adds emissions information to a decision the operator can make about a job’s timing or location, after filtering for capacity, data access and service requirements. A lower grid-intensity signal does not establish a better result if the destination cannot run the job or the transfer adds work that changes the expected benefit. Buyers therefore need a transparent comparison with a feasible alternative, including compatible time and geographic boundaries and the full execution window. Flexible training and batch tasks may provide choices that immediate-response services do not, making a limited trial useful before control expands. Japan’s infrastructure planning connects placement with power and communications availability, while German buyers also need to distinguish operational decisions from procurement accounting. The forecast covers qualifying placement software, simulation and governance, excluding electricity purchases, carbon credits and general reporting without this function. [5]
Key Market Trends & Insights
- Monitoring & telemetry holds 27.0% of platform function in 2026, joining workload activity and power use with emissions information that has a defined time and location.
- SaaS / public cloud holds 38.0% of deployment model in 2026, giving eligible batch jobs a choice among approved regions subject to capacity and data restrictions.
- 251–500 kW holds 32.0% of AI rack density in 2026, requiring destination headroom and cooling capacity to remain feasible alongside any favorable carbon signal.
- Hyperscale AI data centers account for 46.0% of data center type in 2026, with queue priorities determining the portion of work that can change its time or location.
Regional Highlights
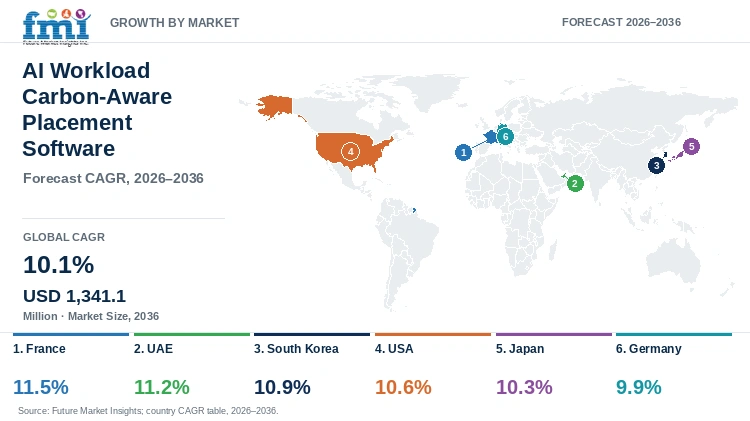
- France has the highest profiled CAGR at 11.5% during 2026–2036.
- The next two profiled growth rates are UAE at 11.2% and South Korea at 10.9% over the same period.
Market Size & Forecast
| Metric | Value |
|---|---|
| 2025 market value | USD 465.4 Million |
| 2026 market estimate | USD 512.4 Million |
| 2036 market forecast | USD 1,341.1 Million |
| Forecast CAGR, 2026–2036 | 10.1% |
The market covers software specifically used to monitor, simulate, govern or control AI workload placement using electricity and carbon-related signals. Electricity procurement, carbon credits and general reporting products without a workload-placement function are excluded.
Carbon-aware placement needs the operating limits of data-center power so that a lower-emissions schedule remains feasible at the receiving facility.
Infrastructure readiness and acceptance
| Documented operating context | Source |
|---|---|
| Commission Delegated Regulation 2024/1364 establishes the first phase of the EU data-center reporting scheme. | [1] |
| Red Hat’s May 2025 technical article describes Kueue-based workload admission and GPU resource allocation in OpenShift AI. | [2] |
| HPE announced GreenLake Intelligence in June 2025 as an approach to coordinated hybrid-IT operations. | [3] |
| The IEA’s 2025 Energy and AI report examines electricity demand and supply constraints associated with AI infrastructure. | [4] |
Analyst Perspective
A placement decision needs an operationally acceptable baseline and emissions information with a clear time and geographic boundary. Recording feasible alternatives, transfer work and completed jobs lets buyers assess the result and decide whether a policy remains useful, rather than treating a favorable signal as a complete carbon outcome.
- Sudip Saha, Principal Analyst at Future Market Insights
How is the AI workload carbon-aware placement software market segmented?
Platform Function covers Monitoring & telemetry, Planning & simulation, Optimization & control, Fault / reliability analytics and Reporting & governance. Deployment Model covers SaaS / public cloud, Private cloud, On-premise and Hybrid deployment. AI Rack Density covers 251–500 kW, 100–250 kW, Below 100 kW and Above 500 kW. Data Center Type covers Hyperscale AI data centers, Colocation AI facilities, Enterprise private AI and HPC & research centers. Commercial Model covers Direct enterprise contract, System integrator / EPC-led, Subscription / license and Managed-service contract.
Data from data-center infrastructure management can help connect a carbon signal to the equipment actually available for the proposed workload.
Why does Monitoring & telemetry lead platform function demand?
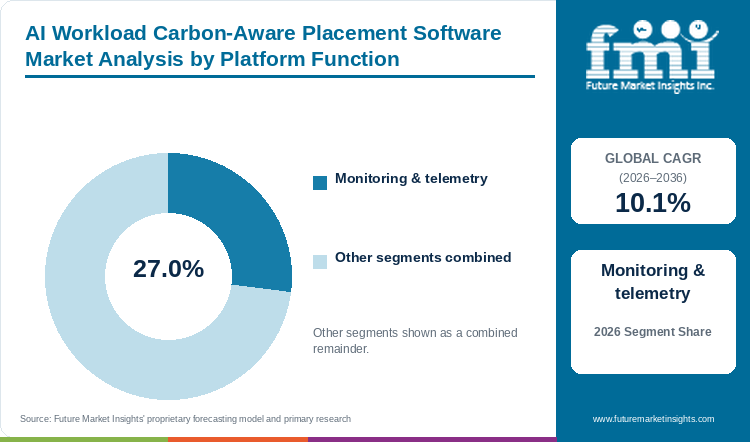
Monitoring & telemetry: 27.0% of platform function in 2026.
Monitoring connects a workload’s location and energy use with emissions information covering the relevant period and area. A broad average may help reporting while offering limited value for a near-term decision, and the duration of the job can extend beyond a brief change in the signal. Clear boundaries allow buyers to assess the comparison and its assumptions before judging an optimization result, rather than relying on a score that conceals how the inputs relate.
- The Monitoring & telemetry segment accounts for 27.0% of platform function in 2026.
- The emissions signal and workload measurements need compatible time and geographic boundaries before they can support a meaningful placement comparison.
Why does SaaS / public cloud lead deployment model demand?
SaaS / public cloud: 38.0% of deployment model in 2026.
A hosted policy can compare approved regions and execution windows for eligible batch jobs, provided it removes unavailable or unauthorized choices before ranking them by emissions. Capacity reservations, data sovereignty, transfer charges and deadlines still determine feasibility, so a region visible in a console is not automatically a valid destination. Showing why alternatives were rejected helps the buyer understand both the selected placement and the practical limits of the comparison.
- The SaaS / public cloud segment accounts for 38.0% of deployment model in 2026.
- A regional carbon comparison should exclude destinations that lack authorized data access or the accelerator capacity needed to complete the job.
What are the drivers, restraints, and opportunities in the AI workload carbon-aware placement software market?
Flexible workloads create placement choices
Some AI work can run later or at another approved site without changing the service purchased by the user. That flexibility gives operators a way to consider emissions alongside cost and completion time. The opportunity does not require construction of a new facility but does require control over the job. Buyers should connect the placement change with measured energy and useful work completed. This makes the decision operational rather than a reporting exercise. The strongest purchase case is a defined set of flexible workloads for which the alternative can be tested and sustained.
Data movement and service constraints limit carbon savings
Always-on inference provides fewer choices than deferrable work, while even a movable job can incur transfer, restart or data-location restrictions. Emissions information adds uncertainty when its time or geographic boundary differs from the workload measure, requiring a transparent comparison of feasible alternatives. A trial without production control can test that policy against completion commitments before autonomous placement is considered.
Auditable scheduling can connect emissions data to operations
Vendors can add carbon-aware decisions to scheduling systems customers already use. An initial deployment should cover jobs that are genuinely movable and a limited group of approved sites. The controller can record the signal and rejected alternatives as well as the final decision. This gives operators a way to review whether the policy remains useful when conditions change. Expansion should follow evidence that the method protects completion requirements and measures the relevant effects. Clear interfaces and a reproducible comparison are more valuable than a broad claim of savings across an unrestricted global fleet.
The constraints established during AI infrastructure commissioning should remain binding when an optimization policy seeks a different time or location for compute.
Which country and market CAGRs are profiled for AI workload carbon-aware placement software?
| Country | CAGR |
|---|---|
| France | 11.5% |
| UAE | 11.2% |
| South Korea | 10.9% |
| USA | 10.6% |
| Japan | 10.3% |
| Germany | 9.9% |
Country-wise Analysis
France
- Nonurgent training gives French operators a possible choice of execution window within approved locations, while data restrictions and network readiness reduce the available options. France has the fastest profiled forecast, at an 11.5% CAGR from 2026 to 2036. Including transfer work and completion requirements allows the policy to compare feasible placements instead of choosing a destination solely for its lower reported grid intensity.
UAE
- Announced UAE energy arrangements need commissioning and a defined operating contribution before they become power available to a site. The 11.2% CAGR forecast for 2026 to 2036 includes opportunities to begin with local forecasts where cross-site transfers are impractical. Identifying jobs that cannot move and retaining the emissions inputs keeps each decision reviewable within jurisdictional and network limits.
South Korea
- South Korean operators need to consider regional electricity conditions alongside the sites and execution windows they can actually use. A trial without production authority can test whether proposed benefits survive capacity and completion constraints within the market’s 10.9% CAGR forecast for 2026 to 2036. Making rejected alternatives visible gives buyers a practical basis for selecting workloads for a later active policy.
USA
- American operators managing connection constraints may already be deciding when flexible jobs should run, with carbon information adding a separate comparison from power price. Within the USA’s 10.6% CAGR forecast for 2026 to 2036, customers need to assess controlled locations and windows and retain the outcome after completion. That distinction makes it possible to compare an expected benefit with an observed result without losing the service deadline.
Japan
- Approved Japanese locations can offer fewer choices than a global cloud demonstration, leaving time shifting useful when transfer between sites is impractical. Japan is forecast to grow at a 10.3% CAGR from 2026 to 2036, with bandwidth, transfer volume and forecast stability shaping the policy. The software also needs to explain when a signal is too uncertain to justify disrupting the existing schedule.
Germany
- Renewable-procurement accounting in Germany does not assign the same physical emissions profile to every operating hour, making retained signals and decision histories useful alongside energy and completed work. The market’s forecast is a 9.9% CAGR from 2026 to 2036 within established governance and workload deadlines. These records help separate reporting obligations from the effect of an actual operational change.
Who are the notable companies in the AI workload carbon-aware placement software market?
NVIDIA, including SchedMD; Red Hat; Hewlett Packard Enterprise; IBM; Siemens Digital Industries Software
Scheduling capability and emissions information are different parts of the offer. A platform may control a queue without assessing the effects of data movement. An emissions-data provider may have no authority over jobs. Customers need to understand how those functions are joined before treating either as a complete placement solution.
Competitive Benchmarking: AI Workload Carbon-Aware Placement Software Market
| Participant | Commercial focus | Buyer qualification priority |
|---|---|---|
| NVIDIA, including SchedMD | AI workload and cluster management | Scheduler integration and recovery controls |
| Red Hat | Kubernetes and OpenShift AI platforms | Admission policy and operational consistency |
| Hewlett Packard Enterprise | Hybrid infrastructure operations | Workload-to-infrastructure visibility |
| IBM | Enterprise workload orchestration | Priority rules and queue governance |
| Siemens Digital Industries Software | HPC workload-management software | Policy integration and deployment support |
Key Developments in the AI Workload Carbon-Aware Placement Software Market
- Red Hat’s May 2025 technical article describes Kueue-based workload admission and GPU resource allocation in OpenShift AI. [2]
- HPE announced GreenLake Intelligence in June 2025 as an approach to coordinated hybrid-IT operations. [3]
Key Players in the AI Workload Carbon-Aware Placement Software Market
- NVIDIA, including SchedMD
- Red Hat
- Hewlett Packard Enterprise
- IBM
- Siemens Digital Industries Software
AI Workload Carbon-Aware Placement Software Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Platform Function; Deployment Model; AI Rack Density; Data Center Type; Commercial Model; Region |
| Quantitative unit | USD Million |
| Market definition | The market covers software specifically used to monitor, simulate, govern or control AI workload placement using electricity and carbon-related signals. Electricity procurement, carbon credits and general reporting products without a workload-placement function are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries / markets profiled | France; UAE; South Korea; USA; Japan; Germany |
| Key companies profiled | NVIDIA, including SchedMD; Red Hat; Hewlett Packard Enterprise; IBM; Siemens Digital Industries Software |
| Base year / forecast period | 2026 / 2026–2036 |
| Estimate coverage | 2025 and 2026 market estimates; 2036 forecast; segment shares and country / market CAGRs. |
AI Workload Carbon-Aware Placement Software Market - Research Methodology
| Method | Application |
|---|---|
| Market definition | The analysis follows the stated product or service boundary and distinguishes direct category revenue from adjacent activities. |
| Secondary research | Official technical, regulatory, research and company publications provide the documented operating context and recent developments cited in this report. |
| Forecast and segmentation | Market estimates, segment shares and geographic forecasts are presented as analytical estimates within the stated commercial scope. |
| Competitive assessment | Participants are compared by their relevant products or services, commercial role and buyer qualification requirements. |
| Interpretation | The assessment considers purchasing conditions and the scope of the documented product, service or performance claim. |
AI Workload Carbon-Aware Placement Software Market by Segments
Platform Function
- Monitoring & telemetry
- Planning & simulation
- Optimization & control
- Fault / reliability analytics
- Reporting & governance
Deployment Model
- SaaS / public cloud
- Private cloud
- On-premise
- Hybrid deployment
AI Rack Density
- 251–500 kW
- 100–250 kW
- Below 100 kW
- Above 500 kW
Data Center Type
- Hyperscale AI data centers
- Colocation AI facilities
- Enterprise private AI
- HPC & research centers
Commercial Model
- Direct enterprise contract
- System integrator / EPC-led
- Subscription / license
- Managed-service contract
AI Workload Carbon-Aware Placement Software Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Commission. (2024, May 17). Commission Delegated Regulation (EU) 2024/1364 on a Common Union Rating Scheme for Data Centres.
- [2] Red Hat. (2025, May 22). Improve GPU utilization with Kueue in OpenShift AI.
- [3] HPE. (2025, June 24). HPE Reimagines Hybrid IT Operations with GreenLake Intelligence.
- [4] International Energy Agency. (2025, April 10). Energy and AI.
- [5] Future Market Insights. (2026). AI Workload Carbon-Aware Placement Software Market: Global industry analysis and opportunity assessment, 2026–2036.
This Report Answers
- How large is the AI workload carbon-aware placement software market in 2026?
- What value and CAGR are forecast through 2036?
- Which platform function segment leads in 2026?
- Which deployment model segment has the largest share?
- Which profiled country or market has the fastest forecast growth?
- Which participants are covered in the competitive assessment?
Frequently Asked Questions
How large is the AI workload carbon-aware placement software market in 2026?
The market was valued at USD 465.4 Million in 2025 and is expected to reach USD 512.4 Million in 2026.
What value and CAGR are forecast through 2036?
The market is projected to reach USD 1,341.1 Million by 2036, with a 10.1% CAGR during 2026–2036.
Which platform function segment leads in 2026?
The Monitoring & telemetry segment accounts for 27.0% of platform function in 2026.
Which deployment model segment has the largest share?
The SaaS / public cloud segment accounts for 38.0% of deployment model in 2026.
Which profiled country or market has the fastest forecast growth?
France has the highest profiled CAGR at 11.5% during 2026–2036.
Which participants are covered in the competitive assessment?
The assessment covers NVIDIA, including SchedMD, Red Hat, Hewlett Packard Enterprise, IBM and Siemens Digital Industries Software.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Platform Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Platform Function, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Platform Function, 2026 to 2036
- Monitoring & telemetry
- Planning & simulation
- Optimization & control
- Fault / reliability analytics
- Reporting & governance
- Y-o-Y Growth Trend Analysis By Platform Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Platform Function, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Deployment Model, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Deployment Model, 2026 to 2036
- SaaS / public cloud
- Private cloud
- On-premise
- Hybrid deployment
- Y-o-Y Growth Trend Analysis By Deployment Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Model, 2026 to 2036
- Global Market Analysis and Forecast, By AI Rack Density, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By AI Rack Density, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By AI Rack Density, 2026 to 2036
- 251–500 kW
- 100–250 kW
- Below 100 kW
- Above 500 kW
- Y-o-Y Growth Trend Analysis By AI Rack Density, 2021 to 2025
- Absolute $ Opportunity Analysis By AI Rack Density, 2026 to 2036
- Global Market Analysis and Forecast, By Data Center Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Data Center Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Data Center Type, 2026 to 2036
- Hyperscale AI data centers
- Colocation AI facilities
- Enterprise private AI
- HPC & research centers
- Y-o-Y Growth Trend Analysis By Data Center Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Data Center Type, 2026 to 2036
- Global Market Analysis and Forecast, By Commercial Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Commercial Model, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Commercial Model, 2026 to 2036
- Direct enterprise contract
- System integrator / EPC-led
- Subscription / license
- Managed-service contract
- Y-o-Y Growth Trend Analysis By Commercial Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Commercial Model, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Platform Function
- By Deployment Model
- By AI Rack Density
- By Data Center Type
- By Commercial Model
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- NVIDIA, including SchedMD
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Red Hat
- Hewlett Packard Enterprise
- IBM
- Siemens Digital Industries Software
- NVIDIA, including SchedMD
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


