
- Market Size (2026)
- USD 52.0 Bn
- Forecast (2036)
- USD 99.1 Bn
- CAGR (2026 to 2036)
- 6.7%
How big is Barrier Packaging Market in 2026?
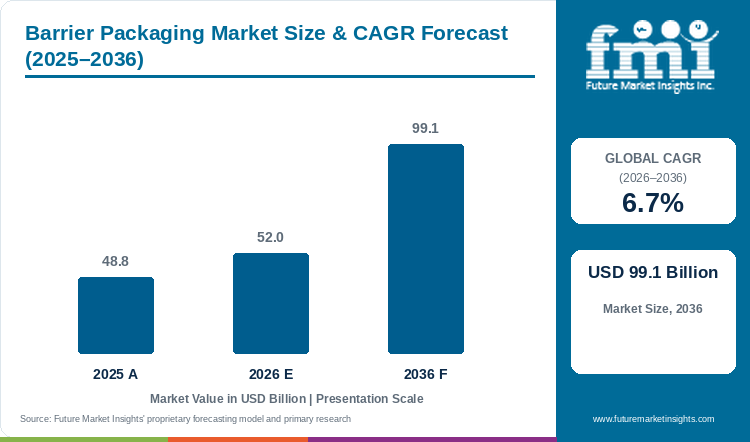
Global barrier packaging market was valued at USD 48.8 billion in 2025 and stands at USD 52.0 billion in 2026. The industry is forecast to reach USD 99.1 billion by 2036 at a 6.7% CAGR.
Controlling oxygen ingress and water vapor transmission across grocery and pharmaceutical supply chains determines how much perishable food and oral solid medication survives transit without spoiling. According to FMI, global barrier packaging revenue climbs from USD 48.8 billion in 2025 to USD 52.0 billion in 2026 and is set to attain USD 99.1 billion by 2036 at a 6.7% CAGR, creating USD 47.1 billion in cumulative expansion. Plastic Films account for 47.0% of material sales in 2026 through co-extruded EVOH polyolefin webs. In January 2025, the U.S. Food and Drug Administration noted that 30% to 40% of the national food supply is wasted across retail and household stages, prompting food processors to specify vacuum skin films and modified-atmosphere laminations that extend fresh case life.
Key Market Trends & Insights
- By material type: Co-extruded mono-polyolefin structures with EVOH barrier cores place Plastic Films at 47.0% of 2026 material demand.
- By application: Perishable meat and dry coffee preservation keeps Food & Beverage at 56.0% of 2026 application revenue.
- By packaging format: High-speed form-fill-seal pouching lines put Pouches at 34.0% of 2026 format sales across wet pet food and dry snacks.
- By barrier type: Formulations requiring oxygen transmission below 1.0 cc/m²/day give High Barrier structures 41.0% of 2026 barrier revenue.
- By sales channel: Multi-year film qualification contracts between multinational brand owners and converters anchor Direct Supply at 58.0% of 2026 channel volume.
Regional Highlights
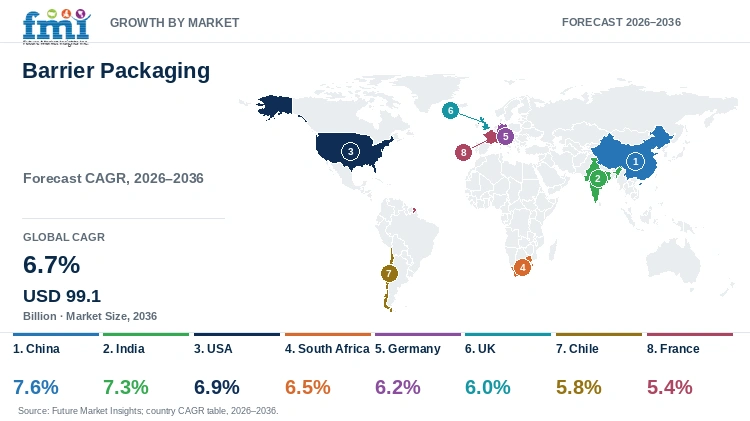
- Fastest-growing evaluated country: E-commerce grocery fulfillment and domestic pharmaceutical blister lines propel China to a leading 7.6% CAGR from 2026 to 2036.
- By country: India (7.3%) and the USA (6.9%) expand on packaged dairy and vacuum meat films while South Africa (6.5%) and Germany (6.2%) lead regional upgrades ahead of the UK (6.0%) and export-driven demand in Chile (5.8%) and France (5.4%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Barrier Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| Global Market Value (2025) | USD 48.8 billion |
| Global Market Value (2026) | USD 52.0 billion |
| Projected Market Value (2036) | USD 99.1 billion |
| Forecast CAGR (2026 to 2036) | 6.7% |
| Absolute Dollar Opportunity (2026 to 2036) | USD 47.1 billion |
Converter capital investment shifts across jurisdictions as plastic packaging taxes and metal import tariffs alter the cost balance between polymer films and functional barrier paper. In February 2026, UK HM Revenue & Customs raised the Plastic Packaging Tax rate to GBP 228.82 per metric ton effective April 1, 2026 for plastic packaging containing less than 30% recycled content. Brand owners in Europe and North America are consequently replacing non-recyclable PET/aluminum-foil/PE laminates with machine-direction-oriented polyethylene (MDO-PE) and dispersion-coated high barrier packaging films that pass curbside recyclability audits without sacrificing moisture holdout.
Oxygen and Moisture Permeation Engineering and Substrate Transition Sizing
Table 2: Barrier Packaging Permeation Standards and Substrate Conversion Metrics (OTR, WVTR, and Million Metric Tons), mixed historical and forecast years from 2025 to 2036
| Barrier Engineering Metric | 2025 | 2026 | 2036 | Permeation & Recyclability Benchmark |
|---|---|---|---|---|
| Global Converted Barrier Packaging Volume | 19.8 million MT | 20.9 million MT | 36.8 million MT | Includes polymer webs, coated barrier papers, foil laminates, and pharma blisters |
| Recycle-Ready Mono-Polyolefin (PE/EVOH, PP/SiOx) Share | 31.5% | 35.8% | 68.0% | Replacing multi-material PET/AlOx/PE to satisfy EU PPWR 2030 recyclability rules |
| High-Barrier OTR / WVTR Qualification Standard | < 1.0 cc/m²/day | < 0.5 to 1.0 cc/m²/day | < 0.1 to 0.5 cc/m²/day | Measured at 23°C, 0% RH (OTR) and 38°C, 90% RH (WVTR) per ASTM D3985 / F1249 |
| Functional Barrier Paper Share of Flexible Wraps | 11.2% | 12.8% | 24.5% | Water-based PVDC-free dispersion coatings and metallized cellulosic webs |
Operational note: Tonnage figures encompass multilayer and mono-material barrier plastic films alongside dispersion-coated barrier papers and aluminum foil laminates sold to commercial packers. Recycle-ready mono-material structures must maintain at least 90% to 95% polyolefin weight fraction (limiting EVOH tie layers to below 5%) to qualify under European RecyClass and U.S. APR guidelines.
Per Capita & End-Use Packaging Line Barrier Intensity
Multi-layer barrier webs have become essential across modern food processing and pharmaceutical manufacturing because even microscopic oxygen or humidity ingress degrades active ingredients and triggers lipid rancidity. Historically, converters achieved near-zero permeation by adhesive-laminating polyester and aluminum foil into composite webs that could not be separated in mechanical recycling streams. Today, 9-layer and 11-layer blown and cast co-extrusion lines allow engineers to sandwich sub-micron ethylene vinyl alcohol (EVOH) cores between oriented polyethylene layers, matching legacy foil shelf life while running at full speed on existing form-fill-seal machines.
Table 3: Per Capita and Packaging Line Spending Indicators for the Barrier Packaging Market (USD), mixed historical and forecast years from 2025 to 2036
| Country / Region | 2026 Per Capita Spend (USD) | 2036 Per Capita Spend (USD) | Annual Barrier Film Spend per High-Speed Line (USD thousand) |
|---|---|---|---|
| United States | USD 41.20 | USD 76.50 | USD 2,150 thousand |
| Germany | USD 36.80 | USD 65.40 | USD 1,890 thousand |
| United Kingdom | USD 33.50 | USD 58.20 | USD 1,740 thousand |
| China | USD 7.90 | USD 16.40 | USD 1,320 thousand |
| India | USD 2.40 | USD 4.85 | USD 840 thousand |
Table 4: Application & Barrier Tier Technical Indicators for the Barrier Packaging Market (OTR/WVTR and Shares), mixed reporting years from 2025 to 2026
| Application Tier | Share of Barrier Revenue (2026) | Required OTR / WVTR Threshold | Dominant Barrier Architecture |
|---|---|---|---|
| Chilled Meat, Poultry & Cheese Vacuum Packs | 28.5% | OTR < 1.0 to 2.0 cc/m²/day | 7- to 11-layer PA/EVOH/PE vacuum skin film and thermoformed bottom webs |
| Dry Coffee, Snacks, Pet Food & Culinary Powders | 27.5% | OTR < 0.5 cc/m²/day; WVTR < 0.5 g/m²/day | MDO-PE/EVOH, VMPET, or ultra-high-barrier coated paper stand-up pouches |
| Pharmaceutical Solid Dose Blisters & Sachets | 21.0% | WVTR < 0.05 to 0.2 g/m²/day | Cold-form Alu-Alu foil, PCTFE (Aclar) thermoform film, and PVDC-coated PVC |
| Personal Care, Cosmetics & Industrial Chemicals | 23.0% | OTR < 1.0 cc/m²/day; chemical resistance | PBL/ABL laminated tubes, EVOH agrochemical jerrycans, and moisture-barrier bags |
Analyst Perspective
"Brand owners are replacing aluminum-foil laminates with mono-polyolefin EVOH films and dispersion-coated barrier papers to meet 2030 recyclability mandates. Yet narrowing heat-seal temperature windows on high-speed form-fill-seal lines and 50% U.S. aluminum foil tariffs continue to challenge converters."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Barrier Packaging Market Segmented?
The market is segmented by material type, application, packaging format, barrier type, sales channel, and region. Plastic Films lead material type at 47.0% share in 2026, while Food & Beverage accounts for 56.0% of application revenue.
By material type: Plastic Films, Paper & Paperboard, Aluminum Foil, Metallized Films, and Coated Materials.
By application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial, and Others.
By packaging format: Pouches, Bags, Blisters, Trays, and Wraps.
By barrier type: High Barrier, Medium Barrier, and Low Barrier.
By sales channel: Direct Supply, Contract Converting, and Distributor Sales.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why Do Plastic Films Lead Barrier Packaging Material Type Demand?
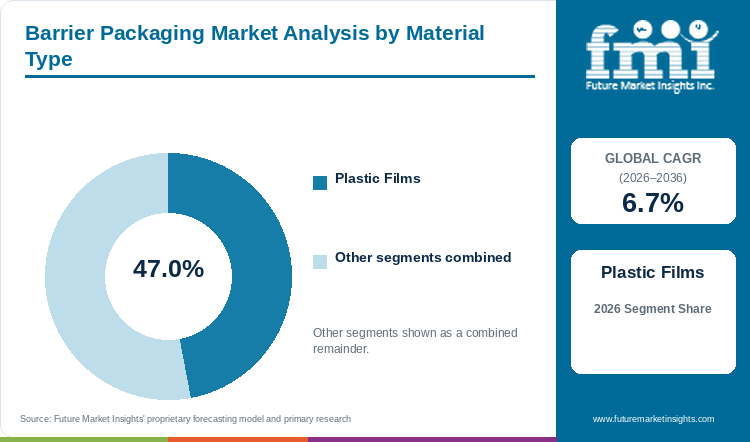
Plastic Films represent 47.0% of material type revenue in 2026 through co-extruded PE/EVOH and BOPP barrier webs.
Table 5: Barrier Packaging Market Share by Material Type (2026)
| Material Type Segment | 2026 Value Share (%) | Primary Barrier Mechanism & Substrate Role |
|---|---|---|
| Plastic Films | 47.0% | Co-extruded BOPP, MDO-PE, PA, and PET webs integrating EVOH or PVDC barrier cores |
| All Other Material Types* | 53.0% | Dispersion-coated barrier paperboard, aluminum foil laminates, VMPET/VMCPP, and AlOx/SiOx coatings |
| Total | 100.0% | Global Barrier Packaging Material Universe |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Material Type Segment Context for the Barrier Packaging Market (2026 to 2036)
| Metric | Value |
|---|---|
| Leading Material Segment (2026) | Plastic Films (47.0%) |
| Second-Largest Material Segment (2026) | Paper & Paperboard (18.5%) |
| Third-Largest Material Segment (2026) | Aluminum Foil (14.2%) |
| Primary Circularity Transition | Migration from multi-material PET/Alu/PE to mono-PE/EVOH and FunctionalBarrier Paper |
Co-extruded and laminated polymer films spanning biaxially oriented polypropylene (BOPP) and polyethylene (PE) with EVOH cores anchor material demand because they deliver puncture resistance and hermetic heat-sealability at a fraction of rigid container weight. By keeping the EVOH oxygen-barrier layer below 5% of total film weight, converters engineer EVOH films for packaging that pass polyethylene stream recyclability testing. Paper & Paperboard holds 18.5% share in 2026 as brands adopt water-based dispersion-coated papers while Aluminum Foil (14.2%) and Metallized Films (11.8%) alongside Coated Materials (8.5%) serve zero-permeation pharmaceutical and snack applications.
- Mono-material MDO-PE and BOPE co-extrusions keep Plastic Films at 47.0% of material sales in 2026 by replacing unrecyclable duplex laminates.
- In March 2026, Amcor announced a major capital investment to expand its Lugo, Italy flexible packaging plant to scale recycle-ready mono-material high-barrier films for European food and healthcare brands.
What Makes Food & Beverage Central based on Application Type?
Food & Beverage secures 56.0% share in 2026 application demand as processors curb retail spoilage across meat and coffee.
Food and beverage processors consume more than half of all barrier packaging because lipid oxidation and moisture gain directly dictate retail sell-by dates and supermarket chargebacks. Fresh red meat and poultry rely on vacuum skin packaging and EVOH shrink bags to extend chilled case life from 4 days to 21 days, while roasted coffee and culinary spices require aroma-tight barriers that block UV light and humidity. Pharmaceuticals represent the second-largest application at 21.0% in 2026 for moisture-sensitive oral tablets while Personal Care (11.5%) and Industrial (7.0%) alongside Others (4.5%) cover cosmetic sachets and agrochemical liners.
- Extended shelf-life mandates across chilled protein and dry culinary goods keep Food & Beverage at 56.0% share in 2026 by application.
- In February 2026, Mondi partnered with European spice producer Prymat to replace multi-material plastic-and-foil laminates with recyclable FunctionalBarrier Paper Ultimate, preserving essential oil aroma and moisture protection.
Why Do Pouches Anchor Barrier Packaging Format Selection?
Pouches capture 34.0% of 2026 format revenue through lightweight stand-up and retortable pouch conversion.
Stand-up and flat-bottom retortable pouches lead format revenue because they use up to 75% less material by weight than rigid metal cans or glass jars while offering wide front-and-back billboard panels. Consumer brands use reclosable zipper pouches and spouted pouches across wet pet food and grated cheese to maximize shelf facing and cut inbound truckloads of empty containers. Bags hold 23.5% share in 2026 for bulk pet kibble and coffee while Blisters (16.8%) serve blister packaging in pharmaceuticals alongside Trays (14.2%) and Wraps (11.5%) for meat lidding and confectionery.
- High-speed horizontal form-fill-seal pouching lines and foil-free retort webs sustain the 34.0% share of Pouches during 2026.
- In February 2026, ProAmpac launched its ProActive Recyclable RP-2000 High Barrier Series fiber-based pouch and bag platform engineered to run on conventional form-fill-seal lines.
What Supports High Barrier Leadership Across Barrier Type?
High Barrier commands 41.0% share in 2026 by barrier type, keeping oxygen transmission below 1.0 cc/m²/day.
High-barrier structures defined by oxygen transmission rates below 1.0 cc/m²/day and water vapor transmission rates below 1.0 g/m²/day command the largest revenue share because premium pet nutrition and pharmaceutical formulations cannot tolerate atmospheric permeation during 12-to-24-month shelf lives. Achieving this performance without aluminum foil requires vacuum-deposited aluminum oxide (AlOx), silicon oxide (SiOx), or multi-layer EVOH co-extrusions across metallized barrier film and coated paper substrates. Medium Barrier webs hold 36.5% share in 2026 for dry pasta and serial liners, while Low Barrier structures account for 22.5% across breathable produce wraps.
- Stringent 12-to-24-month ambient shelf-life requirements keep High Barrier at 41.0% share in 2026 based on barrier type.
- In August 2025 Mondi scaled production of its FunctionalBarrier Paper Ultimate range to provide ultra-high oxygen and water-vapor barrier performance for roasted coffee and culinary seasoning brands.
How Does Direct Supply Maintain Sales Channel Dominance?
Direct Supply accounts for 58.0% of 2026 channel turnover through multi-year converter-to-brand film qualification.
Direct B2B supply contracts between primary barrier film converters and multinational food and pharmaceutical manufacturers dominate channel revenue because barrier webs must be custom-calibrated to each plant's sealing jaws and sterilization temperature. Qualifying a new mono-material barrier laminate or cold-form blister foil typically requires 6 to 18 months of accelerated shelf-life stability testing. Contract Converting accounts for 24.5% of 2026 channel sales as co-packers procure pre-qualified rollstock for private-label brands, while Distributor Sales hold 17.5% for standardized vacuum bags.
- Multi-month shelf-life validation and custom seal-jaw calibration keep Direct Supply at 58.0% of 2026 sales channel revenue.
- In October 2026, Amcor entered a joint technical collaboration with Australian pet-nutrition brands Sea Fairy and Petino to supply custom direct-printed high-barrier pouches.
What Are the Drivers, Restraints, and Opportunities in the Barrier Packaging Market?
Global food-loss reduction targets and pharmaceutical cold-form blister demand drive barrier packaging growth, while 50% U.S. aluminum foil tariffs and narrower heat-seal windows on mono-polyolefin webs restrain converter margins. Ultra-high-barrier functional papers and transparent AlOx/SiOx coatings unlock high-margin substitution opportunities through 2036.
- Driver: Retail food-spoilage reduction initiatives and high-moisture biological drug formulations compel packers to upgrade oxygen and water-vapor barrier specifications.
- Restraint: Elevated tariffs on imported aluminum foil and narrower sealing temperature tolerances on mono-material PE/EVOH webs increase line scrap and unit costs.
- Opportunity: Replacing unrecyclable foil laminates with PVDC-free dispersion-coated barrier papers and transparent SiOx/AlOx films captures EPR fee discounts across Europe and North America.
Supply-Chain Food Spoilage Reduction and Cold-Chain Shelf-Life Extension
Reducing perishable food waste across long-distance grocery supply chains and protecting moisture-sensitive pharmaceuticals serve as the foundational growth drivers for barrier packaging. In July 2025, the Food and Agriculture Organization and UN Sustainable Development Goal 12 progress tracking highlighted that 13.2% of global food production is lost between harvest and retail markets, alongside 19% wasted at retail and household levels. Switching fresh beef and poultry from PVC overwrap to EVOH modified atmosphere packaging and vacuum skin trays more than triples retail display life, cutting supermarket markdown losses by 30% to 50%.
Aluminum Foil Tariff Escalation and Mono-Material Heat-Seal Friction
Raw material tariff shocks and technical trade-offs during mono-material film conversion restrain converter profitability. In June 2025, a U.S. Presidential Proclamation published in the Federal Register raised Section 232 tariffs on imported aluminum articles and derivative foil products from 25% to 50%, sharply increasing landed costs for converter plants laminating ultra-thin 6-to-9-micron barrier aluminum foil. At the same time, European Union PPWR rules require all packaging placed on the EU market by 2030 to be recyclable at scale. However, replacing forgiving PET/foil/PE structures with all-polyethylene (MDO-PE/PE) barrier webs narrows the heat-seal temperature window on form-fill-seal machines, requiring costly retrofits of constant-heat sealing bars.
Ultra-High-Barrier Functional Papers and Recycle-Ready Pharma Blisters
Commercializing fiber-based barrier papers that run on existing horizontal and vertical form-fill-seal lines, alongside PVC-free and aluminum-free pharmaceutical blisters, represents a major revenue opportunity through 2036. By applying multi-stage aqueous dispersion coatings and ultra-thin vacuum metallization onto high-density kraft paper, converters achieve oxygen transmission rates below 0.5 cc/m²/day while passing standard paper-mill repulping tests. In October 2025, Amcor showcased its expanded recycle-ready pharmaceutical blister and sachet portfolio at CPHI Frankfurt, enabling European drugmakers to replace traditional PVDC-coated PVC and cold-form foil with mono-polyolefin pharmaceutical packaging. Parallel gains in flexible barrier packaging and bopp films alongside retort pouches reinforce this shift.
Barrier Packaging Market by Country (2026 to 2036)
Expansion across the eight profiled countries reflects cold-chain grocery buildouts and statutory eco-modulated EPR fee schedules. China leads global growth at a 7.6% CAGR from 2026 to 2036 as e-commerce fresh-food delivery and domestic pharmaceutical blister lines scale, followed closely by India at 7.3% and the United States at 6.9%. Chilled beef and fruit export demand lifts South Africa to a 6.5% CAGR while Germany (6.2%) and the United Kingdom (6.0%) join Chile (5.8%) and France (5.4%) in advancing recycle-ready mono-polyolefin and functional barrier paper conversions.
Table 7: Barrier Packaging Market CAGR by Country (2026 to 2036)
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 7.6% | 15.9 trillion yuan online retail parcel volume, fresh-food cold-chain pouches, and domestic EVOH/BOPP lines |
| India | 7.3% | PMKSY food processing parks, small-format moisture-barrier FMCG sachets, and generic pharma blisters |
| USA | 6.9% | Midwest vacuum skin meatpacking, wet pet-food pouches, and Section 232 foil-tariff substitution |
| South Africa | 6.5% | Formal supermarket chilled meat expansion, load-shedding spoilage protection, and citrus export liners |
| Germany | 6.2% | ZSVR minimum-standard recyclability grading driving MDO-PE/EVOH and FunctionalBarrier Paper adoption |
| UK | 6.0% | GBP 228.82/tonne Plastic Packaging Tax (Apr 2026) and high per-capita chilled ready-meal MAP trays |
| Chile | 5.8% | Trans-Pacific salmon vacuum skin films, cherry modified-atmosphere liners, and wine bag-in-box webs |
| France | 5.4% | Citeo eco-modulated EPR penalties on aluminum/PVC laminates and pharmacy blister modernization |
Source: Future Market Insights analysis
China Barrier Packaging Market Outlook (2026 to 2036)
High-frequency fresh grocery delivery and domestic generic pharmaceutical manufacturing make China the fastest-expanding national market for co-extruded barrier films and cold-form blister foils. According to China's National Bureau of Statistics in February 2026 national online retail sales of physical goods reached CNY 13092.3 billion in 2025, propelling demand for puncture-resistant vacuum meat pouches and nitrogen-flushed snack bags. Chinese barrier web consumption will climb at a leading 7.6% CAGR through 2036 across Jiangsu and Guangdong converting clusters. Yet commercial margins face pressure from domestic BOPP and BOPET film overcapacity, compelling top Chinese converters to shift toward ultra-thin AlOx-coated and 9-layer EVOH co-extruded webs for cold-chain meat processors and regional pharmaceutical blister packers.
Key takeaway: In China, rapid e-commerce fresh-food delivery and domestic EVOH film localization sustain a leading 7.6% CAGR through 2036.
India Barrier Packaging Market Outlook (2026 to 2036)
Extreme monsoon humidity combined with rural single-serve sachet pricing models makes moisture-and-oxygen barrier lamination essential for Indian culinary spices and oral solid pharmaceutical tablets. India's Ministry of Food Processing Industries reported in April 2026 that 1600+ sanctioned cold-chain and preservation projects under PMKSY have expanded packaged food output nationwide. Indian barrier film and blister foil sales are projected to advance at a 7.3% CAGR from 2026 to 2036. However, India's Plastic Waste Management rules restricting non-recyclable multi-layered plastic sachets force domestic converters like UFlex and Jindal Poly Films to re-engineer metallized polyester wrappers into recyclable mono-polyolefin structures and solvent-free adhesive laminations across regional converting plants in Gujarat and Maharashtra.
Key takeaway: In India, monsoon moisture protection for rural FMCG packs and pharmaceutical blister exports drive a 7.3% CAGR toward recyclable barrier laminates.
USA Barrier Packaging Market Outlook (2026 to 2036)
Centralized Midwest meatpacking plants and national pet-nutrition brands make the United States the largest revenue market for multi-layer EVOH vacuum shrink bags and reclosable stand-up pouches across supermarket chains. According to the USDA Economic Research Service in June 2026 total U.S. food expenditure reached USD 2.51 trillion in 2025, underpinning high-volume supermarket turnover of case-ready proteins and shelf-stable meals. United States barrier packaging demand is estimated to expand at a 6.9% CAGR through 2036. Nonetheless, the June 2025 U.S. Section 232 tariff hike to 50% on imported aluminum foil has raised costs for foil-laminated pouches, accelerating CPG qualification of foil-free MDO-PE and SiOx-coated webs.
Key takeaway: In the USA, case-ready meat vacuum-skin packaging and tariff-driven substitution of aluminum foil laminates anchor a 6.9% CAGR.
South Africa Barrier Packaging Market Outlook (2026 to 2036)
Long ambient trucking distances across Southern Africa and periodic municipal power fluctuations make passive oxygen and moisture barrier films critical for protecting South African chilled beef and dairy products. The USDA Foreign Agricultural Service Pretoria office reported in October 2026 that South Africa's formal retail food sector expanded to over USD 42 billion as supermarket chains added regional distribution centers. South African barrier film and pouch turnover is expected to progress at a 6.5% CAGR between 2026 and 2036. The central commercial obstacle involves reliance on imported specialty EVOH and ionomer resins, exposing local converters in Johannesburg and Cape Town to rand exchange-rate volatility during multi-year supermarket supply contracts.
Key takeaway: In South Africa, supermarket cold-chain protection and counter-seasonal citrus and beef exports sustain a 6.5% CAGR for vacuum and MAP barrier films.
Germany Barrier Packaging Market Outlook (2026 to 2036)
Rigorous recyclability auditing by Germany's Central Agency Packaging Register (ZSVR) and dual-system EPR operators has made Germany the primary European proving ground for mono-polyolefin EVOH films and dispersion-coated barrier papers. Eurostat packaging waste datasets in October 2025 confirmed Germany's position as Europe's largest packaging consumer, accelerating converter investment ahead of EU PPWR 2030 recyclability thresholds. German barrier packaging revenue is projected to record a 6.2% CAGR over the 2026 to 2036 period. Discount supermarket groups including Aldi and Lidl penalize unrecyclable composite laminates, though slower form-fill-seal line speeds on thicker barrier paper webs still challenge continental food co-packers and private-label coffee roasters operating high-speed horizontal packaging lines.
Key takeaway: In Germany, ZSVR minimum-recyclability standards and discounter private-label mandates steer chilled meat and roasted coffee packers toward mono-PE and paper barriers.
UK Barrier Packaging Market Outlook (2026 to 2036)
Europe's highest per-capita consumption of chilled prepared meals and store-brand vacuum-packed meats shapes a British barrier packaging market heavily weighted toward modified-atmosphere lidding films and thermoformed barrier trays. Official UK DEFRA waste statistics published in July 2025 documented a 64.8% national packaging recovery rate as Extended Producer Responsibility fees and the GBP 228.82-per-tonne Plastic Packaging Tax reshaped converter specifications. British barrier web sales are forecast to rise at a 6.0% CAGR through 2036. While supermarkets aggressively replace rigid trays with flexible vacuum skin films to cut plastic weight, strict food-contact safety rules limit mechanical PCR content in direct food-contact sealing layers across British supermarket meat and chilled ready-meal processors.
Key takeaway: In the UK, high chilled ready-meal consumption and the GBP 228.82/tonne Plastic Packaging Tax accelerate adoption of downgauged vacuum skin and mono-PE webs.
Chile Barrier Packaging Market Outlook (2026 to 2036)
Export-led aquaculture and horticulture define Chile's barrier packaging landscape as Atlantic salmon fillets and fresh cherries require 30-to-45-day controlled-atmosphere ocean transit to Northern Hemisphere ports. The USDA Foreign Agricultural Service Exporter Guide for Chile in July 2025 highlighted the nation's USD 21+ billion agricultural and seafood export engine, which depends on modified-atmosphere carton liners and deep-draw vacuum skin films. Chilean demand for high-barrier webs is predicted to advance at a 5.8% CAGR through 2036. However, strict recyclability rules under Chile's REP Extended Producer Responsibility law penalize multi-material foil pouches across domestic retail grocery channels and encourage Chilean exporters to qualify recyclable mono-PE vacuum webs.
Key takeaway: In Chile, trans-Pacific salmon vacuum skin packaging and cherry modified-atmosphere liners anchor a 5.8% CAGR through 2036.
France Barrier Packaging Market Outlook (2026 to 2036)
Eco-modulated Extended Producer Responsibility fees administered by Citeo under France's AGEC law impose steep financial malus penalties on packaging containing aluminum foil layers or chlorinated PVDC and PVC webs. Eurostat reported in October 2025 that France generated 7.5 million tonnes of packaging waste while accelerating plastic format reduction toward EU circularity targets. French barrier packaging revenues are anticipated to grow at a 5.4% CAGR from 2026 to 2036. While French dairy and pharmaceutical plants provide a large recurring demand base, national packaging reduction mandates restrain raw tonnage growth and shift converter revenue toward recycle-ready mono-polypropylene and dispersion-coated paper webs across national retail grocery chains.
Key takeaway: In France, Citeo malus penalties on aluminum and PVDC laminates drive culinary dairy and pharmaceutical packers toward mono-polyolefin and fiber barriers.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who Are the Notable Companies in the Barrier Packaging Market?
Leading global suppliers include Amcor plc, Sealed Air Corporation, Mondi plc, Sonoco Products Company, Huhtamäki Oyj, and ProAmpac LLC. Competitors differentiate through 9- to 11-layer EVOH co-extrusion, AlOx/SiOx vacuum deposition, and PVDC-free functional barrier papers.
Supplier selection in barrier packaging centers on a converter's ability to match the oxygen and moisture holdout of legacy foil laminates using recycle-ready mono-polyolefin or fiber-based structures. Amcor plc (reinforced by its 2025 combination with Berry Global) and Sealed Air Corporation lead global high-barrier polymer webs and pharmaceutical blister laminates. Mondi plc and Huhtamäki Oyj spearhead paper-based functional barriers and foil-free pouches while ProAmpac LLC and Sonoco Products Company alongside Constantia Flexibles scale regional rotogravure converting.
- Global Multi-Technology Barrier Film & Blister Leaders: Amcor plc (including Berry Global), Sealed Air Corporation (Cryovac), and Constantia Flexibles Group GmbH operate global co-extrusion, AlOx/SiOx coating, and cold-form pharmaceutical blister networks.
- Fiber-Based Functional Barrier & Flexible Pouch Pioneers: Mondi plc, Huhtamäki Oyj, ProAmpac LLC, and Sonoco Products Company lead in dispersion-coated high-barrier kraft papers, foil-free retort pouches, and recyclable snacks/coffee laminates.
- Specialty Barrier Resin & Regional Converting Powerhouses: Kuraray Co., Ltd. (EVAL EVOH resin), Mitsubishi Chemical Group (Soarnol EVOH), UFlex Limited, Jindal Poly Films, Winpak Ltd., and Coveris Management GmbH supply core barrier polymers and regional thermoforming webs.
Competitive Benchmarking: Barrier Packaging Market
Table 8: Competitive Benchmarking of Key Players in the Barrier Packaging Market (2026)
| Company | Material & Format Portfolio | OTR / WVTR Engineering Tech | Recycle-Ready Mono-Material Share | Global Converting Footprint |
|---|---|---|---|---|
| Amcor plc (incl. Berry Global) | High (AmPrima mono-PE/PP, AmFiber paper, AmSky pharma blisters) | High (SiOx/AlOx Ceramis, EVOH co-extrusion, cold-form foil) | High (Recycle-ready alternatives across 90%+ of flexible portfolio) | High (400+ sites across North America, Europe, APAC, LATAM) |
| Sealed Air Corporation (SEE) | High (Cryovac vacuum skin films, shrink bags, barrier tray lidding) | High (Multi-layer oxygen/moisture barrier meat & cheese webs) | High (Recycle-ready mono-PE shrink bags & rPET barrier trays) | High (100+ manufacturing facilities serving 115 countries) |
| Mondi plc | High (FunctionalBarrier Paper Ultimate, MonoFormable PP, pouches) | High (Integrated kraft paper mill + aqueous/extrusion barrier coating) | High (85%+ of packaging portfolio reusable, recyclable, or compostable) | High (100+ production sites across Europe, North America & APAC) |
| Huhtamäki Oyj | High (blueloop mono-PE, mono-PP, and high-barrier paper flexibles) | High (Foil-free metallized PP and dispersion-coated fiber webs) | High (95%+ of new flexible developments designed for recyclability) | High (100+ operating locations across 37 countries) |
| Sonoco Products Company | High (Flexible barrier pouches, rigid paper cans, thermoformed trays) | Medium-High (Reclosable barrier snack packs & retortable laminations) | High (GREENCAN recyclable paperboard barrier cans & mono-PE webs) | High (300+ operations across 33 countries globally) |
| ProAmpac LLC | High (ProActive Recyclable RP-2000 fiber & ProActive mono-PE pouches) | High (High-barrier fiber coatings & foil-replacement retort films) | High (Rapid expansion of curbside-recyclable paper & PE platforms) | Medium-High (50+ manufacturing sites in North America & Europe) |
Evaluation framework: Benchmark ratings reflect each converter's substrate diversity and documented OTR and WVTR permeation performance below 0.5 cc/m²/day alongside RecyClass mono-material certifications and multi-region plant reach.
Key Developments in the Barrier Packaging Market (2025 to 2026)
- In September 2026, Sealed Air Corporation introduced CRYOVAC Brand ZeroPrep high-barrier foodservice pouch packaging engineered to reduce back-of-house kitchen prep waste and extend ambient and chilled ingredient shelf life.
- In April 2026, Mondi partnered with multiple packaging machinery OEMs ahead of Interpack 2026 to validate high-speed horizontal and vertical form-fill-seal runnability for its recyclable FunctionalBarrier Paper and mono-polyolefin webs.
- In November 2025, Amcor launched its Amcor Lift-Off Winter 2025/26 Challenge to co-develop next-generation bio-based and ultra-thin oxygen/moisture barrier coatings for flexible paper and polymer packaging.
Key Players in the Barrier Packaging Market
Tier 1: Global Integrated Flexible & Rigid Barrier Packaging Leaders
- Amcor plc (including Berry Global Group)
- Sealed Air Corporation (SEE / Cryovac)
- Mondi plc
- Sonoco Products Company
- Huhtamäki Oyj
- Constantia Flexibles Group GmbH
Tier 2: High-Barrier Pouch, Blister & Specialty Film Converters
- ProAmpac LLC
- Winpak Ltd.
- Coveris Management GmbH
- UFlex Limited
- Jindal Poly Films Limited
- Klöckner Pentaplast Group (kp)
Tier 3: Barrier Polymer Resin & Coating Technology Specialists
- Kuraray Co., Ltd. (EVAL EVOH Division)
- Mitsubishi Chemical Group (Soarnol EVOH)
- Toppan Inc. (GL Barrier Film)
- Cosmo First Limited
- Bischof + Klein SE & Co. KG
- Schur Flexibles / Südpack Verpackungen SE & Co. KG
Barrier Packaging Market - Report Scope
Table 9: Report Scope and Market Definition for the Barrier Packaging Market
| Coverage field | Report scope |
|---|---|
| Market Definition | Flexible and semi-rigid packaging materials, containers, and laminations engineered with specialized functional layers (such as EVOH, PVDC, aluminum foil, vacuum-deposited AlOx/SiOx, or aqueous dispersion coatings) to restrict the permeation of oxygen, water vapor, UV light, aromas, and oils. Category Scope Note: Market valuation captures converted barrier films, pouches, bags, blister webs, lidding/thermoforming trays, and coated barrier papers sold to food, beverage, pharmaceutical, personal care, and industrial packers; bulk commodity non-barrier polyethylene shrink wraps and corrugated shipping cartons are excluded. |
| Base Year & Forecast Period | Base Year: 2025 | Estimated Year: 2026 | Forecast Period: 2026 to 2036 |
| Historical Data Horizon | 2020 to 2025 |
| Quantitative Units | Revenue in USD billion; converted substrate volume in million metric tons; growth in CAGR (%) |
| Segmentation Axes Covered | Material Type (5), Application (5), Packaging Format (5), Barrier Type (3), Sales Channel (3), Region (7) & 8 Key Countries |
Barrier Packaging Market - Research Methodology
Table 10: Research Methodology and Analytical Framework for the Barrier Packaging Market
| Method | Approach |
|---|---|
| Primary Research Validation | In-depth interviews with 45 multi-layer film extrusion directors, barrier coating R&D managers, meat and coffee packaging specification engineers, and pharmaceutical blister procurement heads across North America, Europe, Asia-Pacific, and Latin America. |
| Bottom-Up Market Sizing & Triangulation | Global market value is derived bottom-up by modeling converted barrier substrate tonnage (20.9 million MT in 2026) across polymer films, barrier papers, aluminum foil laminates, and metallized/oxide-coated webs, multiplied by verified contract pricing per metric ton across High, Medium, and Low barrier tiers. |
| Country Forecasting Econometric Model | Country-level CAGRs (2026 to 2036) are calculated via a multivariable econometric model weighting packaged food, pet nutrition, and pharmaceutical output growth (40%), cold-chain and e-commerce grocery penetration (25%), statutory EPR / plastic tax / recyclability conversion premiums (20%), and aluminum foil tariff substitution dynamics (15%) relative to the 6.7% global baseline. |
| Operational Benchmark Traceability | Permeation and structural metrics in Tables 2, 3, and 4 (OTR < 0.1 to 1.0 cc/m²/day per ASTM D3985, WVTR < 0.05 to 1.0 g/m²/day per ASTM F1249, < 5% EVOH weight thresholds for RecyClass/APR compliance, and 35.8% to 68.0% recycle-ready conversion shares) are verified against FDA/FAO food loss studies, UK HMRC Plastic Packaging Tax guidance, and technical data sheets from Amcor, Mondi, Sealed Air, and Kuraray. |
Barrier Packaging Market by Segments
Barrier Packaging Market segmented by Material Type:
- Plastic Films
- Paper & Paperboard
- Aluminum Foil
- Metallized Films
- Coated Materials
Barrier Packaging Market segmented by Application:
- Food & Beverage
- Pharmaceuticals
- Personal Care
- Industrial
- Others
Barrier Packaging Market segmented by Packaging Format:
- Pouches
- Bags
- Blisters
- Trays
- Wraps
Barrier Packaging Market segmented by Barrier Type:
- High Barrier
- Medium Barrier
- Low Barrier
Barrier Packaging Market segmented by Sales Channel:
- Direct Supply
- Contract Converting
- Distributor Sales
Barrier Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Poland
- Czechia
- Hungary
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Indonesia
- Australia & New Zealand
- Thailand
- Rest of South Asia and Pacific
- Middle East and Africa
- South Africa
- GCC Countries
- Turkey
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration (FDA). (2025, January 13). Food Loss and Waste. U.S. Food and Drug Administration.
- [2] HM Revenue & Customs (HMRC). (2026, February 12). Plastic Packaging Tax: steps to take. GOV.UK.
- [3] Amcor plc. (2026, March 09). Amcor Invests in Italy to Increase Recycle-Ready Packaging. Amcor plc.
- [4] Mondi plc. (2026, February 18). How Prymat improved spice preservation with Mondi's recyclable ultra-high barrier paper solution. Mondi Group.
- [5] ProAmpac LLC. (2026, February 17). ProAmpac Pushes the Limits of Fiber Packaging with New High Barrier Packaging Innovation Platform. ProAmpac.
- [6] Mondi plc. (2025, August 14). Mondi ramps up FunctionalBarrier Paper Ultimate to meet growing demand for sustainable high-barrier paper-based packaging. Mondi Group.
- [7] Amcor plc. (2026, October 13). Amcor, Sea Fairy and Petino pioneer collaborative model for pet nutrition packaging. Amcor plc.
- [8] Food and Agriculture Organization of the United Nations (FAO) & UN DESA. (2025, July 15). Goal 12: Ensure sustainable consumption and production patterns. United Nations Department of Economic and Social Affairs & FAO Codex.
- [9] Executive Office of the President of the United States. (2025, June 09). Adjusting Imports of Aluminum and Steel Into the United States. Federal Register (Proclamation 10947 of June 3, 2025).
- [10] Amcor plc. (2025, October 02). Amcor to showcase responsible and patient-centric packaging at CPHI Frankfurt 2025. Amcor plc.
- [11] National Bureau of Statistics of China (NBS). (2026, February 28). Statistical Communiqué of the People's Republic of China on the 2025 National Economic and Social Development. National Bureau of Statistics of China.
- [12] Press Information Bureau (PIB), Ministry of Food Processing Industries, Government of India. (2026, April 21). Strengthening India's Food Processing Ecosystem. Press Information Bureau (PIB) India.
- [13] U.S. Department of Agriculture, Economic Research Service (USDA ERS). (2026, June 01). Total food spending reached $2.51 trillion in 2025. USDA Economic Research Service.
- [14] U.S. Department of Agriculture, Foreign Agricultural Service (USDA FAS). (2026, October 02). South Africa: Retail Foods Annual. USDA Foreign Agricultural Service GAIN.
- [15] Eurostat. (2025, October 10). Packaging waste statistics. European Commission Eurostat Statistics Explained.
- [16] Department for Environment, Food & Rural Affairs (DEFRA). (2025, July 23). UK statistics on waste. GOV.UK Official Statistics.
- [17] U.S. Department of Agriculture, Foreign Agricultural Service (USDA FAS). (2025, July 03). Exporter Guide Annual: Santiago, Chile (Report CI2025-0013). USDA Foreign Agricultural Service GAIN.
- [18] Eurostat. (2025, October 10). Waste statistics. European Commission Eurostat Statistics Explained.
- [19] Sealed Air Corporation. (2026, September 22). CRYOVAC® Brand Food Packaging Introduces ZeroPrep. Sealed Air Corporation.
- [20] Mondi plc. (2026, April 23). Mondi brings sustainable packaging innovation to Interpack 2026 through multiple OEM collaborations. Mondi Group.
- [21] Amcor plc. (2025, November 18). Amcor Lift-Off to accelerate more sustainable packaging innovation with Winter 2025/26 challenge. Amcor plc.
- [22] Amcor plc. (2026, February 10). Combination with Berry provides best-in-industry PE shrink portfolio. Amcor plc.
- [23] Huhtamäki Oyj. (2026, January 12). Huhtamaki Solutions Recognised at the WorldStar Awards 2026. Huhtamaki.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the global barrier packaging market in 2025 and 2026, and what is the projected valuation by 2036?
- Why do Plastic Films command 47.0% of material demand while Paper & Paperboard emerges as the fastest-shifting circular alternative?
- How do converters keep EVOH layers below 5% of film weight to pass RecyClass and APR polyethylene recyclability standards?
- What impact does the June 2025 U.S. 50% Section 232 aluminum tariff have on foil-laminated pouch and blister economics?
- Why do China (7.6% CAGR), India (7.3% CAGR), and the USA (6.9% CAGR) lead global expansion through 2036?
- How are Amcor, Sealed Air, Mondi, Huhtamaki, Sonoco, and ProAmpac positioning their mono-material and fiber barrier platforms?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Plastic Films
- Paper & Paperboard
- Aluminum Foil
- Metallized Films
- Coated Materials
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Food & Beverage
- Pharmaceuticals
- Personal Care
- Industrial
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Pouches
- Bags
- Blisters
- Trays
- Wraps
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Type, 2026 to 2036
- High Barrier
- Medium Barrier
- Low Barrier
- Y-o-Y Growth Trend Analysis By Barrier Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct Supply
- Contract Converting
- Distributor Sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- BENELUX
- Rest of Western Europe
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czechia
- Hungary
- Rest of Eastern Europe
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Indonesia
- Australia & New Zealand
- Thailand
- Rest of South Asia and Pacific
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- GCC Countries
- Turkey
- Rest of Middle East and Africa
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Application
- By Packaging Format
- By Barrier Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc (incl. Berry Global)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sealed Air Corporation (SEE)
- Mondi plc
- Huhtamäki Oyj
- Sonoco Products Company
- ProAmpac LLC
- Amcor plc (including Berry Global Group)
- Sealed Air Corporation (SEE / Cryovac)
- Constantia Flexibles Group GmbH
- Winpak Ltd.
- Coveris Management GmbH
- UFlex Limited
- Jindal Poly Films Limited
- Klöckner Pentaplast Group (kp)
- Kuraray Co., Ltd. (EVAL EVOH Division)
- Mitsubishi Chemical Group (Soarnol EVOH)
- Toppan Inc. (GL Barrier Film)
- Cosmo First Limited
- Bischof + Klein SE & Co. KG
- Schur Flexibles / Südpack Verpackungen SE & Co. KG
- Amcor plc (incl. Berry Global)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Barrier Type, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packaging Format
- Figure 12: Global Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Barrier Type
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Material Type
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Packaging Format
- Figure 38: North America Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Barrier Type
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Material Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 54: Latin America Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Barrier Type
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Material Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Application
- Figure 67: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 70: Western Europe Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Barrier Type
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Material Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Application
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Barrier Type
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Material Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Application
- Figure 99: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 102: East Asia Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Barrier Type
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Material Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Barrier Type
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Material Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Barrier Type, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Barrier Type, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Barrier Type
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the global barrier packaging market in 2026 and 2036?
According to Future Market Insights, the global barrier packaging market is valued at USD 52.0 billion in 2026 (up from USD 48.8 billion in 2025) and is projected to reach USD 99.1 billion by 2036, expanding at a 6.7% CAGR.
Which material type leads the barrier packaging market?
Plastic Films hold the largest material share at 47.0% in 2026, underpinned by 7- to 11-layer co-extruded polyolefin and EVOH webs that combine oxygen/moisture protection with mechanical recyclability.
Which application segment consumes the most barrier packaging?
Food & Beverage accounts for 56.0% of total demand in 2026, driven by vacuum skin meat films, modified-atmosphere cheese and poultry trays, and aroma-barrier coffee and snack pouches.
Which country is projected to grow fastest in the barrier packaging market?
FMI projects China to record the fastest growth among evaluated countries at a 7.6% CAGR from 2026 to 2036, followed closely by India at 7.3% and the United States at 6.9%.
What defines High Barrier packaging performance?
High Barrier packaging (41.0% share in 2026) is defined by oxygen transmission rates (OTR) below 1.0 cc/m²/day and water vapor transmission rates (WVTR) below 1.0 g/m²/day, protecting oxygen- and moisture-sensitive foods and pharmaceuticals for 12 to 24 months.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
