

- Market Size (2026)
- USD 194.5 Mn
- Forecast (2036)
- USD 427.8 Mn
- CAGR (2026 to 2036)
- 8.2%
How big is the carob-based cocoa replacers market in 2026?
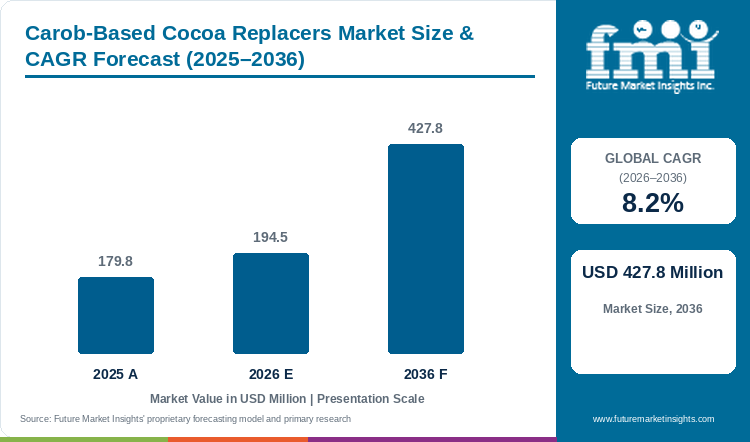
The market was valued at USD 179.8 million in 2025 and is expected to reach USD 194.5 million in 2026. It is projected to reach USD 427.8 million by 2036 at a CAGR of 8.2% from 2026 to 2036.
The carob-based cocoa replacers market was valued at USD 179.8 million in 2025 and is estimated at USD 194.5 million in 2026. At a forecast CAGR of 8.2%, the market would reach USD 427.8 million by 2036. Standard grade holds 42.0% of product type demand in 2026 because established bakery recipes need a consistent roast, color and particle specification. The International Cocoa Organization's August 2026 bulletin estimated world cocoa production 8.5% higher and grindings 3.3% lower in 2024/25, leaving a surplus of 37,000 tonnes.[1] That changing cocoa backdrop makes lasting carob demand a question of recipe performance as well as ingredient cost. Suppliers gain recurring orders when partial substitution works in cakes and breads and the approved preparation remains in use after cocoa supply conditions change. The supplier must also manage the roasted note, color and dose of carob so that a substitution improves the economics of an established product without altering its accepted character.
Key Market Trends & Insights
- By product type: Standard Grade represented 42.0% of 2026 product type demand. Standard grade holds the largest share because bakeries can build a recipe around an agreed roast and particle specification. Once a recipe is approved, a change in roast means development work starts again.
- By form: Powder / Dry accounted for 43.0% of 2026 form demand. Powder wins on handling. It goes straight into the weighing and mixing routines bakeries already run, so a trial doesn't need a separate liquid preparation.
- By application: Bread & Rolls held 29.0% of 2026 application demand. This is the top application, because carob's roasted note and colour suit a dough. It's also a test of dose, since every bread or roll recipe needs its own inclusion level.
Regional Highlights
- At 9.6% CAGR over 2026 to 2036, the UAE heads the carob-based cocoa replacer country outlook; wider use still depends on acceptable color and roasted flavor in established bakery products.
- Saudi Arabia is forecast at 9.3%, South Korea at 8.9% and the USA at 8.6%, compared with 7.4% in Japan, the slowest of the eight profiled countries.
Market Size & Forecast
Table 1: Carob-Based Cocoa Replacers Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value (actual) | USD 179.8 million |
| Estimated market size in 2026 | USD 194.5 million |
| Projected market size by 2036 | USD 427.8 million |
| CAGR (2026-2036) | 8.2% |
The practical opportunity depends on how carob performs in the finished recipe. CSM introduced Nuaré in November 2025 for bakery and ice-cream formulations, and Döhler presented a system combining carob powder, barley malt and colouring concentrates in December 2025.[2][3] Both place part of the work of balancing flavour, colour and texture inside the ingredient, although a launch alone cannot show that customers will keep the product in production. The National University of Singapore reported enzyme-based methods to improve the aroma and taste of roasted carob pulp in December 2025,[4] which indicates that flavour remains an active development issue. Substitution level also requires attention because it determines how much replacer each batch consumes. Consequently, actual demand will depend on whether a finished product retains acceptable taste, texture and cost as cocoa conditions change.
The market is segmented by Product Type, Form, Application, Claim, Sales Channel and Region. The forecast period runs from 2026 to 2036.
Carob competes within a changing cocoa ingredients environment. ICCO’s August 2026 bulletin estimated 2024/25 gross production at 4,733,000 tonnes and grindings at 4,649,000 tonnes.[1] A better crop balance can reduce the urgency behind substitution, leaving the replacement recipe to justify its continuing use on taste and cost. Manufacturers can also respond to expensive cocoa by changing portion size or product mix, so an alternative ingredient has to compete with more than the original cocoa powder. A carob formulation retained after the immediate purchasing pressure eases gives its supplier a more dependable position than one ordered only during a shortage.
Recent supplier launches address several parts of that recipe decision. CSM introduced Nuaré in November 2025 for bakery and ice-cream formulations.[2] Döhler’s December 2025 system combines carob, barley malt and colouring concentrates.[3] These formulations offer customers a different proposition from plain powder: part of the work of balancing flavour, colour and texture has already been brought into the ingredient system. The customer still has to establish the result in the intended application. A cake and a chilled filling can require different adjustments, so a successful replacement in one product does not automatically open the whole account to the supplier.
Sensory differences set a practical limit on those opportunities. The National University of Singapore reported enzyme-based methods to improve the aroma and taste of roasted carob pulp in December 2025.[4] The work points to a route for further ingredient development, while current purchasing still depends on the flavour acceptable in a finished recipe. Partial replacement preserves some cocoa character and produces a smaller replacer order per batch. A product developed around carob’s own roasted notes permits a different formulation. These routes can coexist within one supplier portfolio, but they carry different customer expectations and different amounts of carob-containing ingredient into production.
Table 2: Supporting Industry Indicators for the Carob-Based Cocoa Replacers Market, 2025 to 2026 and current product specifications
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Cocoa production | ICCO estimated 2024/25 gross production at 4,733,000 tonnes, up 8.5%. | Improved supply can alter the financial incentive to substitute. | [1] |
| Cocoa processing demand | World grindings were estimated at 4,649,000 tonnes, down 3.3%. | Lower processing demand changes the commercial pressure to reformulate. | [1] |
| Cocoa balance | The 2024/25 supply surplus was estimated at 37,000 tonnes. | Replacement decisions take place in a changing supply environment. | [1] |
| Formulated carob alternative | CSM introduced Nuaré in November 2025. | Application-specific blends widen the alternatives available to manufacturers. | [2] |
| Multi-ingredient system | Döhler combines carob, barley malt and colouring concentrates. | The offer addresses flavour, colour and functional requirements together. | [3] |
| Flavour research | NUS reported enzyme-based carob-flavour research in December 2025. | Sensory differences remain an active technical development issue. | [4] |
Demand Intensity Analysis
The carob-based cocoa replacers market is forecast to generate an additional USD 233.3 million in annual revenue between 2026 and 2036. Part of this growth can come from changes to ingredient use within finished foods. Replacing part of the cocoa in an existing cake creates a replacer sale even if the number of cakes remains unchanged. ICCO’s estimate of lower cocoa grindings alongside higher production shows the wider market moving in a different direction.[1] Carob suppliers can still gain business within that setting, but the opportunity depends on retaining recipes through changes in cocoa availability and price. A temporary cost advantage may secure a trial without sustaining the resulting order.
The choice between plain powder and a formulated system influences how much spending suppliers can capture. A powder leaves the balancing of flavour, colour and texture with the customer, while a system such as Döhler’s brings part of that work into the ingredient.[3] New systems and flavour research widen the range of applications in which carob could be accepted, but the revenue base grows only as those applications enter commercial production.[2][3][4] These distinctions matter when assessing the market’s projected 8.2% CAGR. Manufacturers can also respond to expensive cocoa by changing portion size or product mix, so the forecast requires gains beyond temporary cost pressure. Retained carob formulations offer one possible route, particularly where acceptable taste and cost hold across repeated production runs.
Powder / dry represents USD 83.6 million in 2026. The amount purchased per batch varies with the substitution level and with the composition of the replacement system. A partial-replacement recipe consumes less replacer than a full-replacement recipe at the same finished-food volume. Formulated systems such as Döhler’s also contain ingredients beyond carob.[3] Those differences matter to suppliers planning raw-material purchases and production capacity. The relevant sales unit is the qualified preparation that the customer orders, while the quantity of agricultural carob required follows the composition of that preparation.
Direct industrial-bakery supply accounts for USD 95.3 million in 2026. An industrial recipe can support substantial recurring orders once the ingredient has passed production and sensory review. The difficulty is preserving that position when the original cocoa recipe becomes less expensive again. A replacer that also meets a continuing sourcing or formulation need has a stronger case for retention. Supplier consistency matters here because a change in roast or blend composition can reopen development work. The cost of that disruption can outweigh a modest saving on the ingredient itself. Long-term sales are ultimately determined by how much finished product the bakery makes with the carob recipe, how often it runs that recipe and the share of cocoa replaced in each batch.
Table 3: Demand Intensity Metrics for the Carob-Based Cocoa Replacers Market, 2026 to 2036 with relevant industry comparisons
| Demand intensity metric | Value | Basis |
|---|---|---|
| Carob-based replacers value CAGR | 8.2% | Global value forecast, 2026 to 2036. |
| Cocoa production change | +8.5% | ICCO 2024/25 estimate; upstream commodity, August 2026 bulletin.[1] |
| Cocoa grindings change | −3.3% | ICCO 2024/25 estimate; processing activity, not replacer sales.[1] |
| Standard grade revenue, 2026 | USD 81.7 million | Product Type category; 42.0% of the market. |
| Powder / dry revenue, 2026 | USD 83.6 million | Form category; 43.0% of the market. |
| Direct industrial-bakery revenue, 2026 | USD 95.3 million | Sales Channel category. |
| Added revenue through 2036 | USD 233.3 million | Change in forecast market value between 2026 and 2036. |
Analyst Perspective
Carob earns a durable place when the replacement recipe survives an improvement in cocoa supply. Suppliers that hold a dependable roast profile and an accepted finished flavour keep that position, while a saving that disappears with the next cocoa quotation leaves demand exposed.
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the carob-based cocoa replacers market segmented?
The carob-based cocoa replacers market is segmented by Product Type (Standard grade, Premium / specialty grade, Organic certified, Clean label grade), Form (Powder / dry, Liquid, Paste / semi-solid, Granules / pieces), Application (Bread & rolls, Cakes & muffins, Biscuits & cookies, Viennoiserie & pastry, Other bakery & snacks), Claim (Conventional, Clean label, Organic, Non-GMO / identity preserved), and Sales Channel (Direct to industrial bakeries, Ingredient distributors, Foodservice & artisan supply, Online B2B). Regionally, the market is segmented into North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Standard grade retain the largest Product Type position?
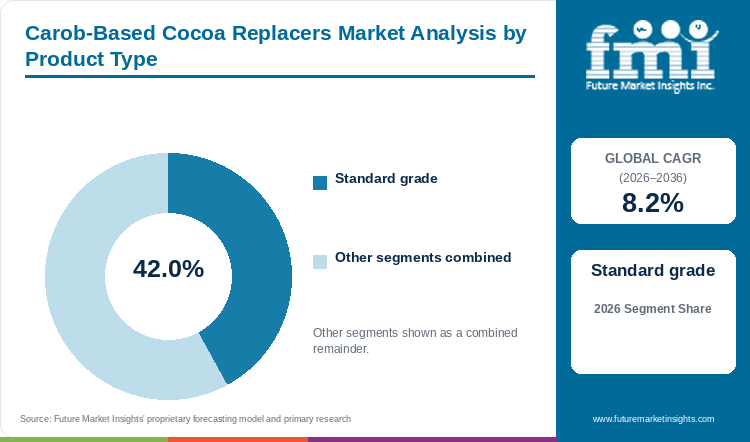
Standard grade leads with 42.0% of Product Type revenue in 2026.
An agreed roast and particle specification allows customers to work from a consistent ingredient when balancing colour and sweetness. This is commercially valuable in recurring recipes because a material change can force new development work. More specialised grades add different sourcing or sensory requirements, with their value depending on the intended finished product.
- Standard grade accounts for 42.0% of Product Type revenue in 2026.
- Later deliveries need to match the approved roast and particle specification.
What gives Powder / dry the operational advantage among forms?
Powder / dry holds 43.0% of Form revenue in 2026.
Powder can enter weighing and mixing routines already used for bakery mixes, giving customers a route to trial without introducing a separate liquid preparation. Its effect on water balance and crumb still influences the finished recipe. The format reduces some handling changes while leaving application development as a material part of the sale.
- Powder / dry holds 43.0% of Form revenue in 2026.
- Dry handling and the effect on recipe water need to be checked together.
How do Bread & rolls lead Application despite carob’s confectionery associations?
Bread & rolls represent 29.0% of Application revenue in 2026.
In suitable recipes, carob supplies a roasted note or colour at a dose suited to the dough. The market opportunity differs from applications built around a strong cocoa identity, where sensory limits can restrict replacement. Each additional recipe adopted by a bakery changes the volume available to its carob supplier.
- Bread & rolls represent 29.0% of Application revenue in 2026.
- Inclusion levels need to be established for each bread or roll recipe.
Why does Conventional lead the Claim segmentation?
Conventional leads Claim with 56.0% of revenue in 2026.
Formulated replacements can contain several components, as Döhler’s carob, malt and colouring system illustrates.[3] A sourcing or composition claim therefore depends on the blend as a whole. Additional claim restrictions can narrow formulation choices and affect the cost of meeting the customer’s sensory requirements.
- Conventional leads Claim at 56.0% of revenue in 2026.
- A blended replacement carries the claims and declarations of its actual ingredients.
Why do industrial bakery contracts dominate the Sales Channel mix?
Direct to industrial bakeries holds 49.0% of Sales Channel revenue in 2026.
Direct relationships bring ingredient development into the purchasing agreement, which matters when a replacement changes several parts of a recipe. The supplier’s position strengthens as the formulation becomes established across regular production. Distributors serve a different need by combining ingredient availability and smaller order quantities after the product specification is settled.
- Direct to industrial bakeries accounts for 49.0% of Sales Channel revenue in 2026.
- Recipe changes and supply specifications need to stay aligned between supplier and bakery.
What are the drivers, restraints and opportunities in the carob-based cocoa replacers market?
Cocoa purchasing uncertainty encourages qualified alternatives
A retained alternative recipe gives a bakery more choice when it negotiates cocoa supply. ICCO’s August 2026 figures show that crop output and processing demand can change substantially from one season to the next.[1] Completing the formulation work before a purchasing disruption gives the customer a usable option. The resulting carob business is more durable when that option continues to offer acceptable taste and cost after the immediate pressure passes.
Sensory and recipe differences limit straightforward substitution
The limit on substitution is often the finished product. A familiar cocoa recipe may allow only a small change in sweetness, roast character or colour, restricting the amount of carob used. NUS research into improved carob flavour addresses this technical problem.[4] For suppliers, closer sensory performance could broaden applications, while current revenue depends on the replacement levels that customers can already retain in production.
Application-specific systems can reach beyond plain carob powder
Döhler’s December 2025 system combines carob powder, barley malt and colouring concentrates, reducing the number of separate changes left to the developer.[3] That opens a commercial route beyond plain powder. Application boundaries still matter: a confectionery coating has to set and feel acceptable as well as provide colour. A blend sold around a defined use can make the development offer more precise and reduce unsuccessful trials.
Which country CAGRs are profiled in the carob-based cocoa replacers market?
Table 4: Country growth outlook for the carob-based cocoa replacers market
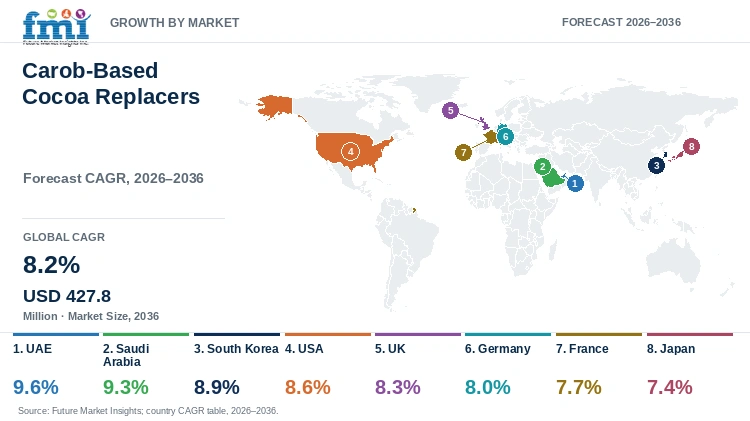
| Country | CAGR, 2026 to 2036 |
|---|---|
| UAE | 9.6% |
| Saudi Arabia | 9.3% |
| South Korea | 8.9% |
| USA | 8.6% |
| UK | 8.3% |
| Germany | 8.0% |
| France | 7.7% |
| Japan | 7.4% |
UAE
The UAE is forecast to record the highest growth among the profiled countries, at 9.6% CAGR between 2026 and 2036. Dubai’s Department of Economy and Tourism reported 19.59 million international overnight visitors in 2025, up from 18.72 million in 2024, widening the customer base for hotel pastry kitchens. Visitor numbers show the size of the hospitality market, not which dessert recipes stay on a menu. Carob can replace part of the cocoa in these recipes or anchor products built around its own roasted character. The two uses generate different orders per batch, since a partial replacement consumes less replacer than a full one. Growth will depend on how many hospitality recipes become permanent menu items and on the replacement level each retains.
Saudi Arabia
Saudi Arabia is forecast to expand at 9.3% CAGR through 2036, above the global rate of 8.2%. The Ministry of Tourism reported about 122 million domestic and international visits in 2025, 5.0% above the previous year in preliminary estimates. A larger visitor base supports bakery chains and hotel kitchens without showing which recipes stay in production. A carob recipe that stays available through changes in cocoa purchasing conditions gives such operators a dependable alternative to cocoa-only formulations. The limitation is that a change in roast or blend composition can force a kitchen to repeat the original formulation work. Demand will therefore depend on how many operators keep an approved carob recipe in regular production and whether the supplier holds its specified composition.
South Korea
South Korea is projected to expand at 8.9% CAGR, above the global forecast of 8.2%. The USDA Foreign Agricultural Service reported in its 2025 Retail Foods report that South Korean imports of chocolate and cocoa products grew 18.0% between 2023 and 2024. Growth in imported cocoa products can increase interest in alternatives, although it does not show that buyers will accept a different flavour. A new recipe gives developers more freedom to use carob’s own flavour than the reformulation of an established cocoa product. The two routes carry different sensory limits and consume different amounts of replacer in each finished batch. Sustained demand depends on how many newly developed products stay in regular production after the trial period.
USA
The USA is projected at 8.6% CAGR through 2036, slightly above the global average. The US Bureau of Labor Statistics reported that producer prices for chocolate and confectionery made from cacao rose 143.9% between December 2019 and November 2024, while imported cocoa prices rose 107.4%. Increases of that scale give industrial customers a reason to qualify an alternative but do not decide whether it stays in the recipe. Customers can buy plain powder for their own formulation work or a multi-function system, which gives the supplier a larger role in development. However, a cost advantage that fades as cocoa prices ease may not justify keeping a second specification in production. Continuing orders will depend on the preparation’s cost and performance in full production.
UK
The UK forecast is 8.3% CAGR, close to the global rate of 8.2%. The Office for National Statistics reported that the sugar, jam, syrups, chocolate and confectionery class made the largest upward contribution to the change in the annual food inflation rate in May 2025. In November 2025 the same class made a downward contribution, so price pressure shifts from month to month and weakens a purchasing case built only on cost. A replacement changes the economics of an existing recipe only if the cost benefit survives adjustments to dose, sweetness and texture. However, keeping both a cocoa recipe and an alternative leaves two specifications to maintain. Demand will depend on how many recipes retain their agreed character without adding substantial preparation work.
Germany
Germany’s forecast CAGR of 8.0% is slightly below the global average. Destatis reported that German production of cocoa-containing chocolate products fell 5.8% in 2024 to just under 1.07 million tonnes. Lower output of cocoa-based products indicates that carob replacer growth cannot rely on rising chocolate volumes and has to come from changes in recipes. Partial substitution can preserve a role for cocoa while creating recurring carob demand within the same recipe. The amount purchased is therefore sensitive to the accepted replacement level, not simply to the number of customers trialling an alternative ingredient. Demand will depend on the replacement level customers can maintain once a recipe enters regular production, and on how many recipes reach that stage.
France
France is forecast at 7.7% CAGR from 2026 to 2036, below the global rate of 8.2%. INSEE reported that consumer prices of cocoa-based products rose 22.0% between mid-2023 and May 2025. That increase gives manufacturers a cost reason to examine alternatives, but it does not widen the range of products in which a substitute is acceptable. Clear application limits can reduce development time and concentrate sales work on products where the alternative is commercially credible. However, products with a strong cocoa identity give a replacement supplier less room for sensory change than a newly developed carob recipe. Demand will depend on how many French recipes are developed around carob’s own character rather than adapted from cocoa.
Japan
Japan has the lowest forecast CAGR among the profiled countries at 7.4%. The Statistics Bureau of Japan’s retail price survey recorded Tokyo chocolate prices 30.2% higher in January 2025 than a year earlier, and a further 24.2% higher in January 2026. Price rises on that scale support interest in alternatives, although they say little about whether Japanese buyers will accept a different flavour. A consistent roast profile matters when a customer keeps an alternative recipe available between production runs. Material changes can force renewed development before that recipe can be used again, reducing the purchasing flexibility that the carob ingredient was intended to provide. Suppliers will generate sustained demand when the specified roast and blend remain constant across production runs, even if cocoa prices ease.
Who are the notable companies in the carob-based cocoa replacers market?
CSM Ingredients; Döhler; Foreverland; Colony Gums; American International Foods
The supplier field includes formulated alternatives and individual carob powders. CSM Ingredients and Döhler offer replacement systems, while Foreverland supplies alternatives through Choruba. Colony Gums and American International Foods supply powder for customer-developed recipes. These offers place different portions of the formulation work with the bakery.
The distinction affects how suppliers compete. A powder supplier competes on the ingredient and its continuity; a system developer also competes on the time needed to reach an acceptable finished product. Both depend on preserving the specified roast and handling properties after development, when the customer starts ordering for production.
Competitive Benchmarking: Carob-Based Cocoa Replacers Market
Table 5: Company capabilities in the carob-based cocoa replacers market
| Company | Relevant offer | Commercial capability |
|---|---|---|
| CSM Ingredients | Nuaré carob-based cocoa alternatives | Formulated systems for bakery and related applications |
| Döhler | Carob-containing cocoa powder replacement systems | Combines carob, malt and colour expertise |
| Foreverland | Choruba cocoa alternatives and powder | Carob-based ingredient formats for industrial applications |
| Colony Gums | Carob powder | Ingredient supply for food formulation |
| American International Foods | Carob powder supply | Industrial ingredient sourcing |
Key Developments in the Carob-Based Cocoa Replacers Market
- CSM Ingredients launched Nuaré in November 2025 for bakery and ice-cream formulations, adding a range of carob-based cocoa alternatives to the available ingredient choices.[2]
- Döhler presented a bakery replacement system in December 2025 that combines carob powder, barley malt and colouring concentrates. It addresses flavour and colour within the same blend.[3]
- The National University of Singapore described methods to improve roasted-carob-pulp flavour in December 2025. The research examines a sensory difficulty relevant to cocoa-alternative development.[4]
Key Players in the Carob-Based Cocoa Replacers Market
- CSM Ingredients
- Döhler
- Foreverland
- Colony Gums
- American International Foods
Carob-Based Cocoa Replacers Market - Report Scope
Table 6: Report scope for the carob-based cocoa replacers market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Form; Application; Claim; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Revenue from carob-based cocoa-replacement ingredients and formulated systems sold for the applications and sales channels covered. Excludes downstream finished-bakery revenue, conventional cocoa products, non-carob substitutes, standalone locust bean gum and carob products not marketed for cocoa replacement. For mixed solutions, only the carob replacement ingredient component is included, where it can be identified separately. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE; Saudi Arabia; South Korea; USA; UK; Germany; France; Japan |
| Key Companies Profiled | CSM Ingredients; Döhler; Foreverland; Colony Gums; American International Foods |
| Forecast Period | 2026 to 2036 |
| Approach | Market assessment supported by official technical and regulatory publications, company product information and country operating conditions. |
Carob-Based Cocoa Replacers Market - Research Methodology
Table 7: Research approach for the carob-based cocoa replacers market
| Method | Approach |
|---|---|
| Market coverage | Coverage follows carob-based cocoa-replacement ingredients and formulated systems, excluding conventional cocoa, non-carob substitutes and finished foods. |
| Secondary evidence | Government and technical publications are considered alongside first-party product information and dated corporate announcements. |
| Commercial analysis | Purchasing requirements, operating constraints, service needs and country-specific routes to market inform the interpretation of demand. |
| Forecast presentation | Global values, leading segment shares and country growth rates are stated for the 2026 to 2036 forecast period. |
Carob-Based Cocoa Replacers Market by Segments
Product Type
- Standard grade
- Premium / specialty grade
- Organic certified
- Clean label grade
Form
- Powder / dry
- Liquid
- Paste / semi-solid
- Granules / pieces
Application
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
Claim
- Conventional
- Clean label
- Organic
- Non-GMO / identity preserved
Sales Channel
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
Carob-Based Cocoa Replacers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Cocoa Organization. (2026, August 31). August 2026 quarterly bulletin of cocoa statistics.
- [2] CSM Ingredients. (2025, November 13). CSM Ingredients Group launches Nuaré, a range of cocoa alternatives.
- [3] Döhler. (2025, December). Döhler unveils all-in-one product solution for cocoa powder replacement.
- [4] National University of Singapore. (2025, December 8). NUS scientists enhance the flavour of carob-based chocolate alternatives with novel methods.
This Report Answers
- How large is the carob-based cocoa replacers market in 2026 and 2036?
- What cocoa procurement pressures support demand for carob substitutes?
- Why does Standard grade lead Product Type?
- What explains Powder / dry leadership in industrial bakery formulations?
- How do growth rates differ among the eight profiled countries?
- Which profiled companies provide direct or adjacent formulation capabilities?
Frequently Asked Questions
How big is the carob-based cocoa replacers market in 2026, and what is forecast for 2036?
It is valued at USD 194.5 Million in 2026 and is forecast to reach USD 427.8 Million by 2036.
What is the expected CAGR for the carob-based cocoa replacers market from 2026 to 2036?
The expected CAGR is 8.2% from 2026 to 2036.
Which Product Type leads the carob-based cocoa replacers market in 2026?
Standard grade leads with a 42.0% share in 2026. It supports routine purchasing where a stable roast profile and consistent handling take priority over specialised claims.
Which Form has the largest share of carob-based cocoa replacers in 2026?
Powder / dry leads with a 43.0% share in 2026. Dry blending compatibility helps existing bakery production lines trial the ingredient without a full wet-process redesign.
Which profiled countries have the highest carob-based cocoa replacers growth rates?
The UAE at 9.6% and Saudi Arabia at 9.3% have the highest profiled CAGRs over 2026 to 2036.
Which companies participate in the carob-based cocoa replacers market?
Relevant participants include CSM Ingredients, Döhler, Foreverland, Colony Gums and American International Foods.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Standard grade
- Premium / specialty grade
- Organic certified
- Clean label grade
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder / dry
- Liquid
- Paste / semi-solid
- Granules / pieces
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim, 2026 to 2036
- Conventional
- Clean label
- Organic
- Non-GMO / identity preserved
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- CSM Ingredients
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Döhler
- Foreverland
- Colony Gums
- American International Foods
- CSM Ingredients
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


