

- Market Size (2026)
- USD 52.2 Bn
- Forecast (2036)
- USD 83.5 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Coated Fabrics Market in 2026?
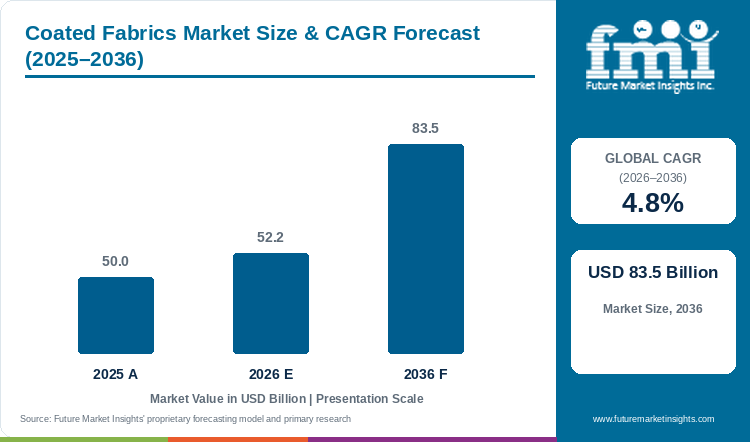
Coated fabrics advance on a 4.8% CAGR from 2026 to 2036. The 2025 base of USD 50.0 billion becomes an estimated USD 52.2 billion in 2026 and a projected USD 83.5 billion by 2036.
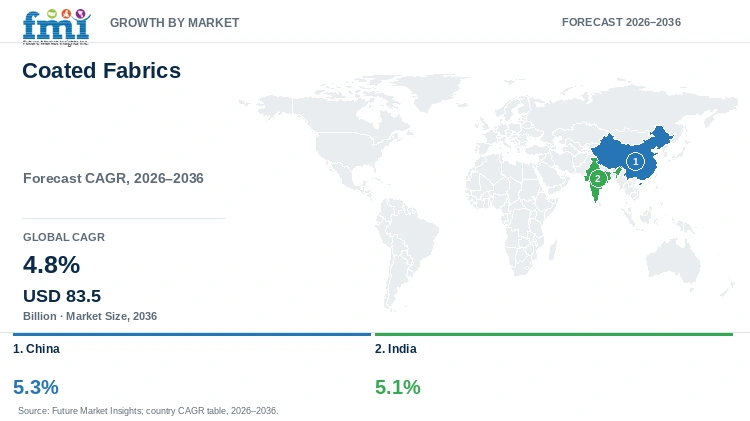
Demand for coated fabrics is moving toward China and India, with China set for a 5.3% CAGR to 2036 and India for 5.1%. Coated fabrics market size stood at USD 50.0 billion in 2025 and is estimated at USD 52.2 billion in 2026. Sales are projected to reach USD 83.5 billion by 2036 in the FMI study, a 4.8% CAGR from 2026 to 2036.
OICA reported in April 2026 that global vehicle output rose 3.9% to 96.4 million units in 2025.[1] Asia built about 59.2 million units, up 7.6%, and European output slipped 0.8% to 17.2 million.[1] Due to this, seat, airbag and trim fabric orders are shifting to coaters near Asian car plants. Following the flow of new investment into Asian car plants, coaters will add seat and airbag fabric lines in China and India first. Transportation already buys about 30% of 2026 sales.
Adoption of coated grades is rising in construction, transport and industrial jobs, and the technical textiles market is forecast at a 6.2% CAGR from 2026 to 2036. Protective clothing takes 22% of 2026 sales, and the protective clothing market is set for a 6.8% CAGR from 2026 to 2036. Increasing PPE procurement is supporting the demand for flame-retardant coated nylon. Key challenges in the coated fabrics market include PFAS limits on fluoropolymer finishes and emission checks on PVC lines. PFAS-free and low-emission grades are therefore gaining preference in car and PPE tenders.
Key Market Trends & Insights
- Polymer-coated fabrics lead material type sales at 25% in 2026, just above fabric-backed vinyl composites at an estimated 24.2%.
- Demand for polyester base cloth is the largest among substrates, at 46% of 2026 volume.
- Car makers and truck builders make transportation the top application at 30%, and PPE buyers bring protective clothing to 22%.
- PVC holds an estimated 34.5% of coating chemistry sales, on the lowest cost per square metre for tarpaulins and truck curtains.
- Seat suppliers buying straight from approved mills give direct OEM supply about 36% of 2026 channel sales (estimated).
- Buyer preference for wear life puts abrasion resistance first at about 26% (estimated), with flame retardancy at an estimated 23.5%.
Regional Highlights
- Coated fabric demand in China is set for a 5.3% CAGR from 2026 to 2036 in the FMI forecast, the faster of the two profiled countries.
- India follows at 5.1%, and both Asian markets run above the 4.8% global CAGR.
- Third-round textile PLI approvals in April 2026 covered 52 applications, with 18 in technical textiles.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Coated Fabrics Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 50.0 billion |
| Estimated Market Size in 2026 | USD 52.2 billion |
| Projected Market Size by 2036 | USD 83.5 billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Revenue, 2026 to 2036 | USD 31.3 billion |
| Market Expansion Multiple | 1.6x |
Transportation, at 30%, and protective clothing, at 22%, hold the two largest application shares in 2026. FMI places the incremental opportunity at USD 31.3 billion between 2026 and 2036. Car output and PPE procurement will therefore drive the largest part of that sum.
Fluorine-Free Finishes and New End Uses
The DMSRDE laboratory of DRDO signed an MoU with the Uttar Pradesh Textile Technology Institute in July 2026 to develop high-performance fabrics, including protective clothing and ballistic materials.[3] India reported domestic defence production of a record ₹1.78 lakh crore in FY 2025-26.[3] Defence clothing programs will need coated nylon and aramid fabrics with flame and chemical resistance.
ECHA's Risk Assessment Committee completed the scientific evaluation of the proposed EU-wide PFAS restriction, European Coatings reported in March 2026.[4] A final SEAC opinion is due by late 2026.[4] Riopele developed a fluorine-free water-repellent finish based on a modified resin formulation, Innovation in Textiles reported in September 2026.[5] Fluorine-free finishes will spread first in apparel and outdoor fabrics and then reach industrial coated grades.
Table 2: Vehicle Output, Policy and Finish Chemistry Indicators for the Coated Fabrics Market (units, INR and dates), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Global vehicle production, 2025 | 96.4 million units, up 3.9% | Volume base for seat, airbag and trim fabric. | [1] |
| Asia vehicle production, 2025 | About 59.2 million, up 7.6% | Seat and airbag fabric orders follow Asian car plants. | [1] |
| Europe vehicle production, 2025 | 17.2 million, down 0.8% | Flat demand at European interior suppliers. | [1] |
| China vehicle sales outlook, 2026 | 34.75 million units, up 1% | Slower volume growth in the largest auto base. | [6] |
| EU PFAS restriction, March 2026 | RAC opinion adopted; final SEAC opinion by end of 2026 | Timeline for fluoropolymer finish limits. | [4] |
| India textiles PLI Round III, April 2026 | 52 applications; 18 technical textiles; ₹6,708 crore | New Indian technical textile capacity. | [2] |
| India technical textile exports, FY 2024-25 | USD 2.92 billion | Export pull for Indian mills. | [7] |
| India domestic defence production, FY 2025-26 | ₹1.78 lakh crore | Demand base for defence textiles. | [3] |
Analyst Perspective
“Coated fabric margins will hold best in PFAS-free PPE and defence grades, because buyers there pay for certification and long service life. I expect commodity PVC tarpaulin prices to stay tight as Chinese and Indian capacity grows, so mills will protect margin by moving volume into certified flame-retardant and low-emission grades.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the coated fabrics market segmented?
Six product axes frame coated fabrics alongside region, from material type and substrate to performance property. Polyester leads substrates at 46%, transportation leads applications at 30%, and polymer-coated grades lead materials at 25% in 2026.
By material type: polymer-coated fabrics, rubber-coated fabrics, fabric-backed vinyl composites, silicone-coated fabrics, and fluoropolymer-coated fabrics.
By substrate: polyester, nylon, cotton and blends, fiberglass, and aramid and high-modulus fibers.
By application: transportation, protective clothing, industrial, commercial tents and structures, furniture and upholstery, and other applications.
By coating chemistry: PU, PVC, TPU, silicone, and PTFE/PVDF systems.
By distribution channel: direct OEM supply, converters and fabricators, industrial distributors, project-based procurement, and aftermarket and replacement sales.
By performance property: abrasion resistance, chemical resistance, flame retardancy, weatherability, and low-emission interiors.
By region: North America (NA), Latin America (LATAM), Western Europe (WE), Eastern Europe (EE), Middle East and Africa (MEA), East Asia (EA, including China), and South Asia and Pacific (SAP, including India).
Why do polymer-coated fabrics lead material type sales?
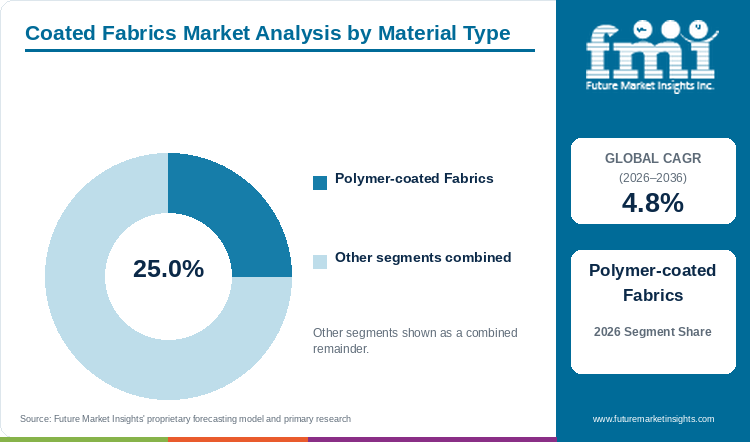
Polymer-coated fabrics hold 25% of 2026 material type sales, a narrow lead over fabric-backed vinyl composites.
Table 3: Material Type Share for the Coated Fabrics Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Polymer-coated Fabrics | 25% |
| Fabric-backed Vinyl Composites | 24.2% |
| Rubber-coated Fabrics | 18.6% |
| Fluoropolymer-coated Fabrics | 16.8% |
| Silicone-coated Fabrics | 15.4% |
| Total | 100.0% |
Table 4: Material Type Leadership and Market Growth for the Coated Fabrics Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Polymer-coated Fabrics |
Polymer-coated fabrics hold 25% of 2026 material type sales on FMI figures. Bag, seat and PPE makers pick polymer-coated cloth over fabric-backed vinyl composites (an estimated 24.2%) because polymer grades are lighter and softer to sew. Vinyl composites keep truck curtains and wall coverings on price per metre. Rubber-coated fabrics, near 18.6% by estimate, lose to polymer grades on weight and colour range and stay in hoses, diaphragms and inflatable boats. Fluoropolymer-coated fabrics cost far more and go mainly into roof membranes, at an estimated 16.8%. Coaters buy PTFE and PVDF resin for high-heat and chemical-resistant grades, and the fluoropolymer market is set for a 5.6% CAGR from 2026 to 2036. EU PFAS review still hangs over those membrane grades.[4] Silicone coatings, about 15.4% (estimated), serve only heat and food-contact jobs.
- Seat, bag and PPE makers are the main cloth buyers in the polymer coated fabrics market.
Why does polyester lead substrate demand?
Polyester carries 46% of 2026 substrate demand, far ahead of nylon.
Table 5: Substrate Share for the Coated Fabrics Market (percentage share), 2026
| Substrate | Estimated Share (2026) |
|---|---|
| Polyester | 46% |
| Nylon | 21.5% |
| Cotton and Blends | 13% |
| Fiberglass | 12.3% |
| Aramid and High-modulus Fibers | 7.2% |
| Total | 100.0% |
Polyester carries 46% of 2026 substrate demand as per FMI, more than twice nylon at an estimated 21.5%. At a lower cost than nylon, polyester cloth also stretches less under sunlight, so tarpaulin and membrane coaters choose polyester by default. Nylon keeps airbags and light packs owing to higher tear strength. Workwear and heritage tent makers stay with cotton and blends (near 13% by estimate) out of comfort and habit. Glass cloth does not burn, which gives fiberglass an estimated 12.3% in fire curtains and PTFE roofs. Aramid and high-modulus fibers take about 7.2% (estimated) and remain small on price. Dimension-Polyant launched X-Pac hyperTEC laminates with a 100% Ultra-PE face fabric in October 2026.[8] As a result, Ultra-PE faces will compete with nylon in packs before polyester volume is affected.
Why does transportation lead application sales?
Transportation buys 30% of 2026 application volume, with protective clothing at 22%.
Table 6: Application Share for the Coated Fabrics Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Transportation | 30% |
| Protective Clothing | 22% |
| Industrial | 17.5% |
| Furniture and Upholstery | 12.5% |
| Commercial Tents and Structures | 11% |
| Other Applications | 7% |
| Total | 100.0% |
OICA counted 34.53 million vehicles built in China in 2025, including 16.626 million new-energy vehicles, up 29%.[1] Each car carries coated seat fabric, airbag cloth and trim, so transportation takes 30% of 2026 application sales, FMI finds. Protective clothing, at 22%, uses less fabric per buyer and pays more per metre for flame and chemical ratings. Industrial uses take an estimated 17.5% from conveyor belts and machine covers, in line with factory maintenance cycles. For sofas and chairs, coated fabric competes with leather and woven cloth, which keeps furniture and upholstery near 12.5% by estimate. Coated fabric competes with knitted trim inside the automotive fabrics market, and carmakers pick one of the two for each interior program.
- Event organisers and stadium builders keep commercial tents and structures at about 11% (estimated).
- CAAM projects 2026 sales of China-made vehicles at 34.75 million units, up 1%.[6]
Why does PVC lead coating chemistry sales?
PVC coatings hold an estimated 34.5% of 2026 coating chemistry sales, ahead of PU at about 31%.
Table 7: Coating Chemistry Share for the Coated Fabrics Market (percentage share), 2026
| Coating Chemistry | Estimated Share (2026) |
|---|---|
| PVC | 34.5% |
| PU | 31% |
| Silicone | 12.5% |
| TPU | 12% |
| PTFE/PVDF Systems | 10% |
| Total | 100.0% |
PVC gives the lowest cost per square metre for tarpaulins, truck curtains and tensile roofs. Due to this, PVC holds an estimated 34.5% of 2026 coating chemistry sales. Seat and apparel makers pay more for PU, about 31% by estimate, to get a softer hand. Silicone survives higher heat than PVC, so airbags and oven belts keep silicone near 12.5% by estimate. TPU contains no plasticiser and is gaining preference in welded bags and inflatables, at an estimated 12%. Weather life is the strength of PTFE/PVDF systems, which hold about 10% (estimated). PTFE/PVDF lines face the EU-wide PFAS restriction review.[4] TPU and other plasticiser-free coatings will compete with PVC for car interior programs as car makers run emission tests on each grade.
Why does direct OEM supply lead distribution channel sales?
Car and seat makers buying direct from mills give direct OEM supply about 36% (estimated) of the 2026 channel split.
Table 8: Distribution Channel Share for the Coated Fabrics Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Direct OEM Supply | 36% |
| Converters and Fabricators | 27.5% |
| Industrial Distributors | 16% |
| Project-based Procurement | 11.5% |
| Aftermarket and Replacement Sales | 9% |
| Total | 100.0% |
Car makers qualify coated fabric by colour, abrasion and emission tests and then buy from the approved mill for the life of a model. Direct OEM supply holds about 36% of 2026 channel sales by estimate. Converters and fabricators buy roll goods in smaller lots for tents, covers and PPE, so mills sell through converters at higher margin and lower volume, an estimated 27.5%. Small shops buy standard grades off the shelf from industrial distributors, at an estimated 16%.
- Project-based procurement (about 11.5%, estimated) and aftermarket sales (about 9%, estimated) follow stadium tenders and seat repairs.
Why does abrasion resistance lead performance property sales?
Abrasion-rated grades lead the 2026 performance property split with about 26% by estimate, and flame-retardant grades rank second.
Table 9: Performance Property Share for the Coated Fabrics Market (percentage share), 2026
| Performance Property | Estimated Share (2026) |
|---|---|
| Abrasion Resistance | 26% |
| Flame Retardancy | 23.5% |
| Weatherability | 20% |
| Chemical Resistance | 18% |
| Low-emission Interiors | 12.5% |
| Total | 100.0% |
Abrasion resistance comes first at about 26% (estimated). Seats, conveyor covers and truck curtains fail by rubbing, so nearly every tender names an abrasion rating. Flame retardancy, at an estimated 23.5%, is a narrower buy pulled by PPE and rail rules. Tent and membrane buyers pay for weatherability, near 20% by estimate, and interior buyers seldom do.
- An estimated 18% goes to chemical-resistant grades for hazmat suits and tank covers.
- Low-emission interior grades hold about 12.5% (estimated) and sell to car makers that run cabin emission tests.
What are the drivers, restraints, and opportunities in the coated fabrics market?
Adoption of coated fabrics grows with vehicle output, PPE standards and engineered structures. PFAS-free finishes and low-emission interiors shape product trends, and resin cost volatility is the main restraint.
- Driver: Asian vehicle output and safety rules raise coated fabric use.
- Restraint: PFAS limits and resin price swings raise compliance and input costs.
- Opportunity: Defence and PPE programs in India buy coated technical textiles.
Asian Vehicle Output Pulls Interior and Airbag Fabric
Car plants buy the largest single share of coated fabric, 30% of 2026 application sales, analysts at FMI see. Asian vehicle output rose 7.6% to about 59.2 million units in 2025, more than 61% of global output, OICA reported.[1] European output fell 0.8% to 17.2 million vehicles.[1] Seat and airbag fabric orders will follow the Asian output gain, and European coaters will look to export programs for growth.
PFAS Review Raises Compliance Costs for Fluoropolymer Coaters
Producers of fluoropolymer-coated fabrics face the EU PFAS restriction, a long rule-making path, and resin cost volatility. The PFAS proposal, submitted in January 2023 by Denmark, Germany, the Netherlands, Norway and Sweden, aims to address all PFAS uses.[4] SEAC will put a draft opinion to a 60-day public consultation.[4] Fluoropolymer-coated membranes and PTFE-coated glass cloth will need derogations or new chemistry before the European Commission proposes a restriction.
Indian Defence and PPE Programs Open New Accounts
Indian defence and PPE buyers are ordering coated technical textiles from domestic mills. The National Technical Textiles Mission carries an outlay of ₹1,480 crore, Textile Excellence reported in July 2026.[3] India recorded technical textile exports of USD 2.92 billion in FY 2024-25, Textile World reported citing the Ministry of Textiles.[7] SRF Limited and other Indian coaters will gain from coated nylon and aramid orders for defence clothing.
Which country CAGRs are profiled in the coated fabrics market?
Table 10: Country CAGR Comparison for the Coated Fabrics Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 5.3% |
| India | 5.1% |
How do country-level CAGRs compare in the coated fabrics market?
Chinese coaters supply seat and airbag fabric for the 34.53 million vehicles built in China in 2025.[1] The 5.3% CAGR for China from 2026 to 2036 and the 5.1% CAGR for India, as FMI predicts, both exceed the 4.8% global CAGR. In India, third-round PLI approvals pledged ₹6,708 crore of investment, and those mills are changing the economics of scaling production for tarpaulins and PPE fabrics.[2]
- The largest vehicle base, new-energy interiors and export car programs back the Chinese rate.
- India adds PLI-backed technical textile capacity, defence clothing demand and car output.
Full report country CAGRs cover: country tables for India and China inside SAP and EA, plus tables for NA, LATAM, WE, EE and MEA.
Country-wise Analysis
China Coated Fabrics Market Outlook (2026 to 2036)
China built 34.53 million vehicles in 2025, adding roughly 3.25 million in a single year, OICA reported.[1] Gasgoo, citing CAAM, put Chinese vehicle shipments abroad at over 7 million in 2025, of which 2.615 million were NEVs.[6] Export cars carry seat, door and airbag fabric made by Chinese coaters, so coated fabric demand follows export models as well as home sales. CAAM expects 2026 sales to edge up 1%.[6] Chinese coated fabric sales are projected at a 5.3% CAGR from 2026 to 2036, ahead of India.
Key takeaway: Over 7 million Chinese vehicle exports in 2025 give Chinese coaters a second outlet beside home sales.
India Coated Fabrics Market Outlook (2026 to 2036)
India is set for a 5.1% CAGR from 2026 to 2036. Investment pledged in the third PLI round came to ₹6,708 crore, and expected turnover to ₹21,186 crore, Textile Excellence reported in April 2026.[2] India produced 6.49 million vehicles in 2025.[1] Defence textile research under the DMSRDE and UPTTI MoU targets protective clothing and ballistic materials.[3] New PLI mills will need coating lines for tarpaulins, PPE and car fabrics.
Key takeaway: The 52 mills approved in the third PLI round will add the first new Indian coating lines.
Who are the notable companies in the coated fabrics market?
Continental AG, Serge Ferrari Group, Trelleborg AB, Sioen Industries NV, Saint-Gobain Performance Fabrics, Seaman Corporation, Spradling International, Haartz Corporation, Cooley Group and SRF Limited are the profiled suppliers.
The global group of top companies operating in the coated fabrics market covers Continental, Serge Ferrari, Trelleborg, Sioen, Saint-Gobain Performance Fabrics and Seaman Corporation. Spradling International, Haartz Corporation, Cooley Group and SRF Limited compete in regional and specialist niches. Every supplier with a fluoropolymer line faces the same EU PFAS review, with a final SEAC opinion due by late 2026.[4] Sioen subsidiary Dimension-Polyant launched X-Pac hyperTEC laminates in October 2026.[8]
- Major global suppliers: Continental AG, Serge Ferrari Group, Trelleborg AB, Sioen Industries NV, Saint-Gobain Performance Fabrics, and Seaman Corporation.
- Regional and specialist suppliers: Spradling International, Haartz Corporation, Cooley Group, and SRF Limited.
Competitive Benchmarking: Coated Fabrics Market
Table 11: Competitive Benchmarking for the Coated Fabrics Market (qualitative documentation ratings), 2026
| Company | Product Launch Activity | PFAS-Free Range | India or China Exposure | Recency |
|---|---|---|---|---|
| Sioen Industries NV | High | Medium | Low | High |
| SRF Limited | Low | Low | High | Low |
| Serge Ferrari Group | Low | Low | Low | Low |
| Continental AG | Low | Low | Medium | Low |
| Saint-Gobain Performance Fabrics | Low | Low | Low | Low |
Cells marked High draw on several dated launches, filings or trade reports, and cells marked Low draw on few, so the grid says nothing about market share.
Key Developments in the Coated Fabrics Market
- In October 2026, Dimension-Polyant, owned by Sioen Industries, launched X-Pac hyperTEC laminates for mountaineering and bikepacking gear.[8]
- In September 2026, Riopele developed a fluorine-free water-repellent finish for protective fabrics.[5]
- In July 2026, DMSRDE and UPTTI signed an MoU on high-performance defence and civilian textiles.[3]
- In April 2026, OICA reported global vehicle production of 96.4 million units for 2025.[1]
- In April 2026, India cleared a third round of 52 textile PLI applications.[2]
- In March 2026, the ECHA Risk Assessment Committee completed scientific evaluation of the proposed EU-wide PFAS restriction.[4]
- In January 2026, CAAM reported 2025 vehicle production of 34.531 million units in China.[6]
- In November 2025, Techtextil India announced a 10th edition in Mumbai with over 215 exhibitors.[7]
Key Players in the Coated Fabrics Market
Major Global Suppliers
- Continental AG
- Serge Ferrari Group
- Trelleborg AB
- Sioen Industries NV
- Saint-Gobain Performance Fabrics
- Seaman Corporation
Regional and Specialist Suppliers
- Spradling International
- Haartz Corporation
- Cooley Group
- SRF Limited
Coated Fabrics Market - Report Scope
Table 12: Report Scope for the Coated Fabrics Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material type; substrate; application; coating chemistry; distribution channel; performance property; region |
| Quantitative units | USD billion |
| Market definition | Textile substrates coated with polymer, rubber, vinyl, silicone or fluoropolymer layers for transportation, protective clothing, industrial, structural, furniture and other uses. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; India |
| Key companies profiled | Continental AG, Serge Ferrari Group, Trelleborg AB, Sioen Industries NV, Saint-Gobain Performance Fabrics, Seaman Corporation, Spradling International, Haartz Corporation, Cooley Group, SRF Limited |
| Forecast period | 2026 to 2036 |
Coated Fabrics Market - Research Methodology
Table 13: Research Methodology for the Coated Fabrics Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Vehicle output, policy and product facts come from OICA, CAAM, regulator updates and textile trade press dated May 2025 or later. |
| Desk Research | Desk research covers vehicle production, PFAS rules, Indian textile schemes and coated fabric launches. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 50.0 billion and the 4.8% CAGR from 2026 to 2036. |
| Data Validation | Chinese vehicle figures were matched across OICA and CAAM releases for 2025. |
Coated Fabrics Market by Segments
Coated Fabrics Market segmented by Material Type:
- Polymer-coated Fabrics
- Rubber-coated Fabrics
- Fabric-backed Vinyl Composites
- Silicone-coated Fabrics
- Fluoropolymer-coated Fabrics
Coated Fabrics Market segmented by Substrate:
- Polyester
- Nylon
- Cotton and Blends
- Fiberglass
- Aramid and High-modulus Fibers
Coated Fabrics Market segmented by Application:
- Transportation
- Protective Clothing
- Industrial
- Commercial Tents and Structures
- Furniture and Upholstery
- Other Applications
Coated Fabrics Market segmented by Coating Chemistry:
- PU
- PVC
- TPU
- Silicone
- PTFE/PVDF Systems
Coated Fabrics Market segmented by Distribution Channel:
- Direct OEM Supply
- Converters and Fabricators
- Industrial Distributors
- Project-based Procurement
- Aftermarket and Replacement Sales
Coated Fabrics Market segmented by Performance Property:
- Abrasion Resistance
- Chemical Resistance
- Flame Retardancy
- Weatherability
- Low-emission Interiors
Coated Fabrics Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- China
- South Asia and Pacific
- India
- Middle East and Africa
Research Sources and Bibliography
- [1] International Organization of Motor Vehicle Manufacturers (OICA). (2026, April 23). Auto industry growth shifted east in 2025 amid global repositioning. https://oica.net/auto-industry-growth-shifted-east-in-2025-amid-global-repositioning/
- [2] Textile Excellence. (2026, April 16). 52 New Applications Approved Under PLI Scheme For Textiles. https://textileexcellence.com/single-news/6885/52-new-applications-approved-under-pli-scheme-for-textiles
- [3] Textile Excellence. (2026, July 28). DRDO MoU With Uttar Pradesh Textile Tech Institute Signals Big Push For Defence Textiles. https://textileexcellence.com/single-news/7094/drdo-mou-with-uttar-pradesh-textile-tech-institute-signals-big-push-for-defence-textiles
- [4] European Coatings. (2026, March 5). ECHA's RAC adopts opinion on PFAS restriction proposal. https://www.european-coatings.com/news/legislation/echas-rac-adopts-opinion-on-pfas-restriction-proposal/
- [5] Innovation in Textiles. (2026, September 28). Fluorocarbon-free fabric finish from Riopele. https://innovationintextiles.com/fluorocarbon-free-fabric-finish-from-riopele/
- [6] Gasgoo (China Association of Automobile Manufacturers data). (2026, January 15). China's auto sales reach 34.40 million in 2025, 2026 expected to edge up 1%. https://autonews.gasgoo.com/articles/market-industry/chinas-auto-sales-reach-3440-million-in-2025-2026-expected-to-edge-up-1-2011759388677484544
- [7] Textile World. (2025, November 13). Techtextil India 2025: Weaving India's Journey Toward Global Functional Textile Leadership. https://www.textileworld.com/textile-world/nonwovens-technical-textiles/2025/11/techtextil-india-2025-weaving-indias-journey-toward-global-functional-textile-leadership/
- [8] Innovation in Textiles. (2026, October 7). X-Pac takes sailcloth technology into outdoor fabrics. https://innovationintextiles.com/x-pac-takes-sailcloth-technology-into-outdoor-fabrics/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will coated fabrics market size be in 2026 and 2036?
- What CAGR will coated fabric sales post from 2026 to 2036?
- Which application will buy the most coated fabric in 2026?
- Which substrate and coating chemistry will lead?
- Which of the two profiled Asian countries will grow faster?
- Which suppliers will compete for automotive and PPE contracts?
Frequently Asked Questions
What is the coated fabrics market size in 2026?
At USD 52.2 billion in 2026, market size will rise to the USD 83.5 billion FMI expects for 2036.
What growth rate will coated fabrics post?
Coated fabric demand will expand at a 4.8% CAGR from 2026 to 2036, carried by car interiors, PPE and engineered structures.
Which application will lead in 2026?
Transportation will stay first at 30% of application sales, and protective clothing will follow at 22%.
Which substrate will carry the most demand?
Polyester will carry 46% of 2026 substrate demand on cost and coating adhesion.
Which country will grow faster through 2036?
China will outpace India, FMI projects, at a 5.3% CAGR from 2026 to 2036 against 5.1%.
Which companies will compete in coated fabrics?
Continental, Serge Ferrari, Trelleborg, Sioen, Saint-Gobain Performance Fabrics and Seaman will compete globally, and Spradling, Haartz, Cooley and SRF will compete in regional and specialist niches.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Polymer-coated Fabrics
- Rubber-coated Fabrics
- Fabric-backed Vinyl Composites
- Silicone-coated Fabrics
- Fluoropolymer-coated Fabrics
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Substrate, 2026 to 2036
- Polyester
- Nylon
- Cotton and Blends
- Fiberglass
- Aramid and High-modulus Fibers
- Y-o-Y Growth Trend Analysis By Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Transportation
- Protective Clothing
- Industrial
- Commercial Tents and Structures
- Furniture and Upholstery
- Other Applications
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Coating Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coating Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coating Chemistry, 2026 to 2036
- PU
- PVC
- TPU
- Silicone
- PTFE/PVDF Systems
- Y-o-Y Growth Trend Analysis By Coating Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct OEM Supply
- Converters and Fabricators
- Industrial Distributors
- Project-based Procurement
- Aftermarket and Replacement Sales
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Performance Property, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Performance Property, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Performance Property, 2026 to 2036
- Abrasion Resistance
- Chemical Resistance
- Flame Retardancy
- Weatherability
- Low-emission Interiors
- Y-o-Y Growth Trend Analysis By Performance Property, 2021 to 2025
- Absolute $ Opportunity Analysis By Performance Property, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Key Takeaways
- Key Countries Market Analysis
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- India
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Substrate
- By Application
- By Coating Chemistry
- By Distribution Channel
- By Performance Property
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Sioen Industries NV
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SRF Limited
- Serge Ferrari Group
- Continental AG
- Saint-Gobain Performance Fabrics
- Trelleborg AB
- Seaman Corporation
- Spradling International
- Haartz Corporation
- Cooley Group
- Sioen Industries NV
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


