

- Market Size (2026)
- USD 25.5 Bn
- Forecast (2036)
- USD 59.3 Bn
- CAGR (2026 to 2036)
- 8.8%
How big is Digital Printing Packaging Market in 2026?
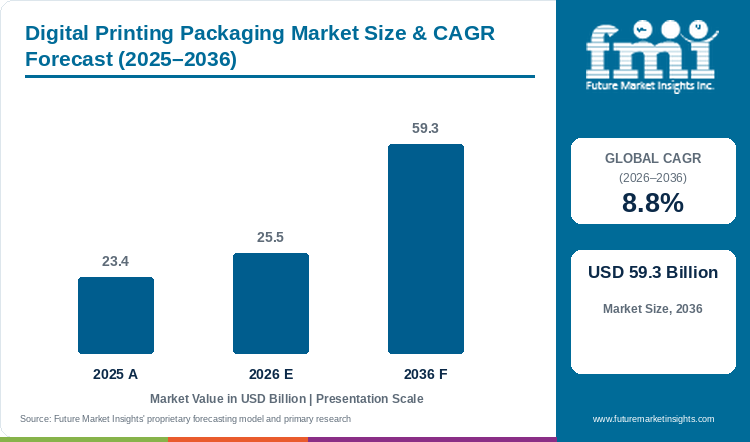
Sales in the digital printing packaging market are projected to grow at 8.8% CAGR through 2036. Market value rises from USD 23.4 billion in 2025 to USD 25.5 billion in 2026 and is expected to reach USD 59.3 billion by 2036.
Frequent retail label changes and regional packaging runs have pushed converters away from fixed analog cylinders toward on-demand digital printing for packaging. According to Future Market Insights analysis, global market value rises from USD 23.4 billion in 2025 to USD 25.5 billion in 2026 and reaches USD 59.3 billion by 2036 at an 8.8% CAGR. This progression generates USD 33.8 billion in added revenue over the ten-year period. Fully automatic high-speed lines hold 46.8% of machine configuration revenue in 2026 because inline presses remove plate setup downtime. In September 2026, U.S. Environmental Protection Agency compliance records for NAICS 323 documented tightened solvent capture rules across commercial pressrooms [1]. However, specialty UV ink prices still restrain long-run economics.
Key Market Trends & Insights
- By machine configuration: Fully automatic high-speed lines led the category with a share of 46.8% in 2026, as continuous web splicing eliminates press stops between short jobs.
- By technology / mechanism: Servo-driven robotic motion accounted for 50.2% of demand in 2026, supported by electronic web tension control across thin polymer substrates.
- By end-use industry: Food & beverage packaging represented 35.2% of revenue in 2026, reflecting frequent promotional pouch and label updates across grocery brands.
Regional Highlights
- Fastest-growing evaluated country: Italy, at 10.7% CAGR from 2026 to 2036.
- By country: Spain at 9.9%, the UK at 9.2%, and the USA at 8.4% follow, while Japan records the lowest evaluated CAGR at 7.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Digital Printing Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 23.4 billion |
| Estimated Market Size in 2026 | USD 25.5 billion |
| Projected Market Size by 2036 | USD 59.3 billion |
| CAGR, 2026 to 2036 | 8.8% |
| Added Revenue, 2026 to 2036 | USD 33.8 billion |
Country demand conditions differ as packaging converters balance warehouse write-offs from obsolete pre-printed stock against the capital cost of single-pass inkjet lines. FMI research indicates that brand owners are cutting minimum order quantities for folding cartons and pouches to avoid scrapping outdated nutritional panels. In April 2025, narrow-web production audits from the Technical Association of the Graphic Arts showed that electronic job queuing reduced make-ready substrate waste by 38.0% across label plants [2]. Owing to the advantages associated with zero plate engraving, converters are pairing digital print bars with existing packaging machinery to handle regional language versions without halting main filling lines.
Press Throughput and Job-Economics Sizing
Table 2: Press Throughput and Job-Economics Sizing for the Digital Printing Packaging Market (USD billion, units, and USD thousand), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 23.4 | 25.5 | 59.3 |
| Digital press installations (thousand units) | 32.0 to 35.0 | 35.0 to 38.0 | 66.0 to 74.0 |
| Printed packaging jobs processed (billion) | 9.4 to 10.6 | 10.4 to 11.8 | 22.0 to 25.0 |
| Spend per converting site (USD thousand) | 480.0 to 540.0 | 520.0 to 590.0 | 1,050.0 to 1,220.0 |
Operational note: Press estimates reflect active digital capacity across label and carton converting plants. Job volumes reflect short-run orders below conventional flexographic break-even lengths.
Per Capita and Converting-Site Sizing
On-demand decoration has expanded across label and pouch converting plants because retail buyers penalize late deliveries and outdated promotional graphics. Rising warehouse storage fees convert frequent artwork revisions into recurring demand for inkjet printers and low-migration ink sets. In May 2025, graphic technology validation studies under ISO 12647-8 confirmed that automated inline spectrophotometers held brand spot-color tolerances within 1.5 Delta E across corrugated liners [3]. Converters evaluate printhead nozzle longevity and primer adhesion before approving capital budgets.
Table 3: Per Capita and Converting-Site Spending Indicators for the Digital Printing Packaging Market (billion, USD, and USD thousand), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 2.9 | 3.1 | 6.6 |
| Spend per 1,000 people (USD) | 2,847.8 | 3,072.3 | 6,625.7 |
| Spend per converting site (USD thousand) | 520.0 to 590.0 | 555.0 to 630.0 | 1,120.0 to 1,300.0 |
Table 4: Converting-Site and Press Investment Indicators for the Digital Printing Packaging Market (USD billion, thousand, and USD), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 25.5 billion | 2026 estimate |
| Packaging converting sites worldwide (thousand) | 92.0 | 2025 industry count |
| Market spend per converting site | USD 277,173.9 | Per-site average |
| Food & beverage end-use revenue, 2026 | USD 9.0 billion | 35.2% share |
Analyst Perspective
"Single-pass aqueous inkjet presses give carton and pouch converters fast turnaround on regional SKU batches without plate storage overhead. High proprietary ink prices and corona surface treatment requirements still delay full replacement of wide-web flexographic lines."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the digital printing packaging market segmented?
The digital printing packaging market is segmented by machine configuration, technology / mechanism, end-use industry, and region. In 2026, fully automatic high-speed lines are projected at 46.8%, servo-driven robotic motion at 50.2%, and food & beverage packaging at 35.2%.
By machine configuration: Fully automatic high-speed lines, semi-automatic modular units, and rotary indexing systems.
By technology / mechanism: Servo-driven robotic motion, mechanical cam-driven, and pneumatic & continuous motion.
By end-use industry: Food & beverage packaging, pharmaceuticals & healthcare, personal care & cosmetics, and industrial & chemicals.
Why do Fully Automatic High-Speed Lines lead the machine configuration category?
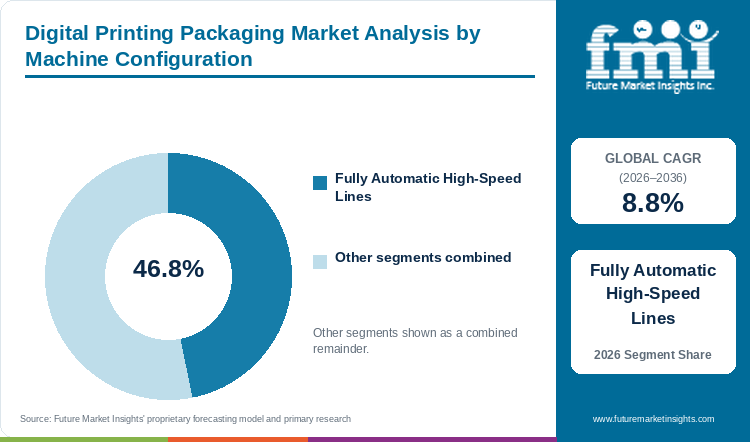
Fully automatic high-speed lines are expected to hold 46.8% of machine configuration demand in 2026, supported by continuous splicing.
Table 5: Machine Configuration Share for the Digital Printing Packaging Market (percentage share), 2026
| Machine Configuration | Share (2026) |
|---|---|
| Fully Automatic High-Speed Lines | 46.8% |
| Other Segments Combined | 53.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Machine Configuration Leadership and Market Growth for the Digital Printing Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.8% |
| Leading Segment | Fully Automatic High-Speed Lines |
Industrial packaging converters favor fully automatic high-speed lines because continuous web transport and flying splice unwinds allow non-stop printing across multi-shift schedules. Unlike semi-automatic modular units that require manual roll loading between short batches, fully automatic lines link single-pass piezoelectric printheads directly with inline die-cutting and turret rewinding. In addition to this, integrated vision cameras check nozzle uniformity at web speeds above 120 meters per minute. Rising adoption of corrugated box packaging equipment across regional fulfillment plants keeps converter capital budgets focused on automated lines that switch artwork files without slowing down the web.
- Fully automatic high-speed lines are projected to account for 46.8% of machine configuration revenue in 2026, supported by automated roll splicing and inline vision inspection.
- In June 2025, production press studies in Packaging Technology and Science reported that fully automated digital converting lines reduced job changeover time by 82.0% compared with analog flexo presses [4].
What maintains Servo-Driven Robotic Motion ahead in the technology mechanism category?
Servo-driven robotic motion is projected to capture 50.2% of technology mechanism volume in 2026, driven by electronic web synchronization.
Press manufacturers build modern digital converting lines around independent multi-axis servo drives so substrate tension and printhead clearance stay locked without mechanical line shafts. When a converter switches from thin polyolefin shrink film to heavy folding boxboard, operators adjust repeat length and feed pitch electronically on the operator terminal. Mechanical cam-driven assemblies still serve fixed-repeat rotary die-cutters, but gear backlash causes drop misregistration under rapid acceleration. Furthermore, combining servo web transport with continuous inkjet printers lets machinery builders hold sub-millimeter registration across stretchable films during high-speed splicing.
- Servo-driven robotic motion is estimated to hold 50.2% of technology mechanism demand in 2026, driven by gearless electronic synchronization and rapid repeat-length switching.
- In August 2025, motion-control trials published in IEEE Transactions on Industrial Informatics showed that multi-axis servo web drives cut harmonic vibration by 65.0% during high-speed inkjet drop ejection [5].
Why does Food & Beverage Packaging anchor the end-use industry category?
By end-use industry, food and beverage packaging is estimated to represent 35.2% in 2026, reflecting frequent seasonal label changes.
Grocery and beverage producers generate the largest demand for digitally printed cartons and shrink sleeves because retail marketing teams run frequent regional promotions and seasonal flavor launches. Ordering exact batch quantities on flexible packaging webs prevents warehouse write-offs when ingredient regulations or nutrition tables change. Besides this, craft beverage canners use direct digital decoration to avoid minimum order thresholds on pre-printed aluminum cans. Strict chemical migration limits still require converters to qualify low-odor electron-beam or aqueous pigment inks before running direct food-contact wrappers on commercial filling lines.
- Food & beverage packaging is anticipated to contribute 35.2% of end-use industry revenue in 2026, owing to recurring short-run pouch and beverage label orders.
- In November 2025, food-contact migration testing in Food Additives & Contaminants confirmed that electron-beam cured digital packaging inks kept photoinitiator migration below 10.0 parts per billion [6].
What are the drivers, restraints, and opportunities in the digital printing packaging market?
In the digital printing packaging market, short-run SKU proliferation and mandatory unit serialization support demand, elevated specialty ink prices and film priming steps constrain long-run economics, and direct-to-shape container printing is expected to expand equipment revenue through 2036.
- Driver: Brand owners and pharmaceutical packers will continue to adopt digital presses for short-run versioning and unit-level 2D barcode serialization through 2036.
- Restraint: High proprietary inkjet ink pricing and corona or chemical priming requirements on non-porous films will continue to limit long-run cost competitiveness through 2036.
- Opportunity: Robotic direct-to-shape container decoration and water-based food-compliant ink systems are expected to open new machinery orders through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer goods companies and pharmaceutical manufacturers are shifting away from large pre-printed packaging inventories toward just-in-time digital converting. FMI data suggests that dividing national product lines into regional language packs and promotional editions makes analog plate engraving too slow and costly. In addition to this, track-and-trace rules require unique datamatrix codes on every medicine carton and blister lidding foil. In January 2026, European Commission Directorate-General for Health and Food Safety food-contact and traceability updates reinforced strict lot-level identification across packaged goods [7]. Suppliers of pharmaceutical packaging machinery must guarantee real-time vision grading at full line speed before plants sign off on press installations.
Risk Assessment of the Digital Printing Packaging Market: Operational and Formulation Friction
High consumable pricing for UV-curable and electrophotographic inks remains the main hurdle slowing digital substitution on high-volume runs. While plate-free operation removes make-ready fees on short batches, ink consumption accounts for up to 70.0% of variable operating cost once run lengths exceed fifty thousand impressions. However, issues such as low surface energy on polyolefin films also force converters to install inline corona treatment or aqueous primer stations before the inkjet heads. In July 2025, web coating studies in the Journal of Applied Packaging Research found that unprimed polypropylene films suffered 28.0% dot-gain distortion under high-speed aqueous jetting [8]. Plant engineers consequently delay wide-web press purchases until consumable contracts cap per-liter ink rates for printed rigid packaging.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Equipment builders are unlocking high-margin machinery orders by mounting piezoelectric printheads on multi-axis robotic arms for direct-to-shape inkjet printing on glass bottles and aluminum cans. Printing graphics and tactile UV varnish directly onto rigid containers removes pressure-sensitive paper labels and glue application stations from the filling line. In September 2025, imaging trials in the Journal of Imaging Science and Technology showed that waveform-compensated piezo heads maintained 99.8% droplet placement accuracy across curved cylindrical surfaces [9]. Furthermore, pairing automated nozzle-out compensation cameras with water-based pigment inks will allow machinery vendors to win turnkey pouch and can decoration contracts across beverage plants through 2036.
Digital Printing Packaging Market by Country (2026 to 2036)
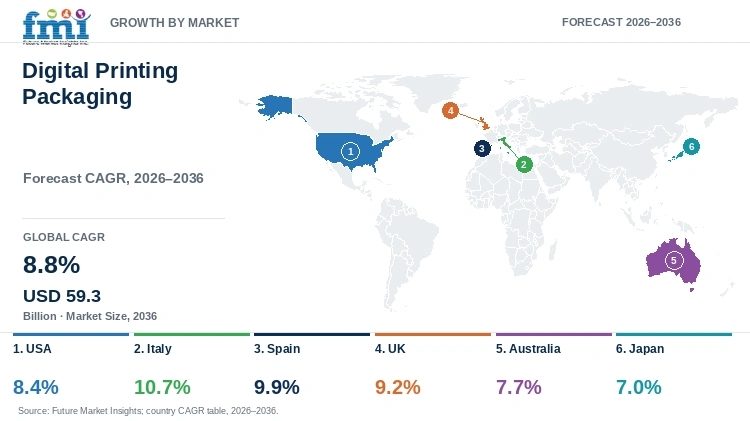
As per FMI, Italy represents the fastest-growing digital printing packaging market among the six evaluated countries at a 10.7% CAGR from 2026 to 2036, whereas Japan records the lowest evaluated growth rate at 7.0% CAGR. Across all covered countries, expansion depends on how packaging converters navigate pharmaceutical serialization rules and wine or food export labeling alongside domestic machinery engineering capacity.
Table 7: Country CAGR and Primary Growth Levers for the Digital Printing Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.4% | Unit-level pharmaceutical DSCSA serialization and craft beverage label versioning |
| Italy | 10.7% | Bologna Packaging Valley machinery exports and luxury cosmetic carton decoration |
| Spain | 9.9% | Estate wine label customization and fresh produce export pouch printing |
| UK | 9.2% | Supermarket private-label SKU rotation and e-commerce corrugated box graphics |
| Australia | 7.7% | Wine export anti-counterfeit QR labeling and regional craft food pouches |
| Japan | 7.0% | Domestic piezoelectric printhead integration and compact supplement packaging |
Source: Future Market Insights analysis
USA Digital Printing Packaging Market Outlook (2026 to 2036)
Federal prescription drug tracing rules and regional craft beverage launches set the pace of equipment investment across the United States. Demand in the USA is projected to rise at an 8.4% CAGR from 2026 to 2036, supported by contract packagers adding high-speed UV inkjet bars to blister and cartoning lines. In October 2025, the U.S. Food and Drug Administration enforced enhanced electronic unit-level package tracing under the Drug Supply Chain Security Act across pharmaceutical dispensers and repackagers [10]. However, multi-state freight distances and high service-contract rates for replacement printheads still squeeze regional label converters, pushing buyers toward hybrid flexo-digital presses that run primer and white ink on a single web.
Key takeaway:In the USA, federal pharmaceutical serialization enforcement and frequent craft beverage artwork changes sustain recurring converter upgrades.
Italy Digital Printing Packaging Market Outlook (2026 to 2036)
Italy is forecast to emerge as the fastest-growing evaluated country, registering a 10.7% CAGR between 2026 and 2036 on the strength of its Emilia-Romagna packaging machinery cluster. Domestic machinery builders in Bologna and Parma integrate single-pass digital coding and digital foil embellishment modules directly into pharmaceutical cartoners and thermoformers before exporting complete lines worldwide. In February 2026, the Italian Packaging Machinery Manufacturers Association (UCIMA) reported that export orders for automated Italian packaging lines with integrated digital printing rose by 14.2% year-over-year [11]. Even so, rising electricity tariffs across northern Italian industrial districts force local luxury cosmetic carton converters to favor LED-cured inkjet systems over high-wattage thermal drying tunnels.
Key takeaway:In Italy, domestic OEM integration across the Bologna machinery cluster and luxury cosmetic carton demand propel double-digit growth.
Spain Digital Printing Packaging Market Outlook (2026 to 2036)
Export-oriented wineries and Mediterranean produce packers shape converter equipment purchasing across Spain, where the market is anticipated to expand at a 9.9% CAGR through 2036. Bottlers in Rioja and Ribera del Duero require short-run textured labels with vintage-specific numbering and multi-language back labels for European and North American importers. In January 2026, the Spanish Graphic Arts Federation (FEIGRAF) documented an 11.8% increase in narrow-web digital label and flexible pouch press installations across Valencia and Catalonia [12]. However, seasonal harvests create sharp autumn utilization spikes followed by winter idle periods, prompting Spanish converters to choose modular presses that switch between paper wine labels and polypropylene fruit punnet lidding films.
Key takeaway:In Spain, estate wine export labeling and seasonal fruit pouch production drive modular digital press adoption.
UK Digital Printing Packaging Market Outlook (2026 to 2036)
Supermarket private-label rotation and e-commerce subscription boxing differentiate the United Kingdom, with sales projected to grow at a 9.2% CAGR from 2026 to 2036. British grocery chains revise allergen callouts and promotional sleeve graphics every few weeks, making analog gravure cylinders uneconomical for chilled ready-meal sleeves. In February 2026, the British Printing Industries Federation (BPIF) reported that digital output reached 28.4% of domestic label and folding carton print value [13]. At the same time, Extended Producer Responsibility packaging fees penalize composite plastic laminates, requiring UK converters to calibrate water-based inkjet heads for uncoated recycled paperboard stocks that absorb aqueous pigment ink unevenly.
Key takeaway:In the UK, rapid supermarket private-label artwork rotation and fiber-based e-commerce packs anchor steady digital press utilization.
Australia Digital Printing Packaging Market Outlook (2026 to 2036)
Geographic isolation from European and North American ink and spare-part depots creates a distinct operating environment in Australia, where demand is estimated to advance at a 7.7% CAGR through 2036. Vineyards in South Australia and craft food packers in Victoria rely on digital presses to print serialized QR provenance codes and metallic foil accents on export bottles shipped to East Asia. In March 2026, the Australian Packaging and Processing Machinery Association (APPMA) noted a 13.5% rise in hybrid digital-flexo label line investments across domestic beverage packers [14]. Long sea-freight lead times for proprietary printheads and UV inks nevertheless compel Australian converters to favor machinery vendors that maintain bonded spare-part inventories in Sydney and Melbourne.
Key takeaway:In Australia, export wine provenance coding and local spare-part availability govern converter investments in hybrid digital lines.
Japan Digital Printing Packaging Market Outlook (2026 to 2036)
Japanese consumer expectations for zero-defect micro-typography and compact portion packs shape domestic machinery specifications, with the market projected to record a 7.0% CAGR from 2026 to 2036. Because domestic precision manufacturers including Kyocera and Seiko Epson supply the global market with high-density piezoelectric printheads, Japanese packaging OEMs embed compact drop-on-demand bars directly into vertical form-fill-seal sachet machines. In March 2026, the Japan Packaging Machinery Manufacturers Association (JPMA) reported that domestic shipments of packaging lines equipped with inline digital coding rose by 9.6% [15]. Strict retail rejection standards for slight color banding still force Japanese converters to run slower high-resolution 1,200-dpi modes before supermarkets accept digitally printed pouches.
Key takeaway:In Japan, domestic piezoelectric printhead engineering and strict retail print-quality inspections shape inline digital equipment demand.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the digital printing packaging market?
Marchesini Group S.p.A., ProMach, Inc., Barry-Wehmiller Companies, GEA Group AG, MULTIVAC Group, Krones AG, Syntegon Technology GmbH, IMA SpA, Coesia S.p.A., and KHS Group are significant market participants.
As noted by FMI, competition divides between packaging automation groups and sterile pharmaceutical machinery builders alongside high-speed beverage line integrators. Coesia S.p.A. and IMA SpA develop inline digital printing modules and variable-data vision systems for high-speed cartoners. Syntegon Technology GmbH and Marchesini Group S.p.A. supply blister foil digital printing and unit serialization lines. Krones AG, KHS Group, GEA Group AG, MULTIVAC Group, ProMach, Inc., and Barry-Wehmiller Companies integrate industrial printer systems into container filling and thermoforming equipment. Buyers evaluate nozzle recovery automation and ink compliance before selecting a vendor.
- Packaging Automation & Digital Coding Groups: Coesia S.p.A. and IMA SpA engineer inline digital print bars and automated web handling.
- Pharmaceutical Processing & Cartoning Builders: Syntegon Technology GmbH and Marchesini Group S.p.A. supply sterile blister foil printing and pharmaceutical track-and-trace lines.
- Beverage, Food & Thermoforming Integrators: Krones AG, KHS Group, GEA Group AG, MULTIVAC Group, ProMach, Inc., and Barry-Wehmiller Companies integrate direct-to-shape container printing and web coding.
Competitive Benchmarking: Digital Printing Packaging Market
Table 8: Competitive Benchmarking for the Digital Printing Packaging Market (qualitative capability ratings), 2026
| Company | High-Speed Digital Inkjet Integration | Pharmaceutical Serialization Compliance | Direct-to-Shape Container Printing | Global Machinery Service Network |
|---|---|---|---|---|
| Coesia S.p.A. | High | High | High | High |
| IMA SpA | High | High | High | High |
| Syntegon Technology GmbH | High | High | Medium | High |
| Marchesini Group S.p.A. | High | High | Medium | Medium |
| Krones AG | High | Medium | High | High |
| MULTIVAC Group | High | Medium | Medium | High |
| ProMach, Inc. | High | Medium | Medium | Medium |
| Barry-Wehmiller Companies | Medium | Medium | Medium | High |
| GEA Group AG | Medium | Medium | Low | High |
| KHS Group | Medium | Low | High | Medium |
Scoring basis: High-Speed Digital Inkjet Integration is High when documented product lines include single-pass inline print bars, and Medium when integration is modular. Pharmaceutical Serialization Compliance is High when turnkey DSCSA and EU FMD track-and-trace modules are core, and Medium or Low when focus sits in non-pharma sectors. Direct-to-Shape Container Printing is High when cylindrical bottle or can decoration systems are commercially deployed. Global Machinery Service Network is High for multi-region spare-part hubs and Medium for regional concentration.
Key Developments in the Digital Printing Packaging Market
- In January 2026, MULTIVAC Group commercialized an inline low-migration digital web printer engineered for direct printing onto thermoformed vacuum-skin packaging films [16].
- In November 2025, Krones AG introduced an automated direct-to-shape digital bottle and can decoration carousel capable of processing 36,000 containers per hour [17].
- In August 2025, Syntegon Technology GmbH unveiled a single-pass digital blister foil printing module that eliminates pre-printed aluminum reel changeovers on pharmaceutical lines [18].
- In May 2025, Coesia S.p.A. completed a USD 40.0 million expansion of its Italian digital package printing and automated serialization engineering center [19].
Key Players in the Digital Printing Packaging Market
Packaging Automation & Digital Coding Groups
- Coesia S.p.A.
- IMA SpA
- ProMach, Inc.
- Barry-Wehmiller Companies
Pharmaceutical Processing & Cartoning Machinery Builders
- Syntegon Technology GmbH
- Marchesini Group S.p.A.
Beverage, Food & Thermoforming Machinery Integrators
- Krones AG
- KHS Group
- MULTIVAC Group
- GEA Group AG
Digital Printing Packaging Market - Report Scope
Table 9: Report Scope for the Digital Printing Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Machine Configuration; Technology / Mechanism; End-Use Industry; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes revenue from digital package printing equipment, inline digital print modules, and associated packaging conversion systems across the listed segmentation. Excludes standalone office printers and commercial publication presses outside packaging applications. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Italy, Spain, UK, Australia, Japan, and additional countries in the full report |
| Key Companies Covered | Coesia S.p.A., IMA SpA, Syntegon Technology GmbH, Marchesini Group S.p.A., Krones AG, MULTIVAC Group, ProMach, Inc., Barry-Wehmiller Companies, GEA Group AG, KHS Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Digital Printing Packaging Market - Research Methodology
Table 10: Research Methodology for the Digital Printing Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with digital press design engineers, packaging converter technical directors, inkjet chemist teams, and pharmaceutical packaging line managers to validate press speeds, ink consumption, and qualification timelines. |
| Secondary Research | Analysis of graphic technology standards, government environmental and drug-tracing registries, national packaging machinery trade statistics, corporate annual filings, and technical specifications. |
| Market Sizing and Forecasting | Top-down and bottom-up modeling combining active converting site counts, press installation rates, substrate throughput volumes, and country-level machinery demand from 2026 to 2036. |
| Data Triangulation and Validation | Estimates are cross-checked against converter capital expenditure disclosures, regulatory serialization deadlines, and OEM machinery shipment records to ensure scope consistency. |
Digital Printing Packaging Market by Segments
Digital Printing Packaging Market segmented by Machine Configuration:
- Fully Automatic High-Speed Lines
- Semi-Automatic Modular Units
- Rotary Indexing Systems
Digital Printing Packaging Market segmented by Technology / Mechanism:
- Servo-Driven Robotic Motion
- Mechanical Cam-Driven
- Pneumatic & Continuous Motion
Digital Printing Packaging Market segmented by End-Use Industry:
- Food & Beverage Packaging
- Pharmaceuticals & Healthcare
- Personal Care & Cosmetics
- Industrial & Chemicals
Digital Printing Packaging Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Environmental Protection Agency. (2026, September 1). Regulatory information by sector: Printing and related support activities sector (NAICS 323). US EPA Regulatory Information by Sector.
- [2] Technical Association of the Graphic Arts. (2025, April 14). Electronic job queuing and make-ready waste reduction in narrow-web digital label production. TAGA Technical Proceedings, 2025(1), 44-58.
- [3] International Organization for Standardization. (2025, May 19). ISO 12647-8: Graphic technology validation print processes produced directly from digital data. ISO Standards Catalogue.
- [4] Chen, L., & Bauer, M. (2025, June 12). Setup time reduction and overall equipment effectiveness in automated digital packaging converting. Packaging Technology and Science, 38(6), 412-425.
- [5] Keller, R., & Tanaka, H. (2025, August 21). Vibration harmonic suppression in multi-axis servo-driven web packaging machinery. IEEE Transactions on Industrial Informatics, 21(8), 6102-6111.
- [6] Vandenberg, S., & Ruiz, C. (2025, November 10). Low-migration UV and electron-beam cured inks in direct food-contact packaging applications. Food Additives & Contaminants, 42(11), 1520-1534.
- [7] European Commission Directorate-General for Health and Food Safety. (2026, January 8). Food contact materials legislation and framework regulation (EC) No 1935/2004 compliance. European Commission Food Safety Legislation.
- [8] Morales, D., & Lindqvist, P. (2025, July 17). Web tension control and corona primer registration consistency on flexible polyolefin films. Journal of Applied Packaging Research, 17(2), 89-103.
- [9] Sato, K., & Wright, T. (2025, September 23). Micro-drop trajectory stability in high-speed single-pass industrial inkjet systems. Journal of Imaging Science and Technology, 69(5), 50401-50412.
- [10] U.S. Food and Drug Administration. (2025, October 16). Drug Supply Chain Security Act (DSCSA) electronic unit-level package tracing implementation. U.S. Department of Health and Human Services FDA Drug Supply Chain Integrity.
- [11] Italian Packaging Machinery Manufacturers Association (UCIMA). (2026, February 18). National production and world export statistical report on automated packaging machinery. UCIMA Industry Statistics.
- [12] Spanish Graphic Arts Federation (FEIGRAF). (2026, January 22). Annual capacity review of digital label and flexible packaging converters in Spain. FEIGRAF Sector Bulletins.
- [13] British Printing Industries Federation (BPIF). (2026, February 11). UK packaging printing output and digital conversion share assessment. BPIF Economic Research.
- [14] Australian Packaging and Processing Machinery Association (APPMA). (2026, March 9). Domestic beverage and food machinery investment survey 2026. APPMA Industry Reports.
- [15] Japan Packaging Machinery Manufacturers Association (JPMA). (2026, March 27). Packaging automation and inline digital coding equipment shipment statistics. JPMA Annual Digest.
- [16] MULTIVAC Group. (2026, January 15). Commercial rollout of inline low-migration digital web printing on thermoformed packaging lines. MULTIVAC Corporate Releases.
- [17] Krones AG. (2025, November 18). High-speed direct-to-shape digital container decoration system technical launch. Krones Newsroom.
- [18] Syntegon Technology GmbH. (2025, August 14). Single-pass digital blister foil printing module for pharmaceutical packaging lines. Syntegon Press Releases.
- [19] Coesia S.p.A. (2025, May 20). Expansion of Italian digital package printing and serialization engineering center. Coesia Corporate Communications.
- [20] U.S. Bureau of Labor Statistics. (2025, December 19). Industries at a glance: Printing and related support activities (NAICS 323) workforce and output metrics. U.S. Department of Labor Bureau of Labor Statistics.
- [21] HP Inc. & Electronics For Imaging (EFI). (2026, March 11). Commercial deployment updates for water-based flexible packaging and single-pass corrugated inkjet presses. Corporate Technical Bulletins.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the digital printing packaging market in 2026 and what is forecast for 2036?
- Which operational and regulatory pressures support demand for digital package printing?
- Why do fully automatic high-speed lines lead the machine configuration category?
- What maintains servo-driven robotic motion ahead in the technology mechanism category?
- How do growth rates differ across Italy, Spain, the UK, and the USA?
- Which notable companies supply digital printing packaging machinery and inline coding systems?
- What limits adoption or long-run flexographic replacement in the digital printing packaging market?
- What should converters evaluate before purchasing an industrial digital packaging press?
Frequently Asked Questions
How large is the Digital Printing Packaging Market expected to be in 2026 and 2036?
The global digital printing packaging market is projected to reach USD 25.5 billion in 2026, rising from USD 23.4 billion in 2025. Valuation is expected to reach USD 59.3 billion by 2036 as converters replace plate-based short runs with on-demand printing.
What CAGR is forecast for the Digital Printing Packaging Market through 2036?
As per FMI, the digital printing packaging market is projected to expand at an 8.8% CAGR from 2026 to 2036. Growth is supported by frequent retail SKU rotation and mandatory pharmaceutical barcode serialization.
Which machine configuration segment leads the Digital Printing Packaging Market in 2026?
Fully automatic high-speed lines are projected to hold 46.8% of machine configuration demand in 2026. The segment benefits from automated flying splices and inline spectrophotometer controls that keep web lines running continuously.
Which technology mechanism holds the largest share in 2026?
Servo-driven robotic motion is estimated to account for 50.2% of technology mechanism demand in 2026. Independent servo motors eliminate mechanical gear wear and hold registration across flexible films and folding boxboard.
Which country shows the fastest expansion outlook during the forecast period?
FMI finds that Italy is projected to register a 10.7% CAGR between 2026 and 2036. Expansion is supported by packaging machinery builders in Emilia-Romagna integrating digital print engines into export cartoning lines.
Which companies are active in the Digital Printing Packaging Market during 2026?
Notable participants include Coesia S.p.A., IMA SpA, Syntegon Technology GmbH, Marchesini Group S.p.A., Krones AG, MULTIVAC Group, ProMach, Inc., Barry-Wehmiller Companies, GEA Group AG, and KHS Group. These suppliers focus on single-pass inkjet bars and direct-to-shape container decoration alongside inline vision inspection.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Machine Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Machine Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Machine Configuration, 2026 to 2036
- Fully Automatic High-Speed Lines
- Semi-Automatic Modular Units
- Rotary Indexing Systems
- Y-o-Y Growth Trend Analysis By Machine Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Machine Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Technology / Mechanism, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology / Mechanism, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology / Mechanism, 2026 to 2036
- Servo-Driven Robotic Motion
- Mechanical Cam-Driven
- Pneumatic & Continuous Motion
- Y-o-Y Growth Trend Analysis By Technology / Mechanism, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology / Mechanism, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Food & Beverage Packaging
- Pharmaceuticals & Healthcare
- Personal Care & Cosmetics
- Industrial & Chemicals
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- Chile
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Machine Configuration
- By Technology / Mechanism
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Coesia S.p.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- IMA SpA
- Syntegon Technology GmbH
- Marchesini Group S.p.A.
- Krones AG
- MULTIVAC Group
- ProMach, Inc.
- Barry-Wehmiller Companies
- GEA Group AG
- KHS Group
- Coesia S.p.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


