
- Market Size (2026)
- USD 1.2 Bn
- Forecast (2036)
- USD 3.8 Bn
- CAGR (2026 to 2036)
- 12.4%
How big is Digital Pathology Market in 2026?
Starting from USD 1.1 billion in 2025, the digital pathology market valuation advanced to USD 1.2 billion in 2026, with projections pointing toward USD 3.8 billion by 2036 at a CAGR of 12.4%.
The global digital pathology market was valued at USD 1.1 billion in 2025 and is estimated to reach USD 1.2 billion in 2026. The market is projected to reach USD 3.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 12.4% between 2026 and 2036. Whole slide imaging scanners are projected to hold an estimated 48.0% share of 2026 component demand, since reference laboratories must digitize physical glass slides before deploying image management or computational triage tools. FMI's clinical workflow audit finds that demand for digital pathology is supported by biopsy turnaround economics, given that sub-minute slide digitization allows one subspecialty pathologist to sign out cancer cases across multiple hospital sites without courier delays [1].
That workflow conversion separates the sector from broader anatomic pathology services expanding at a 5.1% CAGR, where routine reagent consumption tracks surgical biopsy volume while digital equipment orders follow multi-site hospital capital upgrades. Suppliers are consolidating hardware and software platforms to capture those enterprise contracts, as Agilent Technologies signed a definitive agreement valued at up to USD 270 million in October 2026 to acquire Proscia and deploy its Concentriq software across more than 4,000 laboratories [2]. Hospital laboratory directors renew scanner and software contracts when vendor-agnostic platforms cut primary diagnosis sign-out times and integrate directly with laboratory information systems through 2036.
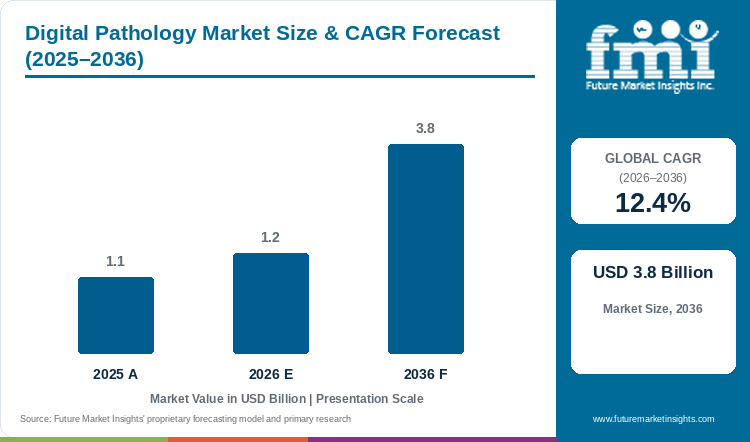
Key Market Trends & Insights
- By component solution: Whole Slide Imaging Scanners are projected to hold an estimated 48.0% share in 2026 since continuous rack-fed optical scanning remains the foundational hardware purchase for laboratory digitization.
- By application domain: Oncology Biopsy Diagnosis is anticipated to represent 56.0% in 2026 driven by mandatory immunohistochemical and companion diagnostic scoring across solid tumor biopsies.
- By end-user: Diagnostic Pathology Laboratories are expected to account for 62.0% in 2026 given that centralized commercial laboratories process multi-hospital slide volumes on round-the-clock shifts.
- By scanning throughput: High-Throughput Automated Systems are forecast to secure 58.0% in 2026 owing to multi-hundred-slide loader capacity that eliminates manual technologist reloading.
- By deployment mode: Cloud-Based and Hybrid Platforms are estimated to command 54.0% in 2026 through elastic petabyte archiving and cross-hospital teleconsultation access.
Regional Highlights
- Top national expansion: Australia leads national growth projections at a 13.5% CAGR through 2036 under federal Medicare pathology modernization and regional telepathology network investments.
- Broader country progression: South Korea tracks at a 13.2% CAGR ahead of the USA at 12.9% and Canada at 12.6%, while the UK advances at 12.3% and Japan records an 11.4% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Digital Pathology Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.1 billion |
| Estimated Market Size in 2026 | USD 1.2 billion |
| Projected Market Size by 2036 | USD 3.8 billion |
| CAGR, 2026 to 2036 | 12.4% |
| Added Revenue, 2026 to 2036 | USD 2.6 billion |
Reference pathology laboratories and academic cancer centers face acute shortages of board-certified histopathologists while complex multi-stain oncology biopsy volumes rise each year. When departments rely exclusively on manual brightfield microscopes and physical slide couriers, second-opinion consultations take days and delay targeted therapy initiation. In May 2026, the U.S. Food and Drug Administration released its HistoGen histopathology cell nuclei generation tool within the Regulatory Science Tools Catalog to help developers validate whole-slide image algorithms when annotated clinical tissue datasets are scarce [3]. Consequently, laboratory medical directors pair FDA-cleared slide scanners with standardized image management software to accelerate primary sign-out and quantitative biomarker scoring.
Digitized Slide Volume and Storage Sizing
Table 2: Digitized Slide Volume and Storage Sizing for the Digital Pathology Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.1 | 1.2 | 3.8 |
| Digitized clinical & research slides (million slides/year) | 185.0 to 210.0 | 215.0 to 245.0 | 740.0 to 830.0 |
| Active enterprise cloud & PACS archive volume (petabytes) | 110.0 to 135.0 | 130.0 to 160.0 | 520.0 to 610.0 |
| Average software & storage spend per digitized slide (USD) | 1.45 to 1.80 | 1.50 to 1.85 | 1.75 to 2.15 |
Conversion of a high-volume histopathology laboratory from physical glass cabinets to full digital primary diagnosis requires predictable reimbursement codes and tiered cloud storage economics. As documented by the Digital Pathology Association in April 2026, expanded Category III and clinical reimbursement pathways are directly lowering the payback period for US laboratories billing digitized slide preparation [4].
Clinical Laboratory & Scanner Fleet Sizing
Table 3: Clinical Laboratory and Scanner Fleet Indicators for the Digital Pathology Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Installed clinical & research WSI scanner base (units) | 14,200 | 16,100 | 46,500 |
| Annual spend per accredited clinical lab (USD thousand) | 78.0 to 92.0 | 85.0 to 102.0 | 195.0 to 235.0 |
| Primary digital diagnosis adoption in oncology labs (%) | 28.0% to 32.0% | 31.0% to 36.0% | 68.0% to 75.0% |
| AI-assisted slide triage & biomarker scoring share (%) | 18.0% to 22.0% | 21.0% to 26.0% | 52.0% to 59.0% |
Table 4: Institutional Pathology & Channel Reference Indicators for the Digital Pathology Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.2 billion | 2026 global revenue baseline |
| Laboratories & clinics using enterprise DP software | 4,000+ facilities | Proscia / Agilent Oct 2026 clinical & life-science footprint |
| Whole Slide Imaging Scanners revenue, 2026 | USD 0.58 billion | 48.0% component solution allocation |
| Diagnostic Pathology Laboratories revenue, 2026 | USD 0.74 billion | 62.0% end-user channel allocation |
Pathology networks evaluating enterprise scanner tenders prioritize interoperability between whole-slide scanners, picture archiving systems, and third-party artificial intelligence modules. A national service consultation initiated by the Royal College of Pathologists in March 2026 confirmed that UK histopathology departments rank IT storage infrastructure and cross-trust governance as primary determinants of full digital workflow readiness [5].
Analyst Perspective
"Clinical laboratories no longer purchase whole-slide scanners as isolated research cameras; they procure end-to-end diagnostic throughput that lets fewer pathologists clear rising oncology biopsy backlogs. Vendors that combine rapid continuous-load scanning with open DICOM cloud software and pre-validated companion diagnostic algorithms are capturing multi-year health-system enterprise contracts."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the Digital Pathology Market segmented?
The digital pathology market is segmented by component solution, application domain, end-user, scanning throughput, and deployment mode. In 2026, Whole Slide Imaging Scanners are projected at 48.0%, Oncology Biopsy Diagnosis at 56.0%, Diagnostic Pathology Laboratories at 62.0%, High-Throughput Automated Systems at 58.0%, and Cloud-Based and Hybrid Platforms at 54.0%.
By component solution: Whole Slide Imaging Scanners, Pathology Image Management Software, AI-Powered Diagnostic Algorithms, and Storage and Cloud Archiving Infrastructure.
By application domain: Oncology Biopsy Diagnosis, Drug Discovery and Clinical Trials, Academic Research and Pathology Education, and Hematopathology and Immunology.
By end-user: Diagnostic Pathology Laboratories, Academic Medical Centers and Hospitals, Pharmaceutical and Contract Research Organizations, and Government and Reference Research Institutes.
By scanning throughput: High-Throughput Automated Systems, Medium-Throughput Benchtop Scanners, Low-Throughput Compact Units, and Modular Multi-Slide Platforms.
By deployment mode: Cloud-Based and Hybrid Platforms, On-Premises Server Installations, Vendor-Hosted Enterprise Clouds, and Federated Multi-Site Networks.
Why do Whole Slide Imaging Scanners lead the component solution category?
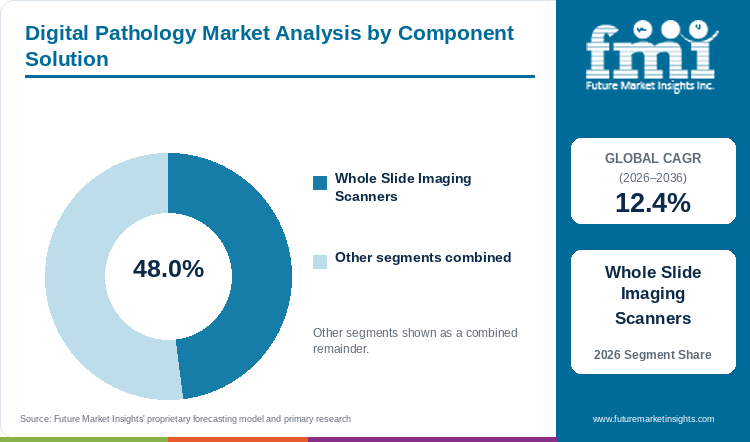
Whole Slide Imaging Scanners hold an estimated 48.0% of component solution demand in 2026, anchored by high-throughput optical digitization across reference laboratories.
Table 5: Component Solution Share for the Digital Pathology Market (percentage share), 2026
| Component Solution | Share (2026) |
|---|---|
| Whole Slide Imaging Scanners | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining component solution categories account for the balance of 2026 global digital pathology demand.
Table 6: Component Solution Leadership and Market Growth for the Digital Pathology Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.4% |
| Leading Segment | Whole Slide Imaging Scanners |
Whole Slide Imaging Scanners serve as the mandatory hardware entry point for every hospital and commercial reference laboratory converting from optical microscopy to digital sign-out. High-speed line-scan and time-delay integration sensors capture crisp Z-stack tissue planes across hematoxylin-and-eosin and immunohistochemical slides without manual focus intervention. Laboratory procurement teams upgrading cellular pathology workflows favor continuous-load scanners that process hundreds of barcoded slides overnight, although high upfront capital prices per scanner still require multi-year volume justification across smaller community hospitals.
- Within the component solution segment, Whole Slide Imaging Scanners are projected to account for a leading 48.0% share in 2026, supported by multi-unit hardware refreshes across reference laboratories.
- Leica Biosystems secured multiple FDA 510(k) clearances in August 2026 expanding its clinical Aperio scanner and viewing portfolio to accelerate primary cancer diagnosis across US laboratories [6].
What sustains Oncology Biopsy Diagnosis leadership in the application domain segment?
Oncology Biopsy Diagnosis represents an estimated 56.0% of the application domain category in 2026, supported by companion diagnostic scoring and remote tumor boards.
Higher solid-tumor biopsy volumes and mandatory companion diagnostic scoring for targeted therapies anchor commercial adoption inside the Oncology Biopsy Diagnosis category. Pathologists grading breast and lung or prostate and gastrointestinal biopsies require exact quantitative measurement of PD-L1 and HER2-low expression across whole tissue sections. Software rendering advancements support this clinical shift, as Landvater and Balis demonstrated in April 2025 that the Iris rendering engine buffers and streams gigapixel pathology images at 1.36 gigabytes per second for rapid tumor margin review [7]. Strict regulatory validation requirements for clinical oncology algorithms remain a primary operational hurdle slowing automated sign-out.
- In 2026, Oncology Biopsy Diagnosis is anticipated to capture 56.0% of global application domain demand, driven by precision cancer staging and companion biomarker quantification.
- Segment growth is projected to accelerate through 2036 as hospital tumor boards integrate precision cancer imaging platforms with multiplex digital histopathology to guide perioperative immunotherapy selection.
How do Diagnostic Pathology Laboratories lead the end-user category?
Diagnostic Pathology Laboratories account for an estimated 62.0% of end-user demand in 2026, driven by centralized multi-hospital biopsy processing.
Commercial and hospital-affiliated Diagnostic Pathology Laboratories process the vast majority of routine surgical biopsies, cytology smears, and dermatopathology specimens under strict 24-to-48-hour turnaround contracts. Centralized reference laboratories deploy banks of high-capacity scanners linked to digital telepathology networks so subspecialty pathologists can review complex cases remotely without shipping fragile glass slides between regional hubs. Legacy laboratory information system integration with new image management software remains the main technical bottleneck during multi-site rollouts.
- By end-user, demand from Diagnostic Pathology Laboratories is estimated to reach 62.0% of total category share in 2026 as commercial testing networks centralize remote specialist sign-out.
- A February 2026 study by Matzko in Frontiers in Digital Health documented how regulatory-approved whole-slide AI workflows reduce interobserver variability in PD-L1 and CAMELYON cancer histopathology across clinical laboratories [8].
Why do High-Throughput Automated Systems lead the scanning throughput category?
High-Throughput Automated Systems secure an estimated 58.0% of scanning throughput volume in 2026, supported by continuous overnight slide-rack loading.
Large histology laboratories generating more than 1,000 stained slides per day cannot afford technologist bottlenecks caused by low-capacity manual slide loaders. High-Throughput Automated Systems holding 240 to 1,000 slides per run feature continuous rack loading, automated barcode verification, and real-time tissue detection that pairs directly with tissue diagnostics instruments. Clinical adoption is reinforced by hospital deployments, as Hamamatsu Photonics documented in August 2025 that Sorlandet Hospital achieved 100% digital histology diagnostics by pairing NanoZoomer S60v2MD and S20MD scanners with its picture archiving system [9].
- Strong repeat ordering across reference hubs places High-Throughput Automated Systems on course to hold an estimated 58.0% share of the scanning throughput category in 2026.
- While benchtop units serve frozen-section operating suites, high-capacity continuous loaders are forecast to retain volume dominance as laboratories automate overnight batch scanning.
What gives Cloud-Based and Hybrid Platforms the leading position in deployment mode?
Cloud-Based and Hybrid Platforms command an estimated 54.0% of deployment mode share in 2026, anchored by elastic petabyte storage and telepathology access.
Each digitized biopsy slide generates between 0.5 and 2.0 gigabytes of pyramidal image data, rapidly exhausting local on-premises hospital server racks within a single budget cycle. Cloud-Based and Hybrid Platforms allow laboratory IT directors to keep active 30-day diagnostic cases on fast local cache while archiving multi-year slide repositories in elastic cloud storage compatible with pathology imaging systems. Cybersecurity governance and cross-border patient data residency laws remain the principal compliance hurdles evaluated during hospital procurement.
- Cloud-Based and Hybrid Platforms are predicted to secure 54.0% of deployment mode demand in 2026, supported by lower capital storage expenditure and instant multi-site case sharing.
- Philips expanded its digital pathology portfolio in March 2026 by launching the cloud-enabled IntelliSite Pathology Solution on HealthSuite powered by Amazon Web Services for scalable clinical archiving [10].
What are the drivers, restraints, and opportunities in the Digital Pathology Market?
In the digital pathology market, pathologist workforce shortages and rising cancer biopsy complexity are projected to drive adoption while high scanner and storage capital costs restrain smaller labs and AI companion diagnostics create new software revenue streams.
- Driver: Widening global shortages of board-certified pathologists and rising cancer biopsy complexity compel laboratories to adopt automated whole-slide scanning and remote sign-out workflows.
- Restraint: High upfront capital expenditure for multi-scanner fleets and petabyte-scale image archiving infrastructure restricts rapid adoption across smaller community hospitals.
- Opportunity: Clinical deployment of artificial intelligence companion diagnostic algorithms and standardized DICOM interoperability creates recurring software licensing revenue across biopharma and clinical labs.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Pathology departments across major healthcare systems are confronting an expanding gap between retiring histopathologists and escalating oncology biopsy workloads that require multi-marker immunohistochemical grading. When hospitals digitize glass slides immediately after coverslipping, cases route automatically to subspecialty pathologists across regional networks rather than waiting in physical mailrooms. Integration of immunohistochemistry staining assays with digital image management eliminates manual slide sorting and shortens diagnostic turnaround times for cancer patients. Empirical findings published by Baviello et al. in Life in August 2026 substantiate this operational shift, demonstrating that convolutional and deep-learning whole-slide architectures objectively quantify sub-visual morphological signatures and protein expression across billions of pixels [11].
Risk Assessment of the Digital Pathology Market: Operational and Capital Friction
Capital budget constraints and diagnostic workflow variability represent the primary operational barriers slowing full digital conversion across community and mid-sized hospital laboratories. Conversion from optical microscopes requires not only purchasing multi-hundred-thousand-dollar scanners but also funding redundant petabyte storage, high-luminance medical displays, and bidirectional anatomic pathology track and trace interfaces. Furthermore, human visual interpretation of gigapixel monitors introduces ergonomic and consistency challenges when staff transition from glass eyepieces. In October 2025, Thai et al. introduced the PathoGaze1.0 dataset across 19 pathologists interpreting 397 whole-slide images and reported that baseline diagnostic accuracy on gigapixel images averages roughly 70% without standardized viewport navigation and decision support [12].
Commercial Opportunity Analysis: AI Companion Diagnostics and Cloud Interoperability
Software developers and scanner manufacturers are generating high-margin recurring revenue by embedding regulatory-cleared artificial intelligence algorithms directly into clinical image management workspaces. Pharmaceutical sponsors running precision oncology trials actively contract digital pathology vendors to quantify novel tissue biomarkers in coordination with oncology molecular diagnostics. Clinical governance frameworks are maturing rapidly to support hospital purchasing of these tools. In April 2026, the Royal College of Pathologists announced an initiative to establish an open register of artificial intelligence products for digital pathology services to give hospital procurement teams transparent validation benchmarks [13].
Digital Pathology Market by Country (2026 to 2036)
FMI country modeling indicates that Australia leads digital pathology expansion at a 13.5% CAGR through 2036, while South Korea advances at 13.2% and the USA tracks at 12.9% ahead of Japan at an 11.4% CAGR. National adoption rates depend on public reimbursement coding for digitized slides, national telepathology procurement frameworks, and regulatory clearances for primary digital diagnosis.
Table 7: Country CAGR and Primary Growth Levers for the Digital Pathology Market (CAGR percentage and operational drivers), 2026 to 2036
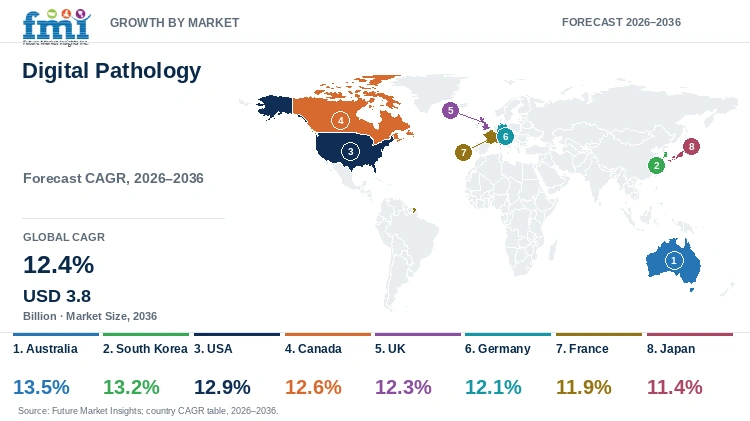
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 13.5% | Medicare pathology modernization and interstate regional telepathology networks |
| South Korea | 13.2% | Tertiary hospital glassless histology conversion and domestic AI software integration |
| USA | 12.9% | FDA 510(k) primary diagnosis clearances and Category III CPT billing expansion |
| Canada | 12.6% | Provincial multi-hospital telepathology networks and CCTG centralized digital slide repositories |
| UK | 12.3% | NHS 5-lot Digital Pathology Framework procurement and trust consortium consolidation |
| Germany | 12.1% | Hospital Future Act funding and GOA/EBM pathology reimbursement across MVZ labs |
| France | 11.9% | Private ACP laboratory consolidation and IVDR-certified CaloPix 6 diagnostic rollouts |
| Japan | 11.4% | High aging-population cancer biopsy volume and Japanese Society of Digital Pathology automation |
Source: Future Market Insights analysis
Australia Digital Pathology Market Outlook (2026 to 2036)
Demand for digital pathology in Australia is projected to expand at a leading 13.5% CAGR between 2026 and 2036 as state pathology networks and private laboratory groups link metropolitan specialists with regional hospitals. What distinguishes Australia from other Asia-Pacific markets is the vast geographic distance between rural biopsy collection clinics and specialist histopathologists concentrated in Sydney, Melbourne, and Brisbane. Official figures published by the Australian Department of Health and Aged Care in August 2026 confirm sustained national testing volume in its Medicare Quarterly Statistics Total Pathology Summary for the June quarter of 2025-26 [14]. Accredited laboratories consequently deploy high-throughput scanners and cloud telepathology viewers to eliminate interstate slide air-freight delays.
Key takeaway: In Australia, interstate telepathology requirements and high Medicare pathology volumes are projected to drive leading adoption of cloud-connected whole-slide scanners.
South Korea Digital Pathology Market Outlook (2026 to 2036)
South Korea's tertiary university hospitals in Seoul and Gyeonggi are rapidly converting oncology histopathology departments into fully paperless and glassless diagnostic centers. Consequently, national digital pathology adoption is anticipated to advance at a 13.2% CAGR through 2036, outpacing Western European averages owing to dense fiber-optic hospital infrastructure and domestic artificial intelligence software development. Technical research published by Omoush et al. in the Journal of Molecular Pathology in January 2026 confirms that high-throughput whole-slide imaging paired with deep-learning algorithms accelerates quantitative image analysis and laboratory workflow standardization [15]. High local server integration costs across smaller regional hospitals remain the primary factor moderating rural uptake.
Key takeaway: In South Korea, tertiary hospital digitization and domestic computational pathology software deployment are anticipated to sustain rapid 13.2% annual growth.
USA Digital Pathology Market Outlook (2026 to 2036)
Commercial digital pathology expansion in the USA is forecast to progress at a 12.9% CAGR from 2026 to 2036 across integrated health delivery networks, academic cancer centers, and national reference laboratories. Compared with single-payer European systems, American laboratory procurement is driven by FDA 510(k) primary diagnosis clearances and dedicated Category III digital pathology CPT billing codes. Regulatory momentum in North America is also reinforced by cross-border quality standards, as 3DHISTECH achieved Medical Device Single Audit Program certification in January 2025 covering regulatory compliance across North American and Asia-Pacific jurisdictions [16].
Key takeaway: In the USA, FDA-cleared primary diagnostic platforms and expanding CPT reimbursement codes are forecast to anchor large-scale reference laboratory scanner rollouts.
Canada Digital Pathology Market Outlook (2026 to 2036)
Provincial laboratory networks across Ontario, Quebec, and British Columbia are projected to drive Canadian digital pathology growth at a 12.6% CAGR between 2026 and 2036. Canadian healthcare authorities diverge from fragmented private clinic models by executing multi-hospital provincial tenders that connect community surgical centers to academic subspecialty pathologists in Toronto, Montreal, and Vancouver. In June 2026, a Canadian Cancer Trials Group pathology working group led by Schaeffer et al. recommended establishing a centralized national digital slide repository with standardized scanning protocols in collaboration with the Canadian Association of Pathologists to eliminate physical block transfers [17]. Cold-weather courier disruptions across northern territories further incentivize remote slide sign-out.
Key takeaway: In Canada, provincial multi-hospital telepathology networks and CCTG centralized digital slide repositories are projected to support a 12.6% CAGR through 2036.
UK Digital Pathology Market Outlook (2026 to 2036)
Digital pathology procurement in the UK is estimated to grow at a 12.3% CAGR from 2026 to 2036 as National Health Service pathology consortia complete multi-trust digitization programs. What sets the UK apart from continental European markets is centralized public tendering that bundles scanners, image management software, and cloud storage into unified procurement lots. In January 2025, the UK Government published its five-lot Digital Pathology Framework Agreement covering slide scanners and AI software plus storage and end-to-end solutions for NHS Trusts [18]. Legacy hospital IT incompatibilities still require dedicated middleware integration during trust-wide rollouts.
Key takeaway: In the UK, centralized NHS multi-lot procurement frameworks and regional pathology network consolidation are estimated to sustain strong enterprise scanner and AI software demand.
Germany Digital Pathology Market Outlook (2026 to 2036)
In Germany, market expansion is slated to track at a 12.1% CAGR over the 2026 to 2036 forecast period as university hospital pathology institutes and private MVZ laboratory chains modernize diagnostic lines. German laboratories differ from Anglo-American cloud adopters by enforcing strict federal patient data privacy standards and prioritizing vendor-neutral DICOM whole-slide interoperability with automated slide labeling machines. Reimbursement research published by Kirchhoff et al. in Frontiers in Digital Health in October 2025 benchmarked AI-assisted digital pathology workflows against German GOA 4800 and 4810 histology fee codes of EUR 12 to EUR 17 per slide and EBM GOP 19310 schedules [19]. Stringent EU In Vitro Diagnostic Medical Device Regulation compliance timelines govern all new clinical algorithm deployments.
Key takeaway: In Germany, Hospital Future Act funding and structured GOA and EBM pathology reimbursement benchmarks across university hospitals and MVZ labs are slated to drive steady 12.1% growth.
France Digital Pathology Market Outlook (2026 to 2036)
National cancer screening plans and hospital laboratory consolidation in France are likely to propel digital pathology demand at an 11.9% CAGR between 2026 and 2036. French anatomic pathology structures combine public university hospital centers with private regional ACP laboratory groups that process high outpatient oncology biopsy volumes. On June 30, 2026, Paris-headquartered Tribun Health announced the commercial release of CaloPix 6 as its first IVDR-certified digital pathology and AI orchestration platform for routine diagnostic use across French and European hospitals [20]. Reimbursement alignment for computational algorithm scoring remains the key policy lever determining how fast private French laboratories add automated triage modules.
Key takeaway: In France, private ACP laboratory consolidation and domestic deployment of IVDR-certified platforms such as Tribun Health CaloPix 6 are likely to support an 11.9% CAGR through 2036.
Japan Digital Pathology Market Outlook (2026 to 2036)
Japanese digital pathology adoption is predicted to advance at an 11.4% CAGR from 2026 to 2036 across university hospitals, national cancer centers, and commercial clinical testing laboratories. Japan's rapidly aging population generates high per-capita gastric, colorectal, and lung cancer biopsy volumes while the national roster of board-certified pathologists remains under 3,000 specialists. In August 2026, Hamamatsu Photonics showcased its clinical NanoZoomer whole-slide imaging systems at the 24th Annual Meeting of the Japanese Society of Digital Pathology to support telepathology and automated slide review across Japanese hospital laboratories [21]. Domestic optical precision leaders including Hamamatsu Photonics and Evident anchor strong local hardware preference.
Key takeaway: In Japan, high oncology biopsy volumes from an aging population and Japanese Society of Digital Pathology hospital deployments are predicted to sustain an 11.4% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Digital Pathology Market?
F. Hoffmann-La Roche Ltd, Leica Biosystems Nussloch GmbH, Koninklijke Philips NV, Hamamatsu Photonics KK, Indica Labs Inc., Proscia Inc., Visiopharm AS, 3DHISTECH Ltd., Agilent Technologies Inc., and Evident Corporation are the notable companies in the digital pathology market.
Competitive positioning in the digital pathology industry separates integrated hardware-and-software diagnostics conglomerates, pure-play enterprise image management and AI software developers, and specialized optical scanner manufacturers. Roche Diagnostics, Leica Biosystems, Koninklijke Philips NV, and Agilent Technologies deliver end-to-end clinical scanners, staining instruments, and enterprise software. Indica Labs, Proscia, Visiopharm, and 3DHISTECH compete through hardware-independent image viewers and quantitative biomarker software, while Hamamatsu Photonics and Evident supply precision optical scanning hardware.
- Integrated End-to-End Clinical Pathology Leaders: F. Hoffmann-La Roche Ltd, Leica Biosystems Nussloch GmbH, Koninklijke Philips NV, and Agilent Technologies Inc. combine FDA-cleared whole-slide scanners and enterprise software.
- Enterprise Image Management and Quantitative AI Specialists: Indica Labs Inc., Proscia Inc., Visiopharm AS, and 3DHISTECH Ltd. engineer vendor-agnostic viewing platforms and regulatory-cleared biomarker algorithms.
- Precision Optical Scanner and Microscopy Innovators: Hamamatsu Photonics KK and Evident Corporation manufacture high-numerical-aperture NanoZoomer and VS-series optical slide scanners for clinical and research laboratories.
Competitive Benchmarking: Digital Pathology Market
Table 8: Competitive Benchmarking for the Digital Pathology Market (qualitative capability ratings), 2026
| Company | Primary Diagnostic Scanner Clearance | Cloud IMS & DICOM Interoperability | AI Biomarker & CDx Portfolio | Geographic Reach |
|---|---|---|---|---|
| F. Hoffmann-La Roche Ltd | High | High | High | Global diagnostics network; VENTANA DP 600/200 scanners and navify Digital Pathology |
| Leica Biosystems Nussloch GmbH | High | High | High | Global Danaher pathology leader; Aperio GT 450 DX and GT Elite launched in EMEA in June 2026 |
| Koninklijke Philips NV | High | High | Medium | Global hospital informatics footprint; launched cloud IntelliSite on AWS HealthSuite in March 2026 |
| Hamamatsu Photonics KK | High | High | Medium | Global optical scanner supplier; NanoZoomer S360MD and S60v2MD clinical hospital installations |
| Indica Labs Inc. | Unscored | High | High | US, Europe, and APAC software footprint; FDA-cleared HALO AP Dx and ASCO May 2026 CDx suite |
| Proscia Inc. | Unscored | High | High | 4,000+ labs in US and Europe; FDA-cleared Concentriq AP-Dx; acquired by Agilent in Oct 2026 |
| Visiopharm AS | Unscored | High | High | European and North American clinical AI footprint; CE-IVDR breast and oncology IHC algorithms |
| 3DHISTECH Ltd. | High | High | Medium | Global PANNORAMIC scanner installed base; achieved MDSAP certification in Jan 2025 |
| Agilent Technologies Inc. | Medium | High | High | Global Dako IHC and CDx leader; announced USD 270M acquisition of Proscia in Oct 2026 |
| Evident Corporation | Medium | Medium | Medium | Global life-science and clinical microscopy network; SLIDEVIEW VS200 whole-slide scanners |
Key Developments in the Digital Pathology Market
- In October 2026, Agilent Technologies Inc. entered into a definitive agreement to acquire Proscia Inc., a provider of digital pathology software for clinical and life sciences applications. The all-cash transaction is valued at USD 240 million at closing, with up to an additional USD 30 million subject to future performance milestones [25].
- In May 2026, Indica Labs announced a major expansion of its companion diagnostics capabilities ahead of the 2026 American Society of Clinical Oncology Annual Meeting. The offering combines the company’s AI and biomarker analysis expertise with Leica Biosystems’ companion diagnostics commercialization experience to accelerate drug development and support AI-powered companion diagnostics [26].
- In May 2025, F. Hoffmann-La Roche Ltd received FDA approval for the VENTANA MET (SP44) RxDx Assay as the first companion diagnostic to identify non-squamous non-small cell lung cancer patients eligible for treatment with Emrelis. The assay detects the MET protein based on the percentage of tumor cells stained and the intensity of the staining [27].
Key Players in the Digital Pathology Market
Integrated End-to-End Clinical Pathology Leaders
- F. Hoffmann-La Roche Ltd
- Leica Biosystems Nussloch GmbH
- Koninklijke Philips NV
- Agilent Technologies Inc.
Enterprise Image Management and Quantitative AI Specialists
- Indica Labs Inc.
- Proscia Inc.
- Visiopharm AS
- 3DHISTECH Ltd.
Precision Optical Scanner and Microscopy Innovators
- Hamamatsu Photonics KK
- Evident Corporation
Digital Pathology Market - Report Scope
Table 9: Report Scope for the Digital Pathology Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component Solution; Application Domain; End-User; Scanning Throughput; Deployment Mode |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from whole-slide imaging (WSI) scanners, pathology image management systems (IMS), clinical and research computational pathology AI software, and dedicated pathology storage/cloud archiving infrastructure. Category Scope Note: Excludes routine manual brightfield microscopes, histology tissue processors, microtomes, and bulk chemical staining reagents. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, South Korea, USA, Canada, UK, Germany, France, Japan, and additional countries in the full report |
| Key Companies Covered | F. Hoffmann-La Roche Ltd, Leica Biosystems Nussloch GmbH, Koninklijke Philips NV, Hamamatsu Photonics KK, Indica Labs Inc., Proscia Inc., Visiopharm AS, 3DHISTECH Ltd., Agilent Technologies Inc., Evident Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Digital Pathology Market - Research Methodology
Table 10: Research Methodology for the Digital Pathology Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with hospital anatomic pathology directors, commercial reference laboratory CIOs, whole-slide scanner optical engineers, and biopharma translational oncology leads to validate scanner utilization and per-slide cloud storage costs. |
| Secondary Research | Analysis of FDA 510(k) and De Novo medical device clearances, UK NHS framework tender notices, Australian Medicare Benefits Schedule pathology statistics, Royal College of Pathologists consultations, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down anatomic and cellular pathology equipment baselines reconciled against bottom-up installed WSI scanner fleets (16,100 units in 2026), annual digitized slide volumes (215M to 245M slides), and software/storage subscriptions from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight national cancer biopsy volumes, pathologist-to-population ratios, public telepathology tender budgets, and digital pathology reimbursement codes across eight national markets. |
| Operational Benchmark Traceability | Digitized slide volumes, petabyte storage ranges, and laboratory spending indicators in Tables 2, 3, and 4 trace to FDA CDRH regulatory science benchmarks, DPA reimbursement analyses, and corporate deployment disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate whole-slide scanning hardware, image management software, computational pathology AI modules, and dedicated slide storage while strictly excluding manual optical microscopes and wet histology reagents. |
Digital Pathology Market by Segments
Digital Pathology Market segmented by Component Solution:
- Whole Slide Imaging Scanners
- Pathology Image Management Software
- AI-Powered Diagnostic Algorithms
- Storage and Cloud Archiving Infrastructure
Digital Pathology Market segmented by Application Domain:
- Oncology Biopsy Diagnosis
- Drug Discovery and Clinical Trials
- Academic Research and Pathology Education
- Hematopathology and Immunology
Digital Pathology Market segmented by End-User:
- Diagnostic Pathology Laboratories
- Academic Medical Centers and Hospitals
- Pharmaceutical and Contract Research Organizations
- Government and Reference Research Institutes
- Specialty Dermatology and Veterinary Clinics
Digital Pathology Market segmented by Scanning Throughput:
- High-Throughput Automated Systems
- Medium-Throughput Benchtop Scanners
- Low-Throughput Compact Units
- Modular Multi-Slide Platforms
Digital Pathology Market segmented by Deployment Mode:
- Cloud-Based and Hybrid Platforms
- On-Premises Server Installations
- Vendor-Hosted Enterprise Clouds
- Federated Multi-Site Networks
Digital Pathology Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration. (2025, March 7). ValidPath: Whole Slide Image Processing and Machine Learning Performance Assessment Tool. Center for Devices and Radiological Health Regulatory Science Tools Catalog.
- [2] Proscia Inc. (2026, October 13). Agilent to Acquire Proscia, Advancing AI-Enabled Digital Pathology and Scientific Intelligence. Proscia Corporate Press Releases.
- [3] U.S. Food and Drug Administration. (2026, May 14). HistoGen: Histopathology Cell Nuclei Image Generation Tool. FDA Office of Science and Engineering Laboratories.
- [4] Digital Pathology Association. (2026, April 6). Full Speed Ahead: Shaping the Future of Digital Pathology Reimbursement in 2026. Digital Pathology Association Regulatory and Reimbursement Publications.
- [5] Royal College of Pathologists. (2026, March 3). Digital pathology and AI - update and have your say. The Royal College of Pathologists London.
- [6] Leica Biosystems. (2026, August 11). New FDA 510(k) Clearances for Digital Pathology Portfolio: Leica Biosystems Enables Faster Cancer Diagnoses Through Multiple Digital Pathology FDA 510(k) Clearances. Leica Biosystems Nussloch GmbH Media Releases.
- [7] Landvater, E., & Balis, U. (2025, April 21). Iris: A Next Generation Digital Pathology Rendering Engine. Journal of Pathology Informatics, 16, 100414 (arXiv:2504.15437).
- [8] Matzko, R. O. (2026, February 18). Translational AI in whole-slide image cancer histopathology: state of the art and regulatory-approved solutions. Frontiers in Digital Health, 8, 1863382.
- [9] Hamamatsu Photonics. (2025, August 19). Inside Sorlandet Hospital's transition to fully digital pathology. Hamamatsu Photonics Clinical Case Studies.
- [10] Koninklijke Philips N.V. (2026, March 11). Philips expands digital pathology portfolio with cloud-enabled Philips IntelliSite Pathology Solution on HealthSuite. Philips Global Press Center.
- [11] Baviello, C., et al. (2026, August 16). Artificial Intelligence and Digital Pathology: Technological Transformation and Strategic Impact in Clinical Research and Medical Affairs. Life (MDPI), 16(8), 1346.
- [12] Thai, V., Li, R., Ling, M., Jiang, S., Wolfe, J., Machiraju, R., Hu, Y., Li, Z., Parwani, A., & Chen, J. (2025, October 28). Eye-Tracking, Mouse Tracking, Stimulus Tracking, and Decision-Making Datasets in Digital Pathology. arXiv Open-Access Computer Vision Repository (arXiv:2510.24653).
- [13] Royal College of Pathologists. (2026, April 16). Establishing an open register of AI products for digital pathology. The Royal College of Pathologists Resource Reports.
- [14] Australian Government Department of Health and Aged Care. (2026, August 10). Medicare Quarterly Statistics - Total Pathology Summary (June quarter 2025-26). Commonwealth of Australia Health Publications.
- [15] Omoush, S. A., Alzyoud, J. A. M., El-Omari, N. K. T., & Ahmad, M. (2026, January 1). The Role of Whole Slide Imaging in AI-Based Digital Pathology: Current Challenges and Future Directions - An Updated Literature Review. Journal of Molecular Pathology (MDPI), 7(1), 2.
- [16] 3DHISTECH Ltd. (2025, January 22). 3DHISTECH Achieves MDSAP Certification, Expanding Opportunities in Canada and Australia. 3DHISTECH Corporate News.
- [17] Schaeffer, D. F., Chan, J., & Morin, J. (2026, June 8). Strengthening Biomarker Research in Canadian Cancer Clinical Trials: A Pathology-Focused White Paper. Current Oncology (MDPI), 33(6), 347.
- [18] UK Government Crown Commercial Service. (2025, January 15). Digital Pathology 2024 Framework (Lots 1 to 5: Scanners, Software, Storage, and End-to-End Solutions). GOV.UK Find a Tender Service.
- [19] Kirchhoff, J., Schieder, C., Berns, F., & Schobel, J. (2025, October 20). Valuing diagnostic AI: a structured reimbursement model for learning healthcare systems. Frontiers in Digital Health, 7, 1642750.
- [20] Tribun Health. (2026, June 30). Tribun Health Announces CaloPix 6, Its First IVDR-Certified Version for Routine Diagnostic Use. Tribun Health Official Corporate Releases Paris.
- [21] Hamamatsu Photonics K.K. (2026, August 20). The 24th Annual Meeting of Japanese Society of Digital Pathology in 2026. Hamamatsu Photonics Corporate News Hamamatsu City.
- [22] Leica Biosystems. (2026, June 15). Leica Biosystems Launches AI-Powered Digital Pathology Solution in Europe and the Middle East. Leica Biosystems Newsroom.
- [23] Indica Labs Inc. (2026, May 27). Indica Labs Unveils AI-Powered Companion Diagnostics Offering Ahead of ASCO 2026. Indica Labs Corporate Press Releases.
- [24] F. Hoffmann-La Roche Ltd. (2025, May 14). Roche receives FDA approval for the VENTANA MET (SP44) RxDx Assay as the first companion diagnostic in non-small cell lung cancer. Roche Group Media Releases.
- [25] Agilent Technologies Inc. (2026). Agilent to Acquire Proscia, Expanding Its AI-Enabled Digital Pathology and Life Sciences Portfolio. Business Wire, 13 October 2026. https://www.businesswire.com/news/home/20261013500590/en/
- [26] Indica Labs. (2026). Indica Labs Unveils AI-Powered Companion Diagnostics Offering Ahead of ASCO 2026. Indica Labs Newsroom, 27 May 2026. https://indicalab.com/news/press-release/cdx-offering-ahead-of-asco2026/
- [27] F. Hoffmann-La Roche Ltd. (2025). Roche receives FDA approval for the VENTANA MET (SP44) RxDx Assay as the first companion diagnostic to identify non-squamous non-small cell lung cancer patients eligible for treatment with Emrelis. Roche Media Release, 14 May 2025. https://www.roche.com/media/releases/med-cor-2025-05-14
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the digital pathology market in 2026 and what is forecast for 2036?
- Which pathologist workforce and oncology biopsy pressures support demand for digital pathology?
- Why do Whole Slide Imaging Scanners lead the component solution category?
- Why does Oncology Biopsy Diagnosis lead the application domain category globally?
- How do growth rates differ across Australia and South Korea versus the USA and the UK?
- Which leading companies supply integrated clinical scanners versus vendor-agnostic AI software?
- What capital storage and workflow hurdles restrain adoption in the digital pathology market?
- What should hospital laboratories evaluate before transitioning from optical microscopy to cloud sign-out?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component Solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component Solution, 2026 to 2036
- Whole Slide Imaging Scanners
- Pathology Image Management Software
- AI-Powered Diagnostic Algorithms
- Storage and Cloud Archiving Infrastructure
- Y-o-Y Growth Trend Analysis By Component Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Component Solution, 2026 to 2036
- Global Market Analysis and Forecast, By Application Domain, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Domain, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Domain, 2026 to 2036
- Oncology Biopsy Diagnosis
- Drug Discovery and Clinical Trials
- Academic Research and Pathology Education
- Hematopathology and Immunology
- Y-o-Y Growth Trend Analysis By Application Domain, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Domain, 2026 to 2036
- Global Market Analysis and Forecast, By End-User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-User, 2026 to 2036
- Diagnostic Pathology Laboratories
- Academic Medical Centers and Hospitals
- Pharmaceutical and Contract Research Organizations
- Government and Reference Research Institutes
- Specialty Dermatology and Veterinary Clinics
- Y-o-Y Growth Trend Analysis By End-User, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User, 2026 to 2036
- Global Market Analysis and Forecast, By Scanning Throughput, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Scanning Throughput, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Scanning Throughput, 2026 to 2036
- High-Throughput Automated Systems
- Medium-Throughput Benchtop Scanners
- Low-Throughput Compact Units
- Modular Multi-Slide Platforms
- Y-o-Y Growth Trend Analysis By Scanning Throughput, 2021 to 2025
- Absolute $ Opportunity Analysis By Scanning Throughput, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment Mode, 2026 to 2036
- Cloud-Based and Hybrid Platforms
- On-Premises Server Installations
- Vendor-Hosted Enterprise Clouds
- Federated Multi-Site Networks
- Y-o-Y Growth Trend Analysis By Deployment Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component Solution
- By Application Domain
- By End-User
- By Scanning Throughput
- By Deployment Mode
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- F. Hoffmann-La Roche Ltd
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Leica Biosystems Nussloch GmbH
- Koninklijke Philips NV
- Hamamatsu Photonics KK
- Indica Labs Inc.
- Proscia Inc.
- Visiopharm AS
- 3DHISTECH Ltd.
- Agilent Technologies Inc.
- Evident Corporation
- F. Hoffmann-La Roche Ltd
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Component Solution, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Application Domain, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-User, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Scanning Throughput, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Deployment Mode, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component Solution
- Figure 6: Global Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application Domain
- Figure 9: Global Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-User
- Figure 12: Global Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Scanning Throughput
- Figure 15: Global Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Deployment Mode
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Component Solution
- Figure 32: North America Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application Domain
- Figure 35: North America Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-User
- Figure 38: North America Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Scanning Throughput
- Figure 41: North America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Deployment Mode
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Component Solution
- Figure 48: Latin America Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application Domain
- Figure 51: Latin America Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-User
- Figure 54: Latin America Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Scanning Throughput
- Figure 57: Latin America Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Deployment Mode
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Component Solution
- Figure 64: Western Europe Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Application Domain
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-User
- Figure 70: Western Europe Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Scanning Throughput
- Figure 73: Western Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Deployment Mode
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Component Solution
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Application Domain
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-User
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Scanning Throughput
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Deployment Mode
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Component Solution
- Figure 96: East Asia Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Application Domain
- Figure 99: East Asia Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-User
- Figure 102: East Asia Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Scanning Throughput
- Figure 105: East Asia Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Deployment Mode
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Component Solution
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Application Domain
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-User
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Scanning Throughput
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Deployment Mode
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Component Solution, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Component Solution, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Component Solution
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Application Domain, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Application Domain, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Application Domain
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-User, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-User, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-User
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Scanning Throughput, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Scanning Throughput, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Scanning Throughput
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Deployment Mode, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment Mode, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Deployment Mode
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Digital Pathology Market in 2026, and what is forecast for 2036?
FMI estimates that global digital pathology valuation stood at USD 1.1 billion in 2025 and reached an estimated USD 1.2 billion in 2026. Total industry revenue is on course to hit USD 3.8 billion by 2036 as clinical laboratories automate whole-slide scanning and cloud-based primary diagnosis.
What is the CAGR for the Digital Pathology Market from 2026 to 2036?
The digital pathology sector is projected to expand at a 12.4% CAGR over the 2026 to 2036 window, generating USD 2.6 billion in incremental revenue across hospital and reference laboratories.
Which component solution segment leads the Digital Pathology Market?
Whole Slide Imaging Scanners are projected to hold 48.0% of component solution demand in 2026 since high-speed optical slide capture is required before laboratories can deploy digital viewing or AI triage.
Which application domain segment leads the Digital Pathology Market?
Oncology Biopsy Diagnosis is anticipated to represent 56.0% of the application domain category in 2026 as cancer centers standardize quantitative biomarker scoring and remote tumor board reviews.
Which country has a notable growth outlook during the assessment period?
Australia leads national expansion projections at a 13.5% CAGR through 2036, supported by federal Medicare pathology updates and interstate telepathology network rollouts.
Who are the key players in the market?
F. Hoffmann-La Roche Ltd, Leica Biosystems Nussloch GmbH, Koninklijke Philips NV, Hamamatsu Photonics KK, Indica Labs, Proscia Inc., Visiopharm AS, 3DHISTECH Ltd., Agilent Technologies Inc., and Evident Corporation lead commercial supply across clinical whole-slide scanners and enterprise pathology software.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
