
- Market Size (2026)
- USD 792.1 Mn
- Forecast (2036)
- USD 1278.0 Mn
- CAGR (2026 to 2036)
- 4.9%
How big is Drag Reducing Agents Market in 2026?
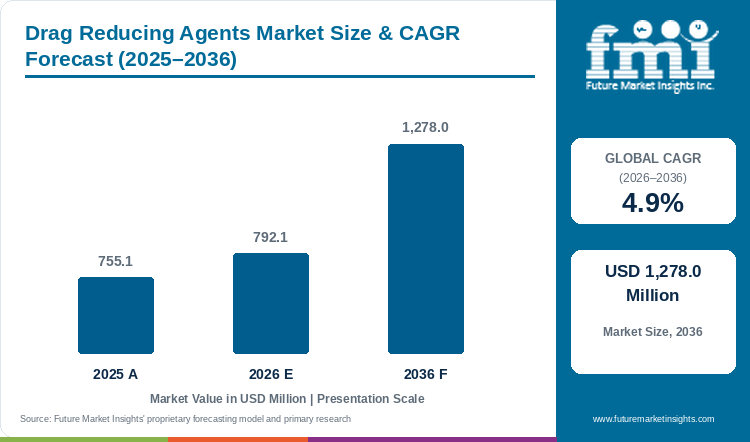
Drag reducing agent sales move from USD 755.1 million (2025) to USD 792.1 million (2026), with FMI forecasting USD 1,278.0 million for 2036 at a 4.9% CAGR, as operators of full crude and product lines add chemical capacity.
Western Canadian export lines ran close to physical limits in 2025, with the Enbridge Mainline moving 3.08 million barrels a day against 3.23 million barrels a day of available capacity, a 95.2% utilization rate, and Trans Mountain averaging 85%. Trans Mountain carried 840,000 barrels a day in the second quarter of 2026, 94% of a 890,000 barrel nominal capacity, with a drag reducing agent project expected to add about 90,000 barrels a day by the end of 2026. FMI places drag reducing agent demand at USD 755.1 million for 2025, USD 792.1 million for 2026 and USD 1,278.0 million for 2036, a 4.9% annual rate across the forecast decade. That uplift equals roughly a tenth of nominal capacity, and the same second-quarter volume would fill 85.7% of the enlarged 980,000 barrel system. Field dosing stays in the parts-per-million range, as a Baker Hughes deepwater Gulf of Mexico case recorded 31% maximum drag reduction at 40 ppm and 13,597 additional barrels a day, 5.19% above a 262,000 barrel maximum. Operators of full lines can buy roughly a tenth more capacity through chemistry, which keeps DRA volumes tied to throughput on existing pipe more than to new construction.
Suppliers are adding plant capacity and contract scope around this debottlenecking demand. Innospec raised drag reducing agent output at Pleasanton, Texas, with new capacity due in the fourth quarter of 2025, and Oilfield Services sales rose 14% to USD 115.4 million in the second quarter of 2026, an improvement management linked to the DRA plant expansion. Baker Hughes signed a multi-year agreement in July 2025 to supply FLO drag reducers, management services and automated monitoring to Genesis Energy's Cameron Highway and Poseidon offshore crude systems. Trans Mountain's chief financial officer put stronger pumping stations at $3 billion to $4 billion in September 2025, against a low-cost chemical option worth 5% to 10% more capacity. FMI expects suppliers that pair injection skids, dosing optimization and site service with product supply to secure the larger share of new pipeline contracts through 2036.
Key Market Trends & Insights
- Polymer concentrates led material type demand with 50% in 2026, as gel and solution grades of ultra-high molecular weight polymer still serve most crude trunk lines. IndianOil's XtraFlo polymer, at 10 to 20 million Dalton, lifted a Bihar crude line by 15% in 2025.
- Light and medium crude oil represented an estimated 55% of 2026 application demand, consistent with crude trunk lines carrying the bulk of pipeline volume. LSPI notes that conventional drag reducers lose effect below 23° API, a limit that separates this segment from heavy crude grades.
- Oil and gas accounted for an estimated 84% of 2026 end-use industry demand, carried by midstream operators facing full trunk lines in North America.
Regional Highlights
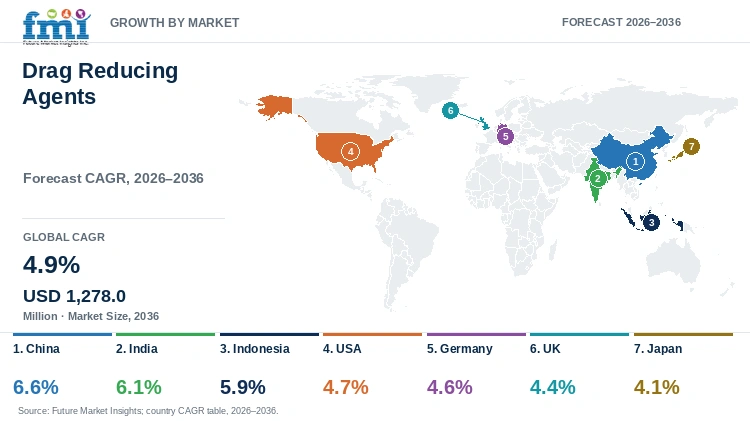
- China heads the country forecast at 6.6% a year, with India (6.1%) and Indonesia (5.9%) next.
- Japan sits at the lower end of the profiled set with a 4.1% CAGR, close to the United Kingdom at 4.4%.
- Operational petroleum and product pipelines in India totalled 67.95 MMTPA of capacity in March 2026, with a further 45.9 MMTPA partly commissioned or under construction.
Market Size & Forecast
Table 1: Market Size and Forecast for the Drag Reducing Agents Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 755.1 million |
| Estimated Market Size in 2026 | USD 792.1 million |
| Projected Market Size by 2036 | USD 1,278.0 million |
| CAGR, 2026 to 2036 | 4.9% |
| Added Revenue, 2026 to 2036 | USD 485.9 million |
| Market Expansion Multiple | 1.6x |
Planned capacity additions on existing pipe now name drag reducers alongside hardware. Enbridge lists drag-reducing agents among the measures in Phase 1 of a Mainline Optimization programme that adds 150,000 barrels a day. Trans Mountain plans 210,000 barrels a day from a Mainline Optimization Project by the fourth quarter of 2028, which together with DRA would take the system to as much as 1,190,000 barrels a day. The chemical step supplies 30% of that planned 300,000 barrel gain about two years before the hardware phase. Upstream sellers of oilfield chemicals and midstream operators planning oil pipeline infrastructure now treat flow improvers as a scheduled capacity layer. Heavy crude below 23° API needs specialist grades, and shear at pumps degrades polymer chains, limiting the gain on short or heavily pumped routes. Pricing on crude and product trunk lines follows delivered barrels more than chemical tonnage, with steady volume growth expected as lines stay full.
Pipeline Capacity Utilization and Chemical Dosing Economics
Six indicators below pair utilization on full trunk lines with published dose-response and throughput results, covering 2024 to 2026 disclosures.
Table 2: Pipeline Throughput and DRA Dosing Indicators for the Drag Reducing Agents Market (mixed units), mixed reporting years from 2024 to 2026
| Indicator | Data Point | Why this matters | Source |
|---|---|---|---|
| Enbridge Mainline utilization, 2025 | 3.08 vs 3.23 MMb/d available, 95.2% | Little spare room on the largest Canadian export system | |
| Trans Mountain throughput, Q2 2026 | 840,000 b/d on 890,000 b/d nominal, 94% | A full line is the usual trigger for DRA spending | |
| Trans Mountain DRA project | About 90,000 b/d (10.1% of nominal capacity); 16 units at 12 pump stations; CER Order XO-005-2026, 4 June 2026 | Sizes the capacity a single DRA programme can add | |
| Pump station alternative, Trans Mountain | $3 billion to $4 billion, per CFO, September 2025 | Sets the capital cost DRA can defer | - |
| Dose-response, HP-DRA product line | 23.24% drag reduction at 3 ppm, 33.95% at 5 ppm, 41.39% at 8 ppm | Drag reduction per ppm falls from 7.7 to 5.2 points, capping economic dose | - |
| Field result, IndianOil XtraFlo | 3.0 to 3.45 MMTPA (+15%); rail rakes cut from 24 to 9 a month; Rs 1.6 crore a month saved | Converts uplift into avoided logistics cost | - |
Analyst Perspective
“Trans Mountain, Enbridge and IndianOil now plan drag reducers as a first capacity step on lines running above 90% full, before pumps or looping. Suppliers able to show a measured barrel-per-day gain at a stated ppm dose are likely to secure multi-year contracts through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Drag Reducing Agents Market segmented?
Drag reducing agents market is segmented by three primary commercial axes and region: material type, application, end-use industry, and region. In 2026, polymer concentrates are projected at 50%, light and medium crude oil at an estimated 55%, and oil and gas at an estimated 84%.
By material type: polymer concentrates (gel and solution), polymer suspensions, and surfactants.
By application: light and medium crude oil, heavy and asphaltenic crude oil, refined products, multiphase flow, and water transportation.
By end-use industry: oil and gas, chemicals and petrochemicals, agriculture and water utilities, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do polymer concentrates hold half of material type demand?
Gel and solution polymer concentrates take 50% of 2026 material type demand, backed by a long field record across crude trunk lines.
Table 3: Material Type Share for the Drag Reducing Agents Market (percentage share), 2026
| Material Type | Share (2026) |
|---|---|
| Polymer Concentrates (Gel and Solution) | 50% |
| Other Segments Combined | 50%* |
| Total | 100% |
*The balance remaining after deducting the leading segment's reported share from 100%.
Table 4: Material Type Leadership and Market Growth for the Drag Reducing Agents Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.9% |
| Leading Segment | Polymer Concentrates (Gel and Solution) |
Polymer concentrates account for 50% of material type demand in 2026. IndianOil reformulated a polymer blend twice for Oil India's crude before three injection stations lifted the Paradip-Haldia-Barauni line from about 440 to nearly 500 cubic metres an hour in 2026. Suspension-based grades compete on handling, and LSPI's LiquidPower suspensions claim 80% or greater drag reduction on suitable crude. FMI flags this split as directional: flagship supplier products such as LSPI's LiquidPower and Baker Hughes' FLO lines are predominantly suspension or slurry grades, so field practice may lean more toward suspension-based chemistry than the reported classification implies. Surfactant grades stay a smaller pool sourced alongside oilfield surfactants.
- Each new trunk-line approval adds injection points, keeping polymer concentrates at 50% share in 2026.
- Licensing of national technology, such as IndianOil's XtraFlo production by Dorf Ketal at Dahej, widens regional supply of polymer grades.
Why does light and medium crude oil remain the leading application?
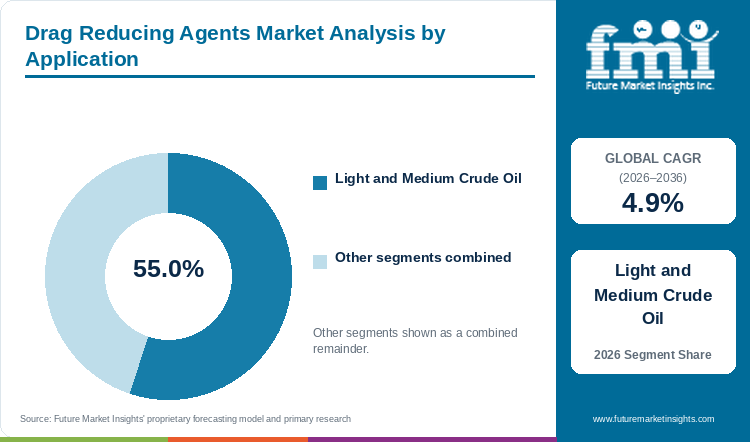
Light and medium crude oil, the dominant volume moved through crude export trunk lines, takes an estimated 55% of 2026 application demand.
Light and medium crude oil represents an estimated 55% of application demand in 2026, in line with trunk-line throughput data showing crude movements dominating pipeline volume. Heavy grades form a separate, smaller pool, and Baker Hughes reported a 35% throughput increase on asphaltenic crude below 23° API with a FLO ULTIMA grade. Refined products and multiphase lines take smaller volumes still, and a 100 ppm field trial on Total's 42 km Bekapai multiphase line in Indonesia lifted peak oil flow to 9,800 barrels a day from a 6,500 barrel average.
- Light and medium crude oil leads at an estimated 55% in 2026, consistent with trunk-line volumes dominating pipeline throughput.
- Heavy crude growth requires specialist chemistries rated below 23° API.
What keeps oil and gas the largest end-use industry?
Midstream and offshore oil and gas operators account for an estimated 84% of 2026 end-use demand.
Oil and gas holds an estimated 84% of end-use industry demand in 2026. Genesis Energy owns 64% of the Cameron Highway and Poseidon systems that took a multi-year Baker Hughes DRA contract in July 2025. Product pipelines add a second buying group, as HPCL reports dose-response results for HP-DRA on a refined product line. FMI expects midstream operators to extend DRA budgets as capacity requests outrun new pipeline approvals.
- Crude and product pipeline owners remain the core buyers, keeping oil and gas at an estimated 84% share in 2026.
- Water utilities and agriculture remain a smaller pool, using DRA mainly in conveyance trials.
What are the drivers, restraints, and opportunities in the Drag Reducing Agents Market?
In the drag reducing agents market, full trunk pipelines drive chemical debottlenecking, heavy crude and shear degradation constrain the achievable gain, and capacity programmes on existing lines in Canada and India open the principal commercial opportunity.
- Driver: Crude and product pipelines operating above 90% of capacity.
- Restraint: Weak performance below 23° API and polymer loss through pumps.
- Opportunity: Optimization programmes that schedule DRA ahead of pump and terminal work.
Full lines push operators toward chemical capacity
The Enbridge Mainline ran at 95.2% in 2025, the highest annual average since 2019, and Trans Mountain recorded a monthly record of 855,000 barrels a day in November 2025. Trans Mountain reported a line 98% full in July 2026. Operators facing nominations above capacity are keeping DRA in base operating plans, a pattern also shaping growth in crude oil flow improvers.
Heavy crude and shear cap the uplift
LSPI states that traditional drag reducers become ineffective and uneconomic below 23° API, and markets a separate ExtremePower grade claiming more than 50% drag reduction on heavy crude. HP-DRA results show drag reduction gains per ppm narrowing as dose rises, from 23.24% at 3 ppm to 41.39% at 8 ppm. Buyers tend to cap dosing once extra ppm no longer pays for the barrels added.
Optimization programmes open scheduled demand
Trans Mountain targets about 90,000 barrels a day from DRA and 210,000 from a Mainline Optimization Project by the fourth quarter of 2028. Enbridge's Phase 1 optimization uses drag-reducing agents with piping, storage and terminal changes to add 150,000 barrels a day. Such programmes give suppliers multi-year volume visibility on fixed injection sites.
Which country CAGRs are profiled in the Drag Reducing Agents Market?
Table 5: Country CAGR Comparison for the Drag Reducing Agents Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 6.6% |
| India | 6.1% |
| Indonesia | 5.9% |
| USA | 4.7% |
| Germany | 4.6% |
| UK | 4.4% |
| Japan | 4.1% |
How do country-level CAGRs compare in the Drag Reducing Agents market?
New pipeline build and refinery-linked crude movements separate the profiled rates. FMI finds that China (6.6%), India (6.1%) and Indonesia (5.9%) form the faster group on expanding crude and product networks, with the USA (4.7%), Germany (4.6%), the UK (4.4%) and Japan (4.1%) growing from mature systems with gains coming mostly from optimizing existing lines.
- China adds crude trunk capacity under the 15th Five-Year Plan.
- India pairs new product pipeline capacity with home-grown DRA chemistry.
- Indonesia's demand is concentrated in offshore and multiphase gathering lines.
- US demand centres on offshore and Permian takeaway systems.
- Germany's volumes follow crude imports through the Transalpine system.
- The UK relies on a smaller set of crude and jet fuel lines.
- Japan ranks lowest in the profiled set, since few long-distance crude lines operate there.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- China leads the profiled set with drag reducing agent demand forecast to expand at 6.6% CAGR through 2036. PipeChina put the Lianyungang-Huai'an section of the Lianyungang-Yizheng crude line into service in August 2026, part of an 18.5 million tonne a year system with a 70,000 tonne daily maximum. Each new long-distance crude line adds pump stations, so polymer injection can raise flow later in the asset's life.
- India is projected to record 6.1% CAGR through 2036. IndianOil's XtraFlo raised Paradip-Haldia-Barauni throughput from 3.0 to 3.45 MMTPA and cut rail rakes from 24 to 9 a month, saving Rs 1.6 crore a month, about Rs 19.2 crore a year. The Numaligarh-Siliguri product line took the hardware route in March 2026, moving from 1.72 to 5.5 MMTPA through converted pumping stations at a cost of around Rs 7.5 billion.
- Indonesia's demand for drag reducing agents is anticipated to expand at 5.9% CAGR through 2036. A 100 ppm trial on the 12-inch Bekapai multiphase line in Indonesia showed a peak gain of about 3,300 barrels a day of oil and a potential commercial benefit above USD 150,000 a day.
- The USA is estimated to grow at 4.7% CAGR through 2036. Baker Hughes' FLO XLWR added 13,597 barrels a day at 40 ppm on a deepwater Gulf of Mexico line, and a 2025 Genesis Energy contract covers two offshore crude systems. Enbridge's 120,000 barrel a day Gray Oak expansion, after an initial 80,000 barrels a day came online in April 2025, was originally targeted to complete its balance in the first half of 2026, per the project's 2025 announcement.
- Germany is projected to grow at 4.6% CAGR through 2036. Germany's volumes are tied to transit throughput on the TAL pipeline system; the TAL-Plus upgrade, inaugurated in April 2025, raised crude deliveries along the German-Austrian-Czech corridor to about 8 million tonnes a year for Czech refineries, though this is transit-corridor evidence rather than direct German domestic demand data.
- The UK drag reducing agents market is predicted to rise at 4.4% CAGR through 2036. ExxonMobil Fawley completed its Southampton to London Pipeline installation in April 2026, with upgraded on-site facilities raising jet fuel flow rates and strengthening supply to London’s airports.
- Japan is forecast to expand at 4.1% CAGR through 2036, the lowest in the profiled set. Japanese demand links mainly to refined product and industrial fluid transfer, with limited long-distance crude pipeline exposure.
Who are the notable companies in the Drag Reducing Agents Market?
LiquidPower Specialty Products, Baker Hughes, Innospec, Flowchem, Indian Oil Corporation, Dorf Ketal Chemicals, Hindustan Petroleum Corporation, Sino Oil King Shine Chemical, Oil Flux Americas, and IRIS Tech make up the FMI company set.
Four US-based flow-improver specialists head the FMI company set, with LSPI reporting treatment of more than 50 million barrels of hydrocarbon liquids a day across over 40 countries. Indian refiners have built home-grown grades, and Chinese and smaller specialist producers serve regional and heavy crude niches. Flowchem was acquired by SCF Partners from Entegris in March 2024 and continues to operate independently under that ownership. LiquidPower Specialty Products (LSPI), a separate Berkshire Hathaway company, traces its origins to Conoco’s flow improver programme in the 1970s and has operated independently of Lubrizol since 2017 [6][14].
- Global flow-improver specialists: LiquidPower Specialty Products, Baker Hughes, Innospec, Flowchem.
- Refiner-developed and licensed grades: Indian Oil Corporation, Dorf Ketal Chemicals, Hindustan Petroleum Corporation.
- Regional and niche producers: Sino Oil King Shine Chemical, Oil Flux Americas, IRIS Tech.
Competitive Benchmarking: Drag Reducing Agents Market
Table 6: Competitive Benchmarking for the Drag Reducing Agents Market (qualitative capability ratings), 2026
| Company | Crude Oil DRA | Refined Products DRA | Heavy Crude DRA | Reach |
|---|---|---|---|---|
| LiquidPower Specialty Products | High | High | High | High |
| Baker Hughes | High | Medium | High | High |
| Innospec | Medium | Low | Low | Medium |
| Flowchem | Medium | Low | Low | Medium |
| Indian Oil Corporation | Medium | Medium | Low | Medium |
| Dorf Ketal Chemicals | Medium | Medium | Low | Medium |
| Hindustan Petroleum Corporation | Low | Medium | Low | Low |
| Sino Oil King Shine Chemical | Medium | Low | Low | Low |
| Oil Flux Americas | Medium | Low | Medium | Low |
| IRIS Tech | Low | Low | Medium | Low |
Key Developments in the Drag Reducing Agents Market
- In August 2026, Innospec reported second-quarter 2026 Oilfield Services revenue of USD 115.4 million, up 14% year on year, with operating income rising 40%, driven by the DRA plant expansion at Pleasanton, Texas, and growing customer demand in North America and the Middle East.
- In July 2026, IndianOil reported a 15% throughput increase on the Paradip-Haldia-Barauni crude line using a XtraFlo drag reducer.
- In June 2026, the Canada Energy Regulator approved Trans Mountain's drag reducing agent project under Order XO-005-2026.
- In July 2025, Baker Hughes agreed a multi-year supply of FLO drag reducers to Genesis Energy's Cameron Highway and Poseidon pipelines.
Key Players in the Drag Reducing Agents Market
Global Flow-improver Specialists
- LiquidPower Specialty Products (Berkshire Hathaway)
- Baker Hughes
- Innospec
- Flowchem (SCF Partners)
Refiner-developed and Licensed Grades
- Indian Oil Corporation
- Dorf Ketal Chemicals
- Hindustan Petroleum Corporation
Regional and Niche Producers
- Sino Oil King Shine Chemical
- Oil Flux Americas
- IRIS Tech
Drag Reducing Agents Market - Report Scope
Table 7: Report Scope for the Drag Reducing Agents Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material type; application; end-use industry; region |
| Quantitative units | USD million |
| Market definition | Revenue from chemical additives that suppress turbulent friction in pipelines and conduits carrying crude oil, refined products, multiphase streams, heavy crude and water, in polymer concentrate, polymer suspension and surfactant forms, including associated dosing and injection services; excludes corrosion inhibitors, demulsifiers, viscosity modifiers and engine fuel additives that do not target turbulence suppression |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; India; Indonesia; USA; Germany; UK; Japan |
| Key companies profiled | LiquidPower Specialty Products; Baker Hughes; Innospec; Flowchem; Indian Oil Corporation; Dorf Ketal Chemicals; Hindustan Petroleum Corporation; Sino Oil King Shine Chemical; Oil Flux Americas; IRIS Tech |
| Forecast period | 2026 to 2036 |
| Approach | A bottom-up build was reconciled against top-down estimates covering pipeline throughput, dosing rates and supplier revenue within the defined revenue boundary. |
Drag Reducing Agents Market - Research Methodology
Table 8: Research Methodology for the Drag Reducing Agents Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with pipeline operators, flow assurance engineers and DRA suppliers. |
| Desk Research | Review of regulator throughput data, operator capacity disclosures, supplier case studies and company results. |
| Market Sizing and Forecasting | Throughput-based demand modelling by application and country, linked to dosage ranges and pricing. |
| Data Validation | Triangulation of model outputs against supplier revenue and regulator data, with analyst review of outliers. |
Drag Reducing Agents Market by Segments
Drag Reducing Agents Market segmented by Material Type:
- Polymer Concentrates (Gel and Solution)
- Polymer Suspensions
- Surfactants
Drag Reducing Agents Market segmented by Application:
- Light and Medium Crude Oil
- Heavy and Asphaltenic Crude Oil
- Refined Products
- Multiphase Flow
- Water Transportation
Drag Reducing Agents Market segmented by End-use Industry:
- Oil and Gas
- Chemicals and Petrochemicals
- Agriculture and Water Utilities
- Others
Drag Reducing Agents Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Canada Energy Regulator. (2026, June 24). Market Snapshot: Oil pipeline throughputs remained high in 2025. https://neb-one.gc.ca/en/data-analysis/energy-markets/market-snapshots/2026/market-snapshot-oil-pipeline-throughputs-remained-high-in-2025.html
- [2] RBN Energy. (2026, August 29). Trans Mountain expects to add 90 Mb/d of capacity by year-end. https://rbnenergy.com/daily-posts/analyst-insight/trans-mountain-expects-add-90-mbd-capacity-year-end
- [3] Innospec Inc. (2026, August 4). Innospec reports second quarter 2026 financial results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0001054905/000119312526333724/iosp-ex99_1.htm
- [4] Indian Chemical News. (2026, July 21). Cross-company synergy boosts IndianOil Northeast crude flow by 15%: Arvind Kumar, Director (Refineries), IndianOil. https://www.indianchemicalnews.com/opinion/cross-company-synergy-boosts-indianoil-northeast-crude-flow-by-15-arvind-kumar-director-refineries-indianoil-31172
- [5] Trans Mountain Corporation. (2026, July). Trans Mountain fact sheet, July 2026. https://docs.transmountain.com/About-Us/2026-July-TM-Fact-Sheet-EN.pdf
- [6] LiquidPower Specialty Products Inc. (2025). LSPI brochure 2025. https://www.liquidpower.com/wp-content/uploads/LSPI-Brochure-2025.pdf
- [7] Baker Hughes. (2024). FLO ULTIMA drag reducing agent increased throughput 35%, North America (case study). https://dam.bakerhughes.com/m/396fea0b4a728389/original/FLO-ULTIMA-drag-reducing-agent-increased-throughput-35-North-America-cs.pdf
- [8] Indonesian Petroleum Association. (2014). Application of drag reducing agent (DRA) in multiphase pipeline for Bekapai production debottlenecking. https://www.ipa.or.id/id/publications/application-of-drag-reducing-agent-dra-in-multiphase-pipeline-for-bekapai-production-debottlenecking
- [9] Baker Hughes. (2025, July 24). Baker Hughes to supply drag-reducing agents to Genesis Energy, increasing offshore pipeline capacity. https://www.bakerhughes.com/company/news/baker-hughes-supply-dragreducing-agents-genesis-energy-increasing-offshore-pipeline
- [10] Hindustan Petroleum Corporation Limited. (n.d.). HP-DRA brochure. https://www.hindustanpetroleum.com/documents/pdf/HP-DRA-Brouchure.pdf
- [11] Trans Mountain Corporation. (2026). Drag reducing agent project. https://engage.transmountain.com/drag-reducing-agent
- [12] CBC News. (2025, September 4). Why Trans Mountain wants to expand when the oil pipeline isn't even full. https://www.cbc.ca/lite/story/1.7624323
- [13] Baker Hughes. (2024). FLO XLWR drag reducing agent lowered pipeline pressure, increased production (case study). https://dam.bakerhughes.com/m/5fc88cd1e2d96cf1/original/FLO-XLWR-drag-reducing-agent-lowered-pipeline-pressure-increased-production-cs.pdf
- [14] LiquidPower Specialty Products Inc. (n.d.). Company. https://www.liquidpower.com/about-lspi/company
- [15] Dorf Ketal. (2021, March 25). IndianOil inks pact with Dorf Ketal Chemicals. https://www.dorfketal.com/news/348-indianoil-inks-pact-with-dorf-ketal-chemicals
- [16] Innospec Inc. (2025, March 3). Innospec expands production of drag reducing agents. https://www.globenewswire.com/news-release/2025/03/03/3035669/0/en/Innospec-Expands-Production-of-Drag-Reducing-Agents.html
- [17] Pipeline & Gas Journal. (2024, March 4). SCF Partners acquires Flowchem, Val-Tex and Sealweld, leaders in midstream solutions. https://pgjonline.com/news/2024/march/scf-partners-acquires-flowchem-val-tex-and-sealweld-leaders-in-midstream-solutions
- [18] Enbridge. (2026). Mainline Optimization. https://www.enbridge.com/projects-and-infrastructure/projects/mainline-optimization
- [19] Petroleum and Natural Gas Regulatory Board. (2026, March 31). Petroleum and petroleum product pipelines in India, March 2026. https://pngrb.gov.in/data-bank/20260331-PPPL.pdf
- [20] Indian Infrastructure. (2026, March 16). Capacity augmentation of Numaligarh-Siliguri product pipeline and Phase I of North East Gas Grid witnesses inauguration. https://indianinfrastructure.com/2026/03/16/capacity-augmentation-of-numaligarh-siliguri-product-pipeline-and-phase-i-of-north-east-gas-grid-witnesses-inauguration/
- [21] China Services Info. (2026, August 17). PipeChina launches key crude oil pipeline in East China to boost energy security. https://www.chinaservicesinfo.com/s/202608/17/WS6a827ef7498e23165e071f8c/pipechina-launches-key-crude-oil-pipeline-in-east-china-to-boost-energy-security.html
- [22] S&P Global Commodity Insights. (2025, April 17). Czech Republic ready to end Russian crude imports after launching TAL pipeline upgrade. https://www.spglobal.com/energy/en/news-research/latest-news/refined-products/041725-czech-republic-ready-to-end-russian-crude-imports-after-launching-tal-pipeline-upgrade
- [23] Pipeline Journal. (2026, April 9). ExxonMobil completes major pipeline upgrade in U.K. to boost aviation fuel supply. https://www.pipeline-journal.net/news/exxonmobil-completes-major-pipeline-upgrade-uk-boost-aviation-fuel-supply
- [24] Justia Patents. (2025). Patents assigned to IRIS Tech Inc. https://patents.justia.com/assignee/iris-tech-inc
- [25] Enbridge. (2026). 2026 Liquids Pipelines Customer Handbook: North America and beyond. https://www.enbridge.com/Reports/2026-Liquids-Pipelines-Customer-Handbook/North-America-and-beyond
- [26] Canada Energy Regulator. (2026). Trans Mountain Pipeline ULC - Drag Reducing Agent Project. https://neb-one.gc.ca/en/applications-hearings/view-applications-projects/trans-mountain-drag-reducing-agent-project-notification/index.html
This Report Answers
- How big is the drag reducing agents market during 2026?
- What value is projected by 2036?
- Which material type holds leading share?
- Which application holds leading share?
- Which countries have leading growth?
- Which companies are key in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material Type, 2026 to 2036
- Polymer Concentrates (Gel and Solution)
- Polymer Suspensions
- Surfactants
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Light and Medium Crude Oil
- Heavy and Asphaltenic Crude Oil
- Refined Products
- Multiphase Flow
- Water Transportation
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End-use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-use Industry, 2026 to 2036
- Oil and Gas
- Chemicals and Petrochemicals
- Agriculture and Water Utilities
- Others
- Y-o-Y Growth Trend Analysis By End-use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material Type
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By End-use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By End-use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Application
- By End-use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- LiquidPower Specialty Products
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Baker Hughes
- Innospec
- Flowchem
- Indian Oil Corporation
- Dorf Ketal Chemicals
- Hindustan Petroleum Corporation
- Sino Oil King Shine Chemical
- Oil Flux Americas
- IRIS Tech
- LiquidPower Specialty Products (Berkshire Hathaway)
- Flowchem (SCF Partners)
- LiquidPower Specialty Products
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Material Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by End-use Industry, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-use Industry
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Material Type
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-use Industry
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Material Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-use Industry
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Material Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-use Industry
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Material Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-use Industry
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Material Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-use Industry
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Material Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-use Industry
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Material Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-use Industry, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-use Industry, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-use Industry
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the drag reducing agents market expected in 2026?
USD 792.1 million in 2026 on FMI estimates, rising to USD 1,278.0 million by 2036, about 1.6 times the 2026 base.
What CAGR is projected for the drag reducing agents market through 2036?
FMI puts the annual rate at 4.9% over 2026 to 2036. Utilization above 90% on major crude export lines keeps operators adding chemical capacity ahead of pump and looping projects.
Which material type holds a leading market share in 2026?
Polymer concentrates in gel and solution form are reported at 50% of material type demand in 2026, though flagship supplier products such as LSPI's LiquidPower and Baker Hughes' FLO lines are predominantly suspension or slurry grades, so the split is best read directionally. Polymer suspensions and surfactants share the remaining 50%.
Which application holds a leading share in 2026?
Light and medium crude oil, at an estimated 55% of application demand in 2026. Heavy and asphaltenic crude below 23° API needs specialist grades such as FLO ULTIMA and ExtremePower.
Which country has a leading expansion outlook through 2036?
China, at 6.6% CAGR from 2026 to 2036, ahead of India at 6.1% and Indonesia at 5.9%. India also has measured field evidence, with a 15% throughput gain reported on the Paradip–Haldia–Barauni line in 2026.
Who are the key companies in the drag reducing agents market?
Notable companies include LiquidPower Specialty Products, Baker Hughes, Innospec, Flowchem, Indian Oil Corporation, Dorf Ketal Chemicals, Hindustan Petroleum Corporation, Sino Oil King Shine Chemical, Oil Flux Americas, and IRIS Tech.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
