

- Market Size (2026)
- USD 1.8 Bn
- Forecast (2036)
- USD 2.8 Bn
- CAGR (2026 to 2036)
- 4.3%
How big is the Friction Modifier Additives Market in 2026?
USD 1.8 billion in 2026, reaching USD 2.8 billion by 2036 at a 4.3% CAGR
The friction modifier additives market was valued at USD 1.8 billion in 2025. The market is set to reach USD 1.8 billion by 2026-end and grow at a CAGR of 4.3% between 2026-2036 to reach USD 2.8 billion by 2036. Organic will dominate with a 23.0% share, while Automobile Lubricants will lead with a 41.0% share.
Friction modifier additive procurement is shaped by automotive lubricant formulation requirements, fuel efficiency regulations, and industrial equipment protection standards. Demand reflects investment in organic, inorganic, and polymer-based friction modifiers that reduce wear, improve fuel economy, and extend lubricant drain intervals. Buyers include lubricant blenders, OEM engine test managers, and industrial maintenance teams evaluating additive performance in boundary lubrication conditions.
Growth reflects tightening fuel efficiency mandates and evolving engine oil specifications that require advanced friction modifier chemistry. ILSAC confirmed updated GF-7 gasoline engine oil specification development in its 2025 progress report, supporting procurement of next-generation friction modifier additives for low-viscosity engine oil formulations.
Differentiation in this market rests on additive chemistry versatility, base oil compatibility, and formulation support for lubricant blenders. Afton Chemical and Lubrizol lead through comprehensive additive package portfolios, while Infineum and BASF gain preference where engine test data and OEM specification compliance drive friction modifier selection.
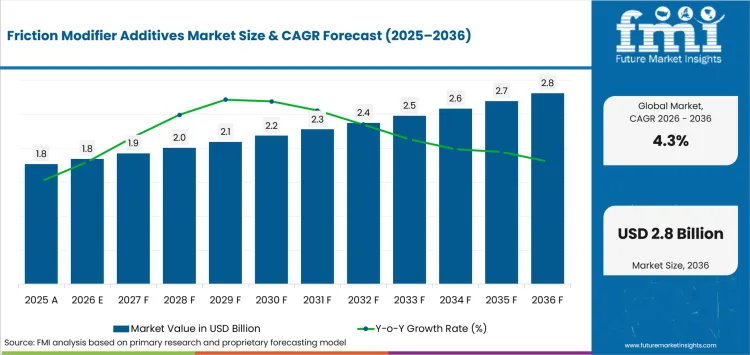
Key Takeaways of Friction Modifier Additives Market
- Fuel efficiency regulations are expected to sustain friction modifier procurement as lubricant blenders formulate lower-viscosity engine oils.
- Organic is expected to account for 23.0% of product type demand in 2026 due to broad compatibility with mineral and synthetic base oils across engine and industrial lubricant formulations.
- Automobile Lubricants is projected to hold 41.0% of application demand in 2026, driven by passenger car and commercial vehicle engine oil formulation volumes.
- Mineral Oil Compatible Additives is anticipated to represent 39.0% of base oil compatibility demand in 2026, supported by the large installed base of mineral oil-based lubricant production.
- China leads with a 5.8% CAGR through 2036 as automotive lubricant production and industrial equipment maintenance sustain friction modifier procurement.
- Afton Chemical and Lubrizol are expected to compete through comprehensive lubricant additive package portfolios.
Analyst Perspective
"Buyers are expected to judge organic on performance and total cost of ownership rather than headline price. Friction modifier additive adoption is expected to depend on fuel efficiency mandates and evolving engine oil specification requirements. Suppliers that combine additive chemistry versatility with OEM engine test validation are likely to secure multi-year blender supply agreements. Market success is projected to depend on meeting low-viscosity lubricant performance requirements while maintaining wear protection across engine and industrial applications."
- Nikhil Kaitwade, Principal Consultant at Future Market Insights
Why is the Friction Modifier Additives Market growing?
Rising Organic and Automobile Lubricants demand across industrial end users
- Friction-modifier demand follows lubricant formulation cycles and fuel-economy and wear-protection requirements rather than commodity buying.
- China leads growth at 5.8% CAGR as automotive lubricant production and industrial equipment maintenance sustain friction modifier procurement.
- Automobile Lubricants holds 41.0% of application revenue, indicating where standardization is concentrating buyer spend.
Because additives are qualified into oil formulations, friction-modifier spend concentrates with producers offering performance-validated chemistries, consistent supply, and formulation support into lubricant blenders.
How is the Friction Modifier Additives Market segmented?
The friction modifier additives industry is segmented by product type, application, base oil compatibility, function, end use industry, and region.
The friction modifier additives market is segmented by product type, application, base oil compatibility, function, end use industry, and region. By product type, the market covers organic, polymer, fatty acids, esters and amides, inorganic, MoDTC, MoS2, graphite, and other. By application, the market covers automobile lubricants, industrial lubricants, rail lubricants, aviation lubricants, power generation lubricants, and others. By base oil compatibility, the market covers mineral oil compatible additives, synthetic oil compatible additives, and bio based oil compatible additives. By function, the market covers anti wear performance, fuel efficiency enhancement, and thermal stability improvement. By end use industry, the market covers automotive industry, manufacturing industry, and energy and power industry. Regions include North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
How does organic product type shape demand?
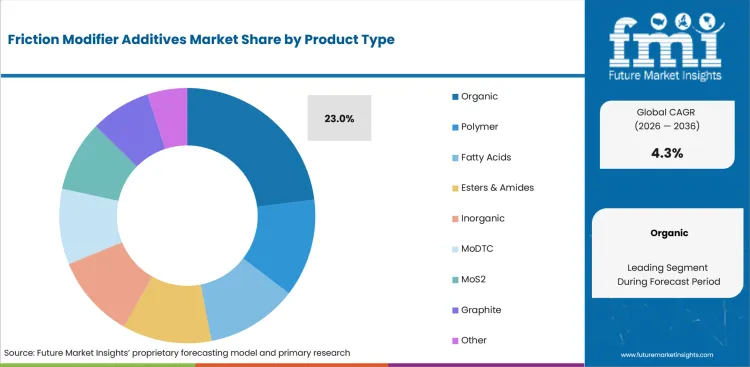
Product type selection determines base oil compatibility and lubrication regime performance. Organic friction modifiers including fatty acid derivatives provide boundary lubrication protection across engine and industrial applications.
- Organic is expected to account for 23.0% of product type demand in 2026.
- Anti Wear Performance is projected to hold 46.0% of function demand as engine and equipment protection remains the primary friction modifier performance requirement.
What supports automobile lubricant application demand?
Automobile lubricant application shapes buyer requirements because segment choice here determines specification compliance, downstream compatibility, and qualification effort for formulators. Demand concentrates here because passenger car and commercial vehicle engine oil formulation volumes generate the largest friction modifier consumption.
- Automobile Lubricants is projected to hold 41.0% of application demand in 2026 because passenger car and commercial vehicle engine oil formulation volumes generate the largest friction modifier consumption.
- Automotive Industry is forecast to represent 52.0% of end-use industry demand as vehicle production and fleet maintenance sustain lubricant additive procurement.
How do base oil compatibility and function shape procurement?
Base oil compatibility and function decide who controls the purchase and how the product reaches the account; together they determine specification compliance, downstream compatibility, and qualification effort for formulators. Demand concentrates here because the large installed mineral oil lubricant production base sustains friction modifier procurement.
- Mineral Oil Compatible Additives is expected to hold 39.0% of base oil compatibility demand in 2026 because the large installed mineral oil lubricant production base sustains friction modifier procurement.
- Anti Wear Performance is anticipated to account for 46.0% of function demand as engine wear protection remains the primary additive performance requirement alongside fuel efficiency enhancement.
What are the drivers, restraints, and opportunities in the Friction Modifier Additives Market?
Near-term procurement is shaped by fuel efficiency mandates, engine oil specification evolution, and EV drivetrain lubricant development.
- Driver: Fuel efficiency regulations and evolving engine oil specifications are expected to push friction modifier procurement as lubricant blenders formulate lower-viscosity products.
- Restraint: EV penetration growth is likely to slow conventional engine oil friction modifier demand if ICE vehicle production declines reduce total lubricant formulation volumes.
- Opportunity: EV drivetrain lubricant development is expected to open supplier access if e-axle and transmission fluid formulations require specialized friction modifier chemistry.
Fuel efficiency mandates are expected to increase friction modifier procurement for lower-viscosity engine oil formulations. Afton Chemical reported in 2025 that its friction modifier portfolio maintained growth across passenger car and heavy-duty engine oil applications.
EV penetration is expected to limit conventional engine oil volumes if ICE vehicle production declines in major automotive markets. IEA reported in 2025 that global EV sales continued to grow, reshaping lubricant demand composition.
EV drivetrain lubricant creates a practical route by requiring friction modifiers optimized for e-axle gear protection and thermal management. Lubrizol reported in 2025 that its EV drivetrain fluid additive portfolio expanded with new friction modifier formulations for electric vehicle transmissions.
Which country CAGRs are profiled in the Friction Modifier Additives Market?
China 5.8%, India 5.3%, Germany 4.9%, UK 4.1%, USA 4.1% through 2036
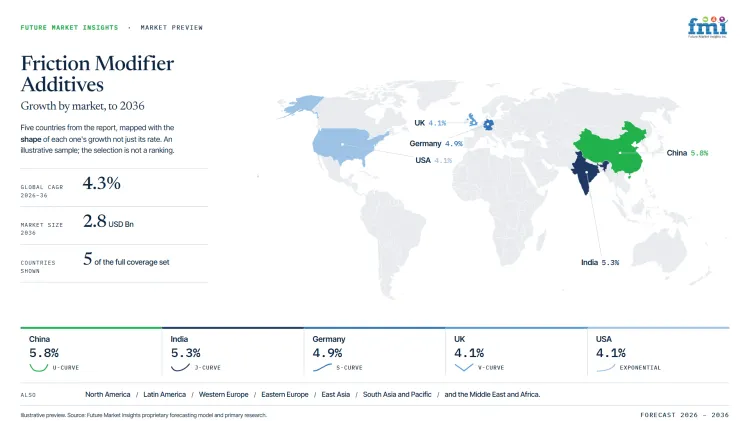
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 5.8% |
| India | 5.3% |
| Germany | 4.9% |
| UK | 4.1% |
| USA | 4.1% |
Source: FMI's proprietary forecasting model and primary research. 5 of the countries covered in the full report are shown here as a representative subset.
How do country-level CAGRs compare in the Friction Modifier Additives Market?
The country comparison spans 1.7 percentage points and reveals three distinct growth groups across the friction modifier additives market. China and India form the upper tier with a 0.5-point difference, while Germany occupies the middle position at 4.9%. The United Kingdom and the United States create the lower group with identical 4.1% CAGRs.
- China leads the comparison at a 5.8% CAGR through 2036, supported by large domestic production capacity, integrated feedstock access and tightening environmental compliance, which are reshaping supplier qualification across industrial clusters.
- India follows at a 5.3% CAGR, remaining 0.5 percentage points below China. Capacity additions, import substitution and export-oriented specialty production are expanding domestic consumption and merchant supply.
- Germany records a 4.9% CAGR, creating a 0.4-percentage-point gap from India. Its integrated chemical industry, energy-cost pressures and strict environmental requirements shape friction modifier additives demand and supplier selection.
- The United Kingdom grows at a 4.1% CAGR, remaining 0.8 percentage points below Germany. Import-reliant supply, compliance-driven specifications and stable downstream formulation demand support a replacement-oriented market.
- The United States also records a 4.1% CAGR, matching the United Kingdom. Established downstream demand, reshoring of specialty production and strict compliance documentation shape supplier qualification and market development.
Comparable CAGRs can still produce different market conditions. Differences in lubricant demand, fuel-economy requirements, electrification, feedstock access, environmental compliance, domestic production capacity and downstream formulation activity influence friction modifier additives demand across countries. The full report provides country-level CAGR analysis across major regions and individual markets within the friction modifier additives market.
Country-wise Analysis
- China's integrated production complexes and direct feedstock access anchor friction modifier additives supply at scale. The Friction Modifier Additives Market in China is projected to record a 5.8% CAGR during the assessment period, supported by large domestic capacity and integrated feedstock access. Organic friction modifiers lead application demand in 2026, concentrating spend on engine-oil additive packages. Environmental-compliance tightening at domestic sites can disrupt friction modifier additives availability and trigger requalification. Friction modifier additives suppliers need consistent purity documentation, compliant sites, and reliable logistics into downstream clusters to hold qualified status.
- India's capacity additions and import substitution are widening the domestic friction modifier additives base. Demand draws on fuel efficiency regulations and evolving engine oil specifications. Sales in India are forecast to expand at a 5.3% CAGR by 2036, supported by capacity additions and import substitution momentum. Reliance on imported feedstock and sharp price competition pressure non-integrated friction modifier additives producers. Friction modifier additives suppliers need reliable feedstock arrangements and consistent export-grade quality to serve scaling formulators.
- German friction modifier additives demand runs through integrated chemical parks and export-oriented specialty manufacturing. The market outlook in Germany is anticipated to advance at a 4.9% CAGR over the assessment period, supported by an integrated chemical industry and specification-led demand. Energy-cost pressure and strict environmental rules constrain domestic capacity economics.Friction modifier additives suppliers need consistent quality and dependable logistics into dense industrial clusters.
- UK friction modifier additives demand is import-based and specified to full compliance documentation. Demand in the United Kingdom is forecast to rise at a 4.1% CAGR over the forecast period, supported by stable downstream formulation demand and compliance-driven specification. Import routing and duplicated UK compliance paperwork add friction modifier additives cost and lead time. Friction modifier additives suppliers need dependable logistics and full regulatory documentation to hold positions with UK formulators.
- US friction modifier additives demand combines established downstream consumption with reshoring of specialty production. Adoption in the United States is estimated to expand at a 4.1% CAGR through 2036, supported by established downstream demand and reshoring of specialty production. Deeply qualified US supply chains make it slow to displace incumbent friction modifier additives producers. Friction modifier additives suppliers need consistent specification compliance and secure logistics to hold long-qualified positions.
Who are the notable companies in the Friction Modifier Additives Market?
Afton Chemical Corporation, The Lubrizol Corporation, Infineum International Limited, BASF SE, Croda International Plc, Evonik Industries AG, Shell plc, and LANXESS AG are the notable companies shaping this market.
The field concentrates around lubricant-additive producers that link friction-modifier chemistry to performance validation and blender supply. Global lubricant additive companies compete across Friction modifier formulations, Lubricant additive packages and Engine oil additive technology throughout established accounts. Specialty chemical and performance additive companies emphasize Bio-based friction modifiers and Performance lubricant additives, while integrated energy and chemical companies serve regional demand through Integrated lubricant solutions. A workable entry is a bio-based or performance friction-modifier niche, or a regional supply position into lubricant blenders. Growth then depends on performance validation, consistent supply, and formulation support into blenders. Breadth pays off through application labs that qualify additive packages and co-develop chemistries with lubricant formulators.
- Afton Chemical Corporation and The Lubrizol Corporation combine Friction modifier formulations and Lubricant additive packages across multiple national markets. Infineum International Limited adds Engine oil additive technology through established account relationships. Their edge comes from additive-package breadth spanning engine-oil and specialty friction modifiers.
- Croda International Plc, Evonik Industries AG and LANXESS AG follow focused routes across Bio-based friction modifiers, Performance lubricant additives and Specialty additive chemistry. Their commercial edge comes from bio-based and performance-additive niches rather than one standardized chemistry.
- Shell plc, Chevron Oronite Company LLC and Sinopec Lubricant Company provide regional coverage through Integrated lubricant solutions. These firms compete on focused friction-modifier strengths, though reach trails the global additive majors.
Competitive Benchmarking: Friction Modifier Additives Market
| Company | Portfolio Relevance | Additive Focus | Account Access | Service Reach |
|---|---|---|---|---|
| Afton Chemical Corporation | High | Friction modifier formulations | Strong | Global |
| The Lubrizol Corporation | High | Lubricant additive packages | Strong | Global |
| Infineum International Limited | High | Engine oil additive technology | Strong | Global |
| BASF SE | Medium | Specialty chemical additives | Strong | Global |
| Croda International Plc | Medium | Bio-based friction modifiers | Strong | Global |
| Evonik Industries AG | Medium | Performance lubricant additives | Strong | Global |
| Shell plc | Medium | Integrated lubricant solutions | Strong | Global |
| LANXESS AG | Medium | Specialty additive chemistry | Strong | Regional |
Source: Future Market Insights competitive analysis, 2026. Ratings reflect relative portfolio relevance, workflow or project fit, service capability, and geographic reach.
Key Developments in the Friction Modifier Additives Market
- In October 2025, LANXESS AG launched an ISCC PLUS-certified, sustainable version of its Additin RC 2515 lubricant additive, cutting the product's carbon footprint by 34% while maintaining extreme-pressure and friction performance for industrial gear oils, metalworking fluids, and heavy metal-free EP greases.
- In 2025, Infineum International Limited completed a new engine oil additive blending facility in India, expanding regional production capacity for engine oil additive packages including friction modifier components to serve India's fast-growing automotive lubricant market.
Key Players in the Friction Modifier Additives Market
Global lubricant additive companies
- Afton Chemical Corporation
- The Lubrizol Corporation
- Infineum International Limited
- BASF SE
Specialty chemical and performance additive companies
- Croda International Plc
- Evonik Industries AG
- LANXESS AG
Integrated energy and chemical companies
- Shell plc
- Chevron Oronite Company LLC
- Sinopec Lubricant Company
Friction Modifier Additives Market: Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type, application, base oil compatibility, function, end use industry, and region. |
| Market Definition | Friction modifier additives include organic, inorganic, and polymer-based chemical compounds added to lubricant formulations to reduce friction, improve fuel efficiency, and extend equipment life across automotive, industrial, rail, aviation, and power generation applications. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa. |
| Countries Covered | United States, China, India, Germany, Brazil, United Kingdom, and Japan. |
| Key Companies Profiled | Afton Chemical Corporation, The Lubrizol Corporation, Infineum International Limited, BASF SE, Croda International Plc, Evonik Industries AG, Shell plc, LANXESS AG. |
| Forecast Period | 2026 to 2036. |
| Approach | FMI used primary interviews, source validation, company authentication, and proprietary demand modeling to estimate market size, segment shares, country CAGRs, and competitive positioning. |
Source: Future Market Insights, analysis driven by proprietary forecasting models and primary research
Friction Modifier Additives Market: Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI interviewed friction modifier additives suppliers, buyers, distributors, and procurement leads. Inputs tested adoption triggers, product preferences, and replacement patterns. |
| Desk Research | Desk research used government releases, regulator updates, standards-body references, company filings, and official product pages. |
| Market Sizing and Forecasting | The forecast model linked 2026 revenue anchors to demand drivers, distribution reach, penetration rates, and country-specific conditions. |
| Data Validation | Data validation reconciled every external statistic against its source. Forecast values were checked against the ten-year CAGR formula. |
Source: Future Market Insights (FMI) analysis, based on proprietary forecasting model and primary research
Market Segmentation Analysis
Friction Modifier Additives Market Segmented by Product Type:
- Organic
- Organic Friction Modifier Compounds
- Improved Fuel Efficiency
- Enhanced Lubrication Performance
- Surface Active Organic Additives
- Reduced Metal Wear
- Improved Thermal Stability
- Organic Friction Modifier Compounds
- Polymer
- High Molecular Polymer Additives
- Enhanced Viscosity Control
- Improved Friction Reduction
- Advanced Synthetic Polymer Modifiers
- Improved Shear Stability
- Extended Lubricant Lifespan
- High Molecular Polymer Additives
- Fatty Acids
- Natural Fatty Acid Additives
- Biodegradable Lubrication Support
- Improved Surface Protection
- Synthetic Fatty Acid Modifiers
- Enhanced Boundary Lubrication
- Reduced Friction Losses
- Natural Fatty Acid Additives
- Esters & Amides
- Synthetic Ester Additives
- Amide Based Friction Modifiers
- Inorganic
- Ceramic Based Additives
- Metallic Inorganic Compounds
- MoDTC
- Molybdenum Dithiocarbamate Additives
- High Performance MoDTC Formulations
- MoS2
- Molybdenum Disulfide Additives
- Nano MoS2 Lubricants
- Graphite
- Natural Graphite Additives
- Synthetic Graphite Modifiers
- Other
Friction Modifier Additives Market Segmented by Application:
- Automobile Lubricants
- Engine Oil Applications
- Improved Fuel Economy
- Enhanced Engine Protection
- Transmission Fluid Additives
- Reduced Mechanical Wear
- Enhanced Vehicle Performance
- Engine Oil Applications
- Industrial Lubricants
- Heavy Machinery Lubrication
- Reduced Equipment Downtime
- Enhanced Operational Efficiency
- Hydraulic System Lubricants
- Improved System Reliability
- Extended Service Life
- Heavy Machinery Lubrication
- Rail Lubricants
- Rail Track Lubrication
- Reduced Wheel Friction
- Enhanced Operational Safety
- Locomotive Engine Lubricants
- Improved Equipment Durability
- Reduced Maintenance Costs
- Rail Track Lubrication
- Aviation Lubricants
- Aircraft Engine Lubricants
- High Temperature Performance
- Enhanced Flight Safety
- Aerospace Hydraulic Lubricants
- Improved System Stability
- Reduced Component Wear
- Aircraft Engine Lubricants
- Power Generation Lubricants
- Turbine Lubrication Systems
- Enhanced Energy Efficiency
- Improved Equipment Reliability
- Generator Bearing Lubricants
- Reduced Operational Failures
- Extended Machinery Lifespan
- Turbine Lubrication Systems
- Others
Friction Modifier Additives Market Segmented by Base Oil Compatibility:
- Mineral Oil Compatible Additives
- Conventional Engine Oil Applications
- Cost Effective Lubrication Solutions
- Wide Industrial Compatibility
- Industrial Mineral Lubricants
- Enhanced Wear Protection
- Improved Operational Stability
- Conventional Engine Oil Applications
- Synthetic Oil Compatible Additives
- High Performance Synthetic Lubricants
- Superior Thermal Stability
- Extended Drain Interval Support
- Fully Synthetic Engine Oils
- Improved Fuel Efficiency
- Enhanced Oxidation Resistance
- High Performance Synthetic Lubricants
- Bio Based Oil Compatible Additives
- Biodegradable Lubrication Systems
- Reduced Environmental Impact
- Improved Sustainability Performance
- Renewable Base Oil Formulations
- Enhanced Eco Friendly Operations
- Industrial Green Lubrication Support
- Biodegradable Lubrication Systems
Friction Modifier Additives Market Segmented by Function:
- Anti Wear Performance
- Surface Protection Additives
- Reduced Metal To Metal Contact
- Extended Equipment Lifespan
- High Load Lubrication Support
- Improved Mechanical Durability
- Enhanced Operational Reliability
- Surface Protection Additives
- Fuel Efficiency Enhancement
- Low Friction Lubrication Systems
- Reduced Energy Consumption
- Improved Vehicle Mileage
- Engine Efficiency Additives
- Optimized Power Transmission
- Reduced Carbon Emissions
- Low Friction Lubrication Systems
- Thermal Stability Improvement
- High Temperature Lubricant Additives
- Improved Oxidation Resistance
- Enhanced System Reliability
- Extreme Condition Lubrication
- Stable Performance Under Stress
- Reduced Lubricant Degradation
- High Temperature Lubricant Additives
Friction Modifier Additives Market Segmented by End Use Industry:
- Automotive Industry
- Passenger Vehicle Lubrication
- Enhanced Engine Performance
- Improved Fuel Economy
- Commercial Vehicle Applications
- Heavy Duty Wear Protection
- Extended Maintenance Intervals
- Passenger Vehicle Lubrication
- Manufacturing Industry
- Industrial Equipment Lubrication
- Improved Machine Efficiency
- Reduced Production Downtime
- Metal Processing Applications
- Enhanced Operational Durability
- Improved Equipment Reliability
- Industrial Equipment Lubrication
- Energy And Power Industry
- Power Plant Lubrication Systems
- Enhanced Turbine Efficiency
- Reduced Maintenance Costs
- Renewable Energy Equipment Lubricants
- Improved Gearbox Protection
- Extended Operational Lifespan
- Power Plant Lubrication Systems
Friction Modifier Additives Market by Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- International Lubricants Standardization and Approval Committee. (2025). GF-7 Gasoline Engine Oil Specification Progress.
- International Energy Agency. (2025). Global EV Outlook and Lubricant Demand Impact.
- Afton Chemical Corporation. (2025). Friction Modifier Portfolio Performance Report.
- The Lubrizol Corporation. (2025). EV Drivetrain Fluid Additive Portfolio Expansion.
- BASF SE. (2025). Lubricant Additive Division Annual Report.
- LANXESS AG. (2025). Sustainable Lubricant Additive for Extreme Pressure Applications — Additin RC 2515 ISCC PLUS Launch. (LANXESS.com press releases, October 29, 2025)
- Society of Automotive Engineers. (2025). Engine Oil Specification and Test Method Updates.
- Verband der Automobilindustrie Germany. (2025). Automotive Lubricant Specification Standards.
- Japan Automobile Standards Internationalization Center. (2025). JASO Engine Oil Standard Assessment.
- Petroleum Planning and Analysis Cell India. (2025). Lubricant Production and Consumption Statistics.
- China Petroleum and Chemical Industry Federation. (2025). Lubricant Additive Market Report.
This bibliography is provided for reader reference and uses primary government sources plus standards-body sources. Company sources are included.
This Report Answers
- What is the estimated 2026 value of the friction modifier additives market?
- What market value is projected by 2036?
- What CAGR is forecast from 2026 to 2036?
- Which product type is expected to account for a notable 2026 share?
- Which countries are profiled for CAGR comparison?
- Which companies are notable in the competitive landscape?
Frequently Asked Questions
How big is the Friction Modifier Additives Market in 2026?
The Friction Modifier Additives Market is valued at USD 1.8 billion in 2026 and is forecast to reach USD 2.8 billion by 2036, expanding at a 4.3% CAGR. The Friction Modifier Additives Market grew from USD 1.8 billion in 2025, with Organic holding 23.0% of product type demand in 2026.
What is the CAGR of the Friction Modifier Additives Market from 2026 to 2036?
The Friction Modifier Additives Market is projected to grow at a CAGR of 4.3% between 2026 and 2036, supported by tightening fuel efficiency mandates and evolving engine oil specifications that require advanced friction modifier chemistry. Organic holds 23.0% of Friction Modifier Additives Market product type demand in 2026, while Automobile Lubricants leads application with 41.0% in 2026.
Which product type leads the Friction Modifier Additives Market?
Organic accounts for 23.0% of the Friction Modifier Additives Market by product type in 2026, driven by tightening fuel efficiency mandates and evolving engine oil specifications that require advanced friction modifier. The Friction Modifier Additives Market grows at a 4.3% CAGR through 2036, while Automobile Lubricants leads application with 41.0% in 2026.
How much will the Friction Modifier Additives Market add between 2026 and 2036?
The Friction Modifier Additives Market is set to add USD 1.0 billion between 2026 and 2036, growing from USD 1.8 billion to USD 2.8 billion at a 4.3% CAGR. Automobile Lubricants leads application with 41.0% of Friction Modifier Additives Market revenue in 2026, anchoring that incremental demand.
Who are the leading companies in the Friction Modifier Additives Market?
The Friction Modifier Additives Market profiles 8 key companies in 2026, led by Afton Chemical Corporation, The Lubrizol Corporation, Infineum International Limited, BASF SE, and Croda International Plc. These suppliers compete across product type, where Organic holds 23.0% of Friction Modifier Additives Market demand in 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Organic
- Organic Friction Modifier Compounds
- Surface Active Organic Additives
- Polymer
- High Molecular Polymer Additives
- Advanced Synthetic Polymer Modifiers
- Fatty Acids
- Natural Fatty Acid Additives
- Synthetic Fatty Acid Modifiers
- Esters & Amides
- Synthetic Ester Additives
- Amide Based Friction Modifiers
- Inorganic
- Ceramic Based Additives
- Metallic Inorganic Compounds
- MoDTC
- Molybdenum Dithiocarbamate Additives
- High Performance MoDTC Formulations
- MoS2
- Molybdenum Disulfide Additives
- Nano MoS2 Lubricants
- Graphite
- Natural Graphite Additives
- Synthetic Graphite Modifiers
- Other
- Organic
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Automobile Lubricants
- Engine Oil Applications
- Transmission Fluid Additives
- Industrial Lubricants
- Heavy Machinery Lubrication
- Hydraulic System Lubricants
- Rail Lubricants
- Rail Track Lubrication
- Locomotive Engine Lubricants
- Aviation Lubricants
- Aircraft Engine Lubricants
- Aerospace Hydraulic Lubricants
- Power Generation Lubricants
- Turbine Lubrication Systems
- Generator Bearing Lubricants
- Others
- Automobile Lubricants
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Base Oil Compatibility, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Base Oil Compatibility, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Base Oil Compatibility, 2026 to 2036
- Mineral Oil Compatible Additives
- Conventional Engine Oil Applications
- Industrial Mineral Lubricants
- Synthetic Oil Compatible Additives
- High Performance Synthetic Lubricants
- Fully Synthetic Engine Oils
- Bio Based Oil Compatible Additives
- Biodegradable Lubrication Systems
- Renewable Base Oil Formulations
- Mineral Oil Compatible Additives
- Y-o-Y Growth Trend Analysis By Base Oil Compatibility, 2021 to 2025
- Absolute $ Opportunity Analysis By Base Oil Compatibility, 2026 to 2036
- Global Market Analysis and Forecast, By Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Function, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Function, 2026 to 2036
- Anti Wear Performance
- Surface Protection Additives
- High Load Lubrication Support
- Fuel Efficiency Enhancement
- Low Friction Lubrication Systems
- Engine Efficiency Additives
- Thermal Stability Improvement
- High Temperature Lubricant Additives
- Extreme Condition Lubrication
- Anti Wear Performance
- Y-o-Y Growth Trend Analysis By Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Function, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use Industry, 2026 to 2036
- Automotive Industry
- Passenger Vehicle Lubrication
- Commercial Vehicle Applications
- Manufacturing Industry
- Industrial Equipment Lubrication
- Metal Processing Applications
- Energy And Power Industry
- Power Plant Lubrication Systems
- Renewable Energy Equipment Lubricants
- Automotive Industry
- Y-o-Y Growth Trend Analysis By End Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Base Oil Compatibility
- By Function
- By End Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Afton Chemical Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Lubrizol Corporation
- Infineum International Limited
- BASF SE
- Croda International Plc
- Chevron Oronite Company LLC
- Royal Dutch Shell Plc
- Evonik Industries AG
- Tianhe Chemicals Group
- Vanderbilt Chemicals LLC
- LANXESS AG
- Sinopec Lubricant Company
- Adeka Corporation
- MidContinental Chemical Company
- King Industries, Inc.
- Afton Chemical Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


