
- Market Size (2026)
- USD 16.9 Bn
- Forecast (2036)
- USD 28.1 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Frozen Pet Food Market in 2026?
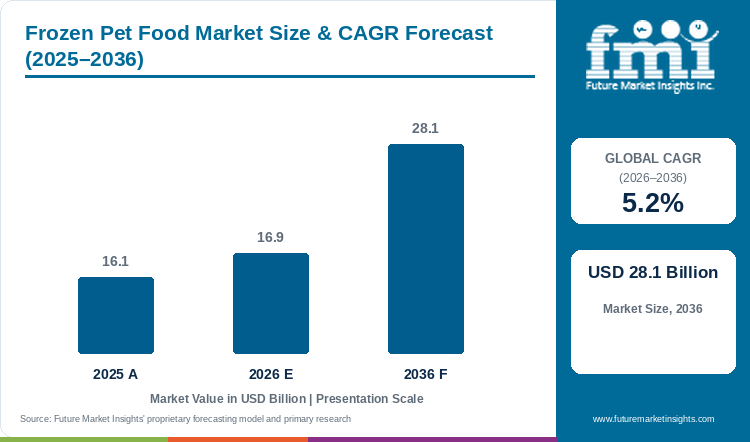
The global frozen pet food market is valued at USD 16.1 billion in 2025, reaches USD 16.9 billion in 2026, and is projected to reach USD 28.1 billion by 2036 at a 5.2% CAGR.
Pet owner preference for minimally processed, high-moisture dog and cat meals over dry extruded kibble is reshaping retail freezer aisles and direct-to-home subscription delivery, lifting the global frozen pet food market from USD 16.1 billion in 2025 to USD 16.9 billion in 2026. Over the 2026 to 2036 assessment period, category turnover is forecast to expand at a 5.2% CAGR to reach USD 28.1 billion, creating USD 11.2 billion in added commercial value as canine recipes generate 73.9% of species demand and High-Pressure Pasteurized (HPP) raw rations secure 56.9% by processing method. Veterinary clinics and pet specialty retailers regularly require validated pressure or low-temperature cooking steps before stocking commercial frozen pet diets, a safety measure reinforced by an October 2025 study in the Journal of Food Protection (PubMed) documenting H5N1 avian influenza risks in untreated raw pet foods and milk as well as industry liability [1]. Despite strong subscription retention, costly dry-ice parcel shipping and limited freezer door space in mainstream supermarkets still hold back wider household conversion.
Key Market Trends & Insights
- By companion species: Canine Raw & Gently Cooked Diets are projected to capture 73.9% in 2026 because medium and large dogs consume four to five times more daily food mass than indoor cats.
- By processing method: High-Pressure Pasteurized Raw Frozen BARF is estimated to command 56.9% in 2026 as 600 MPa cold pressure achieves a 5-log pathogen kill without cooking native enzymes.
- By protein source: Beef, Chicken & Turkey Muscle/Organ Blends are expected to concentrate 62.9% in 2026 because skeletal meat paired with liver and heart provides complete amino acid profiles.
- By portion format: Pre-Portioned Patties, Medallions & Pourable Bites are forecast to generate 51.3% in 2026 owing to scoop-and-serve convenience and 25%-caloric kibble topper usage.
- By channel, tier & scale: Personalized D2C Cold-Chain Subscriptions lead channels at 45.7% in 2026, while Mid-Tier Mainstream Brands hold 51.8% by price tier and Multinational CPG and Food Processors command 54.3% by buyer scale.
Regional Highlights
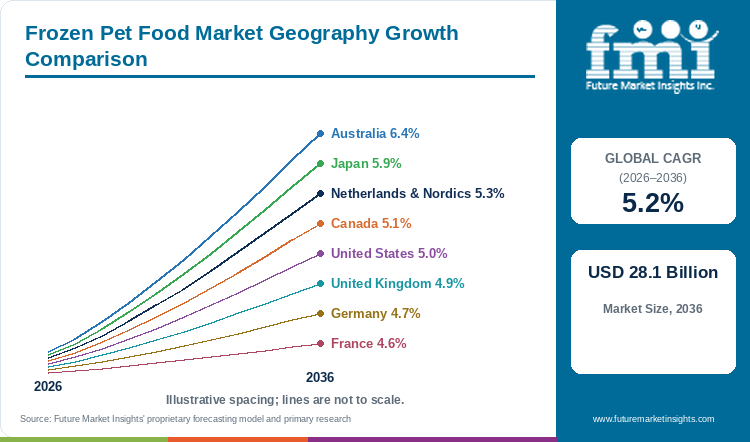
- Top national expansion: Australia is projected to lead national growth at a 6.4% CAGR through 2036 supported by domestic human-grade beef and kangaroo supply and supermarket freezer chests.
- Broader country progression: Japan is expected to expand at 5.9% CAGR ahead of the United States at 5.0% and the United Kingdom at 4.9%, while Germany is forecast to advance at a 4.7% yearly pace.
Market Size & Forecast
Table 1: Market Size and Forecast for the Frozen Pet Food Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 16.1 billion |
| Estimated Market Size in 2026 | USD 16.9 billion |
| Projected Market Size by 2036 | USD 28.1 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Value, 2026 to 2036 | USD 11.2 billion |
Pet specialty retailers and veterinary clinics confront strict federal enforcement against Salmonella, Listeria monocytogenes, and Highly Pathogenic Avian Influenza (H5N1) in minimally processed companion animal rations. Unpasteurized backyard grinds expose multi-pet households to zoonotic cross-contamination and fatal feline viral infections. In July 2025, veterinary nutrition researchers published in Frontiers in Veterinary Science (PubMed) called for harmonizing the definitions of raw meat-based diets and biologically appropriate companion animal nutrition across raw and fresh canine diets [2]. Consequently, commercial brands pair 600 MPa HPP or 74-degree sous-vide cooking with PCR test-and-hold batch release.
Companion-Animal Cohort and Cold-Chain Tonnage Sizing
Table 2: Companion-Animal Cohort and Cold-Chain Tonnage Sizing for the Frozen Pet Food Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 16.1 | 16.9 | 28.1 |
| Companion dogs & cats on frozen/topper plans (million) | 24.5 to 27.0 | 26.0 to 28.5 | 41.0 to 45.5 |
| Commercial frozen output (million MT) | 1.45 to 1.60 | 1.52 to 1.68 | 2.40 to 2.65 |
| Avg. daily feeding spend per pet (USD) | 1.65 to 4.80 | 1.70 to 4.95 | 1.95 to 5.60 |
Operational note: Tonnage and daily ration ranges reflect complete-and-balanced full-bowl feeding (350g-650g/day for dogs; 110g-160g/day for cats) blended with 25%-caloric topper adoption across cold-chain channels.
Eliminating manual knife slicing and messy raw-meat thawing in household kitchens has accelerated consumer migration toward IQF pourable nuggets and pre-portioned flat-pack pouches. Manufacturers routinely co-merchandise frozen raw medallions as well as freeze-dried companion animal rations.
Per Pet & Retail Freezer Door Spending Sizing
Table 3: Per Capita and Facility Spending Indicators for the Frozen Pet Food Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 1,963.4 | 2,036.1 | 3,122.2 |
| Annual spend per subscribing pet household (USD) | 580.0 to 1,420.0 | 610.0 to 1,480.0 | 720.0 to 1,750.0 |
| D2C cold-chain subscription share (%) | 45.2% | 45.7% | 46.8% to 48.0% |
Table 4: Commercial & Institutional Spending Indicators for the Frozen Pet Food Market (USD billion and percentages), 2026
| Metric | Value | Commercial Reference Basis |
|---|---|---|
| Market size, 2026 | USD 16.9 billion | 2026 global manufacturer & D2C baseline |
| Canine Raw & Gently Cooked Allocation | USD 12.49 billion | 73.9% companion species share in 2026 |
| HPP Raw Frozen BARF Allocation | USD 9.62 billion | 56.9% processing method share in 2026 |
| Multinational CPG Processor Scale | USD 9.18 billion | 54.3% buyer/operator scale share in 2026 |
Mainstream grocery adoption requires bridging the daily feeding cost gap between extruded dry kibble and human-grade frozen rations. Multinational CPG brands now roll out mid-tier resealable meatball pouches and sliceable rolls positioned as daily meal mixers within the broader global pet nutrition sector.
Analyst Perspective
"Biosecurity validation and portion convenience now separate category leaders from regional casualties in frozen pet nutrition. Manufacturers combining 600 MPa High-Pressure Pasteurization or USDA human-grade sous-vide kitchens with pourable topper formats are capturing both D2C subscriptions and supermarket freezer doors."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the frozen pet food market segmented?
The frozen pet food market is segmented by companion species, processing method, protein source, portion format, distribution channel, price tier, and buyer scale. In 2026, Canine Raw & Gently Cooked Diets is projected at 73.9%, High-Pressure Pasteurized Raw Frozen BARF at 56.9%, Beef, Chicken & Turkey Muscle/Organ Blends at 62.9%, Pre-Portioned Patties, Medallions & Pourable Bites at 51.3%, Personalized D2C Cold-Chain Subscriptions at 45.7%, Mid-Tier Mainstream Brands at 51.8%, and Multinational CPG and Food Processors at 54.3%.
By companion species: Canine Raw & Gently Cooked Diets and Feline Obligate-Carnivore Medallions.
By processing method: High-Pressure Pasteurized Raw Frozen BARF and Gently Sous-Vide Cooked Human-Grade Frozen.
By protein source: Beef, Chicken & Turkey Muscle/Organ Blends and Novel Venison, Duck, Rabbit, Kangaroo & Salmon.
By portion format: Pre-Portioned Patties, Medallions & Pourable Bites and Chub Rolls & Flat-Pack Meal Pouches.
By channel, price tier & buyer scale: Personalized D2C Cold-Chain Subscriptions (45.7%), Independent Pet Specialty Freezer Chests (31.8%), and Supermarkets & Veterinary Clinics (22.5%); Mid-Tier Mainstream Brands (51.8%), Premium Specialty and Artisanal (32.6%), and Private-Label and Economy (15.6%); Multinational CPG and Food Processors (54.3%), Regional Mid-Market Food Brands (29.4%), and Artisanal and Independent Foodservice Buyers (16.3%).
Why do Canine Raw & Gently Cooked Diets lead the companion species category?
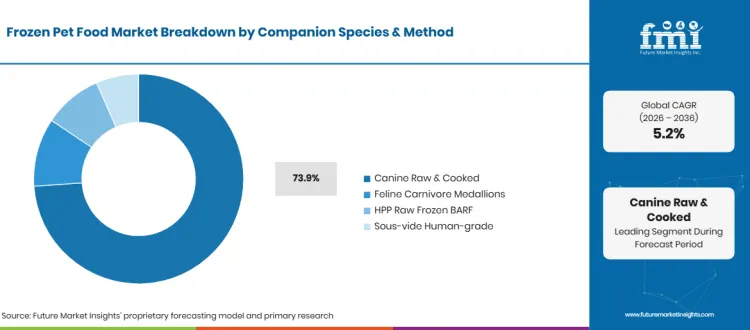
Canine Raw & Gently Cooked Diets are projected to capture 73.9% of companion species demand in 2026, supported by higher per-dog daily caloric intake and D2C subscription adoption.
Table 5: Companion Species Share for the Frozen Pet Food Market (percentage share), 2026
| Companion Species | Share (2026) |
|---|---|
| Canine Raw & Gently Cooked Diets | 73.9% |
| Feline Obligate-Carnivore Medallions | 26.1%* |
| Total | 100.0% |
*Note: Remaining companion species categories sum to 100.0% of 2026 commercial volume.
Table 6: Companion Species Leadership and Market Growth for the Frozen Pet Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Canine Raw & Gently Cooked Diets (73.9%) |
Dog owners represent the primary subscription and retail freezer cohort because canine daily caloric requirements exceed feline intake by fourfold and owners actively seek high-digestibility rations to manage canine skin allergies and stool quality across specialized canine nutrition categories.
- Canine Raw & Gently Cooked Diets are projected to secure 73.9% of companion species demand in 2026 by anchoring D2C human-grade pouches and retail HPP patty sales.
- A July 2025 genomic surveillance study published in Scientific Reports (PubMed) identified multidrug-resistant Salmonella enterica in pet dogs and cats, confirming the necessity of pasteurized commercial canine diets [3].
Why does High-Pressure Pasteurized Raw Frozen BARF define the largest processing method segment?
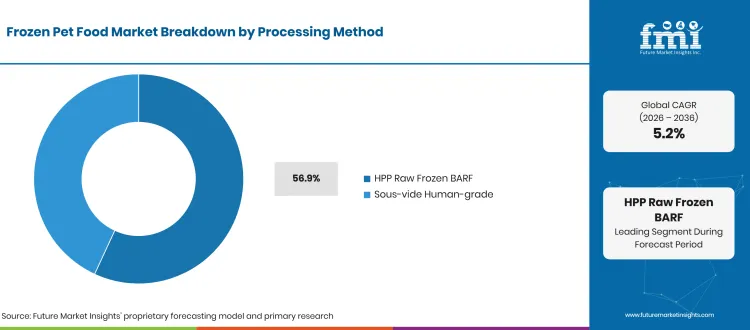
High-Pressure Pasteurized Raw Frozen BARF is estimated to secure 56.9% of the processing method category in 2026, driven by 600 MPa non-thermal pathogen inactivation.
Subjecting vacuum-sealed raw muscle, bone, and organ blends to 600 MPa of cold hydrostatic pressure for three to five minutes achieves a validated 5-log reduction in Salmonella, E. coli, Listeria, and avian influenza while preserving raw protein bioavailability as well as specialized feline wet and frozen meals.
- High-Pressure Pasteurized Raw Frozen BARF is estimated to command 56.9% of the processing method segment in 2026 as raw-feeding advocates demand pathogen-free biological nutrition.
- Veterinary microbiology surveillance published in Antibiotics (Basel) in March 2026 documented antimicrobial-resistant bacteria and Campylobacter in untreated commercial raw pet foods in Belgium, validating industry conversion to HPP [4].
What keeps Beef, Chicken & Turkey Muscle/Organ Blends ahead by protein source?
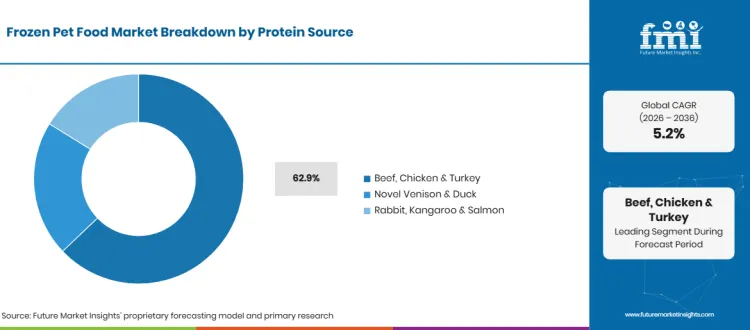
Beef, Chicken & Turkey Muscle/Organ Blends are expected to command 62.9% of protein source volume in 2026, supported by complete amino-acid and organ micronutrient density.
USDA- and EU-inspected beef chuck, boneless chicken, turkey thigh, and nutrient-dense beef liver and heart provide abundant taurine, iron, and bioavailable amino acids at stable contract pricing for human-grade pet nutrition benchmarks.
- Beef, Chicken & Turkey Muscle/Organ Blends are expected to hold 62.9% of protein source sales in 2026 because poultry and beef anchor everyday canine and feline palatability.
- Clinical diagnostic monitoring published in the New Zealand Veterinary Journal in July 2025 tracked bacterial susceptibility patterns in canine and feline samples, supporting hygienic veterinary-grade protein sourcing [5].
Why do Pre-Portioned Patties, Medallions & Pourable Bites lead the portion format category?
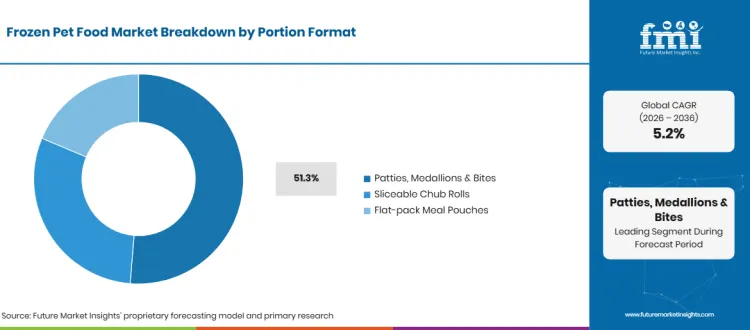
Pre-Portioned Patties, Medallions & Pourable Bites are forecast to generate 51.3% of portion format value in 2026, owing to zero-prep scoop-and-serve mealtime convenience.
Cryogenically frozen IQF nuggets, 1-ounce medallions, and calibrated 8-ounce patties thaw in minutes inside the pet bowl and allow owners to scoop exact gram weights with zero raw-meat hand contact.
- Pre-Portioned Patties, Medallions & Pourable Bites are forecast to account for 51.3% of portion format demand in 2026 as busy pet parents use pourable bites both as complete meals and kibble toppers.
- A January 2026 whole-genome sequencing study in Frontiers in Microbiology emphasized managing multidrug-resistant Pseudomonas aeruginosa in companion animals through strict kitchen hygiene and no-touch feeding formats [6].
What gives Personalized D2C Subscriptions, Mid-Tier Brands & Multinational CPGs the leading positions?
Personalized D2C Cold-Chain Subscriptions (45.7%), Mid-Tier Mainstream Brands (51.8%), and Multinational CPG and Food Processors (54.3%) lead their respective channel, price tier, and scale categories in 2026.
Algorithmic D2C onboarding questionnaires calculate breed, age, body-condition, and activity-adjusted daily calorie packs shipped on 2-to-6-week cadences, while multinational CPG processors scale mid-tier mainstream frozen rolls and bites across supermarket coolers.
- Personalized D2C Cold-Chain Subscriptions capture 45.7% of channel revenue in 2026, while Mid-Tier Mainstream Brands hold 51.8% of price tier sales and Multinational CPG and Food Processors command 54.3% of buyer scale.
- A June 2025 clinical study in Antibiotics (Basel) characterizing methicillin-resistant staphylococci in dogs and cats further reinforced veterinary advocacy for biosecure, factory-sealed cold-chain nutrition [7].
What are the drivers, restraints, and opportunities in the frozen pet food market?
In the frozen pet food market, veterinary digestibility recommendations and HPP/sous-vide biosecurity expand subscription cohorts whereas dry-ice parcel freight costs restrain full-bowl adoption and pourable kibble toppers create mid-tier growth opportunities.
- Driver: Veterinary digestibility recommendations, pet humanization, and FDA H5N1/Salmonella preventive-control mandates accelerate adoption of HPP raw and human-grade sous-vide frozen meals.
- Restraint: High dry-ice parcel shipping costs (USD 12-22 per box), household freezer space limits, and zoonotic recall liability on unpasteurized raw poultry restrain full-bowl conversion.
- Opportunity: Pourable IQF meal-topper bites, feline obligate-carnivore high-moisture medallions, and hypoallergenic novel proteins (venison, rabbit, duck, kangaroo) deliver high-margin growth.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Veterinarians and pet parents managing canine chronic enteropathies, pruritic skin allergies, and feline lower urinary tract disease are replacing high-starch extruded kibble with high-moisture (70%+), gently cooked or HPP raw diets that complement veterinary therapeutic pet diets. In September 2026, a genomic survey in Veterinary Microbiology analyzing vancomycin- and linezolid-resistant enterococci in dogs and cats confirmed the clinical importance of biosecure dietary management [8].
Risk Assessment of the Frozen Pet Food Market: Operational and Formulation Friction
Zoonotic viral and bacterial contamination represents the sharpest operational risk in the frozen pet food sector. Following confirmed feline deaths from Highly Pathogenic Avian Influenza (H5N1) in unpasteurized raw poultry and raw milk, the U.S. Food and Drug Administration (FDA) Center for Veterinary Medicine directed all cat and dog food processors to integrate H5N1 hazard controls into their FSMA Preventive Controls Food Safety Plans as well as certified organic companion animal diets [9]. Brands lacking validated thermal or 600 MPa HPP lethality face regulatory enforcement and retailer delisting.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Formulating high-palatability feline obligate-carnivore medallions and mid-tier canine pourable meal toppers allows manufacturers to capture multi-cat urban households and cost-conscious kibble mixers simultaneously. Pairing 95% meat/organ/bone ratios with natural yeast and bone-broth aroma enhancers aligns with natural pet food palatability systems. In January 2025, the American Veterinary Medical Association (AVMA) documented the clinical and commercial requirement of validated pathogen inactivation following bird-flu-linked raw pet food recalls [10].
Frozen Pet Food Market by Country (2026 to 2036)
As per FMI, Australia is projected to lead frozen pet food expansion at a 6.4% CAGR through 2036, followed by Japan at 5.9% and the United States at 5.0%, while the United Kingdom (4.9%) and Germany (4.7%) anchor European cold-chain volume. National performance depends on D2C cold-storage fulfillment density, supermarket pet cooler installations, and veterinary biosecurity regulations.
Table 7: Country CAGR and Primary Growth Levers for the Frozen Pet Food Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 6.4% | Domestic human-grade beef/kangaroo supply and Coles/Woolworths freezer chests |
| Japan | 5.9% | Single-serve gently cooked frozen gourmet trays for toy and small-breed pets |
| Netherlands & Nordics | 5.3% | Strict Salmonella-free meat standards and high digital D2C subscription adoption |
| Canada | 5.1% | Pet Valu specialty freezer networks and cross-border CPG cooler rollouts |
| United States | 5.0% | The Farmer's Dog, NOM NOM, Stella & Chewy's, Instinct, and Blue Buffalo Love Made Fresh |
| United Kingdom | 4.9% | Butternut Box gently cooked subscriptions and Pets at Home raw BARF freezer aisles |
| Germany | 4.7% | Established BARF raw feeding culture and Fressnapf cold-chain retail |
| France | 4.6% | Veterinary-recommended gently cooked diets and specialty pet store coolers |
Source: Future Market Insights analysis
United States Frozen Pet Food Market Outlook (2026 to 2036)
The United States frozen pet food market is projected to expand at a 5.0% CAGR from USD 7.45 billion in 2026 to USD 12.14 billion by 2036. Demand is anchored by The Farmer's Dog's nationwide D2C subscription network, Mars Petcare's NOM NOM and ORIJEN FreshPrey, Stella & Chewy's, Nature's Variety (Instinct FreshRaw), Primal Pet Foods, and General Mills' Blue Buffalo Love Made Fresh retail rollout. In May 2026, a CDC Morbidity and Mortality Weekly Report (MMWR) investigation of H5N1 serologic evidence in veterinary personnel exposed to infected cats reinforced strict federal and state biosecurity protocols for raw and frozen pet diets [11].
Key takeaway: In the United States, D2C human-grade subscriptions and multinational CPG grocery cooler rollouts sustain a 5.0% CAGR through 2036.
United Kingdom Frozen Pet Food Market Outlook (2026 to 2036)
Commercial frozen pet food turnover in the United Kingdom is forecast to rise at a 4.9% CAGR from USD 1.70 billion in 2026 to USD 2.74 billion by 2036. Growth is propelled by Butternut Box's gently cooked D2C subscriptions and dedicated frozen raw BARF aisles across Pets at Home and independent pet shops stocking HPP-validated raw meals such as Instinct FreshRaw Meals introduced in July 2025 [12].
Key takeaway: In the United Kingdom, Pets at Home freezer expansion and gently cooked D2C subscriptions underpin a 4.9% annual growth pace.
Germany Frozen Pet Food Market Outlook (2026 to 2036)
Germany is expected to advance at a 4.7% CAGR between 2026 and 2036, growing from USD 1.42 billion in 2026 to USD 2.25 billion by 2036. German dog owners exhibit the highest per-capita adherence to Biologically Appropriate Raw Food (BARF) feeding in continental Europe, supported by Fressnapf freezer chests and veterinary research investments led by global human-grade subscription platforms [13].
Key takeaway: In Germany, deeply entrenched BARF raw feeding culture and specialty pet superstore freezers support a 4.7% CAGR.
Australia Frozen Pet Food Market Outlook (2026 to 2036)
Australia leads global country-level expansion at a 6.4% CAGR through 2036, rising from USD 0.95 billion in 2026 to USD 1.77 billion by 2036. Coles, Woolworths, and Petbarn allocate multi-door chilled and frozen bays to domestic human-grade beef, lamb, and wild kangaroo pet rations as well as protein-rich fresh/frozen launches such as Mars Petcare / Champion Petfoods' ORIJEN FreshPrey introduced in March 2026 [14].
Key takeaway: In Australia, abundant human-grade beef and kangaroo supply paired with mainstream supermarket freezer doors drives a 6.4% CAGR.
Japan Frozen Pet Food Market Outlook (2026 to 2036)
Japan is projected to expand at a 5.9% CAGR over 2026 to 2036, increasing from USD 0.78 billion in 2026 to USD 1.38 billion by 2036. Owners of toy and miniature dog breeds and indoor cats purchase single-serve gently cooked frozen gourmet trays to support healthy senior pet aging, a benefit supported by Cornell University and The Farmer's Dog's October 2025 metabolomic aging study [15].
Key takeaway: In Japan, ultra-premium single-serve frozen meals for small-breed dogs and indoor cats sustain a 5.9% CAGR.
Canada Frozen Pet Food Market Outlook (2026 to 2036)
Canada is anticipated to progress at a 5.1% CAGR through 2036, supported by Pet Valu and Homes Alive Pets freezer networks as well as cross-border expansion of North American fresh/frozen CPG brands such as Blue Buffalo Love Made Fresh and Edgard & Cooper [16].
Key takeaway: In Canada, specialty pet boutique freezer chains and cross-border CPG launches drive a 5.1% CAGR.
France Frozen Pet Food Market Outlook (2026 to 2036)
France is forecast to grow at a 4.6% CAGR between 2026 and 2036 as Jardiland, Maxi Zoo, and veterinary clinics expand refrigerated and frozen human-grade dog and cat meal cabinets while enforcing strict public health monitoring against H5 avian influenza in raw pet food [17].
Key takeaway: In France, veterinary-recommended gently cooked rations and garden-center pet freezers support a 4.6% CAGR.
Netherlands & Nordics Frozen Pet Food Market Outlook (2026 to 2036)
Northern European markets (Netherlands, Sweden, Denmark) are slated to expand at a 5.3% CAGR through 2036, supported by strict Salmonella-free meat inspection standards aligned with USDA FSIS and EU Category 3 verification programs [18].
Key takeaway: In Northern Europe, zero-tolerance Salmonella meat standards and high digital D2C subscription adoption sustain a 5.3% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the frozen pet food market?
Nature's Variety (Instinct), Stella & Chewy's LLC, The Farmer's Dog, Inc., Mars Petcare Inc. (NOM NOM, ORIJEN), Primal Pet Foods, Inc., General Mills, Inc. (Blue Buffalo), Freshpet, Inc., and Butternut Box are the notable companies in the frozen pet food market.
FMI analysis indicates that the global frozen pet food competitive arena divides between multinational CPG and petcare conglomerates (54.3% share), direct-to-consumer human-grade subscription platforms, and High-Pressure Pasteurized (HPP) raw BARF specialists.
- Multinational CPG & Petcare Conglomerates: Mars Petcare Inc. (NOM NOM, ORIJEN FreshPrey) and General Mills, Inc. (Blue Buffalo Love Made Fresh) as well as Nature's Variety (Agrolimen/Instinct) use global cold-chain and grocery scale.
- D2C Human-Grade Subscription Leaders: The Farmer's Dog, Inc. and Butternut Box operate algorithmic, veterinary-formulated sous-vide frozen meal delivery platforms.
- HPP Raw BARF & Pet Specialty Pioneers: Stella & Chewy's LLC and Primal Pet Foods, Inc. anchor independent pet specialty freezer chests with 600 MPa HPP raw patties, morsels, and gently cooked FreshMade recipes.
Competitive Benchmarking: Frozen Pet Food Market
Table 8: Competitive Benchmarking for the Frozen Pet Food Market (qualitative capability ratings), 2026
| Company | Species & Protein Breadth | HPP / Sous-Vide Safety Tech | D2C / Retail Freezer Access | Geographic Reach |
|---|---|---|---|---|
| Nature's Variety (Instinct) | High | High | High | High |
| Stella & Chewy's LLC | High | High | High | Medium |
| The Farmer's Dog, Inc. | Medium | High | High | Medium |
| Mars Petcare Inc. (NOM NOM) | High | High | High | High |
| Primal Pet Foods, Inc. | High | High | High | Medium |
| General Mills (Blue Buffalo) | Medium | High | High | High |
| Freshpet, Inc. | High | High | High | High |
| Butternut Box | Medium | High | High | Medium |
Scoring basis: Capability tiers evaluate companion species and novel protein breadth, validated pathogen-kill technology (600 MPa HPP and USDA human-grade sous-vide), D2C and supermarket freezer access, and multi-region cold-chain reach.
Key Developments in the Frozen Pet Food Market
- General Mills, Inc. and Blue Buffalo launched 'Love Made Fresh' nationwide across U.S. retail coolers in October 2025 to enter the USD 3 billion+ fresh and frozen pet food category [19].
- The U.S. Food and Drug Administration (FDA) issued an August 2026 compliance warning letter to Raaw Energy LLC reinforcing zero-tolerance enforcement against pathogen contamination in commercial raw frozen pet food facilities [20].
- General Mills reported in September 2026 that Blue Buffalo Love Made Fresh fourth-quarter sales surged 80% as well as double-digit Tiki Cat growth after scaling retail cooler distribution [21].
Key Players in the Frozen Pet Food Market
Multinational Petcare & CPG Processors
- Mars Petcare Inc. (NOM NOM)
- Nature's Variety (Instinct)
- General Mills, Inc. (Blue Buffalo)
D2C Human-Grade & Refrigerated/Frozen Leaders
- The Farmer's Dog, Inc.
- Freshpet, Inc.
- Butternut Box
HPP Raw Frozen BARF & Specialty Pioneers
- Stella & Chewy's LLC
- Primal Pet Foods, Inc.
Frozen Pet Food Market - Report Scope
Table 9: Report Scope for the Frozen Pet Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Companion Species; Processing Method; Protein Source; Portion Format; Distribution Channel; Price Tier; Buyer Scale |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from High-Pressure Pasteurized (HPP) raw frozen BARF diets and gently sous-vide/steamed human-grade cooked frozen meals and toppers for dogs and cats distributed in sub-zero or chilled cold chains. Excludes dry extruded kibble and retorted cans. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, United Kingdom, Germany, Australia, Japan, Canada, France, Netherlands, and additional countries in the full report |
| Key Companies Covered | Nature's Variety, Stella & Chewy's LLC, The Farmer's Dog, Inc., Mars Petcare Inc., Primal Pet Foods, Inc., General Mills, Inc., Freshpet, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Frozen Pet Food Market - Research Methodology
Table 10: Research Methodology for the Frozen Pet Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with board-certified veterinary nutritionists (DACVIM), HPP tolling directors, D2C cold-chain logistics executives, and pet specialty/supermarket freezer category buyers. |
| Secondary Research | Analysis of FDA Center for Veterinary Medicine (CVM) H5N1 updates and Warning Letters, CDC MMWR reports, USDA FSIS Salmonella verification reports, corporate press releases, and PubMed veterinary microbiology studies. |
| Market Sizing and Forecasting | Top-down D2C active subscriber cohorts and retail freezer scanner sales reconciled against bottom-up HPP tolling capacity and USDA/EU Category 3 meat allocations from 2026 to 2036. |
| Country Forecasting Model | Econometric projections weight pet humanization expenditure, D2C 1-to-2-day ground cold-chain coverage, and supermarket pet cooler installations across key national markets. |
| Operational Benchmark Traceability | Feeding cohorts, pathogen lethality, and spend indicators in Tables 2, 3, and 4 trace to Journal of Food Protection, Scientific Reports, and Antibiotics studies in PubMed as well as FDA 21 CFR Part 507 standards. |
| Data Triangulation and Validation | Demand estimates are cross-checked against commercial cold-storage throughput and retail scanner data without double counting ambient freeze-dried treats. |
Frozen Pet Food Market by Segments
Frozen Pet Food Market segmented by Companion Species & Method:
- Canine Raw & Cooked
- Feline Carnivore Medallions
- HPP Raw Frozen BARF
- Sous-Vide Human-Grade
Frozen Pet Food Market segmented by Protein Source:
- Beef, Chicken & Turkey
- Novel Venison & Duck
- Rabbit, Kangaroo & Salmon
Frozen Pet Food Market segmented by Portion Format:
- Patties, Medallions & Bites
- Sliceable Chub Rolls
- Flat-Pack Meal Pouches
Frozen Pet Food Market segmented by Distribution Channel:
- D2C Cold-Chain Subscriptions
- Pet Specialty Freezer Chests
- Mainstream Supermarkets
- Veterinary Clinic Freezers
Frozen Pet Food Market segmented by Price Tier & Buyer Scale:
- Mid-Tier Mainstream Brands
- Premium Specialty Artisanal
- Private-Label & Economy
- Multinational CPG Processors
- Regional & Independent Brands
Frozen Pet Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Graziosi, G., Lupini, C., & Catelli, E. (2025, October 15). Highly Pathogenic Avian Influenza (HPAI) H5N1 in Raw Pet Foods and Milk: A Growing Threat to both Companion Animals and Human Health, and Potential Raw Pet Food Industry Liability. Journal of Food Protection, 88(11), 100628 (PubMed PMID 41016509).
- [2] Montegiove, N., Calzoni, E., & Emiliani, C. (2025, July 8). Reconciling the definitions of raw meat-based diets and biologically appropriate companion animal nutrition. Frontiers in Veterinary Science (PubMed PMID 40697637; PMCID PMC12282422).
- [3] Ramos, C. P., & Silva, R. O. S. (2025, July 1). Genomic insights into multidrug-resistant Salmonella enterica isolates from pet dogs and cats. Scientific Reports, 15(1), 22104 (PubMed PMID 40596330).
- [4] Botteldoorn, N., & Rasschaert, G. (2026, March 10). Occurrence of Antimicrobial Resistance in Indicator Bacteria and Campylobacter spp. Isolated from Commercial Raw-Meat-Based Food for Dogs and Cats in Belgium. Antibiotics (Basel), 15(3), 282 (PubMed PMID 41892444).
- [5] Toombs-Ruane, L. J., Benschop, J., & Burgess, S. A. (2025, July 30). Antimicrobial susceptibility of bacteria isolated from canine and feline urinary tract samples submitted to veterinary laboratories in New Zealand. New Zealand Veterinary Journal (PubMed PMID 40738173).
- [6] Lübke-Becker, A., & Walther, B. (2026, January 28). Comprehensive genomic analysis of multidrug-resistant Pseudomonas aeruginosa isolates from companion animals in Germany. Frontiers in Microbiology, 17, 1754860 (PubMed PMID 41684679).
- [7] Haenni, M., & Madec, J. Y. (2025, June 20). Antimicrobial Resistance Characterization of Methicillin-Resistant Staphylococcus aureus and Staphylococcus pseudintermedius Isolates from Clinical Cases in Dogs and Cats in Belgium. Antibiotics (Basel), 14(7), 631 (PubMed PMID 40723934).
- [8] Damborg, P., & Guardabassi, L. (2026, September 22). Genomic survey and comprehensive analysis of acquired vancomycin and linezolid resistance in enterococci isolated from dogs and cats. Veterinary Microbiology, 322, 111227 (PubMed PMID 42790234).
- [9] U.S. Food and Drug Administration (FDA). (2025, January 17). Cat and Dog Food Manufacturers Required to Consider H5N1 in Food Safety Plans. U.S. Food and Drug Administration (FDA Center for Veterinary Medicine).
- [10] American Veterinary Medical Association (AVMA). (2025, January 15). Cat deaths linked to bird flu-contaminated raw pet food, sparking voluntary recall. American Veterinary Medical Association.
- [11] Centers for Disease Control and Prevention (CDC). (2026, May 7). Serologic Evidence of Highly Pathogenic Avian Influenza A(H5N1) in Companion Cat Exposure Investigation. Morbidity and Mortality Weekly Report (MMWR), 75(17).
- [12] Nature's Variety (Instinct Pet Food). (2025, July 1). A Fresh Take on Raw - Introducing Instinct FreshRaw Meals. Instinct Pet Food.
- [13] The Farmer's Dog, Inc. (2025, May 22). The Farmer's Dog Announces Additional $10 Million Investment in Veterinary Research. The Farmer's Dog Digest.
- [14] Mars Petcare Inc. / Champion Petfoods. (2026, March 5). ORIJEN unleashes FRESHPREY elevating fresh pet food to new heights. Mars, Incorporated Newsroom.
- [15] The Farmer's Dog, Inc. & Cornell University. (2025, October 20). New Study From The Farmer's Dog Shows That Fresh Food Can Support Healthier Aging in Senior Dogs. The Farmer's Dog Digest.
- [16] General Mills, Inc. (2025, June 23). General Mills Accelerates Growth with Blue Buffalo Expansion into Fresh and Edgard & Cooper U.S. Launch. General Mills Corporate Newsroom.
- [17] Los Angeles County Department of Public Health. (2025, September 25). H5 Bird Flu in Animals - Los Angeles County Public Health Alert on Raw Pet Food. Los Angeles County Department of Public Health.
- [18] USDA Food Safety and Inspection Service (FSIS). (2026, June 5). Salmonella Verification Testing: April 27, 2025 through April 25, 2026. U.S. Department of Agriculture (USDA FSIS).
- [19] General Mills, Inc. (2025, October 21). Blue Buffalo Launches Love Made Fresh Nationwide, Making Every Meal a Fresh Act of Love for Your Dog. General Mills Corporate Newsroom.
- [20] U.S. Food and Drug Administration (FDA). (2026, August 21). Raaw Energy LLC - 723820 - 08/21/2026 Warning Letter. U.S. Food and Drug Administration (.gov).
- [21] Petfood Industry. (2026, September 9). General Mills sees cat food, fresh growth as it works to stabilize Wilderness. Petfood Industry (WATT Global Media).
- [22] Blue Buffalo Company, Ltd. (2026, March 20). Love Made Fresh Chicken Meatballs Small Adult Dog Food. Blue Buffalo Company, Ltd. (General Mills).
- [23] Petfood Industry. (2025, October 21). Blue Buffalo launches fresh pet food category in US. Petfood Industry (WATT Global Media).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the frozen pet food market in 2026 and what is forecast for 2036?
- Which H5N1 biosecurity and digestibility drivers support frozen pet food adoption?
- Why do Canine Raw & Gently Cooked Diets lead the companion species category?
- Why does High-Pressure Pasteurized Raw Frozen BARF lead the processing method category?
- How do growth rates differ across Australia, Japan, the USA, the UK, and Germany?
- Which leading companies supply HPP raw and human-grade gently cooked pet meals today?
- What cold-chain shipping and freezer-space hurdles limit mass-market conversion?
- What pathogen lethality and AAFCO human-grade metrics should buyers evaluate?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Companion Species & Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Companion Species & Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Companion Species & Method, 2026 to 2036
- Canine Raw & Cooked
- Feline Carnivore Medallions
- HPP Raw Frozen BARF
- Sous-Vide Human-Grade
- Y-o-Y Growth Trend Analysis By Companion Species & Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Companion Species & Method, 2026 to 2036
- Global Market Analysis and Forecast, By Protein Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Protein Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Protein Source, 2026 to 2036
- Beef, Chicken & Turkey
- Novel Venison & Duck
- Rabbit, Kangaroo & Salmon
- Y-o-Y Growth Trend Analysis By Protein Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Protein Source, 2026 to 2036
- Global Market Analysis and Forecast, By Portion Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Portion Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Portion Format, 2026 to 2036
- Patties, Medallions & Bites
- Sliceable Chub Rolls
- Flat-Pack Meal Pouches
- Y-o-Y Growth Trend Analysis By Portion Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Portion Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- D2C Cold-Chain Subscriptions
- Pet Specialty Freezer Chests
- Mainstream Supermarkets
- Veterinary Clinic Freezers
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier & Buyer Scale, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier & Buyer Scale, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier & Buyer Scale, 2026 to 2036
- Mid-Tier Mainstream Brands
- Premium Specialty Artisanal
- Private-Label & Economy
- Multinational CPG Processors
- Regional & Independent Brands
- Y-o-Y Growth Trend Analysis By Price Tier & Buyer Scale, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier & Buyer Scale, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- By Country
- Market Attractiveness Analysis
- By Country
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Netherlands & Nordics
- Pricing Analysis
- Market Share Analysis, 2025
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Companion Species & Method
- By Protein Source
- By Portion Format
- By Distribution Channel
- By Price Tier & Buyer Scale
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nature's Variety (Instinct)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Stella & Chewy's LLC
- The Farmer's Dog, Inc.
- Mars Petcare Inc. (NOM NOM)
- Primal Pet Foods, Inc.
- General Mills (Blue Buffalo)
- Freshpet, Inc.
- Butternut Box
- General Mills, Inc. (Blue Buffalo)
- Nature's Variety (Instinct)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Companion Species & Method, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Portion Format, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier & Buyer Scale, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Companion Species & Method
- Figure 6: Global Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Protein Source
- Figure 9: Global Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Portion Format
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Companion Species & Method
- Figure 32: North America Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Protein Source
- Figure 35: North America Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Portion Format
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Companion Species & Method
- Figure 48: Latin America Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Protein Source
- Figure 51: Latin America Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Portion Format
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Companion Species & Method
- Figure 64: Western Europe Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Protein Source
- Figure 67: Western Europe Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Portion Format
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Companion Species & Method
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Protein Source
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Portion Format
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Companion Species & Method
- Figure 96: East Asia Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Protein Source
- Figure 99: East Asia Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Portion Format
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Companion Species & Method
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Protein Source
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Portion Format
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Companion Species & Method, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Companion Species & Method, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Companion Species & Method
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Protein Source
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Portion Format, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Portion Format, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Portion Format
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Price Tier & Buyer Scale, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier & Buyer Scale, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Price Tier & Buyer Scale
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the frozen pet food market in 2026, and what is forecast for 2036?
According to FMI, global frozen pet food valuation is estimated to reach USD 16.9 billion in 2026 from USD 16.1 billion in 2025. Demand is forecast to hit USD 28.1 billion by 2036 as pet owners trade up to HPP raw and gently cooked human-grade meals.
What is the CAGR for the frozen pet food market from 2026 to 2036?
Future Market Insights projects a 5.2% compound annual growth rate between 2026 and 2036, representing an anticipated USD 11.2 billion increase in annual market value across D2C subscription, pet specialty, and grocery channels.
Which companion species and processing method lead the frozen pet food market?
Canine Raw & Gently Cooked Diets capture 73.9% of companion species demand in 2026, while High-Pressure Pasteurized Raw Frozen BARF secures 56.9% of the processing method category ahead of Gently Sous-Vide Cooked Human-Grade Frozen (43.1%).
Which protein source, portion format, channel, price tier, and buyer scale lead in 2026?
Beef, Chicken & Turkey Muscle/Organ Blends lead proteins at 62.9%, Pre-Portioned Patties, Medallions & Pourable Bites lead formats at 51.3%, Personalized D2C Cold-Chain Subscriptions lead channels at 45.7%, Mid-Tier Mainstream Brands lead price tiers at 51.8%, and Multinational CPG and Food Processors lead buyer scale at 54.3%.
Which countries have the fastest growth outlook during the assessment period?
Australia is projected to lead national growth at a 6.4% CAGR through 2036, followed by Japan at 5.9%, the United States at 5.0%, the United Kingdom at 4.9%, and Germany at 4.7%.
Who are the key players in the market?
Nature's Variety (Instinct), Stella & Chewy's LLC, The Farmer's Dog, Inc., Mars Petcare Inc. (NOM NOM, ORIJEN), and Primal Pet Foods, Inc., as well as General Mills (Blue Buffalo) and Freshpet, lead commercial supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
