
- Market Size (2026)
- USD 44.8 Bn
- Forecast (2036)
- USD 84.9 Bn
- CAGR (2026 to 2036)
- 6.6%
How big is Frozen Bakery Market in 2026?
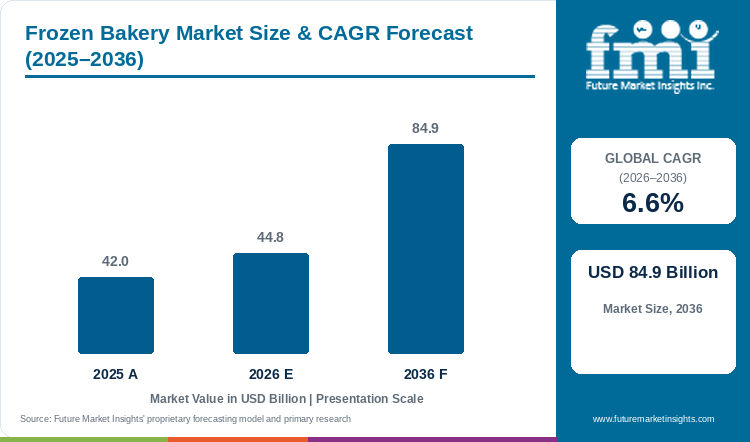
The frozen bakery market demonstrated steady progress from USD 42.0 billion in 2025 to USD 44.8 billion in 2026, building toward a targeted valuation of USD 84.9 billion by 2036 at a CAGR of 6.6%.
The global frozen bakery market was valued at USD 42.0 billion in 2025 and is estimated to reach USD 44.8 billion in 2026. Overall industry valuation is projected to reach USD 84.9 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.6% between 2026 and 2036. Production-line assessment at FMI indicates that Frozen Bread Rolls and Baguettes capture an estimated 38.0% share of 2026 product category demand, given that grocery chains and quick-service restaurants rely on standardized crusty loaves and sandwich carriers across all meal dayparts. Market growth is driven by bake-off conversion economics, where retail and hospitality operators replace scratch night-shift dough mixing with centralized blast-frozen products to eliminate skilled baker shortages and cut end-of-day staling waste. That broad multi-format substitution explains why the overall sector commands a far larger revenue base than the specialized par-baked bread segment alone, since centralized commissaries bundle laminated croissants, pizza doughs and thaw-and-serve cakes onto the same sub-zero delivery trucks. Industrial capacity commitments confirm this expansion, as Europastry reported in March 2026 that its 2025 revenue rose 8% to EUR 1.63 billion while allocating EUR 38 million to its Azuqueca brioche plant and EUR 50 million to its Carregado pastry hub [1]. European consolidation is accelerating in parallel, evidenced when Vandemoortele reported EUR 2.21 billion in turnover in March 2026 after acquiring Italian frozen bakery producer Lizzi Srl across four Northern Italy plants [2]. Sustained contract retention through 2036 depends on cryoprotectant dough conditioning that prevents ice-crystal gluten damage during multi-month freezer storage.
Key Market Trends & Insights
- By product category: Frozen Bread Rolls and Baguettes hold an estimated 38.0% share in 2026 since grocery bake-off stations and cafes bake small batches to match hourly foot traffic.
- By stage of baking: Ready-to-Bake Raw Frozen Dough represents an expected 54.0% in 2026 owing to lower carton volume per thousand pieces and fresh-baked crust aroma in stores.
- By end-use sector: Commercial Artisanal In-Store Bakeries account for a projected 48.0% in 2026 driven by supermarket elimination of scratch flour mixing rooms.
- By distribution channel: B2B Direct Commissary and Bakery Supply secures an anticipated 57.0% in 2026 through direct palletized cold-chain contracts with retail and restaurant chains.
- By formulation claim: Conventional Formulation commands an estimated 66.0% in 2026 supported by active wheat gluten freeze-thaw tolerance and proven emulsifier cost-in-use.
Regional Highlights
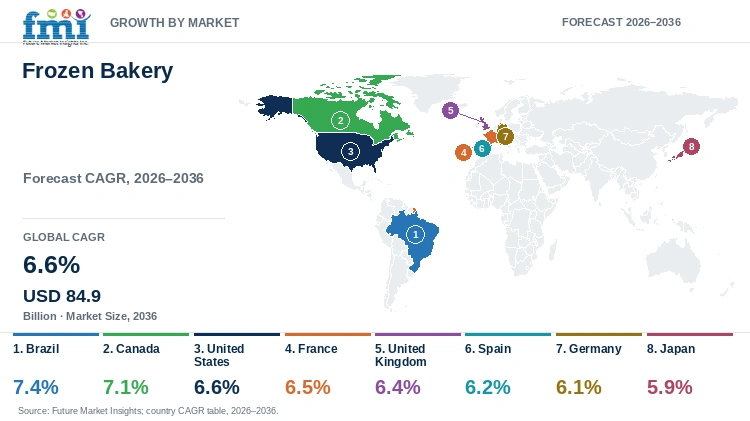
- Top national expansion: Brazil leads national growth projections at a 7.4% CAGR through 2036 driven by supermarket padaria bake-off counters and frozen cheese bread distribution.
- Broader country progression: Canada tracks at a 7.1% CAGR ahead of the United States at 6.6% and France at 6.5%, while Japan advances at a 5.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Frozen Bakery Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 42.0 billion |
| Estimated Market Size in 2026 | USD 44.8 billion |
| Projected Market Size by 2036 | USD 84.9 billion |
| CAGR, 2026 to 2036 | 6.6% |
| Added Revenue, 2026 to 2036 | USD 40.1 billion |
Industrial bakeries producing frozen dough confront structural moisture migration and ice crystallization when dough pieces remain at minus 18 degrees Celsius for eight weeks or longer. Free water separating from the gluten matrix forms sharp ice crystals that puncture gas cells and reduce oven spring after thawing. In January 2025, food physicists publishing in Foods demonstrated through low-field nuclear magnetic resonance that incorporating 0.6% glycerol monooleate binds free water and achieves a specific loaf volume of 3.48 milliliters per gram with lower crumb hardness after eight weeks of frozen storage [3]. Consequently, commercial commissaries pair targeted lipid emulsifiers with high-velocity sub-zero tunnel freezing to protect loaf height.
Blast-Frozen Tonnage and Wholesale Realization Sizing
Table 2: Blast-Frozen Tonnage and Wholesale Realization Sizing for the Frozen Bakery Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 42.0 | 44.8 | 84.9 |
| Global blast-frozen dough & par-baked volume (million metric tons) | 13.2 to 14.5 | 14.0 to 15.4 | 24.8 to 27.2 |
| Average wholesale commissary price realization (USD per kg) | 2.90 to 3.18 | 2.95 to 3.25 | 3.15 to 3.48 |
| Cold-chain storage temperature specification (degrees Celsius) | -18.0 to -22.0 | -18.0 to -22.0 | -18.0 to -24.0 |
Operational note: Tonnage ranges cover raw unproofed frozen dough pieces, pre-proofed laminated pastries, 80%-baked par-baked loaves and fully baked shock-frozen cakes shipped through minus 18 degrees Celsius logistics networks.
Rheological trials published in MDPI Foods in November 2025 confirmed that lipid polarity and melting profile govern dough viscoelasticity and gas retention during 60-minute post-thaw proofing at 35 degrees Celsius and 80% relative humidity [4]. Precise optimization of shortening and emulsifier blends allows industrial producers of frozen baked goods to prevent blistered crusts and collapsed sidewalls when retail staff bake frozen rolls in high-convection rack ovens.
Bake-Off Waste Reduction & Cryoprotectant Performance Indicators
Table 3: Bake-Off Waste Reduction and Specific Volume and Bake-Time Indicators for the Frozen Bakery Market (percentages, mL/g and minutes), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| In-store bake-off staling waste reduction vs scratch (%) | 28.0% to 34.0% | 30.0% to 36.0% | 38.0% to 44.0% |
| Cryoprotectant & lipid-modified dough specific volume (mL/g) | 3.20 to 3.48 | 3.25 to 3.55 | 3.45 to 3.80 |
| Par-baked final oven finish cycle time (minutes at 210C) | 12.0 to 15.0 | 11.0 to 14.0 | 8.0 to 12.0 |
| Clean-label & sourdough frozen bakery share (%) | 29.0% to 32.0% | 31.0% to 34.5% | 44.0% to 48.0% |
Table 4: Channel Allocation and Representative European Turnover Indicators for the Frozen Bakery Market (USD, EUR and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 44.8 billion | 2026 global industry valuation baseline |
| Commercial Artisanal In-Store Bakeries allocation, 2026 | USD 21.5 billion | 48.0% primary end-use sector share |
| Ready-to-Bake Raw Frozen Dough allocation, 2026 | USD 24.2 billion | 54.0% primary stage-of-baking share |
| Representative European frozen bakery leader turnover (2025) | EUR 2.21 billion | Vandemoortele 2026 financial disclosure across 36 plants |
Yeast cell mortality during repeated freeze-thaw distribution cycles has historically forced bakeries to overdose compressed yeast by up to 2% of flour weight, unlike short-shelf-life refrigerated dough products stored above freezing. In November 2025, microbiologists reporting in Food Research International demonstrated that evolved Saccharomyces cerevisiae strains maintain superior plasma-membrane integrity and gassing power after sub-zero storage [5]. Commercial adoption of freeze-tolerant yeast strains allows B2B commissaries to guarantee uniform proof heights across distant export markets without yeasty off-flavors.
Analyst Perspective
"Supermarket chains and coffee shops can no longer staff skilled scratch bakers at 3:00 AM across thousands of store locations. Centralized blast-frozen dough and par-baked loaves turn the in-store bakery from a high-labor craft workshop into a predictable, low-waste retail profit center that bakes fresh aroma on demand."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the frozen bakery market segmented?
The frozen bakery market is segmented by product category, stage of baking, end-use sector, distribution channel, and formulation claim. In 2026, Frozen Bread Rolls and Baguettes are projected at 38.0%, Ready-to-Bake Raw Frozen Dough at 54.0%, Commercial Artisanal In-Store Bakeries at 48.0%, B2B Direct Commissary and Bakery Supply at 57.0%, and Conventional Formulation at 66.0%.
By product category: Frozen Bread Rolls and Baguettes, Frozen Croissants Pastries and Danishes, Frozen Pizza Crusts and Doughs , and Frozen Cakes Muffins and Waffles.
By stage of baking: Ready-to-Bake Raw Frozen Dough, Par-Baked Partially Baked Frozen, Fully Baked Thaw-and-Serve Formats and Pre-Proofed Freezer-to-Oven Dough.
By end-use sector: Commercial Artisanal In-Store Bakeries, Foodservice Quick-Service Restaurants and Hotels, Retail Consumer Home Freezers and Institutional Catering.
By distribution channel: B2B Direct Commissary and Bakery Supply, Supermarkets and Hypermarkets, Convenience Stores and Forecourts and Online Grocery Delivery.
By formulation claim: Conventional Formulation, Gluten-Free Frozen Bakery, Certified Organic and Clean-Label Preservative-Free.
Why do Frozen Bread Rolls and Baguettes lead the product category?
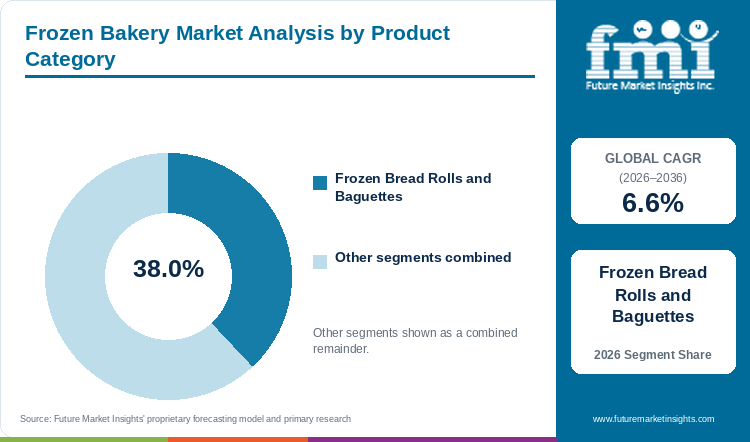
Frozen Bread Rolls and Baguettes hold an estimated 38.0% of product category demand in 2026, anchored by daily multi-batch bake-off turnover in grocery and quick-service outlets.
Table 5: Product Category Share for the Frozen Bakery Market (percentage share), 2026
| Product Category | Share (2026) |
|---|---|
| Frozen Bread Rolls and Baguettes | 38.0% |
| Other Segments Combined | 62.0%* |
| Total | 100.0% |
*Note: Remaining product categories account for the balance of 2026 global frozen bakery demand.
Table 6: Product Category Leadership and Market Growth for the Frozen Bakery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.6% |
| Leading Segment | Frozen Bread Rolls and Baguettes |
Crusty baguettes and dinner rolls, burger buns and artisan ciabatta loaves represent the highest-tonnage staple across European, North American and Latin American bake-off operations. Because crusty table breads stale within six to eight hours of baking due to starch retrogradation, supermarkets and restaurants bake frozen or par-baked rolls in three to four staggered daily waves rather than accepting morning-only deliveries. In July 2026, food technologists in MDPI Foods demonstrated that par-baked breads baked initially for 9 minutes at 210 degrees Celsius and stored at minus 18 degrees Celsius for up to 60 days recover full crust crispness and volatile aroma after a 14-minute final bake [6]. High-volume bun and roll lines also share cold-storage distribution with frozen pizza crusts across quick-service restaurant commissaries, although laminated butter croissants command higher per-kilogram margins.
- Within the product category segment, Frozen Bread Rolls and Baguettes are projected to account for a leading 38.0% share in 2026, driven by high-frequency daily meal consumption.
- Frozen croissants, brioche buns, and laminated Danish pastries are anticipated to post faster value growth through 2036 as coffee chains expand all-day breakfast menus.
What sustains Ready-to-Bake Raw Frozen Dough leadership in the stage of baking segment?
Ready-to-Bake Raw Frozen Dough represents an expected 54.0% of the stage of baking category in 2026, supported by lower carton freight volume and fresh-baked aroma at the point of sale.
Unbaked raw and pre-proofed frozen dough pieces dominate commercial stage-of-baking volume because unexpanded dough occupies less than half the freezer carton volume of fully risen par-baked loaves. Bulk shipment of dense unbaked dough pucks and laminated triangles cuts sub-zero freight costs per unit while releasing rich Maillard baking aromas inside the store or cafe kitchen during oven finishing. Formulators blending dough-based premixes must still fortify raw frozen dough with cryoprotectants and ascorbic acid so ice crystals do not weaken gluten films during extended freezer holding.
- In 2026, Ready-to-Bake Raw Frozen Dough is anticipated to capture 54.0% of global stage of baking demand, reflecting superior cold-storage pallet density and fresh-baked crust quality.
- In August 2026, researchers in MDPI Foods verified that adding soybean oligosaccharides to frozen dough inhibits ice recrystallization and preserves gluten network stability after 8-hour refrigerated thawing [7].
How do Commercial Artisanal In-Store Bakeries lead the end-use sector category?
Commercial Artisanal In-Store Bakeries account for a projected 48.0% of end-use sector demand in 2026, driven by supermarket conversion from scratch mixing to bake-off ovens.
Supermarket in-store bakeries and modern retail bake-off counters anchor global frozen bakery consumption as grocers use the scent of warm bread and pastries to drive perimeter foot traffic. Active transitioning grocery bakeries from scratch flour mixing to pre-formed frozen dough pucks and partially baked baguettes allows store managers to operate a full bakery counter using one retail clerk rather than a team of certified night-shift bakers. In September 2026, Europastry highlighted in its Annual Report 2025 that exclusive specialization in frozen bakery dough enables retail and foodservice customers to launch differentiated artisan loaves with zero dough-mixing waste [8]. Centralized commissaries supplying in-store bakeries also standardize bread concentrates across plants, though convenience-store space constraints limit proof-box installations in smaller outlets.
- By end-use sector, demand from Commercial Artisanal In-Store Bakeries is estimated to reach 48.0% of total category share in 2026 as grocery chains standardize bake-off rack ovens.
- Quick-service restaurants and coffee-shop chains are forecast to generate rapid incremental orders through 2036 by adopting freezer-to-oven breakfast sandwiches and thaw-and-serve cakes.
Why does B2B Direct Commissary and Bakery Supply lead the distribution channel category?
B2B Direct Commissary and Bakery Supply secures an estimated 57.0% of distribution channel share in 2026, supported by palletized cold-storage contracts with grocery and QSR chains.
Multi-year business-to-business supply contracts between industrial frozen bakery manufacturers and national supermarket, hotel, and restaurant chains account for the majority of global revenue. Unlike retail consumer freezer boxes that require individual printed cartons and slotting fees, B2B commissary shipments move in high-density bulk corrugated cases on dedicated minus 20 degrees Celsius reefer trailers. Diesel fuel surcharges and cold-storage warehouse lease rates still require tight route optimization across regional distribution hubs.
- High-volume pallet contracting with grocery bake-off counters and restaurant chains places B2B Direct Commissary and Bakery Supply on course to hold an estimated 57.0% share of the distribution channel category in 2026.
- Flowers Foods documented in its 2025 Form 10-K Annual Report that commercial foodservice and retail bakery accounts rely on direct cold-chain and warehouse delivery networks to maintain product freshness [9].
What gives Conventional Formulation the leading position in formulation claim?
Conventional Formulation commands a projected 66.0% of formulation claim volume in 2026, anchored by wheat gluten freeze-thaw elasticity and cost-effective emulsifier systems.
Conventional wheat-flour formulations fortified with active wheat gluten, diacetyl tartaric acid esters of mono- and diglycerides (DATEM), and maltogenic amylases dominate commercial frozen bakery output due to superior freeze-thaw machinability. Multi-layer croissant lamination and high-speed baguette moulding subject dough to mechanical shear and sub-zero thermal shock that unfortified doughs struggle to survive without tearing. Industrial scale in conventional frozen bread continues to consolidate, as seen when Grupo Bimbo reached an agreement with General Mills to acquire its frozen bread business in Argentina [10]. Even so, supermarket clean-label charters are pushing R&D teams to replace synthetic emulsifiers with enzymatic and sourdough conditioners.
- Conventional Formulation is predicted to secure 66.0% of formulation claim demand in 2026, supported by reliable oven spring and low per-ton ingredient cost.
- Clean-label preservative-free and gluten-free frozen bakery lines are projected to capture growing premium shelf space across North American and European grocers through 2036.
What are the drivers, restraints, and opportunities in the frozen bakery market?
In the frozen bakery market, skilled baker shortages and supermarket bake-off conversion are projected to drive adoption, while sub-zero cold-chain electricity costs and ice-crystal gluten damage restrain margins and freeze-tolerant sourdough and gluten-free lines create new growth avenues.
- Driver: Chronic shortages of skilled night-shift scratch bakers and strict retail food-waste targets compel supermarkets and cafes to adopt blast-frozen dough and par-baked loaves.
- Restraint: High industrial electricity tariffs for minus 40 degrees Celsius spiral blast freezers and sub-zero reefer transport inflate operating costs and compress processor margins.
- Opportunity: Long-fermented frozen sourdough loaves, gluten-free par-baked rolls, and air-fryer-ready home freezer pastries create premium margin avenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Higher bakery labor wages and a structural shortage of trained scratch bakers are accelerating the global transition toward centralized frozen dough and par-baked commissaries. When a supermarket chain or hotel kitchen switches from scratch flour mixing to par-baked artisan bread loaves and store staff can bake twelve golden baguettes in 12 minutes without mixers, floor proofers, or 4:00 AM shift premiums. Cryoprotectant formulation advances also ensure that frozen dough matches fresh-mixed loaf volume. In August 2026, food scientists indexed in PubMed demonstrated that natural oligosaccharide cryoprotectants protect disulfide bond integrity in wheat gluten networks against sub-zero ice recrystallization [11].
Risk Assessment of the Frozen Bakery Market: Operational and Formulation Friction
Continuous sub-zero cold-chain dependency and industrial refrigeration power consumption represent the primary operational friction restraining frozen bakery expansion in emerging markets. Spiral blast freezing dough to core temperatures of minus 18 degrees Celsius followed by multi-month cold warehousing and refrigerated trucking consumes substantially more megawatt-hours per ton than ambient bread distribution, while prolonged freezer dwell times can mute delicate artisan sourdough aromatics if cold chains fluctuate. In February 2026, Grupo Bimbo noted in its full-year financial disclosures that managing logistics, energy and raw material cost inflation across global baking networks requires continuous plant efficiency investments [12].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Container convenience and cold-chain packaging continue to influence retail household repeat rates, while quick-service restaurant (QSR) chains partner with industrial frozen bakeries to guarantee batch-to-batch uniformity across thousands of franchise units. Product announcements from General Mills in September 2026 demonstrate how industrial bakers leverage automated freezing and pre-proofed laminated dough formulations to deliver freezer-to-oven croissants and pastries with consistent crumb elasticity [13].
Frozen Bakery Market by Country (2026 to 2036)
FMI country modeling indicates that Brazil leads national frozen bakery expansion at a 7.4% CAGR through 2036, while Japan advances at a 5.9% CAGR. National growth trajectories reflect domestic wheat milling balances, supermarket bake-off penetration, quick-service restaurant expansion and cold-storage logistics maturity.
Table 7: Country CAGR and Primary Growth Levers for the Frozen Bakery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 7.4% | Padaria supermarket bake-off expansion and frozen pão de queijo and baguette distribution |
| Canada | 7.1% | National grocery chain in-store bake-off modernization across USD 125 billion retail food sector |
| United States | 6.6% | Quick-service restaurant bun, biscuit, and laminated pastry standardization across multi-unit chains |
| France | 6.5% | Industrial par-baked baguette and viennoiserie lamination serving 17,500 agri-food enterprises |
| United Kingdom | 6.4% | Supermarket private-label bake-off counters and coffee-shop thaw-and-serve muffin programs |
| Spain | 6.2% | Major domestic brioche and pastry line capex led by Barcelona and Madrid frozen dough plants |
| Germany | 6.1% | Automated discounter Brötchen bake-off stations and shock-frozen pretzel dough consumption |
| Japan | 5.9% | Convenience-store freshly baked croissant rollouts and April 2027 food tax reduction tailwinds |
Source: Future Market Insights analysis
Brazil Frozen Bakery Market Outlook (2026 to 2036)
Demand for frozen bakery products in Brazil is projected to expand at a leading 7.4% CAGR between 2026 and 2036 as neighborhood padarias, supermarkets, and cash-and-carry atacarejo stores standardize frozen French-roll dough (pão francês) and frozen cassava cheese bread (pão de queijo). What distinguishes Brazil from North American markets is the high daily frequency of warm bread purchases across urban bakery counters paired with structural domestic wheat deficits that favor centralized industrial dough blending. In August 2026, South American grain attaché analysts documented that Brazil's domestic wheat production is forecast to drop 22.5% to 6.1 million metric tons in 2026/2027, pushing import reliance to record highs [14]. Industrial frozen dough manufacturers able to blend imported high-protein wheat with enzymatic improvers are capturing multi-year supply agreements across Brazilian grocery chains.
Key takeaway: In Brazil, supermarket padaria bake-off conversion and centralized wheat flour blending are projected to drive a leading 7.4% CAGR.
Canada Frozen Bakery Market Outlook (2026 to 2036)
In Canada, frozen bakery sales are anticipated to advance at a 7.1% CAGR from 2026 to 2036, supported by high-capacity industrial bake-off plants in Ontario and Quebec supplying both domestic supermarkets and cross-border North American foodservice accounts. Canadian grocery chains rely heavily on par-baked artisan sourdough loaves, bagels, and laminated viennoiserie to differentiate perimeter fresh departments amid high store-level baker wage rates. Official retail trade analysis from Canadian grocery trade monitors in October 2026 documented that Canadian retail food sales reached an estimated 125 billion dollars with supermarkets leading offline grocery distribution at a 22.2% share [15]. Canadian frozen dough exporters utilizing high-protein Canadian Western Red Spring wheat continue to win private-label tenders across North American retail chains.
Key takeaway: In Canada, high-protein spring wheat dough quality and supermarket in-store bake-off modernization are anticipated to sustain a 7.1% CAGR.
United States Frozen Bakery Market Outlook (2026 to 2036)
The United States anchors North American frozen bakery consumption through coast-to-coast quick-service restaurant chains, supermarket in-store bakeries, and household freezer aisles. FMI country modeling indicates that United States frozen bakery demand is forecast to progress at a 6.6% CAGR through 2036 as multi-unit restaurant operators replace scratch biscuit, bun, and pizza dough preparation with freezer-to-oven formats. Abundant domestic grain and oilseed harvests stabilize flour and shortening costs for American commissaries, as reflected in May 2026 USDA Foreign Agricultural Service commodity export and domestic supply reports [16]. Thaw-and-serve sweet bakery goods including layer cakes, brownies, and mini-muffins also generate high-margin impulse sales in United States grocery perimeter display cases.
Key takeaway: In the United States, quick-service restaurant freezer-to-oven standardization and supermarket thaw-and-serve sweet goods are forecast to support a 6.6% CAGR.
France Frozen Bakery Market Outlook (2026 to 2036)
Commercial frozen bakery valuation in France is estimated to expand at a 6.5% CAGR between 2026 and 2036, driven by world-leading industrial lamination of pure-butter croissants, pains au chocolat and stone-baked par-baked baguettes. While independent French boulangeries defend scratch baking traditions, hotel breakfast buffets, highway service plazas and supermarket terminals rely extensively on shock-frozen raw and par-baked viennoiserie to guarantee warm morning availability. In April 2026, Paris agricultural attaché filings confirmed that the French agri-food sector encompasses 17,000 to 18,000 enterprises employing 450,000 workers while confronting rising energy and labor costs [17]. French frozen bakery specialists are scaling export shipments of Charentes-Poitou butter croissants across European and Asian coffee chains.
Key takeaway: In France, pure-butter viennoiserie lamination and foodservice bake-off adoption are estimated to anchor a 6.5% CAGR through 2036.
United Kingdom Frozen Bakery Market Outlook (2026 to 2036)
Frozen bakery expenditure in the United Kingdom is projected to grow at a 6.4% CAGR from 2026 to 2036 as British supermarkets and high-street coffee chains expand private-label bake-off counters and frozen home-air-fryer pastry ranges. What sets the United Kingdom apart from continental Europe is the dominance of private-label grocery programs and rapid consumer adoption of premium frozen sourdough rolls and sweet morning goods. In October 2026, British grocery market analysts noted in the October 2026 United Kingdom Retail Foods Annual assessment that private-label products captured a record 52.2% of UK grocery spending in early 2026 [18]. British bake-off suppliers that formulate clean-label par-baked rolls and vegan sausage-roll pastry sheets are winning long-term supermarket supply contracts.
Key takeaway: In the United Kingdom, record 52.2% supermarket private-label penetration and coffee-shop bake-off counters are projected to sustain a 6.4% CAGR.
Spain Frozen Bakery Market Outlook (2026 to 2036)
Turnover of frozen bakery products in Spain is slated to climb at a 6.2% CAGR over the 2026 to 2036 forecast period, driven by high hospitality tourism demand and Europe's most concentrated industrial frozen dough manufacturing cluster. Spanish supermarkets, tapas bars and coastal hotels depend on par-baked rustic loaves, gourmet brioche burger buns and frozen churros or Dots to serve millions of seasonal visitors without kitchen bottlenecks. Wider European agri-food labor statistics published by UK DEFRA in July 2026 illustrate why foodservice operators across Western Europe steadily outsource labor-intensive baking prep to automated factories [19]. Major capital investments in Spanish brioche and pastry lines continue to strengthen Iberia's role as a primary export hub.
Key takeaway: In Spain, hospitality tourism bake-off demand and large-scale domestic brioche and pastry plant expansions are anticipated to drive a 6.2% CAGR.
Germany Frozen Bakery Market Outlook (2026 to 2036)
Germany represents Europe's largest national market for automated self-service bake-off stations, with frozen bakery demand forecast to increase at a 6.1% CAGR through 2036. Every major German discount and full-range supermarket chain operates multi-deck in-store ovens that bake pre-proofed frozen wheat rolls (Brötchen), lye pretzels (Laugengebäck), and quark pockets throughout shopping hours. In September 2026, European retail trade specialists confirmed in the September 2026 Germany Retail Foods Annual report that price-conscious German shoppers heavily patronize discount grocers and private-label convenience ranges [20]. German industrial bakeries are retrofitting ammonia spiral freezers and waste-heat recovery systems to offset industrial electricity costs and protect discounter tender margins.
Key takeaway: In Germany, automated discounter Brötchen and pretzel bake-off stations are forecast to support a 6.1% CAGR through 2036.
Japan Frozen Bakery Market Outlook (2026 to 2036)
Procurement of frozen bakery products in Japan is estimated to progress at a 5.9% CAGR between 2026 and 2036 as convenience stores, train-station micro-bakeries, and hotels adopt frozen laminated croissant and Hokkaido milk-bread doughs. Acute demographic aging and night-shift labor shortages across Japanese retail bakeries make centralized frozen dough production essential for maintaining daily store assortments. Macro policy shifts also influence foodservice budgets, as Tokyo food tax analysts noted in September 2026 that Japan's planned consumption tax reduction on food and beverages effective April 2027 is expected to support overall food consumption [21]. Japanese frozen dough formulators emphasize ultra-soft crumb textures and individual microwave-or-toaster freezer packs for urban households.
Key takeaway: In Japan, retail bakery labor shortages and convenience-store bake-off croissant programs are estimated to sustain a 5.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the frozen bakery market?
Grupo Bimbo SAB de CV, Aryzta AG, General Mills Inc., Flowers Foods Inc., Associated British Foods plc, Rich Products Corporation, Vandemoortele NV, Lantmannen Unibake, Europastry SA, and Dawn Foods Inc. are the notable companies in the frozen bakery market.
Competitive positioning across the global frozen bakery industry divides into diversified global baking conglomerates, pure-play European B2B bake-off and viennoiserie specialists, and North American foodservice dough and sweet-bakery leaders. Grupo Bimbo, Associated British Foods, Flowers Foods and General Mills operate extensive multi-plant baking and flour-conditioning networks. Aryzta AG and Vandemoortele NV, Lantmannen Unibake and Europastry SA lead European and international par-baked bread and laminated pastry supply while Rich Products Corporation and Dawn Foods Inc anchor foodservice pizza doughs, cakes and sweet bakery finishers.
- Diversified Global and National Baking Conglomerates: Grupo Bimbo SAB de CV, Associated British Foods plc, Flowers Foods Inc and General Mills Inc combine high-speed bread and bun manufacturing with frozen retail and foodservice distribution.
- European Pure-Play Bake-Off and Viennoiserie Specialists: Aryzta AG and Vandemoortele NV, Lantmannen Unibake and Europastry SA engineer shock-frozen artisan baguettes, brioche buns and laminated butter croissants.
- Foodservice Pizza Crust and Sweet Bakery Leaders: Rich Products Corporation and Dawn Foods Inc supply par-baked pizza crusts and flatbreads, thaw-and-serve layer cakes, muffins and glazes.
Competitive Benchmarking: Frozen Bakery Market
Table 8: Competitive Benchmarking for the Frozen Bakery Market (qualitative capability ratings), 2026
| Company | Blast-Freezing Capacity | Par-Baked & Laminated Range | Foodservice & In-Store Reach | Geographic Reach |
|---|---|---|---|---|
| Grupo Bimbo SAB de CV | High | High | High | Global bakery leader operating across the Americas, Europe, Asia, and Africa |
| Aryzta AG | High | High | High | Swiss-headquartered B2B bake-off specialist across Europe and Asia-Pacific |
| General Mills Inc. | High | High | High | North American Pillsbury frozen dough, biscuits, and Annie's retail freezer lines |
| Flowers Foods Inc. | High | Medium | High | U.S. national bakery network supplying retail and foodservice frozen bread and rolls |
| Associated British Foods plc | High | Medium | High | Allied Bakeries, Hovis integration, and AB Mauri cryogenic dough conditioning |
| Rich Products Corporation | High | High | High | Global family-owned leader in frozen pizza doughs, cakes, icings, and par-baked rolls |
| Vandemoortele NV | High | High | High | 35 European and 1 U.S. plant; acquired Lizzi Srl in Italy for frozen patisserie |
| Lantmannen Unibake | High | High | High | Nordic and global supplier of Schulstad frozen Danish pastries and fast-food buns |
| Europastry SA | High | High | High | Spanish frozen dough leader with EUR 1.63 billion 2025 revenue and global export hubs |
| Dawn Foods Inc. | Medium | High | High | Global sweet bakery manufacturer supplying frozen cakes, muffins, and donuts |
Evaluation basis: Blast-Freezing Capacity assesses multi-plant spiral freezer tonnage and sub-zero warehouse network scale, while Par-Baked & Laminated Range evaluates stone-oven par-baked artisan bread and multi-layer viennoiserie lamination capabilities. Foodservice & In-Store Reach measures direct B2B supply contracts with supermarket bake-off counters and quick-service restaurant chains.
Key Developments in the Frozen Bakery Market
- Associated British Foods plc released its 2026 Annual Results on November 3, 2026, reporting £1,327 million in adjusted operating profit while advancing the integration of Hovis and specialty yeast investments in AB Mauri [22].
- Rich Products Corporation earned a 2026 Sustainability in the Food Industry Award on October 19, 2026 and expanded its global headquarters Customer Innovation Center in Buffalo, New York to accelerate QSR and retail bakery co-development [23].
- General Mills Inc announced on September 30, 2026 the appointment of Dana McNabb as Chief Executive Officer to lead the next phase of its Accelerate growth strategy across North American retail and commercial foodservice baking [24].
Key Players in the Frozen Bakery Market
Diversified Global and National Baking Conglomerates
- Grupo Bimbo SAB de CV
- Associated British Foods plc
- Flowers Foods Inc.
- General Mills Inc.
European Pure-Play Bake-Off and Viennoiserie Specialists
- Aryzta AG
- Vandemoortele NV
- Lantmannen Unibake
- Europastry SA
Foodservice Pizza Crust and Sweet Bakery Leaders
- Rich Products Corporation
- Dawn Foods Inc.
Frozen Bakery Market - Report Scope
Table 9: Report Scope for the Frozen Bakery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Category; Stage of Baking; End-Use Sector; Distribution Channel; Formulation Claim |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from blast-frozen raw unproofed dough, pre-proofed freezer-to-oven dough, par-baked (partially baked and shock-frozen) breads and rolls, and fully baked thaw-and-serve sweet and savory bakery items distributed at minus 18 degrees Celsius or below. Category Scope Note: Excludes ambient shelf-stable packaged bread, chilled +4C refrigerated biscuit cans, dry bakery flour premixes, and frozen savory ready meals. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Canada, United States, France, United Kingdom, Spain, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Grupo Bimbo SAB de CV, Aryzta AG, General Mills Inc., Flowers Foods Inc., Associated British Foods plc, Rich Products Corporation, Vandemoortele NV, Lantmannen Unibake, Europastry SA, Dawn Foods Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Frozen Bakery Market - Research Methodology
Table 10: Research Methodology for the Frozen Bakery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with industrial spiral-freezer operations directors, supermarket in-store bakery category buyers, quick-service restaurant supply-chain managers, and cereal cryoprotectant formulators. |
| Secondary Research | Analysis of USDA Foreign Agricultural Service (FAS) Retail Foods and Food Processing Annual reports, GOV.UK DEFRA food statistics, peer-reviewed frozen dough NMR and yeast tolerance studies, and corporate annual reports. |
| Market Sizing and Forecasting | Top-down global commercial bakery baselines reconciled against bottom-up blast-frozen dough and par-baked tonnage (14.0M to 15.4M MT in 2026) and wholesale price realizations per kilogram from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight supermarket bake-off station penetration, quick-service restaurant store counts, commercial baker wage inflation, and cold-storage warehouse capacity across eight countries. |
| Operational Benchmark Traceability | Tonnage, specific loaf volume, and bake-off waste indicators in Tables 2, 3, and 4 trace to MDPI Foods NMR moisture trials, Food Research International yeast studies, and corporate financial disclosures. |
| Data Triangulation and Validation | Valuation estimates isolate sub-zero frozen dough, par-baked, and thaw-and-serve bakery goods while strictly excluding ambient wrapped bread, chilled dough tubes, and dry flour mixes. |
Frozen Bakery Market by Segments
Frozen Bakery Market segmented by Product Category:
- Frozen Bread Rolls and Baguettes
- Frozen Croissants Pastries and Danishes
- Frozen Pizza Crusts and Doughs
- Frozen Cakes Muffins Cheesecakes Waffles and Pancakes
Frozen Bakery Market segmented by Stage of Baking:
- Ready-to-Bake Raw Frozen Dough
- Par-Baked Partially Baked Frozen
- Fully Baked Thaw-and-Serve Formats
- Pre-Proofed Freezer-to-Oven Dough
Frozen Bakery Market segmented by End-Use Sector:
- Commercial Artisanal In-Store Bakeries
- Foodservice Quick-Service Restaurants
- Hotels and Hospitality Catering
- Retail Consumer Home Freezers
- Institutional Travel and Healthcare Dining
Frozen Bakery Market segmented by Distribution Channel:
- B2B Direct Commissary and Bakery Supply
- Supermarkets and Hypermarkets
- Convenience Stores and Forecourts
- Online Grocery Delivery
Frozen Bakery Market segmented by Formulation Claim:
- Conventional Formulation
- Gluten-Free Frozen Bakery
- Certified Organic
- Clean-Label Preservative-Free
Frozen Bakery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Europastry S.A. (2026, March 25). Europastry Reaches EUR 1.63 Billion in 2025 Revenue and Invests EUR 88 Million in Spain and Portugal Frozen Dough Lines. Europastry Corporate Newsroom.
- [2] Vandemoortele NV. (2026, March 30). Vandemoortele Achieves EUR 2.21 Billion Turnover and Expands Italian Frozen Bakery Footprint via Lizzi Acquisition. Vandemoortele Official Press Room.
- [3] Zhao, L., & Wang, Y. (2025, January 20). Effects of Glycerol Monooleate on Improving Quality Characteristics and Moisture Distribution of Frozen Dough. Foods, 14(2), 326 (PubMed PMID 39856992).
- [4] Sun, Q., & Li, J. (2025, November 25). Impact of Different Types of Lipids on the Rheological and Baking Quality of Frozen Dough. MDPI Foods, 14(23), 4032.
- [5] Chen, H., & Liu, X. (2025, November 11). Evolved Saccharomyces cerevisiae Strains Exhibit Superior Freeze-Thaw Tolerance and Frozen Dough Performance. Food Research International, 223, 117843 (PubMed PMID 41352789).
- [6] Yilmaz, E., & Demir, M. (2026, July 5). The Effect of the Partial Baking Method on the Quality and Volatile Profile of Par-Baked Bread Stored at Minus 18 Degrees Celsius. MDPI Foods, 15(13), 2392.
- [7] Wu, Z., & Tang, K. (2026, August 18). Cryoprotective Role of Soybean Oligosaccharides in Frozen Dough for Enhanced Gluten Stability and Bread Quality. MDPI Foods, 15(16), 2878.
- [8] Europastry S.A. (2026, September 10). Europastry Annual Report 2025 on Global Frozen Bakery Production and R&D Specialization. Europastry Corporate Publications.
- [9] Flowers Foods Inc. (2026, October 1). Flowers Foods 2025 Annual Report Form 10-K on Commercial Bakery and Foodservice Operations. Flowers Foods Investor Relations.
- [10] Grupo Bimbo S.A.B. de C.V. (2025, May 12). Grupo Bimbo Reaches Agreement to Acquire Frozen Bread Business in Argentina from General Mills. Grupo Bimbo Official Press Releases.
- [11] Zhang, M., & Xu, B. (2026, August 18). Inhibition of Ice Recrystallization and Disulfide Cleavage in Frozen Dough Matrices. PubMed Indexed Food Science Study (PMID 42650572).
- [12] Grupo Bimbo S.A.B. de C.V. (2026, February 26). Grupo Bimbo 2025 Fourth Quarter and Full Year Financial Reports for Global Bakery Operations. Grupo Bimbo Investor Relations.
- [13] General Mills Inc. (2026, September 3). Pillsbury Introduces Frozen Grands! Croissants in Butter and Chocolate Varieties. General Mills Corporate Newsroom.
- [14] USDA Foreign Agricultural Service. (2026, August 5). Brazil Grain and Feed Update on Domestic Wheat Production Deficit and Milling Import Demand. U.S. Department of Agriculture GAIN Report BR2026-0022.
- [15] USDA Foreign Agricultural Service. (2026, October 20). Canada Retail Foods Annual Report on Supermarket In-Store Bakeries and Frozen Food Channels. U.S. Department of Agriculture GAIN Report CA2026-0024.
- [16] USDA Foreign Agricultural Service. (2026, May 29). U.S. Grain and Oilseed Export Sales and Domestic Bakery Milling Supply. U.S. Department of Agriculture FAS Newsroom.
- [17] USDA Foreign Agricultural Service. (2026, April 3). France Food Processing Ingredients Annual Report on French Agri-Food and Industrial Bakery Enterprises. U.S. Department of Agriculture GAIN Report FR2026-0009.
- [18] USDA Foreign Agricultural Service. (2026, October 1). United Kingdom Retail Foods Annual Report on USD 343 Billion Grocery Market and Private-Label Share. U.S. Department of Agriculture GAIN Report UK2026-0027.
- [19] UK Department for Environment, Food and Rural Affairs. (2026, July 29). Food Statistics in Your Pocket on UK Agri-Food Gross Value Added and Bakery Employment. GOV.UK Official Statistics.
- [20] USDA Foreign Agricultural Service. (2026, September 25). Germany Retail Foods Annual Report on Discount Bake-Off Stations and Frozen Grocery Channels. U.S. Department of Agriculture GAIN Report GM2026-0018.
- [21] USDA Foreign Agricultural Service. (2026, September 30). Japan Grain and Feed Update on Wheat versus Rice Bakery Consumption and Tax Policy. U.S. Department of Agriculture GAIN Report JA2026-0029.
- [22] Associated British Foods plc. (2026, November 3). 2026 Annual Results Announcement Covering Allied Bakeries, Hovis Integration, and AB Mauri Ingredients. Associated British Foods Official Media Room.
- [23] Rich Products Corporation. (2026, October 19). Rich Products Recognized with 2026 Sustainability Award and Expands Customer Innovation Center. Rich Products Official Newsroom.
- [24] General Mills Inc. (2026, September 30). General Mills Announces CEO Transition and Accelerate Growth Strategy Across Retail and Foodservice. General Mills Official Press Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the frozen bakery market in 2026 and what is forecast for 2036?
- Which bake-off labor and waste-reduction economics support demand for frozen bakery?
- Why do Frozen Bread Rolls and Baguettes lead the product category?
- Why does Ready-to-Bake Raw Frozen Dough lead the stage of baking category?
- How do growth rates differ across Brazil and Canada, the United States, France and Spain?
- Which notable companies lead European bake-off versus North American foodservice supply?
- What cold-chain electricity and ice-crystallization risks restrain the frozen bakery market?
- What should bakeries evaluate when adopting freeze-tolerant yeast and cryoprotectant lipids?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Category, 2026 to 2036
- Frozen Bread Rolls and Baguettes
- Frozen Croissants Pastries and Danishes
- Frozen Pizza Crusts and Doughs
- Frozen Cakes Muffins Cheesecakes Waffles and Pancakes
- Y-o-Y Growth Trend Analysis By Product Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Category, 2026 to 2036
- Global Market Analysis and Forecast, By Stage of Baking, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Stage of Baking, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Stage of Baking, 2026 to 2036
- Ready-to-Bake Raw Frozen Dough
- Par-Baked Partially Baked Frozen
- Fully Baked Thaw-and-Serve Formats
- Pre-Proofed Freezer-to-Oven Dough
- Y-o-Y Growth Trend Analysis By Stage of Baking, 2021 to 2025
- Absolute $ Opportunity Analysis By Stage of Baking, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Commercial Artisanal In-Store Bakeries
- Foodservice Quick-Service Restaurants
- Hotels and Hospitality Catering
- Retail Consumer Home Freezers
- Institutional Travel and Healthcare Dining
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- B2B Direct Commissary and Bakery Supply
- Supermarkets and Hypermarkets
- Convenience Stores and Forecourts
- Online Grocery Delivery
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Claim, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Claim, 2026 to 2036
- Conventional Formulation
- Gluten-Free Frozen Bakery
- Certified Organic
- Clean-Label Preservative-Free
- Y-o-Y Growth Trend Analysis By Formulation Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Category
- By Stage of Baking
- By End-Use Sector
- By Distribution Channel
- By Formulation Claim
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Grupo Bimbo SAB de CV
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Aryzta AG
- General Mills Inc.
- Flowers Foods Inc.
- Associated British Foods plc
- Rich Products Corporation
- Vandemoortele NV
- Lantmannen Unibake
- Europastry SA
- Dawn Foods Inc.
- Grupo Bimbo SAB de CV
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Stage of Baking, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Category
- Figure 6: Global Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Stage of Baking
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Formulation Claim
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Category
- Figure 32: North America Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Stage of Baking
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Sector
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Formulation Claim
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Category
- Figure 48: Latin America Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Stage of Baking
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Formulation Claim
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Category
- Figure 64: Western Europe Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Stage of Baking
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Formulation Claim
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Category
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Stage of Baking
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Formulation Claim
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Category
- Figure 96: East Asia Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Stage of Baking
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Formulation Claim
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Category
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Stage of Baking
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Formulation Claim
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Category
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Stage of Baking, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Stage of Baking, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Stage of Baking
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Formulation Claim
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the frozen bakery market in 2026, and what is forecast for 2036?
Global frozen bakery valuation advanced from USD 42.0 billion in 2025 to USD 44.8 billion in 2026 and is forecast to reach USD 84.9 billion by 2036.
What is the CAGR for the frozen bakery market from 2026 to 2036?
The global frozen bakery sector is projected to expand at a 6.6% CAGR over the 2026 to 2036 forecast period, adding USD 40.1 billion in incremental revenue.
Which product category segment leads the frozen bakery market?
Frozen Bread Rolls and Baguettes hold an estimated 38.0% of product category demand in 2026 since grocery bake-off counters and restaurants replenish warm bread throughout the day.
Which stage of baking segment leads the frozen bakery market?
Ready-to-Bake Raw Frozen Dough represents a projected 54.0% of the stage of baking category in 2026 owing to high freezer carton density and fresh-baked aroma at the store.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 7.4% CAGR through 2036, driven by supermarket padaria bake-off counters and domestic wheat import blending.
Who are the key players in the market?
Grupo Bimbo and Aryzta and General Mills and Flowers Foods and Associated British Foods and Rich Products and Vandemoortele, Lantmannen Unibake, Europastry and Dawn Foods lead global frozen bakery supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
