
- Market Size (2026)
- USD 73.0 Bn
- Forecast (2036)
- USD 125.8 Bn
- CAGR (2026 to 2036)
- 5.6%
How big is Frozen Potatoes Market in 2026?
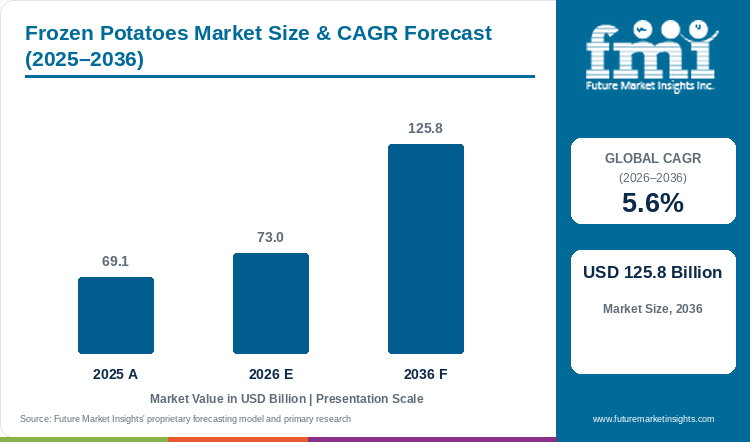
Sales in the frozen potatoes market are projected to grow at 5.6% CAGR, with market size rising from USD 69.1 billion in 2025 to USD 73.0 billion in 2026 and reaching USD 125.8 billion by 2036.
Increasing expansion of quick-service restaurant chains and rising dependence on ready-to-finish food have brought frozen potatoes into regular purchasing rather than occasional menu buying. According to Future Market Insights analysis, the global frozen potatoes market is valued at USD 69.1 billion in 2025 and is estimated to reach USD 73.0 billion in 2026. At a 5.6% CAGR from 2026 to 2036, overall revenue is projected to attain USD 125.8 billion by 2036, which translates into USD 52.8 billion added over the forecast period. Commercial kitchens require uniform cut dimensions, color stability, and fryer performance across daily service shifts to maintain customer turnaround. Potato fries are therefore expected to account for 46.0% of demand in 2026, while foodservice holds 71.0%. However, crop availability can decide how much of this demand converts into margin. USDA placed 2025 planted potato area across 13 leading states at 912,000 acres, down 2% from 2024. The wider potato processing industry shows the same movement towards standardized output.
Key Market Trends & Insights
- By product: Potato fries are expected to hold 46.0% in 2026 as the cut is already accepted across restaurant menus and does not require operators to change kitchen practice.
- By end use: Foodservice is likely to account for 71.0% in 2026 because repeat orders from restaurant chains move much larger volumes than household packs.
- By processing: Fried formats are projected to represent 79.0% in 2026. Partial frying shifts preparation work to the processor and leaves the kitchen with only the final finish.
- By distribution channel: Offline channels are expected to hold 82.0% in 2026 as frozen deliveries still depend on scheduled routes, temperature checks and distributor-held inventory.
- By packaging: Bags remain useful for commercial kitchens because operators can remove the required quantity without opening several small packs and increasing handling cost.
Regional Highlights
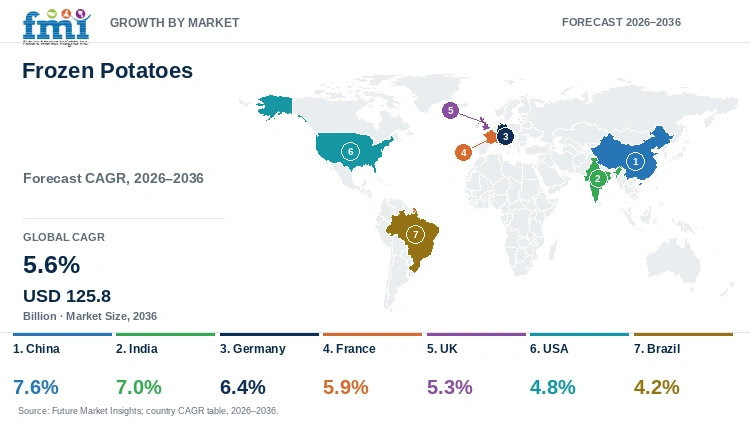
- Fastest-growing evaluated country: China, at 7.6% CAGR from 2026 to 2036.
- India at 7.0%, Germany at 6.4%, and France at 5.9% follow, while Brazil records 4.2% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Frozen Potatoes Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 69.1 billion |
| Estimated Market Size in 2026 | USD 73.0 billion |
| Projected Market Size by 2036 | USD 125.8 billion |
| CAGR, 2026 to 2036 | 5.6% |
| Added Revenue, 2026 to 2036 | USD 52.8 billion |
Tighter crop supply can become a larger issue than end demand when processors are already running against restaurant delivery schedules. USDA estimated combined United States and Canada potato production at 538 million cwt in 2025, down 2% from 2024. This reduction is not enough to stop the market, but it gives processors less room when contracts require fixed cut, color and solids. Longer grower agreements and planned cold-storage positions are therefore likely to increase, particularly among suppliers selling into national foodservice networks where missed supply affects several outlets at once. This also raises the value of dependable foodservice equipment networks where one missed delivery can affect several kitchens.
Potato Throughput and Foodservice Requirement Sizing
Table 2: Throughput and Procurement Indicators for the Frozen Potatoes Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 69.1 | 73.0 | 125.8 |
| Implied processed volume index | 100.0 | 105.6 | 182.1 |
| Foodservice revenue (USD billion) | 49.1 | 51.8 | 89.3 |
| Potato fries revenue (USD billion) | 31.8 | 33.6 | 57.9 |
Per Capita and Channel Sizing
Frozen potatoes are gaining regular kitchen space because they remove washing, peeling and cut variation before service begins. Buyers are not paying only for a potato product; they are buying saved preparation time and a predictable portion. Par-fried formats also shorten the gap between order and serving, which supports high-volume restaurants. The limitation is that every such advantage depends on uninterrupted freezing and storage. A product reaching the kitchen after temperature abuse may lose texture, and cold-chain execution therefore remains part of product quality rather than a separate transport matter. The demand pattern is connected with the wider convenience food category as preparation time becomes part of product value.
Table 3: Per Capita Spending Indicators for the Frozen Potatoes Market
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 8.40 | 8.80 | 14.06 |
| Spend per 1,000 people (USD) | 8,396 | 8,795 | 14,056 |
| Added spend per capita vs. 2026 (USD) | - | - | 5.26 |
Table 4: Foodservice and Processing Revenue Indicators
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 73.0 billion | Report value |
| Foodservice revenue, 2026 | USD 51.8 billion | 71.0% share |
| Fried-processing revenue, 2026 | USD 57.7 billion | 79.0% share |
| Offline-channel revenue, 2026 | USD 59.9 billion | 82.0% share |
Analyst Perspective
"Frozen potato processors need dependable crop sourcing and coatings that protect crispness through delivery. Suppliers aligning capacity with QSR specifications will secure longer foodservice agreements."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Frozen Potatoes Market segmented?
The frozen potatoes market is segmented by product, end use, distribution channel, packaging, and processing. In 2026, potato fries lead product at 46.0%, foodservice leads end use at 71.0%, fried leads processing at 79.0%, and offline leads distribution at 82.0%.
As per FMI, the frozen potatoes market is segmented across five key commercial axes: Product, End Use, Distribution Channel, Packaging, and Processing.
By product: Potato Fries, Potato Wedges, Stuffed Potatoes, Potato Slices, Potato Chunks, Potato Dices, Baked Potatoes, and Other Products.
By end use: Foodservice and Retail.
By distribution channel: Offline and Online.
By packaging: Bags and Boxes.
By processing: Fried and Baked.
Why does Potato Fries lead the product category?
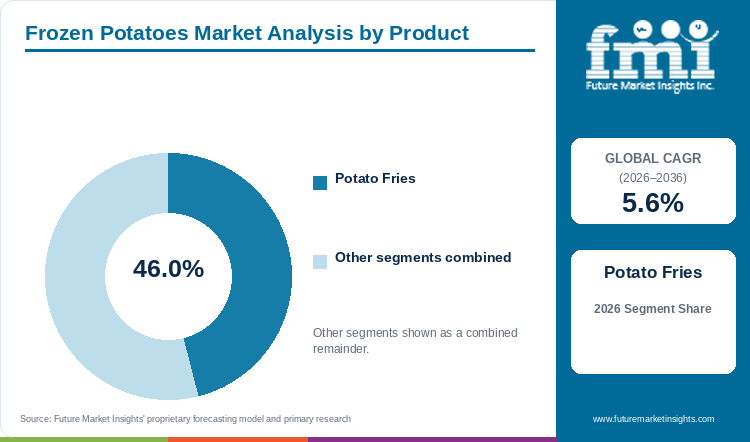
Potato fries represent 46.0% of product demand in 2026, combining menu familiarity with predictable fryer performance.
Table 5: Product Share for the Frozen Potatoes Market, 2026
| Product | Share (2026) |
|---|---|
| Potato Fries | 46.0% |
| Other Segments Combined | 54.0% |
| Total | 100.0% |
*Other segments combined equals 100.0% less the leading share.
Table 6: Product Leadership and Market Growth, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR | 5.6% |
| Leading Segment | Potato Fries |
Potato fries remain ahead because the product already sits across burger, chicken and snack menus, meaning a new outlet can add it without re-educating the customer. The 46.0% share expected in 2026 also reflects production economics, as straight and coated cuts can be made at large scale. What may weaken this position is not lack of familiarity but poor hold performance, because delivery-led meals expose fries to steam and time after frying. Commercial fries cutting equipment supports the uniform dimensions required at scale.
- Potato fries are projected to hold 46.0% share in 2026 because menu familiarity converts directly into repeat chain procurement.
- Buyers compare cut consistency with the actual minutes of crispness retained, since a cheaper fry can become costly if complaints and replacement portions rise.
What supports Foodservice as the preferred end-use channel?
Foodservice accounts for 71.0% of end use in 2026, underpinned by recurring chain-level procurement.
Foodservice holds 71.0% of 2026 demand because one approved specification can move through hundreds or thousands of outlets, while retail buying remains divided among households and brands. A restaurant contract also repeats weekly, making foodservice more dependable for plant planning. This share can work against a processor when too much capacity depends on a few large accounts, as price negotiations become harder and a specification failure can affect large volume at once.
- Foodservice is projected to hold 71.0% in 2026 as centralized chain buying converts each approved product into recurring multi-location demand.
- The stronger supplier is not only the lowest bidder; it is the one that can keep the same fry result when crop solids and storage age change.
How does Fried Processing meet changing application needs?
Fried processing holds 79.0% of processing demand in 2026, supported by rapid final preparation.
Fried processing is expected to hold 79.0% in 2026 because partial frying completes the difficult part of surface formation before the product enters a commercial kitchen. Operators then use existing fryers and fixed cooking instructions, which limits training and service variation. Oil cost and nutrition concerns can slow some demand, but these pressures are more likely to move product design towards lighter coatings or reduced-oil claims than remove fried formats from core menus. Dependable commercial refrigeration systems remain necessary for preserving the advantage created at the processing plant.
- Fried products are projected to account for 79.0% in 2026 because final preparation remains quick while color and surface texture are largely controlled at the plant.
- Processing demand could shift at the edges towards baked formats, yet high-throughput restaurants will continue using fried products where speed and familiar taste matter more.
Why are buyers selecting Offline Distribution?
Offline distribution captures 82.0% of channel demand in 2026, reinforced by refrigerated distributor coverage.
Offline distribution is expected to capture 82.0% in 2026 because frozen potatoes cannot be treated like an ordinary parcel after an order is placed. Distributors consolidate stock, verify temperature and place deliveries into kitchen schedules. Digital ordering will still grow, but the physical movement remains tied to refrigerated depots and vehicles. The opportunity sits in combining online ordering visibility with established cold-chain fulfilment rather than expecting the online channel to replace the distributor. Established cold chain packaging systems support the same temperature discipline through transport.
- Offline channels are likely to hold 82.0% in 2026 as the distributor performs storage and delivery work that the ordering interface cannot perform.
- Channel share may change slowly even when digital orders rise, because ordering can move online while fulfilment continues through the same refrigerated network.
What are the drivers, restraints, and opportunities in the Frozen Potatoes Market?
QSR expansion lifts recurring volume, agricultural variability pressures processor margins, and air-fryer compatible formats create retail value.
- Driver: Every new QSR outlet becomes a repeat frozen fry buying point once the cut and cooking specification is approved.
- Restraint: Lower yields or weak solids can raise raw material use per tonne of finished product and reduce processor margin before selling prices are changed.
- Opportunity: Air-fryer and baked formats can bring frozen potatoes into households that avoid regular deep frying but still want short preparation time.
Growth Analysis and Future Potential: Foodservice Demand Catalysts
FMI research indicates that expansion of restaurant outlets supports demand, but the larger reason is replication. A chain does not want one outlet making a better fry than another; therefore, frozen fries are purchased around a fixed cut, coating and hold time. This makes every approved location a recurring procurement point and explains why foodservice is expected to reach 71.0% of 2026 demand. In May 2026, McCain Foods reported that its inaugural Spud Report covered more than 12,000 consumers across 11 countries, showing that fries continue to travel well across different eating habits. The growing frozen food sector gives processors related retail and foodservice routes. Similar specification pressure is visible across airport quick-service restaurant operations where serving time remains narrow.
Risk Assessment of the Frozen Potatoes Market: Agricultural and Cold-Chain Friction
Agricultural variability enters the frozen category before the product reaches a freezer. Potato size, dry matter and color influence recovery and frying result, meaning processors cannot substitute one crop for another without adjustment. USDA estimated United States potato production at 412 million cwt in 2025, down 2% from 2024. Lower output may increase crop-haul distance and plant sourcing cost. Large suppliers can spread this pressure through contracted acreage and several storage points; smaller plants may have to accept expensive spot supply or lower utilization.
Commercial Opportunity Analysis: Coating and Retail Format Differentiation
Retail demand can move beyond conventional fries when the product solves a home-cooking issue rather than only copying restaurant food. Air-fryer instructions and reduced-oil formats allow a household to obtain crispness without managing a deep fryer. Packaging must also survive freezer handling and close properly after part use. Lamb Weston promotes frozen par-fried products prepared with olive oil and has communicated packaging changes. These formats can earn a better shelf position, although a premium will hold only when the finished texture is visibly different from a standard pack. This makes the frozen food packaging category part of retail performance rather than only pack appearance.
Frozen Potatoes Market by Country (2026 to 2036)
As noted by FMI, China is expected to record the highest growth among the evaluated countries at 7.6% CAGR through 2036, while Brazil is projected at 4.2%. The difference is not only consumer size. China has faster addition of restaurant points and digitally supported cold delivery, whereas Brazil must cover longer routes with a smaller processing base. India follows at 7.0% as organized foodservice moves into more cities, while mature markets grow through replacement, premium formats and better cooking performance rather than first-time category entry.
Table 7: Country CAGR and Primary Growth Levers for the Frozen Potatoes Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 7.6% | QSR expansion and e-commerce cold-chain reach |
| India | 7.0% | Organized foodservice growth and new processing investment |
| Germany | 6.4% | Established retail demand and foodservice standards |
| France | 5.9% | Large frozen-food retail base and restaurant demand |
| UK | 5.3% | Convenience retail and delivery-led foodservice |
| USA | 4.8% | Large QSR installed base and product innovation |
| Brazil | 4.2% | Domestic capacity expansion and urban foodservice growth |
Source: Future Market Insights analysis
China Frozen Potatoes Market Outlook (2026 to 2036)
China at 7.6% CAGR is being shaped by outlet replication and distribution reach at the same time. Western and domestic chains can open in lower-tier cities only when fries of the same specification are available outside coastal hubs. E-commerce logistics helps retail access, but restaurant demand still requires depot stock and scheduled delivery. Domestic processing can reduce import exposure; however, local crop suitability and uneven cold storage may keep quality inconsistent between regions. Growth will move faster where processors place capacity near potato belts and link it with city warehouses.
For China, the market moves in favour of suppliers that can make a local crop perform like a chain-approved fry and then deliver the same result across several city clusters.
India Frozen Potatoes Market Outlook (2026 to 2036)
India at 7.0% CAGR has a different demand path because frozen fries are moving with organized restaurants beyond the largest metros. The consumer base is not the main limitation; freezer space, power cost and fragmented last-mile handling are. Regional processing close to northern potato belts can shorten raw material movement, while distributor partnerships can protect product temperature into tier-2 and tier-3 cities. Demand can rise quickly with QSR openings, but adoption may remain uneven if a city gains outlets before dependable frozen distribution is available.
In India, processing investment will create value only when it is matched with regional cold storage, otherwise added plant volume can remain concentrated around a few large cities.
Germany Frozen Potatoes Market Outlook (2026 to 2036)
Germany is projected to grow at 6.4% CAGR, supported by an established frozen-food habit rather than first-time adoption. The market gives suppliers steady retail movement and technically demanding foodservice accounts, but energy use and packaging compliance can take away the benefit of higher volume. Retailers are likely to favour suppliers that document sourcing and move towards recyclable packs without weakening freezer performance. Growth therefore depends on making an already familiar category better, not simply placing more standard fries on shelves.
Germany can reward efficient plants and compliant packs, while suppliers relying only on scale may find that energy and redesign cost absorbs the expected market growth.
France Frozen Potatoes Market Outlook (2026 to 2036)
France is expected to expand at 5.9% CAGR as frozen retail remains well developed and restaurants continue using standardized potato products. The opportunity is wider in premium cuts, skin-on formats and products carrying clearer oil or salt positioning. A conventional product with a long ingredient list may lose shelf support even if its frying performance is acceptable. Suppliers may therefore need separate retail and restaurant formulations, one built around label and home preparation, the other around speed and consistency during service.
France will not be won by one universal product; the retail side asks for a cleaner and more differentiated pack, while restaurant kitchens continue paying for reliable output.
UK Frozen Potatoes Market Outlook (2026 to 2036)
The UK is projected to grow at 5.3% CAGR, where convenience retail and delivery-led foodservice keep frozen potatoes in regular use. The pressure comes from energy, farm uncertainty and value-sensitive restaurant menus. In February 2026, McCain Foods announced a 202-hectare UK Farm of the Future, indicating that processors are bringing agronomy closer to long-term supply planning. Suppliers with grower programs and national distribution are better placed, as they can balance weak crops and still meet weekly chain deliveries.
The UK market is likely to favour processors that control more of the path from farm practice to national delivery, because reliability has become as important as adding a new fry variant.
USA Frozen Potatoes Market Outlook (2026 to 2036)
The United States is projected to grow at 4.8% CAGR, slower than China and India because frozen fries already sit across a very large QSR base. Growth comes from menu replacement, coatings that survive delivery and retail packs made for air fryers. USDA estimated 2025 potato production at 412 million cwt, down 2% from 2024, which can tighten grower negotiations when restaurant customers are resisting price increases. Scale remains useful, but a large plant also carries utilization risk if a major chain changes volume or specification.
In the United States, mature demand protects base volume, while margin will be decided by crop contracts and whether product innovation solves delivery or kitchen problems.
Brazil Frozen Potatoes Market Outlook (2026 to 2036)
Brazil is expected to record 4.2% CAGR, the lowest rate in the evaluated set, yet local capacity can change the quality of this growth. Frozen fries have often carried import and long-distance freight exposure, and production closer to consumption can therefore improve availability and working capital. In November 2025, McCain Foods announced an R$1.8 billion expansion of its Araxa facility in Minas Gerais, Brazil, adding a new French fry production line and a pre-formed products line to serve rising regional demand. Imported equipment cost and the distance between major cities remain hurdles. Regional warehouses and locally sourced potatoes can support growth, but only when finished products continue meeting chain-level color and texture requirements.
Brazil has room to replace imported movement with local output, although the advantage will disappear if domestic sourcing creates variation that restaurant chains cannot accept.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Frozen Potatoes Market?
McCain Foods, Lamb Weston, J.R. Simplot Company, Aviko, Farm Frites, Agristo, and Cavendish Farms are notable companies operating in this market.
Competition is moving around crop access and customer dependence rather than product count alone. McCain Foods and Lamb Weston have the scale to connect grower programs with national restaurant agreements. J.R. Simplot Company has a strong North American foodservice position, while Aviko, Farm Frites and Agristo use European processing and export reach. Regional processors can still win where freight is high or customers need flexible specifications, but they carry more risk when a poor crop or one major account affects a large share of plant volume. The wider food packaging sector also influences retail qualification as material use comes under review.
- Competition covered in the FMI report is moving around crop access and customer dependence rather than product count alone.
- European Processing Platforms: Aviko, Farm Frites, and Agristo.
- North American Regional Scale: Cavendish Farms.
Competitive Benchmarking: Frozen Potatoes Market
Table 8: Competitive Benchmarking for the Frozen Potatoes Market, 2026
| Company | Processing Scale | QSR Relationships | Coating Technology | Geographic Reach |
|---|---|---|---|---|
| McCain Foods | High | High | High | High |
| Lamb Weston | High | High | High | High |
| J.R. Simplot Company | High | High | Medium | High |
| Aviko | High | Medium | Medium | High |
| Farm Frites | Medium | Medium | Medium | High |
| Agristo | Medium | Medium | Medium | High |
| Cavendish Farms | Medium | High | Medium | Medium |
High indicates broad public evidence across processing, customer access or geographic coverage. Medium indicates an established but narrower position. The rating does not state product quality and should not be read as audited market share.
Key Developments in the Frozen Potatoes Market
- In February 2026, McCain Foods released its 2025 Global Sustainability Report and announced its third Farm of the Future, extending regenerative agriculture testing into the UK.
- In November 2025, McCain Foods agreed to acquire Penobscot McCrum, adding processing and grower relationships to its North American footprint.
- In November 2025, McCain Foods announced an R$1.8 billion expansion of its Araxá facility in Minas Gerais, Brazil, increasing the role of local production in its regional supply. [10]
- During fiscal 2025, Lamb Weston continued manufacturing-network actions while advancing products and packaging intended to improve customer performance.
Key Players in the Frozen Potatoes Market
Global Frozen Potato Processors
- McCain Foods
- Lamb Weston
- J.R. Simplot Company
European Specialists
- Aviko
- Farm Frites
- Agristo
Regional Integrated Processor
- Cavendish Farms
Frozen Potatoes Market - Report Scope
Table 9: Report Scope for the Frozen Potatoes Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; End Use; Distribution Channel; Packaging; Processing |
| Quantitative units | USD Billion |
| Market definition | Commercially traded frozen potato products processed by cutting, blanching, partial frying or baking, and freezing. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA, UK, Germany, France, China, India, Brazil, and additional countries |
| Key companies covered | McCain Foods, Lamb Weston, J.R. Simplot Company, Aviko, Farm Frites, Agristo, Cavendish Farms |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Frozen Potatoes Market - Research Methodology
Table 10: Research Methodology for the Frozen Potatoes Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with processors, growers, distributors, foodservice procurement teams, retailers, and industry specialists validate demand and purchasing patterns. |
| Secondary Research | Company reports, investor presentations, regulatory publications, associations, technical papers, trade journals, company websites, and product literature support evidence collection. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess value demand, product mix, channel shares, and country growth from 2026 to 2036. |
| Data Triangulation and Validation | Findings are checked against crop output, cold-storage indicators, corporate disclosures, trade activity, and historical trends. |
Frozen Potatoes Market by Segments
Frozen Potatoes Market segmented by Product:
- Potato Fries
- Potato Wedges
- Stuffed Potatoes
- Potato Slices
- Potato Chunks
- Potato Dices
- Baked Potatoes
- Other Products
Frozen Potatoes Market segmented by End Use:
- Foodservice
- Retail
Frozen Potatoes Market segmented by Distribution Channel:
- Offline
- Online
Frozen Potatoes Market segmented by Packaging:
- Bags
- Boxes
Frozen Potatoes Market segmented by Processing:
- Fried
- Baked
Frozen Potatoes Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2025, July 31). Vegetables and pulses outlook: July 2025.
- [2] U.S. Department of Agriculture, National Agricultural Statistics Service. (2025, December 19). North American potatoes.
- [3] McCain Foods Limited. (2026, May 26). The world agrees on fries: Inaugural Spud Report.
- [4] Lamb Weston Holdings, Inc. (2026). Product innovation and sustainable packaging platform.
- [5] McCain Foods Limited. (2026, February 8). New UK Farm of the Future announcement.
- [6] U.S. Department of Agriculture, National Agricultural Statistics Service. (2025, December 19). United States potato production, 2025.
- [7] McCain Foods Limited. (2025, November 30). R$1.8 billion expansion of the Araxá facility.
- [8] McCain Foods Limited. (2026, February 5). 2025 Global Sustainability Report and third Farm of the Future.
- [9] McCain Foods Limited. (2025, November 12). Agreement to acquire Penobscot McCrum.
- [10] McCain Foods Limited. (2025, November 30). Major expansion of the Araxá processing facility in Brazil.
- [11] Lamb Weston Holdings, Inc. (2025). Annual report and manufacturing network update.
Only sources used for external statistics or company developments are listed. Linked titles open the originating government or company page.
This Report Answers
- How large is the frozen potatoes market in 2026 and what is forecast for 2036?
- Which foodservice and retail forces support frozen potato demand?
- Why do potato fries lead the product category?
- Why does foodservice dominate end use?
- How do growth rates differ across major evaluated countries?
- Which processors hold significant competitive positions?
- What limits adoption or supplier switching?
- What should buyers evaluate before qualifying a frozen potato supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Potato Fries
- Potato Wedges
- Stuffed Potatoes
- Potato Slices
- Potato Chunks
- Potato Dices
- Baked Potatoes
- Other Products
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Foodservice
- Retail
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Offline
- Online
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging, 2026 to 2036
- Bags
- Boxes
- Y-o-Y Growth Trend Analysis By Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Processing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing, 2026 to 2036
- Fried
- Baked
- Y-o-Y Growth Trend Analysis By Processing, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By End Use
- By Distribution Channel
- By Packaging
- By Processing
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- McCain Foods
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Lamb Weston
- J.R. Simplot Company
- Aviko
- Farm Frites
- Agristo
- Cavendish Farms
- McCain Foods
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Processing, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Packaging, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Processing, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Packaging
- Figure 15: Global Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Processing
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Packaging
- Figure 41: North America Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Processing
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product
- Figure 48: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End Use
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Packaging
- Figure 57: Latin America Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Processing
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product
- Figure 64: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by End Use
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Packaging
- Figure 73: Western Europe Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Processing
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Packaging
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Processing
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product
- Figure 96: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by End Use
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Packaging
- Figure 105: East Asia Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Processing
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Packaging
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Processing
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Packaging, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Packaging
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Processing, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Processing, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Processing
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the frozen potatoes market in 2026, and what is forecast for 2036?
The FMI forecast places the frozen potatoes market at USD 73.0 billion in 2026 and USD 125.8 billion by 2036, as restaurant procurement and retail convenience continue adding recurring demand.
What is the CAGR from 2026 to 2036?
The market is expected to rise at 5.6% CAGR from 2026 to 2036. As per FMI assessment, this pace reflects steady volume addition rather than a short demand spike.
Which product segment leads?
Potato fries lead with 46.0% share in 2026 because they already have menu familiarity and standardized preparation across foodservice and retail.
Which end-use segment leads?
Foodservice accounts for 71.0% of 2026 demand as one chain approval can support repeat purchasing across several outlets.
Which country has the strongest listed growth outlook?
China records the strongest listed outlook at 7.6% CAGR through 2036, supported by QSR rollout and wider refrigerated distribution.
Who are the key players?
McCain Foods, Lamb Weston, J.R. Simplot Company, Aviko, Farm Frites, Agristo and Cavendish Farms are among the notable processors covered in the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
