

- Market Size (2026)
- USD 24.0 Bn
- Forecast (2036)
- USD 41.4 Bn
- CAGR (2026 to 2036)
- 5.6%
How big is Frozen Pizza Market in 2026?
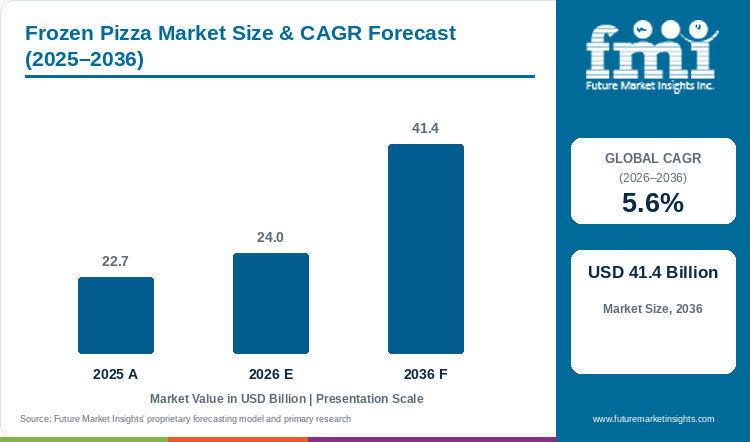
Sales in the frozen pizza market are projected to grow at 5.6% CAGR, with market size rising from USD 22.7 billion in 2025 to USD 24.0 billion in 2026 and reaching USD 41.4 billion by 2036.
According to Future Market Insights analysis, the frozen pizza market stands at USD 22.7 billion in 2025 and rises to USD 24.0 billion in 2026. Industry valuation is projected to reach USD 41.4 billion by 2036 at a 5.6% CAGR, generating USD 17.4 billion in added revenue. Household demand builds when pizza replaces a restaurant order without extra cooking time or preparation risk. In January 2026, Conagra documented USD 93.5 billion in annual United States frozen department sales [1]. That scale confirms freezer aisles as routine trips, as seen in the broader commercial frozen food sector.
Key Market Trends & Insights
- By product positioning: standard branded pizza is projected to account for 40.5% in 2026, supported by familiar recipes and wide retail listings.
- By processing state: frozen ready-to-bake pizza is estimated to hold 46.9% in 2026, owing to long storage life and predictable oven preparation.
- By end use: household retail consumption is forecast to represent 51.5% in 2026, underpinned by repeat supermarket purchasing.
- By sales channel: supermarkets and hypermarkets remain central because frozen aisles support broad price and pack choices.
- By pack size: family-size and multipack formats benefit from planned household meals, while single-serve products suit smaller households.
Regional Highlights
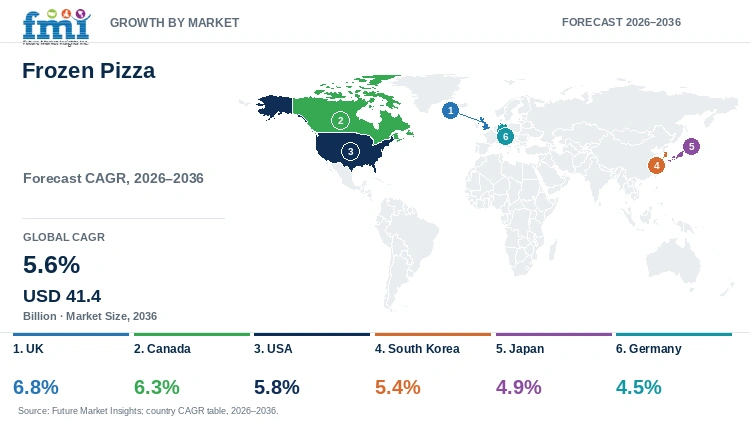
- Fastest-growing evaluated country: the UK, at 6.8% CAGR from 2026 to 2036.
- Follower countries: Canada at 6.3%, the USA at 5.8%, South Korea at 5.4%, and Japan at 4.9%, while Germany records the lowest evaluated CAGR at 4.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Frozen Pizza Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 22.7 billion |
| Estimated Market Size in 2026 | USD 24.0 billion |
| Projected Market Size by 2036 | USD 41.4 billion |
| CAGR, 2026 to 2036 | 5.6% |
| Added Revenue, 2026 to 2036 | USD 17.4 billion |
Consumption Occasion and Household Sizing
Table 2: Consumption Occasion and Household Sizing for the Frozen Pizza Market (USD billion and scenario indicators), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 22.7 | 24.0 | 41.4 |
| Estimated annual eating occasions (billion) | 5.6 to 6.1 | 5.9 to 6.5 | 8.4 to 9.2 |
| Average supplier revenue per occasion (USD) | 3.72 to 4.05 | 3.69 to 4.07 | 4.50 to 4.93 |
| Household retail revenue share | 50.8% | 51.5% | 52.2% |
Per Capita & Retail-Channel Sizing
FMI data suggests per-person frozen pizza spend aligns with reported revenue and population baselines. The tables below translate the USD 24.0 billion 2026 value into eating occasions and retail indicators. Buyers can use these ranges to test price and velocity assumptions before listing decisions.
Table 3: Per Capita and Retail Indicators for the Frozen Pizza Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Market spend per capita (USD) | 2.76 | 2.89 | 4.63 |
| Spend per 1,000 people (USD) | 2,758 | 2,892 | 4,626 |
| Household end-use revenue (USD billion) | 11.5 | 12.4 | 21.6 |
Table 4: Retail and Frozen-Food Operating Indicators for the Frozen Pizza Market (USD billion and percentages), 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Frozen pizza market, 2026 | USD 24.0 billion | Report value |
| U.S. frozen food department, 2026 | USD 93.5 billion | Conagra report |
| Household retail revenue, 2026 | USD 12.4 billion | 51.5% share |
| Added frozen pizza revenue, 2026 to 2036 | USD 17.4 billion | Forecast difference |
Analyst Perspective
“Retailers will expand frozen pizza space when recipe quality raises repeat purchases without weakening price discipline. Brands that separate family value from premium occasions can protect distribution through changing household budgets.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Frozen Pizza Market segmented?
The frozen pizza market is segmented by crust type, product positioning, processing state, toppings, sales channel, end use, and pack size. In 2026, standard branded pizza is projected at 40.5%, frozen ready-to-bake at 46.9%, and household retail consumption at 51.5%.
By crust type: thin crust, thick crust, stuffed crust, gluten-free crust, and others.
By product positioning: standard branded pizza, organic and clean-label pizza, premium specialty pizza, and private-label pizza.
By processing state: frozen ready-to-bake pizza, chilled pizza, par-baked foodservice pizza, and pizza kits.
By toppings: cheese, meat, vegetable, plant-based, and mixed specialty toppings.
By sales channel: supermarkets and hypermarkets, convenience stores, online grocery, club stores, and foodservice distributors.
By end use: household retail consumption, foodservice and hospitality, institutional catering, and commercial food manufacturing.
By pack size: single-serve, family-size, multipack, and foodservice bulk.
Why does standard branded pizza lead product positioning demand?
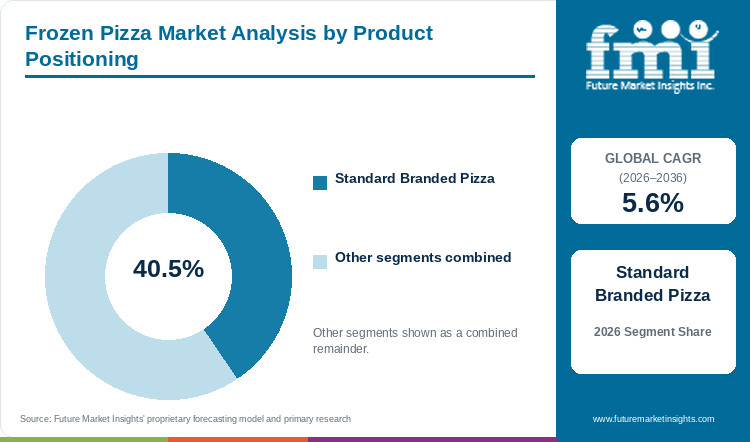
Based on product positioning, standard branded pizza is projected to account for 40.5% in 2026, supported by familiar taste.
Table 5: Product Positioning Share for the Frozen Pizza Market (percentage share), 2026
| Product Positioning | Share (2026) |
|---|---|
| Standard branded pizza | 40.5% |
| Other Segments Combined | 59.5%* |
| Total | 100.0% |
Table 6: Product Positioning Leadership and Market Growth for the Frozen Pizza Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.6% |
| Leading Segment | Standard branded pizza |
Standard branded pizza retains shelf space through recognizable flavor and dependable promotional volume. Retailers place it between private label and premium ranges without asking shoppers to learn new promises, a dynamic also seen with plant-based alternatives in packaged grocery. Brands can trial thin or stuffed bases under the same label while keeping cheese and meat volumes stable.
- Standard branded pizza represents 40.5% of product positioning in 2026 as familiar recipes support repeat purchasing.
- In April 2026, Dr. Oetker confirmed the 40th anniversary of Pizza Ristorante in its Business Year 2025 results, describing it as one of the best-known brands in the frozen pizza segment [3].
What supports frozen ready-to-bake pizza as the preferred processing state?
By processing state, frozen ready-to-bake pizza is estimated to hold 46.9% in 2026, owing to long storage and predictable preparation.
Frozen ready-to-bake formats let retailers carry several recipes without the short sell-by windows attached to chilled pizza. Households choose the cooking time, which makes the product useful for planned meals and unexpected schedule changes. Chilled lines cannot match that window, so frozen formats capture wider freezer door allocation.
- Frozen ready-to-bake pizza holds 46.9% of processing state demand through storage flexibility and controlled preparation.
How does household retail consumption lead frozen pizza end use?
In 2026, household retail consumption is expected to lead end use with 51.5% share, reflecting repeat supermarket purchasing.
Households buy frozen pizza as a scheduled meal and as backup food when cooking time narrows. Family packs improve value comparison, while single-serve products match smaller households and individual eating times. Single-serve and family packs let the same brand serve solo dinners and shared tables, while dairy-free extensions indicate expanding consumer variety.
- Household retail consumption accounts for 51.5% of end use as shoppers keep flexible meals available at home.
- Repeat velocity decides listings, so suppliers support core product lines with seasonal toppings that do not disrupt base supply.
What are the drivers, restraints, and opportunities in the Frozen Pizza Market?
Household meal substitution expands demand, whereas cold-chain cost limits assortment, and premium dietary formats create new purchase occasions.
- Driver: At-home dining gives frozen pizza a lower-effort substitute for restaurant delivery and scratch cooking.
- Restraint: Frozen storage, energy use, transport continuity, and retailer freezer fees limit slow-moving assortment depth.
- Opportunity: Premium crusts, plant-based toppings, and portion-specific packs widen household meal occasions.
Growth Analysis and Future Potential: Household Meal Substitution
FMI research indicates at-home dining gives frozen pizza a lower-effort substitute for delivery and scratch cooking. In January 2026, Conagra flagged restaurant-style frozen meals as a repeat category driver [5]. Frozen pizza converts that behavior through familiar toppings and predictable portions. Products categorized alongside the frozen snacks category also capture weekend sharing occasions, prompting manufacturers to provide clear oven preparation instructions.
Risk Assessment of the Frozen Pizza Market: Cold-Chain Cost Pressure
Frozen distribution protects product life but raises the cost attached to each extra recipe. Cold-chain depth supports supply, yet power and transport bills punish slow lines. As noted by FMI, smaller brands face the sharpest hurdle since they cannot spread shipments across many stores. Strict cold chain packaging standards protect product texture during transport, prompting retailers to trim secondary flavors first when freezer doors tighten.
Commercial Opportunity Analysis: Premium and Dietary Formats
Premium formats create value when they solve a defined household need rather than add novelty. In July 2025, Dr. Oetker announced a limited dessert pizza for September release [6]. An FMI analyst notes similar room in gluten-free formulations and specialized vegetable toppings across established brand families. Expanding into ready-to-eat meals and distinct crust types allows brands to capture added occasions without inflating supply chain complexity.
Frozen Pizza Market by Country (2026 to 2036)
As per FMI analysis, the UK represents the fastest-growing frozen pizza market among six evaluated countries at 6.8% CAGR, while Germany records 4.5% CAGR. Commercial outcomes differ with grocery access, frozen capacity, local eating habits, price pressure, and the cost of maintaining reliable cold distribution.
Table 7: Country CAGR and Primary Growth Levers for the Frozen Pizza Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UK | 6.8% | Food-retail scale and online grocery access |
| Canada | 6.3% | Frozen manufacturing and cold-storage capacity |
| USA | 5.8% | Large frozen department and in-home meal substitution |
| South Korea | 5.4% | Processed-food retail and imported-food compliance |
| Japan | 4.9% | Prepared-food demand and compact household formats |
| Germany | 4.5% | Established frozen consumption and recipe renewal |
Source: Future Market Insights analysis
UK Frozen Pizza Market Outlook (2026 to 2036)
Frozen pizza demand in the UK is forecast to rise at 6.8% CAGR over the forecast period, supported by broad food retail and online food delivery access. While value-focused households compare grocery meal prices with restaurant spending, freezer energy costs and tight shelf competition restrict slow-moving flavors. Suppliers answer with family value multi-packs, premium thin crusts, and retailer-specific packs that turn rapidly within limited door space.
Key takeaway: In the UK, broad grocery access converts household food spending into repeat frozen pizza purchasing when pack value remains visible.
Canada Frozen Pizza Market Outlook (2026 to 2036)
Cold storage and domestic frozen manufacturing give Canadian retailers a practical base for broader pizza assortments, allowing Canada to grow at a projected 6.3% CAGR through 2036. The central operational hurdle is freight across a dispersed population outside major urban corridors. Manufacturers concentrate proven high-velocity recipes in regional distribution hubs, adding dietary or premium variants only where local store volume supports sustained replenishment.
Key takeaway: In Canada, frozen manufacturing depth supports pizza availability, while regional freight economics determine assortment breadth.
USA Frozen Pizza Market Outlook (2026 to 2036)
Frozen pizza sales in the USA are forecast to expand at 5.8% CAGR by 2036, owing to restaurant-style demand moving into the home. In its January 2026 review, Conagra placed takeout-style frozen foods at USD 14.3 billion in annual United States sales [9]. While expansive frozen aisles provide immediate scale, heavy promotional dependence can erode supplier margins and train shoppers to wait for discounts. Brands respond by integrating protein-led toppings, air-fryer directions, and specialized food packaging formats that protect crust texture while justifying stable shelf prices.
Key takeaway: In the USA, scale creates access, but clearly separated eating occasions protect frozen pizza from permanent discounting.
South Korea Frozen Pizza Market Outlook (2026 to 2036)
Adoption of frozen pizza in South Korea is estimated to expand at 5.4% CAGR through 2036, influenced by urban retail and Western-style home meals. Imported frozen pizza must fit local labeling, packaging, and food-safety requirements before flavor can influence demand. Suppliers use compact portion packs, crisp crusts, and localized toppings that connect with Korean eating habits while preserving compliant cold-chain information.
Key takeaway: In South Korea, regulatory fit and localized flavor design determine whether imported or domestic frozen pizza reaches repeat purchase.
Japan Frozen Pizza Market Outlook (2026 to 2036)
Japan's frozen pizza outlook is anticipated to advance at 4.9% CAGR over the assessment period, supported by demand for easy-to-prepare and ready-to-eat convenience foods. A November 2025 USDA Foreign Agricultural Service retail report placed Japanese food retail sales at USD 193.0 billion for 2024, reflecting stable sector performance [11]. Because compact kitchens and limited freezer space discourage bulky family packs, producers introduce single-serve pizzas, divisible multi-packs, and smaller crust dimensions that cook evenly in countertop appliances without generating leftovers.
Key takeaway: In Japan, compact portions and appliance-friendly preparation turn prepared-food demand into a practical frozen pizza occasion.
Germany Frozen Pizza Market Outlook (2026 to 2036)
The German frozen pizza sector is projected to record 4.5% CAGR during the assessment period, linked to established consumption and steady product renewal. The German Frozen Food Institute reported 4.2 million tonnes of frozen food sales in 2025, up 2.5% [12]. Market maturity and intense private-label presence limit easy volume expansion. Established brands respond by introducing salt-reduced formulations, sourdough crusts, and seasonal topping variations that refresh consumer interest without abandoning familiar heritage lines.
Key takeaway: In Germany, high frozen-food familiarity rewards recipe renewal more than basic category education.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Frozen Pizza Market?
Dr. Oetker GmbH, Conagra Brands, Inc., Nestle S.A., General Mills, Inc., Schwan’s Company, Palermo Villa, Inc., Amy’s Kitchen, Inc., and Daiya Foods Inc. are significant frozen pizza market participants.
Competition divides between global frozen-food groups, pizza-focused manufacturers, and dietary-positioned suppliers. Global groups use retailer reach to support wide distribution, while specialists rely on pizza expertise or dietary claims.
Global branded platforms: Dr. Oetker GmbH, Conagra Brands, Inc., Nestle S.A., and General Mills, Inc. compete through broad retail access.
Pizza-focused manufacturers: Schwan’s Company and Palermo Villa, Inc. concentrate production and portfolio decisions around frozen pizza.
Dietary-positioned suppliers: Amy’s Kitchen, Inc. and Daiya Foods Inc. use organic, vegetarian, gluten-free, or plant-based positioning.
Competitive Benchmarking: Frozen Pizza Market
Table 8: Competitive Benchmarking for the Frozen Pizza Market (qualitative capability ratings), 2026
| Company | Pizza Portfolio Breadth | Dietary-Format Depth | Retail Access | Geographic Reach |
|---|---|---|---|---|
| Dr. Oetker GmbH | High | High | High | High |
| Conagra Brands, Inc. | High | High | High | Medium |
| Nestle S.A. | High | Medium | High | High |
| General Mills, Inc. | Medium | High | High | High |
| Schwan’s Company | High | Medium | High | Medium |
| Palermo Villa, Inc. | High | Medium | Medium | Low |
| Amy’s Kitchen, Inc. | Medium | High | Medium | Medium |
| Daiya Foods Inc. | Low | High | Medium | Medium |
Key Developments in the Frozen Pizza Market
- In April 2026, Dr. Oetker reported that pizza supported Western European growth during financial year 2025 [13].
- In January 2026, Conagra published its third annual frozen-food review and flagged restaurant-style meals as a repeat growth theme.
- In September 2025, Dr. Oetker introduced a limited-edition Ristorante Pizza à la Tiramisu in Germany to mark the brand's 40th anniversary, featuring mascarpone cream, Amarettini pieces, and a thin crust base [6].
Key Players in the Frozen Pizza Market
Global Frozen-Food Platforms
- Dr. Oetker GmbH
- Conagra Brands, Inc.
- Nestle S.A.
- General Mills, Inc.
Pizza-Focused Manufacturers
- Schwan’s Company
- Palermo Villa, Inc.
Dietary-Positioned Frozen-Food Suppliers
- Amy’s Kitchen, Inc.
- Daiya Foods Inc.
Frozen Pizza Market - Report Scope
Table 9: Report Scope for the Frozen Pizza Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Crust Type; Product Positioning; Processing State; Toppings; Sales Channel; End Use; Pack Size |
| Quantitative Units | USD Billion |
| Market Definition | Supplier revenue from in-scope frozen pizza products sold through retail and foodservice channels. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UK, Canada, USA, South Korea, Japan, Germany, and additional countries in the full report |
| Key Companies Covered | Dr. Oetker GmbH, Conagra Brands, Inc., Nestle S.A., General Mills, Inc., Schwan’s Company, Palermo Villa, Inc., Amy’s Kitchen, Inc., Daiya Foods Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Frozen Pizza Market - Research Methodology
Table 10: Research Methodology for the Frozen Pizza Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, ingredient suppliers, frozen-food distributors, retailers, foodservice buyers, industry experts, and category professionals to validate product demand, purchasing decisions, pricing, and channel requirements. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other publicly available sources relevant to frozen pizza. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 used top-down and bottom-up approaches to assess revenue, pricing, household adoption, channel participation, and country demand. |
| Data Triangulation and Validation | Data was validated against macroeconomic indicators, food expenditure, frozen-food activity, regulatory conditions, company developments, and historical trends without double counting chilled pizza or restaurant sales. |
Frozen Pizza Market by Segments
Frozen Pizza Market segmented by Crust Type:
- Thin Crust
- Thick Crust
- Stuffed Crust
- Gluten-Free Crust
- Others
Frozen Pizza Market segmented by Product Positioning:
- Standard Branded Pizza
- Organic and Clean-Label Pizza
- Premium Specialty Pizza
- Private-Label Pizza
Frozen Pizza Market segmented by Processing State:
- Frozen Ready-to-Bake Pizza
- Chilled Pizza
- Par-Baked Foodservice Pizza
- Pizza Kits
Frozen Pizza Market segmented by Toppings:
- Cheese
- Meat
- Vegetable
- Plant-Based
- Mixed Specialty Toppings
Frozen Pizza Market segmented by Sales Channel:
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Grocery
- Club Stores
- Foodservice Distributors
Frozen Pizza Market segmented by End Use:
- Household Retail Consumption
- Foodservice and Hospitality
- Institutional Catering
- Commercial Food Manufacturing
Frozen Pizza Market segmented by Pack Size:
- Single-Serve
- Family-Size
- Multipack
- Foodservice Bulk
Frozen Pizza Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Conagra Brands, Inc. (2026, January 14). Future of Frozen Food 2026 reviews trends shaping USD 93.5 billion industry. Conagra Brands newsroom.
- [2] U.S. Food and Drug Administration. (2025). Added sugars on the Nutrition Facts label: Requirements for packaged foods. U.S. Department of Health and Human Services.
- [3] Dr. Oetker. (2026, April 20). Business Year 2025: Dr. Oetker and Coppenrath & Wiese hold their ground in a challenging economic environment. Dr. August Oetker KG.
- [4] Statistics Canada. (2025, March 6). Stocks of frozen and chilled meats, January 1, 2025: 134,689 tonnes, up 5.2% annually. Government of Canada.
- [5] Conagra Brands, Inc. (2026, January). The Future of Frozen Food 2026: Restaurant-style frozen meals as a repeat category driver. Conagra Brands category review.
- [6] Dr. Oetker. (2026, April 20). Business Year 2025: Pizza Ristorante 40th anniversary and dessert segment. Dr. August Oetker KG.
- [7] Department for Environment, Food and Rural Affairs. (2025). Food statistics in your pocket: UK food and alcoholic-drink expenditure. UK Government.
- [8] Agriculture and Agri-Food Canada. (2025). Customized report service: Frozen ready meals in Canada at USD 4.0 billion retail sales. Government of Canada.
- [9] Conagra Brands, Inc. (2026, January). The Future of Frozen Food 2026: Takeout-style frozen foods at USD 14.3 billion in annual United States sales. Conagra Brands category review.
- [10] Ministry of Food and Drug Safety. (2025, June 17). Draft amendments to the Food Labeling Standard: Expanded use of electronic labeling for packaged food. Government of Korea.
- [11] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, November 19). Retail foods annual: Japan food retail sales at USD 193.0 billion. U.S. Government.
- [12] German Frozen Food Institute. (2026, April 23). Sales statistics 2025: Frozen food sales at 4.2 million tonnes, up 2.5%. Deutsches Tiefkuhlinstitut.
- [13] Dr. Oetker / Dr. August Oetker KG. (2026, April 20). Business Year 2025: Dr. Oetker and Coppenrath & Wiese hold their ground in a challenging economic environment. Dr. August Oetker KG press release.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the frozen pizza market in 2026 and 2036?
- Which household pressures support frozen pizza purchasing through the forecast period?
- Why does standard branded pizza lead product positioning demand?
- How does frozen ready-to-bake pizza lead the processing-state category?
- Which evaluated countries show a notable frozen pizza expansion outlook?
- Which companies manufacture and distribute frozen pizza in covered markets?
- What limits adoption or supplier switching in the frozen pizza market?
- What should retail buyers evaluate before listing frozen pizza products?
Frequently Asked Questions
How big is the frozen pizza market in 2026, and what is forecast for 2036?
Future Market Insights estimates the frozen pizza market at USD 24.0 billion in 2026 and projects USD 41.4 billion by 2036.
What is the frozen pizza market CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at 5.6% CAGR over the assessment period.
Which product-positioning segment leads the frozen pizza market?
Standard branded pizza is projected to account for 40.5% of product positioning demand in 2026.
Which processing-state segment leads the frozen pizza market?
Frozen ready-to-bake pizza is estimated to hold 46.9% of processing-state demand in 2026.
Which country has a notable growth outlook during the assessment period?
The UK is projected to record 6.8% CAGR from 2026 to 2036, supported by food-retail scale and online grocery access.
Who are the key frozen pizza market participants?
Key participants include Dr. Oetker GmbH, Conagra Brands, Inc., Nestle S.A., General Mills, Inc., Schwan’s Company, and Palermo Villa, Inc.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Crust Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Crust Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Crust Type, 2026 to 2036
- Thin Crust
- Thick Crust
- Stuffed Crust
- Gluten-Free Crust
- Others
- Y-o-Y Growth Trend Analysis By Crust Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Crust Type, 2026 to 2036
- Global Market Analysis and Forecast, By Product Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Positioning, 2026 to 2036
- Standard Branded Pizza
- Organic and Clean-Label Pizza
- Premium Specialty Pizza
- Private-Label Pizza
- Y-o-Y Growth Trend Analysis By Product Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Frozen Ready-to-Bake Pizza
- Chilled Pizza
- Par-Baked Foodservice Pizza
- Pizza Kits
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By Toppings, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Toppings, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Toppings, 2026 to 2036
- Cheese
- Meat
- Vegetable
- Plant-Based
- Mixed Specialty Toppings
- Y-o-Y Growth Trend Analysis By Toppings, 2021 to 2025
- Absolute $ Opportunity Analysis By Toppings, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Grocery
- Club Stores
- Foodservice Distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Household Retail Consumption
- Foodservice and Hospitality
- Institutional Catering
- Commercial Food Manufacturing
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Pack Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pack Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pack Size, 2026 to 2036
- Single-Serve
- Family-Size
- Multipack
- Foodservice Bulk
- Y-o-Y Growth Trend Analysis By Pack Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Pack Size, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Crust Type
- By Product Positioning
- By Processing State
- By Toppings
- By Sales Channel
- By End Use
- By Pack Size
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Dr. Oetker GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Conagra Brands, Inc.
- Nestle S.A.
- General Mills, Inc.
- Schwan’s Company
- Palermo Villa, Inc.
- Amy’s Kitchen, Inc.
- Daiya Foods Inc.
- Dr. Oetker GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


