

- Market Size (2026)
- USD 8.4 Bn
- Forecast (2036)
- USD 15.8 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is IBC Liner Market in 2026?
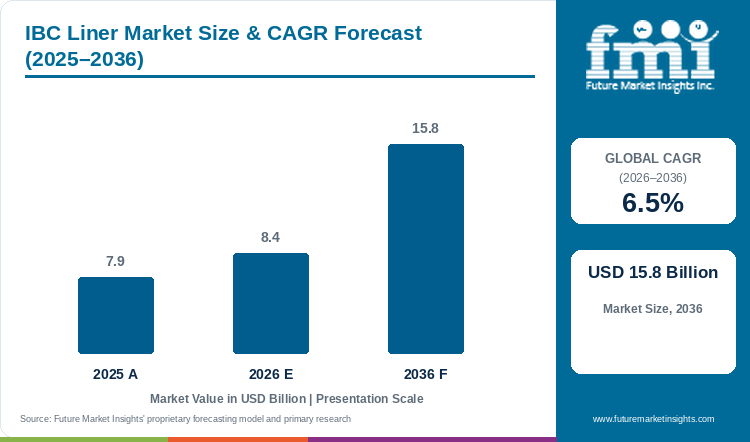
IBC liner demand advances from USD 7.9 billion in 2025 to USD 8.4 billion in 2026 and reaches USD 15.8 billion by 2036 at 6.5% CAGR.
Eliminating caustic tank washout cycles and municipal effluent surcharges compels bulk liquid processors to fit single-trip flexible bladders inside reusable outer totes. Against a 2025 baseline of USD 7.9 billion, global IBC liner sales reach USD 8.4 billion in 2026 and climb to USD 15.8 billion by 2036 at a 6.5% CAGR as shippers add USD 7.4 billion in new orders. Form-Fit IBC Liners captures 42.3% of liner format sales in 2026 because cube-shaped polyethylene bladders sit flush inside 1,000-liter cages across intermediate bulk container fleets without trapping viscous payload in corner folds. For instance, in January 2025 Greif, Inc. rolled out its GCUBE Flex Intermediate Bulk Container system featuring a sterile inner liner bag and a 2-inch butterfly valve that prevents product residue during container reuse [1].
Key Market Trends & Insights
- By liner format: Form-Fit IBC Liners commands 42.3% of 2026 liner format revenue because pre-welded gusseted bladders match the internal geometry of 1,000-liter collapsible totes and prevent corner air pockets.
- By material substrate: Linear Low-Density Polyethylene Films generates 30.4% of substrate turnover in 2026 as multi-ply LLDPE co-extrusions deliver high biaxial tear strength and low-extractable food compliance.
- By end-use sector: Food & Beverage represents 36.8% of 2026 end-use demand through sanitary bulk transport of dairy concentrates and liquid sucrose alongside culinary oils.
Regional Highlights
- Fastest-growing evaluated country: Australia leads national expansion with a 7.9% annual growth trajectory from 2026 to 2036 as drought-prone wineries and creameries eliminate caustic tank washing.
- By country: Spain records 6.8% growth on aseptic olive-oil and juice exports while Germany reaches 6.2% through closed-loop chemical tote pooling, ahead of Japan at 5.7% and the UK at 5.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the IBC Liner Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 7.9 billion |
| Estimated Market Size in 2026 | USD 8.4 billion |
| Projected Market Size by 2036 | USD 15.8 billion |
| CAGR, 2026 to 2036 | 6.5% |
| Added Revenue, 2026 to 2036 | USD 7.4 billion |
Chemical blenders across Germany and food-ingredient exporters in Australia and Spain are replacing single-trip steel drums with reusable outer totes fitted with disposable inner bladders. European bulk liquid shippers must satisfy mandatory reusable industrial packaging targets under Regulation (EU) 2025/40, for which the European Commission published implementation guidance in March 2026 favoring replaceable inner bulk liner bladders inside multi-trip outer containers [2]. Instead of shipping empty rigid containers back to centralized wash stations for solvent or steam cleaning, plant operators strip out the spent 1,000-liter film liner on site and reload the outer tote immediately. This closed-loop liner workflow cuts backhaul freight emissions alongside water consumption across transcontinental agricultural and latex trade lanes.
Bulk Liquid Fill Volume and Tote Fleet Turnaround Sizing
Table 2: Bulk Liquid Fill Volume and Liner Utilization Indicators for the IBC Liner Market (USD billion, million liners, and billion liters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 7.9 | 8.4 | 15.8 |
| Commercial IBC liners deployed (million units) | 148.0 to 162.0 | 157.0 to 172.0 | 288.0 to 315.0 |
| Bulk liquid volume transported in liners (billion liters) | 142.0 to 156.0 | 150.0 to 165.0 | 276.0 to 302.0 |
| Average converted system price per liner assembly (USD) | 48.80 to 53.40 | 48.80 to 53.50 | 50.20 to 54.90 |
Operational note: Liner deployment and liquid volume figures cover 500-to-1,500-liter form-fit and pillow liner assemblies with integrated dispense valves alongside paired octabin or collapsible tote cassette supports.
Container Fleet Economics & Sector Revenue Allocation
Industrial liquid fillers evaluate IBC liner assemblies on flex-crack resistance during long-distance ocean and rail vibration as well as oxygen barrier performance and residual heel drainage. Cube-shaped form-fit liners match the internal geometry of 1,000-liter rigid cages and collapsible plastic totes, which eliminates corner folds that trap viscous product and cause film rupture. For high-viscosity tomato paste and silicone emulsions, buyers pair foil-laminate liners with bag-in-box liquid systems and pneumatic follower plates that evacuate over 99.5% of the payload. Reducing residual product waste by even 8 liters per tote directly offsets the purchase price of the disposable liner.
Table 3: Per Capita and Industrial Liquid Handling Indicators for the IBC Liner Market (USD and liters per capita), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| IBC liner spend per capita (USD) | 0.96 | 1.01 | 1.77 |
| IBC liner spend per 1,000 people (USD) | 959.90 | 1,012.05 | 1,765.36 |
| Liner-transported bulk liquid per capita (liters) | 17.3 to 19.0 | 18.1 to 19.9 | 30.8 to 33.7 |
Table 4: Segment Revenue Concentration and Fleet Allocation for the IBC Liner Market (USD billion and percentages), 2026
| Metric | Value | Benchmark Context |
|---|---|---|
| Total IBC liner valuation, 2026 | USD 8.4 billion | Global baseline |
| Form-Fit IBC Liners format allocation, 2026 | USD 3.6 billion | 42.3% format share |
| Linear Low-Density Polyethylene Films allocation, 2026 | USD 2.6 billion | 30.4% substrate share |
| Food & Beverage end-use allocation, 2026 | USD 3.1 billion | 36.8% end-use share |
Analyst Perspective
"Replacing caustic tote washing with form-fit barrier liners lets bulk liquid shippers turn reusable IBC fleets around immediately while cutting wastewater discharge. Preventing flex-crack pinholes and valve-flange leaks during long-haul ocean transit remains the decisive qualification test for film converters."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the ibc liner market segmented?
The IBC liner market is segmented by liner format, material substrate, end-use sector, and region. Form-Fit IBC Liners captures 42.3% of liner format demand in 2026, while Linear Low-Density Polyethylene Films holds 30.4% of material substrate and Food & Beverage secures 36.8% of end-use revenue.
By liner format: Form-Fit (Cube-Shaped) IBC Liners, Pillow-Style IBC Liners, and Baffled & Antistatic Specialty IBC Liners.
By material substrate: Linear Low-Density Polyethylene (LLDPE & LDPE) Films, EVOH & Polyamide Barrier Co-Extrusions, Aluminum-Foil & Metallized Barrier Laminates, and Post-Consumer Recycled & Bio-Based Films.
By end-use sector: Food & Beverage, Industrial & Specialty Chemicals, Pharmaceuticals & Bioprocessing, and Paints, Inks & Lubricants.
Why Does Form-Fit IBC Liners Lead the IBC Liner Market by Liner Format?
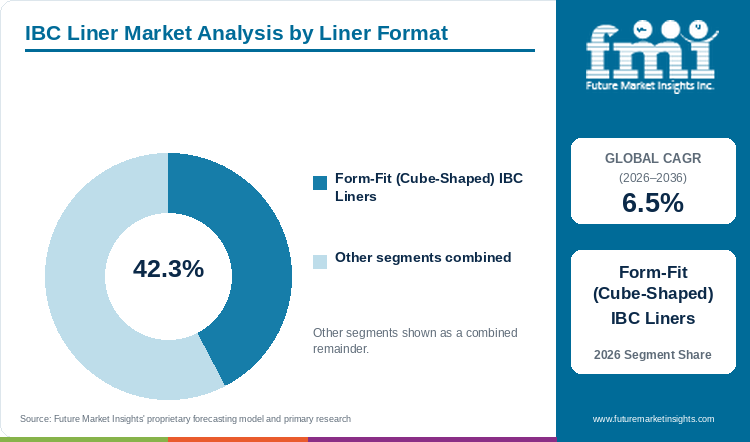
With an estimated 42.3% share in 2026, Form-Fit IBC Liners leads the liner format category through corner-free liquid evacuation.
Table 5: Liner Format Share for the IBC Liner Market (percentage share), 2026
| Liner Format | Share (2026) |
|---|---|
| Form-Fit IBC Liners | 42.3% |
| Other Segments Combined | 57.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Liner Format Leadership and Market Growth for the IBC Liner Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Leading Segment | Form-Fit IBC Liners |
Chemical distributors and liquid-sweetener refiners favor cube-shaped form-fit IBC liners because their pre-welded top and bottom gussets match the exact internal dimensions of 1,000-liter foldable plastic totes and corrugated octabins. Whereas flat two-dimensional pillow liners bunch up in the bottom corners of a rectangular tote and trap 5 to 12 liters of viscous liquid during pumping, a form-fit liner sits flush against the container walls without bridging or stress concentration on the heat welds. When supplied in pre-folded cardboard cassettes with integrated 2-inch bottom discharge valves, form-fit liners allow one operator to line reconditioned bulk containers in under 90 seconds without climbing onto the tote frame.
- Form-Fit IBC Liners generates 42.3% of liner format turnover in 2026 as fleet operators prioritize corner-free fitting alongside lower weld stress and near-zero residual liquid heel.
- In August 2025, SCHÜTZ GmbH & Co KGaA opened a 370,000-square-foot production facility in Kenosha in Wisconsin to expand North American capacity for intermediate bulk containers and form-fit liner-compatible systems [3].
What Makes Linear Low-Density Polyethylene Films Central to the Material Substrate Category?
Linear Low-Density Polyethylene Films is anticipated to contribute 30.4% of material substrate sales in 2026 due to flex-crack toughness.
Blown-film extruders rely on metallocene and octene-grade linear low-density polyethylene (LLDPE) blended with low-density polyethylene as the foundational structural and product-contact substrate for 1,000-liter bulk liquid liners. To survive continuous hydraulic sloshing during 30-day ocean voyages, IBC liners are constructed from two to four independent 75-to-100-micron LLDPE plies that slide against each other to dissipate wave energy without pinholing. In addition to its high elongation and dart-impact strength, virgin LLDPE contains no plasticizers or heavy metals, making it ideal for lining heavy-duty corrugated and folding board octabin sleeves and collapsible plastic totes.
- Linear Low-Density Polyethylene Films secures 30.4% of material substrate sales in 2026 because multi-ply LLDPE bladders deliver superior biaxial flex-crack resistance and clean food-contact compliance.
- In November 2025, Mondi plc launched an extended heavy-duty corrugated and solid board portfolio engineered to pair with polyethylene inner liners for bulk food and industrial transport [4].
Why Does Food & Beverage Anchor the End-Use Sector Category?
Food & Beverage is set to command 36.8% of end-use sector revenue in 2026 via aseptic bulk syrup transport.
Large-scale fruit processors and edible-oil refineries alongside dairy creameries represent the largest volume buyers of irradiated aseptic and sanitary food-grade IBC liners. Shipping 1,000 liters of tomato paste or mango puree inside a gamma-sterilized EVOH or metallized-film liner preserves flavor and prevents enzymatic browning over six-to-twelve-month ambient storage cycles without refrigeration. Compared with 200-liter steel drums that require four times as many connection cycles and leave higher residual product heels, bulk aseptic liquid filling liners cut labor hours and microbial spoilage risk.
- Food & Beverage holds 36.8% of end-use sector turnover in 2026 through aseptic and sanitary bulk transport of syrups and dairy concentrates alongside edible oils.
- In April 2025, Amcor plc completed its all-stock combination with Berry Global Group, Inc. to unite two major global producers of co-extruded food-grade barrier films and bulk liquid liners [5].
What are the drivers, restraints, and opportunities in the ibc liner market?
Mandatory container-reuse rules and washout cost savings propel liner adoption, whereas flex-crack pinholing and antistatic chemical limits restrain use while recyclable mono-polyethylene barrier structures create growth opportunities.
- Driver: Rising industrial wastewater treatment tariffs and circular-packaging reuse mandates are pushing chemical and food shippers to line reusable totes instead of washing rigid containers or buying single-trip drums.
- Restraint: Dynamic hydraulic surging during long-haul ocean and rail transit induces flex-crack pinholes in multi-layer barrier films, while flammable solvents require specialized antistatic grounding certifications.
- Opportunity: Commercializing ethylene-vinyl-alcohol-compatible mono-polyethylene liners and automated bottom-evacuation follower systems unlocks high-viscosity food and specialty chemical contracts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Industrial chemical plants and food-ingredient processors are replacing 200-liter drum fleets and unlined rigid totes with lined intermediate bulk containers to eliminate hazardous washwater effluent and speed up fleet turnaround. Cleaning a single unlined 1,000-liter tote contaminated with acrylic emulsion or edible oil consumes 150 to 300 liters of heated water and caustic detergent, whereas stripping out a 3-kilogram polyethylene liner takes less than five minutes. In October 2025, Eurostat reported in its packaging waste statistics release that European Union packaging waste generation reached 79.7 million tonnes, reinforcing regulatory pressure under the EU Packaging and Packaging Waste Regulation to maximize multi-trip outer container reuse via replaceable inner liners [6]. As a result, bulk liquid distributors are standardizing on collapsible totes and rigid industrial drums fitted with pre-sterilized form-fit bladders.
Risk Assessment of the IBC Liner Market: Operational and Supply Friction
Mechanical stress from harmonic wave action during sea freight and rail shunting subjects 1,000-liter liquid liners to severe biaxial flex fatigue at the corner welds and gland seals. Standard metallized polyester or foil-laminated liners can develop microscopic flex-crack pinholes when shipped without internal surge baffles, allowing oxygen ingress that spoils wine must or moisture-curing urethane prepolymers. Furthermore, filling low-flashpoint solvents or combustible powders inside plastic-lined totes creates electrostatic spark hazards unless the film incorporates certified dissipative polymers compliant with IEC 61340-4-4 and UN dangerous goods rules. Full-year 2025 financial disclosures released by Smurfit Westrock plc in February 2026 noted that volatile industrial energy and raw material costs continue to pressure heavy-duty bulk packaging margins across European manufacturing corridors [7].
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Film converters that replace non-recyclable polyamide and aluminum-foil barrier plies with recycle-ready polyethylene-EVOH co-extrusions are winning multi-year contracts from multinational food and personal care groups. Integrating 3-inch sanitary camlock fitments and internal anti-slosh baffles directly into cube-shaped liners allows processors to pump viscous chocolate liquor and silicone sealants with less than 0.3% residual heel loss. In September 2026, Mondi plc announced a showcase of its high-barrier paper and recyclable mono-material industrial bag structures for PACK EXPO International 2026 to target bulk food and industrial shippers [8]. Pairing these high-recovery liquid packaging bags with automated cassette-loading frames reduces operator lifting injuries and accelerates filling-line throughput.
IBC Liner Market by Country (2026 to 2036)
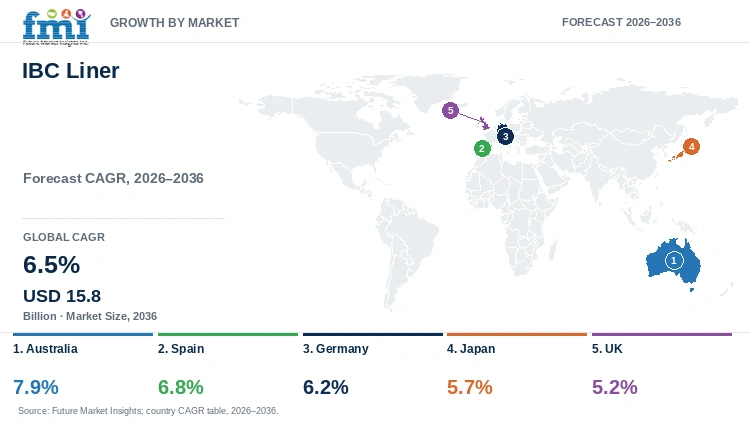
Five profiled IBC liner economies diverge between 2026 and 2036, led by Australia at 7.9% and Spain at 6.8% while Germany records 6.2% above Japan at 5.7% and the UK at 5.2%. Variations in national growth stem from bulk wine and olive-oil export campaigns alongside closed-loop chemical tote pooling density and local trade-waste water tariffs.
Table 7: Country CAGR and Primary Growth Levers for the IBC Liner Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Australia | 7.9% | Bulk wine, dairy concentrate, and mining reagent logistics combined with drought-driven washwater restrictions |
| Spain | 6.8% | Export-scale bulk olive oil, citrus juice concentrate, and tomato paste aseptic liner shipments |
| Germany | 6.2% | Specialty chemical, automotive coating, and closed-loop composite IBC pooling under PPWR reuse rules |
| Japan | 5.7% | High-purity electronic chemical, soy sauce, and liquid seasoning transport in space-saving foldable totes |
| UK | 5.2% | Foodservice syrup, dairy, and contract chemical blending under Plastic Packaging Tax recycled-content rules |
Source: Future Market Insights analysis
Australia IBC Liner Market Outlook (2026 to 2036)
Chronic water scarcity across Murray-Darling Basin agricultural processing zones and steep municipal trade-waste tariffs make caustic washing of rigid bulk tanks economically unviable for Australian wineries and dairy creameries. National Accounts figures published by the Australian Bureau of Statistics in September 2026 for the June 2026 quarter confirmed that agricultural and food-beverage export supply chains remained key contributors to national trade activity [9]. Driven by this shift toward waterless container turnaround, Australia's IBC liner market will expand at a leading 7.9% compound annual growth rate from 2026 to 2036. While high-barrier EVOH wine and whey-protein liners cut container turnaround times across South Australia and Victoria, vast interstate trucking distances inflate empty tote repositioning costs and drive demand for collapsible lined containers.
Key takeaway: In Australia, strict industrial washwater tariffs and bulk wine and dairy export logistics drive rapid adoption of high-barrier EVOH tote liners.
Spain IBC Liner Market Outlook (2026 to 2036)
Export-scale Mediterranean olive-oil mills and tomato-paste canneries across Andalusia and Extremadura anchor Spain's position as Europe's largest seasonal buyer of aseptic bulk liquid liners. Provisional Industrial Production Index data issued by Spain's National Statistics Institute (INE) in September 2026 recorded a 2.3% year-on-year output gain for July 2026 backed by intermediate goods and food processing [10]. This agricultural export volume propels Spanish IBC liner revenues along an anticipated 6.8% annual growth trajectory between 2026 and 2036. On the other hand, intense harvest seasonality between October and February creates acute lead-time bottlenecks for gamma-irradiated metallized liners fitted with 2-inch steam-sterilizable valves and forces Valencia converters to hold buffer stock.
Key takeaway: In Spain, concentrated olive-oil and aseptic tomato-paste export campaigns require localized cleanroom buffer stocks of irradiated IBC liners.
Germany IBC Liner Market Outlook (2026 to 2036)
Dense closed-loop pooling of steel-caged composite IBCs across Rhine-Ruhr chemical parks and automotive coatings plants shapes Germany's demand around technical antistatic and high-barrier form-fit bladders. Manufacturing order statistics from Germany's Federal Statistical Office (Destatis) in September 2026 showed factory new orders rising 2.5% month-on-month in July 2026 as chemical and industrial machinery activity stabilized [11]. Anchored by these closed-loop industrial fleets, German IBC liner turnover is forecast to grow at 6.2% annually over the decade through 2036. However, rigorous federal dangerous-goods transport rules under BAM and ADR frameworks lengthen qualification timelines for new dissipative LDPE/PA liner structures, favoring certified domestic extruders that guarantee zero solvent permeation.
Key takeaway: In Germany, closed-loop chemical tote pooling under strict ADR dangerous-goods and PPWR reuse rules sustains demand for certified antistatic form-fit liners.
Japan IBC Liner Market Outlook (2026 to 2036)
Acute truck-driver shortages under statutory overtime caps and high urban warehouse land prices compel Japanese soy-sauce brewers and electronic-chemical plants to replace 200-liter steel drums with foldable lined totes. Revised August 2026 industrial production tables from Japan's Ministry of Economy, Trade and Industry documented ongoing automation and logistics efficiency upgrades across domestic chemical and food factories [12]. These industrial container-standardization programs across Tokyo and Nagoya position Japanese IBC liner sales for 5.7% yearly expansion through the 2036 horizon. Nonetheless, semiconductor photoresist and culinary buyers enforce near-zero extractable and particle-count thresholds on inner polyethylene films, requiring converters to extrude ultra-pure additive-free LLDPE bladders inside ISO-classified cleanrooms.
Key takeaway: In Japan, freight labor constraints and ultra-clean semiconductor and culinary liquid standards drive procurement of cassette-loaded foldable tote liners.
UK IBC Liner Market Outlook (2026 to 2036)
Contract beverage-syrup blending and outsourced personal-care surfactant tolling across the Midlands and Northern England make the United Kingdom a steady replacement market for 1,000-liter pillow and form-fit liners. According to the October 2026 Index of Production bulletin from the UK Office for National Statistics, domestic manufacturing output edged higher in August 2026 as food and chemical plants stabilized operating schedules [13]. Against this steady processing baseline, British IBC liner demand progresses at a 5.2% annual rate over the decade to 2036. Nevertheless, the UK Plastic Packaging Tax penalizes packaging components containing less than 30% recycled plastic, pushing British converters to pair virgin food-contact inner plies with chemically recycled mass-balance polyethylene outer layers.
Key takeaway: In the UK, foodservice syrup and chemical tolling demand alongside Plastic Packaging Tax thresholds accelerates mass-balance recycled polyethylene liner adoption.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the ibc liner market?
Sealed Air Corporation, Amcor plc, Berry Global Group, Inc., SIG Group AG, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Greif, Inc., and SCHÜTZ GmbH & Co KGaA are the notable companies active in this market.
Competitive positioning in the IBC liner sector depends on wide-web multi-layer blown-film co-extrusion and automated gland-welding precision alongside integration with reusable outer totes and corrugated octabins. Liquid-packaging and barrier-film leaders including Sealed Air Corporation and SIG Group AG together with Amcor plc (combined with Berry Global Group, Inc.) manufacture high-strength LLDPE and metallized aseptic bladders. Fiber and flexible converting groups such as Mondi plc and Huhtamaki Oyj alongside Sonoco Products Company supply heavy-duty corrugated octabins and barrier laminate structures across container liner assemblies. Meanwhile, industrial container leaders Greif, Inc. and SCHÜTZ GmbH & Co KGaA integrate certified inner liners directly into their global composite IBC and collapsible tote fleets.
- Established Market Leaders: Sealed Air Corporation and Amcor plc together with SIG Group AG supply co-extruded EVOH/LLDPE bulk liquid liners and aseptic dispense fitments for automated bag-in-tote filling lines.
- Specialized Manufacturers: Berry Global Group, Inc. and Huhtamaki Oyj alongside Mondi plc provide multi-ply polyethylene form-fit bladders and heavy-duty corrugated octabin liner sleeves.
- Regional and Emerging Players: Sonoco Products Company and Greif, Inc. together with SCHÜTZ GmbH & Co KGaA deliver industrial paperboard bulk sleeves and lined GCUBE Flex composite IBCs alongside antistatic liner-fitted container systems.
Competitive Benchmarking: IBC Liner Market
Table 8: Competitive Benchmarking for the IBC Liner Market (qualitative capability ratings), 2026
| Company | Product Breadth | Geographic Reach | Quality Certification | Innovation |
|---|---|---|---|---|
| Sealed Air Corporation | High | High | High | High |
| Amcor plc | High | High | High | High |
| Berry Global Group, Inc. | High | High | High | Medium |
| SIG Group AG | High | High | High | High |
| Mondi plc | Medium | High | High | High |
| Huhtamaki Oyj | Medium | High | High | Medium |
| Sonoco Products Company | High | Medium | High | Medium |
| Greif, Inc. | High | High | High | High |
Scoring basis: Capability evaluations assign High for Product Breadth when a supplier offers form-fit and baffled liner geometries alongside dispense fitments or paired octabin and composite outer totes, whereas Medium reflects specialization in specific film or sleeve tiers. Blown-film extrusion and container depot footprints across the Americas and Europe as well as Asia-Pacific determine the regional reach rating. Quality Certification reflects documented FDA/EU food-contact and UN dangerous-goods testing alongside woven bulk bags, while Innovation assesses recycle-ready EVOH films and low-heel evacuation designs.
Key Developments in the IBC Liner Market
- In October 2026, Mondi plc published its Q3 2026 trading update highlighting commercial ramp-up of recently completed kraft paper and heavy-duty corrugated bulk packaging capacity investments across Europe [14].
- In November 2025, Sealed Air Corporation reported third-quarter 2025 financial results highlighting sustained operational execution across its Cryovac food-barrier film and Liquibox bulk liquid packaging platforms [15].
- In March 2026, SIG Group AG reported a 24% sales expansion in aluminum-layer-free aseptic barrier packaging structures during 2025, reinforcing its recycle-ready barrier film and bulk liquid dispensing platforms [16].
Key Players in the IBC Liner Market
Established Market Leaders
- Sealed Air Corporation
- Amcor plc
- SIG Group AG
Specialized Manufacturers
- Berry Global Group, Inc.
- Huhtamaki Oyj
- Mondi plc
Regional and Emerging Players
- Sonoco Products Company
- Greif, Inc.
- SCHÜTZ GmbH & Co KGaA
IBC Liner Market - Report Scope
Table 9: Report Scope for the IBC Liner Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Liner Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes global supplier revenue from flexible Intermediate Bulk Container (IBC) inner liners, form-fit and pillow bladders, baffled and antistatic bulk liners, integrated dispense valves/fitments, and paired paperboard octabin or collapsible tote liner cassettes used for bulk liquid, paste, and granular transport. Scope & Format Note: Market valuation captures the complete IBC liner containment assembly across Form-Fit IBC Liners (42.3%), Pillow-Style IBC Liners, and Baffled & Antistatic Specialty IBC Liners fitted inside reusable composite cages, collapsible plastic/metal totes, and heavy-duty corrugated octabins. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Australia, Spain, Germany, Japan, UK, and additional countries in the full report |
| Key Companies Covered | Sealed Air Corporation, Amcor plc, Berry Global Group, Inc., SIG Group AG, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Greif, Inc., SCHÜTZ GmbH & Co KGaA |
| Forecast Period | 2026 to 2036 (Base Year: 2025) |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
IBC Liner Market - Research Methodology
Table 10: Research Methodology for the IBC Liner Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with blown-film extruders, IBC liner converters, rigid tote and octabin manufacturers, chemical fleet pooling operators, and bulk food processors to validate liner replacement ratios, valve specifications, and pricing. |
| Secondary Research | Secondary research incorporated corporate annual reports (10-K filings), U.S. DOT PHMSA 49 CFR and EU PPWR regulatory texts, Eurostat packaging waste databases, national industrial production bulletins, and ISTA/ASTM bulk container test standards. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period reconciled global active IBC tote fleet counts and one-way paperboard octabin shipments against single-trip liner consumption per container turn. |
| Data Triangulation and Validation | Estimates were cross-validated against linear low-density polyethylene (LLDPE), EVOH barrier resin, and heavy-duty containerboard consumption across bulk liquid food, chemical, and pharmaceutical logistics. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's bulk industrial packaging econometric model, calibrating evaluated national growth rates against the 6.5% global baseline through verified bulk liquid food/chemical export volumes, industrial washwater cost indices, and statutory container-reuse mandates. |
| Operational Benchmark Traceability | Operational benchmarks (commercial IBC liners deployed, bulk liquid volume transported in liners, and average converted system price per liner assembly) represent modeled estimates synthesized from Eurostat waste registries, U.S. DOT 49 CFR container standards, national statistical agencies (ABS, INE Spain, Destatis, METI, ONS), and commercial converter disclosures. |
IBC Liner Market by Segments
IBC Liner Market segmented by Liner Format:
- Form-Fit (Cube-Shaped) IBC Liners
- Pillow-Style IBC Liners
- Baffled & Antistatic Specialty IBC Liners
IBC Liner Market segmented by Material Substrate:
- Linear Low-Density Polyethylene (LLDPE & LDPE) Films
- EVOH & Polyamide Barrier Co-Extrusions
- Aluminum-Foil & Metallized Barrier Laminates
- Post-Consumer Recycled & Bio-Based Films
IBC Liner Market segmented by End-Use Sector:
- Food & Beverage
- Industrial & Specialty Chemicals
- Pharmaceuticals & Bioprocessing
- Paints, Inks & Lubricants
IBC Liner Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Greif, Inc. (2025, January 09). Featured Innovation: GCUBE Flex IBC. Greif Industrial Packaging.
- [2] European Commission. (2026, March 29). Commission publishes guidance to support implementation of new packaging rules. European Commission Press Corner.
- [3] SCHÜTZ GmbH & Co KGaA. (2025, August 18). SCHÜTZ opens new production facility in Kenosha, Wisconsin. SCHÜTZ Industrial Packaging News.
- [4] Mondi plc. (2025, November 18). Mondi launches extended corrugated and solid board portfolio for the food packaging industry. Mondi Group News and Insight.
- [5] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global. Amcor Media News.
- [6] Eurostat. (2025, October 10). Packaging waste statistics. European Commission.
- [7] Smurfit Westrock plc. (2026, February 11). Smurfit Westrock Reports Fourth Quarter and Full Year 2025 Results. Smurfit Westrock Investor Relations.
- [8] Mondi plc. (2026, September 24). Mondi highlights sustainable packaging innovations at PACK EXPO International 2026. Mondi Group News and Insight.
- [9] Australian Bureau of Statistics. (2026, September 02). Australian National Accounts: National Income, Expenditure and Product, June 2026. Australian Bureau of Statistics.
- [10] Instituto Nacional de Estadística (INE). (2026, September 10). Industrial Production Index (IPI). July 2026. Provisional data. INE Spain.
- [11] Federal Statistical Office (Destatis). (2026, September 04). New orders in manufacturing in July 2026: +2.5% on the previous month. Statistisches Bundesamt.
- [12] Ministry of Economy, Trade and Industry. (2026, August 09). Indices of Industrial Production for August, 2026 (Revised Report). Ministry of Economy, Trade and Industry.
- [13] Office for National Statistics. (2026, October 15). Index of Production, UK: August 2026. Office for National Statistics.
- [14] Mondi plc. (2026, October 15). Q3 Trading Update 2026. Mondi Group News and Insight.
- [15] Sealed Air Corporation. (2025, November 04). Sealed Air Reports Q3 2025 Financial Results. Sealed Air Media Center.
- [16] SIG Group AG. (2026, March 17). 24% sales growth: SIG's alu-layer-free aseptic cartons gained widespread adoption in 2025. SIG Media Releases.
- [17] SIG Group AG. (2025, July 08). SIG announces expansion of its state-of-the-art carton packaging plant in Queretaro, Mexico. SIG Media Releases.
- [18] Huhtamaki Oyj. (2026, October 15). Interim Report Q1 2026. Huhtamaki Investors.
- [19] Sonoco Products Company. (2026, February 17). Sonoco Provides Investors with Strategy and Financial Update. Sonoco Investor News.
- [20] Amcor plc. (2025, October 02). Amcor to showcase responsible and patient-centric packaging. Amcor Media News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ibc liner market in 2026 and what is forecast for 2036?
- Which industry factors support demand for ibc liner products?
- Why does Form-Fit IBC Liners lead the liner format category?
- Why does Linear Low-Density Polyethylene Films lead the material substrate category globally?
- How do growth rates differ across Australia, Spain, Germany, and Japan?
- Which leading companies supply ibc liner products today?
- What limits adoption or supplier switching in the ibc liner market?
- What should buyers evaluate before purchasing ibc liner products?
Frequently Asked Questions
How big is the ibc liner market in 2026, and what is forecast for 2036?
Bulk IBC liner demand advances from USD 7.9 billion in 2025 to USD 8.4 billion in 2026 and is forecast to hit USD 15.8 billion in 2036, representing USD 7.4 billion in ten-year expansion.
What CAGR is forecast for the IBC Liner Market through 2036?
Global IBC liner sales advance at a 6.5% annual pace through 2036 as bulk food and chemical processors replace caustic tote washing and single-trip steel drums with disposable inner bladders.
Which liner format holds a notable ibc liner demand share in 2026?
Cube-shaped gusseted bladders that eliminate corner folds and maximize liquid evacuation inside 1,000-liter totes give Form-Fit IBC Liners 42.3% of 2026 format volume.
Which material substrate segment holds a notable ibc liner share in 2026?
Multi-ply LLDPE co-extrusions engineered to resist biaxial flex-crack fatigue during sea and rail freight place Linear Low-Density Polyethylene Films at 30.4% of 2026 substrate demand.
Which country has a notable ibc liner expansion outlook during the forecast period?
Australia posts the fastest growth among evaluated countries at a 7.9% CAGR through 2036 owing to bulk wine and dairy concentrate export logistics paired with strict industrial washwater limits.
Which companies are active in the IBC Liner Market during 2026?
Prominent suppliers operating in the IBC liner sector include Sealed Air Corporation, Amcor plc, Berry Global Group, Inc., SIG Group AG, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Greif, Inc., and SCHÜTZ GmbH & Co KGaA. These companies engineer co-extruded EVOH barrier films and aseptic dispense valves alongside heavy-duty lined tote and octabin systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Liner Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Liner Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Liner Format, 2026 to 2036
- Form-Fit (Cube-Shaped) IBC Liners
- Pillow-Style IBC Liners
- Baffled & Antistatic Specialty IBC Liners
- Y-o-Y Growth Trend Analysis By Liner Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Liner Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Linear Low-Density Polyethylene (LLDPE & LDPE) Films
- EVOH & Polyamide Barrier Co-Extrusions
- Aluminum-Foil & Metallized Barrier Laminates
- Post-Consumer Recycled & Bio-Based Films
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Industrial & Specialty Chemicals
- Pharmaceuticals & Bioprocessing
- Paints, Inks & Lubricants
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Spain
- Italy
- Benelux
- Nordics
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Liner Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Liner Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Liner Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Sealed Air Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Amcor plc
- Berry Global Group, Inc.
- SIG Group AG
- Mondi plc
- Huhtamaki Oyj
- Sonoco Products Company
- Greif, Inc.
- SCHÜTZ GmbH & Co KGaA
- Sealed Air Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


