

- Market Size (2026)
- USD 5.8 Bn
- Forecast (2036)
- USD 10.2 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Liquid Egg Market in 2026?
Sales in the liquid egg market are projected to grow at 5.8% CAGR, with the market size rising from USD 5.5 Billion in 2025 to USD 5.8 Billion in 2026 and reaching USD 10.2 Billion by 2036.
Cracking raw shell eggs by hand on high-speed bakery and commissary lines creates cross-contamination hazards and slows down batch preparation. In January 2025, USDA poultry processing reports confirmed that commercial breaking plants cracked over 72 million cases of shell eggs into liquid products to meet industrial demand [1]. Global liquid egg sales rise from USD 5.5 Billion in 2025 to USD 5.8 Billion in 2026 and are projected to reach USD 10.2 Billion by 2036, expanding at a 5.8% CAGR from 2026 to 2036, as per FMI. Liquid whole egg holds 52.4% share in 2026, though recurring avian flu losses still tighten processor margins.
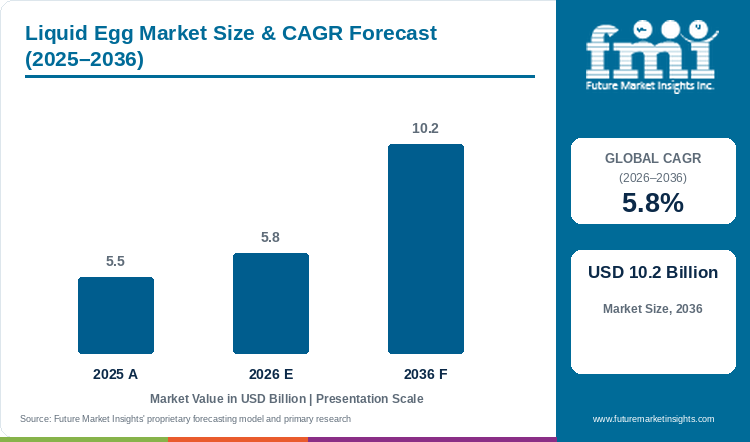
Key Market Trends & Insights
- By product type: Liquid whole egg led the market with a share of 52.4% in 2026, as pre-blended yolk and albumen solids deliver steady aeration and binding in commercial baking.
- By source / egg type: Cage-free and free-range accounted for 44.6% of demand in 2026, reflecting multi-year animal welfare sourcing pledges across restaurant and grocery chains.
- By end-use / application: Industrial bakery and confectionery represented 46.2% of revenue in 2026, supported by continuous dough mixers that require pumpable liquid dosing.
- By packaging format: With a 56.8% share in 2026, bulk tankers and bag-in-box led the category by cutting per-liter packaging waste on high-volume factory lines.
Regional Highlights
- Fastest-growing evaluated country: USA, at 7.1% CAGR from 2026 to 2036.
- By country: The UK (6.5%), Canada (6.0%), and South Korea (5.6%) follow, while Japan (5.1%) and Germany (4.6%) record more moderate expansion rates.
Market Size & Forecast
Table 1: Market Size and Forecast for the Liquid Egg Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.5 Billion |
| Estimated Market Size in 2026 | USD 5.8 Billion |
| Projected Market Size by 2036 | USD 10.2 Billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 4.4 Billion |
Hospitality chains, hospitals, and nursing homes across North America and Western Europe have phased out raw shell egg handling to prevent foodborne outbreaks and cut kitchen labor hours. In February 2025, U.S. Food and Drug Administration food code updates required healthcare and senior dining kitchens to use pasteurized egg products in all soft-cooked and batch-mixed recipes [2]. While U.S. breaking plants focus on high-speed tubular pasteurization for quick-service breakfast chains, European processors must also segregate KAT- and Lion-certified aviary flocks. Buyers use chilled aseptic cartons for daily cooking and reserve spray-dried egg powder for ambient dry premix lines where refrigerated storage is unavailable.
Shell Egg Breaking and Liquid Processing Capacity Sizing
Table 2: Shell Egg Breaking and Liquid Processing Capacity Sizing for the Liquid Egg Market (USD Billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 5.5 | 5.8 | 10.2 |
| Shell eggs cracked industrially (billion units) | 88.0 to 94.0 | 92.5 to 98.5 | 160.0 to 172.0 |
| Liquid egg volume produced (million metric tons) | 4.4 to 4.7 | 4.6 to 4.9 | 8.0 to 8.6 |
| Average wholesale realization per metric ton (USD) | 1,210 to 1,280 | 1,230 to 1,305 | 1,240 to 1,320 |
Yield reference: Commercial breaking facilities average 50 grams of liquid egg yield per cracked shell egg across whole, white, and yolk separation lines.
Per Capita Egg Consumption and Industrial Processing Indicators
Quick-service breakfast chains and wholesale pastry plants rely on insulated liquid egg storage tanks to keep batter viscosity uniform across continuous shifts. Refrigerated tanker fleets link rural layer complexes directly to urban mixing plants under strict 4-degree-Celsius temperature logging. Growing adoption of aseptic liquid packaging also lets processors ship pasteurized egg blends over longer regional routes without chemical preservatives.
Table 3: Per Capita and Industrial Spending Indicators for the Liquid Egg Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.67 | 0.70 | 1.14 |
| Spend per 1,000 people (USD) | 668.3 | 698.8 | 1,139.7 |
| Commercial industrial bakery annual liquid egg spend (USD thousand) | 145.0 to 160.0 | 152.0 to 168.0 | 245.0 to 270.0 |
Table 4: Commercial Kitchen & Industrial Bakery Sizing Indicators for the Liquid Egg Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 5.8 Billion | 2026 baseline |
| Commercial industrial bakeries worldwide | 38.5 thousand | 2024 industrial census |
| Average annual revenue per industrial bakery | USD 150.6 Thousand | Facility average |
| Industrial bakery application revenue, 2026 | USD 2.7 Billion | 46.2% share |
Analyst Perspective
"Egg processors that pair inline aseptic packaging with contracted cage-free aviary flocks are winning multi-year supply tenders from wholesale bakeries. However, seasonal avian influenza culls and strict 4-degree-Celsius transit rules still require food manufacturers to qualify secondary breaking plants."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the liquid egg market segmented?
The liquid egg market is segmented by product type, source / egg type, end-use / application, and packaging format. In 2026, Liquid Whole Egg is projected at 52.4%, cage-free / free-range at 44.6%, industrial bakery & confectionery at 46.2%, and bulk tankers & bag-in-box at 56.8%.
By product type: Liquid whole egg, liquid egg white, and liquid egg yolk.
By source / egg type: Cage-free and free-range, conventional caged, and certified organic.
By end-use / application: Industrial bakery and confectionery, food service and commercial kitchens, processed food and ready meals, and direct retail consumption.
By packaging format: Bulk tankers and bag-in-box, pure-pak and gable top cartons, and PET bottles and pouches.
Why does Liquid Whole Egg lead the product type category?
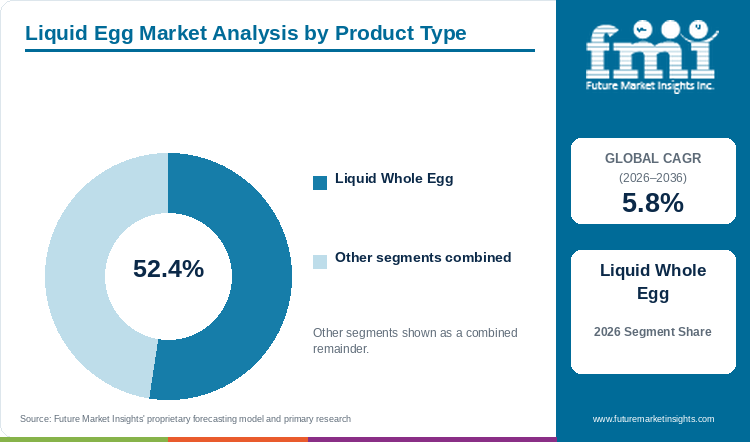
Liquid whole egg is expected to account for 52.4% of product type revenue in 2026, supported by balanced baking emulsification.
Table 5: Product Type Share for the Liquid Egg Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Liquid Whole Egg | 52.4% |
| Other Segments Combined | 47.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Liquid Egg Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Liquid Whole Egg |
Sponge cakes, brioche doughs, and egg noodles depend on the natural balance of yolk lipids and albumen proteins found in liquid whole egg for golden crust color and crumb lift. Homogenized liquid whole egg meters directly into slurry mixers alongside bakery ingredients without shell fragments or manual cracking delays. Separated whites and yolks remain essential for specialized meringues or mayonnaise, yet whole egg covers both emulsification and heat-set coagulation across everyday baking and institutional breakfast menus. Even so, plate heat exchangers must be held within narrow pasteurization windows so the protein does not coagulate inside the tubes.
- Liquid whole egg is projected to account for 52.4% of product type revenue in 2026, supported by broad formulation use across commercial bakeries, pasta plants, and breakfast kitchens.
- In March 2025, Food and Agriculture Organization global production updates confirmed that liquid whole egg accounted for more than half of commercial egg breaking throughput worldwide [3].
What makes Cage-Free & Free-Range central to the source egg type category?
Cage-free and free-range is estimated to represent 44.6% of source egg type demand in 2026, reflecting corporate welfare commitments.
Multinational restaurant groups, hotel caterers, and grocery chains are enforcing 2025 and 2026 animal-welfare procurement pledges, which has shifted contract volume toward cage-free and free-range liquid egg. Statutory bans on conventional battery cages in Germany, the UK, California, and Michigan have also required layer farms to rebuild barns around multi-tier aviaries. Food brands combining humane sourcing labels with specialty egg formulations are locking in multi-year supermarket shelf space. Higher feed conversion ratios and aviary capital costs still keep cage-free liquid prices above conventional grades, slowing switching among budget institutional kitchens.
- Cage-free and free-range is estimated to hold 44.6% of source egg type demand in 2026, reflecting binding corporate animal welfare pledges and statutory layer housing laws.
- In April 2025, European Food Safety Authority welfare assessments reported that over 65% of commercial laying hens across the European Union operated in barn, free-range, or organic housing [4].
What keeps Industrial Bakery & Confectionery ahead by end-use application?
Industrial bakery and confectionery is projected to capture 46.2% of end-use application sales in 2026, driven by continuous dough mixing.
Continuous tunnel ovens producing sweet biscuits, waffles, muffins, and laminated pastries cannot pause for manual shell cracking, making industrial bakeries the largest buyers of pasteurized liquid egg. Automated liquid metering keeps batter density steady from shift to shift while eliminating wet eggshell waste from the bakery floor. Some snack formulators test plant-based egg replacement ingredients when avian flu spikes shell egg prices, but natural liquid egg remains hard to replace where a recipe needs simultaneous whipping lift and lipid emulsification. Consequently, wholesale bakeries sign annual off-take contracts with regional breaking plants.
- Industrial bakery and confectionery is forecast to capture 46.2% of end-use application sales in 2026, driven by automated batch dosing and functional emulsification needs.
- In May 2025, Germany's Federal Statistical Office (Destatis) reported that commercial bread and pastry manufacturers consumed more than 42% of domestically processed liquid egg volume [5].
How do Bulk Tankers & Bag-in-Box anchor the packaging format category?
With an estimated 56.8% share in 2026, bulk tankers and bag-in-box lead packaging format demand, underpinned by automated pump dosing.
Receiving pasteurized egg in 20-ton insulated road tankers or 1,000-liter aseptic bag-in-box totes allows large food plants to pump liquid directly into closed-loop mixing manifolds. Compared with 1-kilogram gable-top cartons that require manual opening and carton disposal, bulk delivery cuts packaging cost per liter across processed egg products. Collapsible bag-in-box liners also prevent air contact as the tote empties, protecting yolk lipids from oxidation over multi-day production runs. Adopting bulk tanker delivery still requires the buyer to install jacketed chilled silos and automated clean-in-place (CIP) sanitation lines.
- Bulk tankers and bag-in-box are anticipated to hold 56.8% of packaging format demand in 2026, underpinned by lower freight cost per liter and closed-loop sanitary pumping.
- In June 2026, Post Holdings reported that Michael Foods expanded its refrigerated tanker and bulk tote logistics across Midwest food manufacturing accounts [6].
What are the drivers, restraints, and opportunities in the liquid egg market?
In the Liquid Egg Market, commercial kitchen automation and pasteurization rules support demand, avian influenza flock losses and cold-chain costs constrain supply, and extended-shelf-life aseptic processing creates new growth opportunities through 2036.
- Driver: Commercial bakery automation and strict foodservice Salmonella controls will continue to shift buyers from raw shell eggs to pasteurized liquid formats through 2036.
- Restraint: Recurring highly pathogenic avian influenza outbreaks and refrigerated transport costs will continue to trigger raw egg price swings and tighten breaking margins through 2036.
- Opportunity: Ultra-pasteurized aseptic packaging and fractionated albumen ingredients are expected to unlock longer export routes and sports nutrition contracts through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
In August 2026, the USDA Food Safety and Inspection Service updated its Salmonella lethality verification rules for pasteurized egg plants, reinforcing strict microbiological testing across breaking lines [7]. Stricter pathogen audits and rising kitchen wages are pushing commercial caterers and wholesale bakeries to replace shell eggs with pasteurized liquid shipments. FMI data suggests that industrial food makers also procure salted yolks and egg yolk lecithin to stabilize emulsified sauces and salad dressings on high-shear lines. Before a breaking plant wins a national supply contract, it must provide continuous pasteurization temperature records and third-party hazard audit certificates.
Risk Assessment of the Liquid Egg Market: Operational and Formulation Friction
Outbreaks of highly pathogenic avian influenza (HPAI) can wipe out millions of laying hens in a single quarter, creating immediate raw egg shortages for commercial breaking plants. In May 2025, the World Organisation for Animal Health reported that seasonal avian influenza outbreaks caused the loss of over 48 million commercial poultry birds across reporting countries [8]. Whenever layer flocks are depopulated, spot shell egg prices surge and breaking plants must ration non-contracted liquid volume. Pasteurized liquid egg also requires uninterrupted refrigeration below 4 degrees Celsius, meaning any chiller breakdown during summer road transit ruins the load.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Standard pasteurized liquid egg carries a chilled shelf life of only 14 to 21 days, which restricts long-distance shipping and export sales. In February 2026, Bouwhuis Enthoven introduced an enzymatically modified, heat-stable liquid egg yolk range engineered for industrial bakery glazes and dressings [9]. Combining gentle ultra-pasteurization with sterile bag-in-box filling extends refrigerated shelf life beyond 75 days without chemical preservatives. At the same time, fractionating high-purity liquid albumen alongside egg white protein powder opens high-margin contracts with ready-to-drink sports nutrition brands that need clean whipping and gelation performance.
Liquid Egg Market by Country (2026 to 2036)
Quick-service breakfast automation and state cage-free laws propel the USA to a 7.1% CAGR from 2026 to 2036, whereas mature German bakery channels expand at a 4.6% CAGR. In the UK (6.5%), Canada (6.0%), South Korea (5.6%), and Japan (5.1%), liquid egg adoption tracks how breaking plants manage avian flu biosecurity, farm quota rules, and cold-chain utility costs.
Table 7: Country CAGR and Primary Growth Levers for the Liquid Egg Market (CAGR percentage and operational drivers), 2026 to 2036
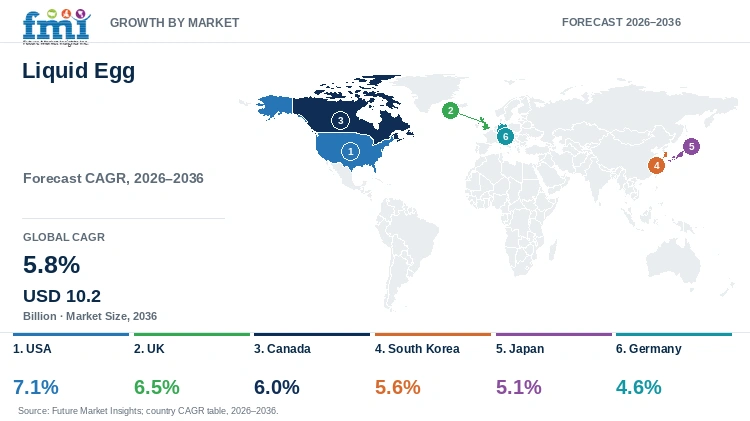
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 7.1% | QSR breakfast menu automation and statewide cage-free egg confinement legislation |
| UK | 6.5% | Lion Code food safety standards and corporate bakery transition to pasteurized liquid |
| Canada | 6.0% | Supply-managed poultry quota stability and provincial industrial bakery expansion |
| South Korea | 5.6% | Commercial bakery franchise growth and food service kitchen labor reduction protocols |
| Japan | 5.1% | High per-capita egg consumption and advanced convenience store ready-meal manufacturing |
| Germany | 4.6% | KAT animal welfare certifications and industrial confectionery ingredient standardization |
Source: Future Market Insights analysis
USA Liquid Egg Market Outlook (2026 to 2036)
Quick-service breakfast sandwich programs and industrial pastry plants make the United States the largest volume buyer of pasteurized liquid egg. By 2036, the USA market is projected to grow at a 7.1% CAGR, supported by state-level cage-free housing laws in California, Massachusetts, and Michigan that require breaking plants to segregate compliant layer flocks. In September 2025, the USDA Economic Research Service reported that cage-free hens reached 40.2% of the U.S. commercial table-egg layer flock as foodservice buyers accelerated contract conversions [10]. Periodic Midwest avian flu outbreaks still create tight spot supply, prompting processors to build geographically dispersed breaking complexes with inline pasteurizers.
Key takeaway: Quick-service breakfast menu automation and state cage-free laws in the USA drive heavy investment in segregated breaking and pasteurization capacity.
UK Liquid Egg Market Outlook (2026 to 2036)
Demand across the UK liquid egg sector is expected to increase at a 6.5% CAGR through 2036, underpinned by strict retail bakery auditing and the British Lion Quality Code. Supermarket sandwich makers, chilled ready-meal factories, and hospital caterers specify Lion-certified pasteurized liquid egg to guarantee flock-level Salmonella vaccination and full farm traceability. In July 2025, the British Egg Industry Council reported that British Lion approved processors supplied over 90% of domestic food manufacturing liquid egg volume [11]. Rising electricity tariffs for continuous chillers and cold-store depots still squeeze operating margins, leading UK breaking plants to install regenerative heat-recovery pasteurizers.
Key takeaway: Mandatory British Lion food safety auditing and chilled sandwich and bakery manufacturing anchor UK conversion from shell to pasteurized liquid egg.
Canada Liquid Egg Market Outlook (2026 to 2036)
In August 2025, Agriculture and Agri-Food Canada recorded a 5.4% annual rise in shell eggs directed to domestic breaking plants for liquid processing [12]. Canada's national supply-management system coordinates provincial layer production quotas with industrial breaking allocations, creating predictable contract pricing that differs from volatile U.S. spot markets. Sales of liquid egg in Canada are forecast to expand at a 6.0% CAGR through 2036 as commercial bakeries in Ontario and Quebec automate pastry and waffle lines. Because tariff-rate quotas limit access to cheaper foreign shell eggs during peak baking seasons, Canadian processors focus on value-added salted yolks and citric-acid-stabilized whole egg blends.
Key takeaway: Provincial supply-management quota stability and Ontario and Quebec bakery automation support steady Canadian investment in pasteurized liquid egg blends.
South Korea Liquid Egg Market Outlook (2026 to 2036)
Between 2026 and 2036, the South Korea liquid egg market is expected to progress at a 5.6% CAGR as commercial kitchens replace manual shell breaking to offset rising kitchen labor wages. Rapid expansion of western-style bakery cafe franchises and convenience store ready meals across Seoul and Gyeonggi Province has reshaped institutional egg procurement. In October 2025, South Korea's Ministry of Agriculture, Food and Rural Affairs reported that licensed egg grading and liquid breaking centers handled 38% more foodservice volume than three years earlier [13]. Because fragmented small-scale layer farms still cause seasonal supply gaps, major Korean food conglomerates pair domestic chilled liquid breaking lines with imported dried eggs for shelf-stable bakery premixes.
Key takeaway: Expanding Seoul bakery cafe franchises and commercial kitchen wage pressures accelerate South Korean adoption of centrally pasteurized liquid egg cartons.
Japan Liquid Egg Market Outlook (2026 to 2036)
Convenience store bento commissaries, industrial noodle plants, and emulsified dressing makers in Japan run automated liquid egg dosing around the clock. In Japan, demand for liquid egg is predicted to advance at a 5.1% CAGR through 2036, supported by strict bacterial count standards in tamagoyaki and custard production. In November 2025, Japan's Ministry of Agriculture, Forestry and Fisheries documented that industrial food processors and mayonnaise plants absorbed more than 51% of national graded egg output [14]. Imported corn feed costs and winter avian flu culls periodically push wholesale egg prices higher, prompting Japanese refiners to use phospholipase enzymatic yolk modification so food makers need less yolk per batch.
Key takeaway: Round-the-clock convenience store bento commissaries and mayonnaise plants sustain high-volume Japanese demand for precision-pasteurized liquid yolk and whole egg.
Germany Liquid Egg Market Outlook (2026 to 2036)
The Germany liquid egg sector is projected to record a 4.6% CAGR during the assessment period, driven by export-oriented fine bakery and egg noodle manufacturing. German food factories operate under Europe's strictest animal husbandry and non-GMO feed verification rules, which shapes every liquid egg contract in the country. In December 2025, the Association for Controlled Alternative Animal Husbandry (KAT) confirmed that over 98% of German retail and food-industry egg volume carried verified barn, free-range, or organic farm traceability [15]. Because discount grocery chains resist wholesale price increases, German breaking plants protect margins by valorizing eggshell calcium for animal feed and selling separated liquid whites to sports nutrition blenders.
Key takeaway: Universal KAT barn and free-range traceability rules shape German liquid egg procurement across industrial pasta and fine bakery lines.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the liquid egg market?
Michael Foods Inc. (Post Holdings), Cargill Incorporated, Rembrandt Enterprises Inc., Dava Foods A/S, Ovostar Union N.V., Bouwhuis Enthoven B.V., Interovo Egg Group B.V., and Ready Egg Products Ltd are the significant market players in this market.
Large North American poultry integrators such as Michael Foods Inc. (Post Holdings) and Cargill Incorporated run multi-state layer complexes and high-speed breaking lines that deliver bulk tanker loads to national restaurant and bakery chains. In Europe, Dava Foods A/S, Interovo Egg Group B.V., Bouwhuis Enthoven B.V., and Ready Egg Products Ltd focus on KAT- and Lion-certified cage-free cartons, aseptic totes, and co-processed ovalbumin powder, as noted by FMI. Meanwhile, integrated producers Rembrandt Enterprises Inc. and Ovostar Union N.V. pair biosecure aviary farms with inline breaking plants to serve domestic and export food manufacturers.
- Vertically Integrated Agribusiness Conglomerates: Michael Foods Inc. and Cargill Incorporated dominate bulk commercial food service and industrial baking supply agreements.
- Specialized European Egg Processors: Dava Foods A/S, Bouwhuis Enthoven B.V., Interovo Egg Group B.V., and Ready Egg Products Ltd lead certified cage-free liquid egg distribution.
- Integrated Agricultural Producers: Rembrandt Enterprises Inc. and Ovostar Union N.V. operate large-scale layer complexes and egg breaking lines for domestic and export markets.
Competitive Benchmarking: Liquid Egg Market
Table 8: Competitive Benchmarking for the Liquid Egg Market (qualitative capability ratings), 2026
| Company | Egg Breaking & Processing Capacity | Cage-Free Farm Conversion Depth | Cold-Chain Distribution Reach | Geographic Reach |
|---|---|---|---|---|
| Michael Foods Inc. | High | High | High | High |
| Cargill Incorporated | High | High | High | High |
| Rembrandt Enterprises Inc. | High | Medium | High | Medium |
| Dava Foods A/S | Medium | High | High | Medium |
| Ovostar Union N.V. | High | Medium | High | High |
| Bouwhuis Enthoven B.V. | Medium | High | High | High |
| Interovo Egg Group B.V. | High | High | High | High |
| Ready Egg Products Ltd | Medium | High | Medium | Medium |
Scoring basis: Capability ratings reflect verified daily egg breaking throughput, cage-free flock share, and refrigerated tanker and carton logistics coverage rather than revenue rank.
Key Developments in the Liquid Egg Market
- In March 2026, Michael Foods Inc. completed a capacity expansion at its Norwalk, Iowa egg breaking complex, adding two high-speed tubular pasteurization lines for foodservice liquid egg accounts [16].
- In January 2026, Cargill Incorporated expanded its Midwest producer partnership program to convert an additional 4 million laying hens to certified cage-free aviary housing for liquid egg supply [17].
- In November 2025, Dava Foods A/S rolled out a commercial line of organic pasteurized liquid egg whites in renewable gable-top cartons across Nordic retail and foodservice channels [18].
- In August 2025, Interovo Egg Group B.V. commissioned optical-sensor robotic egg breaking lines that raise yolk-from-white separation purity by 15% on industrial bakery runs [19].
Key Players in the Liquid Egg Market
Vertically Integrated Agribusiness Conglomerates
- Michael Foods Inc. (Post Holdings)
- Cargill Incorporated
Specialized European Egg Processors
- Dava Foods A/S
- Bouwhuis Enthoven B.V.
- Interovo Egg Group B.V.
- Ready Egg Products Ltd
Integrated Agricultural Producers
- Rembrandt Enterprises Inc.
- Ovostar Union N.V.
Liquid Egg Market - Report Scope
Table 9: Report Scope for the Liquid Egg Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Source / Egg Type; End-Use / Application; Packaging Format; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from pasteurized liquid whole egg, liquid egg white, and liquid egg yolk sold in bulk tankers, bag-in-box totes, cartons, and bottles. Excludes intact shell eggs sold at retail, dried egg powders, and non-egg plant substitutes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Canada, South Korea, Japan, Germany, and additional countries in the full report |
| Key Companies Covered | Michael Foods Inc. (Post Holdings), Cargill Incorporated, Rembrandt Enterprises Inc., Dava Foods A/S, Ovostar Union N.V., Bouwhuis Enthoven B.V., Interovo Egg Group B.V., Ready Egg Products Ltd |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Liquid Egg Market - Research Methodology
Table 10: Research Methodology for the Liquid Egg Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial egg breaking plant directors, poultry agribusiness executives, wholesale bakery procurement managers, foodservice distributors, and food safety auditors across key markets. |
| Secondary Research | Secondary research included USDA and European Commission egg processing statistics, food hygiene regulatory publications, industry associations, corporate annual reports, investor presentations, and product specifications. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up approaches reconciling commercial shell egg breaking throughput against industrial bakery and foodservice procurement. |
| Data Triangulation and Validation | Estimates were validated against layer flock inventories, commercial breaking yields, cage-free housing conversion trackers, and historical price realizations without double counting dried or shell egg categories. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's poultry and processed egg econometric model, calibrating evaluated national growth rates against the 5.8% global baseline through verified commercial breaking plant automation, cage-free flock conversion mandates, and industrial bakery liquid egg adoption. |
| Operational Benchmark Traceability | Operational benchmarks (shell eggs cracked industrially, pasteurized liquid egg output, and aseptic carton filling speeds) represent modeled estimates synthesized from USDA NASS egg products releases, FDA Salmonella prevention rules, and commercial breaker plant filings. |
Liquid Egg Market by Segments
Liquid Egg Market segmented by Product Type:
- Liquid Whole Egg
- Liquid Egg White
- Liquid Egg Yolk
Liquid Egg Market segmented by Source / Egg Type:
- Cage-Free / Free-Range
- Conventional Caged
- Certified Organic
Liquid Egg Market segmented by End-Use / Application:
- Industrial Bakery & Confectionery
- Food Service & Commercial Kitchens
- Processed Food & Ready Meals
- Direct Retail Consumption
Liquid Egg Market segmented by Packaging Format:
- Bulk Tankers & Bag-in-Box
- Pure-Pak / Gable Top Cartons
- PET Bottles & Pouches
Liquid Egg Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Netherlands
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Turkiye
Research Sources and Bibliography
- [1] National Agricultural Statistics Service (NASS). (2025, January 22). Egg products monthly report: Commercial breaking operations and liquid egg production. U.S. Department of Agriculture.
- [2] Center for Food Safety and Applied Nutrition. (2025, February 18). Egg guidance, regulation, and pasteurized egg food code provisions for Salmonella control. U.S. Food and Drug Administration.
- [3] Food and Agriculture Organization of the United Nations. (2025, March 31). Global livestock and egg processing production statistics: March 2025 update. FAO Statistics Division.
- [4] European Food Safety Authority Panel on Animal Health and Welfare. (2025, April 25). Scientific assessment of laying hen housing systems and Salmonella control in EU egg breaking plants. EFSA Journal, 23(4), e08488.
- [5] Federal Statistical Office (Destatis). (2025, May 18). Industrial food processing statistics: Utilization of pasteurized liquid egg in German bakery manufacturing. Statistisches Bundesamt.
- [6] Post Holdings Inc. (2026, June 20). Michael Foods foodservice refrigerated liquid egg and bulk tanker logistics update. Post Holdings Investor Relations.
- [7] Food Safety and Inspection Service (FSIS). (2026, August 28). Inspection programs for pasteurized egg products and pilot projects for Salmonella control strategies. U.S. Department of Agriculture.
- [8] World Organisation for Animal Health (WOAH). (2025, May 14). Global situation report on highly pathogenic avian influenza in commercial poultry flocks. WOAH Animal Health Information Department.
- [9] Bouwhuis Enthoven B.V. (2026, February 16). Enzymatic modification and thermal stability protocols for industrial liquid egg yolks. Corporate Technical Release.
- [10] Economic Research Service (ERS). (2025, September 15). Commercial egg processing dynamics: Growing share of cage-free egg-laying hens in the United States. U.S. Department of Agriculture.
- [11] British Egg Industry Council (BEIC). (2025, July 22). British Lion Code of Practice: Auditing microbiological safety across UK pasteurized egg processors. BEIC Technical Bulletin.
- [12] Agriculture and Agri-Food Canada. (2025, August 28). Canadian poultry and egg market review: Industrial breaking allocation and liquid egg demand. Government of Canada Sectoral Monograph.
- [13] Ministry of Agriculture, Food and Rural Affairs (MAFRA). (2025, October 16). Commercial pasteurized liquid egg adoption across South Korean bakery and foodservice chains. Government of the Republic of Korea.
- [14] Ministry of Agriculture, Forestry and Fisheries (MAFF). (2025, November 25). Annual survey on graded egg distribution and industrial liquid egg processing in Japan. Government of Japan.
- [15] Association for Controlled Alternative Animal Husbandry (KAT). (2025, December 14). Traceability standards and barn/free-range compliance for processed egg products in Germany. KAT Annual Report.
- [16] Post Holdings Inc. / Michael Foods. (2026, March 18). Completion of high-speed pasteurization line expansion at Norwalk, Iowa breaking complex. Corporate Press Release.
- [17] Cargill Incorporated. (2026, January 22). Strategic partnership with Midwest poultry producers for expanded cage-free liquid egg supply. Cargill Media Announcement.
- [18] Dava Foods A/S. (2025, November 10). Commercial rollout of certified organic pasteurized liquid egg whites in renewable cartons. Dava Foods Product Release.
- [19] Interovo Egg Group B.V. (2025, August 24). Commissioning of optical-sensor robotic egg breaking lines for high-purity component separation. Interovo Manufacturing Update.
- [20] Rembrandt Enterprises Inc. (2026, April 14). Modernization of biosecure aviary layer complexes and inline liquid breaking facilities. Rembrandt Foods Corporate Update.
- [21] Ovostar Union N.V. (2025, October 20). Expansion of pasteurized liquid egg exports to European and Middle Eastern food manufacturers. Ovostar Union Operational Review.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete references and dataset.
This Report Answers
- How large is the liquid egg market in 2026 and what is forecast for 2036?
- Which kitchen hygiene and automation drivers support demand for liquid egg?
- Why does liquid whole egg lead the product type category?
- Why does cage-free and free-range lead the egg farming category globally?
- How do growth rates prominently differ across the USA, UK, Canada, and South Korea?
- Which leading companies supply relevant pasteurized liquid egg products today?
- What limits adoption or cold-chain distribution efficiency in the liquid egg market?
- What should commercial bakery procurement directors evaluate deeply before contracting with a liquid egg supplier?
Frequently Asked Questions
How big is the liquid egg market in 2026, and what is forecast for 2036?
The global liquid egg market is estimated to reach USD 5.8 Billion in 2026 and is projected to expand to USD 10.2 Billion by 2036 as food manufacturers replace manual shell cracking with pasteurized liquid systems.
What is the CAGR for the liquid egg market from 2026 to 2036?
As per FMI, the liquid egg market is projected to grow at a 5.8% CAGR from 2026 to 2036, supported by continuous dough mixing automation and strict Salmonella control rules in commercial kitchens.
Which product type segment leads the liquid egg market in 2026?
Liquid whole egg is projected to hold 52.4% of product type demand in 2026 because its natural yolk-to-white ratio provides balanced emulsification, binding, and aeration across bakery and pasta recipes.
Which egg farming source segment holds the leading share in 2026?
Cage-free and free-range eggs account for 44.6% of source egg type demand in 2026, driven by corporate animal welfare commitments and statutory bans on conventional battery cages.
Which country has a notable growth outlook during the assessment period?
FMI finds that the USA is projected to register a 7.1% CAGR from 2026 to 2036, supported by high-volume quick-service breakfast programs and state-level cage-free egg legislation.
Who are the active companies in the liquid egg market?
Notable companies include Michael Foods Inc. (Post Holdings), Cargill Incorporated, Rembrandt Enterprises Inc., Dava Foods A/S, Ovostar Union N.V., Bouwhuis Enthoven B.V., Interovo Egg Group B.V., and Ready Egg Products Ltd. These suppliers focus on cage-free aviary conversions, high-speed optical breaking, and extended-shelf-life aseptic packaging.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Liquid Whole Egg
- Liquid Egg White
- Liquid Egg Yolk
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source / Egg Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source / Egg Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source / Egg Type, 2026 to 2036
- Cage-Free / Free-Range
- Conventional Caged
- Certified Organic
- Y-o-Y Growth Trend Analysis By Source / Egg Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Source / Egg Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use / Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use / Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use / Application, 2026 to 2036
- Industrial Bakery & Confectionery
- Food Service & Commercial Kitchens
- Processed Food & Ready Meals
- Direct Retail Consumption
- Y-o-Y Growth Trend Analysis By End-Use / Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use / Application, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Bulk Tankers & Bag-in-Box
- Pure-Pak / Gable Top Cartons
- PET Bottles & Pouches
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Netherlands
- Nordics
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Turkiye
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Source / Egg Type
- By End-Use / Application
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Michael Foods Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill Incorporated
- Rembrandt Enterprises Inc.
- Dava Foods A/S
- Ovostar Union N.V.
- Bouwhuis Enthoven B.V.
- Interovo Egg Group B.V.
- Ready Egg Products Ltd
- Michael Foods Inc. (Post Holdings)
- Michael Foods Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


