
- Market Size (2026)
- USD 14.8 Bn
- Forecast (2036)
- USD 29.7 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Meal Replacement Products Market in 2026?
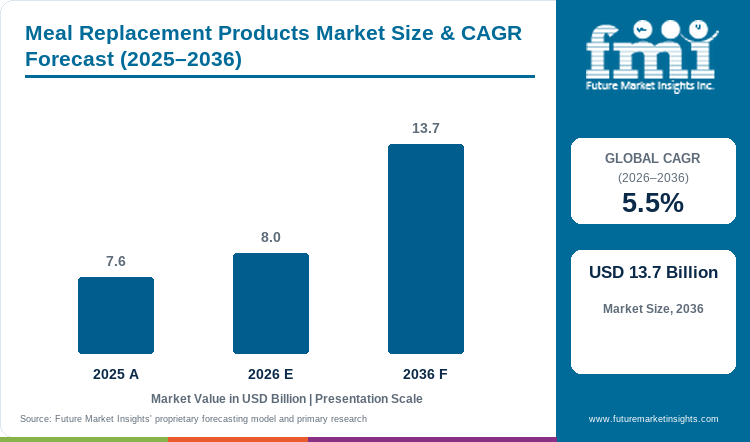
The meal replacement products market establishes its foundation at USD 13.8 billion in 2025, advances to USD 14.8 billion in 2026, and is forecast to scale to USD 29.7 billion by 2036 at a CAGR of 7.2%.
The global meal replacement products market was valued at USD 13.8 billion in 2025 and is estimated to reach USD 14.8 billion in 2026. The market is projected to reach USD 29.7 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.2% between 2026 and 2036. Ready-to-drink RTD shakes and bottles hold an estimated 48.0% share of 2026 demand, since shelf-stable aseptic bottles deliver measured protein and 25+ essential vitamins without blender cleanup. Buyer adoption tracking at FMI shows that demand for meal replacement products is supported by nutrient-intensity uptick per meal occasion, given that patients on GLP-1 receptor agonists experience suppressed appetite and require 1.2 to 1.5 grams of protein per kilogram of body weight daily to prevent lean muscle loss.
That broader commuter and pharmacy base separates the overall market from dedicated GLP-1 meal replacement formulas at 16.3% CAGR, where specialized clinical SKUs expand from a smaller USD 2.4 billion baseline. Manufacturers are also investing in ultra-high-protein RTD capacity to capture these buyers, as BellRing Brands launched its 42-gram Premier Protein Ultimate shakes in July 2026 to serve high-satiety daily meal occasions. Pharmacy chains and subscription platforms retain meal-replacement buyers when 30-plus-gram protein density and low glycemic load prevent muscle wasting and taste fatigue through 2036.
Key Market Trends & Insights
- By product format: Ready-to-Drink RTD Shakes and Bottles are projected to hold a 48.0% share in 2026 since UHT aseptic cartons and HDPE bottles fit single-handed commuter and office consumption.
- By macronutrient profile: High-Protein Low-Carb Formulas are anticipated to represent 52.0% in 2026 given that 30-gram to 45-gram protein dosing protects lean mass without triggering insulin spikes.
- By distribution channel: Pharmacies and Drugstores are estimated to account for 46.0% in 2026 owing to pharmacist-recommended metabolic, bariatric, and senior nutrition merchandising.
- By primary application: Weight Management and GLP-1 Companion Nutrition is forecast to secure 44.0% in 2026 as anti-obesity medication users seek micronutrient-dense mini-meals.
- By formulation claim: Low-Sugar and Glycemic-Controlled products are expected to command 54.0% in 2026 under front-of-pack sugar rules and diabetic-friendly dietary guidelines.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at an 8.4% CAGR through 2036 under urban pharmacy chain expansion and direct-selling nutritional shake networks.
- Broader country progression: Mexico tracks at an 8.2% CAGR ahead of the United States at 7.8% and the United Kingdom at 7.2%, while Canada advances at a 7.0% CAGR and Japan records a 6.4% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Meal Replacement Products Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.8 billion |
| Estimated Market Size in 2026 | USD 14.8 billion |
| Projected Market Size by 2036 | USD 29.7 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 14.9 billion |
Weight-management consumers and outpatient metabolic clinics frequently abandon traditional 800-calorie liquid diets when high-sugar shakes cause rebound hunger and visceral fat stagnation. Formulation of complete meal replacements with slow-digesting micellar casein, milk protein isolate, or pea-rice blends stabilizes post-meal satiety hormones over four-hour windows. Clinical trial evidence published in Nutrients in July 2025 confirmed that self-directed high-protein meal replacement combined with intermittent fasting significantly amplified reductions in body weight, visceral fat mass, and fasting insulin compared with lifestyle counseling alone. Consequently, retail brands pair RTD shakes with portion-controlled meal replacement bars to sustain multi-month dietary adherence.
Aseptic RTD Bottling & Macronutrient Dosing Sizing
Table 2: Aseptic RTD Bottling and Macronutrient Dosing Sizing for the Meal Replacement Products Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 13.8 | 14.8 | 29.7 |
| Global portion-controlled meal servings sold (billion units) | 5.8 to 6.3 | 6.2 to 6.8 | 11.8 to 12.9 |
| Aseptic RTD shake & bottle volume (billion liters) | 1.15 to 1.28 | 1.24 to 1.38 | 2.45 to 2.72 |
| Average retail price per complete meal serving (USD) | 2.20 to 2.45 | 2.22 to 2.48 | 2.35 to 2.65 |
Public health authorities and hospital dietetics departments actively integrate portion-controlled meal replacements into structured adult weight and metabolic management pathways. In October 2026, the World Health Organization updated its global Obesity and Overweight fact sheet emphasizing that structured caloric and nutrient management is essential to curb global adult obesity prevalence. Commercial formulators respond by engineering fortified meal replacement shakes that supply 100% of recommended daily micronutrient minimums per two-meal replacement protocol.
GLP-1 Companion & Adult Muscle-Preservation Sizing
Table 3: GLP-1 Companion and Adult Nutrition Indicators for the Meal Replacement Products Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Active weight-management, GLP-1 & commuter buyers (million) | 64.0 | 68.5 | 124.0 |
| Annual meal-replacement expenditure per active buyer (USD) | 215.6 | 216.1 | 239.5 |
| 30g-to-45g high-protein formula share of total sales (%) | 49.5% to 51.5% | 51.0% to 53.0% | 62.0% to 66.0% |
| GLP-1 companion & clinical sarcopenia share (%) | 15.0% to 17.0% | 16.5% to 18.5% | 28.0% to 32.0% |
Table 4: Pharmacy & Aseptic Channel Indicators for the Meal Replacement Products Market (USD and institutional basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 14.8 billion | 2026 global meal replacement products baseline |
| Dedicated GLP-1 meal replacement market, 2026 | USD 2.4 billion (16.3% CAGR) | FMI GLP-1 Meal Replacement Market 2026-2036 baseline |
| Adult skeletal muscle decline rate after age 40 | 8.0% per decade | Abbott Laboratories adult nutrition clinical benchmark |
| Ready-to-Drink RTD Shakes & Bottles revenue, 2026 | USD 7.10 billion | 48.0% product format allocation |
Demographic aging across North America, Europe, and East Asia is creating a second structural demand wave for high-protein complete nutrition drinks in addition to weight management. In April 2025, Abbott Laboratories reported in its adult nutrition strategy assessment that adults lose approximately 8% of their skeletal muscle mass every decade starting at age 40, driving clinical demand for HMB- and protein-enriched nutritional drinks. Healthcare and retail formulators consequently position GLP-1 nutritional support and active-aging shakes side by side in pharmacy aisles.
Analyst Perspective
"The meal replacement aisle has shifted permanently from sugary 1990s diet powders to 30-to-45-gram high-protein aseptic shakes engineered for GLP-1 muscle preservation and desk-bound commuters. Suppliers that lock in rotary UHT co-packing capacity and pharmacy shelf space will lead category value growth through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Meal Replacement Products Market segmented?
The meal replacement products market is segmented by product format, macronutrient profile, distribution channel, primary application, and formulation claim. In 2026, Ready-to-Drink RTD Shakes and Bottles are projected at 48.0%, High-Protein Low-Carb Formulas at 52.0%, Pharmacies and Drugstores at 46.0%, Weight Management and GLP-1 Companion Nutrition at 44.0%, and Low-Sugar and Glycemic-Controlled at 54.0%.
By product format: Ready-to-Drink RTD Shakes and Bottles and Powdered Drink Mixes generate core beverage turnover. Nutritional Meal Bars, Instant Savory Meal Bowls and Soups, and Portion-Controlled Meal Biscuits and Gels cover solid formats.
By macronutrient profile: High-Protein Low-Carb Formulas and Balanced Complete Nutrition 40-30-30 lead clinical and commuter demand. Ketogenic High-Fat Formulas and Plant-Based 100 Percent Vegan blends serve specialized metabolic and dairy-free buyers.
By distribution channel: Pharmacies and Drugstores and E-Commerce and Direct Subscription anchor repeat consumer purchasing. Specialty Health and Fitness Outlets and Supermarkets and Hypermarkets expand everyday impulse and grocery reach.
By primary application: Weight Management and GLP-1 Companion Nutrition and Adult Clinical and Bariatric Recovery lead medical-adjacent usage. Busy Professional On-the-Go Meals and Athletic Conditioning and Muscle Preservation capture active consumers.
By formulation claim: Low-Sugar and Glycemic-Controlled and Gluten-Free Certified labels dominate retail facings. Lactose-Free and Dairy-Free and Organic and Clean-Label Certified options address digestive and ethical preferences.
Why do Ready-to-Drink RTD Shakes and Bottles lead the product format category?
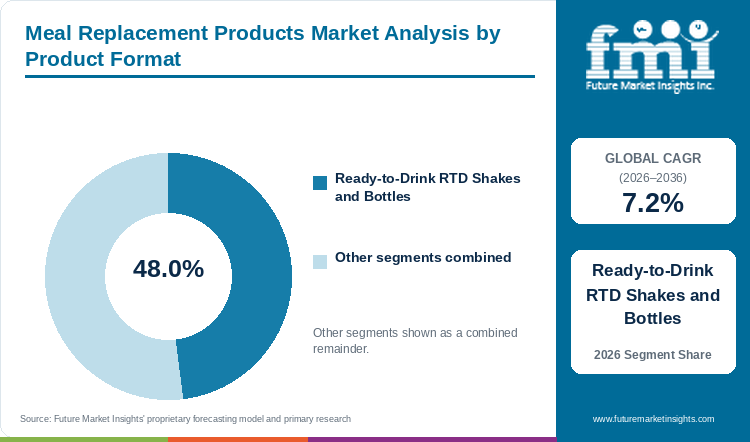
Ready-to-Drink RTD Shakes and Bottles hold an estimated 48.0% of product format demand in 2026, anchored by aseptic grab-and-go convenience and 30g-to-45g protein density.
Table 5: Product Format Share for the Meal Replacement Products Market (percentage share), 2026
| Product Format | Share (2026) |
|---|---|
| Ready-to-Drink RTD Shakes and Bottles | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining product format categories account for the balance of 2026 global meal replacement products demand.
Table 6: Product Format Leadership and Market Growth for the Meal Replacement Products Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Ready-to-Drink RTD Shakes and Bottles |
Shelf-stable RTD shakes and bottles lead commercial sales since aseptic UHT processing and ultrafiltered milk or plant proteins yield a smooth beverage that requires zero mixing or refrigeration prior to opening. Commuters, hospital outpatients, and GLP-1 users strongly prefer grab-and-go 11-ounce and 14-ounce reclosable bottles over bulk powder tubs during workday lunches. Product rollout disclosures from The Simply Good Foods Company in May 2026 confirmed that its Quest Salted Caramel Protein Milkshakes deliver 45 grams of ultrafiltered milk protein with only 2 grams of sugar and 2 grams of net carbs per bottle across Amazon, Kroger, and Walmart.
- Within the product format segment, Ready-to-Drink RTD Shakes and Bottles are projected to account for a leading 48.0% share in 2026, driven by convenience and high repeat multipack velocity.
- Instant Savory Meal Bowls and Soups are anticipated to record strong incremental adoption through 2036 as remote workers seek warm, savory lunch alternatives to sweet shakes.
What sustains High-Protein Low-Carb Formulas leadership in the macronutrient profile segment?
High-Protein Low-Carb Formulas represent 52.0% of the macronutrient profile category in 2026, supported by lean muscle preservation during caloric restriction.
High-Protein Low-Carb Formulas dominate macronutrient selection given that elevating protein to 40% or more of total calories while restricting net carbohydrates below 5 grams preserves fat-free muscle mass and blunts postprandial insulin secretion. Formulators must carefully balance micellar casein, whey protein isolate, and soluble prebiotic fibers so high-protein liquids do not gel or thicken excessively during 12-month ambient shelf storage. While balanced 40-30-30 shakes remain popular among endurance commuters, metabolic and weight-loss buyers overwhelmingly specify high-protein, low-glycemic macros.
- In 2026, High-Protein Low-Carb Formulas are anticipated to capture 52.0% of global macronutrient profile demand, reflecting clinical and consumer focus on lean body composition.
- Secondary analysis of 203 International Weight Control Registry participants published in late 2025 confirmed that higher dietary protein intake per kilogram of body weight negatively predicted BMI and body-fat percentage while positively predicting lean muscle percentage.
How do Pharmacies and Drugstores lead the distribution channel category?
Pharmacies and Drugstores account for 46.0% of distribution channel volume in 2026, driven by outpatient GLP-1, diabetic, and clinical nutrition counseling.
Pharmacies and Drugstores capture the largest channel share since patients filling GLP-1 prescriptions, bariatric recovery orders, or diabetic testing supplies purchase clinical meal replacements during the same pharmacy visit. Chain pharmacies allocate prominent front-of-store end-caps to Abbott Ensure and Nestlé Optifast multipacks supported by pharmacist counseling. Corporate manufacturing disclosures from Danone S.A. in September 2026 confirmed a EUR 70 million investment to commission its largest European specialized nutrition facility in northern France.
- By distribution channel, demand through Pharmacies and Drugstores is estimated to reach 46.0% of total category share in 2026 as retail pharmacies co-merchandise metabolic shakes near prescription counters.
- E-Commerce and Direct Subscription platforms are forecast to expand rapidly through 2036 as consumers enroll in automated monthly deliveries for weight management programs.
Why does Weight Management and GLP-1 Companion Nutrition lead the primary application category?
Weight Management and GLP-1 Companion Nutrition secures 44.0% of primary application value in 2026, supported by nutrient-dense mini-meals for appetite-suppressed users.
Weight Management and GLP-1 Companion Nutrition leads application demand given that pharmacological appetite suppression reduces daily food volume by 30% to 45% and creates a risk of lean-tissue catabolism if meals are skipped. Dedicated companion shakes and pouches pack 25 to 45 grams of complete protein, 5 to 8 grams of soluble fiber, and 26+ vitamins and minerals into a compact 200-to-400-calorie serving that is easy on delayed gastric emptying. Brands must avoid heavy lipid loads that trigger gastrointestinal nausea in medicated users.
- Weight Management and GLP-1 Companion Nutrition is predicted to secure 44.0% of primary application demand in 2026, anchored by clinician-guided and self-directed metabolic protocols.
- Nutritional trend rankings published by Huel in February 2026 documented that 2026 dietary demand has shifted decisively toward nutrient-dense GLP-1 companion meals that deliver high protein, fiber, and micronutrients in smaller food volumes.
What gives Low-Sugar and Glycemic-Controlled the leading position in formulation claim?
Low-Sugar and Glycemic-Controlled formulations command 54.0% of formulation claim share in 2026, anchored by front-of-pack sugar rules and low-glycemic clinical standards.
Low-Sugar and Glycemic-Controlled claims command over half of market value since added sugars above 5 grams per serving disqualify meal replacements from diabetic, ketogenic, and clean-label retail charters. Formulators replace sucrose and corn-syrup solids with allulose, monk fruit, and steviol glycosides to maintain sweet palatability without raising blood glucose. Regulatory priority deliverables released by the U.S. Food and Drug Administration Human Foods Program in February 2026 highlighted mandatory front-of-package added-sugar labeling and updated 'healthy' claim criteria that reward low-sugar nutrient-dense formulations.
- Strict retail sugar caps and metabolic buyer screening place Low-Sugar and Glycemic-Controlled products on course to hold an estimated 54.0% share of the formulation claim category in 2026.
- Lactose-Free and Dairy-Free claims are projected to gain share through 2036 as formulators integrate lactase-treated milk isolates and plant proteins into oral clinical nutrition supplements.
What are the drivers, restraints, and opportunities in the Meal Replacement Products Market?
In the meal replacement products market, GLP-1 muscle-preservation protocols and commuter RTD convenience are projected to drive adoption whereas aseptic bottling constraints and sweet-shake fatigue restrain long-term adherence and savory meal bowls create new demand avenues.
- Driver: Widespread GLP-1 medication adoption, adult sarcopenia prevention, and urban commuter convenience are driving repeat purchases of high-protein RTD shakes and meal powders.
- Restraint: Aseptic UHT co-packing capacity bottlenecks, volatile dairy protein input costs, and sweet-shake taste fatigue restrain long-term daily consumer adherence.
- Opportunity: Developing savory instant meal bowls, 40-plus-gram ultra-high-protein RTD shakes, and personalized direct-to-consumer GLP-1 companion bundles unlocks new revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clinical validation of protein-enriched meal replacements for fat-mass reduction and glycemic regulation is accelerating adoption across both medical weight-loss clinics and retail grocery aisles. Rather than relying on extreme crash fasting that strips skeletal muscle, modern weight-control protocols combine moderate exercise with portion-controlled high-protein shakes. An eight-week randomized controlled trial published in Scientific Reports in April 2025 demonstrated that overweight women combining protein-enriched intermittent meal replacement shakes with moderate-intensity training achieved a 3.70-kilogram body-weight reduction and a 2.25-kilogram fat-mass loss with improved fasting insulin compared with 1.17 kilograms from exercise alone. These measurable body-composition outcomes drive recurring multipack sales and complement enteral nutrition formulas in outpatient care.
Risk Assessment of the Meal Replacement Products Market: Operational and Formulation Friction
High dairy protein concentrate prices, aseptic rotary bottle-filling capacity constraints, and consumer flavor monotony after four to six weeks of liquid-only dieting represent the primary hurdles restraining faster category expansion. When consumers drink exclusively sweet chocolate or vanilla shakes twice daily, sensory fatigue leads to mid-program dropout and weight regain. A clinical weight-loss review published in Nutrients in December 2025 noted that sustaining long-term weight maintenance requires pairing high-protein intake around 1.4 grams per kilogram per day with varied food textures and behavioral dietary adherence strategies. Furthermore, strict European and national rules governing total diet replacement energy and micronutrient claims require costly stability testing across 12-month shelf lives.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Manufacturers are capturing high-margin incremental growth by pairing high-protein RTD shakes with prebiotic soluble fibers, savory hot meal formats, and digestive enzymes tailored to post-weight-loss maintenance. In July 2025, nutrition researchers reviewing the multi-country European DiOGenes trial in the Journal of Nutritional Science confirmed that adults maintaining higher protein and lower-glycemic diets after an 8% weight loss regained 0.93 kilograms less body weight over six months than low-protein control groups. Co-formulation of meal replacements with fast-absorbing hydrolyzed whey proteins, micellar casein, and resistant dextrin fibers enables brands to market two-phase weight-loss and weight-maintenance subscription systems.
Meal Replacement Products Market by Country (2026 to 2036)
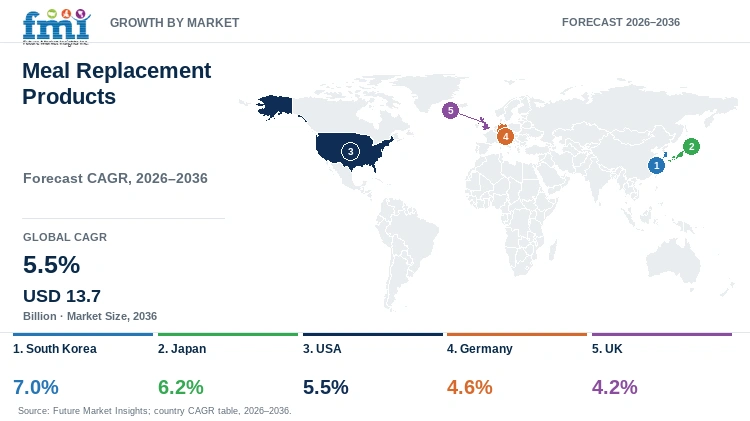
FMI country modeling indicates that Brazil leads meal replacement products expansion at an 8.4% CAGR through 2036, while Mexico advances at an 8.2% CAGR and the United States tracks at a 7.8% CAGR. National growth patterns across Latin American, North American, and European markets reflect pharmacy chain merchandising and GLP-1 prescription velocity.
Table 7: Country CAGR and Primary Growth Levers for the Meal Replacement Products Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.4% | USD 248B food processing sector (+8% YoY) and pharmacy and nutrition-club expansion |
| Mexico | 8.2% | Front-of-pack sugar-octagon reformulation and diabetic-friendly pharmacy shake demand |
| United States | 7.8% | World's largest GLP-1 patient cohort and 42g-to-45g club-store RTD shake multipacks |
| United Kingdom | 7.2% | Supermarket meal-deal chiller integration and NHS weight-remission diet protocols |
| Canada | 7.0% | Health Canada supplemented-food compliance and pharmacy senior muscle nutrition |
| Germany | 6.9% | Drugstore Trinkmahlzeiten velocity and clinical hyperprotein recovery supplementation |
| Spain | 6.7% | 25% surge in new grocery store openings and pharmacist weight-control counseling |
| Japan | 6.4% | Konbini single-serve complete nutrition pouches and senior sarcopenia prevention |
Source: Future Market Insights analysis
Brazil Meal Replacement Products Market Outlook (2026 to 2036)
Brazilian meal replacement products demand is projected to expand at a leading 8.4% CAGR between 2026 and 2036 across national pharmacy chains, direct-selling nutrition clubs, and modern supermarket wellness aisles. What distinguishes Brazil from mature European markets is the rapid expansion of ANVISA-regulated high-protein RTD dairy shakes and pharmacy-dispensed weight-management powders across Sao Paulo, Rio de Janeiro, and Belo Horizonte. Sao Paulo agricultural attachés documented in March 2026 that Brazil's food processing industry expanded 8% year over year in 2025 on strong domestic consumer demand. Local dairy and nutrition processors utilize domestic soy and whey supply to scale affordable 30-gram protein RTD cartons.
Key takeaway: In Brazil, 8% annual food processing expansion and high pharmacy and nutrition-club penetration are projected to drive leading 8.4% CAGR growth.
Mexico Meal Replacement Products Market Outlook (2026 to 2036)
In Mexico, meal replacement products sales are forecast to advance at an 8.2% CAGR through 2036, driven by front-of-pack warning-octagon reformulation and strong demand for diabetic-friendly and weight-control shakes. Compared with markets where meal replacements are used mainly for casual convenience, Mexican consumers and physicians prioritize low-sugar, glycemic-controlled formulas to address high national prevalence of adult overweight and type 2 diabetes. Mexico City agricultural specialists noted in their April 2026 Food Processing Ingredients Annual report that local food manufacturers actively reformulate processed products using functional proteins and non-caloric sweeteners to avoid front-of-pack warning seals. Pharmacy chains and nutrition clubs across Mexico City, Monterrey, and Guadalajara drive recurring powder and RTD turnover.
Key takeaway: In Mexico, front-of-pack sugar-seal reformulation and high metabolic-health demand in pharmacies are forecast to sustain an 8.2% CAGR through 2036.
United States Meal Replacement Products Market Outlook (2026 to 2036)
United States meal replacement products revenue is anticipated to grow at a 7.8% CAGR from 2026 to 2036, anchored by the world's largest GLP-1 patient cohort and nationwide club-store and pharmacy distribution. The United States diverges from international markets through rapid consumer migration toward 30-gram to 45-gram ultra-high-protein RTD shakes sold in 12-pack and 18-pack club cartons. In January 2026, The Simply Good Foods Company noted that its Atkins High Protein Strong Shakes delivering 30 grams of protein and 7 grams of prebiotic fiber support muscle preservation for Americans on GLP-1 weight-loss journeys. Domestic suppliers Abbott and Premier Protein as well as Quest and Huel continue expanding aseptic bottling capacity to meet retail velocity.
Key takeaway: In the United States, mass GLP-1 companion nutrition adoption and club-store 30g-to-45g RTD shake multipacks are anticipated to propel 7.8% annual growth.
United Kingdom Meal Replacement Products Market Outlook (2026 to 2036)
Meal replacement products expenditure in the United Kingdom is estimated to progress at a 7.2% CAGR between 2026 and 2036 across high-street chemists, supermarket meal-deal chillers, and direct-to-consumer subscription brands. What sets the United Kingdom apart in Europe is the mainstream acceptance of nutritionally complete RTD bottles and savory meal pots as everyday desk lunches and NHS-aligned total diet replacement weight-remission pathways. In February 2026, Glanbia plc reported full-year 2025 pro-forma like-for-like revenue growth of 4.5% with 3.6% volume growth while streamlining its portfolio toward high-growth performance and health nutrition brands. British brands led by Huel also expand single-bottle supermarket chiller placement across Tesco, Sainsbury's, and Boots.
Key takeaway: In the United Kingdom, supermarket meal-deal chiller integration and NHS-aligned weight-management protocols are estimated to sustain a 7.2% CAGR.
Canada Meal Replacement Products Market Outlook (2026 to 2036)
Canada's meal replacement market is undergoing steady conversion toward Health Canada-compliant supplemented shakes, clinical pharmacy drinks, and plant-based complete meal powders. Consequently, national meal replacement demand is slated to increase at a 7.0% CAGR over the 2026 to 2036 forecast period, supported by aging baby-boomer nutrition needs and cross-border North American retail banners. In December 2025, Ottawa agricultural analysts documented in their Canada Retail Foods Annual report that Canadian shoppers actively prioritize high-protein and functional health foods across supermarket and drugstore channels. Canadian formulators utilize domestic pea protein and ultrafiltered native whey proteins to meet strict national macronutrient and vitamin fortification rules.
Key takeaway: In Canada, pharmacy-led senior nutrition and Health Canada-compliant high-protein RTD shakes are slated to support a 7.0% CAGR through 2036.
Germany Meal Replacement Products Market Outlook (2026 to 2036)
German meal replacement products demand is predicted to advance at a 6.9% CAGR from 2026 to 2036 across drugstore chains such as dm and Rossmann, pharmacies, and direct-to-consumer e-commerce platforms. Compared with North American markets focused on sweet diet shakes, German buyers show strong adoption of clean-label, low-sugar drinking meals (Trinkmahlzeiten) and high-protein clinical recovery drinks. Randomized clinical trial data published in PLOS ONE in July 2026 confirmed that hypercaloric and hyperprotein oral nutritional supplementation significantly improved clinical tissue recovery in multi-pathological malnourished European patients. German formulators pair whey protein ingredients and oat-pea blends with clean Nutri-Score A ratings to win drugstore shelf space.
Key takeaway: In Germany, strong drugstore Trinkmahlzeiten velocity and clinical hyperprotein supplementation are predicted to drive 6.9% annual growth.
Spain Meal Replacement Products Market Outlook (2026 to 2036)
In Spain, meal replacement products revenue is projected to climb at a 6.7% CAGR between 2026 and 2036, anchored by community pharmacy weight-control counseling and modern supermarket distribution. Spain differs from Northern European markets since community pharmacists play a primary gatekeeper role in recommending portion-controlled substitutive shakes and bars for seasonal weight management. Madrid retail food analysts reported in November 2025 that Spain's grocery distribution sector recorded 244 new store openings between January and April 2025, representing a 25% increase that expanded functional food shelf space. Spanish pharmacy and grocery brands actively introduce Mediterranean-flavored and lactose-free RTD shakes.
Key takeaway: In Spain, pharmacist-guided weight-management counseling and a 25% surge in new grocery store openings are projected to sustain a 6.7% CAGR.
Japan Meal Replacement Products Market Outlook (2026 to 2036)
Japanese meal replacement products sales are expected to grow at a 6.4% CAGR across the 2026 to 2036 horizon, supported by nationwide convenience-store single-serve pouches and geriatric sarcopenia nutrition. What distinguishes Japan from Western markets is the high popularity of chewable complete-nutrition blocks, vitamin-jelly pouches, and savory protein soups next to compact 200-milliliter RTD cartons. Tokyo agricultural attachés confirmed in their September 2026 Japan Retail Foods Annual assessment that Japan's retail sector sees steady consumer demand for single-serve convenience and health-maintenance foods. Domestic pharmacies and convenience chains stock portion-controlled complete meals tailored to solo households.
Key takeaway: In Japan, konbini single-serve pouch distribution and senior sarcopenia nutrition are expected to sustain steady 6.4% CAGR expansion.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Meal Replacement Products Market?
Abbott Laboratories, Herbalife Ltd, Soylent Rosa Foods Inc., Nestlé Health Science, Glanbia plc, Premier Nutrition Company LLC, The Simply Good Foods Company, Danone S.A., and Unilever PLC are the notable companies in the meal replacement products market.
Competitive positioning in the meal replacement products industry spans clinical medical nutrition groups, retail RTD protein shake leaders, and digital-native complete-food brands. Abbott Laboratories and Nestlé Health Science join Danone S.A. in anchoring pharmacy and hospital-adjacent metabolic formulas. Premier Nutrition Company LLC and Simply Good Foods compete with Glanbia plc and Herbalife Ltd across retail shake channels. Soylent Rosa Foods Inc., and Unilever PLC supply plant-based complete meals and functional drinks.
- Clinical and Metabolic Nutrition Leaders: Abbott Laboratories, Nestlé Health Science, and Danone S.A. formulate clinically validated meal replacements for weight loss, diabetes, and muscle preservation.
- High-Velocity RTD Protein Shake Powerhouses: Premier Nutrition Company LLC and Herbalife Ltd with The Simply Good Foods Company and Glanbia plc dominate club, grocery, and direct-selling shake channels.
- Plant-Based Complete-Meal and Functional Nutrition Groups: Soylent Rosa Foods Inc. with Unilever PLC supply vegan complete-nutrition bottles, savory meal packs, and fortified adult nutrition drinks.
Competitive Benchmarking: Meal Replacement Products Market
Table 8: Competitive Benchmarking for the Meal Replacement Products Market (qualitative capability ratings), 2026
| Company | High-Protein & GLP-1 Fit | Aseptic RTD & Format Scale | Pharmacy & Subscription Reach | Geographic Reach |
|---|---|---|---|---|
| Abbott Laboratories | High | High | High | Global pharmacy and hospital network across 160+ countries (Ensure, Protality, Glucerna) |
| Herbalife Ltd | High | Medium | High | 90+ countries via direct-selling nutrition clubs and GLP-1 Companion combos |
| Soylent Rosa Foods Inc. | High | High | High | United States and Canadian retail, pharmacy, and subscription RTD complete meals |
| Nestlé Health Science | High | High | High | Global medical and retail weight-management network (Optifast, Boost, Orgain) |
| Glanbia plc | High | Medium | High | North American and European sports and weight-management channels |
| Premier Nutrition Company LLC | High | High | High | North American and European club, mass, and pharmacy RTD leader under BellRing |
| The Simply Good Foods Company | High | High | High | North American retail and Amazon powerhouse (Atkins, Quest 45g RTD, OWYN) |
| Danone S.A. | High | High | High | European, Latin American, and APAC medical and high-protein nutrition (Nutricia) |
| Unilever PLC | Medium | High | High | South Asian and international pharmacy and grocery malted and protein drinks (Horlicks) |
Key Developments in the Meal Replacement Products Market
- On August 4, 2026, BellRing Brands Inc. released its fiscal third-quarter 2026 results, reporting that Premier Protein ready-to-drink meal replacement shakes continued to anchor revenue performance for the period. Net sales growth for fiscal 2026 was tracking toward the lower half of the company’s 1.0 to 3.0 percent guidance range, reflecting solid demand offset by moderating distribution-gain contributions year over year. Full-year adjusted EBITDA guidance was maintained at 275 million to 295 million U.S. dollars. Management referenced the ongoing rollout of its 42-gram Ultimate protein shake line as a driver of continued volume momentum in the ready-to-drink meal replacement format, particularly within the club and mass retail channels. [22]
-
On June 22, 2026, Danone S.A. announced a binding agreement to acquire MADE Group, an Australian company specializing in ambient ready-to-drink nutritional beverages, at a total enterprise value of approximately AUD 690 million. MADE Group markets products including the JSHealth Vitamins functional nutrition drink brand across the Asia-Pacific, North American, and European retail channels. The transaction extends Danone’s adult specialized nutrition presence beyond its established medical and clinical channels into the broader performance nutrition and wellness drink segment. The agreement is subject to customary regulatory approvals in relevant markets, and Danone indicated that the acquisition aligns with its Renew Danone strategy for growth in high-protein and fortified beverage formats. [23]
Key Players in the Meal Replacement Products Market
Clinical, Pharmacy, and Metabolic Nutrition Leaders
- Abbott Laboratories
- Nestlé Health Science
- Danone S.A.
- Unilever PLC
High-Velocity RTD Protein Shake and Weight-Management Powerhouses
- Premier Nutrition Company LLC (BellRing Brands)
- The Simply Good Foods Company
- Herbalife Ltd
- Glanbia plc
Plant-Based Complete-Meal and Digital-Native Innovators
- Soylent Rosa Foods Inc.
Meal Replacement Products Market - Report Scope
Table 9: Report Scope for the Meal Replacement Products Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Format; Macronutrient Profile; Distribution Channel; Primary Application; Formulation Claim |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial retail, pharmacy, direct-selling, and clinical-outpatient revenue from ready-to-drink (RTD) shakes, powdered meal mixes, nutritional meal bars, instant savory meal bowls/soups, and portion-controlled biscuits formulated with balanced macronutrients and essential micronutrients to replace one or more daily meals. Category Scope Note: Excludes unfortified post-workout protein isolates, caffeinated energy drinks, and standard confectionery bars. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Canada, Germany, Spain, Japan, and additional countries in the full report |
| Key Companies Covered | Abbott Laboratories, Herbalife Ltd, Soylent Rosa Foods Inc., Nestlé Health Science, Glanbia plc, Premier Nutrition Company LLC, The Simply Good Foods Company, Danone S.A., Unilever PLC |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up aseptic RTD unit volume and pharmacy/club channel triangulation. |
Meal Replacement Products Market - Research Methodology
Table 10: Research Methodology for the Meal Replacement Products Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with aseptic UHT beverage formulators, bariatric and GLP-1 clinical dietitians, pharmacy category buyers, and D2C subscription managers to validate protein dosing and repeat-order cadence. |
| Secondary Research | Analysis of WHO obesity fact sheets, FDA Human Foods Program 2026 deliverables, USDA FAS Retail Foods and Food Processing Ingredients Annual reports, and peer-reviewed clinical trials in Nutrients and PLOS ONE. |
| Market Sizing and Forecasting | Top-down global weight-management and adult clinical nutrition baselines reconciled against bottom-up portion-controlled meal unit sales (6.2B to 6.8B servings in 2026) and average serving prices from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight GLP-1 prescription adoption, front-of-pack sugar labeling mandates, pharmacy chain density, and commuter convenience spending across eight countries. |
| Operational Benchmark Traceability | Aseptic RTD volume, muscle-loss, and GLP-1 indicators in Tables 2, 3, and 4 trace to Abbott clinical sarcopenia benchmarks, PMC GLP-1 protein-intake guidelines, and FMI GLP-1 meal replacement baselines. |
| Data Triangulation and Validation | Revenue estimates isolate micronutrient-fortified meal replacement shakes, powders, bars, and savory bowls while strictly excluding standalone sports-protein isolates and infant formulas. |
Meal Replacement Products Market by Segments
Meal Replacement Products Market segmented by Product Format:
- Ready-to-Drink RTD Shakes and Bottles
- Powdered Drink Mixes
- Nutritional Meal Bars
- Instant Savory Meal Bowls and Soups
- Portion-Controlled Meal Biscuits and Gels
Meal Replacement Products Market segmented by Macronutrient Profile:
- High-Protein Low-Carb Formulas
- Balanced Complete Nutrition 40-30-30
- Ketogenic High-Fat Formulas
- Plant-Based 100 Percent Vegan
Meal Replacement Products Market segmented by Distribution Channel:
- Pharmacies and Drugstores
- E-Commerce and Direct Subscription
- Specialty Health and Fitness Outlets
- Supermarkets and Hypermarkets
Meal Replacement Products Market segmented by Primary Application:
- Weight Management and GLP-1 Companion Nutrition
- Adult Clinical and Bariatric Recovery
- Busy Professional On-the-Go Meals
- Athletic Conditioning and Muscle Preservation
Meal Replacement Products Market segmented by Formulation Claim:
- Low-Sugar and Glycemic-Controlled
- Gluten-Free Certified
- Lactose-Free and Dairy-Free
- Organic and Clean-Label Certified
Meal Replacement Products Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Mechanick, J. I., Butsch, W. S., & Christensen, S. M. (2026, May 14). Diabetes-Specific Formula as Meal Replacement for Individuals with Type 2 Diabetes and GLP-1 Sarcopenia Prevention. Frontiers in Endocrinology (PMC13214565).
- [2] BellRing Brands Inc. (2026, July 15). New Premier Protein Ultimate Protein Shakes Pack 42g of Protein in Every Bottle. BellRing Brands Corporate Newsroom.
- [3] Chen, X., Luo, Y., & Zhang, M. (2025, July 16). The Effectiveness of Self-Directed Meal Replacement-Assisted Intermittent Fasting in Adults. Nutrients (PMC12269234).
- [4] World Health Organization. (2026, October 7). Obesity and Overweight Global Fact Sheet and Dietary Management Thresholds. World Health Organization Geneva.
- [5] Abbott Laboratories. (2025, April 11). Favorable Demographics Propel Growth in Adult Nutrition and Muscle Preservation. Abbott Corporate Newsroom Strategy Briefs.
- [6] The Simply Good Foods Company. (2026, May 19). Quest Nutrition Unveils 45-Gram Salted Caramel Protein Milkshakes and High-Protein Snacks. Simply Good Foods Investor Releases.
- [7] Sayer, R. D., Peters, J. C., & Hill, J. O. (2025, September 22). Higher Protein Intakes Predict Leaner Body Composition in Weight Loss Registry Participants. Obesity Science and Practice (PMC12676439).
- [8] Danone S.A. (2026, September 15). Danone Positions Steenvoorde as a Leading European Medical Nutrition Site with EUR 70 Million Line. Danone Group Corporate Press Releases.
- [9] Huel Ltd. (2026, February 12). Biggest Nutrition Trends of 2026 Ranked on GLP-1 Nutrient Density and Meal Replacement. Huel US Nutritional Science Portal.
- [10] U.S. Food and Drug Administration. (2026, February 10). Human Foods Program 2026 Priority Deliverables on Front-of-Package and Healthy Labeling. U.S. Food and Drug Administration Constituent Updates.
- [11] Wang, Y., Li, H., & Zhou, K. (2025, April 11). Protein-Enriched Intermittent Meal Replacement Combined with Moderate-Intensity Training for Weight Loss. Scientific Reports (PMC11992100).
- [12] Papakonstantinou, E., Oikonomou, C., & Nychas, G. (2025, December 19). Dietary and Behavioral Strategies for Weight Loss and Lean Mass Preservation. Nutrients, 18(1), 12.
- [13] Clifton, P. M., & Condo, D. (2025, July 12). Protein, Fiber, and Exercise Narrative Review of Their Roles in Weight Maintenance. Journal of Nutritional Science (PMC12255039).
- [14] USDA Foreign Agricultural Service. (2026, March 31). Brazil Food Processing Ingredients Annual Report BR2026-0011. U.S. Department of Agriculture GAIN Database.
- [15] USDA Foreign Agricultural Service. (2026, April 6). Mexico Food Processing Ingredients Annual Report MX2026-0014. U.S. Department of Agriculture GAIN Database.
- [16] The Simply Good Foods Company. (2026, January 15). Atkins High Protein Strong Shakes and GLP-1 Weight Management Portfolio Update. Simply Good Foods Corporate Releases.
- [17] Glanbia plc. (2026, February 24). Glanbia Full Year 2025 Results and 2026 Performance and Health Nutrition Outlook. Glanbia Corporate Financial Releases.
- [18] USDA Foreign Agricultural Service. (2025, December 30). Canada Retail Foods Annual Report on Health and Convenience Grocery Channels. U.S. Department of Agriculture GAIN Database.
- [19] Sanchez-Sanchez, E., Diaz-Jimenez, J., & Garcia-Garcia, A. (2026, July 29). Use of a Hypercaloric and Hyperprotein Supplement Enriched with Immunonutrients in Malnourished Patients. PLOS ONE, 21(7), e0353933.
- [20] USDA Foreign Agricultural Service. (2025, November 19). Spain Retail Foods Annual Report on Modern Grocery and Convenience Store Openings. U.S. Department of Agriculture GAIN Database.
- [21] USDA Foreign Agricultural Service. (2026, September 28). Japan Retail Foods Annual Report JA2026-0056 on Convenience and Health Retail. U.S. Department of Agriculture GAIN Database.
- [22] BellRing Brands Inc. (2026, August 4). BellRing Brands Reports Results for the Third Quarter of Fiscal Year 2026. BellRing Brands Investor Relations.
- [23] Danone S.A. (2026, June 21). Danone to Acquire MADE Group to Expand High-Protein and Functional Nutrition in Asia-Pacific. Danone Group Corporate Press Releases.
- [24] Herbalife Ltd. (2026, May 8). Herbalife Expands Personalized Performance and Formula 1 Meal Replacement Nutrition Platform. Herbalife Investor Relations Press Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the meal replacement products market in 2026 and what is forecast for 2036?
- Which GLP-1 muscle-preservation and commuter convenience factors support demand for meal replacement products?
- Why do Ready-to-Drink RTD Shakes and Bottles lead the product format category?
- Why do High-Protein Low-Carb Formulas lead the macronutrient profile category globally?
- How do national growth rates compare across Brazil, Mexico, and the United States?
- Which leading companies supply clinical pharmacy shakes versus club-store RTD protein brands today?
- What limits aseptic RTD co-packing capacity or causes sweet-shake taste fatigue in the meal replacement products market?
- What should nutrition brands evaluate before launching GLP-1 companion shakes and savory meal bowls?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Ready-to-Drink RTD Shakes and Bottles
- Powdered Drink Mixes
- Nutritional Meal Bars
- Instant Savory Meal Bowls and Soups
- Portion-Controlled Meal Biscuits and Gels
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By Macronutrient Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Macronutrient Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Macronutrient Profile, 2026 to 2036
- High-Protein Low-Carb Formulas
- Balanced Complete Nutrition 40-30-30
- Ketogenic High-Fat Formulas
- Plant-Based 100 Percent Vegan
- Y-o-Y Growth Trend Analysis By Macronutrient Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Macronutrient Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Pharmacies and Drugstores
- E-Commerce and Direct Subscription
- Specialty Health and Fitness Outlets
- Supermarkets and Hypermarkets
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Primary Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Primary Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Primary Application, 2026 to 2036
- Weight Management and GLP-1 Companion Nutrition
- Adult Clinical and Bariatric Recovery
- Busy Professional On-the-Go Meals
- Athletic Conditioning and Muscle Preservation
- Y-o-Y Growth Trend Analysis By Primary Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Primary Application, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Claim, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Claim, 2026 to 2036
- Low-Sugar and Glycemic-Controlled
- Gluten-Free Certified
- Lactose-Free and Dairy-Free
- Organic and Clean-Label Certified
- Y-o-Y Growth Trend Analysis By Formulation Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Format
- By Macronutrient Profile
- By Distribution Channel
- By Primary Application
- By Formulation Claim
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Abbott Laboratories
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Herbalife Ltd
- Soylent Rosa Foods Inc.
- Nestlé Health Science
- Glanbia plc
- Premier Nutrition Company LLC
- The Simply Good Foods Company
- Danone S.A.
- Unilever PLC
- Premier Nutrition Company LLC (BellRing Brands)
- Abbott Laboratories
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Macronutrient Profile, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Primary Application, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Formulation Claim, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Format
- Figure 6: Global Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Macronutrient Profile
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Primary Application
- Figure 15: Global Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Formulation Claim
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Format
- Figure 32: North America Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Macronutrient Profile
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Primary Application
- Figure 41: North America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Formulation Claim
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Format
- Figure 48: Latin America Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Macronutrient Profile
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Primary Application
- Figure 57: Latin America Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Formulation Claim
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Format
- Figure 64: Western Europe Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Macronutrient Profile
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Primary Application
- Figure 73: Western Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Formulation Claim
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Format
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Macronutrient Profile
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Primary Application
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Formulation Claim
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Format
- Figure 96: East Asia Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Macronutrient Profile
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Primary Application
- Figure 105: East Asia Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Formulation Claim
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Format
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Macronutrient Profile
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Primary Application
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Formulation Claim
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Format
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Macronutrient Profile, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Macronutrient Profile, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Macronutrient Profile
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Primary Application, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Primary Application, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Primary Application
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Formulation Claim, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Formulation Claim, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Formulation Claim
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Meal Replacement Products Market in 2026, and what is forecast for 2036?
FMI estimates that global meal replacement products demand stood at USD 13.8 billion in 2025 and reached USD 14.8 billion in 2026. Overall industry valuation is on track to hit USD 29.7 billion by 2036 as GLP-1 patients, seniors, and commuters adopt high-protein complete meals.
What is the CAGR for the Meal Replacement Products Market from 2026 to 2036?
The meal replacement products sector is projected to expand at a 7.2% CAGR over the 2026 to 2036 window, adding USD 14.9 billion across RTD shakes and savory meal bowls.
Which product format segment leads the Meal Replacement Products Market?
Ready-to-Drink RTD Shakes and Bottles hold 48.0% of product format demand in 2026 since aseptic portion-controlled bottles deliver 30 to 45 grams of protein with zero preparation.
Which macronutrient profile segment leads the Meal Replacement Products Market?
High-Protein Low-Carb Formulas represent 52.0% of the macronutrient profile category in 2026 given their role in preserving lean muscle mass while minimizing net carbohydrates.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at an 8.4% CAGR through 2036, driven by pharmacy chain expansion and direct-selling nutrition clubs.
Who are the key players in the market?
Abbott Laboratories, Herbalife Nutrition Ltd, and Huel Ltd lead commercial meal-replacement supply. Soylent Rosa Foods Inc. and Nestlé Health Science also hold key share with Glanbia plc. Premier Nutrition Company LLC, Simply Good Foods, and Danone S.A. join Unilever PLC in the roster.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
