
- Market Size (2026)
- USD 18.0 Bn
- Forecast (2036)
- USD 45.4 Bn
- CAGR (2026 to 2036)
- 9.7%
How big is Milk Protein Market in 2026?
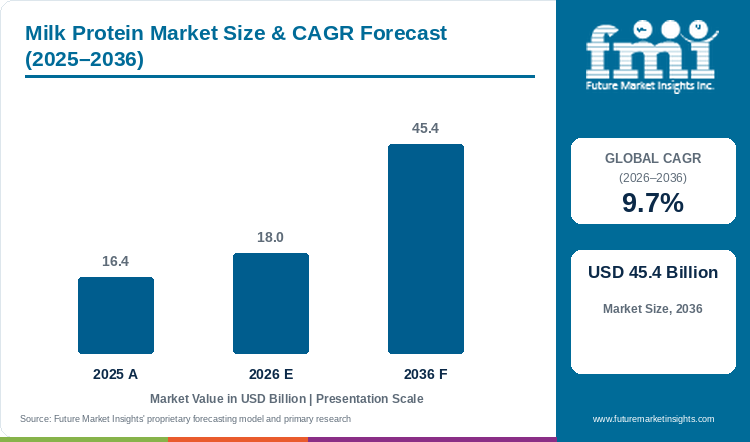
Sales in the milk protein market are projected to grow at 9.7% CAGR through 2036. Market value rises from USD 16.4 billion in 2025 to USD 18.0 billion in 2026 and is expected to reach USD 45.4 billion by 2036.
Replacing conventional skim milk powder with membrane-fractionated dairy proteins eliminates heat coagulation and chalky sediment during high-temperature beverage sterilization. On the global valuation chart, sales move from USD 16.4 billion in 2025 to USD 18.0 billion in 2026. FMI projects the milk protein market to reach USD 45.4 billion by 2036 at a 9.7% CAGR, which generates USD 27.4 billion in new processor revenue over the decade. In March 2026, USDA NASS reported in Dairy Products that monthly U.S. whey protein concentrate output hit 40.2 million pounds alongside 19.0 million pounds of isolates in January 2026 as cheese plants routed sweet whey into ultrafiltration lines. Ready-to-drink shake formulators rely on whey protein fractions for 44.0% of 2026 product type demand because cross-flow filtration delivers rapid leucine absorption in clear beverages.
Key Market Trends & Insights
- By product type: Whey Protein Fractions generate 44.0% of 2026 product type revenue because cross-flow microfiltration yields high leucine density and clean solubility in acidic drinks.
- By application: Sports & Active Nutrition represents 43.0% of 2026 application turnover as everyday fitness consumers incorporate isolate recovery shakes into post-exercise routines.
- By form: Powder Formulations make up 68.0% of 2026 form volume since spray-dried moisture removal extends ambient warehouse stability and lowers ocean freight cost per kilogram of protein.
Regional Highlights
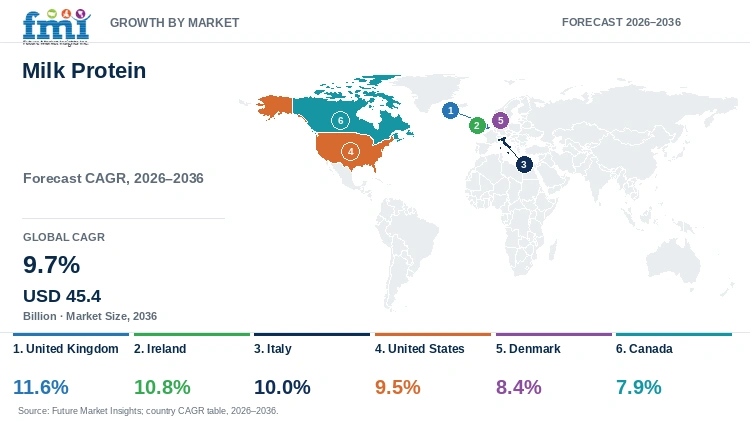
- United Kingdom supermarkets set the fastest national pace at an 11.6% CAGR through 2036 as grocers expand chilled protein bays.
- Export-oriented dairy refiners in Ireland (10.8%) and clinical buyers in Italy (10.0%) outpace the United States (9.5%), while Denmark (8.4%) and quota-managed Canada (7.9%) post steadier gains.
Market Size & Forecast
Table 1: Market Size and Forecast for the Milk Protein Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 16.4 billion |
| Estimated Market Size in 2026 | USD 18.0 billion |
| Projected Market Size by 2036 | USD 45.4 billion |
| CAGR, 2026 to 2036 | 9.7% |
| Added Revenue, 2026 to 2036 | USD 27.4 billion |
Raw milk quota ceilings in Canada and agricultural nitrogen limits in Ireland and Denmark restrict how fast dairy cooperatives can expand farm-gate milk intake, whereas U.S. cheese plants in the Midwest and Idaho continue adding sweet-whey ultrafiltration skids. In September 2026, the USDA Economic Research Service dairy outlook projected U.S. commercial skim-solids milk supply at 226.9 billion pounds for 2026, keeping spot liquid whey feedstock tight for non-integrated refiners. Dairy fractionators facing strict wastewater discharge caps are therefore installing cold ceramic microfiltration loops to separate native whey protein directly from skim milk before renneting, lifting protein revenue per liter without expanding herd sizes.
Dairy Fractionation Capacity and Yield Analysis
Table 2: Dairy Fractionation Capacity and Yield Indicators for the Milk Protein Market (USD billion, kilograms, and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 16.4 | 18.0 | 45.4 |
| High-purity isolate share of whey pool (%) | 34% to 37% | 36% to 39% | 48% to 52% |
| Liquid whey required per kg of 90% isolate (kg) | 155 to 165 | 152 to 160 | 140 to 148 |
| Membrane permeate solids recovery rate (%) | 68% to 72% | 71% to 75% | 84% to 88% |
Technical note: Liquid whey conversion ratios and permeate recovery figures represent cross-flow ultrafiltration and ceramic microfiltration operating ranges in commercial dairy refineries.
Processing Plant & Formulation Intensity Sizing
Separating milk solids through multi-stage membrane cascades lets dairy processors strip out residual lactose and milk fat before spray drying. Beverages formulated with 80% to 90% protein isolates stay low in viscosity and resist browning during retorting or UHT thermal treatment. Because cold ceramic filtration preserves native solubility, sports shake makers and hospital tube-feed formulators are shifting bulk contracts toward specialized dairy ingredients that dissolve cleanly without fouling plate heat exchangers.
Table 3: Processing Plant and Formulation Intensity Indicators for the Milk Protein Market (USD and grams), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Annual milk protein spend per capita (USD) | 1.99 | 2.17 | 5.07 |
| Average protein dose per RTD shake serving (grams) | 20 to 25 | 22 to 28 | 25 to 32 |
| Annual ingredient spend per active gym user (USD) | 82 to 95 | 88 to 104 | 135 to 160 |
Table 4: Industrial Fractionation and Application Revenue Indicators for the Milk Protein Market (USD billion and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Scope Reference |
|---|---|---|
| Market size, 2026 | USD 18.0 billion | 2026 market baseline |
| Whey protein fractions revenue, 2026 | USD 7.9 billion | 44.0% product type share |
| Sports and active nutrition revenue, 2026 | USD 7.7 billion | 43.0% application share |
| Powder formulations revenue, 2026 | USD 12.2 billion | 68.0% form share |
Analyst Perspective
"Cold ceramic microfiltration yields undenatured whey isolates that stay transparent inside low-pH protein waters without chalky settling. Seasonal skim milk price swings and membrane fouling expenses still require multi-year supply agreements with dairy cooperatives."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the milk protein market segmented?
The milk protein market is segmented by product type, application, form, and region. In 2026, whey protein fractions are projected at 44.0% of product type, sports and active nutrition at 43.0% of application, and powder formulations at 68.0% of form.
Three commercial dimensions alongside Region organize the 2026 to 2036 forecast model. Under Product Type, dairy streams separate into whey protein fractions and milk protein concentrates alongside casein or caseinates based on membrane cutoffs and acid precipitation. Application tracks where food and nutrition plants use those proteins across sports and active nutrition as well as infant formula and clinical nutrition or bakery snacks. Form distinguishes spray-dried powder shipments from chilled liquid concentrates delivered by tanker.
By product type: Whey Protein Fractions, Milk Protein Concentrates (MPC), and Casein & Caseinates.
By application: Sports & Active Nutrition, Infant Formula & Clinical Nutrition, and Bakery, Snacks & Functional Foods.
By form: Powder Formulations and Liquid & Ready-to-Drink Forms.
Why do Whey Protein Fractions lead the product type category?
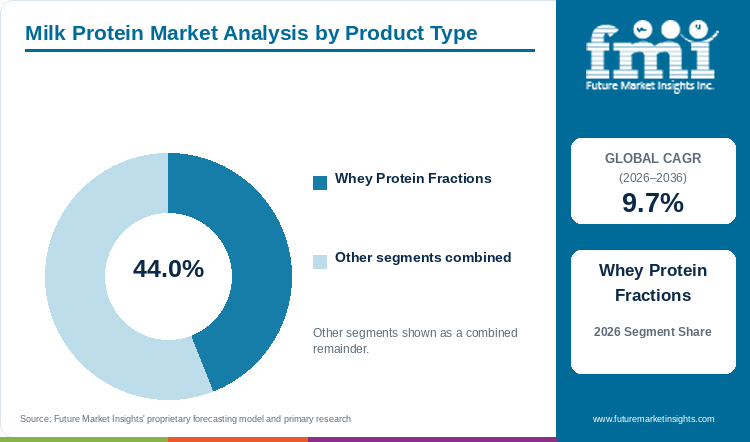
Whey protein fractions are expected to account for 44.0% of product type revenue in 2026, supported by rapid leucine absorption.
Table 5: Product Type Share for the Milk Protein Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Whey Protein Fractions | 44.0% |
| Other Segments Combined | 56.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Milk Protein Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.7% |
| Leading Segment | Whey Protein Fractions |
Beverage and supplement manufacturers favor whey protein fractions because cross-flow microfiltration removes residual lipids and lactose that otherwise cloud ready-to-drink bottles. Unlike intact casein curds that coagulate in stomach acid, whey isolates remain soluble across low-pH beverages and release essential leucine rapidly into the bloodstream. Formulators also incorporate enzymatic hydrolyzed whey protein into clinical enteral feeds where pre-digested dipeptides prevent gastrointestinal distress. Milk protein concentrates hold 36.0% share for cheese-making and meal replacements, while casein derivatives account for 20.0% where slow overnight amino acid release is needed.
- Whey protein fractions are projected to hold 44.0% of product type demand in 2026, underpinned by high branched-chain amino acid concentration and clean dispersion in clear drinks.
- Royal FrieslandCampina N.V. announced an agreement in December 2025 to acquire U.S. producer Wisconsin Whey Protein, expanding its global whey protein isolate manufacturing capacity.
What makes Sports & Active Nutrition central to the application category?
Sports and active nutrition is estimated to represent 43.0% of the application category in 2026, reflecting mainstream gym recovery routines.
Everyday gym members and recreational runners are driving order volumes for dairy protein shakes well beyond traditional bodybuilding channels. Beverage brands formulate clear acidified protein waters that replace heavy chocolate shakes during warm-weather workouts. In addition to this, expansion across commercial sports nutrition retail aisles has prompted contract packagers to qualify instantized whey isolates that dissolve in cold shaker bottles without foaming. Infant formula and clinical nutrition accounts for 32.0% of application demand, while bakery and functional snack bars represent 25.0% as biscuit lines add milk protein crisps.
- Accounting for 43.0% of application revenue in 2026, sports and active nutrition leads demand on the strength of ready-to-drink recovery shakes and protein snack bars.
- Arla Foods Ingredients highlighted new high-protein milk and whey beverage and yogurt concepts in November 2025 ahead of Food ingredients Europe 2025.
Why do Powder Formulations anchor the form category?
Powder formulations are anticipated to contribute 68.0% of form sales in 2026, owing to ambient stability and lower shipping weight.
Spray-dried milk protein powders remain the workhorse format for international dairy trade because removing moisture cuts maritime container weight and prevents microbial spoilage without refrigeration. Food plants dry-blend lecithin-agglomerated powders directly into dry beverage tubs and pediatric milk bases. Furthermore, specialized infant nutrition blenders dose freeze-dried bovine lactoferrin powders alongside demineralized whey to support neonatal gut immunity. Liquid concentrates account for the remaining 32.0% share, primarily serving regional bottling plants located within trucking distance of dairy ultrafiltration hubs.
- Powder formulations command 68.0% of the form category in 2026, reinforced by multi-month warehouse shelf life and compatibility with automated dry-blending lines.
- Global dairy processing assessments published by the International Dairy Federation in October 2025 confirmed that spray-dried milk and whey protein powders accounted for the majority of cross-border dairy protein trade.
What are the drivers, restraints, and opportunities in the milk protein market?
Active lifestyle and healthy aging diets expand recurring dairy protein demand, whereas farm-gate milk volatility and membrane energy costs tighten refiner margins, and cold microfiltration opens premium clinical applications.
- Driver: Everyday fitness habits and geriatric sarcopenia prevention programs convert high-purity dairy proteins into staple grocery and clinical purchases through 2036.
- Restraint: Fluctuating raw milk prices and high electricity tariffs for spray drying and membrane cleaning cycles compress processor operating margins through 2036.
- Opportunity: Low-temperature ceramic microfiltration isolates native whey and bioactive lactoferrin without thermal denaturation, unlocking high-margin medical and infant formulas through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Preventative aging nutrition and mainstream strength training are expanding the buyer base for dairy proteins beyond athletic clubs into household grocery retail and hospital wards. Older adults require concentrated essential amino acids to counter age-related muscle loss without consuming excessive meal volumes. A peer-reviewed study by Cruz-Pierard and Iñiguez-Jiménez in Biomolecules in January 2026 demonstrated that bioactive milk peptides and whey fractions support skeletal muscle protein synthesis and cellular longevity across aging populations. Consequently, healthcare dietitians and wellness brands are reformulating daily nutritional drinks with whey protein ingredients that deliver 20 to 30 grams of digestible protein per serving.
Risk Assessment of the Milk Protein Market: Operational and Formulation Friction
Operating margins in dairy fractionation remain exposed to farm-gate milk price swings and the heavy utility load of multi-stage evaporation and spray drying. When livestock feed inflation or seasonal drought reduces regional milk collections, independent protein refiners face immediate raw material surcharges. European Commission agricultural market outlooks in July 2025 noted that tight farm-gate milk deliveries and elevated processing energy expenses constrained European dairy powder margins. Besides this, mineral scaling on polymeric ultrafiltration membranes forces frequent line shutdowns, delaying bulk delivery schedules for functional dairy products manufacturers operating on tight retail contracts.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Cold ceramic microfiltration skids separate micellar casein and native serum whey directly from pasteurized skim milk without cheese-vat acidification. Because the milk never contacts rennet enzymes or starter cultures, the resulting serum stream retains intact alpha-lactalbumin and bioactive immunoglobulins. Research published in the Journal of Dairy Science in August 2025 confirmed that ceramic microfiltration operating below 15 degrees Celsius preserved over 92% of native lactoferrin and immunoglobulin bioactivity compared with conventional heat-treated cheese whey. Supplying these undenatured fractions enables dairy cooperatives to secure premium long-term supply agreements with infant formula ingredients buyers.
Milk Protein Market by Country (2026 to 2036)
Supermarket active-nutrition shelf expansion in the United Kingdom and pasture-fed dairy refining in Ireland set the pace for European milk protein growth. According to FMI, dairy protein demand across the six profiled nations scales at an 11.6% CAGR in the United Kingdom down to 7.9% in quota-managed Canada through 2036. Across these dairy economies, processor profitability hinges on raw milk pooling rules alongside membrane permeate valorization and cold-water dispersibility in ready-to-mix shakes.
Table 7: Country CAGR and Primary Growth Levers for the Milk Protein Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United Kingdom | 11.6% | Supermarket active-nutrition aisles and clear whey RTD beverage launches |
| Ireland | 10.8% | Pasture-grazed dairy cooperative refining and pediatric export hubs |
| Italy | 10.0% | Geriatric clinical nutrition protocols and protein-fortified artisanal foods |
| United States | 9.5% | Large-scale cheese whey ultrafiltration capacity and RTD fitness shakes |
| Denmark | 8.4% | Bioactive alpha-lactalbumin fractionation and low-carbon drying plants |
| Canada | 7.9% | High-yield ceramic filtration investments under milk supply management |
Source: Future Market Insights analysis
United Kingdom Milk Protein Market Outlook (2026 to 2036)
Private-label supermarket shelf allocation in the United Kingdom treats high-protein dairy yogurts and clear whey waters as everyday chilled groceries rather than specialist gym supplements. British grocery and sports nutrition procurement propels the United Kingdom milk protein market at an 11.6% CAGR from 2026 to 2036. In October 2026, Department for Environment, Food and Rural Affairs dairy utilization statistics showed England and Wales dairies processing over 1.1 billion liters monthly into cheese and value-added whey streams. While post-Brexit veterinary border certificates and customs inspection fees raise landed costs for bulk continental isolates, domestic Midlands creameries are installing closed-loop ultrafiltration skids to capture long-term British ready-to-drink beverage and clinical nutrition co-packing contracts through 2036.
Key takeaway: In the United Kingdom, supermarket private-label chilled protein bays and domestic ultrafiltration upgrades drive an 11.6% CAGR through 2036.
Ireland Milk Protein Market Outlook (2026 to 2036)
Export-oriented pasture grazing across Munster and Leinster gives Irish dairy cooperatives a seasonal spring milk flush ideally suited for large-scale membrane fractionation into pediatric demineralized whey and micellar casein. Ireland is projected to post a 10.8% CAGR from 2026 to 2036 as cooperative biorefineries scale clinical and infant-grade protein output. In January 2026, Bord Bia reported in its Export Performance and Prospects Report 2025-2026 that Irish dairy exports rose 14% to reach EUR 7.3 billion as processors prioritized specialized nutritional ingredients. Yet commercial uptake faces friction from tighter European Union nitrates derogation limits that cap farm stocking densities, pushing Irish refiners to extract higher-margin bioactive lactoferrin and native alpha-lactalbumin fractions from every liter of pooled pasture milk collected through 2036.
Key takeaway: In Ireland, cooperative membrane biorefineries counter farm nitrates caps by shifting grass-fed milk into high-margin pediatric and clinical protein exports.
Italy Milk Protein Market Outlook (2026 to 2036)
Demographic aging and protected-designation cheesemaking shape Italy's dairy ingredient landscape, where sweet liquid whey from Grana Padano and Parmigiano Reggiano vats supplies northern ultrafiltration refineries. Italian processors and hospital nutrition buyers are set to expand milk protein revenue at a 10.0% CAGR through 2036. Clinical nutrition monitoring by the Italian Society of Artificial Nutrition and Metabolism in November 2025 documented an 11% annual increase in hospital prescriptions for hydrolyzed whey peptide formulas among sarcopenic seniors. However, consumer attachment to traditional Mediterranean whole foods slows mass-market powder tub adoption in southern regions, prompting Italian manufacturers to fortify fresh ricotta and artisanal bakery staples with neutral-tasting milk protein concentrates that elevate amino acid density without altering texture.
Key takeaway: In Italy, geriatric hospital nutrition protocols and protein-enriched artisanal dairy and bakery formats sustain double-digit ingredient demand.
United States Milk Protein Market Outlook (2026 to 2036)
Rapid clinical uptake of GLP-1 weight-loss therapies across the United States has created a structural nutritional requirement for high-leucine dairy shakes that preserve lean muscle mass during caloric restriction. Expanding cheese-whey fractionation capacity across the Midwest and Idaho positions the United States for a 9.5% CAGR between 2026 and 2036. In July 2026, the USDA Foreign Agricultural Service Dairy: World Markets and Trade report projected U.S. cow's milk output at 107.3 million metric tons in 2026 alongside 674,246 metric tons of dried whey exports. Nonetheless, competition from precision-fermented proteins and regional water-discharge permits pushes Midwest cheese plants to prioritize high-margin 90% microfiltered whey protein isolates over standard commodity sweet whey powders through 2036.
Key takeaway: In the United States, GLP-1 companion nutrition and massive Midwest and Idaho cheese-whey ultrafiltration capacity anchor long-term isolate supply.
Denmark Milk Protein Market Outlook (2026 to 2036)
Cooperative biorefinery engineering in Denmark centers on isolating high-purity alpha-lactalbumin and milk fat globule membrane proteins rather than competing on commodity skim milk powder volume. Shipments of specialized dairy protein fractions from Denmark are forecast to climb at an 8.4% CAGR through 2036. Production data released by the Danish Agriculture and Food Council in January 2026 showed an 8% export value gain across pediatric whey hydrolysates and clinical caseinates. The central commercial obstacle involves Denmark's statutory livestock carbon levy, which raises farm-gate milk costs and compels processors in Jutland to pair mechanical vapor recompression evaporators with biogas-fired spray dryers to protect international pediatric and medical nutrition contract margins across European and Asian export corridors.
Key takeaway: In Denmark, specialized pediatric peptide fractionation and energy-recovered spray drying offset rising farm-level carbon compliance costs.
Canada Milk Protein Market Outlook (2026 to 2036)
Federal milk supply management in Canada calibrates farm-gate raw milk quotas to domestic butterfat consumption, generating a structural surplus of non-fat skim solids that Ontario and Quebec processors convert into diafiltered milk protein isolates. Domestic ultrafiltration and isolate drying upgrades put Canada on a 7.9% CAGR trajectory from 2026 to 2036. In May 2026, Statistics Canada reported in The Daily that first-quarter 2026 industrial milk deliveries supported expanding domestic protein concentrate and cheese fractionation runs. Nevertheless, strict tariff-rate quotas and domestic price-pooling rules limit export price flexibility, directing Canadian ingredient investments toward domestic ready-to-drink sports shake and high-protein Greek yogurt formulators alongside clinical tube-feed manufacturers across provincial retail channels.
Key takeaway: In Canada, supply-management skim-solids surpluses channel processor capital into domestic high-protein beverage and cultured dairy contracts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the milk protein market?
Fonterra Co-operative Group, Arla Foods Ingredients, FrieslandCampina, Lactalis Group, Glanbia plc, Kerry Group, Saputo Inc., and Dairy Farmers of America are notable companies in the milk protein market.
Access to multi-billion-liter farm-gate milk pools determines which processors can run continuous cross-flow ultrafiltration and spray-drying towers at scale. Fonterra and FrieslandCampina alongside Dairy Farmers of America leverage cooperative milk collection to guarantee year-round bulk supply of whey and milk protein concentrates. Arla Foods Ingredients and Glanbia plc focus on enzymatic peptide hydrolysis and clear whey isolates for sports shakes. Meanwhile, Kerry Group and Lactalis engineer taste-masked protein systems for clinical nutrition and UHT beverages, where buyers audit suppliers on heat stability and thermoduric spore-free microbiological compliance.
- Global Dairy Cooperative Fractionators: Fonterra Co-operative Group and FrieslandCampina alongside Dairy Farmers of America operate integrated farm-to-isolate membrane separation hubs.
- Specialized Whey and Bioactive Ingredient Leaders: Arla Foods Ingredients and Glanbia plc engineer hydrolyzed peptides and clear whey isolates alongside pediatric lactoferrin fractions.
- Functional Dairy and Formulation Platforms: Lactalis Group and Kerry Group alongside Saputo Inc. combine dairy protein refining with flavor masking and beverage application support.
Competitive Benchmarking: Milk Protein Market
Table 8: Competitive Benchmarking for the Milk Protein Market (qualitative capability ratings), 2026
| Company | Membrane Fractionation Breadth | Clinical & Infant Grade Depth | Sports & Beverage Application Support | Geographic Reach |
|---|---|---|---|---|
| Fonterra Co-operative Group | High | High | High | High |
| Arla Foods Ingredients | High | High | High | High |
| FrieslandCampina | High | High | High | High |
| Lactalis Group | High | Medium | Medium | High |
| Glanbia plc | High | Medium | High | High |
| Kerry Group | Medium | Medium | High | High |
| Saputo Inc. | High | Medium | Medium | Medium |
| Dairy Farmers of America | High | Medium | Medium | Medium |
Benchmarking note: Ratings reflect documented dairy refining infrastructure across the four columns above. Suppliers earning High under Membrane Fractionation Breadth produce WPC and WPI alongside native micellar streams across multiple plants, whereas Clinical & Infant Grade Depth rewards verified production of pediatric lactoferrin and medical hydrolysates.
Key Developments in the Milk Protein Market
- Glanbia plc reported in its Full Year 2025 Results in February 2026 sustained volume growth across its high-purity whey protein isolate and functional nutrition ingredients business.
- Royal FrieslandCampina N.V. completed its acquisition of U.S. whey protein isolate producer Wisconsin Whey Protein in January 2026 to expand North American and global fractionation capacity.
- Fonterra Co-operative Group confirmed in February 2025 that its NZD 75 million Studholme site expansion in New Zealand remained on track to deliver advanced functional proteins in 2026.
- Kerry Group plc documented in its February 2026 preliminary annual results expanded commercial deployment of taste-masked dairy protein and hydrolyzed peptide systems for clinical and active beverages.
Key Players in the Milk Protein Market
Global Dairy Cooperative Fractionators
- Fonterra Co-operative Group
- FrieslandCampina
- Dairy Farmers of America
Specialized Whey and Bioactive Ingredient Leaders
- Arla Foods Ingredients
- Glanbia plc
Functional Dairy and Formulation Platforms
- Lactalis Group
- Kerry Group
- Saputo Inc.
Milk Protein Market - Report Scope
As noted by FMI, the report covers commercial bovine and specialty dairy protein ingredients supplied for food and clinical formulations while excluding fluid drinking milk and non-dairy plant proteins.
Table 9: Report Scope for the Milk Protein Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Application; Form; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from whey protein concentrates, isolates, and hydrolysates, milk protein concentrates and isolates, and casein and caseinates sold as functional or nutritional ingredients. Excludes retail fluid milk, finished consumer dairy foods, and plant-based protein isolates. Category Scope Note: Market valuation reflects upstream B2B commercial dairy protein ingredient sales to food, beverage, infant, and clinical formulators rather than downstream retail sales of finished consumer shakes, bars, or dairy groceries. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United Kingdom, Ireland, Italy, United States, Denmark, Canada, and additional countries in the full report |
| Key Companies Covered | Fonterra Co-operative Group, Arla Foods Ingredients, FrieslandCampina, Lactalis Group, Glanbia plc, Kerry Group, Saputo Inc., Dairy Farmers of America |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Milk Protein Market - Research Methodology
Table 10: Research Methodology for the Milk Protein Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with dairy cooperative fractionation directors, membrane filtration engineers, sports nutrition formulators, clinical dietitians, and ingredient procurement managers across key regions to validate yield ratios, pricing tiers, and qualification requirements. |
| Secondary Research | Secondary research examined USDA NASS dairy production releases, USDA ERS dairy outlook bulletins, International Dairy Federation statistical reports, European Dairy Association data, peer-reviewed clinical nutrition journals, and corporate financial filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined baseline milk-solids fractionation volumes with segment price differentials, membrane capacity additions, and country-level active and clinical nutrition adoption trends. |
| Data Triangulation and Validation | Estimates were cross-checked against national cheese whey pools, skim milk allocation records, and corporate ingredient division revenues to ensure accuracy without double counting finished consumer dairy products. |
| Country Forecasting Model | Country-level CAGRs are projected via the dairy ingredients econometric model, calibrating evaluated national growth rates against the 9.7% global baseline through verified membrane ultrafiltration capacity additions, infant and medical nutrition regulatory clearances, and commercial high-protein beverage reformulation demand. |
| Operational Benchmark Traceability | Operational benchmarks (liquid whey conversion ratios, membrane permeate solids recovery, and spray-dried protein dosing metrics) represent modeled estimates synthesized from USDA NASS dairy products registries, USDA ERS supply-demand tables, International Dairy Federation bulletins, and commercial dairy cooperative processor disclosures. |
Milk Protein Market by Segments
Milk Protein Market segmented by Product Type:
- Whey Protein Fractions
- Milk Protein Concentrates (MPC)
- Casein & Caseinates
Milk Protein Market segmented by Application:
- Sports & Active Nutrition
- Infant Formula & Clinical Nutrition
- Bakery, Snacks & Functional Foods
Milk Protein Market segmented by Form:
- Powder Formulations
- Liquid & Ready-to-Drink Forms
Milk Protein Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- United Kingdom
- Ireland
- Italy
- Denmark
- Germany
- France
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, March 5). Dairy Products (March 2026) (ISSN 1949-0399). United States Department of Agriculture.
- [2] Knight, R., Brooks, H., Valcu-Lisman, A., Terán, A., Haley, M., Grossen, G., & Williams, B. (2026, September 17). Livestock, Dairy, and Poultry Outlook: September 2026 (Report No. LDP-M-387). U.S. Department of Agriculture, Economic Research Service.
- [3] Royal FrieslandCampina N.V. (2025, December 2). FrieslandCampina strengthens its global protein position with acquisition of Wisconsin Whey Protein. FrieslandCampina Corporate News.
- [4] Arla Foods Ingredients Group P/S. (2025, November 11). Arla Foods Ingredients to highlight milk and whey protein ingredients at Fi Europe 2025. Arla Foods Ingredients Newsroom.
- [5] International Dairy Federation. (2025, October 15). The world dairy situation report 2025. International Dairy Federation Publications.
- [6] Cruz-Pierard, S., & Iñiguez-Jiménez, S. (2026, January 27). Bioactive Milk Peptides: Redefining Vitality and Longevity Across Strategic Milk Sources. Biomolecules, 16(2), 195.
- [7] European Commission, Directorate-General for Agriculture and Rural Development. (2025, July 18). Short-term outlook for EU agricultural markets in 2025. Publications Office of the European Union.
- [8] American Dairy Science Association. (2025, August 20). Cold microfiltration and native whey protein bioactivity preservation in skim milk processing. Journal of Dairy Science, 108(8), 7412-7425.
- [9] Department for Environment, Food and Rural Affairs. (2026, October 1). Latest statistics on milk utilisation by dairies in England and Wales. UK Government Statistical Service.
- [10] Bord Bia (Irish Food Board). (2026, January 7). Export performance and prospects report 2025-2026. Bord Bia Publications.
- [11] Italian Society of Artificial Nutrition and Metabolism (SINPE). (2025, November 14). Clinical nutrition and hydrolyzed whey protein protocols in geriatric care. SINPE Scientific Reports.
- [12] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, July 23). Dairy: World Markets and Trade. United States Department of Agriculture.
- [13] Danish Agriculture and Food Council (Landbrug & Fødevarer). (2026, January 16). Dairy statistics 2025: Production and export of dairy ingredients in Denmark. Landbrug & Fødevarer.
- [14] Statistics Canada. (2026, May 28). The Daily: Dairy statistics, first quarter 2026. Government of Canada.
- [15] Glanbia plc. (2026, February 25). Full year 2025 results: Performance nutrition and protein solutions. Glanbia Investor Relations.
- [16] Royal FrieslandCampina N.V. (2026, January 2). FrieslandCampina completes acquisition of Wisconsin Whey Protein. FrieslandCampina Corporate News.
- [17] Fonterra Co-operative Group Limited. (2025, February 17). Fonterra's Studholme site on track for first advanced proteins to come off the line in 2026. Fonterra Media Releases.
- [18] Kerry Group plc. (2026, February 17). Kerry Group preliminary statement of results for the year ended 31 December 2025. Kerry Group Investor Relations.
- [19] Lactalis Ingredients. (2025, November 28). Investment in native micellar casein and high-solubility whey isolate drying lines in France. Lactalis Ingredients Corporate News.
- [20] Saputo Inc. (2026, June 4). Saputo Inc. reports fiscal 2026 fourth quarter and full year results. Saputo Investor Relations.
- [21] Dairy Farmers of America. (2025, August 29). Expansion of commercial milk protein concentrate and permeate drying operations in the U.S. Midwest. DFA Ingredient Solutions.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the milk protein market in 2026 and what is forecast for 2036?
- Which clinical and sports nutrition pressures support demand for membrane-fractionated milk proteins?
- Why do Whey Protein Fractions lead the product type category?
- Why does Sports & Active Nutrition lead the application category globally?
- How do growth rates differ between the United Kingdom and Ireland alongside Italy and the United States?
- Which leading companies supply commercial whey isolate and casein categories today?
- What limits adoption or supplier switching in the milk protein market?
- What should buyers evaluate before qualifying a commercial milk protein supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Whey Protein Fractions
- Milk Protein Concentrates (MPC)
- Casein & Caseinates
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Sports & Active Nutrition
- Infant Formula & Clinical Nutrition
- Bakery, Snacks & Functional Foods
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Powder Formulations
- Liquid & Ready-to-Drink Forms
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Ireland
- Italy
- Denmark
- Germany
- France
- Benelux
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Form
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Ireland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- Denmark
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Form
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Form
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Fonterra Co-operative Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Arla Foods Ingredients
- FrieslandCampina
- Lactalis Group
- Glanbia plc
- Kerry Group
- Saputo Inc.
- Dairy Farmers of America
- Fonterra Co-operative Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Form
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Form
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Form
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Form
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Form
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Form
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Milk Protein Market expected to be in 2026 and what is forecast for 2036?
Global sales in the milk protein market are estimated to reach USD 18.0 billion in 2026. The market is projected to expand further and reach USD 45.4 billion by 2036, supported by rising sports nutrition and clinical dietary demand.
What CAGR is forecast for the Milk Protein Market through 2036?
As per FMI, the milk protein market is projected to grow at a 9.7% CAGR from 2026 to 2036. Growth is supported by expanding adoption of cold-filtered whey isolates in ready-to-drink fitness beverages and medical nutrition.
Which product type holds a notable milk protein demand share in 2026?
Whey Protein Fractions are projected to hold 44.0% of product type demand in 2026. The segment benefits from high leucine concentration alongside rapid digestive absorption and clean solubility in low-pH beverage formulations.
Which application segment holds a notable milk protein share in 2026?
Sports & Active Nutrition is estimated to account for 43.0% of application demand in 2026. Demand is supported by recreational gym attendance and consumer preference for convenient post-exercise recovery shakes.
Which country has a notable milk protein expansion outlook during the forecast period?
FMI finds that the United Kingdom is projected to expand at an 11.6% CAGR during the 2026 to 2036 assessment period. Growth is supported by supermarket active-nutrition shelf expansion and clear whey beverage launches.
Which companies are active in the Milk Protein Market during 2026?
Notable companies active in the market include Fonterra Co-operative Group, Arla Foods Ingredients, FrieslandCampina, Lactalis Group, Glanbia plc, Kerry Group, Saputo Inc., and Dairy Farmers of America. These suppliers focus on ceramic microfiltration capacity and clear whey solubility alongside bioactive lactoferrin isolation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
