
- Market Size (2026)
- USD 4.4 Bn
- Forecast (2036)
- USD 6.6 Bn
- CAGR (2026 to 2036)
- 4.1%
How big is Polypropylene Woven Bag and Sack Market in 2026?
The global polypropylene woven bag and sack market demonstrated steady progress from USD 4.2 billion in 2025 to USD 4.4 billion in 2026, building toward a targeted valuation of USD 6.6 billion by 2036 at a CAGR of 4.1%.
Steady orders from grain elevators and cement plants are lifting the global polypropylene woven bag and sack market from USD 4.2 billion in 2025 to USD 4.4 billion in 2026 and toward a 2036 projection of USD 6.6 billion at a 4.1% CAGR. Commodity exporters and agricultural cooperatives rely on tear-resistant woven polypropylene sacks to prevent bag bursts during humid port handling and protect stored harvests from moisture and pests. By coating type, Uncoated Breathable PP Sacks capture 45.7% of 2026 demand ahead of laminated bags because woven tape gaps let freshly harvested grain vent heat during warehouse stacking, while cement and flour packers also buy industrial paper sacks expanding at a 6.9% CAGR. That storage advantage is demonstrated in an October 2025 wheat preservation study in Scientific Reports showing that liner-fitted woven polypropylene bags cut six-month grain weight loss from 6.64% in plain sacks down to 0.93% while preserving bread-baking quality [1]. Even so, swings in propylene resin prices and strict European recycled-plastic rules still create cost hurdles for regional bag converters.
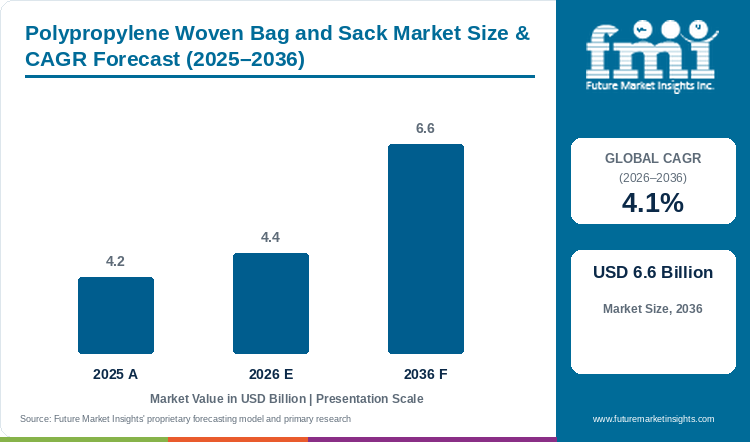
Key Market Trends & Insights
- By coating & lamination: Uncoated Breathable PP Sacks are expected to hold a 45.7% share in 2026, driven by natural airflow requirements for harvested grain and seed.
- By sack construction: Pinch & Block-Bottom Sacks are estimated to command a 54.9% share in 2026, owing to self-standing valve filling and stable interlocking pallet loads.
- By load capacity: 20 to 50 kg formats are projected to account for a 63.9% share in 2026, supported by international manual and semi-automated port handling standards.
- By end-use industry: Agriculture Grain & Feed is predicted to record a 47.3% share in 2026, reinforced by expanding rice and animal feed bagging in emerging markets.
- By order & barrier: Enterprise Standard-Barrier Supply is anticipated to capture a 62.7% share in 2026, enabled by multi-year procurement contracts from multinational milling and cement groups.
Regional Highlights
- Top national expansion: Vietnam is projected to lead national growth at a 5.3% CAGR through 2036, supported by export rice milling and compound aquaculture feed bagging.
- Broader country progression: Brazil is forecast to expand at a 5.1% CAGR ahead of India at 5.0% and Mexico at 4.8%, while China registers 4.4% and the USA reaches 3.7%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Polypropylene Woven Bag and Sack Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.2 billion |
| Estimated Market Size in 2026 | USD 4.4 billion |
| Projected Market Size by 2036 | USD 6.6 billion |
| CAGR, 2026 to 2036 | 4.1% |
| Added Revenue, 2026 to 2036 | USD 2.2 billion |
Agricultural cooperatives, pet food processors, and cement manufacturers require puncture-resistant sacks that survive drops from truck beds while preventing mite and moisture ingress. To capture the USD 2.2 billion expansion between 2026 and 2036, circular-loom converters are pairing high-speed BOPP lamination and hot-air valve sealing with flexible intermediate bulk containers for bulk-to-retail bagging lines. In August 2026, UFlex Limited commissioned its first overseas woven polypropylene bags plant in Altamira, Mexico across a 10-hectare site with an annual capacity of 80 million bags featuring mite-preventive laser venting and hot-air sealing [2].
Circular-Loom Raffia Tonnage and Woven Sack Shipment Sizing
Table 2: Raffia Tonnage and Woven Sack Shipment Sizing for the Polypropylene Woven Bag and Sack Market (USD billion and operational units), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.2 | 4.4 | 6.6 |
| Woven polypropylene resin & raffia fabric consumed (million metric tons) | 2.4 to 2.6 | 2.5 to 2.7 | 3.6 to 3.9 |
| Finished woven PP bags & valve sacks shipped (billion units) | 26.5 to 28.5 | 27.8 to 29.8 | 40.5 to 43.8 |
| Active circular-loom converting & lamination plants (facilities) | 1,850 to 1,980 | 1,910 to 2,040 | 2,420 to 2,600 |
Operational note: Shipment ranges reflect finished 5 kg to above 50 kg woven polypropylene open-mouth and block-bottom valve sacks, excluding non-woven shopping totes and flexible film pouches.
Industrial bagging plant engineers evaluate woven sack suppliers on tape tensile denier, valve self-sealing speed on rotary spouts, and coefficient of friction on stacked export pallets. Brick-shaped block-bottom valve sacks stack 20% higher in shipping containers than pillow-shaped bags and run near industrial bulk bags in automated warehouse palletizers.
Per Capita & Industrial Bagging Line Procurement Sizing
Table 3: Per Capita and Bagging Line Procurement Indicators for the Polypropylene Woven Bag and Sack Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 512.2 | 530.1 | 733.3 |
| Annual woven sack spend per active converting/bagging account (USD) | 118,000 to 126,000 | 121,000 to 130,000 | 148,000 to 160,000 |
| BOPP-laminated & extrusion-coated sack share (%) | 52.0% to 54.0% | 53.5% to 55.5% | 61.0% to 64.0% |
Table 4: Segment & Industry Allocation Indicators for the Polypropylene Woven Bag and Sack Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 4.4 billion | FMI baseline commercial polypropylene woven sack valuation |
| Uncoated breathable woven PP allocation, 2026 | USD 2.0 billion | 45.7% coating and lamination share in 2026 |
| Pinch-bottom & block-bottom valve allocation, 2026 | USD 2.4 billion | 54.9% sack construction share in 2026 |
| Agriculture grain, sugar, flour & feed allocation, 2026 | USD 2.1 billion | 47.3% end-use industry share in 2026 |
Preventing moisture clumping in Portland cement and hygroscopic urea fertilizer while allowing trapped air to escape during high-speed spout filling remains the core technical challenge for sack converters. Producers of commercial woven bags use micro-laser perforations across PP/PE extrusion coatings so bags fill at 2,400 sacks per hour without dust blowback.
Analyst Perspective
"Commodity millers, cement producers, and pet food brands are shifting from stitched pillow sacks to welded pinch-bottom and block-bottom woven polypropylene formats. Converters win multi-year enterprise supply agreements when they combine rotogravure BOPP shelf graphics with laser micro-venting and verified recycled polypropylene tape strength."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the polypropylene woven bag and sack market segmented?
The polypropylene woven bag and sack market is segmented across five core axes covering coating and lamination and sack construction as well as load capacity, end-use industry, and order and barrier tier. In 2026, Uncoated Breathable PP Sacks are projected at 45.7% and Pinch & Block-Bottom Sacks at 54.9%. The 20 to 50 kg tier holds 63.9% and Agriculture Grain & Feed records 47.3%, while Enterprise Standard-Barrier Supply accounts for 62.7%.
By coating & lamination: Uncoated Breathable PP Sacks, Extrusion-Coated & BOPP Sacks, and Kraft-Laminated Hybrid Sacks.
By sack construction: Pinch & Block-Bottom Sacks, Open-Mouth Gusseted Sacks, and Sewn Valve Sacks.
By load capacity: 20 to 50 kg heavy-duty commodity sacks, 5 to 20 kg retail packs, and Above 50 kg bulk sacks.
By end-use industry: Agriculture Grain & Feed in addition to Building & Construction Cement and Chemicals, Fertilizers & Resins.
By order & barrier: Enterprise Standard-Barrier Supply, Regional High-Barrier Orders, and Custom Breathable Batches.
Why do Uncoated Breathable PP Sacks lead the coating and lamination category?
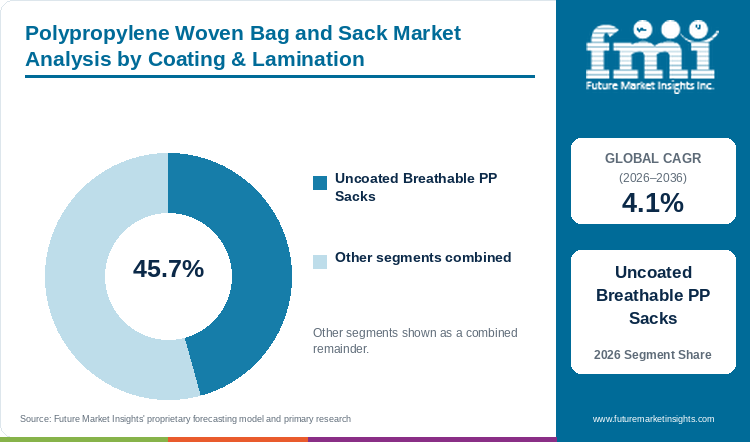
Uncoated Breathable PP Sacks are expected to hold a 45.7% share in 2026, driven by low converting cost and steady air circulation for agricultural harvests.
Table 5: Coating & Lamination Share for the Polypropylene Woven Bag and Sack Market (percentage share), 2026
| Coating & Lamination | Share (2026) |
|---|---|
| Uncoated Breathable PP Sacks | 45.7% |
| Other Segments Combined | 54.3%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Coating & Lamination Leadership and Market Growth for the Polypropylene Woven Bag and Sack Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.1% |
| Leading Segment | Uncoated Breathable PP Sacks |
Uncoated breathable woven polypropylene sacks lead volume demand because freshly threshed paddy, wheat, and pulses require continuous vapor exchange through the weave interstices to prevent fungal heating. Meanwhile, Extrusion-Coated & BOPP Sacks and Kraft-Laminated Hybrid Sacks capture moisture-sensitive cement and premium pet food orders near heavy-duty jumbo bags.
- Uncoated Breathable PP Sacks are projected to capture 45.7% of coating and lamination demand in 2026 because unlaminated circular-loom fabric minimizes tare weight and allows reuse across rural grain depots.
- In March 2026, a Scientific Reports trial on conventional and zinc-biofortified wheat storage confirmed that woven polypropylene bags paired with hermetic inner liners maintain seed germination and protein integrity across seasonal warehouse cycles [3].
Why do Pinch & Block-Bottom Sacks define the largest sack construction segment?
Pinch & Block-Bottom Sacks are estimated to hold a 54.9% share in 2026, owing to stitch-free hot-air welded closures and brick-like pallet stability.
Pinch-bottom and block-bottom valve sacks dominate industrial procurement because hot-air welded top and bottom patches eliminate needle-hole sifting of fine cement, lime, and flour powders. Open-Mouth Gusseted Sacks and Sewn Valve Sacks continue to serve regional seed and feed mills near moisture-resistant cement sacks.
- Pinch & Block-Bottom Sacks are forecast to command 54.9% of the sack construction segment in 2026 because flat rectangular ends allow 360-degree brand printing and automated robotic bag placement.
- In June 2025, a Food Science & Nutrition study demonstrated that controlled thermal processing of biaxially oriented polypropylene films preserves crystalline morphology and heat-seal strength during high-speed bag converting [4].
What keeps 20 to 50 kg ahead in the load capacity category?
The 20 to 50 kg tier is projected to account for a 63.9% share in 2026, supported by global occupational lifting rules and standard 25 kg and 50 kg commodity trading weights.
Heavy-duty 20 kg to 50 kg commodity sacks anchor global shipments because international grain boards, sugar exchanges, and cement distributors standardize trade lots around 25 kg and 50 kg unit weights. Retail 5 to 20 kg pet food and rice bags and Above 50 kg bulk sacks complement core demand across heavy-duty bags and sacks.
- The 20 to 50 kg capacity tier is estimated to hold 63.9% of load capacity demand in 2026 as 850-to-1,000-denier woven polypropylene tapes withstand 1.5-meter drop tests under full 50 kg loads.
- In November 2025, researchers in Polymers reported that biaxial stretching force fields combined with high-modulus oligomers boost polypropylene tensile modulus and tear resistance for heavy-duty synthetic packaging substrates [5].
Why does Agriculture Grain & Feed lead the end-use industry category?
Agriculture Grain & Feed is predicted to record a 47.3% share in 2026, supported by harvest storage expansion and compound livestock feed distribution.
Agricultural grain, sugar, and feed applications generate the largest industry volume because every harvest cycle requires billions of new and replacement sacks to move cereals and oilseeds from farms to mills. Cement and chemical fertilizer sectors also provide high-velocity industrial valve-sack demand across infrastructure and petrochemical hubs.
- Agriculture Grain & Feed is anticipated to represent 47.3% of end-use industry demand in 2026 because woven polypropylene sacks resist rodent and hook damage during rural transport and port stevedoring.
- In September 2025, an Insects field study in Niger verified that triple-layer hermetic storage bags with outer woven polypropylene shells achieved 100% control of millet head miner pests over seven months without chemical fumigants [6].
What gives Enterprise Standard-Barrier Supply the leading position in order and barrier tier?
Enterprise Standard-Barrier Supply is anticipated to capture a 62.7% share in 2026, reinforced by centralized annual tenders from multinational milling, sugar, and cement corporations.
High-volume enterprise contract supply paired with standard moisture and grease protection (49.7% barrier share) leads commercial procurement because national cement and flour groups lock in multi-million-bag annual schedules to guarantee line uptime. Regional High-Barrier Orders and Custom Breathable Batches serve specialty pet food, seed, and export chemical converters.
- Enterprise Standard-Barrier Supply is projected to generate 62.7% of order volume in 2026 as automated filling plants require tight dimensional tolerances and uniform roll-to-roll print registration.
- In May 2026, a Materials study showed that reinforcing recycled polypropylene composites with microcellulose fibers and biochar restores thermal stability and tensile performance for circular industrial molding and extrusion [7].
What are the drivers, restraints, and opportunities in the polypropylene woven bag and sack market?
In the polypropylene woven bag and sack market, grain harvest growth and automated block-bottom cement bagging support a 4.1% CAGR through 2036. At the same time, crude-linked polypropylene resin swings and European PPWR recycled-content compliance restrain converter margins.
- Driver: Higher grain, rice, and cement output across Asia-Pacific and Latin America drives continuous procurement of tear-resistant 25 kg and 50 kg woven polypropylene sacks.
- Restraint: Polypropylene homopolymer price volatility and strict European Union Packaging and Packaging Waste Regulation documentation and recycling mandates pressure converter operating costs.
- Opportunity: Mono-material BOPP-laminated woven polypropylene bags for premium pet food and mechanically recycled rPP industrial sacks open higher-margin retail and European industrial contracts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Record cereal and rice buffer stocks combined with expanding bagged fertilizer distribution across South Asia and Southeast Asia drive sustained baseline demand for woven polypropylene sacks. Agricultural ministries and fertilizer cooperatives specify UV-stabilized woven polypropylene outer sacks paired with inner polyethylene liners for granular fertilizer packaging to prevent caking during monsoon storage. In August 2026, the U.S. Department of Agriculture Foreign Agricultural Service reported in GAIN Report IN2026-0046 that India produced a record 154.02 million metric tons of milled rice and 55.09 million metric tons of corn in marketing year 2025/2026, requiring massive public and private bagged storage [8].
Risk Assessment of the Polypropylene Woven Bag and Sack Market: Resin Volatility and Regulatory Friction
Woven polypropylene converters operate with raw polypropylene homopolymer accounting for 60% to 70% of finished sack manufacturing cost, exposing margins to petrochemical feedstock swings. Meanwhile, industrial buyers in Europe comparing woven polypropylene against plastic and paper multiwall bags face new conformity assessment and substance documentation rules. In August 2026, Royal LC Packaging advised European industrial bag customers that the EU Packaging and Packaging Waste Regulation became applicable on August 12, 2026 and requires complete EU Declarations of Conformity ahead of 2030 recycled-content targets [9].
Commercial Opportunity Analysis: Mono-Material BOPP Pet Food Bags and High-Melt-Strength rPP Tapes
Fastest margin expansion lies in replacing multi-material polyester-laminated pet food bags with 100% polypropylene structures combining woven PP fabric, PP extrusion tie layers, and reverse-printed biaxially oriented polypropylene films. Reactive extrusion additives also allow converters to blend post-consumer recycled polypropylene into raffia tapes without tape breakage on high-speed circular looms. In May 2026, researchers in ACS Omega demonstrated that reactive extrusion of virgin and recycled polypropylene blends improves melt strength and extensional viscosity for lightweight industrial polymer processing [10].
Polypropylene Woven Bag and Sack Market by Country (2026 to 2036)
As per FMI, Vietnam is projected to lead national polypropylene woven bag and sack growth at a 5.3% CAGR between 2026 and 2036, ahead of Brazil at 5.1% and India at 5.0%.
Table 7: Country CAGR and Primary Growth Levers for the Polypropylene Woven Bag and Sack Market (CAGR percentage and operational growth driver), 2026 to 2036
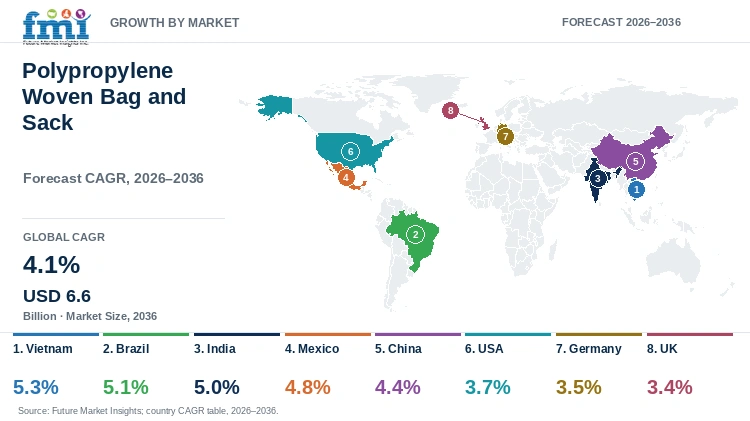
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Vietnam | 5.3% | Mekong Delta rice export bagging, aquaculture feed mills, and low-cost raffia loom exports |
| Brazil | 5.1% | Cerrado soybean seed, sugar, coffee, and imported NPK fertilizer bagging demand |
| India | 5.0% | Foodgrain procurement buffer stocks, cement capacity expansion, and urea bagging |
| Mexico | 4.8% | Nearshore BOPP-laminated pet food bag converting and North American export supply |
| China | 4.4% | High-speed block-bottom valve cement sacks and chemical resin export packaging |
| USA | 3.7% | Premium BOPP-laminated retail pet food, lawn seed, and specialty mineral sacks |
| Germany | 3.5% | PPWR-compliant mono-material rPP industrial sacks and automated chemical valve bags |
| UK | 3.4% | Plastic Packaging Tax 30% recycled-content sacks for construction aggregates and animal feed |
Source: Future Market Insights analysis
Vietnam Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Export-oriented rice milling, coffee processing, and aquaculture feed manufacturing across the Mekong Delta and Dong Nai industrial zones anchor woven polypropylene sack consumption in Vietnam. Between 2026 and 2036, the polypropylene woven bag and sack market in Vietnam is projected to expand at a 5.3% CAGR, supported by domestic circular-loom capacity serving local agribusinesses and export buyers in Japan, Europe, and North America. In February 2026, a Mycotoxin Research systematic review highlighted that replacing damp jute sacks with moisture-barrier woven polypropylene and hermetic storage bags curtails postharvest aflatoxin contamination in tropical cereal supply chains [11]. Vietnamese converters now integrate inline BOPP gravure lamination to supply 5 kg to 25 kg branded jasmine rice and shrimp-feed sacks.
Key takeaway: In Vietnam, rice export bagging and aquaculture feed production are projected to drive 5.3% CAGR through 2036.
Brazil Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Large-scale soybean seed treatment and granular fertilizer blending across Mato Grosso, São Paulo, and Paraná sustain heavy-duty woven sack demand in Brazil. From 2026 to 2036, the market in Brazil is forecast to advance at a 5.1% CAGR, reinforced by agricultural input dealers and port terminals requiring UV-stabilized 25 kg and 50 kg valve and open-mouth sacks. In April 2025, a Molecules study on biaxially oriented polypropylene film morphology confirmed that controlled isotactic polypropylene chain orientation enhances dielectric and moisture-barrier stability under high ambient humidity [12]. Regional converters in southern Brazil supply micro-perforated block-bottom sacks that withstand tropical condensation during inland truck transport. Export sugar terminals in Santos also specify high-tenacity woven outer sacks for humid port transit.
Key takeaway: In Brazil, soybean seed and fertilizer bagging volumes are forecast to sustain 5.1% CAGR through 2036.
India Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Massive public foodgrain procurement by the Food Corporation of India and rapid domestic cement and urea capacity additions make India one of the world's largest raffia converting hubs. Commercial demand in India is estimated to progress at a 5.0% CAGR between 2026 and 2036, supported by automated 50 kg block-bottom cement sack lines and export-oriented flexible and woven packaging investments. In its 37th Annual Report for FY 2025-26, UFlex Limited reported total installed packaging and polymer capacity exceeding 1.38 million metric tons per annum and 114,000 metric tons per annum of global plastic waste recycling capacity [13]. Domestic cement majors across Gujarat, Rajasthan, and Odisha are rapidly converting from stitched sacks to dust-free welded block-bottom valve bags.
Key takeaway: In India, foodgrain storage and dust-free cement valve-sack conversion are estimated to support 5.0% CAGR through 2036.
Mexico Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Nearshore manufacturing of BOPP-laminated pet food, animal nutrition, and building-material sacks for both domestic consumption and duty-free United States export propels growth across Mexico. Between 2026 and 2036, the polypropylene woven bag and sack market in Mexico is anticipated to register a 4.8% CAGR, driven by multinational pet-care brands qualifying high-speed converting plants in Tamaulipas and Nuevo León. In April 2026, the U.S. Department of Agriculture Foreign Agricultural Service reported in GAIN Report CE2026-0001 that standard 50-kilogram urea and muriate of potash woven bags remain the benchmark unit for commercial fertilizer distribution [14]. Converters in Altamira and Monterrey run 300-meter-per-minute water-based ink lamination lines to supply photorealistic pinch-bottom kibble bags.
Key takeaway: In Mexico, nearshore pet-food bag converting and North American export demand are anticipated to generate 4.8% CAGR through 2036.
China Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
High-volume petrochemical resin bagging and automated building-material packaging across Shandong, Zhejiang, and Guangdong anchor demand in China. The market in China is expected to grow at a 4.4% CAGR from 2026 to 2036, supported by domestic equipment upgrades toward ultrasonic valve sealing and lightweight high-tenacity polypropylene tapes. In August 2025, Greif, Inc. reported in its SEC Form 10-Q filing that its Customized Polymer Solutions segment supplies industrial polymer and woven packaging across global chemical and agricultural end markets [15]. Chinese converters are adopting automated visual inspection and inline weight-sorting systems across circular-loom plants to serve zero-defect chemical resin and fertilizer export contracts.Automated palletizing lines across coastal chemical parks further boost block-bottom valve sack orders.
Key takeaway: In China, chemical resin bagging and automated block-bottom converting upgrades are expected to drive 4.4% CAGR through 2036.
USA Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Premium dry pet food, turf and forage seed, and retail de-icing mineral packaging drive value growth across the USA. Between 2026 and 2036, the polypropylene woven bag and sack market in the USA is predicted to expand at a 3.7% CAGR, reinforced by brand owners replacing tear-prone multiwall paper bags with BOPP-laminated pinch-bottom woven polypropylene sacks featuring easy-open pull tabs. In February 2025, a Polymers review of polymer recycling processes highlighted that advanced mechanical and solvent-based purification methods enable post-consumer polyolefins to re-enter high-strength industrial applications [16]. North American pet food brands now specify mono-material all-polypropylene bags to align with Store Drop-Off and extended producer responsibility guidelines.
Key takeaway: In the USA, BOPP-laminated pet food and lawn-seed pinch-bottom bags are predicted to propel 3.7% CAGR through 2036.
Germany Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
Stringent conformity documentation under the EU Packaging and Packaging Waste Regulation and high automation across dry-mix mortar, chemical, and animal-feed plants shape procurement in Germany. From 2026 to 2036, the market in Germany is forecast to record a 3.5% CAGR, supported by industrial buyers specifying mechanically recycled polypropylene content and hybrid kraft-paper-laminated woven sacks. In December 2025, an iScience study demonstrated that combining polypropylene fibers with low-carbon geopolymer binders improves water stability and crack-bridging ductility in sustainable construction materials [17]. Chemical and construction-material producers across North Rhine-Westphalia and Bavaria prioritize block-bottom valve sacks engineered for dust-free high-speed impeller and air-packer lines across automated plants. Regional converters also supply anti-skid coated valve sacks for automated pallet stacking.
Key takeaway: In Germany, PPWR circularity rules and automated chemical and mortar valve bagging are forecast to support 3.5% CAGR through 2036.
UK Polypropylene Woven Bag and Sack Market Outlook (2026 to 2036)
The UK Plastic Packaging Tax charging GBP 217.85 per metric ton on plastic packaging containing less than 30% recycled plastic directly governs woven polypropylene sack specifications across the UK. Commercial demand in the UK is projected to advance at a 3.4% CAGR between 2026 and 2036, linked to builders' merchants and animal-feed mills adopting verified 30%-plus rPP woven sacks. In May 2026, a Scientific Reports investigation confirmed that incorporating 0.8% polypropylene fiber into industrial waste geopolymer mortar increases 28-day flexural and compressive performance over Portland cement controls [18]. Agricultural and construction-aggregate packers across England and Scotland rely on UV-stabilized coated woven sacks to withstand outdoor builder-yard storage.
Key takeaway: In the UK, Plastic Packaging Tax 30% rPP thresholds and outdoor aggregate bagging are projected to sustain 3.4% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the polypropylene woven bag and sack market?
Mondi plc, Conitex Sonoco, Berry Global Group, Inc., LC Packaging International B.V., Anduro Manufacturing, UFlex Limited, Emmbi Industries Limited, and Greif, Inc. anchor global woven polypropylene raffia extrusion, BOPP lamination, and industrial valve-sack manufacturing.
FMI analysis indicates that commercial competition divides between global integrated industrial bag and flexible packaging conglomerates, specialized BOPP-laminated pet food and agricultural bag converters, and vertically integrated circular-loom raffia exporters.
- Global Integrated Industrial Bag & Polymer Leaders: Mondi plc and Berry Global Group Inc. along with Greif Inc. operate multi-continent industrial sack and woven polymer packaging networks serving cement and food multinationals.
- Americas BOPP-Laminated & Specialty Sack Specialists: Conitex Sonoco and Anduro Manufacturing specialize in high-graphics BOPP-laminated pinch-bottom pet food, seed, and specialty agricultural sacks across North and Latin America.
- Vertically Integrated Raffia & Circular FIBC/WPP Exporters: LC Packaging International B.V., UFlex Limited, and Emmbi Industries Limited combine in-house tape extrusion and circular weaving with laser venting and closed-loop rPP recycling.
Competitive Benchmarking: Polypropylene Woven Bag and Sack Market
Table 8: Competitive Benchmarking for the Polypropylene Woven Bag and Sack Market (qualitative capability ratings), 2026
| Company | Circular Loom & Tape Scale | BOPP & Hybrid Barrier Depth | Enterprise Cement & Ag Access | Geographic Reach |
|---|---|---|---|---|
| Mondi plc | High | High | High | High |
| Conitex Sonoco | High | High | High | High |
| Berry Global Group, Inc. | High | High | High | High |
| LC Packaging International B.V. | High | Medium | High | High |
| Anduro Manufacturing | Medium | High | High | Medium |
| UFlex Limited | High | High | High | High |
| Emmbi Industries Limited | Medium | Medium | High | Medium |
| Greif, Inc. | High | Medium | High | High |
Scoring basis: Capability tiers evaluate high-speed circular-loom tape extrusion capacity and rotogravure BOPP lamination technology as well as enterprise cement and agricultural contract coverage and global plant footprint.
Key Developments in the Polypropylene Woven Bag and Sack Market
- Mondi plc expanded its Southeast Asian industrial bags footprint in April 2026 by forming a 60%-owned joint venture with PT Indocement Tunggal Prakarsa Tbk in West Java, Indonesia adding over 200 million bags of annual capacity [19].
- Berry Global Group, Inc. detailed in its FY2024 Form 10-K and subsequent April 2025 combination with Amcor plc its global flexible and woven polyolefin packaging operations targeting 30% circular content by 2030 [20].
- Emmbi Industries Limited completed its 31st Annual General Meeting in September 2025 approving audited FY2024-25 financial results across its Silvassa woven polymer, FIBC, and specialty barrier packaging facilities [21].
Key Players in the Polypropylene Woven Bag and Sack Market
Global Integrated Industrial Bag & Polymer Leaders
- Mondi plc
- Berry Global Group, Inc.
- Greif, Inc.
Americas BOPP-Laminated & Specialty Sack Specialists
- Conitex Sonoco
- Anduro Manufacturing
- UFlex Limited
Vertically Integrated Raffia & Circular WPP Exporters
- LC Packaging International B.V.
- Emmbi Industries Limited
Polypropylene Woven Bag and Sack Market - Report Scope
Table 9: Report Scope for the Polypropylene Woven Bag and Sack Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Coating & Lamination; Sack Construction; Load Capacity; End-Use Industry; Order & Barrier |
| Quantitative Units | USD Billion |
| Market Definition | Commercial supplier sales of circular-woven and flat-woven polypropylene open-mouth, gusseted, pinch-bottom, and block-bottom valve bags and sacks across agricultural, construction, chemical, and retail pet-food applications. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Vietnam, Brazil, India, Mexico, China, USA, Germany, UK, and additional countries in the full report |
| Key Companies Covered | Mondi plc, Conitex Sonoco, Berry Global Group, Inc., LC Packaging International B.V., Anduro Manufacturing, UFlex Limited, Emmbi Industries Limited, and Greif, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Polypropylene Woven Bag and Sack Market - Research Methodology
Table 10: Research Methodology for the Polypropylene Woven Bag and Sack Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with circular-loom raffia plant directors and BOPP lamination engineers as well as procurement heads at grain mills, cement plants, and pet-food brands. |
| Secondary Research | Analysis of corporate annual reports and SEC Form 10-K and 10-Q filings in addition to USDA Foreign Agricultural Service grain and fertilizer reports and EU PPWR compliance guides. |
| Market Sizing and Forecasting | Top-down bulk commodity bagging expenditure models reconciled against bottom-up circular-loom polypropylene tape tonnage and block-bottom welder throughput from 2026 to 2036. |
| Country Forecasting Model | Country growth rates weight cereal and rice harvest volumes, bagged cement consumption, and nearshore pet-food converting investments across eight major markets. |
| Operational Benchmark Traceability | Raffia tonnage and per-account spend indicators in Tables 2, 3, and 4 cross-check against standard 850-to-1,000-denier fabric weights and converter contract pricing. |
| Data Triangulation and Validation | Segment shares and USD billion revenue projections are audited across all five parent axes to verify 100.0% share summation and exclude non-woven carry bags. |
Polypropylene Woven Bag and Sack Market by Segments
Polypropylene Woven Bag and Sack Market segmented by Coating & Lamination:
- Uncoated Breathable PP Sacks
- Extrusion-Coated & BOPP Sacks
- Kraft-Laminated Hybrid Sacks
- Micro-Perforated Laminated Sacks
Polypropylene Woven Bag and Sack Market segmented by Sack Construction:
- Pinch & Block-Bottom Sacks
- Open-Mouth Gusseted Sacks
- Sewn Valve Sacks
Polypropylene Woven Bag and Sack Market segmented by Load Capacity:
- 20 to 50 kg
- 5 to 20 kg
- Above 50 kg
Polypropylene Woven Bag and Sack Market segmented by End-Use Industry:
- Agriculture Grain & Feed
- Construction & Cement Sacks
- Chemicals, Fertilizers & Resins
- Food Sugar & Flour
Polypropylene Woven Bag and Sack Market segmented by Order & Barrier:
- Enterprise Standard-Barrier Supply
- Regional High-Barrier Orders
- Custom Breathable Batches
- UV-Stabilized Export Lots
- Food-Grade Liner Contracts
Polypropylene Woven Bag and Sack Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Yousuf, H. M. B., Yasin, M., Rebouh, N. Y., Aldawood, A. S., Ali, U., & Rosentrater, K. A. (2025, October 6). Comparative assessment of conventional and hermetic storage facilities on wheat grain quality, pest infestation, and bread development. Scientific Reports, 15(1), 34725 (PMCID: PMC12501303; PMID: 41053191).
- [2] UFlex Limited. (2026, August 3). UFlex Commissions First Overseas WPP Bags Plant in Mexico. UFlex Limited Corporate Release.
- [3] Muazzam, M., Bakhtavar, M. A., Farooq, U., Iqbal, S., Ahmad, S., Iqbal, M., Saeed, S. Q., & Sadaf, T. (2026, March 6). Seed quality and nutritional composition of conventional and zinc biofortified wheat under hermetic and conventional storage techniques. Scientific Reports, 16(1), 12337 (PMCID: PMC13079907; PMID: 41787020).
- [4] Kivilcim, F. N. (2025, June 18). Heat Treatment Impacts on Film Morphology in Biaxially Oriented Polypropylene Films. Food Science & Nutrition, 13(6), e70458 (PMCID: PMC12174661; PMID: 40535919).
- [5] Wang, Z., Du, Q., Hong, W., Yu, G., Wang, H., Feng, Y., Chen, X., Li, H., Guo, S., & Li, C. (2025, November 5). Achieving High-Performance Polypropylene-Based Synthetic Paper with High-Modulus Organic Oligomer and Biaxial Stretching Force Field. Polymers, 17(21), 2951 (PMCID: PMC12608191; PMID: 41228711).
- [6] Dan Bawa, H. Y., Baoua, I. B., Rabé, M. M., & Baributsa, D. (2025, September 2). Hermetic Storage as a Chemical-Free Alternative for Millet Preservation in Niger. Insects, 16(9), 917 (PMCID: PMC12471198; PMID: 41009099).
- [7] Wyderkiewicz, W., Miedzianowska-Masłowska, J., Sowińska-Baranowska, A., & Masłowski, M. (2026, May 9). Recycled Polypropylene Composites Reinforced with Microcellulose Fibres and Microcellulose-Derived Biochar: Thermal, Rheological and Mechanical Performance. Materials, 19(10), 1942 (PMCID: PMC13208832; PMID: 42195581).
- [8] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, August 28). Report Name: Grain and Feed Update (India GAIN Report IN2026-0046). USDA Foreign Agricultural Service.
- [9] Royal LC Packaging. (2026, August 6). PPWR: Is Your Packaging Documentation Ready for 12 August?. LC Packaging International B.V.
- [10] Öztoksoy, M. E., Yıldız, R. B., Yıldırım, R., Oral, M. A., Özkoç, G., & Kodal, M. (2026, May 25). High Melt Strength Polypropylene via Reactive Extrusion for Injection-Molded Foams: Performance of Virgin and Recycled Blends. ACS Omega, 11(22), 32290-32309 (PMCID: PMC13261589; PMID: 42294206).
- [11] Chabite, I. T., Kussaga, J., Nyamete, F., & Suleiman, R. (2026, February 27). Current status of aflatoxin contamination and mitigation efforts in mozambique: a systematic review. Mycotoxin Research, 42(2), 29 (PMCID: PMC12948851; PMID: 41760985).
- [12] Zhang, K., Yao, J., Zhu, F., Gao, Y., Gu, Y., Guo, Y., Sun, Y., & An, Y. (2025, April 2). Recent Advances in Preparation and Application of BOPP Film for Energy Storage and Dielectric Capacitors. Molecules, 30(7), 1596 (PMCID: PMC11990598; PMID: 40286211).
- [13] UFlex Limited. (2026, July 15). Annual Report for the Year 2025-2026 (37th Annual Report). UFlex Limited.
- [14] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, April 7). Report Name: Grain and Feed Annual (Sri Lanka GAIN Report CE2026-0001). USDA Foreign Agricultural Service.
- [15] Greif, Inc. (2025, August 28). Form 10-Q Quarterly Report for the Quarterly Period Ended July 31, 2025. U.S. Securities and Exchange Commission.
- [16] Peti, D., Dobránsky, J., & Michalík, P. (2025, February 24). Recent Advances in Polymer Recycling: A Review of Chemical and Biological Processes for Sustainable Solutions. Polymers, 17(5), 603 (PMCID: PMC11902707; PMID: 40076096).
- [17] Chen, L., Wang, X., Deng, Q., & Wang, H. (2025, December 5). Study of performance variation and sustainability of low-carbon geopolymer fiber-stabilized accumulated soil. iScience, 29(1), 114354 (PMCID: PMC12800630; PMID: 41541665).
- [18] Najafitabar, F., Bilondi, M. P., & Ghaffarian, V. (2026, May 7). Polypropylene fiber-reinforced geopolymer mortar from coal washing waste and recycled glass powder: mechanical and microstructural performance. Scientific Reports, 16, 51204 (PMID: 42098327).
- [19] Mondi Group. (2026, April 16). Mondi expands paper bags business in Southeast Asia through new joint venture. Mondi plc Press Release.
- [20] Berry Global Group, Inc. (2025, January 15). Form 10-K Annual Report for the Fiscal Year Ended September 28, 2024. U.S. Securities and Exchange Commission.
- [21] Emmbi Industries Limited. (2025, September 20). Disclosure of Voting Results and Consolidated Scrutinizer Report of the 31st Annual General Meeting. Emmbi Industries Limited Corporate Filing.
- [22] Padavala, S. S. A. B., Noolu, V., Paluri, Y., Harinder, D., & Akula, U. K. (2025, February 24). Performance evaluation of concrete blended with industrial and agricultural wastes reinforced with hybrid fibres - a feasibility study. Scientific Reports, 15(1), 6662 (PMCID: PMC11850793; PMID: 39994208).
- [23] Billich, E., Hogger, E., Sumerskii, I., Sailer-Kronlachner, W., Rosenfeld, C., Duller, M., Blum, C., Potthast, A., & van Herwijnen, H. W. G. (2025, August 8). Wettability of Kraft Paper with Biobased Impregnation Resins for the Production of High-Pressure Laminates. ACS Omega, 10(32), 36115-36125 (PMCID: PMC12368696; PMID: 40852241).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the polypropylene woven bag and sack market in 2026 and what is forecast for 2036?
- Which bulk grain storage and automated cement bagging pressures support woven sack demand?
- Why do Uncoated Breathable PP Sacks lead the coating and lamination category?
- Why do Pinch & Block-Bottom Sacks remain the largest sack construction category globally?
- How do national growth rates differ between Vietnam and Brazil versus India and Mexico?
- Which leading companies manufacture circular-woven raffia sacks and BOPP-laminated bags today?
- What limits recycled polypropylene tape adoption or converter margin expansion?
- What should grain, cement, and pet-food buyers evaluate before qualifying a woven sack supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Coating & Lamination, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coating & Lamination, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coating & Lamination, 2026 to 2036
- Uncoated Breathable PP Sacks
- Extrusion-Coated & BOPP Sacks
- Kraft-Laminated Hybrid Sacks
- Micro-Perforated Laminated Sacks
- Y-o-Y Growth Trend Analysis By Coating & Lamination, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating & Lamination, 2026 to 2036
- Global Market Analysis and Forecast, By Sack Construction, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sack Construction, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sack Construction, 2026 to 2036
- Pinch & Block-Bottom Sacks
- Open-Mouth Gusseted Sacks
- Sewn Valve Sacks
- Y-o-Y Growth Trend Analysis By Sack Construction, 2021 to 2025
- Absolute $ Opportunity Analysis By Sack Construction, 2026 to 2036
- Global Market Analysis and Forecast, By Load Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Load Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Load Capacity, 2026 to 2036
- 20 to 50 kg
- 5 to 20 kg
- Above 50 kg
- Y-o-Y Growth Trend Analysis By Load Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Load Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Agriculture Grain & Feed
- Construction & Cement Sacks
- Chemicals, Fertilizers & Resins
- Food Sugar & Flour
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Order & Barrier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Order & Barrier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Order & Barrier, 2026 to 2036
- Enterprise Standard-Barrier Supply
- Regional High-Barrier Orders
- Custom Breathable Batches
- UV-Stabilized Export Lots
- Food-Grade Liner Contracts
- Y-o-Y Growth Trend Analysis By Order & Barrier, 2021 to 2025
- Absolute $ Opportunity Analysis By Order & Barrier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- By Country
- Market Attractiveness Analysis
- By Country
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Vietnam
- Pricing Analysis
- Market Share Analysis, 2025
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Coating & Lamination
- By Sack Construction
- By Load Capacity
- By End-Use Industry
- By Order & Barrier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mondi plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Conitex Sonoco
- Berry Global Group, Inc.
- LC Packaging International B.V.
- Anduro Manufacturing
- UFlex Limited
- Emmbi Industries Limited
- Greif, Inc.
- Mondi plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Coating & Lamination, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Sack Construction, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Load Capacity, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Order & Barrier, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Coating & Lamination
- Figure 6: Global Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Sack Construction
- Figure 9: Global Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Load Capacity
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Industry
- Figure 15: Global Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Order & Barrier
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Coating & Lamination
- Figure 32: North America Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Sack Construction
- Figure 35: North America Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Load Capacity
- Figure 38: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-Use Industry
- Figure 41: North America Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Order & Barrier
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Coating & Lamination
- Figure 48: Latin America Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sack Construction
- Figure 51: Latin America Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Load Capacity
- Figure 54: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 57: Latin America Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Order & Barrier
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Coating & Lamination
- Figure 64: Western Europe Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Sack Construction
- Figure 67: Western Europe Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Load Capacity
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 73: Western Europe Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Order & Barrier
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Coating & Lamination
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Sack Construction
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Load Capacity
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Order & Barrier
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Coating & Lamination
- Figure 96: East Asia Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Sack Construction
- Figure 99: East Asia Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Load Capacity
- Figure 102: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 105: East Asia Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Order & Barrier
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Coating & Lamination
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Sack Construction
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Load Capacity
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Order & Barrier
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Coating & Lamination, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Coating & Lamination, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Coating & Lamination
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Sack Construction, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Sack Construction, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Sack Construction
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Load Capacity, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Load Capacity, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Load Capacity
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Order & Barrier, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Order & Barrier, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Order & Barrier
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the polypropylene woven bag and sack market in 2026, and what is forecast for 2036?
According to FMI, the global polypropylene woven bag and sack market is estimated at USD 4.4 billion in 2026 after reaching USD 4.2 billion in 2025, and is projected to reach USD 6.6 billion by 2036.
What is the CAGR for the polypropylene woven bag and sack market from 2026 to 2036?
Future Market Insights projects a 4.1% compound annual growth rate between 2026 and 2036, generating USD 2.2 billion in incremental value across agricultural and industrial channels.
Which coating and lamination segment leads the polypropylene woven bag and sack market?
Uncoated Breathable PP Sacks are expected to hold a 45.7% share in 2026, driven by natural ventilation requirements for harvested grains and animal feed.
Which sack construction segment leads the polypropylene woven bag and sack market?
Pinch & Block-Bottom Sacks are estimated to hold a 54.9% share in 2026, owing to stitch-free hot-air welded closures and high-speed automated valve filling in cement and fertilizer plants.
Which country has a notable growth outlook during the assessment period?
Vietnam is projected to lead national expansion at a 5.3% CAGR through 2036, supported by Mekong Delta rice exports and aquaculture feed bagging.
Who are the key players in the market?
Key suppliers include Mondi plc; Conitex Sonoco; Berry Global Group, Inc.; LC Packaging International B.V.; Anduro Manufacturing; UFlex Limited; Emmbi Industries Limited; and Greif, Inc. across global industrial and agricultural channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
