
- Market Size (2026)
- USD 330.0 Bn
- Forecast (2036)
- USD 527.4 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Sheet Metal Market in 2026?
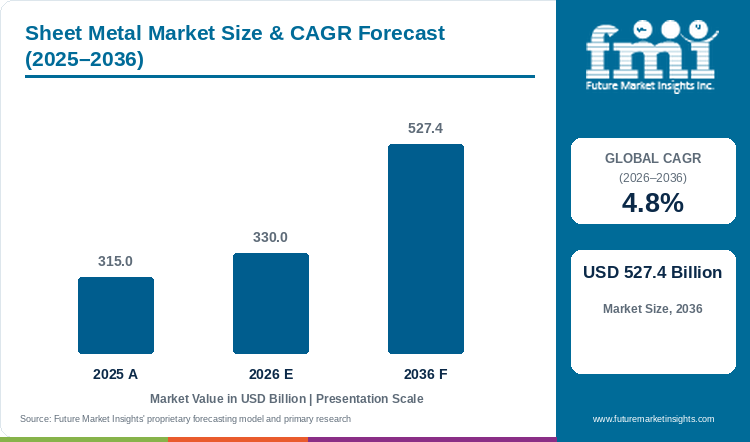
Assessed at USD 315.0 billion in 2025 and progressing to USD 330.0 billion in 2026, the sheet metal market valuation is on course to reach USD 527.4 billion by 2036, supported by a forecast-period CAGR of 4.8%.
Automotive stamping plants, commercial roofing roll-formers and electrical cabinet fabricators are migrating from heavy mild-steel plate toward precision cold-rolled, hot-dip galvanized and 5000 or 6000 series aluminum sheet coils that reduce assembly weight while meeting strict corrosion warranties. Industry analysis by FMI finds that the global sheet metal market size stood at USD 315.0 billion in 2025, reaches an estimated market valuation of USD 330.0 billion in 2026 and is projected to attain an industry valuation of USD 527.4 billion by 2036, expanding at a 4.8% CAGR from 2026 to 2036. Carbon steel and mild steel sheets hold an anticipated 56.0% share of 2026 demand ahead of galvanized, austenitic stainless and aluminum alloy sheets, given that multi-stage transfer presses rely on consistent yield strength and spot-weldability.
Broad ferrous coil volume separates the overall category from the faster-growing aluminum sheets and coils sector at 7.5% CAGR, where electric-vehicle battery closures and beverage can stock pull non-ferrous rolling capacity at a premium rate. Global flat-rolled consumption is supported by continuous primary melt output, with World Steel Association figures released in October 2026 confirming that crude steel production across 70 reporting countries reached 142.4 million metric tons in September 2026. Flat-rolled producers are committing major capital to modernize hot-strip and cold-rolling mills, evidenced in October 2026 when Nippon Steel Corporation announced that the U.S. Steel board approved nearly USD 3.0 billion for a new hot-strip mill investment. Press formability tolerances and multi-year automotive corrosion certifications will govern mill supply contracts through 2036.
Key Market Trends & Insights
- By metal material: Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled hold an estimated 56.0% share in 2026 since low cost per metric ton and reliable robotic weldability anchor automotive and appliance stamping.
- By thickness gauge: Light Gauge Sheet 0.5 to 2 mm represents 52.0% in 2026 as car door skins and server racks standardize thin-gauge coil.
- By end-use industry: Automotive Body Panels Chassis and Structural Components account for 44.0% in 2026 driven by high-tensile crash structures, closures, and electric-vehicle battery tray stamping.
- By manufacturing process: Cold-Rolled Precision Sheet and Coil secures 54.0% in 2026 owing to tight thickness tolerances and smooth surface roughness required for electro-galvanizing and automotive paint lines.
- By distribution channel: Steel Service Centers and Toll Processors command 51.0% in 2026 through just-in-time coil slitting, blanking, and leveling for tier-one stampers.
Regional Highlights
- Top national expansion: India leads national growth projections at a 6.2% CAGR through 2036 under Production-Linked Incentive specialty steel investments and rapid automotive and metro-rail expansion.
- Broader country progression: Poland tracks at a 5.5% CAGR ahead of Mexico at 5.2% and South Korea at 4.9% while Western markets progress between 4.7% and 3.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Sheet Metal Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 315.0 billion |
| Estimated Market Size in 2026 | USD 330.0 billion |
| Projected Market Size by 2036 | USD 527.4 billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Revenue, 2026 to 2036 | USD 197.4 billion |
Tier-one automotive stampers, data center switchgear builders, and pre-engineered metal building contractors require flat-rolled coil with uniform grain structure and zero surface camber to run high-speed progressive dies without coil breaks. When mills pair electric-arc furnace melt shops with continuous tandem cold-rolling and zinc-aluminum-magnesium coating lines, fabricators cut scrap trim loss and eliminate post-stamping pickling. Data from the U.S. Geological Survey Mineral Commodity Summaries 2026, the U.S. iron and steel industry produced 82 million metric tons of raw steel in 2025 across domestic mill operations supplying construction and transportation markets. Consequently, industrial buyers coordinate sheet procurement with flat steel products to lock in quarterly indexed coil pricing.
Global Flat-Rolled Tonnage and Mill Shipment Sizing
Table 2: Global Sheet Metal Tonnage and Material Breakdown Sizing (USD billion and million metric tons), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 315.0 | 330.0 | 527.4 |
| Global finished sheet & coil shipments (million metric tons) | 815.0 to 850.0 | 845.0 to 880.0 | 1,180.0 to 1,240.0 |
| Carbon, mild & galvanized steel sheet volume (million MT) | 740.0 to 770.0 | 765.0 to 795.0 | 1,055.0 to 1,105.0 |
| Stainless steel & aluminum alloy sheet volume (million MT) | 75.0 to 80.0 | 80.0 to 85.0 | 125.0 to 135.0 |
Operational note and material intensity analysis indicate that global finished sheet metal shipments expand from 845.0 to 880.0 million metric tons in 2026 toward 1,180.0 to 1,240.0 million metric tons by 2036. Data from the USGS annual mineral commodity reports 2026 for Aluminum, three domestic companies operated six primary aluminum smelters in 2025 while secondary scrap recovery and flat-rolled sheet imports supplied transportation and packaging converters. Automotive and roofing fabricators balance aluminum sheet weight savings against the lower unit cost of galvanized and coated iron and steel sheets across high-volume production runs.
Mill Capacity Utilization & Stamping Plant Economics
Table 3: Global Mill Utilization and Coating Line Indicators for the Sheet Metal Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Blended realized value per metric ton of sheet (USD/MT) | 370.0 to 386.0 | 375.0 to 391.0 | 425.0 to 447.0 |
| AHSS, coated & specialty alloy share of sheet value (%) | 38.0% to 41.0% | 40.0% to 43.0% | 54.0% to 58.0% |
| EAF & low-carbon recycled sheet share of supply (%) | 32.0% to 35.0% | 34.0% to 37.0% | 49.0% to 54.0% |
| Service-center slit & pre-blanked delivery share (%) | 49.5% to 51.0% | 50.5% to 52.0% | 56.0% to 58.5% |
Data from the OECD Global Forum on Steel Excess Capacity (GFSEC) Ministerial Statement released in Milwaukee in September 2026, global steel excess capacity is forecast to rise from 601 million metric tons in 2024 to 745 million metric tons by 2028. Structural overcapacity in commodity hot-rolled band compels leading flat-rolled steelmakers in North America, Europe and East Asia to shift capital toward value-added automotive advanced high-strength steel (AHSS), electrical silicon steel sheets and corrosion-resistant zinc-coated coils that command USD 280 to USD 450 per metric ton margin premiums over commodity slab.
Table 4: Automotive & Industrial Stamping Channel Benchmarks for the Sheet Metal Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 330.0 billion | 2026 global sheet metal revenue baseline |
| Global monthly crude steel output, Sept 2026 | 142.4 million MT | World Steel Association (worldsteel) 70-country release |
| Automotive Body Panels & Chassis revenue, 2026 | USD 145.2 billion | 44.0% end-use industry allocation |
| Steel Service Centers & Toll Processors revenue, 2026 | USD 168.3 billion | 51.0% distribution channel allocation |
Precision slitting and multi-blank laser cutting lines allow service centers to deliver ready-to-press blanks directly into metal stamping components presses without in-house decoiling at the OEM plant. Commercial capacity additions from Tata Steel in August 2025 illustrate this downstream integration, as Tata Steel dispatched the first batch of galvanized coils from its new continuous galvanizing line at Kalinganagar in Odisha to serve appliance and automotive panel customers.
Analyst Perspective
"Flat-rolled sheet mills no longer win multi-year automotive and HVAC contracts on base hot-rolled coil tonnage alone; procurement teams buy guaranteed hole-expansion ratios, zero-spangle galvanized surface quality, and verified Scope 1 and Scope 2 carbon intensity certificates. Producers that combine electric-arc furnace melting with continuous annealing and on-site service-center blanking will capture the highest-margin stamping accounts through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Sheet Metal Market segmented?
The sheet metal market is segmented by metal material, thickness gauge, end-use industry, manufacturing process, and distribution channel. In 2026, Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled are projected at 56.0%, Light Gauge Sheet 0.5 to 2 mm at 52.0%, Automotive Body Panels Chassis and Structural Components at 44.0%, Cold-Rolled Precision Sheet and Coil at 54.0%, and Steel Service Centers and Toll Processors at 51.0%.
By metal material: Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled and Austenitic 304 and 316 Stainless Steel, as well as 5000 and 6000 Series Aluminum and Galvanized Steel.
By thickness gauge: Light Gauge Sheet 0.5 to 2 mm and Ultra-Thin Foil Gauge Below 0.5 mm, as well as Heavy Gauge Sheet Above 2 mm and Medium Structural Sheet.
By end-use industry: Automotive Body Panels Chassis and Structural Components and Construction Roofing and HVAC Ductwork, as well as Aerospace Wing Skins and Industrial Appliances.
By manufacturing process: Cold-Rolled Precision Sheet and Coil and Hot-Rolled Pickled Sheet, as well as Hot-Dip Galvanized Sheet and Pre-Painted Polymer-Coated Coil.
By distribution channel: Steel Service Centers and Toll Processors and Direct Mill-to-OEM Supply Contracts, as well as Metal Stamping Job Shops and Industrial Distributors.
Why do Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled lead the metal material category?
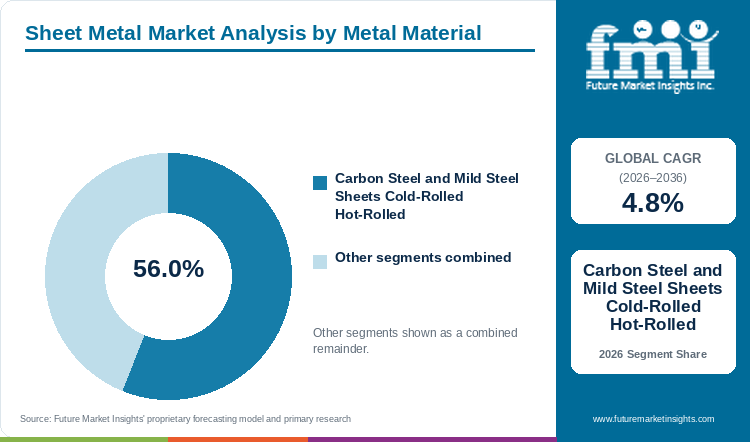
Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled hold an estimated 56.0% of metal material demand in 2026, anchored by cost-effective deep drawing and high-speed robotic weldability.
Table 5: Metal Material Share for the Sheet Metal Market (percentage share), 2026
| Metal Material | Share (2026) |
|---|---|
| Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled | 56.0% |
| Other Segments Combined (Galvanized/Galvalume, Austenitic Stainless & Aluminum Alloy) | 44.0%* |
| Total | 100.0% |
*Note: Remaining metal material categories account for the balance of 2026 global sheet metal demand.
Table 6: Metal Material Leadership and Market Growth for the Sheet Metal Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled |
Cold-rolled and hot-rolled mild and carbon steel coils anchor global flat-rolled consumption since high modulus of elasticity, predictable deep-drawing behavior, and low raw material cost per metric ton make carbon sheet the default substrate for automotive stamping parts and industrial enclosures. While Galvanized and Galvalume Zinc-Coated Steel Sheets and Austenitic 304 and 316 Stainless Steel capture wet or corrosive environments and 5000 and 6000 Series Aluminum Alloy Sheets serve lightweight EV closures, mild and high-strength carbon steel coils remain unmatched in high-speed robotic resistance spot welding. Exposure to red-rust oxidation on uncoated cold-rolled sheet nevertheless requires immediate phosphating, e-coating, or galvanizing.
- Within metal materials, Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled are projected to capture a 56.0% share in 2026 across car body-in-white and domestic appliances.
- Mill modernization investments reinforce this carbon and electrical sheet leadership, evidenced in April 2025 when ArcelorMittal confirmed ongoing commissioning of its new 1.5-million-metric-ton electric arc furnace at AMNS Calvert in the United States to supply domestic automotive steel grades.
What sustains Light Gauge Sheet 0.5 to 2 mm leadership in the thickness gauge segment?
Light Gauge Sheet 0.5 to 2 mm represents 52.0% of the thickness gauge category in 2026, supported by high-volume stamping of car body panels, HVAC ductwork, and appliance enclosures.
Light Gauge Sheet 0.5 to 2 mm represents the primary commercial thickness window for passenger-car outer panels (0.65 to 0.85 mm), commercial HVAC spiral ductwork (0.55 to 1.20 mm) and white-goods refrigerator and washing-machine cabinets whereas Ultra-Thin Foil Gauge Below 0.5 mm serves battery current collectors, fin stock and tinplate packaging and Heavy Gauge Sheet Above 2 mm serves chassis cross-members. Fabricators cross-Evaluating precision stainless steel strip and light-gauge carbon coil rely on 0.5 to 2.0 mm gauges to balance dent resistance against stamping press tonnage. Springback distortion when stamping thin-gauge ultra-high-strength steels above 980 MPa remains a technical hurdle requiring optical die compensation.
- In 2026, Light Gauge Sheet 0.5 to 2 mm is anticipated to capture 52.0% of thickness gauge demand across automotive closures and electrical enclosures.
- Peer-reviewed manufacturing analysis published in the Journal of Manufacturing and Materials Processing in August 2025 confirmed that third-generation advanced high-strength steels, tailored welded blanks, and hot-formed AA6082 and AA7075 aluminum sheets allow conventional sheet-metal body-in-white assemblies to retain repairability and crash performance against single-piece gigacastings.
How do Automotive Body Panels Chassis and Structural Components lead the end-use industry category?
Automotive Body Panels Chassis and Structural Components account for 44.0% of end-use industry volume in 2026, driven by advanced high-strength crash structures and EV battery enclosures.
Global light-vehicle and commercial-truck assembly plants consume approximately 750 to 900 kilograms of stamped flat-rolled steel and aluminum sheet per vehicle across floor pans, pillars, doors and hoods and crash rails. Although Construction Roofing Siding and HVAC Ductwork, Industrial Machinery Cabinets and Aerospace Aircraft Fuselage and Wing Skin Panels generate steady baseline demand, automotive OEMs drive the highest value-added coil specifications for lightweight automotive body panels. Stringent OEM surface-waviness standards (Wa below 0.35 micrometers) create high mill rejection barriers that lock out uncertified commodity rollers.
- By end-use industry, Automotive Body Panels Chassis and Structural Components are estimated to hold 44.0% of total demand in 2026.
- Tribological research published in the journal Machines in June 2025 demonstrated that maskless electrochemical texturing applied to skin-pass cold rolling work rolls directly controls micro-topography on automotive sheet metal to retain press lubricant and prevent galling during deep drawing.
Why does Cold-Rolled Precision Sheet and Coil lead the manufacturing process category?
Cold-Rolled Precision Sheet and Coil secures 54.0% of manufacturing process value in 2026, supported by tight thickness tolerances and smooth surface finish for coating and painting.
Cold reduction of hot-pickled steel or aluminum band through multi-stand tandem mills or reversing Sendzimir mills reduces thickness by 50% to 80% at room temperature, eliminating mill scale and achieving uniform gauge tolerances within plus or minus 0.015 millimeters. Because hot-dip galvanizing lines, pre-painted coil coaters and appliance enamelers require a cold-reduced substrate to guarantee coating adhesion, Cold-Rolled Precision Sheet and Coil anchors downstream value creation ahead of direct hot-rolled pickled sheet. High electricity consumption during cold reduction and batch or continuous annealing furnaces nonetheless exposes rollers to industrial power-tariff volatility.
- Cold-Rolled Precision Sheet and Coil is predicted to secure 54.0% of manufacturing process volume in 2026 across automotive and appliance stamping.
- Segment progression through 2036 is forecast to favor integrated continuous annealing and hot-dip galvanizing lines that process dual-phase and transformation-induced plasticity (TRIP) cold-rolled sheets in a single thermal pass.
What gives Steel Service Centers and Toll Processors the leading position in distribution channel?
Steel Service Centers and Toll Processors command 51.0% of distribution channel share in 2026, anchored by just-in-time coil slitting, leveling, and press-ready blanking.
Primary integrated blast-furnace and electric-arc-furnace steel mills cast and roll 20-metric-ton to 30-metric-ton master coils to maximize rolling-mill campaign efficiency, whereas stamping shops and HVAC contractors require slit coils, trapezoids and cut-to-length leveled sheets in smallerweekly lots. Steel Service Centers and Toll Processors bridge this structural gap by operating high-speed rotary shear cut-to-length lines, stretcher-levelers, and multi-blanking presses while absorbing working-capital inventory risk. Tariff swings and trade-remedy duties on imported flat-rolled steel still create inventory valuation risks for independent service centers.
- Steel Service Centers and Toll Processors are forecast to command 51.0% of distribution channel share in 2026 as OEMs outsource slitting and blanking.
- Official trade review notices from the U.S. International Trade Commission in May 2026 instituting sunset reviews on cut-to-length carbon steel plate imports from China, Russia, and Ukraine confirm how trade enforcement keeps domestic service-center procurement focused on regional mill contracts.
What are the drivers, restraints, and opportunities in the Sheet Metal Market?
In the sheet metal market, automotive lightweighting with advanced high-strength steels and data center enclosure buildouts are projected to drive adoption whereas global crude steel overcapacity and gigacasting substitution restrain base margins and hydrogen-reduced green coils unlock OEM supply contracts.
- Driver: Automotive lightweighting with third-generation advanced high-strength steels and 6000-series aluminum sheet with data center server-rack and HVAC expansion drives precision coil consumption.
- Restraint: Global crude steel excess capacity reaching 745 million metric tons by 2028 and competition from single-piece aluminum gigacastings compress base hot-rolled coil margins and replace multi-part underbody stampings.
- Opportunity: Scaling hydrogen-based direct reduced iron (DRI) green steel sheets and optical-sorted post-consumer recycled aluminum auto-body coils opens premium decarbonized supply contracts with OEMs.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Passenger vehicle manufacturers and battery-pack integrators face strict fleet corporate average fuel economy and electric-range targets that compel body engineers to substitute thick mild steel with thin-gauge advanced high-strength steels (1,180 to 1,500 MPa) and heat-treatable aluminum sheets. When stamping plants run tailored welded blanks on servo-driven stamping machines, vehicle body structures shed 15% to 25% of mass while increasing cabin intrusion resistance during side-pole impacts. Federally funded research released by the U.S. Department of Energy Office of Scientific and Technical Information (OSTI) in April 2025 confirmed that combining thin advanced high-strength steel sheet with localized carbon-fiber-reinforced epoxy reinforcement substantially reduces steel auto-body mass while maintaining structural stiffness.
Risk Assessment of the Sheet Metal Market: Operational and Formulation Friction
Persistent global steelmaking overcapacity combined with high European industrial electricity costs and weak export demand compresses mill utilization margins and triggers anti-dumping trade friction across flat-rolled sheet corridors. At the same time, automotive OEM adoption of high-pressure die-cast aluminum underbody megacastings eliminates dozens of stamped sheet-metal brackets from rear floor assemblies, pressuring commodity stampers and metal coil lamination processors. Market outlook data published by the European Steel Association (EUROFER) in October 2026 documented that EU steel exports fell 20% while European apparent steel consumption remained flat amid import pressure and elevated energy costs. Flat-rolled producers must consequently rationalize older blast-furnace hot-strip capacity and pivot toward specialized coated and electrical sheet grades.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Flat-rolled steel and aluminum rollers open lucrative margin premiums by commercializing closed-loop recycled aluminum body sheet and hydrogen-reduced low-embodied-carbon steel coils tailored to automated welding materials and robotic assembly lines. Automotive and consumer-electronics brands now insert binding kilogram-CO2-per-ton-of-coil ceilings into multi-year purchasing tenders, rewarding mills that separate wrought 5000-series and 6000-series scrap from cast alloys without downcycling. Technical research published via the United States Energy Department OSTI in September 2025 demonstrated an alloy-selective optical sorting process that separates mixed post-consumer aluminum sheet alloys 5182 and 6111 from cast alloys A380 and A356 to expand domestic recycled sheet feedstock.
Sheet Metal Market by Country (2026 to 2036)
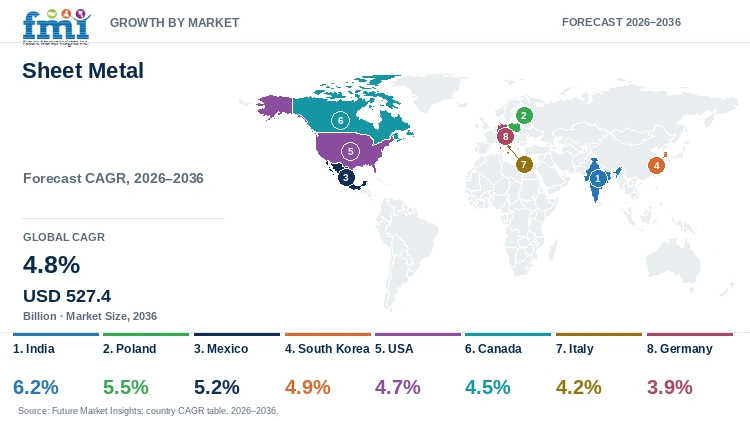
FMI country modeling indicates that India leads global sheet metal expansion at a 6.2% CAGR through 2036, ahead of Poland at 5.5%, Mexico at 5.2% and South Korea at 4.9%. National demand outlooks reflect differences in specialty steel Production-Linked Incentive commissioning, nearshoring appliance and auto-body stamping, and electric-arc furnace decarbonization across North America and Europe.
Table 7: Country CAGR and Primary Growth Levers for the Sheet Metal Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 6.2% | 85 specialty steel PLI 1.2 MoUs and rapid automotive and appliance capacity expansion |
| Poland | 5.5% | European white-goods appliance stamping and pre-painted galvanized roofing hubs |
| Mexico | 5.2% | USMCA automotive body-in-white stamping and nearshoring HVAC/server enclosure plants |
| South Korea | 4.9% | Giga-steel automotive coils, EV battery cases, and LNG shipbuilding plate/sheet demand |
| USA | 4.7% | Low-carbon EAF sheet mill startups, USD 3B hot-strip upgrades, and data center ductwork |
| Canada | 4.5% | Hydro-powered low-carbon aluminum sheet rolling and Ontario EAF automotive steel transition |
| Italy | 4.2% | Precision stainless-steel service centers and commercial food-machinery fabrication |
| Germany | 3.9% | Hydrogen-DRI green automotive body sheet contracts and e-mobility electrical steel coils |
Source: Future Market Insights analysis
India Sheet Metal Market Outlook (2026 to 2036)
Demand for sheet metal in India is projected to expand at a leading 6.2% CAGR between 2026 and 2036 as domestic automotive stampers, white-goods manufacturers, and metro-rail coach builders scale flat-rolled coil procurement. What distinguishes India from mature steel-consuming economies is the rapid localization of import-substituted coated, electrical, and automotive-grade sheets under federal manufacturing incentives. Official records from the Press Information Bureau (PIB) and Ministry of Steel in February 2026 confirm this capacity buildout, documenting the signing of 85 Memoranda of Understanding with 55 companies under PLI Scheme 1.2 for Specialty Steel following INR 22,973 crore of committed investment in earlier rounds. Indian integrated mills in Odisha, Gujarat, and Karnataka are rapidly commissioning continuous galvanizing and cold-rolling complexes to capture domestic auto and solar-mounting demand.
Key takeaway: In India, PLI specialty steel mill commissioning and surging automotive and appliance manufacturing are projected to drive the fastest national sheet metal growth through 2036.
Poland Sheet Metal Market Outlook (2026 to 2036)
In Poland, sheet metal consumption is anticipated to advance at a 5.5% CAGR from 2026 to 2036 anchored by the country's position as Europe's leading hub for household appliance stamping, commercial bus and trailer fabrication and pre-painted steel roofing. Compared with Western European markets experiencing industrial de-stocking, Polish metal fabricators and steel service centers benefit from continuous inflow of cold-rolled and galvanized coils into special economic zones in Silesia and Lower Silesia. Production data from the World Steel Association (worldsteel) in January 2026 tracking global and European crude steel output demonstrates the ongoing shift toward electric-arc furnace and downstream flat-processing investments across Central Europe. Polish roofing and facade roll-formers also drive strong demand for organic polymer-coated galvanized sheet.
Key takeaway: In Poland, export-oriented appliance stamping and pre-painted steel roofing fabrication are anticipated to sustain strong central European sheet metal demand.
Mexico Sheet Metal Market Outlook (2026 to 2036)
Mexican sheet metal demand is forecast to progress at a 5.2% CAGR over the 2026 to 2036 horizon across automotive body-in-white stamping plants, HVAC equipment factories and commercial refrigeration assemblers in Monterrey, Saltillo and Queretaro. Mexico diverges from South American commodity steel markets because USMCA regional automotive rules of origin mandate high North American melted-and-poured steel and aluminum sheet content per vehicle. Corporate filings in ArcelorMittal's Half-Year Report for June 30, 2026 confirm this regional integration, noting dedicated upstream iron ore and slab investments designed to supply ArcelorMittal Mexico flat-steel operations and North American automotive joint ventures. Foreign direct investment into Mexican EV component and server-cabinet stamping lines continues to pull precision slit coil imports and domestic hot-dip galvanizing capacity.
Key takeaway: In Mexico, USMCA automotive rules of origin and nearshoring HVAC and appliance factories are forecast to anchor demand for galvanized and cold-rolled sheet.
South Korea Sheet Metal Market Outlook (2026 to 2036)
Sales of sheet metal in South Korea are estimated to grow at a 4.9% CAGR between 2026 and 2036 across ultra-high-tensile automotive body stamping, LNG carrier cryogenic containment panels, and premium consumer electronics enclosures. South Korea's flat-rolled sector stands apart globally through its concentration of world-scale integrated coastal steelworks in Pohang and Gwangyang that export giga-steel automotive coils and hyper-corrosion-resistant zinc-magnesium-aluminum sheets. Strategic industry analysis published by Nippon Steel in December 2025 examining East Asian supply-demand balances underscores how Korean and Japanese flat-steel leaders focus on high-grade automotive and electrical sheets to counter Chinese commodity export volume. Korean shipbuilders and EV battery-case stampers remain primary domestic buyers of specialty stainless, nickel-alloy, and high-strength steel sheet.
Key takeaway: In South Korea, giga-steel automotive stamping and LNG shipbuilding orders are estimated to sustain high-value specialty sheet metal consumption.
USA Sheet Metal Market Outlook (2026 to 2036)
Commercial sheet metal valuation in the USA is predicted to expand at a 4.7% CAGR through 2036, supported by greenfield electric-arc-furnace flat-rolled mills, hyperscale data center switchgear and cooling ductwork buildouts and Section 232/301 tariff-protected domestic stamping. American sheet metal procurement differs from European blast-furnace supply chains because over 70% of U.S. steel is melted in scrap-fed electric arc furnaces with expanding thin-slab continuous casting and inline galvanizing. Financial results released by Nucor Corporation in July 2026 confirm strong domestic flat-rolled fundamentals, reporting higher second-quarter 2026 earnings in its steel mills segment driven by higher average selling prices and increased shipment volumes at its sheet and plate mills. In parallel, multi-billion-dollar aluminum rolling mill investments in Alabama expand domestic automotive and can-sheet supply.
Key takeaway: In the USA, scrap-fed electric-arc-furnace sheet mill expansions and data center infrastructure buildouts are predicted to anchor domestic coil demand.
Canada Sheet Metal Market Outlook (2026 to 2036)
Canadian sheet metal demand is slated to advance at a 4.5% CAGR during the 2026 to 2036 forecast period across Ontario automotive stamping complexes, Quebec low-carbon aluminum rolling mills, and Western Canadian agricultural grain-bin and energy fabrication. What differentiates Canada in the global sheet metal trade is its abundant hydroelectric power in Quebec and British Columbia that enables the world's lowest-carbon primary aluminum slab production with Ontario's transition from coal blast furnaces to electric arc furnaces. Fiscal year 2026 fourth-quarter disclosures from Novelis Inc. in May 2026 confirm the cross-border North American aluminum rolling and recycling network that supplies Canadian and U.S. automotive body sheet stampers. Canadian metal building roll-formers also maintain steady orders for Galvalume and pre-painted architectural steel sheet.
Key takeaway: In Canada, hydro-powered low-carbon aluminum rolling and Ontario electric-arc-furnace automotive steel upgrades are slated to support steady sheet metal growth.
Italy Sheet Metal Market Outlook (2026 to 2036)
In Italy, the sheet metal market is projected to register a 4.2% CAGR from 2026 to 2036 across northern Italian precision stainless-steel service centers, commercial kitchen and food-processing machinery builders and automotive body-stamping suppliers. Italy diverges from northern European heavy-plate markets through its dense cluster of small-to-medium laser-cutting, press-brake bending and cold-rolling processors in Lombardy, Veneto and Emilia-Romagna. Sector analysis published by EUROFER in June 2026 notes that European steelmakers restarted 10 million metric tons of capacity while navigating modest downstream demand recovery across southern and central European manufacturing hubs. Italian machinery exporters rely heavily on austenitic 304 and 316 stainless steel sheets and pre-coated appliance coils.
Key takeaway: In Italy, precision stainless-steel service centers and commercial food-machinery and appliance exporters are projected to sustain demand for cold-rolled and coated sheets.
Germany Sheet Metal Market Outlook (2026 to 2036)
German sheet metal revenue is forecast to expand at a 3.9% CAGR from 2026 through 2036 across premium passenger-car body-in-white press shops, electrical transformer and traction-motor laminations, and industrial machinery enclosures. Unlike volume-driven emerging markets, Germany focuses on value-dense transition toward hydrogen-based direct reduced iron (DRI) green steel coils and closed-loop automotive aluminum recycling to meet EU Carbon Border Adjustment Mechanism (CBAM) and OEM decarbonization targets. Full-year 2025 and fourth-quarter financial disclosures from ArcelorMittal in February 2026 detail how European flat-steel producers are optimizing strip-mill operations and advancing XCarb low-carbon steel deliveries to German and continental European automakers. High domestic industrial power prices nevertheless restrain commodity hot-rolled band output in the Ruhr valley.
Key takeaway: In Germany, automotive OEM green-steel procurement contracts and electrical steel sheet demand for e-mobility motors are forecast to drive value growth through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the sheet metal market?
ArcelorMittal SA, Nippon Steel Corporation, POSCO Holdings Inc., Tata Steel Limited, Nucor Corporation, Novelis Inc. (Hindalco Industries), United States Steel Corporation, JSW Steel Limited, Thyssenkrupp Steel Europe AG, and Constellium SE are the notable companies in the sheet metal market.
Competitive positioning across the global sheet metal industry separates multi-continent integrated flat-carbon and automotive steelmakers, regional electric-arc-furnace and coated-sheet producers, and specialized global rolled-aluminum sheet leaders. ArcelorMittal, Nippon Steel, POSCO and Thyssenkrupp lead in ultra-high-strength automotive and electrical coils. Nucor and Tata Steel as well as U.S. Steel and JSW Steel drive hot-strip, cold-rolling and continuous galvanizing expansion, while Novelis and Constellium lead in 5000 and 6000 series aluminum flat-rolled sheets.
- Global Integrated Automotive & Specialty Flat Steelmakers: ArcelorMittal, Nippon Steel, POSCO and Thyssenkrupp engineer gigapascal-class automotive body sheets and grain-oriented electrical steels.
- High-Growth EAF & Regional Integrated Sheet Producers: Nucor, Tata Steel, U.S. Steel and JSW Steel operate thin-slab casting, cold-rolling and continuous hot-dip galvanizing complexes.
- Global Flat-Rolled Aluminum Sheet Specialists: Novelis and Constellium manufacture heat-treatable 6000-series and work-hardening 5000-series aluminum body sheets and aerospace plates.
Competitive Benchmarking: Sheet Metal Market
Table 8: Competitive Benchmarking for the Sheet Metal Market (qualitative capability ratings), 2026
| Company | Automotive AHSS & Alloy Grade Depth | Coating & Galvanizing Breadth | Low-Carbon Melt Readiness | Geographic Reach |
|---|---|---|---|---|
| ArcelorMittal SA | High | High | High | Operations in 14 countries; XCarb low-carbon steel and 1.5Mt Calvert US EAF commissioning |
| Nippon Steel Corporation | High | High | High | Japan, US (U.S. Steel), India (AM/NS) & ASEAN; USD 3B hot-strip investment & 100% H2 DRI test |
| POSCO Holdings Inc. | High | High | Medium | South Korea, Mexico, India & China giga-steel automotive and PosMAC coated sheet network |
| Tata Steel Limited | High | High | Medium | India, UK & Netherlands flat-rolled mills; commissioned Kalinganagar CGL in August 2025 |
| Nucor Corporation | Medium | High | High | North American scrap-fed EAF sheet, plate, and galvanizing leader; strong Q2/Q3 2026 results |
| Novelis Inc. (Hindalco) | High | Medium | High | Global leader in 5000/6000 rolled aluminum auto-body and can sheet across 4 continents |
| United States Steel Corporation | High | High | High | North American Big River Steel EAF and Gary Works flat-rolled mills; USD 3B HSM upgrade plan |
| JSW Steel Limited | High | High | Medium | India's largest flat and coated steel producer (30.14 MnT crude steel base) with US/Italy mills |
| Thyssenkrupp Steel Europe AG | High | High | Medium | German and European leader in exposed automotive body sheet and grain-oriented electrical steel |
| Constellium SE | High | Medium | High | European and North American aluminum body sheet and aerospace plate; USD 5.2B H1 2026 revenue |
Key Developments in the Sheet Metal Market
- In November 2026, Nippon Steel Corporation successfully conducted pilot-scale direct reduced iron production using 100% hydrogen as the reducing agent at the shaft furnace of its Hasaki Research and Development Center. The test employed lower-grade blast furnace grade iron ore pellets and produced over 1,000 tonnes of DRI across more than 300 hours of continuous operation, marking a significant step toward the commercialization of carbon-neutral ironmaking technology [1].
- In October 2026, Nucor Corporation reported third-quarter 2026 results with net earnings attributable to stockholders of USD 1.32 billion, or USD 5.80 per diluted share, on net sales of USD 11.25 billion. Earnings grew in both the steel mills and steel products segments compared to the second quarter of 2026, underpinned by higher realized pricing and record year-to-date steel mill shipments [2].
- In July 2026, Constellium SE reported first-half 2026 results with shipments of 751 thousand metric tons and revenue of USD 5.2 billion, up 28.0% year over year, reflecting higher revenue per ton and favorable metal prices. The company achieved record first-half Segment Adjusted EBITDA and raised its full-year 2026 adjusted EBITDA guidance to USD 980 million to USD 1.02 billion [3].
Key Players in the Sheet Metal Market
Global Integrated Automotive & Specialty Flat Steelmakers
- ArcelorMittal SA
- Nippon Steel Corporation
- POSCO Holdings Inc.
- Thyssenkrupp Steel Europe AG
High-Growth EAF & Regional Integrated Sheet Producers
- Nucor Corporation
- Tata Steel Limited
- United States Steel Corporation
- JSW Steel Limited
Global Flat-Rolled Aluminum Sheet & Recycling Specialists
- Novelis Inc. (Hindalco Industries)
- Constellium SE
Sheet Metal Market - Report Scope
Table 9: Report Scope for the Sheet Metal Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Metal Material; Thickness Gauge; End-Use Industry; Manufacturing Process; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes mill and service-center commercial revenue from flat-rolled metallic sheets, coils, and strips (carbon and mild steel, hot-dip and electro-galvanized steel, austenitic/ferritic stainless steel, and 5000/6000/7000 series aluminum alloys) across foil, light, medium, and heavy sheet gauges. Category Scope Note: Excludes long steel products (rebar, wire rod, merchant bar), heavy structural H-beams, tubular pipes, and raw unrolled ingots/slabs. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, Poland, Mexico, South Korea, USA, Canada, Italy, Germany, and additional countries in the full report |
| Key Companies Covered | ArcelorMittal SA, Nippon Steel Corporation, POSCO Holdings Inc., Tata Steel Limited, Nucor Corporation, Novelis Inc. (Hindalco Industries), United States Steel Corporation, JSW Steel Limited, Thyssenkrupp Steel Europe AG, Constellium SE |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up tonnage-to-value triangulation. |
Sheet Metal Market - Research Methodology
Table 10: Research Methodology for the Sheet Metal Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with automotive body-in-white stamping engineers, steel service-center purchasing directors, continuous galvanizing line metallurgists, and HVAC/appliance sheet buyers. |
| Secondary Research | Analysis of World Steel Association (worldsteel) monthly production releases, USGS Mineral Commodity Summaries for Iron/Steel and Aluminum, OECD GFSEC capacity reports, EUROFER outlooks, and USITC trade filings. |
| Market Sizing and Forecasting | Top-down global flat-rolled steel and aluminum production baselines reconciled against bottom-up finished sheet tonnage (845.0M to 880.0M MT in 2026) and grade-weighted transaction prices through 2036. |
| Country Forecasting Model | Econometric national projections weight light-vehicle stamping output, PLI and nearshoring industrial capex, EAF and aluminum rolling capacity additions, and construction cladding demand across eight countries. |
| Operational Benchmark Traceability | Tonnage, realized price per metric ton, and coating/EAF share indicators in Tables 2, 3, and 4 trace to worldsteel 70-country data, USGS domestic production tables, OECD GFSEC records, and corporate 10-K/20-F filings. |
| Data Triangulation and Validation | Revenue estimates isolate finished flat-rolled sheets, coils, and pre-blanked strips while strictly excluding long steel products, heavy structural beams, and downstream stamped assembly labor. |
Sheet Metal Market by Segments
Sheet Metal Market segmented by Metal Material:
- Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled
- Galvanized and Galvalume Zinc-Coated Steel Sheets
- Stainless Steel Sheets Austenitic 304 and 316 Grades
- Aluminum Alloy Sheets 5000 and 6000 Series
Sheet Metal Market segmented by Thickness Gauge:
- Light Gauge Sheet 0.5 to 2 mm
- Ultra-Thin Foil Gauge Below 0.5 mm
- Medium Gauge Sheet 2 to 6 mm
- Heavy Gauge Sheet and Plate Above 2 mm
Sheet Metal Market segmented by End-Use Industry:
- Automotive Body Panels Chassis and Structural Components
- Construction Roofing Siding and HVAC Ductwork
- Industrial Machinery Cabinets Enclosures and Consumer Appliances
- Aerospace Aircraft Fuselage and Wing Skin Panels
- Electrical Equipment and Data Center Server Racks
Sheet Metal Market segmented by Manufacturing Process:
- Cold-Rolled Precision Sheet and Coil
- Hot-Rolled Pickled and Oiled Sheet
- Hot-Dip Galvanized and Electro-Galvanized Sheet
- Pre-Painted and Polymer-Coated Coil
Sheet Metal Market segmented by Distribution Channel:
- Steel Service Centers and Toll Processors
- Direct Mill-to-OEM Supply Contracts
- Metal Stamping and Fabrication Job Shops
- Industrial Metals Distributors
Sheet Metal Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Nippon Steel Corporation official newsroom, November 4, 2026 — nipponsteel.com/en/newsroom/news/2026/20261104_100.html
- [2] Nucor Corporation official press release, October 26, 2026 — nucor.com/investors
- [3] Constellium SE official press release, July 29, 2026 — constellium.com/news/constellium-reports-strong-second-quarter-and-first-half-2026-results
- [4] U.S. Geological Survey. (2026, January 30). Mineral Commodity Summaries 2026: Aluminum Primary Smelting and Flat-Rolled Sheet Supply. U.S. Department of the Interior USGS.
- [5] Organisation for Economic Co-operation and Development. (2026, September 30). Ministerial Statement of the Global Forum on Steel Excess Capacity (GFSEC) in Milwaukee. OECD Steel Forum Publications.
- [6] Tata Steel Limited. (2025, August 6). Tata Steel Dispatches the First Batch of Galvanised Coils from Its New Continuous Galvanising Line in Kalinganagar, Odisha. Tata Steel Official Newsroom.
- [7] ArcelorMittal SA. (2025, April 30). ArcelorMittal Reports First Quarter 2025 Results and Commissioning of 1.5Mt EAF at AMNS Calvert. ArcelorMittal Regulatory News.
- [8] Brito-Franco, A., et al. (2025, August 12). Aluminium Alloy Gigacasting vs. Conventional Sheet Metal Forming in Automotive Body-in-White Manufacturing. Journal of Manufacturing and Materials Processing, 10(8), 260, MDPI.
- [9] Lopes, P., et al. (2025, June 5). Review of Surface Texturing and Maskless Electrochemical Texturing in Skin-Pass Cold Rolling of Sheet Metal. Machines, 13(6), 253, MDPI Open Access.
- [10] U.S. International Trade Commission. (2026, May 26). Cut-to-Length Carbon Steel Plate and Flat-Rolled Trade Review Institution Notice. U.S. International Trade Commission Federal Register.
- [11] U.S. Department of Energy Office of Scientific and Technical Information. (2025, April 30). Reducing Mass of Steel Auto Bodies Using Thin Advanced High-Strength Steel with Carbon-Fiber Reinforced Epoxy (OSTI 2997452). U.S. Department of Energy OSTI.
- [12] European Steel Association (EUROFER). (2026, October 1). Economic and Steel Market Outlook 2026-2027: EU Steel Exports Fall 20% Amid Flat Apparent Consumption. EUROFER Brussels Press Releases.
- [13] U.S. Department of Energy Office of Scientific and Technical Information. (2025, September 18). Alloy Selective Optical Sorting of Mixed Post-Consumer Aluminum Sheet Scrap 5182 and 6111 (OSTI 3021470). U.S. Department of Energy OSTI.
- [14] Press Information Bureau Government of India. (2026, February 9). Ministry of Steel Signs MoUs for 85 Specialty Steel Projects with 55 Companies under PLI Scheme 1.2. Ministry of Steel Government of India.
- [15] World Steel Association (worldsteel). (2026, January 23). December 2025 Crude Steel Production and Full-Year 2025 Global Steel Output Data. World Steel Association Brussels.
- [16] ArcelorMittal SA. (2026, June 30). ArcelorMittal Half-Year Report for the Six Months Ended June 30, 2026: North America and Mexico Flat Steel Operations. ArcelorMittal Corporate Filings.
- [17] Nippon Steel Corporation. (2025, December 12). Global Steel Supply-Demand Structure and High-Grade Automotive Flat Steel Strategy. Nippon Steel Investor Relations Library.
- [18] Nucor Corporation. (2026, July 27). Nucor Reports Results for the Second Quarter of 2026 Driven by Higher Sheet and Plate Mill Volumes. Nucor Corporation Investor Relations.
- [19] Novelis Inc. (2026, May 19). Novelis Reports Fourth Quarter and Full Fiscal Year 2026 Rolled Aluminum Sheet Results. Novelis Investor Relations.
- [20] European Steel Association (EUROFER). (2026, June 25). Economic and Steel Market Outlook 2026-2027 Report: European Flat Steel Capacity and Industrial Demand. EUROFER Publications.
- [21] ArcelorMittal SA. (2026, February 5). ArcelorMittal Reports Fourth Quarter 2025 and Full-Year 2025 Results and European Decarbonization Progress. ArcelorMittal Regulatory News.
- [22] Nippon Steel Corporation. (2026, November 4). Successful Test Production of Direct Reduced Iron from Low-Grade Iron Ore Using 100% Hydrogen. Nippon Steel Newsroom.
- [23] Nucor Corporation. (2026, October 27). Nucor Reports Results for the Third Quarter of 2026 Across Sheet Mills and Steel Products. Nucor Corporation Investor Relations.
- [24] Constellium SE. (2026, July 29). Constellium Reports Strong Second Quarter and First Half 2026 Results with 751 Thousand Metric Tons Shipped. Constellium News Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the sheet metal market in 2026 and what is forecast for 2036?
- Which automotive lightweighting and data center construction pressures support demand for sheet metal?
- Why do Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled lead the metal material category?
- Why does Light Gauge Sheet 0.5 to 2 mm lead the thickness gauge category globally?
- How do growth rates differ across India, Poland, Mexico and South Korea?
- Which leading companies supply integrated automotive steel coils versus flat-rolled aluminum sheets today?
- What limits commodity hot-rolled margins or causes gigacasting substitution in the sheet metal market?
- What should automotive and HVAC stampers evaluate before qualifying low-carbon EAF or hydrogen-DRI sheet coils?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Metal Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Metal Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Metal Material, 2026 to 2036
- Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled
- Galvanized and Galvalume Zinc-Coated Steel Sheets
- Stainless Steel Sheets Austenitic 304 and 316 Grades
- Aluminum Alloy Sheets 5000 and 6000 Series
- Y-o-Y Growth Trend Analysis By Metal Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Metal Material, 2026 to 2036
- Global Market Analysis and Forecast, By Thickness Gauge, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Thickness Gauge, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Thickness Gauge, 2026 to 2036
- Light Gauge Sheet 0.5 to 2 mm
- Ultra-Thin Foil Gauge Below 0.5 mm
- Medium Gauge Sheet 2 to 6 mm
- Heavy Gauge Sheet and Plate Above 2 mm
- Y-o-Y Growth Trend Analysis By Thickness Gauge, 2021 to 2025
- Absolute $ Opportunity Analysis By Thickness Gauge, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Automotive Body Panels Chassis and Structural Components
- Construction Roofing Siding and HVAC Ductwork
- Industrial Machinery Cabinets Enclosures and Consumer Appliances
- Aerospace Aircraft Fuselage and Wing Skin Panels
- Electrical Equipment and Data Center Server Racks
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Manufacturing Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Manufacturing Process, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Manufacturing Process, 2026 to 2036
- Cold-Rolled Precision Sheet and Coil
- Hot-Rolled Pickled and Oiled Sheet
- Hot-Dip Galvanized and Electro-Galvanized Sheet
- Pre-Painted and Polymer-Coated Coil
- Y-o-Y Growth Trend Analysis By Manufacturing Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Manufacturing Process, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Steel Service Centers and Toll Processors
- Direct Mill-to-OEM Supply Contracts
- Metal Stamping and Fabrication Job Shops
- Industrial Metals Distributors
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Metal Material
- By Thickness Gauge
- By End-Use Industry
- By Manufacturing Process
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ArcelorMittal SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nippon Steel Corporation
- POSCO Holdings Inc.
- Tata Steel Limited
- Nucor Corporation
- Novelis Inc. (Hindalco)
- United States Steel Corporation
- JSW Steel Limited
- Thyssenkrupp Steel Europe AG
- Constellium SE
- Novelis Inc. (Hindalco Industries)
- ArcelorMittal SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Metal Material, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Thickness Gauge, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Manufacturing Process, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Metal Material
- Figure 6: Global Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Thickness Gauge
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Industry
- Figure 12: Global Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Manufacturing Process
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Metal Material
- Figure 32: North America Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Thickness Gauge
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: North America Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Manufacturing Process
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Metal Material
- Figure 48: Latin America Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Thickness Gauge
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 54: Latin America Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Manufacturing Process
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Metal Material
- Figure 64: Western Europe Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Thickness Gauge
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 70: Western Europe Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Manufacturing Process
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Metal Material
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Thickness Gauge
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Manufacturing Process
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Metal Material
- Figure 96: East Asia Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Thickness Gauge
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 102: East Asia Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Manufacturing Process
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Metal Material
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Thickness Gauge
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Manufacturing Process
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Metal Material, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Metal Material, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Metal Material
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Thickness Gauge, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Thickness Gauge, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Thickness Gauge
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Manufacturing Process, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Manufacturing Process, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Manufacturing Process
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Sheet Metal Market in 2026, and what is forecast for 2036?
FMI estimates that global sheet metal valuation stood at USD 315.0 billion in 2025 and reached USD 330.0 billion in 2026, with projections hitting USD 527.4 billion by 2036.
What is the CAGR for the Sheet Metal Market from 2026 to 2036?
The sheet metal sector is projected to expand at a 4.8% CAGR over the 2026 to 2036 forecast window, adding USD 197.4 billion in incremental coil and sheet revenue across global manufacturing hubs.
Which metal material segment leads the Sheet Metal Market?
Carbon Steel and Mild Steel Sheets Cold-Rolled Hot-Rolled hold an estimated 56.0% of metal material demand in 2026 since predictable deep-drawing formability and low per-ton cost anchor high-volume automotive and appliance stamping.
Which thickness gauge segment leads the Sheet Metal Market?
Light Gauge Sheet 0.5 to 2 mm represents 52.0% of the thickness gauge category in 2026 as passenger-car body panels, HVAC ductwork, and server cabinets standardize thin-gauge flat-rolled coils.
Which country has a notable growth outlook during the assessment period?
India leads national expansion projections at a 6.2% CAGR through 2036, followed by Poland at 5.5% and Mexico at 5.2%, driven by PLI specialty steel mill additions and nearshoring appliance and automotive stamping.
Who are the key players in the market?
ArcelorMittal, Nippon Steel, POSCO and Tata Steel lead global flat-steel supply with Nucor and U.S. Steel. Other key producers include JSW Steel, Thyssenkrupp, Novelis and Constellium.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
