

- Market Size (2026)
- USD 3.7 Bn
- Forecast (2036)
- USD 16.2 Bn
- CAGR (2026 to 2036)
- 16.0%
How big is Smart Waste Management Market in 2026?
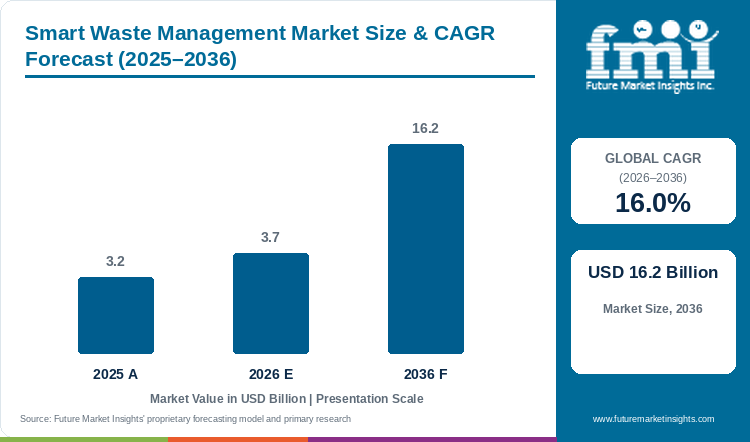
Demand is projected to expand at 16.0% CAGR from 2026 to 2036. Market value rises from USD 3.17 billion in 2025 to USD 3.68 billion in 2026 and USD 16.22 billion by 2036.
The global smart waste management market covers systems and equipment for collection, processing, energy recovery and disposal, connecting operating information with the movement and treatment of waste. Market value rises from USD 3.17 billion in 2025 to an estimated USD 3.68 billion in 2026 and USD 16.22 billion by 2036, at a CAGR of 16.0% for 2026 to 2036. Within the separate 2026 breakdowns, waste-to-energy represents 44.0% of smart energy recovery demand and sanitary landfills account for 43.0% of smart disposal demand, reflecting distinct roles within the wider waste-management chain.
Collection visibility and the need for dependable receiving capacity support investment across this chain. Seaford Town Council's approved thirteen-bin solar-compaction trial for summer 2026 illustrates a municipal programme designed to assess actual usage and capacity. [1] A March 2025 time-of-flight sensing study examines measurement in a small office bin, highlighting the importance of container geometry and sensor coverage. [2] A government-hosted Visakhapatnam case describes an architecture linking sensors, asset identity and collection alerts; its submitted outcomes remain unvalidated. [3] Together, these examples place service integration and local operating conditions at the centre of adoption.
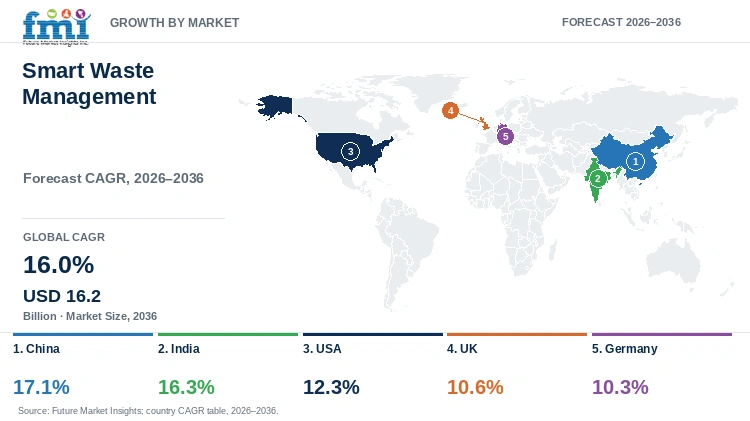
China and India lead the profiled outlook at CAGRs of 17.1% and 16.3%, respectively, for 2026 to 2036. The USA follows at 12.3%, the UK at 10.6% and Germany at 10.3%. EPA's recycling-infrastructure programme provides additional US materials-management investment context. [4]
Republic Services, Veolia North America, SENSONEO, Recycle Smart Solutions and IBM Corporation represent different parts of the competitive field, spanning waste services, connected systems and information technology. Differentiation depends on connecting credible measurements with dispatch and site operations, supported by clear hardware, data and maintenance responsibilities. Collection systems must also fit the waste streams and treatment capacity available locally. Offers that define these interfaces make the operating commitment clearer across initial deployment, continuing service and later system changes.
Key Market Trends & Insights
- Fill-level information is being connected with asset identity and driver dispatch, rather than treated as a standalone display. [3]
- Small sensing studies help define measurement requirements but do not establish fleet-wide savings. [2]
- Municipal trials can test actual capacity needs before a long-term equipment purchase. [1]
Regional Highlights
- China and India have the highest profiled CAGRs, at 17.1% and 16.3% for 2026 to 2036.
- The UK council example is an approved trial, not evidence that the whole country has adopted the same equipment. [1]
- US recycling grants support materials-management infrastructure; their value is not smart-waste market revenue. [4]
Market Size & Forecast
Table 1: Market Size and Forecast for Smart Waste Management Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 3.17 billion |
| 2026 market value | USD 3.68 billion |
| 2036 market value | USD 16.22 billion |
| CAGR 2026 to 2036 | 16.0% |
| Revenue increase 2026 to 2036 | USD 12.54 billion |
| Market expansion 2026 to 2036 | 4.41 times |
A municipality can buy sensors without changing a route, or change dispatch rules without replacing every container. The useful demand assessment identifies which information is missing from the existing service and what operational response the new system enables. Collection hardware also needs to withstand its location and remain serviceable when a sensor, battery or communication link fails. Processing and disposal purchases bring another set of capacity and acceptance requirements. Growth in one part of this chain does not imply that every technology or treatment route expands at the same rate.
The Waste Management Carbon Credit Market covers an adjacent financing context; a credit is distinct from collection equipment revenue.
Collection information must reach a team that can use it
Smart collection is an operating arrangement, not simply a connected bin. The authority needs an asset identity, a credible reading and a way to allocate the next collection. NITI Aayog’s case description of Visakhapatnam links fill-level sensing, RFID, GPS and dashboards, but the portal labels its submitted cases unvalidated. [3] The description is useful evidence of system architecture rather than proof of reported health or efficiency improvements. For a buyer, it raises specific procurement questions about data ownership, lost communications and how drivers receive changes. Those interfaces can determine whether the hardware becomes part of a reliable service or remains a disconnected demonstration.
Table 2: Industry evidence relevant to the smart waste management market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Solar compaction | Seaford approved thirteen bins for a June-September 2026 trial. | A trial can test usage and capacity before a long-term decision. | [1] |
| Optical sensing | A March 2025 study tested time-of-flight readings in a small office bin. | Container geometry and sensor coverage need validation in the intended setting. | [2] |
| Municipal integration | The July 2025 government-hosted case describes sensor-linked collection alerts. | The service needs an explicit link between data and dispatch responsibilities. | [3] |
Analyst Perspective
“Waste-to-energy and landfill contracts need consistent performance across the collection or treatment service the customer can operate. Cost comparisons should include equipment support and the response to incomplete operating data, alongside the functions and delivery responsibilities covered by the price.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Smart Waste Management Market segmented?
The market is segmented by Smart Collection, Smart Processing, Smart Energy Recovery, Smart Disposal, and Region.
Smart collection, processing, energy recovery and disposal are separate market views. A container sensor is also distinct from a waste-to-energy facility: the purchasing authority may coordinate the programmes, but their assets, approvals and service obligations differ. The published benchmarks identify waste-to-energy within energy recovery and sanitary landfills within disposal. A commercial assessment needs to connect those categories with the waste stream and existing infrastructure. Processing decisions affect what material reaches recovery or disposal, while collection information affects the timing and location of the service. The right investment depends on that complete arrangement.
Why does waste-to-energy lead the energy recovery benchmark?
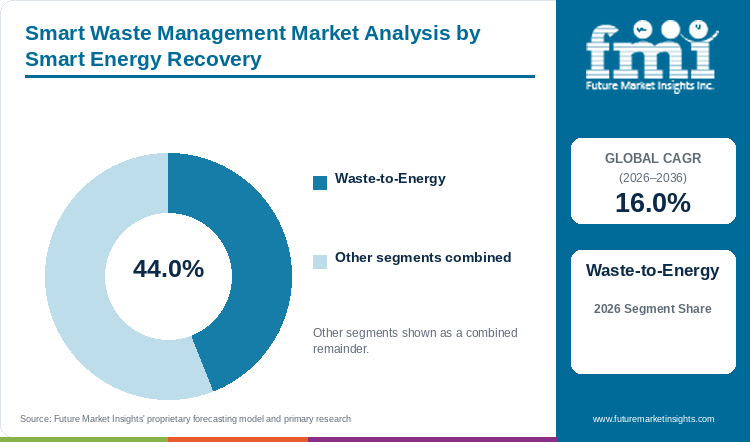
Table 3: Smart Energy Recovery Share for Smart Waste Management Market (percentage share), 2026
| Smart Energy Recovery | Estimated share (2026) |
|---|---|
| Waste-to-Energy | 44.0% |
| Other smart energy recovery segments | 56.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Smart Waste Management Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 16.0% |
| Profiled smart energy recovery segment | Waste-to-Energy |
Energy recovery requires a dependable relationship between incoming waste and the treatment installation. Waste-to-energy holds an estimated 44.0% of smart energy recovery demand in 2026. Buyers need to assess the material received, how it is prepared and the service responsibilities around the plant, rather than treat every waste stream as an interchangeable fuel. Collection and processing changes can alter what arrives at the facility, so the purchasing programme needs to account for those upstream decisions. The equipment contract also differs from the continuing operating arrangement. A supplier’s commercial offer becomes more useful when the customer can identify the capacity, acceptance requirements and maintenance scope it is buying. The market share describes this category’s position; it does not establish that energy recovery is the preferred route for every municipality.
The Waste-to-Energy segment is estimated to account for 44.0% of smart energy recovery demand in 2026.
- Waste-to-Energy represents an estimated 44.0% of smart energy recovery demand in 2026; other recovery routes together represent 56.0%.
- Waste composition, preparation and the receiving facility determine the useful recovery arrangement.
What sustains the sanitary-landfill share?
Table 5: Smart Disposal Share for Smart Waste Management Market (percentage share), 2026
| Smart Disposal | Estimated share (2026) |
|---|---|
| Sanitary Landfills | 43.0% |
| Other smart disposal segments | 57.0% |
| Total | 100.0% |
Disposal remains a receiving service with a defined capacity and an obligation to manage the waste accepted. Sanitary landfills represent an estimated 43.0% of smart disposal demand in 2026. The smart component can connect operating records and monitoring with the decisions made at the site, but it does not remove the need for appropriate infrastructure and management. Customers should distinguish the information system from the physical disposal asset and identify who responds when monitoring indicates a problem. The procurement can include equipment, communications and continuing service, with different replacement cycles for each. This is why a broad digital specification is insufficient on its own. A useful offer explains the operating boundary and how the proposed information supports the customer’s actual site responsibilities throughout the contract.
The Sanitary Landfills segment is estimated to account for 43.0% of smart disposal demand in 2026.
- Sanitary Landfills account for an estimated 43.0% of smart disposal demand in 2026; other disposal routes together account for 57.0%.
- Monitoring and operating records complement the disposal asset and its site-management requirements.
- Monitoring can also form part of site safety. The smart hazard control modules covers an adjacent controls category.
What are the drivers, restraints, and opportunities in the Smart Waste Management Market?
Collection visibility and treatment needs support demand; measurement and service-integration limits constrain adoption; trials with clear operating responsibilities improve the investment decision.
Driver
Authorities and contractors need to know where waste is accumulating and how their collection resources are being used. That creates demand for equipment that connects an identifiable container with information the service team can act on. The Seaford trial explicitly planned to measure usage, capacity needs and real-world performance. [1] Its commercial significance lies in the decision process, not an assumed saving. Similar purchases can support a targeted service change where overflow or uneven demand is a local problem. Treatment and disposal investments follow the separate need to handle the collected material, so the customer’s complete waste programme remains the relevant unit of analysis.
Restraint
A sensor reading may not describe the whole container, and a reliable laboratory link may not remain reliable across an outdoor fleet. The 2025 time-of-flight study used a 250 mm-high office bin and controlled scenarios; it does not demonstrate municipal-scale routing gains. [2] Buyers must therefore test the intended geometry and operating conditions before using the data to change a service. Communications, cleaning and replacement arrangements also create ongoing work. Where responsibilities are unclear, the authority can acquire connected hardware without obtaining a dependable collection improvement. This limits the value of judging proposals by device price or advertised connectivity alone.
Opportunity
There is an opportunity to connect a limited trial with a transparent purchasing decision. A customer can define the information needed, establish how collections will respond and then assess whether the arrangement works in the intended setting. US EPA’s recycling-infrastructure programme supports improvements to local materials-management systems, illustrating the wider investment setting without measuring smart-equipment sales. [4] Suppliers can make bids more useful by stating which hardware, data services and maintenance obligations are included. They can also explain what happens when a reading is unavailable, allowing the service operator to continue collection rather than depend on an untested digital-only process.
The Marine Waste Handling Equipment Market addresses a different receiving and operating environment for waste equipment.
Which country CAGRs are profiled in the Smart Waste Management Market?
Table 6: Country CAGR Comparison for Smart Waste Management Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 17.1% |
| India | 16.3% |
| USA | 12.3% |
| UK | 10.6% |
| Germany | 10.3% |
Country-wise Analysis
China Smart Waste Management Market Outlook (2026 to 2036)
The demand assessment needs to separate connected collection from processing, energy recovery and disposal assets because their customers and contract structures can differ. A collection operator may first need reliable asset identity and dispatch information, whereas a treatment project needs a receiving capacity and a defined material stream. Suppliers can assess the opportunity by identifying which part of the local service is being changed and what information the customer will use. The forecast does not establish a single adoption rate for every city or treatment route. A complete proposal should make hardware support, communications and continuing service responsibilities explicit before the purchaser compares the long-term cost.
India Smart Waste Management Market Outlook (2026 to 2036)
The government-hosted Visakhapatnam case describes a practical chain from fill-level sensing to collection alerts, linking bin identity with GPS and a municipal dashboard. [3] Because the portal marks submissions unvalidated, the architecture can inform procurement questions without turning its reported benefits into verified outcomes. Buyers need to establish who maintains the sensors, who reviews missing readings and how a driver receives a changed instruction. Those details determine whether a connected-container purchase fits the existing service. The market estimate covers a broader set of collection and treatment categories, so it should not be read as the growth forecast for that one city’s system or for a single technology.
USA Smart Waste Management Market Outlook (2026 to 2036)
Recycling infrastructure creates a distinct investment setting in the USA. EPA announced sixteen second-round local-government selections in December 2025 under its Solid Waste Infrastructure for Recycling programme. [4] Those grants address materials-management systems and cannot be counted as smart waste equipment revenue. For vendors, the relevant task is to identify what the authority intends to improve: collection information, receiving capacity or the operation of an existing facility. Each calls for different equipment and service commitments. A project can therefore create useful demand without purchasing every category in the report. Clear boundaries around the supplied hardware, data and maintenance make offers easier for the authority to compare.
UK Smart Waste Management Market Outlook (2026 to 2036)
Seaford’s May 2026 announcement shows a council using a trial before committing to a long-term seafront solution. Thirteen solar-compaction bins were planned for the summer, with fill-level information and a review of actual usage and capacity needs. [1] This is evidence of an approved programme, rather than completed results. A supplier seeking wider orders needs to connect the trial’s measures with the council’s next purchasing decision, including installation, emptying and ongoing support. The same arrangement will not necessarily suit a different location or waste stream. Municipal procurement remains tied to the service problem and the resources available to operate the proposed system.
Germany Smart Waste Management Market Outlook (2026 to 2036)
For Germany, FMI profiles a CAGR of 10.3% over 2026 to 2036. A useful commercial assessment distinguishes renewal of an existing waste service from a new treatment investment. The former may require equipment that works with established containers, vehicles and records; the latter needs a defined receiving and operating arrangement. Data compatibility and a credible support plan can therefore matter as much as the sensor or control hardware itself. Buyers can compare offers by identifying what decision the information changes and who is responsible for the response. The national estimate covers several separate market breakdowns. It does not imply that every disposal route or individual municipal contract expands at the same pace, nor does it provide an equipment replacement schedule.
Who are the notable companies in the Smart Waste Management Market?
Republic Services; Veolia North America; SENSONEO; Recycle Smart Solutions; IBM Corporation
Representative participants span waste services, connected hardware and information systems. The customer may need several of these capabilities, but an equipment bid and a complete operating contract should not be compared as the same product. The table identifies buyer assessment points for companies named in the market coverage. A useful competitive comparison begins with a common service boundary and the information the purchaser expects to use.
Competitive Benchmarking: Smart Waste Management Market
Table 7: Competitive positioning for the smart waste management market
| Company | Positioning | Buyer comparison focus |
|---|---|---|
| Republic Services | Waste-service participant | Compare service boundary, operating responsibilities and equipment support. |
| Veolia North America | Waste-service participant | Identify the treatment or collection programme included in the proposed scope. |
| SENSONEO | Connected waste-system participant | Assess sensor coverage and the link between readings and dispatch. |
| Recycle Smart Solutions | Waste-system participant | Clarify asset records, reporting and continuing maintenance. |
| IBM Corporation | Information-technology participant | Define integration responsibilities and usable data outputs for the operator. |
Key Developments in the Smart Waste Management Market
- Seaford approved a thirteen-bin summer trial in April 2026 and announced it in May. [1]
- A March 2025 study tested time-of-flight waste-level sensing in controlled small-bin scenarios. [2]
- EPA announced sixteen local-government recycling-infrastructure selections in December 2025. [4]
Key Players in the Smart Waste Management Market
Waste-service participant
- Republic Services
- Veolia North America
Connected waste-system participant
- SENSONEO
Waste-system participant
- Recycle Smart Solutions
Information-technology participant
- IBM Corporation
Smart Waste Management Market Report Scope
Table 8: Report Scope for Smart Waste Management Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Systems and equipment covering smart collection, processing, energy recovery and disposal. |
| Quantitative units | USD billion and percentage |
| Forecast period | 2026 to 2036 |
| Segment reference period | 2026 |
| Market breakdown | Smart Collection; Smart Processing; Smart Energy Recovery; Smart Disposal |
| Profiled geographies | China; India; USA; UK; Germany |
| Representative companies | Republic Services; Veolia North America; SENSONEO; Recycle Smart Solutions; IBM Corporation |
Smart Waste Management Market Research Methodology
Table 9: Research Methodology for Smart Waste Management Market, 2026 edition
| Method | Approach |
|---|---|
| Market estimates | FMI’s current scope and FAQ values supply the 2026 and 2036 outlook. |
| Segment shares | Energy recovery and disposal retain their separate 2026 denominators. |
| Country comparison | Five published CAGRs retain the 2026 to 2036 period. |
| Project evidence | Approved trials are distinguished from completed operational outcomes. |
| Research evidence | Small-bin results remain bounded by the study setup. |
| Company assessment | The table compares contract boundaries, integration responsibilities and continuing support. |
Smart Waste Management Market by Segments
Smart Waste Management Market segmented by Smart Collection:
- RFID Technology
- Ultrasonic Sensor
- GPS
- Others
Smart Waste Management Market segmented by Smart Processing:
- Advanced Material Recovery Facilities
- Mechanical Biological Treatment
- RDF (Refuse-Derived Fuel) Facilities
Smart Waste Management Market segmented by Smart Energy Recovery:
- Waste-to-Energy
- Incineration
- Incineration Variants
- Advanced Thermal Recycling
- Biological Treatment
- Direct Use
- Electrical Generation
- Vehicular Use
- Advanced Thermal Treatment
- Gasification
- Pyrolysis
- Plasma Arc Gasification
- Waste-to-Fuel
Smart Waste Management Market segmented by Smart Disposal:
- Sanitary Landfills
- Bioreactor Landfills
- Landfill and Solar Integration
Smart Waste Management Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Eastern Europe
- Poland
- Czech Republic
- Romania
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- New Zealand
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
Research Sources and Bibliography
- [1] Seaford Town Council. 28 May 2026. Seaford Town Council to Trial Smart Solar Bins Along Seafront This Summer
- [2] IPLuso, ISEL and Polytechnic Institute of Setúbal; NIH public archive. March 2025. IoT-Enabled Real-Time Monitoring of Urban Garbage Levels Using Time-of-Flight Sensing Technology
- [3] NITI Aayog — Frontier Tech. Updated 16 July 2025. Clean Cities, Healthy Citizens: AI and IoT for Sanitation-Driven Urban Health
- [4] US Environmental Protection Agency. 2025 grant selections; page updated July 2026. Solid Waste Infrastructure for Recycling Grant Program
This Report Answers
- How big is the smart waste management market in 2026?
- What is the 2036 forecast?
- What does the 44.0% share describe?
- What is the leading smart-disposal share?
- Which profiled country grows fastest?
- Do the public examples establish universal collection savings?
Frequently Asked Questions
What is the estimated market size in 2026?
FMI’s current market scope and FAQ place the 2026 value at about USD 3.68 billion.
What is the 2036 forecast?
The projected value is USD 16.22 billion, with a CAGR of 16.0% for 2026 to 2036.
What does the 44.0% share describe?
It is the estimated Waste-to-Energy share of smart energy recovery demand in 2026.
What is the leading smart-disposal share?
Sanitary Landfills represent an estimated 43.0% of that separate breakdown in 2026.
Which profiled country grows fastest?
China is profiled at 17.1% for 2026 to 2036, followed by India at 16.3%.
Do the public examples establish universal collection savings?
No. The council source describes a planned trial, the sensing research uses a small controlled bin, and the Indian case is a reported system description.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Smart Collection, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Smart Collection, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Smart Collection, 2026 to 2036
- RFID Technology
- Ultrasonic Sensor
- GPS
- Others
- Y-o-Y Growth Trend Analysis By Smart Collection, 2021 to 2025
- Absolute $ Opportunity Analysis By Smart Collection, 2026 to 2036
- Global Market Analysis and Forecast, By Smart Processing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Smart Processing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Smart Processing, 2026 to 2036
- Advanced Material Recovery Facilities
- Mechanical Biological Treatment
- RDF (Refuse-Derived Fuel) Facilities
- Y-o-Y Growth Trend Analysis By Smart Processing, 2021 to 2025
- Absolute $ Opportunity Analysis By Smart Processing, 2026 to 2036
- Global Market Analysis and Forecast, By Smart Energy Recovery, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Smart Energy Recovery, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Smart Energy Recovery, 2026 to 2036
- Waste-to-Energy
- Incineration
- Incineration Variants
- Advanced Thermal Recycling
- Biological Treatment
- Direct Use
- Electrical Generation
- Vehicular Use
- Advanced Thermal Treatment
- Gasification
- Pyrolysis
- Plasma Arc Gasification
- Waste-to-Fuel
- Y-o-Y Growth Trend Analysis By Smart Energy Recovery, 2021 to 2025
- Absolute $ Opportunity Analysis By Smart Energy Recovery, 2026 to 2036
- Global Market Analysis and Forecast, By Smart Disposal, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Smart Disposal, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Smart Disposal, 2026 to 2036
- Sanitary Landfills
- Bioreactor Landfills
- Landfill and Solar Integration
- Y-o-Y Growth Trend Analysis By Smart Disposal, 2021 to 2025
- Absolute $ Opportunity Analysis By Smart Disposal, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- New Zealand
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- United Arab Emirates
- South Africa
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- By Country
- Market Attractiveness Analysis
- By Country
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Smart Collection
- By Smart Processing
- By Smart Energy Recovery
- By Smart Disposal
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Republic Services
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Veolia North America
- SENSONEO
- Recycle Smart Solutions
- IBM Corporation
- Republic Services
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


