
- Market Size (2026)
- USD 13.6 Bn
- Forecast (2036)
- USD 22.8 Bn
- CAGR (2026 to 2036)
- 5.3%
How big is Solar Inverter Market in 2026?
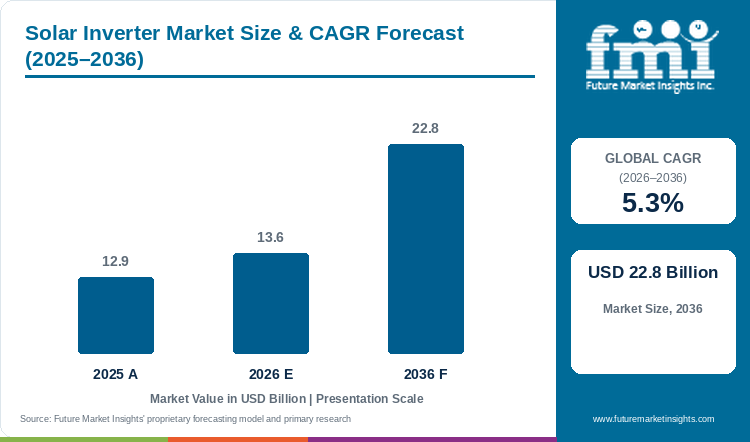
The photovoltaic power electronics solar inverter sector evolved from a 2025 valuation of USD 12.9 billion to USD 13.6 billion in 2026, and is set to achieve USD 22.8 billion by 2036, reflecting a 5.3% CAGR.
FMI forecasts that global solar inverter valuation rises above USD 12.9 billion for 2025 to reach USD 13.6 billion during 2026. Through 2036, annual market value scales toward USD 22.8 billion with a 5.3% CAGR, representing USD 9.2 billion in additional dollar value over the ten-year horizon. While the dedicated utility-scale photovoltaic inverters segment is expanding faster at a 7.4% CAGR as power companies build huge desert solar parks and keep central inverters at 44.6% of inverter type share in 2026, the overall solar inverter market grows at a steadier 5.3% rate because residential rooftop demand in mature markets has cooled and hardware prices per watt continue to come down. The demand for high-power solar inverters is driven by electric utilities and data-center buyers building combined solar-and-battery power plants that require smart grid-stabilizing inverters. Specifically, the U.S. Energy Information Administration reported in February 2026 that developers in the United States are scheduled to add a record 43.4 gigawatts of utility-scale solar capacity plus 24.3 gigawatts of battery storage in 2026, which directly boosts orders for central skids and three-phase string inverters. However, long waits for grid connection permits and falling midday power prices remain key restraining factors that delay project construction and squeeze manufacturer margins. Even so, suppliers that offer 1500-volt inverters with built-in battery storage controls and grid-forming software will capture the strongest utility and commercial orders through 2036.
Key Market Trends & Insights
- By inverter type: Central inverters hold 44.6% of inverter type share in 2026 because pre-built 3.5-to-5.0-megawatt skid stations cut wiring and transformer costs on large solar farms.
- By phase: Three-phase architectures command 67.8% of phase share in 2026 owing to balanced high-voltage AC power needed by commercial factories and utility substations.
- By power output: Above 100 kW units secure 42.8% of power output share in 2026 driven by 250-to-350-kilowatt string inverters and multi-megawatt central skids.
- By grid connection: On-grid utility and commercial systems represent 74.2% of grid connection share in 2026 through net-billing rules and corporate clean-energy power contracts.
- By end use: Utility-scale solar plants account for 51.4% of end-use share in 2026 supported by government solar auctions and data-center electricity contracts.
Regional Highlights
- Latin American solar momentum: Brazil posts a 6.3% decade CAGR through 2036 while Mexico achieves a 6.0% CAGR on commercial distributed generation and factory solar systems.
- OECD grid-modernization pace: Inverter demand in the United States expands at a 5.7% rate from 2026 to 2036, compared with 5.5% in Spain and 5.4% in Australia.
Market Size & Forecast
Table 1: Market Size and Forecast for the Solar Inverter Market (USD Billion and CAGR Percent), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 12.9 billion |
| Estimated Market Size in 2026 | USD 13.6 billion |
| Projected Market Size by 2036 | USD 22.8 billion |
| CAGR, 2026 to 2036 | 5.3% |
| Incremental Dollar Opportunity, 2026 to 2036 | USD 9.2 billion |
FMI estimates that total power-electronics demand for solar inverters steps up beyond USD 12.9 billion recorded during 2025 plus USD 13.6 billion estimated for 2026 to hit USD 22.8 billion during 2036 at a 5.3% growth pace. Higher electricity demand from factories and data centers plus electric vehicles is pushing power companies to build solar plants that can also store power in batteries for evening use. To make these combined plants work smoothly, solar construction firms pair string photovoltaic inverters and central skids with bidirectional battery converters so owners can sell stored solar power when evening electricity prices are high. According to the International Energy Agency Photovoltaic Power Systems Programme Snapshot of Global PV Markets 2026 report released in April 2026, total installed solar capacity surpassed 2.2 terawatts at the end of 2025 after adding over 500 gigawatts of new solar panels in a single year, which is creating massive ongoing demand for inverter hardware.
Annual Shipped Megawatt Capacity and Repowering Pool Sizing
Table 2: Shipped Inverter Capacity and Repowering Sizing for the Solar Inverter Market (USD Billion and GW Shipped), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 12.9 | 13.6 | 22.8 |
| Annual global PV inverter shipments (GW AC) | 485.0 to 520.0 | 515.0 to 555.0 | 890.0 to 960.0 |
| Replacement & repowering inverter shipments (GW AC) | 38.0 to 44.0 | 45.0 to 52.0 | 135.0 to 155.0 |
| Blended average price per watt AC (USD/W) | 0.025 to 0.027 | 0.025 to 0.026 | 0.024 to 0.025 |
Operational note: Annual gigawatt shipment ranges aggregate utility central skids and commercial three-phase string units with residential microinverters and 10-to-12-year replacement inverters for aging solar plants.
A major factor supporting steady sales in the solar inverter market is the need to replace older inverters in solar parks that were built ten to twelve years ago. While glass solar panels last for 25 to 30 years on a roof or in a field, the electronic switches and cooling fans inside an inverter wear out from daily heat after about a decade. Because of this shorter lifespan, solar farm owners are now buying modern photovoltaic inverter systems to replace their old units and boost the power output of their existing solar arrays.
Per Capita & Installed Solar Plant Sizing
Table 3: Per Capita and Wattage Allocation Indicators for the Solar Inverter Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Cumulative global installed PV base (GW) | 2,200.0 | 2,720.0 | 8,400.0 |
| Inverter market value per GW installed base (USD) | 5,863.6 | 5,000.0 | 2,714.3 |
| Average inverter spend per 100 MW utility plant (USD million) | 2.1 to 2.5 | 2.1 to 2.4 | 1.9 to 2.2 |
| Three-phase architecture share (%) | 67.2% to 67.6% | 67.6% to 68.0% | 70.5% to 72.0% |
Table 4: Utility Plant & Commercial Rooftop Indicators for the Solar Inverter Market (USD Billion), 2026
| Metric | Value | Utility & EPC Reference Basis |
|---|---|---|
| Market size, 2026 | USD 13.6 billion | 2026 global industry valuation baseline |
| Annual new + repowered PV additions, 2026 | 535.0 GW AC | Global utility, commercial, and residential installs |
| Average inverter hardware value per MW AC | USD 25,420.6 | Blended central, string, and MLPE realization |
| Utility-scale solar plant allocation, 2026 | USD 7.0 billion | 51.4% end-use segment share allocation |
Strict electrical fire-safety laws for homes and commercial buildings are driving strong rooftop demand for panel-level microinverters and DC power optimizers. Fire codes in the United States and other major markets require rooftop solar systems to shut down high-voltage current within 30 seconds so firefighters can work safely on a roof. To meet these safety rules and get more power from shaded roofs, solar installers are specifying solar microinverter hardware that converts power right under each solar panel.
Analyst Perspective
"Solar inverter selection is no longer just about finding the lowest hardware price per watt, because utilities now require inverters that can stabilize the grid and manage battery storage. Manufacturers that supply 1500-volt grid-forming central skids for solar parks and hybrid storage inverters for businesses are protecting their profits against cheap commodity hardware."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the solar inverter market segmented?
The solar inverter market is segmented by inverter type, phase, power output, grid connection, and end use, and region. In 2026, central inverters are projected at 44.6%, three-phase at 67.8%, above 100 kW at 42.8%, on-grid utility & commercial at 74.2%, and utility-scale solar plants at 51.4%.
By inverter type: central inverters, string inverters, microinverters, and hybrid storage inverters.
By phase: three-phase and single-phase.
By power output: above 100 kW, 10 kW to 100 kW, and below 10 kW.
By grid connection: on-grid utility & commercial and off-grid & microgrid.
By end use: utility-scale solar plants, commercial & industrial rooftops, and residential rooftops.
Why do central inverters account for a notable share of inverter type demand?
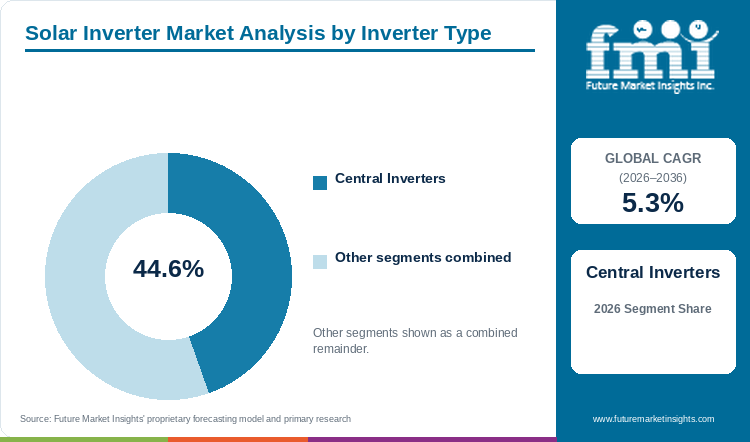
Central inverters command 44.6% of inverter type demand in 2026, supported by turnkey 1500-volt medium-voltage skid stations in utility solar parks.
Table 5: Inverter Type Share for the Solar Inverter Market (Percentage Share), 2026
| Inverter Type | Share (2026) |
|---|---|
| Central Inverters | 44.6% |
| Other Inverter Types Combined | 55.4%* |
| Total | 100.0% |
*Note: Remaining inverter types sum to 100.0% of 2026 global solar inverter market value.
Table 6: Inverter Type Leadership and Growth for the Solar Inverter Market (Segment and Value), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.3% |
| Leading Inverter Type | Central Inverters |
FMI's product evaluation finds that developers building 100-to-800-megawatt solar parks prefer pre-assembled 4.0-to-5.0-megawatt central inverter skids that come with medium-voltage transformers and switchgear in one container. Construction crews place these central skids right next to the solar tracker for power generation rows to cut down on heavy copper wiring and installation labor.
- Central inverters capture 44.6% of inverter type share in 2026 because containerized liquid-cooled skids deliver 99.0% peak conversion efficiency and centralized field maintenance.
- During May 2026, SMA Solar Technology AG disclosed in its first-quarter release that the SMA Group shipped over 4.2 gigawatts of inverter capacity in the first quarter of 2026, led by strong utility orders in its Large Scale & Project Solutions division.
What supports three-phase architectures as a preferred choice in the phase segment?
Three-phase configurations hold 67.8% of the phase category in 2026, anchored by balanced high-voltage AC grid interconnection across commercial and utility arrays.
Factories and cold-storage warehouses plus utility power stations run on 400-volt to 800-volt three-phase power lines that require balanced electricity across all three wires. Commercial solar installers mount three-phase string inverters with multiple power trackers on factory walls so businesses can run their daytime machinery directly off rooftop solar power.
- Three-phase architectures command 67.8% of phase share in 2026 owing to mandatory three-phase grid interconnection codes for commercial systems above 10 kilowatts and all utility solar plants.
- At the same time microinverter makers are also entering commercial three-phase rooftops, with Enphase Energy, Inc. reporting USD 291.9 million in second-quarter 2026 revenue and 725.2 megawatts DC of IQ Microinverter shipments during July 2026.
How are above 100 kW units gaining use across applications in power output?
Above 100 kW ratings secure 42.8% of power output share in 2026, led by 250-to-350 kW high-current string units and multi-megawatt central skids.
Modern utility and commercial solar designs using 1500-volt DC wiring have raised string inverter ratings to 250-to-350 kilowatts while central skids now top 4.4 megawatts. Deployment of higher-wattage units or commercial three-phase microinverters with high-output bifacial solar panels means developers need fewer inverter boxes per megawatt, which lowers mounting and service costs.
- Above 100 kW units secure 42.8% of power output share in 2026 driven by 1500-volt utility-scale solar farms and megawatt-class industrial rooftop installations.
- According to SolarEdge Technologies, Inc. in its April 2026 SEC filing, its commercial and utility DC-optimized inverter systems are now installed across 145 countries including over 60% of Fortune 100 company rooftops.
Why are buyers selecting on-grid utility and commercial systems within grid connection?
On-grid utility and commercial systems represent 74.2% of grid connection share in 2026, supported by wholesale power purchase agreements and net-billing feed-in tariffs.
Almost all utility solar farms and business rooftops connect directly to the public power grid so they can sell extra daytime electricity and earn credits under net-billing or power purchase agreements. Modern on-grid inverters also include smart grid-forming software that helps keep grid voltage steady when clouds pass over a solar farm.
- On-grid utility and commercial systems account for 74.2% of grid connection share in 2026 supported by corporate power purchase agreements and wholesale ancillary-service compensation.
- According to a January 2026 smart-grid study by Al-Shetwi and Hannan in PLoS ONE, pairing grid-forming and grid-support PV inverters with battery storage prevents voltage drops and keeps grid frequency stable.
Which market conditions keep utility-scale solar plants relevant within end use?
Utility-scale solar plants capture 51.4% of end-use share in 2026, fueled by sovereign solar auctions and corporate data-center clean power procurement.
Electric utilities and independent power producers are buying multi-gigawatt blocks of central and string inverters to replace retiring coal plants and supply clean electricity to large data centers. Commercial and industrial rooftops account for 28.4% of end-use demand while residential homes represent 20.2%.
- Utility-scale solar plants hold 51.4% of end-use share in 2026 attributable to sovereign renewable energy auctions and utility-scale solar-plus-storage tax credits.
- Per a December 2025 power-electronics study by Ramesh and Subramanian in Scientific Reports, improved three-phase inverter controllers cut harmonic power distortion across grid-connected hybrid solar plants, making it easier for utilities to approve large solar parks.
What are the drivers, restraints, and opportunities in the solar inverter market?
In the solar inverter market, utility-scale 1500V solar-plus-storage plants and 10-year repowering cycles propel demand whereas grid interconnection queues restrain near-term deliveries and hybrid silicon-carbide topologies create margin expansion opportunities.
- Driver: Utility-scale 1500V solar-plus-storage buildouts and 10-to-12-year repowering of aging first-generation PV plants sustain multi-gigawatt central and string inverter replacement orders.
- Restraint: Multi-year grid interconnection queues and step-up transformer lead times combine with price competition from high-volume inverter manufacturers to compress gross margins.
- Opportunity: Hybrid bidirectional storage inverters and silicon-carbide (SiC) power stage upgrades with grid-forming virtual power plant software generate high-margin hardware and recurring SaaS revenue.
Growth Analysis and Future Potential: Utility Solar-Plus-Storage and Repowering Wave
Future Market Insights notes that electric utilities and solar developers are actively building four-hour lithium battery banks right next to their solar parks, which is driving strong demand for hybrid and DC-coupled central inverters. Plant engineers connect on-grid photovoltaic inverters with site-level power controllers so the plant can store cheap midday solar power and send it to the grid during evening peak hours. Specifically, the U.S. Energy Information Administration reported in August 2025 that solar PV and battery storage together make up more than 80% of all planned U.S. utility-scale power plant additions. This shift toward combined solar-and-battery plants is boosting average inverter selling prices per project.
Risk Assessment of the Solar Inverter Market: Interconnection Queues and Price Compression
Long waiting lists for grid connection approvals and shortages of medium-voltage transformers are the main hurdles delaying utility solar inverter deliveries across North America and Europe. At the same time, home solar installers buying residential solar PV inverters face higher homeowner loan interest rates and lower rooftop export payments in California and Western Europe. Per a November 2025 U.S. Energy Information Administration survey of utility solar developers, grid interconnection paperwork and equipment delivery waits remain the top factors delaying project completion. These permitting bottlenecks cause quarterly swings in inverter shipment volumes.
Commercial Opportunity Analysis: Silicon-Carbide Topologies and Hybrid Microgrids
Inverter manufacturers are creating new growth opportunities by replacing standard silicon switches with silicon-carbide (SiC) power chips that run cooler, weigh 30% less, and push conversion efficiency above 99.0%. At the same time, homeowners and businesses are pairing residential microgrid LFP battery systems with three-phase hybrid inverters so their lights and machines keep running automatically during grid blackouts. In laboratory testing, a February 2025 review by Hassan and Kamel in Energy Reports showed that multi-level transformerless high-power inverters cut electrical leakage current while boosting reactive power support for the grid. Vendors offering SiC hybrid inverters are winning higher-margin commercial and residential orders.
Solar Inverter Market by Country (2026 to 2036)
As per FMI, geographic demand across the solar inverter industry varies according to utility renewable auction schedules and residential battery-storage grid codes. Brazil sets the highest national pace across covered markets at a 6.3% decade CAGR, outperforming Mexico at 6.0% ahead of the United States at 5.7% and Spain at 5.5%.
Table 7: Country CAGR and Primary Growth Levers for the Solar Inverter Market (CAGR Percent), 2026 to 2036
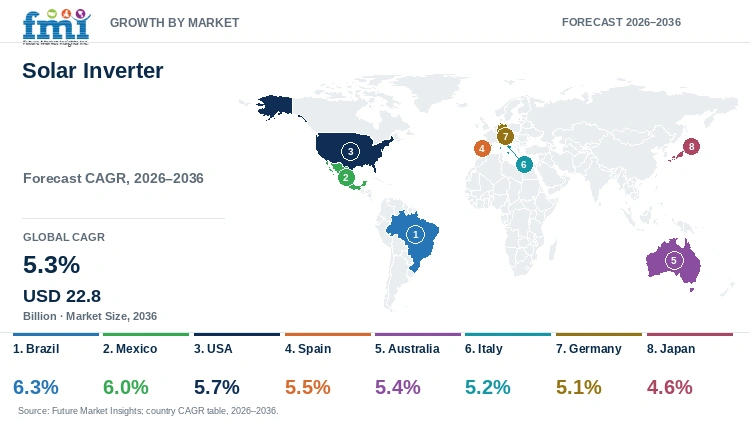
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 6.3% | 16.3 GW annual PV additions and Law 14,300 commercial/agricultural MMGD solar |
| Mexico | 6.0% | Industrial nearshoring microgrids and commercial behind-the-meter distributed PV |
| USA | 5.7% | IRA Section 45X domestic inverter manufacturing credits and utility solar-plus-storage |
| Spain | 5.5% | Utility PV power purchase agreements and industrial autoconsumo self-consumption |
| Australia | 5.4% | Compliant hybrid battery rooftop upgrades and 4.0 GW large-scale solar approvals |
| Italy | 5.2% | 6.4 GW annual PV additions and PNRR 40% Renewable Energy Community grants |
| Germany | 5.1% | 16.4 GW annual PV additions and EEG 2030 215 GW target with hybrid storage demand |
| Japan | 4.6% | Municipal rooftop mandates and repowering of over 100 GW cumulative FIT solar plants |
Source: Future Market Insights analysis
Brazil Solar Inverter Market Outlook (2026 to 2036)
Power-electronics shipments in Brazil record a CAGR of 6.3% spanning 2026 to 2036, fueled by large utility solar parks and distributed rooftop generation under Law 14,300. High retail electricity rates charged by regional power utilities and strong year-round sunshine across Brazil encourage supermarkets and farms plus homeowners to install three-phase string and hybrid inverters. According to the Brazilian Ministry of Mines and Energy and Empresa de Pesquisa Energetica (EPE) in its 2026 Statistical Yearbook of Electricity, Brazil added 16.3 gigawatts of new solar PV capacity in 2025 including 8.8 gigawatts of distributed rooftop and small-ground systems. Although grid curtailment in northeastern states slows some utility parks, battery-ready commercial inverters keep demand growing.
Key takeaway: In Brazil, 16.3 GW annual PV additions and strong commercial and agricultural distributed generation record a 6.3% decade CAGR.
Mexico Solar Inverter Market Outlook (2026 to 2036)
New factories opening under North American nearshoring trends are driving strong commercial and industrial solar inverter demand across northern and central Mexico. Inverter shipments in Mexico achieve a 6.0% annual CAGR over the 2026 to 2036 decade, driven by factory owners installing rooftop solar-plus-storage microgrids to cut daytime power bills and avoid grid voltage drops. Per the International Energy Agency Photovoltaic Power Systems Programme Snapshot 2026 Fact Sheet published in May 2026, global distributed solar installations reached 288 gigawatts in 2025 as commercial self-generation expanded across 39 gigawatt-scale national markets. Because distributed permits in Mexico cap individual rooftop systems without a wholesale license, installers link modular three-phase string inverters with battery peak shaving.
Key takeaway: In Mexico, industrial nearshoring microgrids and commercial behind-the-meter distributed PV installations achieve a 6.0% ten-year CAGR.
USA Solar Inverter Market Outlook (2026 to 2036)
Domestic manufacturing tax credits under Section 45X of the Inflation Reduction Act and strict rooftop rapid-shutdown fire rules shape buyer choices across the United States. Utility solar developers in Texas and California plus Florida buy 1500-volt central skids for solar-plus-storage farms while home installers prefer U.S.-made microinverters and DC optimizers that qualify for extra tax-credit bonuses. Reinforced by data-center clean power contracts, utility and rooftop demand in the USA achieves a 5.7% ten-year CAGR across the forecast period. Per U.S. Department of Energy UNIFI Consortium grid-forming specifications adopted in October 2025, universal interoperability rules guide how inverters stabilize grid voltage and frequency. Local assembly plants help vendors avoid import tariffs.
Key takeaway: In the USA, Section 45X domestic inverter manufacturing credits and utility solar-plus-storage buildouts register a 5.7% ten-year CAGR.
Spain Solar Inverter Market Outlook (2026 to 2036)
Abundant sunshine and corporate clean-power purchase agreements make Spain one of Europe's largest buyers of 1500-volt utility central skids and factory self-consumption (autoconsumo) string inverters. According to Fronius International GmbH in its June 2026 Verto Plus and GEN24 Plus technical release, three-phase commercial and hybrid inverters with built-in arc-fault protection and multi-MPPT tracking help European factories maximize rooftop self-consumption. Food and auto plus chemical plants across Spain install three-phase string inverters to cut their daytime electricity bills. Even though low midday wholesale power prices during sunny spring months slow uncontracted solar parks, hybrid battery retrofits ensure Spain attains a 5.5% annual growth CAGR through 2036.
Key takeaway: In Spain, utility PV power purchase agreements and industrial self-consumption retrofits attain a 5.5% decade CAGR.
Australia Solar Inverter Market Outlook (2026 to 2036)
Inverter shipments in Australia realize a CAGR of 5.4% over the 2026 to 2036 window, reinforced by homeowners replacing old single-phase units with hybrid battery inverters and utilities building new solar parks. With more than one in three Australian homes already having rooftop solar panels, state grid operators now enforce dynamic export limits that require smart connected inverters. According to the Australian Government Clean Energy Regulator in its February 2026 Renewable Energy Target Administrative Report 2025, Australia approved 4.0 gigawatts of large-scale renewable projects in 2025 plus about 3.0 gigawatts of small-scale rooftop solar. Suppliers embed remote curtailment software to meet state emergency backstop rules.
Key takeaway: In Australia, hybrid battery rooftop upgrades and 4.0 GW annual large-scale solar approvals realize a 5.4% annual CAGR.
Italy Solar Inverter Market Outlook (2026 to 2036)
Government Recovery and Resilience Plan (PNRR) grants for local Renewable Energy Communities (CER) and Transition 5.0 factory tax credits are driving commercial and utility inverter orders across Italy. Solar inverter shipments in Italy post a 5.2% forecast-decade CAGR through 2036, driven by repowering of older southern solar farms and new municipal energy-sharing microgrids. According to the International Energy Agency Photovoltaic Power Systems Programme Italy country overview updated in March 2026, Italy added 6.4 gigawatts of new PV capacity in 2025 to reach 43.5 gigawatts total while expanding 40% CER grants to towns up to 50,000 residents. While farmland zoning rules restrict standard ground arrays, raised agrivoltaic string and central inverters from Italian maker FIMER win permit approvals.
Key takeaway: In Italy, 6.4 GW annual PV additions and Renewable Energy Community grants post a 5.2% ten-year CAGR.
Germany Solar Inverter Market Outlook (2026 to 2036)
Simplified Solarpaket I permitting rules and zero value-added tax on home solar-plus-battery systems plus plug-in balcony microinverters (Balkonkraftwerke) drive steady demand across Germany. Homeowners and medium-sized Mittelstand factories across southern and western federal states pair three-phase hybrid inverters from SMA and Fronius with home lithium batteries and heat-pump energy managers. Guided by the national EEG 2030 target of 215 gigawatts of installed solar capacity, annual demand in Germany registers a 5.1% expansion CAGR to 2036. According to the Federal Network Agency in Germany (Bundesnetzagentur) in January 2026, Germany added 16.4 gigawatts of solar capacity in 2025 to reach 117 gigawatts total plus 430,000 registered balcony microinverter units.
Key takeaway: In Germany, 16.4 GW annual PV additions and three-phase hybrid storage and balcony microinverter demand deliver a 5.1% ten-year CAGR.
Japan Solar Inverter Market Outlook (2026 to 2036)
Limited flat land, city rooftop solar mandates in Tokyo and Kawasaki, and the need to replace aging Feed-in-Tariff (FIT) inverters shape buyer demand across Japan. Because large open land parcels are scarce, solar contractors in Japan use multi-MPPT three-phase string inverters on sloped hills and factory roofs while replacing 10-to-15-year-old central inverters installed after 2012. According to the International Energy Agency Photovoltaic Power Systems Programme Japan country report updated in March 2026, Japan's cumulative installed solar capacity passed 100 gigawatts in 2025 with about 5.7 gigawatts of new annual additions. Supported by strict JET grid certification and home backup battery demand, hardware demand in Japan locks in a 4.6% CAGR spanning 2026 to 2036.
Key takeaway: In Japan, municipal rooftop mandates and repowering of over 100 GW of cumulative PV capacity lock in a 4.6% decade CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the solar inverter market?
SMA Solar Technology AG, Fronius International GmbH, Enphase Energy Inc., SolarEdge Technologies Inc., ABB Fimer S.p.A., TMEIC Corporation, Schneider Electric SE, and Ingeteam Power Technology S.A. are the notable companies in the solar inverter market.
FMI analysis indicates that supplier market share across the solar inverter industry divides between European utility-scale central and hybrid string engineering specialists, residential module-level power electronics (MLPE) leaders, and multinational industrial power conversion conglomerates. Major power electronics vendors are scaling up their grid-forming central skids and hybrid battery-ready inverters to serve utility and commercial buyers.
- European Utility, Commercial & Hybrid Specialists: SMA Solar Technology AG and Fronius International GmbH with ABB Fimer S.p.A. and Ingeteam Power Technology S.A. supply central skids and three-phase hybrid string inverters engineered across Europe.
- Module-Level Power Electronics (MLPE) Leaders: Enphase Energy Inc. and SolarEdge Technologies Inc. command residential and commercial rooftop safety compliance through microinverters and DC power optimizers.
- Industrial Power Conversion & Utility Skid Conglomerates: TMEIC Corporation and Schneider Electric SE scale high-power 1500-volt utility central skids and hybrid microgrid storage inverters across global solar parks.
Competitive Benchmarking: Solar Inverter Market
Table 8: Competitive Benchmarking for the Solar Inverter Market (Qualitative Capability Ratings), 2026
| Company | Utility 1500V Central & String Breadth | Hybrid Battery & MLPE Depth | Grid-Forming & Rapid-Shutdown Compliance | Geographic Reach |
|---|---|---|---|---|
| SMA Solar Technology AG | High | High | High | High |
| Fronius International GmbH | Medium | High | High | High |
| Enphase Energy Inc. | Medium | High | High | High |
| SolarEdge Technologies Inc. | Medium | High | High | High |
| ABB Fimer S.p.A. | High | Medium | High | High |
| TMEIC Corporation | High | Medium | High | High |
| Schneider Electric SE | High | High | High | High |
| Ingeteam Power Technology S.A. | High | High | High | High |
Capability tiers evaluate utility 1500V central and string power breadth with hybrid battery-storage integration depth as well as grid-forming firmware certification and multi-continent service reach.
Key Developments in the Solar Inverter Market
- In October 2026, Enphase Energy Inc. posted third-quarter 2026 revenue of USD 293.3 million while expanding commercial three-phase IQ8P-3P microinverters and fourth-generation IQ Battery storage systems.
- In August 2026, SolarEdge Technologies Inc. issued its Form 8-K for the second quarter of 2026, reporting continued commercial rooftop and U.S. domestic-content inverter shipments from its Texas and Florida manufacturing sites.
- In July 2026, SMA Solar Technology AG published preliminary second-quarter 2026 results and raised its full-year 2026 guidance on strong order backlog execution in its Large Scale & Project Solutions utility inverter segment.
Key Players in the Solar Inverter Market
European Central, String & Hybrid Inverter Leaders
- SMA Solar Technology AG
- Fronius International GmbH
- ABB Fimer S.p.A.
Ingeteam Power Technology S.A.
- Module-Level Power Electronics & Rooftop Specialists
- Enphase Energy Inc.
- SolarEdge Technologies Inc.
Industrial Utility Skid & Microgrid Specialists
- TMEIC Corporation
- Schneider Electric SE
Solar Inverter Market - Report Scope
Table 9: Report Scope for the Solar Inverter Market (Coverage Fields and Definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Inverter Type; Phase; Power Output; Grid Connection; End Use |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global commercial valuation of central inverters, string inverters, microinverters, and hybrid storage inverters across single-phase and three-phase configurations for residential, commercial/industrial, and utility-scale photovoltaic systems. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, USA, Spain, Australia, Italy, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | SMA Solar Technology AG, Fronius International GmbH, Enphase Energy Inc., SolarEdge Technologies Inc., ABB Fimer S.p.A., TMEIC Corporation, Schneider Electric SE, Ingeteam Power Technology S.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation in USD Billion. |
Solar Inverter Market - Research Methodology
Table 10: Research Methodology for the Solar Inverter Market (Research Methods and Approach), 2026 to 2036
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from utility solar EPC electrical engineers, independent power producer asset managers, commercial rooftop installers, and power-electronics distributors examining purchasing decisions, grid-code compliance, and repowering cycles. |
| Desk Research | Desk research covered U.S. EIA Today in Energy capacity reports, Bundesnetzagentur, Clean Energy Regulator, EPE Brazil, IEA-PVPS national survey reports, SEC Form 10-K and 8-K filings, and official inverter manufacturer technical disclosures. |
| Market Sizing and Forecasting | The market assessment combined the 2025 baseline valuation with annual gigawatt AC inverter shipments, average selling prices per watt across topologies, repowering replacement cohorts, and country-level PV additions from 2026 to 2036. |
| Country Forecasting Model | Country projections weight annual utility and distributed PV gigawatt additions, 10-to-12-year inverter replacement cohorts, residential battery attachment rates, and domestic manufacturing incentives. |
| Operational Benchmark Traceability | Gigawatt shipment and plant sizing indicators in Tables 2, 3, and 4 trace to IEA-PVPS Snapshot of Global PV Markets 2026, U.S. EIA capacity addition datasets, and audited manufacturer shipment disclosures. |
| Data Validation | Estimates were checked against multiple independent grid connection registries and locked in USD Billion with zero mixing of million units, excluding standalone battery cells and racking hardware to prevent double counting. |
Solar Inverter Market by Segments
Solar Inverter Market segmented by Inverter Type:
- Central Inverters
- String Inverters
- Microinverters
- Hybrid Storage Inverters
Solar Inverter Market segmented by Phase:
- Three-Phase
- Single-Phase
Solar Inverter Market segmented by Power Output:
- Above 100 kW
- 10 to 100 kW
- Below 10 kW
Solar Inverter Market segmented by Grid Connection:
- On-Grid Utility and Commercial
- Off-Grid and Microgrid
Solar Inverter Market segmented by End Use:
- Utility-Scale Solar Plants
- Commercial and Industrial Rooftops
- Residential Rooftops
Solar Inverter Market segmented by Voltage Architecture:
- 1500V DC Utility Architecture
- 1000V DC Commercial Architecture
- Low-Voltage Residential Architecture
- Medium-Voltage Skid Stations
Solar Inverter Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Energy Information Administration (EIA). (2026, February 20). New U.S. Electric Generating Capacity Expected to Reach a Record in 2026 Led by Solar PV and Battery Storage. U.S. Department of Energy EIA.
- [2] International Energy Agency Photovoltaic Power Systems Programme (IEA-PVPS). (2026, April 15). Snapshot of Global PV Markets 2026: Annual and Cumulative Installed Photovoltaic Capacity. International Energy Agency PVPS.
- [3] SMA Solar Technology AG. (2026, May 13). The SMA Group Starts the Fiscal Year 2026 With Sales and Earnings Growth in Large Scale & Project Solutions. SMA Solar Technology AG Investor Relations.
- [4] Enphase Energy, Inc. (2026, July 28). Enphase Energy Reports Financial Results for the Second Quarter of 2026 (725.2 MW DC IQ Microinverters Shipped). Enphase Energy Investor Relations.
- [5] SolarEdge Technologies, Inc. (2026, April 23). Annual Report and Proxy Statement Filing for Fiscal Year 2025 (DC-Optimized Inverter Shipments). U.S. Securities and Exchange Commission EDGAR.
- [6] Al-Shetwi, A. Q., & Hannan, M. A. (2026, January 22). Optimization of power management in PV-based smart grids using grid-forming and grid-support inverters. PLoS ONE, 21(1), e0318492 (PMC12900292).
- [7] Ramesh, K., & Subramanian, S. (2025, December 10). FFO-based controller for 3-phase inverter to reduce power quality issues in grid-connected hybrid PV microgrids. Scientific Reports, 15, 41820 (PMC12694846).
- [8] U.S. Energy Information Administration (EIA). (2025, August 20). U.S. Developers Report Half of New Electric Generating Capacity Additions From Solar PV. U.S. Department of Energy EIA.
- [9] U.S. Energy Information Administration (EIA). (2025, November 10). Fewer U.S. Utility-Scale Solar Photovoltaic Projects Report Construction Delays in Late 2025. U.S. Department of Energy EIA.
- [10] Hassan, M. H., & Kamel, S. (2025, February 18). A review on topology and control strategies of high-power inverters in large-scale photovoltaic power plants. Energy Reports, 13, 1420-1445 (PMC11835574).
- [11] Empresa de Pesquisa Energetica (EPE). (2026, May 20). 2026 Statistical Yearbook of Electricity (Base Year 2025): 16.3 GW New Solar PV Installed Capacity in Brazil. Ministry of Mines and Energy of Brazil.
- [12] International Energy Agency Photovoltaic Power Systems Programme (IEA-PVPS). (2026, May 4). Snapshot of Global PV Markets 2026 Fact Sheet: 698 GW New PV Systems and 288 GW Distributed Solar Additions. International Energy Agency PVPS.
- [13] U.S. Department of Energy Office of Critical Minerals and Energy Innovation. (2025, October 15). Universal Interoperability for Grid-Forming Inverters (UNIFI) Consortium Specifications. U.S. Department of Energy.
- [14] Fronius International GmbH. (2026, June 24). Fronius Verto Plus and GEN24 Plus Hybrid Three-Phase Inverter Technical Architecture. Fronius International GmbH.
- [15] Clean Energy Regulator (CER). (2026, February 27). Renewable Energy Target Administrative Report 2025: Large-Scale Solar Approvals and Small-Scale Rooftop PV. Australian Government Clean Energy Regulator.
- [16] International Energy Agency Photovoltaic Power Systems Programme (IEA-PVPS). (2026, March 25). Italy Country Overview 2025-2026: 6.4 GW New PV Capacity Added Reaching 43.5 GW Cumulative Installations. International Energy Agency PVPS.
- [17] Bundesnetzagentur (Federal Network Agency). (2026, January 8). Growth in Renewable Energy in 2025: Installed Solar PV Capacity in Germany Reaches 117 GW. Federal Network Agency of Germany.
- [18] International Energy Agency Photovoltaic Power Systems Programme (IEA-PVPS). (2026, March 18). National Survey Summary Japan: Cumulative PV Installed Capacity Surpasses 100 GW in 2025. International Energy Agency PVPS.
- [19] Enphase Energy, Inc. (2026, October 27). Form 8-K Exhibit 99.1: Enphase Energy Reports Financial Results for the Third Quarter of 2026 (USD 293.3 Million Revenue). Enphase Energy Investor Relations.
- [20] SolarEdge Technologies, Inc. (2026, August 5). Form 8-K Exhibit 99.1: SolarEdge Reports Second Quarter 2026 Financial Results. U.S. Securities and Exchange Commission EDGAR.
- [21] SMA Solar Technology AG. (2026, July 16). Ad Hoc Announcement: SMA Publishes Preliminary Results for the Second Quarter of 2026 and Raises Full-Year Guidance. SMA Solar Technology AG Investor Relations.
- [22] FIMER S.p.A. (MA Solar Italy). (2026, April 10). FIMER Corporate Profile 2026: Over 60 GW Installed Central and String Solar Inverter Capacity. FIMER S.p.A.
- [23] SolarEdge Technologies, Inc. (2026, February 26). Annual Report on Form 10-K for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete citation list and detailed source mapping.
This Report Answers
- How large is the global solar inverter market in 2026 and 2036?
- How do utility solar-plus-storage plants and repowering cycles drive inverter orders?
- Why do central inverters hold 44.6% of inverter type demand in 2026?
- Why do three-phase systems account for 67.8% of phase demand globally?
- How do installation growth rates compare across Brazil, Mexico, and the USA?
- Which power-electronics manufacturers lead utility skids and microinverters today?
- How do grid interconnection queues and SiC costs impact supplier margins?
- Which grid-forming and rapid-shutdown standards govern EPC selection through 2036?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Inverter Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Inverter Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Inverter Type, 2026 to 2036
- Central Inverters
- String Inverters
- Microinverters
- Hybrid Storage Inverters
- Y-o-Y Growth Trend Analysis By Inverter Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Inverter Type, 2026 to 2036
- Global Market Analysis and Forecast, By Phase, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Phase, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Phase, 2026 to 2036
- Three-Phase
- Single-Phase
- Y-o-Y Growth Trend Analysis By Phase, 2021 to 2025
- Absolute $ Opportunity Analysis By Phase, 2026 to 2036
- Global Market Analysis and Forecast, By Power Output, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Power Output, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Power Output, 2026 to 2036
- Above 100 kW
- 10 to 100 kW
- Below 10 kW
- Y-o-Y Growth Trend Analysis By Power Output, 2021 to 2025
- Absolute $ Opportunity Analysis By Power Output, 2026 to 2036
- Global Market Analysis and Forecast, By Grid Connection, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grid Connection, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grid Connection, 2026 to 2036
- On-Grid Utility and Commercial
- Off-Grid and Microgrid
- Y-o-Y Growth Trend Analysis By Grid Connection, 2021 to 2025
- Absolute $ Opportunity Analysis By Grid Connection, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Utility-Scale Solar Plants
- Commercial and Industrial Rooftops
- Residential Rooftops
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Voltage Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Voltage Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Voltage Architecture, 2026 to 2036
- 1500V DC Utility Architecture
- 1000V DC Commercial Architecture
- Low-Voltage Residential Architecture
- Medium-Voltage Skid Stations
- Y-o-Y Growth Trend Analysis By Voltage Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Voltage Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Inverter Type
- By Phase
- By Power Output
- By Grid Connection
- By End Use
- By Voltage Architecture
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- SMA Solar Technology AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Fronius International GmbH
- Enphase Energy Inc.
- SolarEdge Technologies Inc.
- ABB Fimer S.p.A.
- TMEIC Corporation
- Schneider Electric SE
- Ingeteam Power Technology S.A.
- Module-Level Power Electronics & Rooftop Specialists
- SMA Solar Technology AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 7: Global Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 13: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 14: North America Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 25: Western Europe Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 26: Western Europe Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 27: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 28: Western Europe Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 31: Eastern Europe Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 32: Eastern Europe Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 33: Eastern Europe Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 34: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: Eastern Europe Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: East Asia Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 38: East Asia Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 39: East Asia Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 40: East Asia Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 41: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 42: East Asia Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 43: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: South Asia and Pacific Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 45: South Asia and Pacific Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 46: South Asia and Pacific Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 47: South Asia and Pacific Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 48: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 49: South Asia and Pacific Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 50: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 51: Middle East and Africa Market Value (USD Billion) Forecast by Inverter Type, 2021 to 2036
- Table 52: Middle East and Africa Market Value (USD Billion) Forecast by Phase, 2021 to 2036
- Table 53: Middle East and Africa Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 54: Middle East and Africa Market Value (USD Billion) Forecast by Grid Connection, 2021 to 2036
- Table 55: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 56: Middle East and Africa Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Inverter Type
- Figure 6: Global Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Phase
- Figure 9: Global Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Power Output
- Figure 12: Global Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Grid Connection
- Figure 15: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End Use
- Figure 18: Global Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Voltage Architecture
- Figure 21: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 22: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 23: Global Market Attractiveness Analysis by Region
- Figure 24: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 29: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 30: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 31: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: North America Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Inverter Type
- Figure 35: North America Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Phase
- Figure 38: North America Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Power Output
- Figure 41: North America Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Grid Connection
- Figure 44: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 45: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 46: North America Market Attractiveness Analysis by End Use
- Figure 47: North America Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 48: North America Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 49: North America Market Attractiveness Analysis by Voltage Architecture
- Figure 50: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 51: Latin America Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Inverter Type
- Figure 54: Latin America Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Phase
- Figure 57: Latin America Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Power Output
- Figure 60: Latin America Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Grid Connection
- Figure 63: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by End Use
- Figure 66: Latin America Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Voltage Architecture
- Figure 69: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 70: Western Europe Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Inverter Type
- Figure 73: Western Europe Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Phase
- Figure 76: Western Europe Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 77: Western Europe Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 78: Western Europe Market Attractiveness Analysis by Power Output
- Figure 79: Western Europe Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 80: Western Europe Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 81: Western Europe Market Attractiveness Analysis by Grid Connection
- Figure 82: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 83: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 84: Western Europe Market Attractiveness Analysis by End Use
- Figure 85: Western Europe Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 86: Western Europe Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 87: Western Europe Market Attractiveness Analysis by Voltage Architecture
- Figure 88: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Inverter Type
- Figure 92: Eastern Europe Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 93: Eastern Europe Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 94: Eastern Europe Market Attractiveness Analysis by Phase
- Figure 95: Eastern Europe Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 96: Eastern Europe Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 97: Eastern Europe Market Attractiveness Analysis by Power Output
- Figure 98: Eastern Europe Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 99: Eastern Europe Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 100: Eastern Europe Market Attractiveness Analysis by Grid Connection
- Figure 101: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 102: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 103: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 104: Eastern Europe Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 105: Eastern Europe Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 106: Eastern Europe Market Attractiveness Analysis by Voltage Architecture
- Figure 107: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 108: East Asia Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 109: East Asia Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 110: East Asia Market Attractiveness Analysis by Inverter Type
- Figure 111: East Asia Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 112: East Asia Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 113: East Asia Market Attractiveness Analysis by Phase
- Figure 114: East Asia Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 115: East Asia Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 116: East Asia Market Attractiveness Analysis by Power Output
- Figure 117: East Asia Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 118: East Asia Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 119: East Asia Market Attractiveness Analysis by Grid Connection
- Figure 120: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 121: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 122: East Asia Market Attractiveness Analysis by End Use
- Figure 123: East Asia Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 124: East Asia Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 125: East Asia Market Attractiveness Analysis by Voltage Architecture
- Figure 126: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 127: South Asia and Pacific Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 128: South Asia and Pacific Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 129: South Asia and Pacific Market Attractiveness Analysis by Inverter Type
- Figure 130: South Asia and Pacific Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 131: South Asia and Pacific Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 132: South Asia and Pacific Market Attractiveness Analysis by Phase
- Figure 133: South Asia and Pacific Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 134: South Asia and Pacific Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 135: South Asia and Pacific Market Attractiveness Analysis by Power Output
- Figure 136: South Asia and Pacific Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 137: South Asia and Pacific Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 138: South Asia and Pacific Market Attractiveness Analysis by Grid Connection
- Figure 139: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 140: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 141: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 142: South Asia and Pacific Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 143: South Asia and Pacific Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 144: South Asia and Pacific Market Attractiveness Analysis by Voltage Architecture
- Figure 145: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 146: Middle East and Africa Market Value Share and BPS Analysis by Inverter Type, 2026 and 2036
- Figure 147: Middle East and Africa Market Y-o-Y Growth Comparison by Inverter Type, 2026-2036
- Figure 148: Middle East and Africa Market Attractiveness Analysis by Inverter Type
- Figure 149: Middle East and Africa Market Value Share and BPS Analysis by Phase, 2026 and 2036
- Figure 150: Middle East and Africa Market Y-o-Y Growth Comparison by Phase, 2026-2036
- Figure 151: Middle East and Africa Market Attractiveness Analysis by Phase
- Figure 152: Middle East and Africa Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 153: Middle East and Africa Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 154: Middle East and Africa Market Attractiveness Analysis by Power Output
- Figure 155: Middle East and Africa Market Value Share and BPS Analysis by Grid Connection, 2026 and 2036
- Figure 156: Middle East and Africa Market Y-o-Y Growth Comparison by Grid Connection, 2026-2036
- Figure 157: Middle East and Africa Market Attractiveness Analysis by Grid Connection
- Figure 158: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 159: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 160: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 161: Middle East and Africa Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 162: Middle East and Africa Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 163: Middle East and Africa Market Attractiveness Analysis by Voltage Architecture
- Figure 164: Global Market - Tier Structure Analysis
- Figure 165: Global Market - Company Share Analysis
Frequently Asked Questions
What is the global valuation of the solar inverter market in 2026 and 2036?
In the FMI report, power-electronics solar inverter demand totals USD 13.6 billion in 2026 compared with USD 12.9 billion in 2025 and scales to USD 22.8 billion by 2036.
What compound annual growth rate is projected for the solar inverter market through 2036?
Future Market Insights forecasts that global demand for solar inverters will expand at a 5.3% CAGR over the 2026 to 2036 decade while adding USD 9.2 billion in net hardware valuation.
Which inverter type captures a notable share of the solar inverter market in 2026?
Central inverters command 44.6% of inverter type share in 2026 because multi-megawatt 1500V skid stations anchor utility-scale photovoltaic plants.
Which phase configuration dominates global solar inverter installations?
Three-phase inverters secure 67.8% of phase demand in 2026 due to balanced high-voltage AC grid requirements across commercial and utility projects.
Which evaluated country records notable solar inverter growth from 2026 to 2036?
Brazil leads evaluated national solar inverter expansion at a 6.3% CAGR through 2036 while Mexico advances at 6.0% and the United States grows at 5.7%.
Who are the key players in the market?
SMA Solar Technology AG, Fronius International GmbH, Enphase Energy Inc., SolarEdge Technologies Inc., ABB Fimer S.p.A., TMEIC Corporation, Schneider Electric SE, and Ingeteam Power Technology S.A. lead global supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
